

Key Highlights
- Non-Statutory Stock Options (NSOs) allow employees, consultants, and board members to purchase company shares at a set price, aiding financial planning.
- The exercise cost is based on the market value at the grant date, making NSOs an accessible opportunity for families.
- Tax implications include ordinary income tax on the difference between the exercise price and market value when exercising NSOs.
- Employers typically handle tax deductions, including federal income tax, Social Security, and Medicare taxes, with a withholding rate around 22%.
- Selling shares after exercising NSOs can result in short-term or long-term capital gains tax, depending on the holding period.
- Strategies for managing NSO tax withholding include estimating tax liability, modifying paycheck withholding, and consulting a tax professional.
- Utilising resources like tax calculators, financial planning software, and educational materials can help families manage NSO tax obligations effectively.
- Bright Advisers emphasises fiduciary duty and transparency, offering personalised wealth management strategies for families.
Introduction
Many families feel overwhelmed by the complexities of financial planning, especially when it comes to stock options. These options present a unique opportunity to invest in your own company, but they also come with complex tax implications that can catch many off guard. Together, we can explore practical strategies and insights that will help your family confidently manage these tax responsibilities. Navigating these tax obligations is crucial for your family’s long-term financial stability, and we’re here to help you every step of the way.
Understand Non-Statutory Stock Options (NSOs)
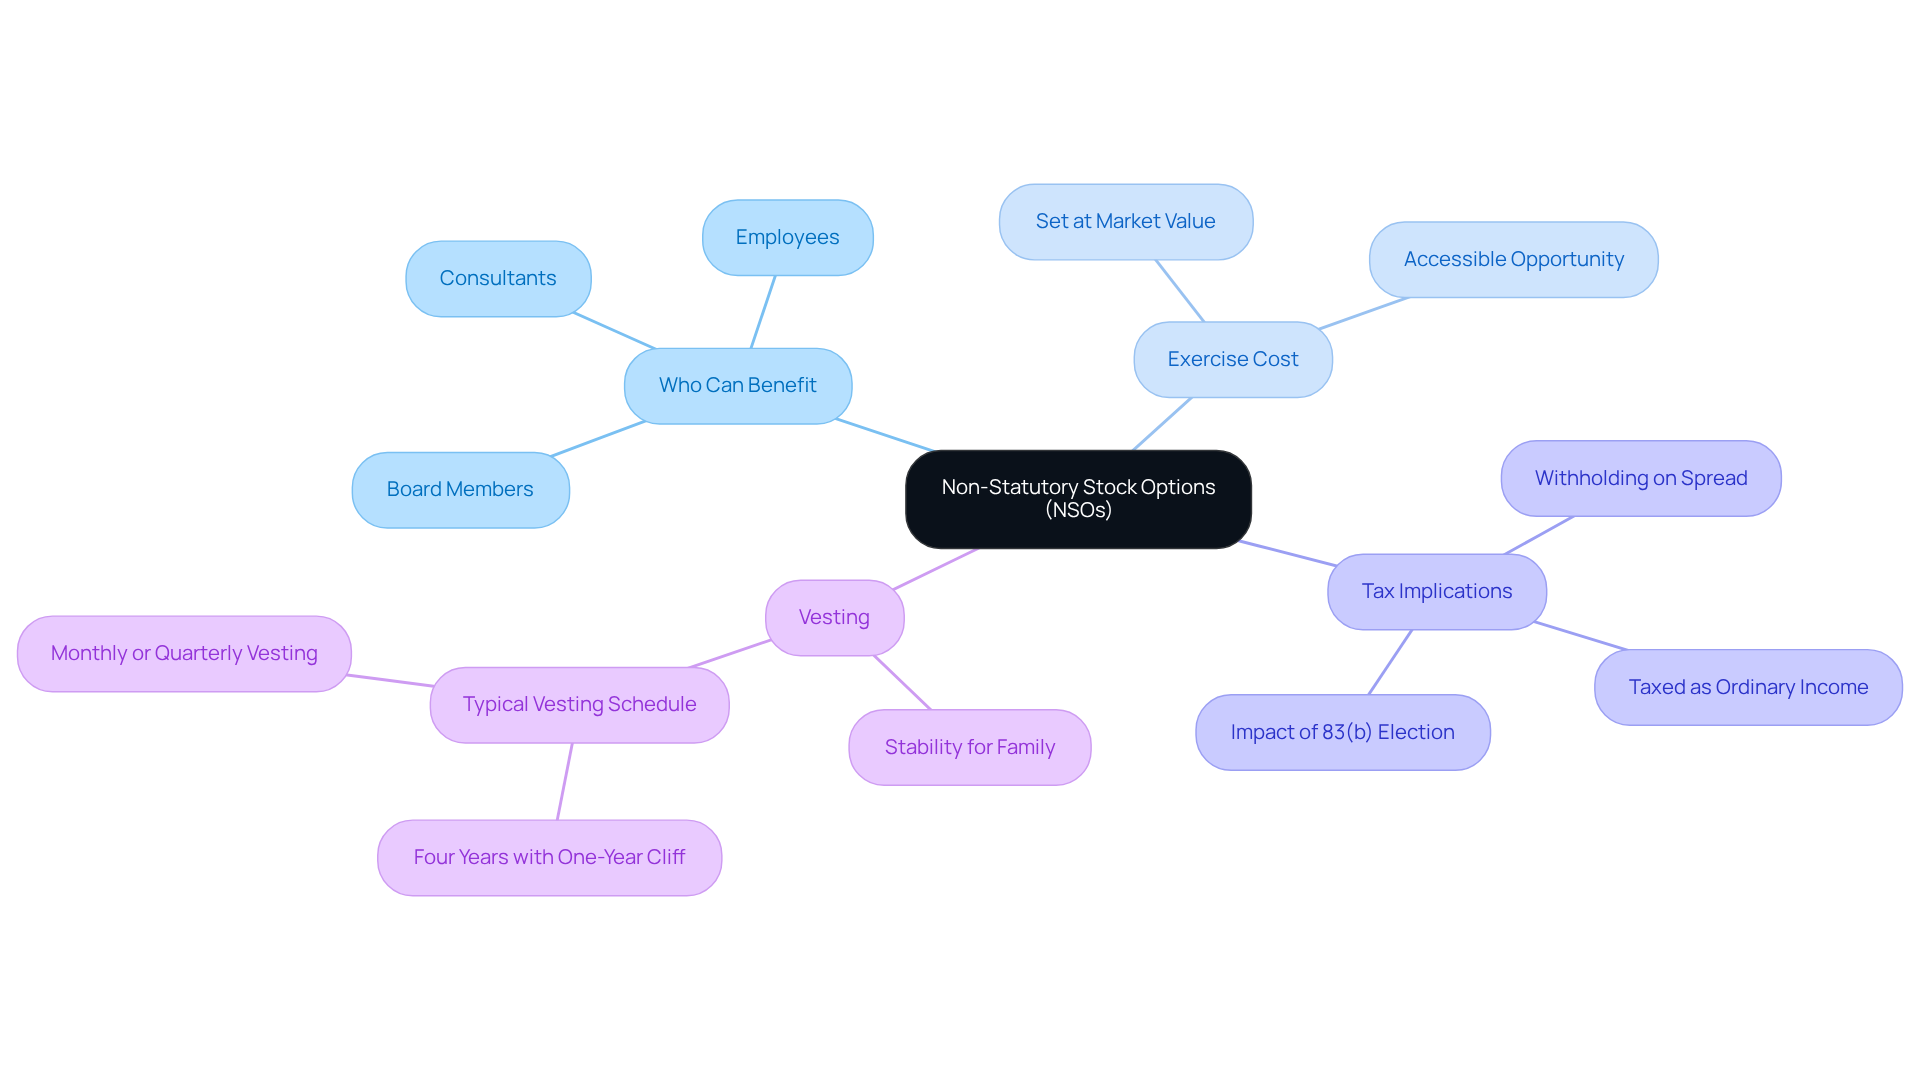
Navigating the world of employee stock options can feel overwhelming, especially when you’re focused on providing for your family. Non-Statutory Stock Options (NSOs) offer you the chance to buy shares in the company you work for at a set price. This flexibility can be a valuable part of your financial planning.
Who can benefit? NSOs are available to employees, consultants, and even board members, giving you more options to consider for your family’s financial future. The exercise cost is typically set at the market value on the grant date, making it an accessible opportunity.
When you use your NSOs, the NSO tax withholding is applied to the difference between what you pay and the market value, which is taxed as regular income. It’s important to understand this so you can plan accordingly for your family’s needs.
Vesting is a key part of NSOs; it means you’ll need to stay with your company for a certain time before you can use these options. This can be a great way to ensure stability for your family while you work towards your goals.
Grasping these fundamentals will empower you to make informed decisions that benefit your family’s future. Remember, we’re here for you as you navigate this journey together.
Explore NSO Tax Implications at Exercise and Sale
Navigating the world of non-qualified stock options can feel overwhelming, especially when it comes to understanding the tax implications that affect your family’s finances.
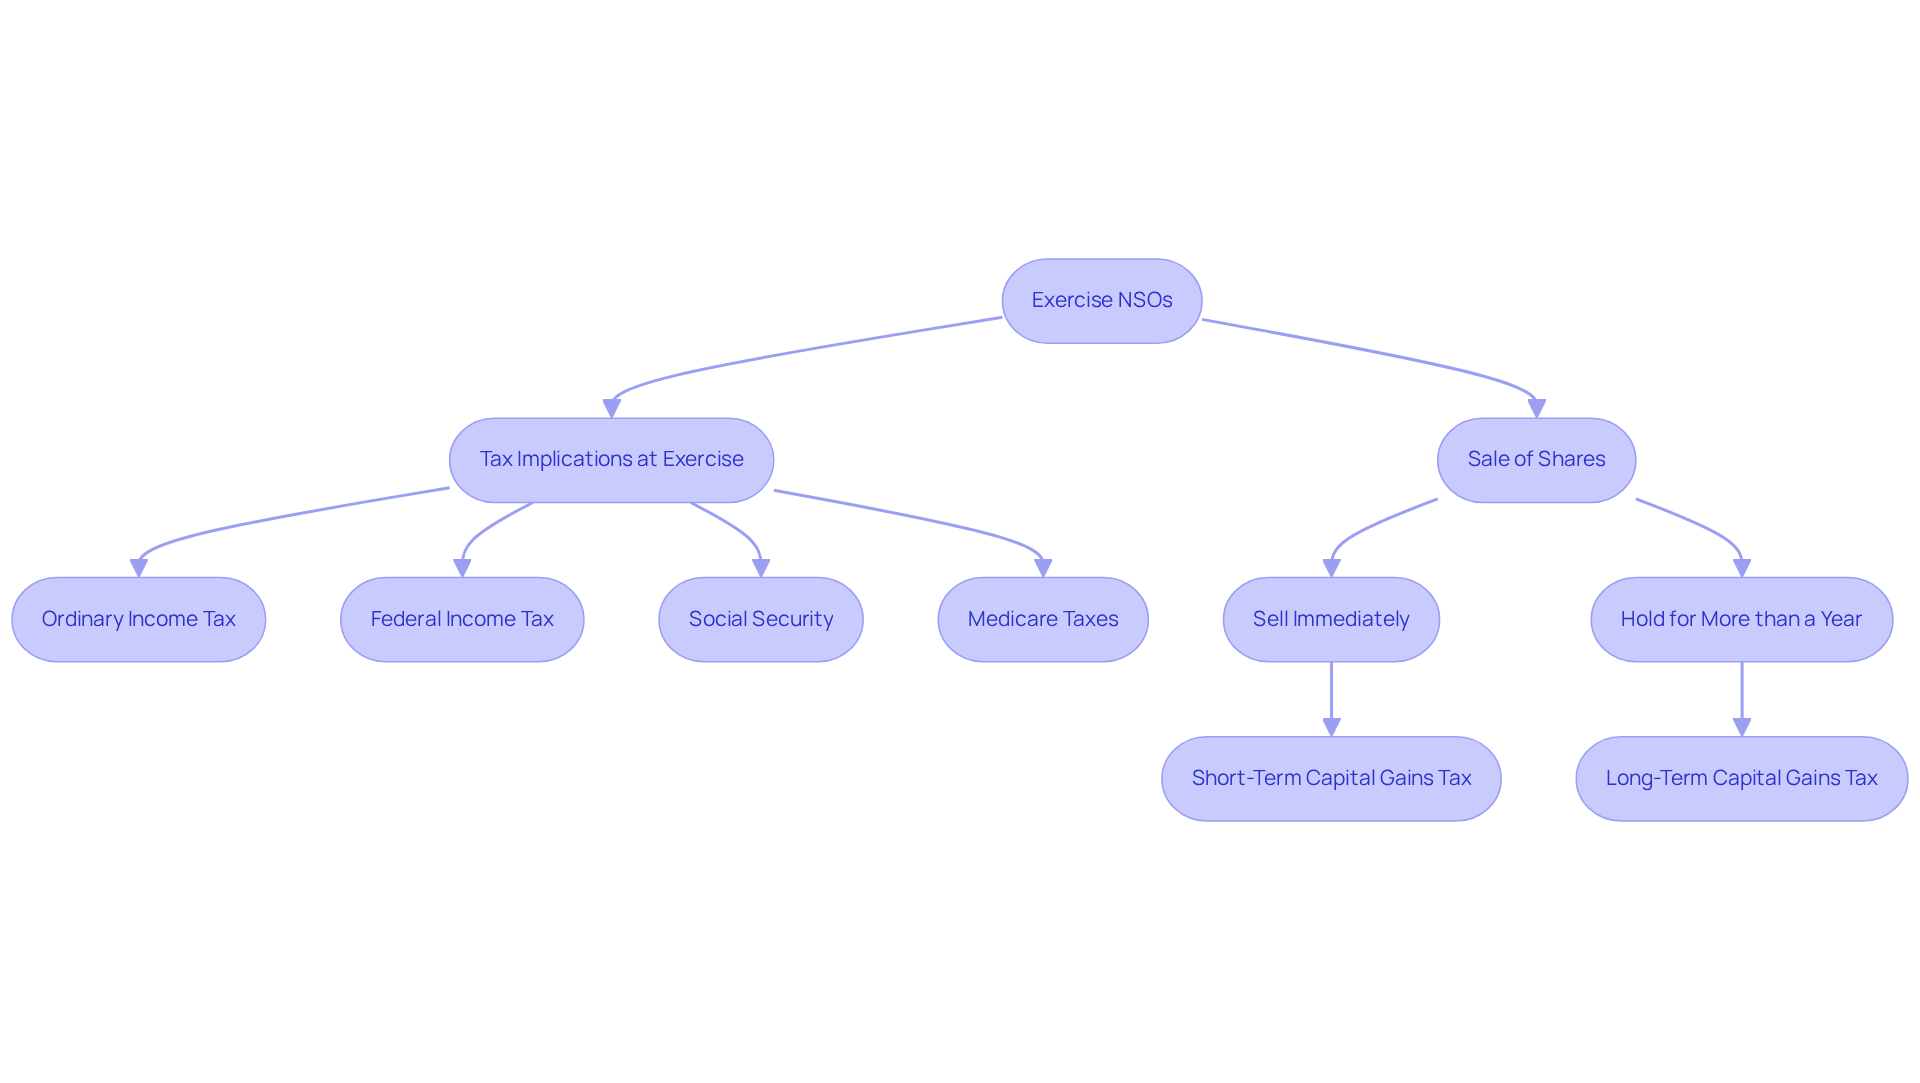
When you exercise your options, the difference between what you pay and the stock’s value can feel like a surprise, as it counts as ordinary income. For example, if you use an NSO with a purchase price of $10 when the stock is valued at $30, you’ll need to account for taxes on that $20 per share difference.
It’s important to know that your employer will handle some deductions when you exercise your options, helping you manage your tax responsibilities. Typically, this includes:
- Federal income tax
- Social Security
- Medicare taxes
With an NSO tax withholding rate often around 22% for non-qualified stock options.
When you sell the shares obtained through non-qualified stock options, any extra profit is taxed as a capital gain. If you sell the shares right after exercising, the gain will be short-term and taxed at ordinary income rates. However, if you hold the shares for more than a year, you might qualify for long-term capital gains rates, which are generally lower.
By grasping these tax details, families can feel more secure and prepared for their financial future. Collaborating with Bright Advisers can help you develop tailored wealth management strategies that not only address immediate tax concerns but also empower you to achieve long-term financial security and freedom. Together, we can navigate this journey.
Implement Strategies for Effective NSO Tax Withholding
Imagine facing a surprise tax bill just when you thought you were on solid financial ground. To help you manage NSO tax withholding effectively, here are some strategies that can ease your mind:
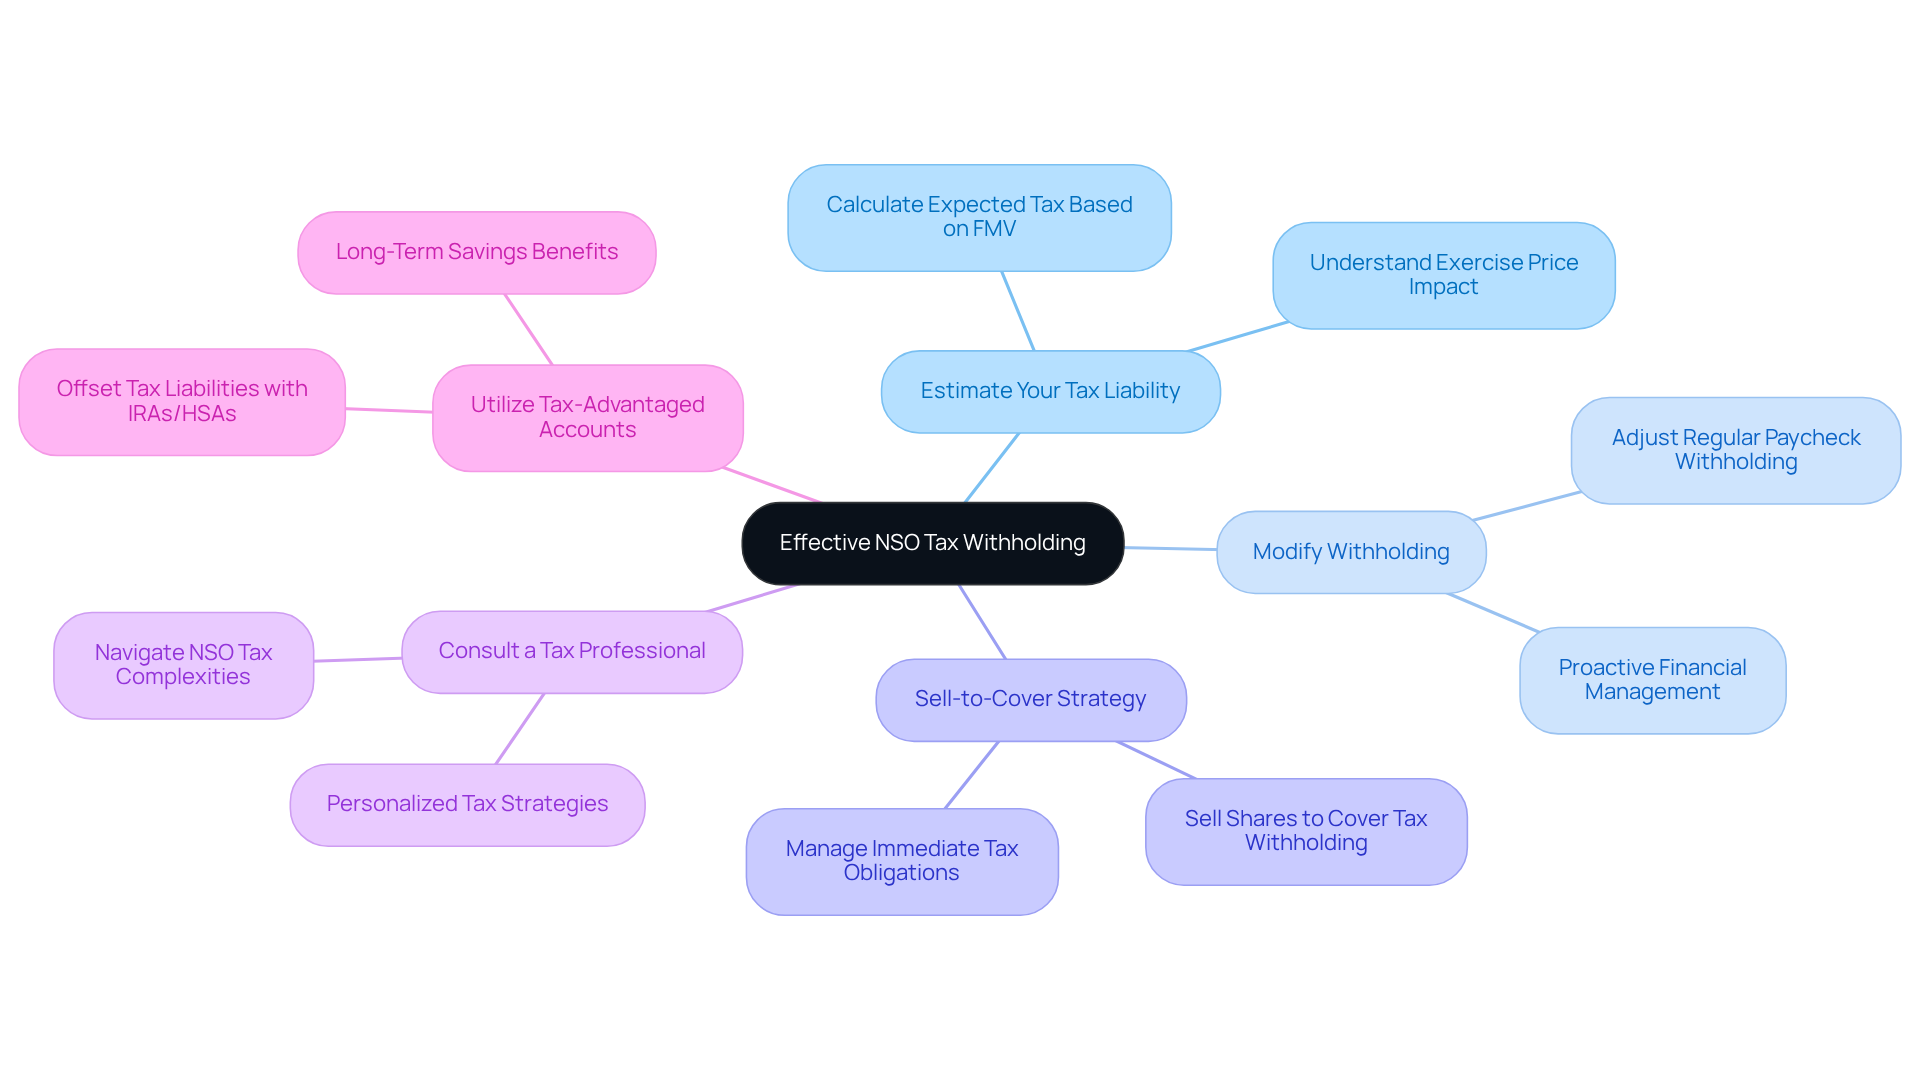
- Estimate Your Tax Liability: Imagine knowing exactly what to expect. By calculating your expected tax liability based on the current fair market value and your exercise price before exercising your NSOs, you can feel more in control of your finances.
- Modify Withholding: If you think your financial obligations might increase, consider adjusting your regular paycheck withholding. This proactive step can help you avoid a substantial tax bill at year-end, giving you peace of mind.
- Sell-to-Cover Strategy: If cash flow is tight, selling a portion of the shares acquired upon exercising your NSOs can help cover the tax withholding. This strategy can be a lifesaver when you need to manage immediate tax obligations.
- Consult a Tax Professional: It’s okay to seek help! A tax professional can offer personalized strategies that fit your unique financial situation, guiding you through the complexities of NSO taxation with care.
- Utilize Tax-Advantaged Accounts: If feasible, consider using tax-advantaged accounts like IRAs or HSAs to offset some of your tax liabilities. This approach not only offers tax benefits but also aids in long-term savings.
By embracing these strategies, you can navigate your nso tax withholding with confidence, alleviating your financial worries and paving the way for a brighter future for your family.
Utilize Resources and Tools for NSO Tax Management
Navigating the complexities of nso tax withholding can feel overwhelming for many families, but it doesn’t have to be that way. Here are some effective recommendations to help you manage this process with confidence:
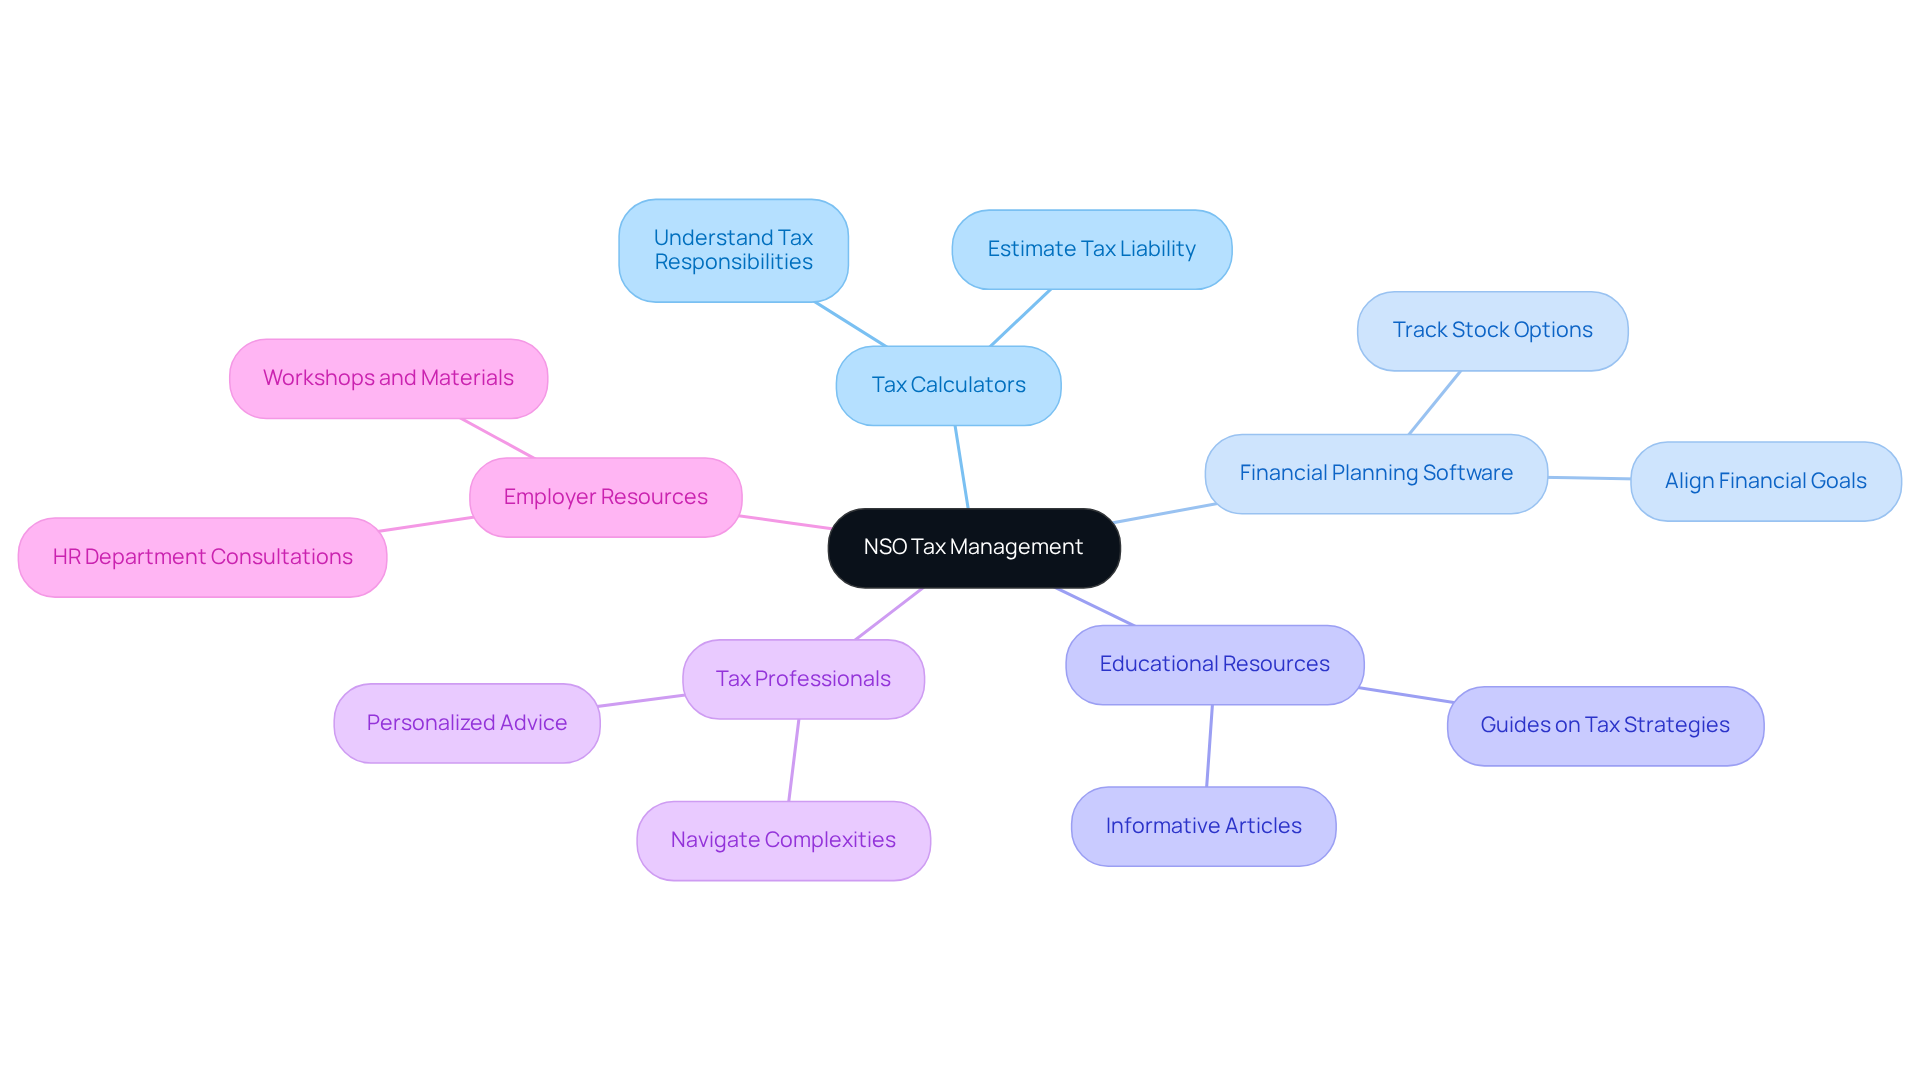
- Tax Calculators: Imagine having a tool that helps you understand your tax responsibilities. Online tax calculators designed for stock options allow you to enter your workout cost, fair market value, and other details, giving you a clearer picture of your tax liability. Remember, nso tax withholding is applicable to Non-Qualified Stock Options, which are taxed as regular income at the time of utilization based on the difference between grant price and fair market value.
- Financial Planning Software: Consider using financial planning software that helps you keep track of your stock options and their tax implications, making it easier to stay organized and informed. Bright Advisers offers personalized portfolio management designed to align with your financial goals, including retirement income strategies and education funding, ensuring you have the right tools at your disposal.
- Educational Resources: Explore platforms like Bright Advisers, which provide informative articles and guides on stock options and tax strategies. These resources are designed to help families navigate the complexities of stock options, emphasizing the significance of understanding nso tax withholding, especially since companies provide over $110 billion in equity compensation each year. Bright Advisers is committed to empowering families with comprehensive financial planning strategies.
- Tax Professionals: Establishing a relationship with a tax professional who specializes in stock options can be invaluable. Their personalized advice can help you navigate the intricacies of nso tax withholding. Bright Advisers also integrates tax planning strategies to help families optimize their financial outcomes.
- Employer Resources: Many companies provide resources and tools for employees regarding stock options. Don’t hesitate to consult your HR department for any available materials or workshops that can enhance your understanding of your NSOs.
By embracing these resources, you’re not just managing taxes; you’re taking a proactive step towards securing your family’s financial future. Bright Advisers emphasizes transparency and a commitment to minimal fund fees, making wealth management more accessible for families seeking financial security.
Conclusion
Imagine navigating the complexities of Non-Statutory Stock Options (NSOs) without feeling overwhelmed. Understanding and managing NSOs is essential for families who want to secure their financial future. Many families find the world of stock options confusing and daunting, but with the right knowledge, you can feel empowered to tackle it head-on. By grasping the intricacies of NSOs, including their tax implications and effective withholding strategies, you can make informed decisions that align with your long-term financial goals.
Key insights from this guide highlight the importance of:
- Estimating tax liabilities
- Adjusting withholdings
- Utilizing resources such as tax calculators and financial planning software
Each strategy discussed serves to alleviate financial stress and promote a proactive approach to managing NSO tax withholding. Collaborating with professionals, like those at Bright Advisers, can further enhance your understanding and provide tailored strategies that fit your unique situation.
By taking these steps, you’re not just managing taxes; you’re building a legacy of financial security for your family. Embrace this opportunity to enhance your financial literacy and ensure that your family’s wealth is preserved across generations.
Frequently Asked Questions
What are Non-Statutory Stock Options (NSOs)?
Non-Statutory Stock Options (NSOs) are options that allow employees, consultants, and board members to buy shares in their company at a predetermined price, providing flexibility in financial planning.
Who can benefit from NSOs?
NSOs are available to employees, consultants, and board members, offering various options for enhancing financial security for families.
How is the exercise cost of NSOs determined?
The exercise cost of NSOs is typically set at the market value on the grant date, making it an accessible opportunity for participants.
How is NSO tax withholding calculated?
NSO tax withholding is applied to the difference between the exercise price and the market value at the time of exercise, and this amount is taxed as regular income.
What is vesting in relation to NSOs?
Vesting refers to the requirement that you must stay with your company for a certain period before you can exercise your NSOs, which can provide stability while working towards financial goals.
Why is understanding NSOs important for financial planning?
Grasping the fundamentals of NSOs empowers individuals to make informed decisions that can positively impact their family’s financial future.
List of Sources
- Understand Non-Statutory Stock Options (NSOs)
- ISO vs NSO: The Tax Implications (https://brightonjones.com/blog/iso-vs-nso)
- ISOs vs. NSOs: What You Need to Know (https://citizensbank.com/private-banking/insights/iso-vs-nso.aspx)
- ISOs v. NSOs: What’s the Difference? | Cooley GO (https://cooleygo.com/isos-v-nsos-whats-the-difference)
- Guide to non-statutory stock options (NSOs) (https://empower.com/the-currency/money/guide-to-nonstatutory-stock-options-nsos)
- Differences Between Incentive Stock Options and Nonqualified Stock Options | Davis Wright Tremaine (https://dwt.com/blogs/startup-law-blog/2020/07/differences-between-iso-nso)
- Explore NSO Tax Implications at Exercise and Sale
- Exercising Stock Options in California: 2026 Tax Guide (https://esofund.com/blog/exercising-stock-options-in-california)
- How Stock Options Are Taxed: ISO vs NSO Tax Treatments (https://carta.com/learn/equity/stock-options/taxes)
- Stock Option Taxes in California: ISO, NSO, and RSU Tax Planning for Tech Workers (https://ietaxattorney.com/stock-option-taxes-in-california-iso-nso-and-rsu-tax-planning-for-tech-workers)
- Frequently asked questions about stock options and tax implications (https://rsmus.com/insights/services/business-tax/frequently-asked-questions-about-stock-options-and-tax-implicati.html)
- How are stock options taxed in California? — Secfi (https://secfi.com/learn/how-are-stock-options-taxed-in-california)
- Implement Strategies for Effective NSO Tax Withholding
- Stock Option Taxes in California: ISO, NSO, and RSU Tax Planning for Tech Workers (https://ietaxattorney.com/stock-option-taxes-in-california-iso-nso-and-rsu-tax-planning-for-tech-workers)
- How Stock Options Are Taxed: ISO vs NSO | Darrow Wealth Management (https://darrowwealthmanagement.com/blog/how-are-stock-options-taxed)
- Exercising Stock Options in California: 2026 Tax Guide (https://esofund.com/blog/exercising-stock-options-in-california)
- Equity Compensation Tax Strategies for High Wealth Individuals (https://bradyware.com/equity-compensation-tax-strategies-high-wealth-individuals)
- Stock Option Compensation: Your ‘Cheat Sheet’ for Planning – Monument Wealth Management (https://monumentwealthmanagement.com/resource/stock-option-compensation-your-cheat-sheet-to-planning)
- Utilize Resources and Tools for NSO Tax Management
- StockOpter Equity Compensation Guidance Software for Advisors (https://stockopter.com/stockopter-products/stockopter-com-for-advisors)
- 35 Quotes for Financial Advisors on a Tough Day | Don Connelly & Associates (https://donconnelly.com/35-quotes-for-financial-advisors)
- Stock Option Tax Calculator 2026 | ISO, NSO & RSU (https://yourincomecalculator.com/us/calculators/stock-option-tax)
- Financial Planning for Stock Options San Francisco (https://babylonwealth.com/financial-planning-stock-options)
- The Top 25 Investing Quotes of All Time (https://investopedia.com/financial-edge/0511/the-top-17-investing-quotes-of-all-time.aspx)

Kevin has advised high-income W-2 tech and biotech families since 2015, and leads the education-first Age Five Family Office from Brea, California.
Connect on LinkedIn → · About KevinThis is part of how we approach Tax Management for high-income W-2 families at Bright Advisers.
Keep reading