

Key Highlights
- Passive activity losses (PALs) arise from activities where individuals are not actively involved, such as real estate leasing.
- In 2026, families with a modified adjusted gross income (MAGI) below $100,000 can deduct up to $25,000 in property-related expenses against non-passive income, with the deduction phasing out at $150,000 MAGI.
- Families must track their involvement in rental activities to qualify for material participation, which allows them to deduct significant property expenses against their W-2 income.
- Proactive income management can help families maximise their deductions and reduce tax obligations.
- Strategies to enhance passive loss deductions include maintaining income within phaseout ranges, leveraging cost segregation, and engaging in additional passive activities.
- Material participation requires meeting IRS criteria, such as participating for over 500 hours in a year, to treat leasing losses as non-passive and offset them against ordinary income.
- Families should keep contemporaneous logs of hours worked and tasks performed to substantiate claims for material participation.
Introduction
Imagine feeling confident about your family’s financial future, even as tax regulations change. As tax rules change, especially looking ahead to 2026, families face the challenge of understanding deductions that could affect their taxes. In this article, we’ll share helpful strategies to make the most of passive loss deductions, showing how families can actively manage their income for better financial health.
How can you make sure your family isn’t missing out on important tax savings while juggling investments and income?
Define Passive Activity Losses and Their Importance
Imagine feeling overwhelmed by tax deductions and wondering how they affect your family’s financial future. Passive activity deductions (PADs) can be tricky, especially for families with young children. These deductions arise from activities where you might not be actively involved, like real estate leasing or limited partnerships. Understanding passive activity loss income limitations 2026 can feel daunting, but it’s crucial to know how these deductions can impact your finances.
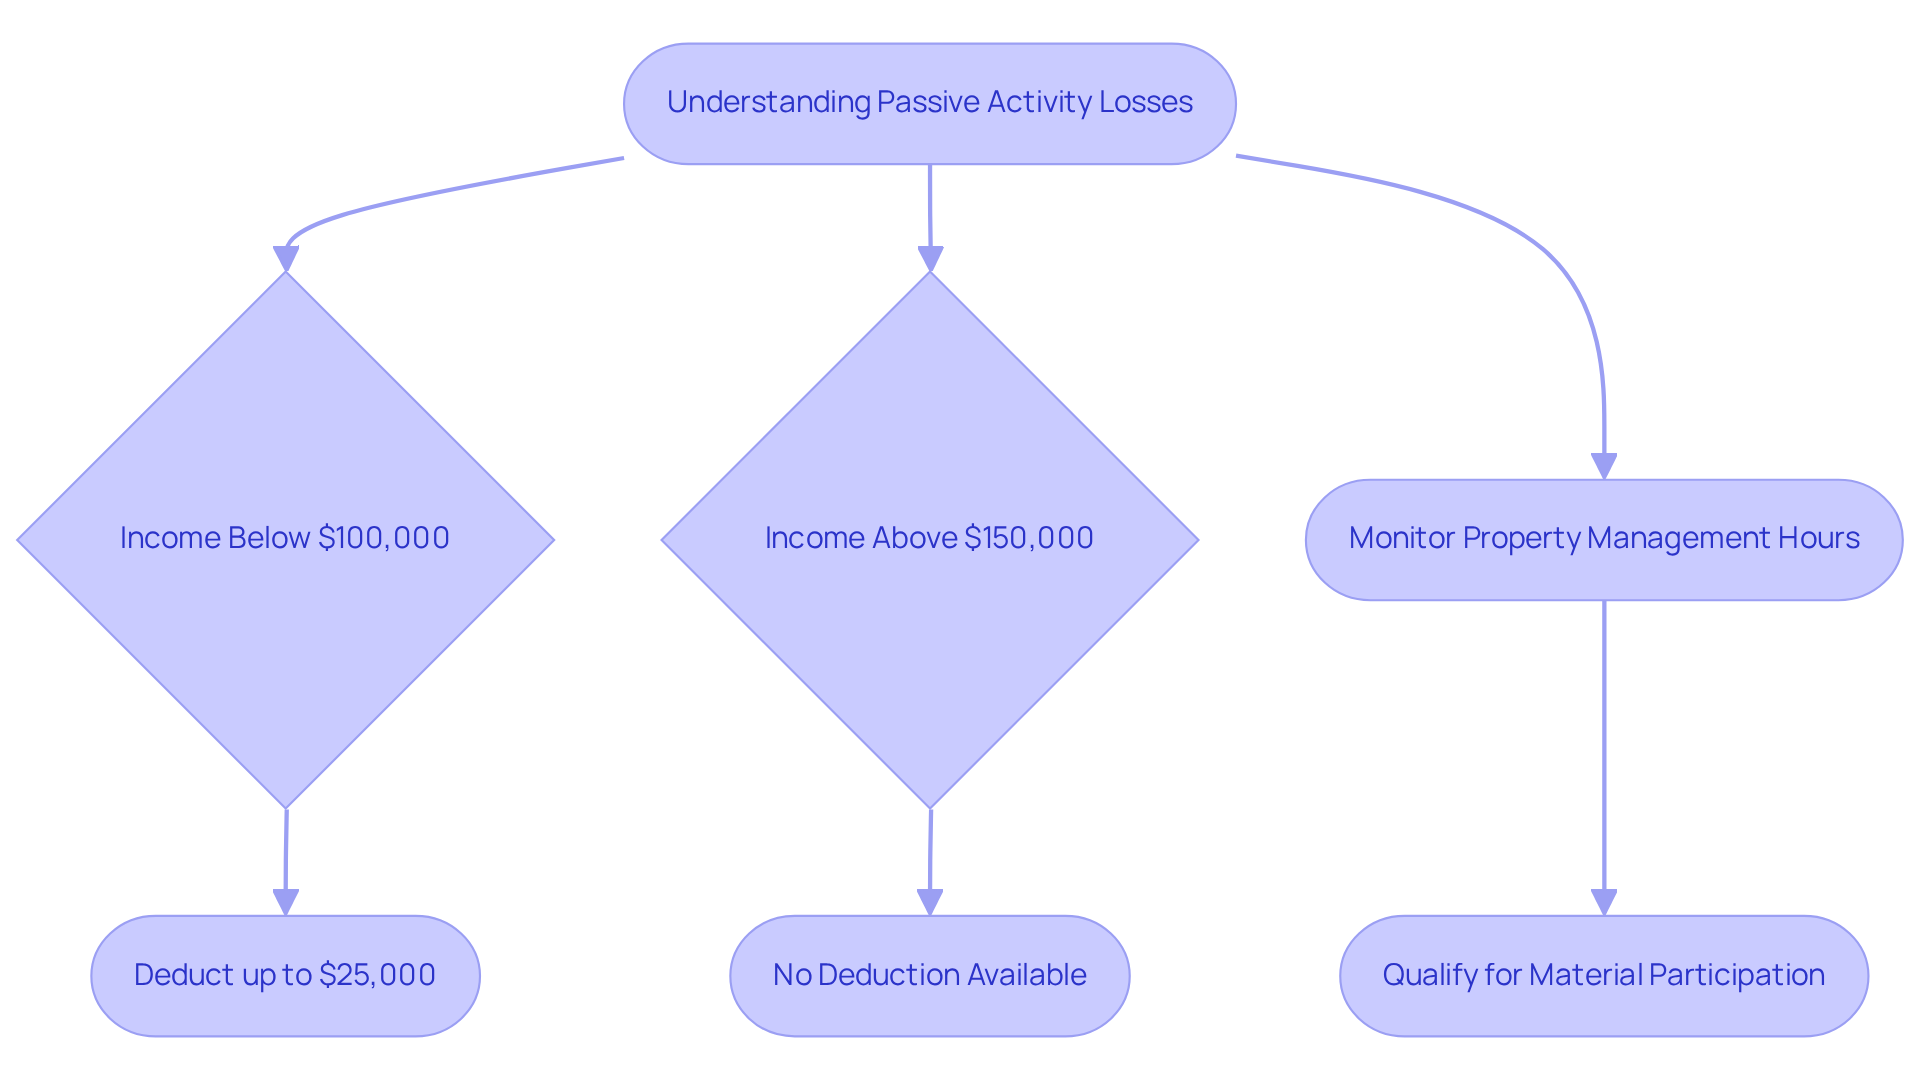
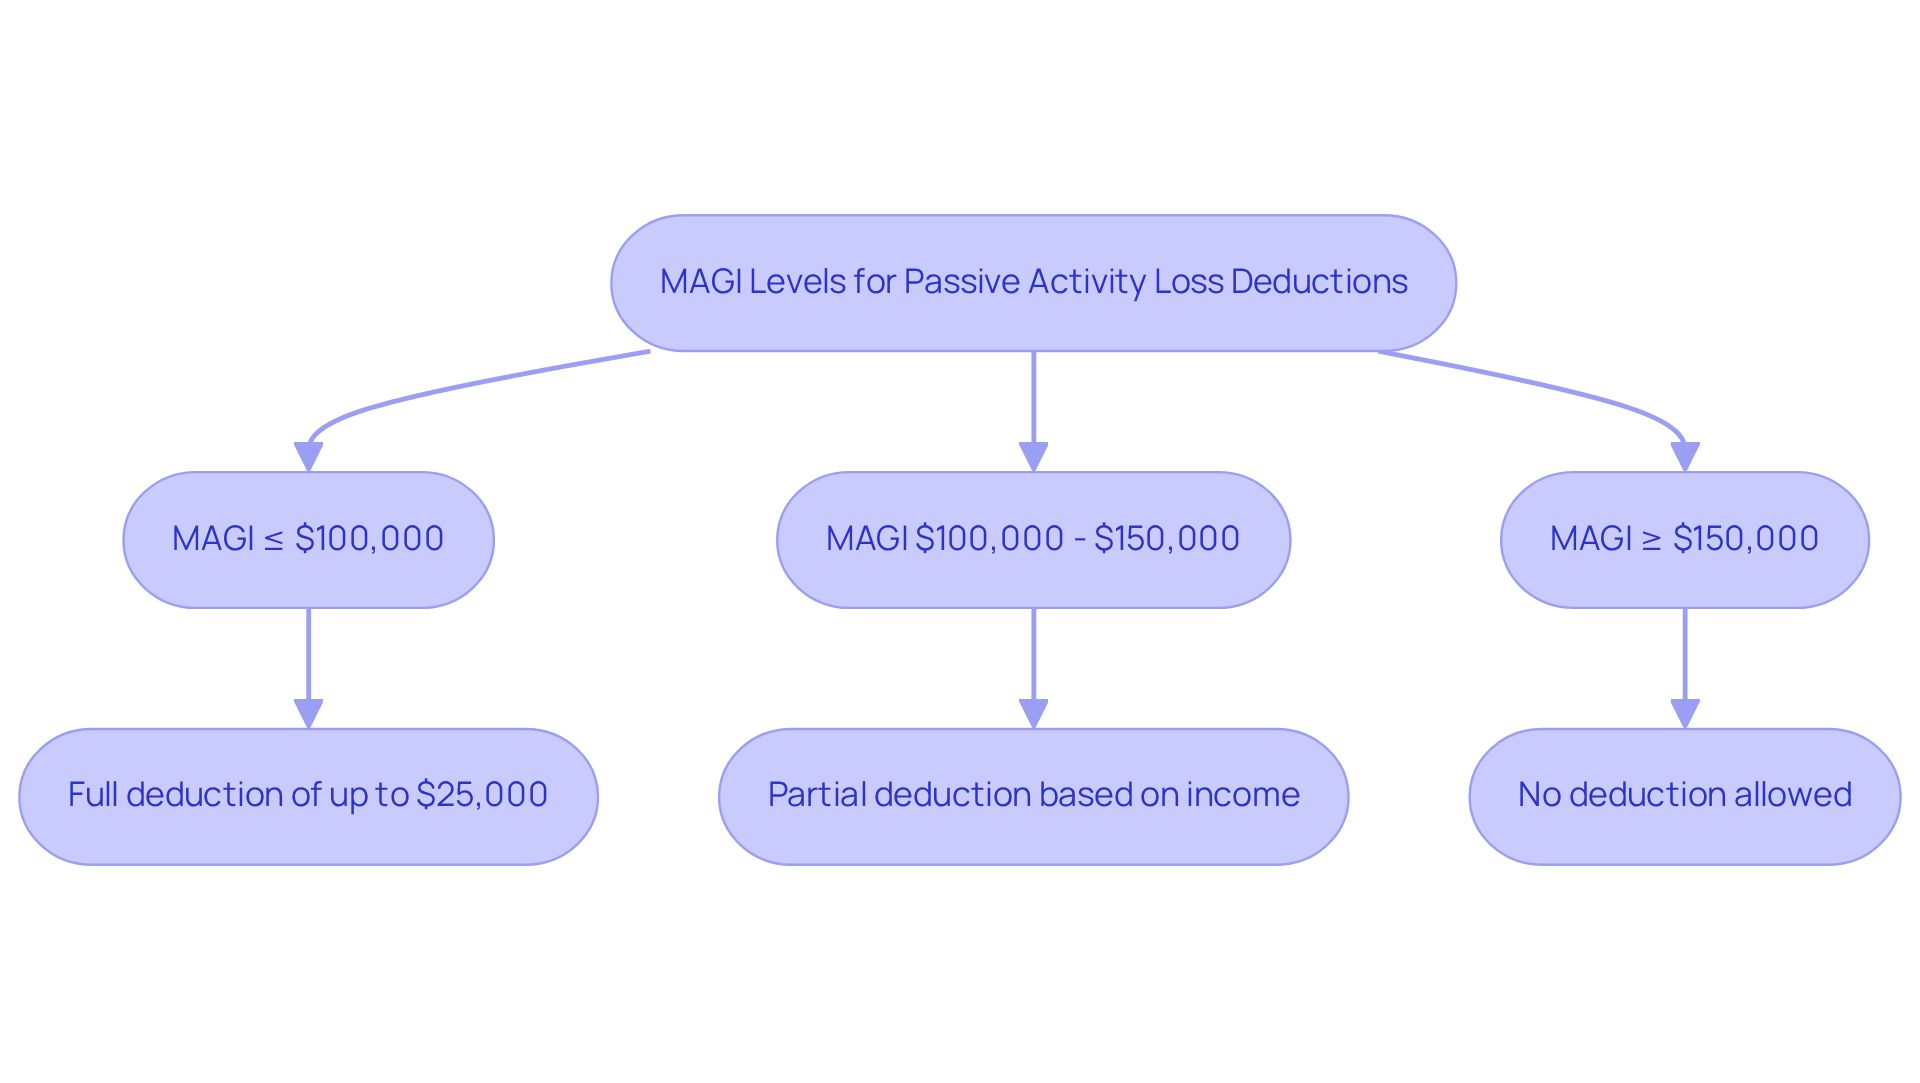
In 2026, families with a modified adjusted gross income (MAGI) below $100,000 can deduct up to $25,000 in property-related expenses against non-passive income, subject to the passive activity loss income limitations 2026. However, this deduction phases out entirely at $150,000 MAGI. It’s important for families to approach financial planning thoughtfully, so they can make the most of these opportunities.
Consider Emily and Mark’s experience with Bright Advisers. They learned how monitoring their property management hours allowed them to qualify for material participation. This meant they could deduct significant property expenses against their W-2 income, even though their MAGI was above the deduction limit.
By recognizing the importance of PALs and keeping track of your involvement in rental activities, families can find ways to enhance their financial situation and make choices that support their long-term goals. With the right support, you can turn these challenges into stepping stones for your family’s financial journey.
Understand Passive Activity Loss Limitations for 2026
Imagine feeling lost in a sea of tax regulations while trying to secure your family’s financial future. For the tax year 2026, the IRS allows taxpayers to deduct up to $25,000 in passive activity loss income limitations 2026 against non-passive income, provided their modified adjusted gross income (MAGI) is $100,000 or less. This means that if your family’s income is between $100,000 and $150,000, you might not be able to take full advantage of this deduction. Households with incomes above these limits may find their ability to utilize passive deductions significantly reduced. For instance, a household with a MAGI of $160,000 can only deduct a portion of their passive losses, as the exemption decreases by $0.50 for every dollar over $150,000, ultimately eliminating the deduction entirely at $200,000.
Understanding the passive activity loss income limitations 2026 is crucial for families like yours, especially if you’re involved in leasing properties or other endeavors that produce passive income. It can be tough to navigate tax deductions, especially when every dollar matters for your family’s needs. Proactive income management can help families maximize their deductions. Take Marcus, for example. He recorded significant involvement in rental pursuits, allowing him to reclassify his deductions and fully offset them against his income, greatly lowering his tax obligation.
It’s important to know that passive income reductions can’t offset regular earnings, like wages, unless specific exceptions apply. For instance, if you qualify as a real estate professional, you can deduct expenses completely, provided you meet the strict requirement of 750 hours of real estate activities each year. This kind of strategic planning can lead to significant tax advantages, making it crucial for families to stay informed about the changing tax environment. Without proper planning, you could miss out on savings that could help your family thrive. Staying informed and proactive can make a world of difference for your family’s financial well-being.
Implement Strategies to Maximize Passive Loss Deductions
Imagine feeling overwhelmed by tax deductions and wondering if you’re missing out on savings that could benefit your family. To enhance passive loss deductions, there are several effective strategies you can consider:
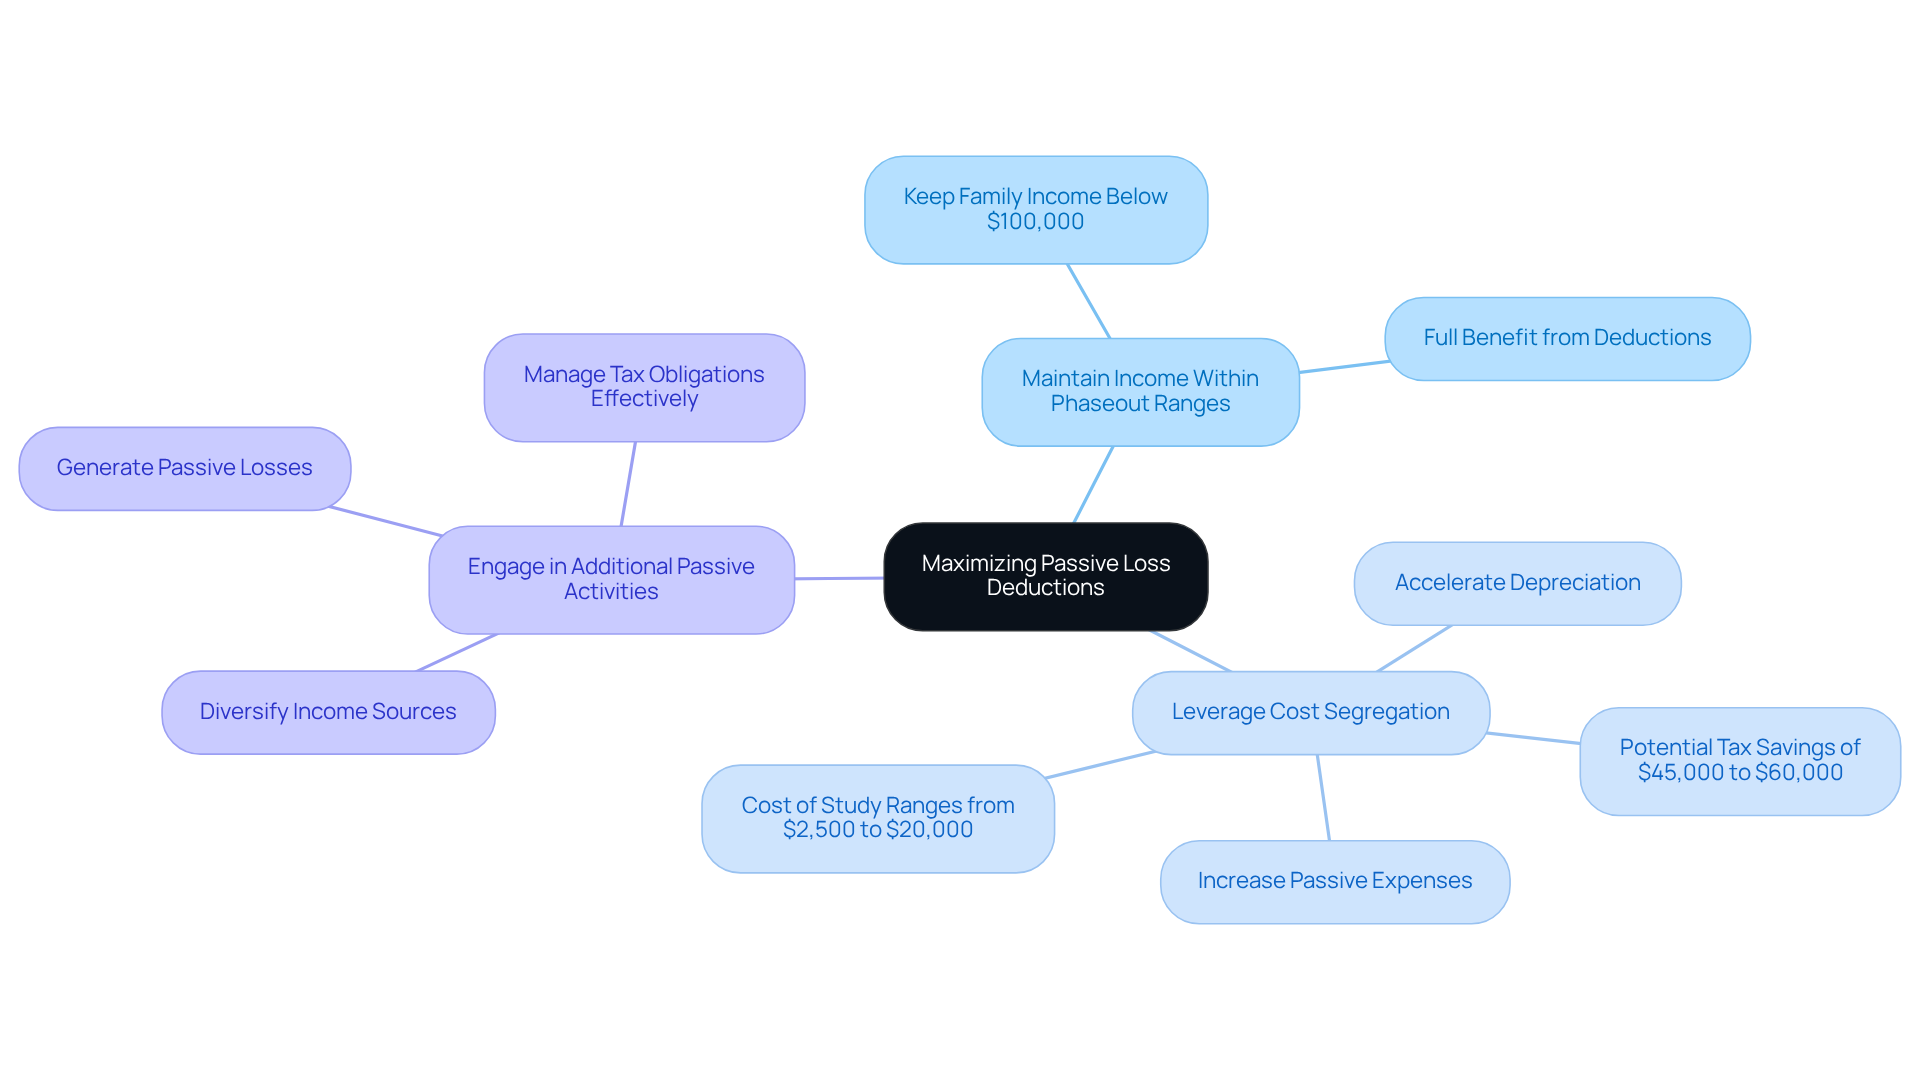
- Maintain Income Within Phaseout Ranges: It’s important to understand that keeping your family’s income below $100,000 can help you fully benefit from valuable deductions, giving you peace of mind during tax season.
- Leverage Cost Segregation: Imagine being able to maximize your tax savings through smart strategies like cost segregation, allowing you to invest more in your family’s future. This approach can significantly accelerate depreciation, increasing your passive expenses and leading to substantial tax savings.
- Engage in Additional Passive Activities: Consider exploring additional passive activities that not only diversify your income but also provide you with more financial freedom to enjoy family moments. By investing in more passive activities, you can create opportunities to generate passive losses that offset passive income, helping you manage your tax obligations more effectively.
By embracing these strategies, you can ease the stress of tax season and focus on what truly matters-your family’s well-being. For example, a residential investment property acquired for $750,000 could provide first-year tax savings of roughly $45,000 to $60,000 through a cost segregation study, illustrating the financial benefits of these strategies. By comprehending and utilizing these techniques, you can navigate the intricacies of passive deduction strategies more efficiently, ensuring your family thrives while navigating the complexities of tax deductions together.
Leverage Material Participation to Enhance Deductions
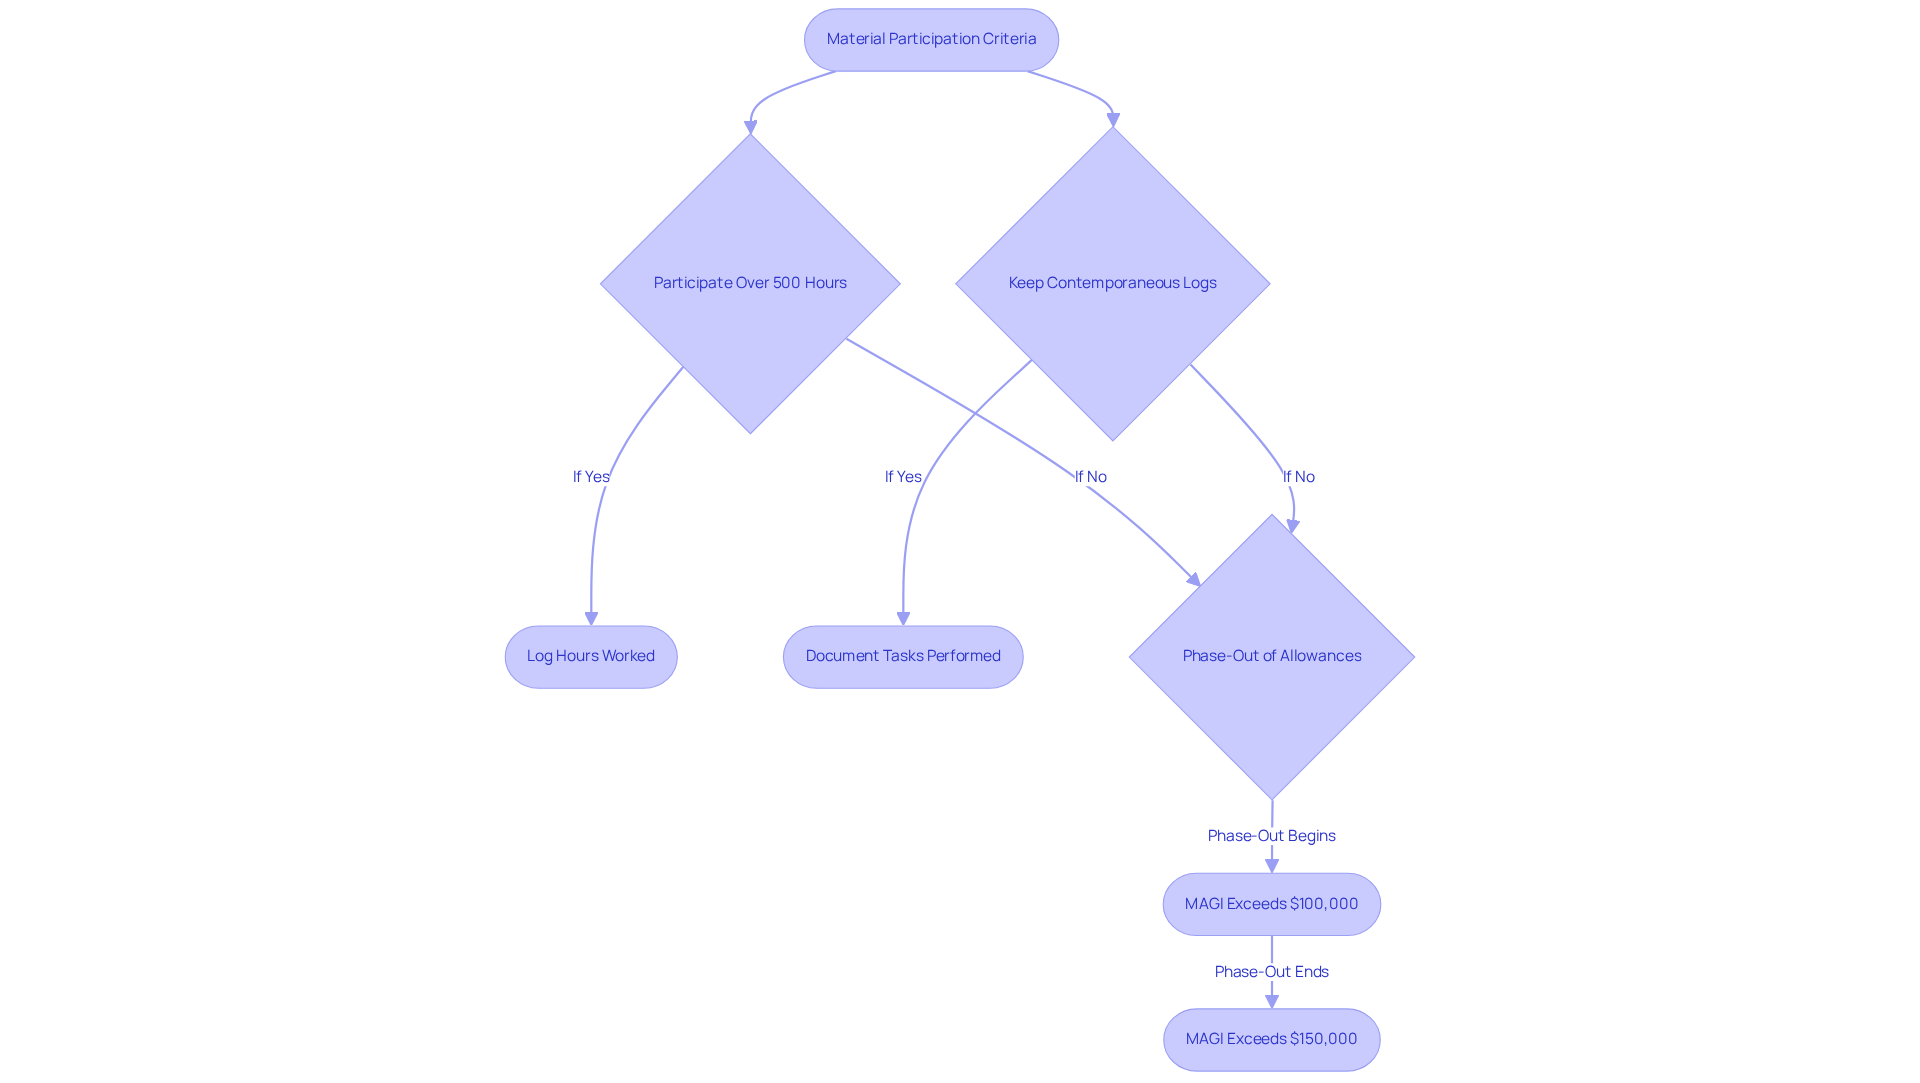
Navigating the world of taxes can be daunting, especially for families trying to make the most of their hard-earned income. Material participation refers to how involved you are in a business or leasing endeavor. To qualify, you need to meet certain IRS tests. For instance, participating for over 500 hours in a year is one way to do this. If you meet these criteria, your family can treat leasing losses as non-passive, which means you can offset these losses against your ordinary income. This can significantly reduce your overall tax liability.
It’s a good idea for families to keep track of their involvement carefully. Consider participating in activities that enhance your engagement in property management. This can help you maximize your tax advantages. Remember, material involvement must be shown for certain leasing endeavors to qualify for non-passive treatment.
As we look ahead to 2026, it’s important to remember that the IRS will still have strict guidelines concerning passive activity loss income limitations. Keeping contemporaneous logs of hours worked and specific tasks performed is crucial to substantiate your claims for material participation. For example, if your household logs over 600 hours of property management tasks, you may qualify for substantial tax deductions, potentially saving thousands in federal taxes.
Also, keep in mind that high earners might face a phase-out of the $25,000 allowance for rental expenses based on modified adjusted gross income (MAGI). By understanding these requirements, families can take control of their financial future and ensure they’re not leaving money on the table.
Conclusion
Navigating tax strategies can feel overwhelming for families, especially with the complexities of passive activity loss limitations looming in 2026. When families understand these deductions, they can feel more confident in making choices that support their financial future. Being able to deduct passive losses can really lighten the financial load for families, especially those involved in real estate or other income-generating activities.
It’s important for families to keep their modified adjusted gross income (MAGI) below $100,000 to fully enjoy the benefits of the $25,000 deduction, along with strategies to maximize their deductions. Families can explore options like cost segregation and ensure they actively participate in their investments to enhance their tax advantages.
Real-life examples, such as Emily and Mark’s proactive approach to property management, show how thoughtful planning can lead to meaningful savings.
By staying informed about passive activity loss limitations, families can feel empowered to take charge of their financial well-being. With the right guidance, families can confidently embrace their financial journey, knowing they have the tools to thrive. Engaging with a fiduciary advisor like Bright Advisers can provide the necessary support to navigate these complexities, ensuring that families make wise wealth decisions and preserve their wealth across generations.
Frequently Asked Questions
What are passive activity losses (PALs)?
Passive activity losses (PALs) are tax deductions that arise from activities in which you are not actively involved, such as real estate leasing or limited partnerships.
Why are passive activity losses important for families?
Understanding passive activity losses is crucial for families as they can significantly impact financial planning and tax deductions, especially for those with young children.
What are the passive activity loss income limitations for 2026?
In 2026, families with a modified adjusted gross income (MAGI) below $100,000 can deduct up to $25,000 in property-related expenses against non-passive income. This deduction phases out entirely at a MAGI of $150,000.
How can families benefit from monitoring their property management hours?
By monitoring their property management hours, families can qualify for material participation, allowing them to deduct significant property expenses against their W-2 income, even if their MAGI exceeds the deduction limit.
What should families consider when planning their finances regarding passive activity losses?
Families should approach financial planning thoughtfully, keeping track of their involvement in rental activities to enhance their financial situation and support long-term goals.
List of Sources
- Define Passive Activity Losses and Their Importance
- Passive Activity Loss Rules 2026: How Real Estate Investors Can Maximize Deductions – Uncle Kam (https://unclekam.com/tax-strategy-blog/passive-activity-loss-rules)
- IRS Form 8582: Calculating Passive Activity Losses for Real Estate (https://turbotax.intuit.com/tax-tips/rental-property/irs-form-8582-calculating-passive-activity-losses-for-real-estate/c71Jm0iM7)
- Avoiding passive loss limitations on rental real estate losses (https://thetaxadviser.com/issues/2024/jul/avoiding-passive-loss-limitations-on-rental-real-estate-losses)
- Navigating Rental Loss Rules (https://bradyware.com/navigating-rental-loss-rules)
- Passive Activity Loss (PAL) Rules: IRS Limits on Deducting Passive Losses (https://nolo.com/legal-encyclopedia/passive-activity-loss-pal-rules-irs-limits-deducting-passive-losses.html)
- Understand Passive Activity Loss Limitations for 2026
- 2026 Passive Loss Limitation Changes: A Complete Guide for Real Estate Investors & Business Owners – Uncle Kam (https://unclekam.com/tax-strategy-blog/2026-passive-loss-limitation-changes-a-complete-guide-for-real-estate-investors-business-owners)
- Passive Activity Loss Limits (https://wcginc.com/kb-rental-property/passive-activity-loss-limits)
- Avoiding passive loss limitations on rental real estate losses (https://thetaxadviser.com/issues/2024/jul/avoiding-passive-loss-limitations-on-rental-real-estate-losses)
- Understanding Passive Activity Loss Limitations (https://taxslayerpro.com/blog/post/understanding-passive-loss-limitations)
- Passive activity loss: Overview and FAQs (https://tax.thomsonreuters.com/en/glossary/passive-activity-loss)
- Implement Strategies to Maximize Passive Loss Deductions
- Cost Segregation Study for Rental Property (2026 Guide) (https://baselane.com/resources/cost-segregation-study-rental-property)
- Cost Segregation Study for Rental Properties: Complete Guide for 2026 (https://cssiservices.com/cost-segregation-for-rental-properties)
- Mastering Passive Activity Losses & Maximizing Tax Savings – Aprio (https://aprio.com/insights-events/mastering-passive-activity-losses-maximizing-tax-savings-ins-article-tax)
- What is a Cost Segregation Study? How It Works and Why It Matters) (https://warrenaverett.com/insights/what-is-cost-segregation)
- Avoiding passive loss limitations on rental real estate losses (https://thetaxadviser.com/issues/2024/jul/avoiding-passive-loss-limitations-on-rental-real-estate-losses)
- Leverage Material Participation to Enhance Deductions
- How LLP and LLC Owners Can Qualify for Material Participation and Maximize Tax Deductions – Thomas Howell Ferguson (https://thf.cpa/2026/06/09/how-llp-and-llc-owners-can-qualify-for-material-participation-and-maximize-tax-deductions)
- Rental Property Tax Rules: Active vs Material Participation and Passive Income Explained – Anders (https://anderscpa.com/learn/blog/rental-property-income-tax-why-active-or-material-participation-matters)
- The Landlord’s Guide to Material Participation, Offsetting PAL Limitations, and Unlocking Tax Savings (https://turbotenant.com/accounting/material-participation)
- What Does Material Participation Mean? The 7 Tests | Taxstra (https://taxstra.com/tax-questions/material-participation)
- Material Participation: Your Complete Guide to Unlocking Business Loss Deductions (https://cssiservices.com/material-participation-guide)

Kevin has advised high-income W-2 tech and biotech families since 2015, and leads the education-first Age Five Family Office from Brea, California.
Connect on LinkedIn → · About KevinThis is part of how we approach Age Five Wealth Education for high-income W-2 families at Bright Advisers.
Keep reading