

Key Highlights
- Understanding portfolio risk allocation is crucial for young parents to secure their family’s financial future.
- Assessing risk tolerance helps determine the right mix of investments, typically around 60% stocks, 30% bonds, and 10% real estate or commodities.
- Different asset classes have unique risk-return profiles; stocks offer higher returns but greater volatility, while bonds provide stability.
- Investment goals should align with portfolio risk allocation, such as saving for children’s education or retirement.
- A longer investment time horizon allows for a higher risk tolerance, while a shorter horizon necessitates a more conservative approach.
- Diversification strategies include asset class, sector, and geographic diversification to mitigate risks.
- Regular portfolio reviews and rebalancing are essential to maintain desired asset allocation and adapt to market changes.
- Advanced investment techniques like factor investing, smart beta strategies, and tax-loss harvesting can enhance returns and manage risks.
Introduction
Many young parents feel the pressure of balancing their family’s needs with financial planning. Navigating the world of investment risks is a crucial step toward safeguarding their family’s future. In this article, we’ll explore how families can manage investment risks effectively, focusing on simple strategies like:
- Diversification
- The importance of regular check-ins on their portfolios
How can families feel confident navigating the complexities of investment while reaching their financial goals? The answers are in learning and applying these essential strategies together.
Understand Portfolio Risk Allocation Fundamentals
Imagine the weight of ensuring your family’s financial security while juggling daily responsibilities. It can feel overwhelming, can’t it? Understanding how to spread your investments across different areas can help you find a balance between potential gains and the risks that come with them.
As a young parent, grasping this concept is vital for safeguarding your family’s financial future. Let’s explore some key ideas together.
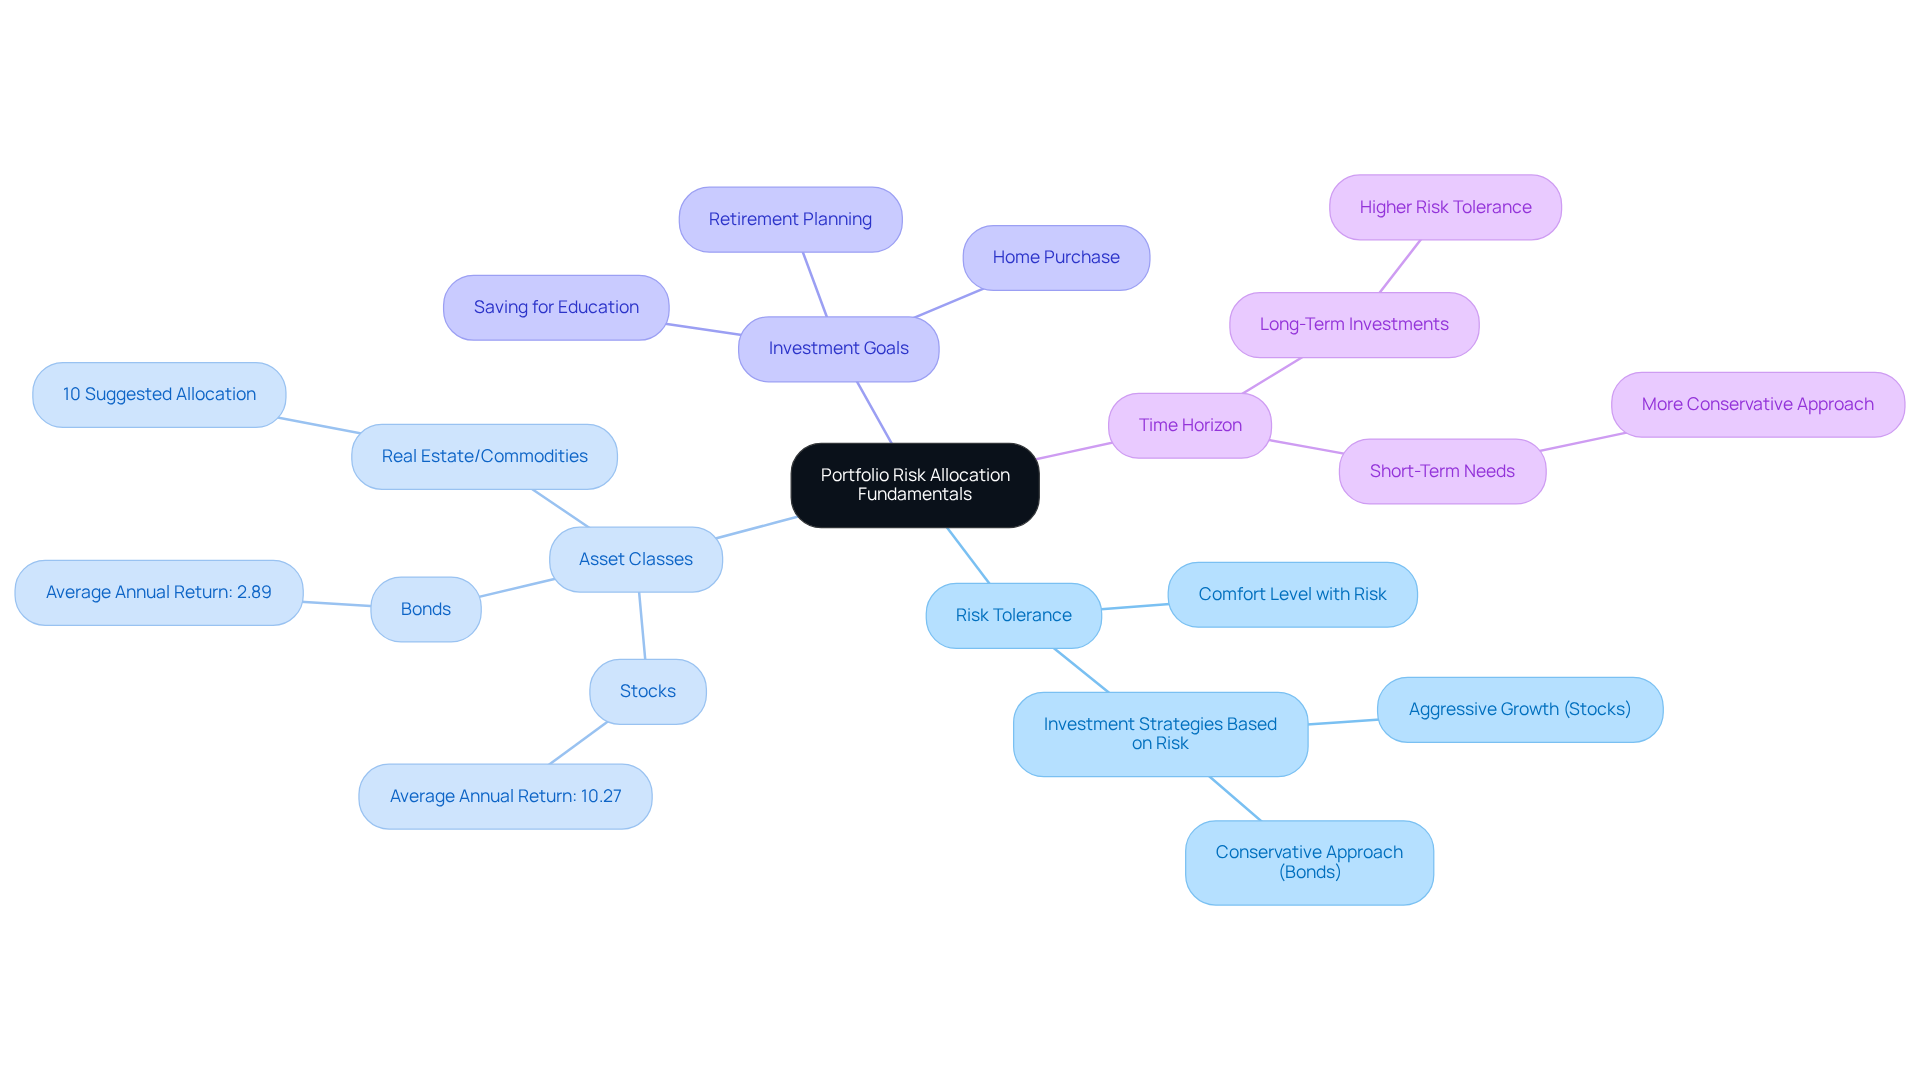
- Define Risk Tolerance: Assess your comfort level with risk, which can vary based on your financial situation, investment goals, and time horizon. For example, many young families find comfort in investing more in stocks for growth while keeping some bonds for that extra layer of security. Many experts suggest that a good mix for young families might be around 60% in stocks for growth, 30% in bonds for stability, and 10% in real estate or commodities for diversification.
- Asset Classes: Familiarize yourself with different asset classes such as stocks, bonds, and real estate. Each class has its own risk-return profile. Stocks generally offer higher returns but come with greater volatility, while bonds provide more stability but lower returns. Historically, stocks have averaged annual returns of approximately 10.27% over the past 30 years, making them attractive for households willing to take risks.
- Investment Goals: Clearly define your objectives, whether it’s saving for your children’s education, retirement, or a home. Aligning your portfolio risk allocation with these goals will guide your decisions. For instance, households frequently invest for their children through custodial accounts, which can act as a proactive method for teaching about money.
- Time Horizon: Consider how long you plan to invest. A longer time horizon allows for a higher risk tolerance, as you can ride out market fluctuations. Conversely, if you need access to funds in the short term, a more conservative approach may be warranted. The less time you have to invest, the more conservative your asset allocation should be.
By understanding these basics, you can make choices that truly reflect your family’s financial goals and comfort with risk. Consistently tracking your portfolio performance and adjusting as needed will help ensure that your assets remain aligned with your financial objectives. Together, we can navigate this journey toward a secure future for your family.
Implement Diversification Strategies for Enhanced Stability
As a young parent, the thought of securing your family’s financial future can feel overwhelming, but it doesn’t have to be. Diversification is a key strategy that can aid in portfolio risk allocation by spreading your resources across different asset classes and sectors, helping to ease those worries. Here are some effective strategies for young parents, brought to you by Bright Advisers, an Age Five Family Office dedicated to helping families make wise wealth decisions:
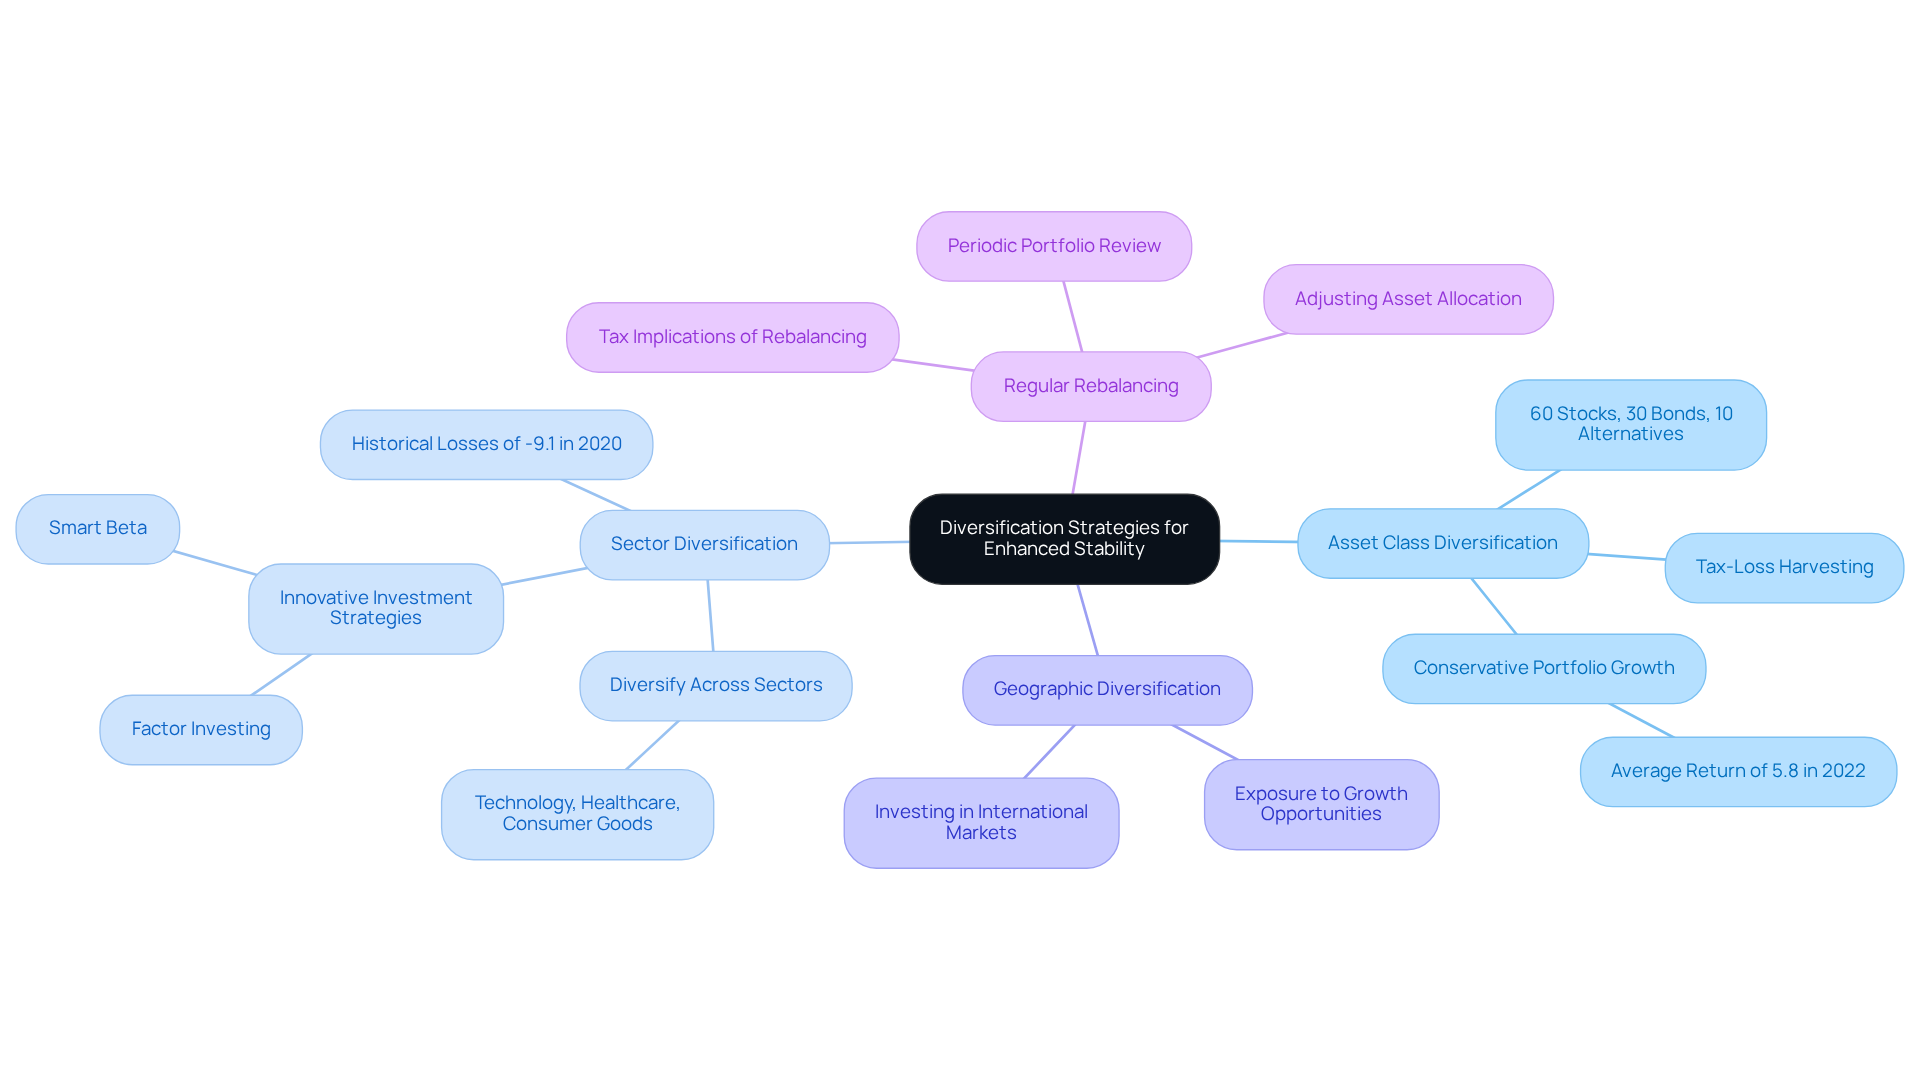
- Asset Class Diversification: Distributing your resources among different asset categories like stocks, bonds, and real estate can provide a safety net. A common approach for young families is to maintain a mix of 60% stocks, 30% bonds, and 10% in alternative investments like real estate or commodities. This balance in portfolio risk allocation can help provide a cushion against market downturns. For instance, the Conservative Portfolio showed consistent growth with an average return of 5.8% in 2022. Plus, tax-loss harvesting strategies can enhance your overall returns by offsetting gains with losses.
- Sector Diversification: Within your stock allocation, it’s wise to diversify across different sectors, such as technology, healthcare, and consumer goods. This approach lessens the impact of poor performance in any single sector on your overall investment. Historical data shows that diversified investment collections experienced peak losses of -9.1% in 2020, underscoring the importance of portfolio risk allocation across sectors. Bright Advisers uses innovative investment strategies, including factor investing and smart beta, to optimize sector exposure.
- Geographic Diversification: Don’t forget about international markets! Investing globally can provide exposure to growth opportunities outside your home country, which can be especially beneficial during times of domestic economic uncertainty. For example, investing in underperforming asset classes can position you to gain when those classes recover, enhancing your overall investment resilience.
- Regular Rebalancing: It’s important to periodically review and adjust your portfolio to maintain your desired asset allocation. This practice ensures that you aren’t overly exposed to any one asset class due to market fluctuations. Regular rebalancing is recommended, either on a set schedule or based on significant changes in asset class weightings, to ensure your portfolio risk allocation aligns with your financial goals. Just be mindful of possible tax consequences when rebalancing, particularly in taxable accounts, as this can influence your overall financial strategy.
Imagine the peace of mind that comes from knowing your family’s financial future is secure, and let us help you achieve that together. If you’re interested in personalized financial planning, consider joining our waitlist at Bright Advisers to learn more about how we can assist you in building a secure financial future.
Leverage Advanced Investment Techniques for Optimal Returns
Imagine feeling secure about your family’s financial future, even amidst the chaos of parenting. Let’s explore some thoughtful strategies that can help you feel more confident in your financial journey:
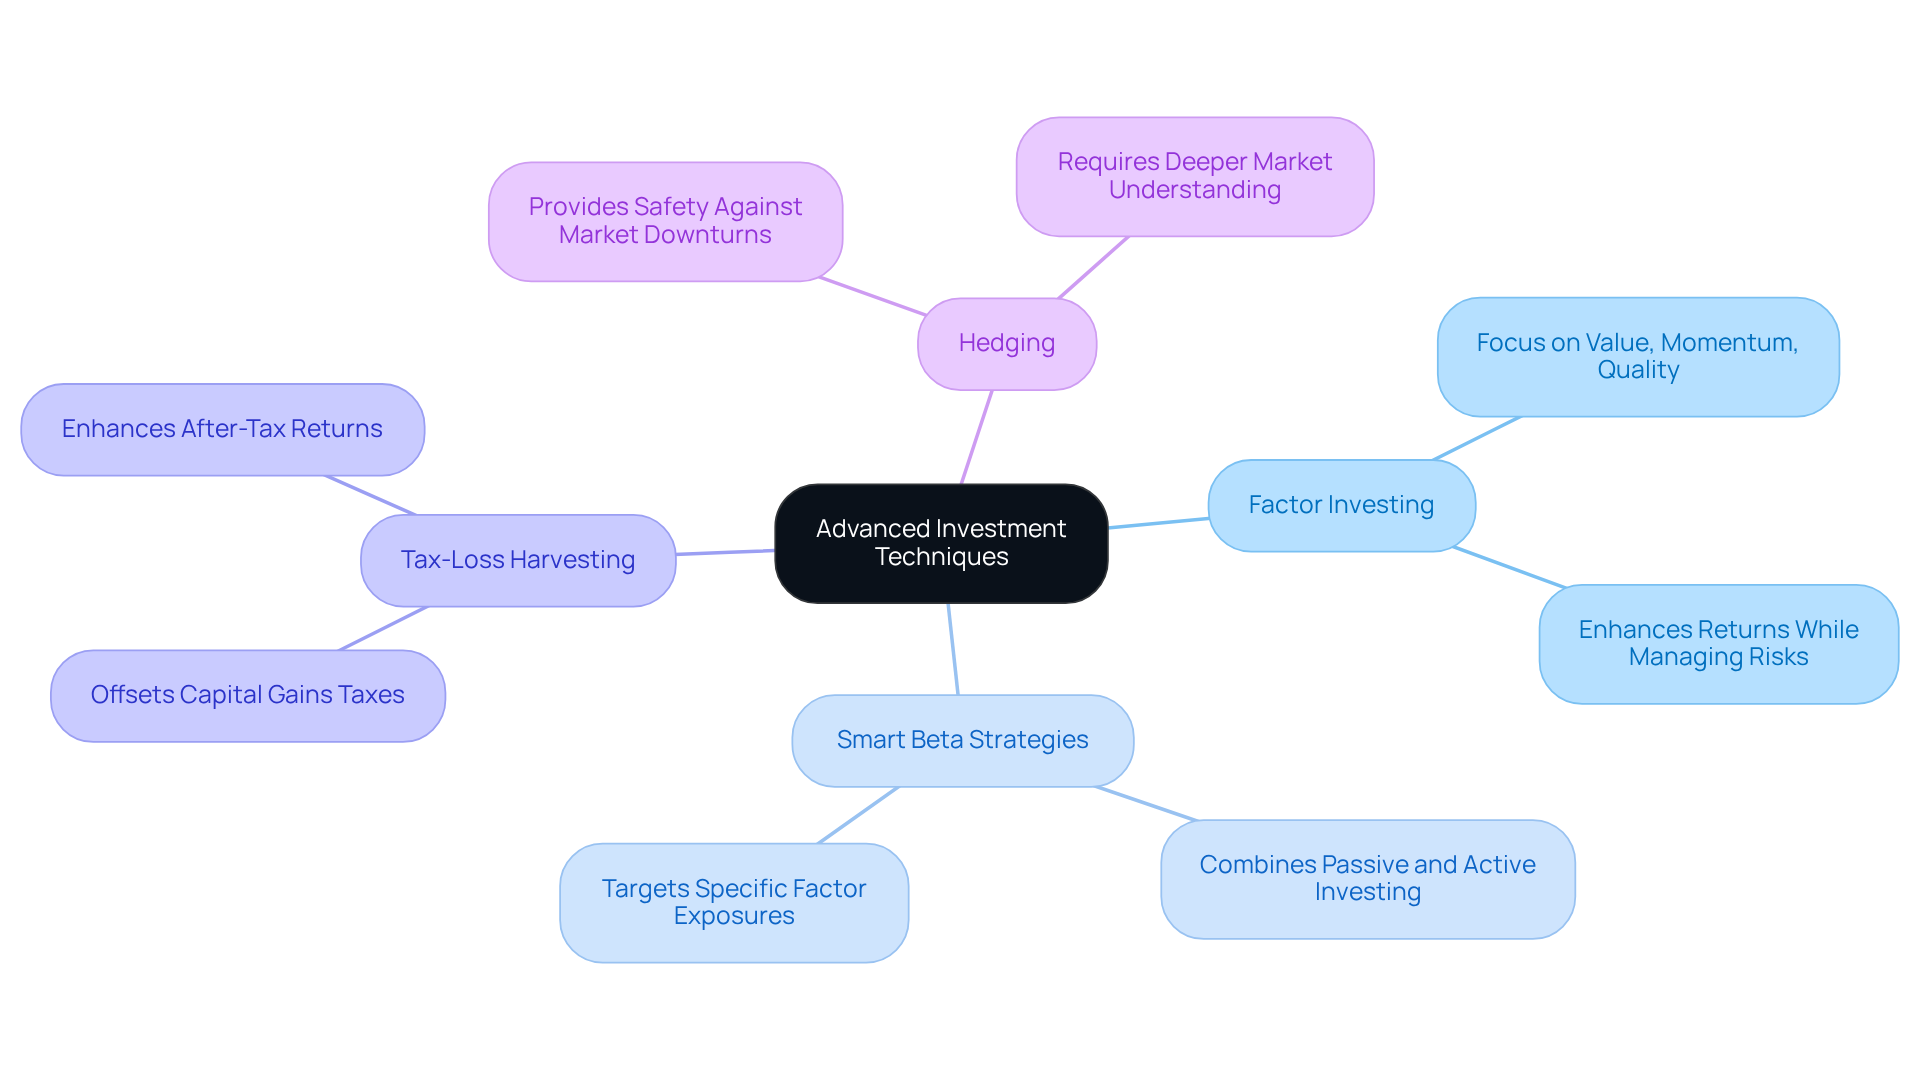
- Factor Investing: This approach focuses on specific drivers of return, like value, momentum, or quality. By honing in on these factors, you might enhance your returns while keeping risks in check. For instance, investing in value stocks could lead to better long-term growth compared to growth stocks during certain market conditions.
- Smart Beta Strategies: Smart beta combines elements of passive and active investing, using alternative weighting methods to boost returns. This strategy can help you achieve better risk-adjusted returns than traditional market-cap-weighted indices, making it a valuable tool for your portfolio risk allocation.
- Tax-Loss Harvesting: This technique involves selling underperforming assets to offset capital gains taxes. By strategically realizing losses, you can enhance your after-tax returns, which is especially beneficial if you’re a high-income earner.
- Hedging: Using options or other derivatives can provide a safety net against potential market downturns. While this approach requires a deeper understanding of the market, it can protect your financial activities during turbulent times.
By embracing these strategies, you can enhance your family’s financial health and create a more secure future for your loved ones. Understanding these strategies allows you to navigate the complexities of investing while focusing on what truly matters: providing for your children.
Conduct Regular Portfolio Reviews and Adjustments
Many families find it challenging to keep their investments on track amidst life’s changes. Regular investment reviews can help. Here’s how to conduct effective portfolio reviews that resonate with your family’s needs:
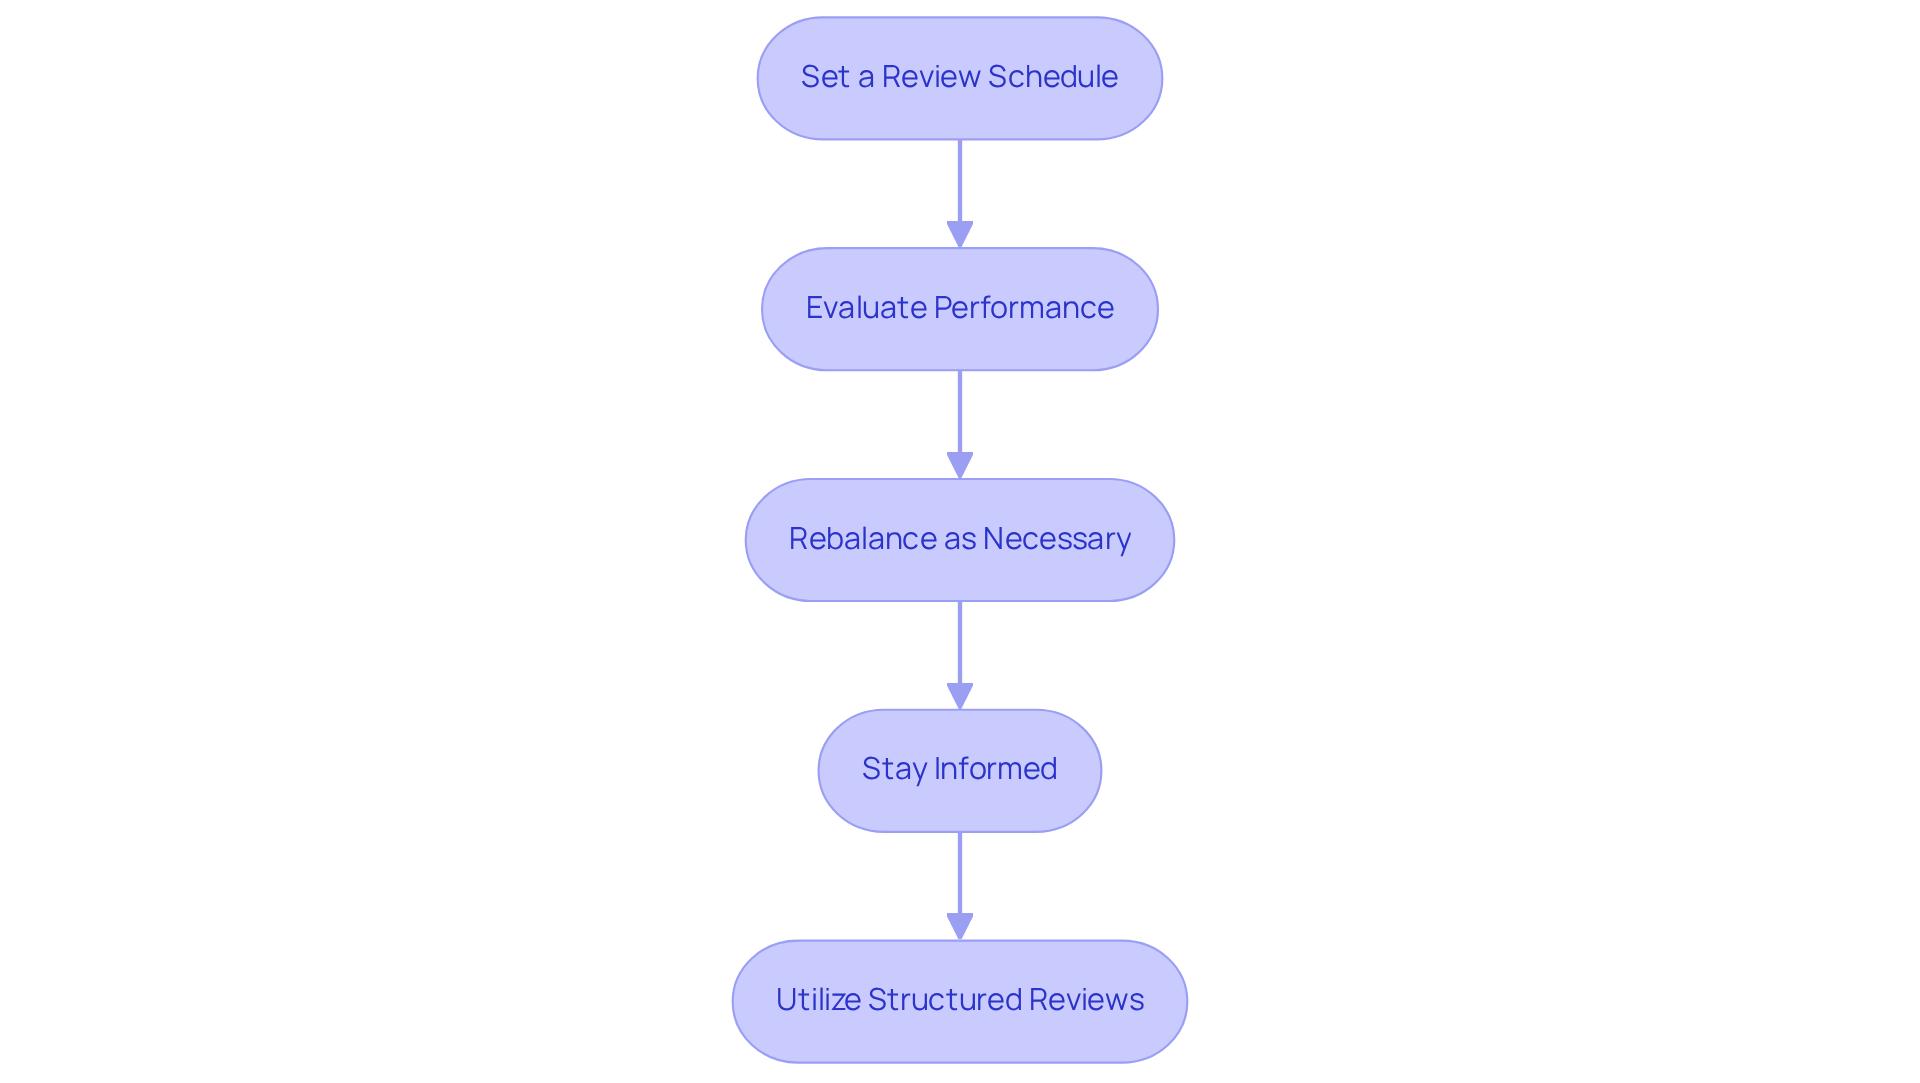
- Set a Review Schedule: Establish a consistent schedule for portfolio reviews, ideally quarterly or bi-annually. This regularity helps families stay informed about their assets and make timely adjustments as needed.
- Evaluate Performance: During each review, take a moment to assess how your assets are performing relative to your financial objectives. Are you on track to meet your goals? If not, it’s important to identify the reasons and consider adjustments to your asset allocation to better align with your targets.
- Rebalance as Necessary: Market fluctuations can cause your portfolio to drift from its target allocation. Rebalancing means buying or selling assets to restore your desired portfolio risk allocation, ensuring that your holdings maintain the intended level of risk and return.
- Stay Informed: Keep up with market trends and economic conditions that could affect your financial assets. Understanding the broader economic landscape can guide your decisions during portfolio reviews.
- Utilize Structured Reviews: Families can benefit from structured reviews that include evaluations of asset allocation, risk tolerance, and tax implications. Regular evaluations help recognize changes in performance and ensure alignment with long-term objectives related to portfolio risk allocation. Incorporating tax strategies can further enhance your planning.
Statistics indicate that a target allocation of 60% stocks and 40% bonds is common, but this may shift based on market performance. For instance, after a year of strong stock market growth, equity exposure might rise to 70%. Regular reviews help manage these changes effectively.
By taking these steps, you’re not just managing your wealth; you’re building a legacy for your family.
Conclusion
Imagine feeling confident about your family’s financial future, even amidst the uncertainties of life. Understanding how to allocate your portfolio effectively is essential for young parents like you, who want to secure a bright future for their loved ones. By grasping the basics of risk tolerance, asset classes, investment goals, and time horizons, you can create a balanced investment strategy that truly reflects your family’s unique needs and aspirations.
Consider this: Diversifying across different asset classes, sectors, and geographies can significantly enhance your portfolio’s stability and potential returns. Techniques like factor investing and smart beta can also play a vital role in your financial journey. Regularly reviewing and adjusting your portfolio ensures that your investments stay aligned with your evolving financial goals, allowing you to adapt to market changes and personal circumstances.
Together, we can navigate the complexities of investing, ensuring a legacy that your children will cherish. By prioritizing informed decision-making and proactive management, you can approach financial security with confidence. Taking that first step today can pave the way for a secure and prosperous tomorrow for your family. Engaging with Bright Advisers can provide the guidance you need to make wise wealth decisions, ensuring a brighter financial future for your loved ones.
Frequently Asked Questions
What is risk tolerance in the context of portfolio risk allocation?
Risk tolerance refers to your comfort level with investment risks, which can vary based on your financial situation, investment goals, and time horizon. For young families, a common approach is to invest around 60% in stocks for growth, 30% in bonds for stability, and 10% in real estate or commodities for diversification.
What are the different asset classes mentioned in the article?
The article discusses three main asset classes: stocks, bonds, and real estate. Stocks typically offer higher returns but come with greater volatility, while bonds provide more stability but lower returns. Real estate can also be included for diversification.
How should investment goals influence portfolio risk allocation?
Clearly defining your investment objectives, such as saving for children’s education, retirement, or a home, is crucial. Aligning your portfolio risk allocation with these goals will guide your investment decisions and strategies.
Why is the time horizon important when considering investments?
The time horizon affects your risk tolerance. A longer time horizon allows for a higher risk tolerance since you can endure market fluctuations. Conversely, if you need access to funds in the short term, a more conservative investment approach is advisable.
How can families ensure their investments align with their financial goals?
By understanding the basics of risk tolerance, asset classes, investment goals, and time horizons, families can make informed choices. Regularly tracking portfolio performance and making adjustments as needed will help keep assets aligned with financial objectives.
List of Sources
- Understand Portfolio Risk Allocation Fundamentals
- Investing Fundamentals For Young Adults: Asset Allocation (https://forbes.com/sites/halseyschreier/2020/05/15/investing-fundamentals-for-young-adults-asset-allocation)
- 5 Steps on How to Diversify My Portfolio for Young Parents – Bright Advisers (https://brightadvisers.com/post/5-steps-on-how-to-diversify-my-portfolio-for-young-parents)
- What is the average asset allocation by age? (https://empower.com/the-currency/money/average-portfolio-mix-by-investor-age)
- A Simple guide to asset allocation for family (https://andsimple.co/guides/family-office-asset-allocation)
- Implement Diversification Strategies for Enhanced Stability
- Don’t Put All Your Eggs (investments) in one Basket! (https://citizensbank.com/learning/why-diversification-is-important.aspx)
- (PDF) Evaluating the Efficiency of Portfolio Diversification Strategies Using Statistical Correlation Metrics (https://researchgate.net/publication/389069850_Evaluating_the_Efficiency_of_Portfolio_Diversification_Strategies_Using_Statistical_Correlation_Metrics)
- The Top 25 Investing Quotes of All Time (https://investopedia.com/financial-edge/0511/the-top-17-investing-quotes-of-all-time.aspx)
- Asset Allocation and Diversification (https://finra.org/investors/investing/investing-basics/asset-allocation-diversification)
- Beginners’ Guide to Asset Allocation, Diversification, and Rebalancing | Investor.gov (https://investor.gov/additional-resources/general-resources/publications-research/info-sheets/beginners-guide-asset)
- Leverage Advanced Investment Techniques for Optimal Returns
- The 11 Best Quotes About Investing (https://anewadvisors.com/blog/the-11-best-quotes-about-investing)
- What are smart beta strategies? A guide to factor-based investing (https://home.saxo/learn/guides/diversification/what-are-smart-beta-strategies-a-guide-to-modern-diversification)
- What is factor investing? | BlackRock (https://blackrock.com/us/individual/investment-ideas/what-is-factor-investing)
- How is factor investing key to a stable investment portfolio? | J.P. Morgan Private Bank EMEA EN (https://privatebank.jpmorgan.com/eur/en/insights/markets-and-investing/how-is-factor-investing-key-to-a-stable-investment-portfolio)
- Conduct Regular Portfolio Reviews and Adjustments
- Evaluating Performance (https://finra.org/investors/investing/investing-basics/evaluating-performance)
- 3 Tips for Evaluating Portfolio Performance (https://raymondjames.com/haycraft/learn-blog/haycraft-ed-financial-advice-blog/2022/07/05/3-tips-for-evaluating-portfolio-performance)
- How Often Should My Investment Portfolio Be Reviewed? – Towerpoint Wealth (https://towerpointwealth.com/how-often-should-my-investment-portfolio-be-reviewed)
- A Year-End Portfolio Review for 2024 (https://morningstar.com/portfolios/year-end-portfolio-review-7-easy-steps)

Kevin has advised high-income W-2 tech and biotech families since 2015, and leads the education-first Age Five Family Office from Brea, California.
Connect on LinkedIn → · About KevinThis is part of how we approach Investment & Risk Management for high-income W-2 families at Bright Advisers.
Keep reading