

Key Highlights
- Restricted Stock Units (RSUs) are shares granted by employers as part of compensation, vesting after a set period or performance goals.
- RSUs can significantly impact family finances, aiding in budgeting and long-term savings, such as funding education or vacations.
- Understanding RSU vesting schedules is crucial for managing cash flow and preparing for tax obligations associated with vested shares.
- Families can face unexpected tax bills upon RSU vesting, necessitating strategies like ‘sell-to-cover’ to manage cash flow effectively.
- Diversification strategies are essential for families with significant net worth tied to employer stock, reducing concentration risk.
- RSUs are generally lower risk compared to stock options, as they hold intrinsic value upon vesting, while stock options may become worthless.
- Tax implications differ between RSUs and stock options, with RSUs taxed as ordinary income at vesting and stock options potentially qualifying for capital gains treatment.
- Bright Advisers emphasises fiduciary duty and transparency, helping families navigate RSU finance and optimise their financial strategies.
Introduction
Imagine feeling confident about your family’s financial future, even amidst the complexities of Restricted Stock Units (RSUs). As RSUs become a part of many compensation packages, it’s essential for young families to navigate their complexities with care and understanding.
How can you manage these assets to boost your family’s cash flow today while also securing your long-term dreams? In this article, we’ll explore strategies to help you master RSU finance, empowering your family to make informed choices for a brighter tomorrow.
Define Restricted Stock Units (RSUs) and Their Importance for Families
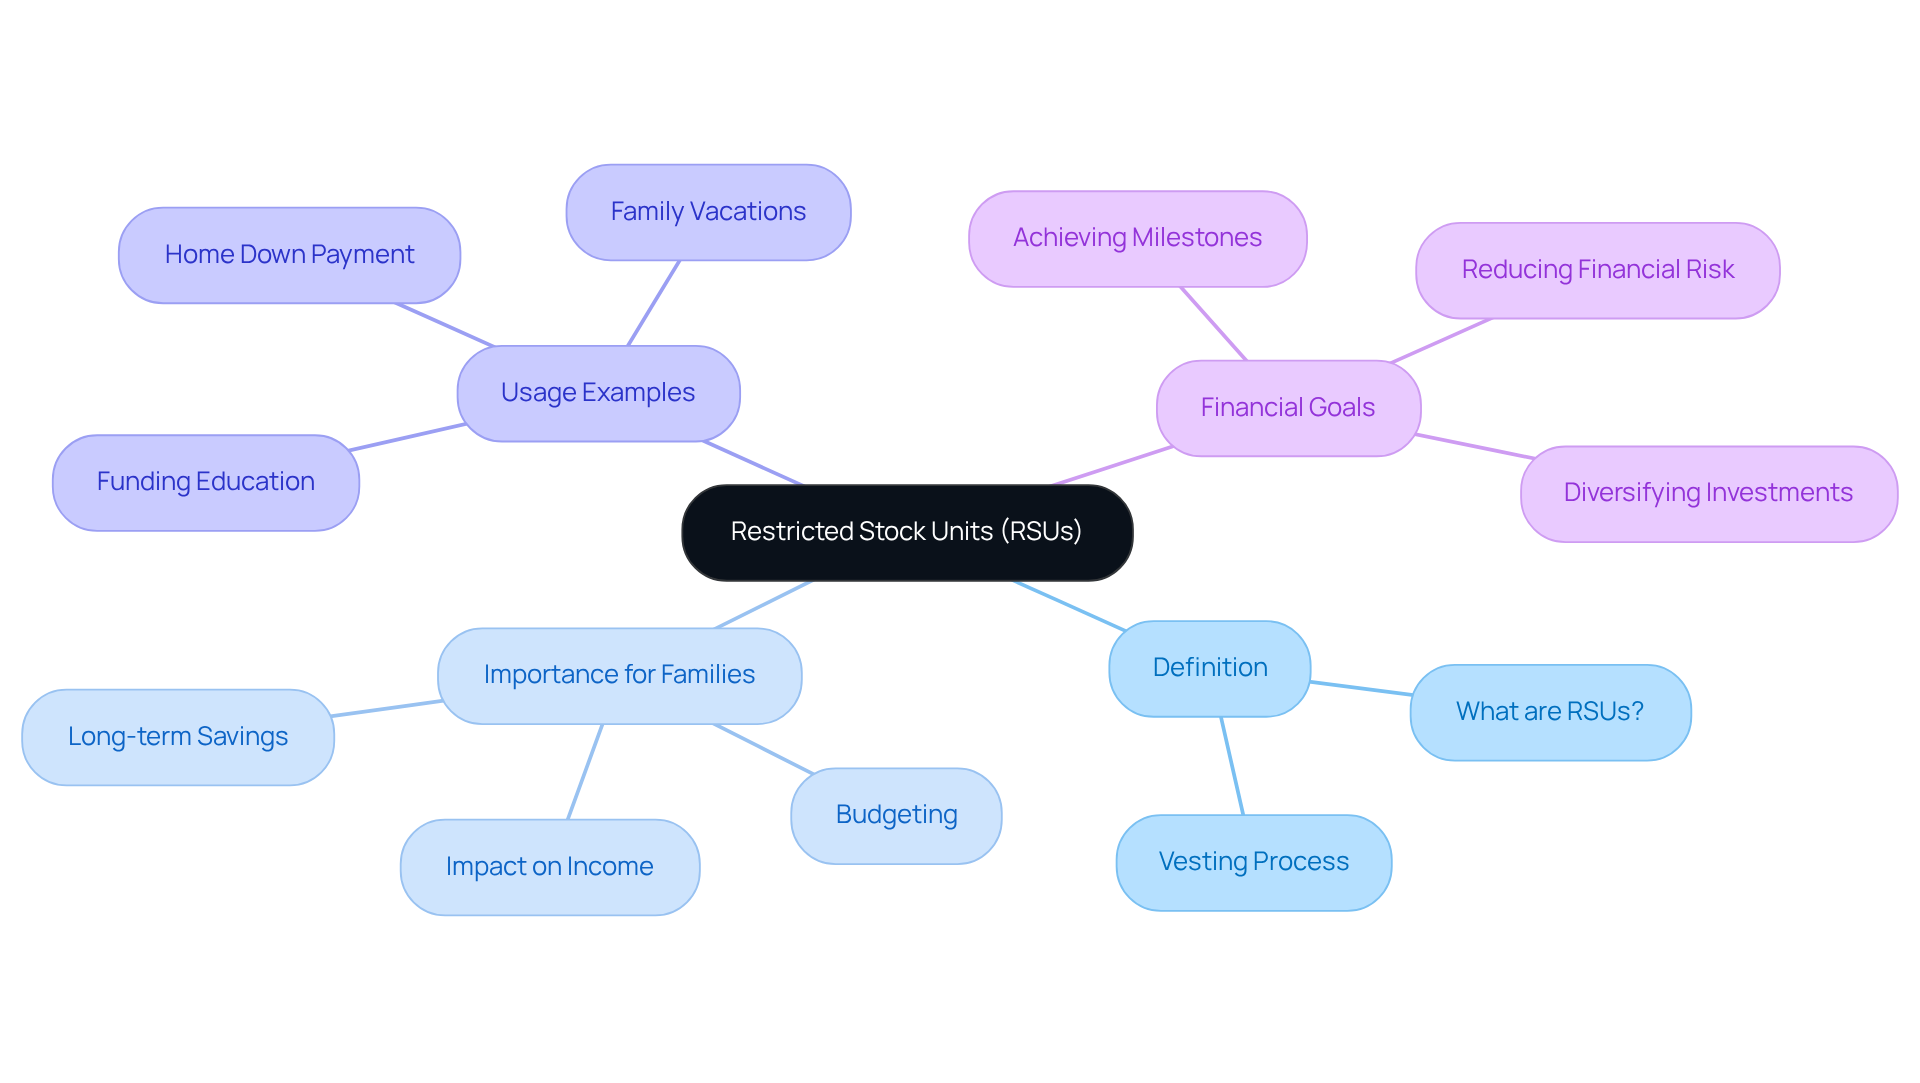
Imagine if you could turn your hard work into a brighter future for your family with the right financial tools. As more families see restricted stock units in their paychecks, it’s important to understand how rsu finance can impact your household’s finances. Restricted stock units, or RSUs, are shares that your employer grants you as part of your compensation, which is a key aspect of rsu finance. Unlike stock options, which require you to buy shares at a set price, RSUs give you shares outright once they vest, usually after a certain period or when specific performance goals are met.
For many families, rsu finance can play a big role in your overall income, affecting everything from your monthly budget to your long-term savings goals. They can be a powerful resource for building a solid financial foundation, especially for households with young children. Imagine using RSUs to help fund your child’s education or to save for a family vacation that creates lasting memories.
Let’s look at how families just like yours have used restricted stock units to achieve their financial dreams. For instance, some households have successfully utilized RSU proceeds to reach significant financial milestones, like a $250,000 down payment on a home. By selling a portion of their vested stock units, families can diversify their investments and reduce risk, paving the way for a more stable financial future. This thoughtful approach not only improves cash flow but also aligns with your family’s broader financial goals.
Understanding how to leverage rsu finance can empower your family to achieve financial goals you once thought were out of reach. Together, we can navigate this journey and ensure a brighter future for your loved ones.
Explore RSU Vesting Schedules and Their Financial Implications
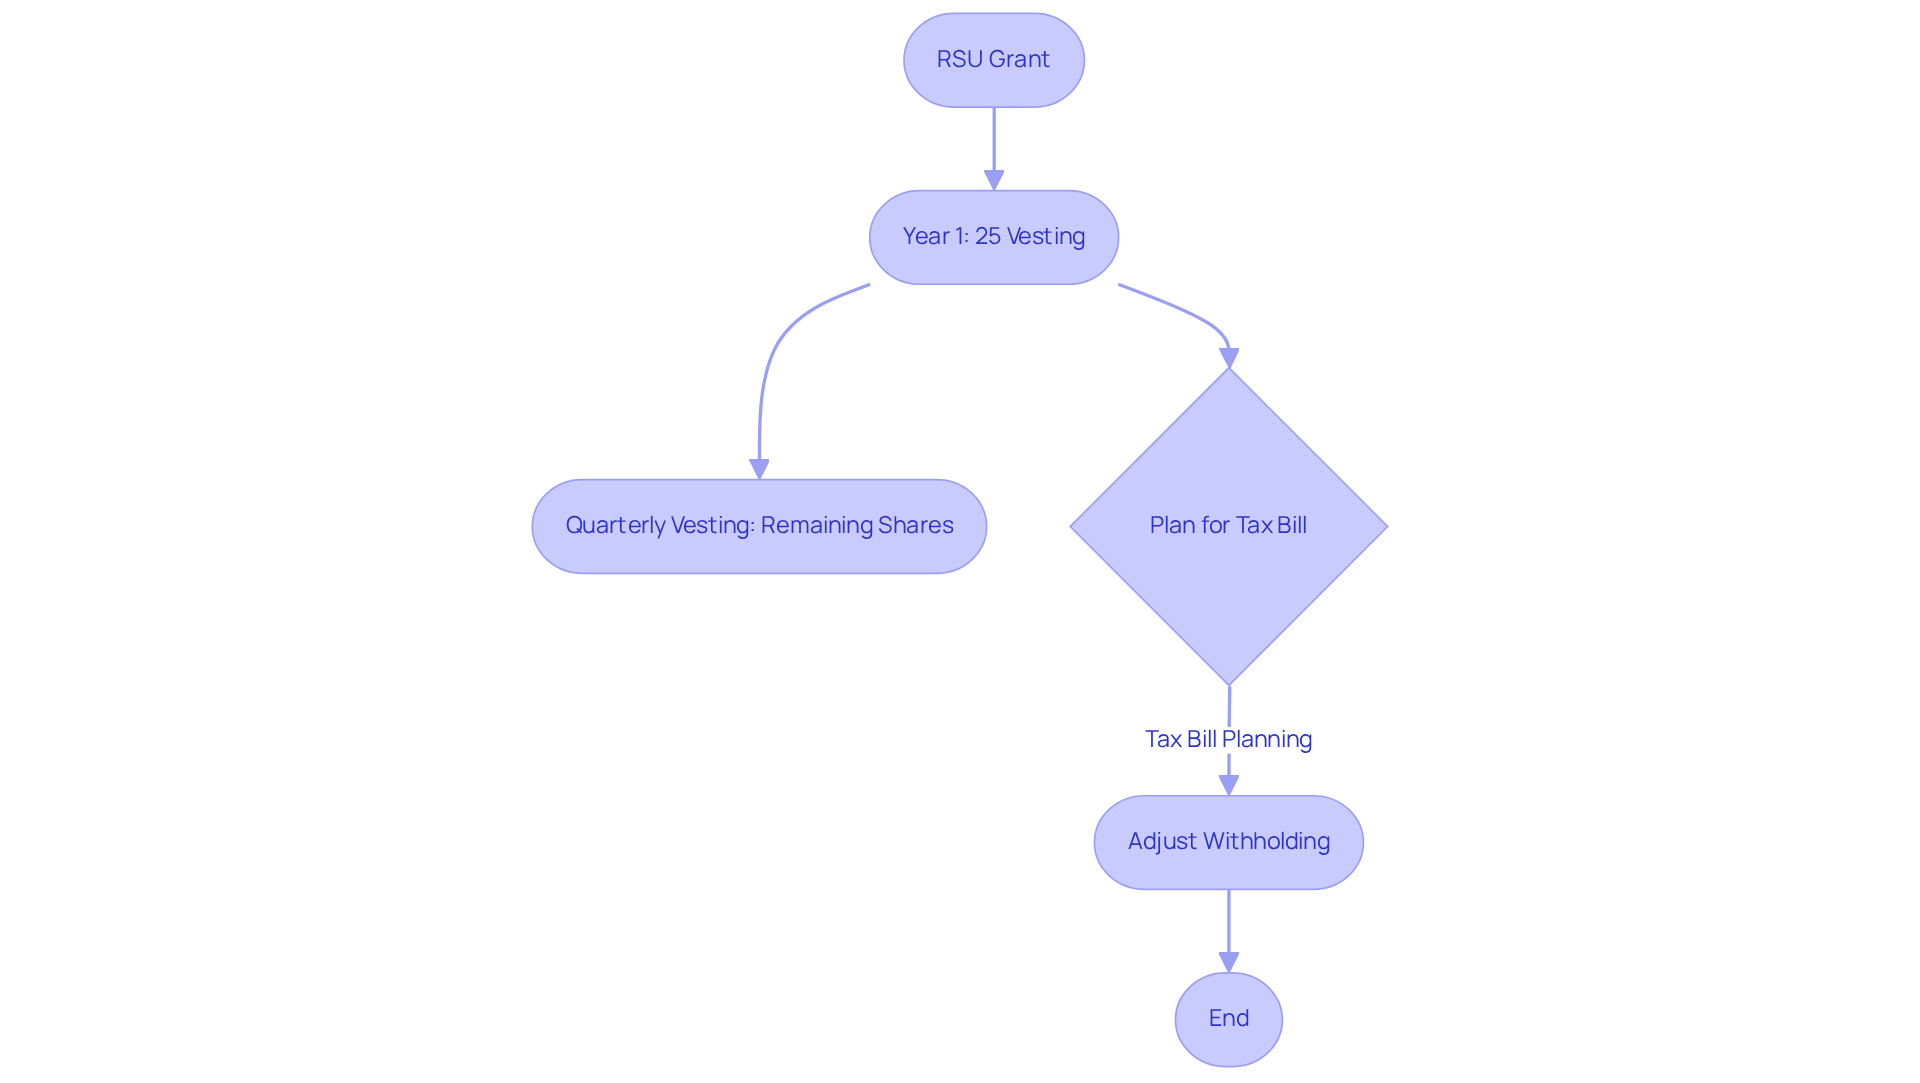
Imagine the surprise of receiving a tax bill just when you thought you were on top of your finances. Restricted Stock Units come with specific timelines that tell you when you’ll own your shares. Understanding these schedules is essential for managing your family’s cash flow and planning for the future.
For example, with a standard four-year vesting schedule, you receive 25% of your RSUs after the first year, followed by quarterly vesting of the remaining shares. Knowing when your shares vest helps you plan for those tax bills, so you’re not caught off guard. This foresight allows you to adjust your withholding or set aside funds in advance, ensuring you’re prepared for those expenses.
Comprehending the timing of share vesting can also assist you in planning your investments and savings. If you expect a substantial tax bill upon vesting, you can strategize to have the necessary funds available. This planning is crucial for achieving long-term goals, like funding your child’s education or buying a home.
Let’s look at a story of a tech family who faced unexpected challenges due to their RSUs. They had a significant portion of their net worth tied to their company’s stock. When the stock price dropped sharply, they experienced considerable losses. This situation highlights the importance of diversification and proactive financial planning. By understanding their RSU finance vesting schedules, families can make informed decisions that align with their financial objectives and mitigate potential risks.
By understanding RSU finance and vesting schedules, you can take control of your financial future and ensure your family’s dreams are within reach.
Understand RSU Taxation and Strategies for Minimizing Tax Burdens
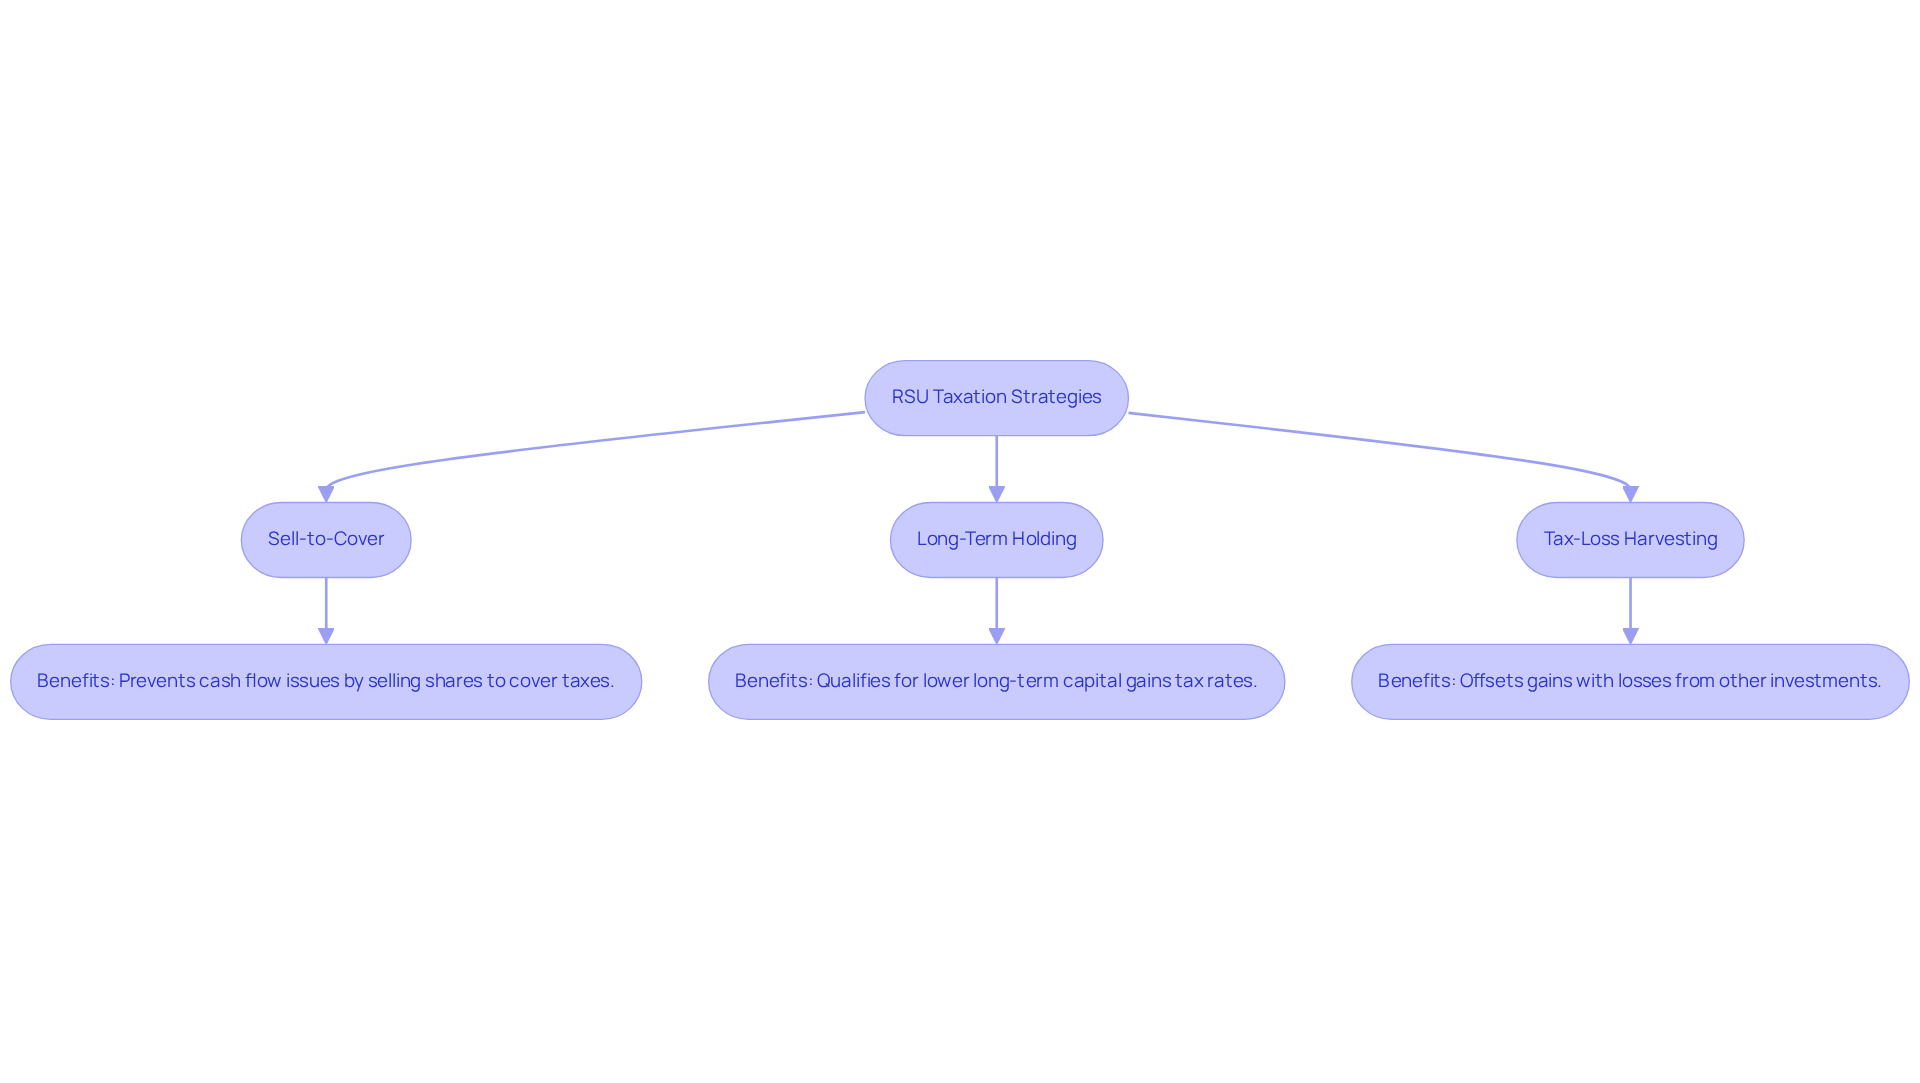
Imagine the surprise when your RSU finance Restricted Stock Units vest, bringing both opportunity and unexpected tax challenges. When these units vest, they’re taxed as regular income based on the fair market value of the shares at that moment. This can lead to unexpected tax bills, especially for families with several RSU finance vesting at once. Here are some gentle strategies to help ease those tax burdens:
- Sell-to-Cover: Selling a portion of the vested shares to cover the tax obligation can help prevent cash flow problems, ensuring that you have the necessary funds available when taxes are due. This approach is crucial, especially in California, where combined tax rates for high earners can exceed 52%.
- Long-Term Holding: If financially feasible, holding onto shares for over a year can qualify for lower long-term capital gains tax rates, significantly reducing the overall tax burden when the shares are eventually sold.
- Tax-Loss Harvesting: Offsetting gains from RSUs with losses from other investments can effectively reduce overall tax liability, enabling families to manage their RSU finance obligations more strategically.
As planning expert Gary Pia reminds us, “Without a solid plan, families risk facing unexpected tax bills that could strain their finances.” By thoughtfully managing RSU finance, families can find peace of mind and avoid surprises that might disrupt their financial goals. This is especially pertinent for households like Allison and Brian, who, through their partnership with Bright Advisers, enhanced their tax circumstances and ensured their economic future. By incorporating integrated tax planning and tax-loss harvesting into their comprehensive monetary strategy, they experienced the peace of mind that comes with economic security, allowing them to enjoy more quality time with their loved ones.
Manage Concentration Risk: Diversification Strategies for RSU Holders
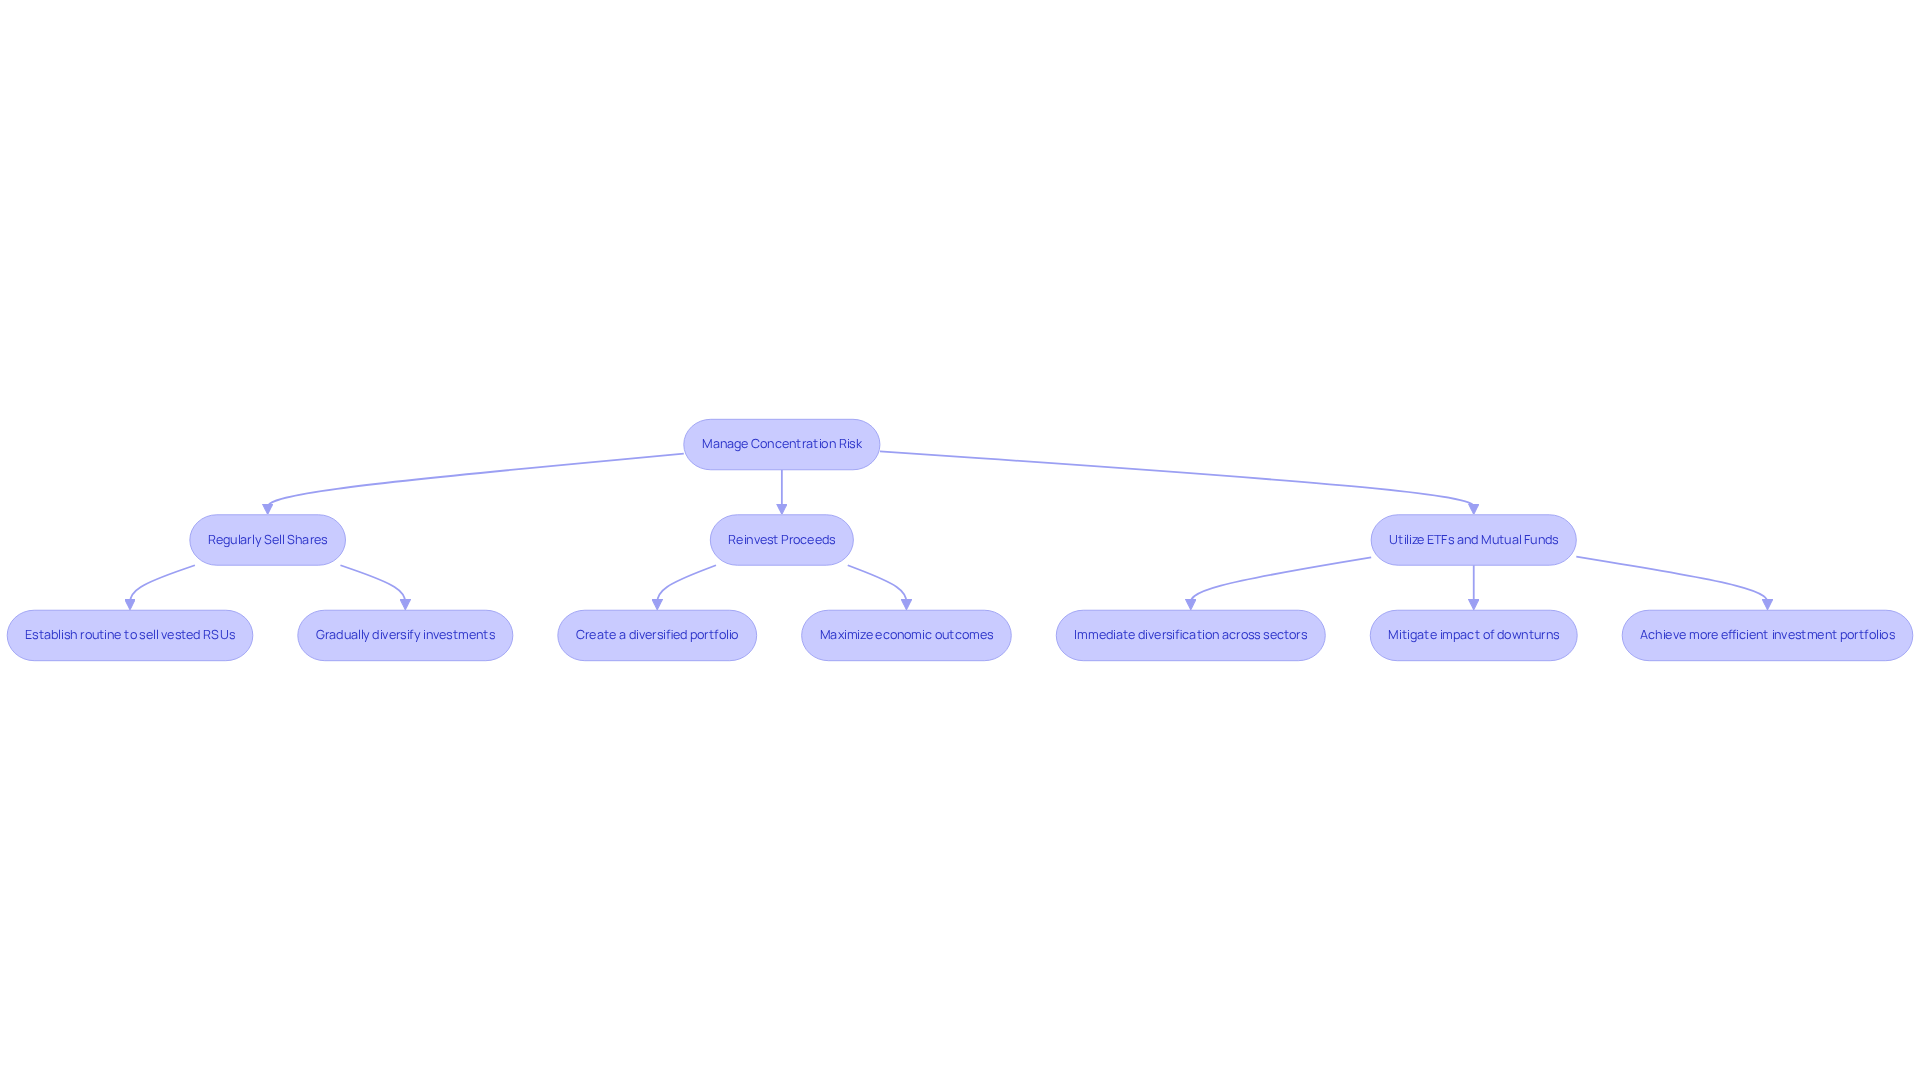
Imagine the stress of knowing your family’s financial future hinges on the ups and downs of a single stock. In Southern California, many families find that having over 10-15% of their net worth tied to employer stock can put them in a risky spot. It’s important to understand how to manage this concentration risk, and here are some gentle strategies to consider:
- Regularly sell shares as part of your RSU finance strategy by establishing a routine to sell a portion of vested RSUs. This proactive approach helps to gradually diversify investments, reducing reliance on a single stock.
- Reinvest Proceeds: Direct the proceeds from RSU finance sales into a diversified portfolio that includes a mix of stocks, bonds, and other asset classes. Bright Advisers utilizes advanced strategies to create hyper-personalized portfolios that maximize economic outcomes.
- Utilize ETFs and Mutual Funds: Investing in exchange-traded funds (ETFs) or mutual funds can provide immediate diversification across various sectors and industries, mitigating the impact of any downturn in a single stock. Bright Advisers’ innovative technology has made traditional investment products functionally obsolete, enabling households to achieve more efficient investment portfolios.
By taking these steps, families can feel more secure and confident in their financial future. Take Jay & Emma, for instance. They found peace of mind by applying these strategies, balancing their current responsibilities with their dreams for the future. Together, we can navigate this journey toward a more secure financial future for your family.
Compare RSUs and Stock Options: Making Informed Choices
Imagine navigating the complexities of compensation packages while trying to secure your family’s financial future. When assessing compensation packages, families often face the decision between stock options and RSU finance. Understanding these key differences can significantly impact your RSU finance strategies.
With Restricted Stock Units, you receive shares right away when they vest, giving you immediate ownership without needing to buy them. Stock options, on the other hand, allow you to buy shares at a set price, but this can be tricky if the stock price doesn’t go up.
Restricted Stock Units, commonly referred to as RSU finance, are generally seen as lower risk since they hold intrinsic value upon vesting, ensuring that you receive something of worth. In contrast, stock options can become worthless if the stock price fails to exceed the exercise price, posing a greater risk to you and your family.
When it comes to taxes, RSU finance shows that RSUs are taxed as ordinary income at the time of vesting, which can lead to significant tax liabilities, especially in high-tax states. Stock options, however, are taxed upon exercise, and if held long-term, they may qualify for capital gains treatment, potentially resulting in lower tax rates.
Choosing between Restricted Stock Units and stock options can feel overwhelming for families, especially when considering their RSU finance for the future. For instance, think about Jay and Emma, who worked with Bright Advisers to navigate these complexities. They managed to optimize their tax situation and create a comprehensive strategy that aligned with their goals.
This decision is vital for ensuring that your compensation aligns with your economic future and supports your overall wealth management strategy. By partnering with Bright Advisers, families can access tailored wealth management solutions that empower financial security and freedom through personalized planning and tax optimization, addressing the unique financial challenges faced by young families. By understanding these options, families can make informed decisions that truly support their financial well-being.
Conclusion
Imagine feeling confident about your family’s financial future, knowing that your hard work can lead to lasting benefits. Understanding and effectively managing Restricted Stock Units (RSUs) can be a key part of that journey. Together, we can explore strategies that make navigating RSU finance feel less daunting and more empowering.
Many families feel overwhelmed by the complexities of RSUs, unsure of how to make the most of these assets. It’s important to understand:
- Vesting schedules
- The implications of taxation
- How to diversify to mitigate concentration risk
Think of RSUs as not just income, but as a stepping stone toward your dreams, whether that’s funding your child’s education or buying a family home.
With the right planning and support from caring advisors, you can navigate your financial journey with confidence and clarity. By implementing thoughtful financial strategies, families can optimize their wealth management and minimize potential pitfalls.
Remember, you’re not alone on this journey; we’re here for you every step of the way. By taking these steps, you can transform your financial landscape, ensuring a future filled with opportunities for your loved ones.
Frequently Asked Questions
What are Restricted Stock Units (RSUs)?
Restricted Stock Units (RSUs) are shares granted by an employer as part of compensation, which are given outright once they vest, typically after a certain period or upon meeting specific performance goals.
How can RSUs impact a family’s finances?
RSUs can significantly affect a family’s overall income, influencing monthly budgets and long-term savings goals. They can be used to fund education, save for vacations, or achieve major financial milestones, such as a down payment on a home.
What is a typical vesting schedule for RSUs?
A standard vesting schedule for RSUs is four years, where 25% of the RSUs vest after the first year, followed by quarterly vesting of the remaining shares.
Why is it important to understand RSU vesting schedules?
Understanding RSU vesting schedules is crucial for managing cash flow and planning for tax bills that arise when shares vest. This foresight allows families to prepare financially for these expenses.
How can families prepare for tax implications related to RSUs?
Families can prepare for tax implications by knowing when their shares vest and adjusting their withholding or setting aside funds in advance to cover potential tax bills.
What are the risks associated with having a significant portion of net worth tied to RSUs?
Families may face risks if a large portion of their net worth is tied to their company’s stock, as fluctuations in stock prices can lead to significant financial losses. Diversification and proactive financial planning are essential to mitigate these risks.
How can understanding RSU finance empower families?
By understanding RSU finance and vesting schedules, families can make informed decisions that align with their financial objectives, helping them achieve their financial goals and secure a brighter future.
List of Sources
- Define Restricted Stock Units (RSUs) and Their Importance for Families
- RSUs: Balancing Opportunity and Risk in Modern Compensation (https://resilientplanning.com/blog/rsus-balancing-opportunity-and-risk-in-modern-compensation)
- This job perk is like a ‘cash bonus’ — but you need a long-term strategy, experts say (https://cnbc.com/2024/04/25/here-are-the-key-things-to-know-about-your-restricted-stock-units.html)
- 4 Key Considerations: Is RSU Better Than Cash for Families? – Bright Advisers (https://brightadvisers.com/4-key-considerations-is-rsu-better-than-cash-for-families)
- Use Restricted Stock Units to Fund Financial Planning Goals (https://zajacgrp.com/insights/restricted-stock-units-to-fund-financial-planning-goals)
- Equity Compensation and the Rise of Restricted Stock Units (https://natlawreview.com/article/equity-compensation-and-rise-restricted-stock-units)
- Explore RSU Vesting Schedules and Their Financial Implications
- California RSU Tax Calculator 2026: Equity Tax Savings (https://sdocpa.com/rsu-tax-calculator-california)
- Financial Planning With Restricted Stock Units: 3 Key Questions | Morgan Stanley at Work (https://morganstanley.com/atwork/employees/learning-center/articles/restricted-stock-units-and-financial-planning)
- RSU Vesting Schedules: When Do You Actually Own Your Stock? | Fireweed Capital (https://fireweedcapital.com/blog/rsu-vesting-schedule-guide)
- RSU Strategy for Tech Employees With Concentrated Stock (https://embarkfunds.com/insights/rsu-strategy-for-tech-employees)
- 2025 Update: Tech Company Stock Pay Accounts for One-Quarter of Withholding Growth So Far in 2025-26 [EconTax Blog] (https://lao.ca.gov/LAOEconTax/Article/Detail/843)
- Understand RSU Taxation and Strategies for Minimizing Tax Burdens
- California RSU Tax Calculator 2026: Equity Tax Savings (https://sdocpa.com/rsu-tax-calculator-california)
- RSU Tax Planning: Tips and Strategies | Citrine Capital (https://citrinecapitaladvisors.com/blog/rsu-tax-planning-guide)
- How Restricted Stock Units (RSUs) are Taxed in California – Summitry (https://summitry.com/blog/rsu-taxes-in-california)
- The Hidden Tax Time Bomb in Your RSU Grants: California Edition – Mission Street Wealth (https://missionstreetwealth.com/california-rsu-taxation-the-hidden-tax-time-bomb)
- RSU Taxes Explained and 4 Tax Strategies for 2023 (https://ceritypartners.com/insights/rsu-taxes-explained-and-4-tax-strategies-for-2023)
- Manage Concentration Risk: Diversification Strategies for RSU Holders
- RSU Stock Strategy: How to Avoid the Concentration Trap | Consilio Wealth Advisors (https://consiliowealth.com/insights/rsu-stock-strategy-concentration-trap)
- Your RSUs Could Put Your Net Worth At Risk—This Strategy Can Tame Them (https://forbes.com/sites/ericroberge/2025/01/28/your-rsus-could-put-your-net-worth-at-risk-this-strategy-can-tame-them)
- 12 statistics illustrating concentration-risk thresholds lenders watch (https://resolvepay.com/blog/12-statistics-illustrating-concentration-risk-thresholds-lenders-watch?hs_amp=true)
- RSU Concentration Risk: When One Company Becomes Too Much of Your Financial Future – Inclinevest (https://inclinevest.com/rsu-concentration-risk)
- How to Diversify Investments After Receiving Rsus (https://linkedin.com/top-content/finance/investment-diversification-techniques/how-to-diversify-investments-after-receiving-rsus)
- Compare RSUs and Stock Options: Making Informed Choices
- RSU vs Stock Options: Key Differences & Benefits (https://carta.com/learn/equity/rsu-vs-stock-options)
- Decoding Stock Options vs RSU: Maximizing Your Rewards — Brooklyn Fi (https://brooklynfi.com/blog/stock-options-vs-rsu)
- Equity vs. RSUs (https://harrisonclarke.com/blog/equity-vs-rsu?hs_amp=true)
- RSU vs. Stock Options: Navigating Equity Compensation (https://tgcsearch.com/business-insights/rsu-vs-stock-options-navigating-equity-compensation)
- RSU vs. stock options: What’s the difference? (https://empower.com/the-currency/money/stock-options-vs-rsu)

Kevin has advised high-income W-2 tech and biotech families since 2015, and leads the education-first Age Five Family Office from Brea, California.
Connect on LinkedIn → · About KevinThis is part of how we approach Tax Management for high-income W-2 families at Bright Advisers.
Keep reading