

Key Highlights
- Restricted Stock Units (RSUs) are shares given as part of compensation, taxed as regular earnings upon vesting.
- Tax liability arises from the fair market value of RSUs at vesting, which can lead to unexpected tax bills due to under-withholding.
- California’s flat tax rate of 10.23% and recent changes in tax laws complicate RSU taxation for high earners.
- Strategies to manage RSU taxes include adjusting withholding, using a sell-to-cover strategy, maximising deductions, making charitable contributions, and holding shares long-term for favourable capital gains tax rates.
- Common mistakes include double-counting earnings, ignoring state tax implications, and inaccurate tracking of cost basis, which can lead to overpayment of taxes.
- Consulting a financial advisor, like those at Bright Advisers, can provide tailored strategies, optimise revenue, and integrate RSU management into broader financial planning.
- Bright Advisers emphasises fiduciary duty and transparency, ensuring no hidden fees or conflicts of interest, and focuses on helping families make wise wealth decisions.
Introduction
Imagine feeling overwhelmed by the complexities of Restricted Stock Units (RSUs) while trying to secure your family’s financial future. As these units become more common, especially in the tech sector, the tax implications can weigh heavily on families striving for financial stability.
Let’s explore some effective strategies together that can help you minimize RSU taxes and navigate the complexities of taxation with confidence. With changing tax laws and potential pitfalls, it’s important to know how to avoid overpaying on your RSU taxes while still securing your family’s financial future.
Understand Restricted Stock Units (RSUs) and Their Tax Implications
Understanding Restricted Stock Units can feel overwhelming, especially for families trying to balance financial planning with everyday life. These units are becoming more common in the tech world, where employees receive shares of stock as part of their compensation after meeting certain criteria, like staying with the company for a while.
Understanding how Restricted Stock Units affect your taxes is crucial, especially when considering how do I avoid paying taxes on RSU, as this can significantly impact your family’s financial planning here in Southern California.
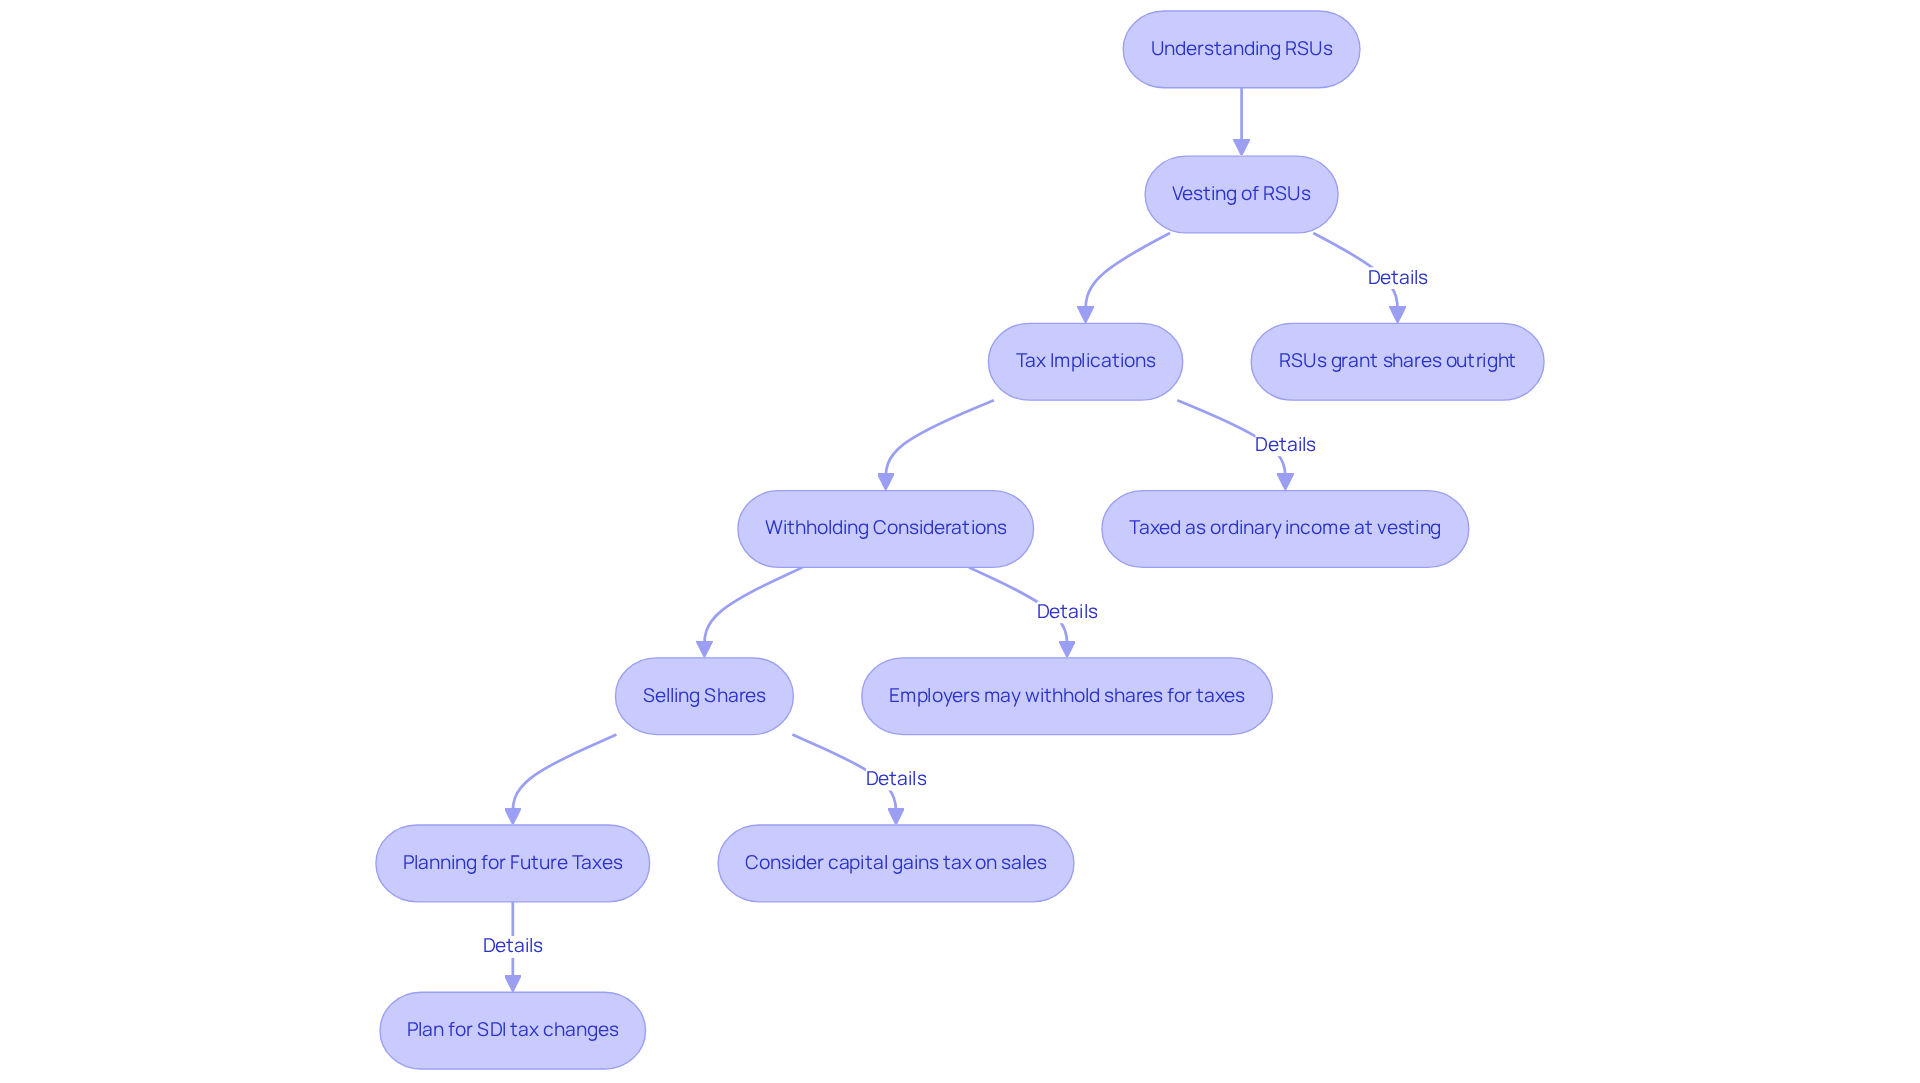
When Restricted Stock Units vest, they are taxed as regular earnings. The fair market value of the shares at that time gets added to your taxable income. For instance, if 1,000 RSUs vest at $50 per share, that means a tax liability of $50,000.
Many families find themselves surprised by tax bills because of under-withholding, leading them to wonder how do I avoid paying taxes on RSU earnings, especially with California’s flat 10.23% rate. Employers usually withhold a portion of the shares to cover tax liabilities, but high earners often face significant under-withholding, leading to unexpected tax bills.
Take, for instance, a tech employee earning $300,000 with $400,000 in RSUs; they could face a staggering $56,280 gap in withholding, which raises the question of how do I avoid paying taxes on RSU and emphasizes the importance of planning ahead for taxes.
After vesting, any gains from selling the shares are subject to capital gains tax, which can be long-term or short-term based on how long you hold the shares, leading to concerns about how do I avoid paying taxes on RSU. If you sell right after vesting, you won’t owe extra taxes on profits. But if the share price goes up, you’ll need to think about how do I avoid paying taxes on RSU gains when you sell.
Recent changes in California’s tax laws, like the removal of the wage cap on State Disability Insurance (SDI), make things even more complicated for RSU holders. Starting in 2024, all income, including RSUs, will be subject to a 0.9% SDI tax without a ceiling, leading many to wonder how do I avoid paying taxes on RSU, which could significantly increase tax liabilities for high earners.
Consider the stories of families like Jay and Emma, who have two kids and sought advice from Bright Advisers to ease their financial stress. They learned how to navigate RSU taxation as part of their comprehensive financial strategy, which included integrated tax planning and investment strategies tailored to their needs. Similarly, Emily and Mark, who aimed for financial independence, benefited from customized planning that helped them understand their RSU tax implications. Allison and Brian, concerned about maximizing their financial potential, also found value in optimizing their tax situation through Bright Advisers. These experiences highlight how important it is to have a solid tax plan and how Bright Advisers can help families like yours navigate the complexities of RSU taxation, particularly in understanding how do I avoid paying taxes on RSU with confidence.
Implement Tax-Reduction Strategies for RSUs
Imagine facing a hefty tax bill just when you thought you were on top of your finances. Managing the tax implications of restricted stock units (RSUs) can feel overwhelming, particularly when wondering how do I avoid paying taxes on RSU while balancing family needs and financial goals. Here are some strategies to help you navigate this journey with confidence:
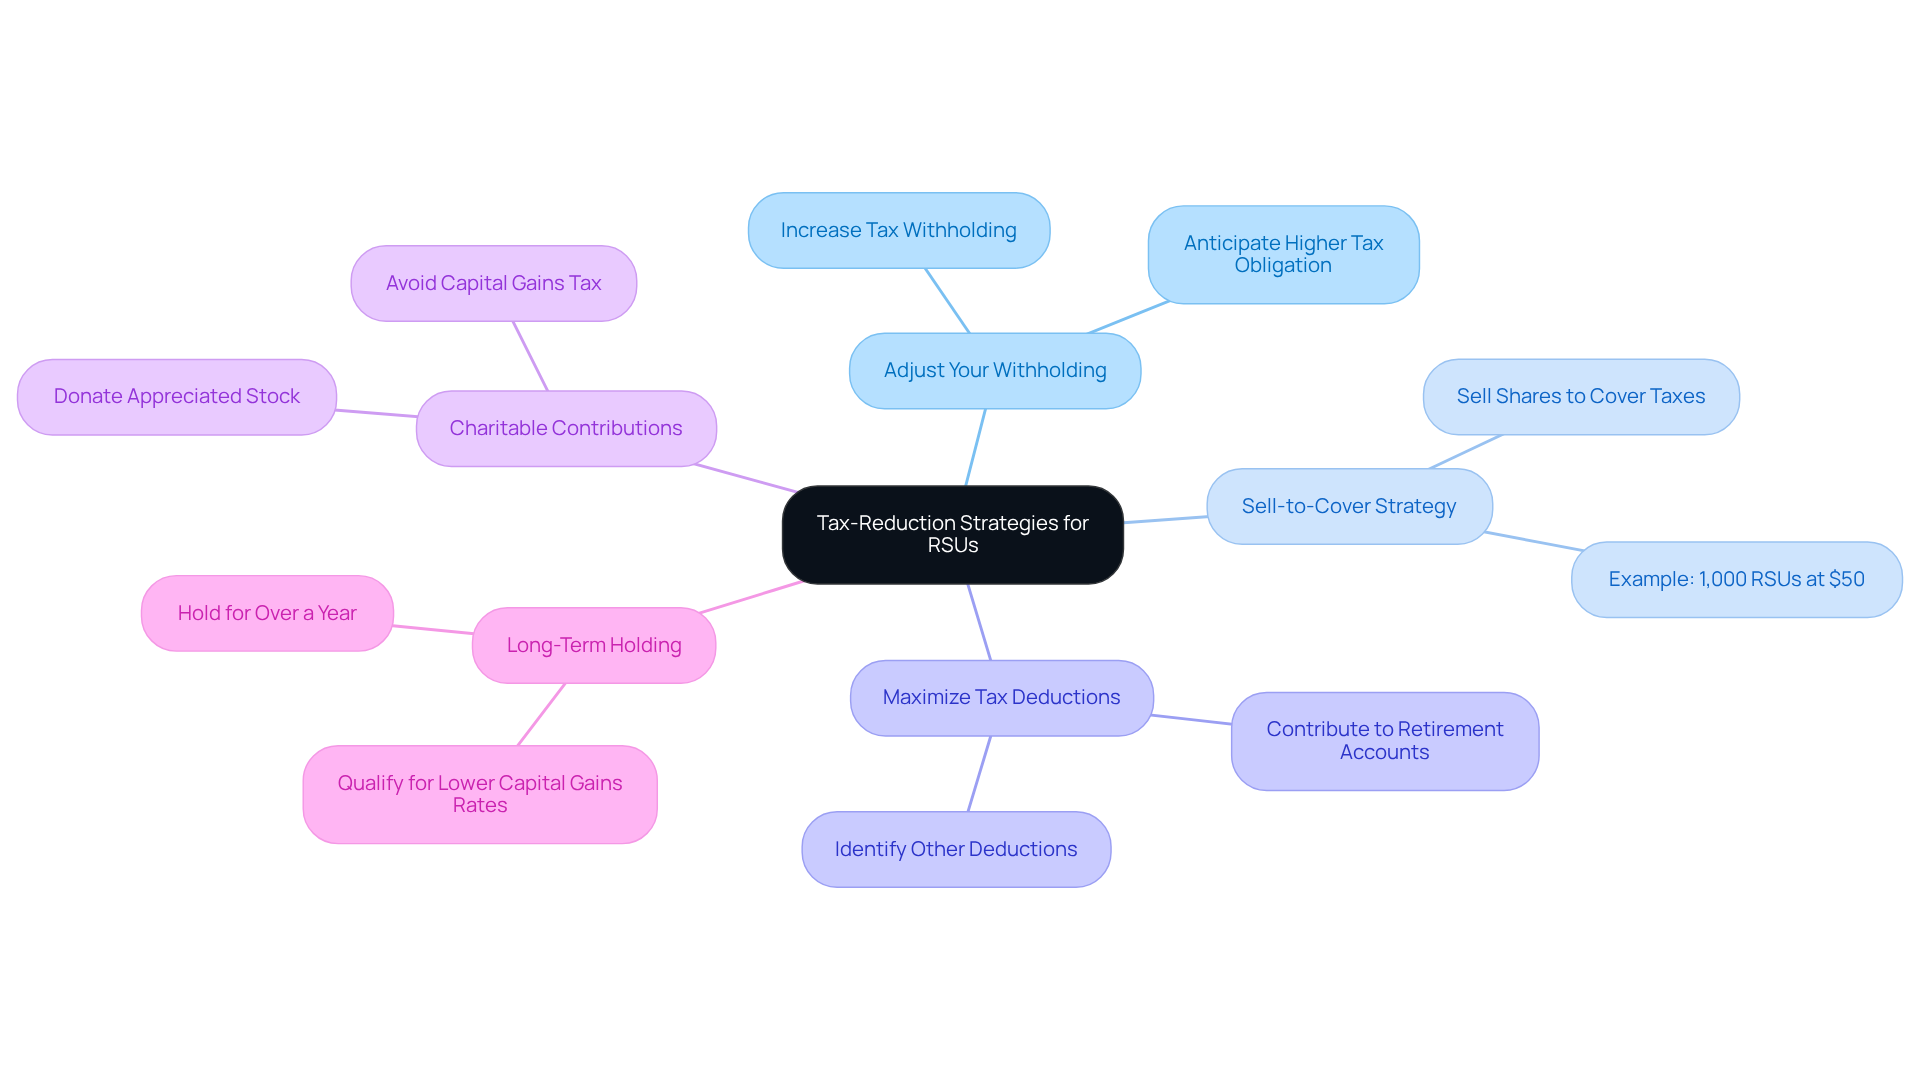
- Adjust Your Withholding: Anticipate a higher tax obligation due to RSUs vesting by increasing your tax withholding on your regular paycheck. This proactive approach can help you figure out how do I avoid paying taxes on RSU and prevent a large tax bill at year-end, especially since high earners may face effective marginal tax rates exceeding 50% in high-tax states.
- Sell-to-Cover Strategy: Imagine selling a portion of your RSUs immediately upon vesting to cover your tax liability. For example, if 1,000 RSUs vest at $50 each, selling 200 shares can provide liquidity for taxes while allowing you to keep the remaining shares for potential growth.
- Maximize Tax Deductions: Look for opportunities to maximize your deductions, such as contributing to retirement accounts like a 401(k) or an IRA. These contributions can reduce your taxable income, possibly balancing the income from RSUs and keeping you in a lower tax bracket.
- Charitable Contributions: Imagine being able to support your favorite charity while also maximizing your tax benefits by donating appreciated stock instead of cash. This strategy allows you to deduct the full value of the shares while avoiding capital gains tax on the appreciation, providing significant tax benefits.
- Long-Term Holding: If feasible, hold onto your RSUs for over a year after vesting before selling. This can qualify you for long-term capital gains tax rates, which can be as low as 0%, 15%, or 20%, compared to ordinary income tax rates that can reach 37%.
By applying these strategies, you can discover how do I avoid paying taxes on RSU while also boosting your family’s financial well-being. Families like Jay & Emma and Emily & Mark have successfully managed their planning with Bright Advisers, attaining peace of mind through customized strategies that meet their distinct needs. Additionally, consider consulting with a financial advisor who specializes in equity compensation to navigate the complexities of state tax obligations, especially if you reside in Southern California. Remember, Bright Advisers, founded by Kevin Luu and Kathleen Chou in 2010, is committed to helping families make wise wealth decisions and preserve wealth across generations. With the right strategies in place, you can secure your family’s financial future and enjoy peace of mind.
Avoid Common Tax Mistakes with RSUs
Imagine the stress of managing your family’s finances while trying to navigate the complexities of RSUs. When it comes to handling RSUs, knowing how do I avoid paying taxes on RSU is crucial for your peace of mind.
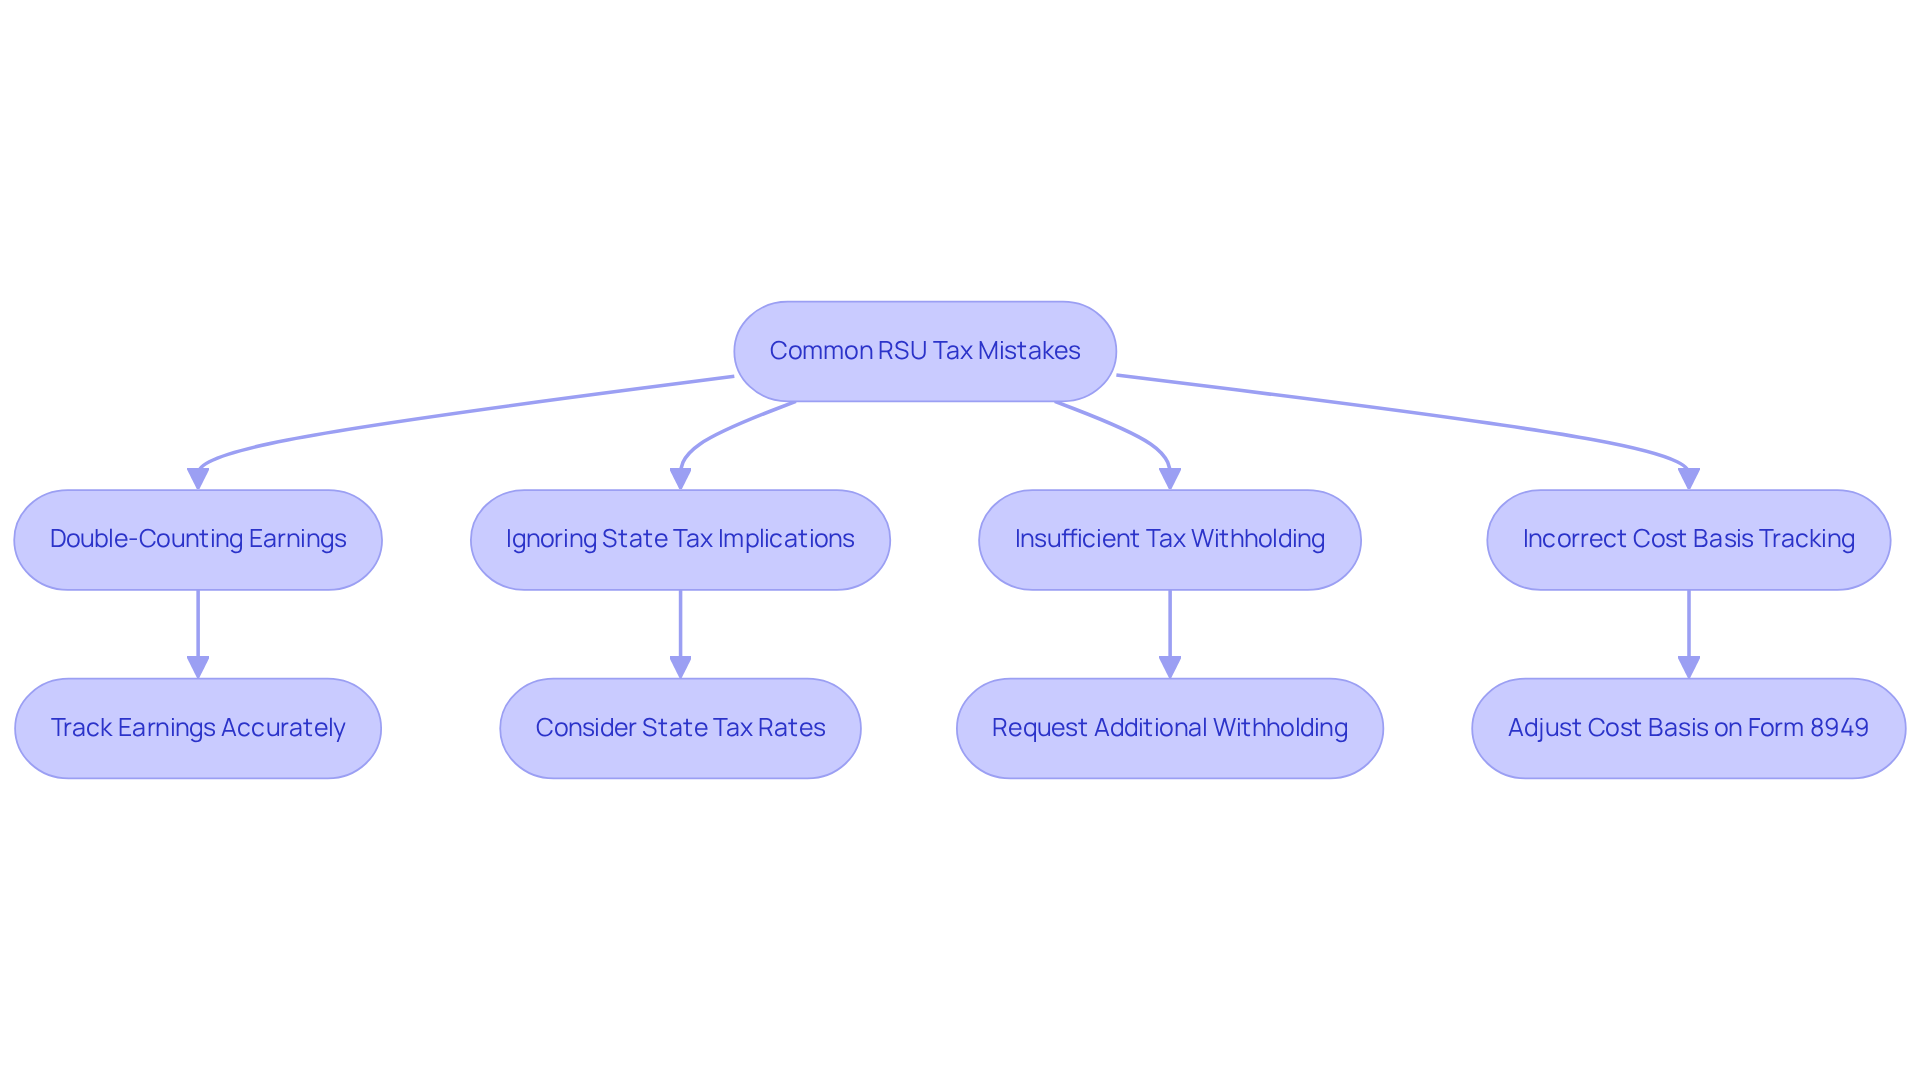
One frequent error is double-counting earnings. If you don’t track your RSU earnings accurately, you could end up paying more in taxes than necessary. As Bjorn Amundson, a caring CFP®, points out, “If you (or your tax preparer) don’t identify this mistake, you might pay taxes twice on the same earnings.”
Many parents feel overwhelmed by the complexities of RSU taxation. Ignoring state tax implications can lead to unexpected surprises. For instance, in states like Minnesota, where the income tax rate can reach 9.85%, it’s essential to factor in these rates during your financial planning. Regularly reviewing your tax situation can help you stay informed about potential liabilities.
It’s important to understand that default tax withholding for restricted stock units is often set at 22%. This may not be enough for those in higher tax brackets. Executives need to either request additional withholding or set aside cash to cover the potential tax gap. Effective RSU planning focuses on proper reporting to address how do I avoid paying taxes on RSU and prevent double taxation.
Accurate tracking of the cost basis when selling RSUs is vital. If you don’t track your cost basis accurately, you could end up paying more in capital gains taxes than necessary. For example, if a brokerage reports a cost basis of $0, the IRS may assume all proceeds are profit, resulting in double taxation. It’s essential to adjust the cost basis on Form 8949 to reflect the correct value at vesting.
Navigating RSU taxation can be complex. Engaging a knowledgeable financial advisor can provide personalized strategies and insights tailored to your unique situation, helping you avoid costly mistakes. A case study illustrates this: a client saved over $71,000 in taxes by adjusting the cost basis on their restricted stock units, demonstrating the importance of professional guidance.
By being aware of these common mistakes, you can better manage your RSUs and understand how do I avoid paying taxes on RSUs to minimize unnecessary tax liabilities. With the right support, you can confidently manage your RSUs and protect your family’s financial future.
Consult a Financial Advisor for Personalized RSU Tax Planning
Understanding RSU taxation can feel overwhelming, especially when you’re juggling the needs of your young family. Consulting a financial advisor, like those at Bright Advisers, can provide invaluable support in several key areas:
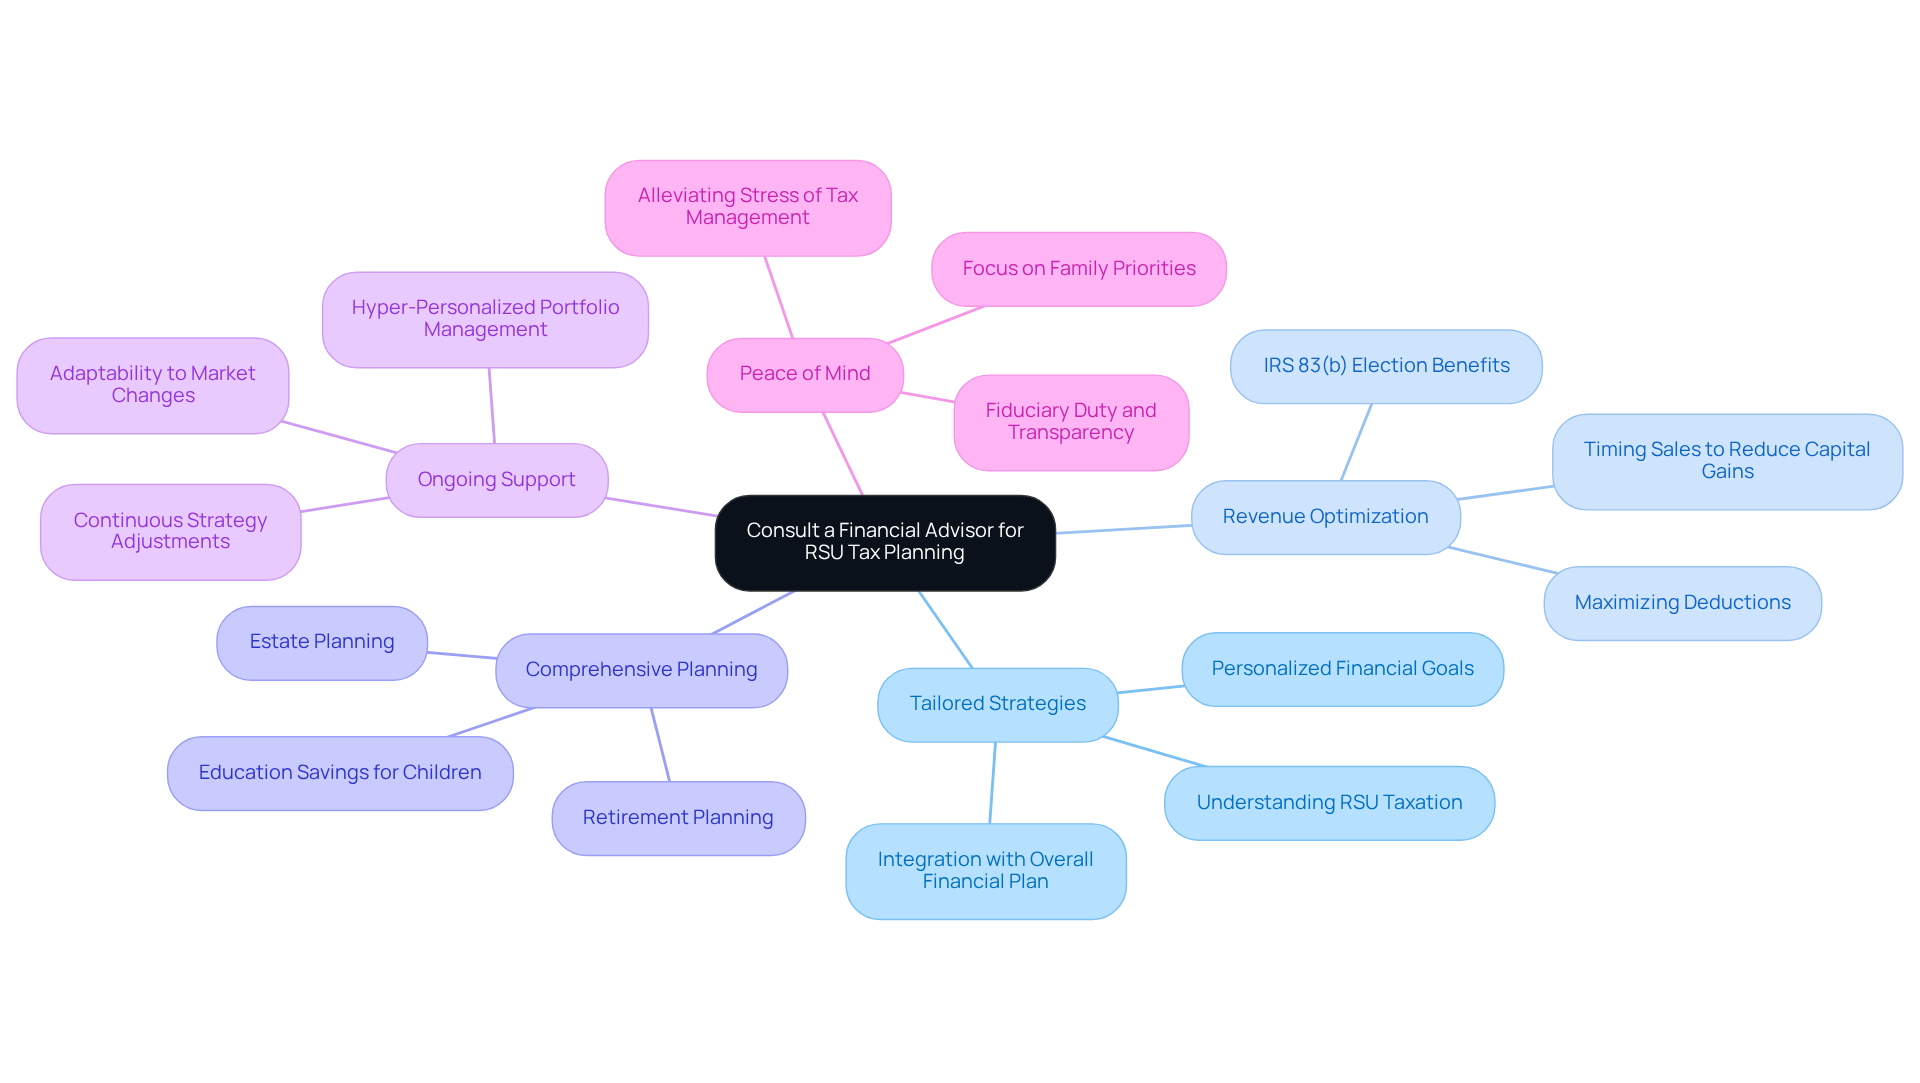
- Tailored Strategies: Financial advisors at Bright Advisers craft personalized strategies that align with your family’s financial goals. They ensure that your RSU management integrates seamlessly into your overall financial plan. For instance, knowing that RSUs are taxed as ordinary income at vesting can help you plan your tax strategy effectively.
- Revenue Optimization: Advisors assist in recognizing savings opportunities tailored to your circumstances. They can help you time sales to reduce capital gains levies or maximize deductions. Many families discover that selling enough shares to cover obligations while keeping others balances immediate needs with potential long-term gains. Additionally, the IRS 83(b) election allows you to pay taxes on RSUs based on their value at grant rather than vesting, which can be a strategic advantage. Bright Advisers also employs integrated tax planning and tax-loss harvesting strategies to enhance your economic outcomes.
- Comprehensive Planning: An advisor can weave RSU management into other aspects of your financial life, including retirement planning, estate planning, and education savings for your children. This holistic approach ensures that all financial elements work together effectively. For example, clients like Jay and Emma successfully navigated funding their children’s education while planning for retirement, achieving a balance between their present responsibilities and long-term aspirations.
- Ongoing Support: As your financial situation evolves, an advisor provides continuous support and adjustments to your strategy, ensuring you remain on track to meet your goals. This adaptability is crucial, especially in the face of changing market conditions or personal circumstances. Bright Advisers’ use of in-house technology allows for hyper-personalized portfolio management, avoiding expensive mutual funds and ETFs.
- Peace of Mind: Working with a professional alleviates the stress of managing complex tax situations, allowing you to focus on what matters most-your family. The complexities of RSUs raise the important question of how do I avoid paying taxes on RSU, and having expert guidance can transform these potential tax liabilities into valuable economic assets. Families who work with financial advisors often find that their stress decreases, allowing them to focus on what truly matters: their loved ones. Bright Advisers emphasizes fiduciary duty and transparency, ensuring no hidden fees or conflicts of interest.
With the right support, you can turn the challenges of RSU taxation into opportunities for your family’s future.
Conclusion
Many families feel overwhelmed by the complexities of Restricted Stock Units (RSUs) and their tax implications, but understanding them is key to securing your financial future. When you understand how RSUs are taxed and use smart strategies, you can avoid pitfalls and reduce your tax burden. Taking these steps can ease financial worries and help your family make choices that support your dreams.
Here are some key insights to keep in mind:
- Adjust your tax withholdings
- Use sell-to-cover strategies
- Maximize your deductions
- Avoid common mistakes like double-counting earnings
Working with a caring financial advisor, like those at Bright Advisers, can help you better understand and manage RSU taxation. Personalized strategies tailored to your unique situation can lead to significant savings and peace of mind, allowing you to focus on what truly matters-your family.
While RSU taxation can be tricky, it also opens doors to new opportunities for your family. Embrace the journey of financial planning with confidence, knowing that with the right strategies in place, your family’s financial well-being can thrive. For personalized support, consider reaching out to Bright Advisers at hello@brightadvisers.com or call (714) 987-2967 to explore how tailored wealth management can help you achieve your financial aspirations.
Frequently Asked Questions
What are Restricted Stock Units (RSUs)?
Restricted Stock Units (RSUs) are shares of stock given to employees as part of their compensation, which vest after certain criteria are met, such as remaining with the company for a specified period.
How are RSUs taxed?
When RSUs vest, they are taxed as regular earnings. The fair market value of the shares at the time of vesting is added to your taxable income.
What happens if I have under-withholding on my RSUs?
Many families experience unexpected tax bills due to under-withholding on RSUs. Employers typically withhold a portion of the shares to cover tax liabilities, but high earners may face significant gaps in withholding.
What are the capital gains tax implications after selling RSUs?
After vesting, any gains from selling RSUs are subject to capital gains tax, which can be either long-term or short-term depending on how long you hold the shares.
How can I avoid paying taxes on RSU earnings?
To avoid paying excessive taxes on RSU earnings, it is important to plan ahead for taxes, considering factors like withholding rates and potential capital gains taxes when selling shares.
What recent changes in California tax laws affect RSU holders?
Starting in 2024, all income, including RSUs, will be subject to a 0.9% State Disability Insurance (SDI) tax without a ceiling, which could increase tax liabilities for high earners.
How can families navigate the complexities of RSU taxation?
Families can benefit from comprehensive financial strategies that include integrated tax planning and investment strategies, as demonstrated by clients of Bright Advisers who received tailored advice on RSU taxation.
Who can help with understanding RSU tax implications?
Bright Advisers, founded by Kevin Luu and Kathleen Chou in 2010, offers guidance to families on navigating RSU taxation and developing effective financial strategies.
List of Sources
- Understand Restricted Stock Units (RSUs) and Their Tax Implications
- California RSU Tax Calculator 2026: Equity Tax Savings (https://sdocpa.com/rsu-tax-calculator-california)
- RSU vs. stock options: What’s the difference? (https://empower.com/the-currency/money/stock-options-vs-rsu)
- Restricted Stock Units (RSUs) and Tax Planning Strategy: 3 Key Questions for Tech Professionals in 2026 (https://maprivatewealth.com/insights/restricted-stock-units-tax-planning-strategy-tech-professionals?hs_amp=true)
- Restricted Stock Units and How They Work | Wealthspire (https://wealthspire.com/blog/restricted-stock-units-rsus-how-they-work-6-common-misconceptions)
- RSUs and California Tax (https://savantwealth.com/savant-views-news/article/rsus-and-california-tax)
- Implement Tax-Reduction Strategies for RSUs
- RSU Taxes Explained and 4 Tax Strategies for 2023 (https://ceritypartners.com/insights/rsu-taxes-explained-and-4-tax-strategies-for-2023)
- RSU Tax Planning: Tips and Strategies | Citrine Capital (https://citrinecapitaladvisors.com/blog/rsu-tax-planning-guide)
- How Can I Reduce Taxes on RSU Income? | AE Tax Advisors (https://aetaxadvisors.com/blog/how-to-reduce-taxes-on-rsu-income)
- The Sell to Cover Tax Strategy for Restricted Stock Units (RSUs) (https://kubera.com/blog/sell-to-cover-rsu)
- Avoid Common Tax Mistakes with RSUs
- 5 Bad Tax-Return Mistakes To Avoid With RSUs, Stock Options, And ESPPs (https://forbes.com/sites/brucebrumberg/2026/02/05/5-bad-tax-return-mistakes-to-avoid-with-rsus-stock-options-and-espps)
- 6 Common RSU Tax Mistakes (and How to Avoid Them) – Summitry (https://summitry.com/blog/common-rsu-tax-mistakes)
- Equity Compensation and Retirement Planning (https://executivewealthplanning.com/blog/what-should-i-consider-before-financing-an-early-stock-option-exercise)
- Understanding and Addressing RSU Double Taxation – Tidemark Financial Partners (https://tidemarkfp.com/rsu-double-tax)
- The 3 Biggest Tax Mistakes Executives Make With RSUs (And How to Avoid Them) — Quarry Hill Advisors (https://quarryhilladvisors.com/blog/the-3-biggest-tax-mistakes-executives-make-with-rsus?hs_amp=true)
- Consult a Financial Advisor for Personalized RSU Tax Planning
- RSU Tax Planning: Tips and Strategies | Citrine Capital (https://citrinecapitaladvisors.com/blog/rsu-tax-planning-guide)
- 77 Financial Advisor Quotes to Send to Clients (https://billgoodmarketing.com/resources/financial-advisor-quotes)
- Restricted Stock Unit Tax Planning – WestStar Prosperity Partners (https://weststarpartners.com/services/restricted-stock-unit-tax-planning)
- RSUs 101: A Tech Professional’s Guide to Equity, Tax Strategy, and Financial Planning (https://merceradvisors.com/investing/rsus-101-a-tech-professionals-guide-to-equity-tax-strategy-and-financial-planning)
- A new study finds that clients working with an advisor would see a 2.39%–2.78% annual return premium (based on investment and tax planning services) over those without an advisor, after accounting… | Michael Kitces (https://linkedin.com/posts/michaelkitces_weekend-reading-for-financial-planners-february-activity-7299473143427985409-W4D7)

Kevin has advised high-income W-2 tech and biotech families since 2015, and leads the education-first Age Five Family Office from Brea, California.
Connect on LinkedIn → · About KevinThis is part of how we approach Tax Management for high-income W-2 families at Bright Advisers.
Keep reading