

Key Highlights:
- Capital gains tax applies to profits made from selling a home, with rates up to 20% depending on income.
- Homeowners can exclude up to $250,000 (single) or $500,000 (married filing jointly) of capital gains from taxes if they meet residency requirements.
- To qualify for the exclusion, the home must be the seller’s primary residence for at least two of the last five years.
- Even if the exclusion applies, sales may need to be reported on tax returns if profits exceed the exclusion limits.
- Special circumstances such as job relocation or health issues may allow for partial exclusion from capital gains tax.
- Inherited properties receive a stepped-up basis, reducing potential taxes on appreciation that occurs after the inheritance.
- Gifts of equity in property transactions carry tax implications for both the giver and receiver, affecting future capital gains taxes.
- Only one property can qualify for the capital gains exclusion in a two-year period, necessitating careful planning for multiple property owners.
- Engaging a tax professional can provide personalised advice, future planning assistance, and peace of mind during the home sale process.
Introduction
Selling your house can feel overwhelming, especially for young families eager to secure their financial future. The tax implications, like capital gains tax and exclusion limits, can seem daunting, but understanding them is crucial. Imagine the peace of mind that comes from knowing how to navigate these waters effectively. What if unexpected situations arise, or if you own multiple properties? This article is here to guide you through essential steps and strategies that can empower you to master the tax process when selling your home. Together, we can ensure you keep more of your hard-earned money in your pocket, allowing you to focus on what truly matters – your family.
Explore Key Tax Concepts in Home Sales
When it comes to selling your home, grasping a few key tax concepts can make a world of difference for your family:
-
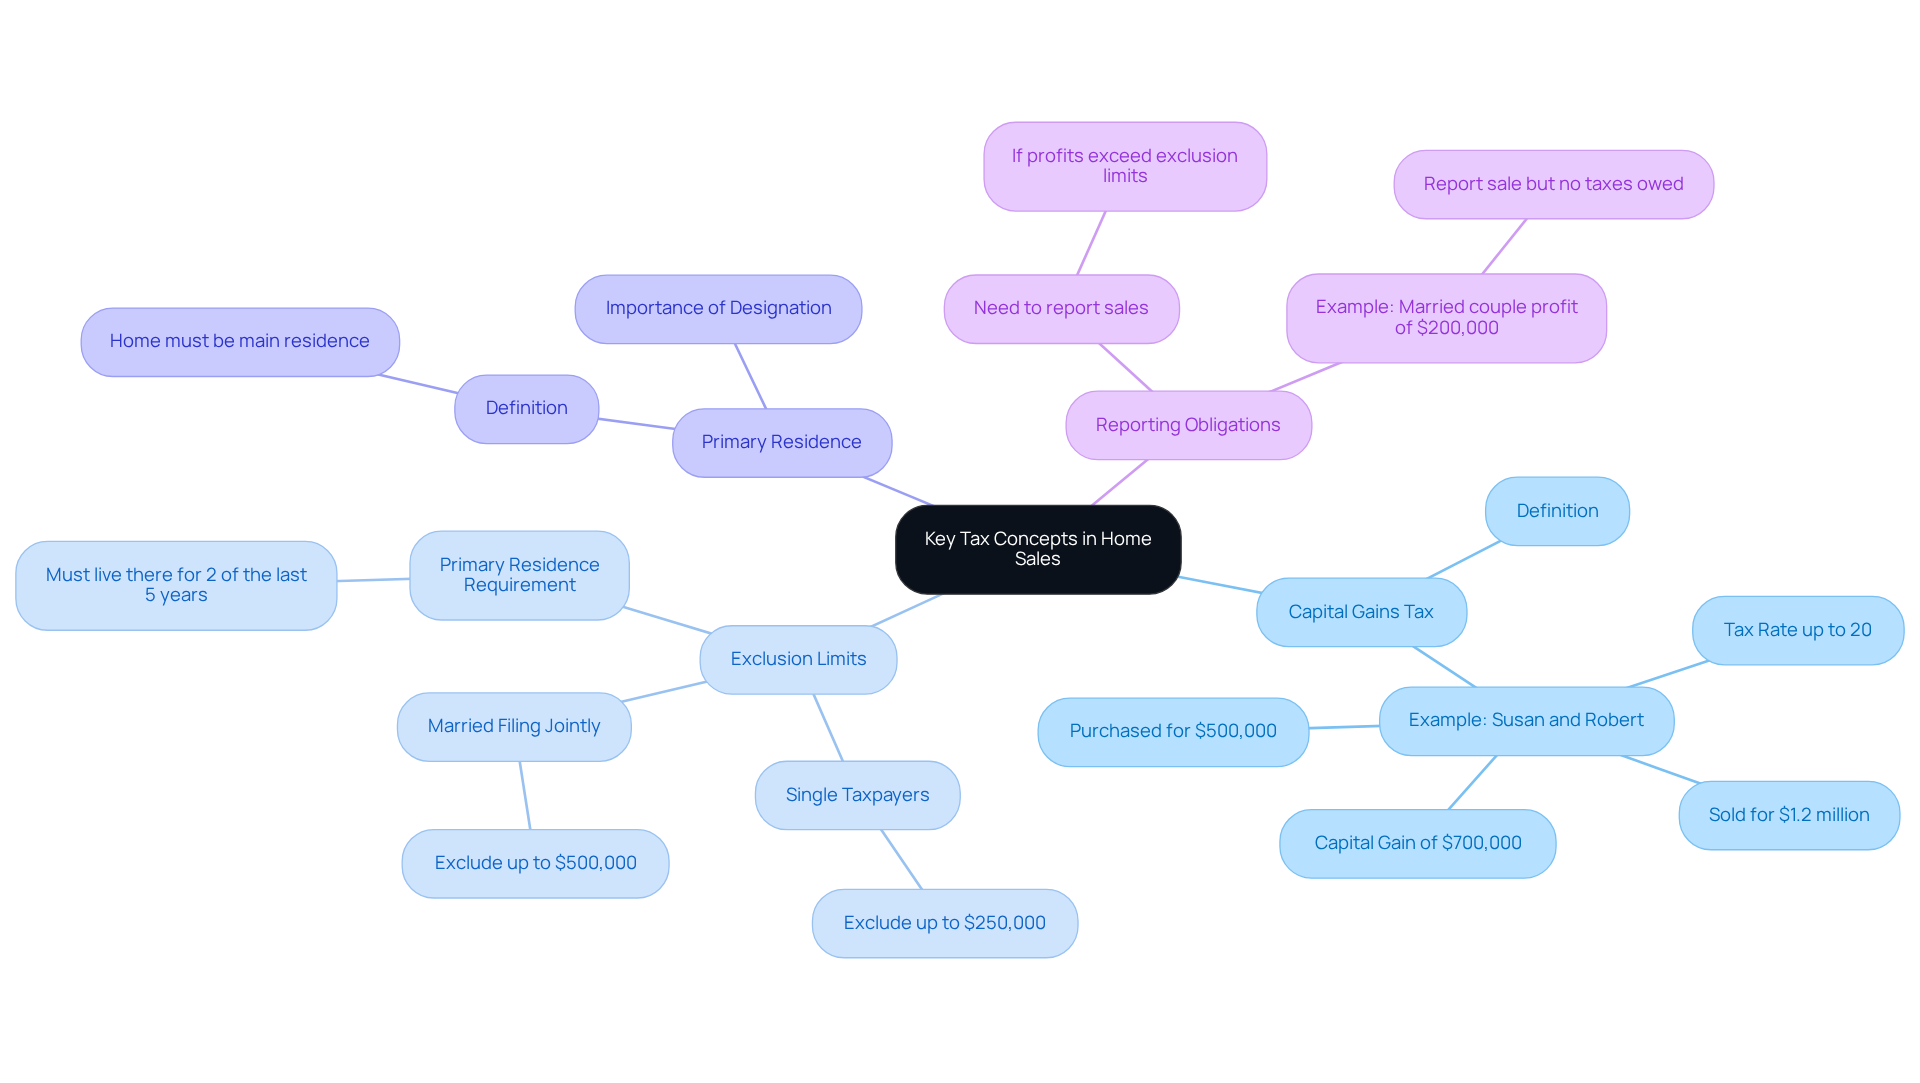
Capital Gains Tax: This is the tax on the profit you make from selling your home. If you sell your property for more than what you paid for it, that difference is considered a capital gain and may be taxed. For instance, if Susan and Robert sell their home for $1.2 million after buying it for $500,000, they have a capital gain of $700,000. The tax rate on this gain can vary, reaching up to 20% depending on your overall income and profit level.
-
Exclusion Limits: Good news for homeowners! You can exclude up to $250,000 of capital gains from taxes if you’re single, or up to $500,000 if you’re married and filing jointly. To qualify, you need to have lived in the home as your primary residence for at least two of the last five years. The IRS states, ‘You can sell your primary residence and be exempt from capital gains taxes on the first $250,000 if you’re single and $500,000 if married filing jointly.’ This exclusion can significantly lessen your taxable gains, helping many families avoid capital gains tax altogether.
-
Primary Residence: To take advantage of the exclusion, your home must be your primary residence. This means you need to have lived there for a significant amount of time, highlighting the importance of designating your property as your main home.
-
Reporting Obligations: Even if you qualify for the exclusion, you might still need to report the sale on your tax return, especially if your profits exceed the exclusion limits. For example, if a married couple sells their home and makes a profit of $200,000 after applying the exclusion, they still need to report the sale, but they won’t owe any taxes on that profit.
Understanding these concepts is crucial for families navigating the complexities of property transactions and the tax when selling a house. By staying informed, you can make decisions that truly benefit your family’s financial future. Remember, we’re here for you, and together, we can navigate this journey.
Calculate and Report Your Home Sale Taxes
Calculating and reporting the tax when selling a house can feel overwhelming, but we’re here to help you through it. Let’s break it down into manageable steps:
-
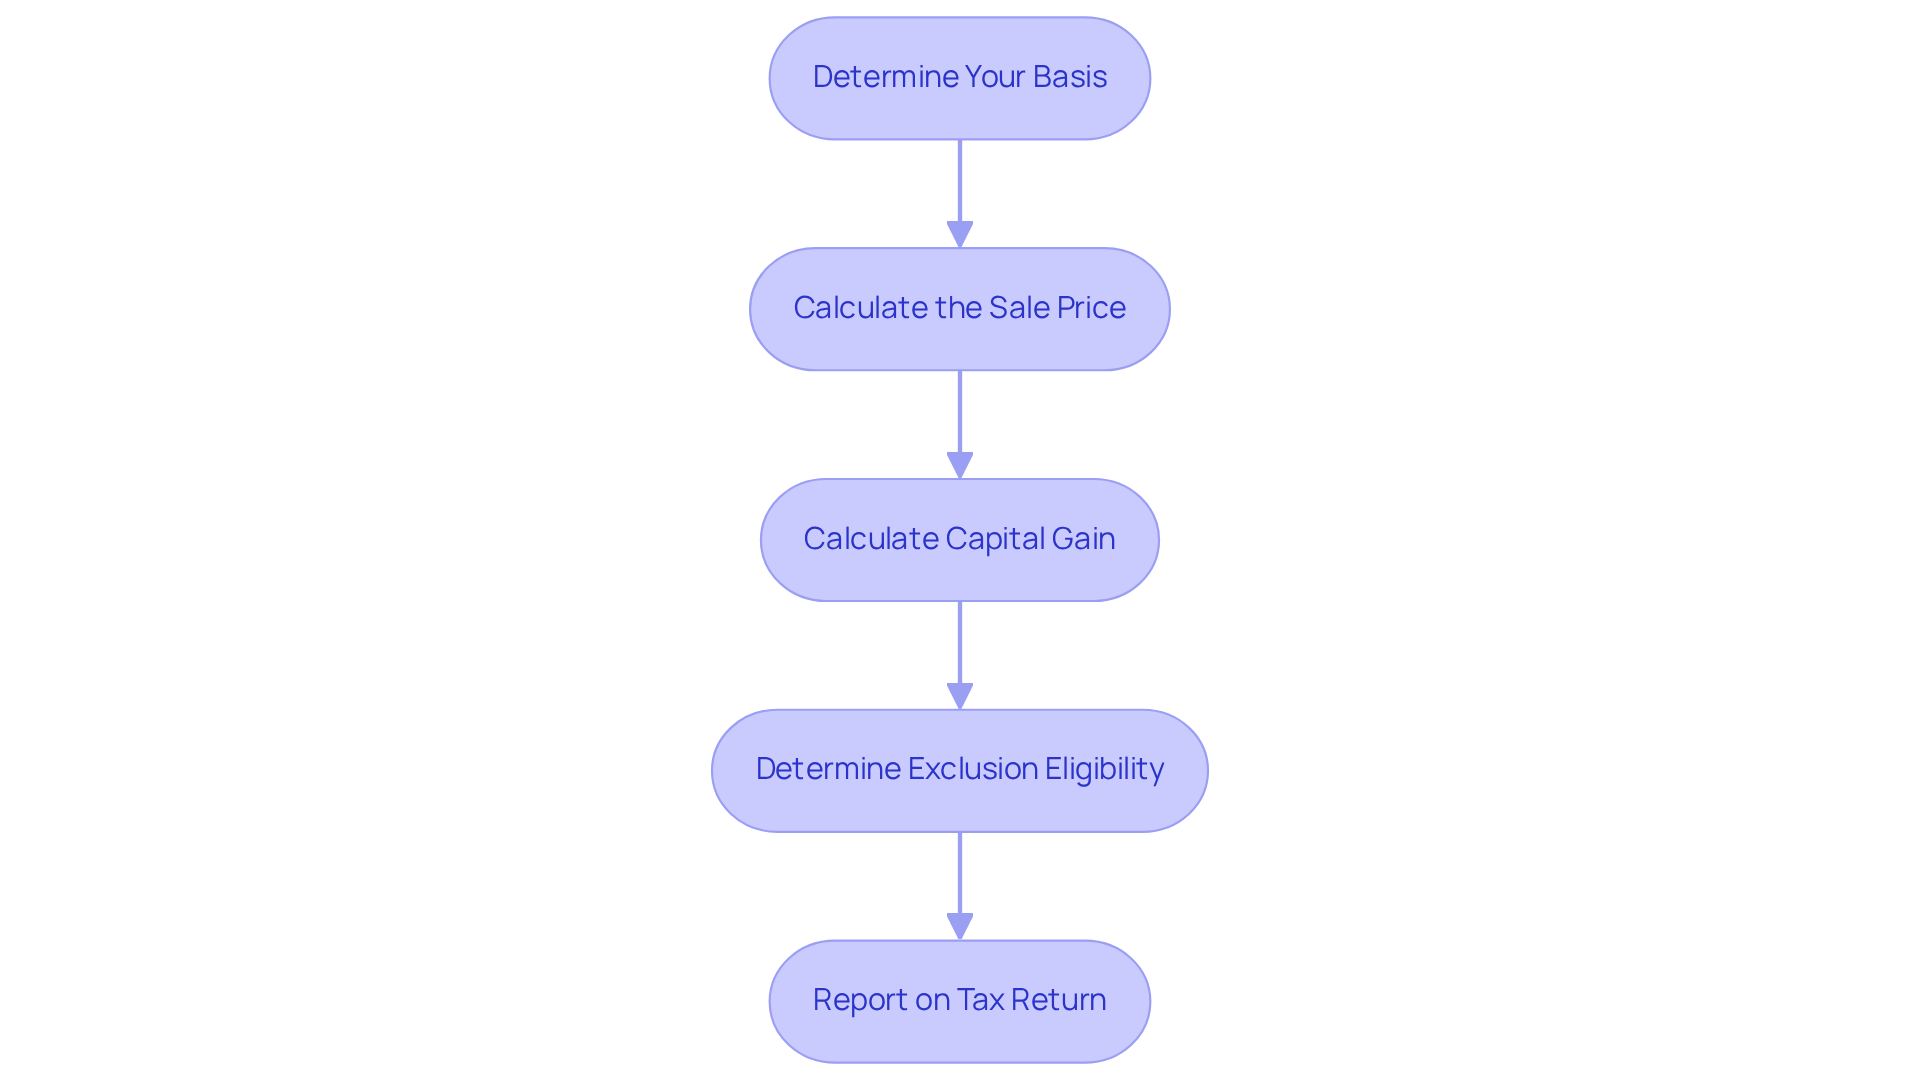
Determine Your Basis: Think of this as the foundation of your investment. It usually includes the purchase price of your property plus any improvements you’ve made. For instance, if you bought your home for $300,000 and spent $50,000 on renovations, your basis would be $350,000.
-
Calculate the Sale Price: This is the amount you sell your property for, minus any selling expenses like agent commissions and closing costs. If you sell your home for $500,000 and pay $30,000 in selling expenses, your effective selling amount is $470,000.
-
Calculate Capital Gain: Now, subtract your basis from the selling price. Using our earlier example, $470,000 (sale price) minus $350,000 (basis) gives you a capital profit of $120,000.
-
Determine Exclusion Eligibility: To qualify for a tax exclusion, you need to have lived in the property for at least two of the last five years. If you meet this requirement, you can deduct up to $250,000 (or $500,000 for married couples) from your capital profit. This could potentially lower your taxable profit to zero! As Sabrina Parys from NerdWallet points out, “You can exclude up to $250,000 in profits from a home transaction if you’re single, and up to $500,000 if you’re married filing jointly.”
-
Report on tax return: If your gain exceeds the exclusion, you’ll need to report it on IRS Form 8949 and Schedule D of your tax return, which includes tax when selling a house. If it doesn’t, you might not need to report the transaction at all.
Looking ahead, in 2026, average selling expenses for properties in the U.S. are expected to be around 6% of the selling price. This can significantly impact your net returns. For example, if you sell your property for $500,000, about $30,000 will be deducted for selling expenses, which affects your total profit.
Consulting with a tax advisor can provide clarity on how to determine your sale price and capital profit calculations, including the tax when selling a house. Together, we can navigate this journey and ensure you maximize your tax benefits.
Understand Special Tax Circumstances and Exclusions
Navigating the sale of your home can be daunting, especially when dealing with tax when selling a house. Understanding these nuances can empower you to make the most of your financial situation, and we’re here to help you through it.
-
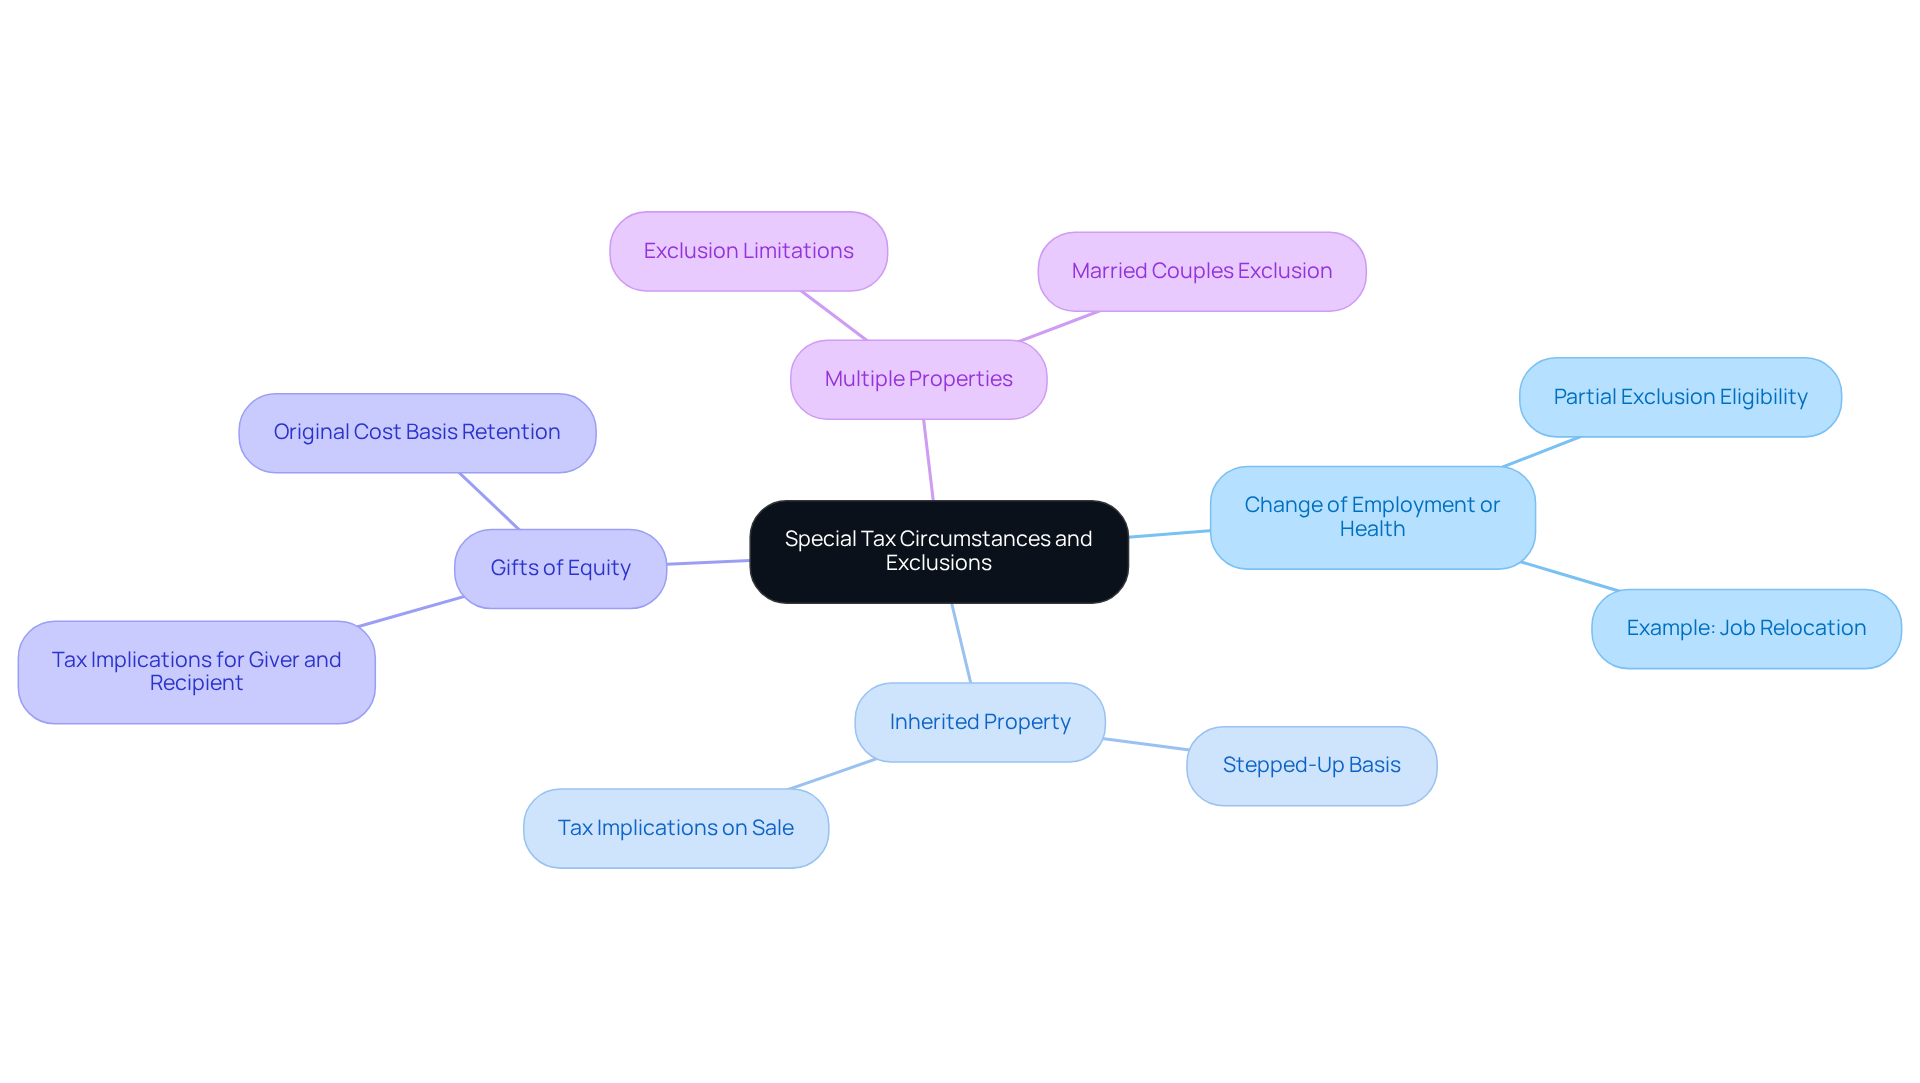
Change of Employment or Health: Imagine having to sell your home because of a job relocation or health issues. In such cases, you might qualify for a partial exclusion from tax when selling a house, even if you haven’t lived there for the full two years. This can be a lifeline for families facing unexpected changes, allowing you to keep more of your hard-earned profits. Just like Allison and Brian, who turned to Bright Advisers for guidance during their financial challenges, you too can find support.
-
Inherited Property: If you inherit a home, the tax basis is stepped up to its market value at the time of the owner’s passing. For instance, if a family residence bought for $100,000 is valued at $500,000 when inherited, this stepped-up basis can significantly reduce the tax when selling a house. You’ll only incur tax when selling a house on the appreciation that occurs after the inheritance. This strategy can be a vital part of your financial planning, much like the comprehensive approach embraced by clients of Bright Advisers.
-
Gifts of Equity: Selling your property to a family member for less than its market value might be seen as a gift of equity, which carries tax implications for both parties. It’s crucial to understand these implications to navigate such transactions wisely and avoid unexpected tax when selling a house. As CPA Victoria Nicole Cypert points out, ‘Gifted assets maintain your original cost basis, meaning the recipient may face higher capital gains taxes when they sell.’ This highlights the importance of strategic tax planning, especially regarding the tax when selling a house, as shown in the success story of Allison and Brian.
-
Multiple Properties: If you own more than one home, remember that only one can qualify for the exclusion in a two-year period. This limitation requires careful planning to determine which property to sell, ensuring you maximize your tax when selling a house benefits. For married couples filing jointly, you can exclude up to $500,000 of profit from the sale, making it a significant consideration for families aiming to manage their tax when selling a house. Just as Bright Advisers helped Allison and Brian secure their financial future with tailored strategies, you too can find the right path forward.
Together, we can navigate these complexities and ensure that your family’s financial future is bright.
Consult Tax Professionals for Tailored Guidance
Selling your home can feel overwhelming, but engaging with a tax professional can make a world of difference. Here’s how they can help you:
-
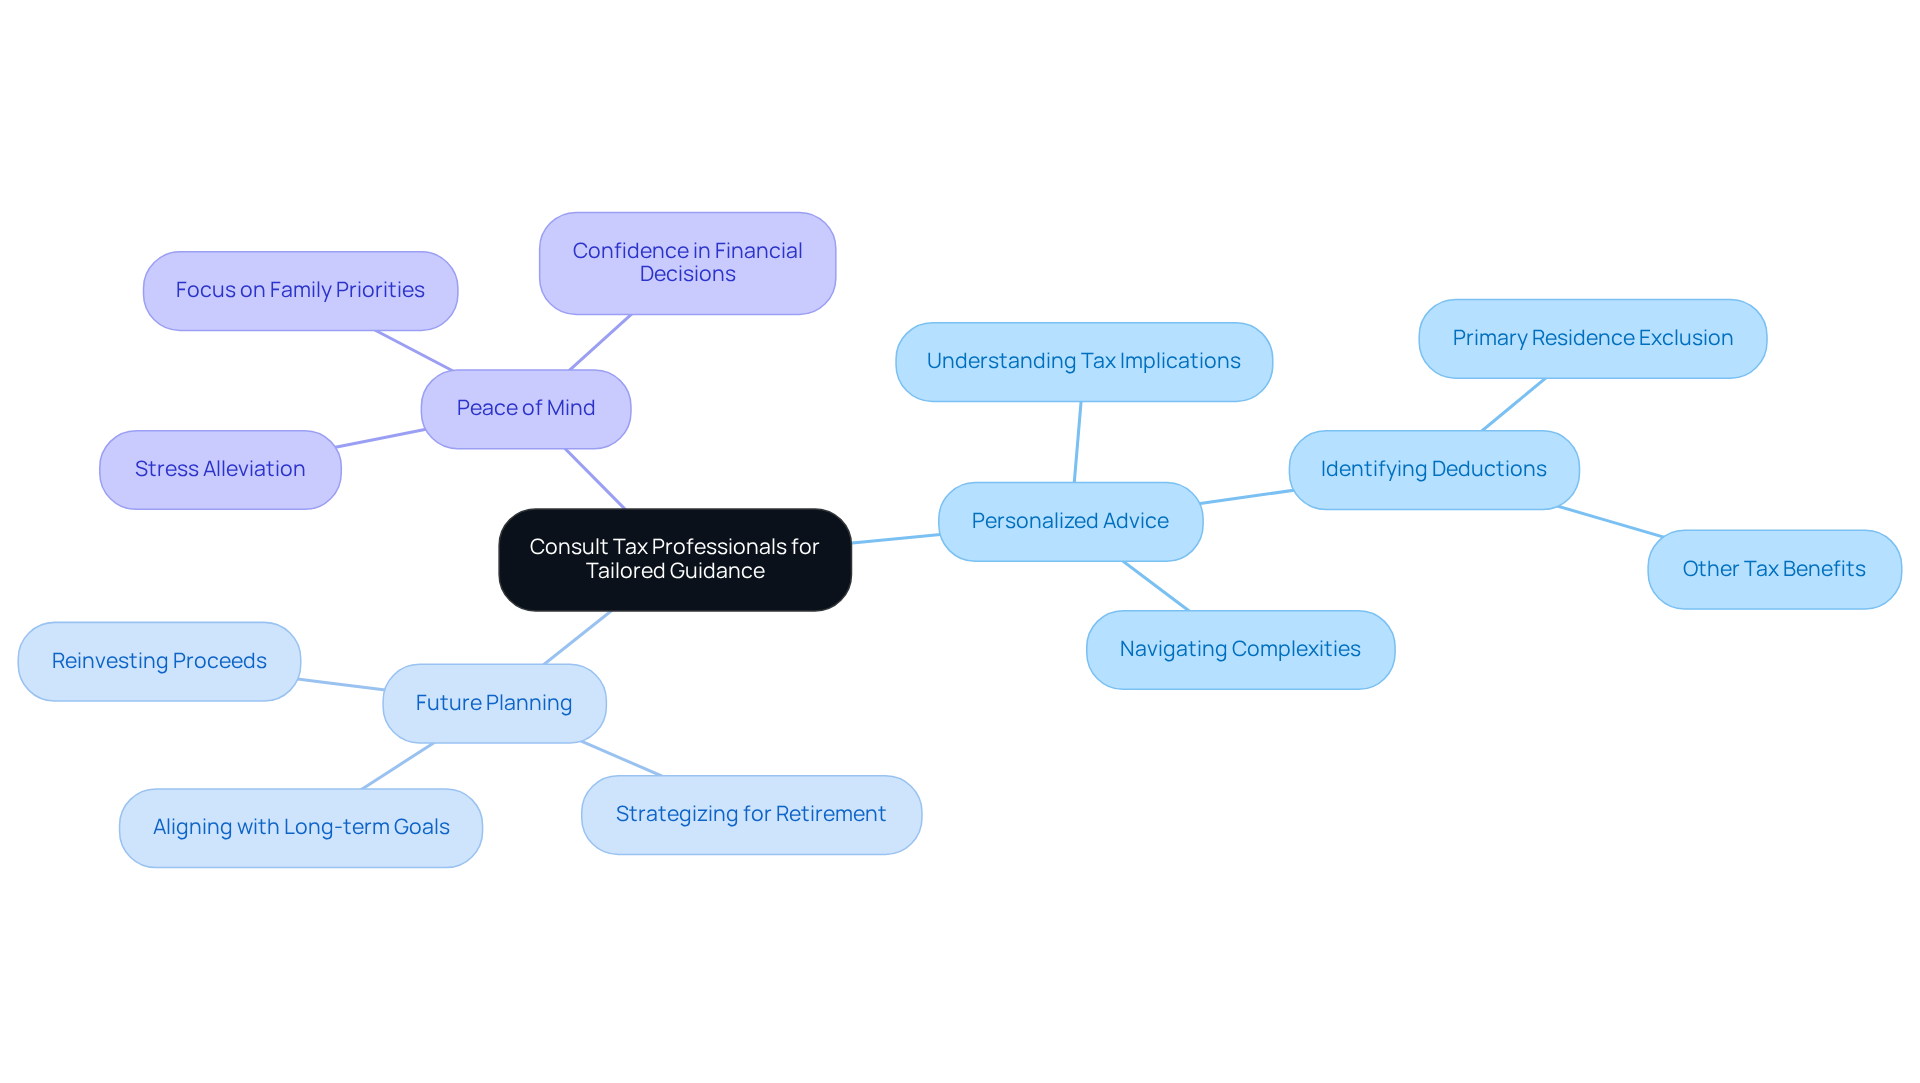
Personalized Advice: Imagine having someone who truly understands your unique situation. A tax professional can help you understand the implications of your sale and optimize your tax when selling a house outcomes. They’ll identify deductions and exclusions that could significantly lower your taxable gain, giving you peace of mind. Navigating complexities can be tricky, especially concerning tax when selling a house. A knowledgeable expert can guide you through these complexities, ensuring you stay compliant while maximizing your benefits. For instance, understanding the primary residence exclusion could help you save on tax when selling a house, potentially saving you thousands.
-
Future Planning: Think about what comes next. A tax advisor can assist you in planning for future financial decisions, like reinvesting your proceeds or strategizing for retirement. This foresight helps you make informed choices that align with your family’s long-term goals.
-
Peace of Mind: Knowing that an expert is handling your tax matters can alleviate stress. You can focus on what truly matters-your family and other priorities. With the right guidance, you can approach your home sale confidently, knowing you’re making the most of your financial situation.
Together, we can navigate this journey and ensure your family’s financial future is bright.
Conclusion
Navigating the tax implications of selling a home can feel overwhelming, especially for young families eager to secure their financial future. It’s crucial to grasp key concepts like capital gains tax, exclusion limits, and reporting obligations. This understanding can empower you to make informed decisions that significantly impact your family’s financial well-being.
Imagine determining your basis and calculating your capital gain with confidence. Recognizing special tax circumstances that may apply can be a game-changer. Families often benefit from exclusions that reduce taxable gains, particularly in situations like job relocations or inherited properties. Consulting with tax professionals can provide tailored guidance, ensuring you not only comply with tax regulations but also maximize your benefits during the home-selling process.
Ultimately, being informed about the tax landscape when selling your house allows you to make strategic decisions that align with your long-term goals. Engaging with experts can lead to better financial outcomes and peace of mind, letting you focus on what truly matters-building a brighter future together. Remember, we’re here for you, and together, we can navigate this journey.
Frequently Asked Questions
What is capital gains tax in the context of home sales?
Capital gains tax is the tax on the profit you make from selling your home. If you sell your property for more than you paid for it, the difference is considered a capital gain and may be taxed, with rates potentially reaching up to 20%.
What are the exclusion limits for capital gains tax when selling a home?
Homeowners can exclude up to $250,000 of capital gains from taxes if they are single, or up to $500,000 if they are married and filing jointly, provided they have lived in the home as their primary residence for at least two of the last five years.
What qualifies as a primary residence for the purpose of capital gains exclusion?
A primary residence is a home where you have lived for a significant amount of time, which is necessary to qualify for the capital gains exclusion.
Are there any reporting obligations when selling a home?
Yes, even if you qualify for the exclusion, you may still need to report the sale on your tax return, especially if your profits exceed the exclusion limits. For instance, a married couple making a profit of $200,000 after applying the exclusion must report the sale but won’t owe taxes on that profit.
Why is it important to understand these tax concepts when selling a home?
Understanding these concepts is crucial for families as it helps navigate the complexities of property transactions and tax implications, allowing for informed decisions that can benefit their financial future.
List of Sources
- Explore Key Tax Concepts in Home Sales
- Capital Gains Tax on Home Sales: How Taxes on Real Estate Work in 2026 – NerdWallet (https://nerdwallet.com/taxes/learn/selling-home-capital-gains-tax)
- 2026 Tax Brackets (https://taxfoundation.org/data/all/federal/2026-tax-brackets)
- Reducing or Avoiding Capital Gains Tax on Home Sales (https://investopedia.com/ask/answers/06/capitalgainhomesale.asp)
- 2025 and 2026 Capital Gains Tax Rates and Rules – NerdWallet (https://nerdwallet.com/taxes/learn/capital-gains-tax-rates)
- IRS unveils higher capital gains tax brackets for 2026 (https://cnbc.com/2025/10/09/capital-gains-tax-2026-federal.html)
- Calculate and Report Your Home Sale Taxes
- Capital gains tax on real estate (https://jacksonhewitt.com/tax-help/tax-tips-topics/real-estate/capital-gains-tax-on-home-sale)
- 2025 and 2026 Capital Gains Tax Rates and Rules – NerdWallet (https://nerdwallet.com/taxes/learn/capital-gains-tax-rates)
- Capital Gains Tax on House Sales: A Comprehensive Guide (https://westcoerealtors.com/capital-gains-tax-on-home-sale)
- Understanding Tax Basis Before Selling Your Home (https://innovativecpagroup.com/resources/newsarticles/understanding-tax-basis-before-selling-your-home)
- Determining Your Home’s Tax Basis (https://nolo.com/legal-encyclopedia/determining-your-homes-tax-basis.html)
- Understand Special Tax Circumstances and Exclusions
- All About the Stepped-Up Basis Loophole (https://smartasset.com/financial-advisor/stepped-up-basis)
- Important tax reminders for people selling a home | Internal Revenue Service (https://irs.gov/newsroom/important-tax-reminders-for-people-selling-a-home)
- Do You Qualify for the Home Gain Sale Exclusion? | Carr, Riggs & Ingram (https://criadv.com/insight/qualify-home-sale-gain-exclusion)
- Stepped-Up Basis: How It Affects Inherited Assets (https://randacpas.com/stepped-up-basis-how-it-affects-inherited-assets)
- How To Reduce Or Avoid Capital Gains Tax On Real Estate (https://sdocpa.com/avoid-capital-gains-tax-on-real-estate)
- Consult Tax Professionals for Tailored Guidance
- Top Benefits of Hiring a Real Estate Tax Accountant | Massey and Company CPA (https://masseyandcompanycpa.com/top-benefits-of-hiring-a-real-estate-tax-accountant)
- 2026 Real Estate Tax Opportunities for Investors and Property Owners | CBIZ (https://cbiz.com/insights/article/2026-real-estate-tax-opportunities-for-investors-and-property-owners)
- Alert (https://hcvt.com/alertarticle-12-Strategies-to-Maximize-After-Tax-Income)
- 130 Inspirational Quotes About Taxes (https://inc.com/geoffrey-james/130-inspirational-quotes-about-taxes.html)

Kevin has advised high-income W-2 tech and biotech families since 2015, and leads the education-first Age Five Family Office from Brea, California.
Connect on LinkedIn → · About KevinThis is part of how we approach Tax Management for high-income W-2 families at Bright Advisers.
Keep reading