

Key Highlights
- A testamentary trust ensures that a family’s wishes are honoured after death, providing comfort and security to loved ones.
- Key benefits include asset protection from creditors, management of assets by a trustee, tax advantages, and control over distribution.
- The step-up basis adjusts the cost basis of inherited properties to fair market value, eliminating capital gains taxes on appreciation during the decedent’s lifetime.
- Establishing a testamentary trust involves consulting an estate planning attorney, drafting a will, choosing a trustee, specifying trust terms, financing the fund, and regular reviews.
- Common challenges include accurately valuing assets, understanding the impact of different arrangements on tax advantages, and staying informed about local estate planning laws.
- Open communication with heirs about the estate plan can prevent confusion and familial disputes, which affect a significant percentage of U.S. adults.
Introduction
Imagine feeling confident about your family’s financial future, even when it comes to the complexities of estate planning. Understanding these intricacies can be overwhelming, but it’s essential for securing your family’s well-being.
Testamentary trusts can be a game-changer for families, providing a clear path to manage and protect your assets while easing tax burdens. Many parents feel overwhelmed by the thought of planning for the future, unsure of where to start.
But what if there was a way to simplify this process and ensure your family’s future is secure? Together, we can navigate this journey to ensure your legacy is protected and your loved ones are taken care of, no matter what life brings.
Define Testamentary Trust and Its Role in Estate Planning
Imagine the peace of mind that comes from knowing your family’s future is secure, even when you’re not there to guide them. A testamentary arrangement is a way to ensure your wishes are honored after you’re gone, providing comfort to your loved ones. It helps manage and distribute your belongings according to your wishes, making things easier for your family during a tough time.
For families like Jay and Emma, who want to reduce financial anxiety and ensure their children’s future security, testamentary trusts offer several critical benefits:
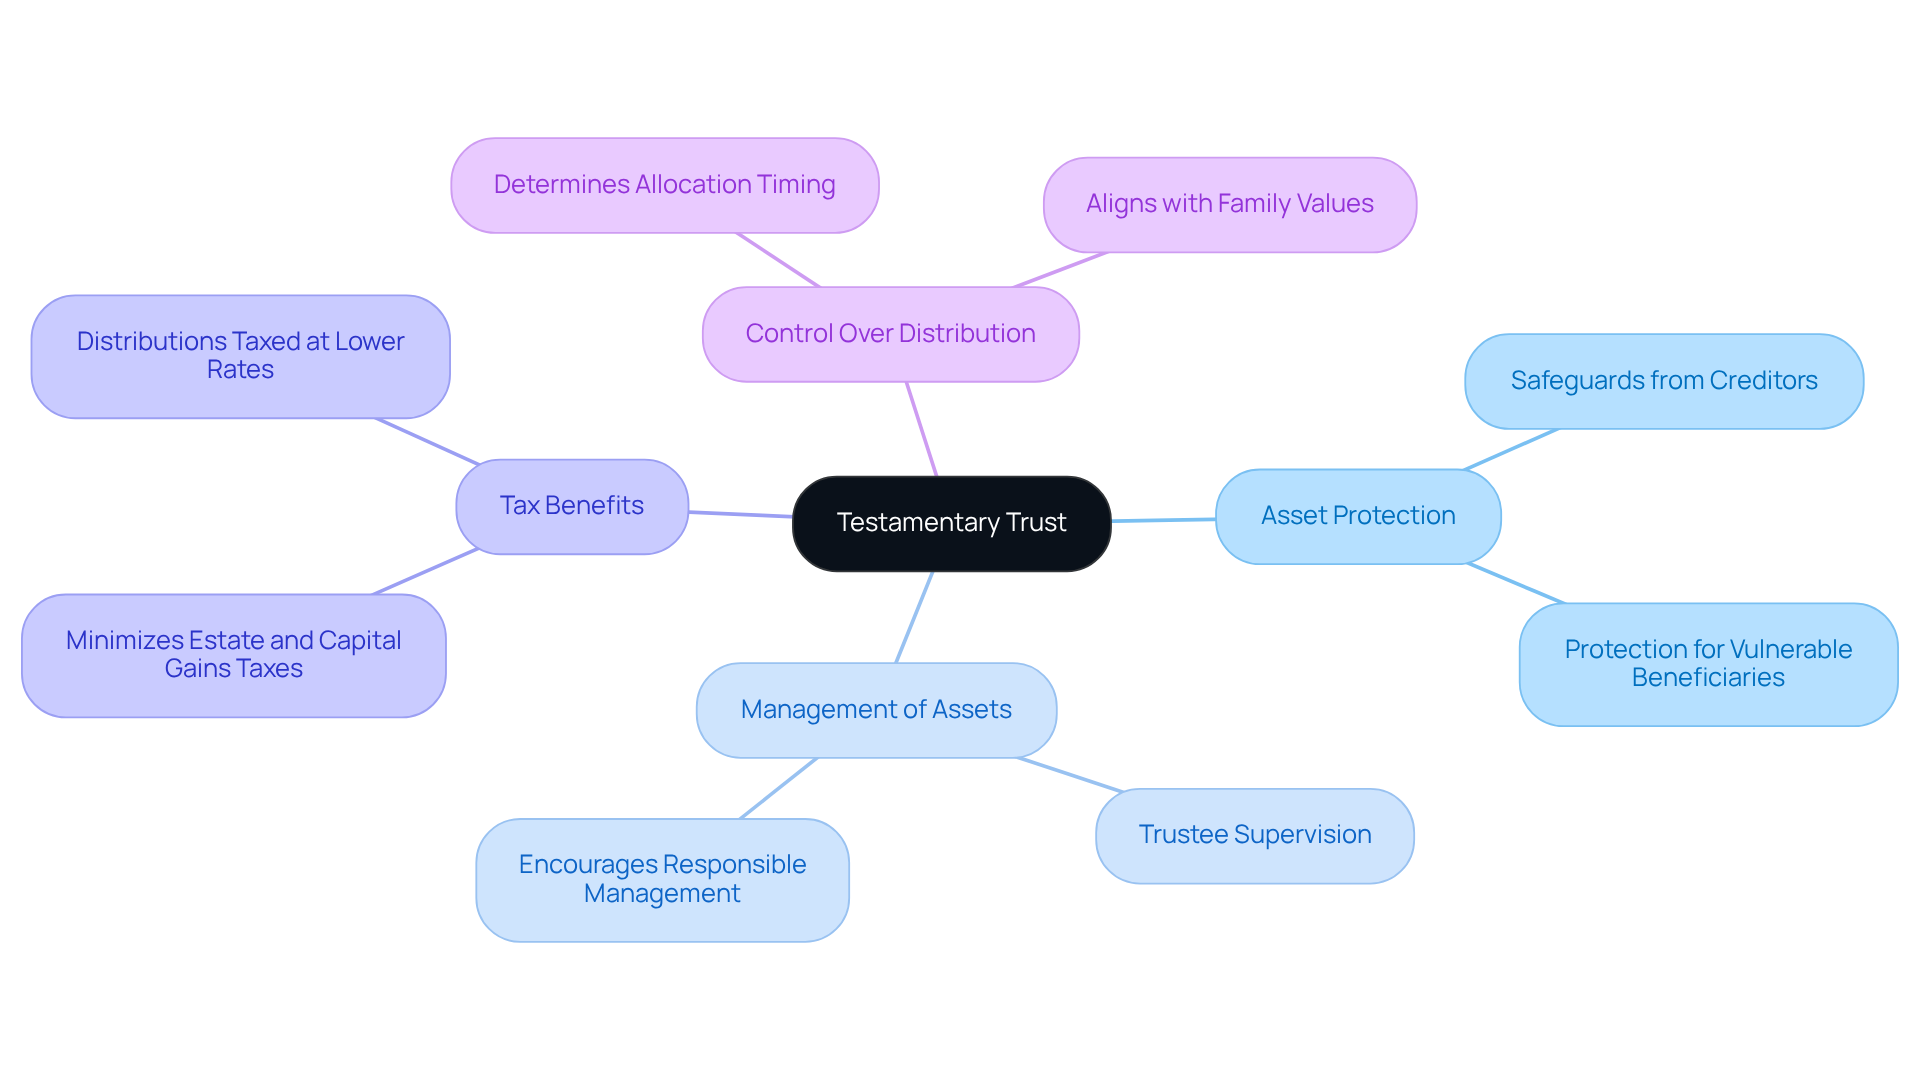
- Asset Protection: They safeguard assets from creditors, ensuring that beneficiaries receive their inheritance in a controlled manner, which is particularly beneficial for vulnerable beneficiaries.
- Management of Assets: A testamentary arrangement can designate a trustee to supervise the assets until the children reach a certain age or meet specific conditions, encouraging responsible resource management. This aligns with Bright Advisers’ dedication to empowering families through tailored planning.
- Tax Benefits: The testamentary trust step up basis can provide significant tax advantages, such as minimizing estate and capital gains taxes for beneficiaries. For instance, distributions to beneficiaries under 18 can be taxed at lower rates, enhancing the overall economic benefit. This is essential for households aiming to enhance their wealth growth and economic well-being.
- Control Over Distribution: The arrangement allows you to determine how and when resources are allocated, ensuring that your children are financially supported in a responsible manner and in line with your family’s values.
Understanding how testamentary arrangements work can help families feel more secure about their future, knowing their legacy will be cared for just as they intended. For example, families like Kate and Nick, who created testamentary arrangements for their children, can ensure that their assets are managed wisely until their children are ready to handle them on their own. This thoughtful planning not only keeps your family’s wealth safe but also teaches your children important lessons about money and responsibility.
It’s also important to know that in California, these arrangements go through a probate process, which means the court will need to confirm your wishes. Families should also be aware that if the trust earns more than $600 in income per year, beneficiaries may need to file a tax return. By leveraging the expertise of Bright Advisers, founded by Kevin Luu and Kathleen Chou in 2010, families can navigate these complexities and build a secure financial future. Together, we can navigate this journey and ensure your family’s legacy is not just preserved, but cherished for generations to come.
Explain Step-Up Basis and Its Application to Testamentary Trusts
Imagine facing the loss of a loved one while also worrying about the financial implications of their estate. The step-up basis can help ease that burden by adjusting the cost basis of inherited properties to their fair market value at the time of the original owner’s passing. This adjustment can lift a heavy weight off your shoulders, as it eliminates capital gains taxes on any appreciation that occurred during the deceased’s lifetime.
Here’s how it applies to testamentary trusts:
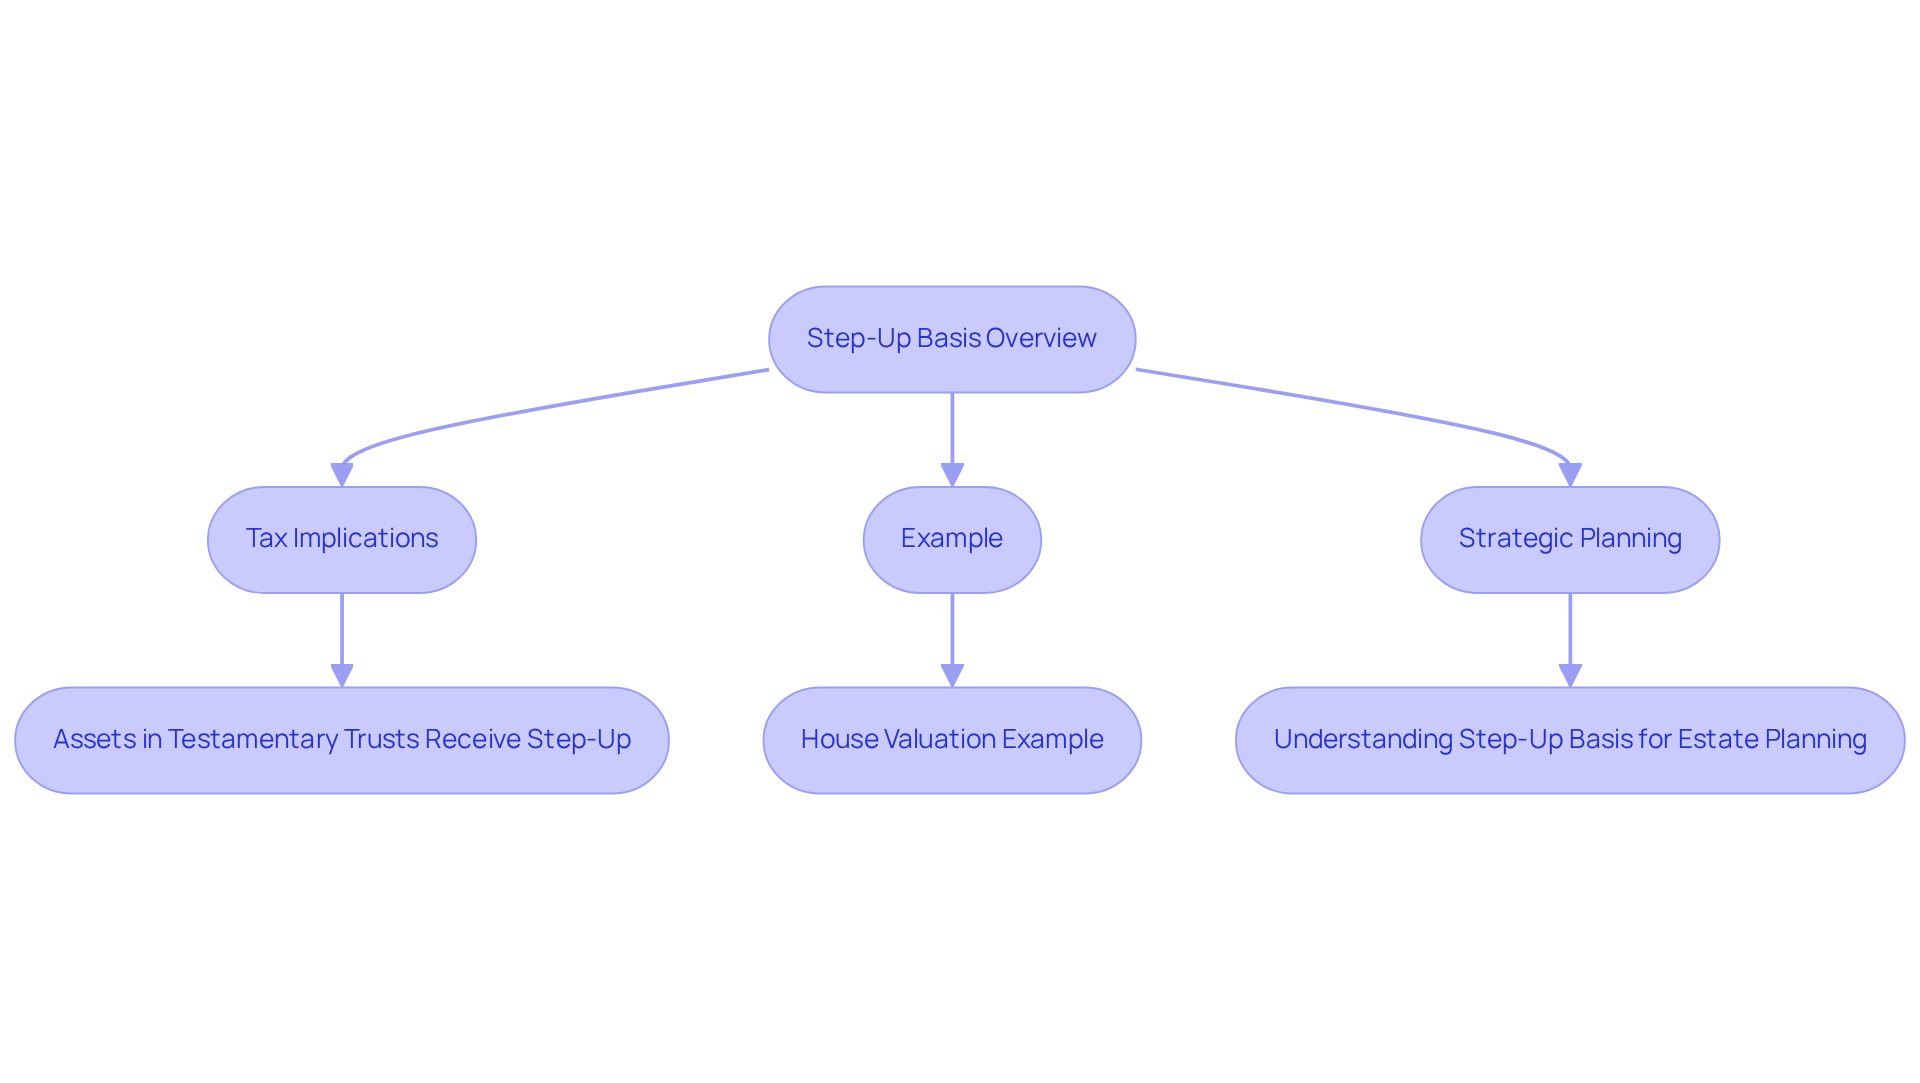
- Tax Implications: Assets placed in a testamentary trust typically receive a step-up in basis. This means beneficiaries can sell the inherited assets without incurring capital gains taxes on the appreciation that occurred before the decedent’s death.
- Example: Consider a scenario where a parent leaves a house valued at $500,000 at the time of their death, which they purchased for $300,000. The beneficiaries inherit the house with a new basis of $500,000. If they sell it for $550,000, they only pay capital gains tax on the $50,000 gain, rather than the $250,000 gain that would have been taxable if the original basis had been used.
- Strategic Planning: By understanding the step-up basis, you can thoughtfully structure your estate plan, ensuring your loved ones benefit from this tax advantage when they need it most. This is especially crucial for families in Southern California, where real estate values can significantly increase over time. By utilizing the testamentary trust step up basis, you can retain more wealth for future generations, making it a crucial factor in estate planning.
Together, we can navigate this journey, ensuring your family’s financial future is secure.
Outline Steps to Establish a Testamentary Trust
Imagine the peace of mind that comes from knowing your family’s future is secure, yet many families overlook a crucial step in safeguarding their legacy. Creating a testamentary trust step up basis is essential for families wanting to protect their financial well-being. Here are the essential steps to follow:
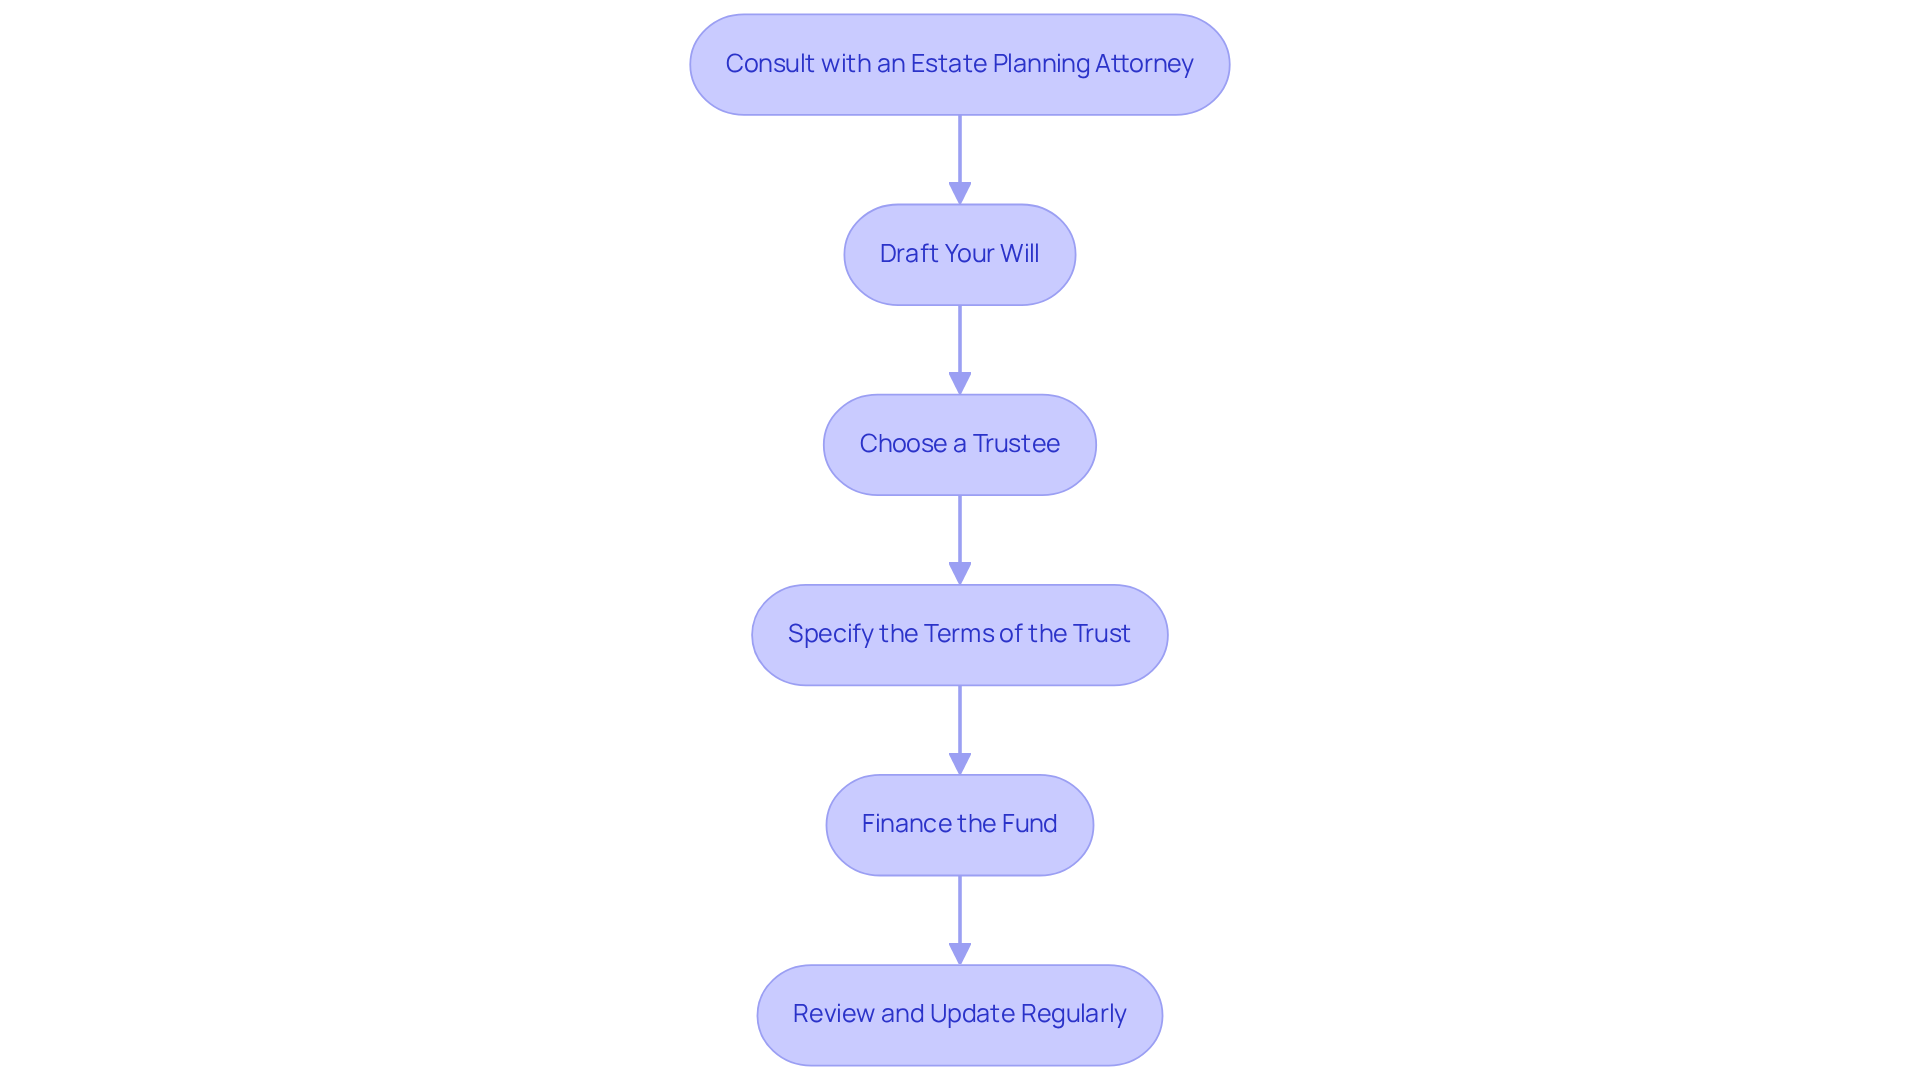
- Consult with an Estate Planning Attorney: Engage a qualified lawyer specializing in estate planning to navigate the complexities of state laws and ensure your arrangement is legally sound.
- Draft Your Will: Include specific provisions in your will that create the testamentary arrangement, detailing the trustee, beneficiaries, and management instructions for the resources.
- Choose a Trustee: Select a dependable person or organization to oversee the fund. This trustee will manage the resources and ensure adherence to the agreement’s conditions.
- Specify the Terms of the Trust: Clearly outline how and when resources will be distributed to beneficiaries, which may include conditions based on age milestones or educational achievements.
- Finance the Fund: While a testamentary arrangement is financed upon the grantor’s passing, it’s crucial to determine which resources will be incorporated and confirm they are recorded in the will.
- Review and Update Regularly: Periodically evaluate your will and the agreement terms to ensure they represent your current desires and household dynamics.
It’s surprising to learn that only 32% of families have taken this important step, leaving many without the security they deserve. Families that use testamentary arrangements can better manage their assets and care for their loved ones, ensuring a secure economic future. In California, the use of testamentary arrangements is increasingly acknowledged as a valuable resource for estate planning, especially for households with young children or intricate circumstances. By following these steps, households can effectively create a testamentary trust step up basis that aligns with their monetary objectives and safeguards their legacy.
At Bright Advisers, we provide extensive estate planning services, including estate plan review and drafting, to assist households like Jay & Emma in alleviating financial stress while preparing for their children’s education and their retirement. Our team is committed to assisting households in making prudent financial choices and maintaining wealth across generations. By taking these steps, you’re not just planning for the future; you’re ensuring your loved ones are cared for, no matter what life brings.
Identify Common Challenges and Considerations in Step-Up Basis Planning
Navigating the complexities of estate planning can feel overwhelming, especially when it comes to understanding the step-up basis and its implications for your family. While the step-up basis offers significant tax advantages, families face several common challenges and considerations.
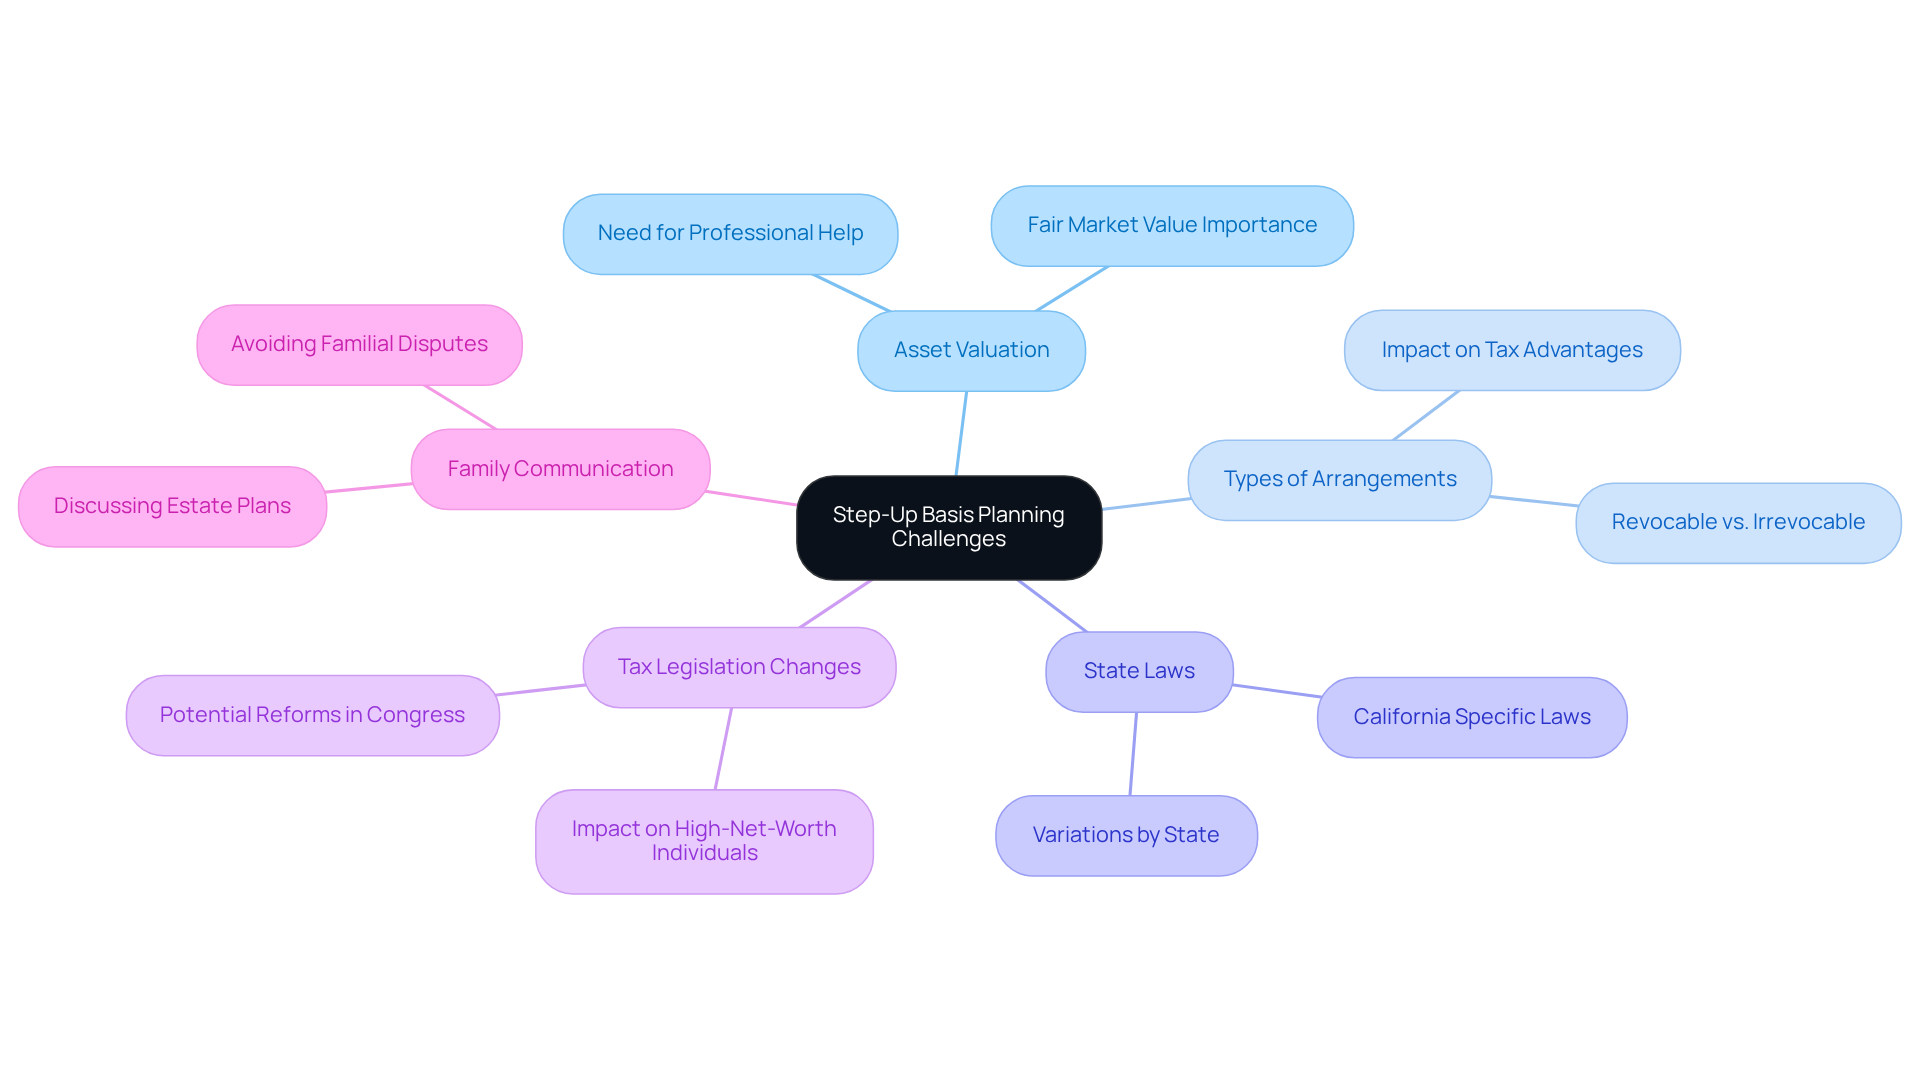
It’s important to know the fair market value of your assets when someone passes away, as this helps set the step-up basis. You might need to get professional help to value your assets correctly, as mistakes can lead to tax issues that complicate your family’s future.
The kind of arrangement you create can significantly influence the step-up basis. For instance, resources maintained in irrevocable arrangements may not obtain the same tax advantages as those in revocable arrangements. Knowing the differences can make a big difference in how smoothly your estate planning goes.
Estate planning laws differ by state, and it’s crucial to be aware of local regulations that may affect the creation and administration of a testamentary trust step up basis. In California, for example, specific laws can affect how assets are treated under the testamentary trust step up basis.
Families should also remain vigilant about potential changes in tax legislation that could impact the testamentary trust step up basis rule. Interacting with a financial consultant can assist households in adjusting their strategies to conform with changing regulations, especially as debates in Congress might result in reforms.
Talking openly with your loved ones about your estate plan can help avoid confusion and conflict later on. Ensuring that heirs understand the purpose and benefits of the testamentary trust is essential for smooth transitions and can mitigate familial disputes, which affect 35% of U.S. adults due to inadequate planning.
By addressing these challenges together, you can ensure your family’s future is secure and your estate planning efforts are truly effective.
Conclusion
Many families feel overwhelmed by the complexities of estate planning, especially when it comes to testamentary trusts and the step-up basis. By establishing a testamentary trust, families can ensure that their assets are managed according to their wishes, providing both protection and control over how wealth is distributed. This thoughtful approach not only safeguards the family’s legacy but also offers tax benefits that truly support their loved ones.
Throughout this article, we’ve shared key insights about the benefits of testamentary trusts, including asset protection and responsible management. We’ve also highlighted the crucial step-up basis that can alleviate tax burdens for heirs. The steps to establish a testamentary trust have been outlined, emphasizing the importance of legal guidance and regular reviews to adapt to changing family dynamics. Additionally, we’ve addressed common challenges in step-up basis planning, underscoring the need for professional assistance and open communication among family members.
Ultimately, estate planning is about ensuring that loved ones are cared for and that family values are preserved across generations. We’re here to help families navigate these complexities with confidence, ensuring they make informed decisions that align with their values. By taking these steps, families can ensure their legacy is not just preserved but cherished, allowing them to focus on creating lasting memories together.
Frequently Asked Questions
What is a testamentary trust?
A testamentary trust is a legal arrangement that ensures your wishes regarding asset distribution are honored after your death, providing comfort and security to your loved ones.
What are the benefits of a testamentary trust for families?
Testamentary trusts offer several benefits, including asset protection from creditors, management of assets by a designated trustee, potential tax advantages, and control over how and when resources are distributed to beneficiaries.
How does a testamentary trust protect assets?
It safeguards assets from creditors, ensuring that beneficiaries receive their inheritance in a controlled manner, which is especially beneficial for vulnerable beneficiaries.
Who manages the assets in a testamentary trust?
A trustee is designated to supervise the assets until the beneficiaries reach a certain age or meet specific conditions, promoting responsible management of resources.
What tax benefits can a testamentary trust provide?
A testamentary trust can minimize estate and capital gains taxes for beneficiaries, and distributions to beneficiaries under 18 can be taxed at lower rates, enhancing overall economic benefits.
How does a testamentary trust allow for control over asset distribution?
It enables you to determine how and when resources are allocated, ensuring that your children are financially supported in a manner that aligns with your family’s values.
What is the probate process in California for testamentary trusts?
In California, testamentary trusts go through a probate process, meaning the court must confirm your wishes regarding the trust.
Are there any tax implications for beneficiaries of a testamentary trust?
Yes, if the trust earns more than $600 in income per year, beneficiaries may need to file a tax return.
Who can help families navigate the complexities of testamentary trusts?
Bright Advisers, founded by Kevin Luu and Kathleen Chou in 2010, can assist families in navigating these complexities and building a secure financial future.
List of Sources
- Define Testamentary Trust and Its Role in Estate Planning
- The Benefits of Testamentary Trusts | BlueRock (https://bluerock.com.au/resources/the-benefits-of-testamentary-trusts)
- Milwaukee, Wisconsin Office (https://heritagelawwi.com/california-estate-planning-maximizing-benefits-with-testamentary-trusts)
- What Are the Benefits of Having a Testamentary Trust? (https://mblawfirm.com/insights/what-are-the-benefits-of-having-a-testamentary-trust)
- Explain Step-Up Basis and Its Application to Testamentary Trusts
- What Is the Step-Up in Basis? | ElmTree Law (https://elmtree.law/blog/what-is-step-up-in-basis)
- Capital Gains & Inheritance: What California Families Need to Know – Estate Planni Attorney (https://herbertlawoffice.com/knowledge-base/capital-gains-inheritance-what-california-families-need-to-know)
- Stepped-Up Basis on Inherited Property in California: Complete Guide (https://baytax.com/stepped-up-basis-california)
- California Step-up In Basis: Avoiding Costly Capital Gains Taxes | Corcoran Smith Law (https://corcoransmithlaw.com/blog/california-step-up-in-basis-avoiding-costly-capital-gains-taxes)
- Step-Up in Basis: How Heirs Reduce Capital Gains on Inherited Property? (https://schorr-law.com/step-up-in-basis-for-heirs)
- Outline Steps to Establish a Testamentary Trust
- 5 Eye-Opening Statistics About Estate Planning – Nickerson Law: A Professional Corporation (https://jeffreycnickersonlaw.com/blog/5-eye-opening-statistics-about-estate-planning)
- 50 Estate Planning Statistics and Facts You Need to Know (https://justvanilla.com/blog/estate-planning-statistics-and-facts-you-need-to-know)
- Alarming Estate Planning Statistics (https://financialsense.com/blog/21022/alarming-estate-planning-statistics)
- Identify Common Challenges and Considerations in Step-Up Basis Planning
- 50 Estate Planning Statistics and Facts You Need to Know (https://justvanilla.com/blog/estate-planning-statistics-and-facts-you-need-to-know)
- Capital Gains and the Step-Up in Basis: Estate Planning Tactics, Compliance Traps, and Post-Death Planning Tools (https://mylawcle.com/products/capital-gains-and-the-step-up-in-basis-estate-planning-tactics-compliance-traps-and-post-death-planning-tools)
- Wealth Planning, Administration, and Fiduciary Disputes (https://robinskaplan.com/services/wealth)
- Alarming Estate Planning Statistics (https://financialsense.com/blog/21022/alarming-estate-planning-statistics)
- Step-Up in Basis Rule: How It Works at Death (2026 Guide) (https://curchin.com/curchin-blog/comprehensive-guide-on-the-step-up-in-basis-rule)

Kevin has advised high-income W-2 tech and biotech families since 2015, and leads the education-first Age Five Family Office from Brea, California.
Connect on LinkedIn → · About KevinThis is part of how we approach Estate Planning for high-income W-2 families at Bright Advisers.
Keep reading