

Key Highlights:
- The 199A tax code, established by the Tax Cuts and Jobs Act of 2017, allows eligible taxpayers to deduct up to 20% of their Qualified Business Income (QBI) from pass-through entities.
- QBI is defined as net income from a qualified trade or business, excluding capital gains, dividends, and interest income.
- Eligible taxpayers include individuals, trusts, and estates, primarily targeting non-corporate taxpayers.
- The deduction is limited to the lesser of 20% of QBI or 20% of taxable earnings minus net capital gains, with increased income thresholds of $75,000 for individuals and $150,000 for joint filers.
- A minimum QBI allowance of $400 applies for those with at least $1,000 in QBI, indexed for inflation.
- The QBI deduction was made permanent, originally set to expire after 2025, providing ongoing tax relief.
- Eligibility criteria include the type of business, income thresholds, business structure, and limitations based on W-2 wages and property.
- To calculate the QBI deduction, determine total QBI, taxable income, and apply the 20% deduction while considering W-2 wages if applicable.
- Accurate reporting involves gathering documentation, completing IRS Form 8995 or 8995-A, and maintaining records for at least three years.
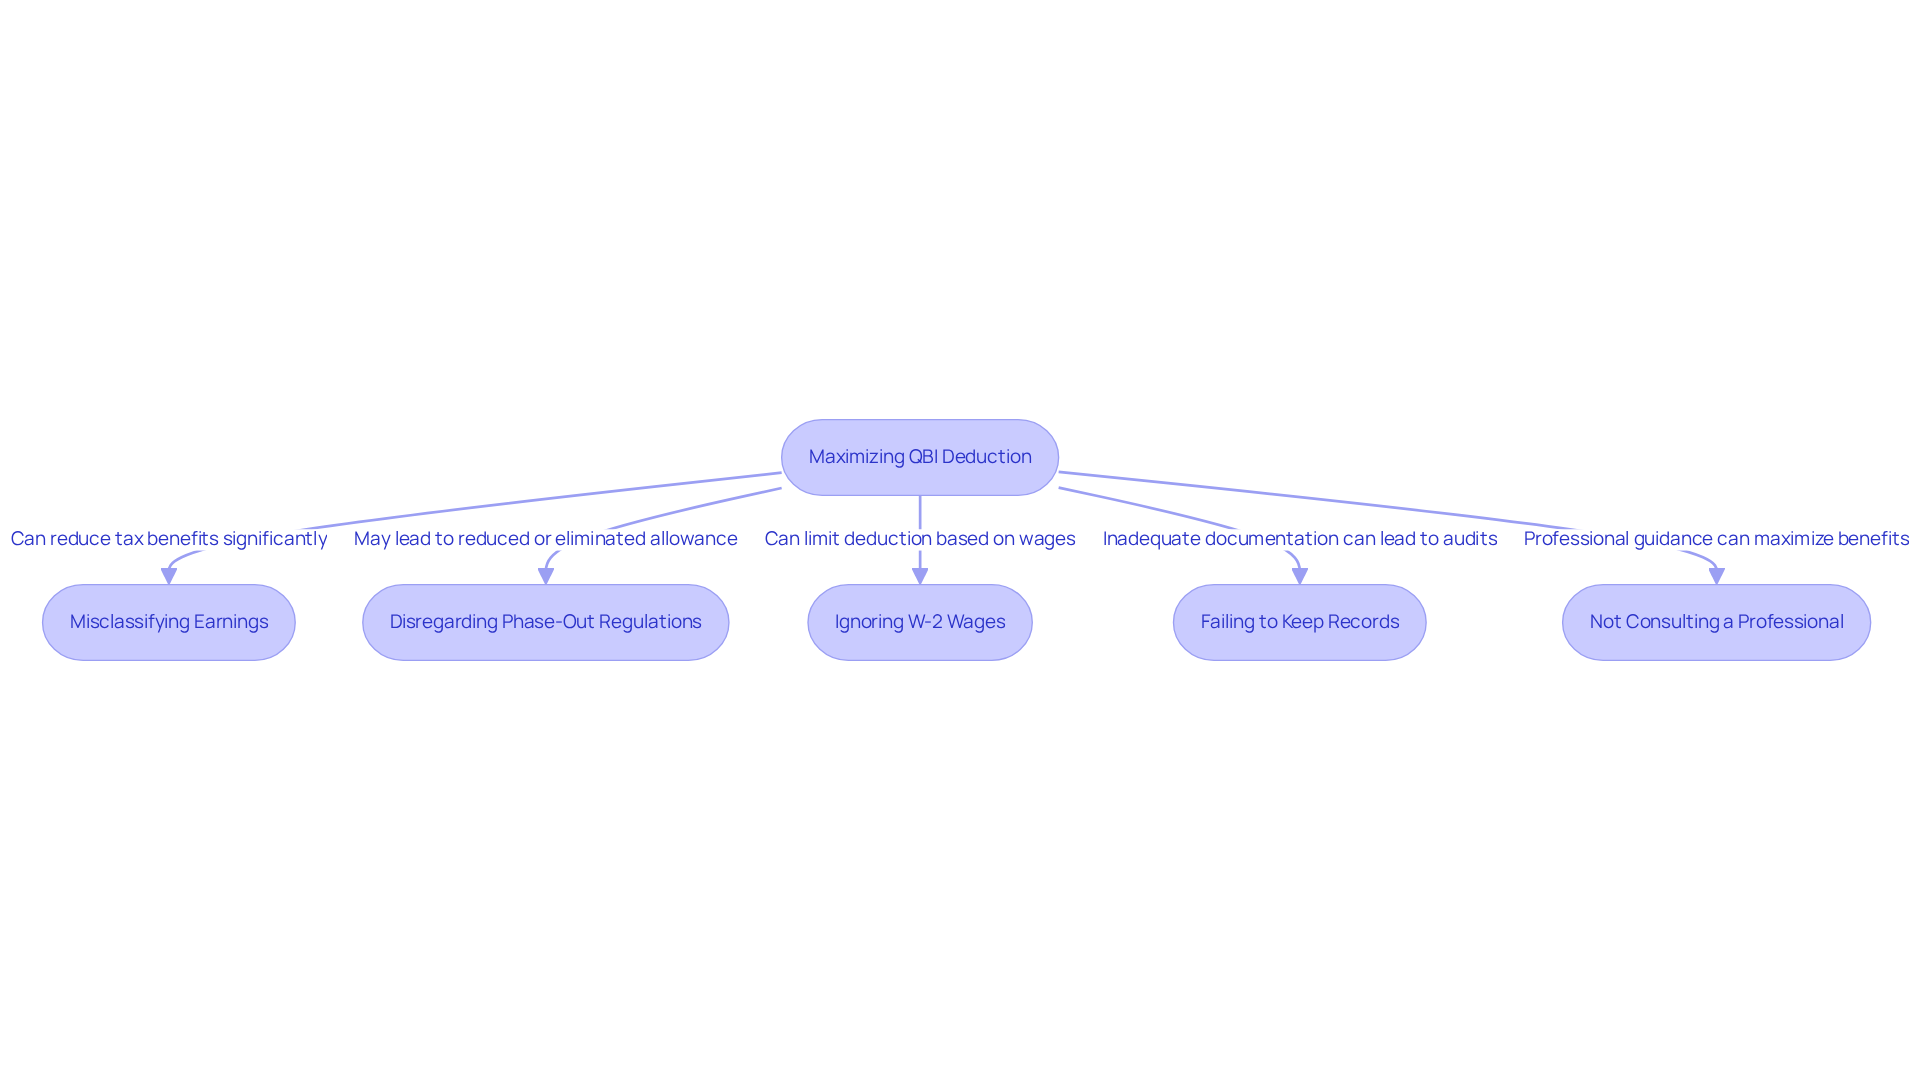
- Common pitfalls include misclassifying earnings, ignoring phase-out regulations, failing to keep adequate records, and not consulting tax professionals.
Introduction
Navigating the 199A tax code can feel overwhelming, especially for young families juggling their financial responsibilities. This tax provision, introduced under the Tax Cuts and Jobs Act of 2017, offers a chance for eligible taxpayers to deduct a significant portion of their qualified business income. It’s a valuable opportunity for financial relief that could make a real difference in your family’s budget.
But understanding the eligibility criteria and calculation methods can be tricky. Many families find themselves confused, and it’s easy to stumble into common pitfalls. Imagine if you could confidently maximize your benefits while steering clear of mistakes in this complex landscape.
We’re here for you, ready to help you navigate these challenges. Together, we can explore how to make the most of the 199A tax code, ensuring that you’re not leaving any potential savings on the table. Let’s take this journey together, focusing on what truly matters-your family’s financial well-being.
Understand the 199A Tax Code Basics
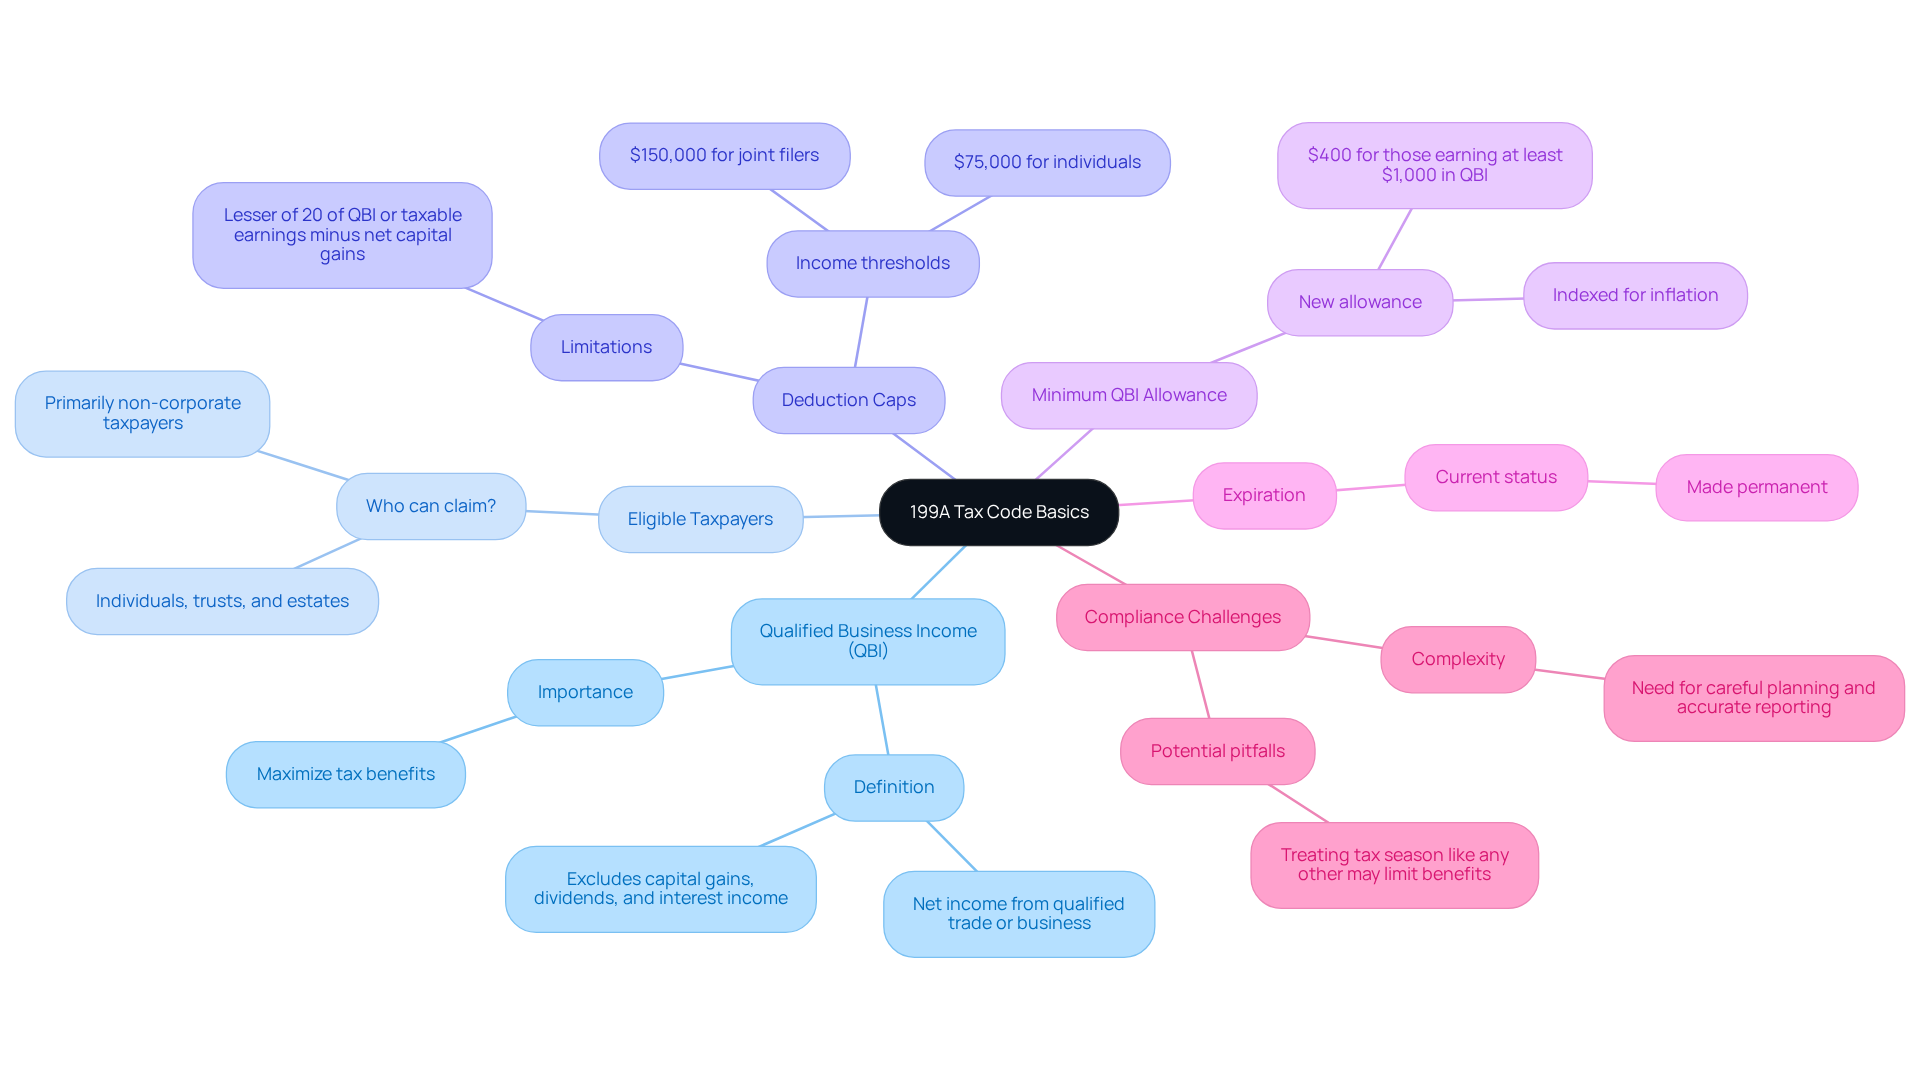
Understanding the can feel overwhelming, but it’s crucial for small business owners and self-employed individuals. Created under the Tax Cuts and Jobs Act of 2017, this code allows qualified taxpayers to deduct up to 20% of their eligible earnings (QBI) from specific pass-through entities like sole proprietorships, partnerships, and S corporations. This provision is designed to provide much-needed tax relief, helping you focus on what truly matters – your family and your business.
Let’s break it down together:
- Qualified Business Income (QBI): This is the net income from a qualified trade or business, excluding capital gains, dividends, and interest income. It’s important to know what counts as QBI to maximize your benefits.
- Eligible Taxpayers: Individuals, trusts, and estates can claim this benefit, but it primarily targets non-corporate taxpayers. If you’re running your own business, you’re likely eligible!
- Deduction Caps: The deduction is limited to the lesser of 20% of QBI or 20% of taxable earnings minus net capital gains. Good news! The income thresholds for additional limits have increased, making it easier for you to qualify – $75,000 for individuals and $150,000 for joint filers.
- Minimum QBI Allowance: There’s a new minimum QBI allowance of $400 for those earning at least $1,000 in QBI, which is indexed for inflation. This means even small earnings can still benefit you.
- Expiration: Originally set to expire after 2025, recent changes have made this tax benefit permanent. This is a win for eligible taxpayers, providing ongoing support for your financial journey.
- Compliance Challenges: Navigating the complexities of the 199a tax code can be tricky. It’s essential to plan carefully and report accurately to ensure you’re making the most of this opportunity.
By grasping these fundamentals, you’ll be better prepared to assess your eligibility and calculate your deduction. As Fiona Chambers, a Partner in Business Tax Services, wisely notes, “The numerous complexities associated with the new pass-through allowance mean that treating this tax season like any other may restrict the advantages of the allowance.”
Remember, you’re not alone in this. Together, we can navigate these financial waters and ensure you’re getting the support you need.
Identify Eligibility for the QBI Deduction
Understanding the QBI deduction can feel overwhelming, but we’re here to help you navigate it with ease. To qualify, there are specific criteria you should be aware of:
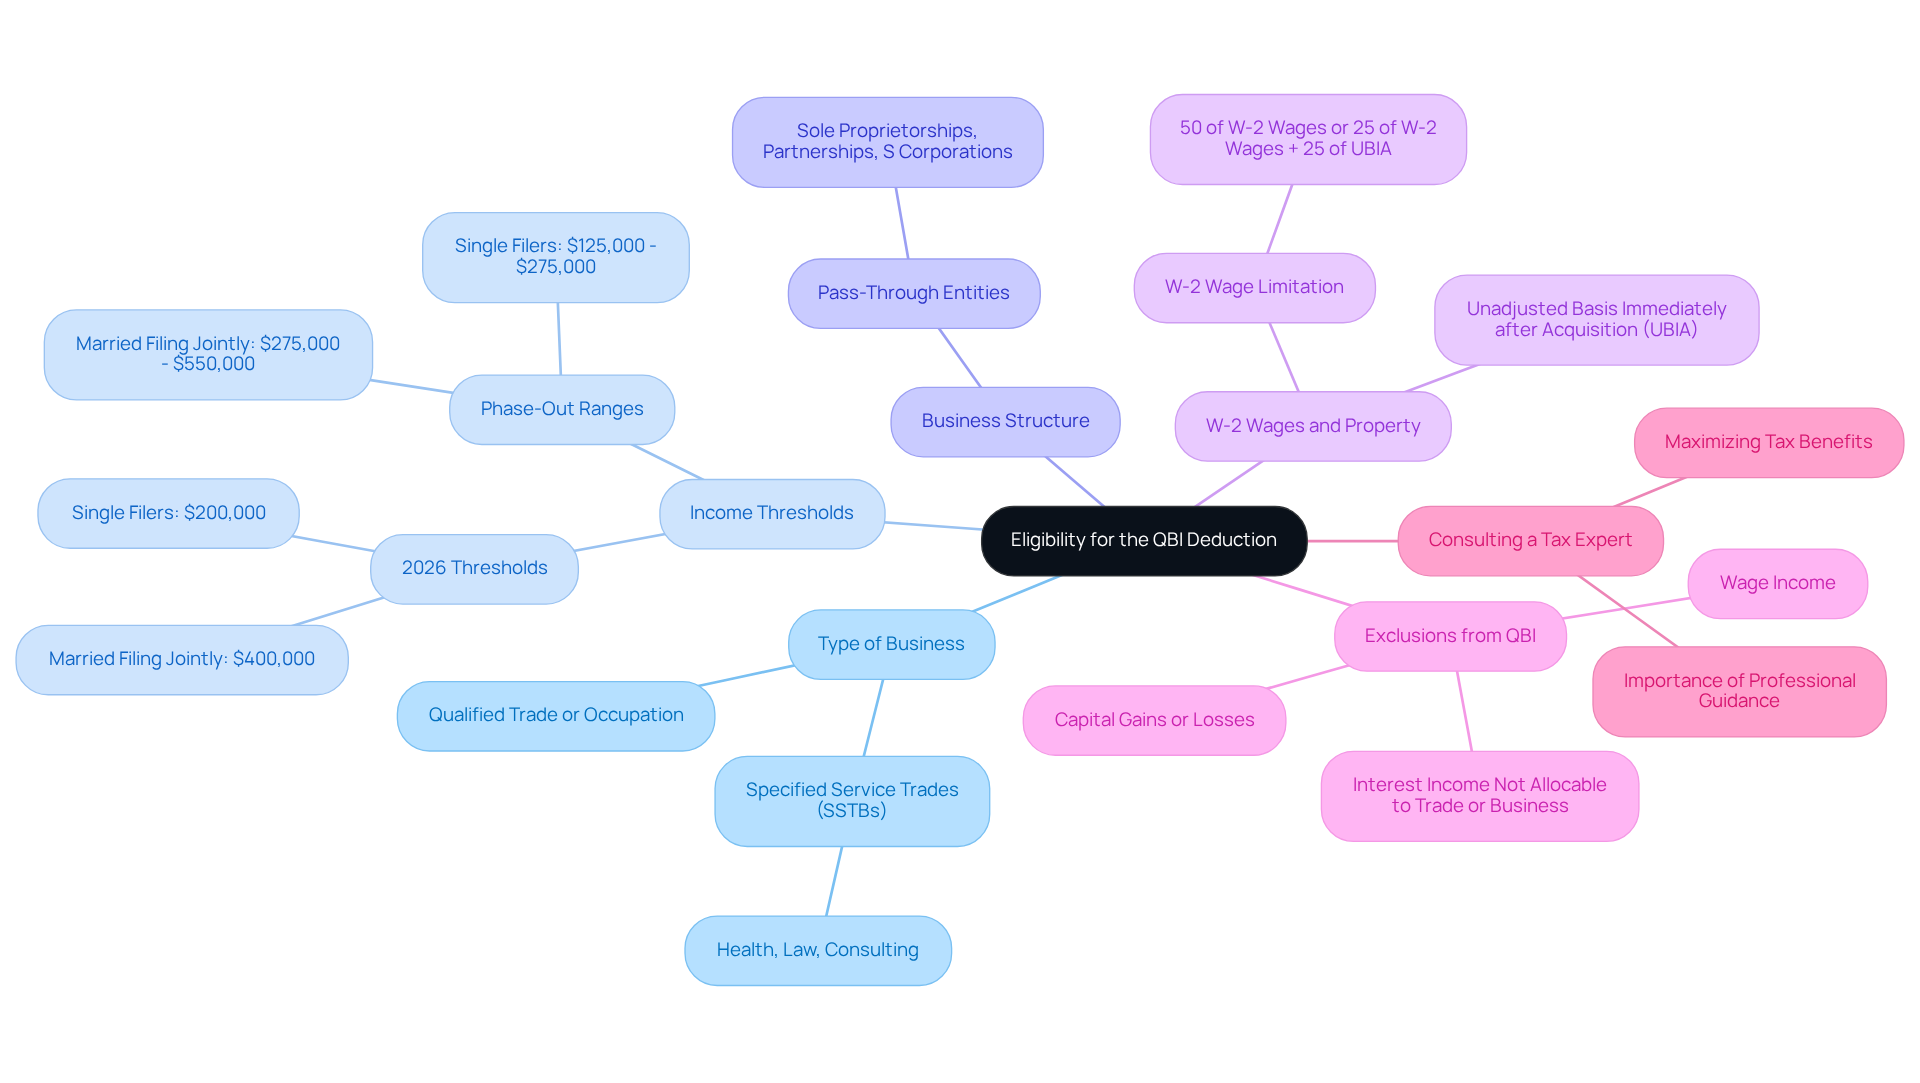
- Type of Business: Your business needs to operate as a qualified trade or occupation. Generally, certain service trades or professions (SSTBs) like health, law, and consulting are excluded if your taxable earnings go beyond certain thresholds.
- Income Thresholds: For the tax year 2026, the thresholds are around $400,000 for married couples filing jointly and $200,000 for single filers. If your income is below these amounts, you can claim the full allowance. However, if you exceed these thresholds, you might see a phased-out benefit.
- Business Structure: The QBI allowance applies to earnings from pass-through entities. This means your business earnings are reported on your personal tax returns rather than being taxed at the corporate level. This structure can be a great advantage for many small businesses and self-employed individuals, like Jay and Emma, who have successfully worked with Bright Advisers to manage their financial planning.
- W-2 Wages and Property: If your taxable earnings exceed the thresholds, the allowance may be limited based on the your business pays or the unadjusted basis of qualified property. For instance, if a construction firm has $200,000 in W-2 wages, this amount can influence the QBI reduction calculation.
- Exclusions from QBI: It’s crucial to understand that certain types of income, such as capital gains or losses, interest income not tied to a trade or business, and wage income, are excluded from the definition of QBI. Knowing these exclusions is key to accurately calculating your QBI and determining your eligibility for the benefit.
- Consulting a Tax Expert: Given the complexities of the QBI allowance, we encourage young families to consult a tax expert. This guidance can help you maximize your tax benefits while ensuring compliance with all relevant regulations. Bright Advisers is here to empower families like Emily and Mark to create comprehensive financial strategies that align with their goals, preparing them for a secure financial future.
By understanding these criteria, you can better grasp your eligibility for the QBI benefit and how it can positively impact your overall tax strategy. Together, we can navigate this journey and ensure your family’s financial well-being.
Calculate Your QBI Deduction
Calculating your QBI deduction can feel overwhelming, but we’re here to help you through it. Let’s break it down step by step, so you can feel confident in maximizing your tax benefits for your family.
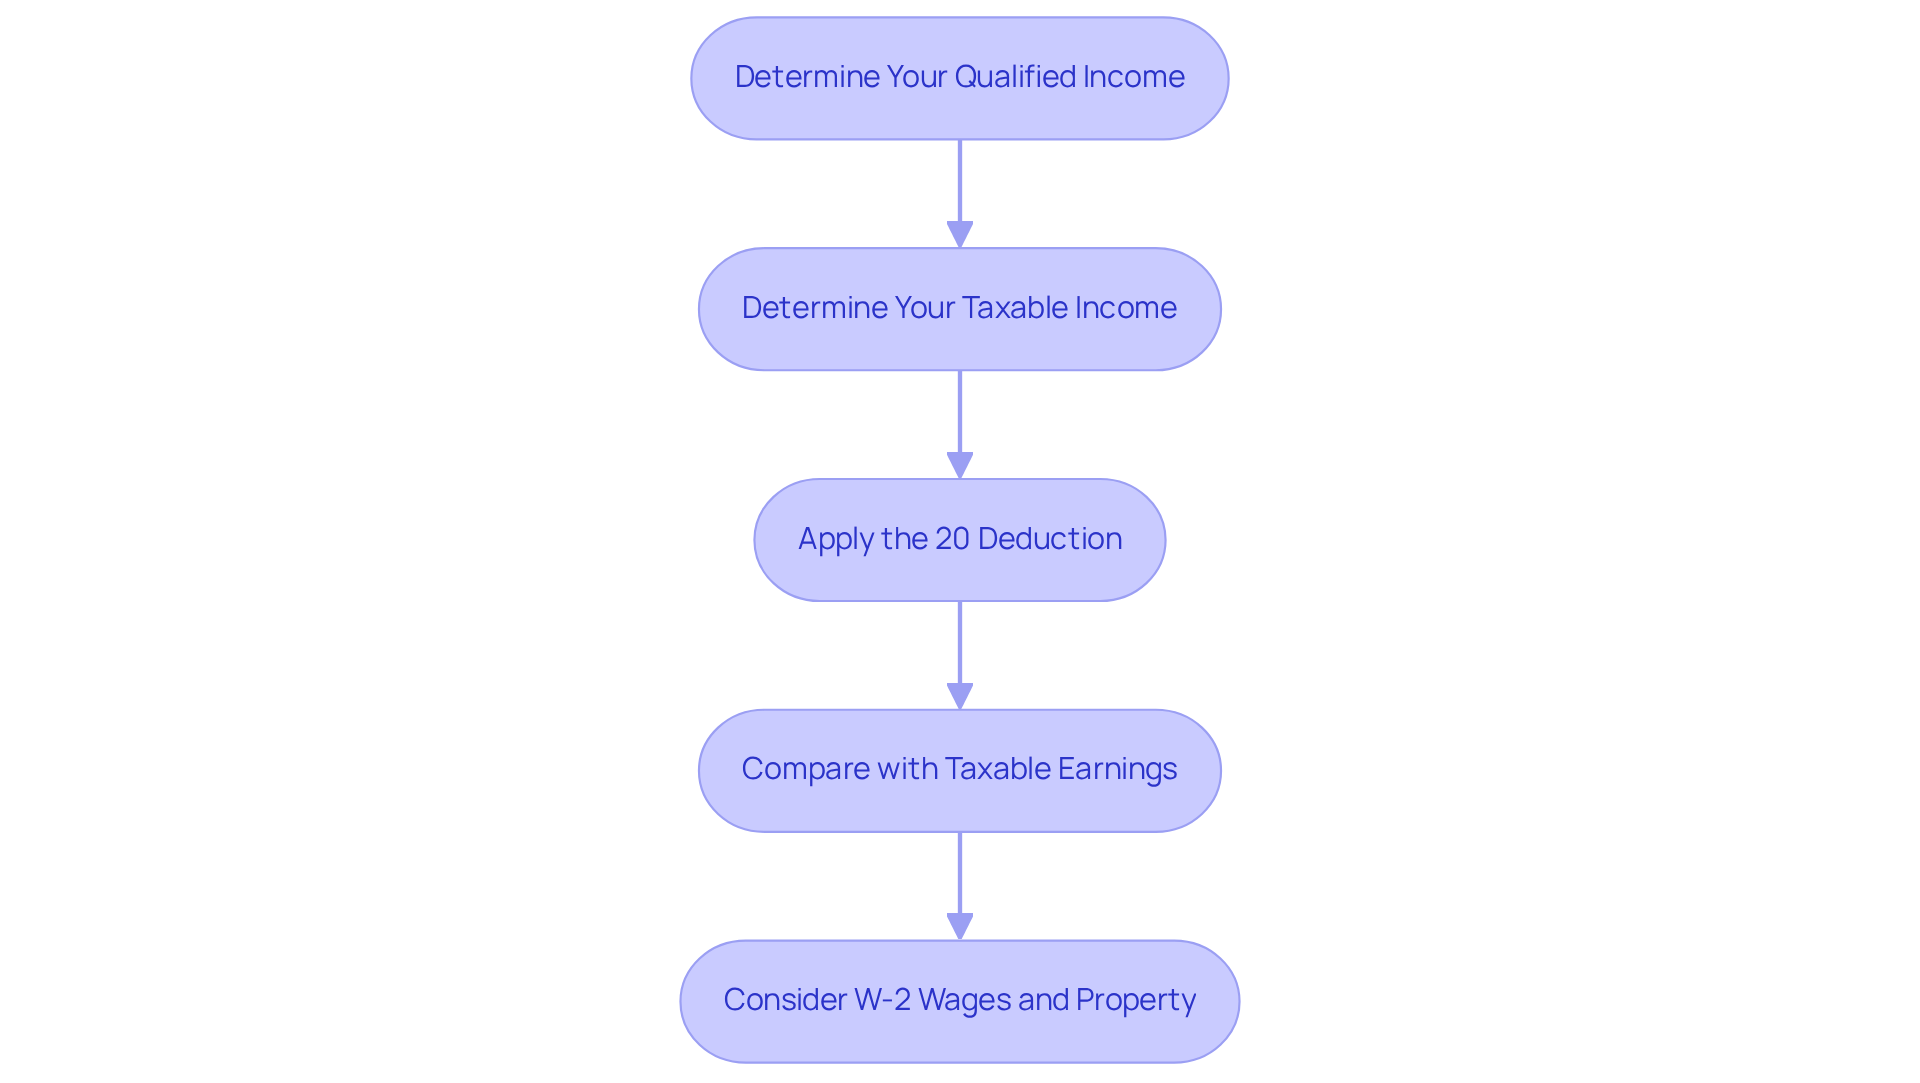
- Determine Your Qualified Income: Start by figuring out your total QBI from your business activities. This includes all the revenue you’ve generated, but remember to exclude capital gains and losses. It’s all about understanding what you’ve earned.
- Determine Your Taxable Income: Next, calculate your taxable income. This is your total income minus any reductions and exemptions. Knowing this number is crucial, as it helps determine the limits on your deductions.
- Apply the 20% Deduction: Now, take your QBI and multiply it by 20%. This gives you your initial deduction amount. It’s a straightforward step that can make a big difference.
- Compare with Taxable Earnings: Calculate 20% of your taxable earnings, minus any net capital gains. The QBI allowance will be the smaller amount between what you calculated in steps 3 and 4. This ensures you’re getting the best benefit possible.
- Consider W-2 Wages and Property: If your taxable earnings exceed certain thresholds, you might need to consider W-2 wages and the unadjusted basis of qualified property to finalize your allowance. It’s important to keep these factors in mind.
Imagine this: If your QBI is $150,000, like Sarah from her consulting business, your initial allowance would be $30,000. But if your taxable income is $80,000, then 20% of that is $16,000. So, your QBI reduction would be limited to $16,000. And starting in 2026, if your QBI is at least $1,000 and you’re actively engaged, you’re guaranteed a minimum reduction of $400. This structured approach not only helps you maximize your tax benefits but also aligns with IRS guidelines.
To make things easier, consider using IRS Form 8995 for straightforward QBI situations. Together, we can navigate this journey and ensure you’re making the most of your .
Report Your QBI Deduction Accurately
To report your QBI deduction accurately, let’s take this step by step:
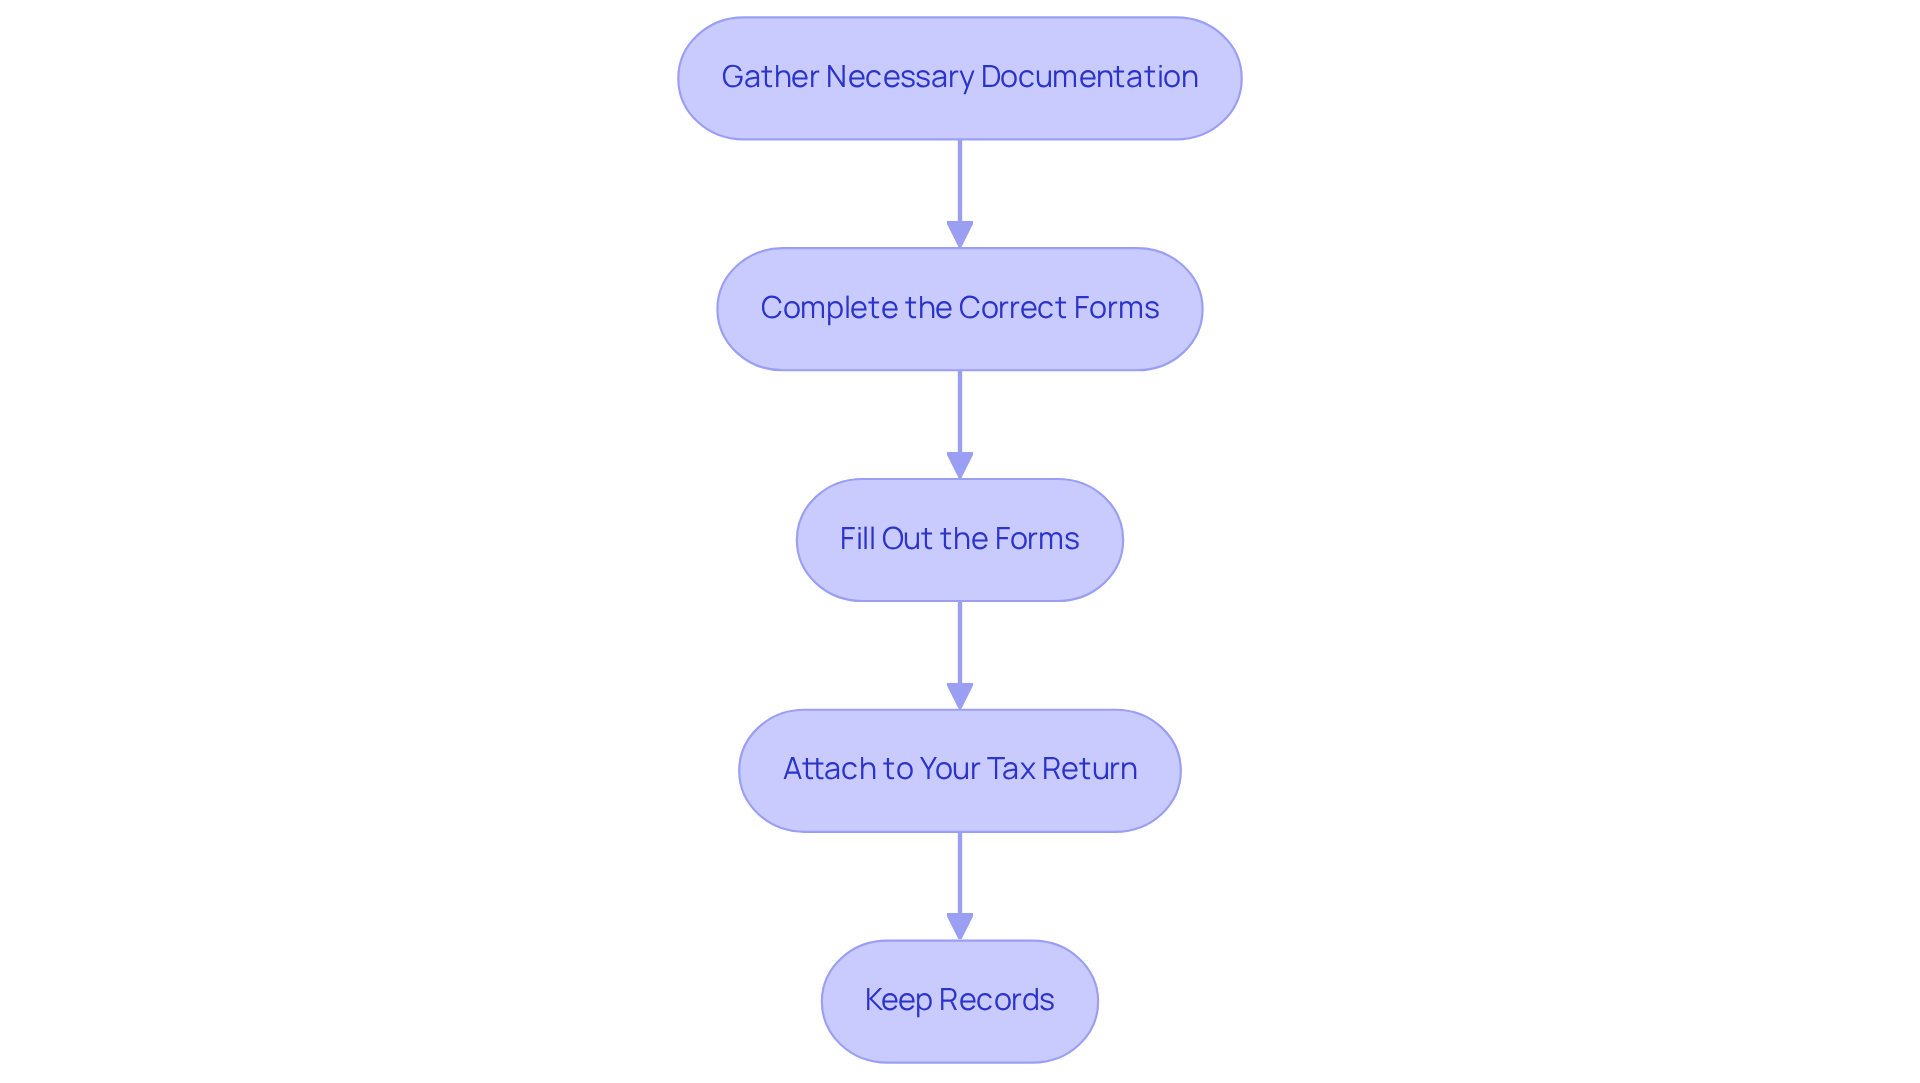
- Gather Necessary Documentation: Start by collecting all your important financial papers. This includes your business revenue statements, tax returns, and any forms related to your QBI. Having everything in one place can ease your mind.
- Complete the Correct Forms: You’ll need to use IRS Form 8995 or Form 8995-A to report your QBI reduction. If your situation is straightforward, Form 8995 is perfect for you. For those with more complex scenarios, Form 8995-A will be your go-to.
- Fill Out the Forms: Take your time to enter your QBI, taxable income, and any other required information on the forms. Double-checking your calculations can help avoid any discrepancies that might cause stress later on.
- Attach to Your Tax Return: Don’t forget to include the completed form with your individual tax return (Form 1040). Filing your return by the deadline is crucial to avoid any penalties, so mark that date on your calendar!
- Keep Records: It’s wise to maintain copies of your forms and supporting documentation for at least three years. This way, you’ll be prepared in case of an audit, giving you peace of mind.
By following these steps, you can ensure that your QBI allowance is reported correctly. This not only maximizes your tax benefits but also keeps you compliant with IRS regulations. Remember, we’re here for you, and together, we can navigate this journey!
Avoid Common Pitfalls and Exceptions
Maximizing your QBI deduction can feel overwhelming, but with a little guidance, you can navigate this journey with confidence. Here are some strategies to help you avoid common pitfalls:
- Misclassifying Earnings: It’s crucial to accurately classify your earnings as Qualified Business Income (QBI). Remember, earnings from don’t qualify for the deduction. Misclassifying these can significantly reduce your potential tax benefits. For instance, a company with $200,000 in eligible earnings might miss out on up to $40,000 in allowances if earnings are misclassified.
- Disregarding Phase-Out Regulations: Be mindful of the earnings limits that trigger phase-outs for the QBI allowance. If your taxable earnings exceed these thresholds, your allowance could be reduced or eliminated, impacting your overall tax savings.
- Ignoring W-2 Wages: For businesses with revenue above certain thresholds, the QBI allowance may be limited based on the W-2 wages paid to employees or the unadjusted basis of qualified property. Overlooking these factors can lead to a smaller deduction than you might expect.
- Failing to Keep Records: Keeping meticulous records of your business income and expenses is essential. Inadequate documentation can create problems during an audit, potentially leading to disallowed expenses. Staying organized throughout the year is key to compliance and optimizing your tax benefits. For example, insufficient mileage documentation can result in rejected claims during audits, as the IRS often challenges mileage assertions.
- Not Consulting a Professional: If your tax situation feels complex, don’t hesitate to seek help from a tax professional. Their expertise can ensure you’re maximizing your QBI allowance while adhering to all regulations, giving you peace of mind. As tax experts often say, ‘The QBI reduction is frequently overlooked or miscalculated,’ highlighting the importance of professional guidance.
By being aware of these common pitfalls, you can approach the QBI deduction process with greater ease and secure the tax benefits available to you. Remember, you’re not alone in this journey; we’re here for you every step of the way.
Conclusion
Mastering the 199A tax code can truly open doors to significant tax savings for young families navigating the complexities of small business ownership. This guide has shed light on the essential aspects of the Qualified Business Income (QBI) deduction, showing how it can ease financial burdens and support your family’s dreams. By understanding the eligibility criteria, calculating your deduction accurately, and reporting it correctly, families can maximize their benefits and pave the way for a brighter financial future.
Key insights discussed include:
- The importance of identifying qualified business income
- Understanding income thresholds
- Recognizing the nuances of business structure
It’s also crucial to keep meticulous records and consult with tax professionals to steer clear of common pitfalls. By staying informed and proactive, families can fully embrace the 199A tax code provisions, ensuring they enjoy the fruits of their hard work.
Ultimately, the 199A tax code is more than just a set of regulations; it’s an opportunity for families to thrive financially. As tax laws continue to evolve, remaining educated and engaged will empower families to make informed decisions that align with their financial aspirations. Taking action today can lead to lasting benefits, so don’t hesitate to explore the possibilities and secure your family’s financial well-being. Together, we can navigate this journey.
Frequently Asked Questions
What is the 199A tax code?
The 199A tax code, created under the Tax Cuts and Jobs Act of 2017, allows qualified taxpayers to deduct up to 20% of their eligible earnings (Qualified Business Income or QBI) from specific pass-through entities like sole proprietorships, partnerships, and S corporations.
What is Qualified Business Income (QBI)?
Qualified Business Income (QBI) is the net income from a qualified trade or business, excluding capital gains, dividends, and interest income.
Who are eligible taxpayers for the 199A deduction?
Eligible taxpayers include individuals, trusts, and estates, primarily targeting non-corporate taxpayers, such as small business owners and self-employed individuals.
What are the deduction caps for the 199A tax code?
The deduction is limited to the lesser of 20% of QBI or 20% of taxable earnings minus net capital gains. Income thresholds for additional limits are $75,000 for individuals and $150,000 for joint filers.
Is there a minimum QBI allowance?
Yes, there is a minimum QBI allowance of $400 for those earning at least $1,000 in QBI, which is indexed for inflation.
Will the 199A tax benefit expire?
Originally set to expire after 2025, the 199A tax benefit has been made permanent, providing ongoing support for eligible taxpayers.
What challenges might taxpayers face with the 199A tax code?
Navigating the complexities of the 199A tax code can be tricky, requiring careful planning and accurate reporting to maximize the benefits.
What criteria must be met to qualify for the QBI deduction?
To qualify for the QBI deduction, businesses must operate as a qualified trade or occupation, meet specific income thresholds, and be structured as pass-through entities.
What are the income thresholds for the QBI deduction?
For the tax year 2026, the income thresholds are approximately $400,000 for married couples filing jointly and $200,000 for single filers. Those below these amounts can claim the full allowance, while exceeding them may lead to a phased-out benefit.
What types of income are excluded from QBI?
Exclusions from QBI include capital gains or losses, interest income not tied to a trade or business, and wage income.
Should individuals consult a tax expert regarding the QBI deduction?
Yes, given the complexities of the QBI allowance, consulting a tax expert is recommended to maximize tax benefits and ensure compliance with regulations.
List of Sources
- Understand the 199A Tax Code Basics
- The One Big Beautiful Bill: Highlights for Business Owners (https://njbmagazine.com/special-sections/2026-njcpa-special-section/the-one-big-beautiful-bill-highlights-for-business-owners)
- Tax Reform’s Elusive Section 199A Deduction Explained (https://deloitte.com/us/en/services/tax/articles/section-199a-deduction-explained.html)
- 2026 Tax Law Changes You Need to Know About | Kirsch CPA Firm Cincinnati (https://kirschcpa.com/accounting-services-blog/2026-tax-law-changes-you-need-to-know-about)
- The QBI Deduction: Good News for Eligible Business Owners – Caras Shulman (https://carasshulman.com/the-qbi-deduction-good-news-for-eligible-business-owners)
- Identify Eligibility for the QBI Deduction
- Qualified Business Income (QBI) Deductions Post-OBBBA (https://actecfoundation.org/podcasts/qualified-business-income-deductions-post-obbba)
- Qualified Business Income: A Guide to the QBI Deduction (https://eztaxreturn.com/blog/qualified-business-income-a-guide-to-the-qbi-deduction)
- Qualified business income deduction | Internal Revenue Service (https://irs.gov/newsroom/qualified-business-income-deduction)
- QBI Deduction 2026: Complete Section 199A Guide (https://sdocpa.com/qualified-business-income-deduction-guide)
- Calculate Your QBI Deduction
- Qualified business income deduction | Internal Revenue Service (https://irs.gov/newsroom/qualified-business-income-deduction)
- QBI Deduction 2026: Complete Section 199A Guide (https://sdocpa.com/qualified-business-income-deduction-guide)
- Understanding the new Sec. 199A business income deduction (https://thetaxadviser.com/issues/2018/apr/understanding-sec-199a-business-income-deduction)
- 2026 OBBBA Tax Changes for Businesses: Key Credits, QBI, and… (https://kahnlitwin.com/blogs/tax-blog/what-the-obbba-means-for-your-business-in-2026)
- Qualified Business Income: A Guide to the QBI Deduction (https://eztaxreturn.com/blog/qualified-business-income-a-guide-to-the-qbi-deduction)
- Avoid Common Pitfalls and Exceptions
- 12 Common Business Tax Filing Mistakes to Avoid | SDO CPA (https://sdocpa.com/common-business-tax-filing-mistakes)
- Maximizing the QBI Deduction: How Business Owners Can Qualify and Optimize Tax Savings – Conway Wealth (https://conwaywealth.com/insights/maximizing-qualified-business-income-deductions)
- Top Mistakes to Avoid to Maximize the QBI Deduction – Anders (https://anderscpa.com/learn/blog/top-mistakes-to-avoid-to-maximize-the-qbi-deduction)

Kevin has advised high-income W-2 tech and biotech families since 2015, and leads the education-first Age Five Family Office from Brea, California.
Connect on LinkedIn → · About Kevin