

Key Highlights
- The IRS allows individuals to gift up to $19,000 per recipient tax-free starting in 2026, with a $250 gift allowance being crucial for wealth transfer.
- Parents can support their children financially while teaching them about saving and investing, potentially gifting a total of $57,000 to three children without tax implications.
- Gifts made during one’s lifetime can reduce taxable estates, benefiting long-term financial planning.
- Direct payments for tuition or medical expenses do not count against the annual gift limit, providing additional support options for families.
- Strategies to maximise the $250 gift allowance include cash gifts, 529 college savings plans, gifting appreciated assets, and establishing a gifting schedule.
- Common misconceptions include assuming all gifts are taxable, gifting unequally, delaying gifts, and ignoring tax implications of appreciated assets.
- Regular consultations with tax and estate planning professionals can enhance gifting strategies and align them with long-term financial goals.
- Bright Advisers emphasises fiduciary duty and transparency, offering personalised wealth management strategies to help families navigate gifting complexities.
Introduction
Imagine feeling overwhelmed by the complexities of financial planning while trying to secure your child’s future. The $250 gift allowance, established by the IRS, offers families a unique opportunity to transfer wealth efficiently and tax-free. This allowance allows for significant contributions that can shape children’s futures. Many families feel overwhelmed by the rules surrounding this allowance, unsure of how to proceed.
How can families maximize this benefit while avoiding common pitfalls? Let’s explore some simple strategies to help you make the most of the $250 gift allowance, so you can preserve your wealth and teach your kids valuable financial lessons.
Define the 250 Gift Allowance and Its Importance in Wealth Management
Imagine being able to support your children’s future while also teaching them the value of financial responsibility. The IRS has established a $250 gift allowance that permits individuals to gift up to $19,000 per recipient in 2026 without incurring gift taxes. This allowance is crucial for households aiming to transfer wealth efficiently across generations.
By utilizing the $250 gift allowance, parents can provide significant monetary support to their children, fostering a culture of saving and investing from an early age. For instance, a household with three kids can provide each child the maximum sum, amounting to $57,000 in tax-exempt contributions. This approach helps manage wealth effectively and teaches your children important lessons about money.
Moreover, the yearly exclusion contributions can be used to transfer wealth without accessing the lifetime exemption. This enables households to maintain their tax benefits while enriching their economic legacies.
Here at Bright Advisers, we’re dedicated to helping families like yours find the best planning strategies to optimize the advantages of the $250 gift allowance. By embracing these strategies, you’re not just planning for the future; you’re nurturing a legacy of financial wisdom for your family.
Explore Regulations and Tax Implications of the 250 Gift Allowance
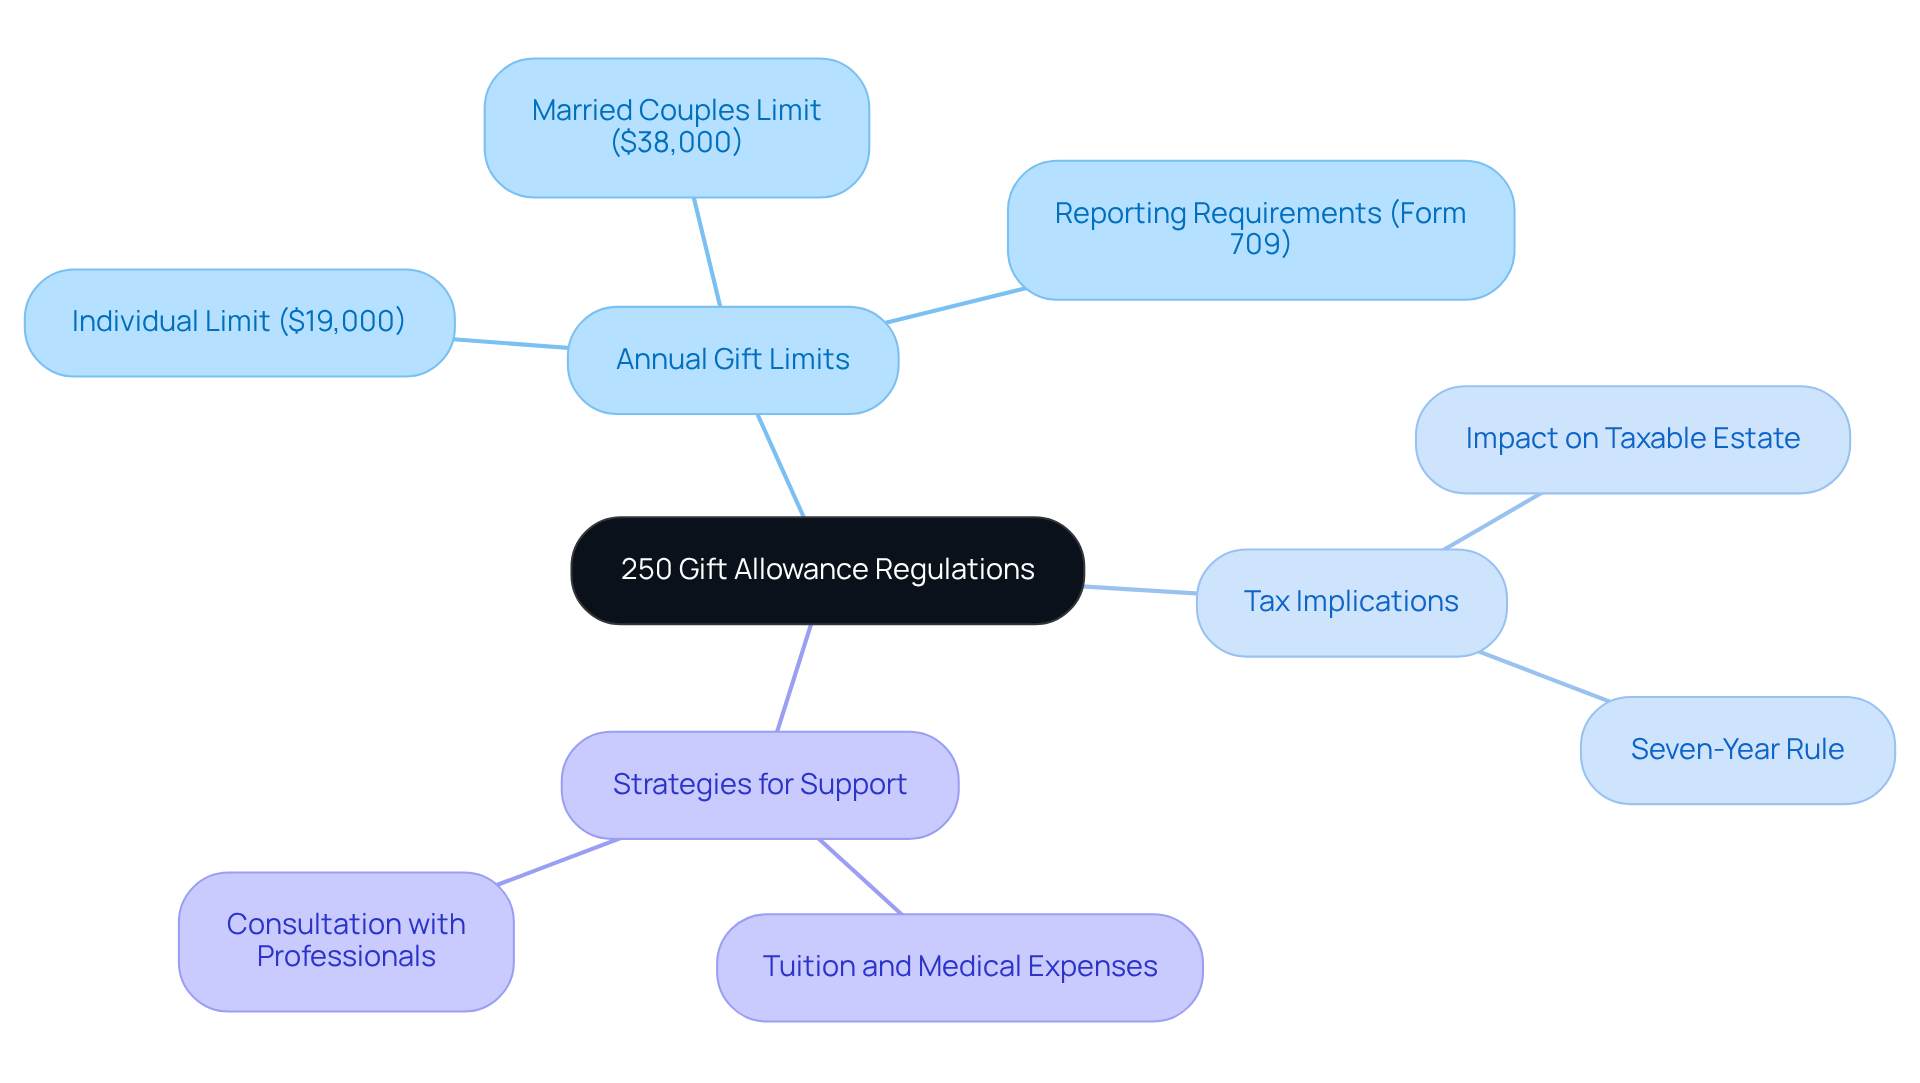
Imagine being able to support your loved ones with up to $19,000 each year, tax-free – this is what the IRS allows starting in 2026. For married couples, this amount doubles to $38,000 per recipient, giving you the chance to make a significant impact on your children’s lives or other beneficiaries. However, if you give more than these amounts, you’ll need to report it on your tax return (Form 709).
It’s important to grasp how gifting can shape your family’s financial future and legacy. Contributions made during your lifetime can help reduce your taxable estate, which is especially beneficial as you plan for your family’s future. Keep in mind the ‘seven-year rule’: gifts made within seven years of your passing may still be counted in your taxable estate, potentially affecting estate tax liabilities.
For instance, if you directly pay for your child’s tuition or medical expenses, it won’t count against your annual gift limit, allowing you to provide even more support when they need it most. This strategy can be a lifesaver for families facing significant educational costs.
When you understand these gifting rules, you can create a thoughtful plan that not only supports your family but also eases your financial worries. Regular consultations with tax and estate planning professionals can enhance your strategies, ensuring they align with your long-term financial goals. At Bright Advisers, we’re here for you, offering comprehensive tax planning and tailored strategies to help you navigate these complexities, ensuring you can support your loved ones while optimizing your tax situation.
Implement Strategies to Maximize the 250 Gift Allowance Benefits
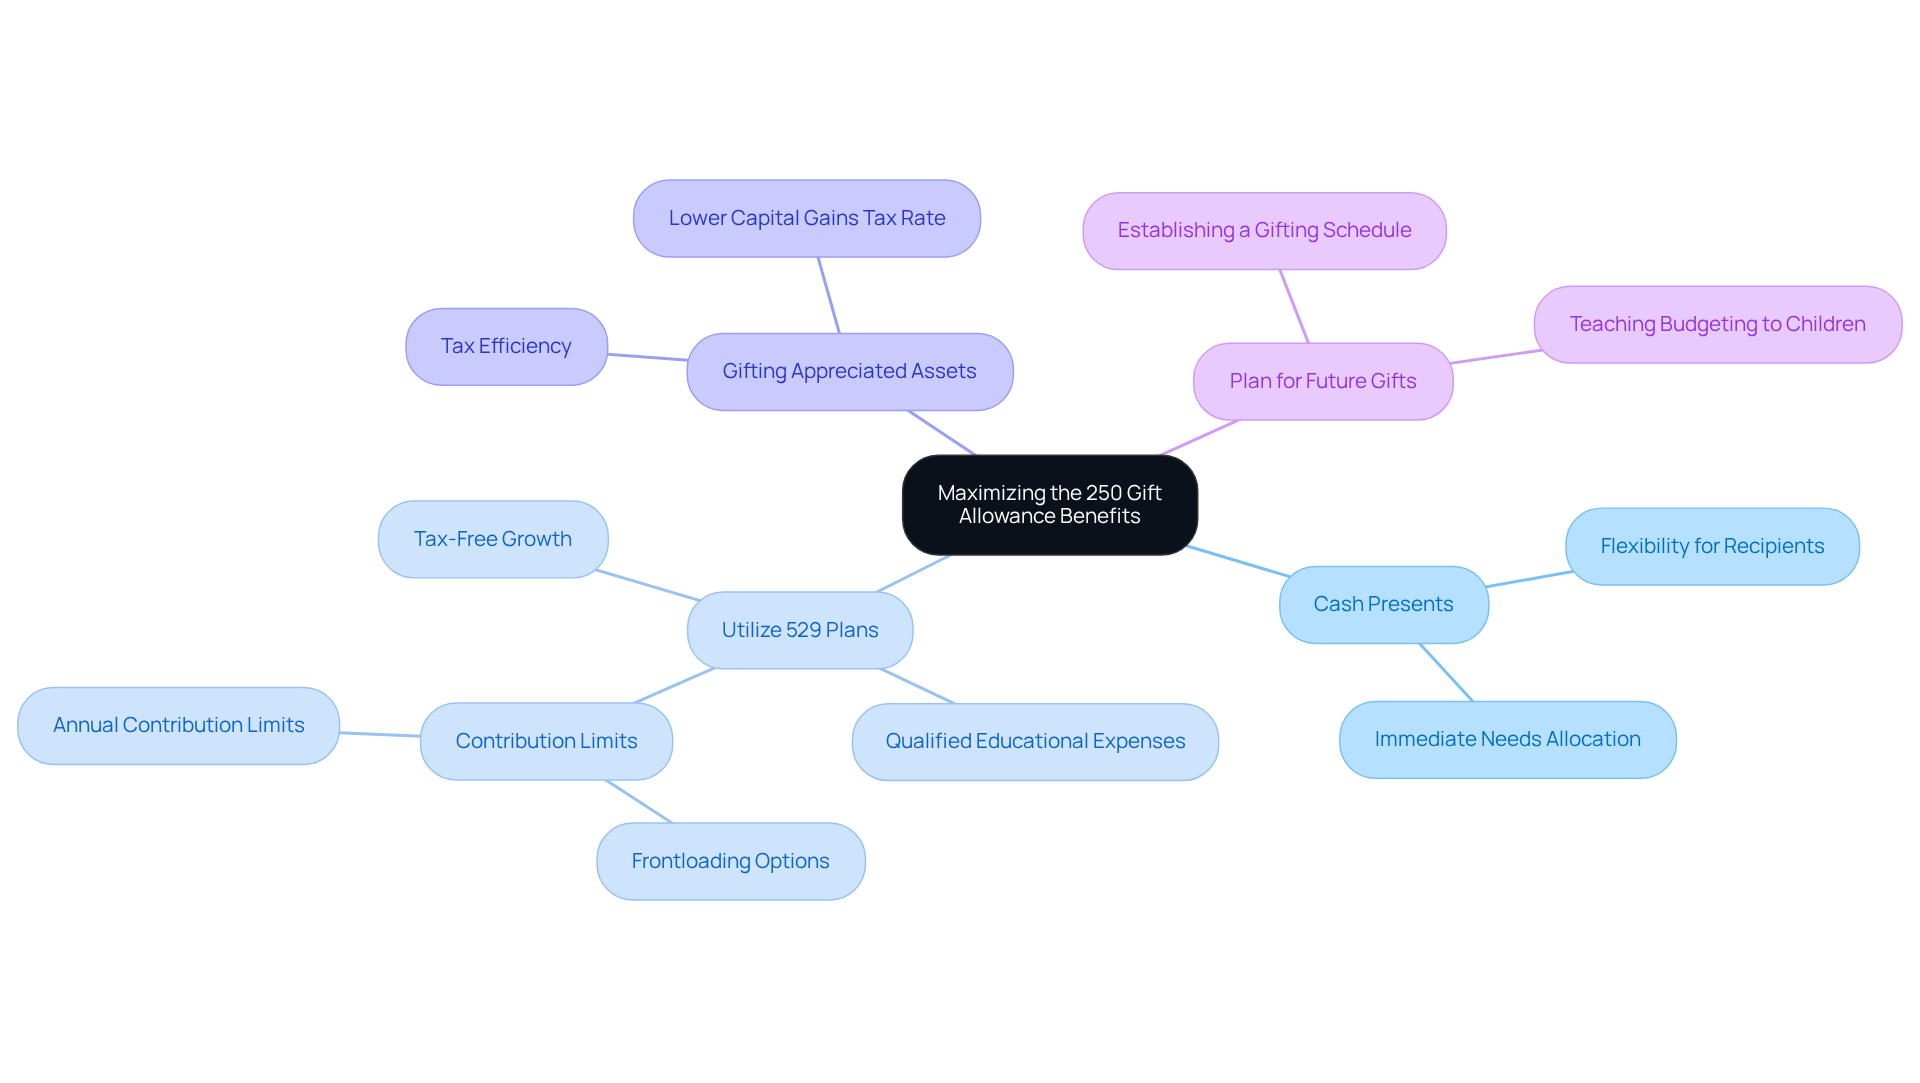
Imagine being able to give your family the gift of financial security while nurturing their dreams and aspirations. To maximize the benefits of the 250 Gift Allowance, families can adopt several effective strategies:
- Cash presents provide the greatest flexibility, allowing recipients to allocate funds according to their immediate needs or preferences.
- Utilize 529 Plans: Contributing to a 529 college savings plan is a smart move, as it allows for tax-free growth and withdrawals for qualified educational expenses. It’s a good idea to check in with a plan administrator or tax advisor to ensure you’re making the best choices for your family’s education funding. For instance, Jay and Emma successfully navigated funding their children’s education while planning for retirement, achieving a balance between their present responsibilities and long-term aspirations with the help of Bright Advisers.
- Gifting Appreciated Assets: Instead of cash, consider gifting appreciated assets such as stocks. This approach can be tax-efficient, as the recipient may benefit from a lower capital gains tax rate upon selling the asset, enhancing overall wealth transfer. Emily and Mark, for example, gained the flexibility to make career decisions based on their desired work-life balance by implementing strategies to manage their finances effectively.
- Plan for Future Gifts: Establishing a gifting schedule ensures that the annual exclusion is fully utilized each year, facilitating systematic wealth transfer. This proactive method not only maximizes the 250 gift allowance for presents but also teaches children the importance of budgeting. Allison and Brian, through their collaboration with Bright Advisers, optimized their tax situation and secured their children’s future through education funding, allowing them to enjoy more quality time with their loved ones.
When you embrace these strategies, you’re not just planning for today; you’re building a legacy that your children can cherish and learn from. Moreover, households should be aware that the lifetime gift and estate tax exemption is $13.99 million per individual in 2025, providing context for their gifting strategies. Remember, past performance does not guarantee future results, and all investments are subject to risk. Advisory services are provided through Lifeworks Advisors, a registered investment adviser. Bright Advisers is dedicated to assisting households in making prudent financial choices and safeguarding wealth across generations. Together, we can ensure that your family’s future is bright and filled with opportunities, allowing you to focus on what truly matters-your loved ones.
Identify Common Misconceptions and Pitfalls in Gifting Practices
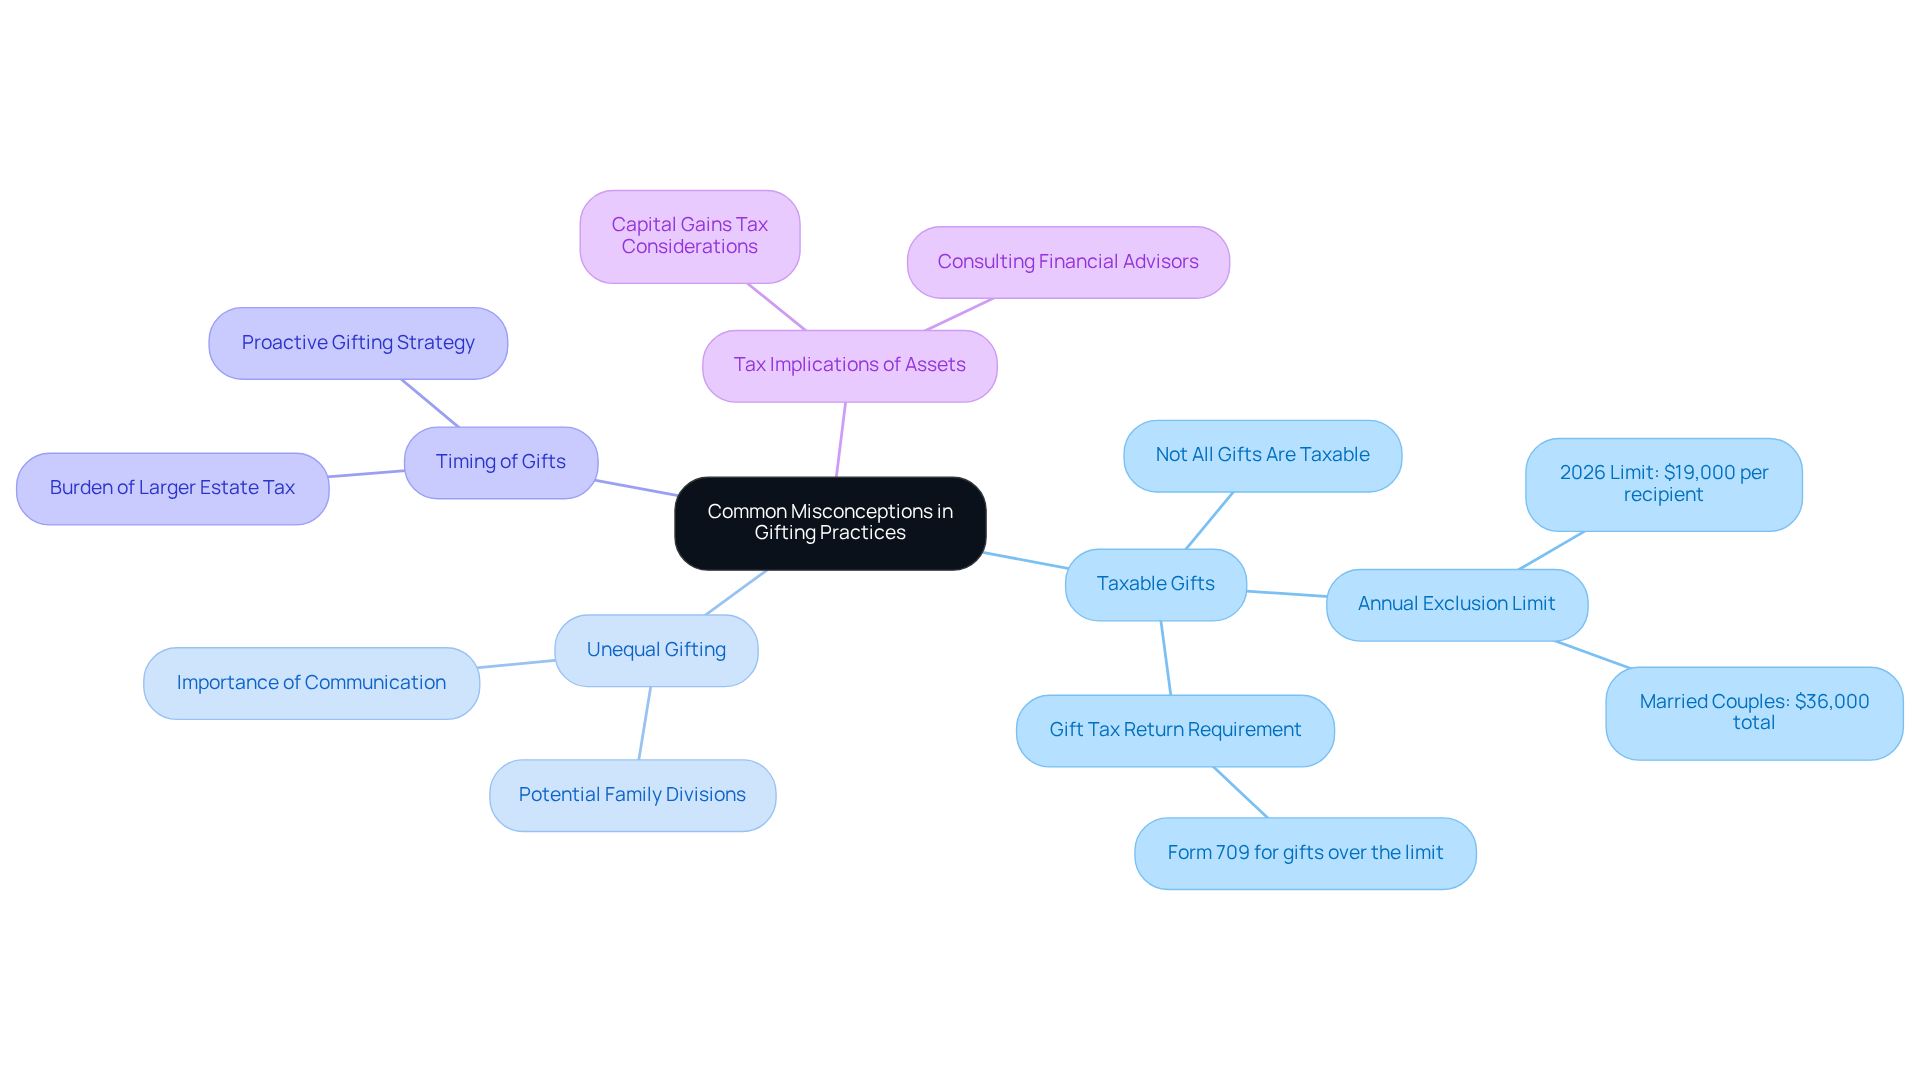
Imagine the confusion that can arise when families misunderstand the rules of gifting, leading to unexpected financial burdens. Many families encounter misconceptions about gifting that can lead to unintended consequences. Here are some common pitfalls to avoid:
- Assuming All Presents Are Taxable: Not all presents incur tax liabilities. Comprehending the annual exclusion limit is essential; for example, in 2026, individuals can provide up to $19,000 per recipient without having to submit a tax return for transfers. A married couple can provide a total of $36,000 per recipient, per year, which allows for significant tax-free contributions. This approach helps families like Allison and Brian make the most of their financial resources with the right guidance.
- Gifting Unequally: Unequal gifts to children can unintentionally create divisions among relatives. Open communication regarding gifting intentions is essential to maintain harmony and ensure that all relatives feel valued. We at Bright Advisers understand that every family is unique, and we’re here to help you find the right wealth management solutions that fit your family’s needs.
- Waiting Too Long to Gift: Imagine the burden of a larger estate tax when you could have given earlier and helped your loved ones now. Delaying gifts until later in life can result in larger taxable estates. Consistent giving can assist in lowering estate levies and offer prompt assistance to family members, making it a proactive monetary approach. This proactive approach not only secures your children’s futures but also strengthens family bonds through shared experiences.
- Ignoring Tax Implications of Assets: Gifting appreciated assets without considering capital gains taxes can lead to unexpected tax liabilities for the recipient. Consulting with a money advisor, such as those at Bright Advisers, can assist households in comprehending the consequences of their gifting strategies and steer clear of possible traps. Through their partnership with Bright Advisers, clients gain clarity on their monetary situations and develop comprehensive plans that align with their long-term goals.
When families understand these gifting strategies, they can foster stronger connections and ensure their financial choices truly reflect their values and goals. Bright Advisers is dedicated to helping families navigate these complexities, empowering them to make wise wealth decisions and preserve their wealth across generations.
Conclusion
Imagine nurturing a legacy of financial wisdom that your children can carry forward. By understanding and effectively utilizing the $250 gift allowance, families can provide substantial support to their children while teaching them the importance of saving and investing. This approach not only facilitates wealth transfer but also empowers families to make informed decisions that align with their long-term financial goals.
Think about how your family can support your children while teaching them the importance of saving and investing. Throughout this article, we’ve highlighted key strategies, including the importance of cash gifts, the benefits of 529 plans, and the advantages of gifting appreciated assets. Being aware of common misconceptions and pitfalls in gifting practices can help families avoid costly mistakes. By embracing these insights, you can maximize the benefits of the $250 gift allowance, ensuring that your financial decisions reflect your values and aspirations.
This $250 gift allowance isn’t just about tax benefits; it’s a chance for your family to grow closer and build a secure future together. We’re here to help you navigate these complexities, so you don’t have to do it alone. By taking proactive steps today, you’re not just planning for the future; you’re creating a legacy of love and support for generations to come.
Frequently Asked Questions
What is the $250 gift allowance?
The $250 gift allowance is a provision established by the IRS that allows individuals to gift up to $19,000 per recipient in 2026 without incurring gift taxes.
Why is the $250 gift allowance important in wealth management?
The $250 gift allowance is important because it enables households to transfer wealth efficiently across generations while avoiding gift taxes, thereby supporting financial planning and legacy building.
How can parents utilize the $250 gift allowance for their children?
Parents can use the $250 gift allowance to provide significant monetary support to their children, fostering a culture of saving and investing from an early age. For example, a household with three children can contribute a total of $57,000 in tax-exempt gifts.
What are the benefits of using yearly exclusion contributions?
Yearly exclusion contributions allow households to transfer wealth without accessing the lifetime exemption, helping them maintain tax benefits while enriching their economic legacies.
How does Bright Advisers assist families with the $250 gift allowance?
Bright Advisers helps families find the best planning strategies to optimize the advantages of the $250 gift allowance, ensuring they nurture a legacy of financial wisdom for future generations.
List of Sources
- Define the 250 Gift Allowance and Its Importance in Wealth Management
- Tax-Free Gifting in 2026: What Financial Givers Should Know (https://merceradvisors.com/family-finance/tax-free-gifting-in-2026-what-financial-givers-should-know)
- Gift Tax Exclusion 2026: How Much You Can Give Tax‑Free This Year (https://kiplinger.com/taxes/gift-tax-exclusion)
- What’s new — Estate and gift tax | Internal Revenue Service (https://irs.gov/businesses/small-businesses-self-employed/whats-new-estate-and-gift-tax)
- Nelson Mullins – 2026 Estate and Gift Tax Update (https://nelsonmullins.com/insights/blogs/tax-reports/all/2026-estate-and-gift-tax-update)
- What is the Annual Gift Tax Exclusion Limit for 2026? (https://adamsbrowncpa.com/blog/what-is-the-annual-gift-tax-exclusion-limit-for-2026)
- Explore Regulations and Tax Implications of the 250 Gift Allowance
- IRS releases tax inflation adjustments for tax year 2026, including amendments from the One, Big, Beautiful Bill | Internal Revenue Service (https://irs.gov/newsroom/irs-releases-tax-inflation-adjustments-for-tax-year-2026-including-amendments-from-the-one-big-beautiful-bill)
- The Estate Tax and Lifetime Gifting (https://schwab.com/learn/story/estate-tax-and-lifetime-gifting)
- 2026 Adjustments to Estate, Gift, Generation-Skipping Transfer Tax, and Income Tax Brackets (https://harrisbeachmurtha.com/insights/2026-adjustments-to-estate-gift-generation-skipping-transfer-tax-and-income-tax-brackets)
- 2026 Gift Tax Exclusions (https://farmoffice.osu.edu/blog/tue-02172026-710pm/2026-gift-tax-exclusions)
- What is the Annual Gift Tax Exclusion Limit for 2026? (https://adamsbrowncpa.com/blog/what-is-the-annual-gift-tax-exclusion-limit-for-2026)
- Implement Strategies to Maximize the 250 Gift Allowance Benefits
- 29 Ways to Use a 529 Plan… Including New Rules and Expanded Uses (https://stwserve.com/29-ways-to-use-a-529-plan-including-new-rules-and-expanded-uses)
- Gift Tax Rules and Strategies for 2025: Annual Exclusion, Lifetime Exemption and Planning Insights (https://creativeplanning.com/insights/taxes/gift-tax-rules-strategies)
- Nelson Mullins – 2026 Estate and Gift Tax Update (https://nelsonmullins.com/insights/blogs/tax-reports/all/2026-estate-and-gift-tax-update)
- How High-Net-Worth Families Use College Funding as a Wealth Planning Tool – Fiducient (https://fiducientadvisors.com/blog/how-high-net-worth-families-use-college-funding-as-a-wealth-planning-tool)
- Wealth of Knowledge: Building A Legacy with 529 Plans (https://financialplanningassociation.org/LEARNING/publications/journal/MAR23-wealth-knowledge-building-legacy-529-plans-OPEN)
- Identify Common Misconceptions and Pitfalls in Gifting Practices
- Frequently asked questions on gift taxes | Internal Revenue Service (https://irs.gov/businesses/small-businesses-self-employed/frequently-asked-questions-on-gift-taxes)
- Clearing Up Common Misconceptions About Gift Tax – Tax Refund Man, LLC (https://taxrefundman.com/clearing-up-common-misconceptions-about-gift-tax)
- Let’s clarify some common misconceptions about the gift tax – Park National Bank (https://parknationalbank.com/lets-clarify-common-misconceptions-gift-tax)
- The Gift Tax (https://turbotax.intuit.com/tax-tips/estates/the-gift-tax/L1sFpFeXV)
- COMMON MISUNDERSTANDINGS ABOUT GIFT TAXES — Drobny Law Offices, Inc. (https://drobnylaw.com/articles/blog-post-three-drx46)

Kevin has advised high-income W-2 tech and biotech families since 2015, and leads the education-first Age Five Family Office from Brea, California.
Connect on LinkedIn → · About KevinThis is part of how we approach Age Five Wealth Education for high-income W-2 families at Bright Advisers.
Keep reading