

Overview
The Rule of 55 offers a compassionate lifeline for individuals aged 55 or older, allowing them to make penalty-free withdrawals from their 401(k) or 403(b) plans when they leave their job. This rule provides essential financial flexibility during significant life transitions, such as job loss or retirement.
Imagine navigating these changes with the peace of mind that comes from understanding your options. This article gently outlines the eligibility requirements and the steps to utilize this rule, while also discussing the pros and cons. It’s important to grasp the tax implications and how they may impact your long-term savings, ensuring you make informed decisions for your family’s future.
As you consider your financial planning, remember that we’re here for you. Together, we can navigate this journey, ensuring that your family’s needs are prioritized during these transitions. Understanding the Rule of 55 can empower you to take control of your financial destiny, giving you the confidence to face the future with optimism.
Key Highlights:
- The Rule of 55 allows penalty-free withdrawals from 401(k) or 403(b) plans if you leave your job during or after age 55.
- This rule provides financial flexibility for unexpected situations like job loss or voluntary departure.
- The Rule of 55 applies only to employer-sponsored plans, not to IRAs or other savings accounts.
- Withdrawals under this rule are still subject to federal and state income taxes, with a potential 20% withholding rate.
- Eligibility requires being at least 55 years old, having separated from your employer, and the plan must be from your most recent employer.
- To utilise the Rule of 55, confirm eligibility, contact your plan administrator, submit a withdrawal request, and understand tax implications.
- Pros of the Rule of 55 include penalty-free access to funds, financial flexibility, and support for retirement planning.
- Cons include tax implications, potential depletion of savings, and limitation to the most recent employer’s plan.
Introduction
Navigating the complexities of retirement savings can feel overwhelming, especially when unexpected life changes come your way. Imagine if you could access your 401(k) or 403(b) funds without facing those typical early withdrawal penalties. The Rule of 55 offers just that opportunity for those leaving their job at or after the age of 55. This provision can provide much-needed financial flexibility during a time of transition.
However, it’s crucial to recognize that while this rule offers benefits, it also carries potential pitfalls that could affect your long-term savings.
What are the key considerations and strategies to effectively leverage the Rule of 55? How can you ensure that you are making informed decisions for your family’s financial future?
We’re here to help you navigate this journey together.
Define the Rule of 55 and Its Purpose
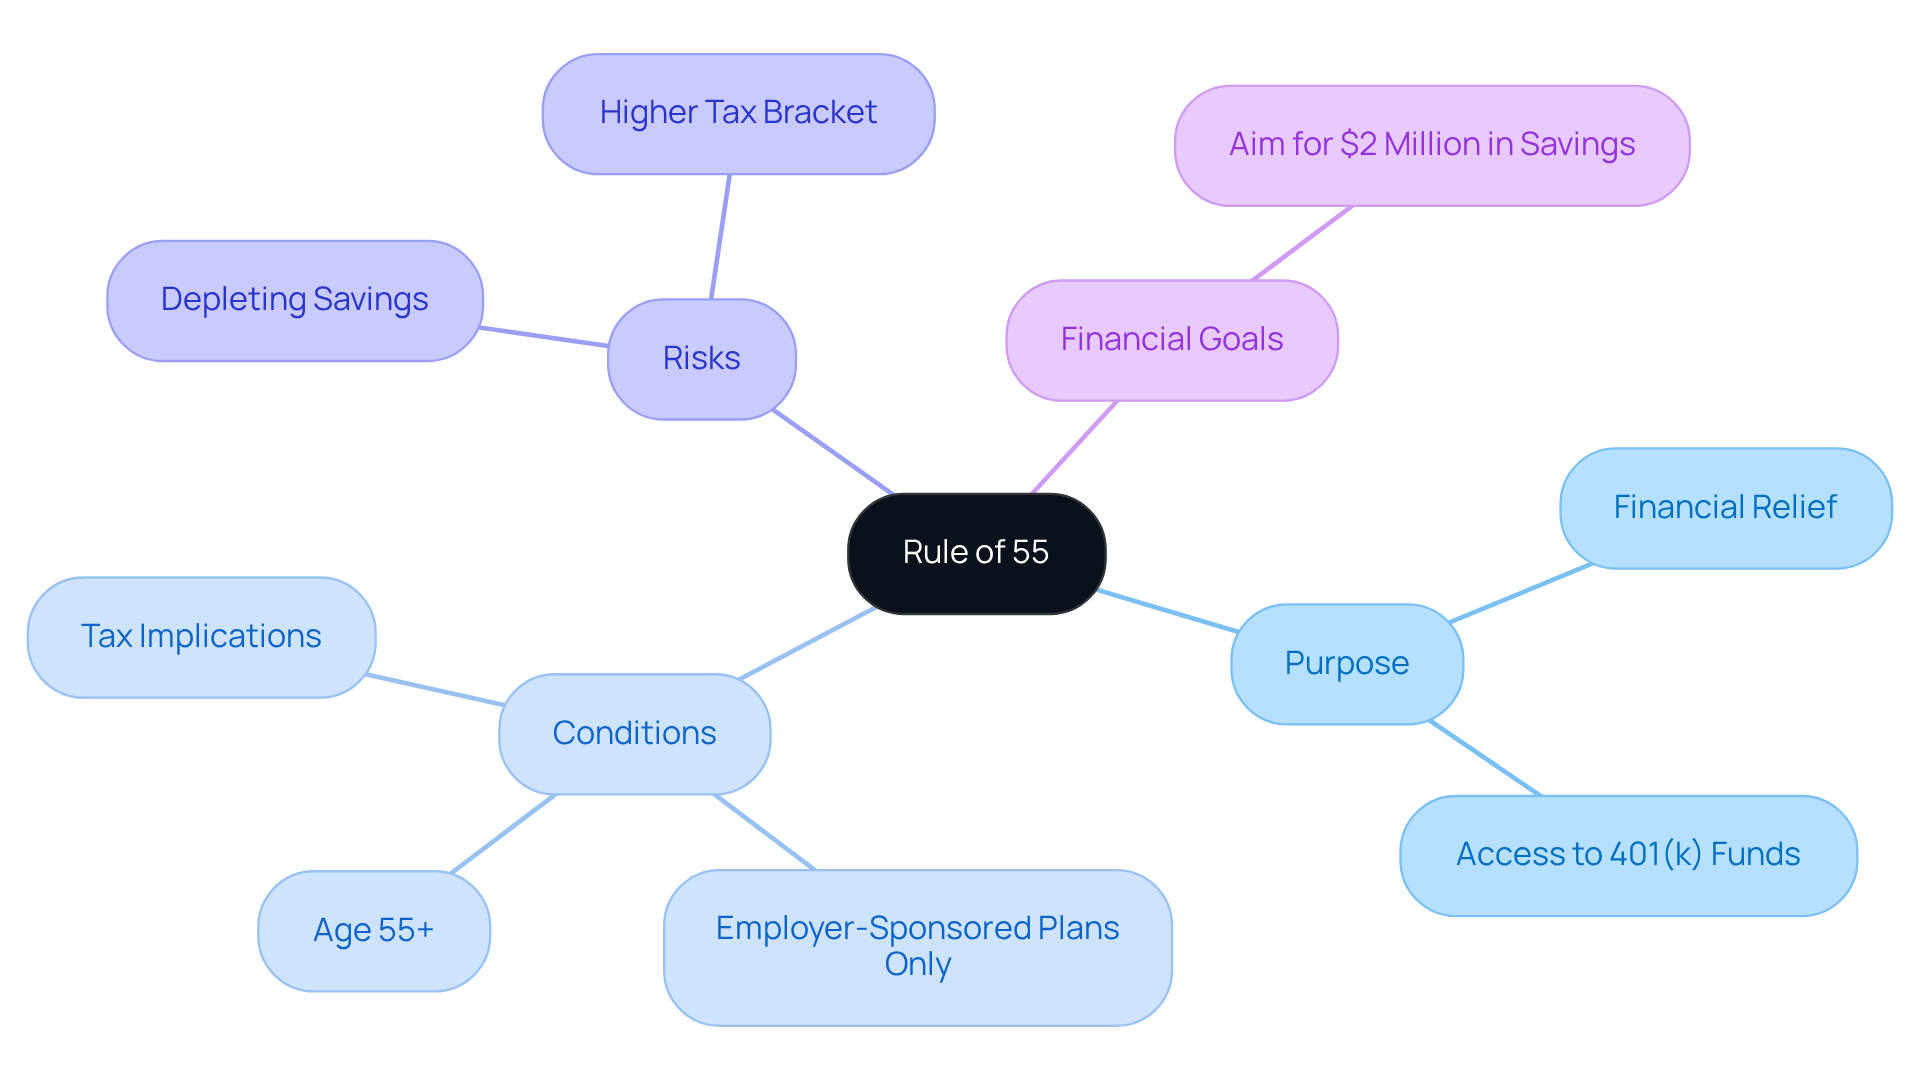
The Rule of 55 is an IRS provision that can provide you with financial relief when you need it most. If you leave your job during or after the year you reach 401k age 55, this rule allows you to withdraw funds from your 401(k) or 403(b) plans without facing the usual 10% early withdrawal penalty. It’s designed to offer financial flexibility for those who might find themselves in unexpected situations, such as job loss or a voluntary departure from work.
However, it’s important to keep in mind that this rule applies specifically to employer-sponsored plans and does not extend to IRAs or other savings accounts. While you can access your funds without the penalty, these distributions are still subject to federal and state income taxes, and a 20 percent income tax withholding rate may apply. Understanding this guideline can empower you to make informed financial choices as you approach retirement.
Imagine if you could navigate your financial future with confidence. While the Rule of 55 offers a pathway to access your savings, it’s essential to consider the potential risks of early withdrawals. These include the possibility of depleting your savings faster than anticipated and even moving into a higher tax bracket.
For those retiring at 55, aiming for approximately $2 million across your 401k age 55, IRA, and taxable accounts can provide a safety net to cover your expenses comfortably. Remember, we’re here for you—together, we can navigate this journey toward financial security for you and your family.
Identify Eligibility Requirements for the Rule of 55
Navigating financial planning can feel overwhelming, especially for young parents. To help you understand how to qualify for the 55 provision, let’s explore the key criteria together:
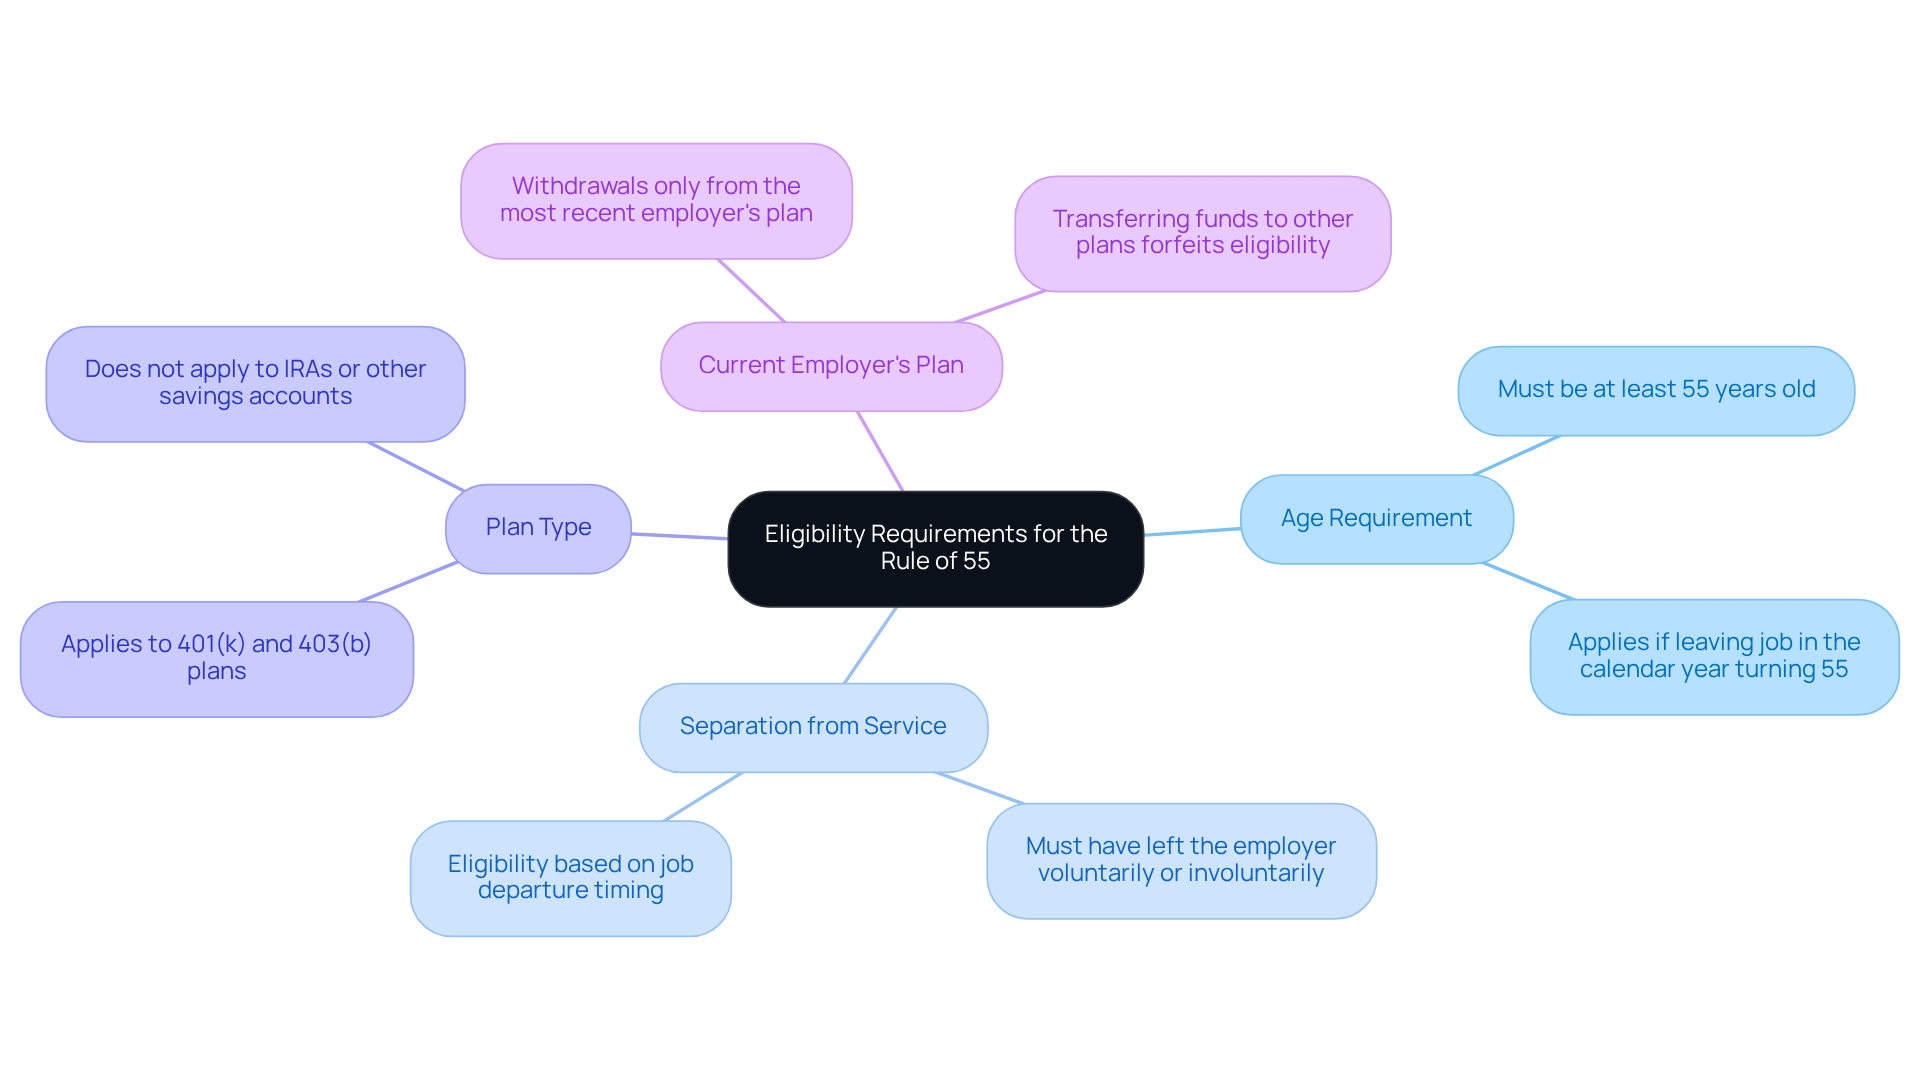
- Age Requirement: Imagine being at least 55 years old during the calendar year when you leave your job to qualify for the 401k age 55. This is an important milestone that opens doors for you.
- Separation from Service: Whether you choose to leave your job or it happens unexpectedly, it’s essential to know that you must have separated from your employer.
- Plan Type: This provision specifically applies to 401(k) age 55 or 403(b) plans maintained by your employer. It’s important to note that it doesn’t extend to IRAs or other savings accounts.
- Current Employer’s Plan: You can only withdraw from the plan of your most recent employer. If you decide to transfer your funds to a different plan or an IRA, you will lose the ability to utilize the 55 provision.
Understanding these requirements is vital for anyone considering early access to their retirement savings. Remember, we’re here for you, and together, we can navigate this journey toward securing your family’s financial future.
Explain How to Utilize the Rule of 55 for Withdrawals
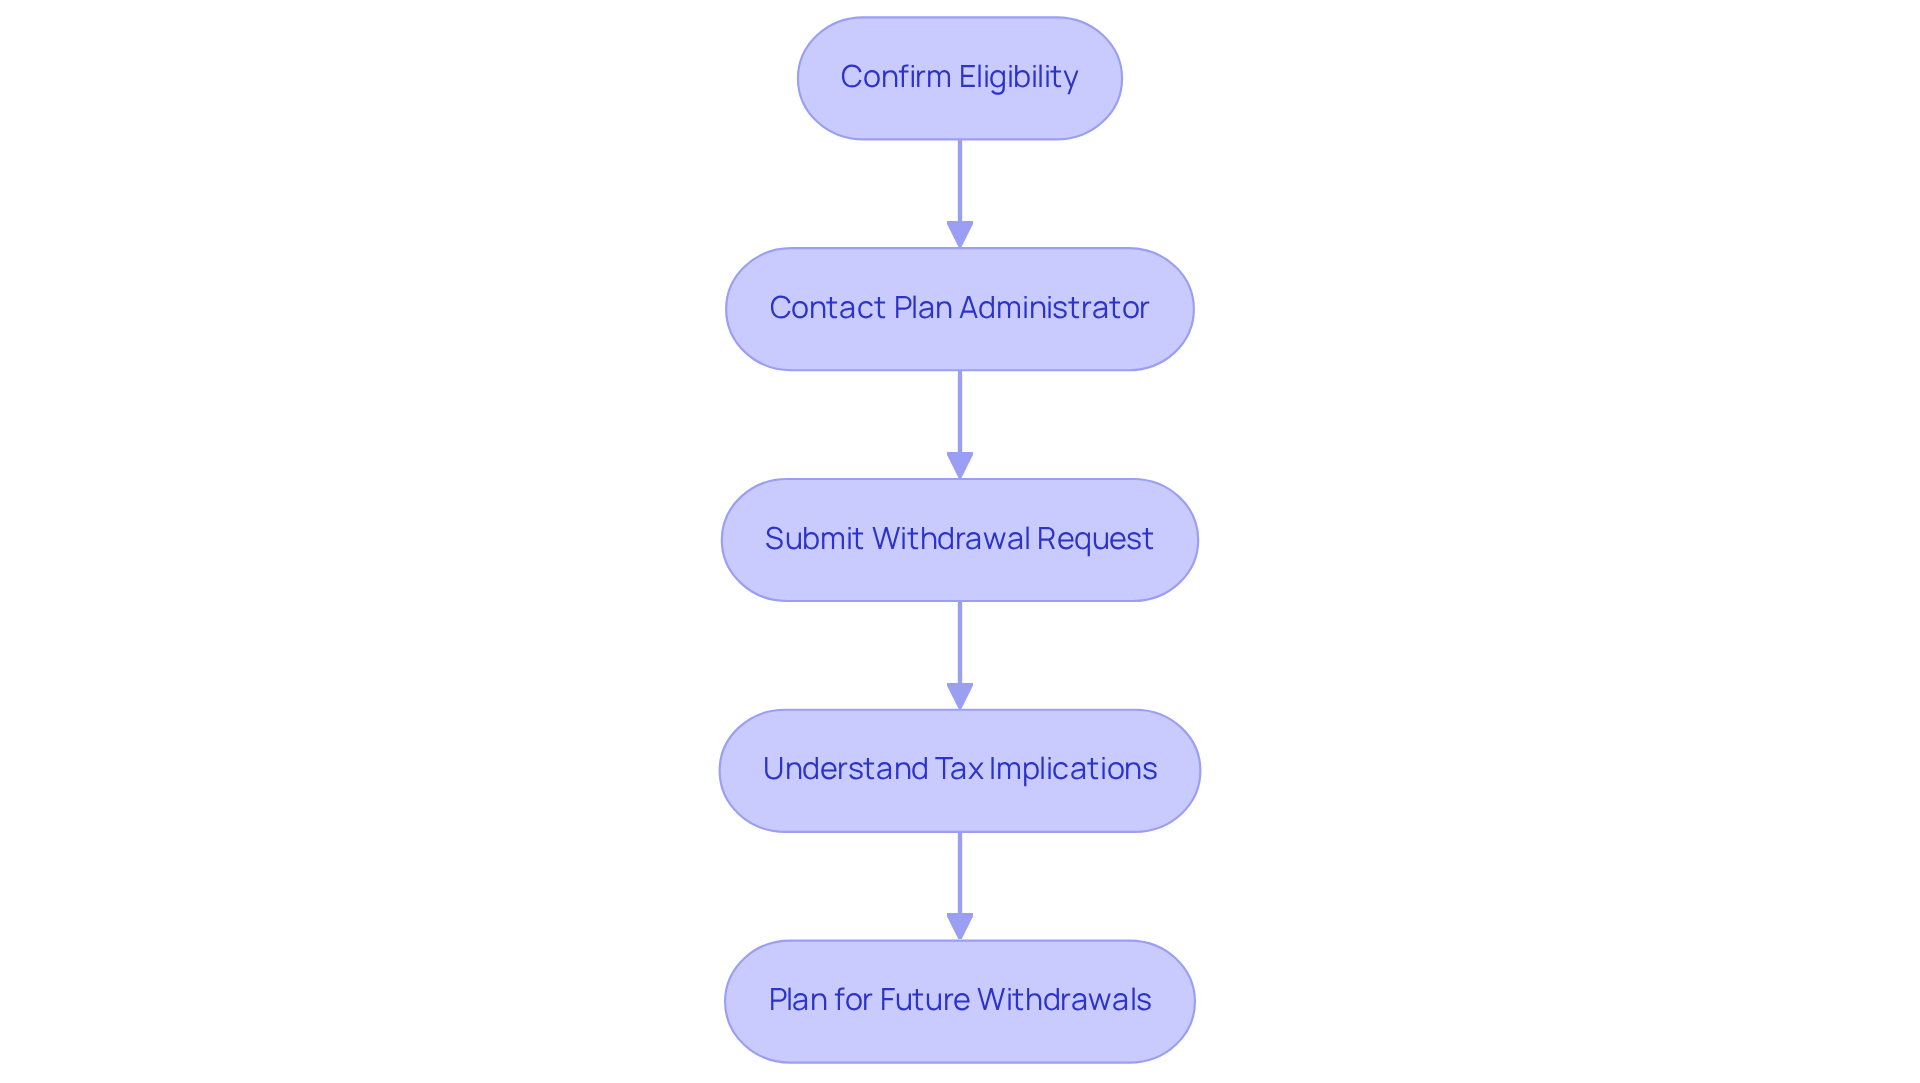
To efficiently apply the 55 guideline for taking funds, let’s walk through these essential steps together:
-
Confirm your eligibility: It’s important to ensure that you meet the age requirement of 401k age 55 and have separated from your employer. According to Facet Wealth, Inc., to qualify, one must retire, quit, or get laid off at or after 401k age 55.
-
Reach Out to Your Plan Administrator: Contact the administrator of your 401(k) or 403(b) plan. This step is crucial to confirm that your specific plan allows distributions under the provision of 55.
-
Submit Your Withdrawal Request: Take the time to complete the necessary forms to initiate your request. Be sure to provide documentation of your separation from service, as this is key to moving forward.
-
Understand the Tax Implications: While the Rule of 55 allows you to avoid the 10% early exit penalty, remember that regular income tax will still apply to the amount you withdraw. It’s wise to seek advice from a tax expert to evaluate how this action may impact your overall tax situation. For example, unreimbursed medical expenses must exceed 7.5% of adjusted gross income to qualify for penalty-free withdrawals.
-
Plan for Future Withdrawals: As you consider the amount you need to withdraw, think about how it aligns with your broader financial strategy. Withdrawing only what is necessary can help minimize tax consequences and preserve your retirement savings. Consulting with a financial planner can provide valuable insights, ensuring you make informed choices about your disbursements.
Remember, we’re here for you on this journey. Together, we can navigate these financial decisions, keeping your family’s priorities at the forefront.
Evaluate Pros and Cons of the Rule of 55
When considering the Rule of 55, it’s essential to reflect on both its advantages and disadvantages, especially as you navigate your family’s financial future:
Pros:
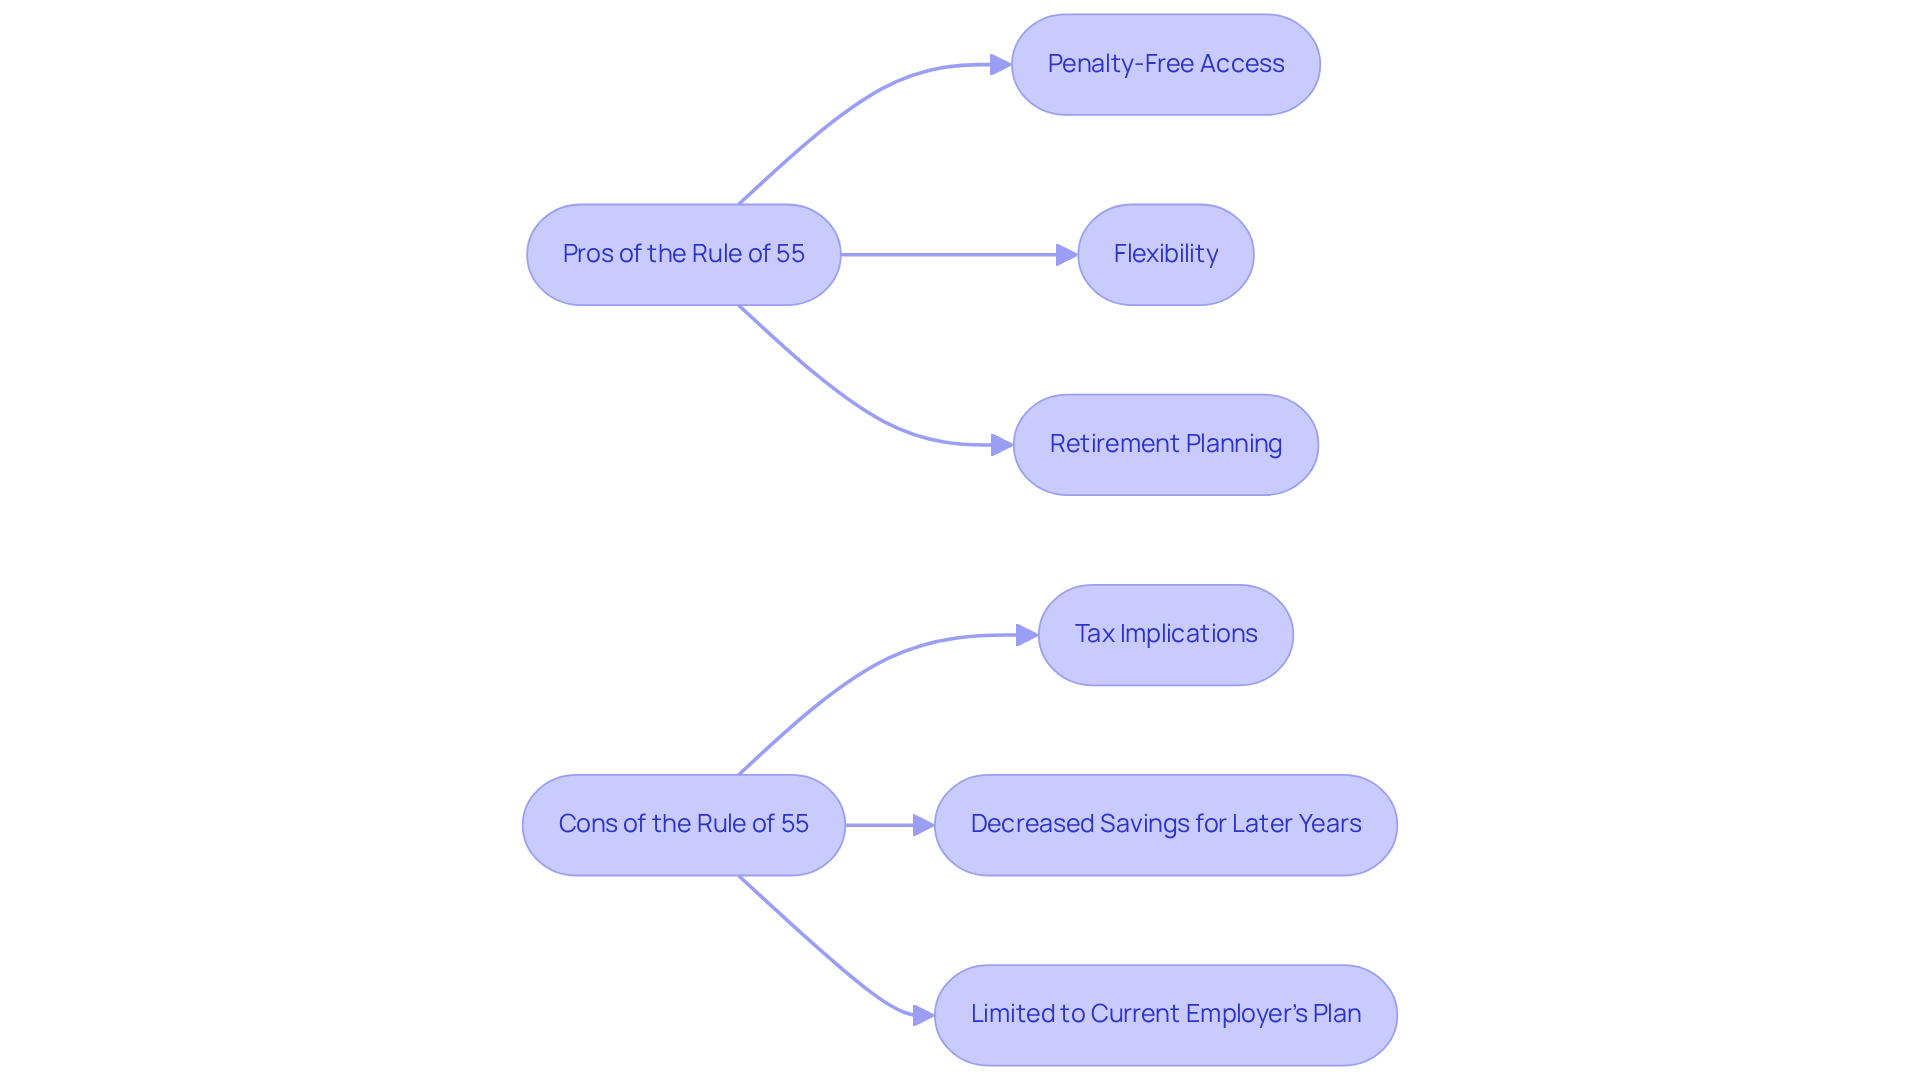
- Penalty-Free Access: Imagine having the ability to access your retirement savings without penalties. This rule allows for penalty-free withdrawals from a 401k at age 55, providing immediate funds in times of financial need, which can be a relief during challenging moments.
- Flexibility: Life can be unpredictable. The Rule of 55 offers financial flexibility for those approaching 401k age 55 who may need to retire early due to job loss or personal circumstances, helping you manage your family’s finances more effectively during these transitional times.
- Retirement Planning: Think of the Rule of 55 as a valuable tool in your broader retirement strategy. It can facilitate a smoother transition into this new phase of life by allowing access to 401k age 55 funds without incurring penalties.
Cons:
- Tax Implications: It’s important to understand that withdrawals under this rule are subject to regular income tax, including a 20% withholding on early withdrawals from a 401(k). This can significantly impact your tax bracket and overall financial situation, potentially leading to unexpected burdens.
- Decreased Savings for Later Years: Early withdrawals can diminish your savings, jeopardizing your long-term financial security. Additionally, this approach sacrifices tax deferral benefits, which may serve you better if other resources can cover your expenses.
- Limited to Current Employer’s Plan: Remember, the Rule of 55 applies only to the savings plan linked to your most recent employer. If you have multiple accounts, this could limit your options. Transferring your 401(k) into an IRA disqualifies you from penalty-free distributions under this rule.
Understanding these pros and cons is vital for making informed decisions about your financial strategy, especially when considering 401k age 55. Did you know that over 17% of traditional IRA owners adjust their distribution timing annually due to penalties for early access and required minimum distributions after age 72? Consulting with a trusted financial advisor or tax professional can provide clarity on the implications of early withdrawals and ensure your retirement planning aligns with your family’s long-term goals. We’re here for you, ready to support you on this journey.
Conclusion
The Rule of 55 is a vital financial strategy for those nearing retirement. If you’re 55 or older, this rule allows you to access your 401(k) or 403(b) funds without facing the usual 10% early withdrawal penalty. This provision can be a lifeline for those encountering unexpected financial challenges, offering a path to greater flexibility during significant life transitions.
Throughout our discussion, we’ve explored essential insights about:
- Eligibility requirements
- The process of utilizing the Rule of 55
- A balanced view of its advantages and disadvantages
Understanding the specific criteria needed to qualify—like age, separation from service, and the type of retirement plan—can empower you to make informed choices. Moreover, our conversation about tax implications and the potential effects on long-term savings underscores the importance of thoughtful planning and seeking guidance from financial professionals.
Ultimately, the Rule of 55 can be a powerful ally in your retirement planning journey, but it does require careful thought and strategic execution. As you navigate your financial future, embracing this rule can pave the way for enhanced security and peace of mind. By accessing your retirement funds wisely, you can help ensure that your financial goals are achieved, setting the stage for a stable and fulfilling retirement. Remember, we’re here for you, and together, we can navigate this journey toward a brighter financial future.
Frequently Asked Questions
What is the Rule of 55?
The Rule of 55 is an IRS provision that allows individuals to withdraw funds from their 401(k) or 403(b) plans without facing the usual 10% early withdrawal penalty if they leave their job during or after the year they turn 55.
Who can benefit from the Rule of 55?
Individuals who leave their job during or after the year they reach age 55 can benefit from the Rule of 55, providing financial relief during unexpected situations like job loss or voluntary departure from work.
Does the Rule of 55 apply to all retirement accounts?
No, the Rule of 55 specifically applies to employer-sponsored plans such as 401(k) and 403(b) plans, and does not extend to IRAs or other types of savings accounts.
Are there any tax implications when using the Rule of 55?
Yes, while individuals can access their funds without the 10% penalty, the distributions are still subject to federal and state income taxes, and a 20 percent income tax withholding rate may apply.
What are the potential risks of withdrawing funds under the Rule of 55?
The potential risks include depleting savings faster than anticipated and possibly moving into a higher tax bracket due to the additional income from withdrawals.
How much should one aim to have saved for retirement if retiring at 55?
It is suggested to aim for approximately $2 million across 401(k), IRA, and taxable accounts to provide a safety net for covering expenses comfortably in retirement.
List of Sources
- Define the Rule of 55 and Its Purpose
- What is the Rule of 55, and What Are the Rules? – Georgia Safe Retirement Planners (https://georgiasaferetirementplanners.com/403b-401k-withdrawal-age-55-rule)
- What Is The Rule Of 55? | Advantages of Retiring at 55 Using Rule of 55 (https://districtcapitalmanagement.com/rule-of-55)
- What Is The Rule Of 55 And How Does It Work? | Bankrate (https://bankrate.com/retirement/rule-of-55)
- When Can You Withdraw? 401(k)s and the Rule of 55 (https://schwab.com/learn/story/retiring-early-5-key-points-about-rule-55)
- The Value of a Financial Advisor: What’s It Really Worth? (https://smartasset.com/financial-advisor/financial-advisor-value-model)
- Identify Eligibility Requirements for the Rule of 55
- When Can You Withdraw? 401(k)s and the Rule of 55 (https://schwab.com/learn/story/retiring-early-5-key-points-about-rule-55)
- Rule of 55: How to Access Your 401(k) Early Without Penalty | Facet (https://facet.com/retirement-planning/rule-of-55-how-it-works-pros-and-cons-considerations)
- Britannica Money (https://britannica.com/money/what-is-401k-rule-of-55)
- The Best Quotes About Retirement (https://retirable.com/advice/lifestyle/best-retirement-quotes)
- Explain How to Utilize the Rule of 55 for Withdrawals
- 7 Quotes from Warren Buffett on How Retirees Should “Invest” in What Matters the Most (https://keenwealthadvisors.com/insights/7-quotes-from-warren-buffett-on-how-retirees-should-invest-in-what-matters-the-most)
- 90 Warren Buffett Quotes on Investing, Business, and Life (https://sarwa.co/blog/warren-buffett-quotes)
- 77 Financial Advisor Quotes to Send to Clients (https://billgoodmarketing.com/resources/financial-advisor-quotes)
- Rule of 55: How to Access Your 401(k) Early Without Penalty | Facet (https://facet.com/retirement-planning/rule-of-55-how-it-works-pros-and-cons-considerations)
- Top 50 Financial Planning Quotes [2025] (https://digitaldefynd.com/IQ/financial-planning-quotes)
- Evaluate Pros and Cons of the Rule of 55
- What Is The Rule Of 55 And How Does It Work? | Bankrate (https://bankrate.com/retirement/rule-of-55)
- When Can You Withdraw? 401(k)s and the Rule of 55 (https://schwab.com/learn/story/retiring-early-5-key-points-about-rule-55)
- The impact of withdrawal penalties on retirement savings (https://sciencedirect.com/science/article/pii/S0047272724000197)
- What Is the Rule of 55? How It Works for Early Retirement (https://sofi.com/learn/content/rule-of-55-retirement)
- Retirement Savings: Additional Data and Analysis Could Provide Insight into Early Withdrawals (https://gao.gov/products/gao-19-179)

Kevin has advised high-income W-2 tech and biotech families since 2015, and leads the education-first Age Five Family Office from Brea, California.
Connect on LinkedIn → · About KevinThis is part of how we approach Retirement & Employee Benefits for high-income W-2 families at Bright Advisers.
Keep reading