

Overview
This article serves as a caring guide for parents looking to navigate the process of rolling over funds from a 529 plan to a Roth IRA. It gently emphasizes the eligibility criteria, transfer limits, and the step-by-step process involved, ensuring that you feel supported every step of the way.
Imagine if you could secure your child’s future while adhering to specific rules, such as:
- Keeping the 529 account open for at least 15 years
- Ensuring the Roth IRA is in the beneficiary’s name
These guidelines not only comply with IRS regulations but also facilitate a tax-free transfer, making the journey smoother for you and your family. Together, we can explore these financial strategies, ensuring that your family’s values and goals are at the forefront of your planning.
Key Highlights:
- A 529 account offers tax-free growth and withdrawals for qualified education expenses, making it ideal for education savings.
- Roth IRAs provide tax-free growth and withdrawals during retirement, focusing on retirement savings.
- To roll over funds from a 529 to a Roth IRA, the 529 account must be open for at least 15 years, and funds must be in the account for a minimum of 5 years.
- Annual transfer limits are $7,000, or $8,000 for beneficiaries aged 50 or older, with a lifetime limit of $35,000 per beneficiary.
- The Roth IRA must be established in the name of the 529 plan beneficiary to comply with IRS regulations.
- Tax-free rollover requires adherence to specific rules to avoid penalties and taxes.
- The rollover process includes verifying eligibility, opening a Roth IRA, contacting the 529 provider, completing and submitting the rollover request, and confirming the transfer.
- Challenges in the rollover process include understanding eligibility, managing paperwork, timing issues, and assessing future educational needs.
Introduction
Navigating the world of education savings and retirement planning can often feel overwhelming for parents. Imagine if you could turn this complexity into a unique opportunity for your family. With new regulations allowing the transfer of funds from a 529 plan to a Roth IRA, families have a chance to maximize their financial strategies in ways that truly matter.
However, it’s important to understand that the complexities surrounding eligibility, rollover rules, and tax implications raise critical questions:
- How can parents effectively leverage this rollover to secure their children’s educational future while also preparing for retirement?
This guide will gently unravel the step-by-step process, equipping you with the knowledge you need to make informed decisions and overcome common challenges along the way. Together, we can navigate this journey, ensuring a brighter future for your family.
Understand 529 Plans and Roth IRAs
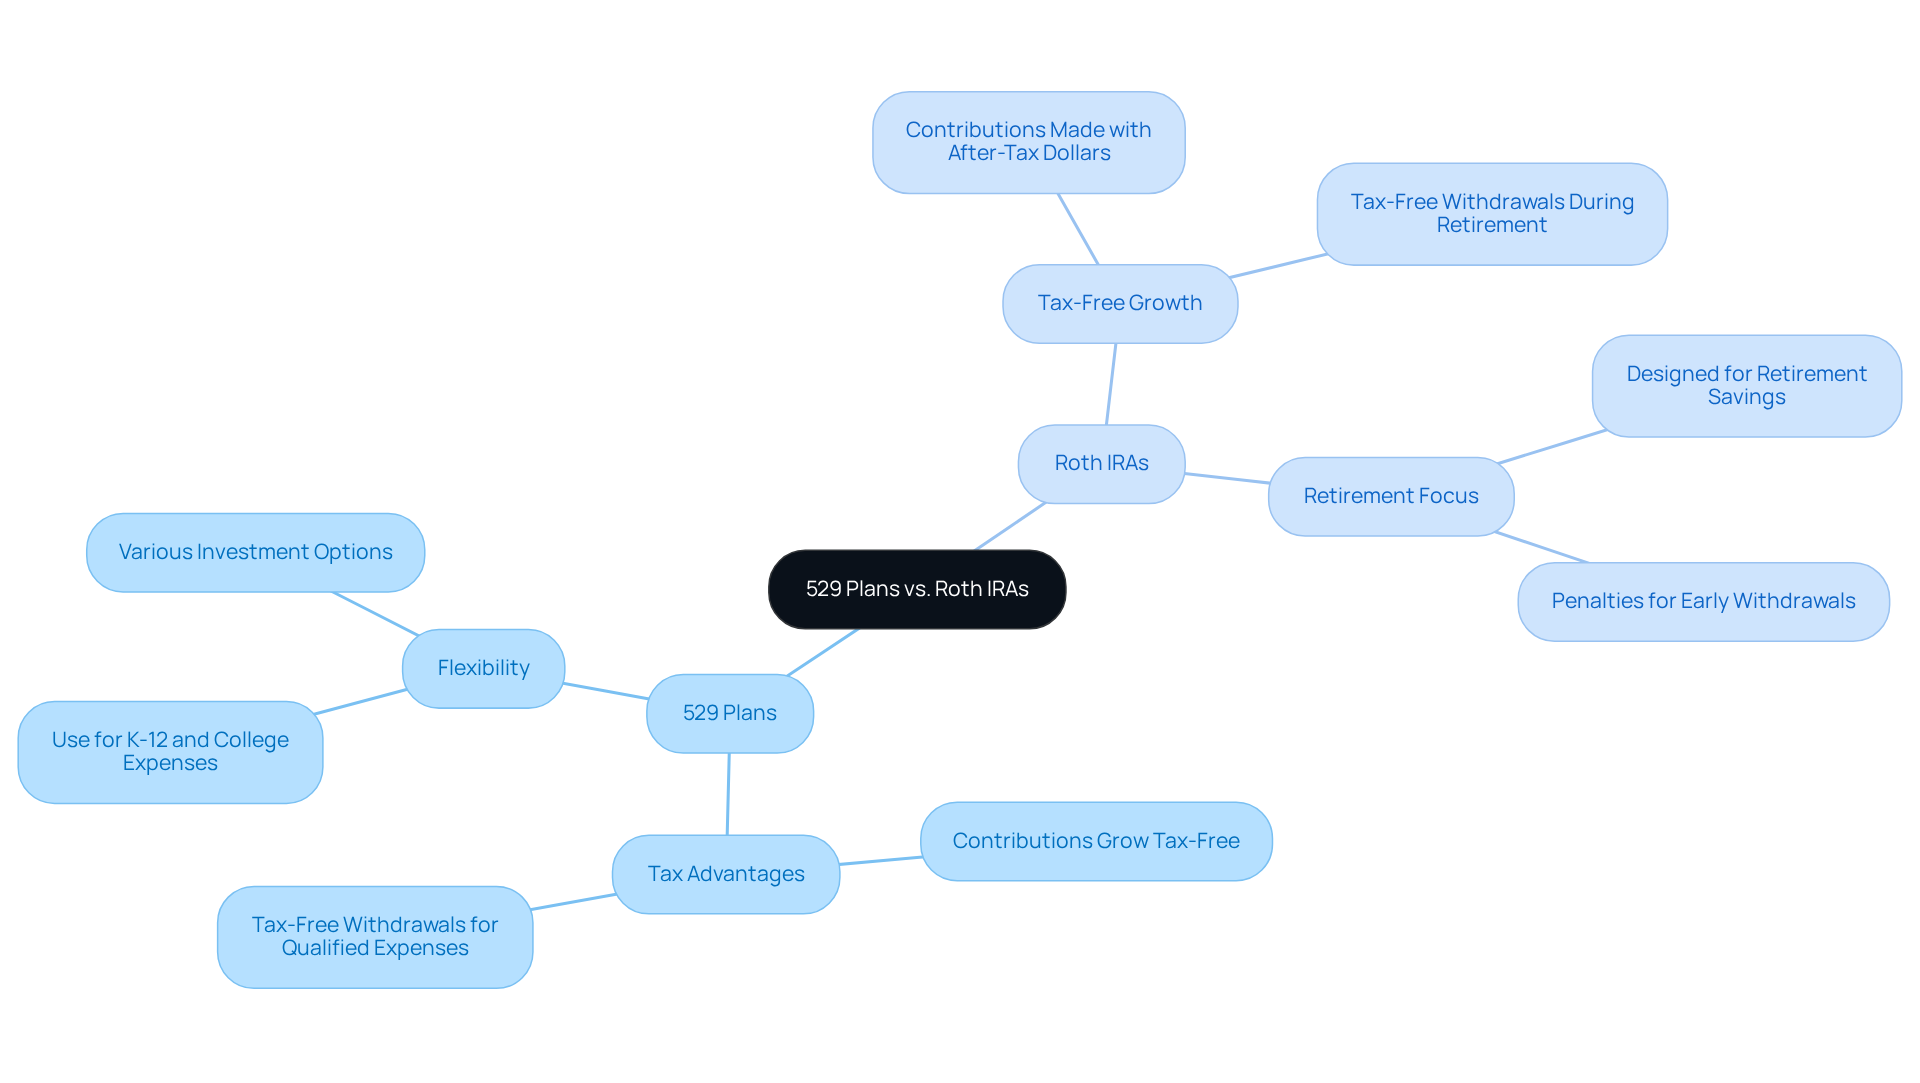
A 529 account is a wonderful option for families looking to save for education expenses, whether for college or K-12 tuition. With a 529 account, your contributions grow , and when it’s time to withdraw funds for qualified education expenses, those withdrawals are also . On the other hand, a specific type of IRA focuses primarily on retirement savings, allowing for tax-free growth and tax-free withdrawals during retirement, as long as certain conditions are met. Understanding these differences is crucial for parents who want to enhance their financial strategies, especially when considering the transfer of funds from a 529 to Roth IRA.
Key Features of 529 Plans:
- Tax Advantages: Contributions grow tax-free, and withdrawals for qualified education expenses are tax-free.
- Flexibility: Funds can be utilized for a range of educational expenses, including tuition, room and board, and K-12 costs.
Key Features of Roth IRAs:
- Tax-Free Growth: Contributions are made with after-tax dollars, allowing for tax-free growth.
- Retirement Focus: Designed for retirement savings, with penalties for early withdrawals unless specific conditions are met.
By understanding these accounts, you can navigate your options for funding your children’s education and addressing future financial needs with confidence. Remember, we’re here for you, and together, we can navigate this journey.
Review Rollover Rules and Limits
Before you consider rolling over funds from a 529 to Roth IRA, it’s important to understand some essential rules and limits that can help guide your decision-making.
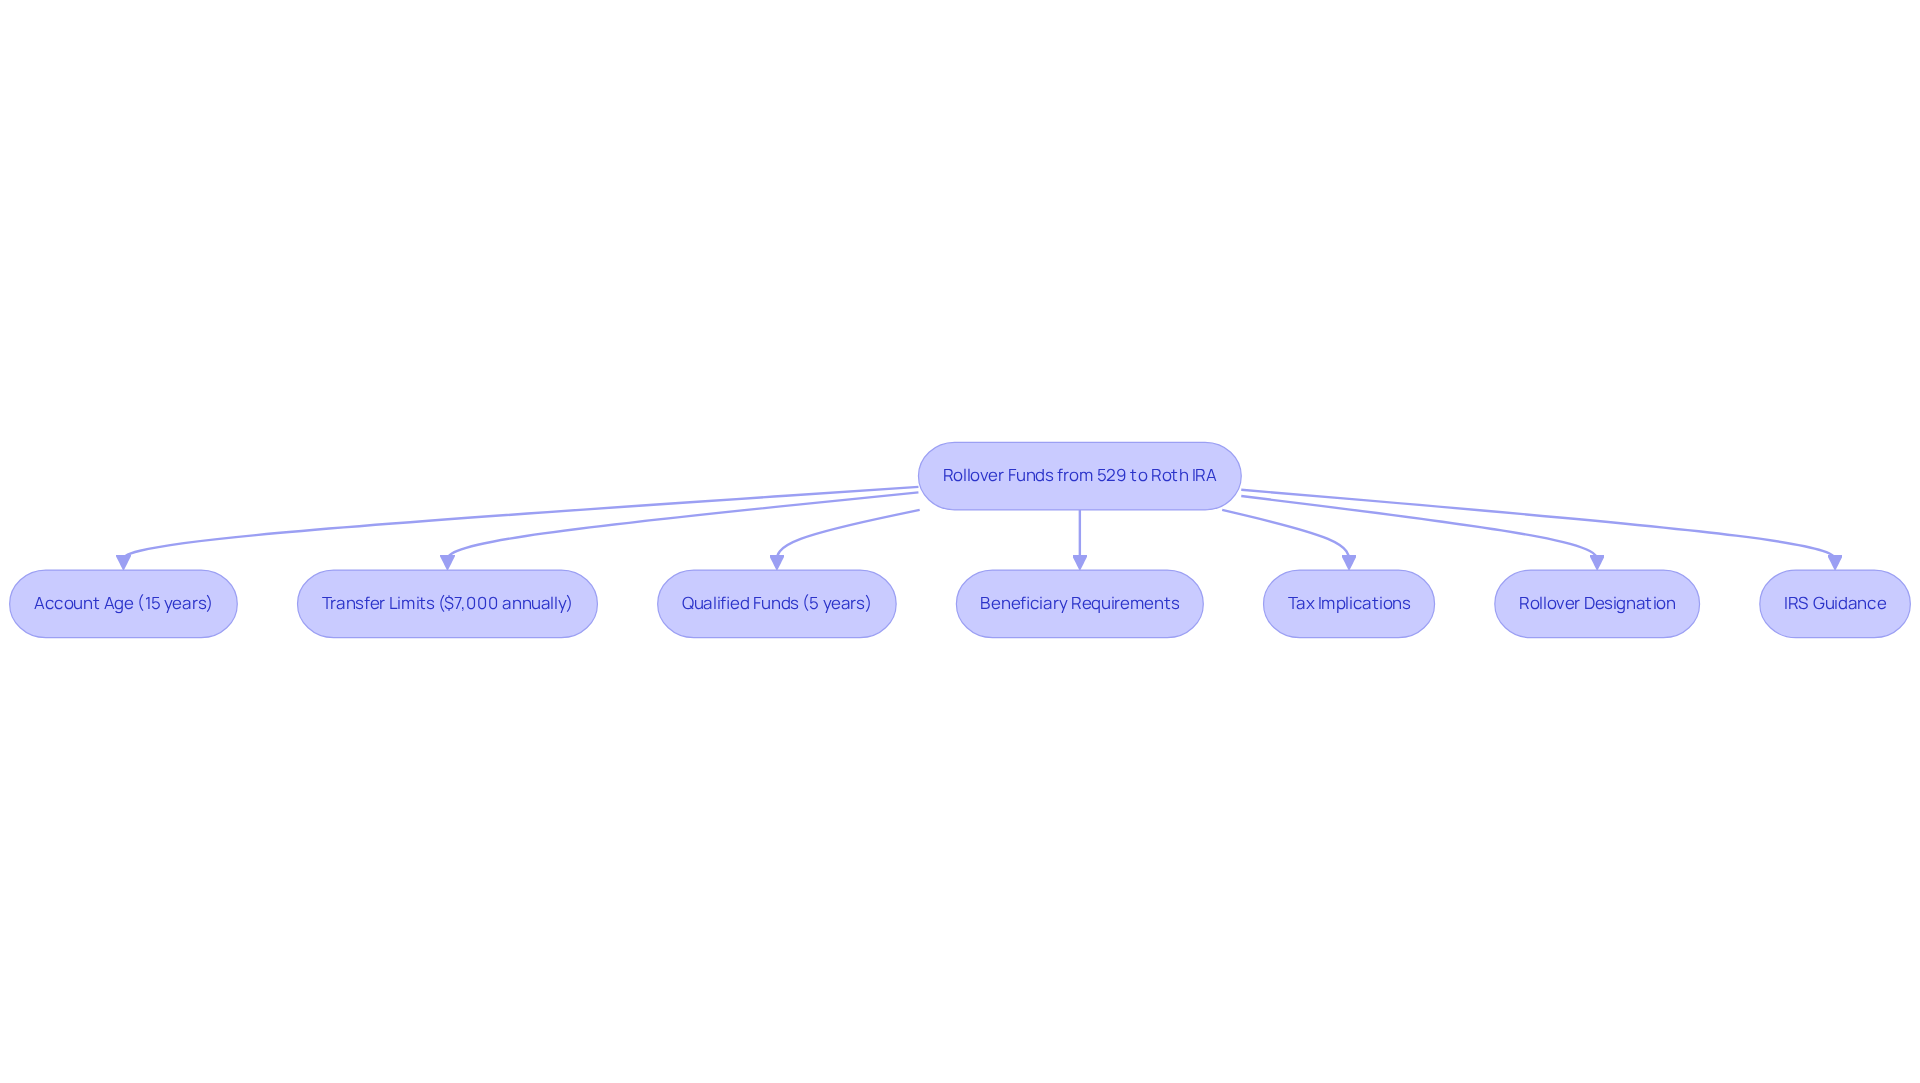
Key Rollover Rules:
- Account Age: Your 529 account should be before you can roll over any funds. This guideline ensures that only long-term savings are eligible for transfer, giving you peace of mind that you’re making the most of your investment.
- Transfer Limits: For the tax years 2024 and 2025, you can transfer up to $7,000 annually, or $8,000 if the beneficiary is 50 years or older. Additionally, there is a lifetime limit of $35,000 per beneficiary for transfers from 529 to Roth IRA.
- Qualified Funds: Only funds that have been in your 529 account for a minimum of 5 years can be transferred. This rule is in place to prevent the transfer of newer contributions or earnings, ensuring that your established savings are utilized effectively.
Important Considerations:
- Beneficiary Requirements: It’s essential that the Roth IRA is set up in the name of the 529 plan beneficiary, not the account owner. This requirement is crucial for complying with IRS regulations and ensuring that you’re on the right track.
- Tax Implications: When you adhere to all the rules, the transferred amounts are exempt from federal taxes and penalties. This makes the strategy of rolling over to a 529 to Roth IRA a tax-efficient option for families looking to secure their financial future.
- Rollover Designation: If you submit rollover requests for 2025, you can designate them as Roth IRA contributions for that tax year, provided they are completed by April 15, 2026. Keep in mind that processing delays can occur, which may impact how promptly these transfers are assigned.
- IRS Guidance: Currently, the IRS has not provided final guidance on the 15-year period for 529 accounts, which is generally considered from the date the account was opened. Understanding these rules is vital for you to navigate the rollover process smoothly and ensure compliance with IRS guidelines.
Together, we can navigate this journey, ensuring that you make informed decisions for your family’s financial well-being.
Follow the Step-by-Step Rollover Process
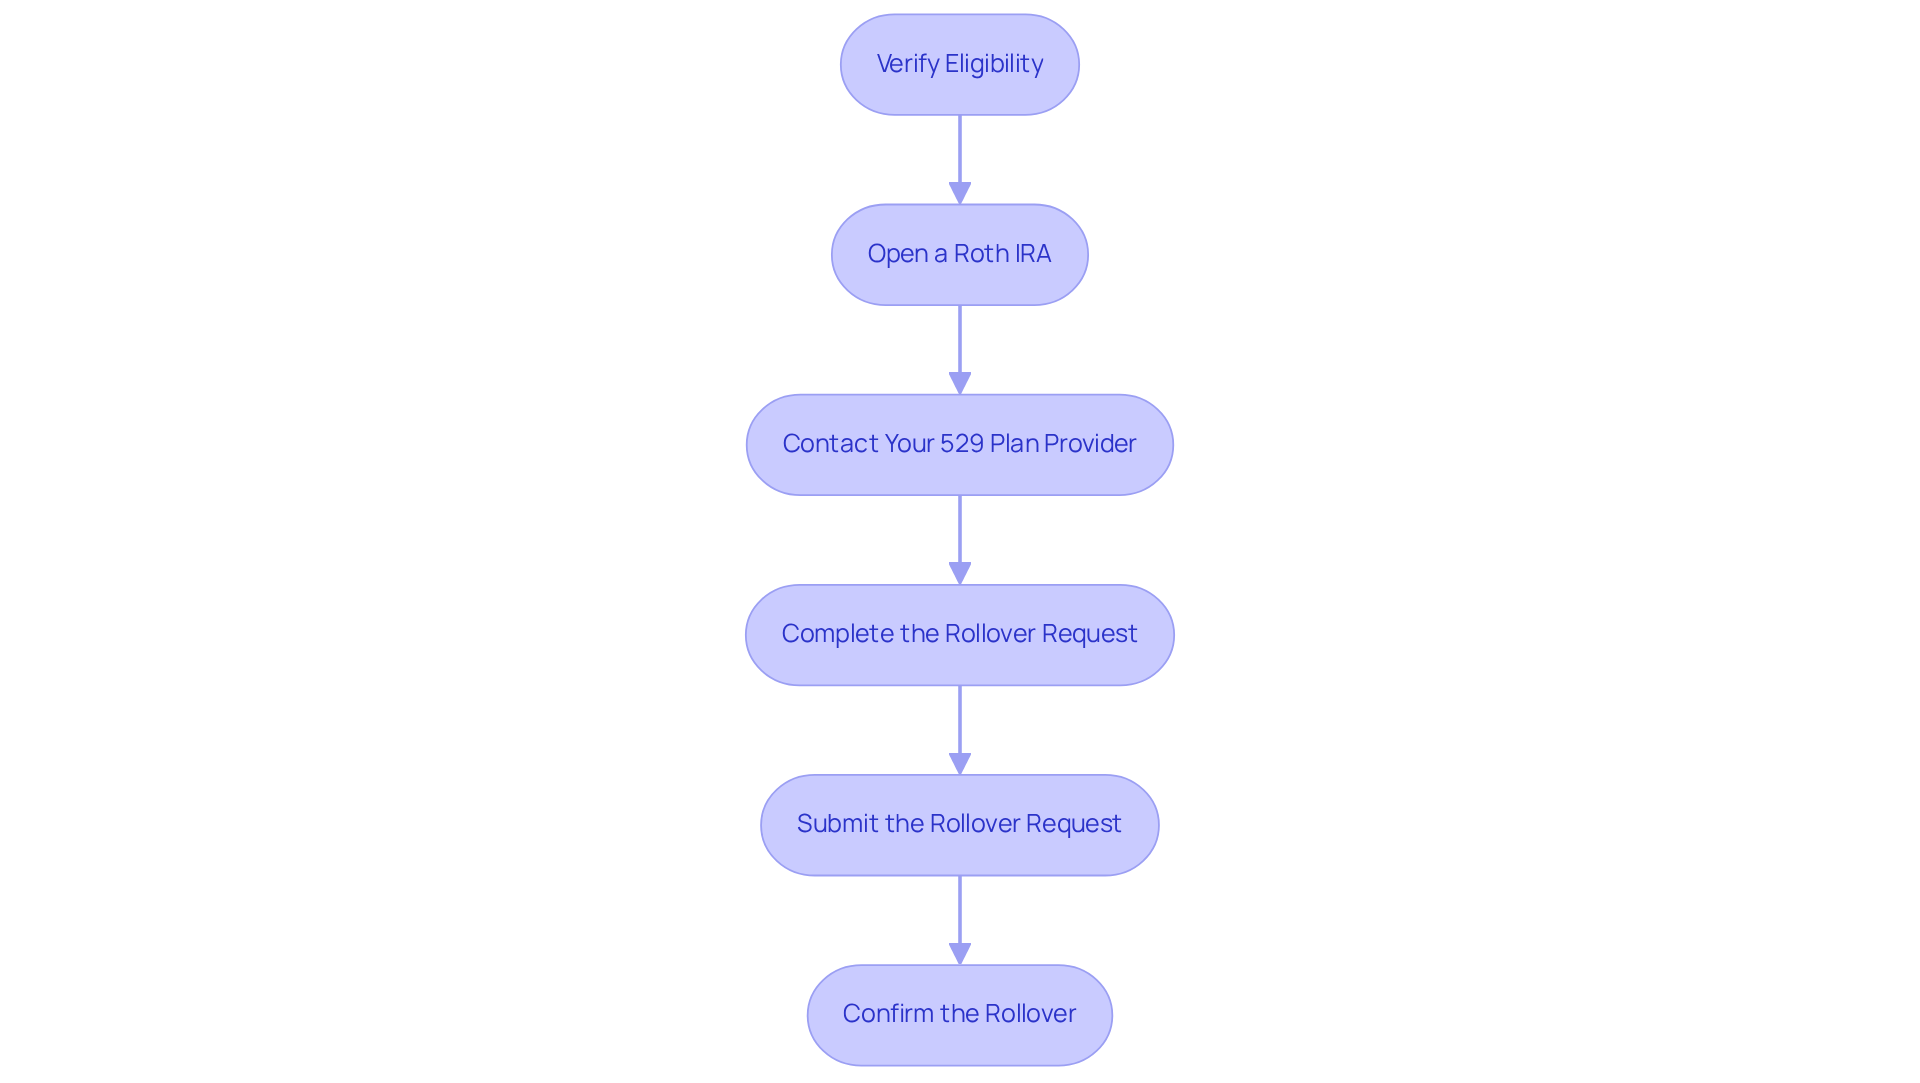
To successfully roll over funds from a 529 plan to a Roth IRA, follow these essential steps:
- Verify Eligibility
Imagine the peace of mind that comes with knowing your 529 account has been active for at least 15 years and that the funds have been in the account for a minimum of 5 years. Confirming this is the first step toward securing your child’s future. - Open a Roth IRA
If you do not already have a Roth IRA, now is the time to open one in the name of the 529 plan beneficiary. Take a moment to research financial institutions that offer Roth IRAs, comparing fees and investment options to find the best fit for your family’s needs. - Contact Your 529 Plan Provider
It’s important to reach out to your 529 plan provider to notify them of your intention to roll over funds. They will guide you through the process, so don’t hesitate to ask for any necessary forms or documentation required for the rollover. - Complete the Rollover Request
When filling out the required forms, including the Roth IRA Rollover Request Form, take your time. Double-check all information to ensure completeness and accuracy, as this will help avoid any delays. - Submit the Rollover Request
Once you have completed the forms, submit them to both your 529 plan provider and the Roth IRA custodian. It’s crucial to carry out the transfer directly to avoid any tax implications. This step is vital for protecting your family’s financial future. - Confirm the Rollover
After submitting your request, confirm with both institutions that the rollover has been successfully completed. Retain records of the transaction for your financial documentation—this will be beneficial for your peace of mind.
As Jeff White, a Certified Educator of Personal Finance, states, “With the new regulations, 529 account owners or beneficiaries can transfer 529 funds into a beneficiary-owned IRA without taxes or penalties starting January 1, 2024, subject to the limitations described below.” By following these steps, you can enable a smooth transfer of funds from a 529 account to an IRA, ensuring you optimize your financial strategies for your children’s future. Remember, together, we can navigate this journey.
Navigate Common Challenges and Considerations
While can offer significant benefits, many parents may face challenges along the way.
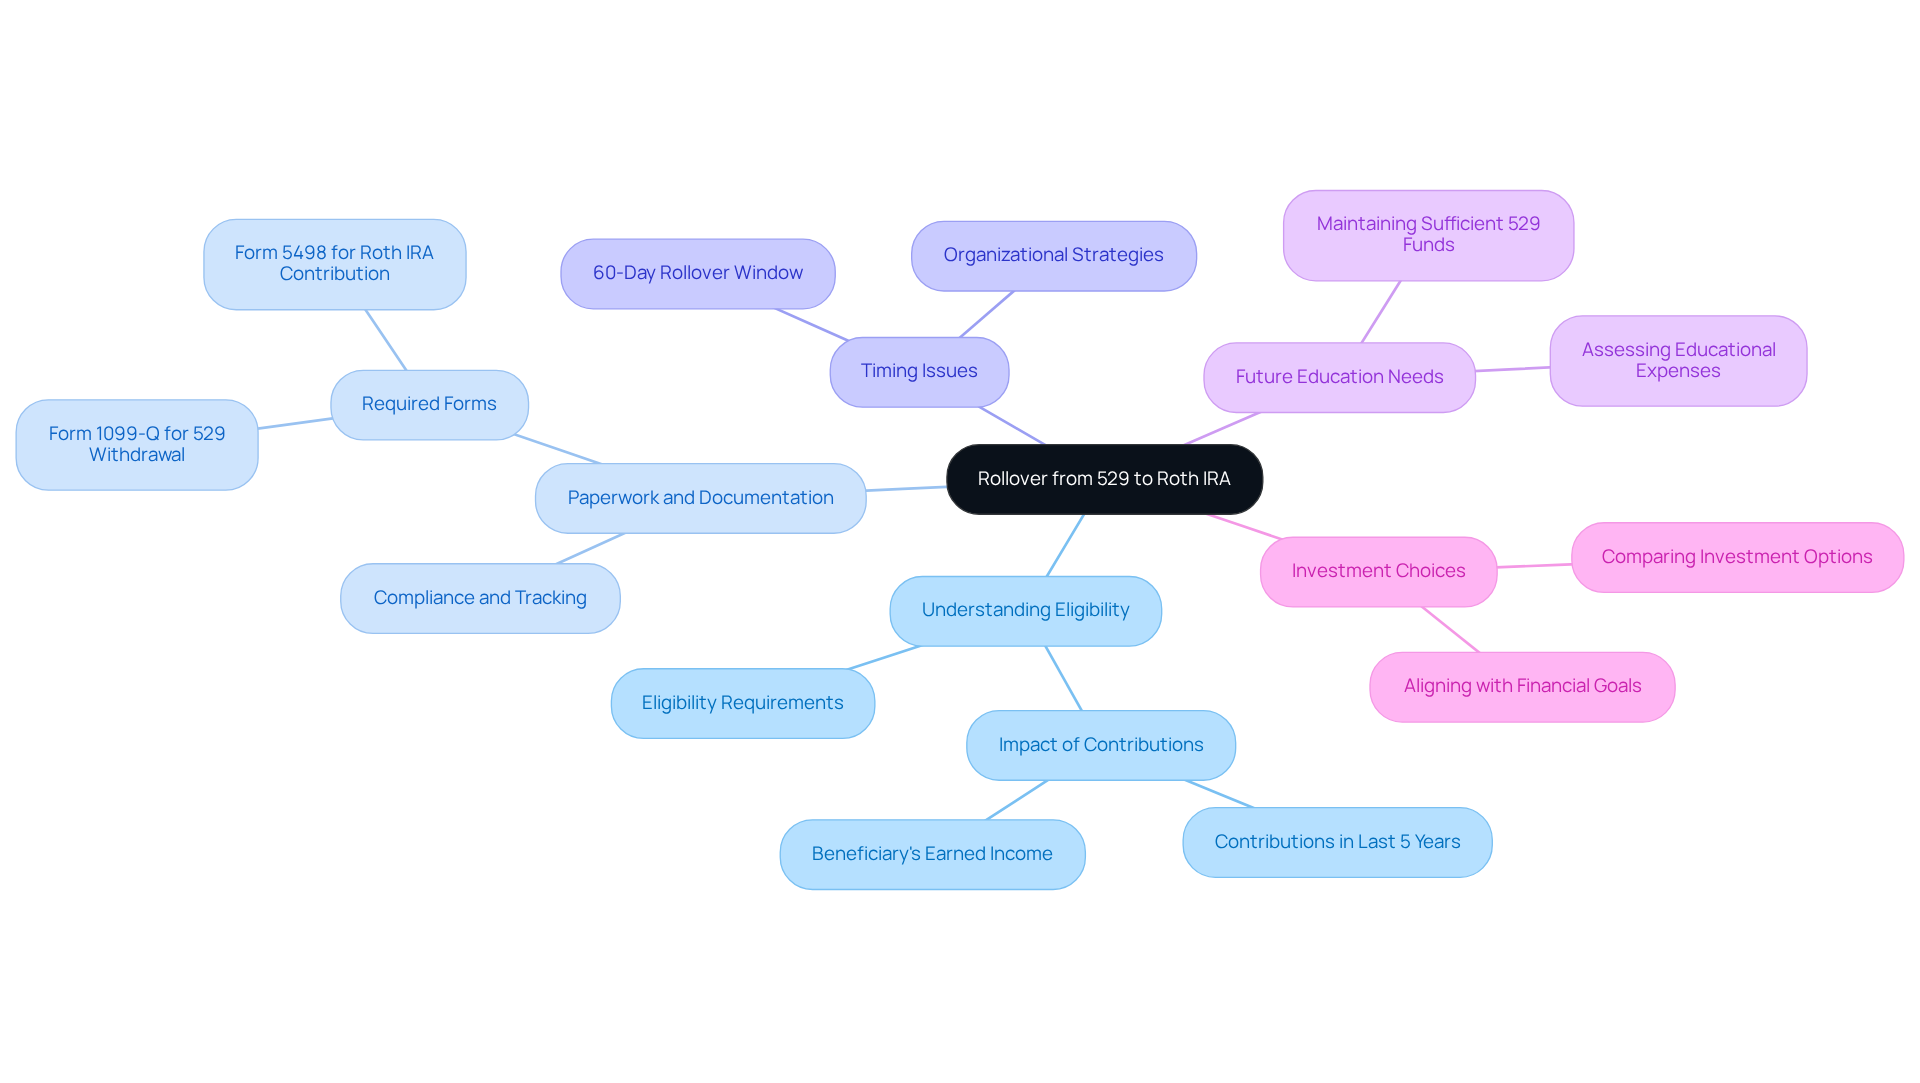
Understanding Eligibility: Imagine feeling uncertain about the eligibility requirements for rollovers. This confusion can lead to costly mistakes. Recent surveys reveal that 76% of parents without a 529 plan are more inclined to consider starting one due to the new transfer advantage. This highlights the importance of clear understanding.
Paperwork and Documentation: The documentation required for finalizing the transfer can feel overwhelming. It’s essential to gather all necessary paperwork, including reporting the transfer on Form 1099-Q for the 529 withdrawal and Form 5498 for the Roth IRA contribution. This ensures compliance and helps prevent delays or penalties.
Timing Issues: Timing is critical in this transition process. Funds must be rolled over within 60 days of withdrawal to avoid penalties. Staying organized and proactive in tracking the rollover process is essential for parents navigating this journey.
Future Education Needs: As you consider rolling over funds, specifically from a 529 to Roth IRA, it’s important to assess how this decision might impact your ability to cover future educational expenses. Contributions made to the 529 account within the last five years cannot be rolled over, so maintaining sufficient funds in the 529 account for education is vital to avoid financial strain later on.
Investment Choices: Take a moment to compare the investment options available in the individual retirement account with those in the 529 plan. The flexibility of a Roth IRA can provide diverse opportunities for growth. Ensure that your chosen investments align with your long-term financial goals.
At Bright Advisers, we are dedicated to minimizing fund fees, enhancing wealth management accessibility for families. Some clients may hold legacy fee-bearing mutual funds and low-fee-bearing ETFs, particularly to gain exposure to fixed income or alternative asset classes. By offering tailored wealth management solutions, we empower parents to make informed decisions that secure their financial futures. Recognizing these challenges and considerations allows parents to navigate the rollover process more effectively. Together, we can navigate this journey, ensuring that your family’s financial future is bright.
Conclusion
Understanding the intricacies of rolling over funds from a 529 plan to a Roth IRA is essential for parents who wish to optimize their financial strategies for their children’s education and future. This process not only allows for the effective utilization of saved funds but also offers tax advantages that can significantly benefit families in the long run. Imagine if you could secure your child’s future while making the most of your savings. By mastering the rollover process, parents can ensure that they are making informed decisions that align with their financial goals.
Throughout this article, we’ve explored key aspects such as the differences between 529 plans and Roth IRAs, the specific rules governing rollovers, and a step-by-step guide to executing this transfer. It’s important to understand the eligibility requirements, documentation needed, and the significance of maintaining sufficient funds in the 529 account for future educational needs. Navigating these elements is crucial for overcoming potential challenges and truly maximizing this financial strategy.
Ultimately, the opportunity to roll over funds from a 529 to a Roth IRA represents a significant advantage for parents planning their financial futures. By taking proactive steps and being well-informed about the rules and implications, families can secure their financial well-being and pave the way for a brighter future. We’re here for you—engaging with financial advisors and utilizing available resources can further empower parents to make the best choices for their children’s education and beyond. Together, we can navigate this journey toward financial security.
Frequently Asked Questions
What is a 529 Plan?
A 529 Plan is a savings account designed for families to save for education expenses, including college and K-12 tuition, allowing contributions to grow tax-free and enabling tax-free withdrawals for qualified education expenses.
What are the key features of a 529 Plan?
The key features of a 529 Plan include tax advantages where contributions grow tax-free and withdrawals for qualified education expenses are also tax-free, as well as flexibility to use funds for various educational costs such as tuition, room and board, and K-12 expenses.
What is a Roth IRA?
A Roth IRA is a type of individual retirement account that focuses on retirement savings, allowing for tax-free growth of contributions made with after-tax dollars and tax-free withdrawals during retirement, provided certain conditions are met.
What are the key features of a Roth IRA?
The key features of a Roth IRA include tax-free growth on contributions and a focus on retirement savings, with penalties for early withdrawals unless specific conditions are satisfied.
How do 529 Plans and Roth IRAs differ?
529 Plans are primarily for education savings with tax-free growth and withdrawals for qualified education expenses, while Roth IRAs are focused on retirement savings, allowing for tax-free growth and withdrawals during retirement under certain conditions.
Can funds be transferred from a 529 Plan to a Roth IRA?
The article implies that understanding the differences between these accounts is important for parents considering the transfer of funds from a 529 Plan to a Roth IRA, although it does not provide specific details on the transfer process.
List of Sources
- Understand 529 Plans and Roth IRAs
- 529 College Savings Plan Statistics | BestColleges (https://bestcolleges.com/research/529-college-savings-plan-statistics)
- 529 Plan Statistics | The Motley Fool (https://fool.com/research/529-plan-statistics)
- 529 Plan And College Savings Statistics (https://thecollegeinvestor.com/529-plan-and-college-savings-statistics?srsltid=AfmBOoqHGzEAbpB9Bb-YnQOhKjKuA9L-RuoPLCxNDsquacoQ-5yuyoyu)
- 529 Plan Surge: Roth IRA Rollover Rule Changes the Game (https://thecollegeinvestor.com/59257/529-plan-account-balances-just-hit-a-record-in-2025?srsltid=AfmBOoq7jDw11sz9QkPBddEmor0C0F_FMbVFZOJyW1LpoPFrDhsdMIJx)
- Review Rollover Rules and Limits
- 529 to Roth IRA: Rollover Rules, Conversion Guide, and FAQs (https://savingforcollege.com/article/roll-over-529-plan-funds-to-a-roth-ira)
- What You Need to Know about Roth IRA Rollovers (https://invest529.com/blog/what-you-need-to-know-about-roth-ira-rollovers)
- The new rules that have money rolling into 529 accounts | TIAA (https://tiaa.org/public/invest/services/wealth-management/perspectives/529-to-roth-ira-rules)
- 529-to-Roth IRA Rollovers: What to Know (https://schwab.com/learn/story/529-to-roth-ira-rollovers-what-to-know)
- Follow the Step-by-Step Rollover Process
- A key change to 529 plans this year is already triggering parents to save more for college (https://cnbc.com/2024/10/25/parents-are-saving-more-for-college-thanks-to-529-to-roth-rollovers.html)
- 529 to Roth IRA: Rollover Rules, Conversion Guide, and FAQs (https://savingforcollege.com/article/roll-over-529-plan-funds-to-a-roth-ira)
- Important Information on 529-to-Roth IRA Rollovers | Lord Abbett (https://lordabbett.com/en-us/financial-advisor/insights/retirement-planning/important-information-on-529-to-roth-ira-rollovers.html)
- A retirement savings head start: 529-to-Roth rollovers (https://thetaxadviser.com/issues/2024/jul/a-retirement-savings-head-start-529-to-roth-rollovers)
- Navigate Common Challenges and Considerations
- A key change to 529 plans this year is already triggering parents to save more for college (https://cnbc.com/2024/10/25/parents-are-saving-more-for-college-thanks-to-529-to-roth-rollovers.html)
- What to Know About Rolling a 529 Account Into a Roth IRA (https://elderlawanswers.com/what-to-know-about-rolling-a-529-account-into-a-roth-ira-20673)
- SECURE 2.0 Act’s New 529-To-Roth Rollover Rules (https://kitces.com/blog/529-to-roth-ira-rollover-retirement-saving-education-planning-secure-2-0-backdoor-roth)
- Awareness of 529 to Roth IRA Rollovers is Small, but Growing (https://psca.org/news/psca-news/2024/11/awareness-of-529-to-roth-ira-rollovers-is-small-but-growing)
- 529 to Roth IRA Rollovers: What You Need to Know (https://theentrustgroup.com/blog/529-rollover-to-roth-ira)

Kevin has advised high-income W-2 tech and biotech families since 2015, and leads the education-first Age Five Family Office from Brea, California.
Connect on LinkedIn → · About KevinThis is part of how we approach Age Five Wealth Education for high-income W-2 families at Bright Advisers.
Keep reading