

Key Highlights:
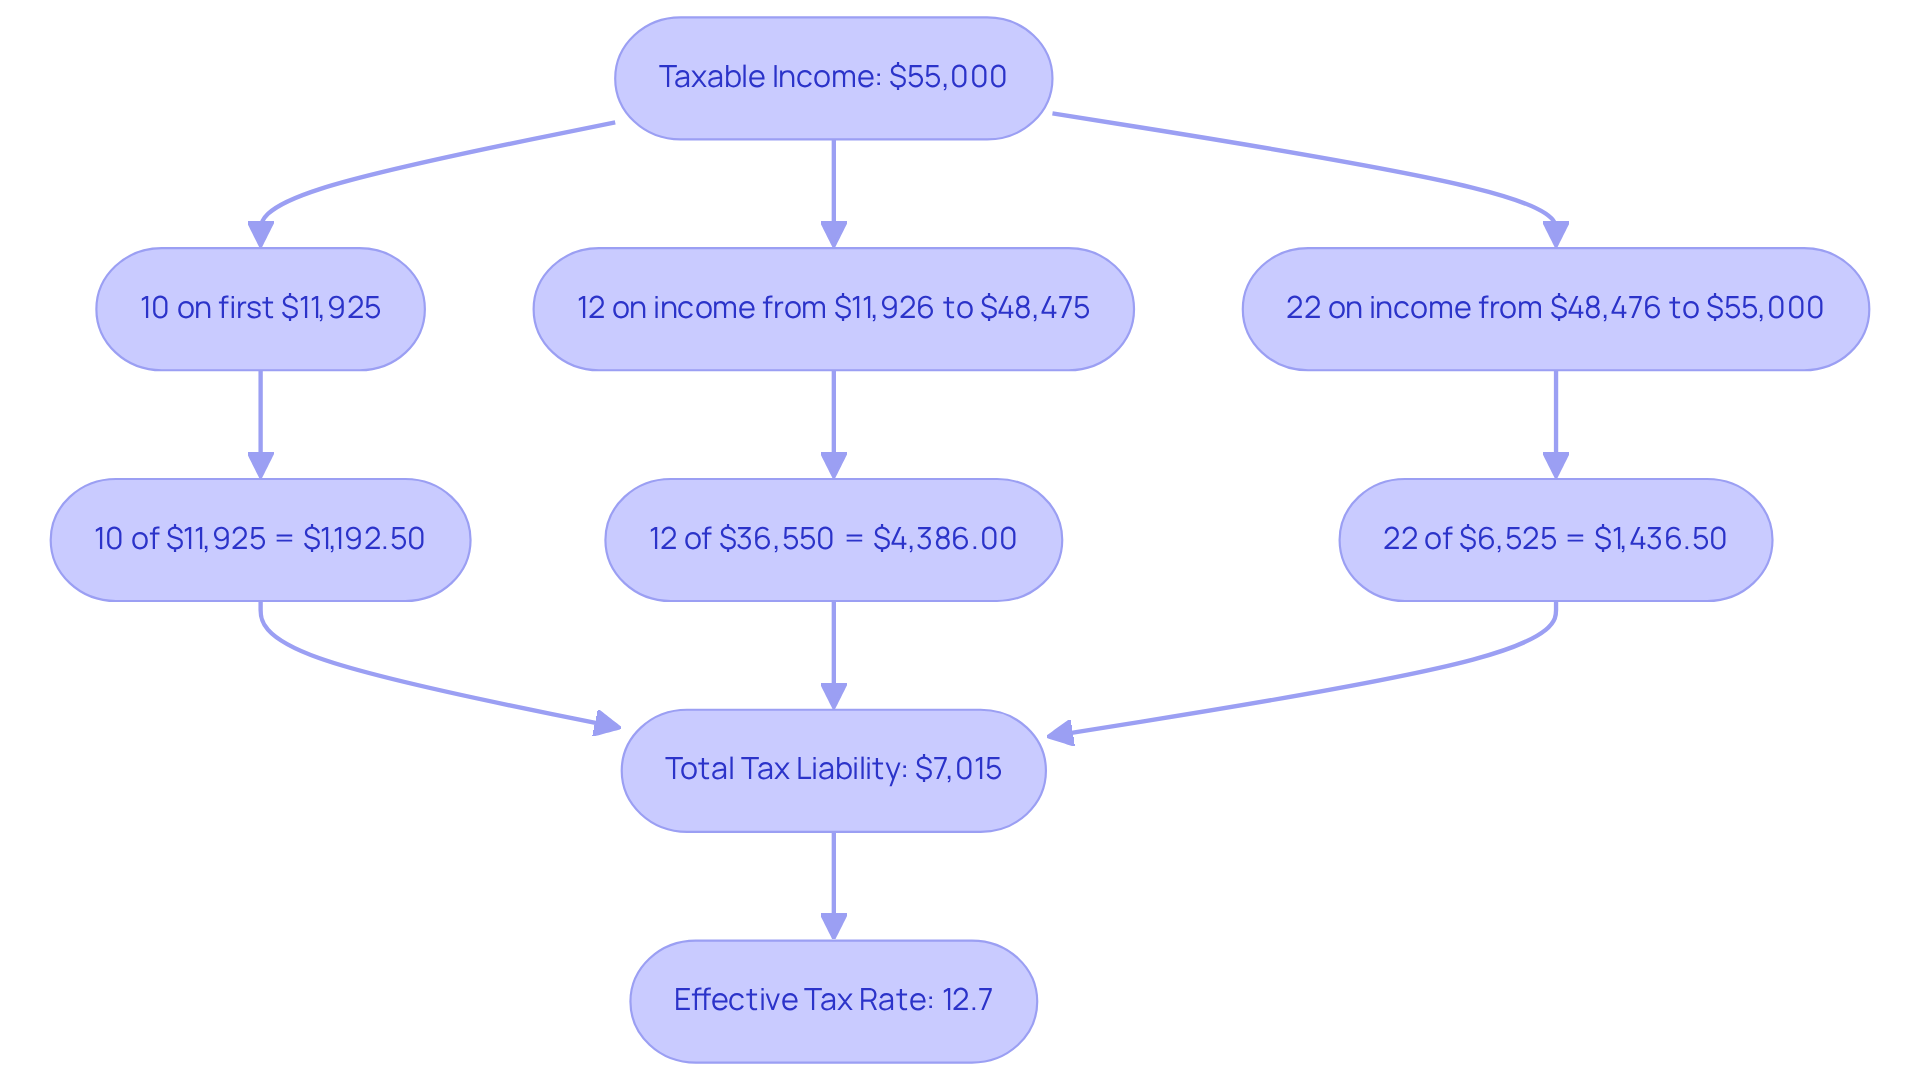
- The 55k tax bracket features progressive taxation: 10% on the first $11,925, 12% on $11,926 to $48,475, and 22% on $48,476 to $55,000.
- Total tax liability for a $55,000 income is approximately $7,015, resulting in an effective tax rate of about 12.7%.
- Key tax credits for families include the Child Tax Credit (up to $2,200 per child), Earned Income Tax Credit (EITC), and Child and Dependent Care Credit.
- The standard deduction for married couples filing jointly is $27,700 for 2025, which can significantly reduce taxable income.
- Strategies for tax optimization include maximising retirement contributions, utilising Flexible Spending Accounts (FSAs), tax-loss harvesting, and reviewing tax withholdings.
- Establishing a long-term tax planning approach involves setting monetary goals, staying updated on tax law changes, reviewing financial plans annually, consulting tax professionals, and educating family members about finances.
Introduction
Navigating the complexities of the 55k tax bracket can feel overwhelming for young families seeking financial stability. Imagine trying to understand how your income is taxed while also identifying deductions and credits that could lead to significant savings. It’s a lot to take in, but it’s essential for making informed financial decisions that benefit your family.
It’s important to recognize that tax laws are constantly changing, and there are many strategies to consider. How can families effectively optimize their tax situation and secure their financial future? This guide is here to help you every step of the way. We’ll walk you through mastering the 55k tax bracket, ensuring you can confidently navigate your fiscal landscape.
Together, we can explore the ins and outs of tax planning, focusing on what truly matters to your family. By understanding these intricacies, you’ll be empowered to make choices that align with your values and goals. Remember, you’re not alone in this journey; we’re here for you, ready to support you in achieving financial peace of mind.
Understand the 55k Tax Bracket Basics
Navigating the 55k tax bracket can feel overwhelming, but understanding how tax brackets work is the first step toward financial confidence. In 2025, our federal taxation system is designed to be progressive, meaning different parts of your income are taxed at different rates. If your taxable income is $55,000, you find yourself in the 55k tax bracket. Let’s break it down together:
- 10% on the first $11,925
- 12% on income from $11,926 to $48,475
- 22% on income from $48,476 to $55,000
While your marginal tax rate is 22%, it’s crucial to remember that not all your income is taxed at this rate. Grasping this structure helps you calculate your effective tax rate and plan your finances more effectively. For instance, if you earn $55,000, your total tax liability would look like this:
- 10% of $11,925 = $1,192.50
- 12% of $36,550 (the amount between $11,926 and $48,475) = $4,386.00
- 22% of $6,525 (the amount between $48,476 and $55,000) = $1,436.50
When you add these amounts together, your total tax liability comes to about $7,015, leading to an effective tax rate of around 12.7%. Understanding this is vital for young families, as it lays the groundwork for effective tax planning and optimization strategies.
Imagine being able to navigate your finances with confidence, knowing you’re making informed decisions for your family’s future. We’re here for you, ready to toward financial well-being.
Identify Tax Deductions and Credits Available
Navigating your tax situation can feel overwhelming, but you’re not alone. It’s essential to identify the deductions and credits available to you, especially when you’re focused on providing for your family. Here are some key options for families earning around $55,000:
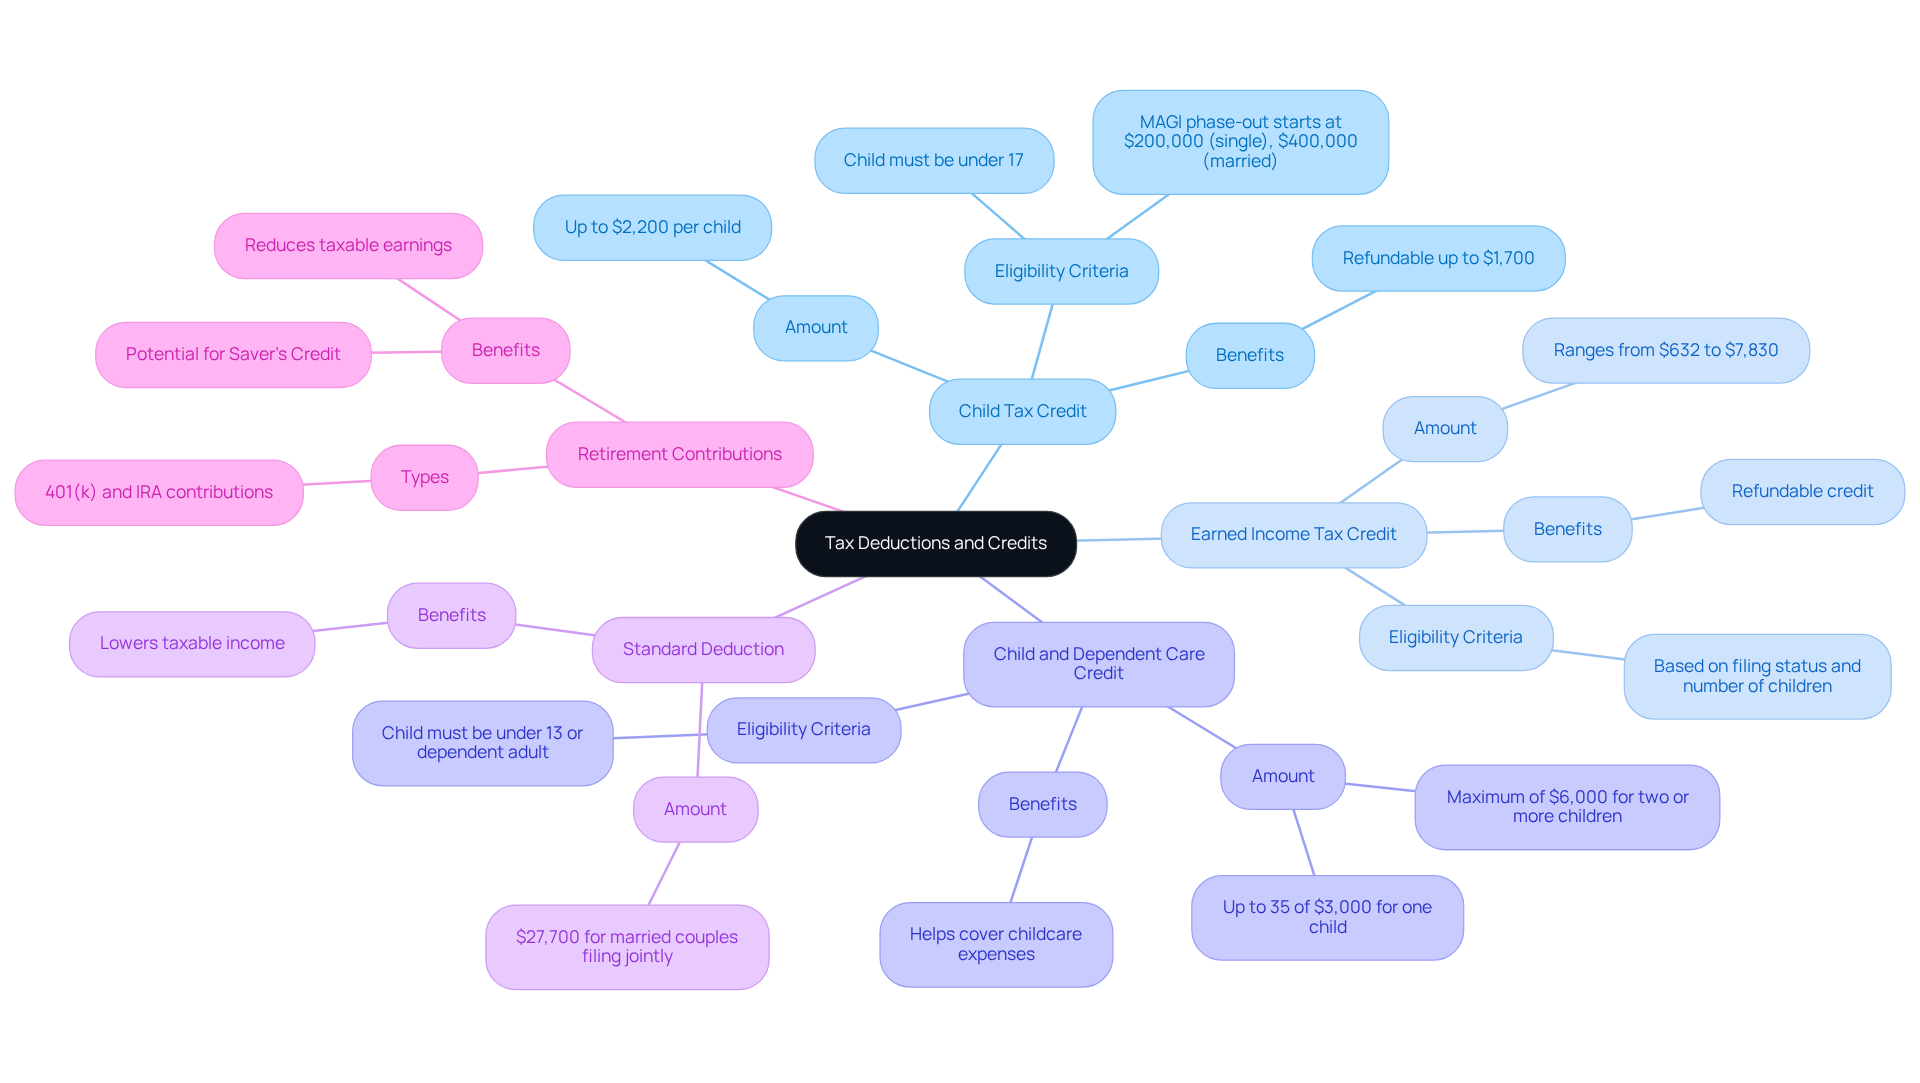
- Child Tax Credit: Imagine being able to claim up to $2,200 for each qualifying child under 17 in 2025. This credit starts to at a modified adjusted gross income (MAGI) of $200,000 for single filers and $400,000 for married couples. At $55,000, you should fully qualify for the 55k tax bracket, which can make a real difference.
- Earned Income Tax Credit (EITC): Depending on your filing status and the number of children you have, you might qualify for this refundable credit. It can provide significant savings, helping families like yours receive refunds that truly enhance your financial situation.
- Child and Dependent Care Credit: If you’re incurring childcare expenses while working or searching for a job, you can claim a percentage of those costs. This can ease your financial burden, allowing you to focus on what matters most.
- Standard Deduction: For 2025, the standard deduction for married couples filing jointly is $27,700. This can significantly lower your taxable amount, giving you more breathing room.
- Retirement Contributions: Contributions to a 401(k) or IRA can reduce your taxable earnings. Plus, if your earnings are below certain thresholds, you may qualify for the Saver’s Credit, helping you save for the future.
By utilizing these deductions and credits, you can effectively lower your taxable earnings and increase your potential refund. Keeping thorough records of your expenses is vital, and consulting with a tax professional can further enhance your tax strategy. Remember, we’re here for you, and together, we can navigate this journey.
Implement Tax Optimization Strategies
Managing your tax liability doesn’t have to feel overwhelming. With a few thoughtful strategies, you can take control of your , just like Allison and Brian did with the help of Bright Advisers. Here’s how you can start:
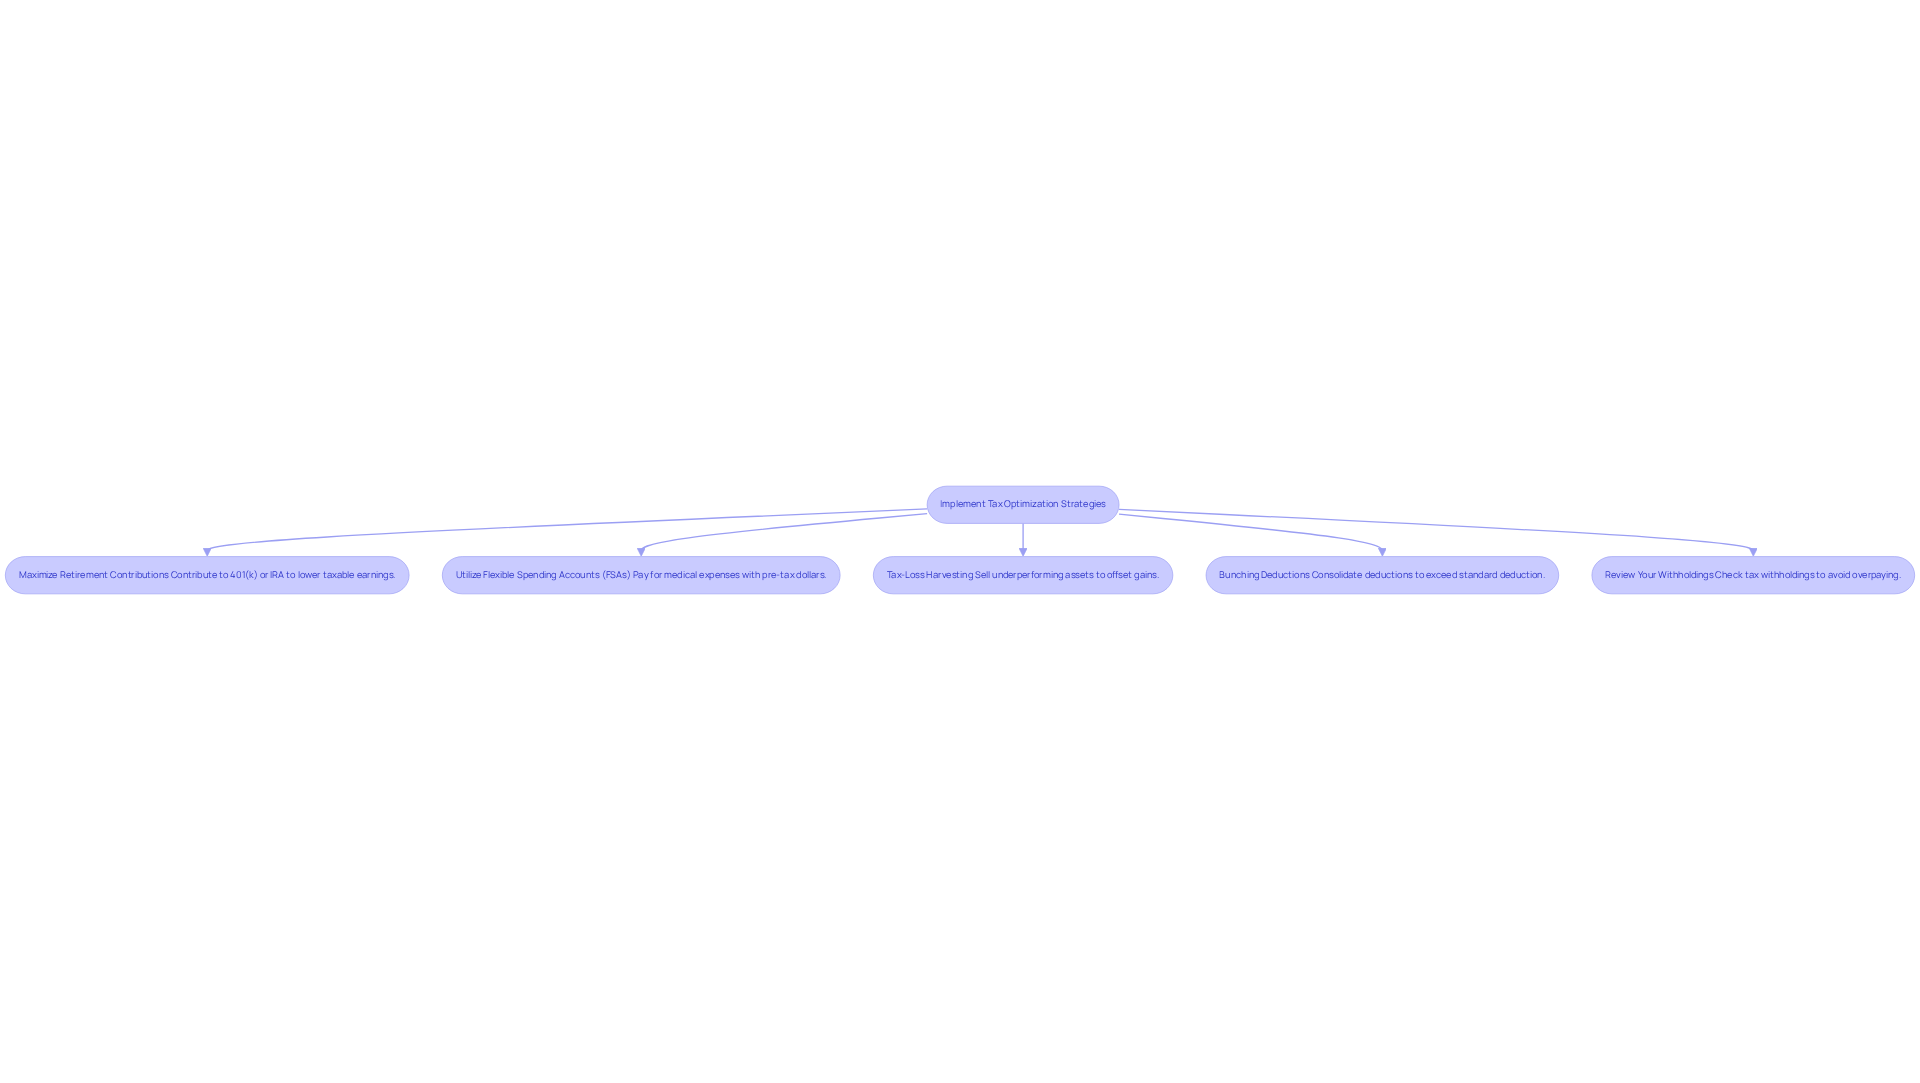
- Maximize Retirement Contributions: Think about contributing to tax-advantaged accounts like a 401(k) or IRA. By doing so, you can significantly lower your taxable earnings. Aim to contribute the maximum allowed-up to $23,500 for individuals under 50 in 2025. This not only helps with tax deferral but also boosts your retirement savings. Many employers offer matching contributions, with a median match of 4.0% of salary. Allison and Brian made the most of their retirement contributions, which was a key part of their financial planning.
- Utilize Flexible Spending Accounts (FSAs): If your employer provides an FSA, don’t miss out! It allows you to pay for eligible medical expenses with pre-tax dollars, which can lower your taxable income. This means you can allocate more resources toward your family’s financial goals. Many families leave FSAs underutilized, missing out on potential savings. As Jake Spiegel from EBRI notes, “Pretax contributions to FSAs help workers stretch their dollars further, allowing them to focus on other needs like emergency savings or retirement.” Allison and Brian took advantage of their FSA, enhancing their financial flexibility.
- Tax-Loss Harvesting: If you have investments in taxable accounts, consider selling underperforming assets to offset gains. This strategy can effectively reduce your overall tax liability, allowing you to keep more of your investment returns. Bright Advisers guided Allison and Brian in this approach, which played a significant role in their financial optimization.
- Bunching Deductions: If you itemize deductions, think about bunching them into one year to exceed the standard deduction threshold. This could mean consolidating charitable contributions or medical expenses, maximizing your tax benefits in a single year. This method was part of the comprehensive planning that helped Allison and Brian secure their financial future.
- Review Your Withholdings: Regularly check your tax withholdings to ensure you’re not overpaying throughout the year. This proactive approach can help you keep more of your earnings until tax time, giving you greater financial flexibility. By working with Bright Advisers, Allison and Brian fine-tuned their withholdings, enhancing their overall financial strategy.
By actively engaging in these strategies, you can optimize your tax situation and keep more of your hard-earned income, just like Allison and Brian did with the support of Bright Advisers. Remember, we’re here for you-together, we can navigate this journey toward financial security.
Establish a Long-Term Tax Planning Approach
Secure Your Family’s Financial Future
Establishing a long-term tax planning approach is essential for your family’s economic well-being. Here are some key steps to consider:
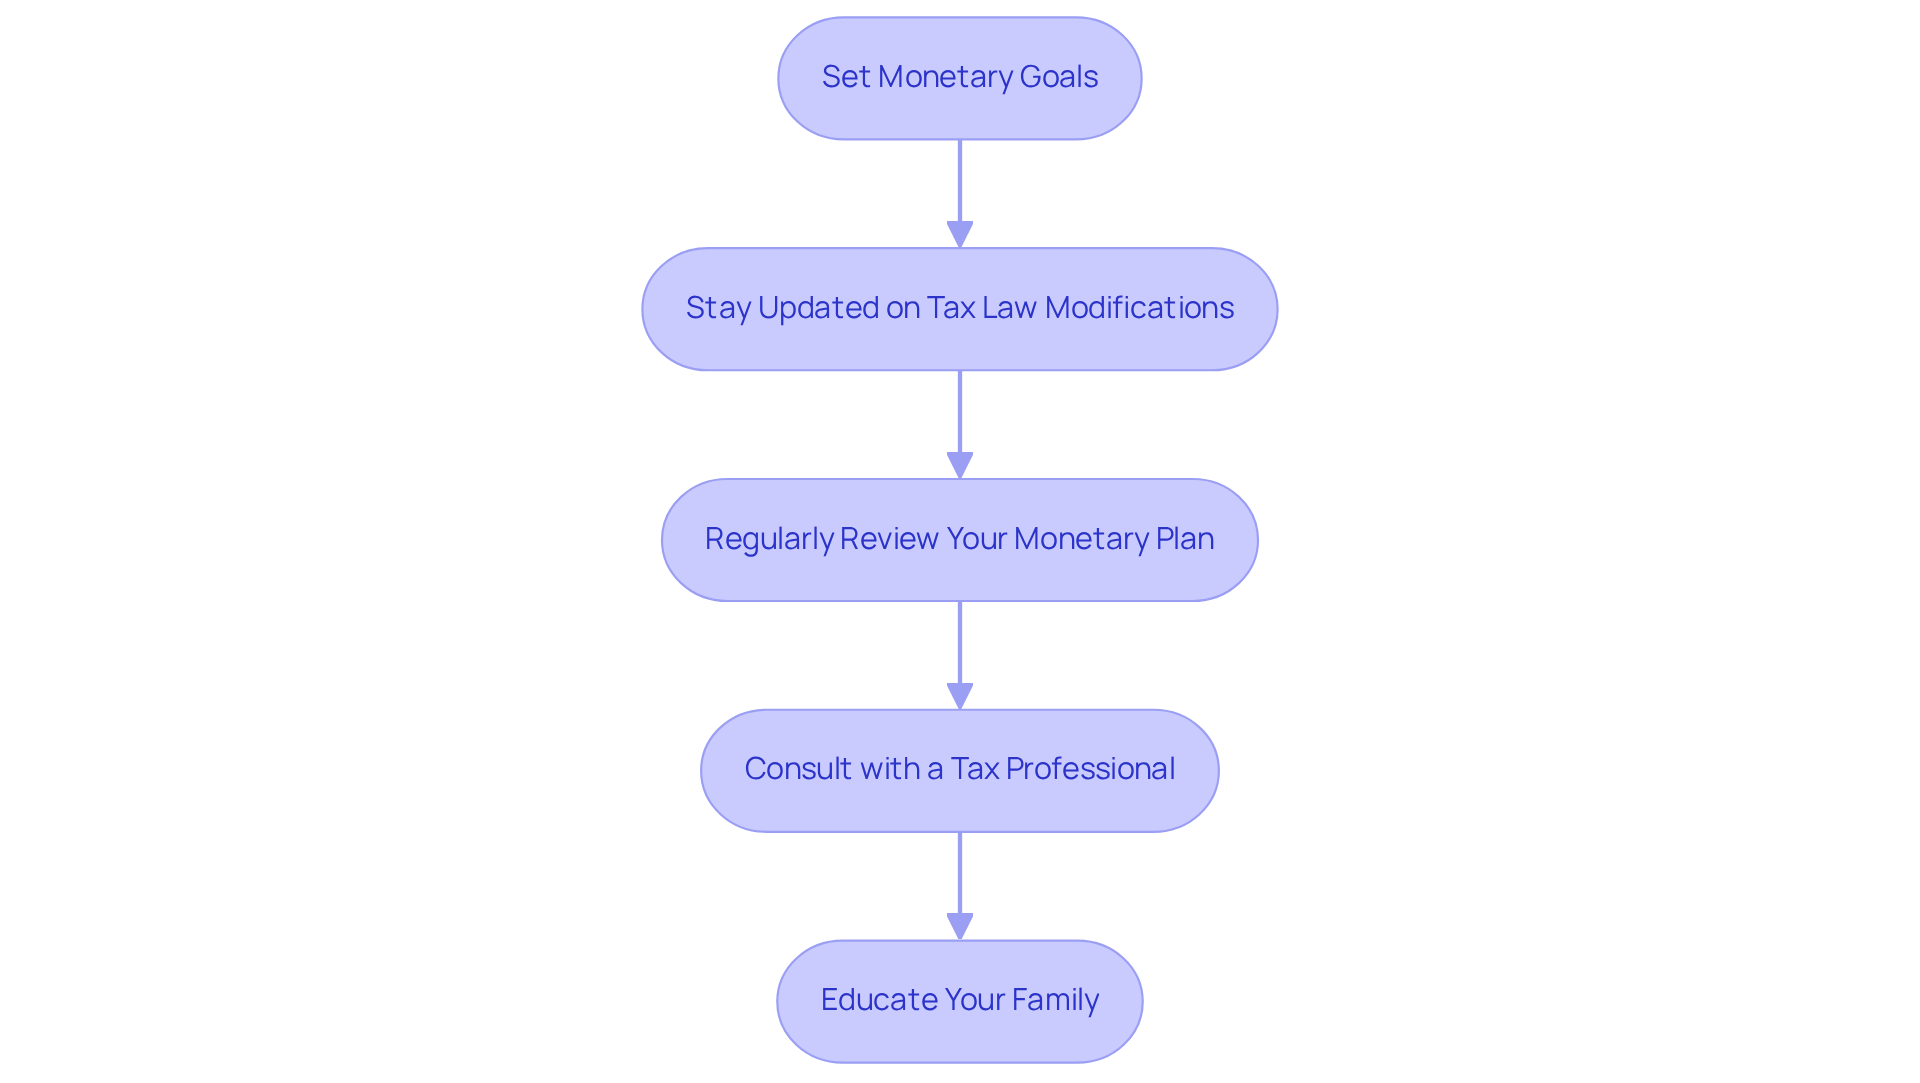
- Set Monetary Goals
Imagine defining both short-term and long-term monetary objectives, like saving for your children’s education, planning for retirement, or making major purchases. These goals will serve as a solid foundation for your tax planning efforts. For instance, did you know that households in the lowest income quantiles had a 0% average total federal tax rate in 2018? This shows how effective tax planning can truly benefit families across different income levels. At Bright Advisers, we’re here to help you develop a thorough strategy that aligns your values and vision with your goals. - Stay Updated on Tax Law Modifications
It’s important to understand that tax regulations change regularly, and these changes can significantly impact your family’s finances. Stay informed about new laws that may affect available credits or deductions. For example, the Child Tax Credit currently leaves 17 million children without complete benefits due to low household earnings. Bright Advisers provides insights into these changes, ensuring your tax strategy remains effective and beneficial for your family. - Regularly Review Your Monetary Plan
Conducting annual assessments of your monetary and tax strategies is crucial. This helps ensure they stay aligned with your evolving circumstances and goals. You might need to make adjustments due to changes in income or household dynamics. Remember, tax provisions are set to expire at the end of 2025 unless extended, highlighting the urgency for families to adapt their strategies. At Bright Advisers, we emphasize the significance of continuous evaluation to enhance your economic well-being. - Consult with a Tax Professional
Engaging a tax advisor who understands your household’s unique economic landscape can be incredibly beneficial. They can provide tailored strategies and insights that align with your financial objectives, helping you navigate complexities like the impact of the Tax Cuts and Jobs Act on your tax responsibilities. Bright Advisers focuses on customized tax planning strategies that empower families to optimize their economic potential. - Educate Your Family
Involve your children in discussions about finances and taxes. Teaching them about money management from a young age can set them up for future success, fostering a culture of informed decision-making within your household. Bright Advisers encourages families to establish a legacy of economic understanding that promotes long-term stability.
By adopting a proactive approach to tax planning, families can effectively navigate the complexities of the tax system and work towards achieving their financial aspirations. Together, we can navigate this journey and ensure a brighter future for your family.
Conclusion
Mastering the 55k tax bracket isn’t just about knowing tax rates; it’s about empowering young families to take charge of their financial futures. Imagine understanding how the tax bracket works and using available deductions and credits to navigate your tax obligations with confidence and clarity. This foundational knowledge equips families to make informed decisions that can positively impact their financial well-being.
Throughout this article, we’ve explored various strategies, from identifying key tax deductions like the Child Tax Credit and the Earned Income Tax Credit to implementing effective tax optimization techniques such as maximizing retirement contributions and utilizing flexible spending accounts. Each of these insights illustrates how proactive tax planning can significantly reduce tax liability and enhance financial security for families earning around $55,000.
Ultimately, establishing a long-term tax planning approach is essential for securing a prosperous future. By setting clear financial goals, staying informed about tax law changes, and consulting with professionals, families can create a roadmap that aligns with their unique circumstances. Engaging in this journey not only fosters financial stability but also instills a culture of informed decision-making that can benefit future generations.
Together, we can embrace the tools and strategies outlined here to ensure a brighter financial outlook for your family.
Frequently Asked Questions
What is the 55k tax bracket?
The 55k tax bracket refers to the federal taxation system where individuals with a taxable income of $55,000 fall under a progressive tax structure, meaning different portions of their income are taxed at varying rates.
What are the tax rates for the 55k tax bracket?
The tax rates for the 55k tax bracket are as follows:
- 10% on the first $11,925
- 12% on income from $11,926 to $48,475
- 22% on income from $48,476 to $55,000
How is the total tax liability calculated for someone earning $55,000?
To calculate the total tax liability for someone earning $55,000, you would apply the following:
- 10% of $11,925 = $1,192.50
- 12% of $36,550 (the amount between $11,926 and $48,475) = $4,386.00
- 22% of $6,525 (the amount between $48,476 and $55,000) = $1,436.50
When you add these amounts together, the total tax liability comes to about $7,015.
What is the effective tax rate for someone in the 55k tax bracket?
The effective tax rate for someone earning $55,000 is approximately 12.7%, calculated by dividing the total tax liability of $7,015 by the taxable income of $55,000.
Why is understanding the 55k tax bracket important for young families?
Understanding the 55k tax bracket is vital for young families as it helps them with effective tax planning and optimization strategies, allowing them to navigate their finances with confidence and make informed decisions for their future.
List of Sources
- Understand the 55k Tax Bracket Basics
- 2025 Federal Income Tax Brackets and Other 2025 Tax Rules (https://bipartisanpolicy.org/explainer/2025-federal-income-tax-brackets-and-other-2025-tax-rules)
- 2025 Tax Brackets (https://taxfoundation.org/data/all/federal/2025-tax-brackets)
- How Much Is Tax on $55,000 Salary? – eTax.com® (https://etax.com/resources/videos/how-much-is-tax-on–55000-salary)
- How Do Tax Brackets Work? (https://experian.com/blogs/ask-experian/how-do-tax-brackets-work)
- Identify Tax Deductions and Credits Available
- Top 10 Biggest Income Tax Credits and Deductions for 2025 (https://cpapracticeadvisor.com/2025/02/03/top-10-biggest-income-tax-credits-and-deductions-for-2025/155382)
- Child tax credit 2025: Child tax credit updates and payments (https://jacksonhewitt.com/tax-help/tax-tips-topics/family/child-tax-credit-2025)
- Child Tax Credit: How it works and who qualifies this year (https://hrblock.com/tax-center/filing/credits/child-tax-credit?srsltid=AfmBOopS-SOcqO9T5NSn6SlYwmtJdGGAYqrZFxTTwJo7AgqTdESnMqJU)
- Child Tax Credit | Internal Revenue Service (https://irs.gov/credits-deductions/individuals/child-tax-credit)
- Earned income and Earned Income Tax Credit (EITC) tables | Internal Revenue Service (https://irs.gov/credits-deductions/individuals/earned-income-tax-credit/earned-income-and-earned-income-tax-credit-eitc-tables)
- Implement Tax Optimization Strategies
- New Study Finds 401(k) Participants Hold 29% More in Retirement Savings Than Others (https://investopedia.com/new-study-finds-401-k-participants-hold-29-more-in-retirement-savings-than-others-11876603)
- 13 Quotes to Help Plan for Retirement | The Motley Fool (https://fool.com/retirement/2020/06/25/13-quotes-to-help-plan-for-retirement.aspx)
- 7 Quotes from Warren Buffett on How Retirees Should “Invest” in What Matters the Most (https://keenwealthadvisors.com/insights/7-quotes-from-warren-buffett-on-how-retirees-should-invest-in-what-matters-the-most)
- Average FSA contributions remain well below annual limit, report finds (https://fsastore.com/articles/learn-average-fsa-contributions-remain-well-below-annual-limit-report-finds.html?srsltid=AfmBOorpOxWAHWvCI1H7BM0hvprC8Pc4V7eEh-uIG2gAe5oBkxpWFiaT)
- New Analysis of 3.2 Million Flexible Spending Accounts Finds Average Contributions Increasing While Half Forfeiting Funds to Their Employers (https://ebri.org/content/new-analysis-of-3.2-million-flexible-spending-accounts-finds-average-contributions-increasing-while-half-forfeiting-funds-to-their-employers)
- Establish a Long-Term Tax Planning Approach
- How Do Tax Policies Affect Individuals and Businesses? (https://siepr.stanford.edu/publications/policy-brief/how-do-tax-policies-affect-individuals-and-businesses)
- oneupnetworks.com (https://oneupnetworks.com/post/best-100-motivational-finance-quotes)
- By the Numbers: House Republican Tax Agenda Favors the Wealthy and Leaves Millions of Working Families Behind (https://cbpp.org/research/federal-tax/by-the-numbers-house-republican-tax-agenda-favors-the-wealthy-and-leaves)
- How has TCJA impacted individual income taxes? | USAFacts (https://usafacts.org/articles/how-has-tcja-impacted-individual-income-taxes)
- The One Big Beautiful Bill Cuts Taxes Across the US, New Analysis Finds (https://taxfoundation.org/data/all/federal/obbba-average-tax-cuts-impact-map)

Kevin has advised high-income W-2 tech and biotech families since 2015, and leads the education-first Age Five Family Office from Brea, California.
Connect on LinkedIn → · About KevinThis is part of how we approach Tax Management for high-income W-2 families at Bright Advisers.
Keep reading