

Overview
The Rule of 55 is a valuable opportunity for individuals who leave their job during or after the year they turn 55. It allows them to withdraw funds from their 401(k) or 403(b) plans without facing a 10% early withdrawal penalty. This provision offers crucial financial access before reaching the age of 59½, which can be especially comforting during transitional life stages.
Imagine if you could access your retirement savings when you need them most. This article outlines the eligibility requirements and the withdrawal process, ensuring you understand how to navigate this option. The benefits are significant, providing financial flexibility that aligns with your family’s needs.
However, it’s important to recognize the associated risks. Informed decision-making is key. We encourage you to consult with a financial advisor who can guide you through this process, ensuring you make choices that support your family’s future.
Together, we can navigate this journey, empowering you to make the most of your financial resources. Remember, you’re not alone in this—support and assistance are available to help you every step of the way.
Key Highlights:
- The Rule of 55 allows individuals who leave their job during or after the year they turn 55 to withdraw from their 401(k) or 403(b) without a 10% early withdrawal penalty.
- This rule provides financial access to savings before age 59½, which can be crucial during unexpected job loss or early retirement.
- Public safety employees can access their funds as early as age 50 under the Rule of 55, enhancing their financial flexibility.
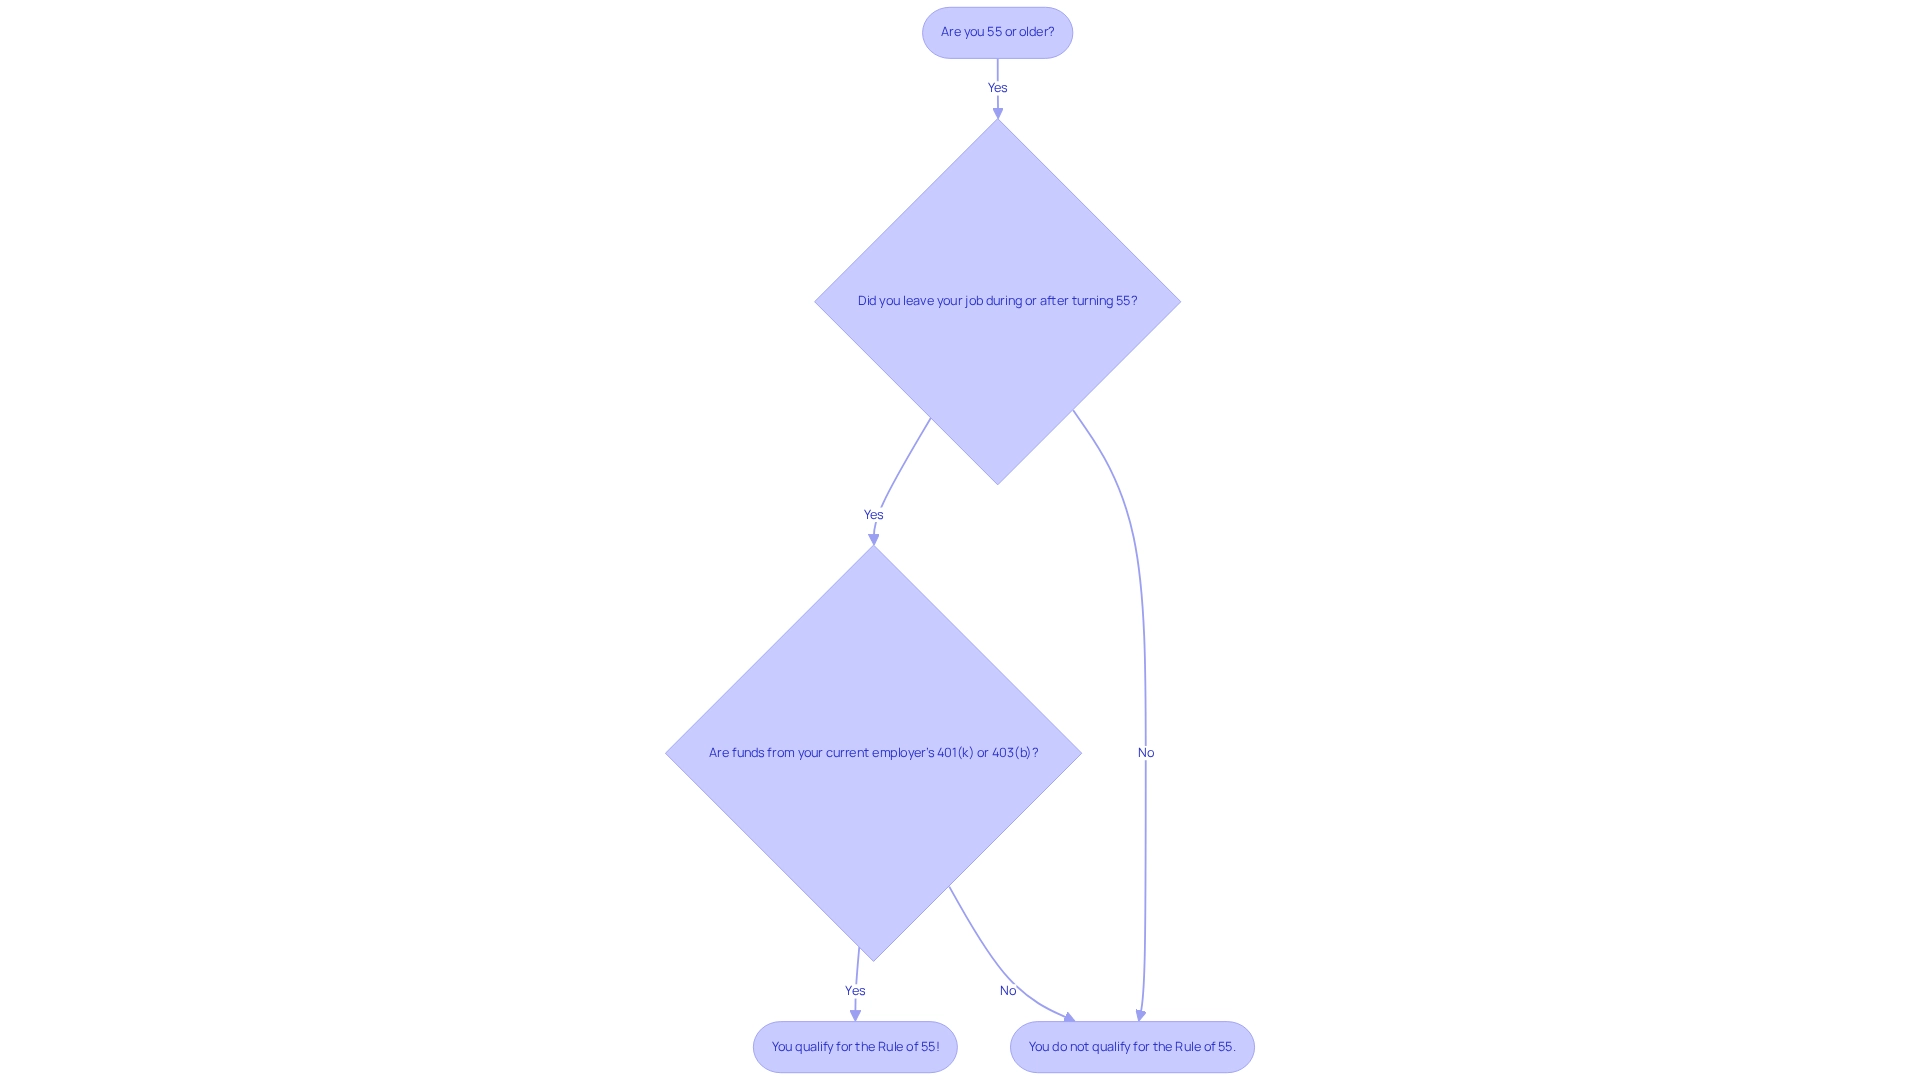
- To qualify for the Rule of 55, individuals must have left their job in the year they turn 55 or later, and the funds must come from their current employer’s retirement plan.
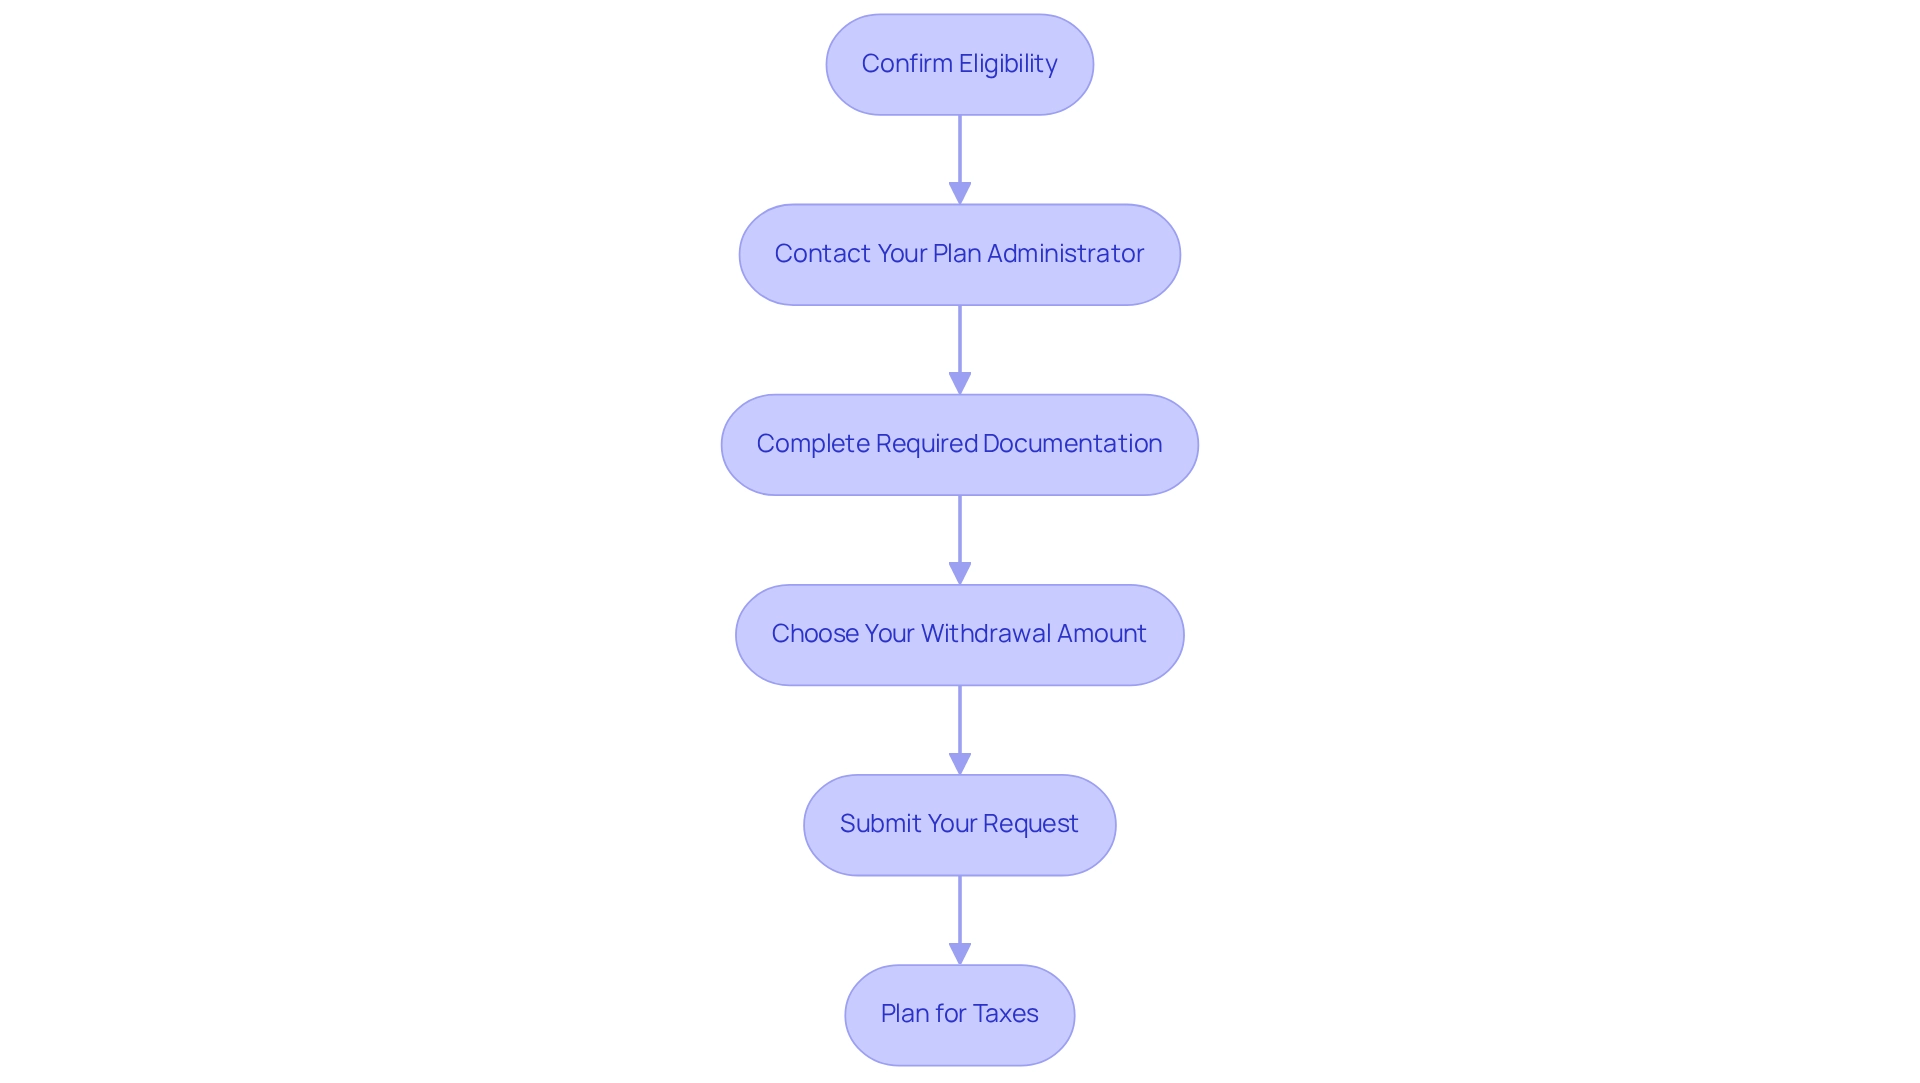
- The withdrawal process involves confirming eligibility, contacting the plan administrator, completing necessary documentation, choosing a withdrawal amount, and planning for taxes.
- Benefits of the Rule of 55 include penalty-free access to funds, financial flexibility, and support for retirement planning.
- Risks include potential depletion of retirement savings, tax implications on withdrawals, and loss of investment growth opportunities.
- Consulting a financial advisor is recommended to navigate the complexities of the Rule of 55 and ensure informed decisions.
Introduction
Navigating the complexities of retirement planning can feel overwhelming, especially as you approach the pivotal age of 55. Imagine a path that leads to financial flexibility: the Rule of 55. This provision shines as a beacon of hope, allowing early access to your 401(k) or 403(b) funds without the typical penalties. It offers a lifeline for those facing unexpected job changes or contemplating early retirement. It’s important to understand the eligibility criteria and potential tax implications involved.
As the trend of early withdrawals grows, weighing the benefits against the risks becomes essential. After all, your financial decisions should align with your long-term retirement goals. Together, we can explore the intricacies of the Rule of 55, focusing on its purpose, qualifications, withdrawal process, and the critical considerations that will empower you to make informed choices for your family’s financial future. We’re here for you, guiding you every step of the way.
Define the Rule of 55 and Its Purpose
The provision of the 55 rule 401k is an IRS guideline that can bring relief to individuals who exit their job during or after the year they turn 55. It allows them to withdraw funds from their 401(k) or 403(b) plans under the 55 rule 401k without incurring the usual 10% penalty for early distribution. For many, this rule is a lifeline, providing access to savings before reaching 59½—a crucial time when unexpected job loss or early retirement can create financial strain.
Imagine if you found yourself needing to access your hard-earned savings during a challenging time. Current statistics reveal that many individuals are taking advantage of the 55 rule 401k for early withdrawals, highlighting a growing trend among those who wish to manage their finances proactively. Experts point out that the 55 rule 401k can help prevent the situation of being ‘401(k)-rich but cash-poor,’ where significant savings remain untapped when urgent cash is needed. Additionally, it’s worth noting that withdrawals from Roth contributions in a 401(k) are generally tax-exempt, offering even more options for those contemplating their withdrawal strategies.
For public safety personnel, such as police officers and firefighters, the 55 rule 401k provision is even more accessible; they can utilize it in the calendar year they turn 50, allowing them earlier access to their 401(k) funds. This unique aspect provides these dedicated professionals with additional financial choices as they approach retirement, showcasing the rule’s flexibility across various careers.
The case study titled ‘Special Considerations for Public Safety Employees’ illustrates how this provision can be particularly beneficial for those in these vital roles. Overall, the 55 rule 401k serves as an essential resource for individuals navigating their savings for later life, especially when faced with financial challenges. Remember, we’re here for you, and together, we can navigate this journey toward financial security.
Identify Qualifications for the Rule of 55
Are you approaching 55 and wondering about your retirement options? Understanding the guidelines surrounding the 55 rule 401k can be crucial for your financial well-being. To qualify, there are a few important criteria to keep in mind:
- You must have left your job, whether by choice or not, during or after the year you turned 55.
- The funds you wish to withdraw need to come from your current employer’s 401(k) or 403(b) plan; this doesn’t apply to IRAs or funds from past employers.
- If you’ve transferred your 401(k) funds into another savings account, you won’t be able to use the 55 rule 401k for those funds.
It’s essential to understand these qualifications to access your savings for the future without incurring penalties. Recent statistics reveal that many employees aged 55 and older are leaving their jobs, making the 55 rule 401k increasingly relevant as it allows them to tap into their savings without the usual restrictions. As financial expert Sam Swenson, CFA, CPA, CFP, notes, “The reasoning for this exception is to acknowledge the physically demanding characteristics of their roles and the earlier age often linked to their professions.”
Seeking guidance from a financial specialist can provide clarity on these eligibility requirements and help navigate the complexities of early job exits.
Together, we can explore how experts can assist you with 401(k) rollovers, simplifying your financial planning and ensuring you make informed decisions for your family’s future. Before you take advantage of the 55 rule 401k, it’s important to confirm that your employer allows early access and to understand the specific regulations governing your retirement plan. Remember, we’re here for you, ready to help you navigate this journey toward financial security.
Implement Steps to Withdraw from 401(k) Using the Rule of 55
Withdrawing from your 401(k) through the 55 rule can feel daunting, but we’re here to help you through it. Let’s take a closer look at the steps you need to follow:
-
Confirm Eligibility: First, it’s important to verify that you qualify for the Rule of 55. The 55 rule permits penalty-free distributions if you leave your job in the year you turn 55 or later. Understanding this can ease some of your concerns.
-
Contact Your Plan Administrator: Next, reach out to your 401(k) plan administrator. Let them know your intention to withdraw funds under this rule. They will provide you with specific instructions and the necessary forms tailored to your plan, ensuring you feel supported every step of the way.
-
Complete Required Documentation: Take the time to fill out any required forms. Typically, this includes a request form along with proof of your age and employment status. It may seem like a lot, but completing this documentation is a crucial part of the process.
-
Choose Your Withdrawal Amount: Now, decide how much you wish to withdraw. Remember, you can access any amount up to your vested balance. For context, the mean 401(k) balance at Fidelity in the third quarter of 2024 was $132,300. This information can help you assess standard disbursement amounts, aligning with your family’s financial needs.
-
Submit Your Request: Once you’ve completed your forms, send them to your plan administrator. They will process your request and inform you of the expected timeline for receiving your funds. Keep in mind that processing times can vary, so it’s wise to ask about this during your initial contact.
-
Plan for Taxes: Although you won’t face the 10% penalty for early withdrawal, it’s important to remember that you will still owe income tax on the amount taken out. Consulting a tax expert can help you fully understand the tax implications of your disbursement. Additionally, be aware that your plan provider may withhold 20% on taxable distributions, which could impact your overall financial planning.
As Lowell pointed out, retiring before 62 means you won’t receive Social Security income. This emphasizes the importance of understanding the long-term financial effects of withdrawing early. If you’re considering a Roth IRA conversion, please note that funds moved to a Roth IRA become ineligible for the 55 provision, which could affect your access to penalty-free distributions.
Together, we can navigate this journey and ensure that your financial decisions align with your family’s values and future goals.
Evaluate Benefits and Risks of the Rule of 55
The 55 rule 401k provides several benefits for individuals considering early access to their 401(k):
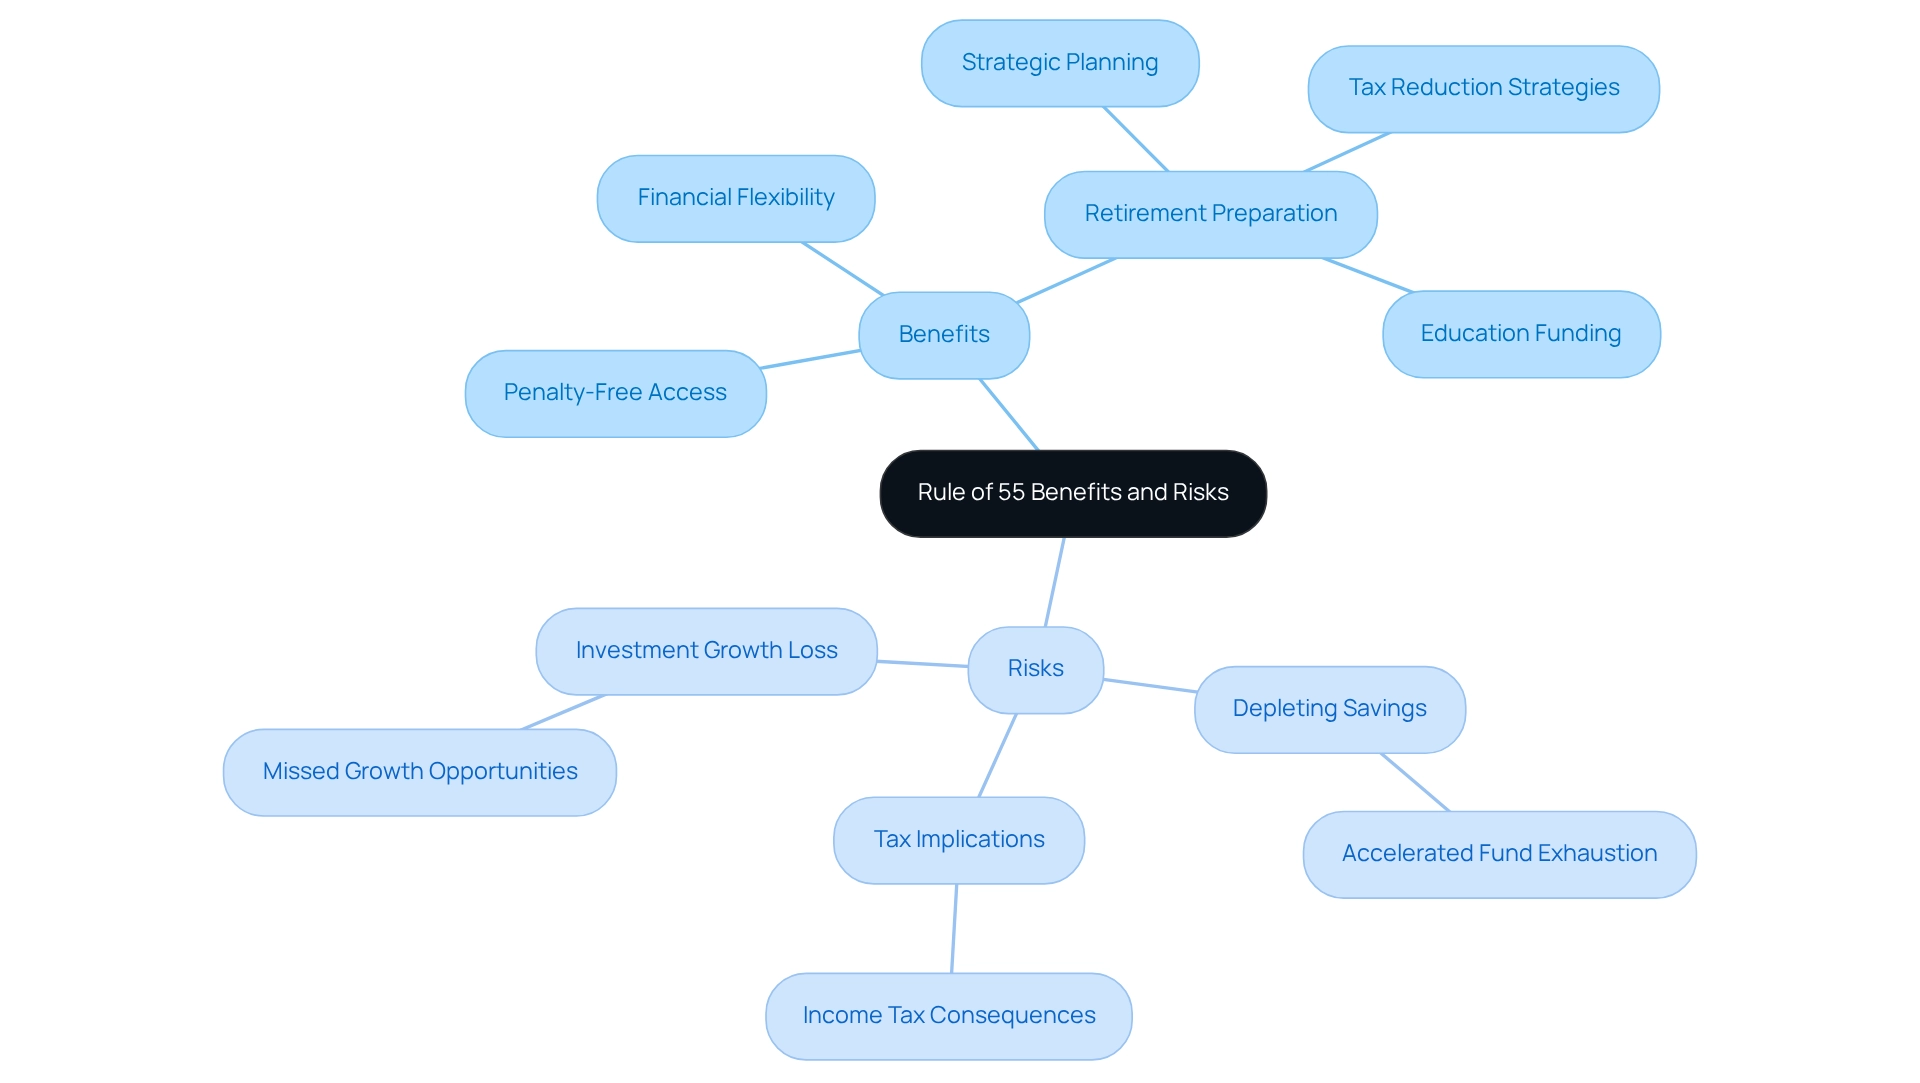
- Penalty-Free Access: This regulation allows individuals to access their pension funds without incurring the 10% withdrawal fee, potentially saving a significant amount of money.
- Financial Flexibility: It provides a financial cushion for those who may need to retire early or face unexpected expenses, acting as a safety net during transitional times.
- Retirement Preparation: The Rule of 55 supports strategic planning around income in later years, particularly for individuals without alternative income sources. This is especially relevant for families like Allison and Brian, who, through their partnership with Bright Advisers, discovered ways to improve their financial situation, achieving a 20% reduction in their tax obligations while ensuring their children’s education funding and preparing for a timely exit from the workforce.
However, it’s crucial to consider the associated risks:
- Depleting Savings for the Future: Early withdrawals can significantly reduce your nest egg, jeopardizing long-term financial security. Statistics indicate that individuals who withdraw early often see their savings diminish at an accelerated rate, with studies showing that early withdrawers can exhaust their funds up to 30% faster than those who do not.
- Tax Implications: Withdrawals are subject to income tax, which can greatly lower the net amount received. Understanding the tax consequences is vital for effective financial planning. This lesson was one that families like Allison and Brian learned as they navigated the complexities of tax planning with Bright Advisers.
- Investment Growth Loss: By withdrawing funds prematurely, individuals miss out on potential investment growth, which can negatively impact their overall retirement strategy. Evaluating these benefits and risks is essential for making informed decisions about utilizing the 55 rule 401k. Financial advisors stress the importance of considering alternatives, such as setting up a payment plan or exploring government benefits, before committing to early withdrawals. Real-world examples illustrate the potential pitfalls of relying solely on this rule, highlighting the need for a comprehensive approach to retirement planning. Additionally, case studies like that of Bright Advisers show how families can navigate financial planning effectively, demonstrating the practical implications of the Rule of 55. Together, we can navigate this journey toward a secure financial future.
Conclusion
Understanding the Rule of 55 is crucial for those approaching retirement, especially if you’re facing unexpected job changes or considering early retirement. This IRS provision allows you to access your 401(k) and 403(b) funds without penalties if you leave your job during or after the year you turn 55. By meeting specific qualifications, you can navigate financial challenges with greater flexibility, ensuring that your retirement savings are accessible when you need them most.
However, while the Rule of 55 offers significant benefits, such as financial flexibility and avoiding early withdrawal penalties, it’s essential to weigh these advantages against potential risks. Early withdrawals can lead to diminished retirement savings and tax implications that may affect your long-term financial health. Engaging with financial experts can provide valuable insights, helping you make informed decisions that align with your overall retirement strategy.
Ultimately, the Rule of 55 serves as a vital tool for navigating the complexities of retirement planning. By understanding its provisions, qualifications, and the implications of early withdrawals, you can take proactive steps toward securing your financial future. Careful consideration and strategic planning will empower you to utilize this rule effectively, ensuring that you achieve your retirement goals while safeguarding your financial well-being. Remember, we’re here for you, and together, we can navigate this journey.
Frequently Asked Questions
What is the 55 rule 401k?
The 55 rule 401k is an IRS guideline that allows individuals who exit their job during or after the year they turn 55 to withdraw funds from their 401(k) or 403(b) plans without incurring the usual 10% penalty for early distribution.
Who can benefit from the 55 rule 401k?
Individuals who leave their job during or after the year they turn 55 can benefit from this rule. Additionally, public safety personnel, such as police officers and firefighters, can access their 401(k) funds in the calendar year they turn 50.
Why is the 55 rule 401k important?
The 55 rule 401k is important because it provides access to savings before reaching age 59½, which can be crucial during times of unexpected job loss or early retirement. It helps prevent individuals from being ‘401(k)-rich but cash-poor.’
Are there any tax benefits associated with the 55 rule 401k?
Yes, withdrawals from Roth contributions in a 401(k) are generally tax-exempt, offering additional options for those considering their withdrawal strategies.
How does the 55 rule 401k help public safety personnel specifically?
Public safety personnel can utilize the 55 rule 401k provision in the calendar year they turn 50, allowing them earlier access to their 401(k) funds, which provides them with additional financial choices as they approach retirement.
What is the significance of the case study ‘Special Considerations for Public Safety Employees’?
The case study illustrates how the 55 rule 401k provision can be particularly beneficial for public safety employees, showcasing the flexibility of the rule across various careers.
How can individuals navigate their savings using the 55 rule 401k?
The 55 rule 401k serves as an essential resource for individuals navigating their savings for later life, especially when faced with financial challenges, providing them with options to access their funds when needed.
List of Sources
- Define the Rule of 55 and Its Purpose
- When Can You Withdraw? 401(k)s and the Rule of 55 (https://schwab.com/learn/story/retiring-early-5-key-points-about-rule-55)
- The Rule of 55: One Way to Fund Early Retirement (https://kiplinger.com/retirement/the-rule-of-55-one-way-to-fund-early-retirement)
- More Americans tapping 401(k)s to pay for financial emergencies (https://newsnationnow.com/business/your-money/americans-tapping-401ks-emergencies)
- Identify Qualifications for the Rule of 55
- Using the Rule of 55 to Take Early 401(k) Withdraws (https://visionretirement.com/articles/employee-benefits/rule-of-55)
- How to Use the Rule of 55 to Take Early 401(k) Withdrawals – Capitalize (https://hicapitalize.com/resources/rule-of-55-401k)
- When Can You Withdraw? 401(k)s and the Rule of 55 (https://schwab.com/learn/story/retiring-early-5-key-points-about-rule-55)
- Implement Steps to Withdraw from 401(k) Using the Rule of 55
- Understanding the rule of 55: A comprehensive guide to early retirement (https://businessinsider.com/personal-finance/investing/rule-of-55-401k-early-withdrawal)
- Retirement Account Statistics 2024 – NerdWallet (https://nerdwallet.com/article/investing/retirement-statistics)
- When Can You Withdraw? 401(k)s and the Rule of 55 (https://schwab.com/learn/story/retiring-early-5-key-points-about-rule-55)
- smartasset.com (https://smartasset.com/retirement/401k-55-rule)
- How To Retire Early With The Rule Of 55 (https://nasdaq.com/articles/how-retire-early-rule-55)
- Evaluate Benefits and Risks of the Rule of 55
- Consequences of Withdrawing Early From Your 401(k) (https://igrad.com/articles/consequences-of-withdrawing-early-from-your-401k)
- 35 Quotes for Financial Advisors on a Tough Day | Don Connelly & Associates (https://donconnelly.com/35-quotes-for-financial-advisors)
- Average 401k Balance by Age: Rising Above Retirement Stats (https://quiverfinancial.com/blog/average-401k-balance-by-age-rising-above-retirement-stats)
- 77 Financial Advisor Quotes to Send to Clients (https://billgoodmarketing.com/resources/financial-advisor-quotes)

Kevin has advised high-income W-2 tech and biotech families since 2015, and leads the education-first Age Five Family Office from Brea, California.
Connect on LinkedIn → · About KevinThis is part of how we approach Retirement & Employee Benefits for high-income W-2 families at Bright Advisers.
Keep reading