

Overview
The 55 Year Rule offers a compassionate lifeline for individuals aged 55 and older, allowing them to make penalty-free withdrawals from their 401(k) or 403(b) plans after leaving their job. This provision provides essential access to retirement savings, especially during the early stages of retirement when financial flexibility is crucial.
Imagine having the ability to tap into your retirement funds without the burden of penalties. This article outlines the eligibility criteria and key steps to access these funds, while also discussing the pros and cons of this option. It’s important to understand that while the rule offers immediate cash flow and strategic planning benefits, individuals must also weigh the tax implications and the potential impact on their long-term retirement savings.
Together, we can navigate this journey, ensuring that your financial decisions align with your family’s values and goals. We’re here to support you in making informed choices that will benefit you and your loved ones in the years to come.
Key Highlights:
- The Rule of 55 permits penalty-free withdrawals from 401(k) or 403(b) plans for individuals who leave their job during or after the year they turn 55.
- This provision is beneficial for those needing early access to retirement savings due to job loss or voluntary retirement.
- Eligibility requires individuals to be at least 55 years old, separated from their employer, and withdrawing from their current employer’s plan.
- Key steps for executing withdrawals include contacting the plan administrator, completing required forms, specifying the withdrawal amount, and submitting the request.
- Pros of the Rule of 55 include penalty-free access to savings, instant cash flow for urgent needs, and enhanced retirement planning.
- Cons include tax implications on withdrawals, potential depletion of retirement savings, and limitations to current employer’s plans.
- Expert advice emphasizes the importance of understanding tax implications and reviewing all accounts before making withdrawals.
Introduction
In a world where financial security is paramount, understanding the intricacies of retirement planning becomes essential, especially as individuals approach the age of 55. Imagine the relief of knowing there’s a way to access your hard-earned retirement savings without facing penalties.
The Rule of 55 shines as a beacon of hope for those seeking early access to their funds. This IRS provision allows individuals who leave their jobs during or after their 55th birthday to withdraw funds from their 401(k) or 403(b) plans.
It’s important to understand that this rule not only provides access but also opens the door to strategic financial planning. By exploring the benefits, eligibility criteria, and execution of withdrawals under this rule, individuals can navigate the complexities of their retirement landscape. Together, we can make informed decisions that align with your long-term goals.
With real-world examples and expert insights, this article delves into how the Rule of 55 can empower you to take control of your financial future during pivotal life transitions. We’re here for you, ready to support you on this journey.
Understand the Rule of 55 and Its Purpose
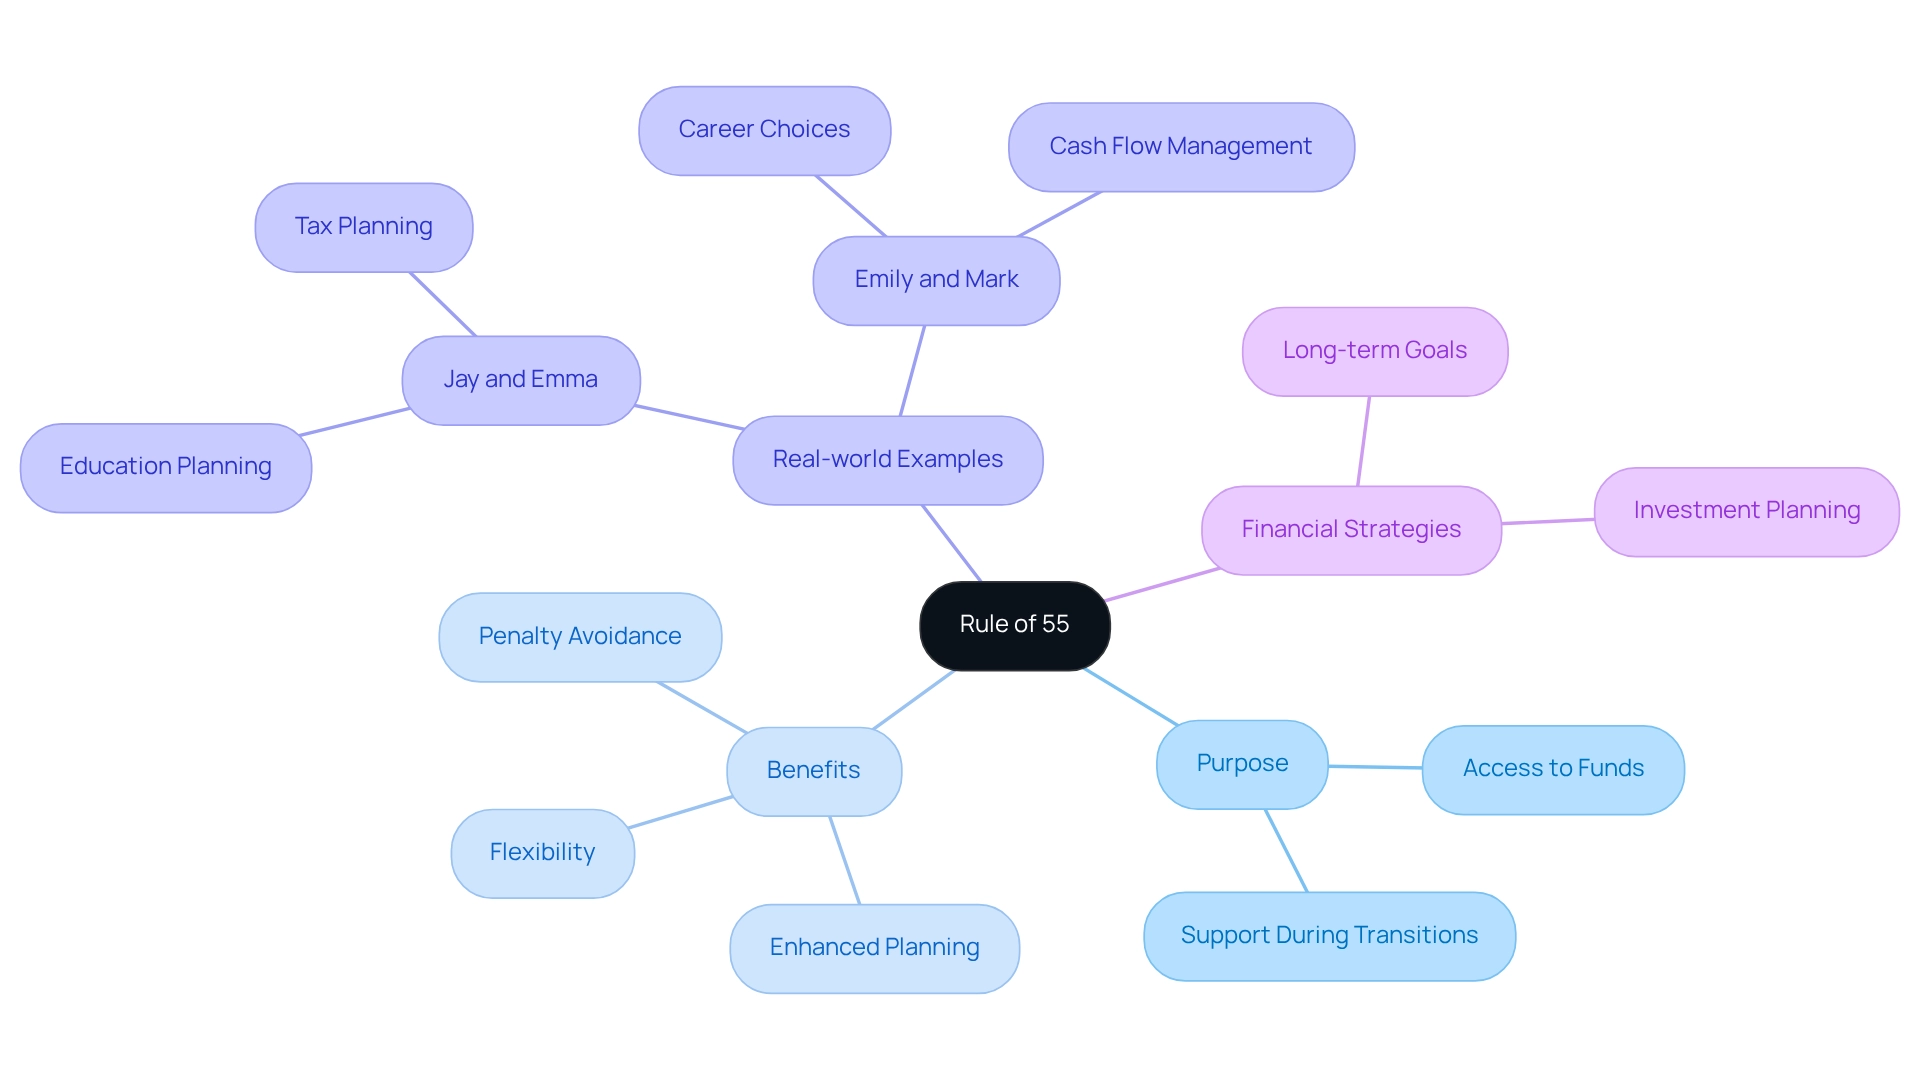
The 55 year rule 401k is an IRS provision that allows individuals who leave their job during or after the year they turn 55 to withdraw funds from their 401(k) or 403(b) plans without incurring the usual 10% early withdrawal penalty. This provision serves as a lifeline for those needing to access their savings earlier than anticipated, whether due to job loss or a voluntary decision to step back from the workforce. By utilizing this guideline, individuals can enhance their planning strategies, allowing for greater adaptability in managing their funds for later years.
Imagine being able to navigate your financial future with confidence. The advantages of the 55 regulation extend beyond merely evading penalties; it empowers individuals to make strategic choices regarding their savings, facilitating a smoother transition into later life. Take Jay and Emma, for example, a couple in their late 40s who sought advice from Bright Advisers to alleviate their financial concerns. By understanding the 55 year rule 401k, they effectively planned for their children’s education while preparing for their own future, striking a balance between current responsibilities and long-term aspirations. They improved their tax planning and explored education savings options, which became essential components of their financial strategy.
Real-world instances illustrate the practical application of the principle of 55. Many individuals have successfully leveraged the 55 year rule 401k to bridge the gap between work and the later stages of life, enabling them to maintain their lifestyle without incurring penalties. Consider Emily and Mark, a couple in their mid-30s, who collaborated with Bright Advisers to develop a comprehensive financial strategy that integrated the principle of 55. This allowed them to make informed choices regarding their careers and financial futures while managing their cash flow and investing wisely.
Moreover, recent data reveals that a significant portion of the workforce has engaged with their savings plans, with 14% of workers in the U.S. taking coronavirus-related distributions from their 401(k) plans in 2020. This underscores the importance of accessible withdrawal options during uncertain times, reinforcing the value of the 55 year rule 401k provision. Experts emphasize that this measure not only provides immediate access to funds but also encourages individuals to reflect on their long-term financial goals. By understanding and utilizing the 55 year rule 401k, individuals can better navigate their retirement landscape, ensuring they are prepared for both expected and unexpected life changes. Remember, we’re here for you—together, we can navigate this journey toward financial security.
Determine Eligibility for the Rule of 55
Navigating the complexities of retirement planning can feel overwhelming, especially for those approaching a new chapter in life. To qualify for the Rule of 55, there are specific criteria to keep in mind:
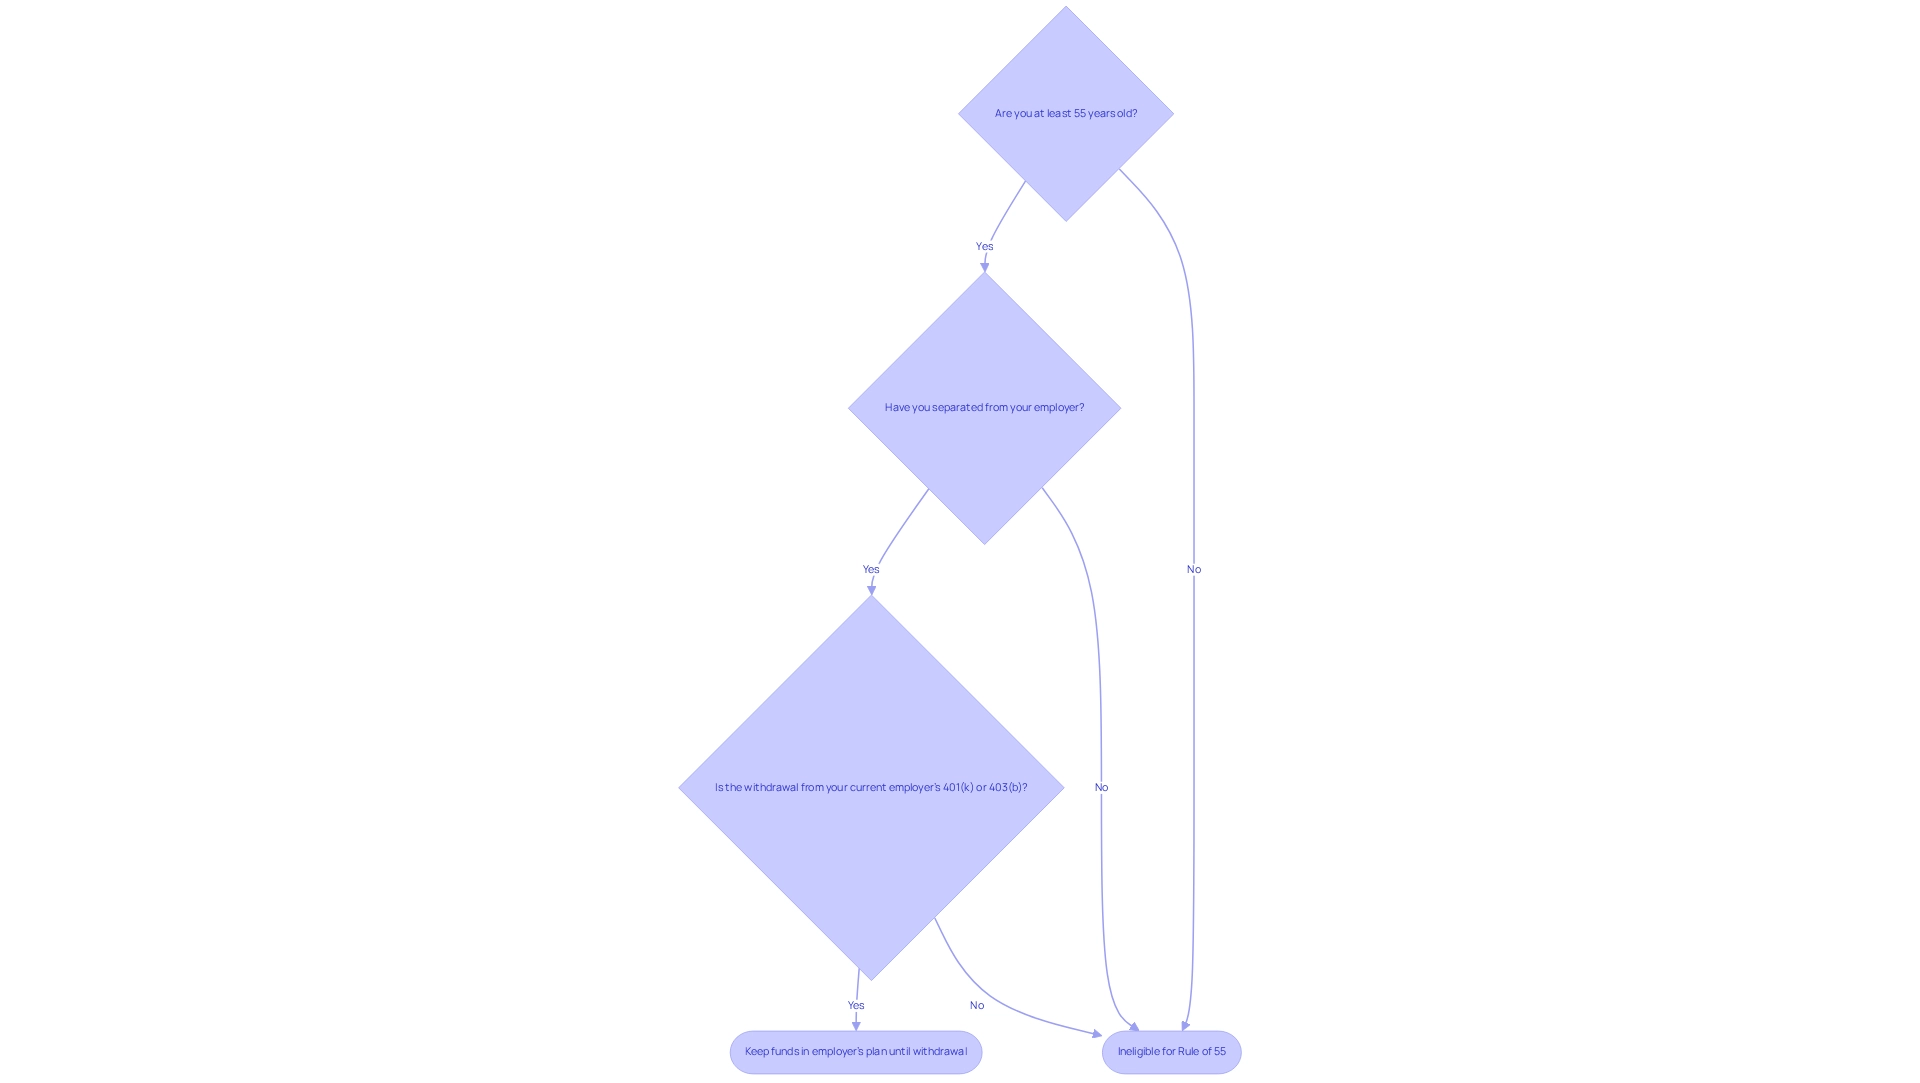
- To benefit from the 55 year rule 401k, you must be at least 55 years old in the year you leave your job.
- You must have separated from your employer, whether voluntarily or involuntarily.
- The funds you wish to withdraw should come from your current employer’s 401(k) or 403(b) plan; this rule does not cover plans from previous employers.
- It’s essential to keep those funds within the employer’s plan until you choose to withdraw them. Understanding the eligibility requirements of the 55 year rule 401k is vital before making any withdrawals.
Imagine if you were among the many employees aged 55 and above who are considering their next steps regarding the 55 year rule 401k. Recent statistics reveal a significant number of individuals in this age group are leaving their positions, underscoring the importance of being informed about post-employment options.
Expert advice highlights the necessity of reviewing all accounts and potential tax implications before making any decisions. As Roger Whitney, a certified advisor, wisely states, “Before you leave your job, make sure you examine all your accounts and assets and assess the potential tax implications.” This strategic planning can help manage your overall tax liability, particularly for Georgia residents, who may face unique tax factors that could impact their savings for the future.
Furthermore, insights from professionals like Jarad Stolz, a Chartered Retirement Planning Counselor, emphasize the importance of understanding these rules to secure a stable financial future. His expertise in retirement planning can offer invaluable guidance for families navigating these complexities, ensuring you feel well-prepared for your retirement years.
Together, we can navigate this journey, ensuring that you and your family are ready for what lies ahead.
Execute Withdrawals Using the Rule of 55
Navigating the 55 year rule 401k can feel overwhelming, but we’re here to guide you through each step with care.
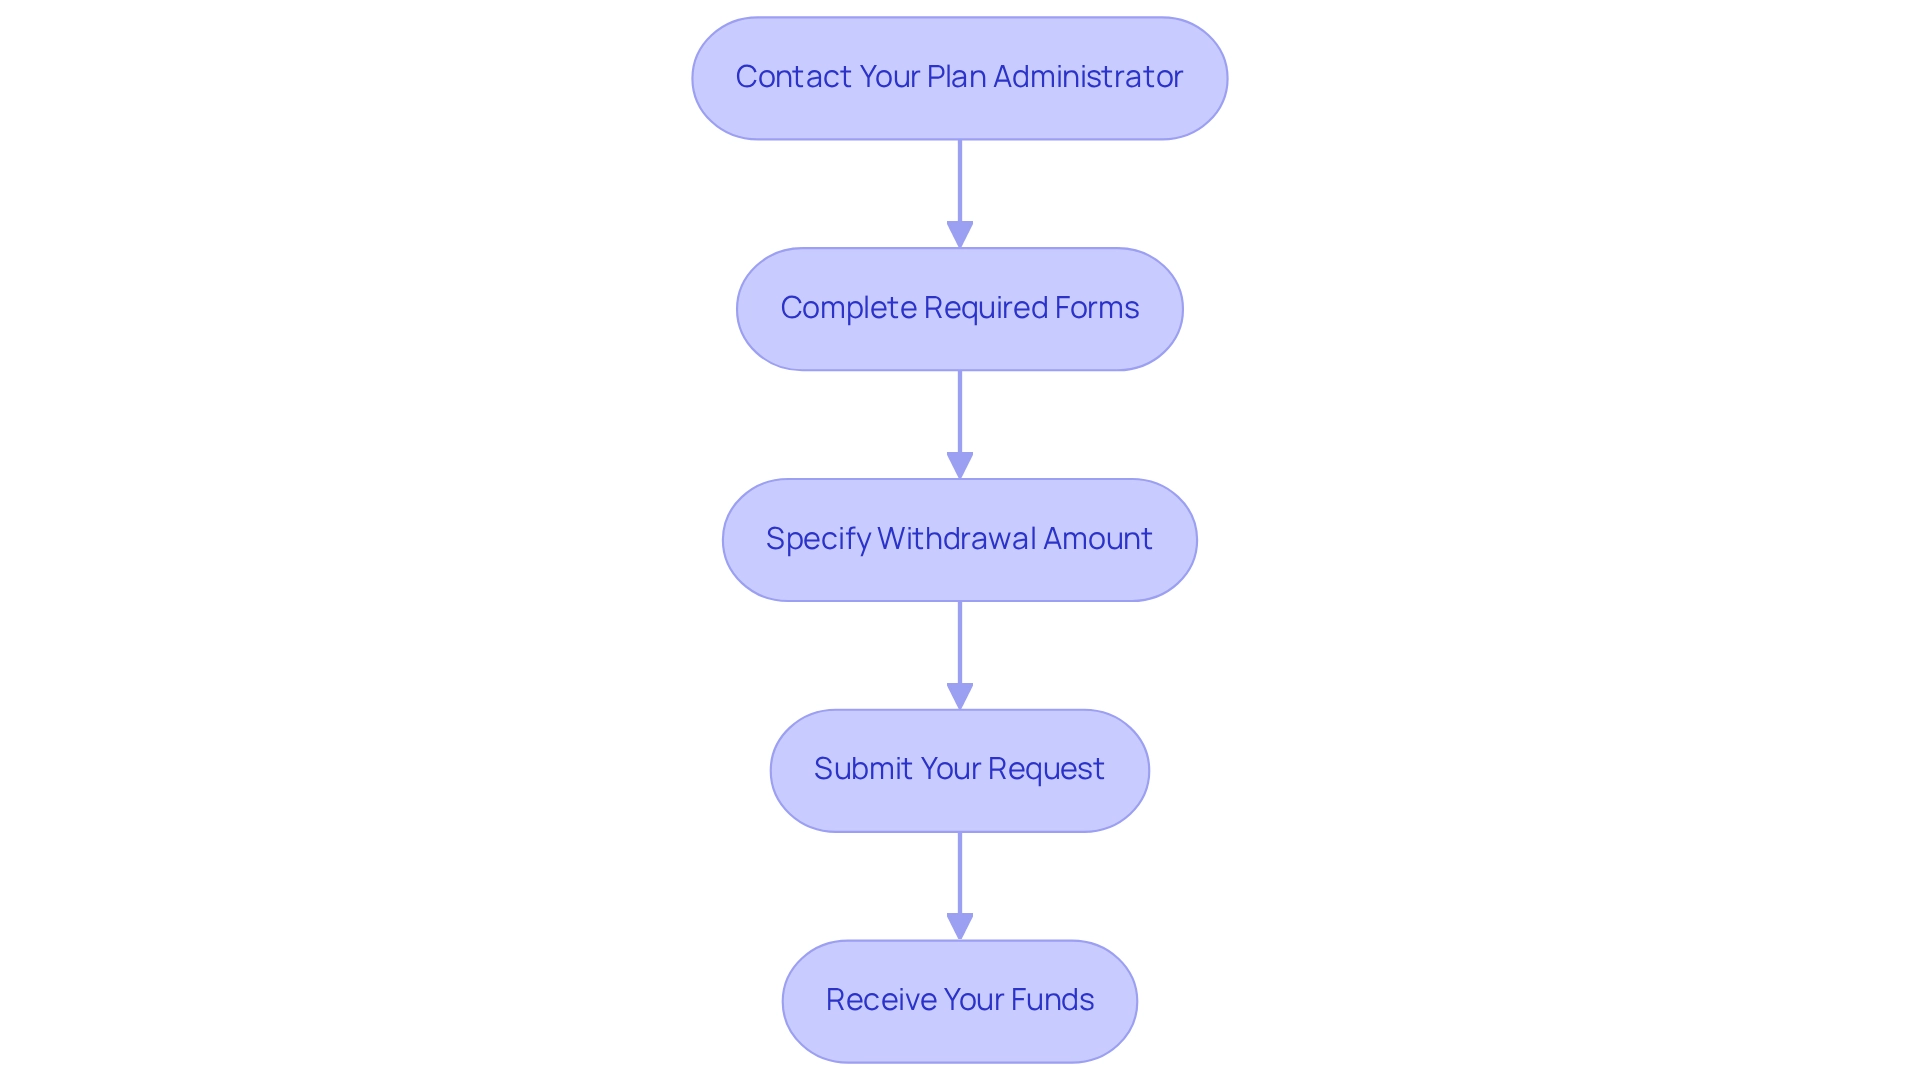
- Contact Your Plan Administrator: Start by reaching out to the administrator of your 401(k) or 403(b) plan. It’s essential to confirm your eligibility and understand the specific process for taking out funds.
- Complete Required Forms: You’ll need to fill out any necessary forms for your departure. This may include providing proof of age and employment separation.
- Specify Withdrawal Amount: Take a moment to decide how much you wish to withdraw. While you can choose any amount, it’s wise to consider the long-term impact on your retirement savings for your family’s future.
- Submit Your Request: Once you’re ready, send your request to withdraw along with any necessary documentation to your plan administrator.
- Receive Your Funds: After your request is approved, the funds will be disbursed to you. Just remember, income taxes will still apply, so it’s important to be aware of the tax implications of your withdrawal.
Statistics show that many employees have utilized their 401(k) plans, highlighting the importance of understanding the process of accessing your funds. Imagine if you could engage a monetary consultant to help you navigate this journey. As Ryan Theisen, CFP®, wisely stated, “Taking a comprehensive approach and seeking expert advice can assist you in making informed choices and enhancing your planning strategy.” This guidance is especially pertinent when managing the intricacies of the 55 year rule 401k provision, ensuring that your withdrawal aligns with your overall retirement goals.
By following these steps and considering expert advice, you can effectively manage the complexities of the 55 year rule 401k. Remember, together, we can navigate this journey to secure your family’s economic future.
Evaluate the Pros and Cons of the Rule of 55
When considering the 55 year rule 401k, it’s essential to thoughtfully weigh its benefits against its drawbacks.
Pros:
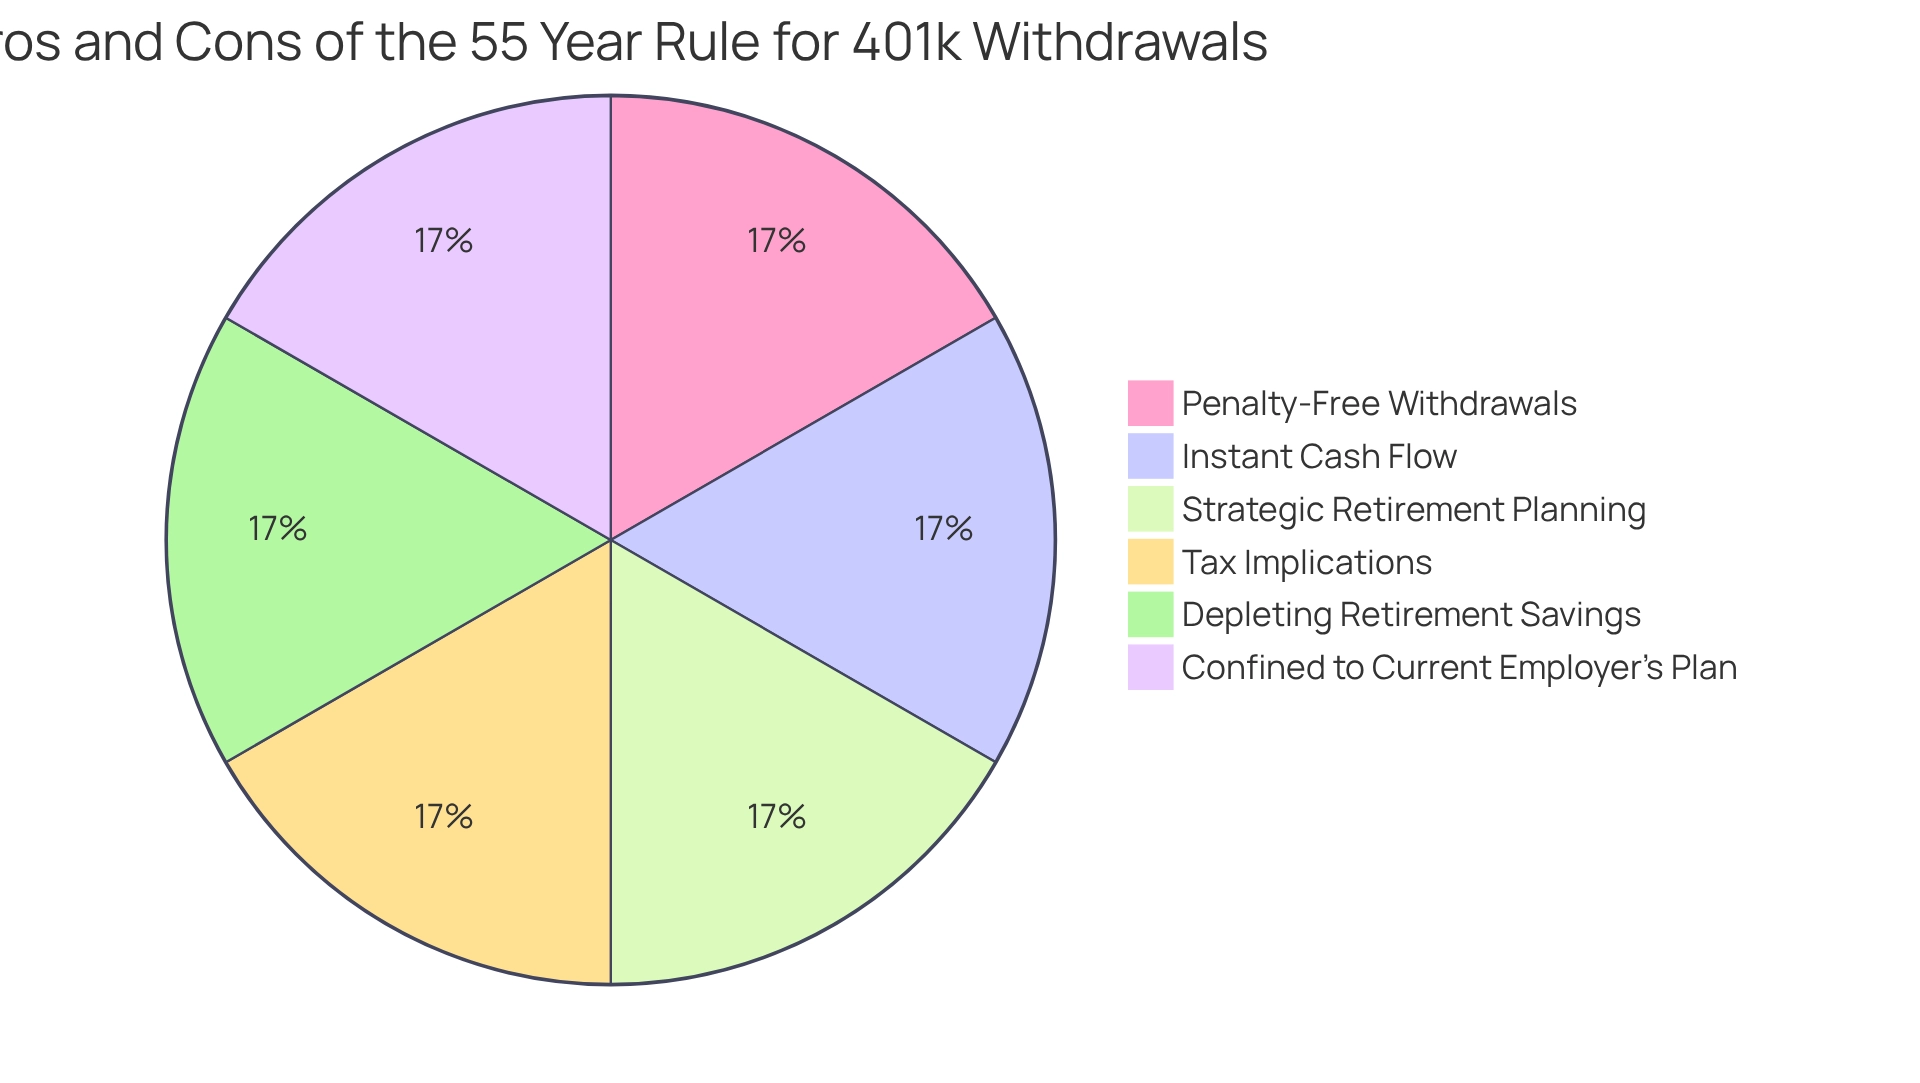
- Penalty-Free Withdrawals: This rule allows you to access your savings without the usual 10% early withdrawal fee, giving you significant financial flexibility.
- Instant Cash Flow: If you’re facing urgent financial needs, like living expenses or investment opportunities, the Rule of 55 can provide a quick solution.
- Strategic Retirement Planning: By utilizing this rule, you can enhance your planning around retirement, aligning your financial strategies with your family’s goals.
Cons:
- Tax Implications: Withdrawals under the Rule of 55 are subject to ordinary income tax, which can greatly reduce the amount you receive. Understanding these tax effects is crucial for effective financial planning.
- Depleting Retirement Savings: Accessing funds early can threaten your long-term financial security if not approached carefully. It’s important to consider how these withdrawals might impact your future income once you leave the workforce.
- Confined to Current Employer’s Plan: Not all employer plans qualify for the 55 provision, which may limit your access to savings from previous employers, potentially restricting your financial options.
In addition to the 55 year rule 401k, the IRS outlines other exceptions for penalty-free distributions, such as medical expenses, disability, or unemployment. As the IRS states, “You might not be able to contribute to your account for six months after you receive the hardship distribution,” underscoring the importance of understanding the implications of accessing funds early.
Imagine if you could explore these alternatives to gain more flexibility in accessing your retirement funds. Seeking guidance from a financial advisor can be a valuable step in assessing your options and ensuring that any withdrawals align with your long-term financial goals. Together, we can navigate this journey. Additionally, examining case studies like “Alternative Paths to Early Retirement Withdrawals” can provide insights into other exceptions for penalty-free withdrawals, enriching your understanding and offering you more choices.
Conclusion
The Rule of 55 is an invaluable provision for those approaching retirement, allowing for penalty-free withdrawals from 401(k) and 403(b) plans for individuals who leave their jobs at or after age 55. This rule not only offers immediate access to retirement funds but also fosters strategic financial planning. Imagine the peace of mind it can bring, as seen in the journeys of individuals like Jay and Emma, and Emily and Mark.
To benefit from the Rule of 55, individuals must meet specific criteria, including age and employment separation. It’s important to understand these requirements fully, and seeking guidance from financial experts can shed light on potential tax implications and their effects on retirement savings.
While the Rule of 55 presents significant advantages, such as enhanced cash flow and flexibility, it’s crucial to consider potential downsides, including tax liabilities and the risk of depleting retirement savings. Careful evaluation and professional guidance are essential to ensure that withdrawals align with your long-term financial goals.
In essence, the Rule of 55 empowers individuals to take charge of their financial futures during pivotal life transitions. By understanding its nuances and utilizing it wisely, you can make informed decisions that strengthen your retirement strategies and enhance your overall financial security. Remember, we’re here for you, and together, we can navigate this journey towards a secure and fulfilling retirement.
Frequently Asked Questions
What is the 55 year rule 401k?
The 55 year rule 401k is an IRS provision that allows individuals who leave their job during or after the year they turn 55 to withdraw funds from their 401(k) or 403(b) plans without incurring the usual 10% early withdrawal penalty.
Who can benefit from the 55 year rule 401k?
Individuals who leave their job during or after the year they turn 55 can benefit from this rule, particularly those needing to access their savings earlier due to job loss or voluntary retirement.
How does the 55 year rule 401k assist in financial planning?
This rule enhances individuals’ planning strategies by allowing for greater adaptability in managing their funds, enabling them to make strategic choices regarding their savings and facilitating a smoother transition into later life.
Can you provide an example of how the 55 year rule 401k has been applied?
Jay and Emma, a couple in their late 40s, utilized the 55 year rule 401k to effectively plan for their children’s education while preparing for their own future, balancing current responsibilities with long-term aspirations.
What is the significance of accessible withdrawal options like the 55 year rule 401k?
Accessible withdrawal options are crucial during uncertain times, as seen with 14% of U.S. workers taking coronavirus-related distributions from their 401(k) plans in 2020. The 55 year rule 401k provides immediate access to funds and encourages individuals to reflect on their long-term financial goals.
How can individuals prepare for unexpected life changes using the 55 year rule 401k?
By understanding and utilizing the 55 year rule 401k, individuals can better navigate their retirement landscape, ensuring they are prepared for both expected and unexpected life changes, allowing for more informed financial decisions.
List of Sources
- Understand the Rule of 55 and Its Purpose
- Warren Buffett’s 105 Best Quotes Of All Time | Investing, Money & Life (https://suredividend.com/warren-buffett-quotes)
- 48 Interesting 401k Plan Statistics For 2023 – Carry (https://carry.com/learn/401k-statistics)
- American Retirement and Tax-Preferred Savings Accounts, Tax Year 2018 (https://taxfoundation.org/data/all/federal/401k-ira-retirement-savings-accounts)
- Determine Eligibility for the Rule of 55
- How To Retire Early With The Rule Of 55 (https://nasdaq.com/articles/how-retire-early-rule-55)
- What is the Rule of 55, and What Are the Rules? – Georgia Safe Retirement Planners (https://georgiasaferetirementplanners.com/403b-401k-withdrawal-age-55-rule)
- Execute Withdrawals Using the Rule of 55
- 48 Interesting 401k Plan Statistics For 2023 – Carry (https://carry.com/learn/401k-statistics)
- Retire Early and Penalty-Free: Navigating the Rule of 55 (https://blog.acadviser.com/retire-early-penalty-free-navigating-the-rule-of-55)
- When Can You Withdraw? 401(k)s and the Rule of 55 (https://schwab.com/learn/story/retiring-early-5-key-points-about-rule-55)
- Evaluate the Pros and Cons of the Rule of 55
- Rule of 55: How to Access Your 401(k) Early Without Penalty | Facet (https://facet.com/retirement-planning/rule-of-55-how-it-works-pros-and-cons-considerations)
- How Many People Made Early 401(k) Withdrawals in 2024 — and How To Avoid the Same (https://finance.yahoo.com/news/many-people-made-early-401-120307965.html)
- Using the Rule of 55 to Take Early 401(k) Withdraws (https://visionretirement.com/articles/employee-benefits/rule-of-55)

Kevin has advised high-income W-2 tech and biotech families since 2015, and leads the education-first Age Five Family Office from Brea, California.
Connect on LinkedIn → · About KevinThis is part of how we approach Retirement & Employee Benefits for high-income W-2 families at Bright Advisers.
Keep reading