

Overview
Raising a child is a beautiful journey, but it comes with its challenges. The average cost of nurturing a little one can exceed $375,000 for middle-income households. This figure encompasses significant expenses in housing, food, healthcare, and childcare. Imagine if you could navigate these financial waters with confidence.
It’s crucial to create a personalized budget that reflects your family’s unique needs. By categorizing your expenses and maintaining flexibility, you empower yourself to adapt to changing financial situations. This approach not only helps you manage your resources effectively but also alleviates some of the stress that can accompany parenting.
Remember, you’re not alone in this journey. Many families face similar challenges, and together we can navigate them. We’re here for you, offering support and guidance as you make informed financial decisions that resonate with your family’s values. Let’s take this step together, ensuring a brighter future for your children.
Key Highlights:
- The average cost of raising a child from birth to age 18 is estimated to exceed $375,000 for middle-income households.
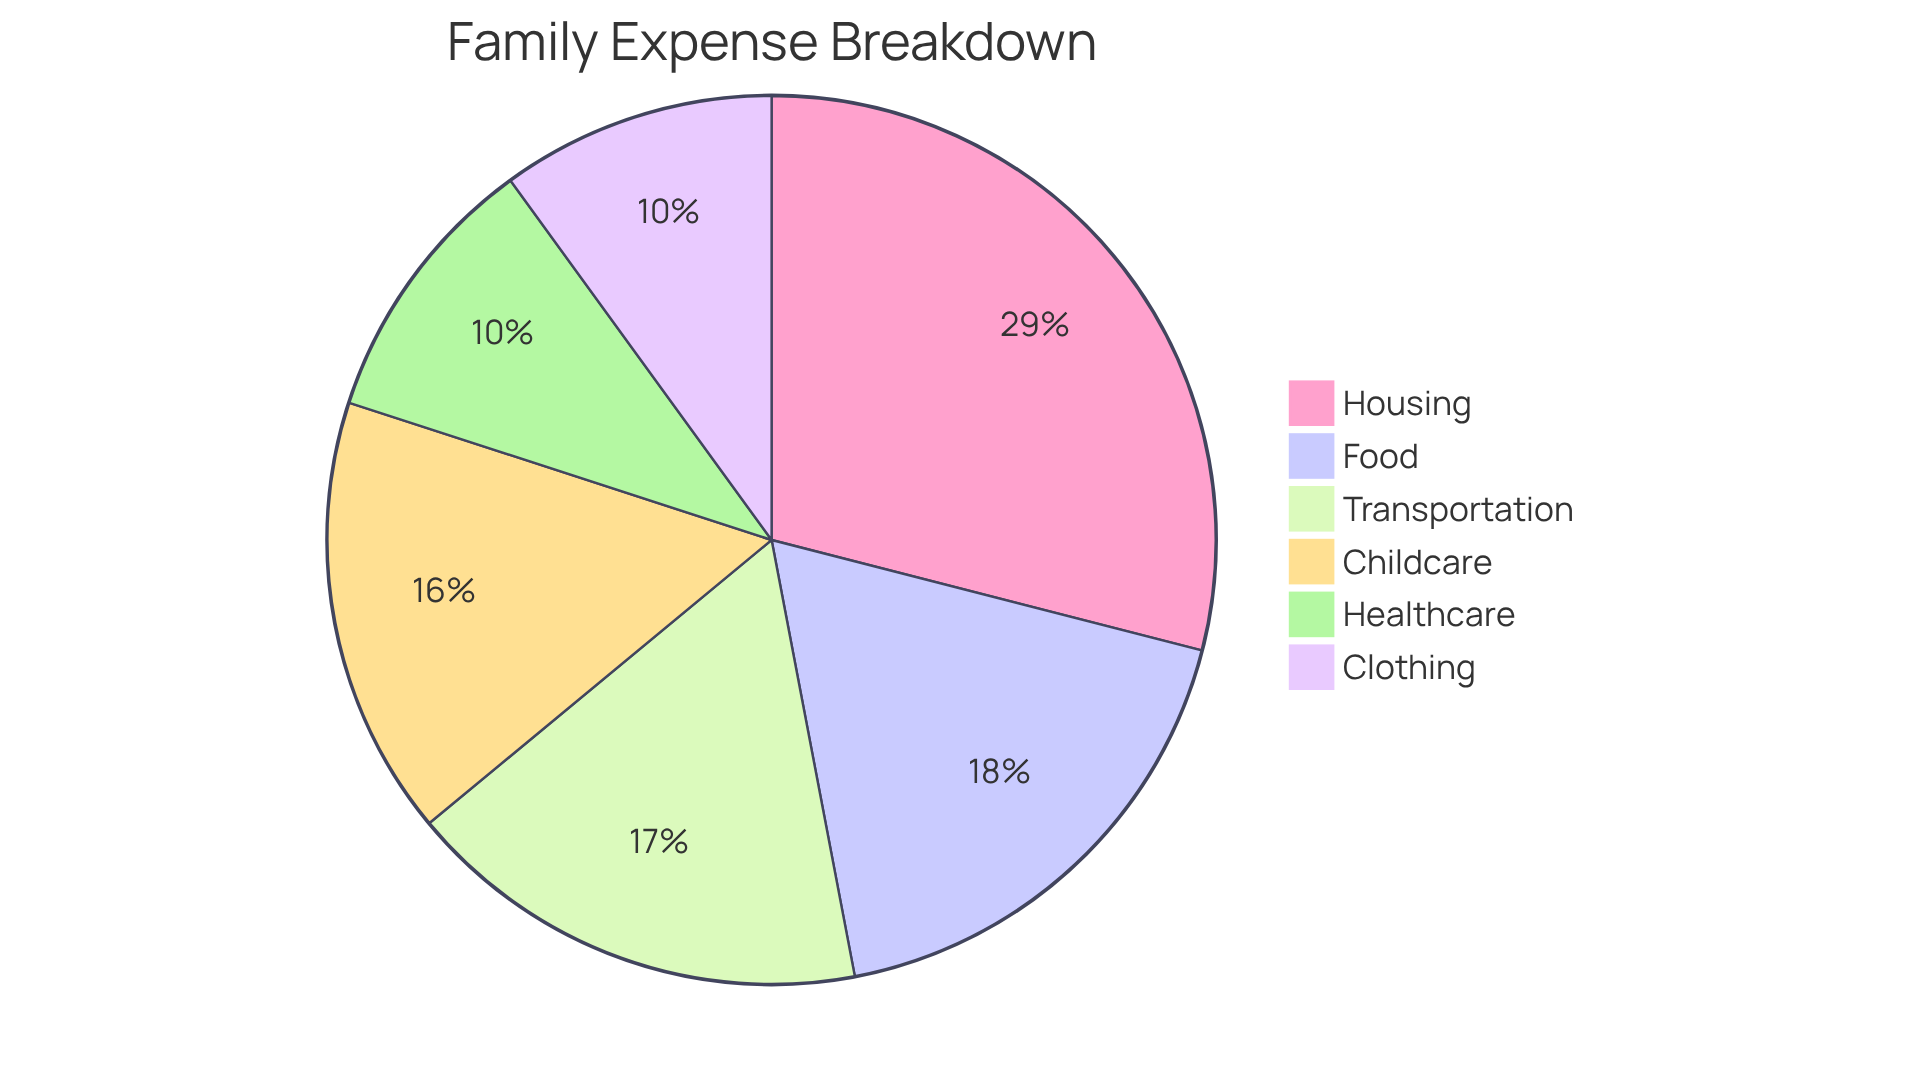
- Key expenses include housing (29% of total costs), food (18%), healthcare, childcare and education (16%), clothing, and transportation.
- Childcare expenses have risen by 28% from January 2015 to April 2025, increasing financial pressures on families.
- Immediate post-birth expenses average between $130 and $300 for essentials like diapers and formula.
- Creating a personalised budget involves gathering financial information, listing all expenses, establishing monetary objectives, and allocating resources effectively.
- Utilising budgeting tools like apps or spreadsheets can simplify tracking and adjusting spending.
- Maintaining budget flexibility is crucial; regular reviews, tracking actual spending, and planning for irregular expenses help adapt to changing financial situations.
Introduction
Navigating the financial landscape of raising a child can feel like wandering through a complex maze, especially as costs continue to rise. Imagine learning that middle-income families may spend over $375,000 from birth to age 18. It’s essential for parents to understand the various expense categories contributing to this daunting figure.
How can families effectively budget and manage these expenses while ensuring they meet their children’s needs? This guide offers a step-by-step approach to mastering the average costs of raising a child, empowering parents to take control of their financial future with confidence. Together, we can navigate this journey.
Understand the Average Costs of Raising a Child
Understanding the average cost of a child can be overwhelming, but you’re not alone. By examining national averages, we can see how costs vary based on location, lifestyle, and household size. Recent estimates indicate that the average cost of a child from birth to age 18 may exceed $375,000 for middle-income households. This figure includes essential expenses like housing, food, healthcare, education, and the average cost of a child. For instance, if your child was born in 2015, the estimated expense is around $310,605.
The USDA’s Expenditures on Children by Households report offers valuable insights into the average cost of a child, demonstrating how families allocate their budgets across various categories. Imagine budgeting for groceries and food—monthly expenses for a school-aged child typically range from $150 to $300. It’s important to note that childcare expenses have risen by 28% from January 2015 to April 2025, highlighting the increasing financial pressures that families face.
Additionally, don’t forget about the immediate post-birth expenses, which average between $130 and $300 for essentials like diapers, wipes, baby clothes, and formula. Comprehending these dynamics will empower you to make informed choices and effectively manage your resources. Remember, we’re here for you, and together, we can navigate this journey of parenthood with confidence.
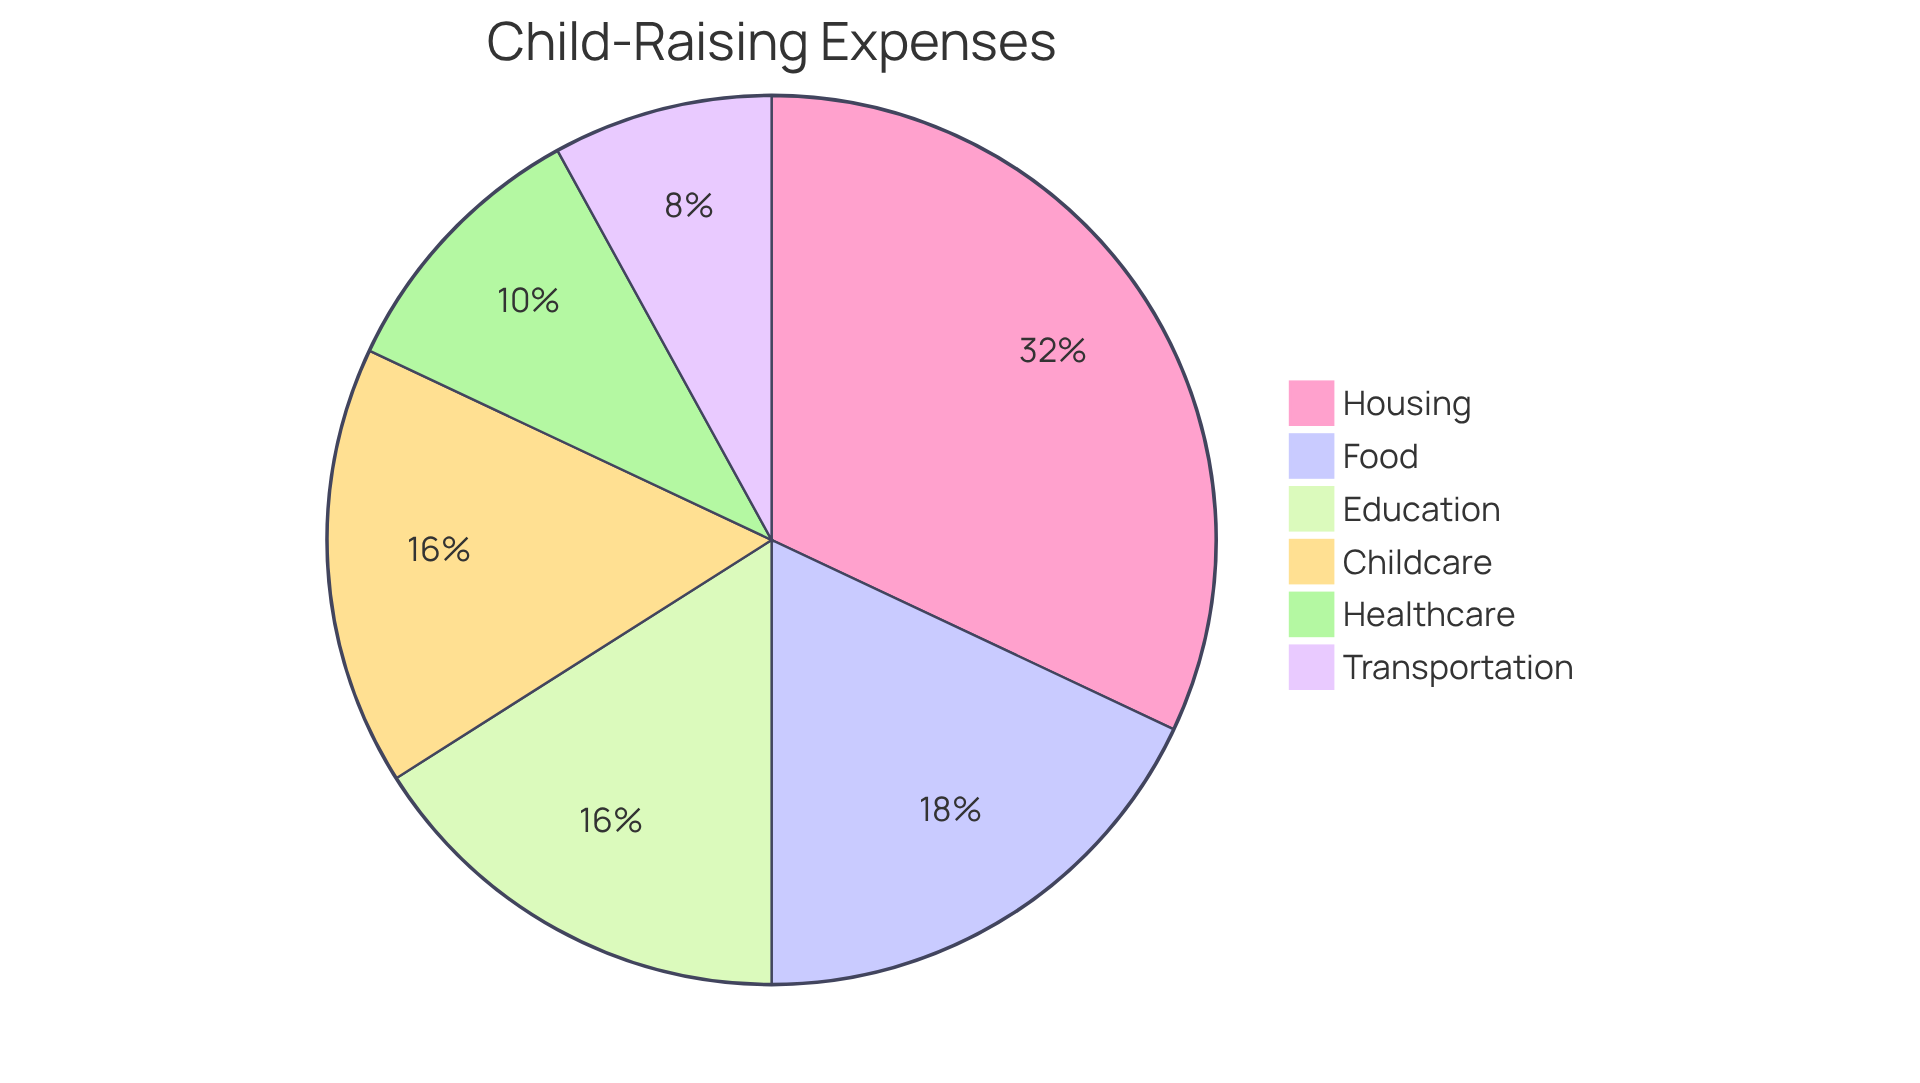
Identify Key Expense Categories: Essentials for Your Budget
As a young household like Jay and Emma, navigating finances can feel overwhelming. It’s essential to break down expenses into essential categories to understand where your money goes. This understanding can help you create an organized budget that meets your family’s needs and eases financial stress. Here are some key expense categories to consider:
- Housing: This includes your mortgage or rent payments, utilities, and maintenance costs. Housing typically accounts for about 29% of the total expenses that contribute to the average cost of a child, making it the largest financial obligation for many families.
- Food: Groceries and dining out can take a significant chunk of your budget. In 2025, families might spend between $11,805 and over $19,100 annually on food, depending on dietary choices and family size. Food expenses can represent roughly 18% of the average cost of a child when considering total child-raising expenditures.
- Healthcare: This category encompasses insurance premiums, out-of-pocket costs, and routine check-ups. It’s vital to consider healthcare expenses, as they can vary widely based on your family’s needs and insurance coverage.
- Childcare and Education: Costs for daycare, preschool, extracurricular activities, and tuition can add up quickly. The average cost of a child can include childcare, which alone can represent 16% of total child-rearing expenses, with yearly costs ranging from $5,357 for home-based care to $17,171 for center-based care, depending on location and the child’s age. Additionally, families can benefit from tailored wealth management solutions, like the Child and Dependent Care Tax Credit (CDCTC), which supports millions of working families with childcare costs.
- Clothing and Personal Care: This includes clothing, diapers, and personal hygiene products. Often overlooked, these expenses can accumulate rapidly, especially for growing children.
- Transportation: Car payments, fuel, and public transportation costs are crucial to consider, as they can significantly impact your overall budget.
By recognizing these categories, you can create a budgeting strategy that aligns with your family’s financial goals and priorities. This clarity will empower you to make informed decisions and allocate resources wisely. As Mark Lino, an economist at the Center for Nutrition Policy and Promotion, states, ‘This report will provide households with a better understanding of the average cost of a child they are likely to encounter while raising children.’ Together, we can navigate this journey towards financial stability.
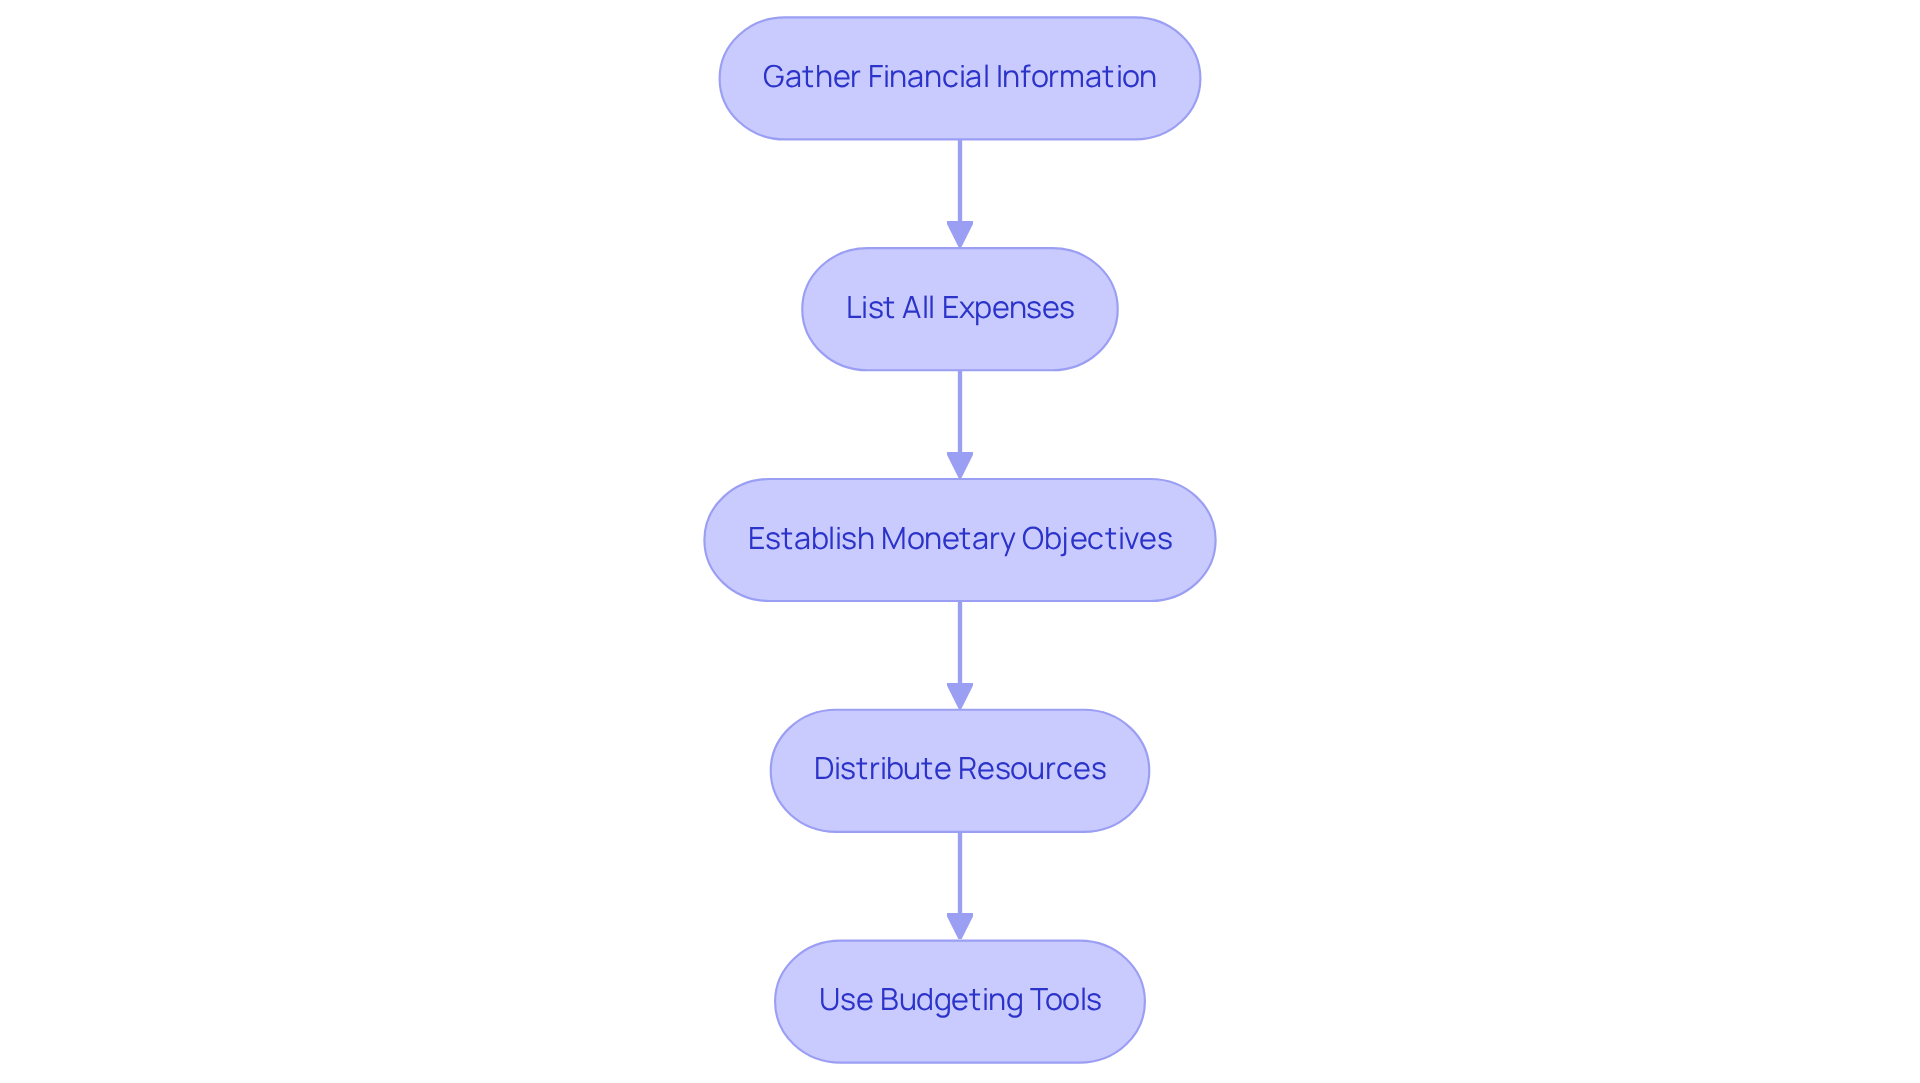
Create a Personalized Budget: Tailor Your Financial Plan
Creating a personalized budget that truly reflects your family’s values and financial goals can feel overwhelming, but it doesn’t have to be. Here are some gentle steps to guide you through the process:
-
Gather Financial Information: Start by collecting all your income sources—salaries, bonuses, and any side income. Understanding your total income is essential for effective budgeting, and it sets a solid foundation for your financial journey.
-
List All Expenses: Take a moment to list all your monthly expenses, using the categories you’ve identified. Be sure to include both fixed and variable costs. This comprehensive overview will help you recognize spending patterns and identify areas for improvement.
-
Establish Monetary Objectives: Think about your short-term and long-term monetary aims, like saving for college or planning a family vacation. It’s vital to align these goals with your family values, as your spending habits should reflect what matters most to you. Remember, Bright Advisers emphasizes the importance of linking your resources with personal priorities, ensuring your budget aligns with what you genuinely value.
-
Distribute Resources: Based on your income and expenses, allocate resources to each category, prioritizing essential needs. Keep in mind that a budget is about telling your money where to go, rather than wondering where it went.
-
Use Budgeting Tools: Consider leveraging budgeting apps or spreadsheets to track your spending and make adjustments as needed. Tools like Mint or YNAB (You Need A Budget) can simplify this process, making it easier for you to stay on track.
Furthermore, it’s wise to maintain a reserve of at least three to six months’ worth of living costs in an emergency fund, ensuring your economic stability. By customizing your budget to your family’s unique needs and utilizing Bright Advisers’ services—like creating a sustainable strategy and leveraging in-house technology for personalized planning—you can develop a plan that not only supports your goals but also brings you peace of mind. Remember, together, we can navigate this journey, and we’re here for you every step of the way.
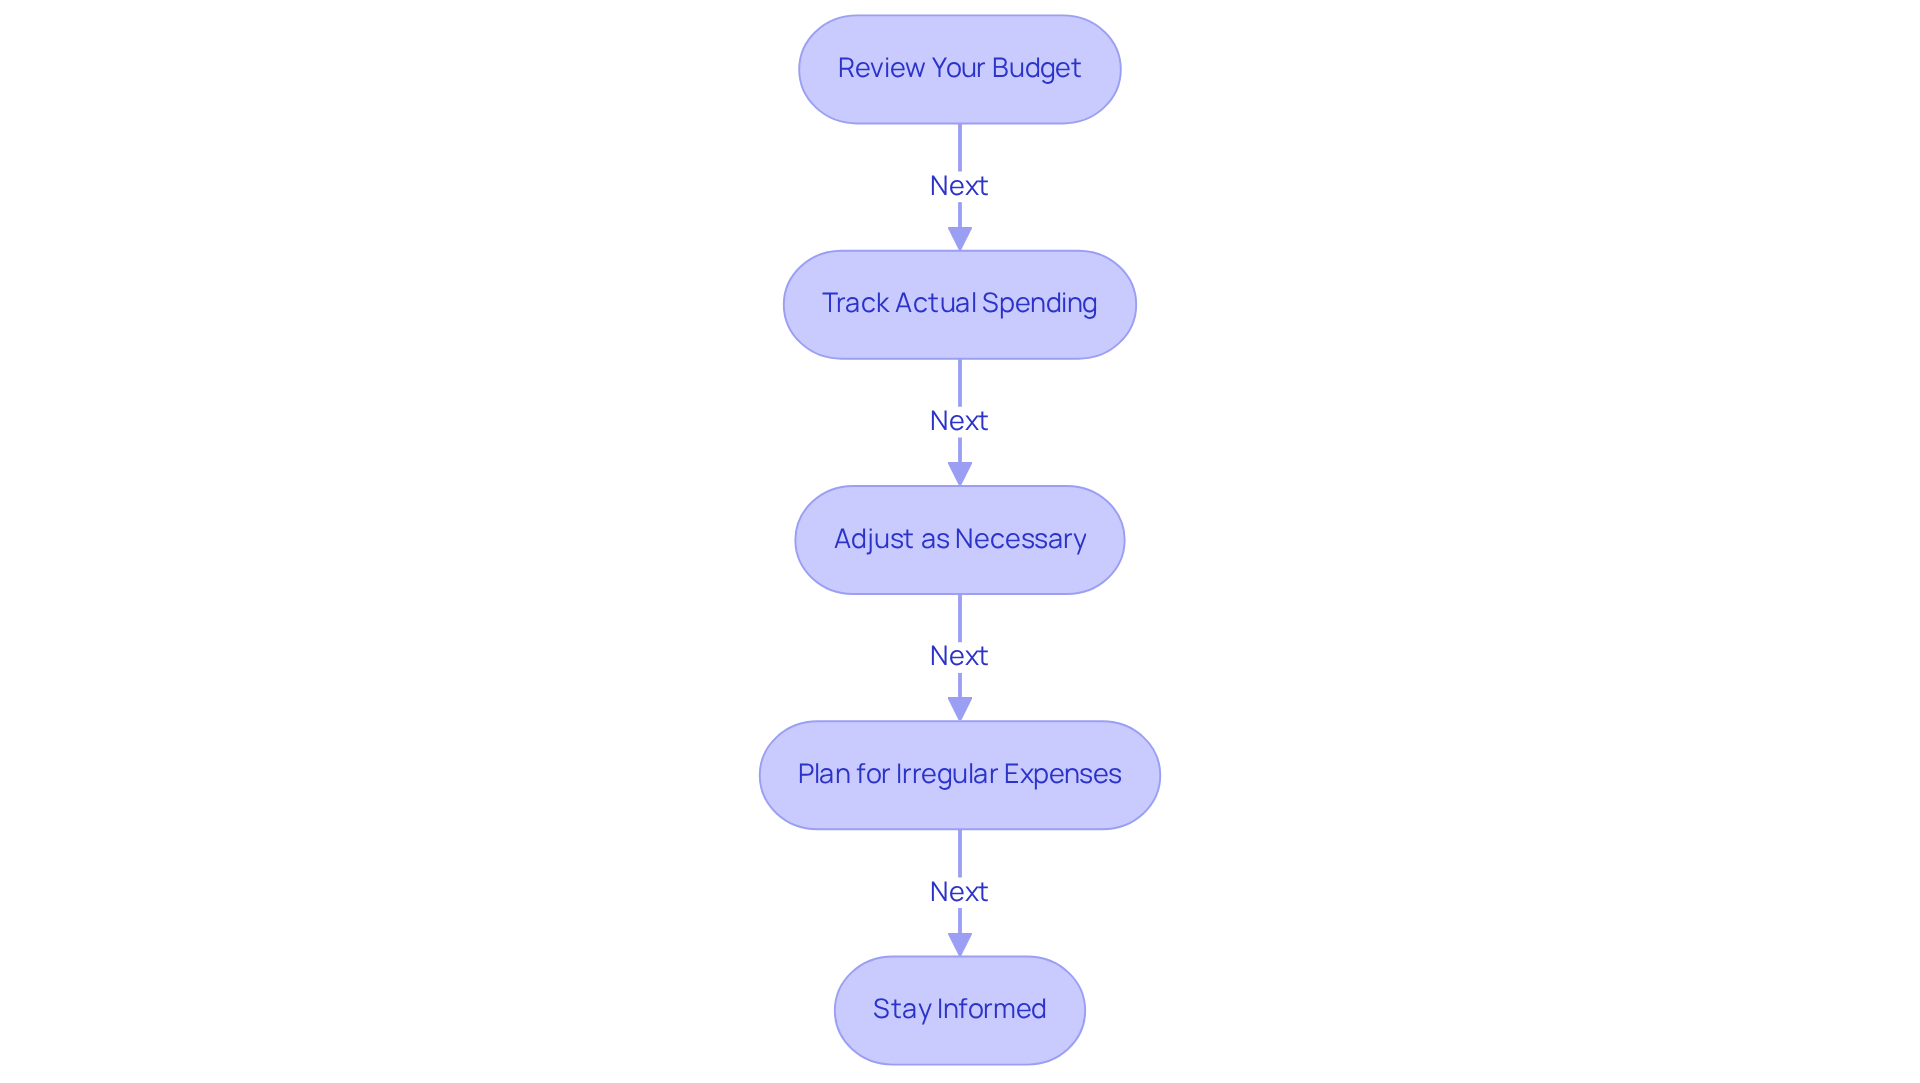
Track and Adjust Your Expenses: Maintain Budget Flexibility
To maintain budget flexibility, consider implementing these nurturing strategies:
-
Regularly Review Your Budget: Imagine dedicating time each month to review your budget and evaluate your spending patterns. This simple practice can help you stay aligned with your financial goals, giving you peace of mind.
-
Track Actual Spending: It’s important to utilize budgeting applications or spreadsheets to record your actual costs against your planned amounts. By pinpointing areas where overspending occurs, you can make timely adjustments that reflect your family’s needs.
-
Adjust as Necessary: If certain categories consistently exceed or fall short of your budget, don’t hesitate to make the necessary adjustments. Reallocating funds from one category to another can better reflect your family’s evolving priorities.
-
Plan for Irregular Expenses: Anticipating irregular expenses, like medical bills or school fees, can alleviate stress. Consider setting aside a small amount each month in a dedicated savings account. This proactive approach can help you feel more secure when unexpected expenses arise.
-
Stay Informed: As life changes, such as job transitions or welcoming new family members, it’s essential to monitor these shifts and modify your budget accordingly. Staying informed empowers you to adjust your budget to suit your changing circumstances.
By actively monitoring and modifying your expenses, you can ensure your budget remains an effective tool for managing your household finances. Remember, as investment consultants often highlight, “A budget is not merely a figure; it represents your household’s values and objectives.” Together, we can navigate this journey. Bright Advisers offers tailored wealth management solutions that can help families implement these budgeting strategies effectively, ensuring financial security and freedom.
Conclusion
Understanding the financial landscape of raising a child is crucial for any family. The average cost of raising a child can feel overwhelming, with estimates suggesting it may surpass $375,000 from birth to age 18. Imagine breaking down these expenses into key categories—like housing, food, healthcare, and childcare. By doing so, families can create a clearer picture of their financial obligations and develop a personalized budget that aligns with their values and goals.
A comprehensive budgeting strategy involves gathering financial information, listing all expenses, and establishing monetary objectives. It’s important to regularly review and adjust this budget, allowing families to maintain flexibility and ensure their financial plan adapts to changing circumstances. The insights shared in this guide empower parents to navigate the complexities of financial planning with confidence and clarity.
Ultimately, the journey of raising a child is both rewarding and challenging. A well-structured budget can serve as a vital tool in achieving financial stability. By prioritizing essential expenses and staying informed about potential changes, families can secure their financial future while enjoying the joys of parenthood. Embracing these budgeting strategies not only alleviates stress but also fosters a nurturing environment for children to thrive. Remember, we’re here for you—together, we can navigate this journey.
Frequently Asked Questions
What is the average cost of raising a child from birth to age 18?
The average cost of raising a child from birth to age 18 for middle-income households may exceed $375,000.
How much does it cost to raise a child born in 2015?
For a child born in 2015, the estimated expense is around $310,605.
What categories of expenses are included in the average cost of raising a child?
The average cost includes essential expenses such as housing, food, healthcare, and education.
What are the monthly food expenses for a school-aged child?
Monthly expenses for groceries and food for a school-aged child typically range from $150 to $300.
How have childcare expenses changed in recent years?
Childcare expenses have risen by 28% from January 2015 to April 2025.
What are the immediate post-birth expenses for a newborn?
Immediate post-birth expenses average between $130 and $300 for essentials like diapers, wipes, baby clothes, and formula.
Why is it important to understand the costs of raising a child?
Understanding these costs can empower parents to make informed choices and effectively manage their resources.
List of Sources
- Understand the Average Costs of Raising a Child
- How Much Does It Cost to Raise a Child in the U.S.? (https://investopedia.com/articles/personal-finance/090415/cost-raising-child-america.asp)
- How Much Does it Cost to Raise a Child? (https://westernsouthern.com/personal-finance/how-much-does-it-cost-to-raise-a-kid)
- Here’s How Much It Costs to Raise a Child | The Motley Fool (https://fool.com/money/research/heres-how-much-it-costs-to-raise-a-child)
- Cost of Raising a Child in Major U.S. Metros – 2025 Study (https://smartasset.com/data-studies/cost-raise-child-metro-2025)
- Identify Key Expense Categories: Essentials for Your Budget
- How Much Does It Cost to Raise a Child in the U.S.? (https://investopedia.com/articles/personal-finance/090415/cost-raising-child-america.asp)
- 200 Quotes About Money And Personal Finance To Inspire You (https://marriagekidsandmoney.com/20-empowering-quotes-about-money-and-personal-finance)
- The Cost of Raising a Child (https://usda.gov/about-usda/news/blog/cost-raising-child)
- New Resource Reveals Notable Changes in Price and Supply of Child Care (https://ffyf.org/resources/2025/05/new-resource-reveals-notable-changes-in-price-and-supply-of-child-care)
- GoHenry | blog – not found (https://gohenry.com/us/blog/financial-education/40-quotes-to-help-your-child-learn-the-value-of-money)
- Create a Personalized Budget: Tailor Your Financial Plan
- 200 Quotes About Money And Personal Finance To Inspire You (https://marriagekidsandmoney.com/20-empowering-quotes-about-money-and-personal-finance)
- Top 150 Financial Planning Quotes [2025] (https://digitaldefynd.com/IQ/financial-planning-quotes)
- Creating a Family Budget Plan | SoFi (https://sofi.com/learn/content/creating-family-budget-plan)
- 14 Quotes From Our Favorite Money Saving Experts (https://chime.com/blog/quotes-from-money-saving-experts)
- Money Talk: 10 Great Quotes About Personal Finance (https://3riversfcu.org/blog/post/money-talk-10-great-quotes-about-personal-finance)
- Track and Adjust Your Expenses: Maintain Budget Flexibility
- 200 Quotes About Money And Personal Finance To Inspire You (https://marriagekidsandmoney.com/20-empowering-quotes-about-money-and-personal-finance)
- How Financially Literate Is America – Key Stats by Age (2025) – Carry (https://carry.com/learn/how-financially-literate-is-america-key-stats)
- 13 Important Personal Finance Stats You Need to Know – Savology (https://savology.com/13-financial-statistics-you-need-to-know)
- Personal Finance Statistics You Should Be Aware of in 2025 (https://moneyzine.com/personal-finance/personal-finance-statistics)
- 15 Timeless Personal Budgeting Quotes – Vasili Africa (https://vasiliafrica.com/15-timeless-personal-budgeting-quotes)

Kevin has advised high-income W-2 tech and biotech families since 2015, and leads the education-first Age Five Family Office from Brea, California.
Connect on LinkedIn → · About Kevin