

Overview
The main focus of this article is to guide families on how to effectively utilize the backdoor Roth IRA contribution process to enhance their retirement savings. Imagine if you could secure a brighter financial future for your family. By making non-deductible contributions to a traditional IRA and converting them to a Roth IRA, families can bypass the income limits set by the IRS.
It’s important to understand that timely conversions are key, and consulting with a financial advisor can help you avoid unexpected tax liabilities. Together, we can navigate this journey toward a more secure retirement.
Key Highlights:
- A backdoor Roth IRA allows high-income individuals to bypass IRS income limits and enhance retirement savings through non-deductible contributions to a traditional IRA.
- Contribution limits for IRAs in 2025 are $7,000, or $8,000 for those aged 50 and older, with additional opportunities to contribute to 401(k) plans.
- The process involves opening a traditional IRA, converting it to a Roth IRA, and filing IRS Form 8606 to report nondeductible contributions and avoid double taxation.
- The pro-rata rule can lead to unexpected tax liabilities during conversions, making it crucial to manage pre-tax and after-tax contributions effectively.
- Timely conversions are essential to maximize tax advantages and avoid taxable growth in traditional IRAs.
- Consulting with financial advisors is recommended to navigate complexities and ensure compliance with tax regulations.
Introduction
In the world of retirement planning, the Backdoor Roth IRA emerges as a valuable strategy for high-income earners who want to maximize their tax-advantaged savings. Imagine being able to bypass the income restrictions that often limit Roth IRA contributions. This innovative approach opens the door to enjoying the benefits of tax-free growth and withdrawals, making it an appealing option for families.
As more families recognize the potential of this financial tool, understanding its intricacies becomes essential. It’s important to grasp how to navigate contribution limits and avoid common pitfalls.
This article will gently guide you through the step-by-step process of executing a Backdoor Roth IRA, while also highlighting the importance of seeking professional guidance. Together, we can optimize your outcomes and minimize tax liabilities, ensuring a brighter financial future for you and your loved ones.
Understand the Backdoor Roth IRA Concept
A back door roth contribution offers a thoughtful strategy for high-income individuals eager to enhance their retirement savings, allowing them to sidestep the income limits set by the IRS. By making a non-deductible contribution to a traditional IRA, individuals can transform their investment into an individual retirement account, unlocking valuable tax advantages. Imagine the peace of mind that comes with tax-free growth and tax-free withdrawals during retirement—truly a wonderful option for long-term family savings. As we approach 2025, the contribution limit for IRAs remains at $7,000, or $8,000 for those aged 50 and older, empowering families to significantly boost their retirement savings through this approach. Additionally, families can contribute an extra $46,500 of after-tax dollars into their 401(k) accounts by December 31, 2025, further enhancing their retirement potential.
Recent statistics reveal that more families are embracing back door roth contribution strategies, indicating a growing awareness of the benefits associated with them. Financial advisors emphasize that this method is particularly advantageous for high-income families, as it allows them to secure tax-free income in retirement while also supporting estate planning—these IRAs can be passed down to heirs. For example, families like Emily and Mark have successfully navigated their financial journeys with the guidance of Bright Advisers, who crafted personalized strategies to help them achieve financial freedom and make work optional.
However, it’s essential to approach this process with care to avoid any unexpected tax implications. Most IRA contributions initially sit in an interest-bearing cash account, and delaying the conversion could lead to a tax bill. Timothy D. Moran, CFP®, advises, “It requires careful planning and attention to detail to avoid unexpected tax consequences, so make sure to consult a professional to ensure they align with your goals.” Moreover, the complexities of the back door roth contribution process can lead to unforeseen tax obligations or penalties, as highlighted in the case study ‘Challenges of Implementing Back Door Roth Contributions.’ This underscores the importance of consulting with a financial professional, like those at Bright Advisers, to align these strategies with your family’s financial goals and maximize potential benefits. Together, we can navigate this journey and ensure a secure future for your loved ones.
Follow the Step-by-Step Contribution Process
Navigating the world of retirement savings can feel overwhelming, especially for young parents. But don’t worry; we’re here to guide you through the process of executing a back door roth contribution with care and clarity. Let’s take this journey together.
- Open a Traditional IRA: If you don’t have one yet, it’s time to set up a traditional IRA account with a financial institution that allows nondeductible deposits. This is your first step toward securing your family’s financial future by making a back door roth contribution: you can contribute up to $7,000 (or $8,000 if you’re 50 or older) to your traditional IRA using after-tax dollars. Remember, while the back door roth contribution won’t be tax-deductible, it’s an important part of your savings strategy. This limit is consistent with the 2025 IRA funding limits, ensuring you’re on the right track.
- Change to a Roth IRA: After making your deposit, consider transferring those funds from your traditional IRA to a Roth IRA. You can usually complete this process through your financial institution’s online platform or by reaching out to customer service. It’s a simple step that can have significant benefits for your family’s future.
- File IRS Form 8606: When tax season rolls around, don’t forget to complete IRS Form 8606. This form is essential for reporting your nondeductible contribution and the conversion. It helps track your basis in the traditional IRA and prevents double taxation on future withdrawals, giving you peace of mind about your back door roth contribution.
- Monitor Your Investments: After the conversion, keep an eye on your IRA investments to ensure they align with your long-term financial objectives. Consulting with a financial advisor can provide you with tailored strategies that resonate with your family’s goals.
- Cautionary Note: If you accidentally contribute more than the allowed limit, it’s important to know that you may face a 6% penalty on the excess amount for every year it remains in the account. Seeking guidance from a tax consultant is a wise choice if you have questions about withdrawing surplus funds from your retirement account. Together, we can navigate these complexities, ensuring your family’s financial well-being is prioritized.
Navigate Common Challenges and Tax Considerations
Navigating the Backdoor retirement account can be beneficial, but it presents particular challenges and tax implications that deserve your careful attention.
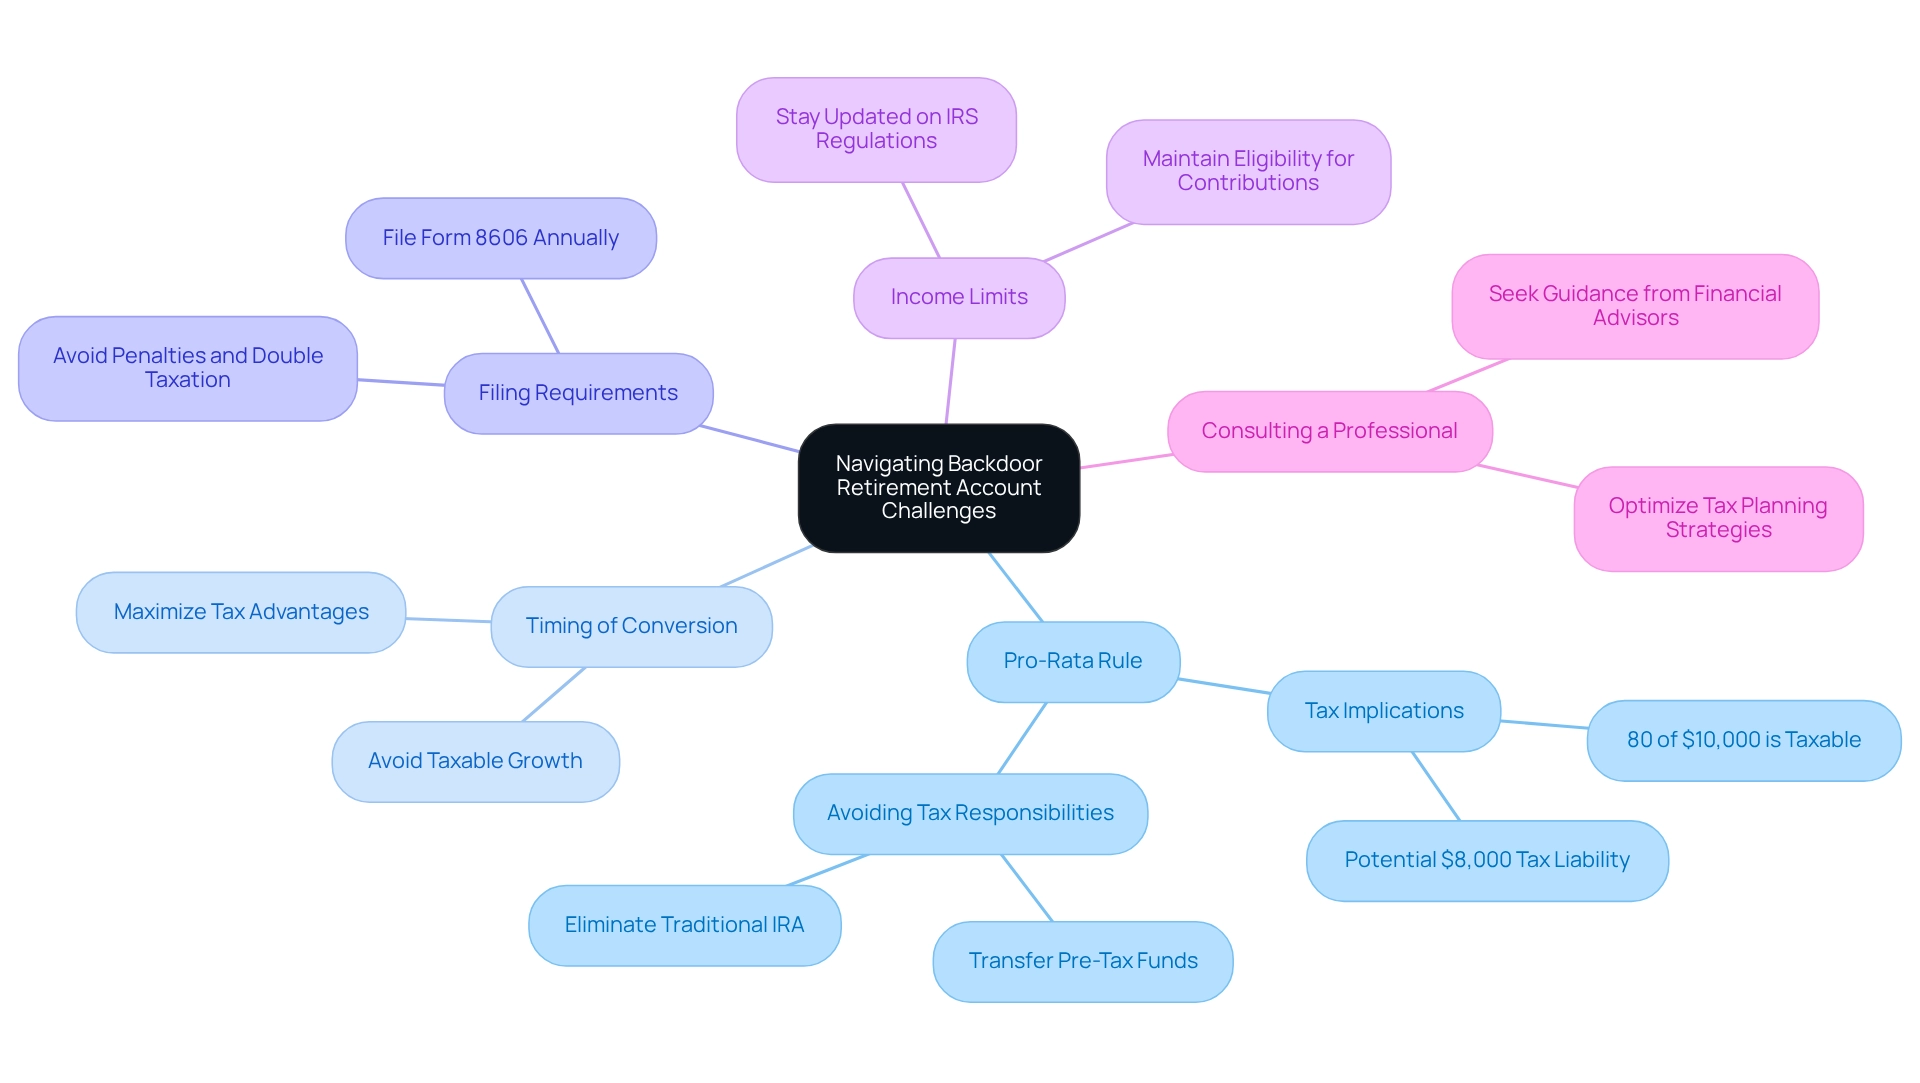
Understanding the Pro-Rata Rule: When converting funds, the IRS requires that all traditional IRAs be considered, including those with pre-tax deposits. This rule can lead to unexpected tax liabilities, making it crucial to understand how it impacts your financial situation. For instance, if 80% of a $10,000 conversion amount is taxable, that translates to $8,000 in potential tax liability. To avoid tax responsibilities from the Pro-Rata Rule, consider transferring pre-tax funds from your Traditional IRA into an employer’s retirement plan. This action can effectively eliminate your Traditional IRA and allow for tax-free Backdoor conversions.
Timing of Conversion Matters: To maximize tax advantages, aim to convert your traditional IRA to a different type of IRA soon after making the deposit. Delaying this conversion can lead to taxable growth, which reduces the benefits of the Backdoor strategy. On average, traditional IRAs can experience significant taxable growth rates before conversion, underscoring the importance of timely action.
Filing Requirements Are Key: Each year you make a nondeductible payment or convert funds, it’s essential to file Form 8606. Neglecting this requirement can lead to penalties and the risk of double taxation on your contributions.
Stay Informed About Income Limits: While the Backdoor IRA offers a pathway for high-income earners to contribute, it’s vital to stay updated on IRS regulations and potential changes to income limits to maintain eligibility. Recent news suggests that the Backdoor strategy can greatly enhance retirement savings when executed properly, highlighting the necessity of understanding these limits.
Consulting a Professional: Given the complexities of the Backdoor IRA, seeking guidance from a financial advisor or tax expert can help ensure compliance with tax regulations and optimize your strategy. Understanding the pro-rata rule and its impact is crucial in avoiding unnecessary tax burdens. Bright Advisers is here to assist you in navigating these complexities, providing valuable insights into the pro-rata rule and its implications. Through their collaboration with Bright Advisers, clients like Allison and Brian have maximized their financial potential by leveraging tax planning strategies that address missed opportunities, such as optimizing contributions and minimizing tax liabilities. By addressing these considerations, families can effectively implement the backdoor Roth contribution to enhance their retirement savings while minimizing tax implications. Remember, together, we can navigate this journey toward a secure financial future.
Conclusion
The Backdoor Roth IRA offers a wonderful opportunity for high-income earners to enhance their retirement savings while sidestepping traditional income restrictions. By making nondeductible contributions to a traditional IRA and then converting those funds into a Roth IRA, individuals can experience the joy of tax-free growth and withdrawals. With contribution limits set at $7,000 for most and $8,000 for those aged 50 and older, this approach can significantly strengthen a family’s long-term financial security.
However, navigating the nuances of the Backdoor Roth IRA calls for thoughtful planning and awareness of potential pitfalls. It’s essential to grasp key challenges, such as the Pro-Rata Rule and the timing of conversions, to avoid unexpected tax liabilities. Moreover, diligent record-keeping, including the filing of IRS Form 8606, is vital to ensure compliance and prevent double taxation. Consulting with financial professionals is invaluable, as they can provide personalized advice to optimize outcomes and align strategies with your family’s financial goals.
In conclusion, the Backdoor Roth IRA is more than just a financial tool; it represents a pathway to greater financial freedom and peace of mind for families striving for a secure retirement. By wisely leveraging this strategy and seeking professional guidance, individuals can maximize their tax-advantaged savings, ensuring a brighter financial future for themselves and their loved ones. Embracing the Backdoor Roth IRA could be a pivotal step in achieving long-term financial success together.
Frequently Asked Questions
What is a back door Roth contribution?
A back door Roth contribution is a strategy that allows high-income individuals to enhance their retirement savings by sidestepping the income limits set by the IRS. It involves making a non-deductible contribution to a traditional IRA and then converting it into a Roth IRA, unlocking valuable tax advantages.
What are the benefits of a back door Roth contribution?
The benefits include tax-free growth and tax-free withdrawals during retirement, making it a great option for long-term family savings. It also supports estate planning, as these IRAs can be passed down to heirs.
What are the contribution limits for IRAs in 2025?
The contribution limit for IRAs in 2025 is $7,000, or $8,000 for individuals aged 50 and older.
Can families contribute to their 401(k) accounts in addition to IRAs?
Yes, families can contribute an extra $46,500 of after-tax dollars into their 401(k) accounts by December 31, 2025, further enhancing their retirement savings potential.
Why is it important to consult a financial professional when using a back door Roth contribution strategy?
It’s essential to consult a financial professional to avoid unexpected tax implications and ensure careful planning. Delaying the conversion of IRA contributions could lead to a tax bill, and complexities in the process may result in unforeseen tax obligations or penalties.
What should individuals be cautious about when implementing back door Roth contributions?
Individuals should be cautious about the potential for unexpected tax consequences and the importance of aligning their strategies with their financial goals. Consulting with professionals, like those at Bright Advisers, is recommended to navigate these complexities effectively.
List of Sources
- Understand the Backdoor Roth IRA Concept
- Making a Backdoor or Mega Backdoor Roth Contribution in 2025 (https://merceradvisors.com/insights/retirement/making-a-backdoor-or-mega-backdoor-roth-contribution-in-2025)
- Backdoor Roth IRA: Advantages and Tax Implications Explained (https://investopedia.com/terms/b/backdoor-roth-ira.asp)
- Understanding the Backdoor Roth Conversion: A Strategy for High-Income Earners – Marshall Financial Group (https://marshallfinancial.com/backdoor-roth-conversion)
- Backdoor Roth IRAs: A Strategic Guide for High-Income Earners (https://condorcapital.com/2025/02/19/backdoor-roth-iras-a-strategic-guide-for-high-income-earners)
- Follow the Step-by-Step Contribution Process
- IRS Unveils Increased 2025 IRA Contribution Limits (https://theentrustgroup.com/blog/ira-contribution-limits)
- Roth IRA Income & Contribution Limits for 2025 – NerdWallet (https://nerdwallet.com/article/investing/roth-ira-contribution-limits)
- Navigate Common Challenges and Tax Considerations
- Understanding the Pro-Rata Rule – Ironwood Wealth Management (https://ironwoodwm.com/understanding-the-pro-rata-rule)
- Pro rata rule on Roth IRA conversions: What to know & how to avoid (https://thrivent.com/insights/retirement-planning/pro-rata-rule-on-roth-ira-conversions-what-to-know-how-to-avoid)
- How the Pro-Rata Rule Impacts Your Backdoor Roth Contributions (https://insights.wjohnsonassociates.com/blog/how-the-pro-rata-rule-impacts-your-backdoor-roth-contributions)
- Avoid the Pro Rata Rule with Backdoor & Mega Roth Conversions | RGWM (https://rgwealth.com/insights/how-to-avoid-the-pro-rata-rule-with-backdoor-and-mega-roth-conversions)

Kevin has advised high-income W-2 tech and biotech families since 2015, and leads the education-first Age Five Family Office from Brea, California.
Connect on LinkedIn → · About KevinThis is part of how we approach Tax Management for high-income W-2 families at Bright Advisers.
Keep reading