

Key Highlights
- Portfolio allocation involves distributing resources across stocks, bonds, and cash to manage risk and achieve financial goals.
- Understanding asset classes is crucial: stocks offer growth, bonds provide stability, and cash equivalents ensure liquidity.
- Diversification acts as a safety net, reducing volatility and potential losses during market downturns.
- Higher potential returns typically come with higher risks; staying invested is essential to capture market gains.
- Assessing your financial situation includes calculating net worth, identifying income sources, and creating a budget for retirement expenses.
- Risk tolerance can be evaluated through comfort level assessments, past experiences, and consultations with financial advisors.
- A diversified portfolio should include a balanced asset allocation, regular rebalancing, and consideration of tax implications.
- Regular portfolio reviews are necessary to align investments with changing financial goals and life circumstances.
- Bright Advisers offers personalised strategies and transparent fee structures to support families in achieving their financial objectives.
Introduction
Many parents feel overwhelmed by the thought of securing their family’s future while planning for retirement. It’s not just about picking investments; it’s about finding the right balance to keep your family secure while aiming for growth. This guide is here to walk you through your financial journey, helping you understand your unique situation and build a portfolio that reflects your family’s dreams. How can you find that perfect balance between growth and security as life changes?
Understand Portfolio Allocation Basics
Imagine feeling overwhelmed by financial choices while trying to secure your family’s future. The best portfolio allocation for retirees involves how you distribute your resources across different investments like stocks, bonds, and cash. Understanding the best portfolio allocation for retirees can significantly change the way you manage risk and achieve your financial goals.
Let’s explore some key concepts that can help you navigate this journey:
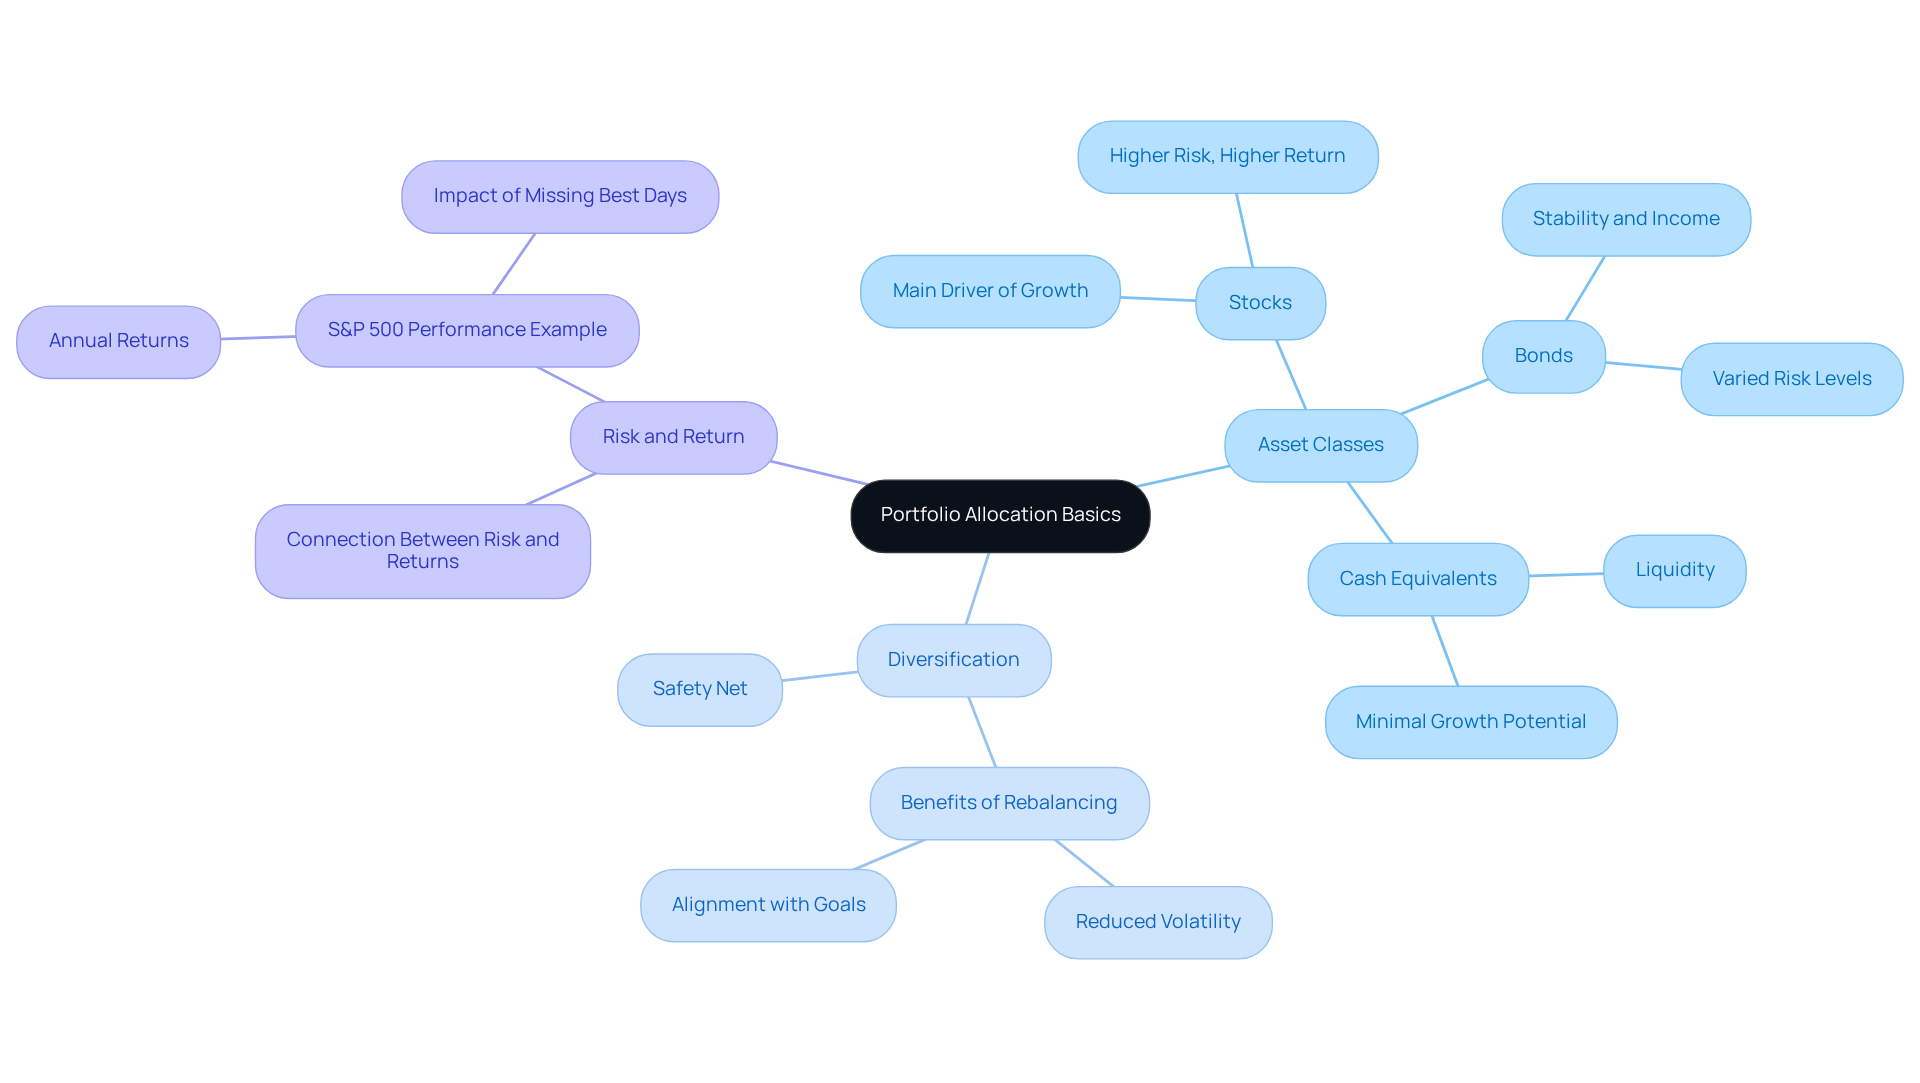
- Asset Classes: Familiarize yourself with different types of investments, including equities (stocks), fixed income (bonds), and cash equivalents. Stocks are generally the primary factor for growth in an investment collection, while bonds can offer stability and income.
- Diversification: Think of diversification as a safety net that can help protect your family’s finances during tough times. A well-diversified investment strategy can reduce losses during market downturns. For instance, a regularly rebalanced investment strategy can be about 20% less volatile than one that isn’t.
- Risk and Return: Generally, higher potential returns come with higher risk. Grasping this connection is essential for making informed choices regarding your investments. For example, in 2024, the S&P 500 had a 23% annual return, but missing the 10 best days resulted in only a 4% return. This highlights the importance of staying invested and not reacting impulsively to market fluctuations.
At Bright Advisers, we’re here for you. We utilize innovative technology to create customized strategies that bypass costly mutual funds, ETFs, and TAMPs, ensuring your assets work effectively for your family’s monetary objectives. Our transparent, all-inclusive fee structure, with no hidden fees or minimum account size, makes our services accessible to all families.
By understanding these fundamentals, you’ll feel more empowered to assess your financial situation and make choices that align with your family’s goals. Consistently evaluating your asset distribution is crucial for achieving the best portfolio allocation for retirees, as it helps align your holdings with your changing monetary objectives. Together, we can navigate this journey toward financial security.
Assess Your Financial Situation
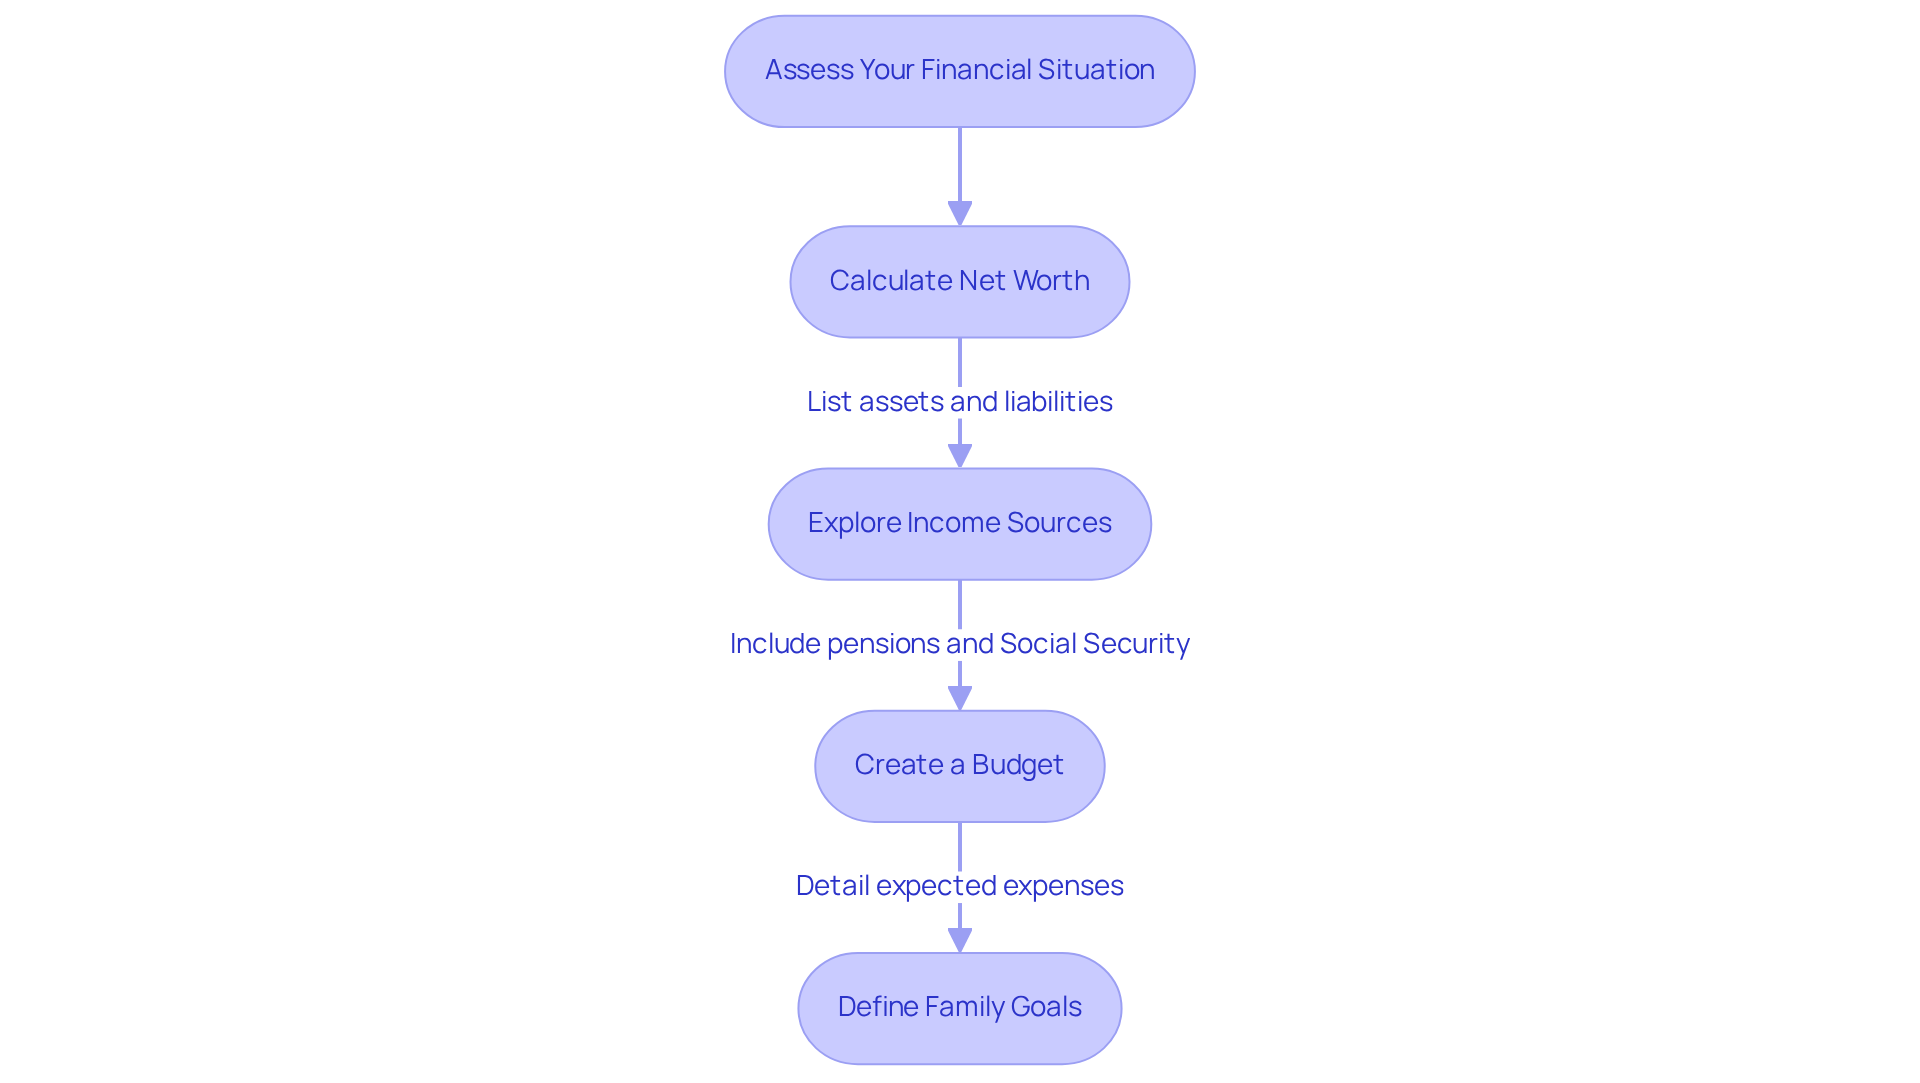
Imagine navigating your family’s future without a clear financial roadmap. To create the best portfolio allocation for retirees, let’s start by calculating your net worth together.
List all your assets, like savings, investments, and property, alongside your liabilities, including debts and loans. This helps you see where you stand financially, which is so important for your family’s well-being.
Next, let’s explore your income sources together. Identify all potential income streams, including pensions, Social Security benefits, and any part-time work you may engage in during retirement. In 2026, the median retirement income for Americans aged 65 and older is projected to be $58,680 per year, highlighting the importance of knowing your income streams.
Now, let’s create a simple budget that shows your expected monthly and yearly expenses in retirement. This should include healthcare, housing, and leisure activities. The average annual spending for retirees over 65 is approximately $62,000, so it’s essential to plan accordingly.
Finally, think about your family’s dreams and goals for the future. Determine your short-term and long-term monetary objectives, such as travel plans, legacy considerations, or funding education for grandchildren. Understanding these goals will guide your financial choices and assist you in achieving the best portfolio allocation for retirees.
With the right guidance, you can ensure a secure and fulfilling retirement for your family.
Identify Your Risk Tolerance
Imagine navigating the world of investments while juggling the responsibilities of parenthood – how do you find your footing? Comprehending your comfort level with uncertainty is essential for deciding how much challenge you can comfortably undertake in your investment portfolio. Let’s explore how you can figure out your risk tolerance:
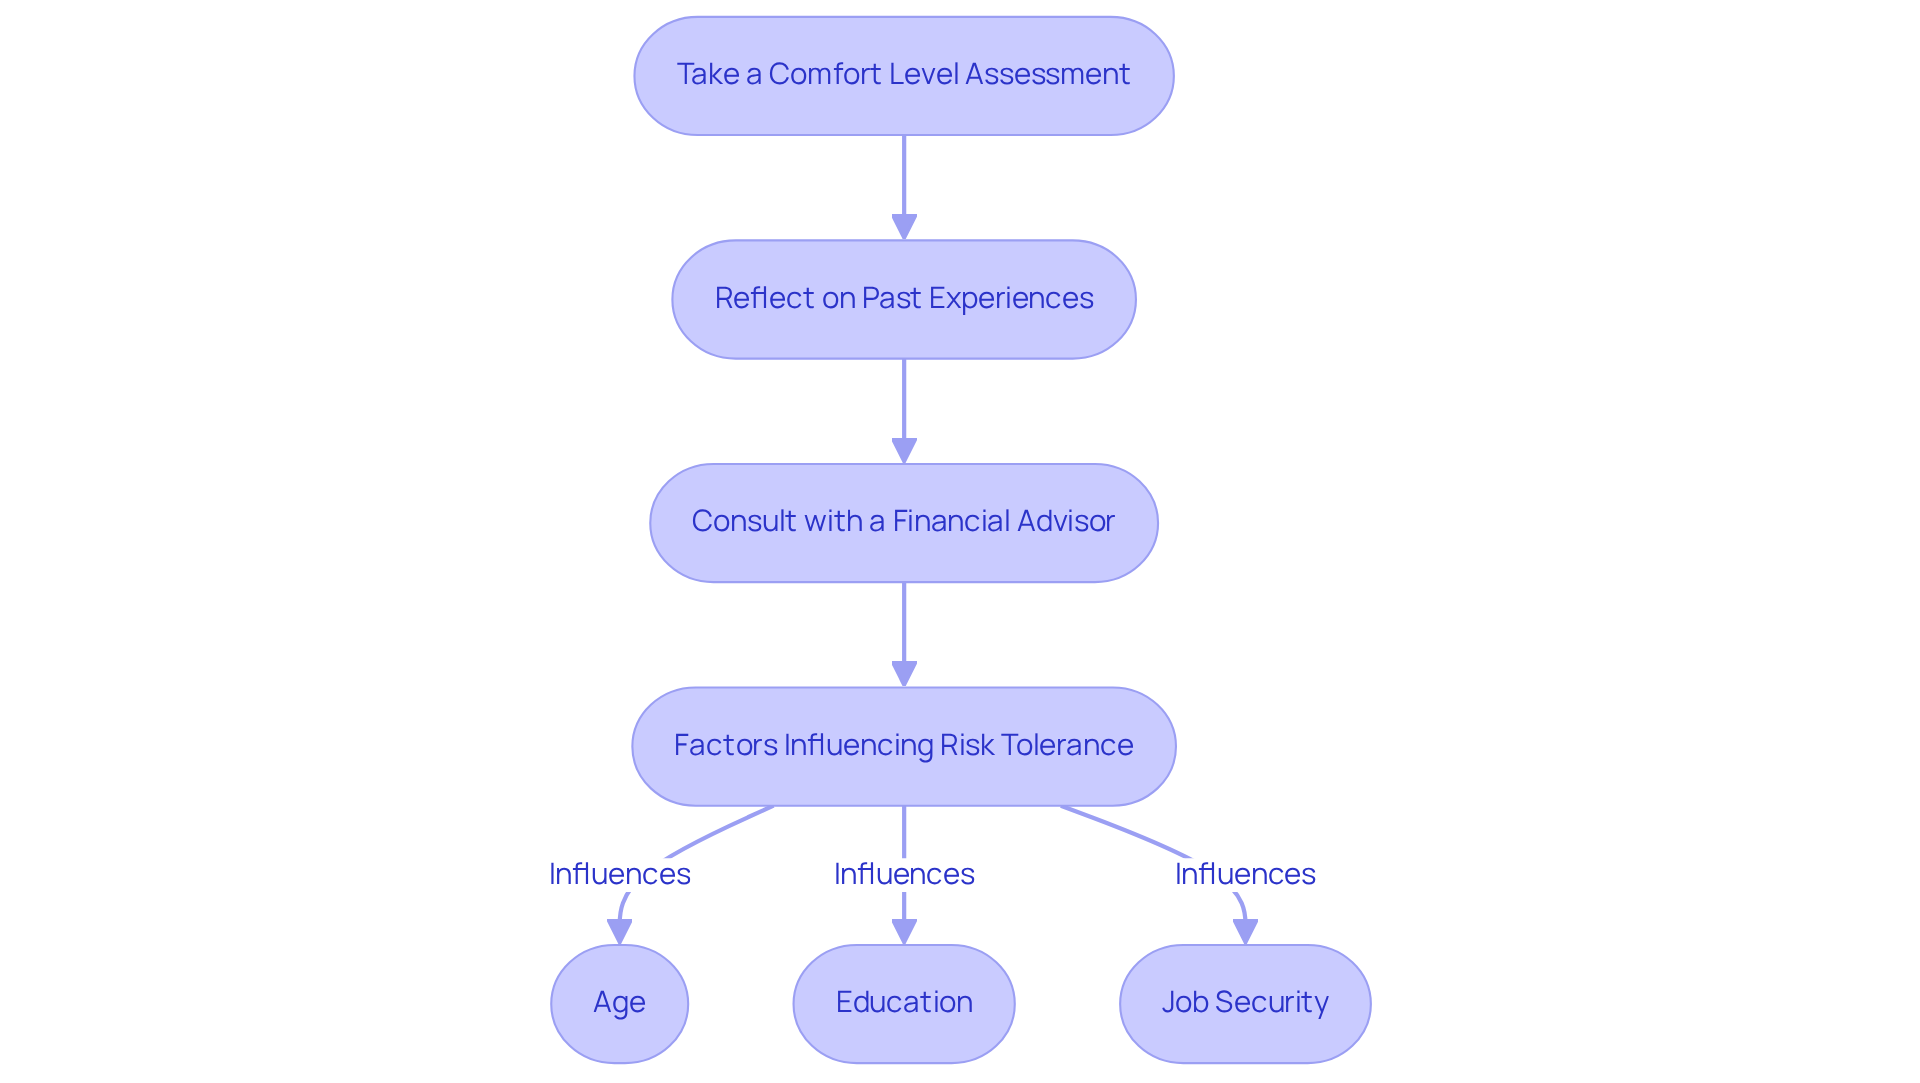
- Take a Comfort Level Assessment: Many institutions offer assessments that help you gauge your ease with uncertainty. These quizzes typically ask about your financial experience, goals, and how you feel when the market fluctuates.
- Reflect on Past Experiences: Think back to how you reacted during previous market downturns. Did you panic and sell, or did you hold steady? Your past actions can provide valuable insights into your tolerance for uncertainty.
- Consult with a Financial Advisor: A professional can help you understand your comfort profile and suggest investment strategies that fit your level of comfort.
Did you know that your comfort with uncertainty can change as you age or depending on your financial situation? For instance, statistics show that as people age, their tolerance for uncertainty tends to decrease by about 1.7% each year, leading to an estimated 20% drop over time. Additionally, factors like education and income can influence this tolerance; individuals with advanced degrees are 32% more likely to embrace risks compared to those with only a high school diploma. Interestingly, those facing potential job displacement are 19% more tolerant of uncertainty than those who are not.
When you understand your comfort with uncertainty, you can create an investment strategy that not only meets your financial goals but also supports your family’s peace of mind, allowing you to invest with confidence.
Explore Different Asset Classes
Imagine feeling secure about your family’s financial future while navigating the complexities of retirement planning. To create the best portfolio allocation for retirees, it’s essential to explore various asset classes that can support your family’s needs.
-
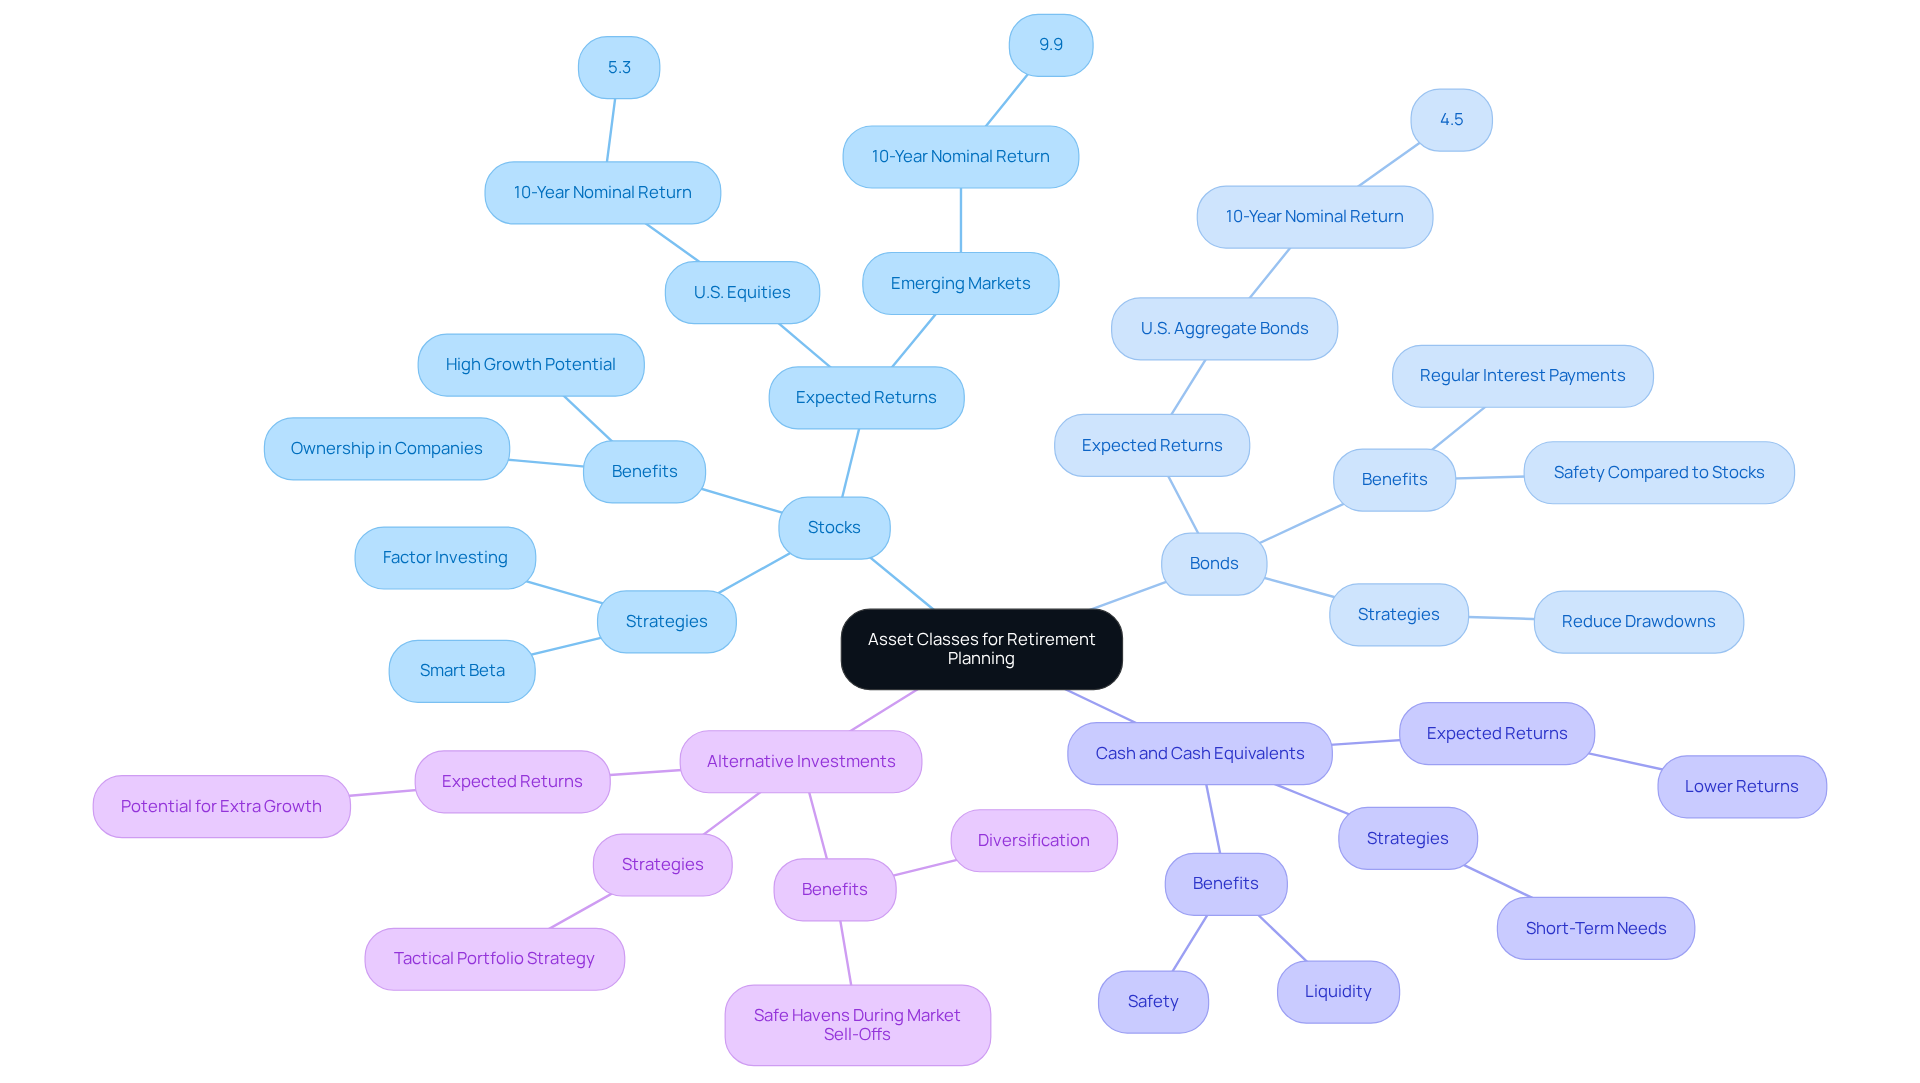
Stocks: Equities represent ownership in a company and can offer high growth potential. Current forecasts suggest a 10-year nominal return of approximately 5.3% for U.S. equities, with emerging markets expected to yield around 9.9%. However, navigating the ups and downs of the stock market can feel overwhelming, especially when planning for your family’s future. At Bright Advisers, we understand that choosing the right stocks can be daunting, so we use innovative strategies like smart beta and factor investing to help you make informed decisions while aiming to enhance returns and control exposure.
-
Bonds: Fixed-income securities provide regular interest payments and are generally considered safer than stocks. The expected nominal return for U.S. aggregate bonds is projected at 4.5% over the next decade. By incorporating bonds into your strategy, you can create a safety net that helps protect your family’s financial future during uncertain times. As stated by J.P. Morgan, bonds can reduce drawdowns in investment holdings, making them an essential element of managing uncertainty.
-
Cash and Cash Equivalents: This category includes savings accounts, money market funds, and short-term government bonds. These assets provide liquidity and safety but typically offer lower returns, making them suitable for short-term needs rather than long-term growth.
-
Alternative Investments: Consider diversifying further with real estate, commodities, or hedge funds. These can offer extra growth possibilities and lessen overall investment uncertainty. While alternative assets can improve returns, they also carry distinct challenges that should be thoroughly assessed. Bright Advisers’ Tactical Portfolio strategy leverages alternative asset classes that serve as safe havens during market sell-offs, enhancing overall portfolio resilience. This strategy contrasts with traditional approaches by focusing on assets that maintain value in volatile markets.
When you understand these asset categories and how they can work for your family, you can make choices that align with your dreams and values. This strategic approach is essential for effective retirement planning, particularly when it focuses on the best portfolio allocation for retirees, enhanced by Bright Advisers’ advanced technology and hyper-personalized financial strategies. Additionally, Bright Advisers offers a transparent, all-inclusive fee structure with no hidden fees, commissions, or trade fees, ensuring families can plan without unexpected costs. Please remember that previous performance does not assure future outcomes, and all financial activities involve uncertainties. Advisory services are provided through Lifeworks Advisors, a registered investment adviser. With the right strategy, you can ensure your family’s dreams are within reach, no matter what the future holds.
Create a Diversified Portfolio
Imagine navigating the complexities of financial planning while ensuring your family’s future is secure. Establishing a varied portfolio can help you achieve the best portfolio allocation for retirees, allowing you to handle uncertainty and reach your retirement objectives.
-
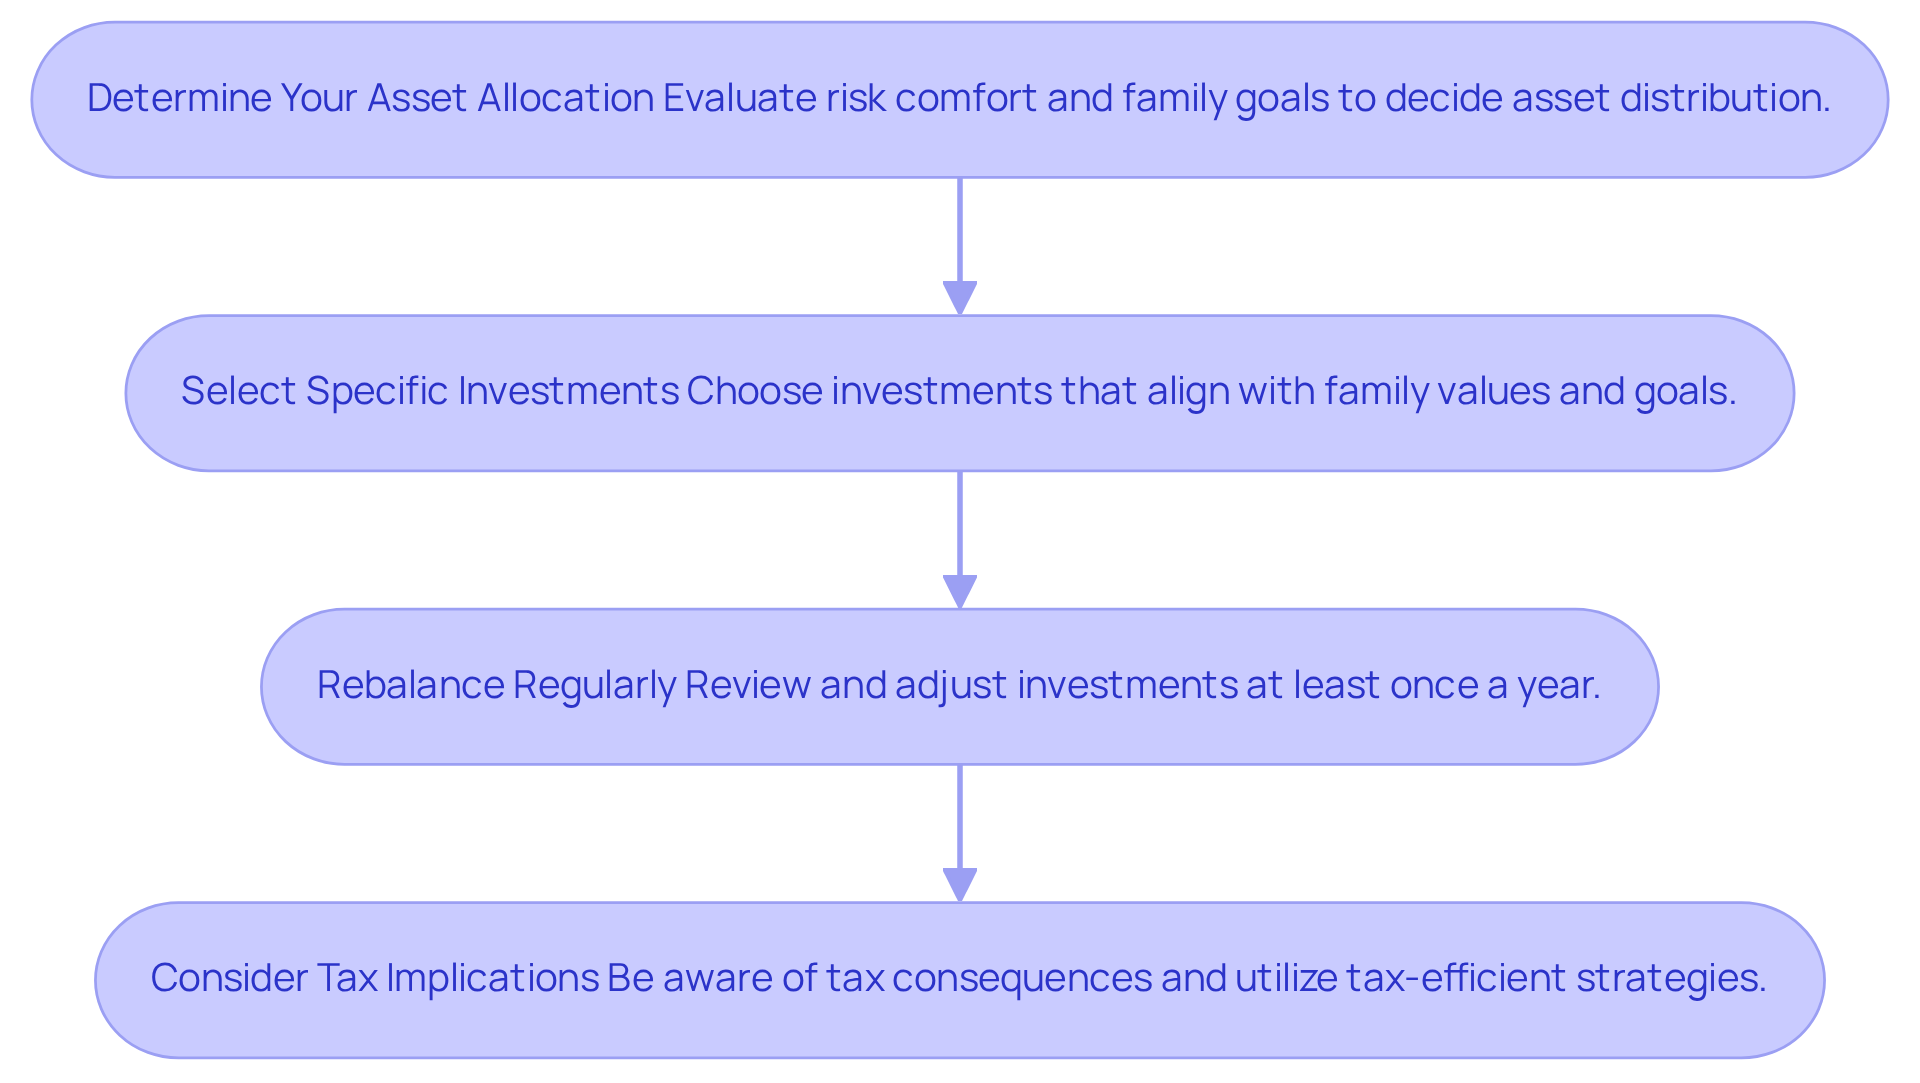
Determine Your Asset Allocation: It’s essential to evaluate your comfort with risk and your family’s goals to decide how to distribute your assets. Many families find a balanced approach, like 60% stocks and 40% bonds, helps ease financial stress while planning for their children’s education and their retirement. For instance, Jay and Emma discovered that this strategy allowed them to feel more secure about their financial future.
-
Select Specific Investments: Think about the investments that resonate with your family’s values and future goals. Low-cost index funds or ETFs can provide broad market exposure while keeping fees low. Emily and Mark, who wanted the freedom to choose whether to continue working, found that selecting options aligned with their long-term financial strategy gave them peace of mind.
-
Rebalance Regularly: As market conditions change, your portfolio may drift from its target allocation. Regularly reviewing and adjusting your investments-ideally at least once a year-ensures that your asset mix remains aligned with your goals. For example, if your stock allocation rises to 75% due to market performance, consider rebalancing back to your target. Allison and Brian learned the importance of rebalancing as they optimized their tax situation and secured their children’s future through education funding.
-
Consider Tax Implications: Be aware of the tax consequences associated with your financial choices. Utilizing tax-efficient accounts and strategies, such as tax-loss harvesting, can enhance your after-tax returns. Bright Advisers emphasizes the significance of tax planning, which can greatly influence your overall economic well-being. For example, retirees aged 90 often hold a significant portion of their assets in cash, which can have tax implications. Furthermore, Bright Advisers provides a clear, all-inclusive fee structure with no concealed charges, commissions, or trading fees, ensuring families comprehend the expenses related to their financial activities.
By following these steps, families can develop a varied investment strategy that not only mitigates uncertainty but also aligns with their long-term financial goals. To achieve a more stable path toward retirement income, diversification is crucial in establishing the best portfolio allocation for retirees, as it helps reduce the impact of market volatility. With the right guidance, you can confidently build a financial future that supports your family’s dreams and aspirations. Bright Advisers is committed to helping families like yours make wise wealth decisions and preserve wealth across generations.
Review and Adjust Your Portfolio Regularly
Imagine the peace of mind that comes from knowing that the best portfolio allocation for retirees is secure and adaptable to your family’s needs. To ensure the best portfolio allocation for retirees, regular reviews and adjustments of your portfolio are essential. Here’s how to effectively manage your retirement portfolio:
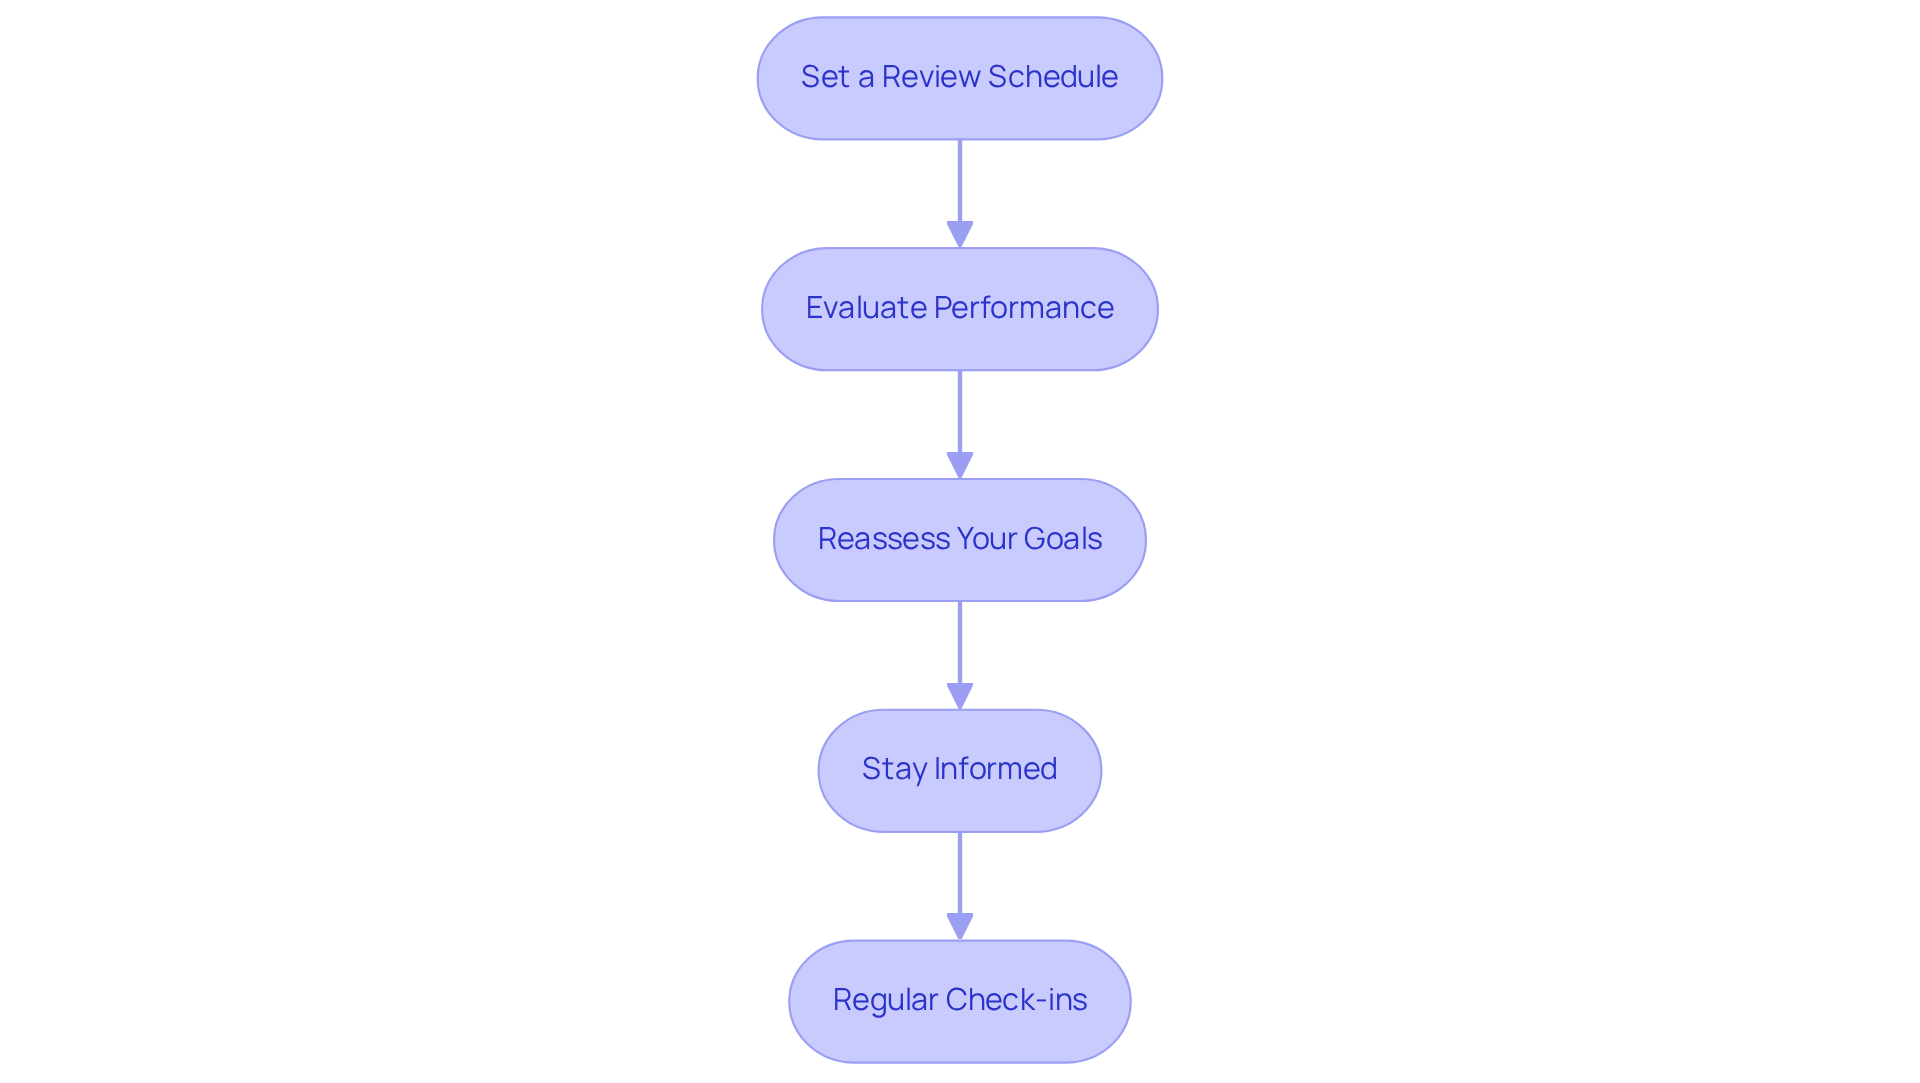
- Set a Review Schedule: Aim to review your portfolio at least annually. However, consider more frequent reviews of the best portfolio allocation for retirees if significant life changes occur, such as retirement, inheritance, or major expenses.
- Evaluate Performance: Assess how your investments have performed against your goals and benchmarks. Many parents share a common worry: the fear of running out of savings, which can feel overwhelming. It’s crucial to take proactive steps to ease that concern.
- Reassess Your Goals: As life circumstances evolve, so too may your financial goals. Consistently review your goals and modify your investments to align with these changes. For instance, the best portfolio allocation for retirees often includes those in their 60s typically holding 35% in U.S. stocks and 8.7% in international stocks.
- Stay Informed: With rising living costs, it’s understandable that many families feel anxious about their retirement plans. Staying informed can help you navigate these challenges with confidence.
By regularly checking in on your portfolio, you help ensure it stays aligned with your family’s financial goals and can adapt to life’s changes, ultimately guiding you towards the best portfolio allocation for retirees. For example, Emily and Mark, a couple in their mid-30s, collaborated with Bright Advisers to navigate their monetary situation. They gained a clearer insight into their financial landscape and developed a comprehensive plan that not only focused on enhancing their economic well-being but also provided them with the freedom to choose whether or not they continue working. Their experience highlights the significance of regular portfolio evaluations in achieving economic stability and educational preparedness for their family.
Furthermore, Bright Advisers highlights tax optimization strategies and financial approaches designed for families, ensuring that your financial plan is thorough and effective. Remember, past performance does not ensure future results, and all financial commitments are subject to risk. Bright Advisers provides advisory services through Lifeworks Advisors, a registered investment adviser, ensuring transparency and compliance. By taking these steps, you’re not just planning for retirement; you’re creating a secure future for your family, one decision at a time.
Conclusion
Imagine facing retirement with uncertainty about your financial future – it’s a common concern for many families. Understanding the best portfolio allocation for retirees is crucial for securing a stable financial future. When you spread your resources across different types of investments, you can reduce risk and work towards your financial goals. This guide has shown how important it is to understand your finances, know your comfort with risk, explore various investments, build a diverse portfolio, and check in on your investments regularly.
Key insights include evaluating your net worth, income sources, and expenses to create a solid financial foundation. Recognizing your risk tolerance helps tailor investment strategies that align with your comfort levels. Diversifying across stocks, bonds, and alternative investments not only mitigates risk but also enhances potential returns. Regular portfolio reviews ensure that your investments remain aligned with your evolving financial goals and market conditions.
In the end, getting your portfolio right is about more than just numbers; it’s about creating a plan that helps your family achieve their dreams. Engaging with a fiduciary advisor like Bright Advisers can provide the guidance needed to navigate these complexities, ensuring that your financial decisions are informed and aligned with your long-term objectives. Taking these steps today can empower you to create a legacy of security and happiness for your family.
Frequently Asked Questions
What is portfolio allocation and why is it important for retirees?
Portfolio allocation refers to how you distribute your resources across different investments like stocks, bonds, and cash. It is important for retirees as it helps manage risk and achieve financial goals.
What are the main asset classes to consider in portfolio allocation?
The main asset classes include equities (stocks), fixed income (bonds), and cash equivalents. Stocks typically drive growth, while bonds provide stability and income.
How does diversification benefit a retirement portfolio?
Diversification acts as a safety net, helping to protect finances during tough times. A well-diversified investment strategy can reduce losses during market downturns and can be about 20% less volatile than a non-diversified strategy.
What is the relationship between risk and return in investments?
Generally, higher potential returns come with higher risk. Understanding this connection is crucial for making informed investment choices. For example, in 2024, the S&P 500 had a 23% annual return, but missing the 10 best days resulted in only a 4% return, emphasizing the importance of staying invested.
How can I assess my financial situation for better portfolio allocation?
Start by calculating your net worth, listing all assets and liabilities. Identify income sources such as pensions and Social Security benefits, and create a budget for expected expenses in retirement. Understanding your financial situation is essential for effective portfolio allocation.
What should I include in my retirement budget?
Your retirement budget should include expected monthly and yearly expenses such as healthcare, housing, and leisure activities. The average annual spending for retirees over 65 is approximately $62,000.
How can I align my portfolio with my family’s financial goals?
Determine your short-term and long-term monetary objectives, such as travel plans or funding education for grandchildren. Understanding these goals will guide your financial choices and help achieve the best portfolio allocation.
What services does Bright Advisers offer to assist with portfolio allocation?
Bright Advisers utilizes innovative technology to create customized strategies that avoid costly mutual funds and ensure assets work effectively for your family’s financial objectives. They offer a transparent fee structure with no hidden fees or minimum account size.
List of Sources
- Understand Portfolio Allocation Basics
- What is the average asset allocation by age? (https://empower.com/the-currency/money/average-portfolio-mix-by-investor-age)
- Asset Allocation Guide: What Is It & How Does It Work? (https://merrilledge.com/article/what-is-asset-allocation)
- Asset Allocation Planning (https://troweprice.com/personal-investing/resources/planning/asset-allocation-planning.html)
- Assess Your Financial Situation
- The average net worth by age in America (https://empower.com/the-currency/life/average-net-worth-by-age)
- Average Retirement Income 2026: By Age, State & Source (https://randallwealthgroup.com/average-retirement-income)
- Average Net Worth by Age: Are You Rich? (https://kiplinger.com/retirement/average-net-worth-by-age-how-do-you-measure-up)
- Net Worth Percentile by Age (US 2026): Where Do You Rank? (https://richify.ai/us/data/average-net-worth-by-age)
- Average and median net worth by age | Fidelity (https://fidelity.com/learning-center/smart-money/average-net-worth-by-age)
- Identify Your Risk Tolerance
- How Much Does Risk Tolerance Change? – PMC (https://pmc.ncbi.nlm.nih.gov/articles/PMC4276321)
- From Risk Tolerance to Portfolio Choice: Insights from a Targeted High-Income Sample (https://financialplanningassociation.org/learning/publications/journal/JAN26-risk-tolerance-portfolio-choice-insights-targeted-high-income-sample-OPEN)
- Quotes on Risk Management • Novel Investor (https://novelinvestor.com/quote-category/risk-management)
- Decomposing the age effect on risk tolerance (https://sciencedirect.com/science/article/abs/pii/S1053535711001119)
- Explore Different Asset Classes
- Stocks vs. Bonds: Historical Returns, Risk, and the Case for Both | Darrow Wealth Management (https://darrowwealthmanagement.com/blog/stocks-vs-bonds-different-risks-returns)
- Vanguard Capital Markets Model® forecasts (https://corporate.vanguard.com/content/corporatesite/us/en/corp/vemo/vemo-return-forecasts.html)
- Experts Forecast Stock and Bond Returns: 2026 Edition (https://morningstar.com/markets/experts-forecast-stock-bond-returns-2026-edition)
- The Capital Markets Fact Book (https://sifma.org/research/statistics/fact-book)
- Create a Diversified Portfolio
- What is the average asset allocation by age? (https://empower.com/the-currency/money/average-portfolio-mix-by-investor-age)
- Portfolio diversification: What it is and how it works | Vanguard (https://investor.vanguard.com/investor-resources-education/portfolio-management/diversifying-your-portfolio)
- What’s the best asset allocation for retirees? (https://iese.edu/insight/articles/best-asset-allocation-retirees)
- What Is Portfolio Diversification? – Fidelity (https://fidelity.com/learning-center/investment-products/mutual-funds/diversification)
- Retirement Portfolio Assets: Allocation by Age (https://schwab.com/learn/story/retirement-portfolio-assets-allocation-by-age)
- Review and Adjust Your Portfolio Regularly
- 14 Must-Know Retirement Stats For 2026 – Carry (https://carry.com/learn/retirement-stats)
- What is the average asset allocation by age? (https://empower.com/the-currency/money/average-portfolio-mix-by-investor-age)
- 44 Retirement Statistics That Might Change Your Plan [2026] (https://getamplifylife.com/learn/blog/retirement-statistics)
- Average retirement savings by age | Fidelity (https://fidelity.com/learning-center/personal-finance/average-retirement-savings)
- Active at retirement: trading and performance of retirees (https://tandfonline.com/doi/full/10.1080/13504851.2026.2654784)

Kevin has advised high-income W-2 tech and biotech families since 2015, and leads the education-first Age Five Family Office from Brea, California.
Connect on LinkedIn → · About KevinThis is part of how we approach Investment & Risk Management for high-income W-2 families at Bright Advisers.
Keep reading