

Key Highlights
- Incentive Stock Options (ISOs) can help families save on taxes but may trigger Alternative Minimum Tax (AMT) when exercised.
- The difference between the exercise price and fair market value (FMV) of ISOs is treated as income for AMT purposes.
- AMT exemption thresholds in 2026 are $90,100 for single filers and $140,200 for married couples filing jointly.
- Implementing an ISO AMT carryforward strategy can help families manage AMT exposure by exercising options over multiple years.
- Families can avoid AMT complications by selling shares immediately after exercising ISOs.
- AMT credits can offset future regular tax obligations, and families should report this on IRS Form 8801.
- Effective strategies include timing income recognition, spreading ISO exercises, and consulting a tax advisor.
- Common mistakes in AMT planning include neglecting record-keeping, exercising ISOs without a plan, and ignoring future tax projections.
Introduction
Many families feel lost when faced with the complexities of financial planning, especially when it comes to Incentive Stock Options and Alternative Minimum Tax. But what if there was a way to turn that confusion into clarity and savings? The ISO AMT carryforward strategy could be your family’s key to managing tax liabilities more effectively. It’s important to understand how families can leverage this strategy to avoid pitfalls and truly maximize their financial well-being.
Understand ISOs and AMT Fundamentals
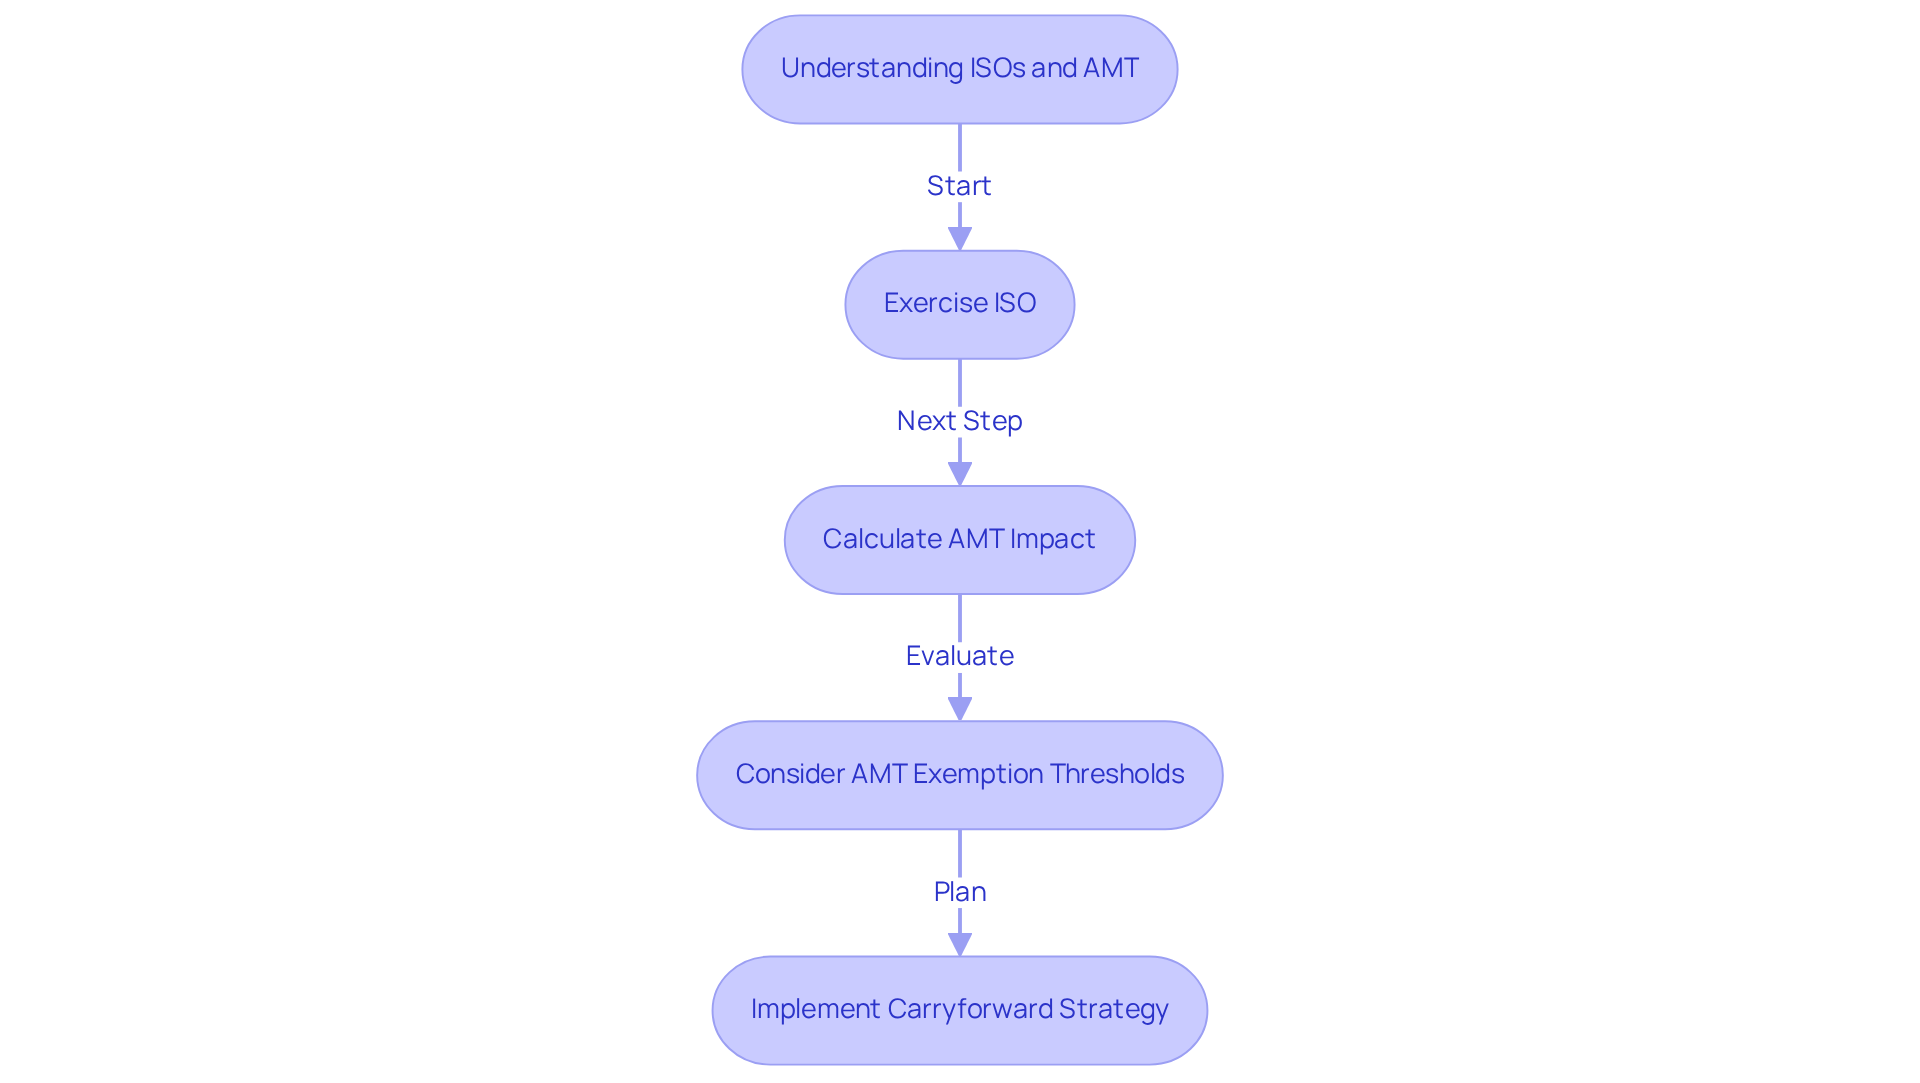
Imagine navigating the complexities of your family’s financial future while juggling the challenges of everyday life – this is where understanding Incentive Stock Options (ISOs) becomes essential. ISOs can be a powerful tool that helps your family save on taxes when used wisely. However, it’s important to know that when you exercise an ISO, the difference between the exercise price and the fair market value (FMV) of the stock is treated as income for AMT purposes. This might create unexpected tax challenges, especially for families trying to make the most of their hard-earned income.
Understanding how ISOs trigger AMT is crucial for households to avoid unforeseen tax burdens and to effectively plan for their financial futures with an ISO AMT carryforward strategy. For instance, if an employee exercises ISOs and holds the shares, they may face AMT on the spread between the exercise price and the FMV. This can create cash flow challenges if they owe taxes without having realized any gains through a sale.
In 2026, the AMT exemption thresholds will be set at $90,100 for single filers and $140,200 for married couples filing jointly. Surpassing these thresholds can greatly influence tax obligations, making it crucial for families to plan their ISO exercises. For example, employees can minimize AMT exposure by implementing an ISO AMT carryforward strategy, which involves exercising a portion of their options each year to keep their AMT income below the exemption threshold.
Case studies illustrate the importance of timing in managing AMT implications. Employees who sell shares immediately after exercising ISOs can avoid AMT complications, while those who hold shares may incur unexpected tax liabilities. When you grasp these concepts, you can confidently steer your family through the complexities of ISOs and AMT, making choices that truly support your financial dreams. Bright Advisers offers customized strategies, such as staggered exercises and prompt sales, to assist families like Allison and Brian in securing their financial futures while effectively managing tax implications. By taking proactive steps today, you can ensure that your family’s financial journey is as smooth as possible, avoiding surprises along the way.
Explore AMT Credit Carryforward Mechanics
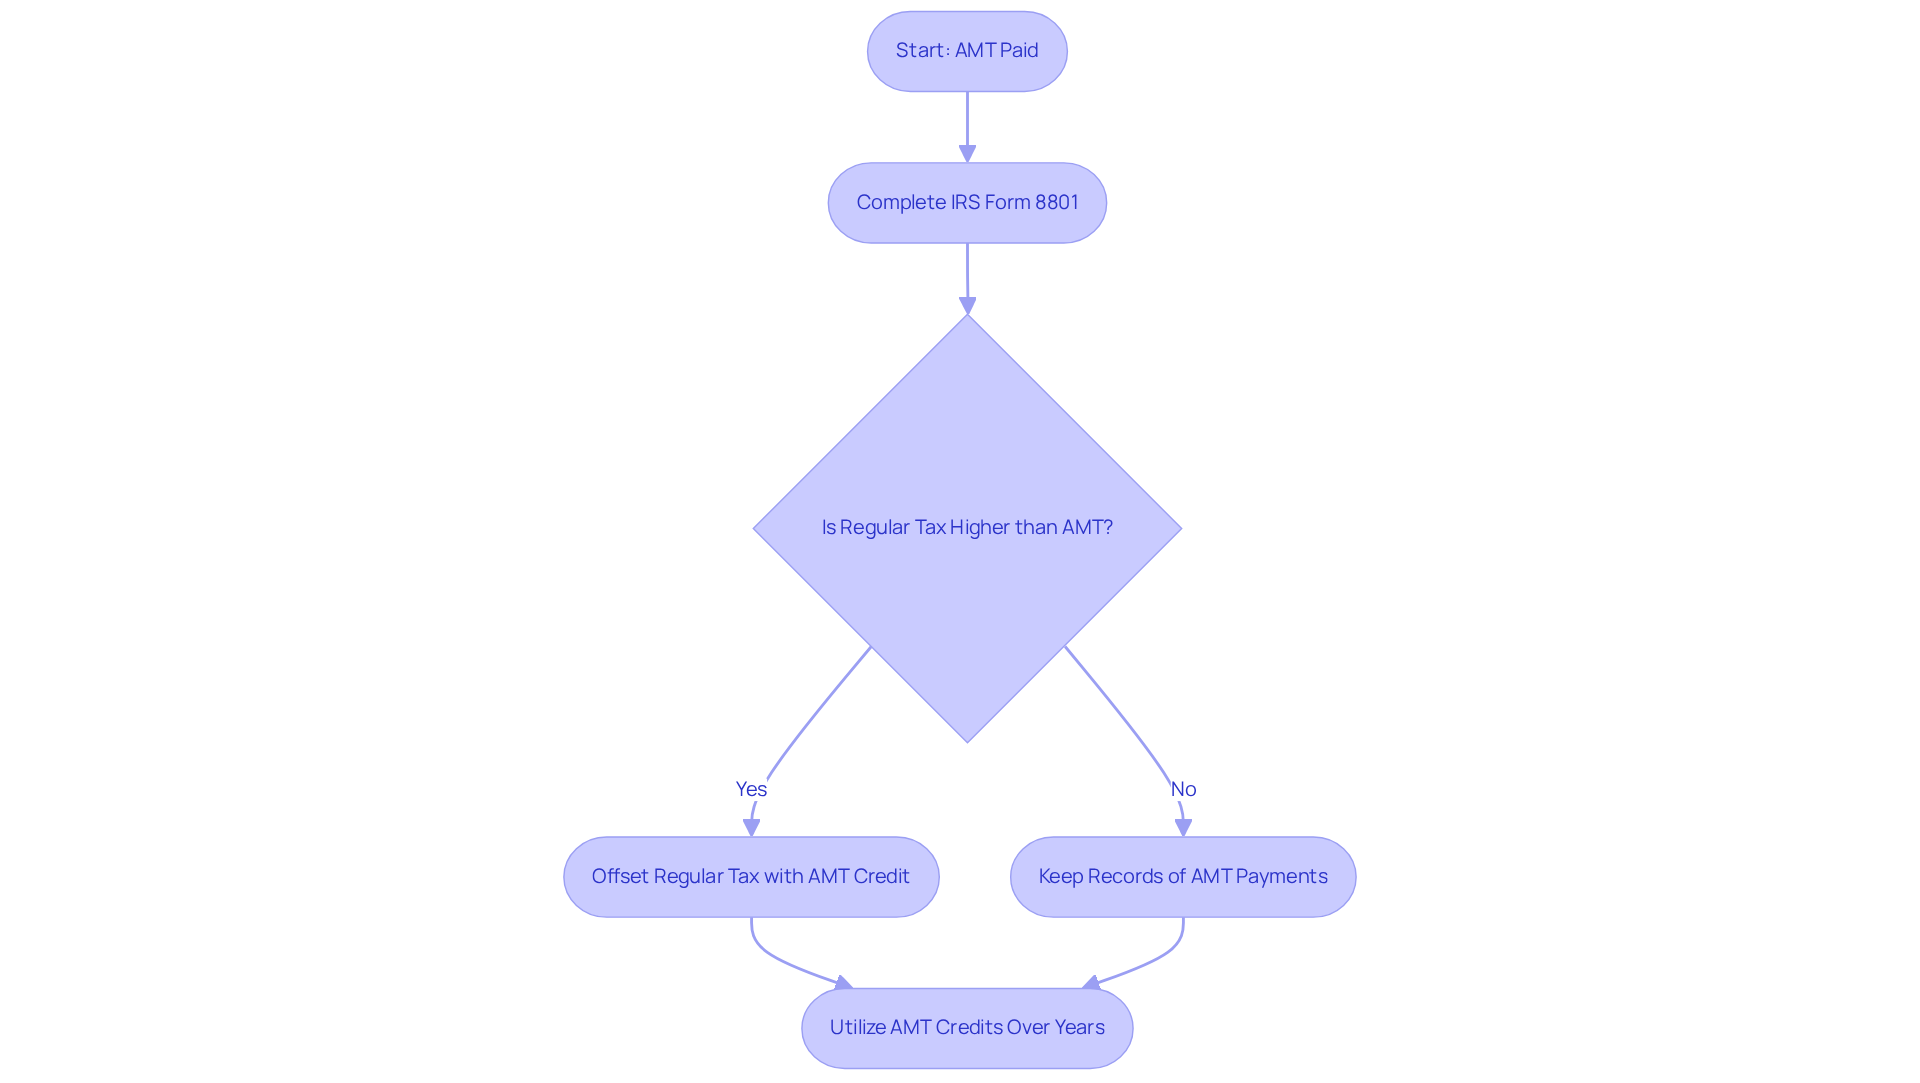
Imagine facing unexpected tax bills while trying to provide for your family – it’s a worry many parents share. When households pay Alternative Minimum Tax (AMT) because of exercising Incentive Stock Options (ISOs), there’s a silver lining: they may qualify for an iso amt carryforward strategy that can help offset future regular tax obligations. You’ll report this benefit on IRS Form 8801, which helps you recover the AMT you paid when your regular tax is higher than your AMT. Keeping precise records of AMT payments and submitting Form 8801 each year until the allowance is depleted is key. The good news? AMT benefits don’t expire, allowing you to utilize an iso amt carryforward strategy over several years to maximize your tax savings.
For example, let’s say a household exercised ISOs with a fair market value of $10 per share and an exercise price of $2. After selling the shares at that fair market value, they faced a regular tax of $95,200, which was completely offset by their AMT benefit, resulting in no tax obligation. This shows how effective planning can lead to significant tax efficiencies.
Think about timing your stock sales wisely; it can really boost the benefits of your AMT credits. For instance, selling appreciated stock in years when your regular tax liability exceeds AMT can help you make the most of available credits. When you understand how AMT works and use smart strategies, you can make tax planning feel a lot less overwhelming and improve your family’s financial health. With the right strategies, you can turn tax complexities into opportunities for your family’s financial future.
Implement Effective AMT Credit Strategies
Imagine feeling confident about your family’s financial future, even amidst the complexities of AMT and tax planning. Let’s explore some thoughtful strategies to help your family make the most of AMT credits:
-
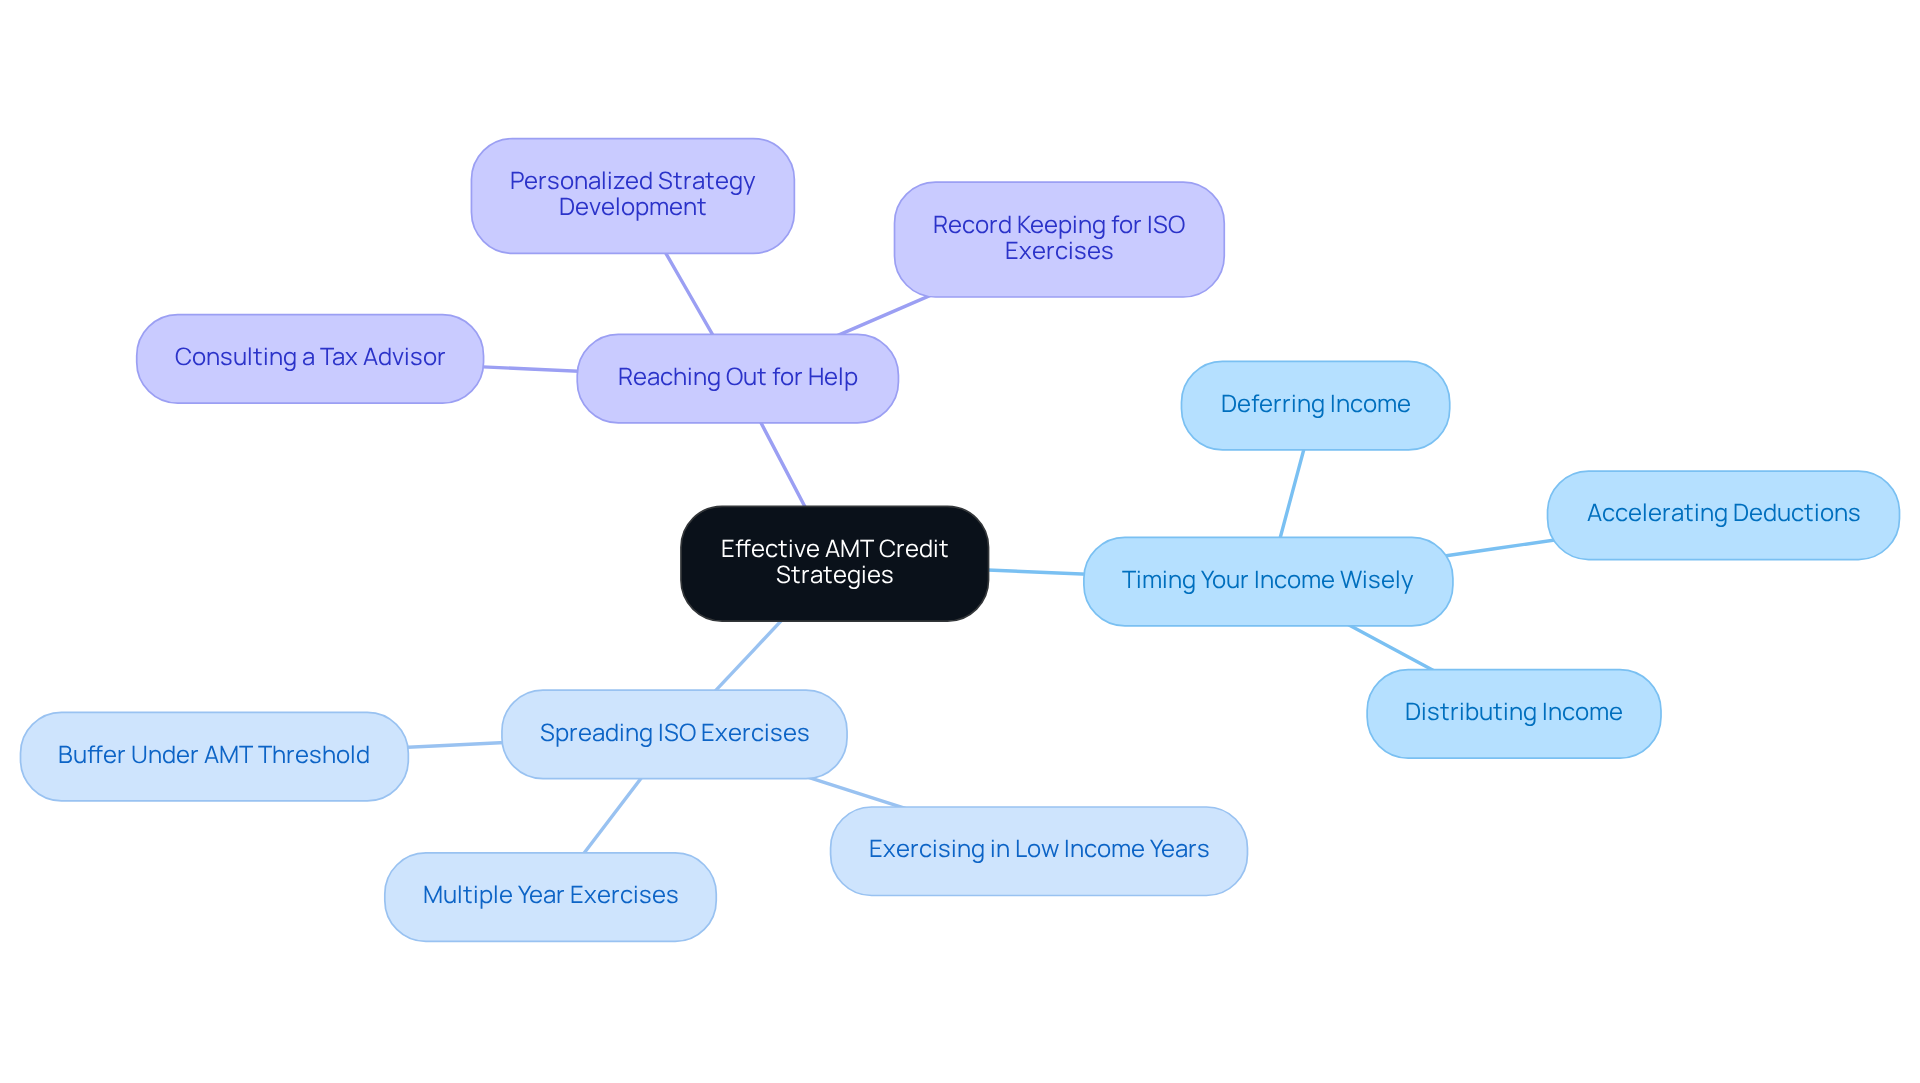
Timing Your Income Wisely: Think about how you can time your income recognition. This way, you can help ensure that your regular tax liability stays above your AMT in the years to come. For instance, deferring income or accelerating deductions can be beneficial. Distributing income wisely can also prevent hitting those AMT thresholds.
-
Spreading ISO Exercises: Instead of exercising all ISOs in one year, consider spreading those exercises over multiple years. This approach can reduce your AMT exposure and help you take full advantage of AMT benefits. Exercising ISOs during lower income years can create a buffer under the AMT threshold, effectively lowering your tax liabilities.
-
Reaching Out for Help: We recommend connecting with a tax advisor who truly understands AMT and ISOs. They can work with you to create a personalized strategy that fits your family’s unique financial goals. Consulting a qualified tax advisor is essential for tailored strategies to manage AMT and ISO exercises effectively.
By applying these strategies, you can enhance your tax situation and ensure your family is making the most of the iso amt carryforward strategy for AMT benefits. Remember, keeping thorough records of ISO exercises is crucial for linking sales to previous AMT payments, which can help recover funds in future years. By taking these steps, you can ensure your family is not only protected but also positioned for a brighter financial future.
Avoid Common Mistakes in AMT Planning
Imagine the stress of realizing you’ve been overpaying your taxes due to simple mistakes in your financial planning. Families should be cautious of the following common mistakes in AMT planning:
-
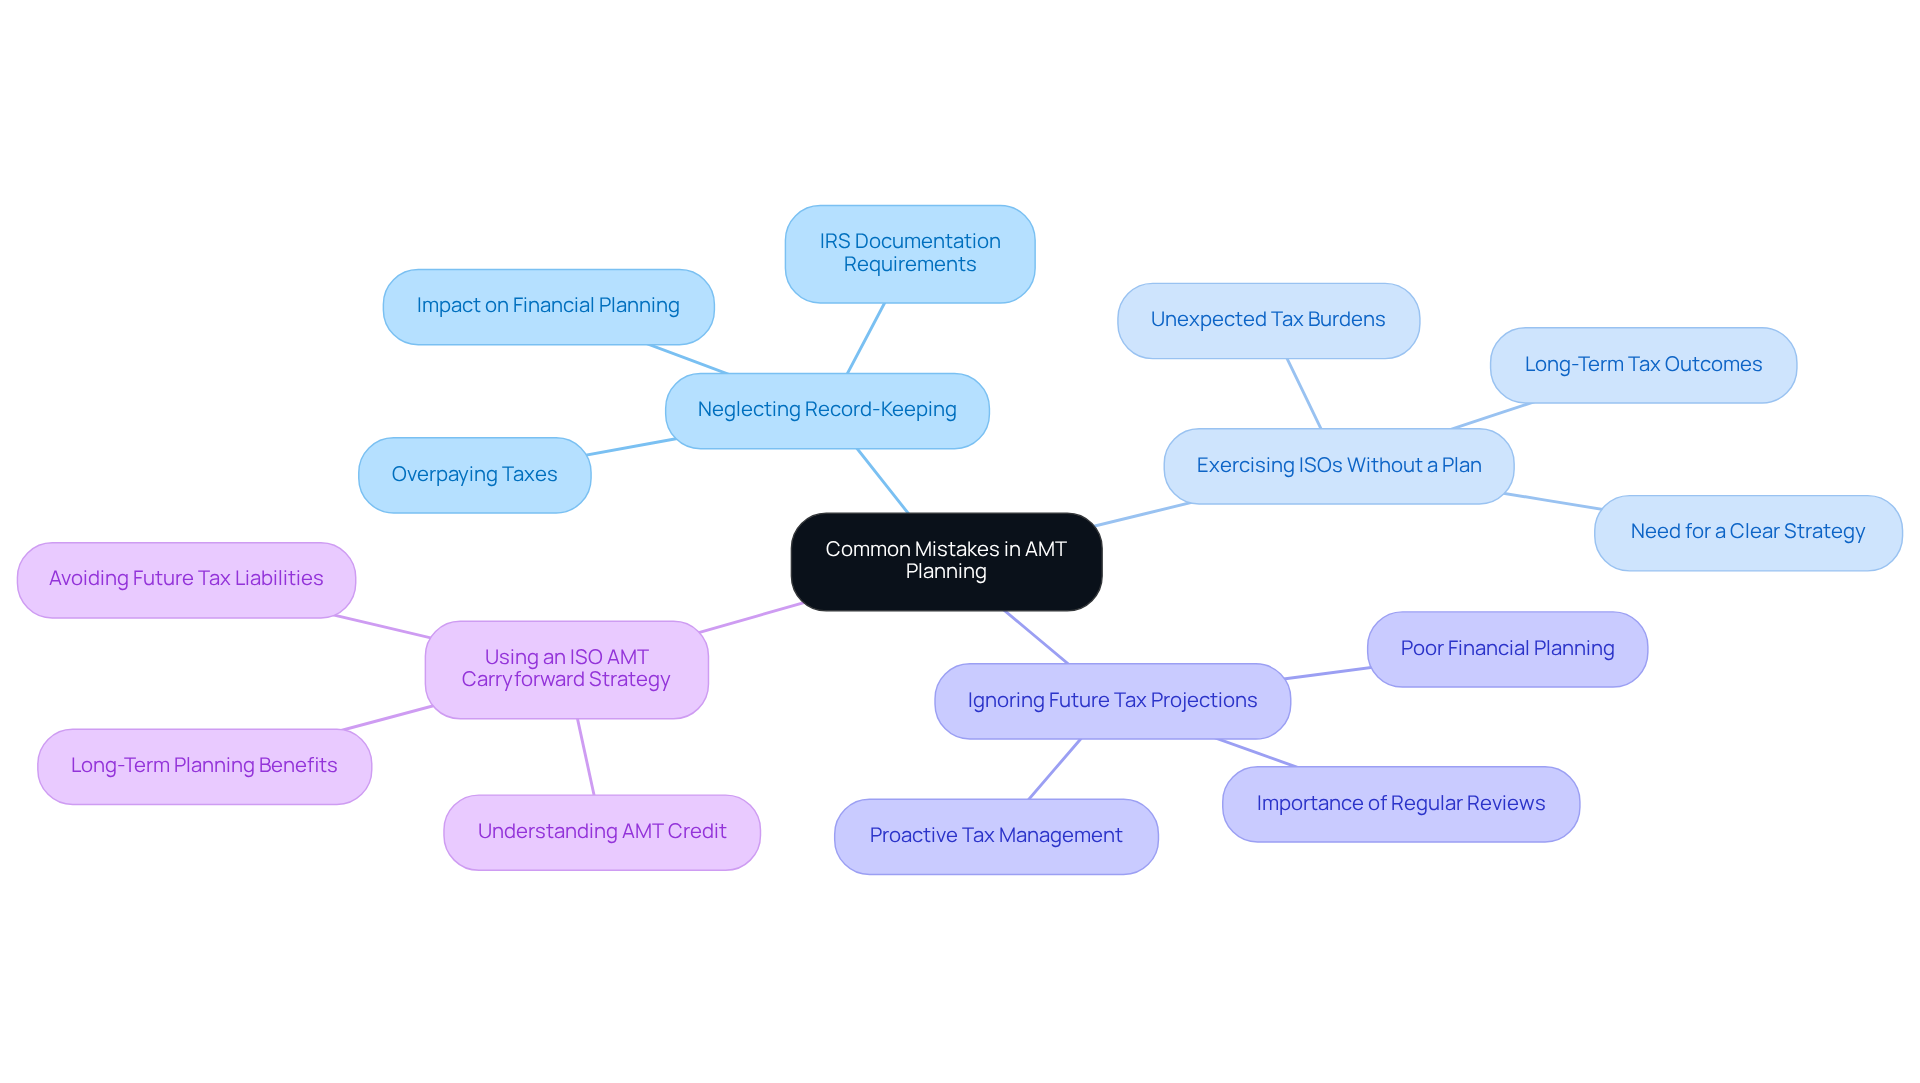
Neglecting Record-Keeping: Many families have found themselves overpaying their taxes by nearly $3,000 a year just because they weren’t keeping good records. The IRS recommends retaining documentation for seven years from the date of the return on which they applied the AMT credit. For instance, Allison and Brian, who sought guidance from Bright Advisers, learned that diligent record-keeping was essential in optimizing their tax situation, ultimately saving them significant amounts and securing their children’s education.
-
Exercising ISOs Without a Plan: Think about exercising your stock options without a solid plan – it’s a recipe for unexpected tax surprises. A clear strategy is essential before exercising options to avoid unforeseen tax burdens. Bright Advisers emphasizes the importance of having a comprehensive plan in place to navigate these complexities effectively.
-
Ignoring Future Tax Projections: Not considering future income and tax projections can lead to poor planning. Regularly reviewing financial situations and adjusting strategies accordingly is crucial for effective AMT management. Allison and Brian’s experience illustrates how proactive tax planning can lead to a more secure financial future, allowing them to retire sooner.
By avoiding these mistakes, households can better manage their AMT liabilities and improve their overall tax outcomes using an iso amt carryforward strategy. Proper planning and diligent record-keeping can significantly enhance financial clarity and reduce the risk of penalties during audits. Together, we can navigate this journey and make sure your family’s financial future is as bright as it can be.
Conclusion
Imagine navigating the complexities of Incentive Stock Options and the Alternative Minimum Tax without feeling overwhelmed. Understanding these intricacies is essential for families aiming to secure their financial futures. When families understand the ISO AMT carryforward strategy, they can better manage tax burdens and find ways to save money. This approach helps families avoid surprise tax bills and make choices that support their financial dreams.
Throughout this article, we’ve shared key strategies, like the importance of timing ISO exercises and keeping detailed records. These insights highlight the need for careful planning to avoid common pitfalls that can lead to overpaying taxes. Families like Allison and Brian show us how strategic planning can lead to real financial benefits, reminding us that these practices can truly make a difference.
Navigating AMT and ISOs can feel daunting, but with the right approach, families can feel confident and prepared. By implementing the strategies discussed, families can turn potential tax challenges into opportunities for financial growth. Engaging with a trusted advisor, like Bright Advisers, can enhance this process, ensuring families are equipped to handle their financial landscape. By taking these proactive steps, families can not only secure their financial future but also create a lasting legacy for their loved ones.
Frequently Asked Questions
What are Incentive Stock Options (ISOs)?
Incentive Stock Options (ISOs) are a type of employee stock option that can provide tax benefits when exercised correctly, allowing families to save on taxes.
How do ISOs affect Alternative Minimum Tax (AMT)?
When you exercise an ISO, the difference between the exercise price and the fair market value (FMV) of the stock is treated as income for AMT purposes, which can lead to unexpected tax challenges.
What is the significance of AMT exemption thresholds?
In 2026, the AMT exemption thresholds will be $90,100 for single filers and $140,200 for married couples filing jointly. Exceeding these thresholds can significantly impact tax obligations.
How can families minimize AMT exposure when exercising ISOs?
Families can minimize AMT exposure by implementing an ISO AMT carryforward strategy, which involves exercising a portion of their options each year to keep their AMT income below the exemption threshold.
What are the potential cash flow challenges associated with ISOs?
If an employee exercises ISOs and holds the shares, they may face AMT on the spread between the exercise price and the FMV, creating cash flow challenges if they owe taxes without having realized any gains through a sale.
What strategies can help manage AMT implications effectively?
Strategies such as staggered exercises and prompt sales can help families manage AMT implications and avoid unexpected tax liabilities.
Why is timing important when exercising ISOs?
Timing is crucial because employees who sell shares immediately after exercising ISOs can avoid AMT complications, while those who hold shares may incur unexpected tax liabilities.
How can Bright Advisers assist families with ISOs and AMT?
Bright Advisers offers customized strategies to help families secure their financial futures while effectively managing tax implications related to ISOs and AMT.
List of Sources
- Understand ISOs and AMT Fundamentals
- Alternative Minimum Tax (AMT): How It Works for Stock Options in 2026 (https://esofund.com/blog/alternative-minimum-tax-amt)
- Stock Options and the Alternative Minimum Tax (AMT) (https://nceo.org/articles/stock-options-alternative-minimum-tax-amt)
- Incentive Stock Options Tax Impacts (https://team.monetagroup.com/team/duff-torney/who-we-serve/executives/resources-for-executives/incentive-stock-options-tax-impacts)
- How ISOs Trigger Alternative Minimum Tax in 2026 (https://wealthgenadvisor.com/how-isos-trigger-alternative-minimum-tax-in-2026)
- Incentive Stock Options (ISO): How ISOs Work (https://carta.com/learn/equity/stock-options/iso)
- Explore AMT Credit Carryforward Mechanics
- Alternative minimum tax optimization methods (https://instead.com/resources/blog/alternative-minimum-tax-optimization-methods)
- The Perpetual Burden of Carryover Substantiation: Lessons on AMT Credits and Recordkeeping from Beacom v. Commissioner — Current Federal Tax Developments (https://currentfederaltaxdevelopments.com/blog/2026/8/11/the-perpetual-burden-of-carryover-substantiation-lessons-on-amt-credits-and-recordkeeping-from-beacom-v-commissioner)
- AMT Credit Carryforward: How To Use It for Tax Savings (https://brightonjones.com/blog/amt-credit-carryforward)
- Alternative Minimum Tax (AMT) Credit Examples | TAN Wealth Management | Certified Financial Planner (CFP®) San Francisco | Advisor (https://tanphan.com/blog/alternative-minimum-tax-amt-credit-examples)
- Implement Effective AMT Credit Strategies
- Planning for the AMT (https://thetaxadviser.com/issues/2025/mar/planning-for-the-amt)
- Strategies to Reduce AMT on Stock Options – Phoenix Strategy Group (https://phoenixstrategy.group/blog/strategies-reduce-amt-stock-options)
- ISO Taxes: How AMT and AMT Credits Work + Avoiding AMT on ISO Exercises | Darrow Wealth Management (https://darrowwealthmanagement.com/blog/tax-isos-amt-credits)
- AMT Credit Carryforward: How To Use It for Tax Savings (https://brightonjones.com/blog/amt-credit-carryforward)
- Alternative minimum tax optimization methods (https://instead.com/resources/blog/alternative-minimum-tax-optimization-methods)
- Avoid Common Mistakes in AMT Planning
- Why Keeping Good Records Can Save You More Than You Think (https://taxforu.com/importance-of-recordkeeping-benefits)
- Alternative Minimum Tax: Common Questions (https://turbotax.intuit.com/tax-tips/irs-tax-return/alternative-minimum-tax-common-questions/L50YotKHP)
- What is the AMT credit? — Secfi (https://secfi.com/learn/amt-credit)
- The Perpetual Burden of Carryover Substantiation: Lessons on AMT Credits and Recordkeeping from Beacom v. Commissioner — Current Federal Tax Developments (https://currentfederaltaxdevelopments.com/blog/2026/8/11/the-perpetual-burden-of-carryover-substantiation-lessons-on-amt-credits-and-recordkeeping-from-beacom-v-commissioner)
- The Importance of Record Keeping for Taxes: A Comprehensive Guide — Tax Preparation, Tax Planning & Bookkeeping Services | Lutz Tax Services (https://tax-prep-services.com/blog/the-importance-of-record-keeping-for-taxes-a-comprehensive-guide)

Kevin has advised high-income W-2 tech and biotech families since 2015, and leads the education-first Age Five Family Office from Brea, California.
Connect on LinkedIn → · About KevinThis is part of how we approach Tax Management for high-income W-2 families at Bright Advisers.
Keep reading