

Key Highlights:
- Capital gains arise from selling assets for more than their purchase price, impacting wealth management.
- Long-term capital gains, from assets held over a year, are taxed at lower rates than short-term gains, which are taxed as ordinary income.
- In 2025, long-term capital gains tax rates are 0%, 15%, or 20%, depending on taxable income thresholds for individuals and married couples.
- Families can optimise tax liabilities by utilising tax-advantaged accounts like 401(k)s and IRAs, which postpone taxes on investment returns.
- Tax-loss harvesting allows families to offset gains by selling underperforming investments, potentially lowering taxable income.
- Married couples can exclude up to $500,000 in profits from the sale of their primary residence under certain conditions.
- Strategically timing asset sales based on income levels can help families remain within favourable tax brackets.
- Understanding capital gains taxes can inform investment strategies and enhance after-tax returns, promoting better financial outcomes.
Introduction
Understanding the complexities of capital gains taxes is crucial for families looking to secure their financial future. These taxes can have a significant impact on investment decisions and overall wealth accumulation. It’s important to grasp how long-term capital gains are taxed.
Imagine if there was a way to enhance your investment returns while minimizing tax liabilities. By exploring effective strategies to navigate the long-term capital gains tax bracket, families can optimize their financial plans and potentially save thousands.
This article delves into the key aspects of capital gains, offering insights and actionable strategies to help families thrive in an ever-changing financial landscape. Together, we can navigate this journey, ensuring that your family’s financial goals are met with understanding and support.
Define Capital Gains: Understanding the Basics
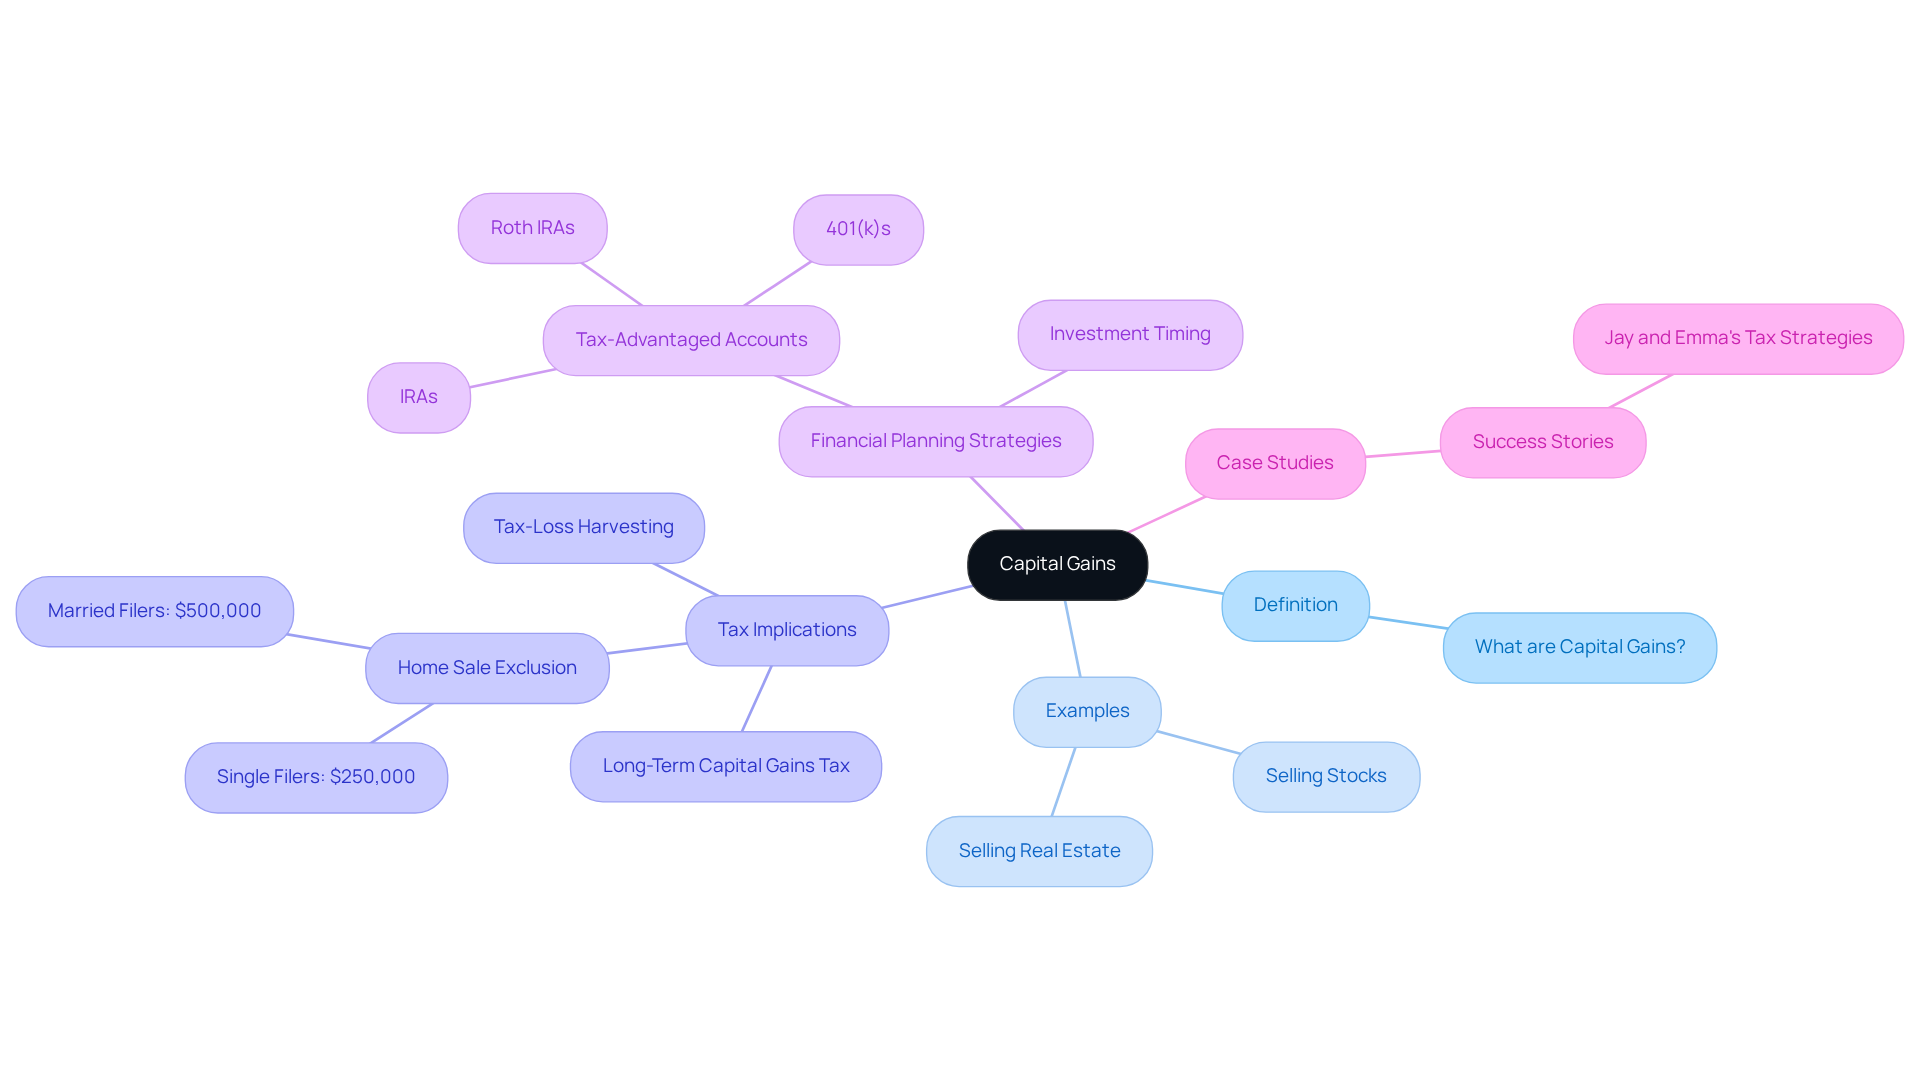
Understanding capital profits is essential for families looking to build and protect their wealth. These profits come from selling an asset for more than what you paid for it, whether it’s stocks, bonds, or real estate. For example, if you buy shares for $1,000 and sell them later for $1,500, you’ve made a profit of $500. However, it’s important to remember that this profit falls within the long term capital gains tax bracket and is subject to taxation by the IRS. Knowing how profits work can help you manage your family’s financial planning more effectively.
Imagine if you could plan your investments in a way that minimizes your tax liabilities. By using tax-advantaged accounts like 401(k)s or IRAs, you can postpone taxes on your investment returns until you withdraw the funds. This strategy can significantly enhance your long-term financial outlook. Additionally, if you’re selling your home, you might qualify for the home sale exclusion, allowing you to exclude up to $250,000 in profits if you’re single, or up to $500,000 if you’re married, provided you meet certain ownership and residency requirements.
Financial advisors emphasize the importance of understanding profit increases in your household financial strategies. By understanding how profit taxes work, including the long term capital gains tax bracket, you can make informed decisions about when to sell assets and how to structure your investments. This knowledge not only helps with tax efficiency but also aligns with your broader financial goals, ensuring you can prioritize your family’s needs while securing your financial future.
Take, for instance, the success stories of families like Jay and Emma, who worked with Bright Advisers to improve their tax strategies. By understanding investment profits, they were able to navigate their financial landscape more effectively. Techniques like tax-loss harvesting can also help offset profits, providing additional avenues for managing taxes.
As you consider your financial planning, pay attention to potential changes to the long term capital gains tax bracket, as these could impact your strategies. Remember, we’re here for you, and together, we can navigate this journey toward a secure financial future for your family.
Differentiate Between Short-Term and Long-Term Capital Gains
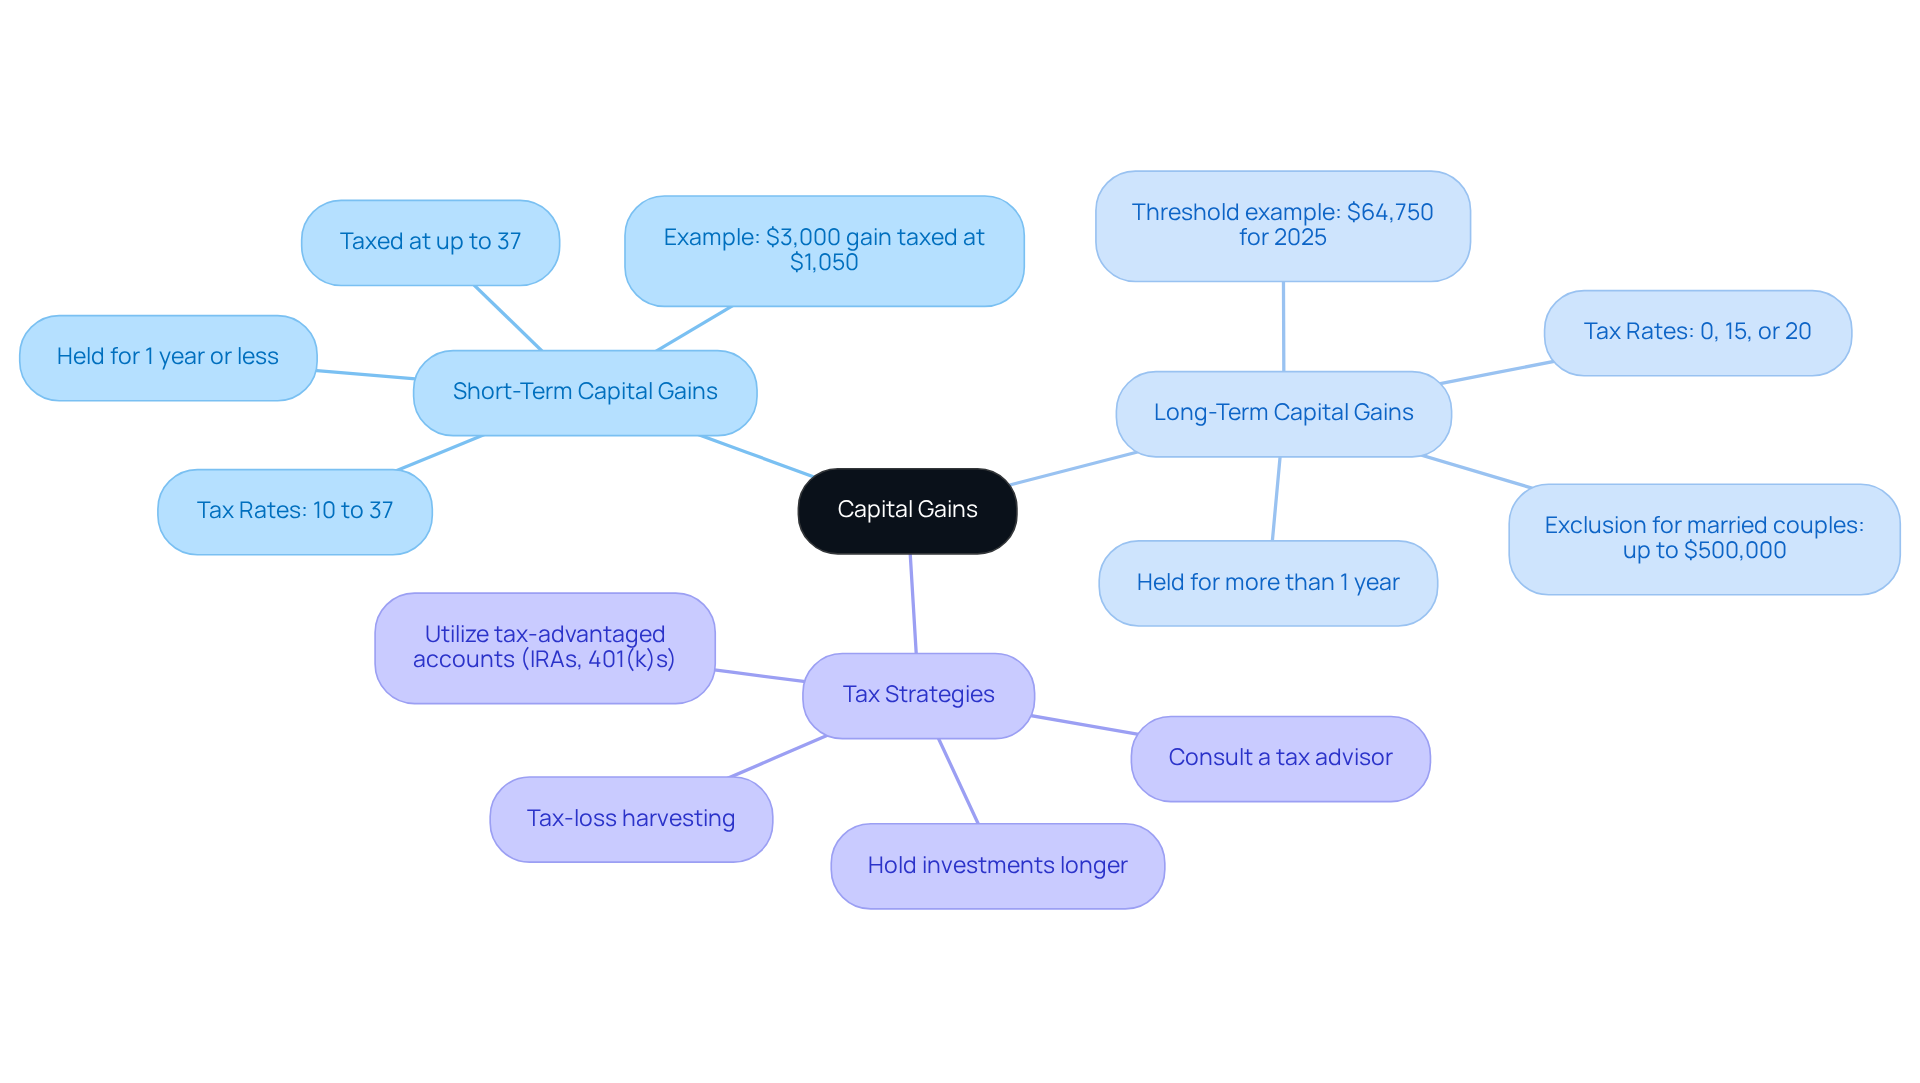
Understanding capital profits can feel overwhelming, especially for young parents trying to secure their family’s future. It’s essential to know that these profits fall into two categories: short-term and long-term, with the long-term capital gains tax bracket affecting the tax implications of the latter. Short-term profits, which come from assets held for a year or less, are taxed at regular income rates that can soar up to 37%. On the other hand, the long-term capital gains tax bracket, applicable to assets held for more than a year, enjoys lower tax rates of 0%, 15%, or 20%, depending on your taxable income.
Imagine if you could save significantly on taxes just by holding onto your investments a little longer. For families, this distinction is crucial. Selling a stock after just six months could result in falling into a much higher long-term capital gains tax bracket compared to if you had held it for over a year. For instance, the threshold for the long-term capital gains tax bracket at a 0% rate for head of household filers increased from $63,000 in 2024 to $64,750 in 2025. This means families like Allison and Brian might avoid profit taxes on their investments if their earnings stay within this range.
Moreover, married couples filing jointly can exclude up to $500,000 of profit from the long-term capital gains tax bracket when selling their primary residence. This is particularly relevant for families considering a home sale. By timing their investments wisely and employing tax optimization strategies—like holding assets longer and planning the sale of their home—families can significantly improve their financial situation. This way, they can keep more of their hard-earned profits for future needs.
Together, we can navigate these complexities. By utilizing expert tax strategies, families like Allison and Brian can manage these intricacies effectively, ensuring they enhance their wealth growth and protect their financial future. Remember, we’re here for you, ready to support you on this journey toward financial security.
Explore Long-Term Capital Gains Tax Rates for 2025
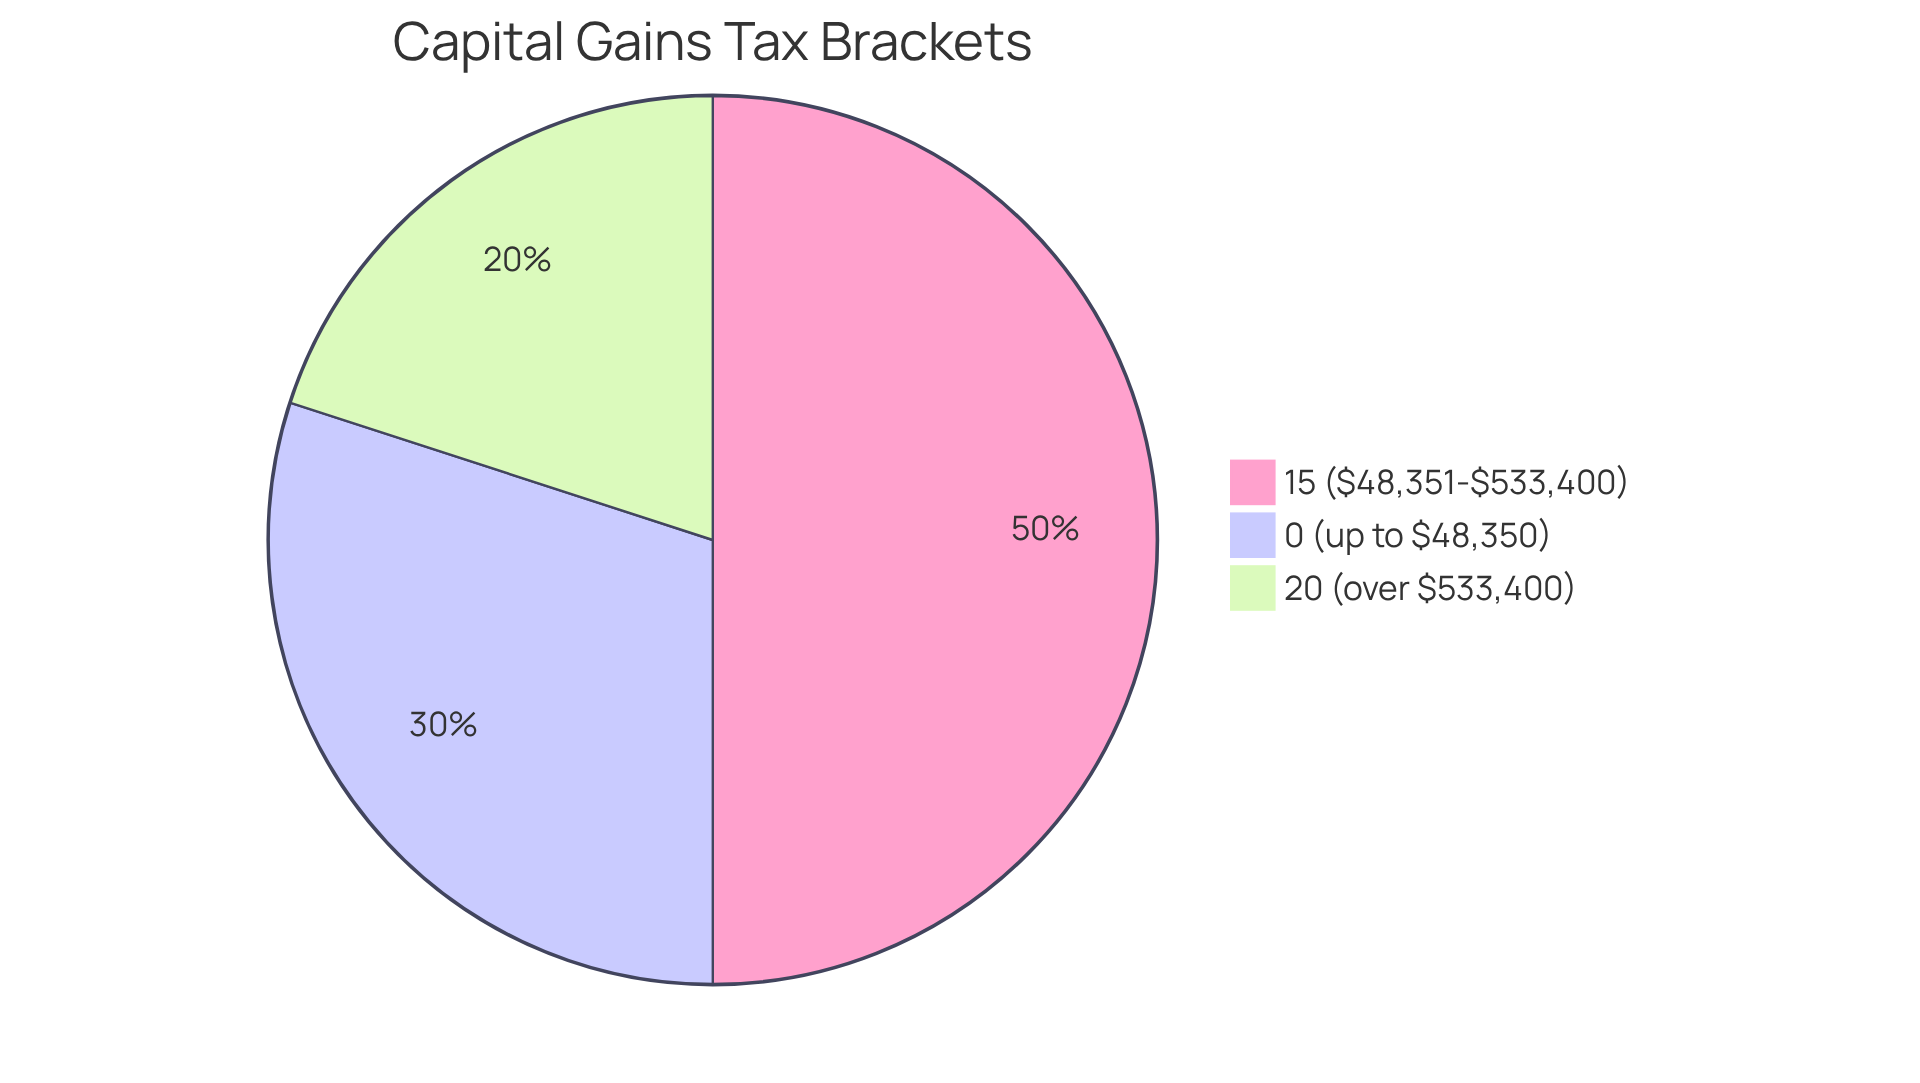
In 2025, understanding the long term capital gains tax bracket can be a game changer for families as they navigate their financial futures. For individuals, the 0% rate applies to those with taxable income up to $48,350. If your income falls between $48,351 and $533,400, you’ll face a 15% rate, while incomes exceeding $533,400 will be taxed at 20%. For married couples filing jointly, the thresholds are set at $96,700 for the 0% rate, $96,701 to $600,050 for the 15% rate, and over $600,050 for the 20% rate.
Imagine if you could plan your finances in a way that minimizes your tax obligations. Comprehending the long term capital gains tax bracket is essential for households, as it enables you to evaluate potential tax responsibilities on profits and strategically time asset sales. For instance, a married couple earning $120,000 could manage their taxable income to stay within the 0% profit bracket, allowing them to sell investments without incurring taxes.
Financial analysts emphasize that leveraging these thresholds can create significant opportunities for families to optimize their financial outcomes. Strategies like tax-loss harvesting—selling certain assets at a loss to offset profits—can help lower your taxable income. It’s important to understand that collaborating with a financial advisor, like those at Bright Advisers, can provide tailored guidance based on your unique financial situation.
By grasping the 2025 tax brackets, particularly the long term capital gains tax bracket, and the benefits of tax-advantaged accounts such as 401(k)s and IRAs, families can make informed choices that align with their financial goals. Additionally, if you have senior family members, be aware of the temporary tax breaks available for older Americans, as these can also influence your overall tax strategy.
Bright Advisers has successfully guided families like Jay and Emma, Emily and Mark, and Allison and Brian in optimizing their financial strategies. Their experiences highlight the value of personalized planning and tax optimization in achieving financial security and freedom. Remember, together, we can navigate this journey and ensure a brighter financial future for your family.
Implement Strategies to Reduce Long-Term Capital Gains Taxes
Smart Strategies for Reducing Long-Term Capital Gains Taxes
As families, we all want to secure a brighter financial future. To help you navigate the complexities of long-term capital gains taxes, here are some thoughtful strategies that can make a real difference:
-
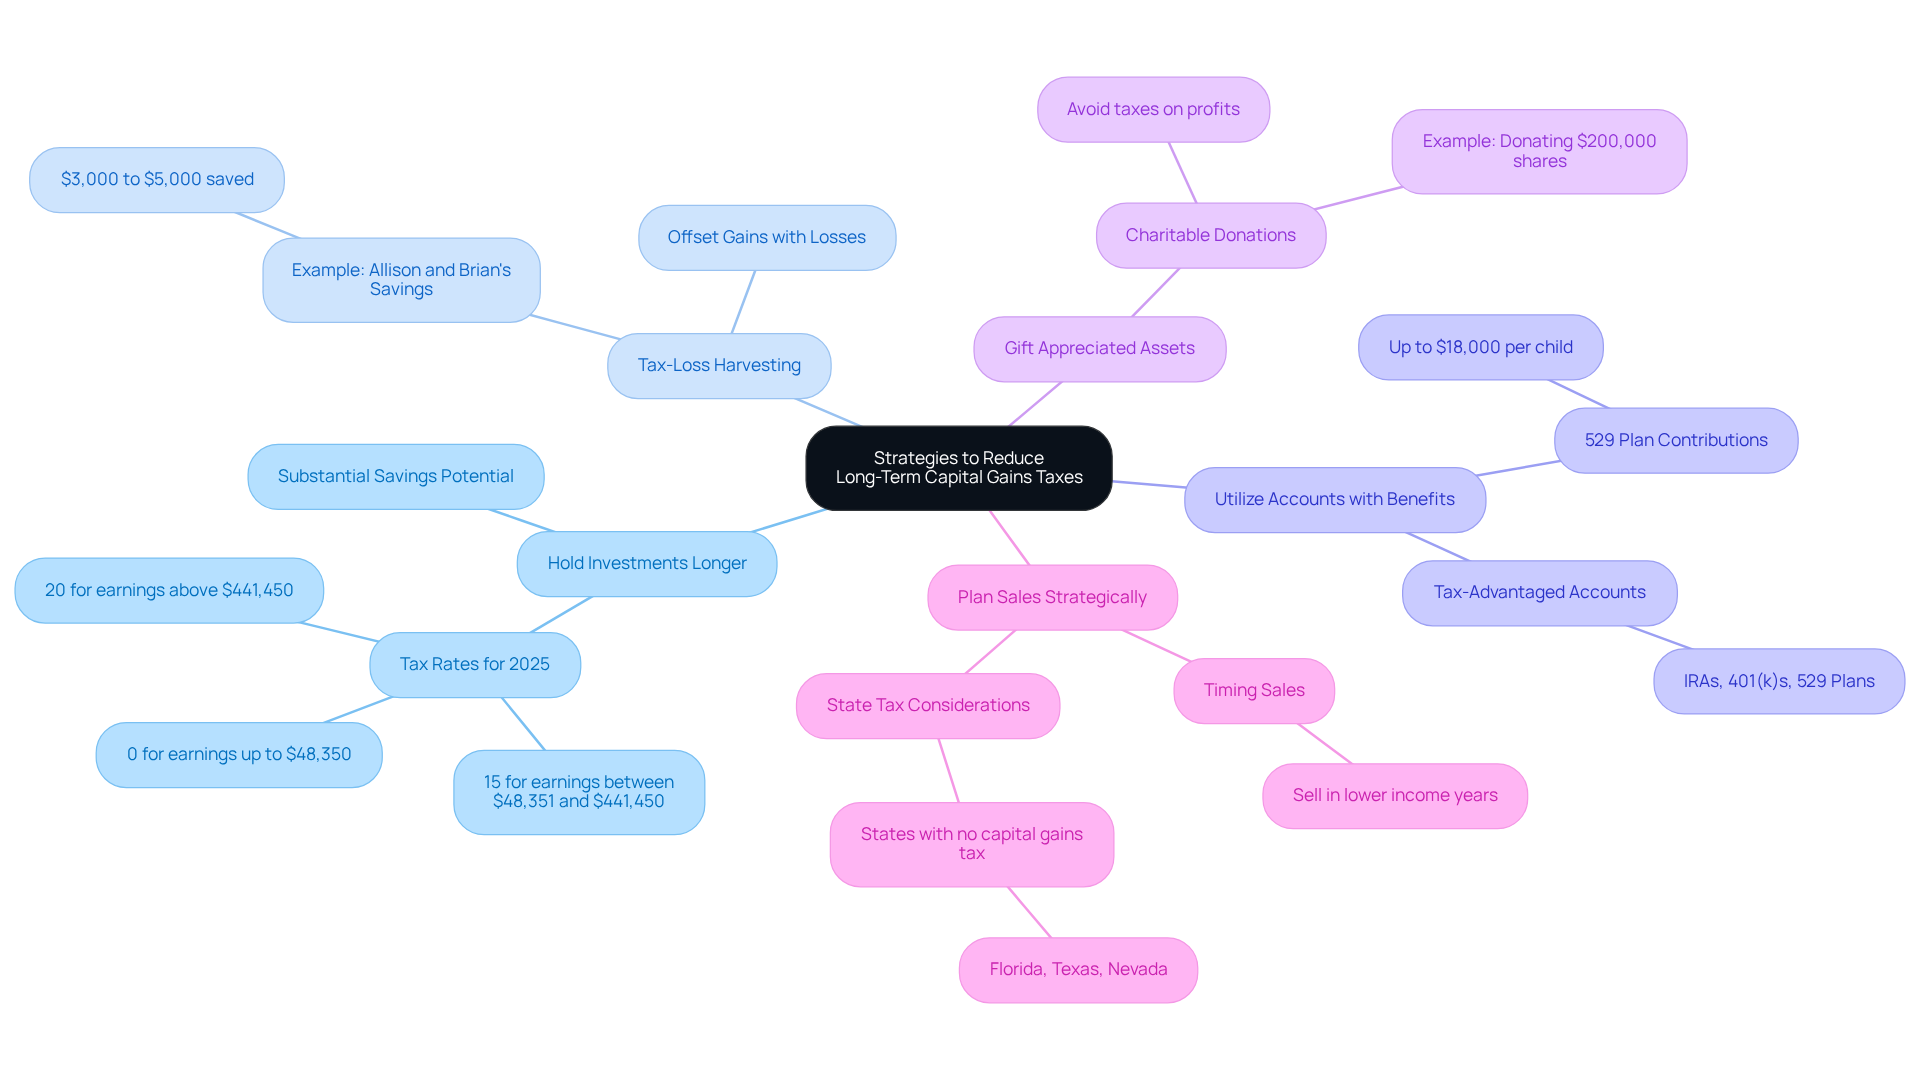
Hold Investments Longer: Imagine holding onto your investments for just a bit longer. By keeping assets for over a year, you can benefit from the long term capital gains tax bracket, which offers significantly lower tax rates on your profits. For instance, in 2025, the profit tax rate is 0% for earnings up to $48,350, 15% for earnings between $48,351 and $441,450, and 20% for earnings above $441,450. This simple shift can lead to substantial savings.
-
Tax-Loss Harvesting: Picture this: you sell off some underperforming investments to balance out the gains from your successful ones. This strategy, known as tax-loss harvesting, can effectively lower your taxable income. Families often find it beneficial to sell investments in years when their income is lower, potentially qualifying for the long term capital gains tax bracket, which may result in zero federal capital profits tax. For example, Allison and Brian saved between $3,000 to $5,000 using this approach, showcasing how proactive financial management can pay off.
-
Utilize Accounts with Benefits: Investing through accounts like IRAs, 401(k)s, and 529 plans allows you to postpone taxes on profits until you withdraw. This not only aids in tax management but also fosters long-term growth without immediate tax implications. For instance, families can contribute up to $18,000 per child to a 529 plan without affecting their lifetime gift tax exemption, ensuring a secure educational future for their children.
-
Gift Appreciated Assets: Have you considered donating appreciated stocks or mutual funds to charity? This generous act can eliminate taxes on profits while providing you with a charitable deduction. For example, if you donate shares valued at $200,000 that you bought for $50,000, you can avoid taxes on the $150,000 profit. It’s a win-win for both your tax position and the causes you care about.
-
Plan Sales Strategically: Timing is everything! By planning when to sell your investments based on your income levels, you can ensure you remain within the long term capital gains tax bracket. For instance, selling during a year of reduced income can significantly lessen your capital gains tax burden. Many families have found success with this strategy, especially in states with higher income tax rates.
By embracing these strategies, you can enhance your family’s financial position and pave the way for a more secure future. Remember, year-round tax planning and utilizing resources like tax-loss harvesting can lead to meaningful savings. Together, we can navigate this journey and help you achieve your financial goals.
Assess the Impact of Capital Gains Taxes on Investment Strategies
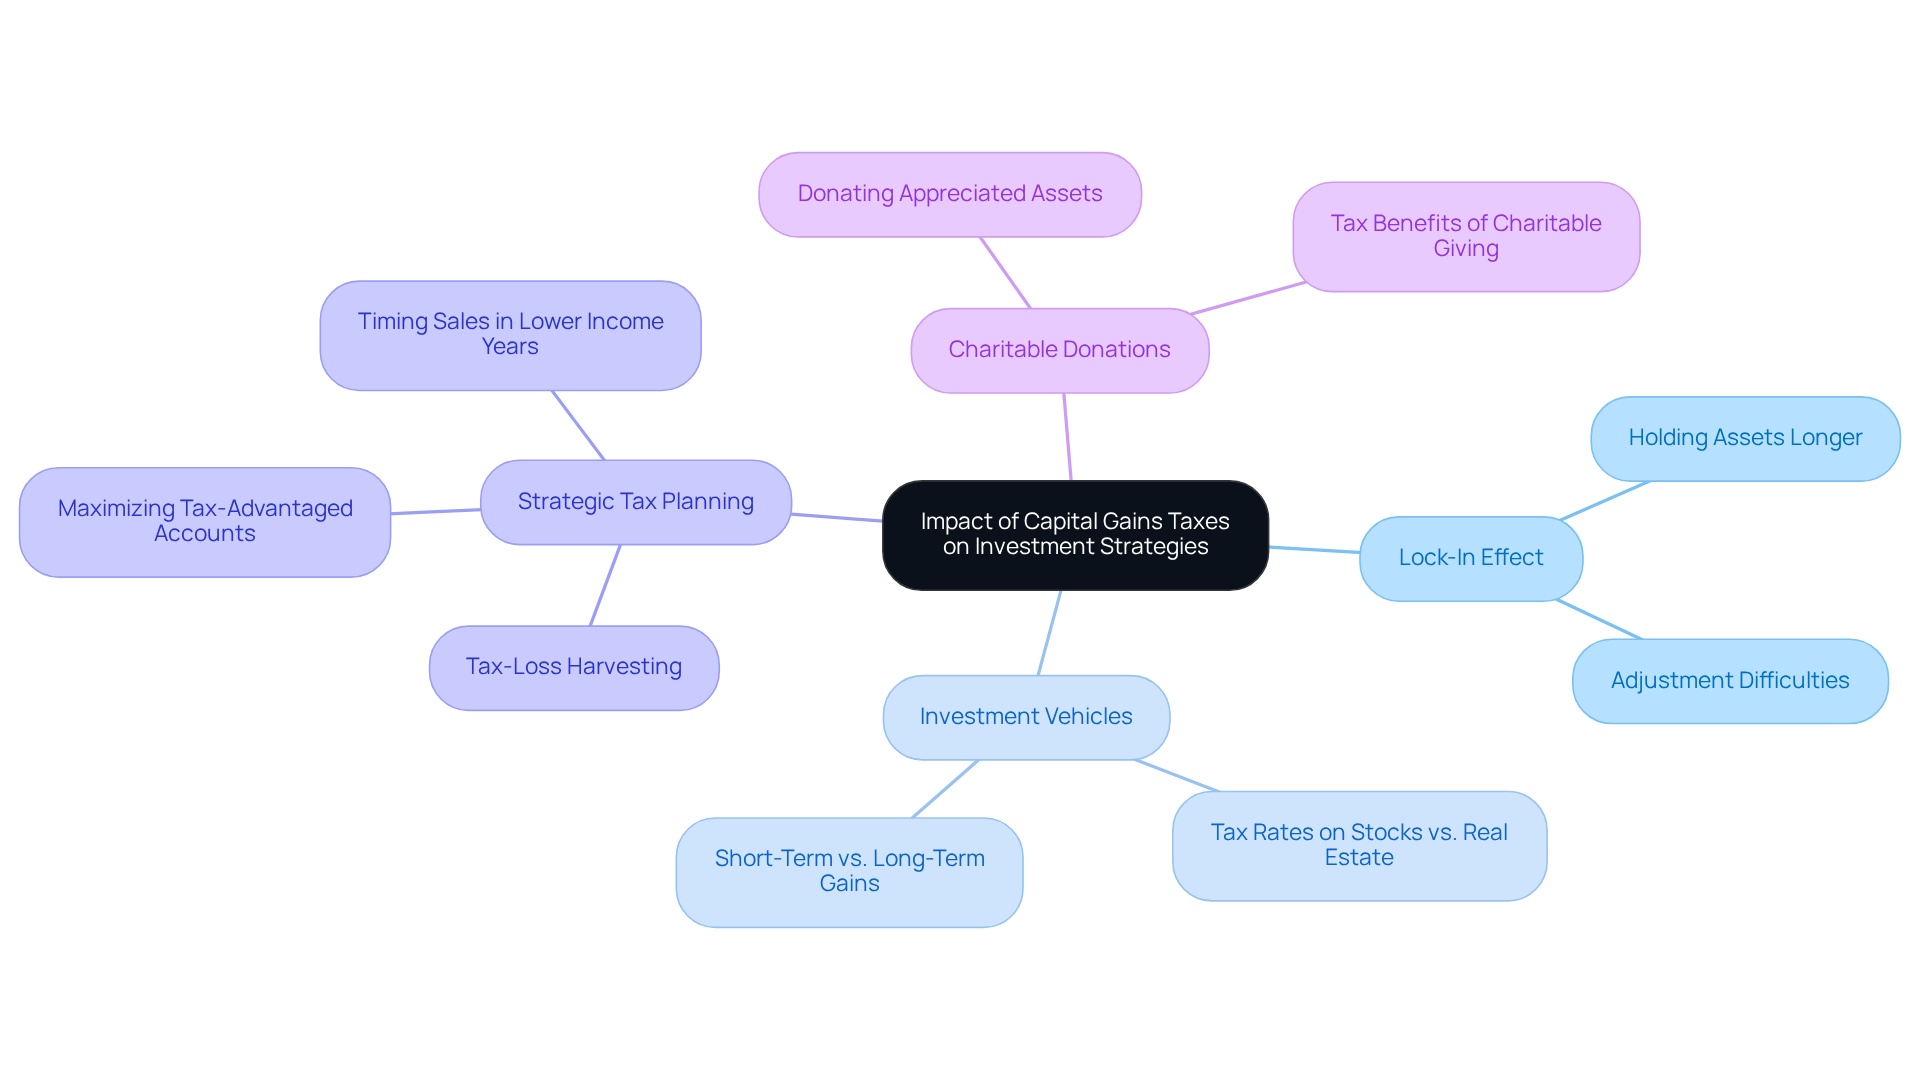
Capital appreciation levies play a crucial role in shaping investment strategies for families, especially those looking to improve their financial futures. These levies can significantly affect overall returns, prompting families to carefully evaluate their investment options. Imagine if increased capital gains taxes made you think twice about selling a profitable investment. This ‘lock-in’ effect can lead families to hold onto assets longer than necessary, making it harder to adjust their portfolios in response to changing financial goals or market conditions.
It’s important to understand the tax implications tied to different investment vehicles—like stocks, bonds, and real estate. This knowledge empowers families to make informed decisions. For instance, stocks might face different profit tax rates compared to real estate, impacting the total tax burden when these assets are sold. By considering tax factors in their investment strategies, families can enhance their portfolios for better after-tax returns.
Take the inspiring story of Allison and Brian, who turned to Bright Advisers for help with their tax situation. Through strategic tax planning, they discovered significant benefits. They embraced strategies like tax-loss harvesting and maximizing contributions to tax-advantaged accounts. Not only did this secure their children’s future through education funding, but it also positioned them to retire sooner. This proactive approach keeps their financial plans aligned with their long-term goals, ensuring a more stable future for their loved ones.
Additionally, families might explore options like donating valued assets to charity. This not only helps reduce tax obligations but also supports causes close to their hearts. By understanding and applying these strategies, families can navigate the complexities of the long term capital gains tax bracket and improve their overall financial well-being.
Together, we can navigate this journey toward financial security, ensuring that your family’s future is bright and filled with possibilities.
Conclusion
Understanding the complexities of long-term capital gains tax is crucial for families looking to secure their financial futures. Imagine if you could make informed decisions about your investments, allowing you to keep more of your hard-earned profits. This knowledge not only helps you navigate tax implications effectively but also aligns your financial strategies with your family’s broader goals.
Throughout this article, we’ve highlighted key points, such as the differences between short-term and long-term capital gains, the specific tax rates for 2025, and various strategies to minimize tax liabilities. Techniques like holding investments longer, tax-loss harvesting, and utilizing tax-advantaged accounts can significantly enhance your financial outcomes. Real-life stories of families successfully optimizing their tax strategies illustrate how these concepts can be practically applied.
Ultimately, the importance of understanding and planning for long-term capital gains taxes cannot be overstated. We encourage families to take proactive steps in their financial planning, leveraging expert advice and strategies to ensure a brighter, more secure future. By prioritizing tax efficiency and making informed investment decisions, families can navigate the complexities of capital gains taxes together, paving the way for lasting financial stability. Remember, we’re here for you, and together, we can navigate this journey.
Frequently Asked Questions
What are capital gains?
Capital gains are the profits made from selling an asset for more than what you paid for it, such as stocks, bonds, or real estate.
How are capital gains taxed?
Capital gains are subject to taxation by the IRS, and the tax rate depends on whether the gains are classified as short-term or long-term.
What is the difference between short-term and long-term capital gains?
Short-term capital gains come from assets held for a year or less and are taxed at regular income rates, which can be as high as 37%. Long-term capital gains come from assets held for more than a year and enjoy lower tax rates of 0%, 15%, or 20%, based on taxable income.
What is the home sale exclusion?
The home sale exclusion allows individuals to exclude up to $250,000 in profits from capital gains tax if single, or up to $500,000 if married, provided certain ownership and residency requirements are met.
How can families minimize their capital gains taxes?
Families can minimize capital gains taxes by using tax-advantaged accounts like 401(k)s or IRAs, holding investments for longer than a year to qualify for lower tax rates, and employing strategies like tax-loss harvesting.
What should families consider when planning their investments?
Families should consider the long-term capital gains tax bracket, potential changes to tax laws, and the timing of asset sales to optimize their financial planning and tax efficiency.
How can financial advisors assist families with capital gains?
Financial advisors can help families understand profit taxes, navigate tax strategies, and structure investments effectively to align with their financial goals and enhance wealth growth.
List of Sources
- Define Capital Gains: Understanding the Basics
- 2025 and 2026 Capital Gains Tax Rates and Rules – NerdWallet (https://nerdwallet.com/taxes/learn/capital-gains-tax-rates)
- TOP 13 CAPITAL GAINS TAX QUOTES | A-Z Quotes (https://azquotes.com/quotes/topics/capital-gains-tax.html)
- Capital Gains Tax Worries Rank High Among Family Business Leaders, New Poll Finds – Thailand Business News (https://thailand-business-news.com/pr-news/capital-gains-tax-worries-rank-high-among-family-business-leaders-new-poll-finds)
- Understanding the New 2025 Tax Policies: Capital Gains Tax Rates and Rules – Bankers Life Blog (https://bankerslife.com/insights/personal-finance/understanding-the-new-2025-tax-policies-capital-gains-tax-rates-and-rules)
- Differentiate Between Short-Term and Long-Term Capital Gains
- Short-term vs. Long-term capital gains (https://public.com/learn/capital-gains-taxes-short-vs-long-term)
- How Capital Gains Are Taxed: Short-Term Vs Long-Term Gains (https://physiciansidegigs.com/long-vs-short-term-capital-gains-tax-rates)
- Short vs. Long-Term Capital Gains & Tax Rates (https://carta.com/learn/equity/stock-options/taxes/capital-gains)
- Short-Term vs. Long-Term Capital Gains: Which Tax Strategies Work Best? (https://foxessellfaster.com/blog/short-term-vs-long-term-capital-gains-which-tax-strategies-work-best)
- Capital Gains Tax Rates 2025 and 2026: What You Need to Know (https://kiplinger.com/taxes/capital-gains-tax/602224/capital-gains-tax-rates)
- Explore Long-Term Capital Gains Tax Rates for 2025
- 2024-2025 Long-Term Capital Gains Tax Rates | Bankrate (https://bankrate.com/investing/long-term-capital-gains-tax)
- 2025 and 2026 Capital Gains Tax Rates and Rules – NerdWallet (https://nerdwallet.com/taxes/learn/capital-gains-tax-rates)
- Who benefits from 0% capital gains for 2025 under Trump’s ‘big beautiful bill’ (https://cnbc.com/2025/08/26/capital-gains-trumps-tax-bill.html)
- Implement Strategies to Reduce Long-Term Capital Gains Taxes
- IRA Ownership Reaches Record Highs | Investment Company Institute (https://ici.org/25-view-ira-ownership-reaches-record-highs)
- Tax-loss harvesting | Capital gains and lower taxes | Fidelity (https://fidelity.com/viewpoints/personal-finance/tax-loss-harvesting)
- 12 Strategies to Help Lower Long-Term Capital Gains Taxes (https://landsbergbennett.com/blogs/insights/12-strategies-to-help-lower-long-term-capital-gains-taxes)
- 10 Essential Tax Planning Webinar Tips for Young Families – Bright Advisers (https://brightadvisers.com/10-essential-tax-planning-webinar-tips-for-young-families)
- Assess the Impact of Capital Gains Taxes on Investment Strategies
- TOP 13 CAPITAL GAINS TAX QUOTES | A-Z Quotes (https://azquotes.com/quotes/topics/capital-gains-tax.html)
- 12 Strategies to Help Lower Long-Term Capital Gains Taxes (https://landsbergbennett.com/blogs/insights/12-strategies-to-help-lower-long-term-capital-gains-taxes)
- Strategic Tax Plan: Timing Investment Gains to Reduce Tax Liability (https://commercetrustcompany.com/research-and-insights/articles/6-strategies-to-lower-capital-gains-taxes-on-investment-returns)
- Impact of Taxes on Investment Returns | U.S. Bank (https://usbank.com/investing/financial-perspectives/investing-insights/impact-of-taxes-on-investment-returns.html)

Kevin has advised high-income W-2 tech and biotech families since 2015, and leads the education-first Age Five Family Office from Brea, California.
Connect on LinkedIn → · About KevinThis is part of how we approach Tax Management for high-income W-2 families at Bright Advisers.
Keep reading