

Overview
Imagine navigating the world of retirement savings while balancing the joys and challenges of parenthood. This article gently guides you through how to effectively use the MAGI calculator to determine your eligibility for Roth IRA contributions. Understanding your Modified Adjusted Gross Income (MAGI) is crucial, especially when it comes to income limits that can impact your family’s financial future.
It’s important to grasp the calculation process, as well as the contribution thresholds for 2025. By doing so, you can make informed decisions that align with your family’s values and goals. We understand that tax planning can feel overwhelming, but with the right strategies, you can optimize your retirement savings and ensure a secure future for your loved ones.
Accurate MAGI calculations are essential to maximize your tax benefits and avoid any disqualification from contributions. Together, we can navigate this journey, ensuring that you feel supported every step of the way. Remember, we’re here for you, and with the right information, you can confidently take control of your financial planning.
Key Highlights:
- Modified Adjusted Gross Income (MAGI) is calculated by adding back specific deductions to your Adjusted Gross Income (AGI), such as student loan interest and foreign earned income exclusion.
- For 2025, the full Roth IRA contribution limits are below $236,000 for married couples filing jointly and below $150,000 for individual filers.
- Exceeding MAGI thresholds can limit Roth IRA contributions, emphasising the need for accurate calculations using a MAGI calculator.
- The calculation process involves determining AGI, identifying add-backs, and applying the formula: MAGI = AGI + Add-Backs.
- Families with MAGI in the phase-out range may need to explore alternative retirement savings options, such as a backdoor Roth IRA strategy.
- Tax planning strategies, like maximising retirement contributions and tax-loss harvesting, can help lower MAGI and enhance financial security.
Introduction
Understanding the nuances of Modified Adjusted Gross Income (MAGI) is essential for families looking to maximize their retirement savings through Roth IRA contributions. Imagine if you could unlock valuable insights that directly influence your financial strategies by diving into the intricacies of the MAGI calculator. However, as income thresholds shift, you might wonder: how can you effectively navigate the complexities of MAGI to avoid missing out on significant tax benefits? This article will gently guide you through the essential steps and considerations for leveraging the MAGI calculator, ensuring a more secure financial future for your family. Together, we can navigate this journey.
Define Modified Adjusted Gross Income (MAGI)
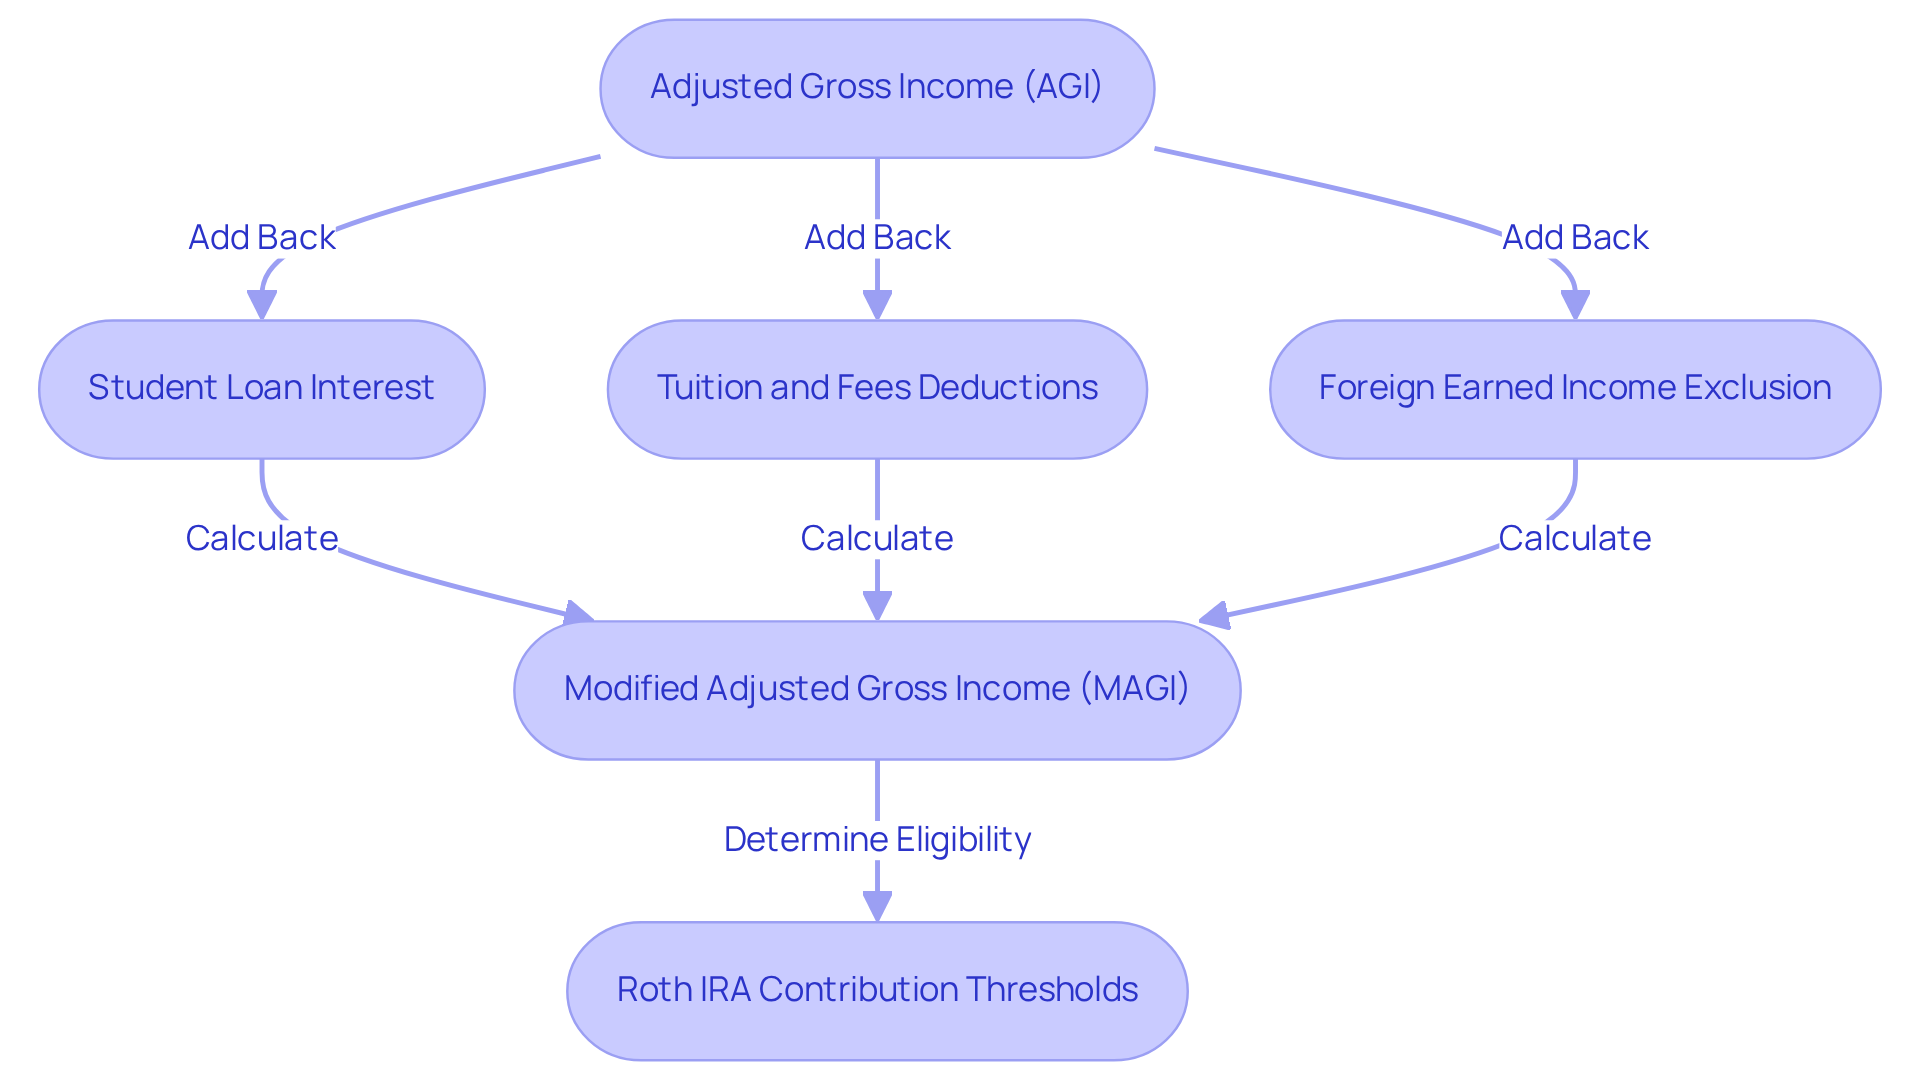
Understanding your Modified Adjusted Gross Income (MAGI) is essential for your family’s financial well-being, especially when it comes to tax benefits like contributions to a Roth IRA. This metric starts with your Adjusted Gross Income (AGI), which represents your total earnings after certain deductions. To calculate your MAGI, you’ll need to add back specific deductions to your AGI, such as:
- student loan interest
- tuition and fees deductions
- the foreign earned income exclusion
For 2025, the thresholds for full Roth IRA contributions are set at below $236,000 for married couples filing jointly and below $150,000 for individual filers. It’s important to understand how the MAGI calculator for Roth IRA affects your family’s ability to contribute to this valuable tool for retirement savings, which allows for tax-free growth and withdrawals.
Imagine if your family’s AGI is $120,000, yet you also have significant tax-exempt interest income. This could push your MAGI over the threshold, limiting your contribution options. Financial consultants emphasize that using a MAGI calculator for Roth IRA can significantly enhance your tax benefits and ensure you make the most of your retirement savings.
Remember, we’re here for you. Together, we can navigate this journey toward securing a brighter financial future for your family. By understanding how to use the MAGI calculator for Roth IRA, you can take proactive steps to maximize your retirement savings and enjoy the peace of mind that comes with informed financial planning.
Calculate Your MAGI: Step-by-Step Guide
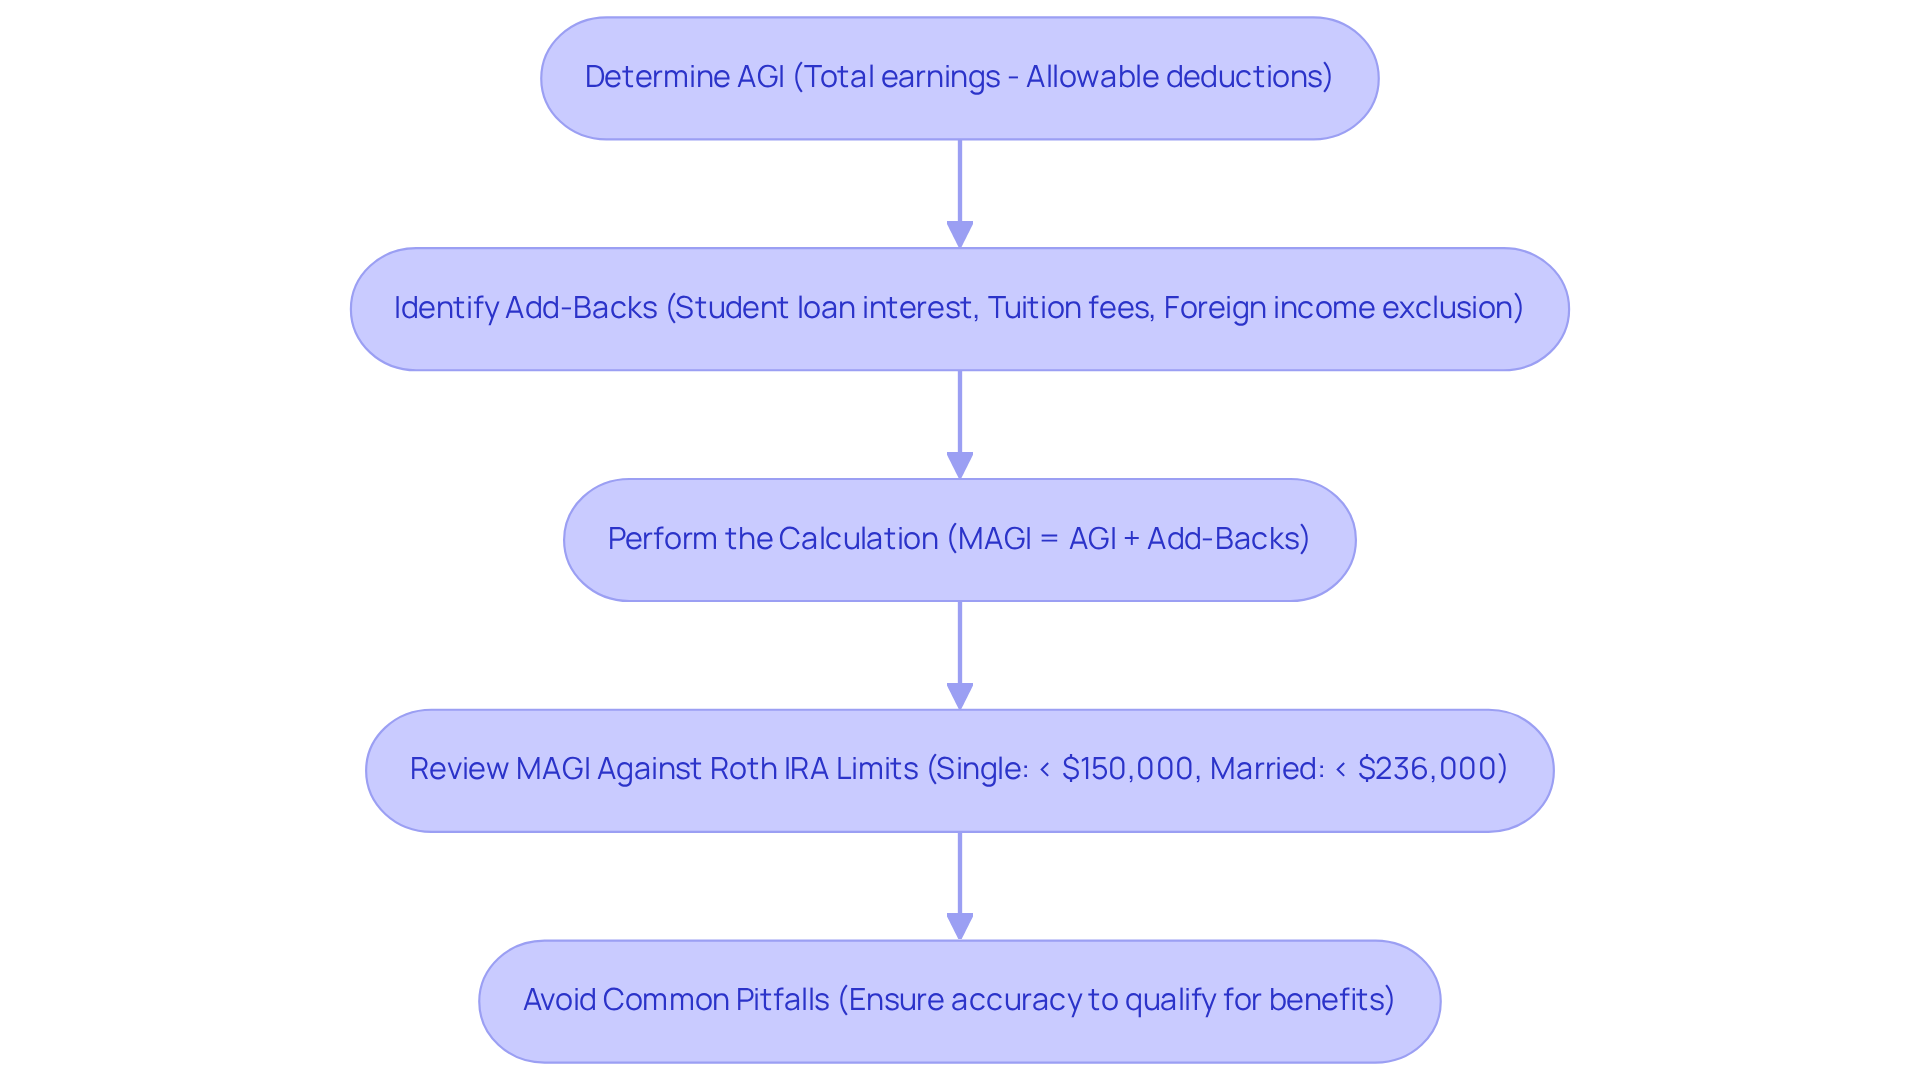
Using a magi calculator for roth ira can help make calculating your MAGI feel less overwhelming, and we’re here to assist you through it, step by step. Let’s break it down together:
-
Determine Your Adjusted Gross Earnings (AGI): Begin with your total earnings from all sources—wages, dividends, and rental income. Don’t forget to subtract allowable deductions like retirement contributions and student loan interest to find your AGI.
-
Identify Add-Backs: Next, review the specific deductions that need to be added back to your AGI. Common add-backs include:
- Student loan interest deduction
- Tuition and fees deduction
- Foreign earned income exclusion
-
Perform the Calculation: Now, add those identified deductions back to your AGI using this simple formula:
MAGI = AGI + Add-Backs -
Review Your Modified Adjusted Gross Income: After calculating, take a moment to compare your Modified Adjusted Gross Income against the Roth IRA income limits. For 2025, single filers can fully contribute if their MAGI is below $150,000, while married couples filing jointly must stay under $236,000. This step is vital for families planning their retirement savings wisely.
Understanding these calculations using a magi calculator for roth ira can help you avoid common pitfalls. Many households mistakenly overlook specific add-backs, leading to an incorrect MAGI, which could disqualify them from valuable tax benefits. By staying informed and precise in your calculations, you can enhance your financial input and secure a more promising future.
At Bright Advisers, we are dedicated to supporting young families like Jay and Emma, Emily and Mark, and Allison and Brian. We offer tailored financial strategies that help you understand how the magi calculator for roth ira impacts your retirement planning and tax optimization. Together, we can navigate this journey, ensuring a balanced approach to your current obligations and future aspirations.
Understand Roth IRA Income Limits and Their Implications
Understanding the magi calculator for roth ira contributions can be overwhelming, particularly due to the varying earnings limits based on your tax filing status. For 2025, here’s how the income limits are structured:
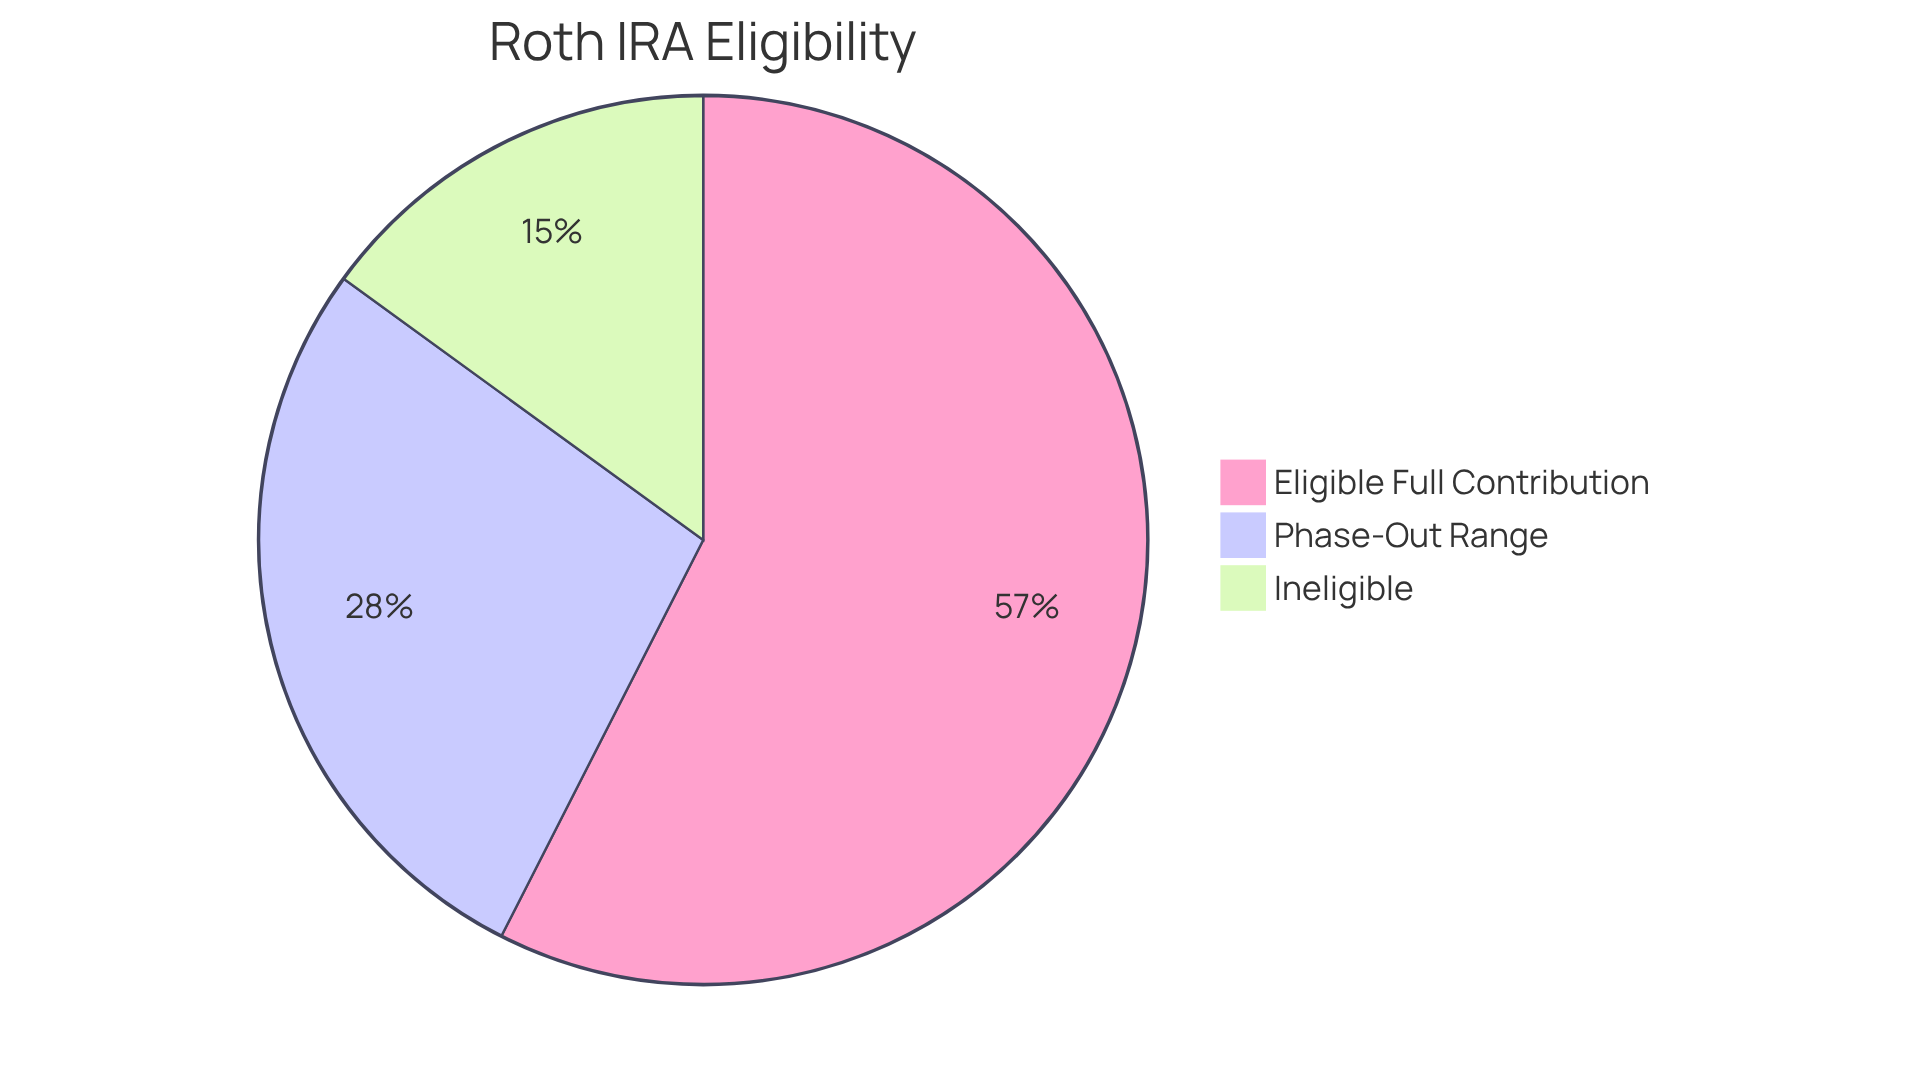
- Single Filers: If your Modified Adjusted Gross Income (MAGI) is below $150,000, you can contribute the full amount. However, contributions begin to diminish between $150,000 and $165,000, and those with an adjusted gross income above $165,000 are disqualified.
- Married Filing Jointly: The full amount is available if your MAGI is below $236,000. The phase-out range extends from $236,000 to $246,000, with ineligibility for those exceeding $246,000.
These limits are particularly significant for families, as they directly impact your retirement savings strategies. Imagine a young couple earning $240,000; they would face restrictions on their Roth IRA contributions, which could hinder their ability to save for retirement in a tax-advantaged account. Financial planners often emphasize the importance of understanding these thresholds, as exceeding them may lead to missed opportunities for tax-free growth, which can be analyzed using a magi calculator for roth ira.
In real-life situations, families frequently navigate these limits. For instance, consider a household with a MAGI of $245,000. They might need to explore alternative retirement savings options, such as a backdoor Roth IRA strategy. This approach allows high earners to bypass revenue restrictions by first contributing to a Traditional IRA and then converting it to a Roth IRA. This method can be especially beneficial for families striving to secure their financial future while managing their current earnings effectively.
By staying informed about these income limits and their implications, families can use a magi calculator for roth ira to make thoughtful decisions that align with their long-term financial goals. Remember, we’re here for you—together, we can navigate this journey toward a secure financial future.
Explore the Impact of MAGI on Roth IRA Contributions
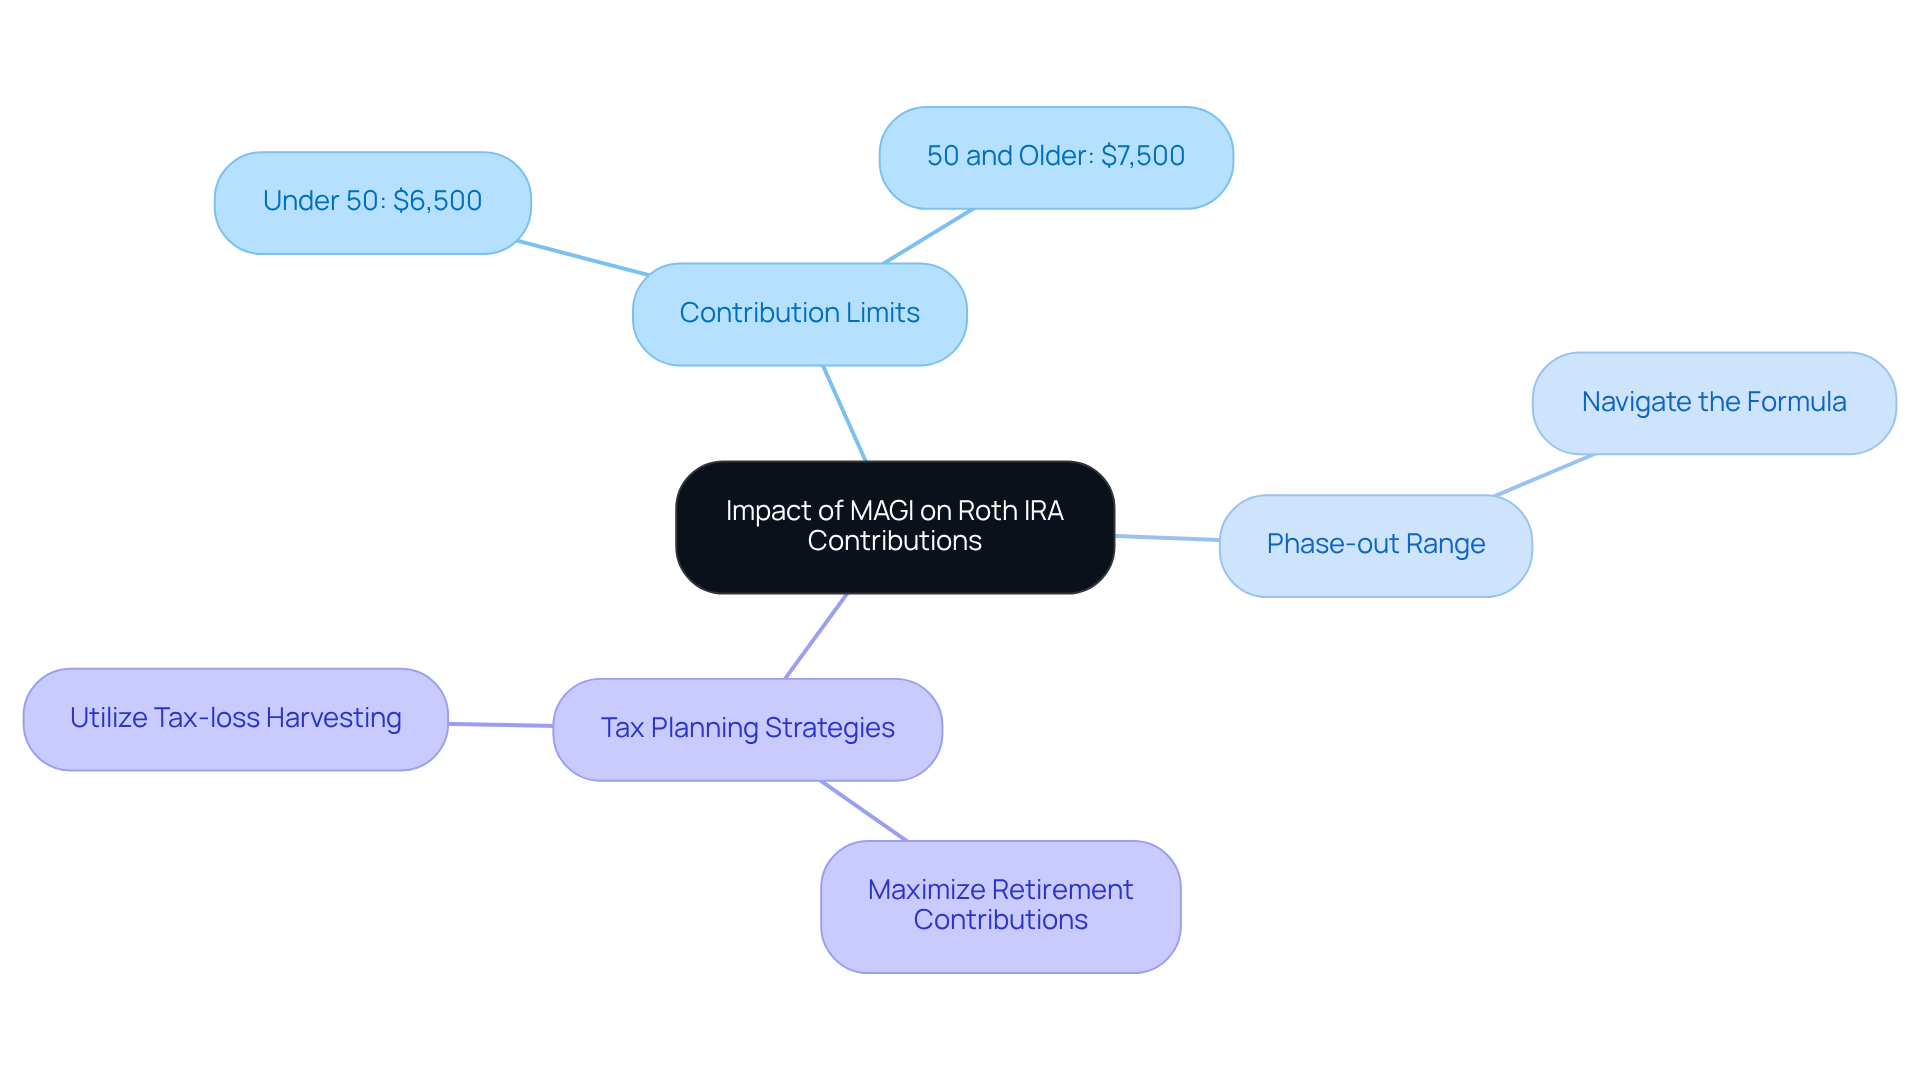
Understanding how Modified Adjusted Gross Income (MAGI) impacts your ability to use a MAGI calculator for Roth IRA contributions can be a significant part of your financial journey. If your MAGI is below the specified limits, you can contribute the maximum amount to your Roth IRA—$6,500 for individuals under 50 and $7,500 for those aged 50 and older in 2025. However, if your MAGI calculator for Roth IRA shows that your income falls within the phase-out range, your contribution limit will be reduced.
Imagine a married couple with an adjusted gross income of $225,000. They would need to navigate the phase-out formula to determine their reduced contribution limit. This adjustment can affect their overall retirement strategy, making it essential for families to use a MAGI calculator for Roth IRA to monitor their MAGI and adjust their contributions accordingly.
It’s also wise for families to explore tax planning strategies that may help lower their MAGI. Consider:
- Maximizing retirement account contributions
- Utilizing tax-loss harvesting
Together, these steps can help you maintain a strong financial foundation for your family’s future. Remember, we’re here for you, and together, we can navigate this journey toward financial security.
Conclusion
Understanding the intricacies of Modified Adjusted Gross Income (MAGI) is crucial for maximizing your Roth IRA contributions and optimizing retirement savings. Imagine being able to navigate your financial landscape more effectively, ensuring that you and your family remain eligible for the full range of benefits that a Roth IRA offers. This knowledge empowers you to take proactive steps toward a secure financial future.
As you explore the step-by-step guide to calculating MAGI, it’s important to identify specific add-backs to your Adjusted Gross Income (AGI) and understand the income limits for Roth IRA contributions in 2025. Recognizing the thresholds for single and married filers allows you to make informed decisions about your contributions. If necessary, you can explore alternative strategies, such as a backdoor Roth IRA. Remember, tax planning plays a significant role in maintaining a favorable MAGI and enhancing your retirement savings.
Ultimately, the relationship between MAGI and Roth IRA contributions cannot be overstated. Staying informed about MAGI calculations and their implications equips you to navigate your financial journey with confidence. By utilizing a MAGI calculator, you can optimize your contributions and secure a path toward financial stability. Embracing this knowledge is not just about meeting contribution limits; it’s about taking control of your financial future and ensuring that your retirement savings are maximized for long-term success. Together, we can navigate this journey, and we’re here for you every step of the way.
Frequently Asked Questions
What is Modified Adjusted Gross Income (MAGI)?
Modified Adjusted Gross Income (MAGI) is a financial metric that starts with your Adjusted Gross Income (AGI) and includes certain deductions added back to it. Understanding MAGI is crucial for determining eligibility for tax benefits, such as contributions to a Roth IRA.
How is MAGI calculated?
To calculate MAGI, you begin with your AGI and add back specific deductions. These deductions can include student loan interest, tuition and fees deductions, and the foreign earned income exclusion.
What are the MAGI thresholds for Roth IRA contributions in 2025?
For 2025, the thresholds for full Roth IRA contributions are set at below $236,000 for married couples filing jointly and below $150,000 for individual filers.
Why is it important to understand MAGI in relation to Roth IRA contributions?
Understanding MAGI is important because it affects your ability to contribute to a Roth IRA, which offers tax-free growth and withdrawals. If your MAGI exceeds the threshold, it may limit your contribution options.
How can a MAGI calculator assist with Roth IRA contributions?
A MAGI calculator can help you determine your MAGI and assess your eligibility for Roth IRA contributions, allowing you to maximize your tax benefits and retirement savings.
What happens if my AGI is below the threshold but I have tax-exempt interest income?
If your AGI is below the threshold but you have significant tax-exempt interest income, it could increase your MAGI above the threshold, potentially limiting your contribution options to a Roth IRA.
How can understanding MAGI contribute to better financial planning?
By understanding MAGI and effectively using a MAGI calculator, you can take proactive steps to maximize your retirement savings and enhance your overall financial planning, leading to a more secure financial future for your family.
List of Sources
- Define Modified Adjusted Gross Income (MAGI)
- Modified Adjusted Gross Income under the Affordable Care Act – UPDATED WITH INFORMATION FOR COVID-19 POLICIES (https://laborcenter.berkeley.edu/modified-adjusted-gross-income-under-the-affordable-care-act)
- What is MAGI or modified adjusted gross income? | healthinsurance.org (https://healthinsurance.org/glossary/modified-adjusted-gross-income-magi)
- What is Modified Adjusted Gross Income (MAGI) and how to calculate it? (https://taxesforexpats.com/articles/financial-planning/modified-adjusted-gross-income-magi.html)
- What Is MAGI? How to Calculate Your Modified Adjusted Gross Income (https://eztaxreturn.com/blog/what-is-magi-how-to-calculate-your-modified-adjusted-gross-income)
- 2025 Medicare Parts A & B Premiums and Deductibles | CMS (https://cms.gov/newsroom/fact-sheets/2025-medicare-parts-b-premiums-and-deductibles)
- Calculate Your MAGI: Step-by-Step Guide
- What Is MAGI? How to Calculate Your Modified Adjusted Gross Income (https://eztaxreturn.com/blog/what-is-magi-how-to-calculate-your-modified-adjusted-gross-income)
- Modified Adjusted Gross Income (MAGI): Calculating and Using It (https://investopedia.com/terms/m/magi.asp)
- What Is Modified Adjusted Gross Income (MAGI)? – NerdWallet (https://nerdwallet.com/article/taxes/modified-adjusted-gross-income-magi)
- What is Modified Adjusted Gross Income (MAGI) and how to calculate it? (https://taxesforexpats.com/articles/financial-planning/modified-adjusted-gross-income-magi.html)
- Understand Roth IRA Income Limits and Their Implications
- Roth IRA Income Limits for 2025 | PensionBee (US) (https://pensionbee.com/us/retirement-explained/retirement-planning/roth-ira-income-limits-for-2025)
- Retirement Account Statistics 2025 – NerdWallet (https://nerdwallet.com/article/investing/retirement-statistics)
- SOI Tax Stats Accumulation and Distribution of Individual Retirement Arrangements | Internal Revenue Service (https://irs.gov/statistics/soi-tax-stats-accumulation-and-distribution-of-individual-retirement-arrangements)

Kevin has advised high-income W-2 tech and biotech families since 2015, and leads the education-first Age Five Family Office from Brea, California.
Connect on LinkedIn → · About KevinThis is part of how we approach Tax Management for high-income W-2 families at Bright Advisers.
Keep reading