

Key Highlights
- The Mega Backdoor Roth IRA allows families to contribute significantly more to retirement accounts, with limits reaching up to $72,000 in 2026 for individuals under 50.
- This strategy enables tax-free growth of retirement savings, allowing for tax-free withdrawals of earnings after five years if the account holder is over 59 1/2.
- Families should cheque their 401(k) plans for after-tax contribution options and in-service withdrawals to utilise this strategy effectively.
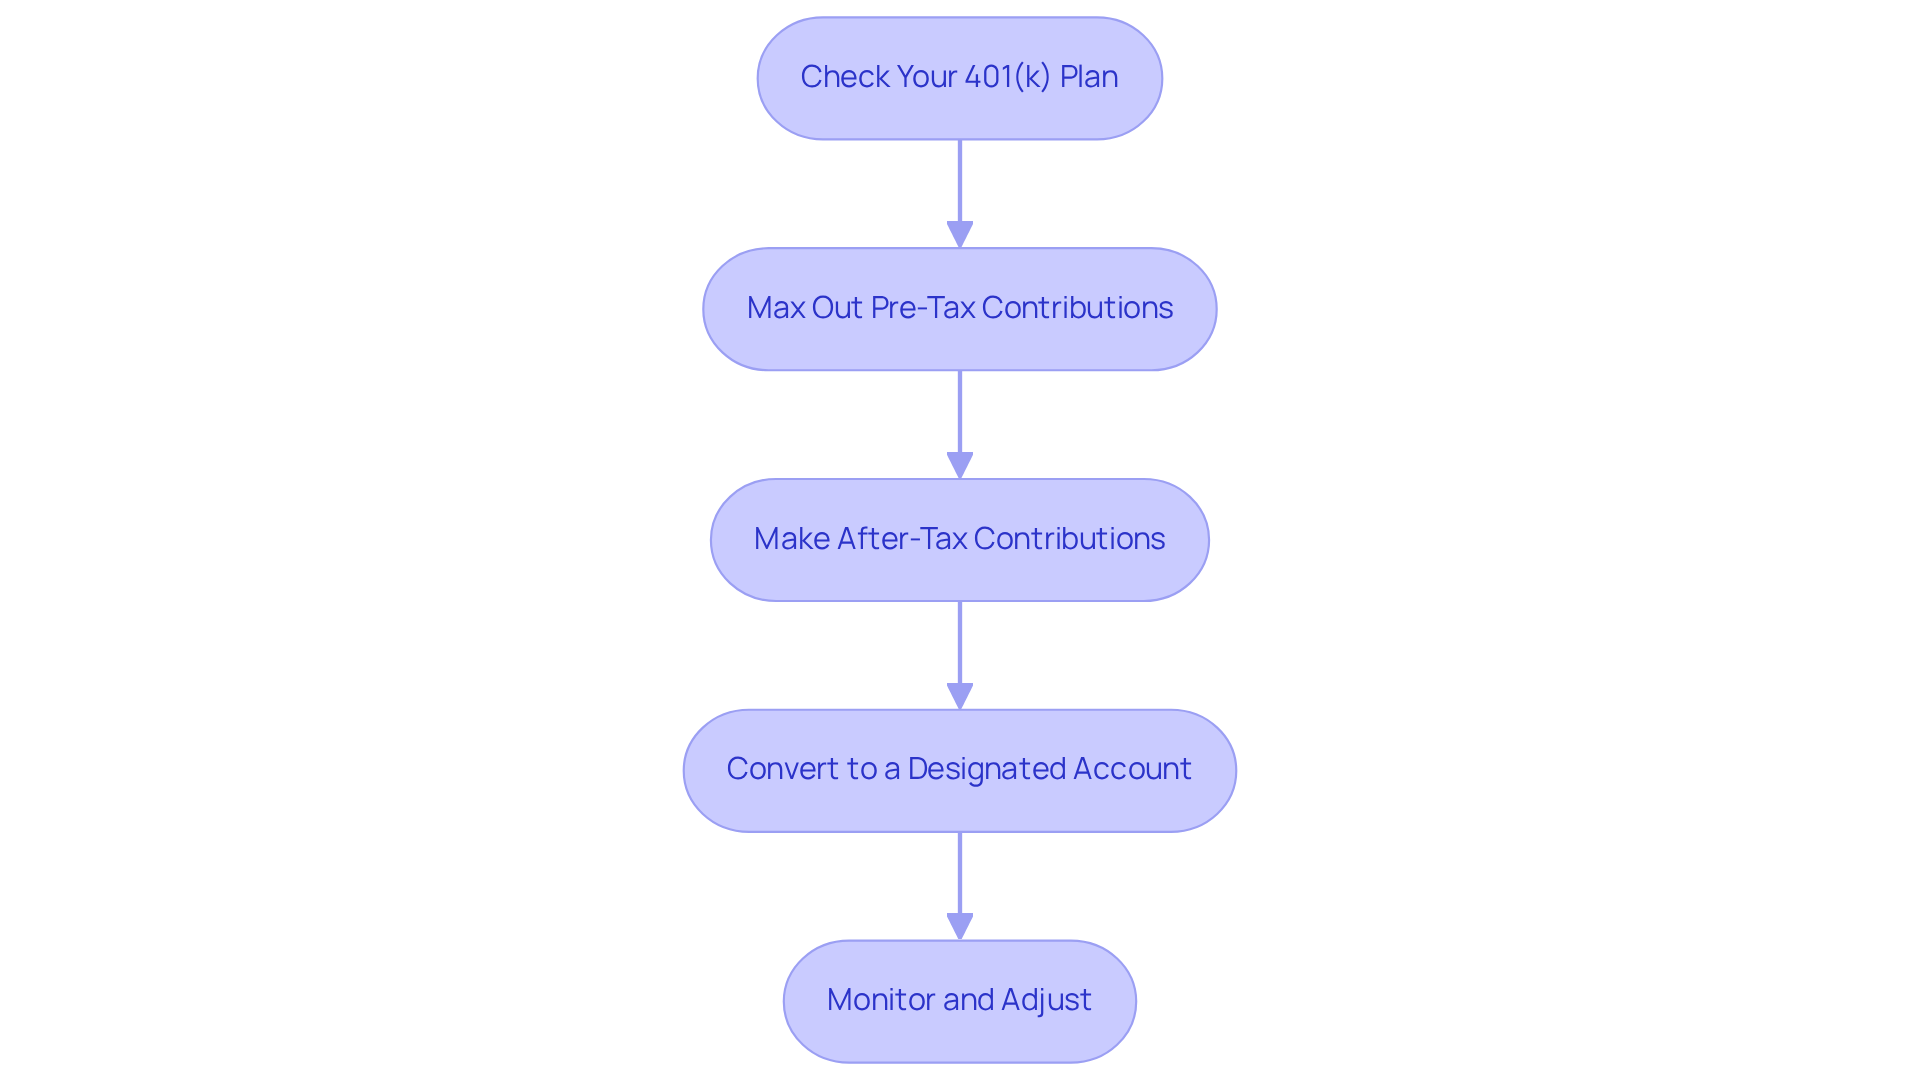
- Key steps include maxing out pre-tax contributions, making after-tax contributions, converting to a designated account, and regularly monitoring contributions.
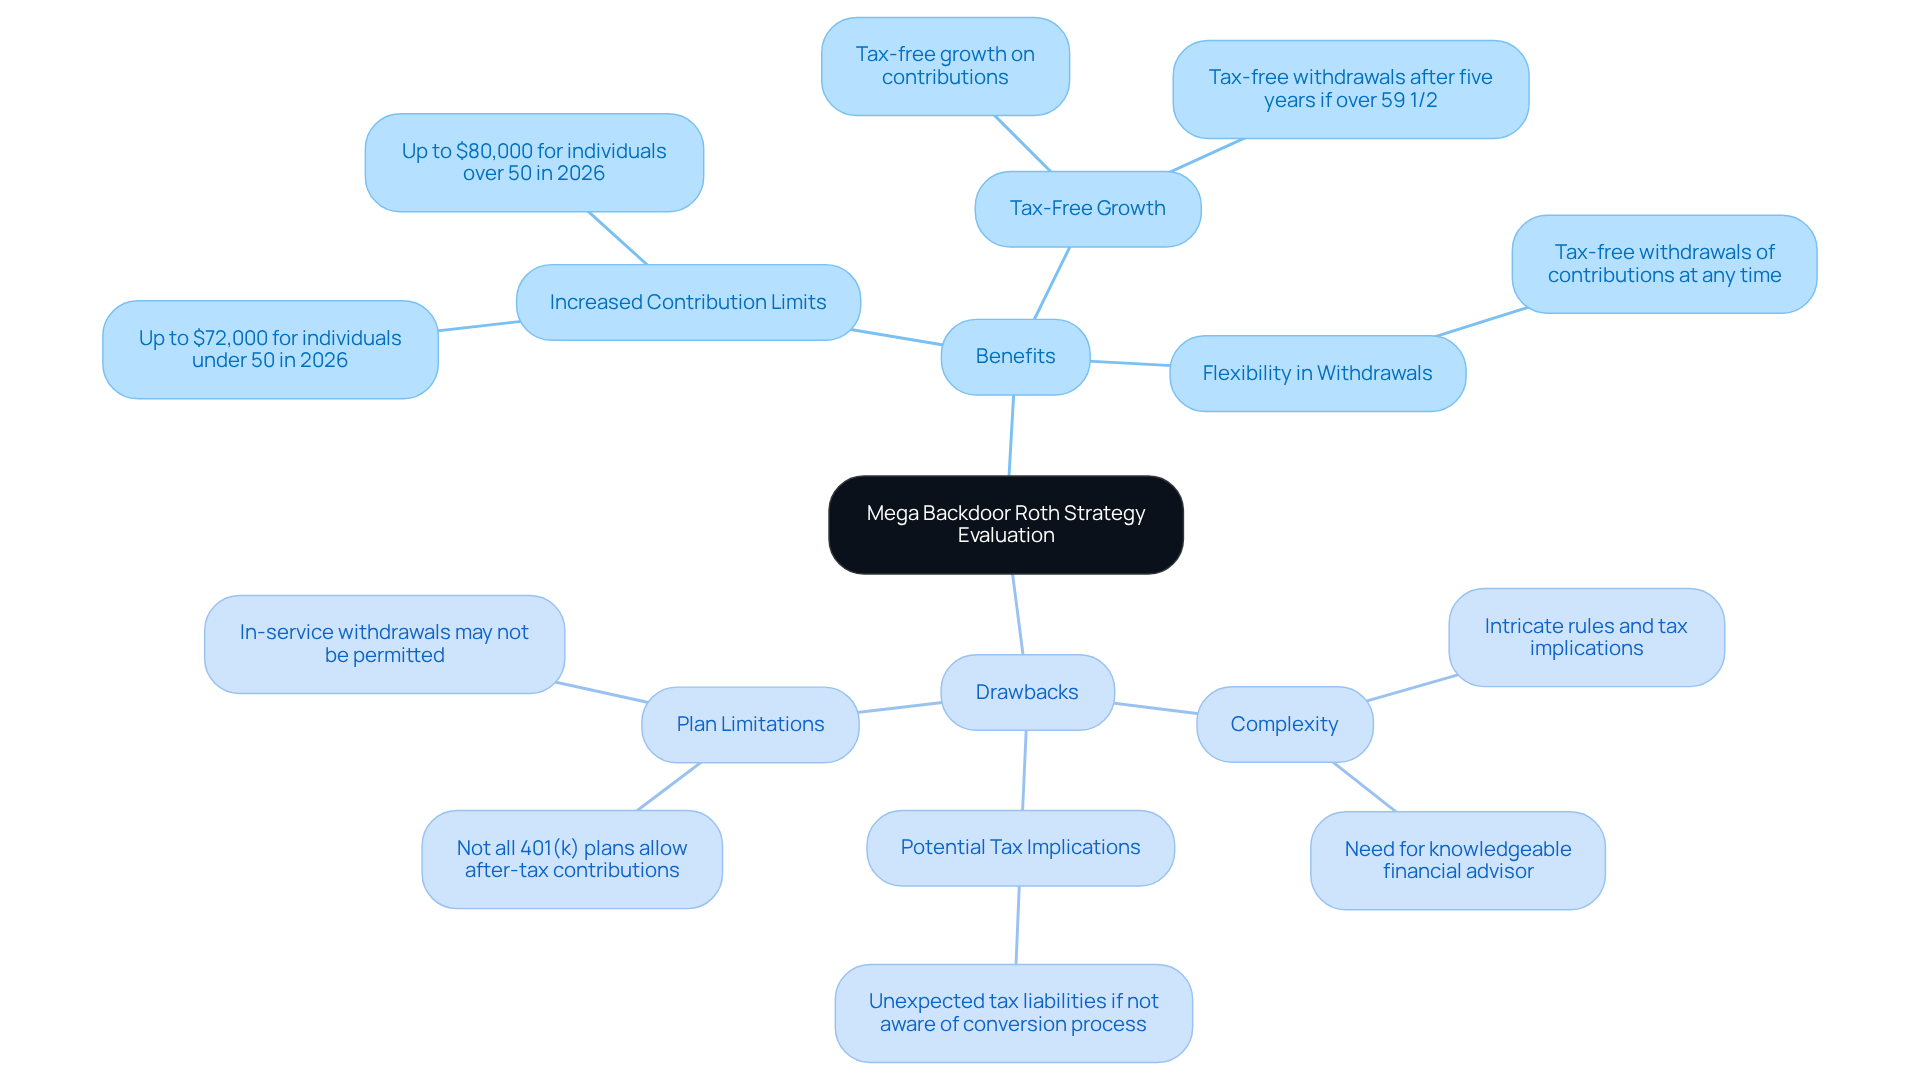
- Benefits include increased contribution limits, tax-free growth, and flexibility in withdrawals, while drawbacks involve complexity and potential tax implications.
- Consulting a financial professional, like Bright Advisers, can help families navigate the complexities of the Mega Backdoor Roth strategy and tailor it to their financial goals.
- As always, past performance does not guarantee future results, and securities investments are subject to risk. Bright Advisers provides advisory services through Lifeworks Advisors, emphasising fiduciary duty and transparency.
Introduction
Imagine feeling empowered to secure your family’s financial future with a strategy that offers both growth and peace of mind. The Mega Backdoor Roth IRA, combined with a traditional IRA, presents a unique opportunity for families to maximize their contributions beyond conventional limits, paving the way for a more secure financial future.
Many families feel lost when it comes to understanding their financial options. Without the right support, they might struggle to secure their financial future.
Understand the Mega Backdoor Roth IRA
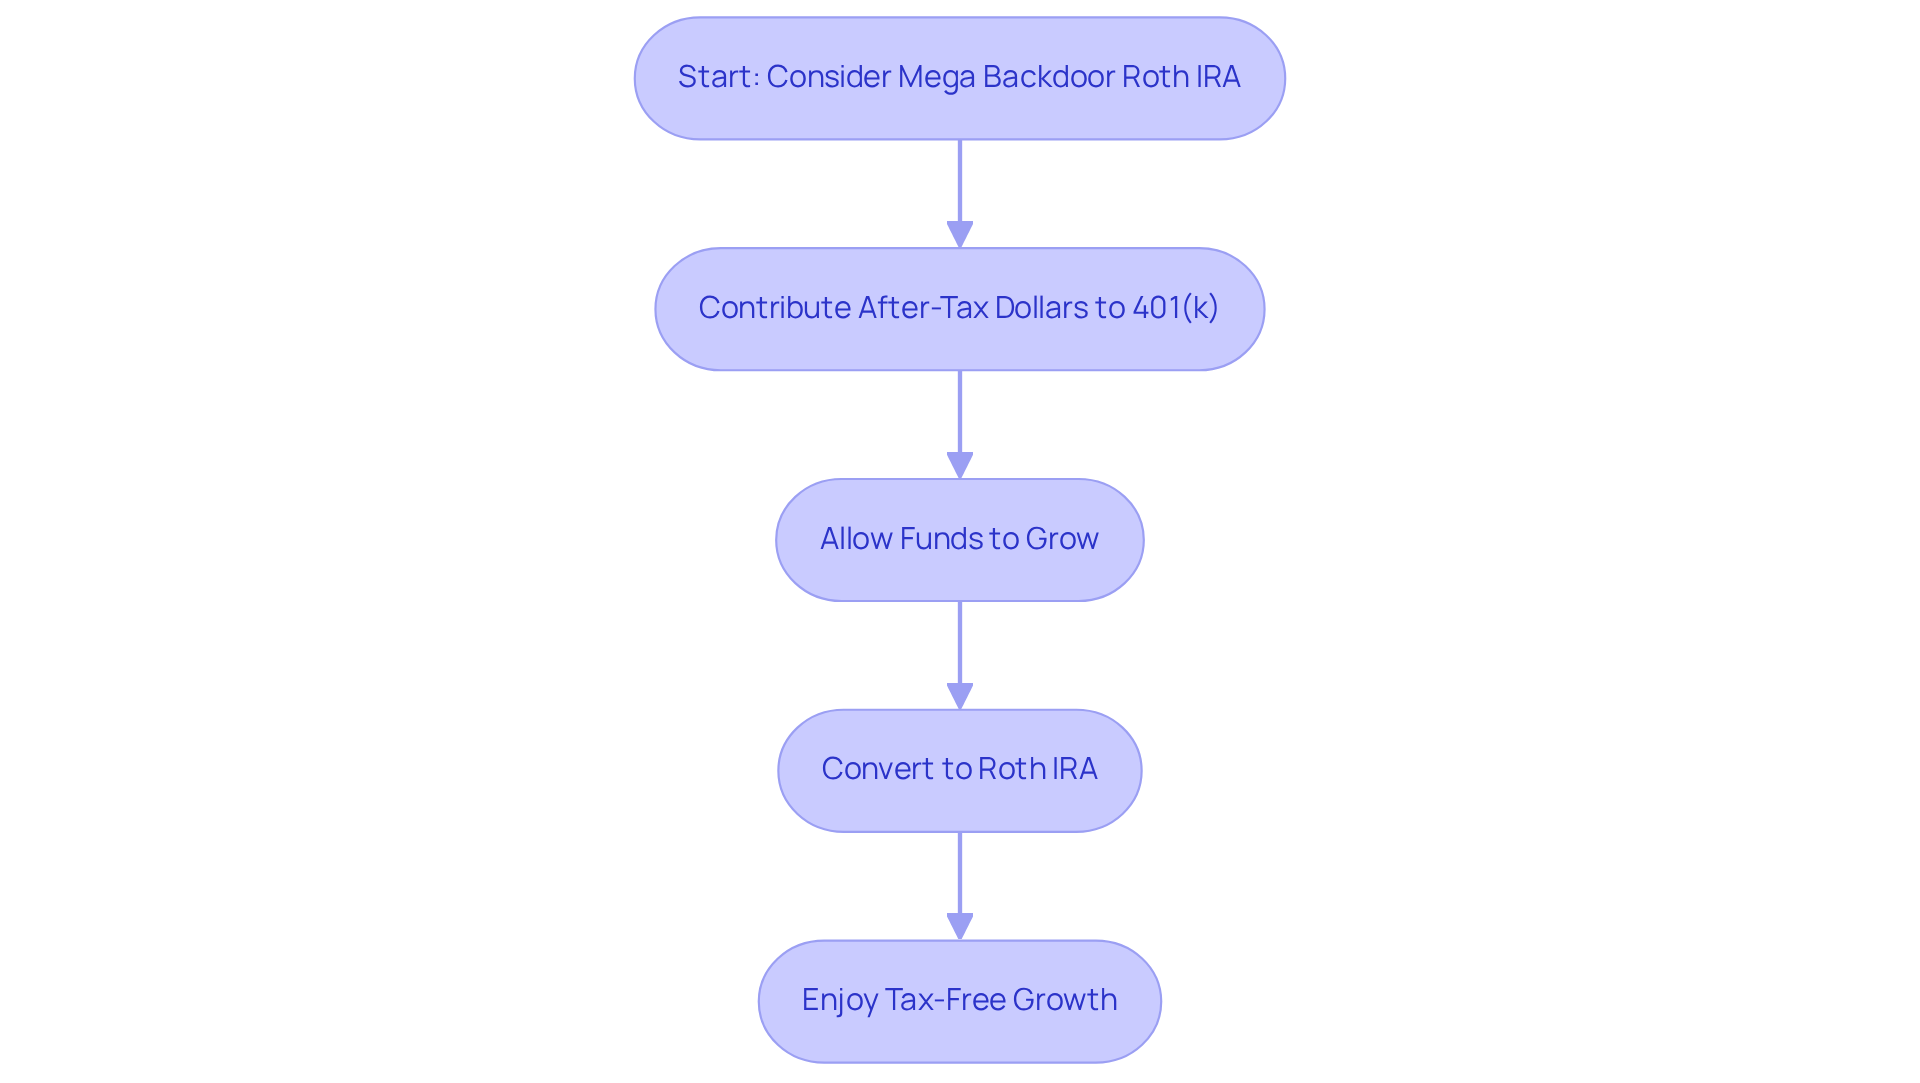
Imagine a way to save more for your family’s future, even if traditional limits feel too restrictive. The mega backdoor Roth with traditional IRA provides a unique opportunity for families to contribute significantly more to their retirement accounts than usual. In 2026, you can contribute up to $47,500 in after-tax dollars to your 401(k). This approach allows families to save more without the usual restrictions, making it easier to secure their children’s future.
By using this approach, families can watch their savings grow without the usual tax worries, helping them build a secure future. For instance, if a household contributes $40,000 in after-tax funds and allows it to grow before conversion, they can maximize their retirement savings potential. This strategy not only enhances wealth accumulation but also provides the flexibility to make career decisions that align with family values.
At Bright Advisers, we’re here to help families like yours navigate these financial waters with personalized planning and support. By utilizing the mega backdoor Roth with traditional IRA strategy, families can alleviate their financial stress while preparing for their children’s education and their own retirement. With the right strategies, you can secure a brighter future for your family, allowing you to focus on what truly matters.
As always, remember that past performance does not guarantee future results, and securities investments are subject to risk. Bright Advisers provides advisory services through Lifeworks Advisors, a registered investment adviser, emphasizing fiduciary duty and transparency with no hidden fees or conflicts of interest.
Implement Steps for Mega Backdoor Roth Contributions
Imagine feeling confident about your family’s financial future, knowing you have a solid plan in place. To effectively implement the Mega Backdoor Roth strategy, follow these essential steps:
- Check Your 401(k) Plan: Confirm that your employer’s 401(k) plan allows after-tax contributions and in-service withdrawals. Not all plans offer these features, so it’s important to check.
- Max Out Pre-Tax Contributions: Start by contributing the maximum allowable amount to your 401(k) as pre-tax contributions. For 2026, this limit is set at $24,500 for individuals under 50.
- Make After-Tax Contributions: Once you reach the pre-tax contribution limit, you can add more after-tax dollars. This allows your total contributions (including employer contributions) to reach up to $72,000.
- Convert to a Designated Account: After making your after-tax contributions, initiate a rollover to a designated IRA or convert them within your 401(k) to a designated account. This conversion helps your contributions grow tax-free.
- Monitor and Adjust: Regularly evaluate your contributions and investment performance to ensure they align with your family’s financial goals. Make adjustments as needed to maximize your benefits.
Many families feel overwhelmed by the complexities of retirement planning. By taking these steps, families can enhance their retirement savings using a mega backdoor Roth with traditional IRA. This creates a pathway to a secure financial future for their children. For example, consider Jay and Emma, a couple aiming to lessen monetary stress while preparing for their children’s education and their retirement. With the support of Bright Advisers, they found ways to optimize their tax planning and create a retirement plan that felt right for their family. Likewise, Emily and Mark, who sought financial independence, employed this approach to establish a strong base for their future, allowing them to make career choices based on their preferred work-life balance. By employing methods to decrease debt, oversee cash flow, invest wisely, and prepare for retirement, households can attain the flexibility and security they seek.
As always, please remember that past performance does not guarantee future results, and all investments are subject to risk. With the right guidance, you can turn financial stress into peace of mind for your family. Bright Advisers is dedicated to assisting households in making prudent financial choices and safeguarding wealth across generations.
Evaluate Benefits and Drawbacks of the Strategy
Imagine a strategy that could significantly enhance your family’s retirement savings while providing flexibility and tax benefits – sounds appealing, right? The Mega Backdoor Roth strategy presents several advantages and challenges that families should carefully evaluate:
Benefits:
- Increased Contribution Limits: Families can significantly boost their contributions to Roth accounts, with limits reaching up to $72,000 in 2026 for individuals under 50, and $80,000 for those over 50. This enhancement allows for greater retirement savings potential.
- Tax-Free Growth: Imagine watching your retirement savings grow without the burden of taxes – this is a significant benefit for families looking to build wealth over time. Plus, it allows for tax-free withdrawals of earnings after five years, provided the account holder is over 59 1/2.
- Flexibility in Withdrawals: These IRAs allow tax-free withdrawals of contributions at any time, giving families the freedom to manage their finances according to their needs without incurring penalties.
The success story of Allison and Brian, clients of Bright Advisers, exemplifies the power of strategic tax planning. By optimizing their tax situation, they not only secured their children’s future through education funding but also gained the ability to retire sooner. Their partnership with Bright Advisers enabled them to integrate tax optimization into their comprehensive monetary strategy, resulting in peace of mind and more quality time with their loved ones.
Drawbacks:
- Complexity: Navigating the Mega Backdoor Roth can feel overwhelming, especially with its intricate rules and tax implications. Families may benefit from consulting a knowledgeable financial advisor to navigate these complexities effectively.
- Potential Tax Implications: Families might face unexpected tax liabilities if they aren’t fully aware of the conversion process and its timing.
- Plan Limitations: It’s important to check if your 401(k) plan allows for after-tax contributions or in-service withdrawals, as this can affect whether the strategy of mega backdoor Roth with traditional IRA is right for you.
Additionally, households aged 60 to 63 can take advantage of the ‘super catch-up’ provision in 2025, allowing for an extra $3,750 in contributions, which further enhances their retirement savings potential. By evaluating these advantages and disadvantages, families can determine if the Mega Backdoor approach corresponds with their monetary objectives and individual situations.
Disclaimer: Investment approaches involve risk, and past performance does not guarantee future results. Families should consult with a registered investment adviser to understand the risks associated with their investment decisions. By understanding both the advantages and challenges of the mega backdoor Roth with traditional IRA, families can make informed decisions that align with their financial goals and values.
Consult a Financial Professional for Tailored Advice
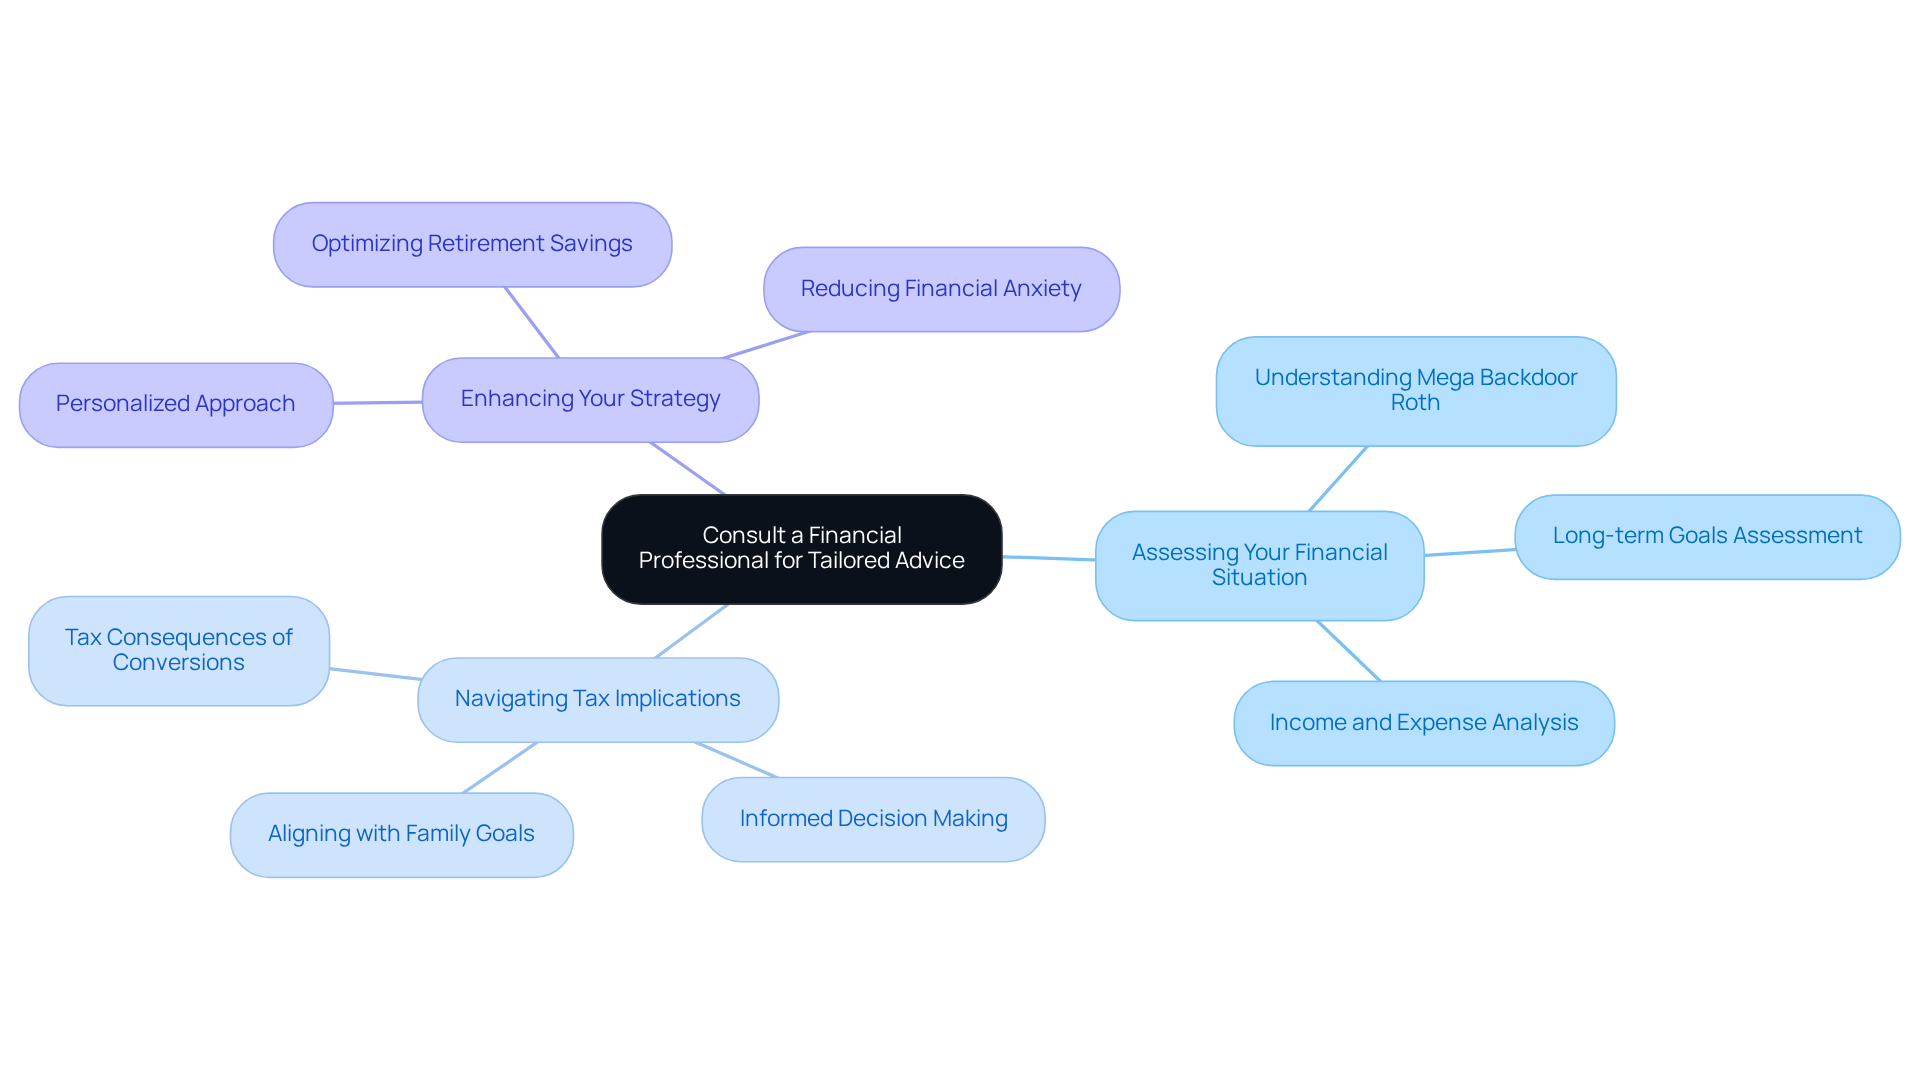
Imagine feeling overwhelmed by financial decisions while trying to secure your family’s future. Working with a caring team like Bright Advisers can provide the support and insights your family truly needs. A dedicated advisor can help you in important ways:
- Assessing Your Financial Situation: They will help you understand how the Mega Backdoor Roth fits into your overall financial plan, considering your income, expenses, and long-term goals. Families who take the time to plan often feel more secure and informed about their financial futures.
- Navigating Tax Implications: Professional guidance on the potential tax consequences associated with conversions and contributions ensures that you make informed decisions that align with your family’s goals. Many families find that working with a trusted advisor leads to better financial outcomes and peace of mind.
- Enhancing Your Strategy: Collaborating with a financial specialist allows you to create a tailored approach that optimizes your retirement savings while reflecting your family’s values. For instance, families who sought advice from money experts reported feeling less financial anxiety, with many feeling more secure in their decisions.
Take Jay and Emma, for example. With Bright Advisers’ support, they crafted a financial plan that balanced their current needs with future goals, easing their worries about education costs and retirement. This balance between present responsibilities and long-term aspirations shows how personalized guidance can lead to positive financial outcomes.
By seeking tailored advice, families can confidently implement the mega backdoor roth with traditional ira strategy, transforming their financial anxiety into confidence and clarity, which ensures a brighter future for their children.
Conclusion
Imagine feeling empowered to secure your family’s future with the Mega Backdoor Roth strategy, especially when paired with a traditional IRA. This approach allows for significantly higher contributions than traditional methods, enabling families to build a more prosperous future for their children. When you embrace this strategy, you can navigate the complexities of retirement planning with newfound confidence and clarity.
Throughout this article, we’ve shared key insights on how to effectively utilize the Mega Backdoor Roth, including essential steps for contributions, the benefits of tax-free growth, and the flexibility it provides. Many families feel lost when it comes to planning for their future, unsure of where to start or what steps to take. We encourage you to evaluate both the advantages and potential drawbacks of this strategy, ensuring that your financial decisions align with your long-term goals. With the right guidance, families can turn confusion into clarity, making informed decisions that pave the way for a secure future.
We encourage you to reach out to a caring financial advisor, like those at Bright Advisers, who can help you tailor your approach and make the most of your retirement savings. Ultimately, the journey toward financial security for families is not just about numbers; it’s about creating a legacy of intentional living and wise wealth management. By taking proactive steps and seeking personalized guidance, families can transform financial stress into peace of mind, allowing them to focus on what truly matters-building a brighter future together. As you consider the Mega Backdoor Roth strategy, remember that with the right support, you can turn your financial dreams into reality for your family.
Frequently Asked Questions
What is the Mega Backdoor Roth IRA?
The Mega Backdoor Roth IRA is a strategy that allows families to contribute significantly more to their retirement accounts than traditional limits permit, specifically by contributing up to $47,500 in after-tax dollars to a 401(k) in 2026.
How does the Mega Backdoor Roth IRA benefit families?
This approach enables families to save more for their future without the usual restrictions, allowing for greater wealth accumulation and the flexibility to make career decisions that align with family values.
What is the potential savings growth using the Mega Backdoor Roth IRA?
For example, if a household contributes $40,000 in after-tax funds and allows it to grow before conversion, they can maximize their retirement savings potential and watch their savings grow without typical tax concerns.
How can Bright Advisers assist families with the Mega Backdoor Roth IRA?
Bright Advisers provides personalized planning and support to help families navigate financial decisions, including utilizing the Mega Backdoor Roth IRA strategy to alleviate financial stress and prepare for their children’s education and retirement.
Are there any risks associated with the Mega Backdoor Roth IRA?
Yes, as with any investment strategy, there are risks involved. It’s important to remember that past performance does not guarantee future results, and securities investments are subject to risk.
What is the fiduciary duty of Bright Advisers?
Bright Advisers emphasizes fiduciary duty and transparency, ensuring there are no hidden fees, commissions, or conflicts of interest, and they charge simple, customizable monthly fees.
Who founded Bright Advisers and when?
Bright Advisers was founded by Kevin Luu and Kathleen Chou in 2010, establishing credibility and heritage in providing financial advisory services.
What advisory services does Bright Advisers provide?
Bright Advisers provides advisory services through Lifeworks Advisors, a registered investment adviser, ensuring compliance and transparency in their financial planning services.
List of Sources
- Understand the Mega Backdoor Roth IRA
- Navigating the Mega Backdoor Roth Limits 2026: A Guide for High Earners (https://commonsllc.com/insights/mega-backdoor-roth-limits-2026)
- Mega Backdoor Roths: How They Work, Limits – NerdWallet (https://nerdwallet.com/retirement/learn/mega-backdoor-roths-work)
- Mega Backdoor Roth 2026: $47,500+ vs $7,500 Backdoor (https://sdocpa.com/roth-vs-mega-backdoor-roth)
- Making a Backdoor or Mega Backdoor Roth Contribution in 2026 (https://merceradvisors.com/retirement/making-a-backdoor-or-mega-backdoor-roth-contribution-in-2026)
- Implement Steps for Mega Backdoor Roth Contributions
- 401(k) Contribution Limits |2026, 2025 and Earlier | ADP (https://adp.com/resources/articles-and-insights/articles/4/401k-contribution-limits.aspx)
- After-Tax 401(k) Contributions – NerdWallet (https://nerdwallet.com/retirement/learn/after-tax-401k-contributions)
- Mega Backdoor Roth 2026: $47,500+ vs $7,500 Backdoor (https://sdocpa.com/roth-vs-mega-backdoor-roth)
- After-Tax 401(k) Contributions | U.S. Bank (https://usbank.com/retirement-planning/financial-perspectives/after-tax-401k-contributions.html)
- Evaluate Benefits and Drawbacks of the Strategy
- Mega Backdoor Roth: What They Are And Contribution Limits December 2025 Edition (https://forbes.com/sites/investor-hub/article/mega-backdoor-roth-what-it-is-contribution-limits)
- Backdoor Roth IRA and Mega Backdoor Roth 401(k) Plans (https://wealthspire.com/blog/the-simple-truth-about-backdoor-roth-ira-and-mega-backdoor-roth-401-k-plans)
- Mega Backdoor Roth IRA: What It Is & How It Works (https://farther.com/foundations/mega-backdoor-roth-iraa-what-it-is-how-it-works)
- Mega Backdoor Roth IRA: A Powerful Strategy for High Earners (https://edelmanfinancialengines.com/education/retirement/mega-backdoor-roth-ira)
- What is a mega backdoor Roth? | IRA conversion | Fidelity (https://fidelity.com/learning-center/personal-finance/mega-backdoor-roth)
- Consult a Financial Professional for Tailored Advice
- 27% of Americans use financial advisors, with 60% prioritizing trust as the top factor (https://yougov.com/en-us/articles/50180-27-americans-use-financial-advisors-60-prioritizing-trust-as-the-top-factor)
- Study: Americans Working With CFP® Professionals Enjoy Greater Financial Well-Being (https://cfp.net/news/2025/02/news-releases/americans-working-with-cfp-professionals-enjoy-greater-financial-well-being)
- Survey reveals the rising importance of financial planning at retirement (https://troweprice.com/en/us/insights/importance-of-financial-planning-at-retirement)
- Cerulli Associates | 53% of Households Believe in the Importance of a… (https://cerulli.com/press-releases/53-of-households-believe-in-the-importance-of-a-financial-plan)
- Wealth and Well-Being: Financial Planners Linked to Improved Mental Health, Family Life (https://wealthtender.com/insights/financial-planning/financial-planners-linked-improved-mental-health-family-life)

Kevin has advised high-income W-2 tech and biotech families since 2015, and leads the education-first Age Five Family Office from Brea, California.
Connect on LinkedIn → · About KevinThis is part of how we approach Tax Management for high-income W-2 families at Bright Advisers.
Keep reading