

Overview
The main focus of this article is to guide you through the SEP IRA deposit deadline and why it matters for securing your family’s financial future. It’s crucial to understand that contributions need to be made by the tax filing deadline, typically April 15, to enjoy the tax deductibility benefits.
Imagine if you could enhance your retirement planning—this is where SEP IRAs shine. They offer fantastic tax advantages and higher contribution limits, making them an excellent choice for self-employed individuals and small business owners.
Together, we can navigate this journey towards effective financial planning for your family.
Key Highlights:
- A SEP IRA is a retirement plan tailored for self-employed individuals and small business owners, funded exclusively through employer contributions.
- Contributions to a SEP IRA are tax-deductible for employers, lowering taxable income and providing significant tax benefits.
- For 2025, employers can contribute up to 25% of an employee’s compensation or a maximum of $70,000, whichever is lower.
- Employers have the flexibility to adjust funding amounts each year based on business performance.
- Employees are fully vested in their SEP IRA contributions immediately upon deposit.
- Equal contributions are required for all eligible employees, and employees cannot contribute to their own SEP IRAs.
- The SEP IRA deposit deadline aligns with the tax filing deadline, typically April 15, and contributions must be made by this date to be tax-deductible.
- Eligibility criteria for employees include being at least 21 years old, having worked for the business for three of the last five years, and earning at least $750.
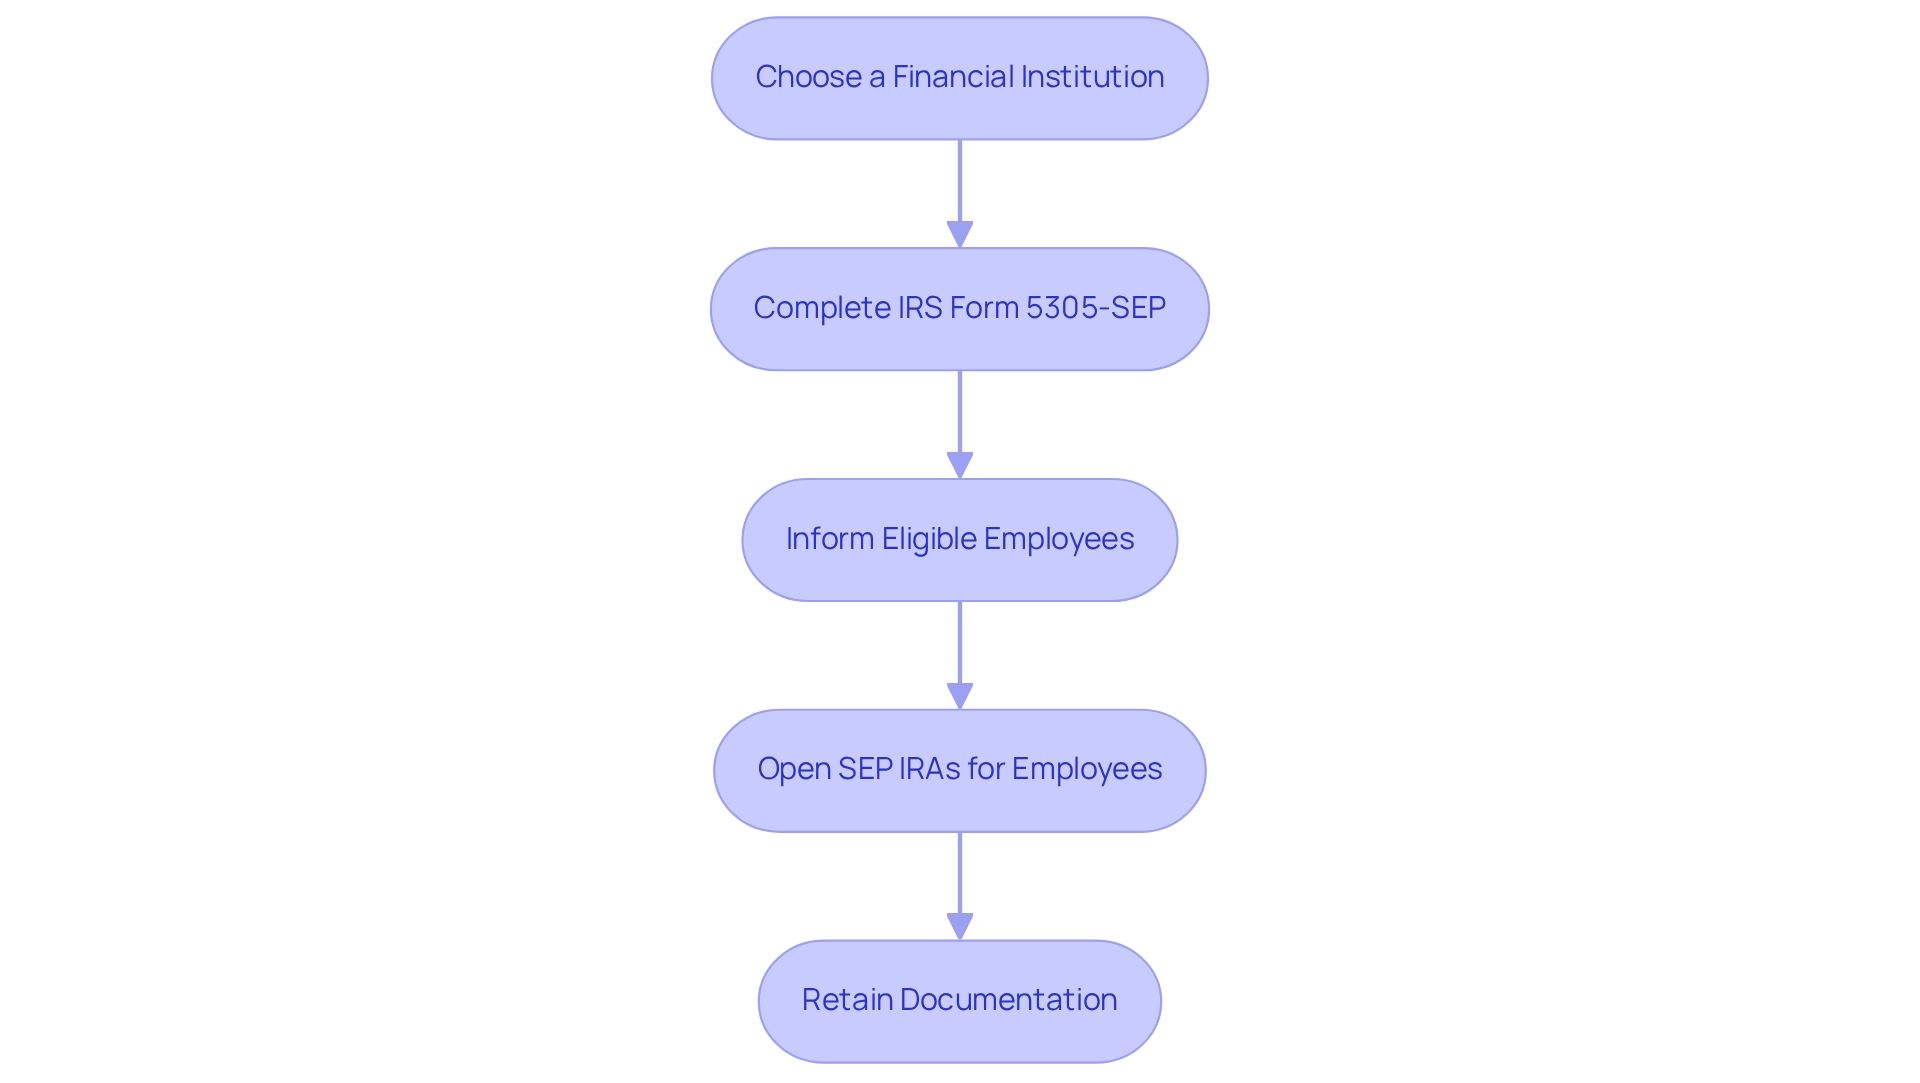
- To set up a SEP IRA, choose a financial institution, complete IRS Form 5305-SEP, inform eligible employees, and retain documentation.
- Planning ahead and consulting with a tax professional can help ensure timely contributions and maximize tax benefits.
Introduction
In the journey of retirement planning, the Simplified Employee Pension (SEP) IRA emerges as a vital ally for self-employed individuals and small business owners. Imagine a retirement plan that not only supports your financial goals but also adapts to the ebb and flow of your business’s performance. This unique structure, where employer-funded contributions play a central role, brings significant tax advantages, providing a sense of relief as families navigate the complexities of financial security. It’s important to understand the nuances of SEP IRAs, as they can be a crucial part of securing your family’s future.
This article will gently guide you through the essential features of SEP IRAs, including contribution limits and setup processes. We’ll explore strategic planning that can empower you to maximize the benefits of a SEP IRA. Together, we can navigate this journey, ensuring that you have the tools necessary to build a secure financial future for your loved ones.
Understand the Basics of SEP IRAs
A Simplified Employee Pension (SEP) IRA is a wonderful retirement plan designed specifically for self-employed individuals and small business owners. Unlike traditional IRAs, which allow personal deposits, SEP IRAs are exclusively funded through employer contributions. Let’s explore some of the key features that make this plan so beneficial for families:
- Tax Advantages: Contributions to a SEP IRA are tax-deductible for the employer, effectively lowering taxable income and providing significant tax benefits. This is especially helpful for families looking to improve their financial situation. As James Royal, Ph.D., notes, “The SEP IRA offers a way for small businesses to contribute to their employees’ retirement plans.”
- Higher Contribution Limits: For 2025, employers can contribute up to 25% of an employee’s compensation or a maximum of $70,000, whichever is lower. This makes it an appealing option for maximizing retirement savings. For comparison, the limit for Solo 401(k) deposits for 2024 is $76,500, highlighting the competitive nature of these retirement plans.
- Flexibility: Employers have the freedom to choose their funding amounts each year, allowing for adjustments based on business performance and financial health. This flexibility can be crucial for families navigating financial challenges.
- Immediate Vesting: Employees are fully vested in their SEP IRA contributions as soon as they are made, ensuring they have complete ownership of the funds right away.
However, it’s important to consider some potential drawbacks of SEP IRAs. For example, there is a requirement for equal contributions to all employees, and employees cannot contribute themselves, which may limit flexibility for some business owners. Recent statistics show that SEP IRAs are becoming increasingly popular among self-employed individuals, with many leveraging these plans to boost their retirement savings. Financial advisors emphasize the tax advantages of SEP IRAs, noting that they can significantly reduce taxable income while providing a solid retirement savings vehicle. For families, understanding these benefits is vital for effective financial planning, especially as they strive to create a secure future.
Additionally, withdrawals made before age 59½ may incur a 10% early withdrawal penalty, which is an important consideration for families needing access to their funds. Real-world examples illustrate how small business owners can use SEP IRAs to optimize their tax situation while ensuring their employees benefit from a strong retirement plan. Familiarizing yourself with these essentials will empower you to manage your SEP IRA effectively, particularly in relation to the SEP IRA deposit deadline, aligning it with your family’s financial aspirations. Remember, we’re here for you as you navigate this journey toward financial stability.
Know Your Contribution Limits and Deadlines
For the tax year 2025, the limits for a SEP IRA are thoughtfully designed to help you maximize your retirement savings. Imagine being able to contribute up to 25% of your compensation, with a maximum cap of $70,000—reflecting a $1,000 increase from the previous year due to inflation adjustments. This increase makes SEP IRAs particularly appealing for self-employed individuals and small business owners who are eager to enhance their retirement funds.
To be eligible for a SEP IRA, employees must meet the following criteria:
- Be at least 21 years old
- Have worked for the business for three of the past five years
- Have earned at least $750 from the job in 2024 and 2025
It’s important to note that the SEP IRA deposit deadline for making contributions coincides with the tax filing deadline, typically April 15 of the following year. If you request an extension, payments can be made until the SEP IRA deposit deadline. Remember, adhering to this deadline is crucial, as contributions not submitted by this cutoff cannot be deducted from that year’s taxes. Proactive planning ensures you can maximize your retirement savings potential.
For households, understanding these guidelines is vital, as they significantly impact long-term financial stability. By staying informed about SEP IRA contribution limits and deadlines, you can make strategic decisions that align with your family’s financial goals. At Bright Advisers, we’re dedicated to providing customized wealth management solutions and reducing fund fees, helping young families navigate their financial futures with confidence. Moreover, SEP IRAs can be especially beneficial for small enterprises with limited staff, offering a valuable retirement savings option for families who are self-employed or considering starting a small business. Together, we can navigate this journey towards a secure financial future.
Set Up Your SEP IRA Correctly
Setting up a SEP IRA can feel overwhelming, but we’re here to guide you through the process with care and support. By following these key steps, you can ensure compliance while maximizing the benefits for your family’s financial future.
- Choose a Financial Institution: Start by selecting a reputable bank, brokerage, or financial institution that offers SEP IRAs. Look for one that provides robust support tailored to small businesses and families, like Bright Advisers, which focuses on minimizing fund fees to make wealth management more accessible.
- Complete IRS Form 5305-SEP: This essential form establishes your SEP plan. It’s important to fill out all required information accurately to avoid any compliance issues that could cause stress later on.
- Inform Eligible Employees: Take the time to notify all eligible employees about the SEP plan. Provide them with the necessary documentation and clarify how the plan works, including its limits and advantages. Open SEP IRAs for Employees: Each eligible employee must have a SEP IRA account established to accept deposits, ensuring everyone can benefit from this valuable retirement savings plan.
- Retain Documentation: Keep copies of the completed Form 5305-SEP and any relevant documents for your records. This is essential for ensuring adherence and for future reference, giving you peace of mind.
By following these steps, you can efficiently establish a SEP IRA, helping you meet the deposit deadline and significantly enhancing your household’s financial future. Bright Advisers empowers young families by offering customized financial planning strategies, keeping you informed about the highest input for 2025, which is the lesser of 25% of an employee’s compensation or $69,000.
Avoid common mistakes, such as failing to notify employees or not retaining proper documentation, as these can lead to complications down the line. For instance, employers must ensure that payments are made equitably among all eligible staff, as highlighted in case studies on employer payments to SEP IRAs. This structure promotes transparency and fairness in retirement savings, which is crucial for young families considering this option. Together, we can navigate this journey towards a secure financial future.
Make Contributions Before the Deadline
To ensure your SEP IRA contributions are made before the deadline, follow these essential steps:
- Calculate Your Amount to Give: Take a moment to evaluate your business income. Understanding how much you can contribute, while considering the limits for 2025, is a crucial first step.
- Plan Ahead: Imagine the peace of mind that comes from setting reminders well in advance of the SEP IRA deposit deadline on April 15. This simple act can help you avoid the last-minute rush that often leads to missed donations.
- Utilize Automated Transfers: If your financial institution offers this option, consider arranging automatic transfers to your SEP IRA. This ensures your payments are consistently made on time, allowing you to focus on what truly matters—your family.
- Consult with a Tax Professional: Engaging a tax advisor before making contributions can be invaluable. They can help you maximize your tax benefits and ensure compliance with IRS regulations. As Brian Dobbis, Retirement Solutions Lead, wisely notes, “These materials do not purport to provide any legal, tax, or accounting advice.”
By applying these strategies, you can feel confident that your contributions to your SEP IRA will be made by the deposit deadline, strengthening your household’s financial future. Statistics show that households who plan ahead can save significantly—up to 74%—by optimizing their investment and tax strategies. Additionally, consider the journey of families like Allison and Brian with Bright Advisers. Their story illustrates how effective tax planning can lead to substantial financial benefits, including enhanced wealth accumulation and optimized tax situations. By prioritizing these steps, you not only simplify the process but also align with the goal of building a strong financial foundation for your family. Remember, we’re here for you, and together, we can navigate this journey.
Conclusion
Understanding the intricacies of a Simplified Employee Pension (SEP) IRA is essential for self-employed individuals and small business owners who want to secure their financial futures. This retirement plan offers significant tax advantages, higher contribution limits, and the flexibility to adapt contributions based on business performance. Imagine being able to leverage the benefits of a SEP IRA to enhance your retirement savings effectively by familiarizing yourself with the basics, including eligibility requirements and immediate vesting.
Timely contributions are pivotal. It’s crucial to stay informed about limits and deadlines for the upcoming tax year. With the potential for substantial contributions—up to 25% of compensation or $70,000—strategic planning and proactive management can significantly impact your long-term financial security. Setting up a SEP IRA correctly involves:
- Choosing a reputable financial institution
- Completing necessary IRS forms
- Ensuring all eligible employees are informed
This fosters a transparent and inclusive retirement savings plan.
Ultimately, the SEP IRA serves as a powerful tool for families and small business owners alike. By maximizing contributions and adhering to deadlines, you can build a robust financial foundation for your loved ones. Embracing the nuances of this retirement plan not only optimizes tax benefits but also instills confidence in navigating the complexities of financial planning. Together, we can navigate this journey, paving the way toward a secure and prosperous future for your family.
Frequently Asked Questions
What is a Simplified Employee Pension (SEP) IRA?
A SEP IRA is a retirement plan specifically designed for self-employed individuals and small business owners, funded exclusively through employer contributions.
What are the tax advantages of a SEP IRA?
Contributions to a SEP IRA are tax-deductible for the employer, which lowers taxable income and provides significant tax benefits, making it advantageous for families looking to improve their financial situation.
What are the contribution limits for a SEP IRA in 2025?
For 2025, employers can contribute up to 25% of an employee’s compensation or a maximum of $70,000, whichever is lower.
How does a SEP IRA provide flexibility to employers?
Employers can choose their funding amounts each year, allowing them to adjust contributions based on business performance and financial health.
When do employees become vested in their SEP IRA contributions?
Employees are fully vested in their SEP IRA contributions as soon as they are made, meaning they have complete ownership of the funds immediately.
What are some potential drawbacks of a SEP IRA?
A key drawback is the requirement for equal contributions to all employees, and employees cannot make personal contributions, which may limit flexibility for some business owners.
What penalty applies to withdrawals from a SEP IRA before age 59½?
Withdrawals made before age 59½ may incur a 10% early withdrawal penalty.
Why are SEP IRAs becoming popular among self-employed individuals?
SEP IRAs are increasingly popular due to their tax advantages and ability to help boost retirement savings for self-employed individuals and small business owners.
How can small business owners use SEP IRAs to optimize their tax situation?
Small business owners can leverage the tax-deductible contributions to reduce their taxable income while providing their employees with a strong retirement plan.
List of Sources
- Understand the Basics of SEP IRAs
- SEP IRA Contribution And Income Limits For 2025 | Bankrate (https://bankrate.com/retirement/sep-ira-contribution-and-income-limits)
- SEP IRA Guide: Rules, Benefits, and Contributions Explained (https://businessinsider.com/personal-finance/investing/sep-ira)
- SEP-IRA Contribution Limits For 2024 & 2025: How To Maximize Retirement Savings in May (https://forbes.com/sites/investor-hub/article/sep-ira-contribution-limits)
- SEP IRA contribution limits for 2024 and 2025 | Fidelity (https://fidelity.com/learning-center/smart-money/sep-ira-contribution-limits)
- Know Your Contribution Limits and Deadlines
- SEP IRA Contribution Limits for 2025 (https://kiplinger.com/retirement/sep-ira/sep-ira-limits)
- SEP-IRA Contribution Limits 2025 | Maximize Your Retirement | Human Interest (https://humaninterest.com/learn/articles/sep-ira-contribution-limits)
- Set Up Your SEP IRA Correctly
- A complete guide to SEP IRAs: Why those who are self-employed should take a look (https://finance.yahoo.com/news/complete-guide-sep-iras-why-165126916.html)
- SEP-IRA Contribution Limits 2025 | Maximize Your Retirement | Human Interest (https://humaninterest.com/learn/articles/sep-ira-contribution-limits)
- SEP IRA contribution limits for 2024 and 2025 | Fidelity (https://fidelity.com/learning-center/smart-money/sep-ira-contribution-limits)
- SEP IRA contribution and income limits for 2024 and 2025: What retirement savers need to know (https://finance.yahoo.com/news/2023-sep-ira-contribution-income-200809218.html)
- Make Contributions Before the Deadline
- SEP IRA Contribution Limits for 2025 (https://kiplinger.com/retirement/sep-ira/sep-ira-limits)
- SEP IRA Contribution Limits for 2024 and 2025 (https://smartasset.com/retirement/sep-ira-contribution-limits)
- Retirement, HSA & Coverdell Accounts: Key Moves to Make Before April 15 | Lord Abbett (https://lordabbett.com/en-us/individual-investor/insights/retirement-planning/2025/retirement-hsa-coverdell-accounts-key-moves-to-make-before-april.html)
- Maximizing Your SEP IRA (https://epwealth.com/blog/maximizing-your-sep-ira)

Kevin has advised high-income W-2 tech and biotech families since 2015, and leads the education-first Age Five Family Office from Brea, California.
Connect on LinkedIn → · About Kevin