

Overview
This article serves as a heartfelt guide for young parents seeking to master ultra-high-net-worth (UHNW) investing. It highlights the critical importance of protecting your family’s wealth, fostering growth, and developing personalized strategies that reflect your unique family values and goals. Imagine if you could secure a prosperous financial future for your loved ones—this guide is here to help you envision that possibility.
By detailing the characteristics of ultra-high-net-worth individuals (UHNWIs), the article emphasizes the necessity of diversification and risk management. It’s important to understand that integrating tax-efficient strategies can significantly impact your family’s financial well-being. Each concept is presented with care, ensuring you feel supported every step of the way.
As you navigate this journey, remember that the goal is to create a secure and thriving environment for your family. Together, we can explore the benefits of effective wealth management, ensuring that your family’s aspirations align with your financial strategies. We’re here for you, ready to assist you in making informed decisions that resonate with your values.
In conclusion, this guide is more than just a resource; it’s a compassionate companion on your financial journey. With the right knowledge and support, you can confidently take the necessary steps to protect and grow your family’s wealth, ensuring a brighter future for generations to come.
Key Highlights:
- Ultra-high-net-worth investing is for individuals or families with a net worth of at least $30 million, focusing on wealth protection and growth.
- Key asset types include equities, fixed income, real estate, and alternatives, used to achieve financial goals like preservation and legacy planning.
- UHNWIs exhibit monetary sophistication and often have diverse portfolios, with 50% allocated to alternative assets, private equity, and real estate.
- Long-term wealth preservation, philanthropy, and proactive risk management are common priorities among UHNWIs.
- Young parents should assess financial goals, evaluate risk tolerance, and diversify assets when developing a personalised investment strategy.
- Regular evaluation of investment performance and alignment with family values are essential for effective financial planning.
- Risk management strategies include creating an emergency fund, utilising insurance, and implementing tax-efficient investment approaches.
- Consulting with tax professionals can help minimise tax burdens and ensure effective estate planning for wealth preservation.
Introduction
Navigating the world of ultra-high-net-worth investing can feel overwhelming, especially for young parents dedicated to securing their family’s financial future. As more individuals achieve net worths of $30 million or more, grasping the nuances of wealth management becomes not just beneficial—it’s essential.
This guide explores the strategies and characteristics that define ultra-high-net-worth investing, offering insights designed to empower parents in making informed financial choices. Imagine how families can effectively balance the growth of their wealth with the urgent need for security and legacy planning in an ever-evolving economic landscape. Together, we can navigate this journey.
Define Ultra-High-Net-Worth Investing
Ultra high net worth investing involves managing assets for individuals or families whose net worth is at least $30 million. This approach includes various strategies designed to protect and grow wealth while meeting specific financial goals. For young parents who want to secure their family’s financial future, understanding this concept is crucial. It encompasses different asset types such as:
- Equities
- Fixed income
- Real estate
- Alternative options
All strategically used to achieve goals like wealth preservation, growth, and legacy planning.
Imagine if you could navigate the complexities of wealth management with confidence. Understanding these intricacies empowers parents to appreciate the value of tailored financial plans that cater to their unique situations. With approximately 626,600 ultra-high-net-worth individuals globally, the demand for ultra high net worth investing and sophisticated asset management is on the rise. This highlights the importance of making informed decisions in this exclusive financial landscape.
Together, we can navigate this journey, ensuring that your family’s future is secure and prosperous. We’re here for you, ready to support you in crafting a personalized financial strategy that aligns with your family’s values and aspirations.

Understand the Characteristics of Ultra-High-Net-Worth Individuals
The distinctive traits of ultra-high-net-worth individuals (UHNWIs) can provide valuable insights for young parents in managing their family’s wealth through ultra high net worth investing. These traits can empower you to make informed decisions for your loved ones. Let’s explore them together:
-
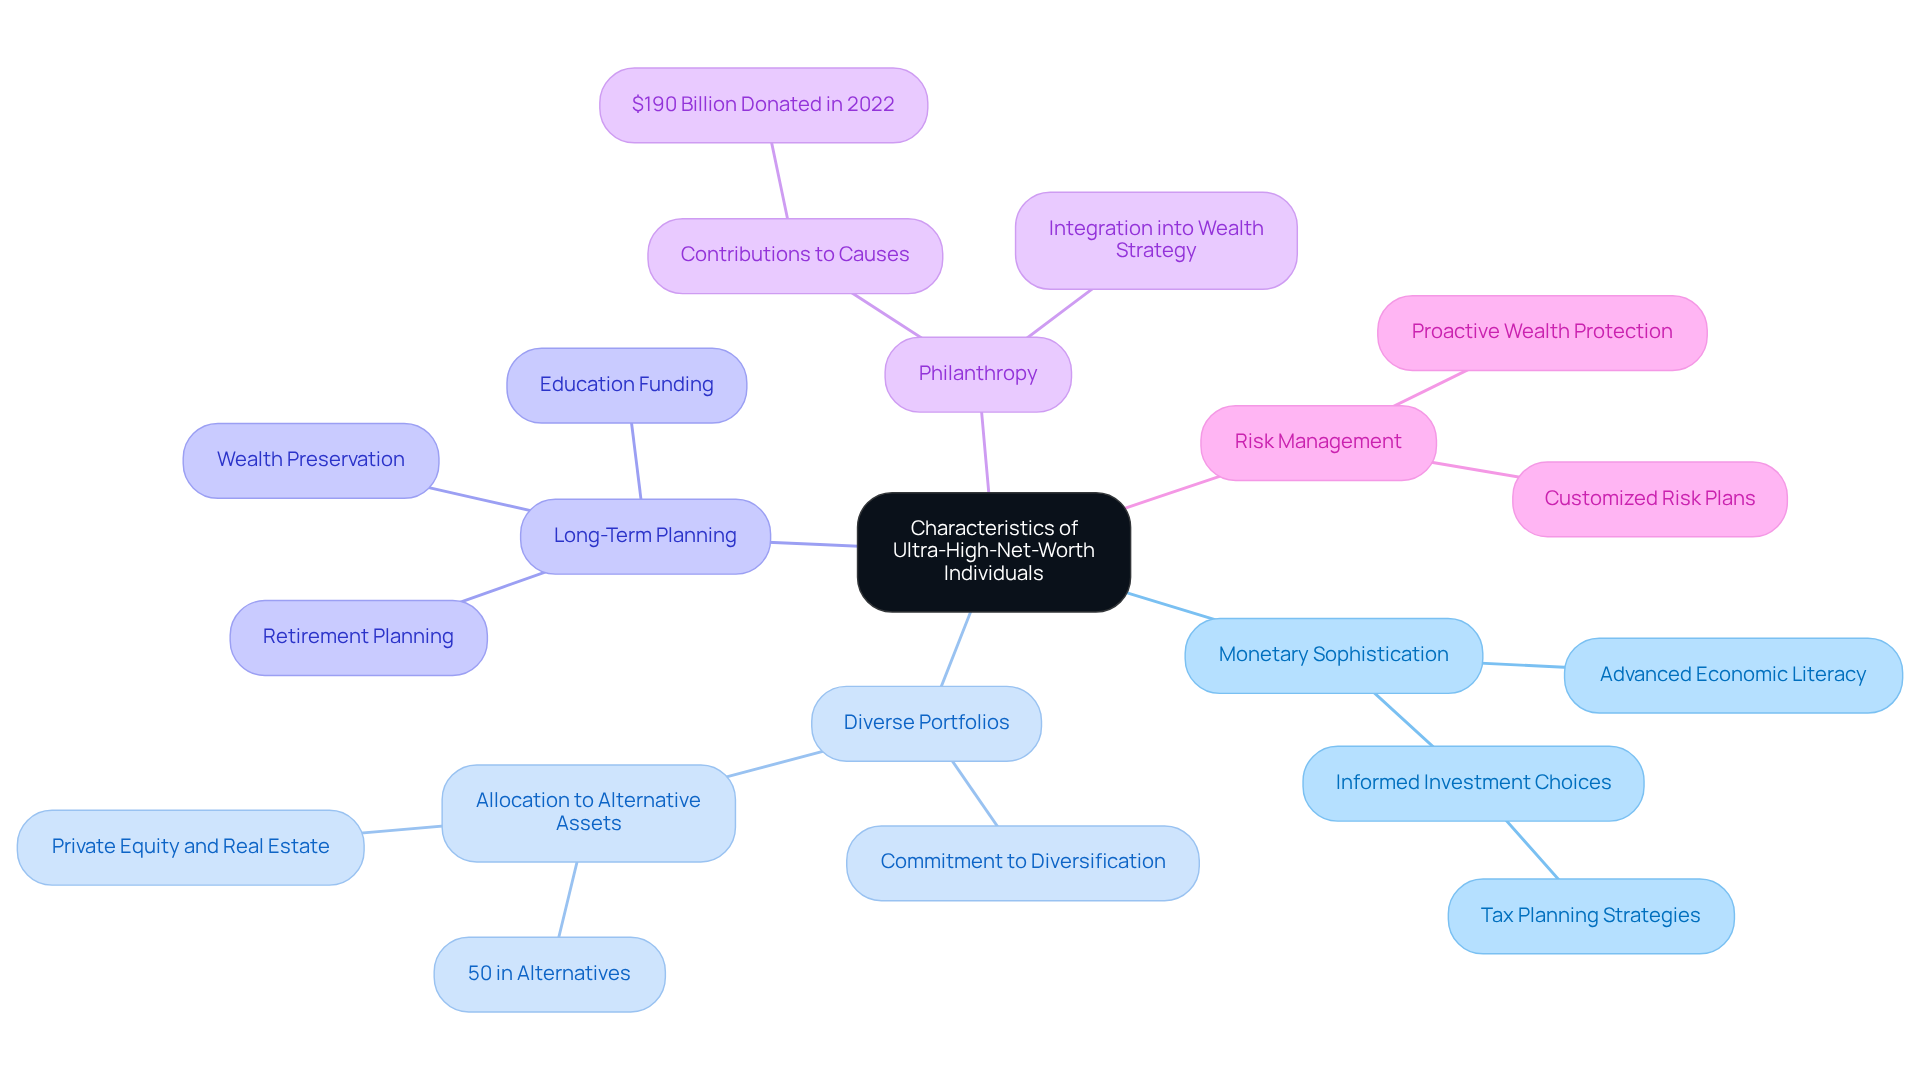
Monetary Sophistication: UHNWIs typically possess advanced economic literacy, enabling them to make informed investment choices. This knowledge is essential for navigating complex economic landscapes. For instance, clients like Allison and Brian, who sought assistance from Bright Advisers, learned how to enhance their economic potential through effective tax planning methods that reduced their tax obligations and fostered their wealth growth.
-
Diverse Portfolios: A defining characteristic of UHNWIs is their commitment to diversification. Approximately 50% of their portfolios are allocated to alternative assets, private equity, and real estate, reflecting their commitment to ultra high net worth investing, which not only mitigates risk but also enhances potential returns. Bright Advisers supports families like Emily and Mark in constructing varied portfolios that align with their financial goals and risk tolerance.
Many UHNWIs prioritize long-term wealth preservation and growth in their ultra high net worth investing strategies, aligning these strategies with personal values and legacy aspirations. This perspective nurtures a sustainable approach to wealth management. Through their collaboration with Bright Advisers, families have secured their children’s futures through education funding and gained the ability to retire sooner, reflecting a commitment to long-term planning.
Engaging in philanthropy is common among individuals involved in ultra high net worth investing, with many contributing to causes they are passionate about. In 2022, UHNW individuals donated a total of $190 billion to philanthropic causes, underscoring the importance of giving back while fulfilling personal values and reaping significant tax benefits. Bright Advisers encourages families to reflect on their philanthropic objectives as part of their overall financial strategy, integrating these interests into their wealth management plans.
Proactive risk management is a priority for those engaged in ultra high net worth investing, who adopt strategies to protect their wealth from market fluctuations. This approach is vital for maintaining economic stability over time. By partnering with Bright Advisers, families can create customized risk management plans that safeguard their assets and provide peace of mind, allowing them to focus on their personal and financial aspirations.
As Charles Kuralt wisely observed, ‘The affection for relatives and the esteem of friends is far more significant than riches and advantage.’ By embracing these principles, young parents can enhance their budgeting efforts, ensuring they are well-prepared to secure their family’s economic future. We’re here for you, guiding you every step of the way.
Develop a Personalized Investment Strategy
As young parents, developing a personalized investment strategy is essential for securing your family’s future. Here are some caring steps to guide you:
-
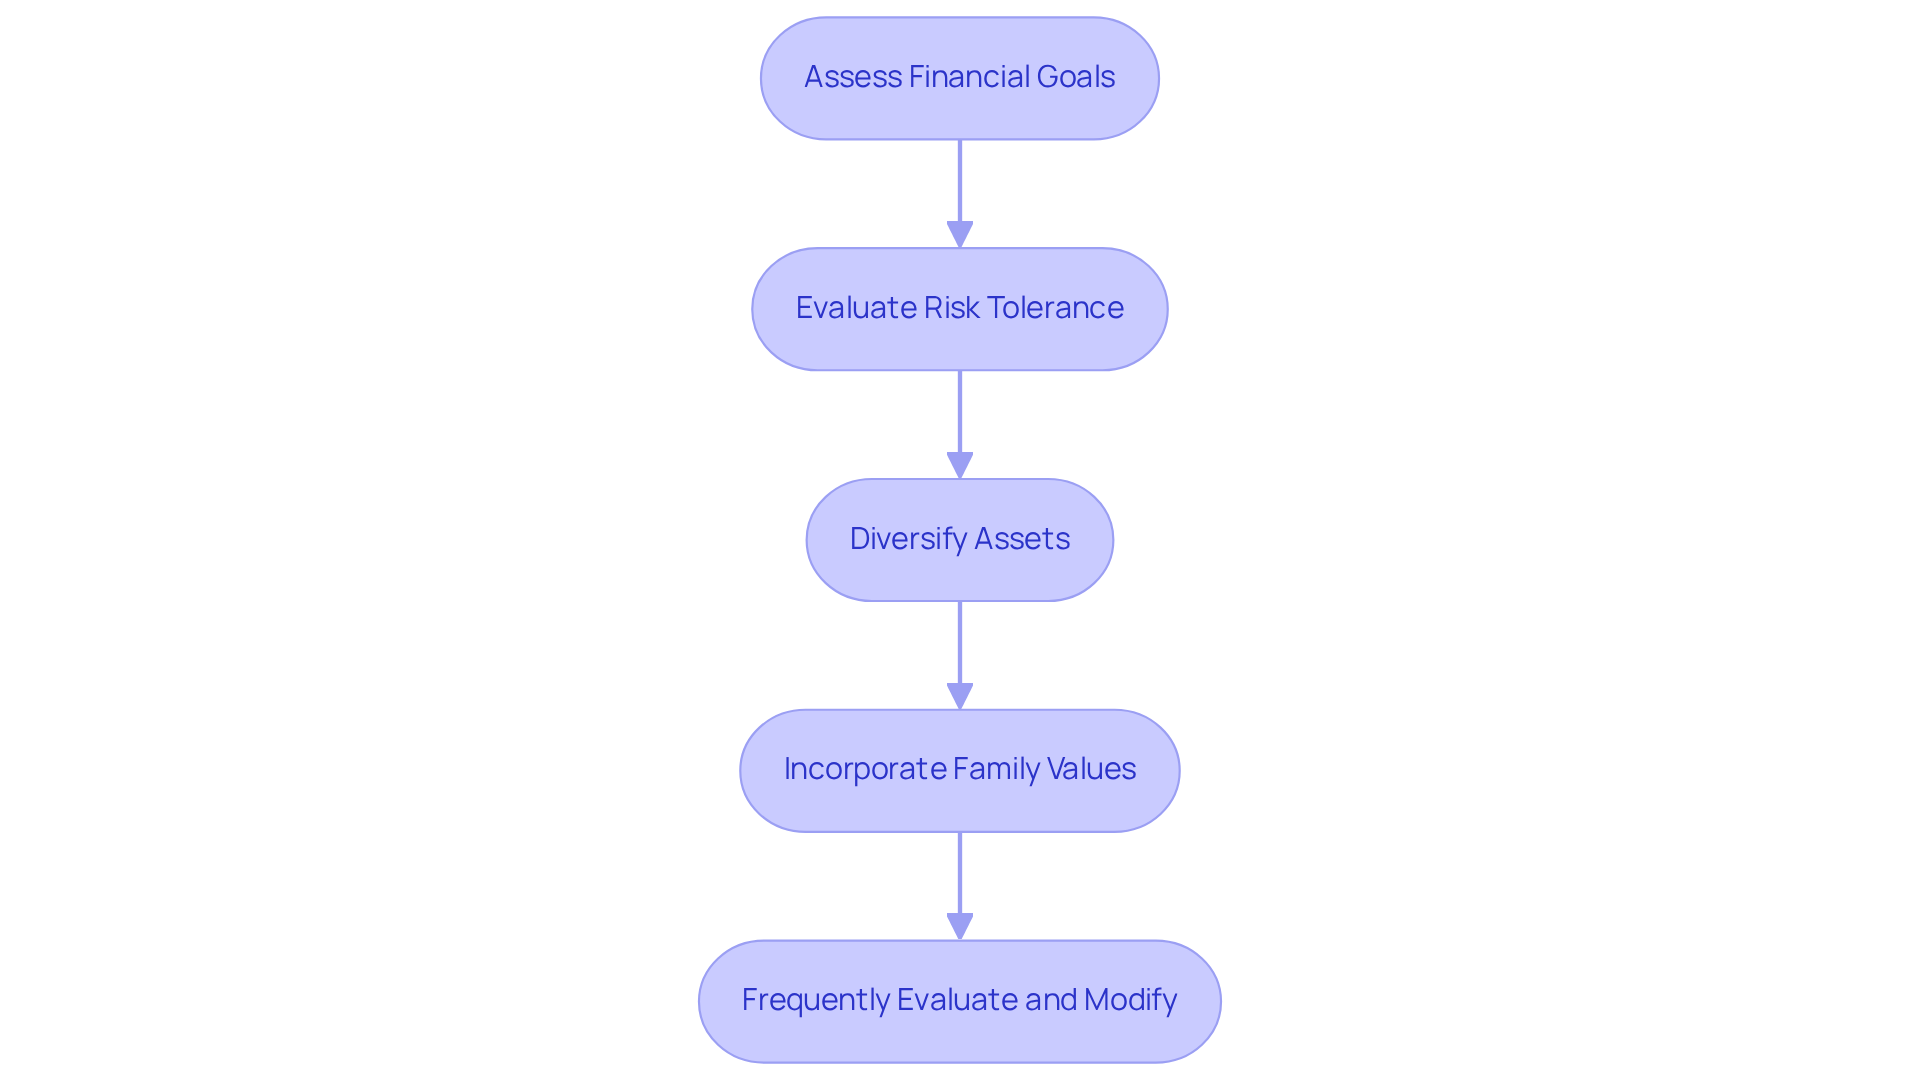
Assess Financial Goals: Begin by identifying your short-term and long-term financial objectives. Whether it’s saving for your children’s education, planning for retirement, or purchasing a home, having clarity in your goals will empower your investment decisions.
-
Evaluate Risk Tolerance: It’s vital to understand your family’s risk tolerance. Consider aspects like your age, income, and financial obligations. Research shows that many moderate investors find comfort in a balanced approach, typically allocating around 60% of their portfolio to stocks and 40% to bonds. This strategy can help manage risk while still pursuing growth.
-
Diversify Assets: Aim to create a well-rounded portfolio that includes a mix of asset classes—stocks, bonds, real estate, and alternative investments. This not only diversifies risk but also enhances potential returns, as different assets respond uniquely to market fluctuations.
-
Incorporate Family Values: Align your financial choices with your family’s principles. Whether you prioritize ethical investing or supporting local businesses, ensuring your monetary decisions reflect what matters most to you can foster a deeper sense of purpose in your financial journey.
-
Frequently Evaluate and Modify: Make it a habit to regularly assess your portfolio’s performance. This allows you to adapt to changing economic conditions and evolving family objectives. By staying proactive, you can ensure that your investments align with your family’s needs.
By following these nurturing steps, you can build a robust investment plan that seeks not just economic growth, but also supports your family’s unique aspirations. Remember, together, we can navigate this journey towards a secure future for your children.
Implement Risk Management and Tax Planning Strategies
To effectively manage risk and optimize tax liabilities, young parents are encouraged to explore the following strategies, which can be enhanced through the personalized financial planning services offered by Bright Advisers:
-
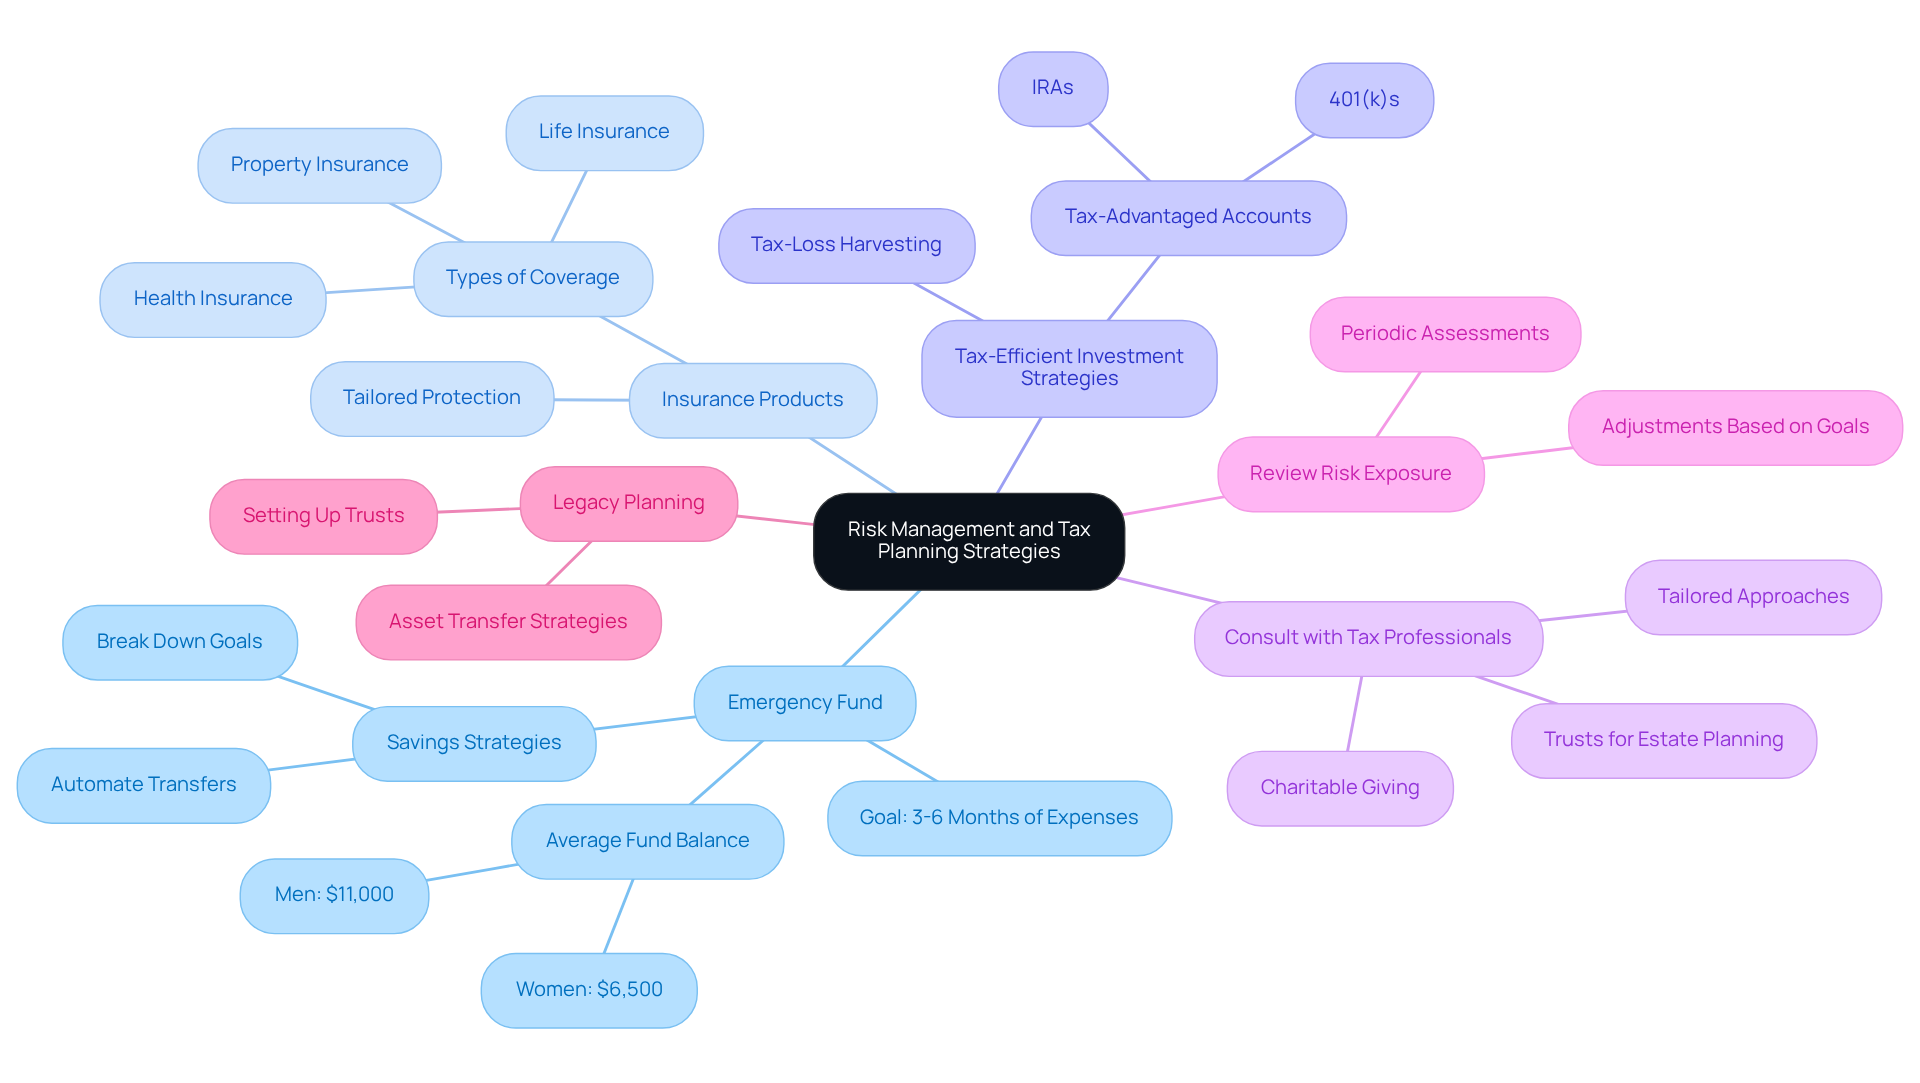
Create an Emergency Fund: Imagine having a safety net in place. Setting aside money in a liquid account can help you manage unforeseen costs, ensuring economic stability during crises. Experts recommend saving three to six months’ worth of essential expenses, providing peace of mind when facing unexpected challenges.
-
Utilize Insurance Products: It’s important to protect your family against unforeseen events. Investing in essential insurance policies, including life, health, and property insurance, safeguards your household’s financial security. Understanding the various types of coverage available can help you tailor protection to your family’s specific needs.
-
Implement Tax-Efficient Investment Strategies: Consider leveraging tax-advantaged accounts such as IRAs or 401(k)s for your retirement savings. Furthermore, explore approaches like tax-loss harvesting to counterbalance capital gains, enhancing overall investment returns while reducing tax responsibilities. Bright Advisers’ technology can assist you in managing these strategies effectively.
-
Consult with Tax Professionals: Collaborating with tax advisors at Bright Advisers can lead to tailored approaches that minimize your tax burdens. This may include charitable giving for tax deductions or utilizing trusts for effective estate planning, ensuring your wealth is preserved for future generations.
-
Regularly Review Risk Exposure: Periodically assessing your portfolio is crucial. Evaluate your risk exposure and make adjustments that correspond with your household’s risk tolerance and financial goals, ensuring your investment approach remains strong amid shifting market conditions.
-
Consider Legacy Planning: Legacy planning is an essential part of wealth management. Including this in your strategy ensures your assets are transferred according to your wishes. This may involve setting up trusts or other vehicles that can help manage your estate effectively.
By implementing these risk management and tax planning strategies, and leveraging the expertise and technology of Bright Advisers, parents can safeguard their wealth while maximizing financial outcomes. Together, we can navigate this journey, securing a prosperous future for your family.
Conclusion
Understanding the intricacies of ultra high net worth investing is essential for young parents aiming to secure their family’s financial future. This investment approach not only involves managing substantial assets but also encompasses strategic planning tailored to individual goals and values. Imagine navigating the complexities of wealth management with confidence, ensuring your family’s prosperity for generations to come.
Key insights from this guide emphasize the importance of:
- Defining clear financial goals
- Assessing risk tolerance
- Diversifying assets
- Incorporating family values into investment strategies
It’s important to understand that implementing effective risk management and tax planning strategies are crucial for protecting wealth and optimizing financial outcomes. Collaborating with experienced advisors, such as Bright Advisers, can further enhance these efforts, providing tailored solutions that align with your family’s aspirations.
Ultimately, the journey towards mastering ultra high net worth investing is not just about accumulating wealth; it’s about fostering a legacy that reflects your personal values and priorities. Young parents are encouraged to take proactive steps in their financial planning, ensuring you are well-equipped to secure a stable and prosperous future for your children. Together, we can navigate this journey and create a meaningful impact on your family’s financial future.
Frequently Asked Questions
What is ultra-high-net-worth investing?
Ultra-high-net-worth investing involves managing assets for individuals or families with a net worth of at least $30 million. It includes various strategies aimed at protecting and growing wealth while achieving specific financial goals.
What types of assets are included in ultra-high-net-worth investing?
The asset types included in ultra-high-net-worth investing are equities, fixed income, real estate, and alternative options.
What are the main goals of ultra-high-net-worth investing?
The main goals of ultra-high-net-worth investing are wealth preservation, growth, and legacy planning.
Why is understanding ultra-high-net-worth investing important for young parents?
Understanding ultra-high-net-worth investing is crucial for young parents who want to secure their family’s financial future. It helps them appreciate the value of tailored financial plans that cater to their unique situations.
How many ultra-high-net-worth individuals are there globally?
There are approximately 626,600 ultra-high-net-worth individuals globally.
What is the significance of tailored financial plans in ultra-high-net-worth investing?
Tailored financial plans are significant in ultra-high-net-worth investing as they align with the unique values and aspirations of families, ensuring informed decisions in the exclusive financial landscape.
List of Sources
- Define Ultra-High-Net-Worth Investing
- What’s considered ultra-high net worth? (https://cointracker.io/blog/whats-considered-ultra-high-net-worth)
- Understanding ultra-high-net-worth individuals (https://clearingcustody.fidelity.com/insights/spotlights/understanding-ultra-high-net-worth-individuals)
- Ultra-High-Net-Worth Individual (UHNWI): Definition and Criteria (https://investopedia.com/terms/u/ultra-high-net-worth-individuals-uhnwi.asp)
- The UHNWI of 2025: more complex, more global, more connected | Simple (https://andsimple.co/insights/the-uhnwi-of-today)
- Ultra-high net worth individuals statistics worldwide| Statista (https://statista.com/statistics/204072/distribution-of-ultra-high-net-worth-individuals-by-world-region?srsltid=AfmBOoqQoRnbIFnrUXppT3iVZLSMYhm7A-oJFGsR3uyntBEH2br_punr)
- Understand the Characteristics of Ultra-High-Net-Worth Individuals
- Understanding ultra-high-net-worth individuals (https://clearingcustody.fidelity.com/insights/spotlights/understanding-ultra-high-net-worth-individuals)
- 200 Quotes About Money And Personal Finance To Inspire You (https://marriagekidsandmoney.com/20-empowering-quotes-about-money-and-personal-finance)
- The unorganised state of Ultra High Net Worth wealth | HSBC Private Bank (https://privatebanking.hsbc.com/entrepreneurs/global-entrepreneurial-wealth-report/the-unorganised-state-of-ultra-high-net-worth-wealth)
- UHNW Individuals Use Alternative Investments – CIRE (https://cirepartners.com/2021/08/25/uhnw-individuals-use-alternative-investments)
- How the Wealthy Invest: A Shift to Private Equity and Real Estate (https://origininvestments.com/how-the-wealthy-invest-a-shift-to-private-equity-and-real-estate)
- Develop a Personalized Investment Strategy
- 12 Financial Planning Quotes for Building Wealth Wisely — Phillip James Financial (https://phillipjamesfinancial.com/blog/12-financial-planning-quotes-for-building-wealth-wisely)
- 2025 Refresh: Financial Planning Guide for New Parents (https://maleckifinancialgroup.com/blog/2025-refresh-financial-planning-guide-for-new-parents)
- What is Risk Tolerance? A Guide for Parents & Teens | Mydoh (https://mydoh.ca/learn/money-101/investing/what-is-risk-tolerance-a-guide-for-parents-teens)
- The Top 25 Investing Quotes of All Time (https://investopedia.com/financial-edge/0511/the-top-17-investing-quotes-of-all-time.aspx)
- Implement Risk Management and Tax Planning Strategies
- Home (https://federalreserve.gov/consumerscommunities/sheddataviz/emergency-savings.html)
- When the Unexpected Happens, Be Ready with an Emergency Fund (https://stlouisfed.org/publications/page-one-economics/2025/sep/when-unexpected-happens-be-ready-with-emergency-fund)
- 42% of Americans Don’t Have an Emergency Fund – Including 49% of Women (https://usnews.com/banking/articles/2025-financial-wellness-survey)
- Bankrate’s 2025 Emergency Savings Report | Bankrate (https://bankrate.com/banking/savings/emergency-savings-report)
- Emergency Fund: What Families Need to Know (https://meetfabric.com/blog/emergency-fund-amount-rainy-day-fund)

Kevin has advised high-income W-2 tech and biotech families since 2015, and leads the education-first Age Five Family Office from Brea, California.
Connect on LinkedIn → · About KevinThis is part of how we approach Investment & Risk Management for high-income W-2 families at Bright Advisers.
Keep reading