

Key Highlights
- Life insurance serves as a financial promise to loved ones, with types including term, whole, and universal life, each catering to different needs.
- Long-term care (LTC) involves services for individuals unable to perform daily activities, impacting financial planning for families.
- Key strategies for using life insurance for LTC funding include living benefit riders, settlements, cash value loans, and hybrid policies.
- Living benefit riders allow access to a portion of the death benefit for immediate LTC expenses, providing financial relief.
- Selling a policy can yield cash for LTC expenses, with the settlement market offering significant potential value.
- Permanent life insurance policies accumulate cash value, which can be borrowed against, though it may affect the death benefit.
- Families should regularly review their life insurance policies and consult with financial advisors at Bright Advisers for tailored strategies.
- Challenges in using life insurance for LTC include policy limitations, potential impacts on death benefits, tax consequences, and health requirements.
- Understanding the terms of your policy and planning ahead are crucial for making informed decisions regarding life insurance and LTC.
Introduction
Imagine the peace of mind that comes from knowing your family is protected, even in uncertain times. Navigating the world of life insurance can feel overwhelming, especially when you think about how it can help cover long-term care costs. For families with young children, understanding how to use life insurance effectively not only secures your financial future but also ensures that your loved ones are cared for when they need it most.
As the demand for long-term care rises, it’s important to consider how families can utilize life insurance to manage these expenses without sacrificing their financial stability. Together, we can explore the strategies that will help you make informed decisions, ensuring your family is cared for and your legacy is secure.
Understand Life Insurance Basics and Long-Term Care Needs
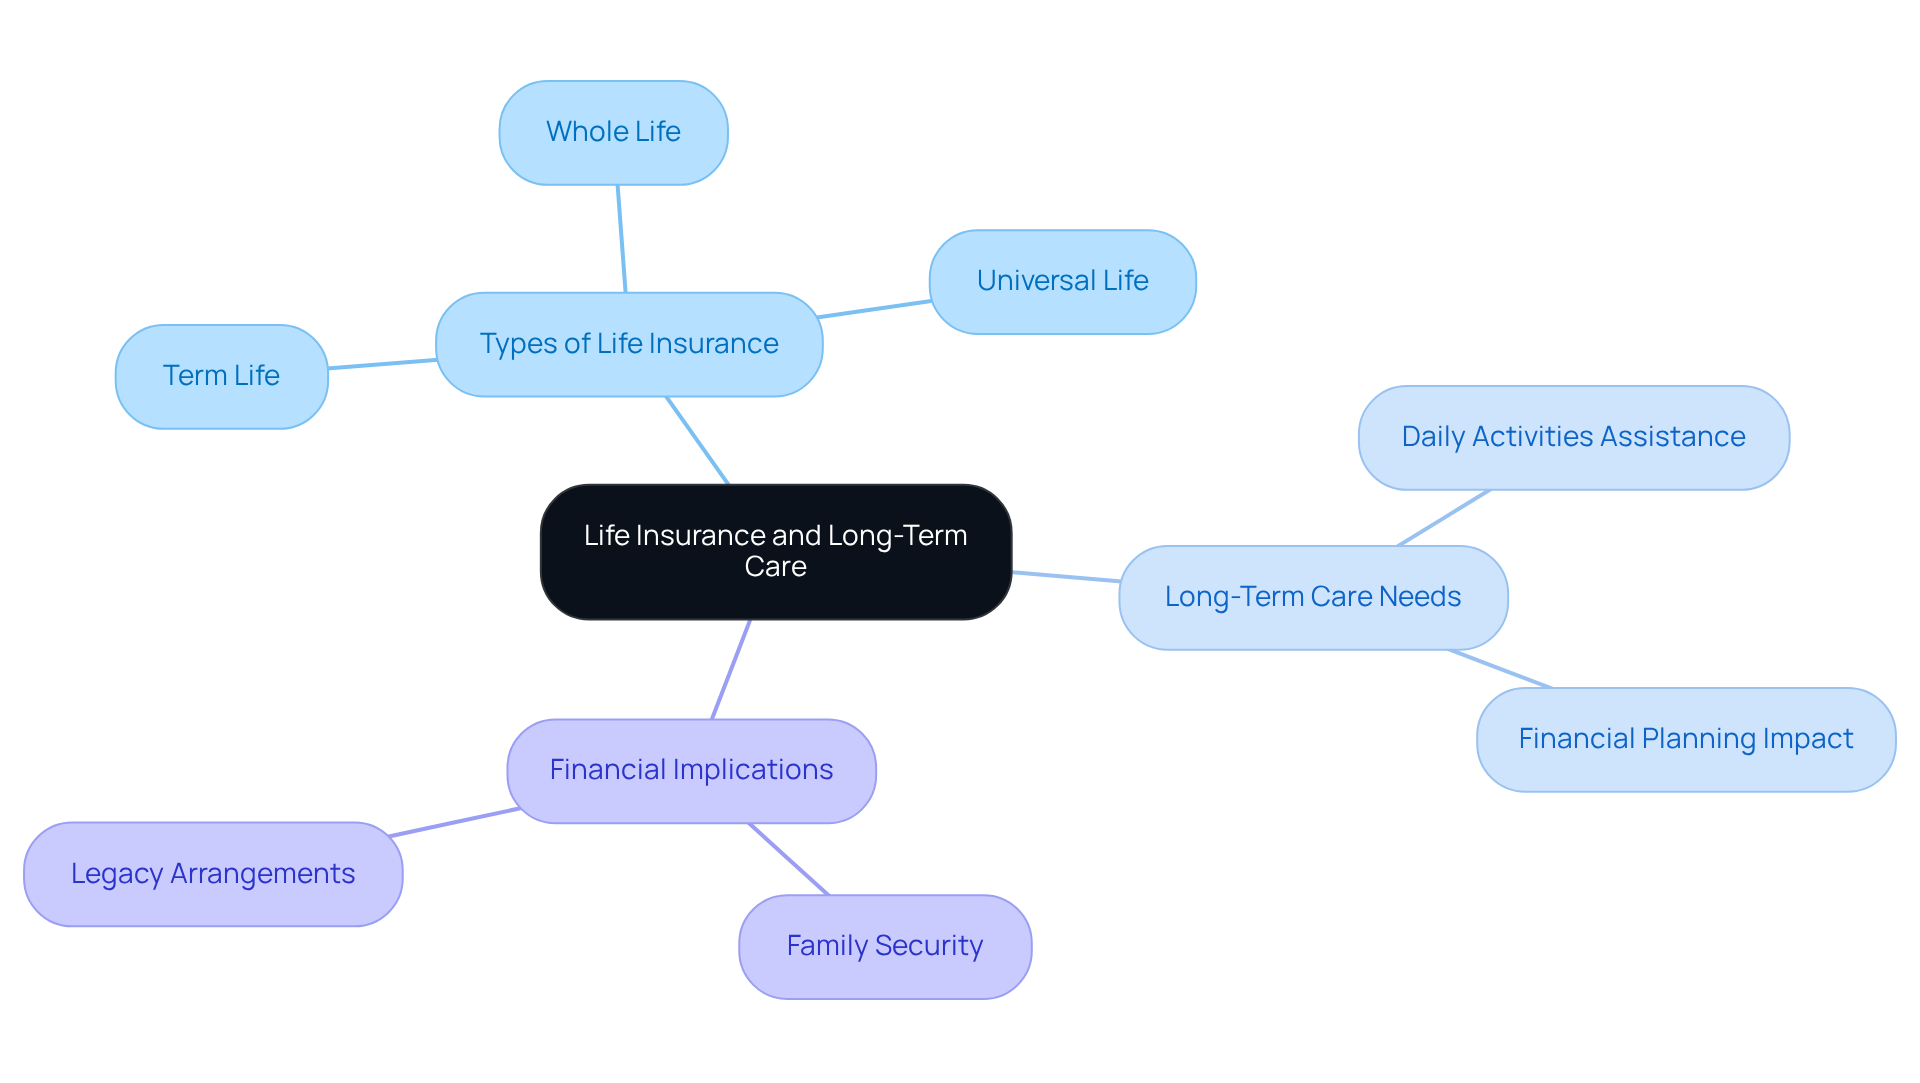
Imagine navigating the complexities of using life insurance to pay for long term care while trying to secure your family’s future; it’s a challenge many parents face. Understanding the importance of using life insurance to pay for long term care is key to effectively managing your family’s future expenses. Life insurance is more than just a policy; think of it as a promise to your loved ones – a way to provide for them even when you’re no longer there. The main types of life insurance include term life, whole life, and universal life, each offering unique features tailored to different financial needs.
Long-term care (LTC) encompasses a range of services designed to assist individuals who can no longer carry out daily activities on their own. This might involve help with bathing, dressing, or managing medications. It’s important to recognize that the need for extended support can significantly impact your financial planning, especially for families with young children who are considering using life insurance to pay for long term care to secure their future.
Key Points:
- Types of Life Insurance: Understand the distinctions between term, whole, and universal life insurance to choose the best fit for your needs.
- Extended Support Requirements: Recognize the significance of preparing for possible extended support needs as a component of your comprehensive financial strategy.
- Financial Implications: Assess how extended support can influence your family’s financial security and legacy arrangements, ensuring that your loved ones are safeguarded.
In Southern California, where the cost of living can be high, understanding these aspects is even more critical. For instance, 49% of American adults remain uninsured, highlighting the importance of securing adequate coverage. Furthermore, 52% of Americans mention coverage as too costly, which can discourage families from securing essential protection. When you take these steps, you’re not just planning; you’re paving the way for a secure and loving future for your family.
Explore Methods to Use Life Insurance for Long-Term Care Funding
Navigating the complexities of financial planning can feel overwhelming, especially for families like Emily and Mark. There are various efficient strategies for using life insurance to pay for long term care expenses. Here are some key strategies:
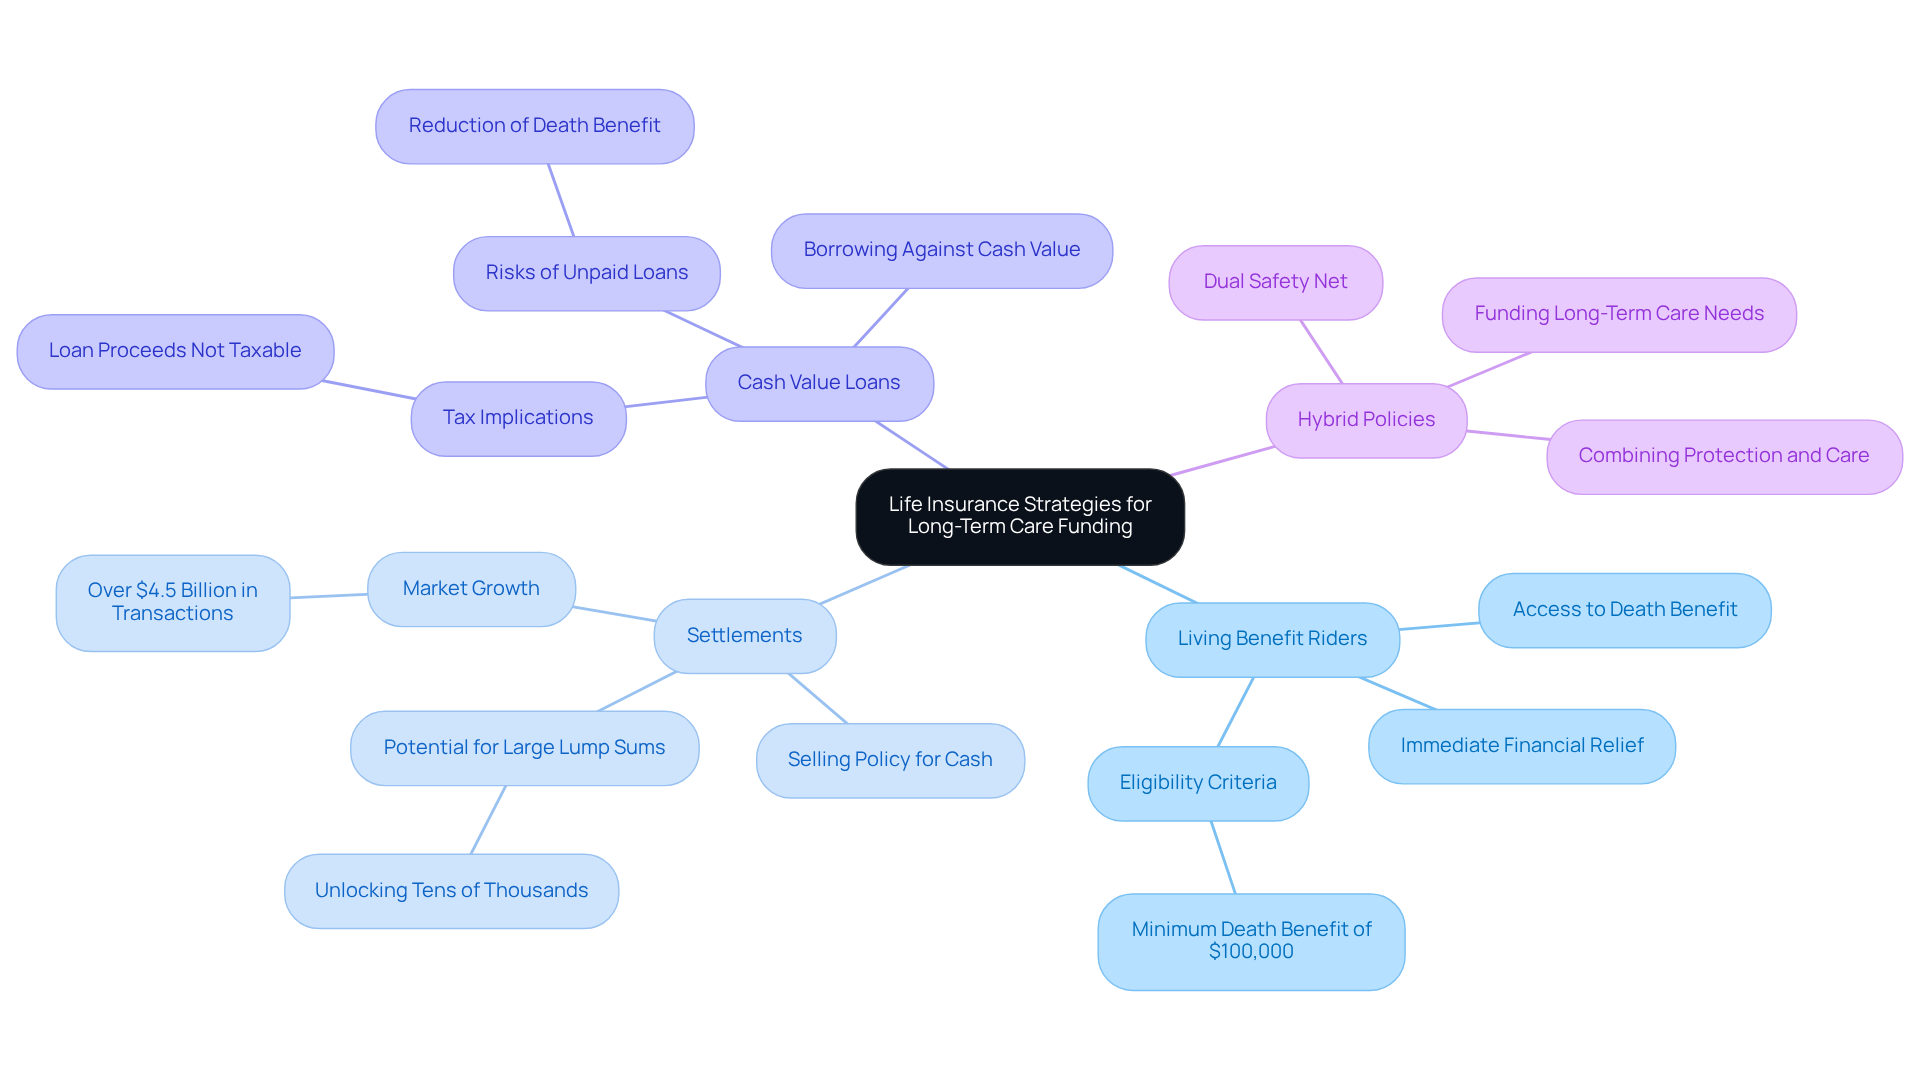
- Living Benefit Riders: Many policies include living benefit riders, allowing policyholders to access up to 50% of their death benefit while still alive if they need long-term assistance. This feature can provide immediate financial relief for support expenses, helping families manage costs without delay.
- Settlements: If you find you no longer need your insurance policy, consider selling it to a third party for a lump sum. This cash can be used to cover extended support expenses, potentially unlocking tens or even hundreds of thousands of dollars. Without proper guidance, you might miss out on opportunities that align with your family’s financial goals, especially since the settlement market has over $4.5 billion in annual transactions.
- Cash Value Loans: Permanent policies accumulate cash value over time, which can be borrowed against to cover extended assistance expenses. Managing loans against your policy’s cash value can be tricky, as unpaid loans may reduce your death benefit. Additionally, be aware of potential tax implications when taking loans against your policy’s cash value.
- Hybrid Policies: Explore hybrid coverage options that merge protection with extended support benefits. These policies offer a dual safety net, ensuring that both protection for loved ones and long-term care needs are addressed, particularly through using life insurance to pay for long term care, thus safeguarding your family’s financial future.
Key Points:
- Evaluate Policy Options: Review your existing life insurance policies to determine if they offer living benefits or cash value that can be accessed.
- Consult Professionals: Engage with a financial advisor at Bright Advisers to explore settlement options and hybrid policies tailored to your family’s specific needs. Our mission is to help families like yours make wise wealth decisions and preserve wealth across generations. With the right support, you can make informed decisions that truly benefit your family’s future.
Implement Strategies to Access Life Insurance Benefits for Care Costs
Imagine facing unexpected long-term care costs without the right support in place. To effectively access life insurance benefits for these costs, follow these steps:
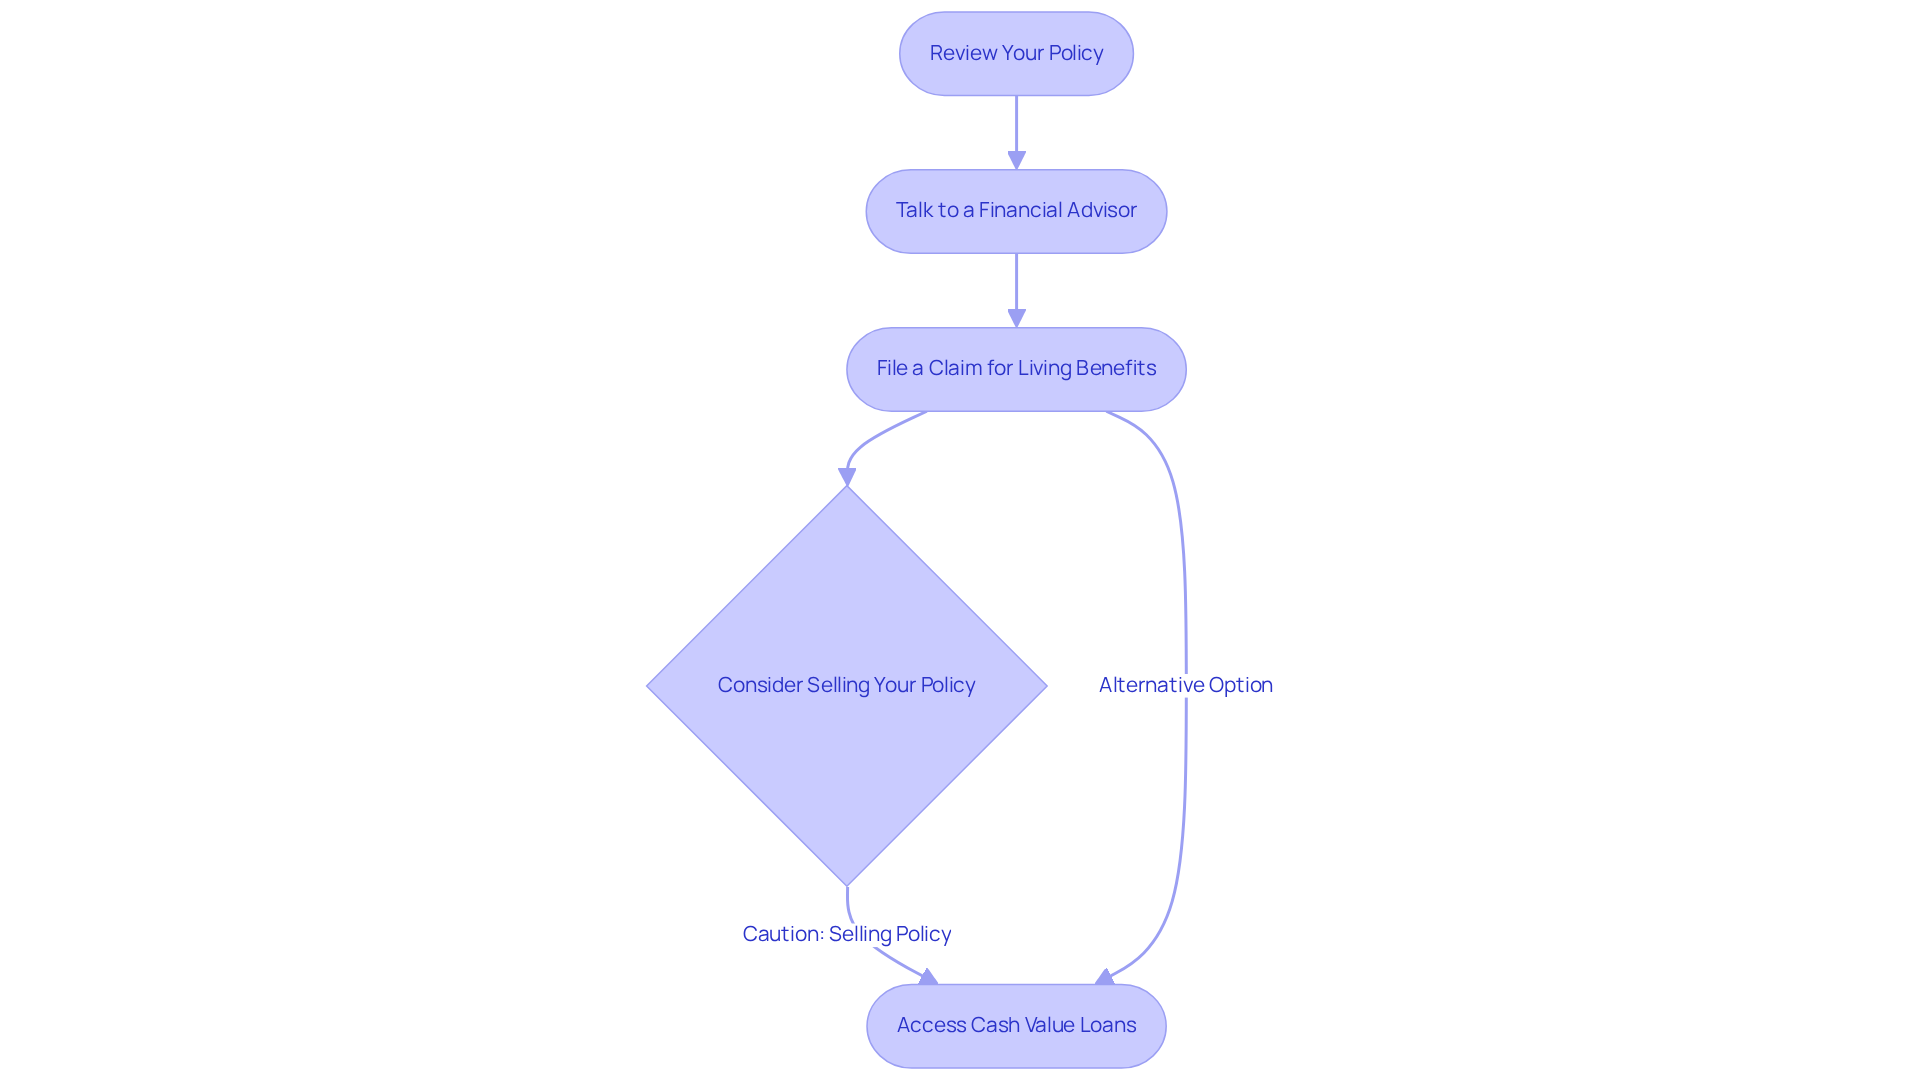
- Review Your Policy: Start by looking over your coverage document. Understand its conditions, including any riders or benefits related to extended support. Check for living benefits or cash value options that might be available.
- Talk to a Financial Advisor: It’s a good idea to chat with a financial advisor who understands life insurance and long-term care. They can help you navigate your options and find the best path based on your financial situation.
- File a Claim for Living Benefits: If your policy includes a living benefit rider, reach out to your insurance provider to start the claim process. Be prepared to provide documentation of your long-term care needs, like medical evaluations or support plans.
- Consider Selling Your Policy: If you decide to sell your policy, work with a trustworthy settlement broker. They can help you find potential buyers and negotiate the best price.
- Access Cash Value Loans: If your policy has cash value, talk to your insurer about how to access it. Be mindful of interest rates and repayment terms to avoid significantly reducing your death benefit.
Key Points:
- Documentation is Key: Keep thorough records of your long-term care needs and any communications with your insurance provider.
- Stay Informed: Regularly review your financial strategy to account for any changes in your policy or long-term care needs.
Additional Insights:
- Growing Need for Long-Term Care: With the number of Americans aged 65 and older projected to reach around 95 million by 2060, understanding how to access life insurance benefits for long-term care costs is crucial.
- Statistics on Extended Support Needs: About 62% of those needing extended support require help with three or more daily living activities, underscoring the importance of planning ahead.
- Proactive Financial Planning: Personal health events often prompt young adults to think about coverage, highlighting the need for early and proactive financial planning.
By following these steps, you can feel more confident in preparing for your family’s future needs.
Navigate Challenges and Considerations in Using Life Insurance
Imagine the peace of mind that comes with knowing your family is protected, but what happens when life insurance becomes a puzzle to solve? While using life insurance to fund long-term care can be beneficial, there are challenges and considerations to keep in mind:
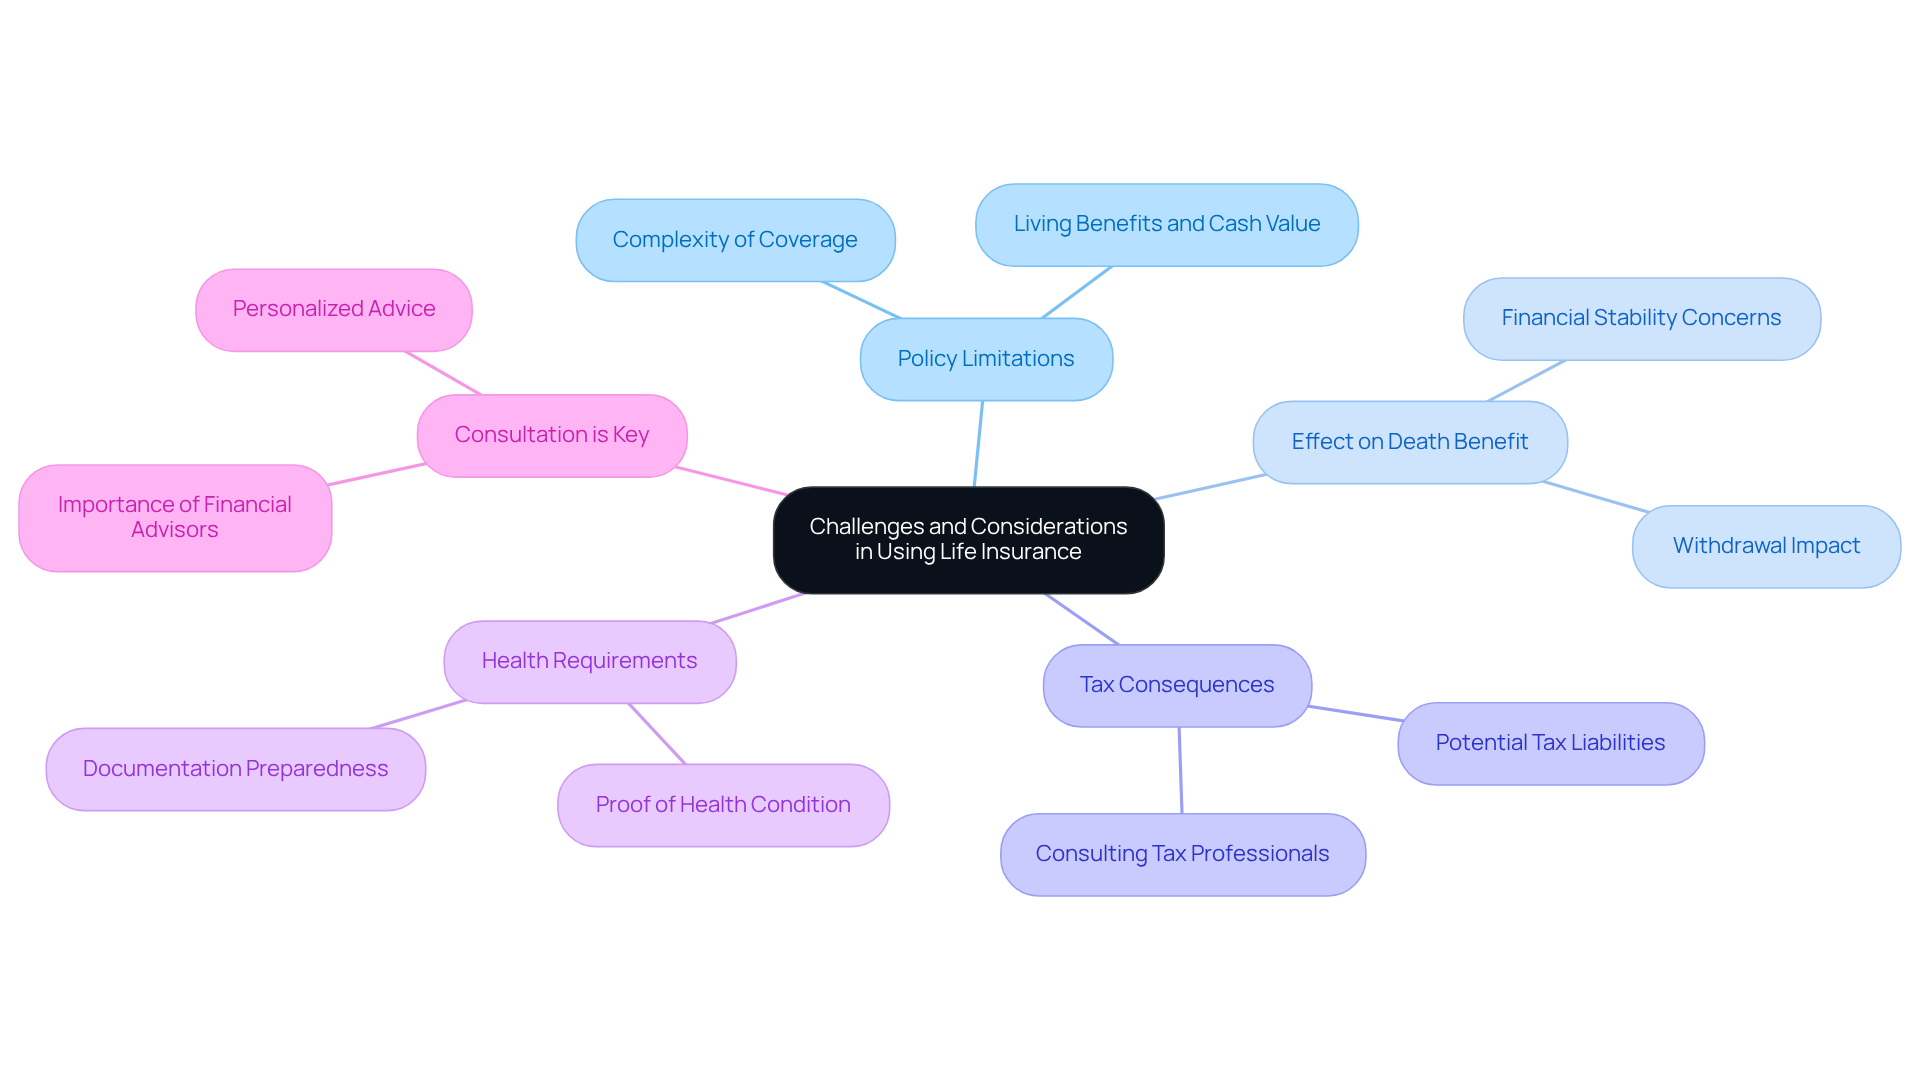
- Policy Limitations: Navigating the complexities of your policy can feel overwhelming, especially when you’re trying to secure your family’s future. Not every coverage plan offers living benefits or cash value alternatives, which can leave you feeling uncertain about your options. Review your policy carefully to understand what is available and any limitations that may apply.
- Effect on Death Benefit: When you withdraw funds from your policy, it can mean less financial support for your loved ones when they need it most, which is a heavy burden to bear. Almost 70% of people over 65 will require some type of extended assistance during their lifetime, making it crucial to think about how this may impact your family’s financial stability and legacy planning.
- Tax Consequences: It’s important to keep in mind that using benefits from your policy might come with tax consequences, and understanding these can help you avoid surprises down the road. The average yearly long-term care premium is expected to be $2,200 for a 55-year-old male and $3,750 for a female in 2025. Consulting with a tax professional can help you understand how withdrawals or loans may impact your tax situation.
- Health Requirements: Some policies might ask for proof of a qualifying health condition before you can access benefits, which can feel daunting when you’re already facing health challenges. The median time to nursing home admission after a dementia diagnosis is 3.3 years, underscoring the urgency of understanding health requirements. Ensure you understand the criteria and have the necessary documentation ready.
- Consultation is Key: We encourage you to reach out to a financial advisor who can help you navigate these important decisions with care. As Anthony Martin states, “Planning ahead can also make a difference.” They can provide personalized advice based on your family’s unique situation.
Key Points:
- Understand Your Policy: Familiarize yourself with the terms and conditions of your life insurance policy to avoid surprises.
- Plan Ahead: Consider the long-term implications of accessing life insurance benefits and how it aligns with your overall financial goals.
By understanding these factors, you can make informed decisions that involve using life insurance to pay for long-term care, truly safeguarding your family’s future and ensuring they thrive even in challenging times.
Conclusion
Imagine facing unexpected health challenges and wondering how to manage the costs while ensuring your family’s future is secure. Understanding how to use life insurance can be a vital part of that journey. Using life insurance wisely can help families prepare for health challenges and protect their loved ones financially. Taking these steps not only helps with immediate care needs but also builds a legacy for your family.
We’ve looked at different ways to use life insurance, like living benefit riders and hybrid policies, to help with long-term care costs. Each option has its own benefits that can make managing long-term care costs easier for families. Talking to a financial advisor at Bright Advisers can provide the personalized help families need to make the best choices for their situation.
Planning for long-term care is incredibly important for families. As the need for support grows, families should take the time to learn about their life insurance options and how to access these benefits. This way, families can feel confident that their financial plans support their long-term goals, bringing peace of mind for years to come.
If you need help, don’t hesitate to contact Bright Advisers at hello@brightadvisers.com or call (714) 987-2967. We’re here to help you find the right solutions for your family.
Frequently Asked Questions
What is the purpose of life insurance in relation to long-term care?
Life insurance serves as a financial tool to help pay for long-term care expenses, ensuring that families can manage future costs and secure their loved ones’ financial future.
What are the main types of life insurance?
The main types of life insurance include term life, whole life, and universal life, each offering unique features tailored to different financial needs.
What does long-term care (LTC) involve?
Long-term care encompasses a range of services designed to assist individuals who can no longer perform daily activities independently, such as bathing, dressing, or managing medications.
Why is it important to prepare for extended support needs?
Preparing for extended support needs is crucial as it significantly impacts financial planning, especially for families with young children considering life insurance to secure their future.
How can extended support influence a family’s financial security?
Extended support can affect a family’s financial security and legacy arrangements, making it essential to assess these implications to safeguard loved ones.
What is the significance of understanding life insurance in Southern California?
In Southern California, where the cost of living is high, understanding life insurance and long-term care is critical, especially since 49% of American adults remain uninsured and 52% find coverage too costly.
What steps can families take to ensure financial security for the future?
Families can secure adequate life insurance coverage and prepare for potential long-term care needs, paving the way for a secure and loving future for their loved ones.
List of Sources
- Understand Life Insurance Basics and Long-Term Care Needs
- Top Life Insurance Statistics, Trends & Facts (https://feather-insurance.com/blog/life-insurance-statistics)
- Life Insurance Statistics, Facts, And Industry Trends For 2026 (https://choicemutual.com/original-research/life-insurance-statistics)
- Life Insurance Statistics (https://thezebra.com/resources/research/life-insurance-statistics)
- Top Life Insurance Statistics of 2026 (https://moneygeek.com/insurance/life/life-insurance-statistics)
- Cost of Long Term Care by State | Cost of Care Report | Carescout (https://carescout.com/cost-of-care)
- Explore Methods to Use Life Insurance for Long-Term Care Funding
- Life Settlements: A Lifeline for Long-Term Care Funding (https://ltcnews.com/life-settlements)
- Using Life Insurance to Pay for Long-Term Care: 5 Options (https://aplaceformom.com/caregiver-resources/articles/life-insurance-for-long-term-care)
- Life Insurance Statistics, Facts, And Industry Trends For 2026 (https://choicemutual.com/original-research/life-insurance-statistics)
- 50 Long-Term Care Statistics: The Real Cost of Aging in 2026 (https://getamplifylife.com/learn/blog/long-term-care-statistics)
- Implement Strategies to Access Life Insurance Benefits for Care Costs
- 35 Quotes for Financial Advisors on a Tough Day | Don Connelly & Associates (https://donconnelly.com/35-quotes-for-financial-advisors)
- 50 Long-Term Care Statistics: The Real Cost of Aging in 2026 (https://getamplifylife.com/learn/blog/long-term-care-statistics)
- Long-Term Care Statistics 2025: What You Should Know (https://inszoneinsurance.com/blog/long-term-care-statistics)
- Long term care insurance facts statistics information on long term care planning from long term care insurance industry organization (https://aaltci.org/long-term-care-insurance/learning-center/fast-facts.php)
- 13 of the best life insurance quotes ever (https://thinkadvisor.com/2015/06/05/13-of-the-best-life-insurance-quotes-ever)
- Navigate Challenges and Considerations in Using Life Insurance
- Life Insurance Statistics (https://thezebra.com/resources/research/life-insurance-statistics)
- Life Insurance Statistics, Facts, And Industry Trends For 2026 (https://choicemutual.com/original-research/life-insurance-statistics)
- 50 Long-Term Care Statistics: The Real Cost of Aging in 2026 (https://getamplifylife.com/learn/blog/long-term-care-statistics)
- 2025 Long-term Care Insurance Statistics Data Facts (https://aaltci.org/long-term-care-insurance/learning-center/ltcfacts-2025.php)
- Long-Term Care Statistics 2026 | JRC Insurance Group™ (https://jrcinsurancegroup.com/long-term-care-statistics)

Kevin has advised high-income W-2 tech and biotech families since 2015, and leads the education-first Age Five Family Office from Brea, California.
Connect on LinkedIn → · About KevinThis is part of how we approach Estate Planning for high-income W-2 families at Bright Advisers.
Keep reading