

Key Highlights
- UTMA accounts allow diverse asset types, including cash, stocks, bonds, and real estate, providing flexibility for family financial goals.
- Earnings in UTMA accounts are taxed at the child’s lower tax rate, offering potential tax savings.
- These accounts serve as educational tools, teaching children about investing and financial responsibility until they reach the age of majority.
- There are no contribution limits for UTMA accounts, allowing families to save for significant future expenses.
- If a child’s unearned income exceeds $1,350, they must file a tax return, and earnings above $2,700 are subject to the Kiddie Tax.
- Strategic investment choices can help minimise taxable earnings, enhancing the account’s growth potential.
- Consulting a tax professional is recommended to navigate the complexities of UTMA tax implications.
- Common mistakes include neglecting tax obligations, misunderstanding Kiddie Tax rules, and failing to engage children in financial education.
- Bright Advisers emphasises fiduciary duty and transparency in wealth management, helping families make informed financial decisions.
Introduction
Imagine standing at the crossroads of your child’s future, feeling the weight of financial decisions pressing down on you. Navigating the financial landscape as a young parent can feel overwhelming. Yet, the maze of UTMA 1099 forms and their tax implications can leave many parents feeling lost and unsure.
How can you and your family turn the potential of UTMA accounts into a stepping stone for your child’s future while sidestepping common pitfalls? Together, we can explore the benefits of these accounts and how to manage them effectively.
Define UTMA Accounts: Key Features and Benefits for Families
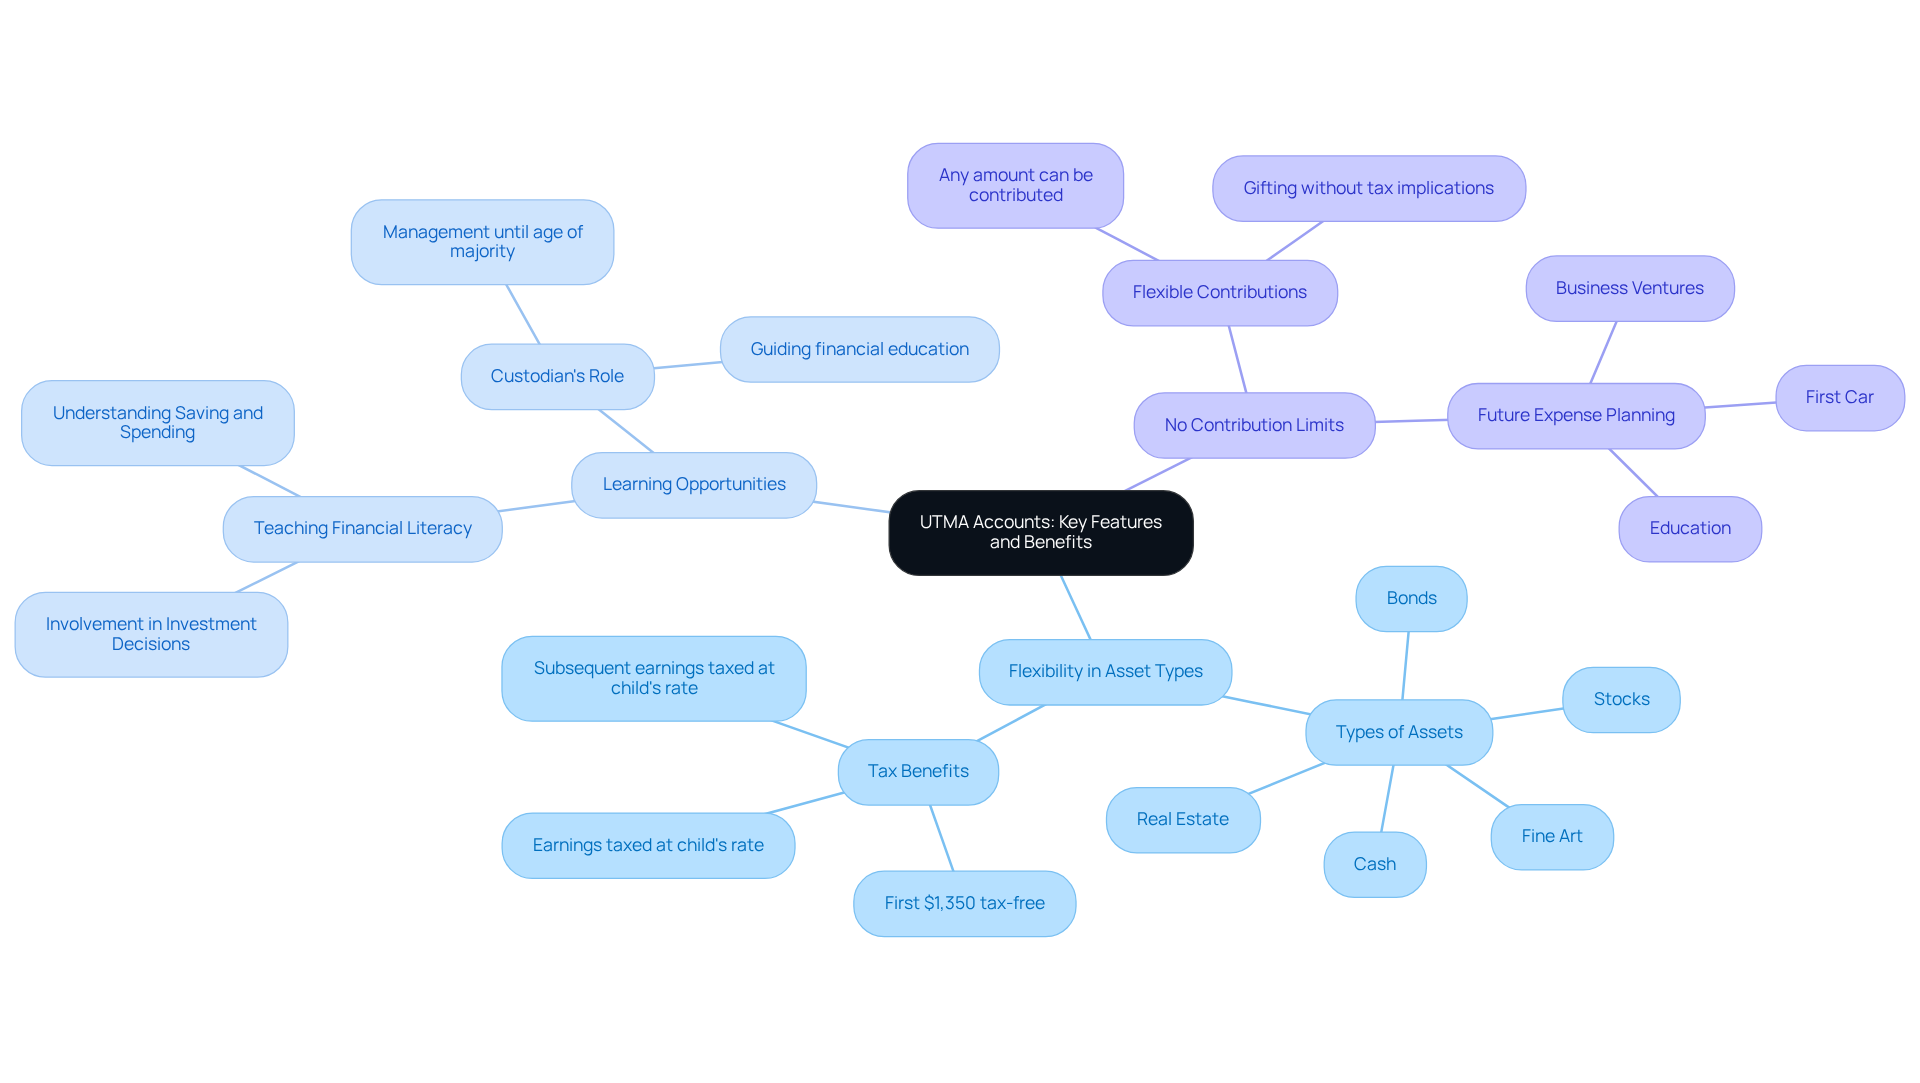
Imagine a world where your child’s financial future is secure, and they learn the value of money from an early age. UTMA 1099 accounts provide a wonderful way to help your child build a secure financial future without the hassle of complicated trusts. Let’s explore some wonderful benefits of UTMA accounts that can truly make a difference for your family:
- Flexibility in Asset Types: UTMA accounts can accommodate a diverse range of assets, including cash, stocks, bonds, and even real estate. This variety allows you to tailor your investment strategies to meet your family’s unique financial goals. Tax benefits indicate that earnings in a UTMA 1099 fund are taxed at your child’s tax rate, which is usually lower than yours, providing possible tax savings. The initial $1,350 of unearned income is exempt from taxes, while the subsequent $1,350 is taxed at the minor’s rate, making these options appealing for families utilizing the UTMA 1099.
- Learning Opportunities: These platforms offer a practical means for teaching your child about investing and financial responsibility, nurturing vital financial literacy from a young age. Involving them in conversations about their UTMA holdings can instill valuable skills that benefit them in adulthood. You oversee the fund until your child reaches the age of majority, which varies by state (usually 18 or 21), as outlined in the UTMA 1099. This ensures that resources are utilized suitably and responsibly until they are prepared to take charge.
- No Contribution Limits: You can contribute any amount to a UTMA 1099 fund, which provides flexibility for saving towards future expenses, whether for education, a first car, or other significant needs.
Together, by understanding these features, you can make informed choices that pave the way for your child’s financial growth and a brighter future.
Explore UTMA 1099 Tax Implications: What Young Parents Need to Know
Navigating the tax implications of UTMA funds can feel overwhelming for young parents, but understanding them is crucial for your family’s financial health. Here are some key points to consider:
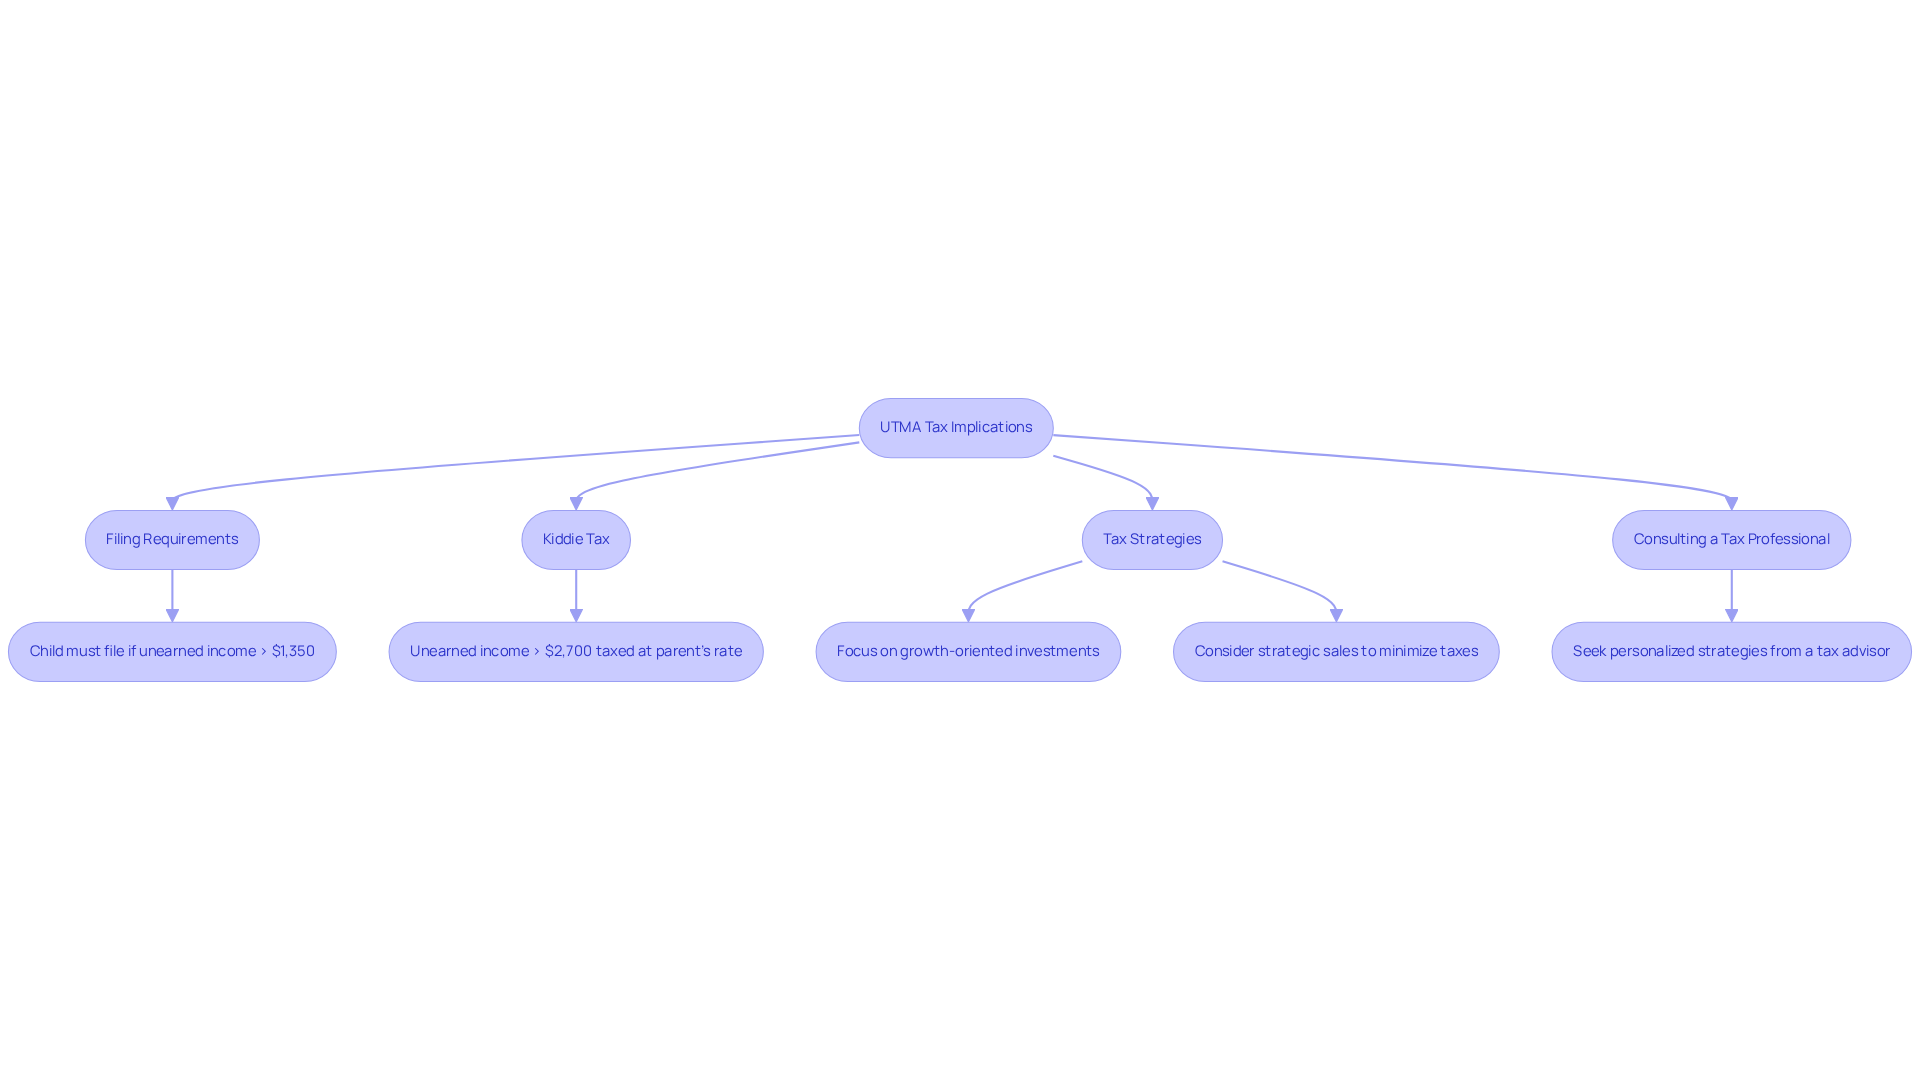
- Filing Requirements: If your child has unearned income exceeding $1,350, they’ll need to file a tax return. This includes earnings from dividends, interest, and capital gains reported on the utma 1099 from the UTMA fund.
- Kiddie Tax: Any unearned earnings above $2,700 are subject to the Kiddie Tax, which means they’ll be taxed at your marginal tax rate. This can significantly impact your family’s overall tax liability. You’ll receive a Form 1099-DIV for any dividends earned in the UTMA fund, and it’s important to include this utma 1099 when filing your child’s tax return.
- Tax Strategies: Consider focusing on growth-oriented investments that keep your child’s taxable earnings low. For instance, strategic sales of investments can help you take advantage of the IRS exemption for the first $1,350 of unearned earnings, enhancing the account’s growth potential. Also, be aware of the Net Investment Income Tax (NIIT), which may apply to dependents required to file Form 8615.
- Consulting a Tax Professional: We understand that tax laws can be tricky, so reaching out to a tax professional can really help you navigate the ins and outs of UTMA funds. This is especially important since minors with unearned income exceeding $2,700 must file Form 8615 to determine their tax responsibilities.
By taking the time to understand these tax implications, you can secure a brighter financial future for your children.
Manage Your UTMA Account: A Step-by-Step Guide to 1099 Filing
It can feel overwhelming to navigate the complexities of tax forms and regulations, especially when it comes to managing a UTMA account and dealing with the UTMA 1099. But with the right steps, you can turn this challenge into an opportunity for your child’s financial future.
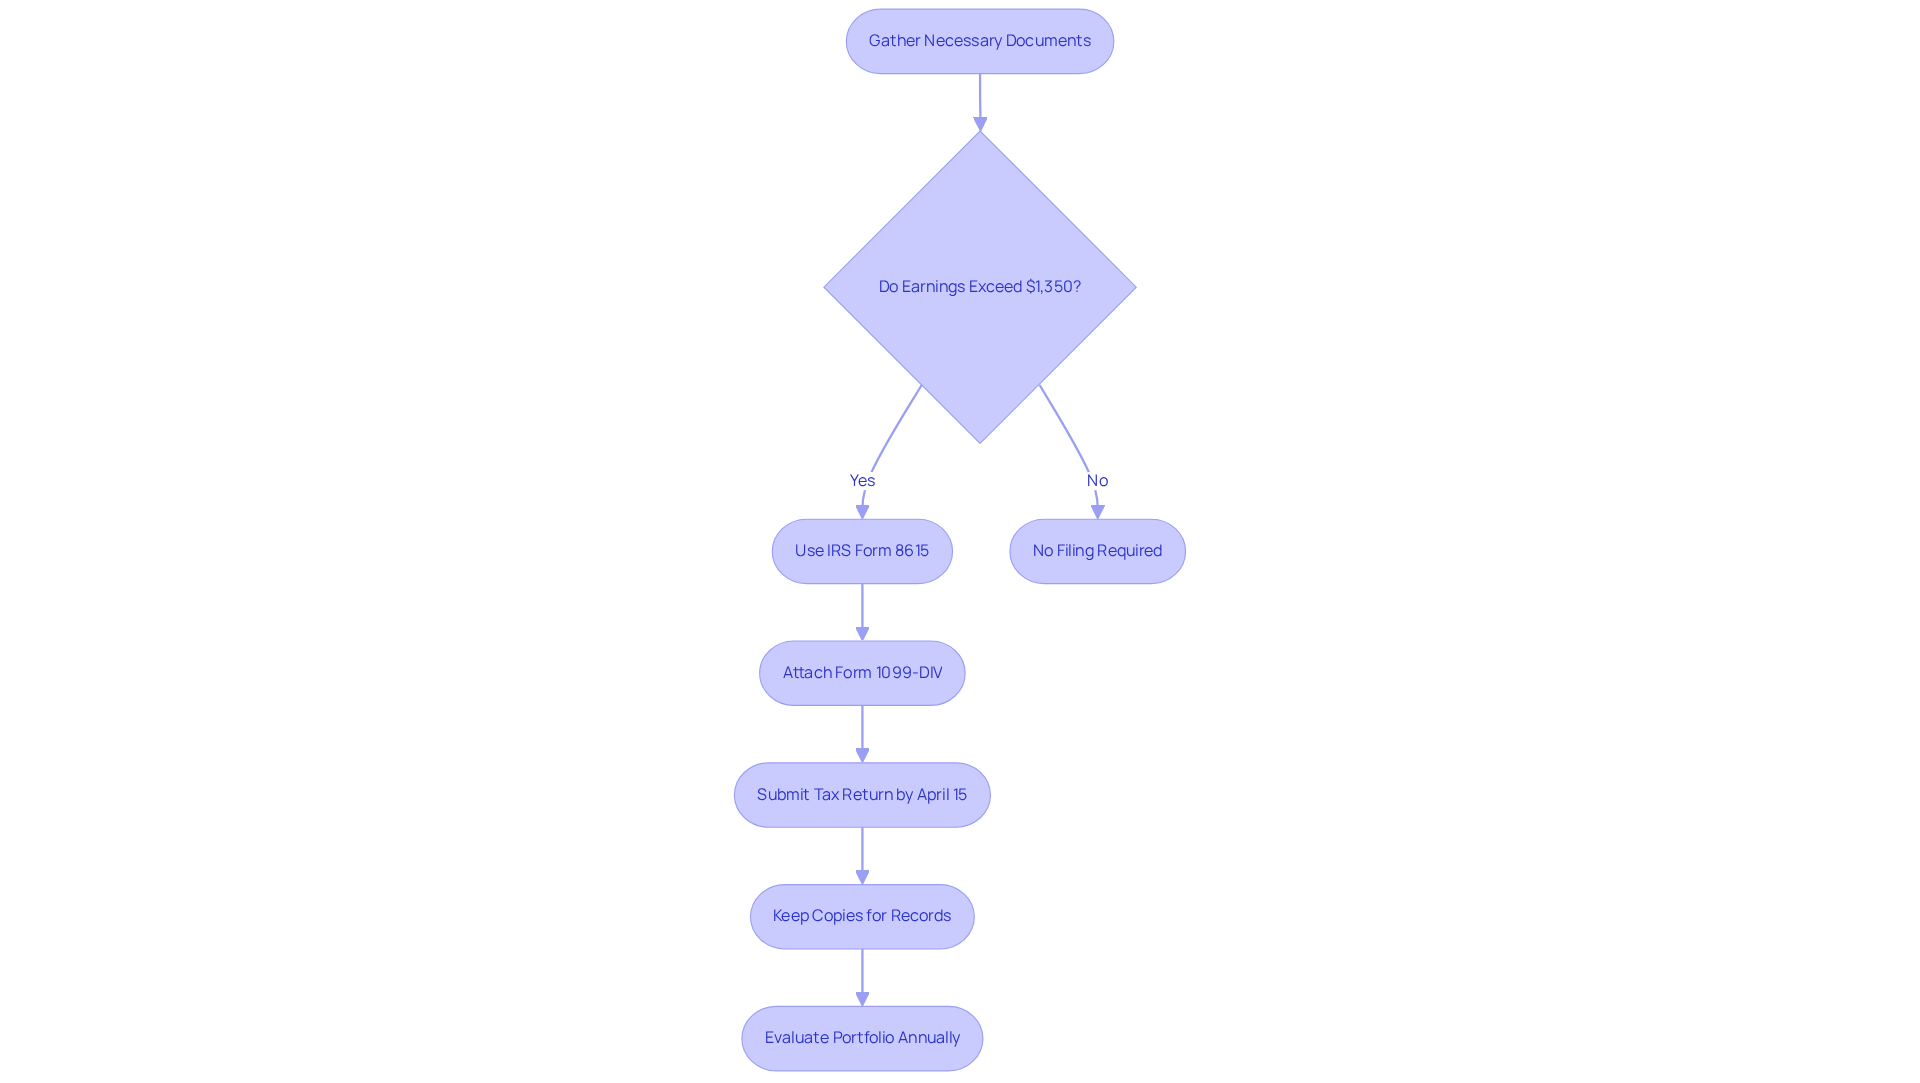
Start by gathering all the necessary documents, like Form 1099-DIV for dividends, to make this process smoother. Next, check if your child’s unearned earnings exceed $1,350, as this will determine if they need to file a tax return.
When you’re ready, use IRS Form 8615 to report your child’s unearned earnings. This form is designed specifically for children and helps calculate the Kiddie Tax. Don’t forget to attach Form 1099-DIV and any other relevant 1099 forms to the tax return. This ensures all income is accurately reported, helping you avoid penalties.
Make sure to submit the completed tax return by the due date, typically April 15. E-filing can make this process quicker and easier for you. Keep copies of all submitted forms and documentation for your records. This will be helpful for future reference and in case of an audit.
Each year, take a moment to evaluate the performance and tax implications of your UTMA 1099 portfolio. This way, you can adjust your investment strategy as needed. Remember, minors gain full control over UGMA and UTMA assets at ages typically between 18 to 21 years old, depending on state laws, so planning ahead can make all the difference in setting your child up for a successful financial future.
Avoid Common Mistakes: Best Practices for UTMA 1099 Management
Imagine the worry that comes with managing your child’s UTMA 1099 account and the potential pitfalls that could arise. Managing these accounts effectively means being aware of common mistakes that can complicate things. Here are some best practices to help you navigate this journey:
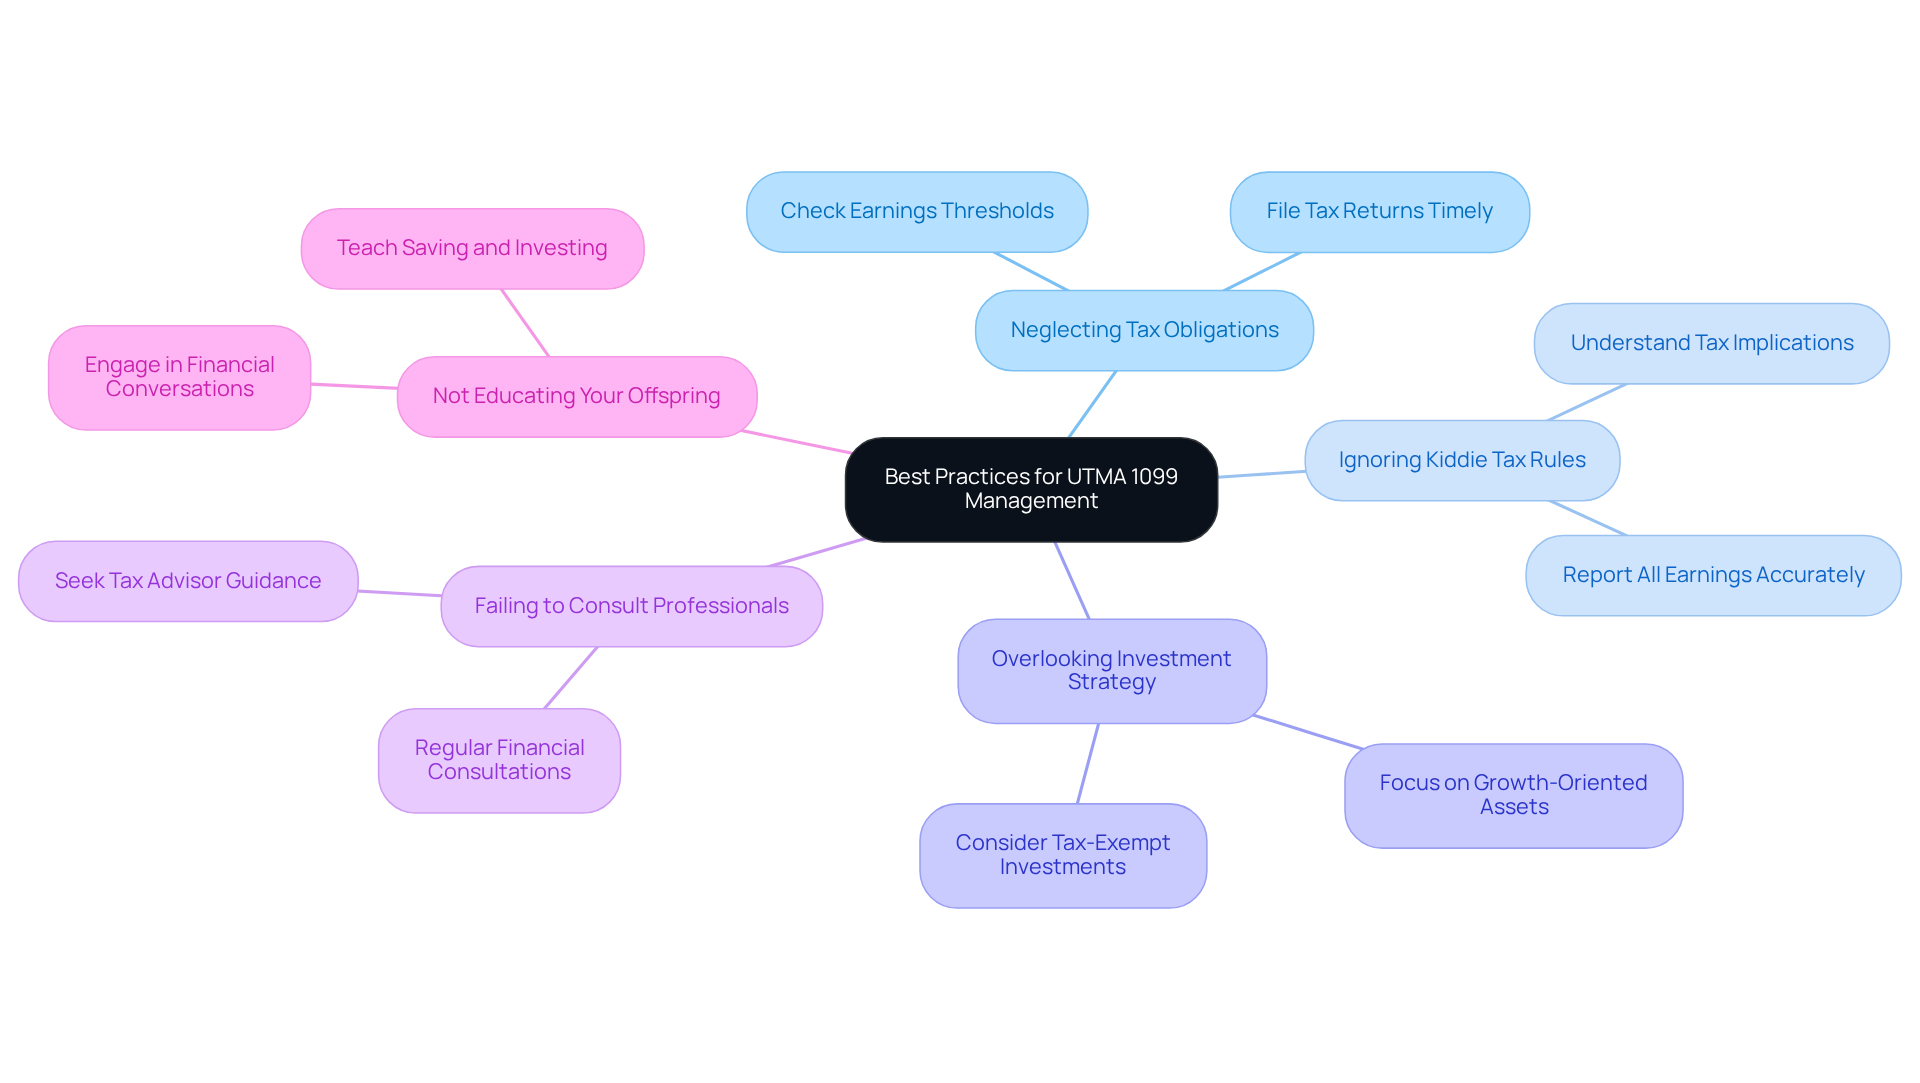
- Neglecting Tax Obligations: Imagine the stress of facing unexpected penalties because of missed tax filings. Always check if your child’s unearned earnings surpass the threshold and file accordingly. For 2026, the first $1,350 of a child’s unearned earnings is tax-free, while amounts exceeding $2,700 are taxed at the parent’s marginal rate.
- Ignoring Kiddie Tax Rules: Not understanding how the Kiddie Tax applies can lead to unexpected tax liabilities. Be aware of the earnings thresholds and how they influence your tax strategy. For instance, any unearned earnings over $2,500 are taxed at the parents’ rate, which can significantly affect your financial planning. Ensure that all earnings from the UTMA 1099 account are accurately reported on tax returns. Double-check the amounts on Form 1099-DIV and other financial statements to avoid discrepancies that could lead to audits or penalties.
- Overlooking Investment Strategy: Investing in high-yielding assets can elevate your child’s earnings above the Kiddie Tax threshold. Consider growth-oriented investments that minimize taxable income, such as U.S. Savings Bonds or municipal bonds, which can provide tax-exempt income.
- Failing to Consult Professionals: Not seeking advice from tax professionals or financial advisors can mean missing out on valuable tax-saving strategies that could benefit your family. Regular consultations can provide insights tailored to your family’s financial situation, especially regarding the complexities of the Kiddie Tax. As noted by financial experts, consulting a tax advisor is crucial for navigating the intricacies of UTMA 1099 management.
- Not Educating Your Offspring: Failing to engage your child in conversations about their UTMA fund can overlook a chance for financial education. Teach them about managing money and the importance of saving and investing, which can set a strong foundation for their financial future.
When you follow these best practices, you not only keep your UTMA accounts in check but also help your kids learn about money management. Bright Advisers exemplifies this approach through tailored wealth management solutions, as seen in the stories of families like Jay & Emma, Emily & Mark, and Allison & Brian, who have successfully navigated their financial journeys with personalized planning and tax optimization strategies. Founded by Kevin Luu and Kathleen Chou in 2010, Bright Advisers is committed to helping families make wise wealth decisions and preserve wealth across generations. Please note that past performance does not guarantee future results, and all advisory services are provided through Lifeworks Advisors, a registered investment adviser. With the right guidance, you can turn these challenges into opportunities for your family’s financial future.
Conclusion
Imagine feeling confident about your child’s financial future, knowing you’re making the right choices today. Mastering the intricacies of UTMA 1099 accounts can truly empower young parents like you to secure your children’s financial futures. By understanding the features and benefits of UTMA accounts, you can foster financial literacy and growth within your family. The flexibility in asset types, the absence of contribution limits, and the chance for your children to learn about money management are just a few of the advantages that make UTMA accounts a valuable resource.
Throughout this guide, we’ve shared key insights regarding the tax implications associated with UTMA accounts, including filing requirements and strategies to minimize tax liabilities. It’s important to understand the Kiddie Tax and the significance of timely filings, as these can significantly impact your family’s financial health. Additionally, we’ve highlighted best practices for managing UTMA accounts, emphasizing the need for proactive engagement and education to avoid common pitfalls.
But remember, navigating the complexities of UTMA accounts can feel overwhelming for many parents. However, with the right knowledge and support, you can turn this challenge into an empowering experience for your family. By taking informed steps and seeking guidance from professionals like Bright Advisers, you can navigate these complexities with confidence. By taking these steps, you’re not just planning for the future; you’re building a legacy of financial wisdom for your children.
Frequently Asked Questions
What is a UTMA account?
A UTMA (Uniform Transfers to Minors Act) account is a custodial account that allows adults to manage assets on behalf of a minor until they reach the age of majority, which is typically 18 or 21, depending on the state.
What types of assets can be held in a UTMA account?
UTMA accounts can accommodate a diverse range of assets, including cash, stocks, bonds, and even real estate, allowing families to tailor their investment strategies to meet unique financial goals.
What are the tax benefits of a UTMA account?
Earnings in a UTMA account are taxed at the child’s tax rate, which is usually lower than the parent’s rate. The first $1,350 of unearned income is exempt from taxes, and the next $1,350 is taxed at the minor’s rate, providing potential tax savings for families.
How can UTMA accounts help with financial education for children?
UTMA accounts provide a practical means for teaching children about investing and financial responsibility. Involving them in discussions about their holdings can nurture vital financial literacy from a young age.
Are there contribution limits for UTMA accounts?
No, there are no contribution limits for UTMA accounts, allowing families to contribute any amount towards future expenses, such as education or significant purchases.
Who manages the UTMA account until the child reaches adulthood?
An adult custodian manages the UTMA account until the child reaches the age of majority, ensuring that the resources are utilized appropriately and responsibly until the child is ready to take charge.
List of Sources
- Define UTMA Accounts: Key Features and Benefits for Families
- The 11 Best Quotes about Investing (https://birchstreetadvisors.com/blog/the-11-best-quotes-about-investing)
- UGMA and UTMA Accounts: What Parents Need to Know Before Opening One (https://elevationfinancial.com/ugma-and-utma-accounts-what-parents-need-to-know-before-opening-one)
- UGMA vs. UTMA Custodial Accounts (https://smartasset.com/investing/ugma-vs-utma)
- What is a UTMA Account, and Why Should You Consider One for Your Kids? | KidVestors (https://kidvestors.co/post/what-is-a-utma-account)
- Explore UTMA 1099 Tax Implications: What Young Parents Need to Know
- Topic no. 553, Tax on a child’s investment and other unearned income (kiddie tax) | Internal Revenue Service (https://irs.gov/taxtopics/tc553)
- Tax Filing Requirements For Minor Children with Investment Income | Greenbush Financial Group (https://greenbushfinancial.com/all-blogs/minor-child-investment-income-tax-return-filing)
- Avoiding Kiddie Taxes on Your Children’s UTMA Accounts (https://canbyfinancial.com/blog/avoiding-kiddie-taxes-on-your-childrens-utma-accounts)
- Watch Out for the Kiddie Tax (https://schwab.com/learn/story/understanding-kiddie-tax)
- Manage Your UTMA Account: A Step-by-Step Guide to 1099 Filing
- UGMA vs UTMA: What’s the Difference? | PortfolioPilot (https://portfoliopilot.com/retirement-planning/resources/ugma-vs-utma-whats-the-difference)
- UGMA & UTMA Custodial Accounts – Finaid (https://finaid.org/savings/ugma)
- Dependents – UGMA and UTMA Custodial Accounts (https://taxact.com/support/14733/2021/dependents-ugma-and-utma-custodial-accounts)
- Taxes on UTMA – The White Coat Investor Forum – Investing & Personal Finance for Doctors (https://forum.whitecoatinvestor.com/tax-reduction/389101-taxes-on-utma)
- What Are UGMA and UTMA Accounts? (https://experian.com/blogs/ask-experian/what-are-ugma-and-utma-accounts)
- Avoid Common Mistakes: Best Practices for UTMA 1099 Management
- What Is the Kiddie Tax? Kiddie Tax Rules | U.S. Bank (https://usbank.com/wealth-management/financial-perspectives/financial-planning/kiddie-tax.html)
- Strategies to Reduce Kiddie Tax Liability in 2024 (https://kahnlitwin.com/blogs/tax-blog/how-can-you-reduce-your-kiddie-tax-liability-for-2024)
- Topic no. 553, Tax on a child’s investment and other unearned income (kiddie tax) | Internal Revenue Service (https://irs.gov/taxtopics/tc553)

Kevin has advised high-income W-2 tech and biotech families since 2015, and leads the education-first Age Five Family Office from Brea, California.
Connect on LinkedIn → · About KevinThis is part of how we approach Age Five Wealth Education for high-income W-2 families at Bright Advisers.
Keep reading