

Overview
This article serves as a compassionate guide for parents seeking to understand how to report taxes for Uniform Transfers to Minors Act (UTMA) accounts. It highlights the tax implications and reporting requirements in a way that feels supportive and reassuring. Understanding the thresholds for unearned income is crucial, and it’s important to know about IRS Form 8615. Imagine if you could navigate these complexities with confidence! Utilizing various tools and resources, such as tax software and professional advice, can make this process much easier. Together, we can ensure that you feel equipped to handle UTMA tax reporting efficiently, allowing you to focus on what truly matters—your family.
Key Highlights:
- UTMA accounts allow for the transfer of assets to minors without the complexities of a formal trust, managed by a custodian.
- Assets in UTMA accounts can include cash, stocks, bonds, and real estate, promoting financial education for children.
- In 2025, the first $1,350 of earnings in a UTMA trust is tax-free for minors; income above this is taxed at the child’s lower tax rate.
- Contributions to UTMA accounts are irrevocable gifts, allowing guardians to benefit from federal tax exemptions up to $19,000 annually.
- Income generated from UTMA accounts must be reported on the child’s tax return, with specific thresholds impacting tax rates.
- IRS Form 8615 is required for reporting children’s unearned income that exceeds $1,350.
- Guardians should maintain detailed records of transactions and income for compliance with IRS regulations.
- Utilising tax preparation software, financial planning apps, and IRS resources can streamline the UTMA tax reporting process.
- Consulting a tax professional is recommended for personalised guidance on tax implications and benefits related to UTMA accounts.
Introduction
Navigating the complexities of financial planning for your children can feel overwhelming, especially when it comes to understanding the nuances of Uniform Transfers to Minors Act (UTMA) accounts. These custodial accounts are designed to facilitate asset transfers, yet they also present unique tax reporting challenges that you, as a parent, must carefully navigate.
This guide provides a step-by-step approach to mastering UTMA account tax reporting, empowering you to optimize your children’s financial futures while ensuring compliance with IRS regulations.
Imagine if you could manage these tax obligations without feeling burdened by the details—together, we can make this journey manageable and rewarding.
Understand UTMA Accounts and Their Purpose
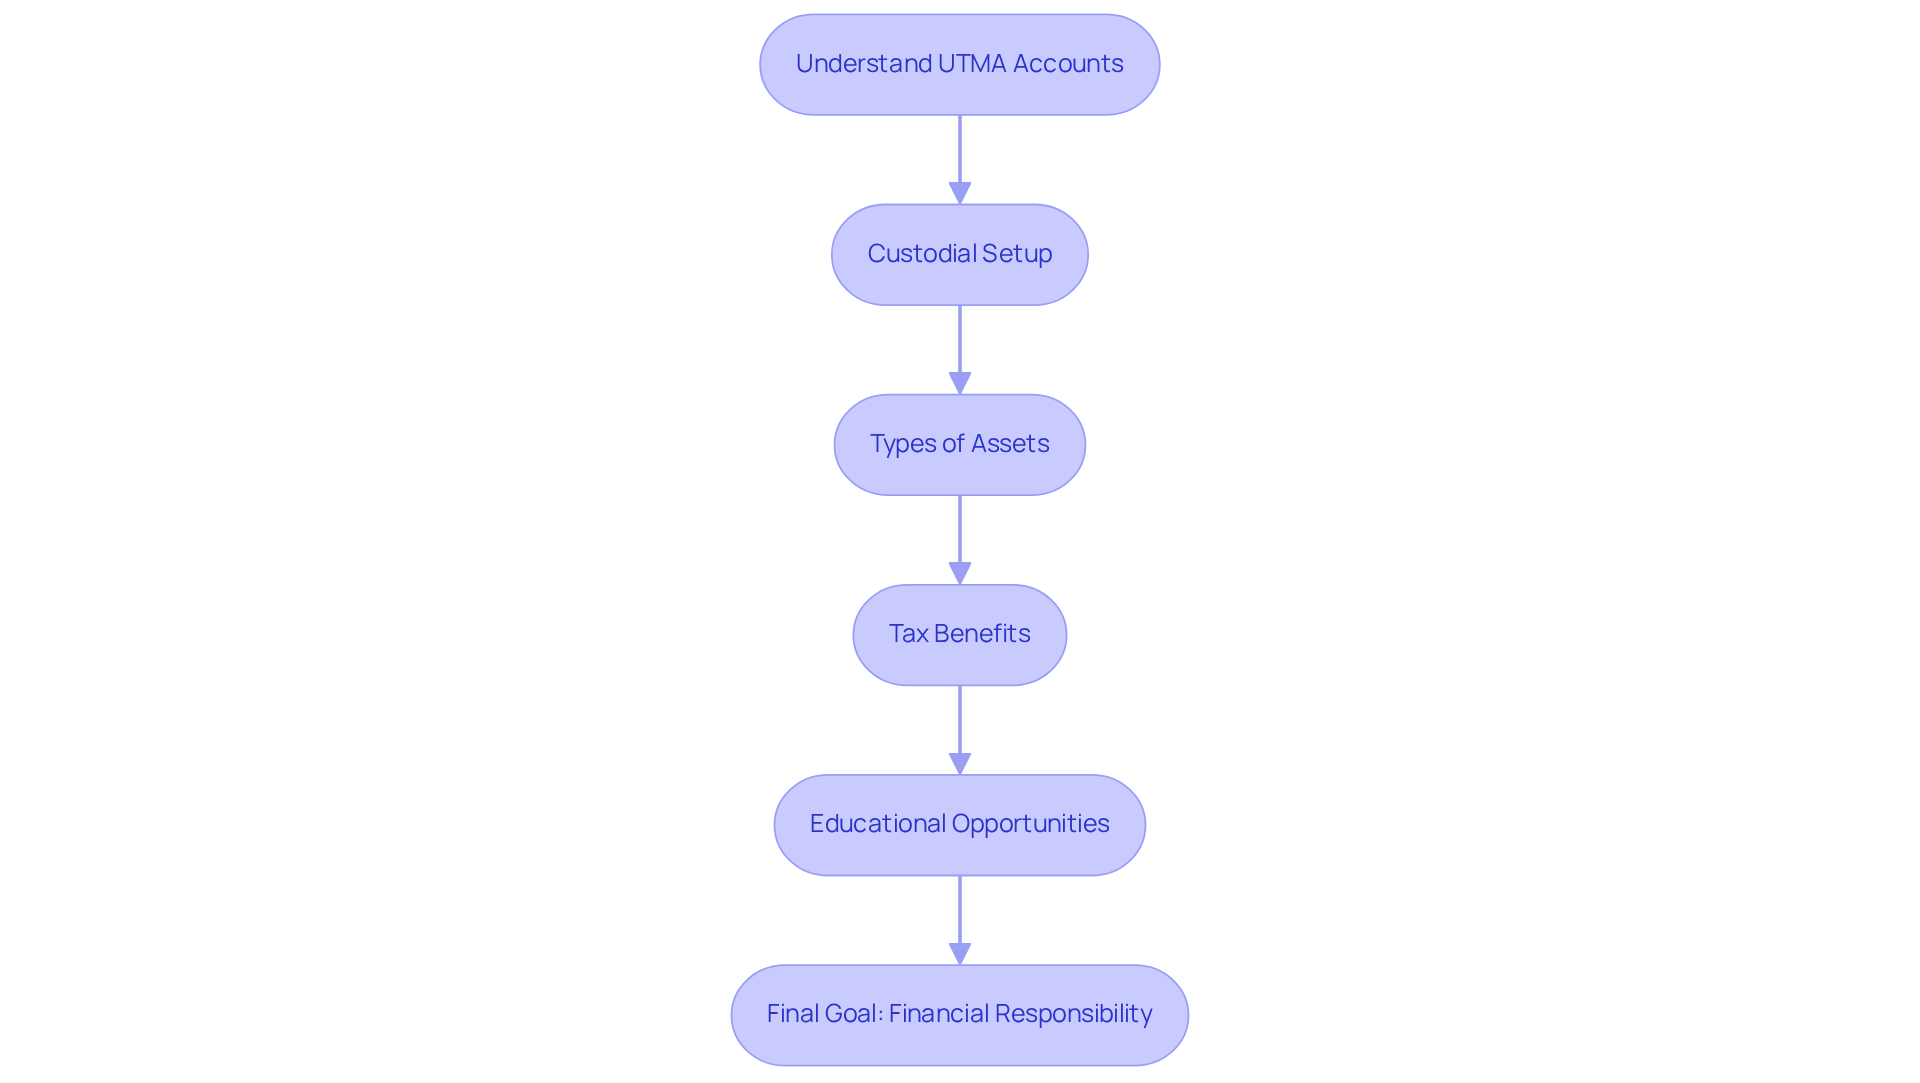
A Uniform Transfers to Minors Act (UTMA) arrangement is a nurturing custodial setup designed to help you transfer assets to your children without the complexities of a formal trust. Managed by a caregiver—often a relative or guardian—these funds can include a variety of assets, such as cash, stocks, bonds, and even real estate. Imagine your child reaching the age of majority, which varies by state (usually 18 or 21), and gaining full control over these funds. This can be a powerful opportunity for financial education and responsibility.
UTMA account tax reporting illustrates the dual purpose of UTMA funds: they allow you to save for your children’s future while also offering potential tax benefits. For instance, in 2025, the first $1,350 of earnings in a UTMA trust is tax-free for minors. Any income above this threshold is taxed at your child’s lower tax rate, which can significantly ease the overall tax burden for your family, especially when it comes to UTMA account tax reporting. Additionally, contributions to these funds are considered irrevocable gifts, allowing for UTMA account tax reporting and enabling you to benefit from federal tax exemptions of up to $19,000 annually per guardian without triggering gift taxes.
Real-world examples highlight the advantages of UTMA assets. One guardian shared that establishing a UTMA fund for their child was a pivotal financial decision, enabling them to save for upcoming educational costs while benefiting from UTMA account tax reporting advantages. Financial advisors stress the importance of involving children in the process, as it not only sparks their economic education but also helps them understand the impact of their financial choices.
Ultimately, the UTMA account tax reporting provides a versatile and tax-effective way for you to secure your children’s financial futures, while also imparting valuable lessons about money management and responsibility. Understanding how these financial instruments work is essential for guardians like you, who are looking to navigate the complexities of financial planning and UTMA account tax reporting confidently. We’re here for you, ready to support you on this journey.
Identify Tax Reporting Requirements for UTMA Accounts
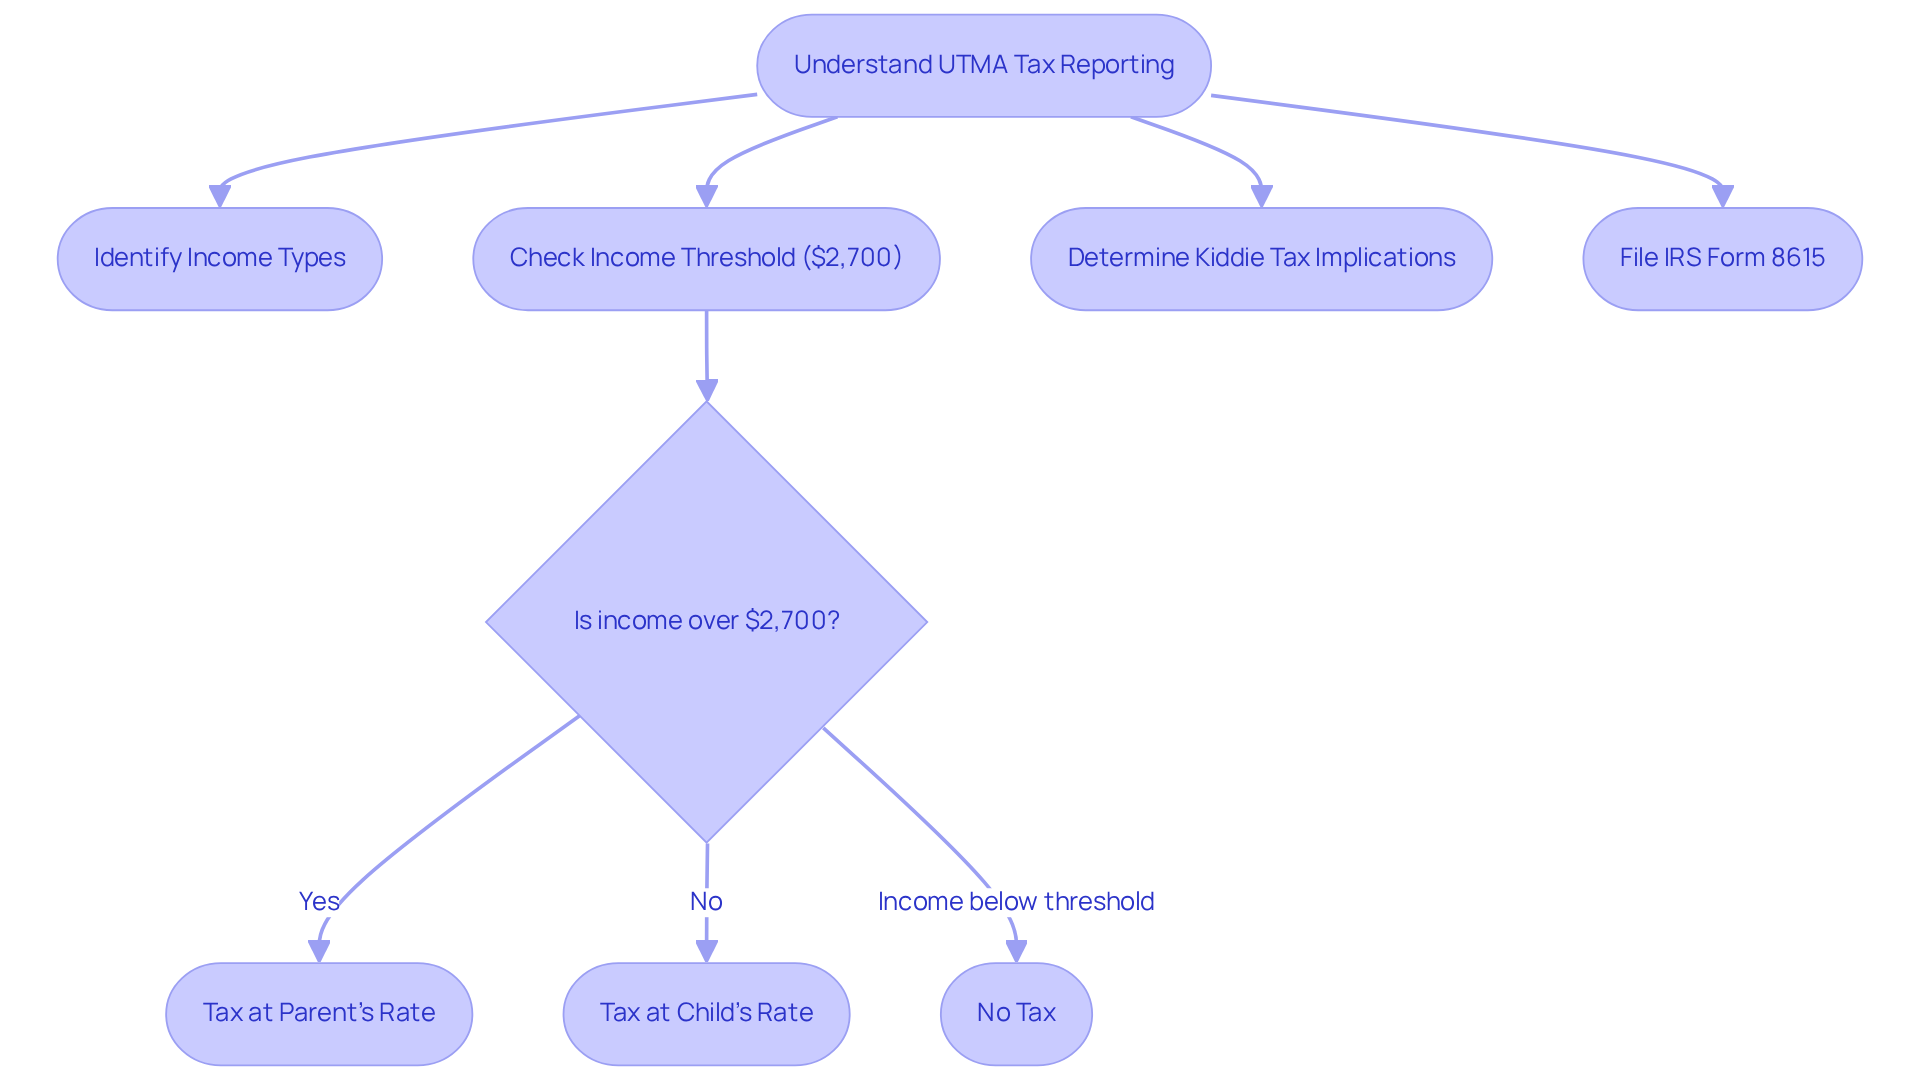
Understanding UTMA account tax reporting is crucial for guardians, as it directly impacts your child’s financial future. Income generated from these accounts—like interest, dividends, and capital gains—must be reported on your child’s tax return. Imagine if your child’s unearned income exceeds $2,700 in 2025; this is where the kiddie tax regulations come into play. Any income beyond this threshold may be taxed at your marginal tax rate, which can significantly affect your family’s finances. For instance, consider a 16-year-old with $5,000 in unearned income facing a total tax liability of $871, with $736 taxed at the guardian’s rate. It’s important to understand these implications to navigate this process effectively.
As custodians, you will need to file IRS Form 8615, which is essential for reporting your child’s unearned income. Keeping detailed documentation of all transactions and income generated within the account is vital to ensure compliance with IRS regulations. This diligence can be a game-changer, as families like Emily and Mark learned through their partnership with Bright Advisers. They received support in managing the complexities of UTMA account tax reporting, which included personalized services like tax optimization and thorough planning.
By grasping these requirements and the implications of the kiddie tax, you can make informed choices that enhance your child’s economic future. Together, we can navigate this journey, ensuring stability and freedom through tailored planning. Remember, we’re here for you, ready to assist you in achieving your family’s financial goals.
Follow Step-by-Step Instructions for Tax Reporting
-
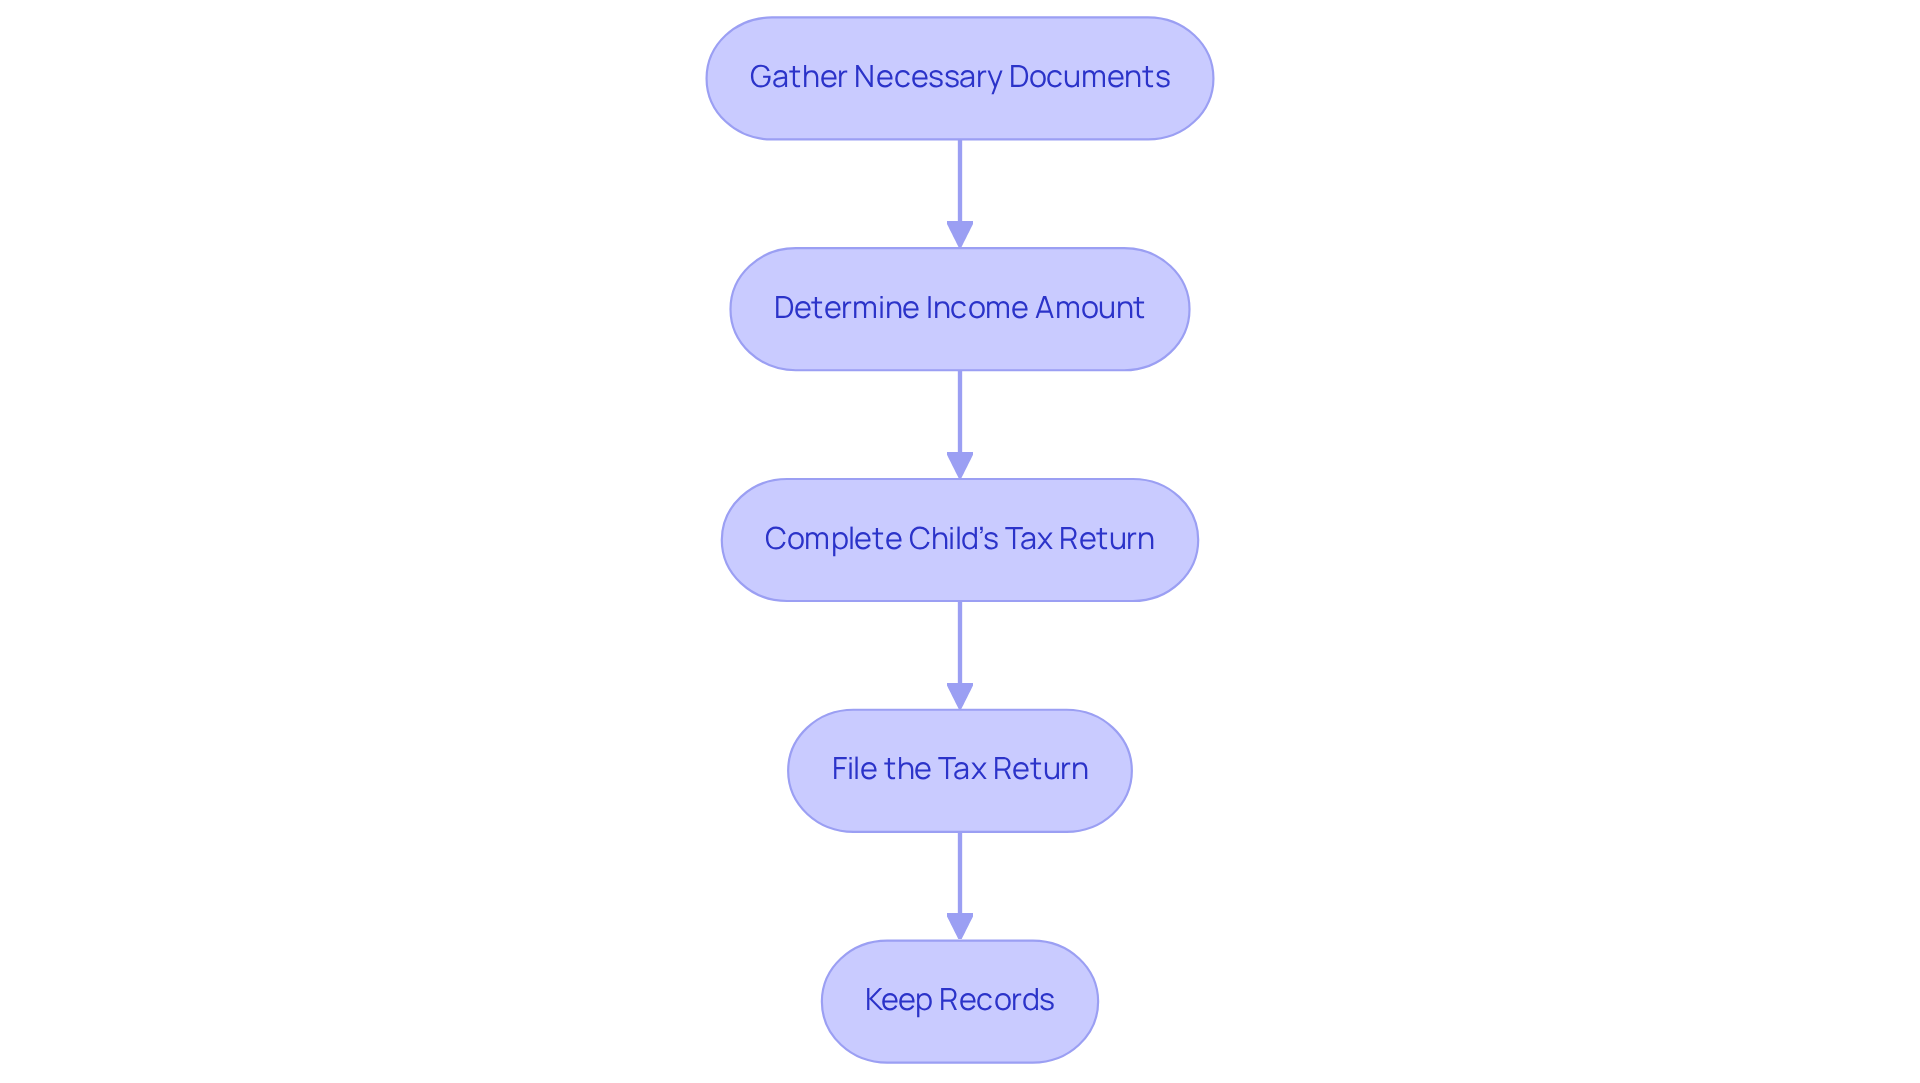
Gather Necessary Documents: Begin your journey by collecting all relevant documents. This includes statements, records of income generated from the UTMA holdings, and any prior tax returns necessary for UTMA account tax reporting. This foundational step ensures you have a complete picture of the financial activity for the year. Think of families like Jay and Emma, who worked with Bright Advisers to establish a comprehensive financial strategy that brought them peace of mind.
-
Determine the income amount by calculating the total unearned income generated by the UTMA account for UTMA account tax reporting in the tax year. This includes interest, dividends, and capital gains. For 2025, remember that the initial $1,350 of unearned income is tax-exempt. Income from $1,350 to $2,700 is taxed at the child’s rate, while any amount above $2,700 is taxed at the guardian’s marginal rate. Additionally, consider the $15,000 standard deduction for individual tax filers, which may influence your overall tax strategy. Just like families such as Allison and Brian, who optimized their tax situations with professional guidance, you can navigate this process with confidence.
-
Complete Child’s Tax Return: It’s time to fill out the child’s tax return accurately, ensuring that you report the unearned income. If the unearned income exceeds $1,350, use IRS Form 8615 to calculate the Kiddie Tax, applicable to dependent children under 18 or full-time students under 24. This form is crucial for compliance and helps determine the tax owed based on the child’s income. It reflects the personalized planning that Bright Advisers provides to empower families like yours.
-
File the Tax Return: Submit the completed tax return by the due date, ensuring all necessary forms are included. It’s essential to complete the parent’s tax return first, as the parent’s taxable income is needed for the Kiddie Tax calculations. Be aware that in New York, the age of majority for UTMA account tax reporting is 21 years, while in California, it is 18 years. This knowledge may influence how you handle the account, similar to how Emily and Mark navigated their monetary complexities with tailored strategies.
-
Keep Records: Finally, maintain copies of all submitted documents and supporting materials for future reference and potential audits. This practice not only assists with inquiries but also supports monitoring the child’s economic growth over time. According to tax experts, guardians usually invest an average of 10 hours finalizing UTMA tax reporting. Staying organized can save you time and lessen stress, just as many families have discovered tranquility through effective monetary planning with Bright Advisers.
By following these steps, you can effectively manage the UTMA account tax reporting process for your child’s fund. Together, we can navigate this journey, ensuring compliance and maximizing potential tax advantages for your family’s future.
Access Tools and Resources for Effective Tax Reporting
Navigating UTMA account tax reporting can feel overwhelming for parents, but there are effective tools and resources available to help you streamline the process. Bright Advisers is here to support you with comprehensive financial strategies tailored to your family’s needs.
-
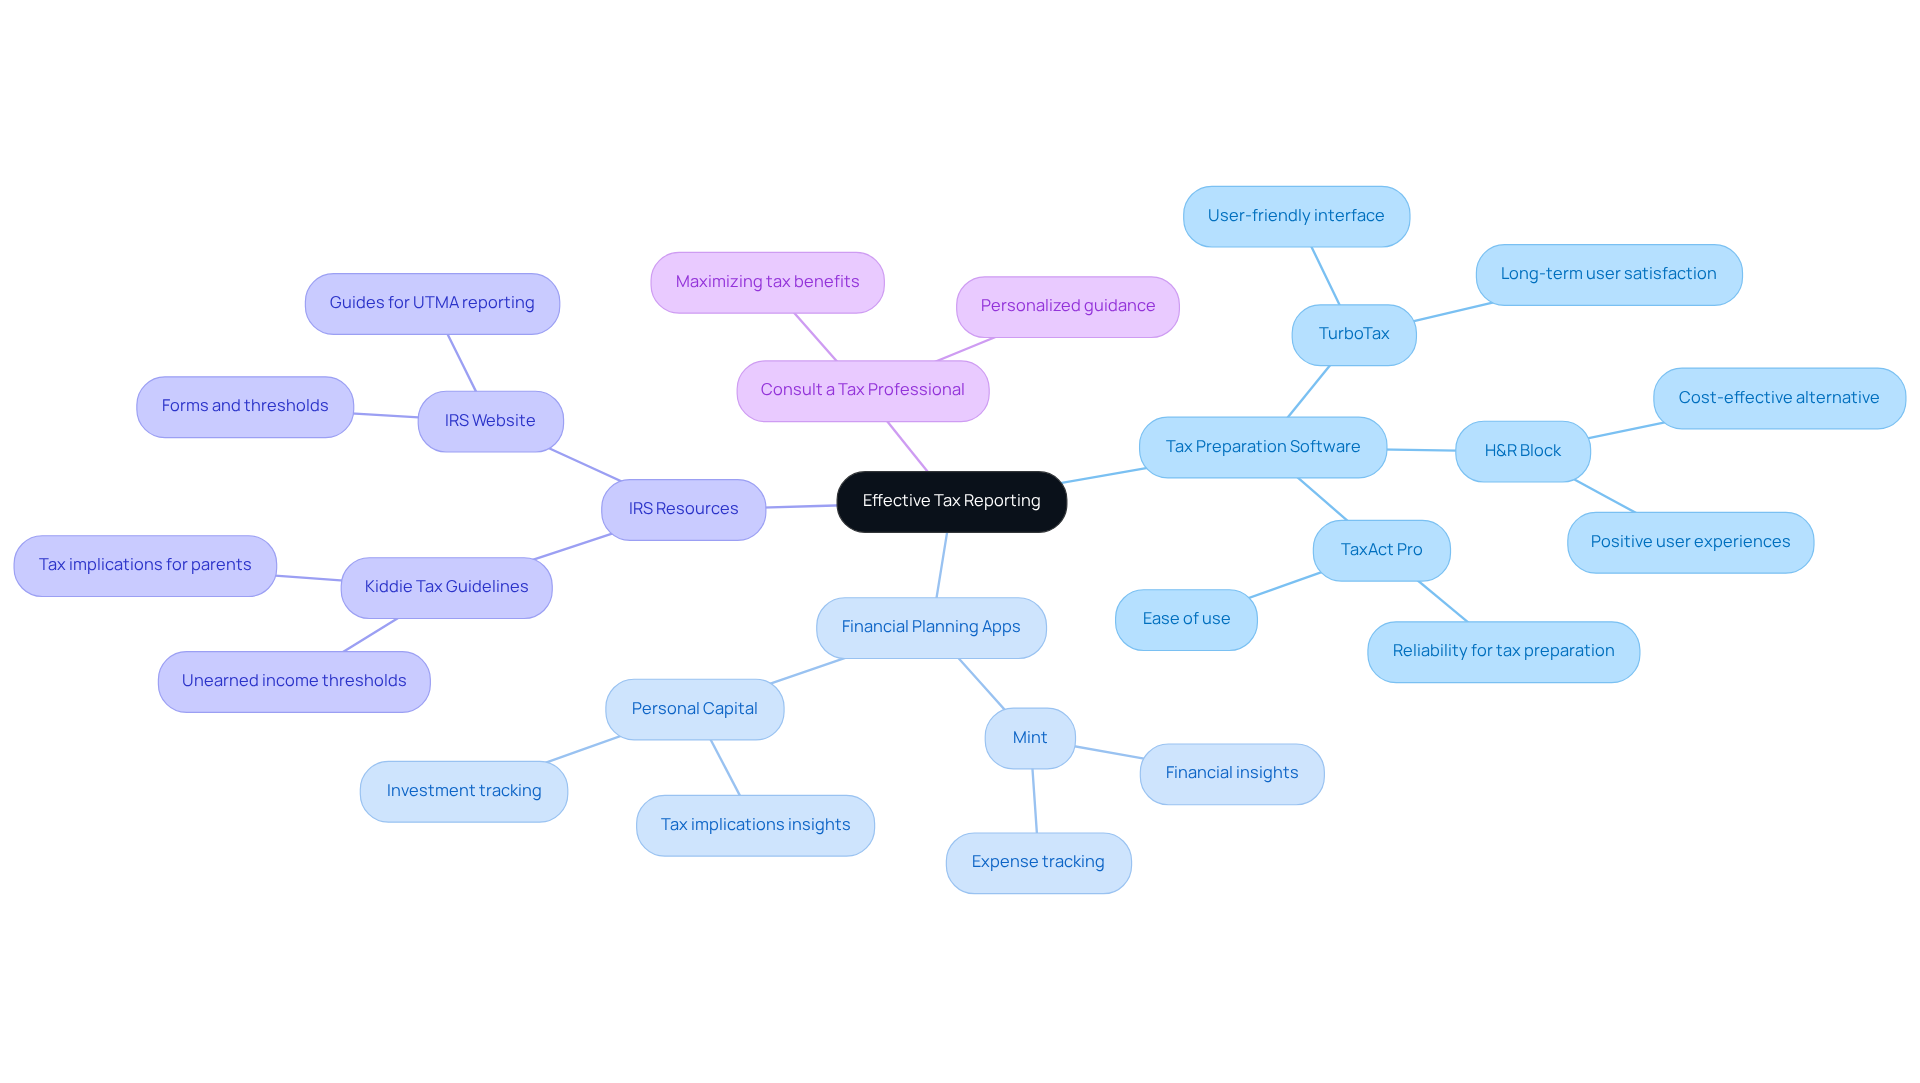
Tax Preparation Software: Imagine filing your taxes with ease using programs like TurboTax and H&R Block. These user-friendly platforms simplify the tax filing process, ensuring compliance with IRS regulations. Bright Advisers encourages families to incorporate such tools into their financial strategy, especially as the personal finance application market continues to grow, highlighting our increasing reliance on these valuable resources.
-
Financial Planning Apps: Picture having all your income and expenses related to UTMA accounts at your fingertips. Applications like Mint and Personal Capital are invaluable for this purpose. They not only help track your financial performance but also provide insights into tax implications, enhancing your overall financial literacy. Bright Advisers’ innovative technology empowers families to make informed financial decisions, with studies showing that users of financial planning apps experience a 30% boost in managing tax-related tasks effectively.
-
IRS Resources: It’s important to understand that the IRS website is a vital resource for parents. It offers detailed guides and forms specific to UTMA account tax reporting. Familiarizing yourself with these resources can significantly ease the tax preparation journey. Pay special attention to the Kiddie tax thresholds—unearned income exceeding $2,700 is taxed at the parent’s marginal tax rate. Bright Advisers motivates families to integrate these insights into their overall planning, ensuring you’re well-prepared.
-
Consult a Tax Professional: For personalized guidance tailored to your family’s unique financial situation, consulting a tax professional who specializes in family finances is highly recommended. Their expertise can shed light on complex tax issues and help you maximize your tax benefits. Bright Advisers offers holistic wealth management services, providing the professional support you need to navigate tax planning challenges effectively.
By utilizing these tools and resources, along with the compassionate support of Bright Advisers, you can confidently and efficiently tackle the complexities of UTMA account tax reporting. Remember, together, we can navigate this journey toward financial clarity and security.
Conclusion
Navigating the complexities of UTMA account tax reporting is essential for parents who wish to secure their children’s financial futures. These accounts not only facilitate the transfer of assets but also offer unique tax advantages that can significantly impact a family’s financial strategy. By understanding the requirements and implications of these accounts, guardians can make informed decisions that benefit both their children and their overall financial health.
Imagine if you could simplify your financial planning while ensuring your children’s future is bright. This article delves into various crucial aspects, including:
- The foundational purpose of UTMA accounts
- The tax benefits associated with them
- The step-by-step process for accurate tax reporting
Key points such as:
- The kiddie tax thresholds
- The necessity of filing IRS Form 8615
- The importance of maintaining thorough documentation
are highlighted. Additionally, utilizing financial tools and seeking professional guidance can streamline the tax reporting process and enhance your financial literacy.
Together, we can embrace the knowledge and resources available for UTMA account tax reporting. This is vital for ensuring compliance and maximizing potential benefits. By taking proactive steps, parents can navigate this journey with confidence and instill valuable financial lessons in their children. The future is bright when families leverage the advantages of UTMA accounts, paving the way for responsible financial management and growth. We’re here for you—let’s make this journey together.
Frequently Asked Questions
What is a UTMA account?
A Uniform Transfers to Minors Act (UTMA) account is a custodial setup that allows for the transfer of assets to children without the complexities of a formal trust. It is managed by a caregiver, often a relative or guardian.
What types of assets can be included in a UTMA account?
UTMA accounts can include a variety of assets such as cash, stocks, bonds, and even real estate.
At what age do children gain control over the funds in a UTMA account?
Children typically gain full control over the funds when they reach the age of majority, which varies by state but is usually 18 or 21.
What are the tax benefits of a UTMA account?
In 2025, the first $1,350 of earnings in a UTMA account is tax-free for minors. Any income above this threshold is taxed at the child’s lower tax rate, which can ease the overall tax burden for families.
How do contributions to a UTMA account affect gift taxes?
Contributions to a UTMA account are considered irrevocable gifts and allow guardians to benefit from federal tax exemptions of up to $19,000 annually without triggering gift taxes.
Why is it important to involve children in the UTMA account process?
Involving children in the UTMA account process helps spark their economic education and allows them to understand the impact of their financial choices.
What is the overall purpose of a UTMA account?
The overall purpose of a UTMA account is to provide a versatile and tax-effective way to secure children’s financial futures while imparting valuable lessons about money management and responsibility.
List of Sources
- Understand UTMA Accounts and Their Purpose
- What is a UTMA Account, and Why Should You Consider One for Your Kids? | KidVestors (https://kidvestors.co/post/what-is-a-utma-account)
- UGMA & UTMA accounts | Tips for custodial accounts | Fidelity (https://fidelity.com/learning-center/personal-finance/custodial-account-for-kids)
- What Is a UTMA or UGMA Account for 2025 | Research.com (https://research.com/student-loans/what-is-a-utma-or-ugma-account)
- Are UTMA Accounts a Good Idea for your Minor Children? (https://vjrussolaw.com/are-utma-accounts-a-good-idea-for-your-minor-children)
- Benefits OnLine | Education Center (https://benefits.ml.com/education/education-articles/articles?title=compareandcontrast4keywaystosaveforcollege)
- Identify Tax Reporting Requirements for UTMA Accounts
- Understanding the Kiddie Tax: Rules and Implications in 2025 (https://jacksonhewitt.com/tax-help/tax-tips-topics/personal-finance-savings/understanding-the-kiddie-tax-2025)
- 7 Essential UTMA Withdrawal Tax Rules Every Parent Should Know – Bright Advisers (https://brightadvisers.com/7-essential-utma-withdrawal-tax-rules-every-parent-should-know)
- Topic no. 553, Tax on a child’s investment and other unearned income (kiddie tax) | Internal Revenue Service (https://irs.gov/taxtopics/tc553)
- The Kiddie Tax: Rates, Limits and Rules for 2025 (https://smartasset.com/taxes/kiddie-tax)
- Tax Filing Requirements For Minor Children with Investment Income | Greenbush Financial Group (https://greenbushfinancial.com/all-blogs/minor-child-investment-income-tax-return-filing)
- Follow Step-by-Step Instructions for Tax Reporting
- Tax Filing Requirements For Minor Children with Investment Income | Greenbush Financial Group (https://greenbushfinancial.com/all-blogs/minor-child-investment-income-tax-return-filing)
- Uniform Transfers to Minors Act (UTMA): What It Is and How It Works | Facet (https://facet.com/estate-planning/what-is-utma-how-does-it-work)
- UTMA Accounts – What You Need To Know – Bridgeview Capital Advisors, Inc. (https://bridgeviewadvisors.com/utma-accounts)
- Custodial Accounts for Children Under Age 21: Montana Uniform Transfers to Minors Act (UTMA) – MSU Extension | Montana State University (https://montana.edu/extension/montguides/montguidehtml/MT199910HR.html)
- Custodial Accounts UTMA (https://pnc.com/en/personal-banking/investments-and-retirement/education-accounts/custodial-accounts-utma.html)
- Access Tools and Resources for Effective Tax Reporting
- Tax Filing Requirements For Minor Children with Investment Income | Greenbush Financial Group (https://greenbushfinancial.com/all-blogs/minor-child-investment-income-tax-return-filing)
- Tax Software – Bogleheads.org (https://bogleheads.org/forum/viewtopic.php?t=389211)
- 1099-Div UTMA brokerage accts (https://ttlc.intuit.com/community/taxes/discussion/1099-div-utma-brokerage-accts/00/1142177)
- Personal Finance App Market Size, Share & Trends, 2025-2033 (https://businessresearchinsights.com/market-reports/personal-finance-app-market-117811)

Kevin has advised high-income W-2 tech and biotech families since 2015, and leads the education-first Age Five Family Office from Brea, California.
Connect on LinkedIn → · About KevinThis is part of how we approach Age Five Wealth Education for high-income W-2 families at Bright Advisers.
Keep reading