

Key Highlights
- UTMA accounts allow adults to transfer assets to minors, managed by a custodian until the child reaches adulthood.
- Key features include custodianship, legal ownership transfer at adulthood, and tax advantages for minors.
- Custodians have fiduciary duties, including making investment decisions, maintaining records, and facilitating the transition of control to the child.
- Choosing the right UTMA beneficiary is crucial; parents should consider primary and secondary beneficiaries and consult financial advisors.
- Common challenges include understanding tax implications, selecting a custodian, preventing asset mismanagement, and navigating age of majority laws.
- UTMA assets can impact a child’s eligibility for financial aid, necessitating careful planning.
- Bright Advisers emphasises fiduciary duty, transparency, and personalised wealth management strategies for families.
Introduction
Many parents feel overwhelmed by the thought of managing their children’s financial futures, but understanding the Uniform Transfers to Minors Act (UTMA) can help ease that burden. This guide gently walks you through the steps of designating beneficiaries for UTMA accounts, empowering you to make informed decisions that align with your family’s goals.
It’s important to understand that while there are challenges, with the right support, you can navigate custodian responsibilities and tax implications to protect your child’s assets.
Understand UTMA Accounts and Their Purpose
Imagine a future where your child is financially savvy and ready to take on the world-this is possible with the right planning today. The Uniform Transfers to Minors legislation allows adults to transfer assets to minors while appointing a custodian to oversee these assets until the minor attains a specified age. Custodial funds provide a varied selection of asset choices, such as cash, stocks, bonds, and even real estate, making them a flexible option for parents looking to ensure their offspring’s financial futures.
Key Features of UTMA Accounts:
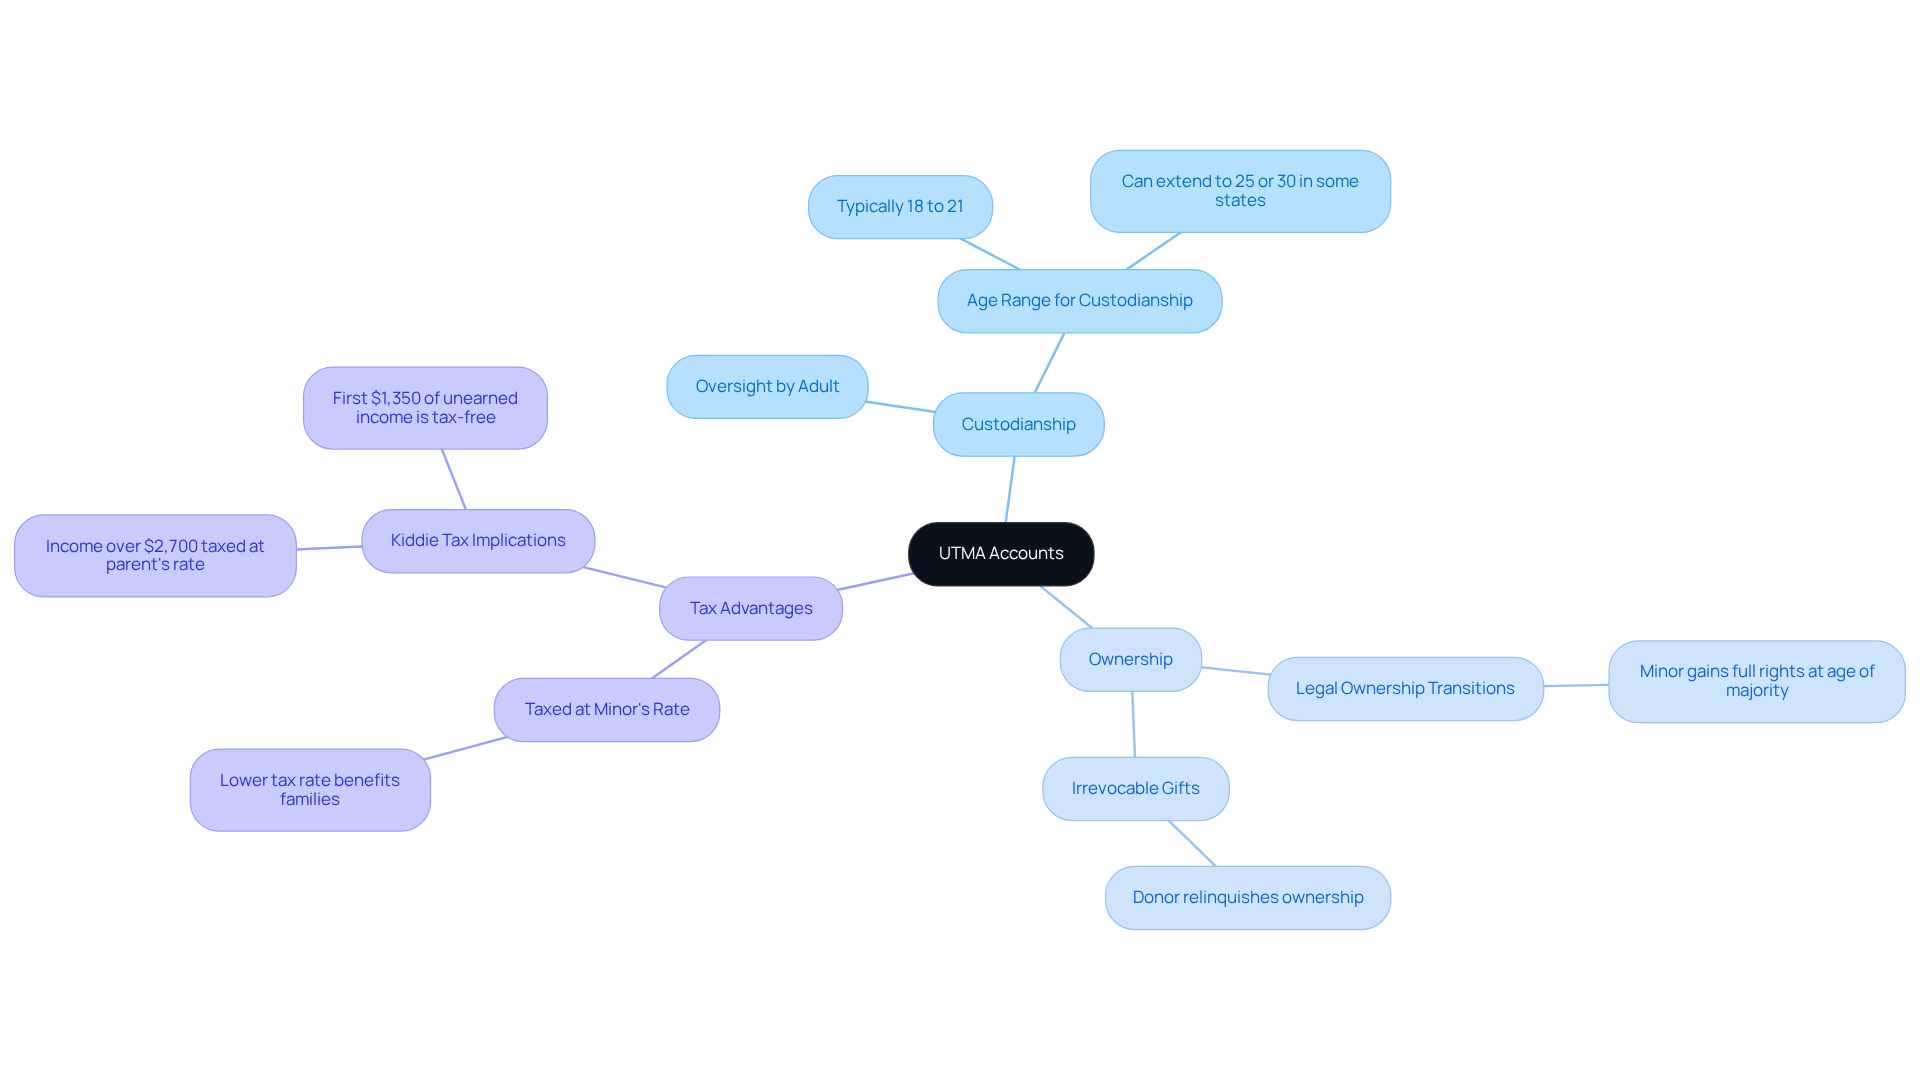
- Custodianship: An adult, typically a parent or guardian, oversees the account until the child attains the age of majority, which varies by state, generally ranging from 18 to 25 years.
- Ownership: The minor becomes the legal owner of the assets, gaining full rights to them upon reaching the designated age.
- Tax Advantages: Income produced within the fund is taxed at the minor’s lower tax rate, which can be advantageous for families, particularly when considering the ‘kiddie tax’ implications.
Understanding these features can help you make the most of UTMA arrangements for your family’s future. Custodians oversee the investments and withdrawals on behalf of the minor, ensuring that the assets are utilized properly for their benefit. When your child reaches adulthood, they’ll take full control of the funds, stepping into a world of financial responsibility that you can help them navigate. This transition highlights the importance of planning ahead to assist children in making prudent monetary choices.
Recent statistics show that custodial savings plans are becoming more popular among families in Southern California, with many parents acknowledging the flexibility and investment choices they offer. For instance, custodial funds can greatly influence aid eligibility, decreasing it by as much as 20% of the value, which is an important factor for families preparing for higher education.
In summary, custodial funds not only enable tax-efficient gifting but also act as a valuable resource for educating youngsters about responsibility with money and managing investments. We’re here to help you explore the best strategies with financial advisors, ensuring your family’s goals are met with care and understanding. By taking these steps now, you’re not just securing their future; you’re empowering them to make wise financial choices as they grow.
Select and Designate Your UTMA Beneficiary
Choosing the right utma beneficiary designation for your fund can feel overwhelming, but it’s a crucial step in securing your child’s financial future. Let’s explore some gentle steps to help you make this important decision with confidence:
Steps to Designate a Beneficiary:
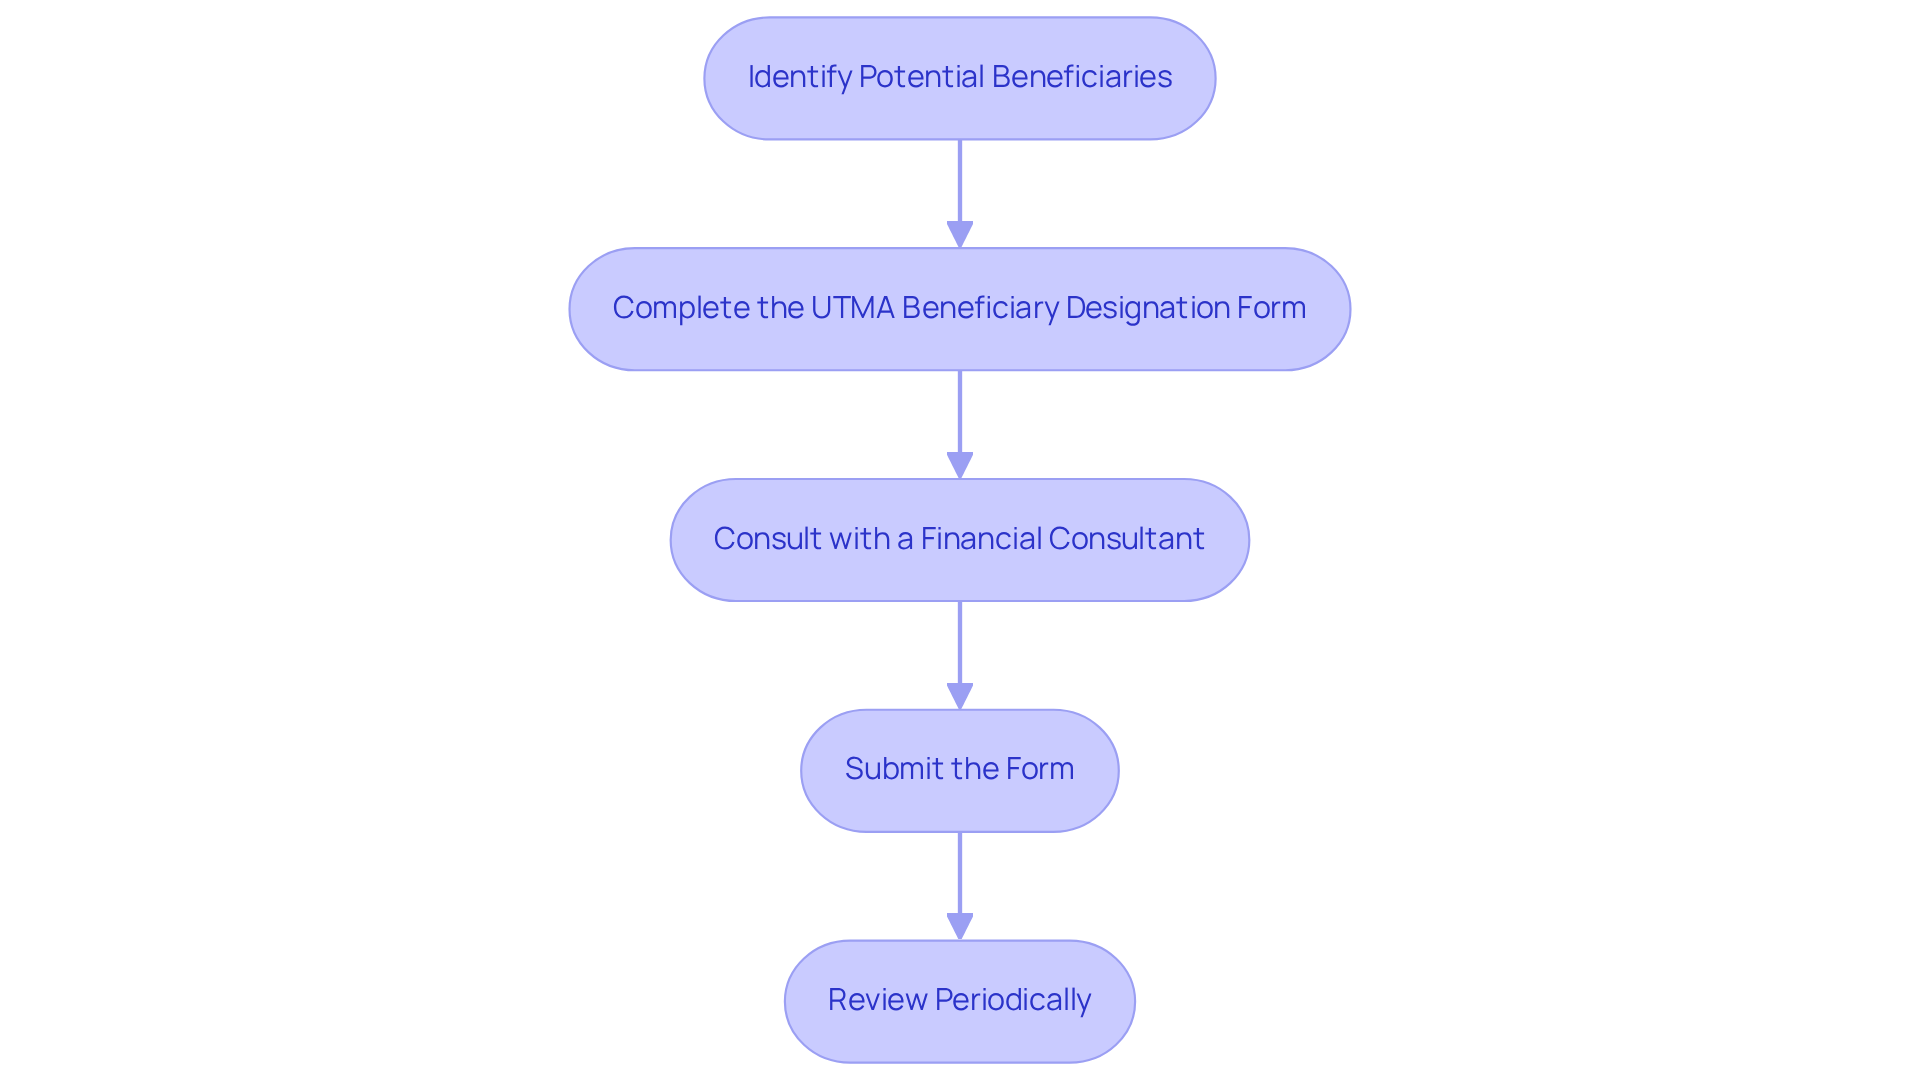
- Identify Potential Beneficiaries: Typically, the primary beneficiary is your minor child. It’s wise to consider naming a secondary beneficiary in your utma beneficiary designation too, just in case the primary one can’t inherit.
- Complete the utma beneficiary designation form: You’ll need to get this form from your bank. It asks for important details like the beneficiary’s name, date of birth, and Social Security number.
- Consult with a Financial Consultant: Talking to a financial consultant can help you feel more secure in your choices, especially when it comes to your child’s future. They can clarify the implications of your decisions, particularly regarding tax and estate planning, ensuring your wishes are honored.
- Submit the Form: Once you’ve filled it out, send it to your bank and keep a copy for your records.
- Review Periodically: Life changes, like marriage or welcoming a new child, may mean it’s time to update your beneficiary designations. Regularly checking the utma beneficiary designation ensures it accurately reflects your current family situation. Remember, outdated beneficiary lists can lead to assets unintentionally going to the wrong people, which is why this step is so important.
By taking these steps, you’re not just planning; you’re ensuring peace of mind for your family’s future. At Bright Advisers, we’re here for you, committed to providing clear, comprehensive fee structures with no hidden charges, so you can focus on what truly matters-your family.
Identify the Custodian’s Responsibilities
Many parents feel overwhelmed when it comes to managing their child’s financial future, especially concerning the UTMA beneficiary designation. Understanding the custodian’s responsibilities is crucial for ensuring your child’s financial well-being.
Custodian Responsibilities:
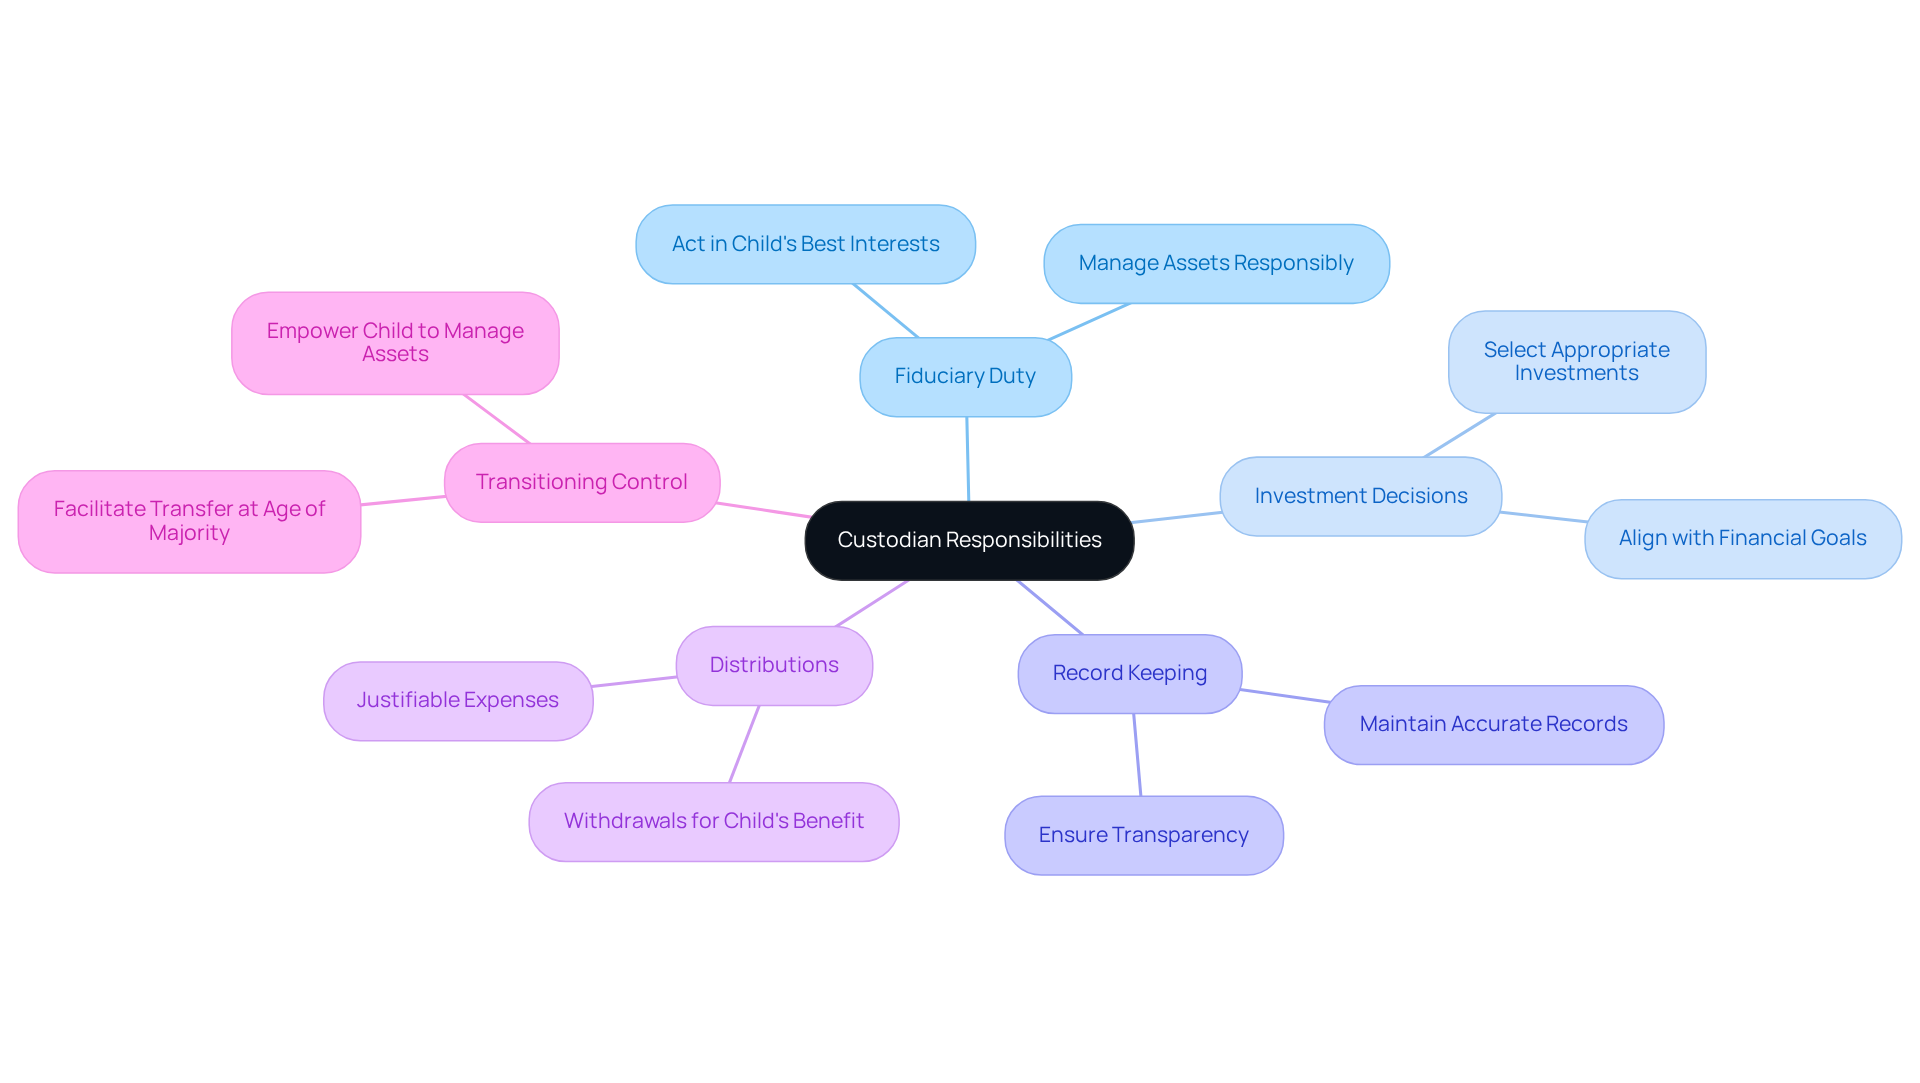
- Fiduciary Duty: It’s important to know that the custodian is there to act in your child’s best interests, managing their assets with care and responsibility. This means making choices that prioritize your child’s economic welfare.
- Investment Decisions: The custodian is responsible for making investment choices that align with your child’s financial goals. This may involve selecting a mix of stocks, bonds, or other investment vehicles that suit their future needs.
- Record Keeping: Maintaining accurate records of all transactions, including deposits, withdrawals, and investment performance, is essential for transparency and accountability. This ensures that both the custodian and your child can monitor the growth and activity of the funds.
- Distributions: The custodian can make withdrawals for your child’s benefit, but these must be justifiable and in line with their needs. This means they can help cover important expenses while still keeping your child’s future in mind.
- Transitioning Control: Once your child reaches the age of majority, usually between 18 and 25 depending on the state, the custodian must facilitate the transfer of control of the funds to them. This process is crucial for ensuring a smooth transition and empowering your child to manage their assets independently.
By grasping these responsibilities, you can feel confident in selecting a custodian who will safeguard your child’s financial well-being. With the right custodian, you can rest assured that your child’s financial future is in caring hands, allowing you to focus on what truly matters-your family’s happiness and security.
Navigate Common Challenges in UTMA Designation
Navigating the world of custodial funds can feel overwhelming for parents, especially when it comes to understanding the UTMA beneficiary designation process. Here are some common issues and strategies to address them:
Common Challenges:
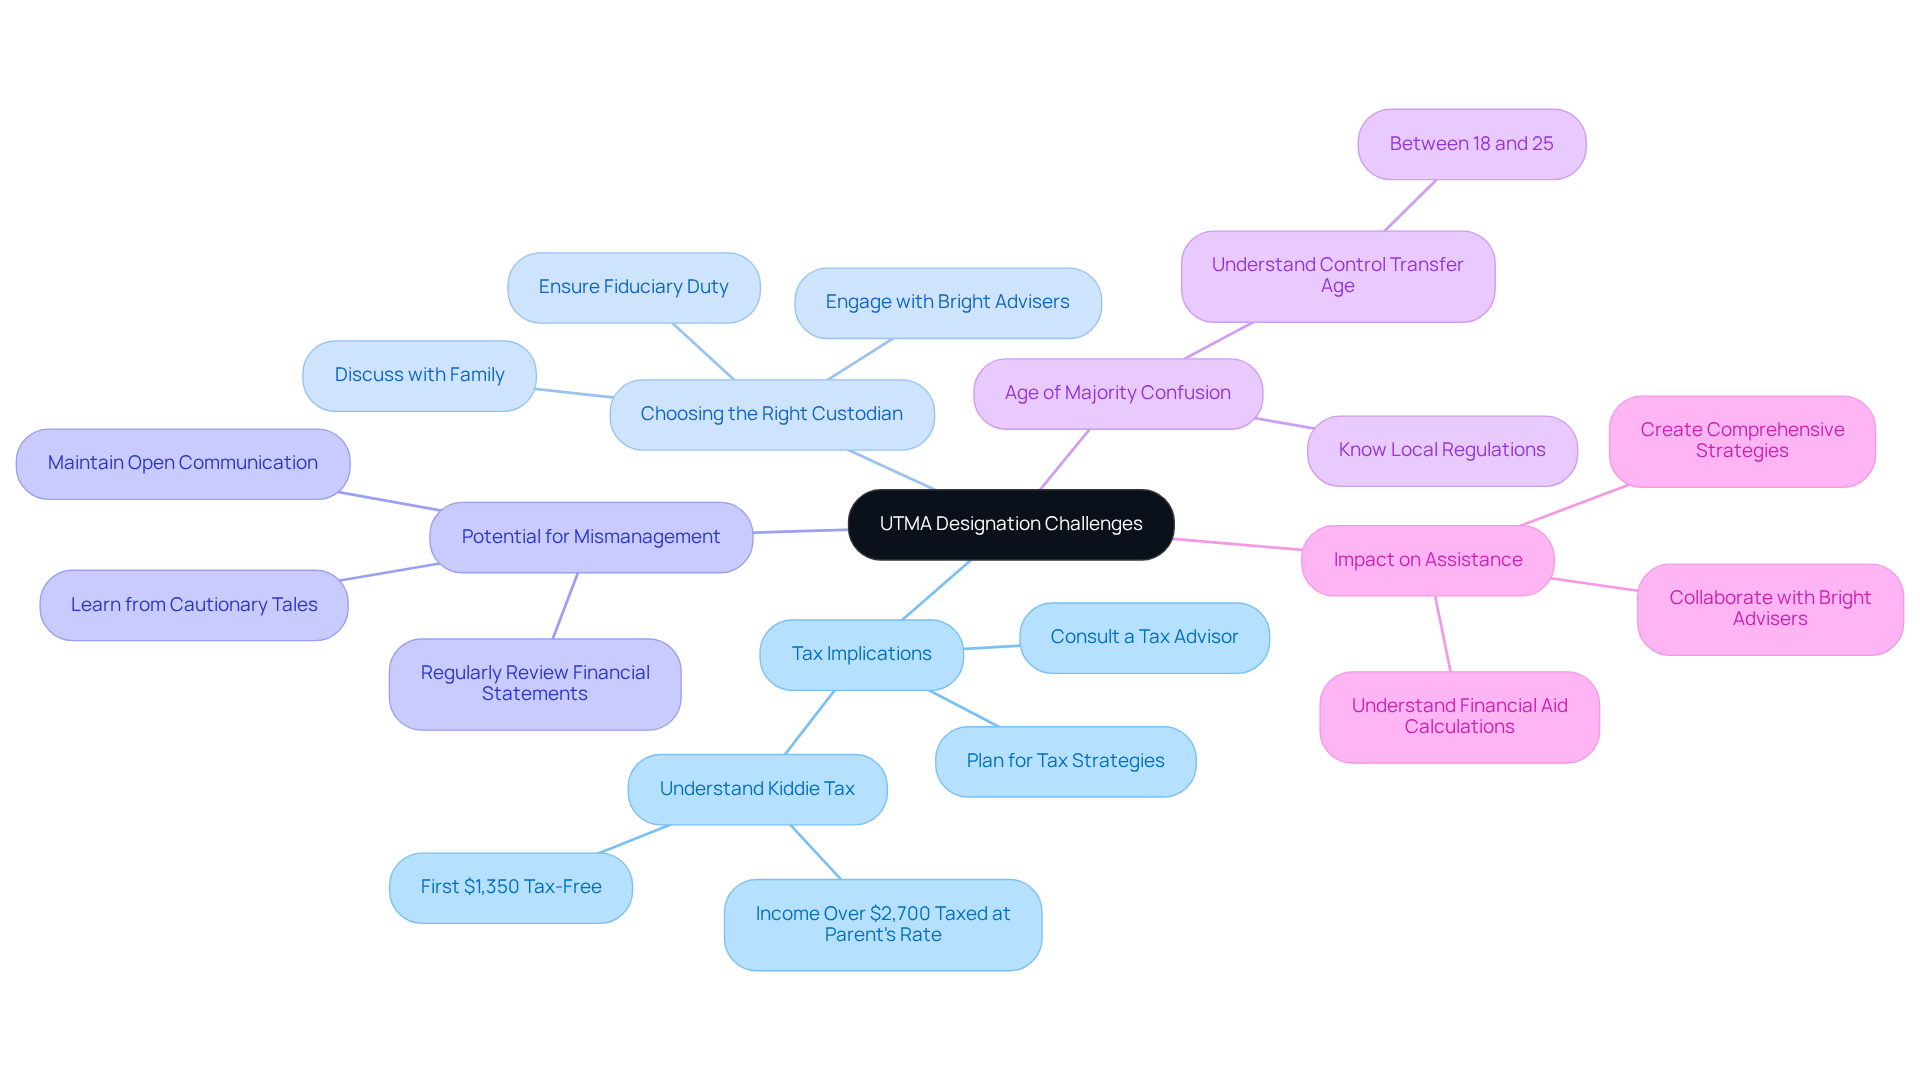
- Understanding the tax implications of the UTMA beneficiary designation, many parents find themselves feeling overwhelmed by the tax implications of UTMA funds. Consulting a tax advisor is essential to grasp how income generated in these accounts will be taxed and its potential impact on overall tax strategies. For 2026, the first $1,350 of a child’s unearned income is tax-free, but any income exceeding $2,700 is taxed at the parent’s marginal rate, making careful planning necessary. Bright Advisers incorporates tax planning strategies to assist families in enhancing their tax situations, much like how Allison and Brian maximized their potential through effective tax optimization.
- Choosing the Right Custodian: Selecting a custodian can be daunting. Choosing someone who truly understands their fiduciary duties can make all the difference for your family. Engaging in discussions with family members about this choice can provide valuable insights and consensus. Bright Advisers emphasizes transparency and fiduciary duty, ensuring that families feel confident in their financial decisions.
- Potential for Mismanagement: There is a risk that custodians may not manage the assets effectively. Parents should regularly examine financial statements and maintain open lines of communication with the custodian to ensure transparency and accountability. A cautionary tale involves a grandfather who withdrew funds from his granddaughters’ UTMA beneficiary designation, leading to legal disputes when they turned 18, which highlights the importance of responsible management. Bright Advisers encourages proactive engagement to prevent such issues.
- Age of Majority Confusion: Laws concerning the age at which a minor obtains control of the funds differ by state. Acquainting yourself with local regulations is essential to prevent unforeseen surprises when your child reaches adulthood, as control usually shifts between the ages of 18 and 25. Bright Advisers can guide families through these complexities, ensuring they are well-informed.
- Impact on Assistance: The UTMA beneficiary designation of assets in a UTMA fund can adversely influence a child’s eligibility for aid, as they are regarded as the child’s property. Understanding how these records influence aid computations is essential for efficient planning. By collaborating with Bright Advisers, families can create thorough strategies that align with their objectives, similar to how Emily and Mark achieved the flexibility to make career choices based on their desired work-life balance.
By taking proactive steps to address these challenges, you can ensure that your UTMA accounts truly support your children’s financial futures. Bright Advisers is dedicated to helping families make wise wealth decisions and preserve wealth across generations.
Conclusion
Imagine feeling confident about your child’s financial future, knowing you’ve taken the right steps to secure it. Mastering the UTMA beneficiary designation process is essential for parents like you who want to ensure their children’s financial well-being. Understanding UTMA accounts can feel overwhelming. But by choosing the right beneficiaries and knowing the custodian’s role, you can navigate this process with confidence.
Think about the tax advantages and the role of custodians. Many parents face challenges during this process, but you’re not alone. By identifying potential beneficiaries and consulting with financial advisors, you can ensure that your plans align with your family’s evolving needs. Remember, it’s important to regularly review these designations to keep everything on track.
At its heart, setting up a UTMA account is about more than just numbers; it’s about creating a secure future for your children. This journey fosters a legacy of financial literacy and responsibility for future generations. Working with experts like Bright Advisers can make this journey smoother, helping you make informed choices for your family’s future. By taking these proactive steps, you’re not just planning for the future; you’re nurturing a legacy of financial wisdom for your children.
Frequently Asked Questions
What is the purpose of UTMA accounts?
UTMA accounts allow adults to transfer assets to minors while appointing a custodian to oversee these assets until the minor reaches a specified age, helping to prepare them for financial responsibility.
Who can be a custodian for a UTMA account?
Typically, a parent or guardian acts as the custodian, overseeing the account until the child attains the age of majority, which varies by state, generally ranging from 18 to 25 years.
What types of assets can be held in a UTMA account?
UTMA accounts can hold a variety of assets, including cash, stocks, bonds, and even real estate, providing flexibility for parents.
What are the tax advantages of UTMA accounts?
Income generated within a UTMA account is taxed at the minor’s lower tax rate, which can be beneficial for families, especially considering the implications of the ‘kiddie tax.’
What happens to the assets in a UTMA account when the minor reaches adulthood?
Upon reaching the designated age, the minor becomes the legal owner of the assets and gains full rights to them, stepping into financial responsibility.
How do custodial funds affect financial aid eligibility for higher education?
Custodial funds can significantly influence aid eligibility, potentially decreasing it by as much as 20% of the account’s value, which is an important consideration for families planning for college.
How can families benefit from UTMA accounts?
UTMA accounts not only enable tax-efficient gifting but also serve as a valuable resource for educating children about financial responsibility and investment management.
What role do financial advisors play in managing UTMA accounts?
Financial advisors can help families explore the best strategies for utilizing UTMA accounts, ensuring that their financial goals are met with care and understanding.
List of Sources
- Understand UTMA Accounts and Their Purpose
- UGMA-UTMA Account: The Benefits of One | Vanguard (https://investor.vanguard.com/accounts-plans/ugma-utma)
- UGMA & UTMA accounts: Complete guide to benefits and setup (https://thrivent.com/insights/college-planning/what-are-ugma-and-utma-accounts)
- UTMA & UGMA Custodial Accounts: Overview, Benefits – NerdWallet (https://nerdwallet.com/investing/learn/utma-ugma)
- Pros and cons of custodial accounts for minors | Dominick Feld Hyde, P.C. (https://dfhlaw.com/2022/10/pros-and-cons-of-custodial-accounts-for-minors)
- UTMA Accounts Explained: Rules, Custodial Brokerages and More (https://kiplinger.com/personal-finance/603545/hey-parents-caution-is-critical-with-utma-custodial-accounts)
- Select and Designate Your UTMA Beneficiary
- Understanding Beneficiary Designation In Estate Planning (https://westernsouthern.com/retirement/beneficiary-designation)
- Beneficiary Considerations – River’s Edge Wealth Management (https://riversedgewm.com/beneficiary-considerations)
- Why naming beneficiaries is so important (https://ameriprise.com/financial-goals-priorities/family-estate/designation-of-beneficiary)
- The Crucial Importance of Listing Beneficiaries on Investment Accounts (https://raymondjames.com/carsonadvisory/blog/2023/08/08/the-crucial-importance-of-listing-beneficiaries-on-investment-accounts)
- UTMA Accounts: How They Help Boston Kids Build Wealth – Sherr Financial Associates (https://sherrfinancial.com/financial-planning/utma-accounts-how-they-help-boston-kids-build-wealth)
- Identify the Custodian’s Responsibilities
- What Are UGMA and UTMA Accounts? (https://experian.com/blogs/ask-experian/what-are-ugma-and-utma-accounts)
- Regulatory Notice 20-07 | FINRA.org (https://finra.org/rules-guidance/notices/20-07)
- UGMA & UTMA Custodial Accounts – Finaid (https://finaid.org/savings/ugma)
- Navigate Common Challenges in UTMA Designation
- UTMA Accounts for Minors: What Could Possibly Go Wrong? (https://davidtobacklaw.com/utma-accounts-for-minors-what-could-possibly-go-wrong)
- What Are the Potential Tax Implications of a Custodial Account? | Chase (https://chase.com/personal/investments/learning-and-insights/article/tax-implications-custodial-accounts)
- UGMA/UTMA Custodial Accounts (https://capitalgroup.com/individual/products/ugma-utma.html)
- Pros and Cons of Custodial Accounts for Minors (https://thklaw.com/custodial-accounts-for-minors)

Kevin has advised high-income W-2 tech and biotech families since 2015, and leads the education-first Age Five Family Office from Brea, California.
Connect on LinkedIn → · About KevinThis is part of how we approach Age Five Wealth Education for high-income W-2 families at Bright Advisers.
Keep reading