

Key Highlights
- UTMA accounts allow parents to transfer assets to their children without a formal trust, providing financial security until adulthood.
- Funds in UTMA accounts can be used for various needs, such as education or starting a business, promoting financial responsibility in children.
- Setting up a UTMA account involves choosing a custodian, selecting a financial institution, and completing necessary documentation.
- Contributions to UTMA accounts are irrevocable gifts and can impact financial aid eligibility for college.
- Tax implications include kiddie tax rules, where unearned income is taxed differently based on thresholds.
- Strategic withdrawals from UTMA accounts can help manage taxes and financial aid considerations effectively.
- Investment strategies for UTMA accounts should include diversification, focusing on growth investments, and regular contributions to enhance long-term growth.
- Bright Advisers emphasises fiduciary duty and transparency in financial planning, helping families navigate the complexities of UTMA accounts.
Introduction
Imagine feeling confident about your child’s financial future, knowing you’ve taken steps to secure it through smart planning. UTMA IRA accounts offer a unique opportunity for young parents to protect their children’s financial futures while teaching them valuable lessons about money management. Many parents feel overwhelmed by the rules and regulations surrounding these accounts. It’s important to understand how to navigate the complexities of eligibility, tax implications, and the best investment strategies.
How can you make the most of UTMA IRA accounts to protect your child’s future while teaching them about financial responsibility?
Define UTMA Accounts and Their Purpose
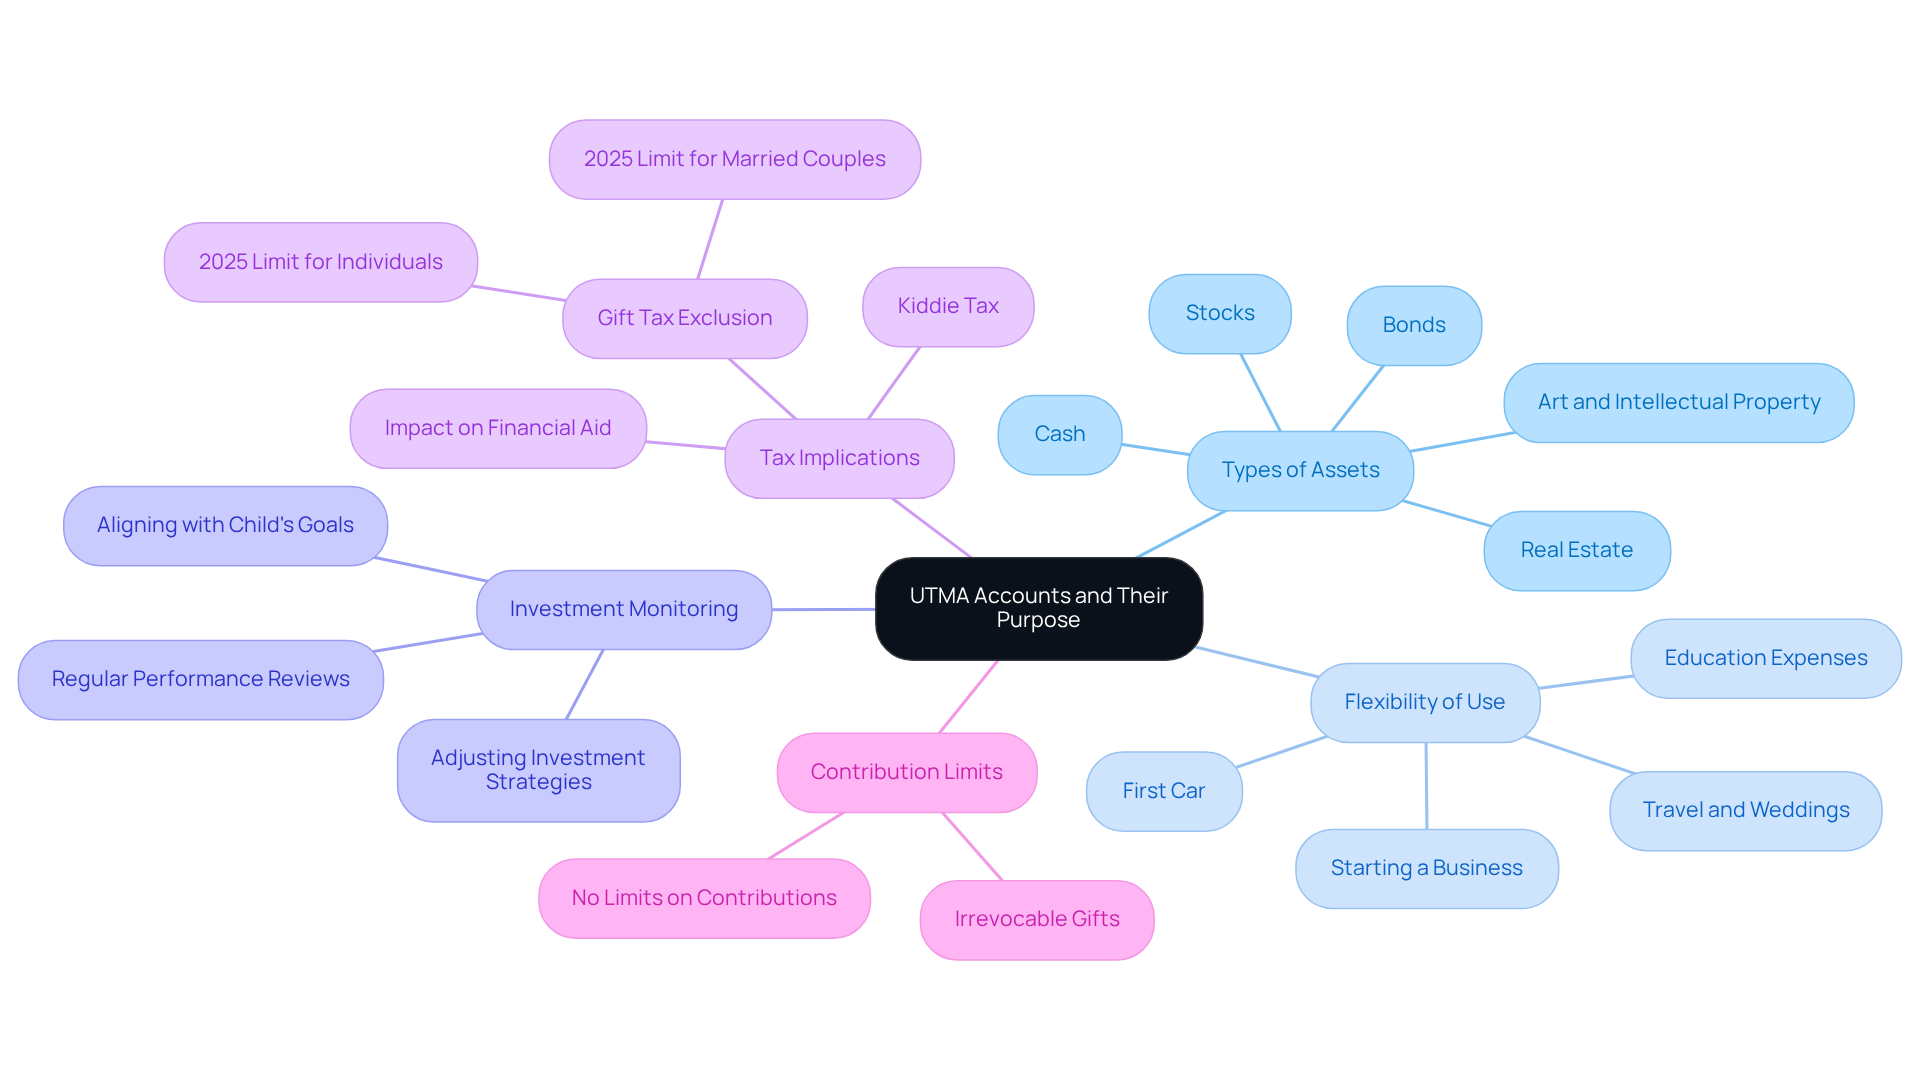
Imagine the peace of mind that comes from knowing your child’s financial future is secure, even before they reach adulthood. A custodial arrangement under the UTMA IRA allows you to transfer assets to your child without the need for a formal trust. These accounts can hold a variety of assets, including cash, stocks, bonds, and even real estate. The goal is simple: to help you save and invest for your child until they reach adulthood, which typically falls between 18 and 21 years, depending on where you live.
Think about how UTMA accounts give you the freedom to use the funds for anything your child might need, whether it’s education, a first car, or even starting a small business. This flexibility not only provides a financial safety net but also helps instill a sense of responsibility in your child as they learn about managing money.
As your child grows, it’s important to regularly check in on how their investments are doing, making adjustments that fit their changing needs and dreams. Understanding the tax implications and rules surrounding custodial funds is also essential for effective financial planning. Remember, contributions to these accounts are considered irrevocable gifts, which can impact financial aid eligibility when your child applies for college.
For 2025, the yearly gift tax exclusion limit is $19,000 for individuals, which is something to keep in mind when considering contributions to custodial funds. Ultimately, UTMA IRA accounts can be a wonderful way to not only secure your child’s future but also to teach them valuable lessons about saving and managing money along the way. With the guidance of Bright Advisers, you can navigate these complexities, ensuring a balanced approach to financial security and educational readiness. With the right guidance, you can turn financial planning into a meaningful journey that prepares your child for a bright future.
Establish Eligibility and Set Up Your UTMA Account
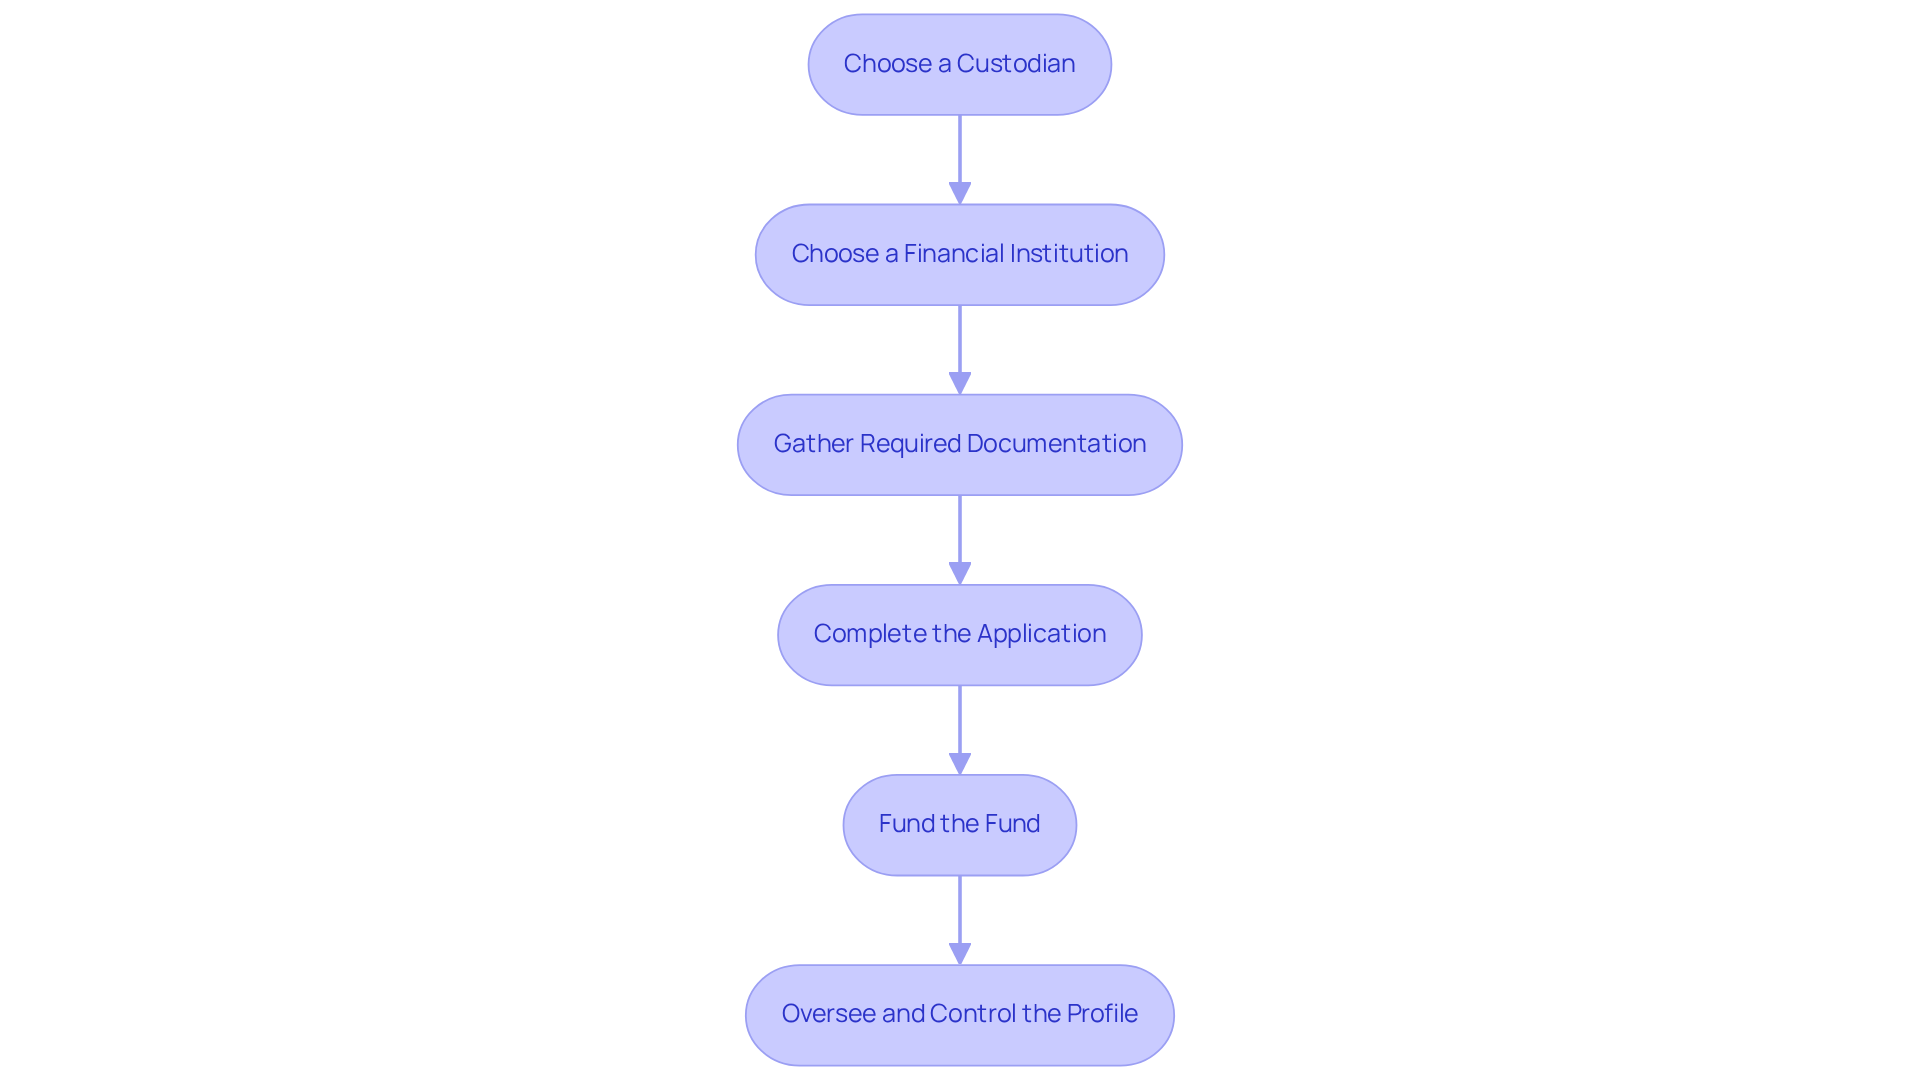
Setting up a custodial savings plan can feel daunting, but it’s a wonderful step toward securing your child’s financial future. Here’s a streamlined process for setting up your UTMA account:
- Choose a Custodian: The custodian, usually a parent or guardian, oversees the funds until the child reaches the age of majority, which varies by state. This role can be filled by a parent, grandparent, or another trusted adult.
- Choose a Financial Institution: You can set up custodial funds at your local bank, credit union, or even a brokerage firm that feels right for you. Take your time to explore different institutions, looking for one that aligns with your family’s needs and offers a variety of investment choices.
- Gather Required Documentation: Prepare the necessary documents, including:
- Identification for the custodian (e.g., driver’s license or passport)
- Social Security number and birth certificate of the minor
- Complete the Application: Fill out the application form provided by the selected institution, ensuring you specify that it is a UTMA IRA arrangement.
- Fund the Fund: You can fund the account with cash, stocks, or other assets. While there are no contribution limits, be aware of potential gift tax implications, especially for contributions exceeding the annual exclusion limit of $19,000 for individuals or $38,000 for married couples in 2026.
- Oversee and Control the Profile: Once your account is set up, keep an eye on the investments to make sure they align with your hopes for your child’s future. This continuous oversight is essential, as the resources in the portfolio can greatly influence the young person’s future assistance eligibility for college.
At Bright Advisers, we recognize the significance of tailored monetary planning for families with young kids. Our group of consultants can assist you in creating a lasting financial strategy that reflects your principles and aspirations, ensuring that your custodial fund supports your offspring’s financial future efficiently. In California, the number of custodial savings opened has been steadily rising, reflecting a growing awareness among families about the advantages of such accounts. These funds not only offer a way to save for a young person’s future but also enable a variety of investment options, including real estate and collectibles, which are distinctive to these types of arrangements compared to UGMA funds. By taking these steps, you’re not just saving; you’re investing in your child’s dreams and future possibilities.
Disclaimer: All advisory services are provided through Lifeworks Advisors, a registered investment adviser. Registration of an investment adviser does not imply any level of skill or training. Past performance is not an indication of and does not guarantee future results. Securities investments are subject to risk and may lose value.
Explore Tax Implications and Financial Aid Impact
Navigating the world of UTMA IRA accounts can feel overwhelming, especially when it comes to your child’s future. Here are some important tax implications to keep in mind:
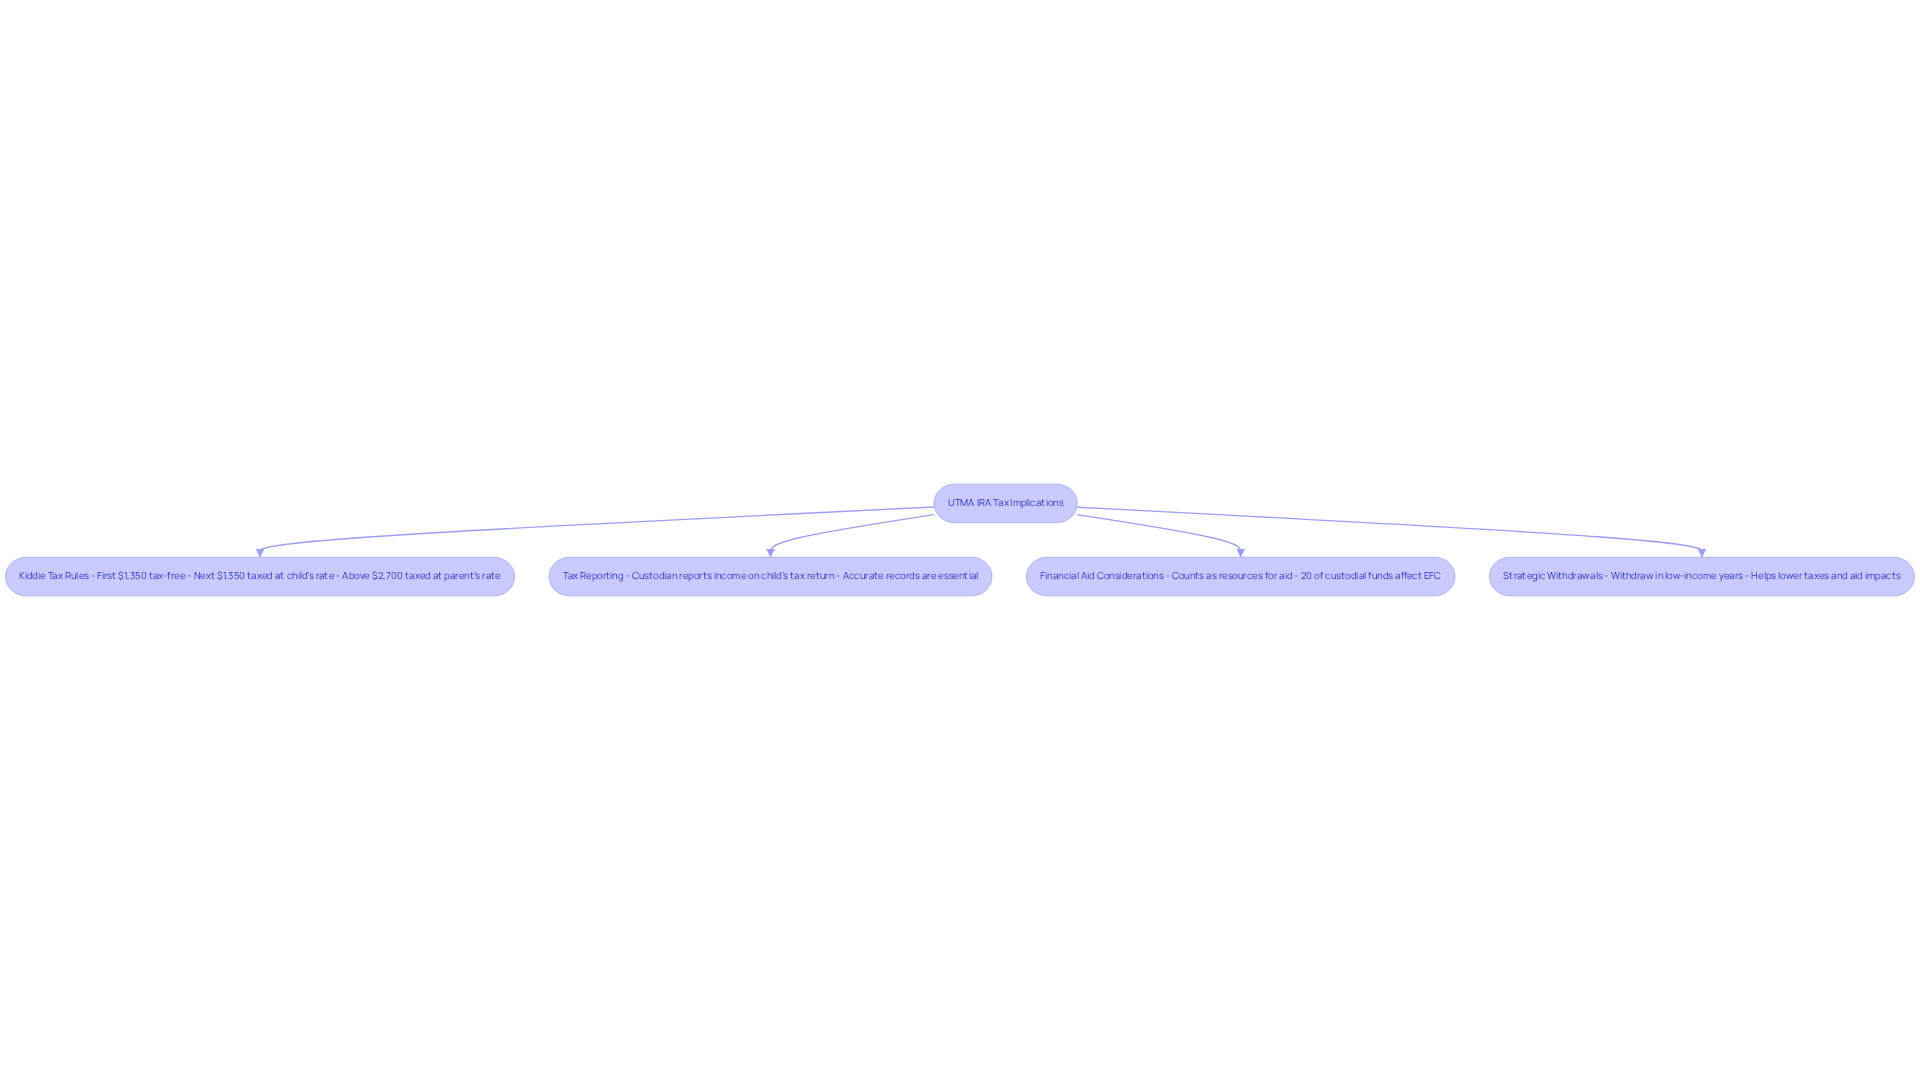
- Earnings in a UTMA IRA fund are subject to kiddie tax rules. For 2026, the first $1,350 of unearned income is tax-free, the next $1,350 is taxed at your child’s rate, and any income above $2,700 is taxed at your rate. This setup can really affect how much tax you might owe on your child’s earnings.
- Tax Reporting: It’s important to know that the custodian needs to report any income from the custodial fund on your child’s tax return. Keeping accurate records of all transactions and earnings is essential to ensure compliance and avoid surprises during tax season.
- Assistance Considerations: If you’re looking for financial aid, keep in mind that these accounts count as resources for your child. This can significantly affect the Expected Family Contribution (EFC), as typically, 20% of the worth of the custodial funds will be considered against your family when assessing aid eligibility. It’s crucial to factor UTMA IRA into your long-term strategies for education funding.
- Strategic Withdrawals: Think about making smart withdrawals from the custodial fund to help lower taxes and aid impacts. For instance, withdrawing funds in years when your dependent has lower income can help decrease overall tax obligations, enabling more efficient planning.
Understanding these tax implications can empower you to make informed decisions that support your family’s dreams.
Select Investment Strategies for Long-Term Growth
Navigating the world of investments can feel daunting, especially when you’re focused on your family’s future. Let’s explore some strategies that can help ease your financial worries and secure a brighter future for your family.
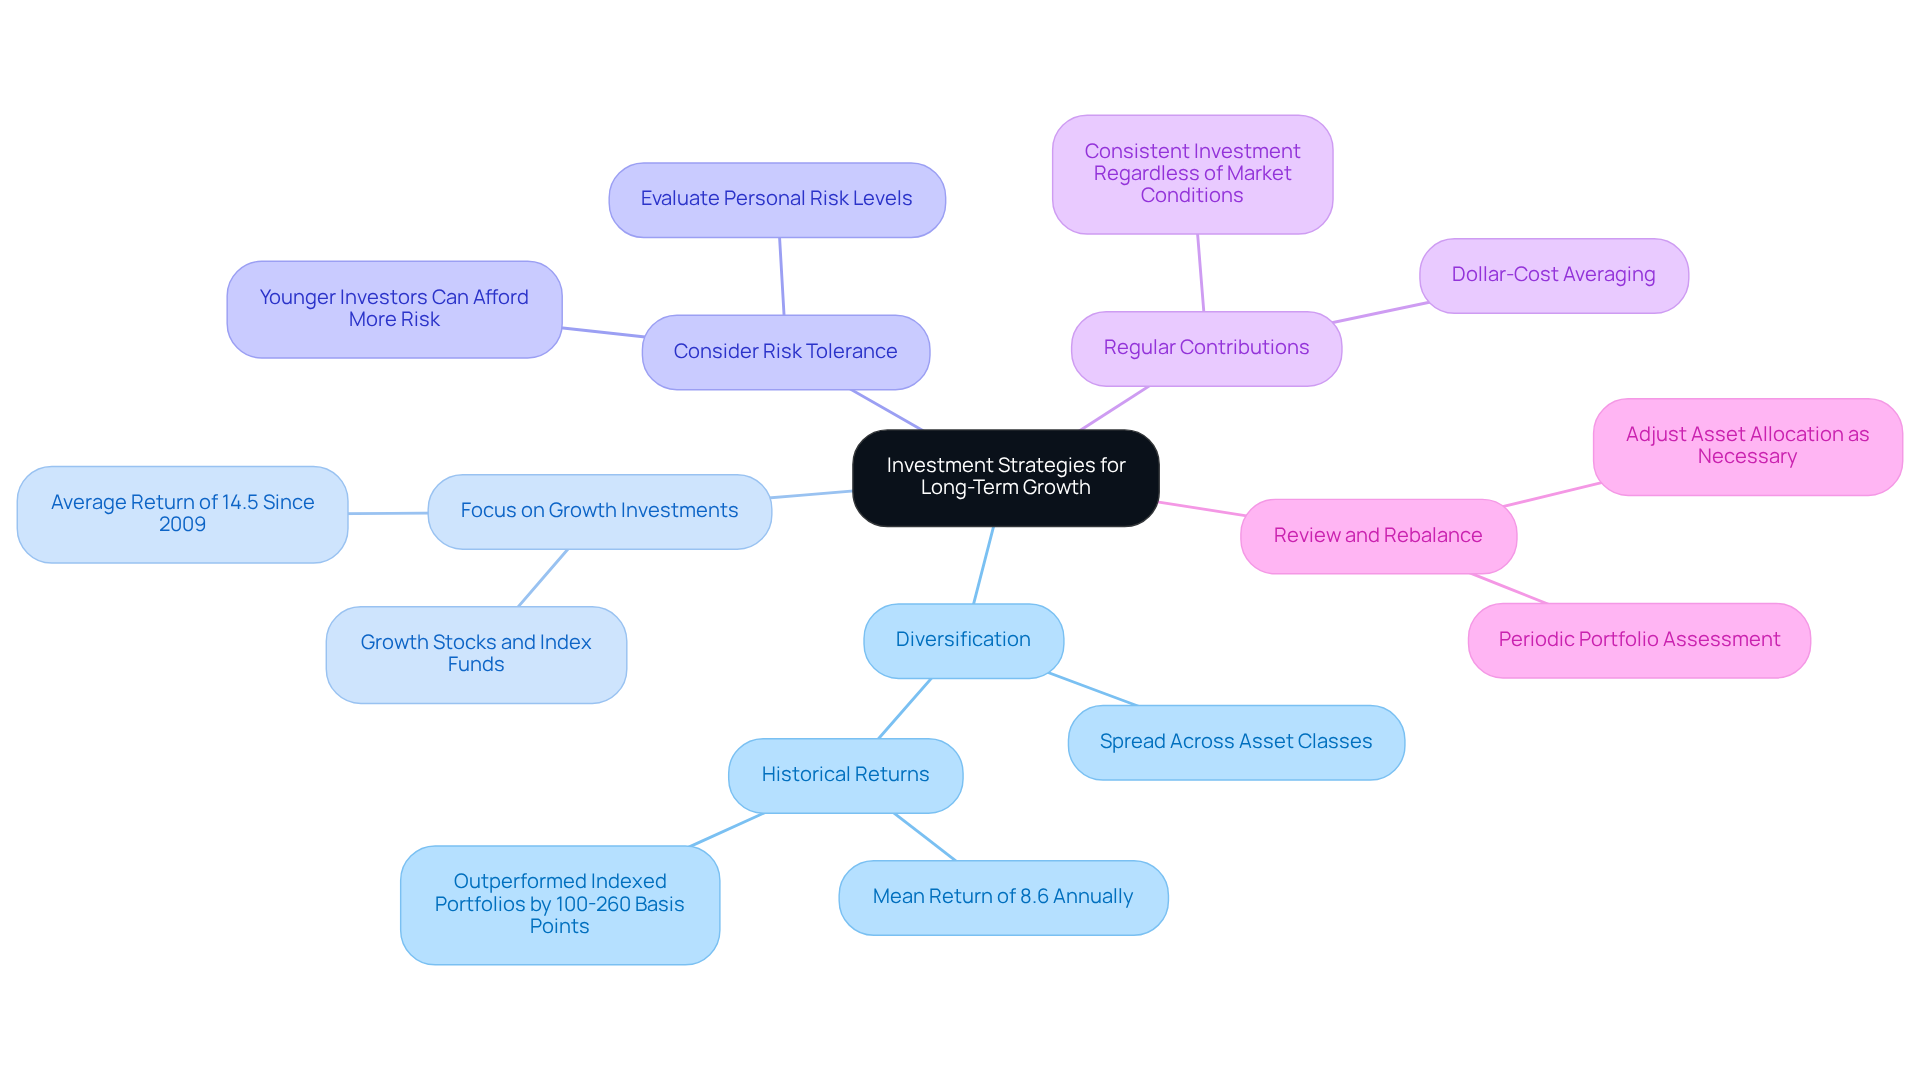
- Diversification: Spread investments across various asset classes, such as stocks, bonds, and mutual funds, to reduce risk. A diversified portfolio can help mitigate losses during market downturns. Historical data shows that investors with highly diversified portfolios achieved a mean return of 8.6% annually, outperforming indexed portfolios by significant margins.
- Focus on Growth Investments: Consider investing in growth stocks or index funds that have the potential for higher returns over the long term. For instance, since 2009, US equities have yielded an average of 14.5% each year, suggesting robust growth potential that can greatly enhance the account’s value by the time your child reaches adulthood.
- Consider Risk Tolerance: Evaluate your risk tolerance and that of your child. Younger children can typically afford to take on more risk since they have a longer time horizon for investments to recover from market fluctuations. This approach aligns with the understanding that the extent of diversification varies according to individual risk tolerance.
- Regular Contributions: Make regular contributions to the UTMA account to take advantage of dollar-cost averaging. This strategy can help smooth out the effects of market volatility over time, ensuring that investments are made consistently regardless of market conditions.
- Review and Rebalance: Periodically assess the investment portfolio and adjust as necessary to ensure it aligns with your monetary objectives and risk tolerance. Adjusting the asset allocation can help maintain the desired level of risk and return, which is crucial for long-term success in wealth management.
We’re here to support families like yours in building a strong financial foundation for the future. We utilize in-house technology to create hyper-personalized portfolios tailored to your needs. Join our waitlist today to learn more about how we can assist you in navigating your financial planning challenges and achieving your long-term goals. Please note that all advisory services are provided through Lifeworks Advisors, a registered investment adviser. Investing involves risks, including the potential loss of principal. Past performance does not guarantee future results.
Conclusion
Many parents feel overwhelmed when it comes to securing their children’s financial futures. Mastering UTMA IRA accounts can be a crucial step in this journey. These custodial accounts not only offer a flexible way to save and invest for your child’s needs but also serve as a valuable educational tool, teaching them about money management and responsibility.
Throughout this guide, we’ve explored key aspects of UTMA IRA accounts, including:
- Their purpose
- Eligibility requirements
- Setup process
- Tax implications
- Investment strategies
Each section highlights the importance of careful planning and ongoing management to ensure that these accounts effectively support your child’s future aspirations. It’s essential for families to consider both the immediate and long-term impacts of their financial choices.
Ultimately, taking these steps today can open doors for your children, allowing them to flourish in a world full of possibilities. Engaging with a fiduciary advisor like Bright Advisers can help families navigate these complexities with confidence, ensuring that every decision aligns with their unique goals and values. By seeking guidance, parents can transform uncertainty into clarity, empowering their children to thrive in an ever-changing world.
Frequently Asked Questions
What is a UTMA account?
A UTMA (Uniform Transfers to Minors Act) account is a custodial arrangement that allows you to transfer assets to your child without the need for a formal trust. It can hold various assets, including cash, stocks, bonds, and real estate.
What is the purpose of a UTMA account?
The purpose of a UTMA account is to help save and invest for your child’s future until they reach adulthood, typically between the ages of 18 and 21, depending on the state.
What can the funds in a UTMA account be used for?
Funds in a UTMA account can be used for various needs, such as education, purchasing a first car, or starting a small business, providing financial flexibility for your child.
How do UTMA accounts help teach children about money management?
UTMA accounts instill a sense of responsibility in children as they learn to manage money and understand the importance of saving and investing for their future.
What should be considered regarding the tax implications of UTMA accounts?
Contributions to UTMA accounts are considered irrevocable gifts, which can affect financial aid eligibility when your child applies for college. It’s important to understand these implications for effective financial planning.
What is the yearly gift tax exclusion limit for 2025?
For 2025, the yearly gift tax exclusion limit is $19,000 for individuals, which is important to consider when making contributions to custodial funds.
How can Bright Advisers assist with UTMA accounts?
Bright Advisers can provide guidance in navigating the complexities of UTMA accounts, ensuring a balanced approach to financial security and educational readiness for your child.
List of Sources
- Define UTMA Accounts and Their Purpose
- What Are UTMA Accounts? | City National Bank (https://cnb.com/personal-banking/insights/utma-ugma-accounts.html)
- Financial Advisors Guide: UTMA and UGMA Accounts for Kids (https://wealthtender.com/insights/utma-and-ugma-accounts-for-kids)
- UTMA Accounts Explained: Rules, Custodial Brokerages and More (https://kiplinger.com/personal-finance/603545/hey-parents-caution-is-critical-with-utma-custodial-accounts)
- Establish Eligibility and Set Up Your UTMA Account
- UGMA-UTMA Account: The Benefits of One | Vanguard (https://investor.vanguard.com/accounts-plans/ugma-utma)
- What Are UTMA Accounts? | City National Bank (https://cnb.com/personal-banking/insights/utma-ugma-accounts.html)
- UGMA & UTMA accounts | Tips for custodial accounts | Fidelity (https://fidelity.com/learning-center/personal-finance/custodial-account-for-kids)
- Explore Tax Implications and Financial Aid Impact
- What Are the Potential Tax Implications of a Custodial Account? | Chase (https://chase.com/personal/investments/learning-and-insights/article/tax-implications-custodial-accounts)
- UGMA & UTMA accounts | Tips for custodial accounts | Fidelity (https://fidelity.com/learning-center/personal-finance/custodial-account-for-kids)
- 5 UTMA Facts Every Parent Needs to Know in 2026 (https://unest.co/insights/5-utma-facts-every-parent-needs-to-know)
- Custodial Account Rules: Taxes & Withdrawals (https://acorns.com/learn/investing/custodial-account-rules)
- UTMAs and the FAFSA — How to Pay for College (https://howtopayforcollege.com/blog/utmas-and-the-fafsa)
- Select Investment Strategies for Long-Term Growth
- Diversification Quotes (20 quotes) (https://goodreads.com/quotes/tag/diversification)
- Quotes on Diversification • Novel Investor (https://novelinvestor.com/quote-category/diversification)
- A Diversified Portfolio Offers a Smoother Ride – AMG Wealth (https://wealth.amg.com/insights/keep-calm-and-remain-diversified/diversified-portfolio-offers-smoother-ride)
- Over the Long Term, Diversification Still Wins – Cambridge Associates (https://cambridgeassociates.com/insight/long-term-diversification-still-wins)
- What Is the Average Stock Market Return? | Chase (https://chase.com/personal/investments/learning-and-insights/article/what-is-the-average-stock-market-return)

Kevin has advised high-income W-2 tech and biotech families since 2015, and leads the education-first Age Five Family Office from Brea, California.
Connect on LinkedIn → · About KevinThis is part of how we approach Age Five Wealth Education for high-income W-2 families at Bright Advisers.
Keep reading