

Key Highlights
- For 2026, the annual wedding gift tax exclusion is $19,000 per individual, allowing married couples to give up to $38,000 tax-free to a single recipient.
- The wedding gift tax exemption enables parents to support their children’s wedding expenses without tax implications, provided they stay within the limits.
- Gifts must be usable by the recipient immediately, such as cash or contributions to a wedding fund, to qualify for the exemption.
- If a gift exceeds the annual exclusion limit, it must be reported using IRS Form 709, which details contributions made during the tax year.
- Common misconceptions include the belief that all gifts are taxable, only cash gifts are taxable, and that the recipient pays the tax; in reality, the giver is responsible for reporting any taxable gifts.
- Failing to document contributions can lead to complications with the IRS, making it essential to keep accurate records of all gifts given.
Introduction
Imagine wanting to support your child on their wedding day, but feeling lost in the maze of tax regulations that could affect your generosity. Navigating the intricacies of wedding gift tax exemptions can be overwhelming for young parents eager to help during one of life’s most joyous occasions. This exemption lets you help your child without worrying about surprise tax bills, making it easier to celebrate their love. Yet, many parents feel overwhelmed by the specifics of limits and reporting requirements, unsure of how to give the best support. By understanding these steps, you can give generously and keep your family’s financial peace of mind intact.
Clarify Wedding Gift Tax Exemption Basics
Imagine being able to support your child’s wedding without the stress of tax surprises looming over you. The wedding gift tax exemption enables you to assist your child with their wedding expenses without the concern of taxes, provided you remain within specified limits. For 2026, the yearly tax exclusion for presents is set at $19,000 for each individual. This means a married couple can provide up to $38,000 to a single recipient without activating any tax on transfers. It’s a wonderful way for parents to assist their children during important life events like weddings, ensuring that love and support shine through while taking advantage of the wedding gift tax exemption.
This wedding gift tax exemption provides a fantastic opportunity for families to lend a helping hand during these joyful times, making the journey into married life a little easier for your child. Plus, there’s a lifetime exemption that allows you to give even more without tax worries, making it easier to support your family’s future. As Kyle Svetlik, a CFP® Partner, shares, “Most individuals never pay transfer tax because they utilize the annual exclusion and the lifetime estate and transfer tax exemption.”
Understanding these tax benefits can empower you to give your family the support they deserve during life’s most cherished moments. At Bright Advisers, we’re here for families like Jay & Emma, Emily & Mark, and Allison & Brian. We provide tailored wealth management solutions that include integrated tax planning and personalized strategies. Our goal is to help families achieve financial security and educational readiness, ensuring they can support their loved ones while optimizing their financial resources. Together, we can navigate the complexities of financial planning with confidence, knowing you have a dedicated team focused on your unique needs.
Identify Criteria for Tax Exemption on Wedding Gifts
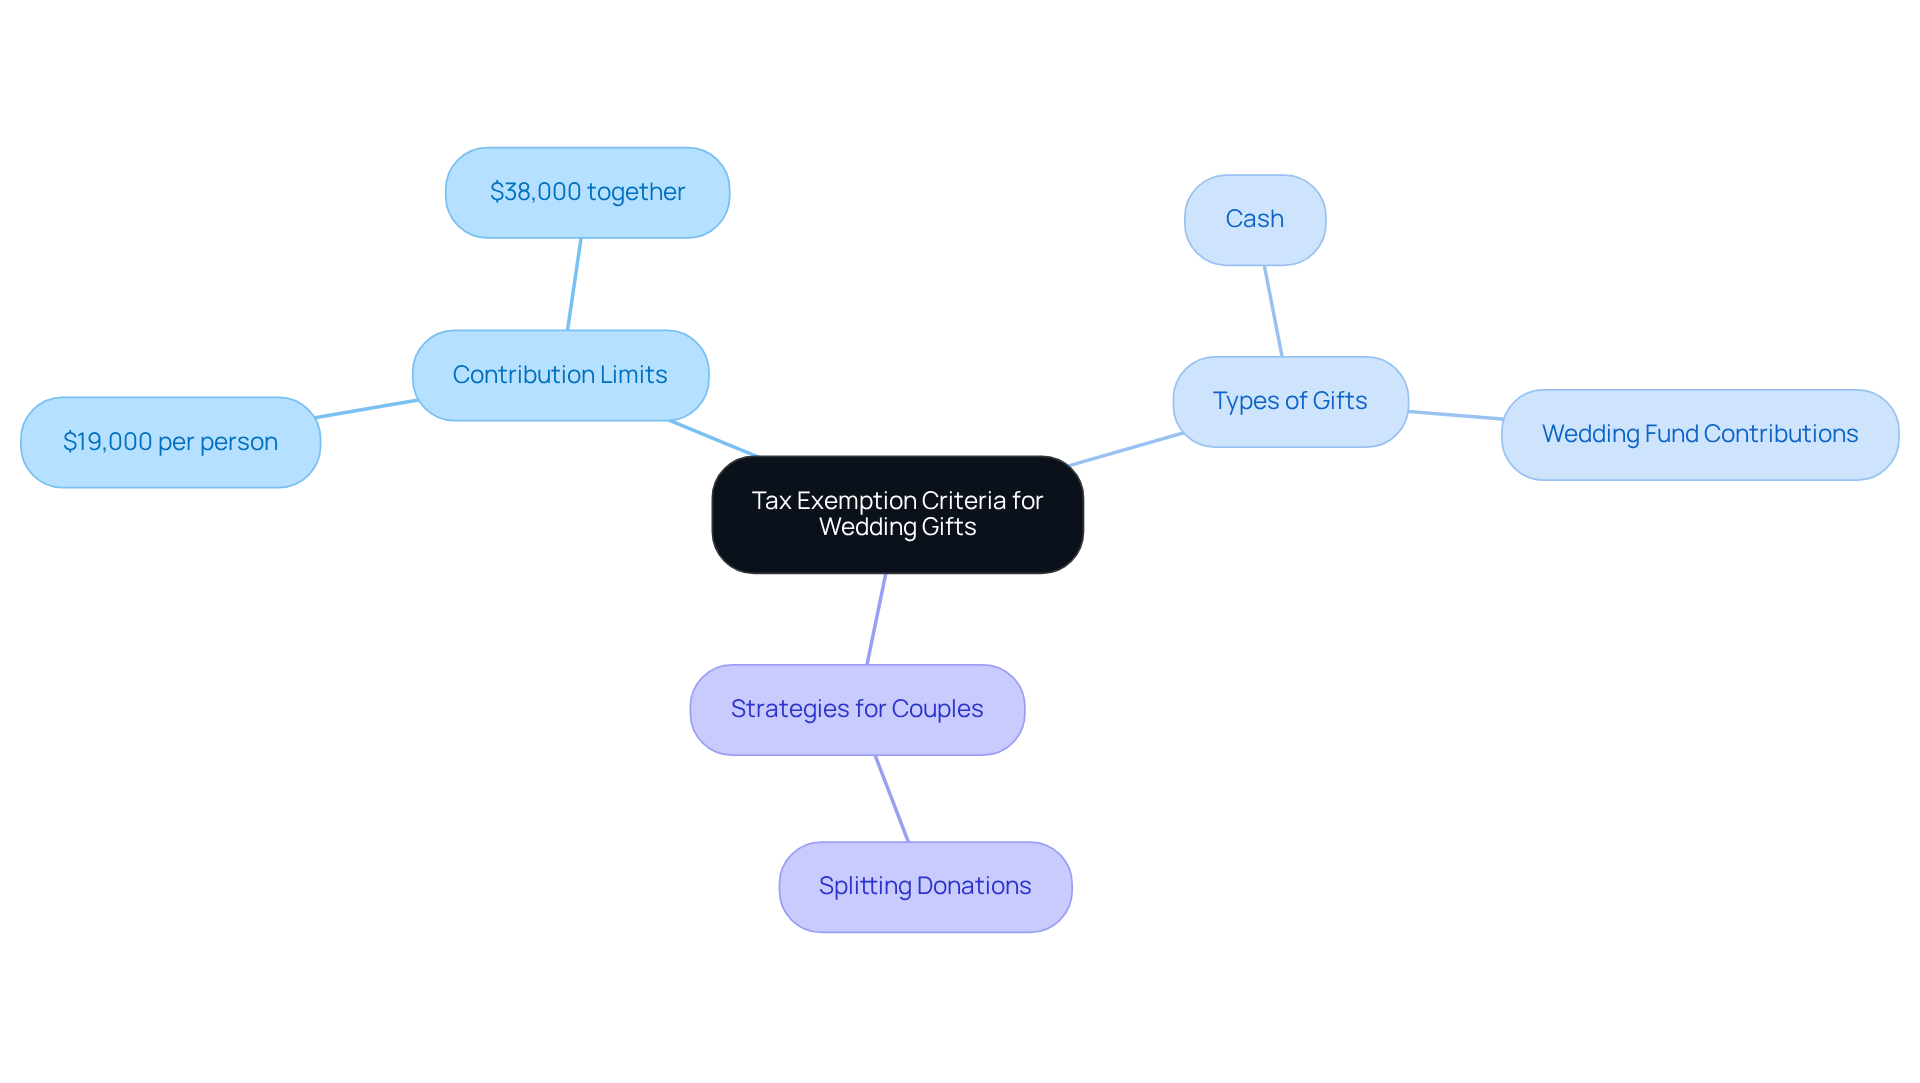
Navigating the world of wedding gifts can feel overwhelming, especially when tax regulations come into play. Imagine being able to give your child a generous wedding gift while benefiting from the wedding gift tax exemption without worrying about taxes. For 2026, you can contribute up to $19,000 each, or $38,000 together, under the wedding gift tax exemption without any tax implications.
It’s important to remember that the gift needs to be something your child can use right away, like cash or contributions to their wedding fund. Keeping track of your contributions is a smart move, even if you don’t have to report them. It helps ensure everything is clear and compliant with IRS regulations.
If you’re married, consider splitting your donations. This way, you can double the amount you give tax-free thanks to the wedding gift tax exemption, making those wedding gifts even more special! By understanding these criteria, you can confidently support your loved ones while ensuring compliance with tax regulations, making those special moments even more memorable.
Outline Steps for Reporting Wedding Gifts
Navigating the complexities of wedding gifts can be daunting, particularly regarding the wedding gift tax exemption and its implications. When a wedding gift exceeds the annual exclusion limit, follow these essential steps to ensure proper reporting:
-
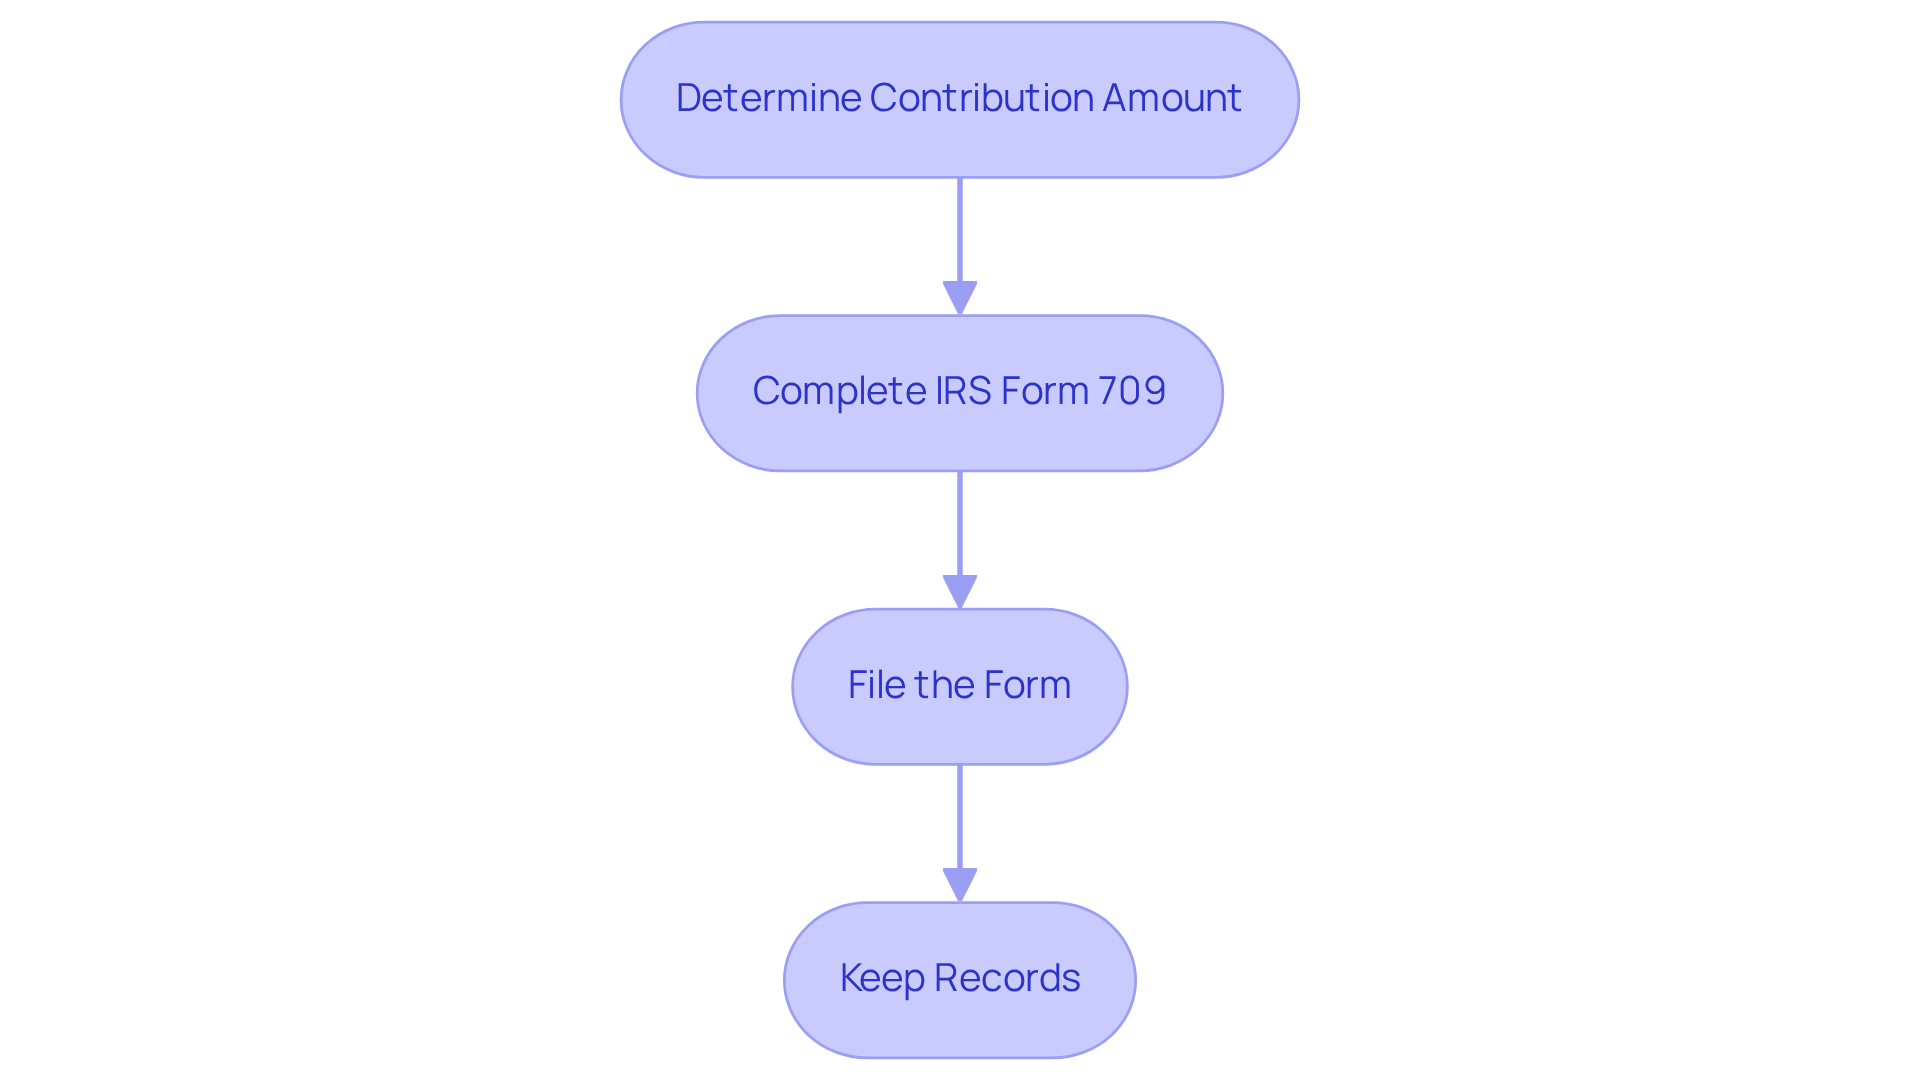
Determine the Contribution Amount: Evaluate the overall worth of the present provided to each individual. If it surpasses $19,000 for the year 2026, it must be reported to the IRS under the wedding gift tax exemption.
-
Complete IRS Form 709: You’ll need to fill out IRS Form 709, which is the U.S. Gift Tax Return, carefully. This form requires detailed information about the contributions made during the tax year, including the recipient’s name and the value of each contribution, to qualify for the wedding gift tax exemption.
-
File the Form: Submit Form 709 to the IRS by the tax filing deadline, which is typically April 15 of the following year. If you can’t meet this deadline, you may request an extension using Form 4868, which provides an automatic six-month extension for filing your federal income tax return.
-
Keep Records: It’s important to maintain copies of Form 709 and any supporting documentation, such as bank statements or donation letters. This documentation is essential for future reference, particularly in the case of an audit or if you need to clarify the nature of the contributions later.
Imagine having a trusted guide by your side, helping you navigate these requirements and ensuring you’re on the right track. Engaging a financial advisor can be beneficial in this journey. At Bright Advisers, we’re here to help you with personalized tax planning and portfolio strategies that fit your family’s needs. For example, strategies such as dividing presents with a spouse can assist in lowering tax obligations, as highlighted in the experiences of families like Jay & Emma and Emily & Mark, who effectively managed their financial planning with our assistance. Additionally, insights from tax professionals emphasize the importance of accurate reporting to protect taxpayers and their heirs, particularly in relation to the wedding gift tax exemption in future estate planning. By understanding these steps and seeking professional guidance, young parents can effectively manage their financial responsibilities while focusing on their families. By taking these steps, you can ensure peace of mind while focusing on what truly matters-your family.
Highlight Common Misconceptions and Pitfalls
Imagine the confusion that can arise regarding the wedding gift tax exemption.
Several misconceptions can lead to misunderstandings:
-
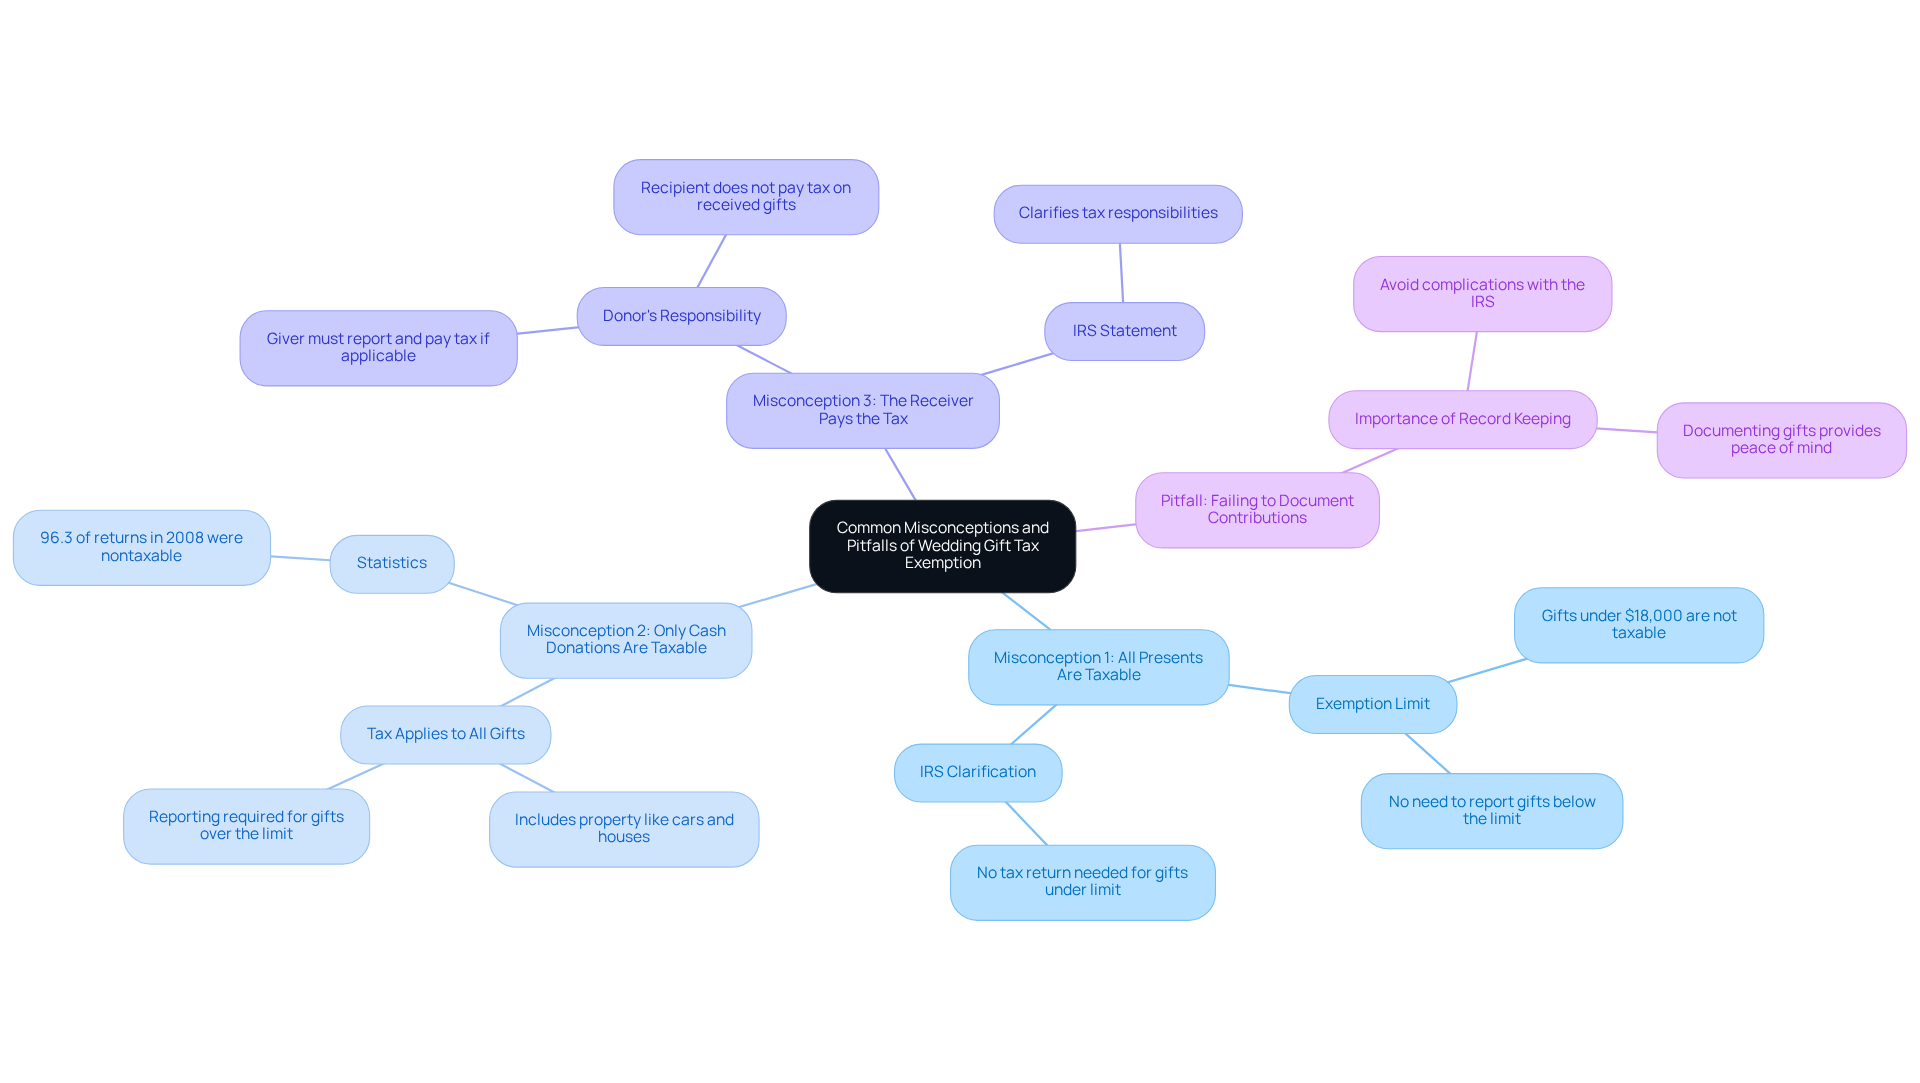
Misconception: All Presents Are Taxable: Many believe that any offering given is automatically taxable. But here’s the good news: presents that fall under the wedding gift tax exemption limit of $18,000 per recipient for 2024 are not taxable and don’t need to be reported. As the IRS states, ‘Provide no more than $18,000 per individual, per year and you won’t need to be concerned about submitting a tax return for donations or reducing your designated federal estate tax exemption amount.’ Imagine the stress of thinking every gift you receive could come with a tax bill.
-
Misconception: Only Cash Donations Are Taxable: Some think only cash donations are subject to tax. But remember, if you give more than the exclusion limit, whether it’s cash or something like a car or a house, you’ll need to report it. In fact, in 2008, 96.3% of tax returns submitted were nontaxable, showing that most contributions fall below the taxable threshold.
-
Misconception: The Receiver Pays the Tax: It’s easy to worry about this, especially when you’re just trying to enjoy the joy of receiving gifts. The giver is responsible for reporting and potentially paying any tax on the donation, not the receiver. The IRS clarifies that regardless of the amount, the recipient does not have to pay tax on the donation received because of the wedding gift tax exemption.
-
Pitfall: Failing to Document Contributions: If you don’t keep track of your gifts, it could lead to some headaches down the road if the IRS comes asking. Not maintaining records of contributions can lead to complications if the IRS questions the amounts provided. Always document gifts to ensure compliance and clarity, providing peace of mind. This oversight could not only complicate your tax reporting but also lead to unnecessary financial stress.
By understanding these misconceptions, you can navigate gift-giving with confidence and ease.
Conclusion
Imagine wanting to give your child the gift of a beautiful wedding without the worry of tax implications looming over you. Understanding the wedding gift tax exemption can feel daunting, but it’s essential for young parents who want to support their children during significant life events like weddings. This exemption helps parents give meaningful financial support without worrying about tax bills, as long as they follow the set limits.
By using the annual exclusion and lifetime exemption wisely, families can confidently support their loved ones, free from unexpected tax worries. Throughout this article, we’ve shared key insights about the criteria for tax exemption, the steps for reporting gifts, and common misconceptions that can lead to confusion. Remember, gifts under the annual exclusion limit don’t require reporting, and keeping proper documentation is vital for compliance.
With the right guidance, you can turn confusion into clarity, allowing you to focus on celebrating your child’s milestone. Engaging with a financial advisor can further enhance your understanding and management of these responsibilities, ensuring you can concentrate on what truly matters – celebrating your loved ones.
By taking these steps, you can create lasting memories for your family while ensuring your financial future remains secure. For personalized guidance tailored to your unique situation, consider reaching out to Bright Advisers at hello@brightadvisers.com or call (714) 987-2967. Embrace the joy of giving while safeguarding your financial future.
Frequently Asked Questions
What is the wedding gift tax exemption?
The wedding gift tax exemption allows individuals to support their child’s wedding expenses without incurring tax liabilities, as long as they stay within specified limits.
What are the limits for the wedding gift tax exemption in 2026?
In 2026, the yearly tax exclusion for gifts is set at $19,000 per individual, meaning a married couple can give up to $38,000 to a single recipient without triggering any tax on the transfer.
How can the wedding gift tax exemption benefit families?
This exemption provides families with a way to assist their children during significant life events, like weddings, without the stress of tax implications, making the transition into married life smoother.
Is there a lifetime exemption related to the wedding gift tax?
Yes, there is a lifetime exemption that allows individuals to give more without tax concerns, further supporting family financial needs.
Who can provide guidance on utilizing the wedding gift tax exemption?
Financial professionals, such as Certified Financial Planners (CFP®), can offer insights on how to effectively use the annual exclusion and lifetime exemptions to avoid transfer taxes.
What services does Bright Advisers offer related to financial planning?
Bright Advisers provides tailored wealth management solutions that include integrated tax planning and personalized strategies to help families achieve financial security and support their loved ones.
What is the mission of Bright Advisers?
Bright Advisers aims to help families make wise wealth decisions and preserve wealth across generations, ensuring they can support their loved ones while optimizing financial resources.
List of Sources
- Clarify Wedding Gift Tax Exemption Basics
- Nelson Mullins – 2026 Estate and Gift Tax Update (https://nelsonmullins.com/insights/blogs/tax-reports/all/2026-estate-and-gift-tax-update)
- Tax-Free Gifting in 2026: What Financial Givers Should Know (https://merceradvisors.com/family-finance/tax-free-gifting-in-2026-what-financial-givers-should-know)
- What is the Annual Gift Tax Exclusion Limit for 2026? (https://adamsbrowncpa.com/blog/what-is-the-annual-gift-tax-exclusion-limit-for-2026)
- Annual Gift Tax and Estate Tax Exemptions for 2026 (https://elderlawanswers.com/annual-gift-tax-and-estate-tax-exemptions-for-2026-21282)
- Identify Criteria for Tax Exemption on Wedding Gifts
- What is the Annual Gift Tax Exclusion Limit for 2026? (https://adamsbrowncpa.com/blog/what-is-the-annual-gift-tax-exclusion-limit-for-2026)
- Nelson Mullins – 2026 Estate and Gift Tax Update (https://nelsonmullins.com/insights/blogs/tax-reports/all/2026-estate-and-gift-tax-update)
- Your Guide to Tax-Free Family Gifting (https://bairdwealth.com/insights/wealth-management-perspectives/2022/06/everything-you-need-to-know-about-tax-free-gifting)
- Gift Tax: How It Works, 2025 and 2026 Exclusions and Limits – NerdWallet (https://nerdwallet.com/taxes/learn/gift-tax-rate)
- Are Wedding Gifts Taxable? (https://northwesternmutual.com/life-and-money/are-wedding-gifts-taxable)
- Outline Steps for Reporting Wedding Gifts
- Frequently asked questions on gift taxes | Internal Revenue Service (https://irs.gov/businesses/small-businesses-self-employed/frequently-asked-questions-on-gift-taxes)
- Are Wedding Gifts Taxable? (https://northwesternmutual.com/life-and-money/are-wedding-gifts-taxable)
- About Form 709, United States Gift (and Generation-Skipping Transfer) Tax Return | Internal Revenue Service (https://irs.gov/forms-pubs/about-form-709)
- End of Tax Season Messages, Inspirational & Funny Quotes for Accountants & CPAs (https://swagmagic.com/blog/end-of-tax-season-quotes)
- Form 709: How U.S. Taxpayers Report Gifts to the IRS (https://brighttax.com/blog/us-gift-tax-limits-form-709)
- Highlight Common Misconceptions and Pitfalls
- SOI tax stats – Gift tax statistics | Internal Revenue Service (https://irs.gov/statistics/soi-tax-stats-gift-tax-statistics)
- Let’s clarify some common misconceptions about the gift tax – Park National Bank (https://parknationalbank.com/lets-clarify-common-misconceptions-gift-tax)
- Debunking Gift-Tax Myths (https://hahnlaw.com/insights/debunking-six-gift-tax-myths)
- Clearing Up Common Misconceptions About Gift Tax – Tax Refund Man, LLC (https://taxrefundman.com/clearing-up-common-misconceptions-about-gift-tax)

Kevin has advised high-income W-2 tech and biotech families since 2015, and leads the education-first Age Five Family Office from Brea, California.
Connect on LinkedIn → · About KevinThis is part of how we approach Estate Planning for high-income W-2 families at Bright Advisers.
Keep reading