

Key Highlights
- Understanding IPOs is crucial for families as it significantly impacts their financial situation.
- Selling shares from an IPO triggers capital gains taxes, with rates varying based on the holding period.
- Long-term capital gains tax rates for 2026 are 0% for income up to $49,450, 15% for income from $49,451 to $545,500, and 20% for income over $545,501.
- RSUs and PSUs count as ordinary income, affecting overall tax liabilities.
- Transferring shares before an IPO can lower estate obligations and pass future growth to loved ones.
- Tax-loss harvesting can offset gains and reduce tax liabilities, providing financial flexibility.
- Charitable giving of appreciated shares can reduce capital gains liabilities and provide tax deductions.
- Consulting a tax advisor is essential for personalised guidance on IPO tax strategies.
- Families should regularly review and adjust their tax strategies to adapt to changing financial situations and regulations.
- Educational efforts involving family members about financial management can enhance future decision-making.
Introduction
Imagine feeling overwhelmed by the complexities of an Initial Public Offering (IPO) and the tax implications that come with it. Understanding how to navigate an IPO tax strategy can truly shape your family’s financial future and help you achieve your dreams. Many families feel overwhelmed by the intricacies of an IPO, especially when it comes to taxes. Without a solid strategy, families risk jeopardizing their financial stability and future goals.
Together, we’ll explore a step-by-step approach to:
- Assess your financial situation
- Explore strategic options
- Implement a robust tax plan that secures your financial future
Understand IPO Basics and Tax Implications
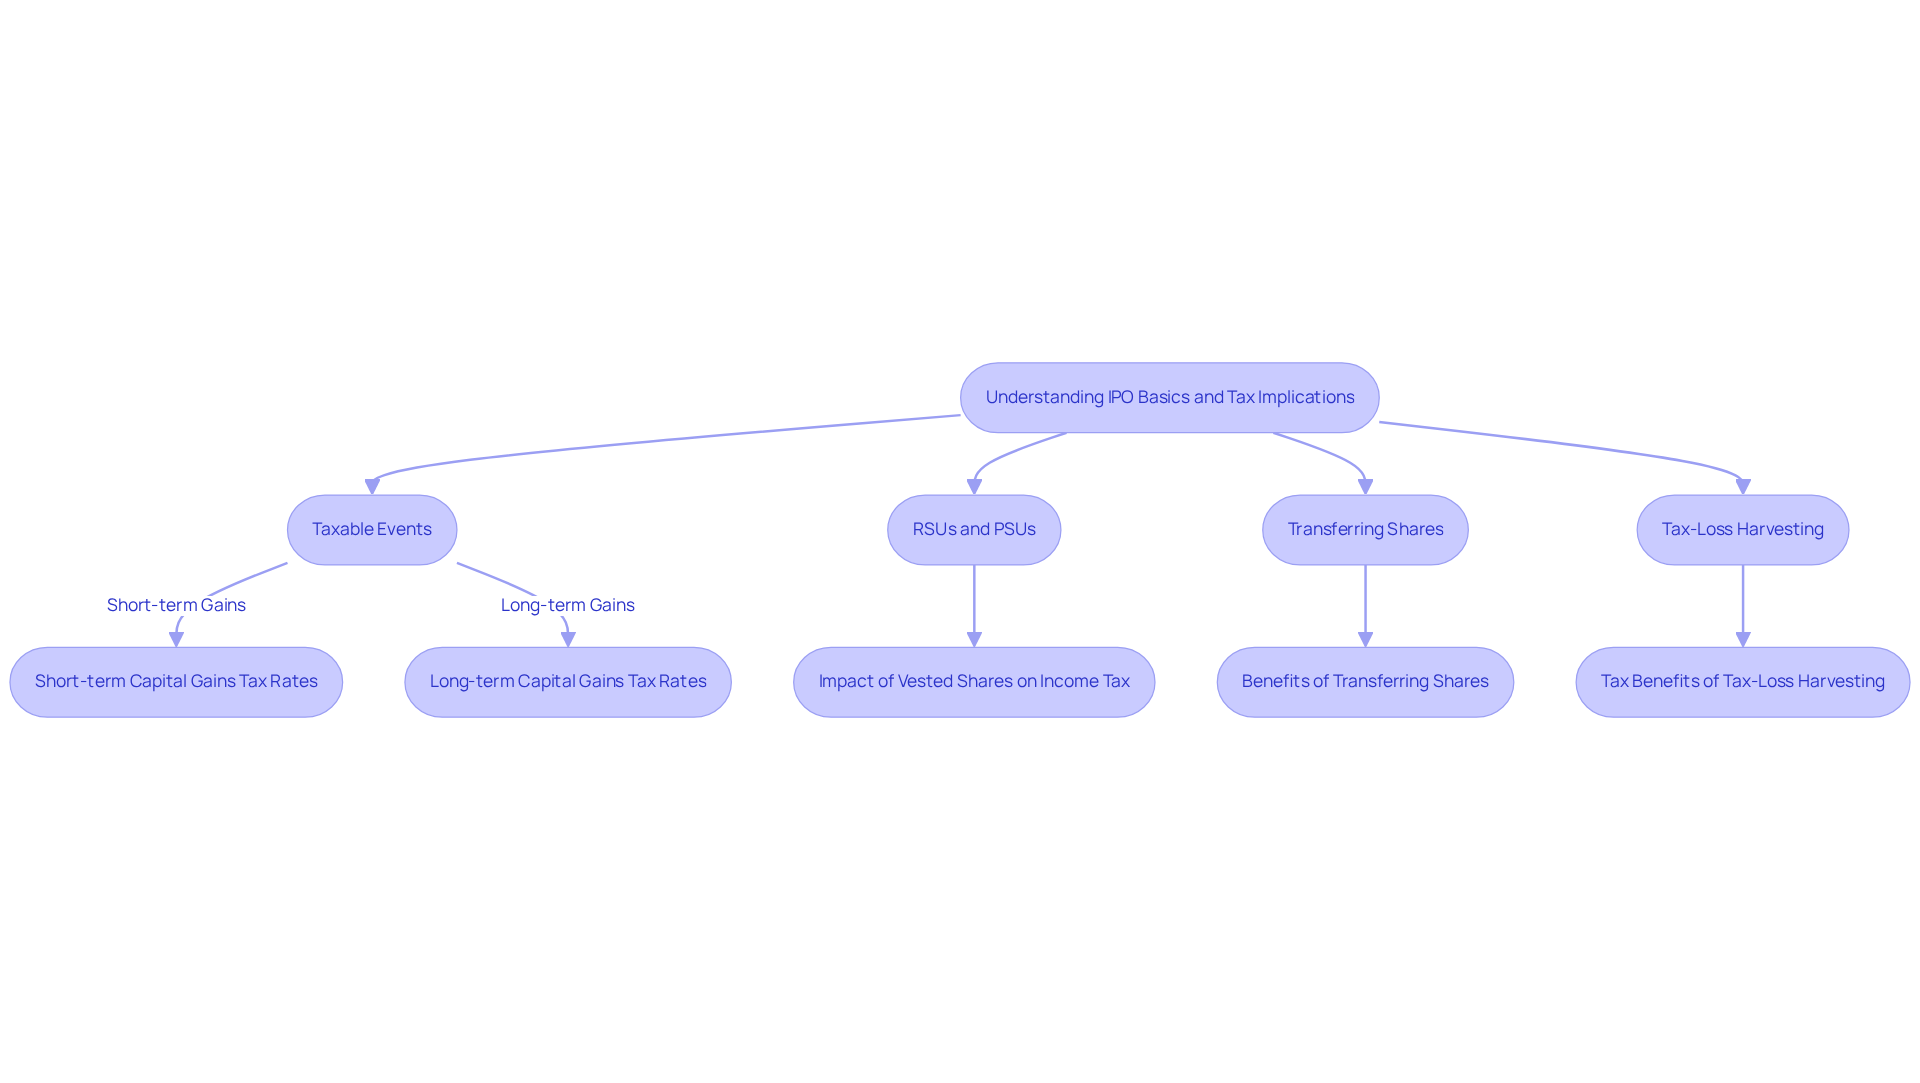
Navigating the world of finance can be daunting, especially when it comes to understanding the implications of an Initial Public Offering (IPO). For families, grasping the ipo tax strategy is crucial, as it can significantly impact their financial situation. Here are some essential points to consider:
- Taxable Events: Selling shares triggers capital gains taxes. If shares are held for less than a year, they are taxed at ordinary income rates; if held longer, they qualify for lower long-term capital gains rates. For 2026, long-term capital gains tax rates are structured at 0% for income up to $49,450, 15% for income from $49,451 to $545,500, and 20% for income over $545,501.
- RSUs and PSUs: It’s important for families to understand how these shares can impact their income tax, as the value of vested shares counts as ordinary income.
Transferring shares before an IPO can help lower estate obligations and pass on future growth to loved ones. This approach is especially beneficial for families looking to manage wealth across generations, offering potential tax advantages.
By understanding these fundamentals, families can better prepare for the financial implications of an IPO tax strategy, ensuring they effectively navigate the complexities of capital gains taxes. Case studies show that higher income levels lead to elevated tax rates on gains, underscoring the importance of income planning in investment strategies. For instance, Jay and Emma, a couple with two children, successfully navigated funding their children’s education while planning for retirement with the help of Bright Advisers. They created a detailed budget and chose investment approaches centered on diversification, balancing growth potential and risk management. Likewise, Allison and Brian, who are worried about their economic well-being, sought guidance to enhance their monetary potential through effective tax planning. By integrating tax efficiency into their financial plan, they found peace of mind and the opportunity to enjoy quality time with their loved ones.
Moreover, tax-loss harvesting can be a beneficial approach to counterbalance gains, enabling households to handle their tax obligations more effectively. Emily and Mark, both high-earning professionals, gained the flexibility to make career choices based on their desired work-life balance by adopting methods to reduce debt and manage cash flow. In summary, by taking the time to understand these financial aspects, families can pave the way for a more secure future together.
Assess Your Family’s Financial and Tax Situation
Imagine feeling confident about your family’s financial future, even as you navigate the complexities of an IPO tax strategy. Here’s how to approach it with care:
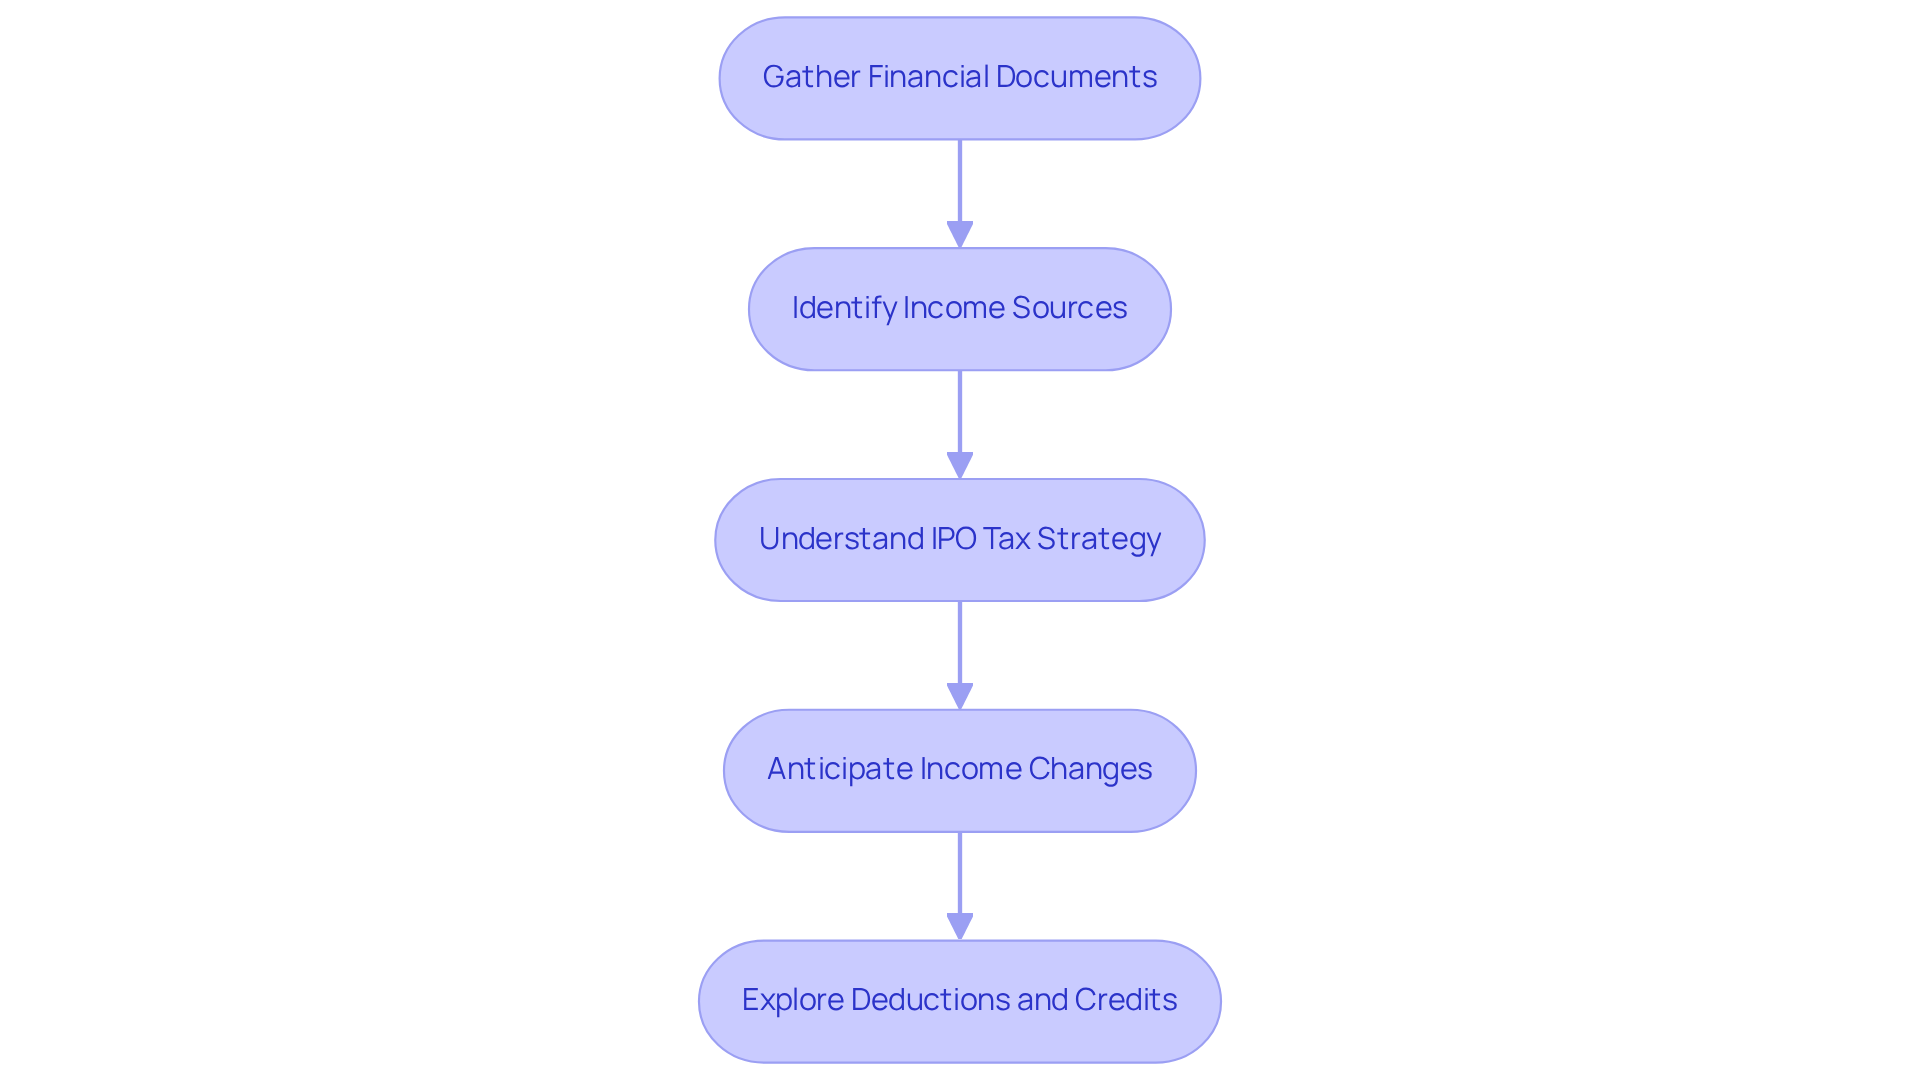
- Let’s start by gathering your financial documents together: Collect recent tax returns, income statements, and investment account statements. This will help us get a clear picture of your monetary health.
- Next, let’s take a moment to identify all your income sources: This includes salary, bonuses, and any investments. Understanding your total income will help in estimating tax liabilities and is crucial for implementing an effective IPO tax strategy, making the process feel less daunting.
- Understanding your IPO tax strategy is crucial, as it helps you see how much tax you might owe on any gains from the IPO, which can feel overwhelming but is manageable with the right approach. In 2026, the tax brackets for single filers range from 10% for incomes up to $12,400 to 37% for incomes exceeding $640,600.
- Think about any changes in your income that might come with the IPO: This could include bonuses or the vesting of restricted stock units (RSUs). Anticipating these changes can ease some worries about the IPO tax strategy and its implications.
- Let’s also look at any deductions or credits that could lighten your tax burden: For instance, the Child Tax Credit, which is $2,200 per qualifying child in 2026, can really make a difference for families.
By taking the time to understand your financial situation, you can feel more confident in creating an IPO tax strategy that works for your family. Understanding the impact of the One Big Beautiful Bill Act (OBBBA) on tax rates can empower households to plan more effectively, as it established numerous tax provisions as permanent, helping to avoid increases that could affect your budgeting. Moreover, examining case studies of how others have successfully managed their financial evaluations prior to IPOs can lead to more informed choices about their IPO tax strategy and potentially reduced tax obligations. With the right guidance, you can turn potential tax challenges into opportunities for your family’s growth and security.
Explore Tax Strategies and Tools for IPO Readiness
Imagine the relief of knowing you can navigate the tax implications of an IPO using an effective ipo tax strategy, ensuring your family’s financial future is secure.
To effectively prepare for the tax implications of an IPO, families should consider a few thoughtful strategies and tools:
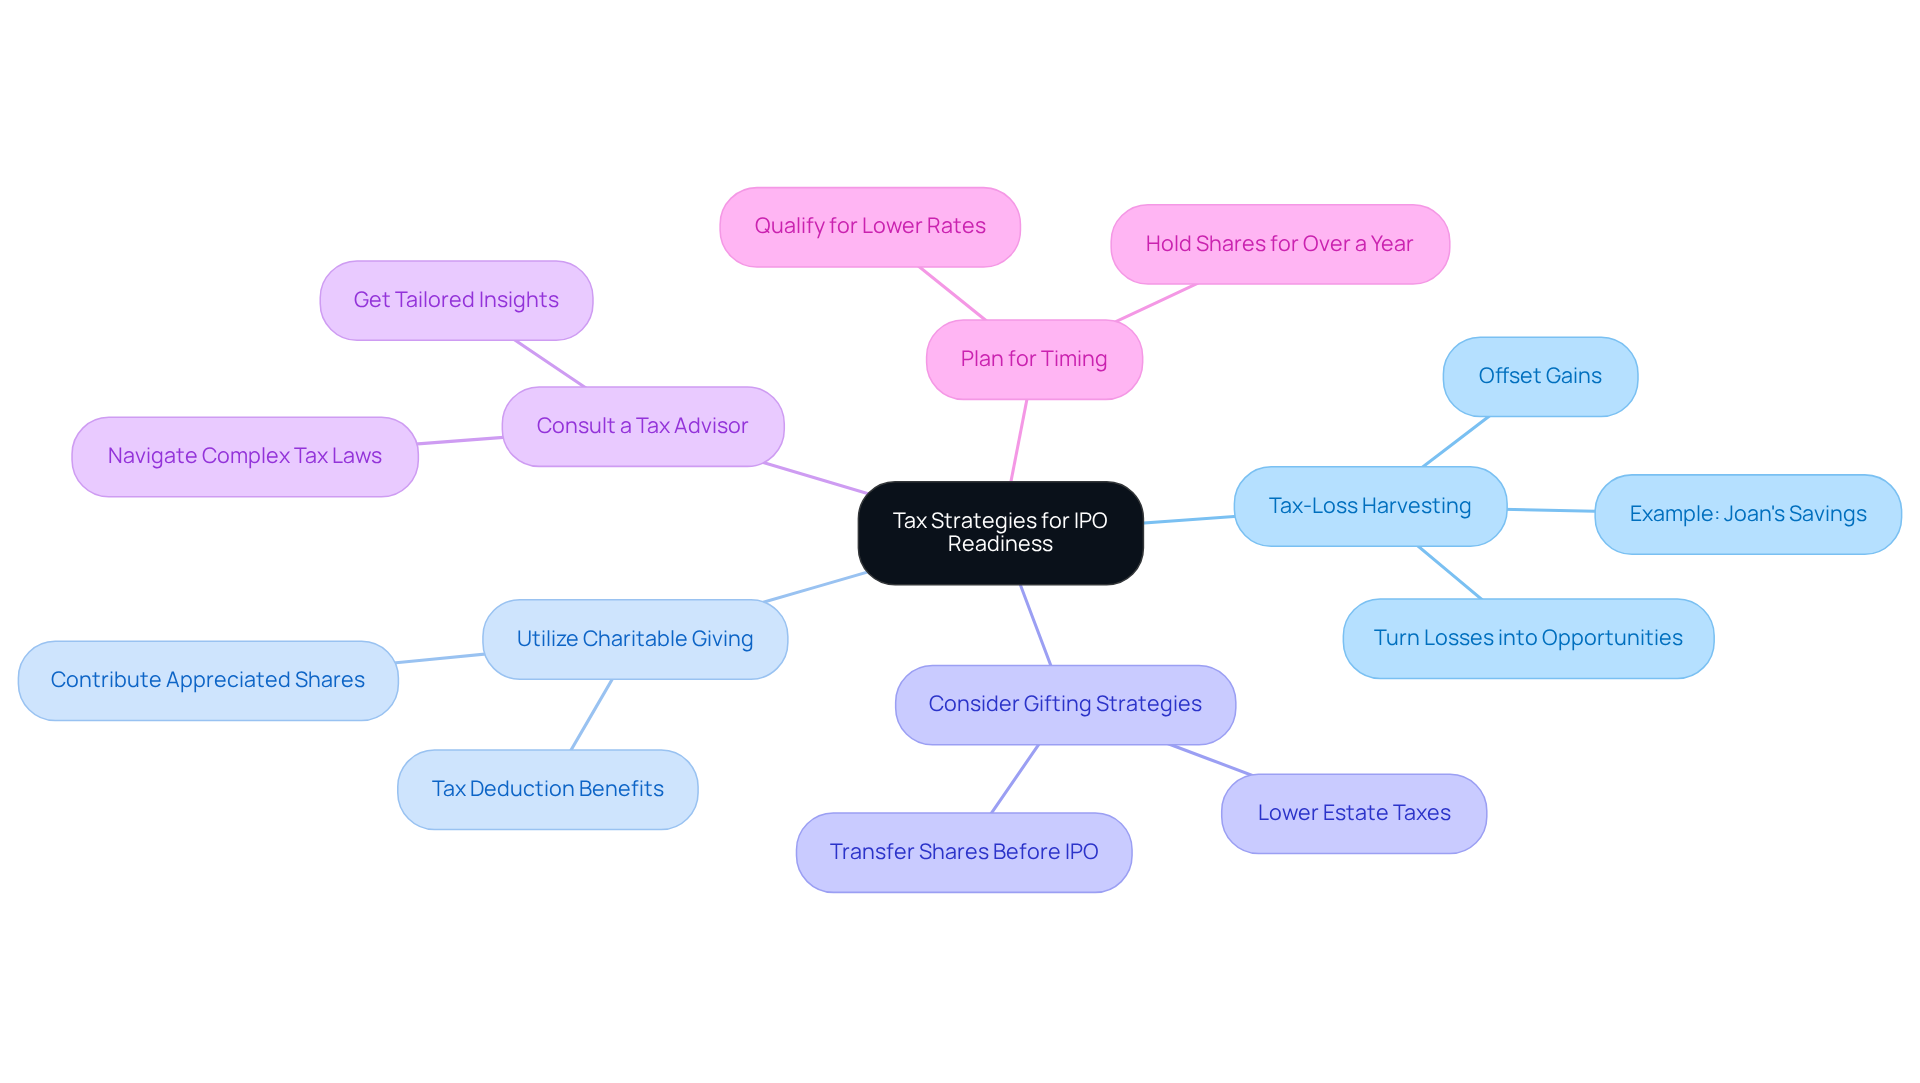
- Tax-Loss Harvesting: Think of tax-loss harvesting as a way to turn losses into opportunities, helping your family save on taxes when the IPO comes around. By recognizing losses, you can lower your taxable income, which is especially beneficial if you expect substantial gains from your ipo tax strategy. For instance, if your family realizes a $50,000 loss, you can use the IPO tax strategy to offset that against gains from the IPO, potentially lowering your tax liability significantly.
- Utilize Charitable Giving: Contributing appreciated shares to charity can help reduce capital gains liabilities. This strategy not only supports charitable causes but also provides a tax deduction based on the fair market value of the shares. For example, if you contribute shares valued at $100,000 that have increased from $60,000, you can remove capital gains obligations on the $40,000 increase while claiming a deduction for the entire $100,000.
- Consider Gifting Strategies: Transferring shares before the IPO can assist in passing future appreciation to relatives and lowering estate taxes. This proactive strategy enables your family to manage wealth efficiently while offering monetary advantages to your children or other loved ones.
- Consult a Tax Advisor: We’re here to help you find the right guidance for your family’s unique situation-don’t hesitate to reach out to a qualified tax advisor who understands your needs. Collaborating with a tax expert who emphasizes an ipo tax strategy can provide tailored insights and approaches that align with your household’s economic circumstances. They can help navigate complex tax laws and ensure compliance, which is crucial during the IPO process and the development of an IPO tax strategy.
- Plan for Timing: Timing the sale of shares can significantly impact tax liabilities. Families should consider holding shares for over a year to qualify for lower long-term capital gains rates, which can range from 0% to 20%, compared to ordinary income tax rates that can be as high as 37%.
By embracing these strategies, your family can feel more prepared for the IPO tax strategy, ensuring you are ready to tackle any tax challenges that come your way. This method reflects the effective techniques used by households like Allison and Brian, who found peace of mind through their partnership with Bright Advisers. They not only minimized their tax liabilities but also gained the freedom to focus on what truly matters-creating lasting memories with their loved ones.
Disclaimer: Past performance does not guarantee future results. Securities investments are subject to risk. For personalized advice, please consult with a qualified tax advisor. Interested families are invited to join our current client waitlist to explore how Bright Advisers can assist in achieving your financial goals.
Implement and Monitor Your IPO Tax Strategy
Imagine having a solid IPO tax strategy in place, but feeling unsure about how to implement it and keep it on track. Here’s how to proceed:
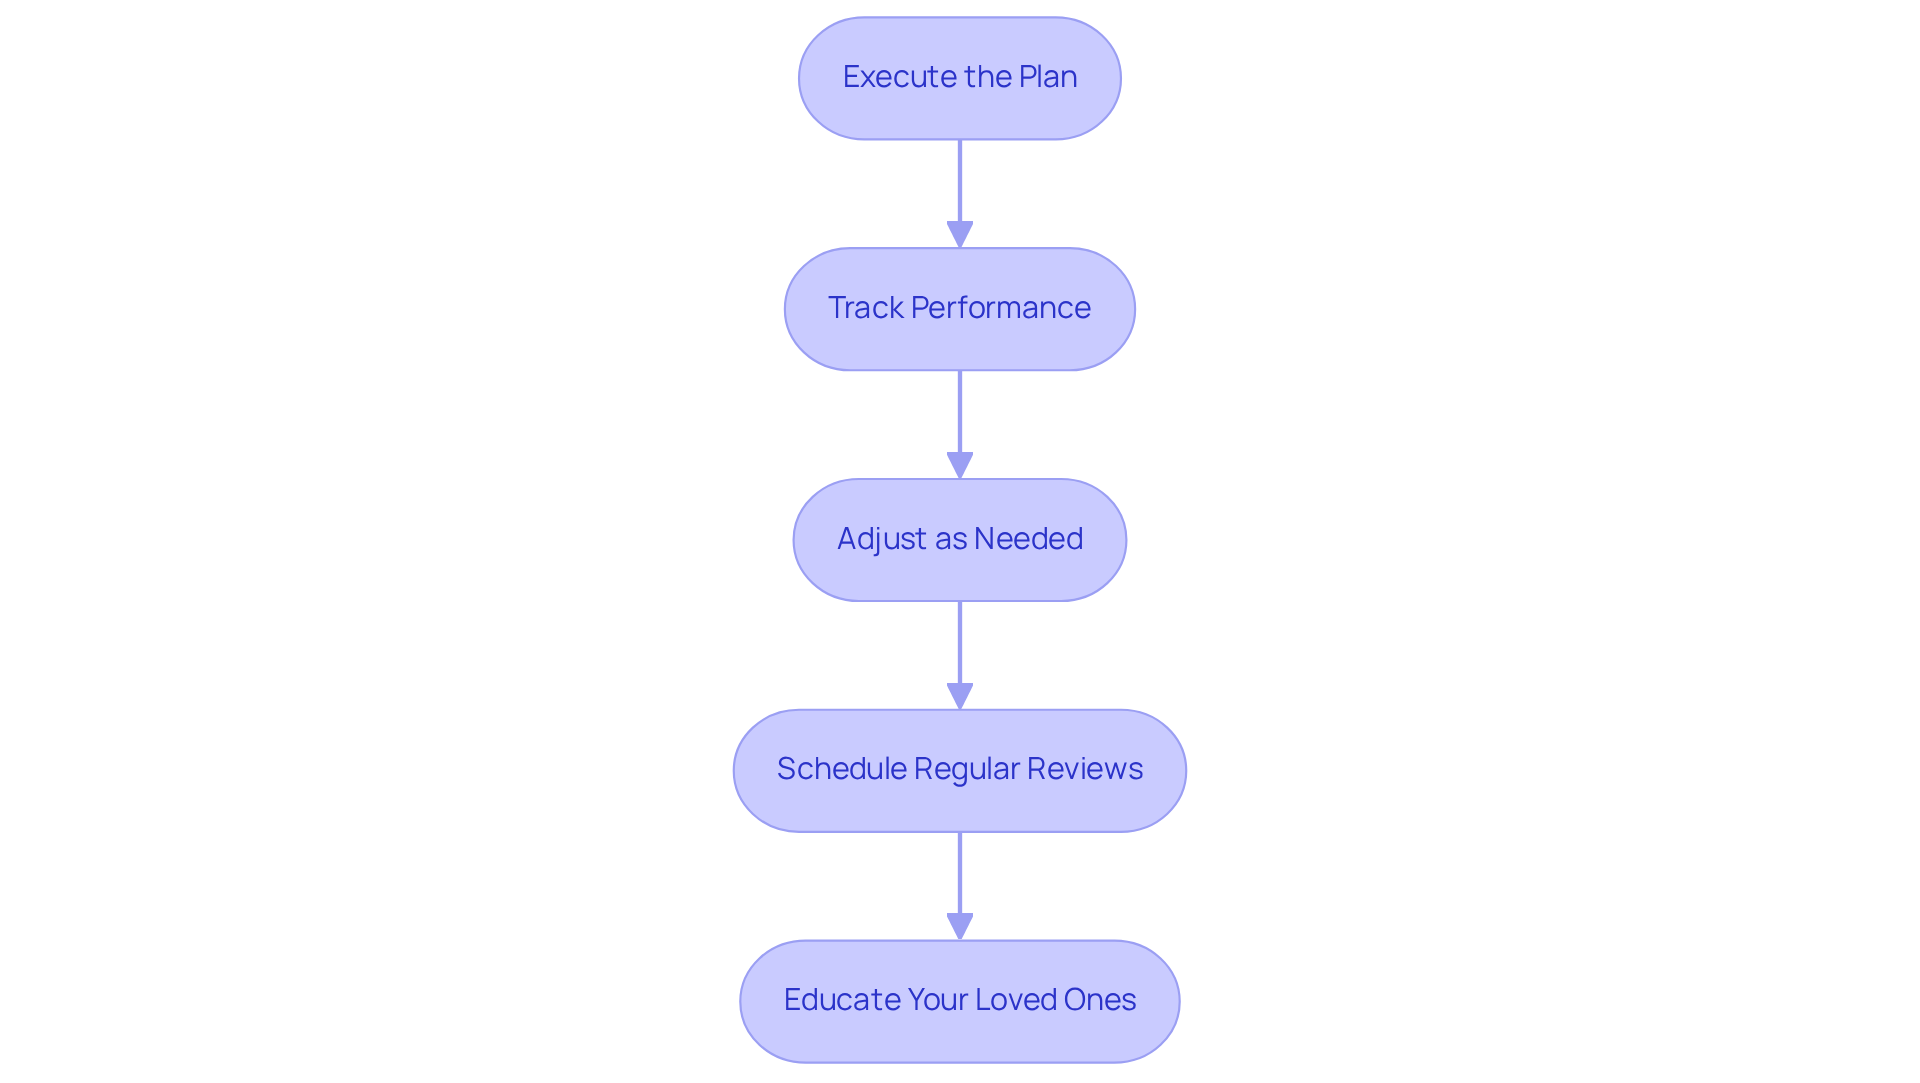
- Execute the Plan: Start by putting your plan into action. This might mean selling investments for tax-loss harvesting or making charitable donations to improve your tax position. For example, families using tax-loss harvesting can balance out gains, which might lower their tax bills and boost their investment returns. Jay and Emma successfully navigated funding their children’s education while planning for retirement with the help of Bright Advisers.
- Track Performance: It’s important to keep an eye on your investments and how they affect your taxes, so you can make the best choices for your family. Staying informed about your tax liabilities will help you make timely adjustments. Recent data shows that assets in tax-aware long/short approaches have surged from $35 billion to over $150 billion in the past year, highlighting the significance of tax-aware methods for families. Emily and Mark gained from a thorough evaluation of their monetary situation, which clarified their tax responsibilities.
- Adjust as Needed: Be ready to adapt your approach when changes arise in your economic situation, tax regulations, or market conditions. Imagine facing unexpected changes in your financial landscape and feeling uncertain about your next steps. By embracing flexibility, you can navigate these changes with confidence and ensure your family’s financial future remains secure. For instance, the standard deduction for married couples filing jointly has increased to $32,200 in 2026, which may impact your tax planning. Allison and Brian learned to optimize their tax situation, securing their children’s future through education funding and gaining the ability to retire sooner.
- Schedule Regular Reviews: Arrange periodic meetings with your tax advisor to assess your approach and make necessary adjustments. This ensures compliance and helps you capitalize on new tax-saving opportunities. Regular evaluations can reveal new approaches that align with changing tax regulations, just as Bright Advisers assisted households like Jay and Emma in developing a solid plan.
- Educate Your Loved Ones: Involve your relatives in discussions about the IPO and its implications. Teaching them about money management and tax strategies will equip them for future financial choices.
With ongoing support and guidance, you can confidently navigate your tax strategy, ensuring your family’s financial future is bright and secure. By implementing and continuously monitoring your IPO tax strategy, you can effectively manage your tax obligations and enhance your household’s economic well-being.
Conclusion
Imagine feeling overwhelmed by the complexities of an Initial Public Offering (IPO) and wondering how to secure your family’s financial future. It’s important to understand how an IPO can affect your family’s finances, especially when it comes to taxes. When you know the basics of capital gains taxes and how restricted stock units (RSUs) work, you can better prepare for what comes next after an IPO.
Consider strategies like:
- Assessing your family’s financial situation
- Exploring tax-loss harvesting
- Charitable giving to ease tax burdens
Families like Jay and Emma, as well as Allison and Brian, have successfully implemented these strategies with the guidance of Bright Advisers, allowing them to focus on what truly matters while managing their tax obligations effectively. Remember, consulting with a tax advisor and regularly reviewing your financial plan are crucial steps to ensure you stay compliant and adaptable in a changing economic environment.
This journey can lead to a sense of security and growth for your family, turning challenges into opportunities. By taking proactive steps and leveraging the right tools, you can transform potential tax challenges into pathways for wealth preservation and generational success. By partnering with Bright Advisers, you can turn the challenges of an IPO into a pathway for your family’s lasting success and peace of mind.
Frequently Asked Questions
What is an Initial Public Offering (IPO)?
An Initial Public Offering (IPO) is the process through which a private company offers its shares to the public for the first time, allowing it to raise capital from public investors.
How do IPOs affect taxes for families?
Selling shares from an IPO triggers capital gains taxes. If shares are held for less than a year, they are taxed at ordinary income rates. If held longer, they qualify for lower long-term capital gains rates, which for 2026 are 0% for income up to $49,450, 15% for income from $49,451 to $545,500, and 20% for income over $545,501.
What are RSUs and PSUs, and how do they impact taxes?
RSUs (Restricted Stock Units) and PSUs (Performance Stock Units) are types of shares that, when vested, count as ordinary income for tax purposes. Families need to understand how these shares can affect their overall income tax.
How can transferring shares before an IPO benefit families?
Transferring shares before an IPO can help lower estate obligations and allow families to pass on future growth to their loved ones, potentially offering tax advantages.
Why is income planning important in investment strategies related to IPOs?
Higher income levels lead to elevated tax rates on gains, making income planning crucial for families to manage their tax obligations effectively and maximize their investment strategies.
Can you provide an example of how families have successfully navigated IPO tax strategies?
Jay and Emma, a couple with two children, successfully funded their children’s education while planning for retirement by creating a detailed budget and choosing diversified investment approaches. They received guidance from Bright Advisers to balance growth potential and risk management.
What is tax-loss harvesting, and how can it help families?
Tax-loss harvesting is a strategy that involves selling securities at a loss to offset capital gains, helping households manage their tax obligations more effectively.
How can effective tax planning enhance a family’s financial well-being?
By integrating tax efficiency into their financial plan, families can find peace of mind and enjoy quality time together, as demonstrated by Allison and Brian, who sought guidance to enhance their monetary potential through effective tax planning.
List of Sources
- Understand IPO Basics and Tax Implications
- Capital Gains Tax Rates: Short-term vs. Long-term (https://schwab.com/learn/story/how-are-capital-gains-taxed)
- Capital Gains Tax Rates for 2026: Long-Term and Short-Term | SoFi (https://sofi.com/learn/content/capital-gains-tax-rate)
- SEC.gov | Initial Public Offerings (IPOs) (https://sec.gov/data-research/statistics-data-visualizations/initial-public-offerings-ipos)
- US IPO market trends (https://ey.com/en_us/insights/ipo/ipo-market-trends)
- Key IPO Market Insights: IPO Research Tools & Screeners (https://renaissancecapital.com/IPO-Center/Stats)
- Assess Your Family’s Financial and Tax Situation
- 2026 Tax Brackets (https://taxfoundation.org/data/all/federal/2026-tax-brackets)
- 2025 and 2026 tax brackets and federal income tax rates | Fidelity (https://fidelity.com/learning-center/personal-finance/tax-brackets)
- Tax brackets 2026 and federal income tax rates (https://jacksonhewitt.com/tax-help/tax-tips-topics/filing-your-taxes/2026-tax-brackets)
- Understanding the 2026 Federal Income Tax Brackets (https://onedigital.com/en-US/articles/understanding-the-2026-federal-income-tax-brackets)
- Explore Tax Strategies and Tools for IPO Readiness
- How to lower taxable income with charitable giving (https://dafgiving360.org/tax-2026)
- Help Maximize Your Savings With Tax-Loss Harvesting (https://creativeplanning.com/insights/financial-planning/tax-loss-harvesting-strategy)
- What is Tax-Loss Harvesting? Rules & Examples | New York Life (https://newyorklife.com/articles/what-is-tax-loss-harvesting)
- Tax-Loss Harvesting Guide: Cut Your Capital Gains Tax | GTA Accounting Group (https://gtaaccountinggroup.com/blog/tax-loss-harvesting-guide-cut-your-capital-gains-tax)
- Navigating Charitable Giving in the Wake of New Tax Reform | NPTrust (https://nptrust.org/philanthropic-resources/philanthropist/navigating-charitable-giving-in-the-wake-of-new-tax-reform)
- Implement and Monitor Your IPO Tax Strategy
- How tax-efficient investing could boost your portfolio returns in 2026 and beyond (https://cnbc.com/2026/01/12/tax-efficient-investing.html)
- 2026 Tax Planning: Building a Tax-Smart Portfolio (https://agemy.com/blog/2026-tax-planning-building-a-tax-smart-portfolio)
- Top Tax Planning Strategies for 2026 (https://mgocpa.com/perspective/top-tax-planning-strategies-2026)
- Tax moves for 2026 | Fidelity (https://fidelity.com/learning-center/personal-finance/tax-moves)
- Tax trends and tactics Q2 2026: Tax-aware investing | Natixis Investment Managers (https://im.natixis.com/en-us/insights/tax-management/2026/tax-trends-and-tactics-tax-aware-investing)

Kevin has advised high-income W-2 tech and biotech families since 2015, and leads the education-first Age Five Family Office from Brea, California.
Connect on LinkedIn → · About KevinThis is part of how we approach Tax Management for high-income W-2 families at Bright Advisers.
Keep reading