

Overview
Mastering the distinction between needs and wants is a fundamental aspect of effective family budgeting. It’s vital to understand that categorizing expenses into essential needs and discretionary wants can truly transform your financial journey. Imagine if you could create a realistic budget that not only supports your financial goals but also brings peace of mind to your family. Practical steps, like using the 50/30/20 rule to allocate funds appropriately, can make a significant difference.
Involving your family members in the budgeting process is crucial. It’s important to understand how everyone can contribute to this shared goal, fostering a sense of teamwork and responsibility. Together, you can navigate this journey, ensuring that each member feels valued and heard.
As you embark on this path, remember that you’re not alone. We’re here for you, ready to support you with resources and guidance that resonate with your family’s values. By mastering the art of budgeting, you’re not just managing money; you’re investing in your family’s future.
Key Highlights:
- Needs are essential expenses for survival, such as food, shelter, and healthcare, while wants are non-essential items that enhance life.
- To categorise expenses, list monthly expenditures, classify them as needs or wants, and reflect on how wants impact financial goals.
- Understanding the difference between needs and wants is crucial for effective budgeting and long-term financial health.
- Evaluate your financial situation by calculating total income, tracking expenses, assessing debts, determining net worth, and reviewing monetary goals.
- Create a realistic budget by choosing a budgeting method, allocating funds to needs and wants, setting spending limits, involving family members, and regularly modifying the budget as necessary.
- The 50/30/20 rule is a recommended budgeting method, allocating 50% to needs, 30% to wants, and 20% to savings or debt repayment.
Introduction
Understanding the delicate balance between needs and wants is essential for effective family budgeting. Imagine the peace of mind that comes from knowing you can manage your finances with confidence. By distinguishing between the essentials that sustain daily life and the luxuries that enhance it, families can take control of their financial futures.
However, many struggle with this distinction, leading to stress and overspending. It’s important to understand that you’re not alone in this journey. How can families master this crucial skill to ensure both their basic needs are met and their desires are fulfilled? Together, we can navigate this journey to financial well-being.
Define Needs and Wants in Budgeting
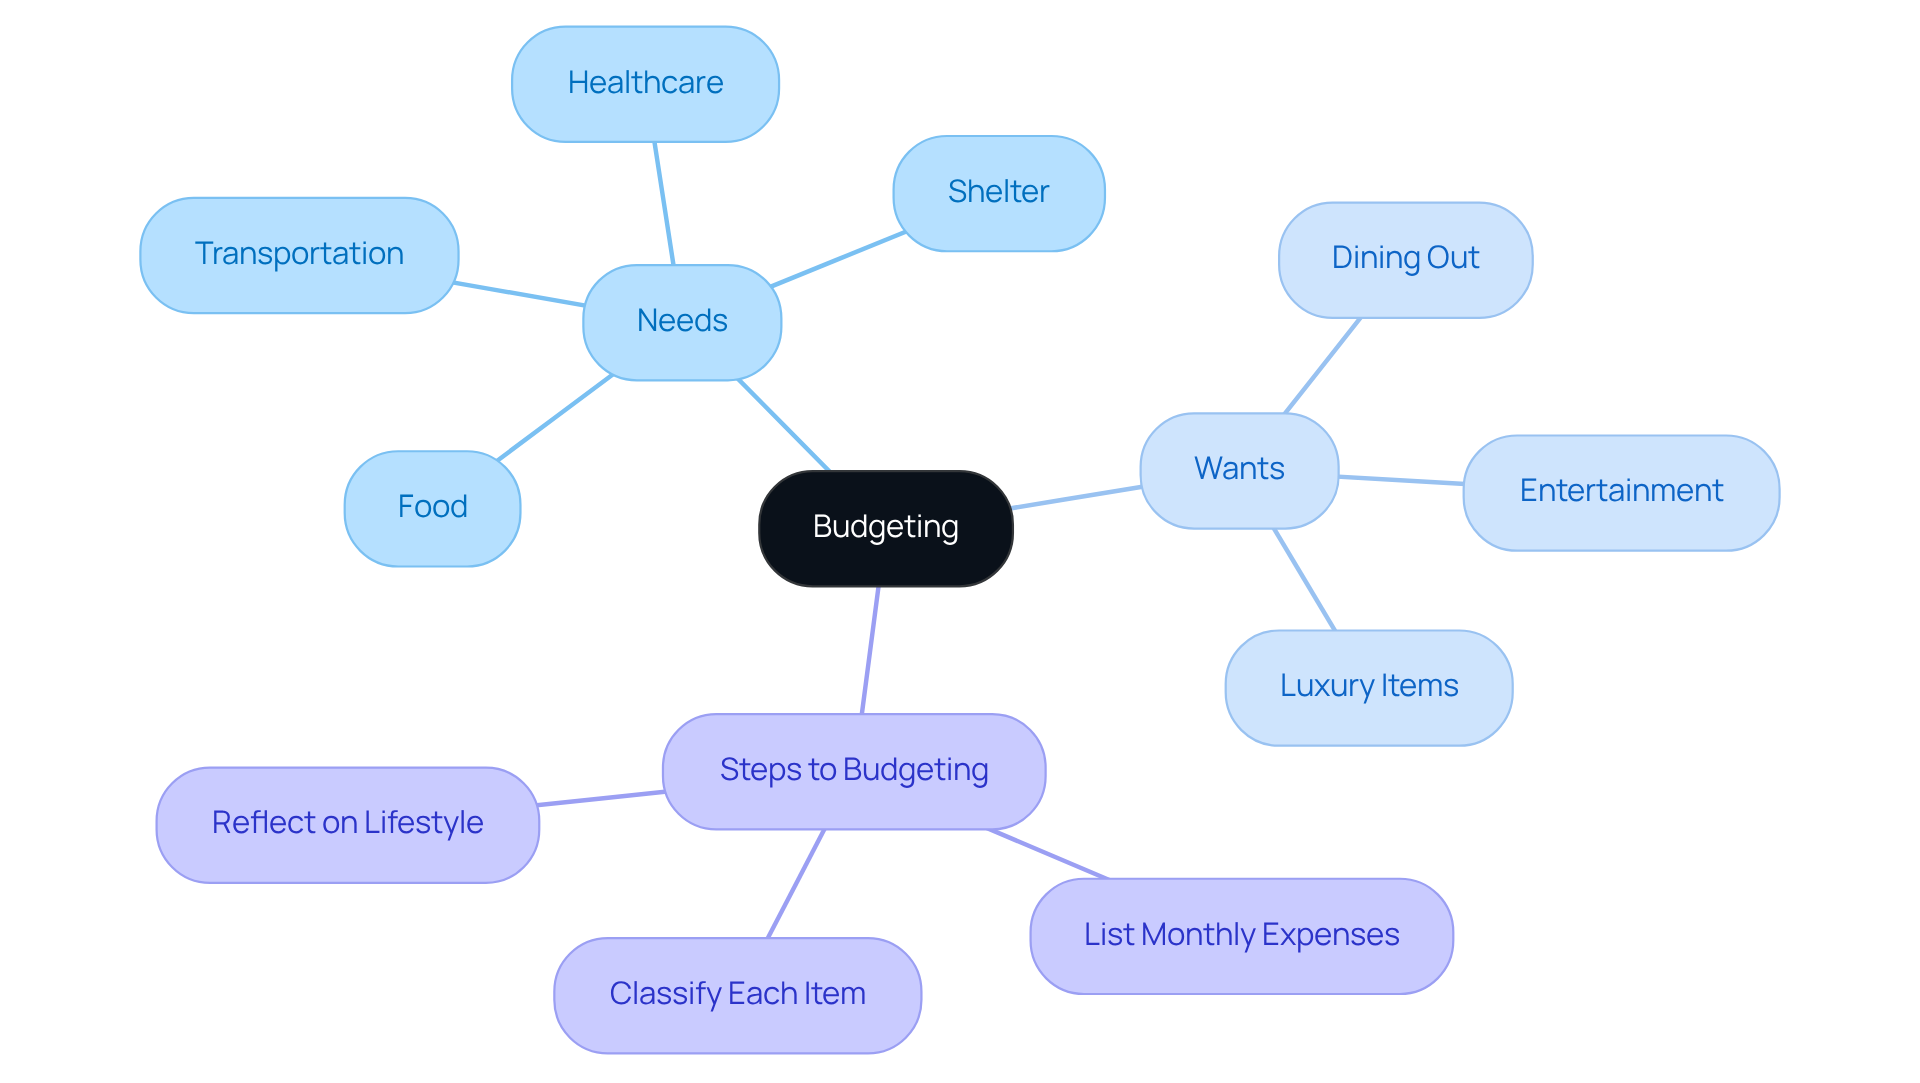
Successfully managing your family budget starts with understanding your needs and wants. Needs are the essentials for survival and daily life—think food, shelter, healthcare, and transportation. These expenses are non-negotiable and must take precedence to ensure your family maintains a basic standard of living.
On the other hand, wants are those delightful extras that enhance your life but aren’t critical for survival. Consider dining out, entertainment subscriptions, or luxury items. While these can add joy to your life, they are also flexible and can be adjusted or even eliminated when necessary.
To help you categorize your expenses effectively, imagine this:
- List all your monthly expenses: Write down every single expenditure, from rent and groceries to that occasional movie night.
- Classify each item: Go through your list and label each expense as a necessity or a want. This simple exercise can illuminate your spending habits and reveal areas where you might save.
- Reflect on your lifestyle: Think about how your wants affect your financial goals. Are there desires you could lessen or remove to better support your family’s needs? This reflection is vital for aligning your budget with your family’s values and priorities, including your needs and wants.
It’s important to recognize that many households struggle to differentiate between necessities and desires, which can lead to financial stress. Advisors stress that understanding this distinction is key to effective budgeting and long-term financial health. By mastering this skill, families can create a sustainable financial plan that prioritizes essential expenses while still allowing for those cherished treats.
Together, we can navigate this journey towards better financial management, ensuring your family’s needs are met while still enjoying life’s little pleasures.
Assess Your Personal Financial Situation
To effectively manage your household’s resources, begin by taking a moment to evaluate your personal financial situation. This assessment will shed light on your current monetary standing and help you create a plan tailored to your family’s unique needs.
-
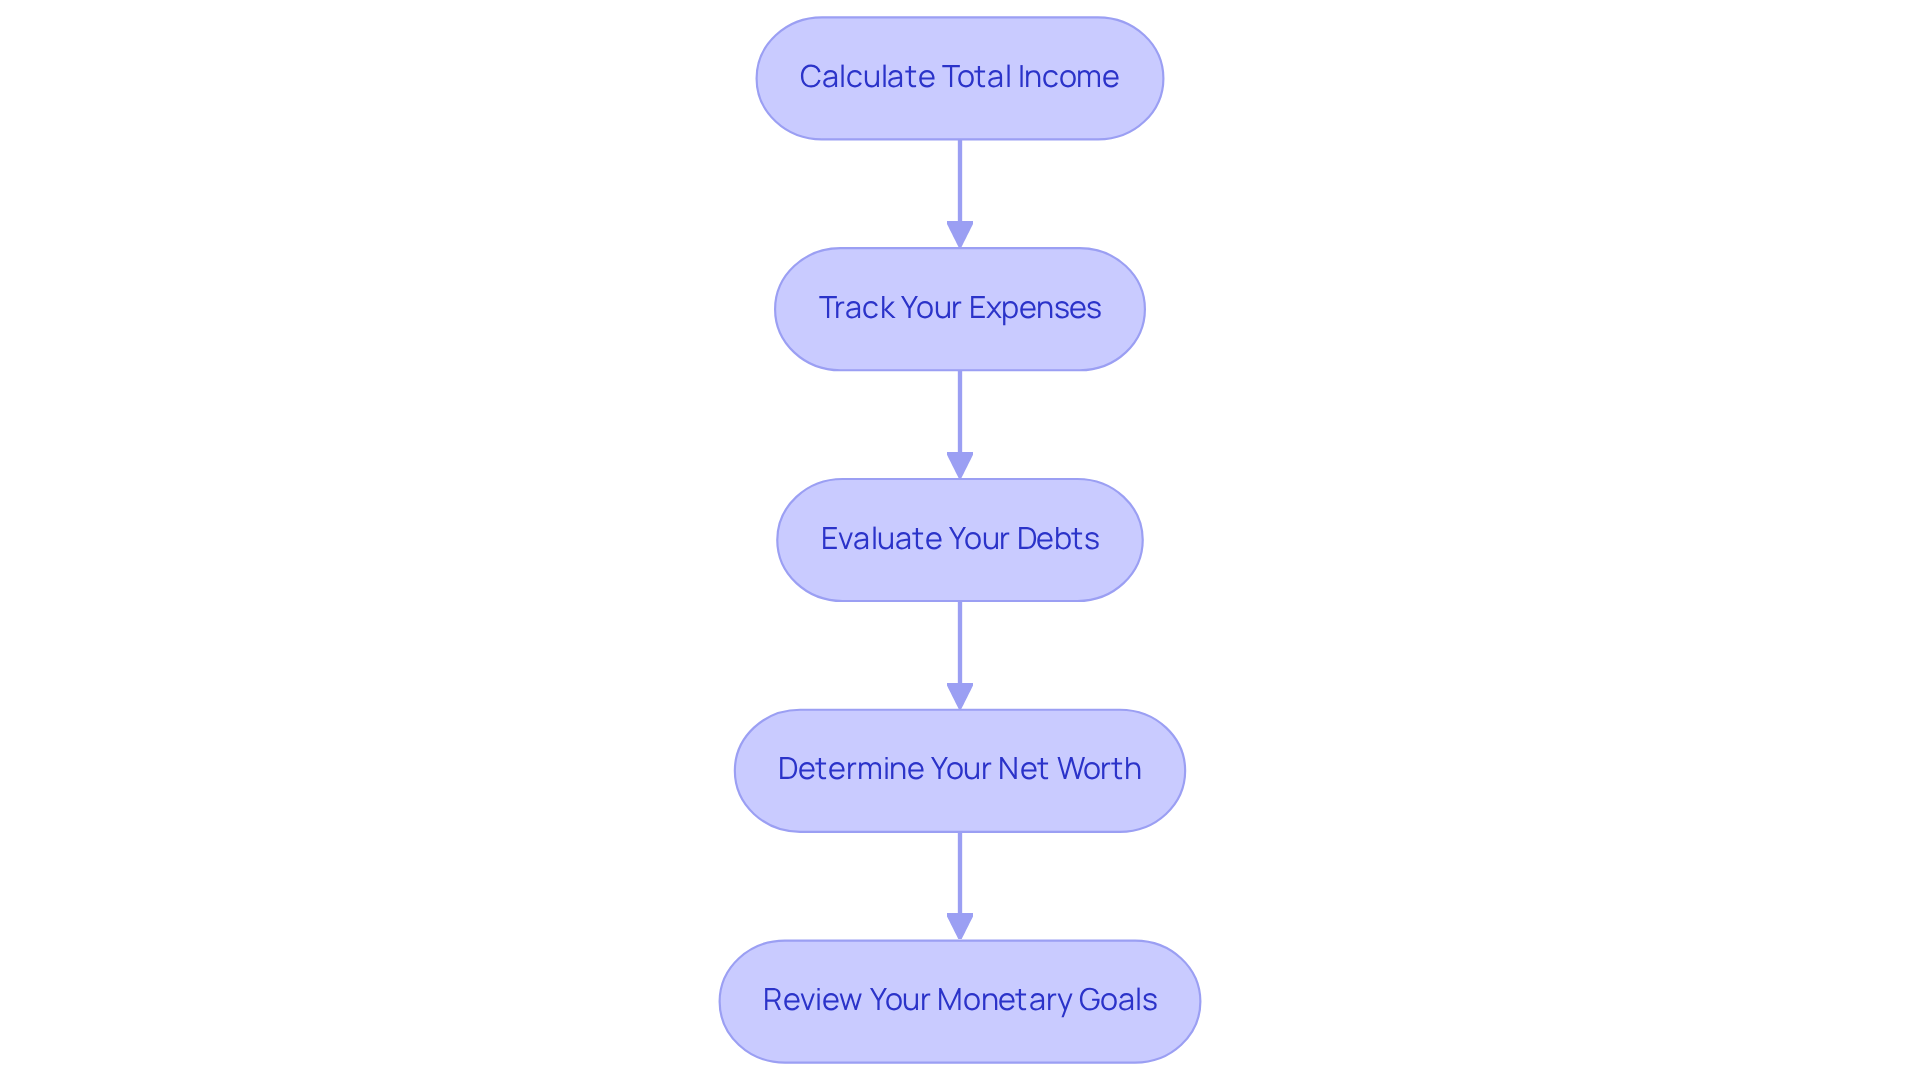
Calculate your total income: Start by determining your total monthly income, including all sources such as salaries, bonuses, rental income, and side hustles. This comprehensive view lays a strong foundation for your financial plan.
-
Track your expenses: For at least one month, diligently record all your expenses. Consider using budgeting apps or spreadsheets to categorize your spending, which will help you identify patterns and spot areas where you might be overspending. Recent data shows that the average American household carries over $152,000 in debt, highlighting the importance of careful expense tracking.
-
Evaluate your debts: Create a list of all your debts, including credit cards, student loans, and mortgages. Document the monthly payments and interest rates for each. Understanding your debt landscape is crucial for prioritizing payments and managing your budget effectively. For example, the average credit card debt per household is around $10,037, underscoring the need for thoughtful debt management.
-
Determine your net worth: Calculate your net worth by subtracting total liabilities (debts) from total assets (savings, investments, property). This snapshot of your financial health will help you set realistic economic goals. With total U.S. household debt reaching $18.39 trillion, grasping your net worth can provide clarity in a complex economic environment.
-
Review your monetary goals: Reflect on both your short-term and long-term financial aspirations. Are you saving for a home, your children’s education, or retirement? Aligning your financial plan with your needs and wants will empower you to effectively prioritize spending and savings.
By thoughtfully evaluating your financial situation, you can create a plan that addresses your needs and wants while also supporting your long-term economic aspirations. Remember, we’re here for you, and together, we can navigate this journey.
Create a Realistic Budget Plan
Understanding your needs and wants, along with your household’s financial situation, is crucial for creating a practical budget. Here are some essential steps to develop a budget that effectively supports your family’s financial goals:
-
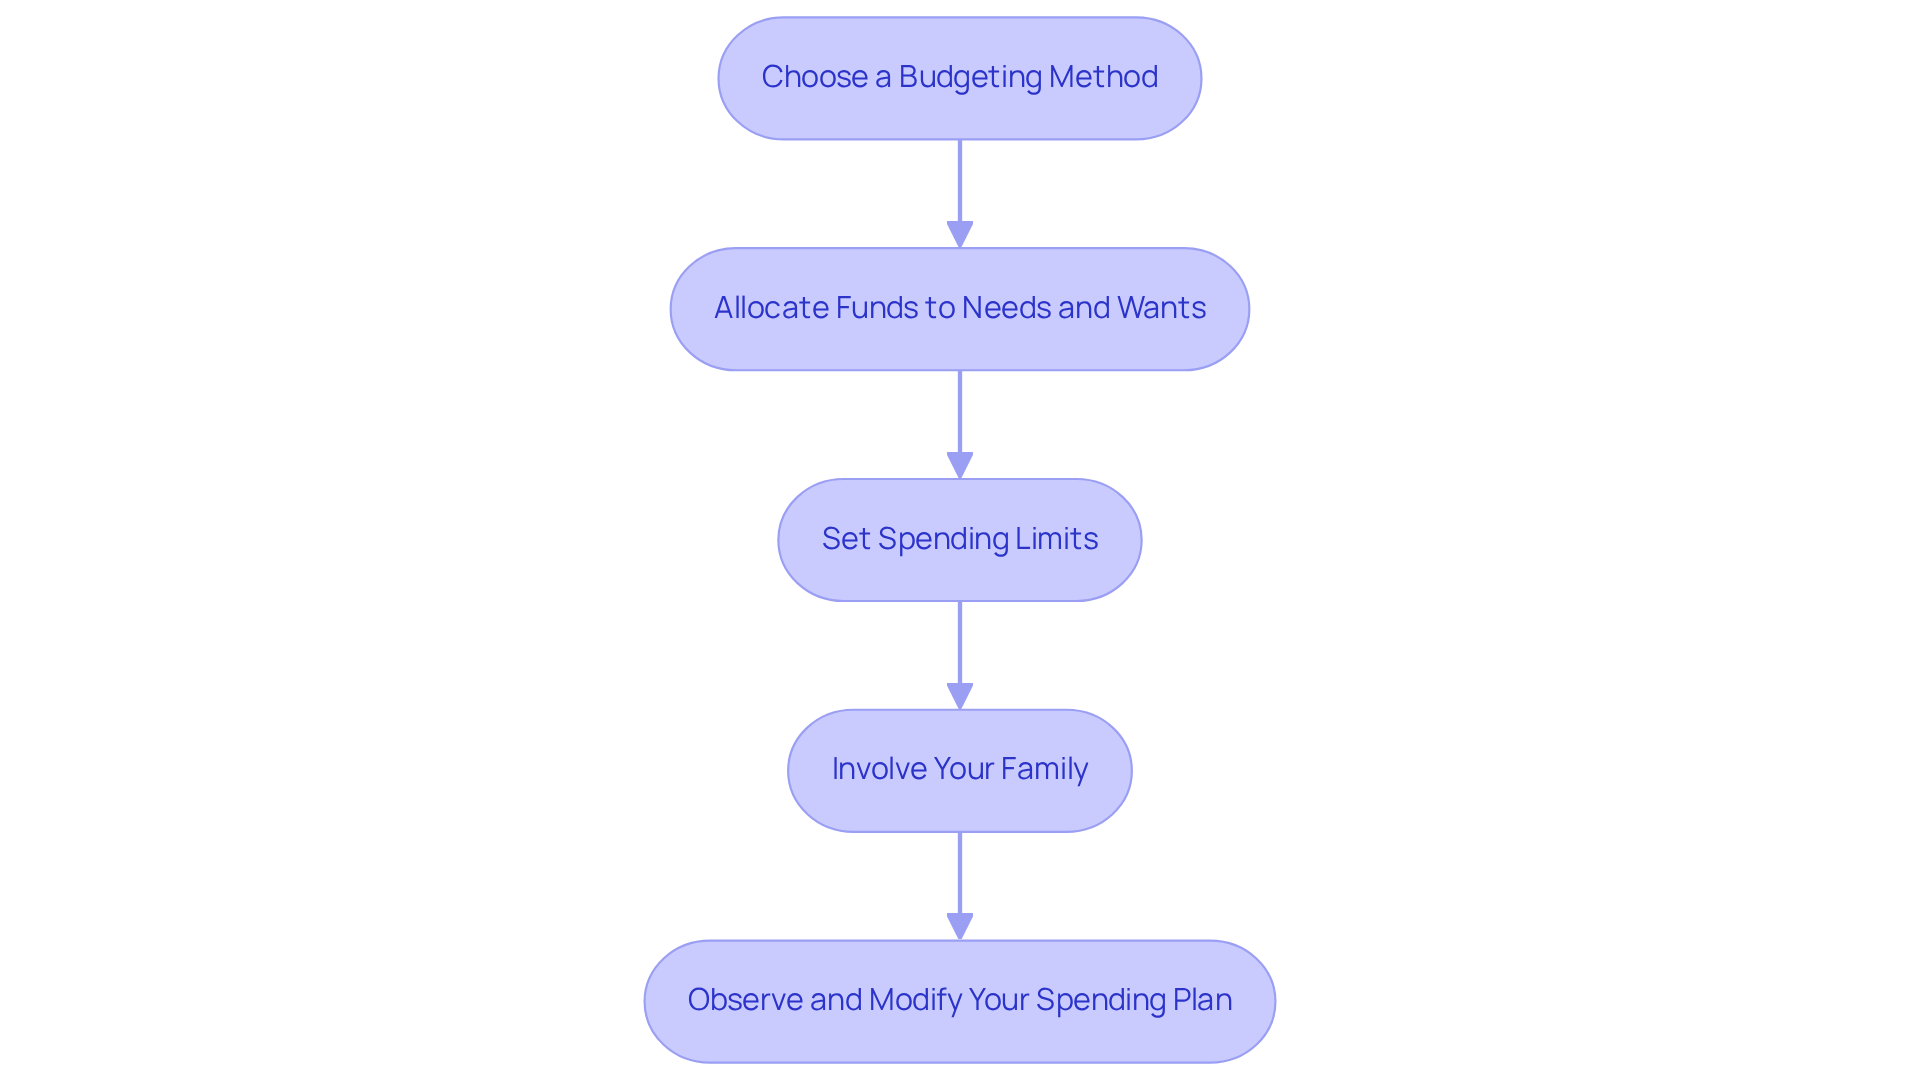
Choose a Budgeting Method: Consider a budgeting approach that aligns with your family’s financial objectives and lifestyle. You might find the 50/30/20 rule helpful, which allocates 50% of your income for necessities, 30% for wants, and 20% for savings or debt repayment. Alternatively, zero-based budgeting gives every dollar a purpose, while the envelope system uses cash for specific spending categories.
-
Allocate Funds to Needs and Wants: After categorizing your expenses, decide how much of your income to allocate to each category. Many families find success with the 50/30/20 distribution, ensuring that essential needs are prioritized while still allowing for some discretionary spending and savings.
-
Set Spending Limits: It’s important to establish realistic spending limits for each category based on your financial priorities. While it is essential to address your needs and wants, allowing some flexibility ensures that your budget reflects your family’s values and lifestyle.
-
Involve Your Family: Engage your family members in the budgeting process, especially your children. This involvement fosters an understanding of financial responsibility and the importance of prioritizing your needs and wants, laying a foundation for their future spending habits.
-
Observe and Modify Your Spending Plan: Regularly review your budget to ensure it aligns with your current financial situation. Life changes, such as job transitions or unexpected expenses, may necessitate adjustments to your spending limits. Flexibility is key to maintaining a budget that works for your family.
By following these steps, you empower your household to manage resources effectively, make informed purchasing decisions, and strive toward achieving your financial objectives. Remember, budgeting isn’t just about restrictions; it’s about creating a financial plan that resonates with your family’s values and aspirations. Together, we can navigate this journey, and Bright Advisers are here to assist you in aligning your financial resources with what matters most to your family.
Conclusion
Mastering the distinction between needs and wants is essential for effective family budgeting. By clearly defining these categories, families can prioritize their spending, ensuring that essential expenses are met while still allowing for some enjoyment in life. This understanding lays the groundwork for a sustainable financial plan that aligns with family values and financial goals.
Imagine if you could embark on this budgeting journey with confidence. Throughout this article, we’ve outlined key steps to help you along the way:
- Assessing your personal financial situation—taking into account income, expenses, and debts.
- Creating a realistic budget plan that thoughtfully incorporates both needs and wants.
Each element plays a pivotal role in achieving financial stability. Engaging the entire family in this process fosters a culture of financial responsibility and awareness, ensuring that everyone is on the same page.
Ultimately, effective budgeting is not just about cutting costs; it’s about making informed decisions that reflect your family’s priorities and aspirations. By taking actionable steps towards understanding and managing your finances, you can navigate your financial landscape with confidence. Embracing these principles can lead to a more secure and fulfilling financial future, empowering your family to enjoy life’s pleasures without compromising essential needs. Together, we can navigate this journey towards financial well-being.
Frequently Asked Questions
What are considered needs in budgeting?
Needs are the essentials for survival and daily life, including food, shelter, healthcare, and transportation. These expenses are non-negotiable and must take precedence to maintain a basic standard of living.
How are wants defined in the context of budgeting?
Wants are the extras that enhance life but are not critical for survival. Examples include dining out, entertainment subscriptions, or luxury items. These expenses are flexible and can be adjusted or eliminated when necessary.
How can I categorize my expenses into needs and wants?
Start by listing all your monthly expenses, then classify each item as either a necessity or a want. This exercise can help illuminate your spending habits and reveal areas where you might save.
Why is it important to reflect on my lifestyle when budgeting?
Reflecting on your lifestyle helps you understand how your wants affect your financial goals. It allows you to identify desires that could be lessened or removed to better support your family’s needs, aligning your budget with your family’s values and priorities.
What problems can arise from not distinguishing between needs and wants?
Many households struggle to differentiate between necessities and desires, which can lead to financial stress. Understanding this distinction is key to effective budgeting and long-term financial health.
How can mastering the distinction between needs and wants benefit my family?
By mastering this skill, families can create a sustainable financial plan that prioritizes essential expenses while still allowing for occasional treats, ultimately leading to better financial management.
List of Sources
- Define Needs and Wants in Budgeting
- 14 Quotes From Our Favorite Money Saving Experts (https://chime.com/blog/quotes-from-money-saving-experts)
- 9 Inspiring Budgeting Quotes (and How You Can Use Them to Take Action NOW) – Atypical Finance (https://atypicalfinance.com/9-inspiring-budgeting-quotes-and-how-you-can-use-them-to-take-action-now)
- 200 Quotes About Money And Personal Finance To Inspire You (https://marriagekidsandmoney.com/20-empowering-quotes-about-money-and-personal-finance)
- 100 Best Motivational Quotes About Finance to Boost Your Financial Goals in 2025 (https://acecloudhosting.com/blog/motivational-finance-quotes)
- 5 Famous Quotes to Fine-Tune Your Finances (https://my.branchapp.com/post/5-famous-quotes-to-fine-tune-your-finances)
- Assess Your Personal Financial Situation
- How much debt the average American holds (https://businessinsider.com/personal-finance/credit-score/average-american-debt)
- What Is the Average American Debt by Age? (https://synchrony.com/blog/bank/average-american-debt-by-age)
- Total household debt by type (https://fool.com/money/research/average-household-debt)
- Average U.S. Household Debt Reaches $152K (https://cpapracticeadvisor.com/2025/08/12/average-u-s-household-debt-reaches-152k-2/167216)
- American Household Debt: Statistics and Demographics (https://debt.org/faqs/americans-in-debt/demographics)
- Create a Realistic Budget Plan
- 9 Inspiring Budgeting Quotes (and How You Can Use Them to Take Action NOW) – Atypical Finance (https://atypicalfinance.com/9-inspiring-budgeting-quotes-and-how-you-can-use-them-to-take-action-now)
- Top 150 Financial Planning Quotes [2025] (https://digitaldefynd.com/IQ/financial-planning-quotes)

Kevin has advised high-income W-2 tech and biotech families since 2015, and leads the education-first Age Five Family Office from Brea, California.
Connect on LinkedIn → · About Kevin