

Key Highlights
- A Generation-Skipping Trust (GST) allows wealth to be passed directly to grandchildren, avoiding estate taxes and financial uncertainty.
- Key features of a GST include irrevocability, tax benefits, and clear recipient designation.
- Trustees must understand the trust document, manage assets wisely, follow distribution guidelines, and ensure tax compliance.
- The Generation-Skipping Transfer Tax (GSTT) applies to transfers to beneficiaries two or more generations younger, with a flat rate of 40% on amounts exceeding the lifetime exemption.
- Consulting professionals, such as estate planning attorneys and financial advisors, is crucial for effective trust management.
- Regular reviews of the trust’s performance and compliance with legal requirements are essential for safeguarding the family’s legacy.
- Effective communication with beneficiaries involves establishing clear channels, providing regular updates, fostering open dialogue, and educating them about financial literacy.
- Investment advisory services are provided through Lifeworks Advisors, a registered investment adviser, and all investments are subject to risk.
Introduction
Many parents feel overwhelmed when trying to understand the intricacies of a Generation-Skipping Trust (GST) and its impact on their family’s future. This guide is here to gently walk you through the essential roles and responsibilities of a GST trustee.
We’ll highlight best practices that can empower you to manage these trusts effectively. But with the right guidance, you can ensure your family’s legacy not only survives but thrives.
Understand the Basics of a Generation-Skipping Trust
Imagine a future where your grandchildren thrive, free from the burdens of estate taxes and financial uncertainty. A Generation-Skipping Trust (GST) helps you pass on your wealth directly to your grandchildren or younger family members. This means you can skip a generation, making it easier for your loved ones to benefit.
Key Features of a GST:
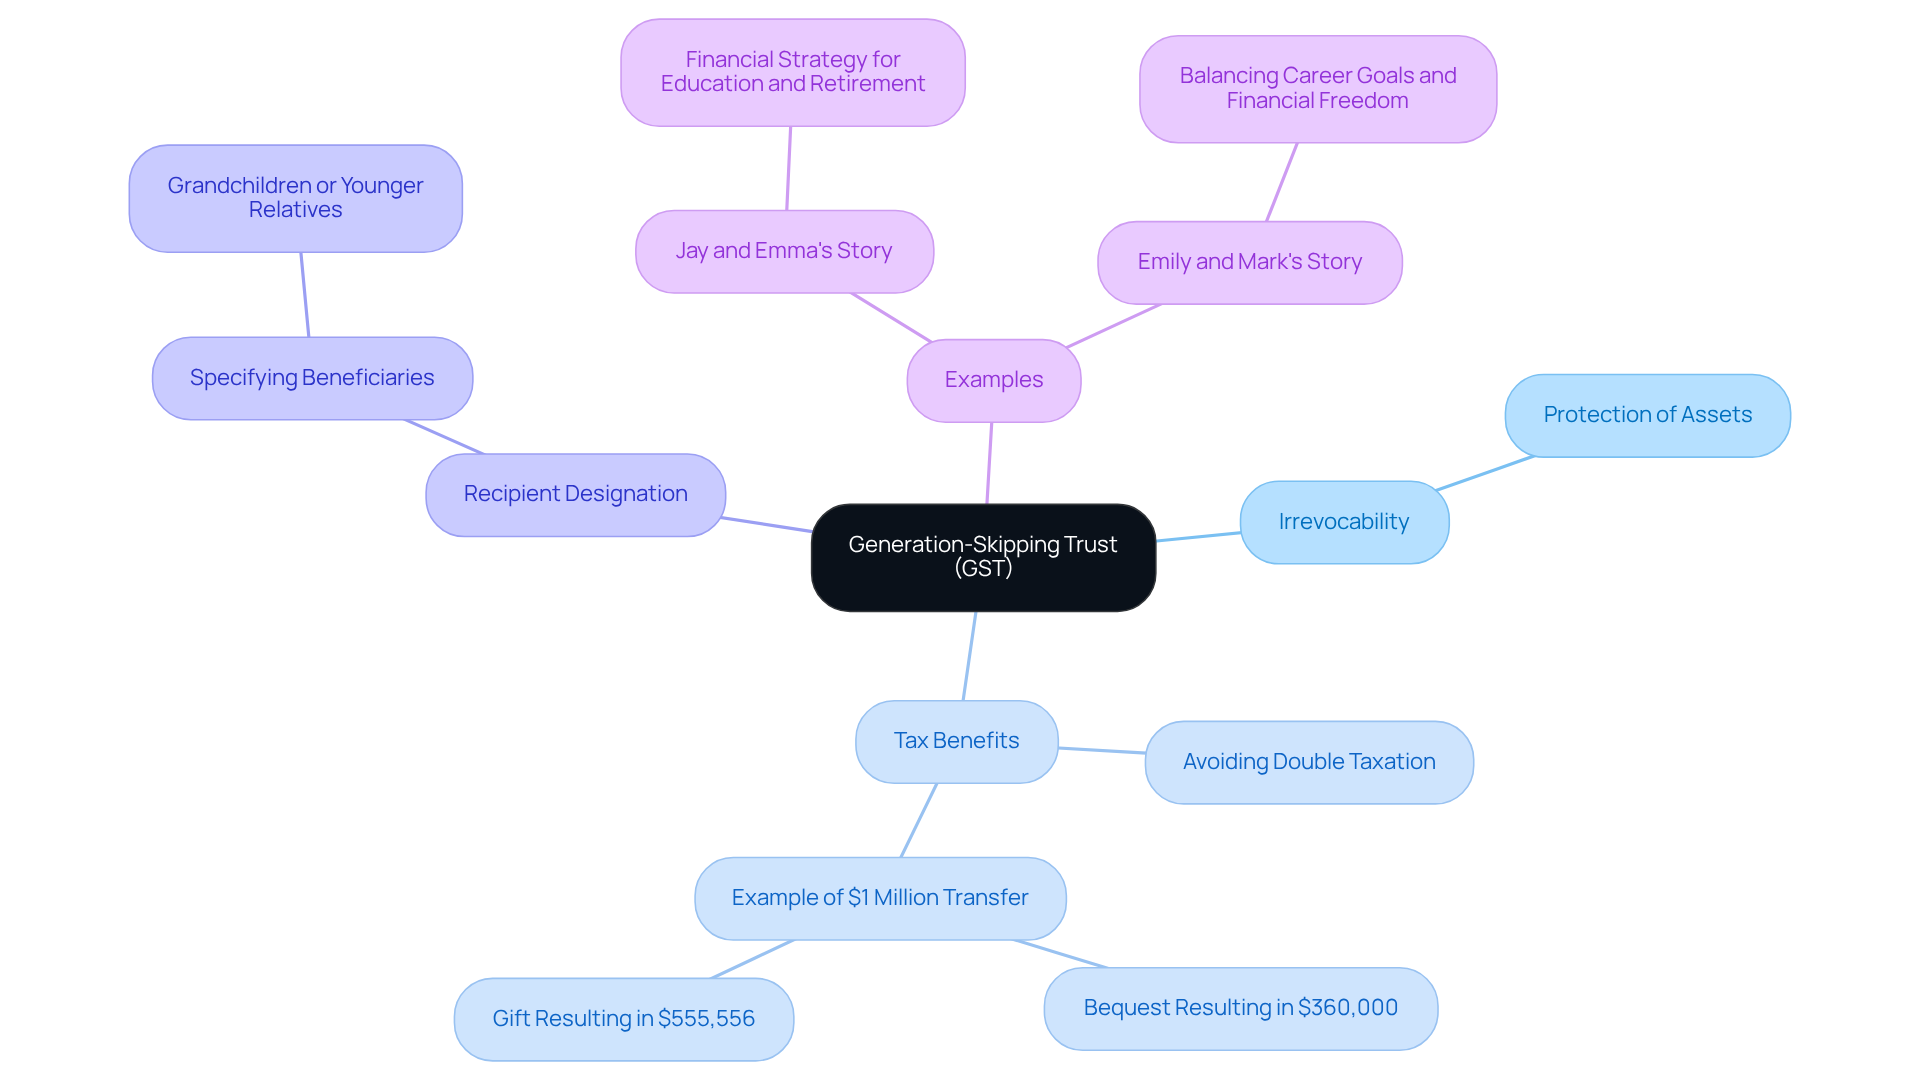
- Irrevocability: Once established, a GST generally cannot be altered or revoked, ensuring that the assets are protected for the intended beneficiaries.
- Tax Benefits: By skipping a generation, the arrangement can help avoid double taxation on the estate. For instance, transferring $1 million through a bequest results in only $360,000 for the recipient after taxes. This highlights the financial advantage of using a GST.
- Recipient Designation: The arrangement must clearly specify who the recipients are, usually grandchildren or younger relatives, ensuring that your wishes are respected.
It’s important for the generation skipping trust trustee to understand these basics, as it helps them make decisions that truly benefit your family. In Southern California, where estate planning complexities can arise, having a generation skipping trust trustee can significantly enhance wealth preservation strategies for families. By implementing a GST, families can ensure their legacies are not only preserved but also flourish for generations to come.
For example, consider the case of Jay and Emma, who sought guidance from Bright Advisers to reduce their financial anxiety while planning for their children’s education and their retirement. With a thoughtful financial strategy, Jay and Emma found peace of mind, balancing their current needs with their dreams for the future. Similarly, Emily and Mark, with their ambitious career goals, worked with Bright Advisers to create a plan that provided them the freedom to choose whether or not to continue working.
With the right guidance, you can create a lasting legacy that supports your family’s dreams and aspirations.
Fulfill Trustee Responsibilities and Duties
Navigating the responsibilities of a Generation-Skipping Fund can feel overwhelming, especially when you want to ensure your family’s future is secure. Here’s a gentle approach to fulfilling these important duties:
-
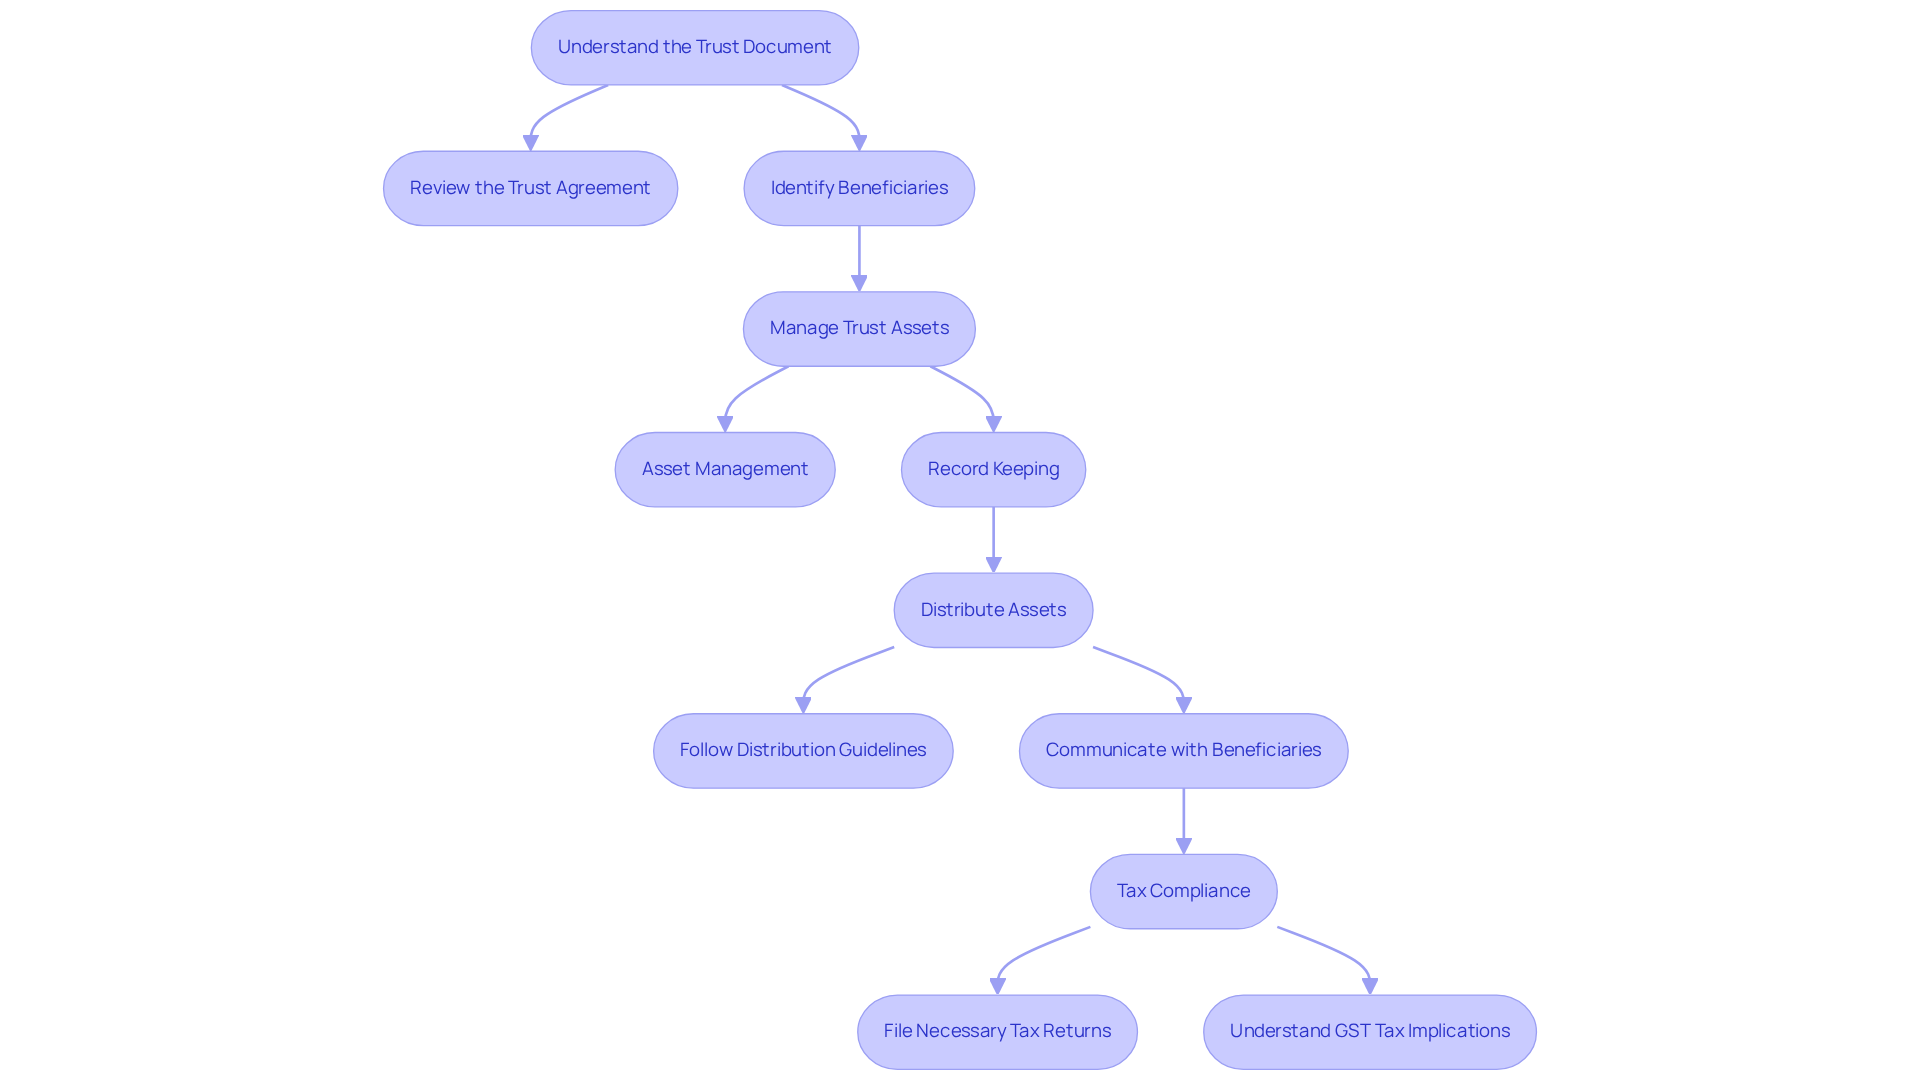
Understand the Trust Document
- Review the Trust Agreement: Take some time to familiarize yourself with the trust document. Understanding the specific powers granted to you and any limitations will help you make informed decisions.
- Identify Beneficiaries: Knowing who the beneficiaries are and their interests in the arrangement is crucial. This understanding will guide your choices as you navigate this journey.
-
Manage Trust Assets
- Asset Management: It’s important to manage the trust assets wisely, so they can grow and support your family’s needs. This might involve investing in a mix of assets to maximize growth while keeping fees low. A well-structured generation skipping trust trustee can help minimize taxes on inherited wealth, allowing your loved ones to keep more of what you’ve passed down.
- Record Keeping: Keeping track of all transactions is essential, as it helps you understand how the trust is performing and what it means for your family. Accurate records of income, expenses, and distributions are vital for clarity.
-
Distribute Assets
- Follow Distribution Guidelines: Adhere to the guidelines in the trust document about when and how to distribute assets. For instance, if a grandchild receives a $1,000,000 distribution without an allocated GST exemption, they may face a hefty tax that reduces their inheritance significantly.
- Communicate with Beneficiaries: Keeping beneficiaries informed about the fund’s performance and any distributions made can help ease potential family tensions, especially in complex family dynamics.
-
Tax Compliance
- File Necessary Tax Returns: Make sure to complete all required tax filings, like Form 1041 for the trust, on time to avoid penalties. Timely compliance is crucial, as the current GST tax rate is a flat 40%.
- Understand GST Tax Implications: Be aware of the Generation-Skipping Transfer Tax (GSTT) and how the generation skipping trust trustee may affect distributions. Each individual has a lifetime GSTT exemption linked to the federal estate and gift tax exemption, which is essential for minimizing tax liabilities. Proper allocation of the GSTT exemption is crucial to avoid a 40% tax on distributions from the estate.
By diligently following these steps, you can protect your family’s legacy and ensure that your loved ones benefit from the wealth you’ve worked hard to build.
Navigate Financial and Legal Considerations
Imagine the peace of mind that comes from securing your family’s financial future, even across generations. Managing a generation skipping trust trustee can feel daunting, especially when considering your family’s financial future. Here’s how to navigate these complexities with care and confidence:
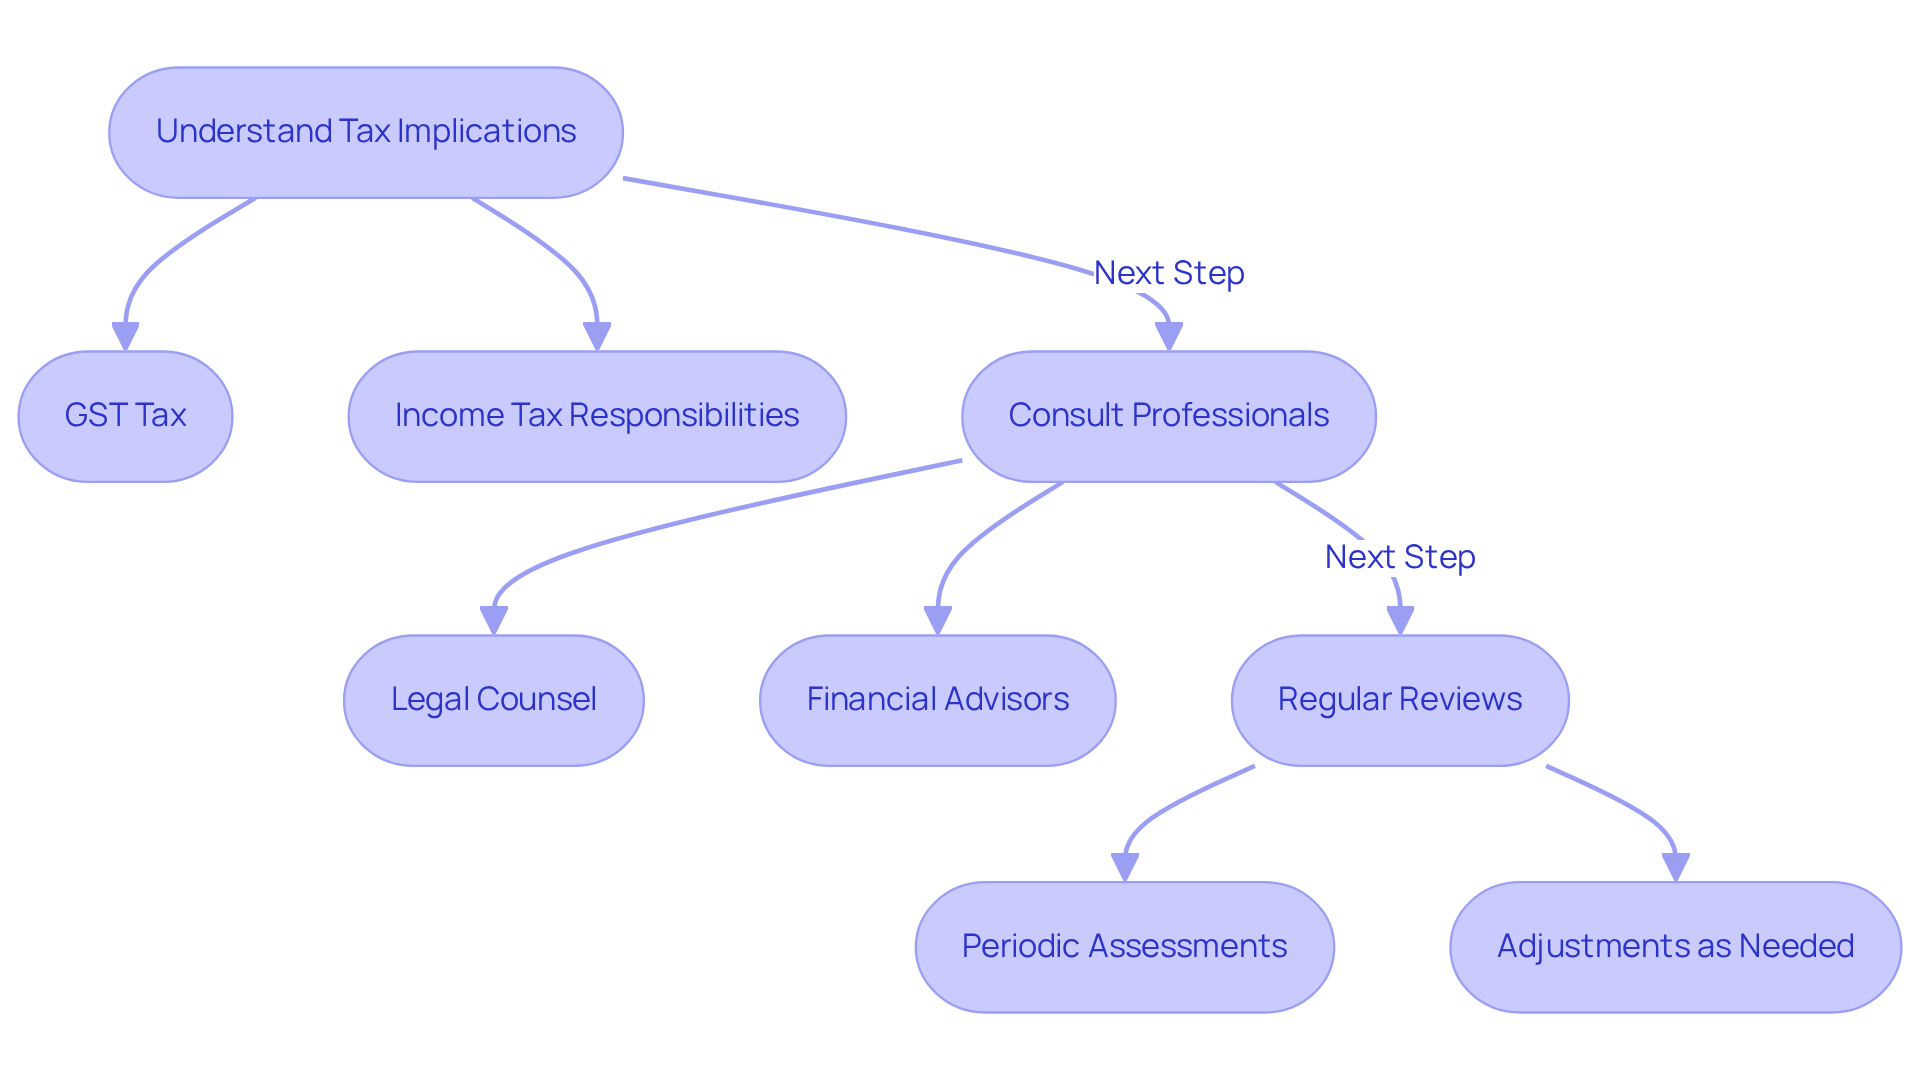
Step 1: Understand Tax Implications
- GST Tax: Familiarize yourself with the Generation-Skipping Transfer Tax (GSTT). This tax applies to transfers made to beneficiaries who are two or more generations younger than you. In 2026, the GSTT is set at a flat rate of 40% on transfers exceeding the lifetime exemption amount of $15 million per individual or $30 million for married couples. Utilizing available exemptions can significantly minimize tax liabilities, helping you keep more for your loved ones.
- Income Tax Responsibilities: It’s important to understand how income generated by the fund is taxed. Depending on how distributions are structured, the entity may be responsible for paying taxes on its income, or it may pass through to beneficiaries.
Step 2: Consult Professionals
- Legal Counsel: Engaging an estate planning attorney can be a crucial step. They ensure compliance with state and federal laws governing trusts, helping you interpret complex legal terminology and offering advice on best practices. This way, you can feel confident that everything is in order regarding the generation skipping trust trustee.
- Financial Advisors: Collaborating with financial advisors, like those at Bright Advisers, can make a world of difference. They have a proven track record of helping families optimize their financial potential through strategic tax planning. For instance, clients like Allison and Brian have successfully navigated their tax situations, securing their children’s future and gaining the ability to retire sooner by leveraging tax optimization strategies. Bright Advisers emphasizes fiduciary duty and transparency, ensuring no hidden fees or conflicts of interest.
Step 3: Regular Reviews
- Periodic Assessments: Conducting regular reviews of the trust’s performance and compliance with legal requirements is essential. This involves assessing investment strategies and ensuring that the fund remains aligned with your intentions. For example, a case study on lifetime exemption utilization shows how strategic gifting can shelter assets from GST tax and estate tax, ensuring appreciation passes to grandchildren without incurring additional taxes.
- Adjustments as Needed: Be prepared to make modifications to the management strategies of the fund based on changing financial circumstances or legal requirements. The flexibility to adapt is essential for effective relationship management.
Taking these steps today can safeguard your family’s legacy for tomorrow, ensuring your loved ones thrive. Remember, you’re not alone in this journey; we’re here for you every step of the way.
Communicate Effectively with Beneficiaries
Many young families feel overwhelmed when it comes to managing their financial futures, unsure of where to start or how to communicate effectively with beneficiaries. Here are some actionable steps to enhance your communication with beneficiaries:
-
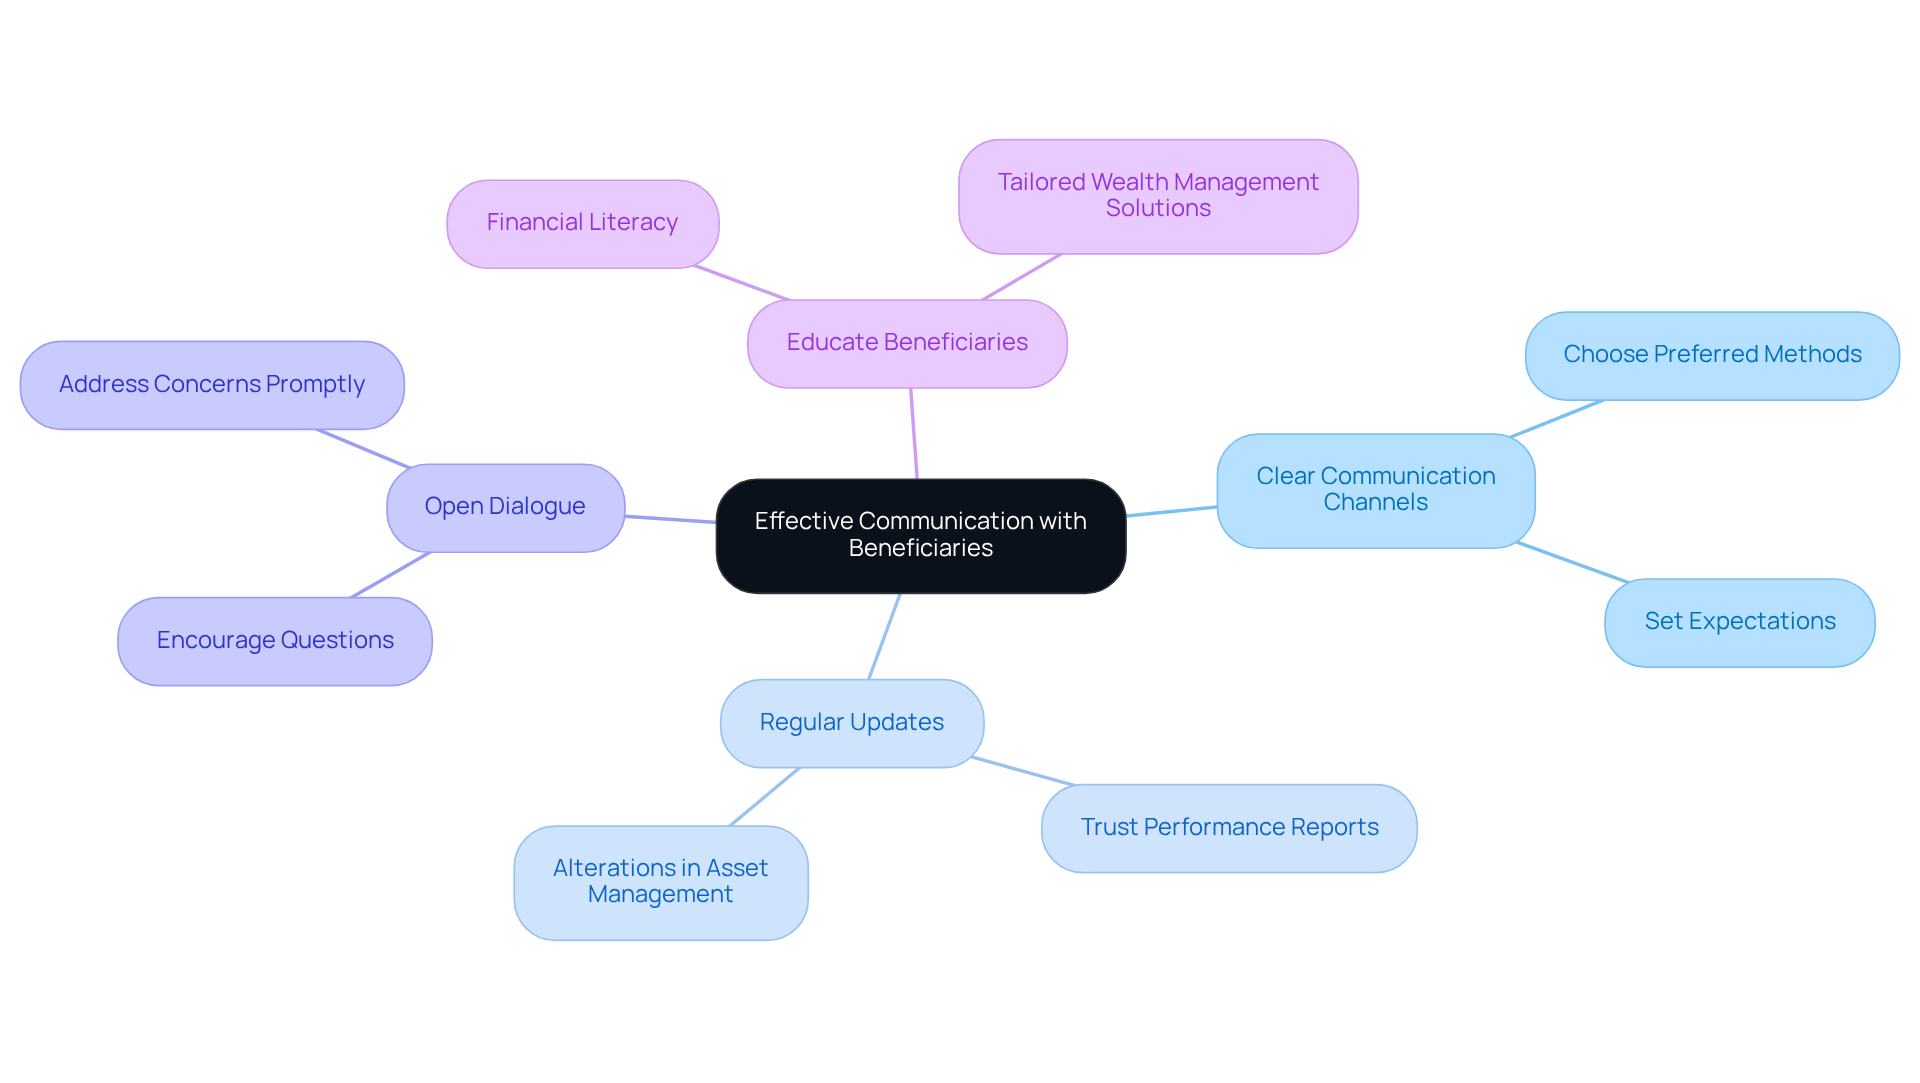
Establish Clear Communication Channels
- Choose Preferred Methods: Identify how beneficiaries prefer to receive information-be it through email, phone calls, or in-person meetings-and set a regular schedule for updates.
- Set Expectations: Clearly outline what beneficiaries can expect regarding the frequency of communication and the types of information that will be shared.
-
Provide Regular Updates
- Trust Performance Reports: Share consistent reports detailing the trust’s performance, including asset values, income generated, and any distributions made. This transparency is essential for sustaining confidence and engagement.
- Alterations in Asset Management: Keep recipients updated on any major modifications in asset management or investment approaches that may affect their interests.
-
- Encourage Questions: Create an environment where beneficiaries feel comfortable asking questions or expressing concerns about the trust. As Stephen R. Covey observed, “When the confidence account is high, communication is easy, instant, and effective.”
- Address Concerns Promptly: Respond to inquiries in a timely manner to build confidence and demonstrate your commitment to their interests.
-
Educate Beneficiaries
- Financial Literacy: Provide educational resources or workshops to help beneficiaries understand the trust’s purpose and their roles within it. This empowers them to make informed decisions in the future. For instance, families like Jay & Emma and Emily & Mark have benefited from Bright Advisers’ tailored wealth management solutions, which focus on financial security and educational readiness for their children.
By prioritizing effective communication, you can create a nurturing environment that fosters trust and understanding, ensuring your family’s financial future is secure and bright. We’re here to help families like yours make wise wealth decisions and preserve wealth across generations, ensuring that your financial strategies are as personalized and effective as possible.
Disclaimer: Investment advisory services are provided through Lifeworks Advisors, a registered investment adviser. Past performance does not guarantee future results, and all investments are subject to risk. Always consult with a financial advisor for personalized advice.
Conclusion
Imagine the peace of mind that comes from knowing your family’s wealth is in safe hands, ready to support future generations. Mastering the role of a Generation-Skipping Trust trustee is essential for ensuring that family wealth is preserved and passed down effectively. Understanding a Generation-Skipping Trust is key. It involves knowing its irrevocability, tax benefits, and how to clearly designate beneficiaries. This role is not just about managing assets; it’s about caring for your family’s future and safeguarding a legacy that can support future generations.
Key responsibilities include:
- Familiarizing yourself with the trust document
- Managing trust assets wisely
- Adhering to distribution guidelines
- Ensuring tax compliance
Regular communication with beneficiaries is crucial, as it fosters transparency and trust, helping to mitigate potential family tensions. Imagine having the support of professionals, like estate planning attorneys and financial advisors at Bright Advisers, guiding you through the complexities of trust management.
By prioritizing effective communication and strategic planning, you can empower beneficiaries and ensure that your family’s financial future remains bright. By taking these thoughtful steps, you’re not just preserving wealth; you’re nurturing a legacy that will enrich your loved ones’ lives for generations to come.
Frequently Asked Questions
What is a Generation-Skipping Trust (GST)?
A Generation-Skipping Trust (GST) is an estate planning tool that allows you to pass on your wealth directly to your grandchildren or younger family members, effectively skipping a generation to help them benefit without the burdens of estate taxes.
What are the key features of a Generation-Skipping Trust?
The key features of a GST include: – Irrevocability: Once established, a GST generally cannot be altered or revoked, protecting the assets for the intended beneficiaries. – Tax Benefits: It can help avoid double taxation on the estate, allowing more wealth to be passed on to recipients. – Recipient Designation: The trust must clearly specify the recipients, usually grandchildren or younger relatives, to ensure your wishes are respected.
How does a Generation-Skipping Trust help with estate taxes?
By skipping a generation, a GST can help avoid double taxation on the estate, which can significantly increase the amount of wealth that is passed on to beneficiaries.
Why is it important for a GST trustee to understand the basics of a Generation-Skipping Trust?
It is important for a GST trustee to understand the basics to make informed decisions that truly benefit the family and ensure that the trust’s intentions are fulfilled.
How can a Generation-Skipping Trust enhance wealth preservation strategies for families?
A GST can enhance wealth preservation strategies by ensuring that legacies are preserved and flourish for generations, helping families navigate the complexities of estate planning.
Can you provide an example of how a Generation-Skipping Trust has benefited a family?
For instance, Jay and Emma worked with Bright Advisers to create a thoughtful financial strategy that reduced their financial anxiety while planning for their children’s education and their retirement, allowing them to balance current needs with future dreams.
What is the mission of Bright Advisers in relation to wealth management?
Bright Advisers aims to help families make wise wealth decisions and preserve wealth across generations, ensuring that their legacies support their dreams and aspirations.
List of Sources
- Understand the Basics of a Generation-Skipping Trust
- Generation-skipping trust for estate planning (https://investmentnews.com/guides/generation-skipping-trust-for-estate-planning/252077)
- The Generation-Skipping Transfer Tax (GSTT) (https://congress.gov/crs-product/IF13053)
- Generation skipping transfer tax (GSTT) explained | Fidelity (https://fidelity.com/viewpoints/wealth-management/insights/generation-skipping-transfer-tax)
- Generation-Skipping Transfer Tax: How It Can Affect Your Estate Plan | U.S. Bank (https://usbank.com/wealth-management/financial-perspectives/trust-and-estate-planning/generation-skipping-tax-affect-on-estate-plan.html)
- Fulfill Trustee Responsibilities and Duties
- Generation Skipping Trust (GST): How It Works & Tax Rules (https://westernsouthern.com/retirement/generation-skipping-trust)
- Generation-Skipping What? An Overview of the GST Tax and Strategies to Mitigate Exposure – Spencer Fane (https://spencerfane.com/insight/generation-skipping-what-an-overview-of-the-gst-tax-and-strategies-to-mitigate-exposure)
- 3 Smart Generation-Skipping Trust Strategies – Lawvex (https://lawvex.com/generation-skipping-trust)
- Generation-Skipping Trust (GST): An Ultimate Guide (https://marshalljones.com/generation-skipping-trust)
- Five Quotes from Financial History to Guide Trustees (https://rpc.cfainstitute.org/blogs/enterprising-investor/2024/five-quotes-from-financial-history-to-guide-trustees)
- Navigate Financial and Legal Considerations
- Generation-Skipping Transfer Tax: How It Can Affect Your Estate Plan | U.S. Bank (https://usbank.com/wealth-management/financial-perspectives/trust-and-estate-planning/generation-skipping-tax-affect-on-estate-plan.html)
- What is the Generation-Skipping Transfer Tax? (https://turbotax.intuit.com/tax-tips/family/what-is-the-generation-skipping-tax/amp/L5mfqiA5z)
- Generation skipping transfer tax (GSTT) explained | Fidelity (https://fidelity.com/viewpoints/wealth-management/insights/generation-skipping-transfer-tax)
- Generation Skipping Trusts | GSTs | Estate Planning | RJS LAW (https://irssolution.com/blog/generation-skipping-trusts)
- Communicate Effectively with Beneficiaries
- 35 Quotes about Communication to Inspire Collaboration (https://vibe.us/blog/35-quotes-about-communication?srsltid=AfmBOoqa4gyEzap0zWKnLhCuFyZ5O3OEAOAV8RWGKstvn0qWir7XKD-n)
- Workplace Trust Statistics 2026 (https://speakwiseapp.com/blog/workplace-trust-statistics)
- Leadership Communication Statistics – Effectiveness, Trust & Team Alignment Data (https://kapable.club/blog/statistics/communication-and-leadership-statistics)
- 10 statistics that drive home why business needs to refocus on trust – Sword and the Script (https://swordandthescript.com/2025/04/trust-statistics)

Kevin has advised high-income W-2 tech and biotech families since 2015, and leads the education-first Age Five Family Office from Brea, California.
Connect on LinkedIn → · About KevinThis is part of how we approach Estate Planning for high-income W-2 families at Bright Advisers.
Keep reading