

Key Highlights
- Earned income comes from active work, such as salaries and wages, while unearned income is generated from investments and passive sources.
- Understanding the differences between earned and unearned income helps families manage their finances and tax implications effectively.
- Unearned income types include interest income, dividends, capital gains, rental income, and royalties, each offering unique financial opportunities.
- Families should be aware of the Kiddie Tax, which taxes children’s unearned income over $2,700 at the parent’s tax rate, impacting financial planning.
- Strategic tax planning can optimise financial situations, helping families secure their children’s education and retirement goals.
- Implementing strategies like diversifying income sources, utilising tax-advantaged accounts, and engaging in financial education can enhance financial security.
- Bright Advisers, founded by Kevin Luu and Kathleen Chou in 2010, focuses on helping families make informed wealth decisions and preserve wealth across generations.
Introduction
Many families struggle to make sense of unearned income, yet understanding it can truly transform their financial journey. This guide explores the different forms of unearned income – like interest, dividends, and rental revenue – and shows how young parents can use these streams to boost their financial well-being.
Many families feel lost when it comes to understanding how to make unearned income work for them. Navigating tax implications and strategic management can feel overwhelming. Without proper guidance, families might miss out on opportunities to secure their financial future.
Define Earned and Unearned Income
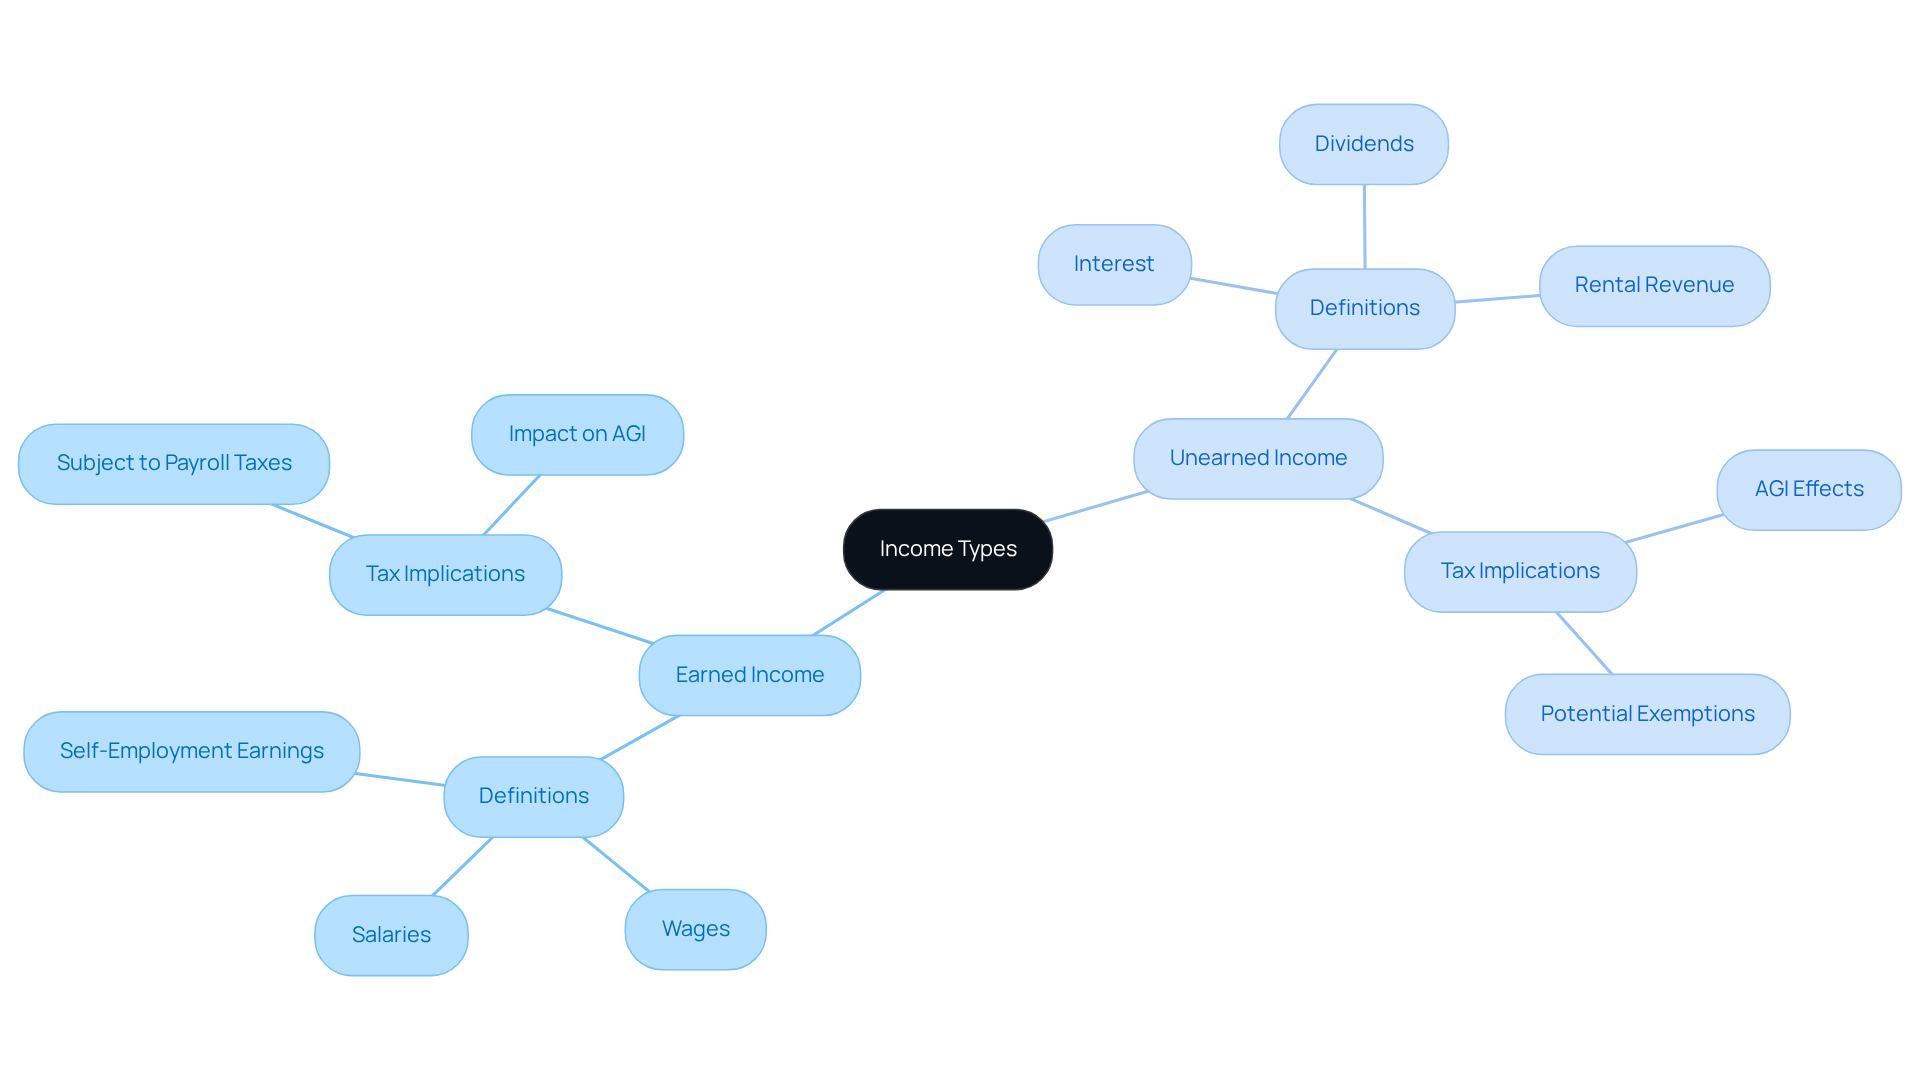
Imagine feeling confident about your family’s financial future, knowing exactly where your income comes from and how to manage it. Earned revenue refers to money received from active work, like salaries, wages, and self-employment earnings. On the other hand, unearned annual income is generated from investments or other non-active sources, such as interest, dividends, and rental revenue. Understanding these differences helps young parents see where their money comes from and how to manage it better.
It’s important to recognize that earned revenue is subject to payroll taxes, while passive income may have different tax implications. For instance, it might be exempt from Social Security and Medicare taxes but still affects your Adjusted Gross Earnings (AGI). As families navigate these complexities in 2026, understanding how unearned annual income can influence eligibility for tax credits like the Earned Income Tax Credit (EITC) becomes crucial. Without this knowledge, families may miss out on valuable tax credits and financial opportunities.
Take Jay and Emma, for example. They wanted to ease their financial stress while preparing for their children’s education and their retirement. By collaborating with Bright Advisers, they created a comprehensive strategy that enhanced their tax planning and explored education savings options. Similarly, Emily and Mark sought financial independence and worked with Bright Advisers to develop a plan that helped them manage their resources effectively while balancing their busy careers.
With tailored wealth management solutions, families like yours can confidently navigate the planning process, ensuring you’re ready for both today and tomorrow. By understanding these financial nuances, you can pave the way for a more secure and prosperous future for your family.
Explore Types of Unearned Income
Many families feel lost when it comes to understanding how to make their money work for them, often missing out on opportunities that could secure their financial future. Unearned annual income can take various forms, each offering distinct opportunities for families to enhance their economic stability. Key types include:
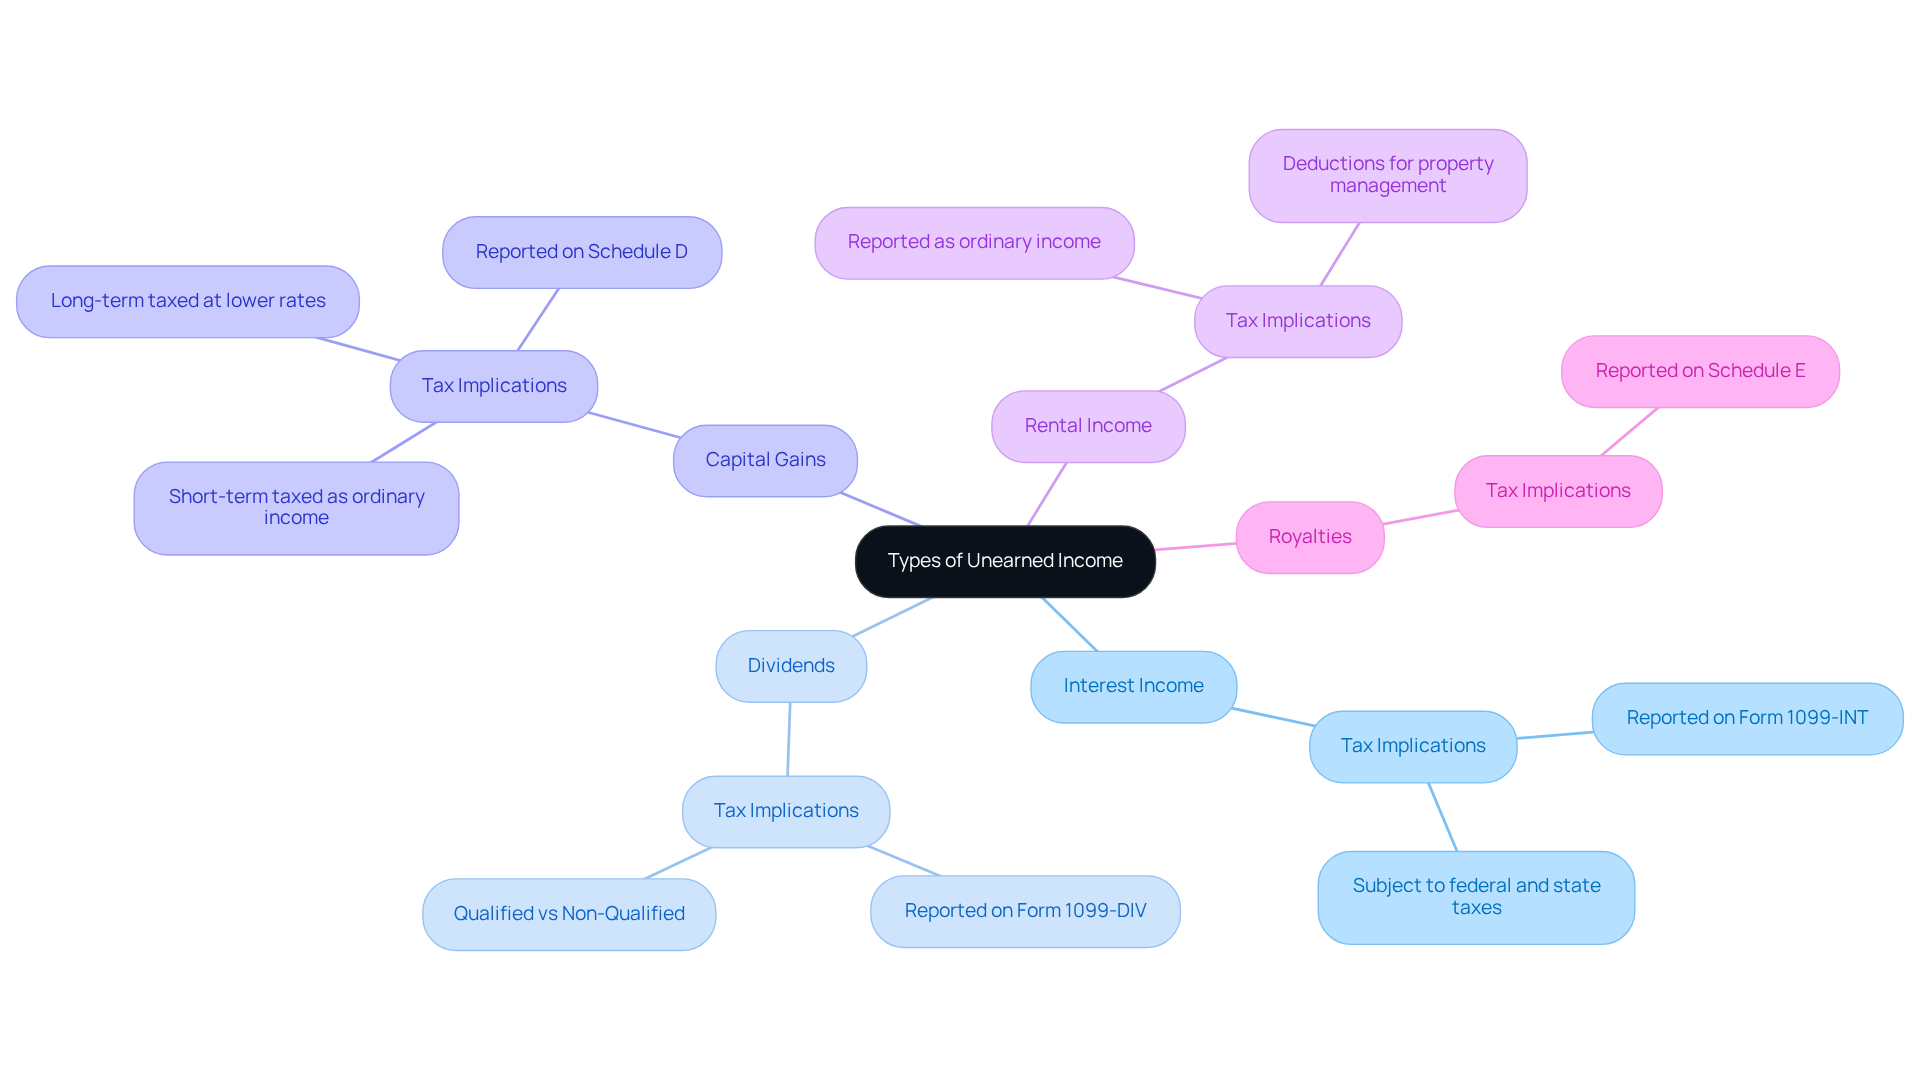
- Interest Income: This includes earnings from savings accounts, bonds, or certificates of deposit, providing a steady stream of revenue without active labor. Interest earnings are typically reported on Form 1099-INT and may be subject to federal and state taxes.
- Dividends: Corporations distribute a portion of their profits to shareholders, allowing families to benefit from their investments in stocks. These payments are reported on Form 1099-DIV and can be qualified or non-qualified, affecting the tax rate applied.
- Capital Gains: Profits realized from the sale of assets, such as stocks or real estate, can significantly contribute to a family’s economic growth. Short-term capital gains are taxed as ordinary income, while long-term capital gains may be taxed at lower rates, reported on Schedule D.
- Rental Income: When it comes to rental income, it’s important to know that you’ll need to report it, but you can also take advantage of deductions for managing and maintaining your property. This can serve as a reliable source of passive income, enhancing overall financial security.
- Royalties: Payments obtained for the utilization of intellectual property, such as books or patents, represent another method for generating passive revenue and are reported on Schedule E as well.
By learning about these revenue streams, families can take control of their finances and create a brighter future for their children through unearned annual income. For instance, Allison and Brian, a couple in their late 40s, sought the expertise of Bright Advisers to navigate the complexities of tax planning. Despite their remarkable earnings, they were oblivious to the monetary opportunities they were overlooking because of insufficient tax strategies. Through their collaboration, they optimized their tax situation, secured their children’s future through education funding, and gained the ability to retire sooner. This success narrative highlights the significance of strategic tax planning in maximizing wealth accumulation and attaining peace of mind. By understanding these revenue types, families can take proactive steps toward a more secure financial future, ensuring their children have the opportunities they deserve.
Understand Tax Implications of Unearned Income
Imagine facing unexpected tax bills just when you thought you had your family’s finances under control. Parents should understand the specific tax rules associated with unearned annual income to manage their family’s finances effectively.
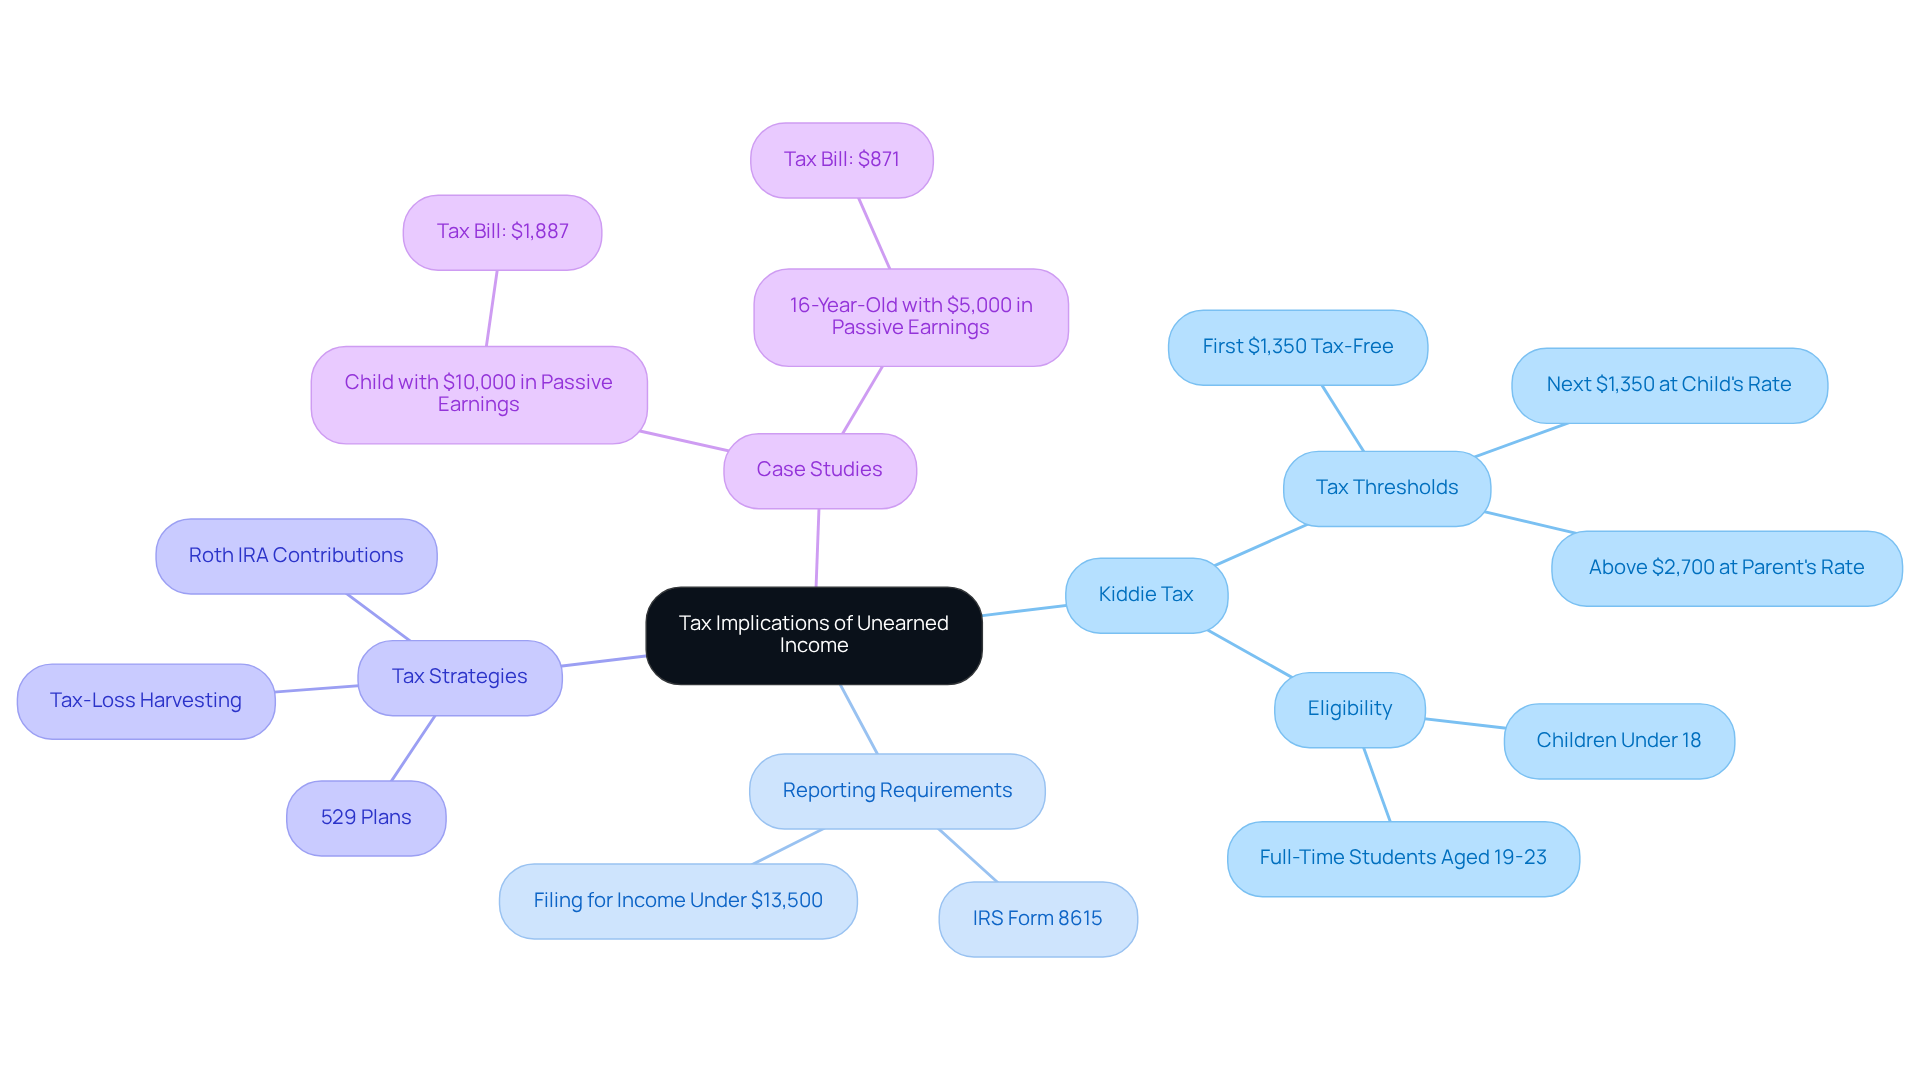
Kiddie Tax: If your child’s unearned income exceeds $2,700 in 2026, it may be taxed at your higher tax rate. This could lead to increased tax liabilities. The first $1,350 of non-earned revenue is tax-exempt, while the next $1,350 is taxed at your child’s rate, which might even be 0% depending on their total income.
Reporting Requirements: It’s important to report your child’s non-earned earnings using IRS Form 8615. This form helps calculate the tax owed on your child’s unearned annual income, ensuring compliance with tax regulations.
Tax Strategies: You might consider strategies like tax-loss harvesting or putting money into tax-friendly accounts, such as 529 plans, to help ease your tax burden. Bright Advisers emphasizes the importance of integrated tax planning, guiding families like Jay & Emma and Emily & Mark through these complexities. By creating tailored financial strategies, including retirement plans and education funding, Bright Advisers helps parents enhance their financial situations, ensuring they’re not caught off guard during tax season.
Case Studies: Picture this: a child with $10,000 in passive earnings could face a hefty tax bill of $1,887, thanks to the kiddie tax rules. It’s a reminder of how important it is to plan ahead. In another scenario, a 16-year-old with $5,000 in passive earnings would pay a total tax of $871, highlighting the significance of strategic planning to handle tax consequences.
By being aware of these tax implications, you can confidently make choices that protect your family’s financial well-being, aligning with your long-term wealth management goals.
Implement Strategies for Managing Unearned Income
Imagine feeling secure about your family’s financial future, even when it comes to unearned annual income. To effectively manage this aspect, parents can implement a few thoughtful strategies:
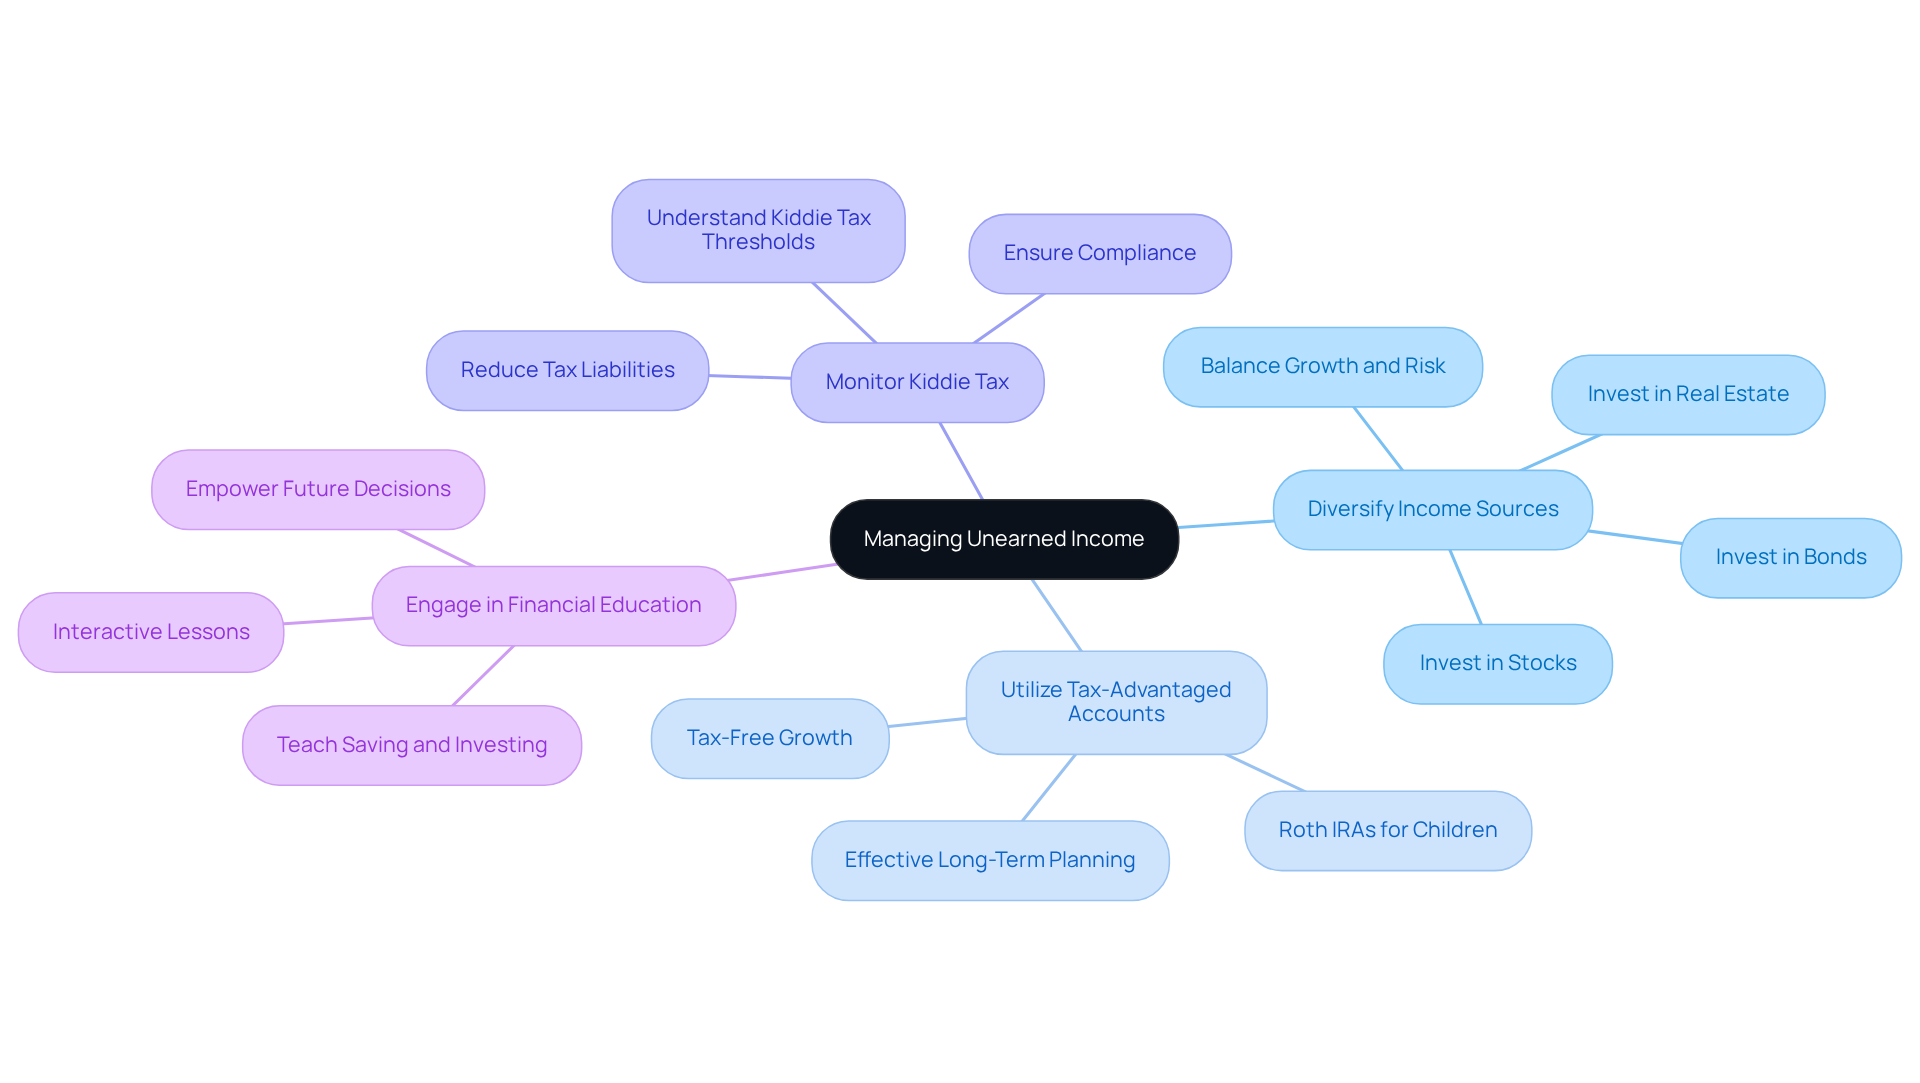
- Diversify Income Sources: Explore various forms of unearned income, like investments in stocks, bonds, or real estate. This way, you can feel more secure knowing your investments are balanced and have the potential to grow. Jay and Emma, supported by Bright Advisers, successfully diversified their investments, balancing growth potential and risk management.
- Utilize Tax-Advantaged Accounts: Consider using accounts like Roth IRAs for children, which allow for tax-free growth and withdrawals in retirement. This can significantly benefit long-term monetary planning and wealth accumulation. At Bright Advisers, we believe in making tax planning simple and effective for families like yours.
- Monitor your child’s unearned annual income to ensure it does not exceed the kiddie tax thresholds, which can lead to higher tax rates. Navigating tax rules can feel overwhelming, especially when it comes to your child’s earnings. For 2024, the yearly non-earned revenue limit for the kiddie tax is $2,600, making it essential for effective tax strategy and reducing liabilities. Jay and Emma’s monetary strategy involved careful observation of their earnings to ensure compliance and enhance their tax situation.
- Engage in Financial Education: Teach children about managing unearned income through interactive lessons, helping them understand the value of saving and investing. This foundational knowledge empowers them to make informed monetary decisions in the future. Bright Advisers motivates families to participate in economic education as part of their comprehensive planning strategy.
When you embrace these strategies, you’re not just improving your financial knowledge; you’re securing a brighter future for your family. Additionally, understanding the implications of the kiddie tax, as highlighted in the case study on its impact on family financial planning, can further guide families in making informed decisions. Bright Advisers, founded by Kevin Luu and Kathleen Chou in 2010, is dedicated to helping families make wise wealth decisions and preserve wealth across generations.
Conclusion
But navigating the world of finances can feel overwhelming, especially when you’re trying to balance family needs and future goals. Understanding unearned annual income is a key step for young parents looking to secure their family’s financial future. When you understand the difference between earned and unearned income, it becomes easier to make choices that support your family’s future. This knowledge helps you tap into different income sources and make smart tax choices that can benefit your family.
We’ve explored various types of unearned income – like interest, dividends, and rental income – and what they mean for your family’s finances. Real families have seen how smart planning with Bright Advisers can make a real difference in managing their unearned income. By taking thoughtful steps, you can explore different income options and use tax-friendly accounts to prepare for what’s ahead.
Mastering unearned income isn’t just about numbers; it’s about building a meaningful future for your family. With the right support from advisors like Bright Advisers, you can feel confident in managing your family’s wealth. Together, let’s take steps to ensure your family’s financial well-being and give your children the resources they need to flourish. For personalized support, reach out to Bright Advisers at hello@brightadvisers.com or call (714) 987-2967.
Frequently Asked Questions
What is earned income?
Earned income refers to money received from active work, such as salaries, wages, and self-employment earnings.
What is unearned income?
Unearned income is generated from investments or other non-active sources, including interest, dividends, and rental revenue.
Why is it important to understand the difference between earned and unearned income?
Understanding the differences helps individuals manage their finances better and recognize how various income types can affect tax implications and eligibility for tax credits.
How are earned and unearned income taxed differently?
Earned income is subject to payroll taxes, while unearned income may have different tax implications, such as being exempt from Social Security and Medicare taxes but still affecting Adjusted Gross Income (AGI).
What is the Earned Income Tax Credit (EITC)?
The Earned Income Tax Credit (EITC) is a tax credit that can benefit low to moderate-income working families, and understanding how unearned income influences eligibility for this credit is crucial for maximizing financial opportunities.
How can families benefit from working with financial advisors like Bright Advisers?
Families can create comprehensive strategies for tax planning, education savings, and effective resource management, helping them navigate financial complexities and prepare for future needs.
What is the mission of Bright Advisers?
Bright Advisers aims to help families make wise wealth decisions and preserve wealth across generations through tailored wealth management solutions.
List of Sources
- Define Earned and Unearned Income
- What is Unearned Income and Is It Taxable? Guide 2026 (https://taxesforexpats.com/articles/expat-tax-rules/what-is-unearned-income-vs-earned-income.html)
- 12 Financial Planning Quotes for Building Wealth Wisely — Phillip James Financial (https://phillipjamesfinancial.com/blog/12-financial-planning-quotes-for-building-wealth-wisely)
- The Earned Income Tax Credit (https://cbpp.org/research/policy-basics-the-earned-income-tax-credit)
- Sources of Personal Income, Tax Year 2018 (https://taxfoundation.org/data/all/federal/personal-income-pi-data)
- Explore Types of Unearned Income
- 25 Best Passive Income Quotes For High Earners (https://debtfreedr.com/passive-income-quotes-2)
- 47 Passive Income Quotes That Will Change How You Think About Money (https://deliberatedirections.com/passive-income-quotes-build-wealth)
- What is Unearned Income and Is It Taxable? Guide 2026 (https://taxesforexpats.com/articles/expat-tax-rules/what-is-unearned-income-vs-earned-income.html)
- Sources of Personal Income, Tax Year 2022 (https://taxfoundation.org/data/all/federal/personal-income-tax-returns-data-2026)
- Understand Tax Implications of Unearned Income
- What Is the Kiddie Tax? Kiddie Tax Rules | U.S. Bank (https://usbank.com/wealth-management/financial-perspectives/financial-planning/kiddie-tax.html)
- The Kiddie Tax: Rates, Limits and Rules for 2026 (https://smartasset.com/taxes/kiddie-tax)
- What Parents Need to Know About the Kiddie Tax | Kirsch CPA Firm Cincinnati (https://kirschcpa.com/accounting-services-blog/what-parents-need-to-know-about-the-kiddie-tax)
- The “kiddie tax” can apply long after childhood (https://cpabr.com/alert-kiddie-tax)
- Implement Strategies for Managing Unearned Income
- 40 quotes to help your child learn the value of money | GoHenry (https://gohenry.com/us/blog/financial-education/40-quotes-to-help-your-child-learn-the-value-of-money)
- Taxing Teens: Working Children, Family Businesses, and the Kiddie Tax | Baker Institute (https://bakerinstitute.org/research/taxing-teens-working-children-family-businesses-and-kiddie-tax)
- Tips to Minimize the Kiddie Tax (https://blog.ssb-cpa.com/news/tips-to-minimize-the-kiddie-tax)

Kevin has advised high-income W-2 tech and biotech families since 2015, and leads the education-first Age Five Family Office from Brea, California.
Connect on LinkedIn → · About KevinThis is part of how we approach Age Five Wealth Education for high-income W-2 families at Bright Advisers.
Keep reading