

Key Highlights
- Unitrust distributions provide flexible income to beneficiaries based on a percentage of the trust’s assets, which varies annually.
- They offer a reliable income stream while preserving principal for future generations, making them ideal for families.
- Understanding unitrust distributions helps families manage wealth and promote harmony in asset allocation.
- Allocations are based on a minimum payout percentage, typically set at 5%, with annual revaluation of trust assets.
- Distributions are taxed in a specific order, allowing for potential tax efficiency in financial planning.
- Unitrusts play a crucial role in legacy planning, ensuring wealth is preserved for future generations.
- Implementing unitrust distributions involves engaging a fiduciary advisor, creating a trust, funding it, and regularly assessing its performance.
- Involving children in understanding the trust fosters financial literacy and prepares them for future responsibilities.
Introduction
Imagine feeling overwhelmed by financial planning while trying to secure a bright future for your family. Unitrust distributions can be a lifeline for families. They provide a flexible income stream that adjusts with the value of trust assets, helping families meet both immediate needs and long-term goals. But it’s important to understand how these distributions work.
- How can families use unitrusts to boost their wealth management strategies?
- What steps can families take to make sure these distributions align with their financial dreams?
With the right support, you can transform financial uncertainty into a clear path toward your family’s dreams.
Define Unitrust Distributions and Their Importance for Families
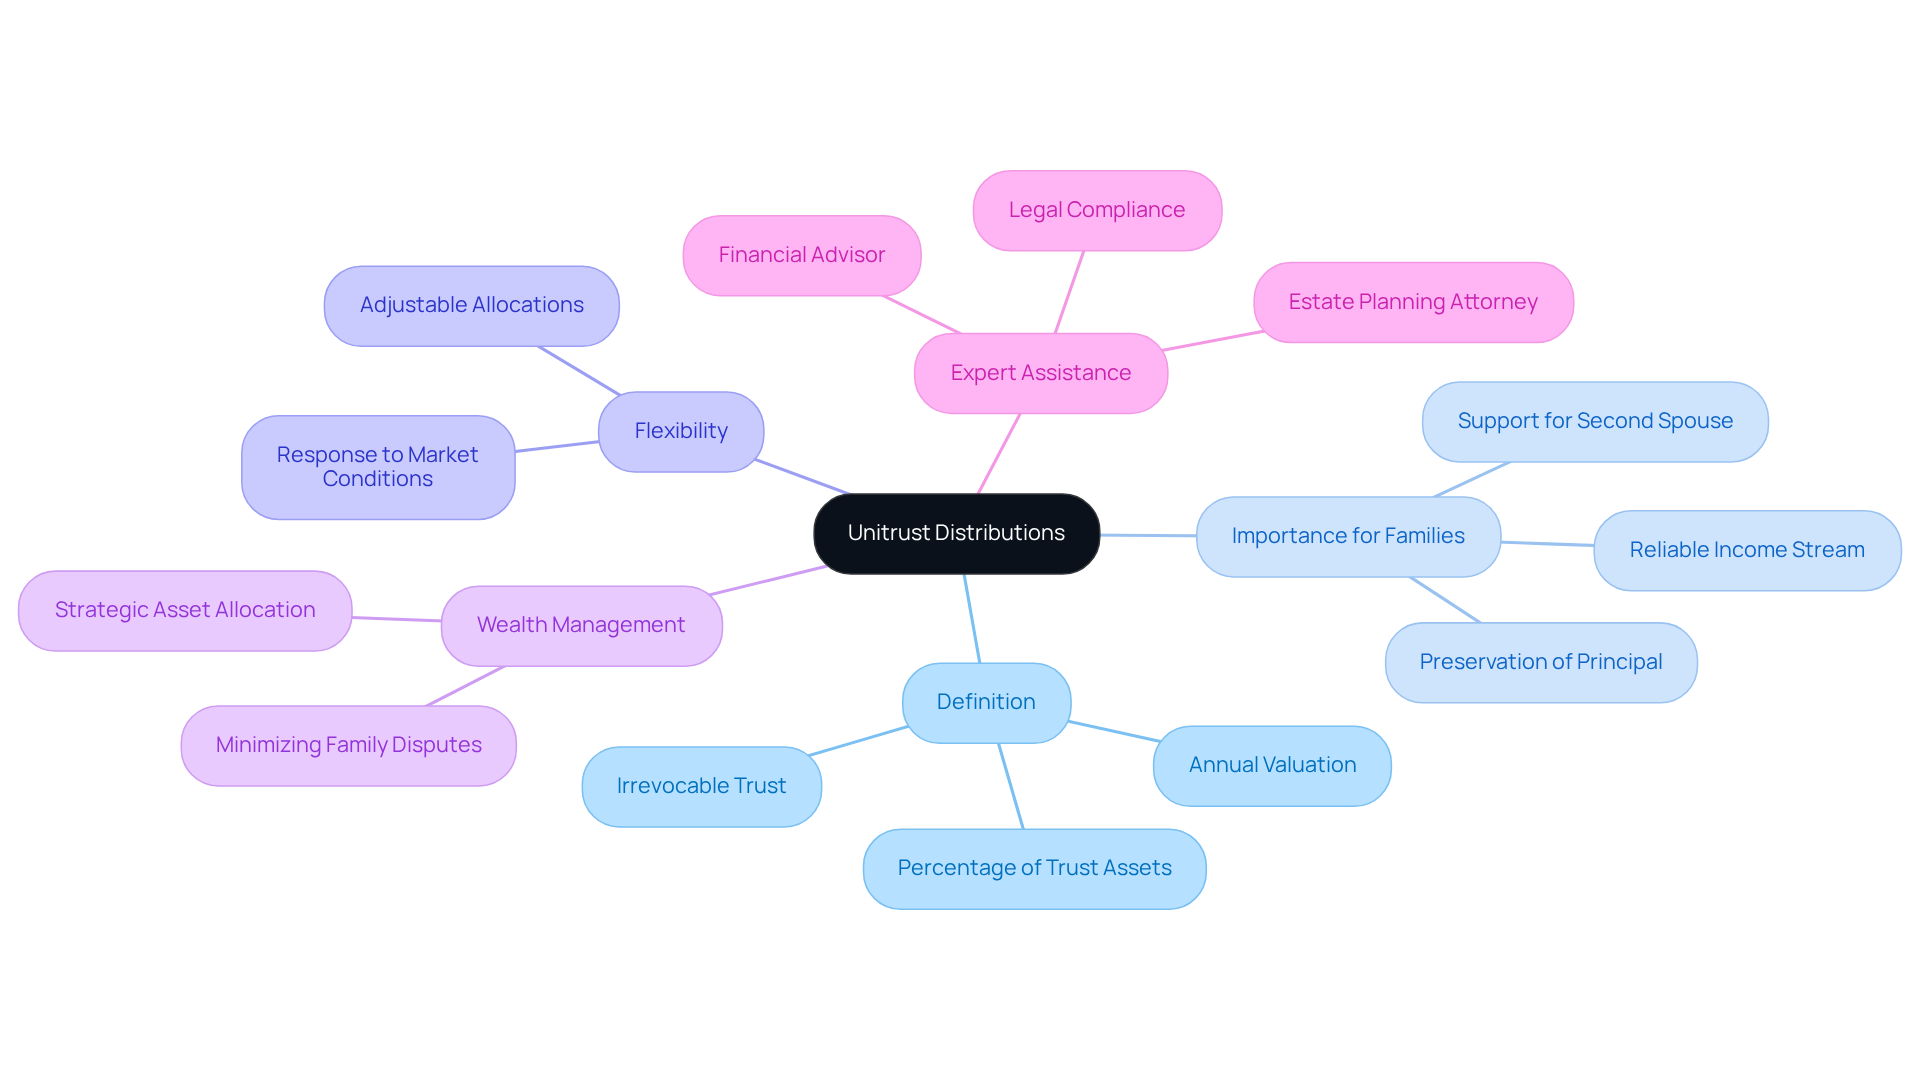
Imagine navigating the complexities of financial planning while ensuring your family’s future is secure and bright. Unitrust distribution consists of the sums given to beneficiaries from a unitrust, which is a specific type of irrevocable trust. In contrast to traditional trusts that give fixed amounts, the unitrust distribution provides a percentage of the trust’s assets, which changes each year based on its value. This means that as the trust’s value fluctuates, so do the allocations, resulting in a more flexible income generation strategy.
For households, especially those with young kids, understanding unitrust distribution allocations is essential. They offer a reliable income stream while preserving the principal for future generations. This flexibility is particularly advantageous as it enables families to adjust their unitrust distribution according to changing financial needs and market conditions.
Imagine a family using unitrusts to ensure both a second spouse is cared for and children receive their rightful inheritance after a loss. This strategic approach not only helps in managing and preserving wealth but also promotes harmony by clearly defining asset allocation.
Working with expert consultants can make setting up a trust smoother, ensuring it meets legal requirements while reflecting your family’s goals. Creating a trust at the right time, preferably when you’re in good health and mentally stable, can lead to better asset management and realization of your wishes regarding allocation.
By understanding trust payouts, you can take confident steps toward securing your family’s financial future, knowing you’re not alone in this journey.
Explain How Unitrust Distributions Work: Calculation and Rules
Imagine feeling overwhelmed by financial responsibilities while trying to secure your family’s future. The allocations for unitrust distribution are based on a set percentage of the trust’s value, which is reviewed each year. The minimum payout percentage is typically set at 5%. For example, if a unitrust has a value of $1,000,000, a 5% payout would generate $50,000 for that year. The rules governing these distributions include:
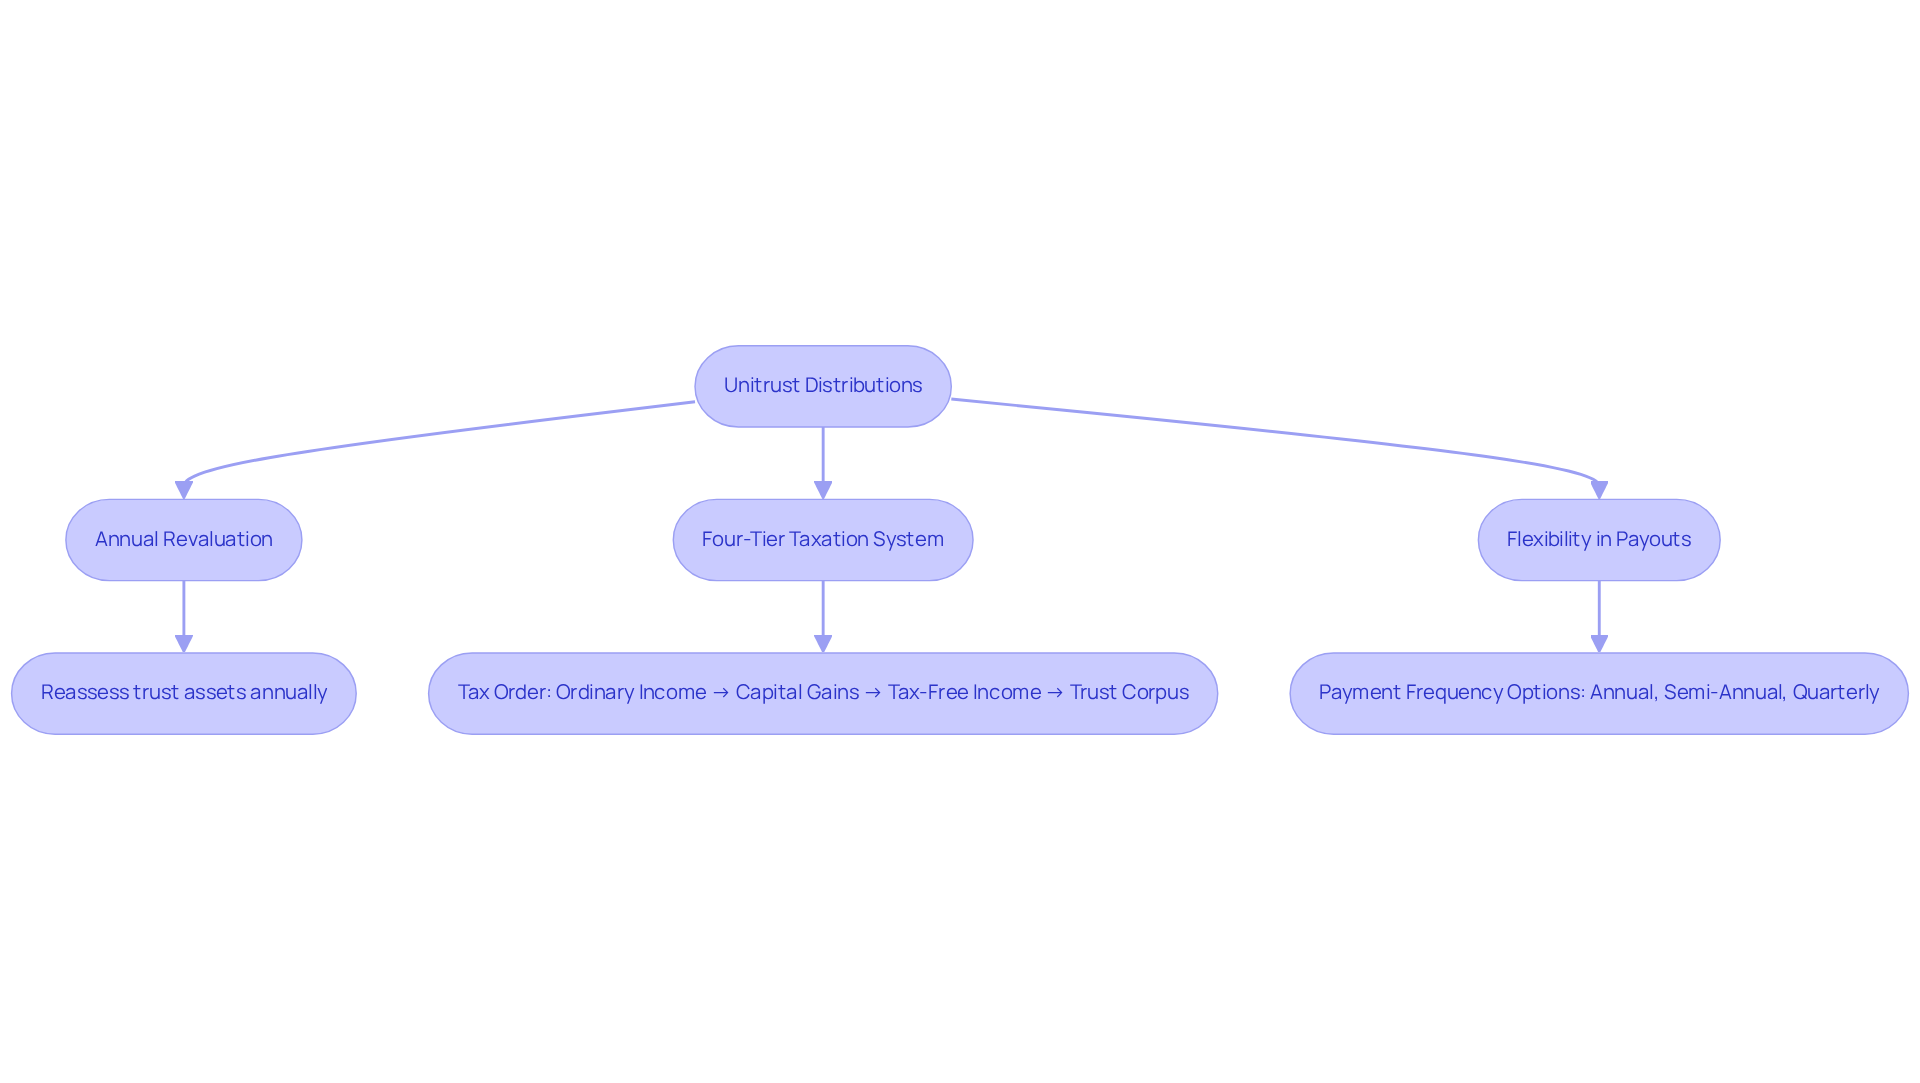
- Annual Revaluation: The trust’s assets are reassessed each year to determine the payout amount, ensuring that disbursements reflect the current value of the trust.
- Four-Tier Taxation System: Distributions are taxed in a specific order: ordinary income, capital gains, tax-free income, and finally, trust corpus.
- Flexibility in Payouts: Beneficiaries can receive payments annually, semi-annually, or quarterly, depending on the trust agreement. This adaptability enables households to coordinate allocations with their monetary requirements.
We understand that young parents, like you, face unique financial challenges every day. Families can optimize their financial strategies by effectively leveraging unitrust distributions, ensuring they meet both immediate needs and long-term goals. For instance, Jay and Emma successfully navigated funding their children’s education while planning for retirement, achieving a balance between their present responsibilities and future aspirations. Likewise, Emily and Mark obtained the liberty to decide whether to keep working by applying strategies that matched their monetary goals. Through personalized planning, integrated tax optimization, and a focus on customized wealth management solutions, Bright Advisers empowers households to secure their economic futures and enjoy peace of mind. With the right guidance, you can transform your financial worries into a roadmap for a secure future for your family.
Discuss the Impact of Unitrust Distributions on Financial Planning
Imagine trying to budget for your family’s future without a steady income stream – it’s a daunting challenge, isn’t it? Unitrust distributions can significantly influence a family’s financial planning in several key areas:
-
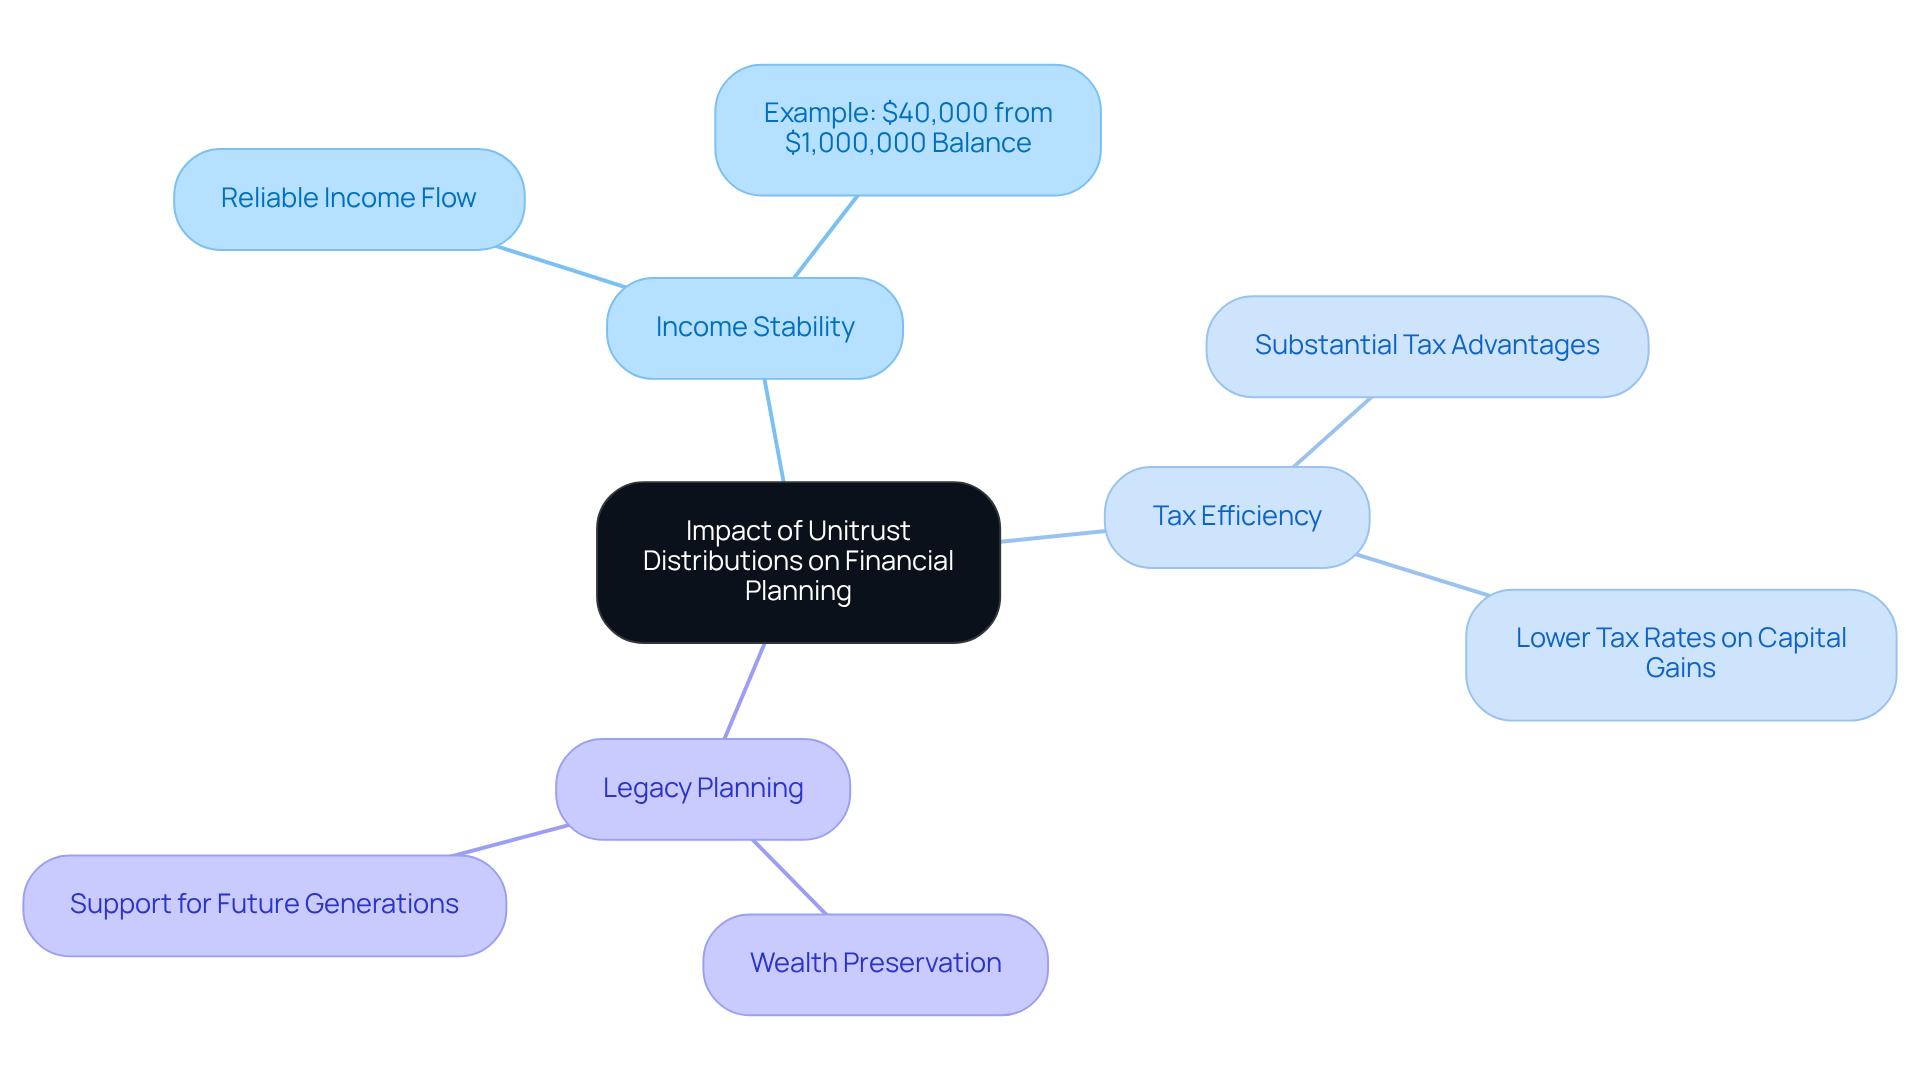
Income Stability: Unitrusts offer a reliable income flow, which is crucial for households to budget effectively. This stability helps cover your ongoing expenses and makes it easier to plan for the future. Imagine a family with a $1,000,000 balance receiving $40,000 each year from a unitrust – this steady income can make all the difference in their financial planning.
-
Tax Efficiency: The structured payout system of unitrusts can offer substantial tax advantages. This can be a game-changer for families looking to make the most of their money while easing their tax worries. Families can manage their tax liabilities more effectively, as capital gains distributions may be taxed at lower rates compared to ordinary income.
-
Legacy Planning: Unitrusts play a vital role in estate planning, ensuring that wealth is preserved and passed down to future generations. This is especially significant for households with young kids, as it enables them to create a legacy that supports their children’s future. When families include unitrusts in their financial plans, they’re not just securing their future – they’re building a legacy for their children.
Case studies highlight the effectiveness of unitrust distribution in both estate and charitable planning. For example, one study showed that beneficiaries of unitrusts not only received dependable income streams but also enjoyed tax advantages that improved their overall economic well-being. This dual purpose of generating income while aiding charitable causes illustrates the strategic benefits of unitrusts in financial planning for households.
By considering a secure financial future for your family, you can ensure their needs are met today and tomorrow through unitrust distributions.
Outline Steps for Implementing Unitrust Distributions in Family Wealth Management
Imagine the peace of mind that comes from knowing your family’s financial future is secure, even in uncertain times. Implementing unitrust distributions in your family’s wealth management strategy involves several essential steps:
-
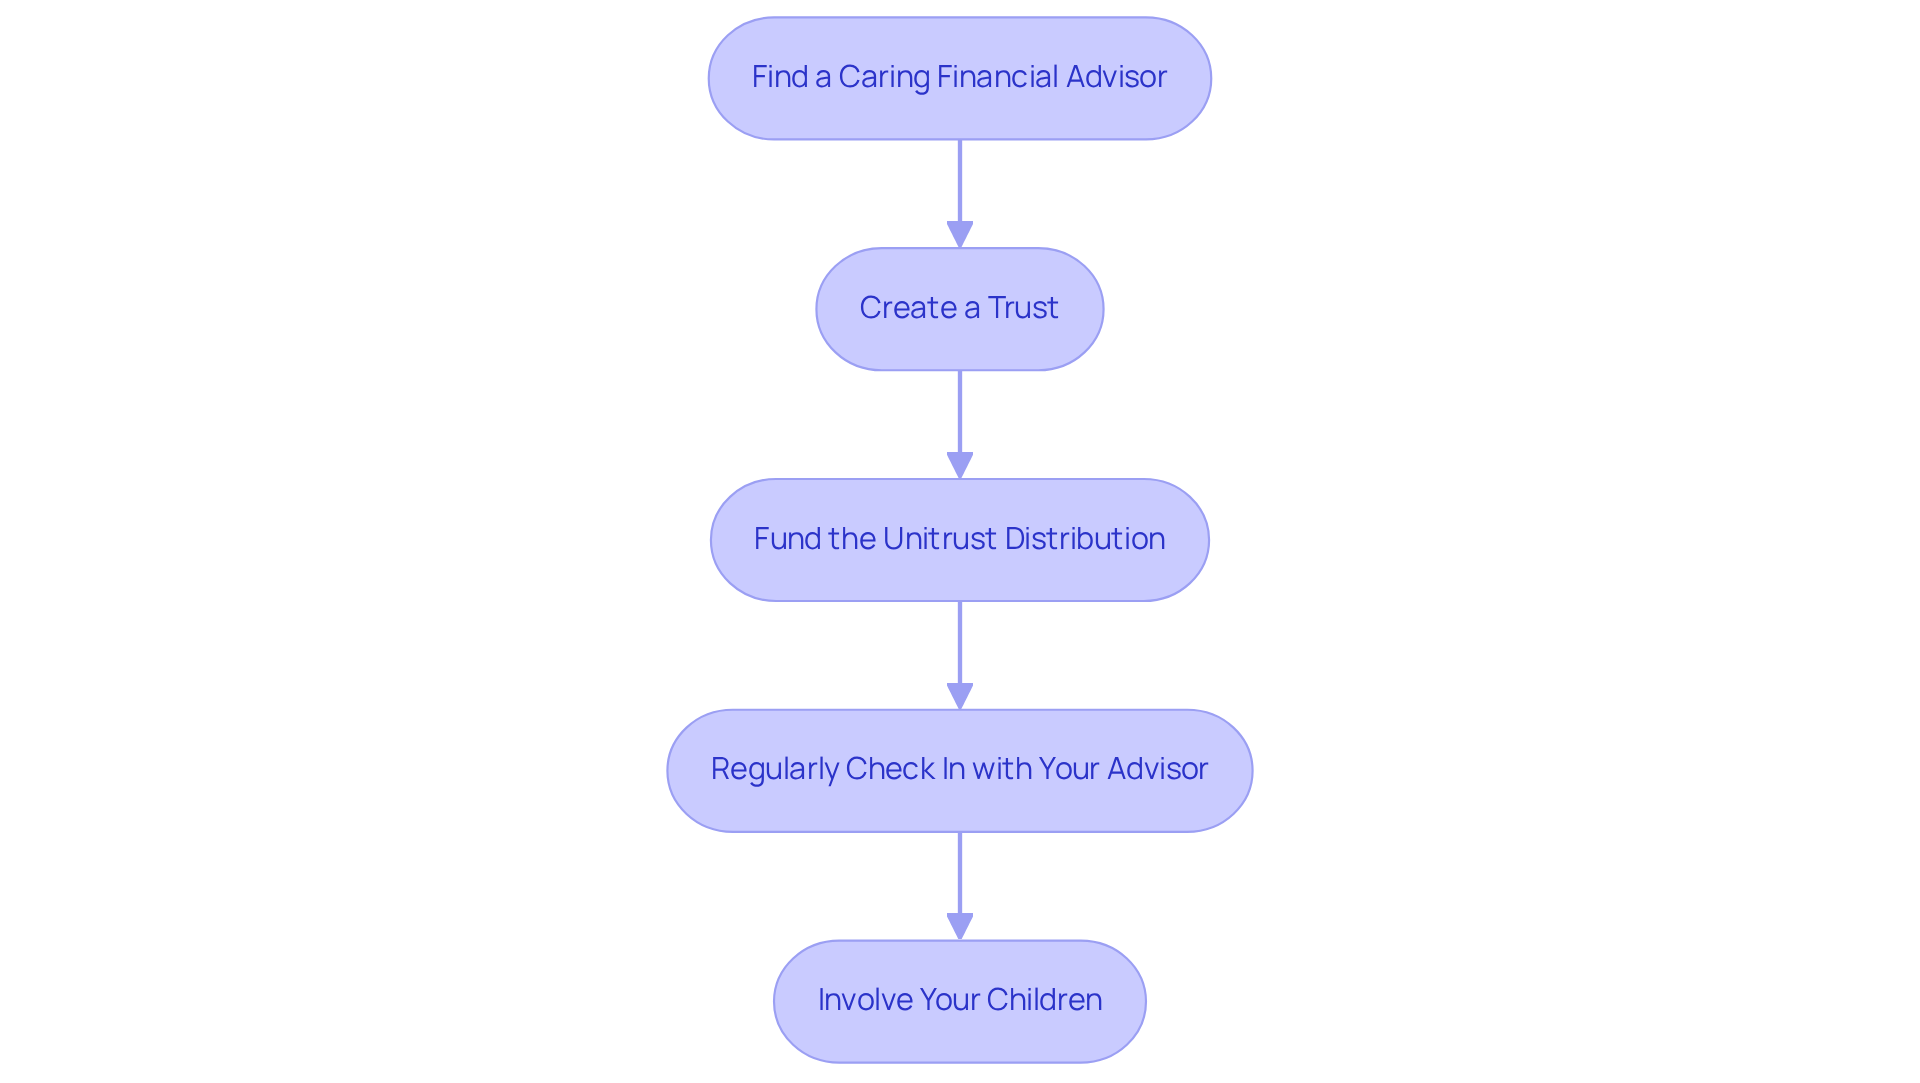
Let’s start by finding a caring financial advisor: Engage with a fiduciary advisor who understands your family’s unique needs and goals. This partnership ensures that your household’s monetary aspirations are prioritized.
-
Together, let’s create a trust: Collaborate with legal experts to develop a trust that reflects your family’s values and goals. This includes determining the payout percentage, which should be tested against expected investment returns and beneficiary needs, and selecting a trustee who can effectively manage the trust.
-
Think of funding the unitrust distribution as planting seeds for your family’s future prosperity: Transfer assets into the unitrust, which can include cash, stocks, or real estate. This step is crucial for generating the income stream that will support both current beneficiaries and future charitable interests.
-
Regularly check in with your advisor: Assess the trust’s performance and distributions to ensure it continues to meet your household’s needs. Modify the payout percentage if needed to match evolving economic conditions, such as market fluctuations or household dynamics.
-
Involve your children in understanding the trust: This not only fosters financial literacy but also prepares them for future responsibilities regarding family wealth, ensuring a smoother transition of financial knowledge across generations.
By taking these steps, you’re not just planning for today; you’re building a legacy of financial wisdom for your children to inherit.
Conclusion
Imagine feeling secure about your family’s financial future, knowing that your wealth can grow and support your children for years to come. Unitrust distributions can be a lifeline for families, especially those with young kids, helping you feel secure in your financial journey. They provide a flexible income that grows with your family’s needs, giving you peace of mind today while protecting your wealth for tomorrow.
When you understand how unitrusts work, you can make choices that truly support your family’s dreams and goals. We’ve shared important insights about how unitrust distributions work, including their benefits for your family’s financial planning. With the stability and tax benefits of unitrusts, families can manage their finances with more confidence and ease.
We’ve seen families just like yours successfully use unitrust distributions to create personalized financial plans that work for them. Understanding unitrust distributions is crucial for your family’s financial well-being. When you take steps to understand and use these strategies, you can build a secure future and a legacy of care for your children.
Working with a caring advisor, like Bright Advisers, can guide your family through this journey, making sure your financial dreams are met with understanding and support. Together, we can take steps towards a brighter financial future for your family.
Frequently Asked Questions
What are unitrust distributions?
Unitrust distributions are sums given to beneficiaries from a unitrust, which is a specific type of irrevocable trust. Unlike traditional trusts that provide fixed amounts, unitrust distributions offer a percentage of the trust’s assets, which varies each year based on the trust’s value.
Why are unitrust distributions important for families?
Unitrust distributions provide a reliable income stream while preserving the principal for future generations. They offer flexibility, allowing families to adjust distributions according to changing financial needs and market conditions.
How can unitrusts benefit families with young children?
Unitrusts can ensure that both a second spouse is cared for and that children receive their rightful inheritance after a loss. This strategic approach helps manage and preserve wealth while promoting harmony through clear asset allocation.
What should families consider when setting up a unitrust?
Families should work with expert consultants to ensure the trust meets legal requirements and reflects their goals. It’s advisable to create a trust when in good health and mentally stable for better asset management and realization of wishes regarding allocation.
How do unitrust distributions adapt to market conditions?
Since unitrust distributions are based on a percentage of the trust’s assets, they fluctuate with the trust’s value. This means that as market conditions change, so do the allocations, providing a more flexible income generation strategy.
What role do trust payouts play in financial planning?
Understanding trust payouts is crucial for securing a family’s financial future. It allows families to make informed decisions about wealth management and ensures that their financial goals are met.
List of Sources
- Define Unitrust Distributions and Their Importance for Families
- Understanding Unitrusts (https://tfginvest.com/insights/understanding-unitrusts?hs_amp=true)
- Charitable Remainder Unitrust | Wilson Edu (https://wilson.edu/charitable-remainder-unitrust)
- Trusts and the Benefits of Giving Back (https://legacyofpeace.afsc.org/charitable-remainder-trusts)
- GiftLaw Pro, our charitable tax reference service, features detailed information on gift and estate planning strategies. It includes links to relevant Internal Revenue code sections, regulations, rulings, cases and more. (https://giving.americanhumane.org/giftlawpro/glawpro_subsection.jsp?CC=3&SS=10&SS2=1)
- Unitrust Distributions | Definition, Creation, Calculation, & Factors (https://financestrategists.com/estate-planning-lawyer/trusts/unitrust-distributions)
- Explain How Unitrust Distributions Work: Calculation and Rules
- GiftLaw Pro, our charitable tax reference service, features detailed information on gift and estate planning strategies. It includes links to relevant Internal Revenue code sections, regulations, rulings, cases and more. (https://giving.americanhumane.org/giftlawpro/glawpro_subsection.jsp?CC=3&SS=10&SS2=4)
- Charitable Remainder Unitrust | Strategic Giving | Case Western Reserve University (https://plannedgiving.case.edu/how-you-can-give/giving-and-generating-income/charitable-remainder-unitrust)
- Unitrust Distributions | Definition, Creation, Calculation, & Factors (https://financestrategists.com/estate-planning-lawyer/trusts/unitrust-distributions)
- Understanding Unitrusts (https://tfginvest.com/insights/understanding-unitrusts?hs_amp=true)
- Discuss the Impact of Unitrust Distributions on Financial Planning
- Unitrust Distributions | Definition, Creation, Calculation, & Factors (https://financestrategists.com/estate-planning-lawyer/trusts/unitrust-distributions)
- Taxation of Unitrust Distributions | SharpeNet – Web That Works (https://sharpenet.givingplan.net/charitable-remainder-unitrust-presentation/taxation-unitrust-distributions)
- Total Return Unitrust Promotes Smooth Sailing (https://probate-florida.com/blog/2016/may/total-return-unitrust-promotes-smooth-sailing)
- Outline Steps for Implementing Unitrust Distributions in Family Wealth Management
- Unitrusts To the Rescue (https://wealthmanagement.com/estate-planning/unitrusts-to-the-rescue)
- What Is a Unitrust? NJ Trust Planning | Simon Law Group, LLC (https://simonattorneys.com/estate-planning/what-is-a-unitrust)
- Total Return Unitrust Promotes Smooth Sailing (https://probate-florida.com/blog/2016/may/total-return-unitrust-promotes-smooth-sailing)
- Unitrust Distributions | Definition, Creation, Calculation, & Factors (https://financestrategists.com/estate-planning-lawyer/trusts/unitrust-distributions)
- Understanding Unitrusts (https://tfginvest.com/insights/understanding-unitrusts?hs_amp=true)

Kevin has advised high-income W-2 tech and biotech families since 2015, and leads the education-first Age Five Family Office from Brea, California.
Connect on LinkedIn → · About KevinThis is part of how we approach Age Five Wealth Education for high-income W-2 families at Bright Advisers.
Keep reading