

Overview
Imagine being able to ease the financial burden of childcare while maximizing your savings. The journey of parenthood brings immense joy, but it can also come with financial challenges. By utilizing both a Dependent Care Flexible Spending Account (DCFSA) and the Child Tax Credit (CTC), families can take significant steps towards a more secure financial future.
Setting aside pre-tax funds for childcare expenses through a DCFSA allows families to manage their budgets more effectively. Coupled with claiming the CTC for any remaining eligible expenses, this strategy can lead to a remarkable reduction in taxable income. In fact, families can save approximately $625 to $875 annually.
It’s important to understand that strategic financial planning is not just about numbers; it’s about creating a nurturing environment for your loved ones. By taking these steps, you are not only investing in your children’s care but also in your family’s overall well-being.
Together, we can navigate this journey of financial planning. Remember, we’re here for you, ready to support you in making the most of your resources. Let’s work towards a brighter, more secure future for your family.
Key Highlights:
- A DCFSA allows families to set aside pre-tax funds for qualified dependent care costs, reducing taxable income.
- Contribution limits are $5,000 per household until 2025, increasing to $7,500 starting January 1, 2026.
- Eligible expenses include daycare, preschool, and summer camps for children under 13 years old.
- Utilising a DCFSA can save families approximately $625 to $875 annually on taxes.
- To qualify for the Child Tax Credit in 2025, children must be under 17, U.S. citizens, and meet support and residency criteria.
- The maximum Child Tax Credit in 2025 is $2,200 per eligible child, with phase-out thresholds based on income.
- Families can combine DCFSA contributions and Child Tax Credit claims for maximum savings, but cannot use the same expenses for both.
- Statistical examples show significant tax savings for families utilising both financial tools effectively.
Introduction
Navigating the complexities of childcare expenses can feel overwhelming for families, especially as costs continue to rise. Imagine if you could find a way to ease that burden. Understanding how to leverage a Dependent Care Flexible Spending Account (DCFSA) alongside the Child Tax Credit can unlock significant savings. By strategically utilizing these financial tools, families can reduce their taxable income and potentially save hundreds, if not thousands, of dollars each year.
It’s important to understand that these options are designed to support you. However, how can parents ensure they are maximizing these benefits without falling into common pitfalls? Together, we can navigate this journey, ensuring that you make the most of the resources available to you.
Understand the Dependent Care FSA Basics
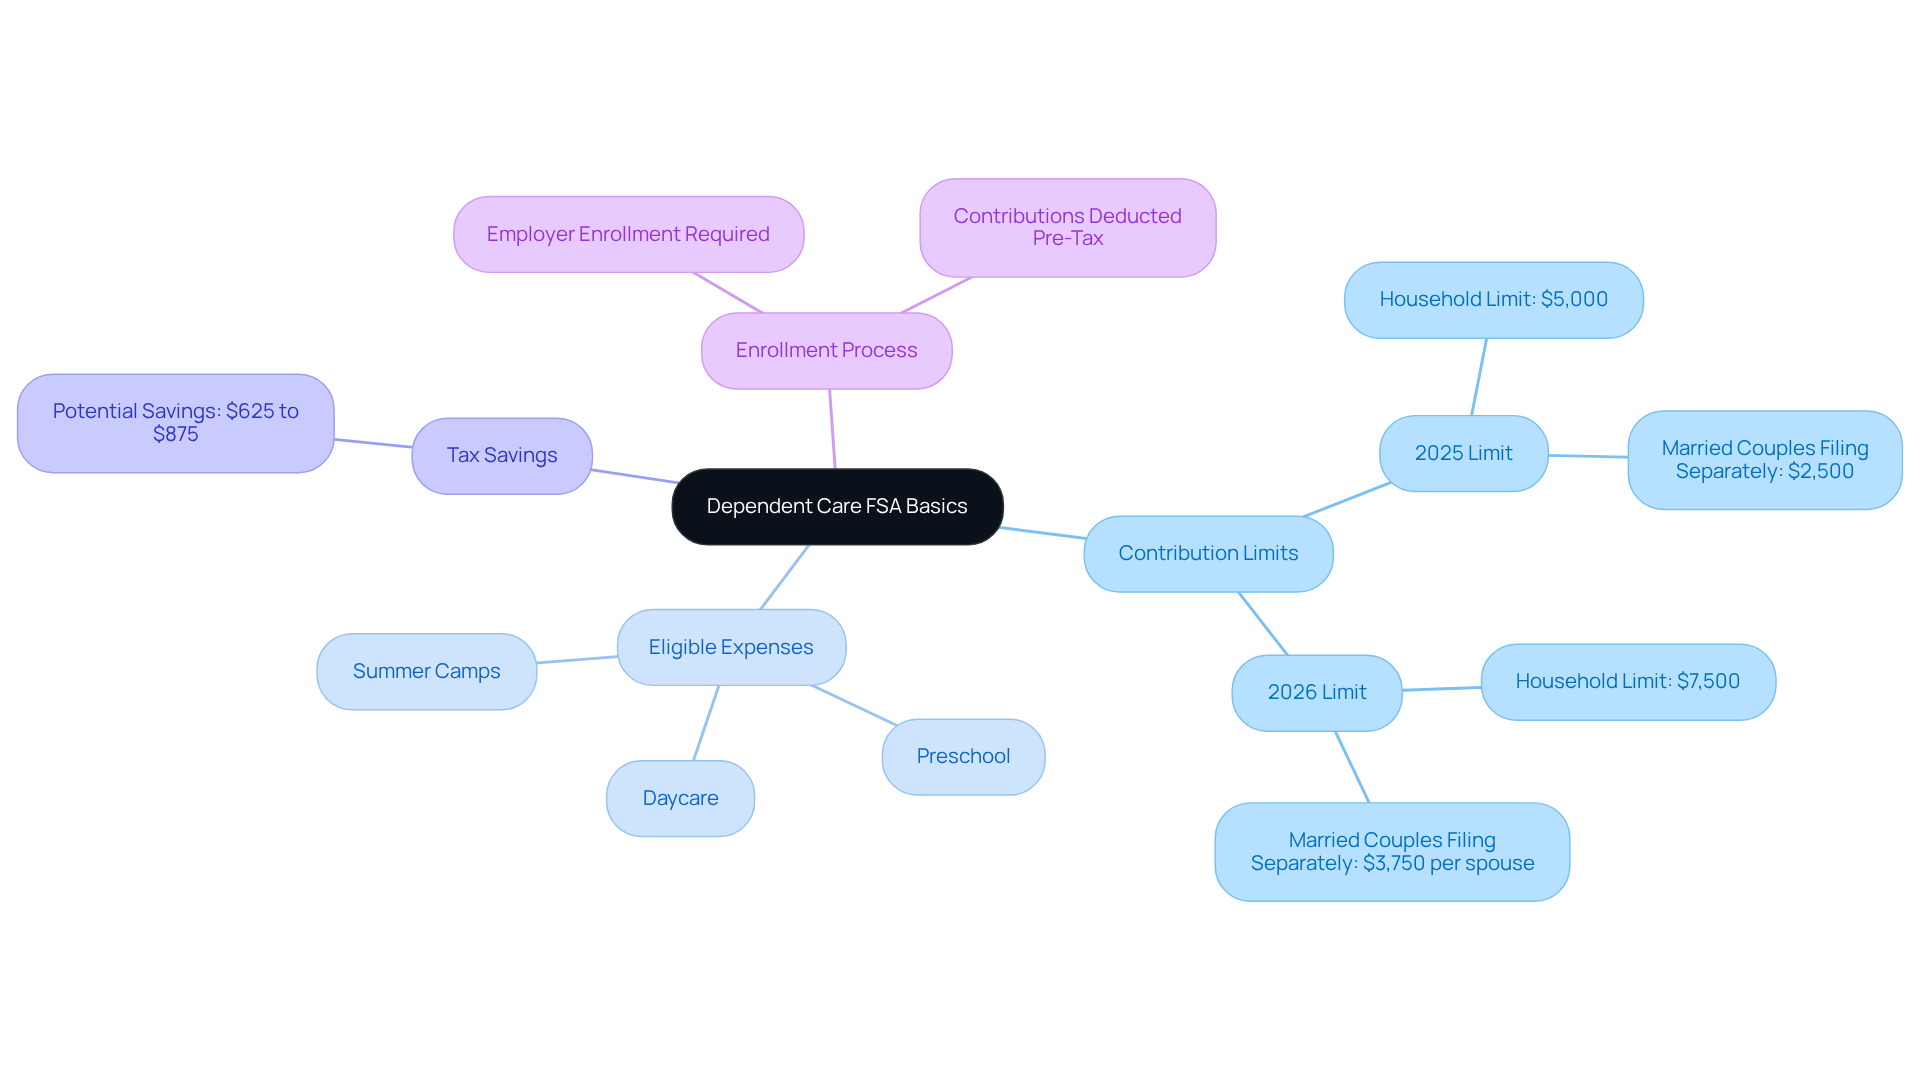
A Dependent Care Flexible Spending Account (DCFSA) can be a game changer for families when combined with the dependent care FSA and child tax credit, allowing you to set aside pre-tax funds from your paycheck specifically for qualified dependent care costs. Imagine being able to contribute up to $5,000 per household in 2025—or $2,500 for married couples filing separately. And there’s good news! Starting January 1, 2026, this limit will increase to $7,500, giving you even more opportunities to save on essential expenses.
Think about the eligible expenses: daycare, preschool, and summer camps for children under 13 years old. These costs are often necessary for you and your spouse to work or seek employment, and they can add up quickly. By contributing to a dependent care FSA and utilizing the child tax credit, you effectively lower your taxable income, which can lead to significant tax savings. In fact, households can save around $625 to $875 each year, providing crucial support as childcare expenses continue to rise.
It’s important to consider minimal fund fees in your overall financial planning as well, as they can further enhance your savings strategy. To take advantage of a DCFSA, enrollment through your employer is required, with contributions deducted from your paycheck before taxes are applied. This thoughtful approach not only boosts your savings but also promotes the financial well-being of your family.
We’re here for you as you navigate these financial decisions. Together, we can make the most of your resources and ensure that your family’s needs are met. Remember, every little bit helps, and planning wisely today can pave the way for a brighter tomorrow.
Explore the Benefits of a Dependent Care FSA
The primary advantage of a Dependent Care Flexible Spending Account (DCFSA) is the significant tax savings it offers, especially when combined with the dependent care FSA and child tax credit, which can be a game-changer for families. Imagine being able to allocate pre-tax dollars for childcare costs—this simple step allows households to effectively reduce their taxable income, leading to a lower overall tax bill.
For instance, the highest contribution cap is currently set at $5,000 for married partners filing jointly until December 31, 2025. This means families can protect this amount from taxation. Starting January 1, 2026, this limit will increase to $7,500, translating into even greater savings. Families can save around $625 to $875 more each year in taxes thanks to the raised flexible spending account limit, which is especially beneficial for those with multiple dependents in care.
Furthermore, a DCFSA helps families budget for childcare expenses throughout the year, enabling them to manage their finances more efficiently. Many employers offer these accounts, simplifying the process of setting aside funds for dependent care. This organized approach not only alleviates financial pressure but also empowers families to tackle their childcare costs proactively.
Financial planners often emphasize the importance of utilizing a DCFSA as a strategic tool for budgeting. By participating in this tax-saving initiative, families can enhance their economic well-being while utilizing the dependent care FSA and child tax credit to meet their childcare needs. This approach mirrors the journey of clients like Emily and Mark, who, through their partnership with Bright Advisers, developed a detailed financial strategy that improved their tax situation and granted them the freedom to choose their work-life balance. Similarly, clients like Allison and Brian have reaped the benefits of such strategies, optimizing their tax situations and securing their children’s future through education funding.
Overall, utilizing a dependent care FSA and child tax credit can help families achieve significant savings and improved resource management while facing the challenges of childcare expenses. Remember, we’re here for you—together, we can navigate this journey towards financial security.
Determine Eligibility for the Child Tax Credit
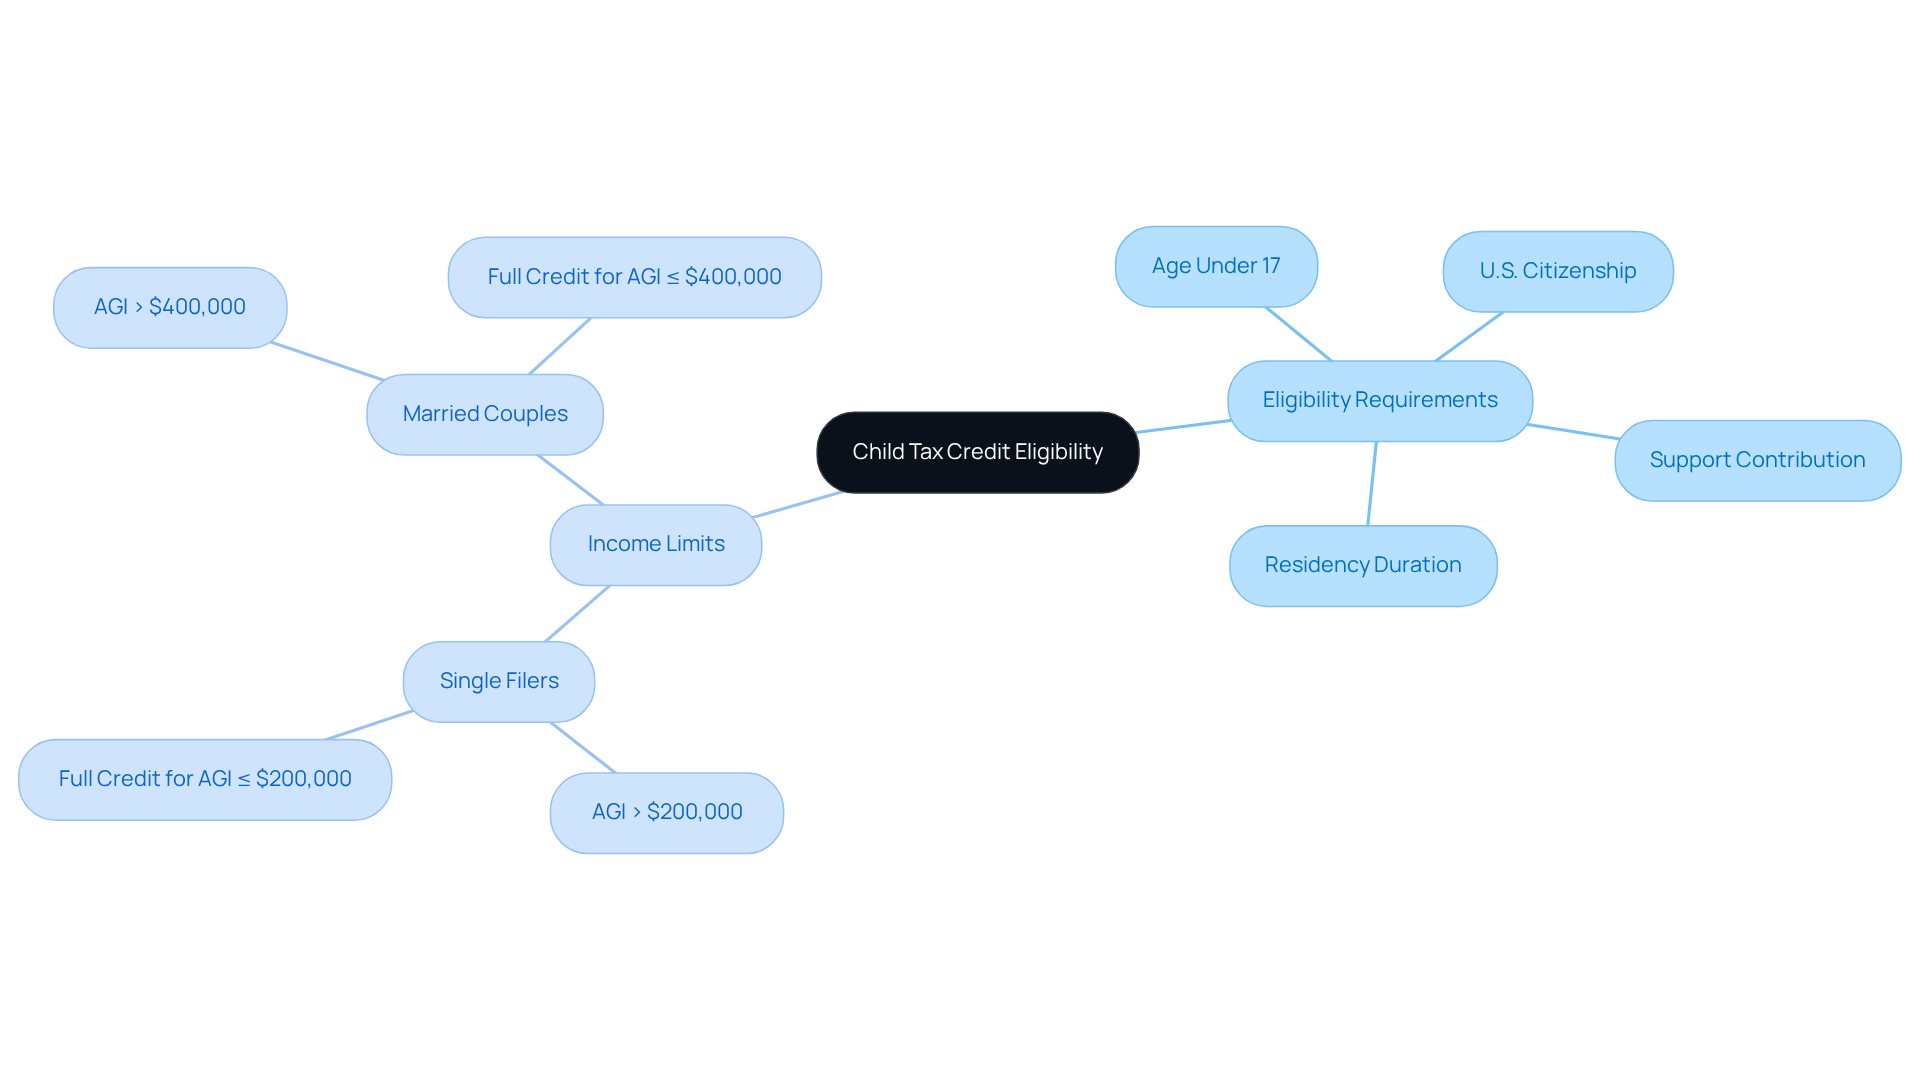
To be eligible for the Child Tax Credit in 2025, your child must:
- Be under 17 at the conclusion of the tax year
- Be a U.S. citizen, national, or resident alien
- Not have contributed more than half of their own support
- Have lived with you for more than half of the year
Income plays a crucial role; the credit begins to phase out for:
- Single filers with an adjusted gross income (AGI) exceeding $200,000
- Married couples filing jointly with an AGI over $400,000
For 2025, the maximum credit amount is set at $2,200 per eligible child, providing significant support for families.
Imagine this: Roughly 90% of taxpayers with children obtained the Child Tax Credit, with households earning between $100,000 and $200,000 receiving the highest average credits, surpassing $3,000. At Bright Advisers, we understand that navigating these financial benefits can feel overwhelming.
We’re here for you. Our customized wealth management strategies empower young families like Jay and Emma, who are striving to ease financial stress while preparing for their children’s education. By refining tax planning and crafting tailored strategies, we assist households in maximizing their financial potential and achieving peace of mind. Together, we can navigate this journey, allowing you to focus on what truly matters—caring for your loved ones.
Combine Savings: Using Both FSA and Child Tax Credit
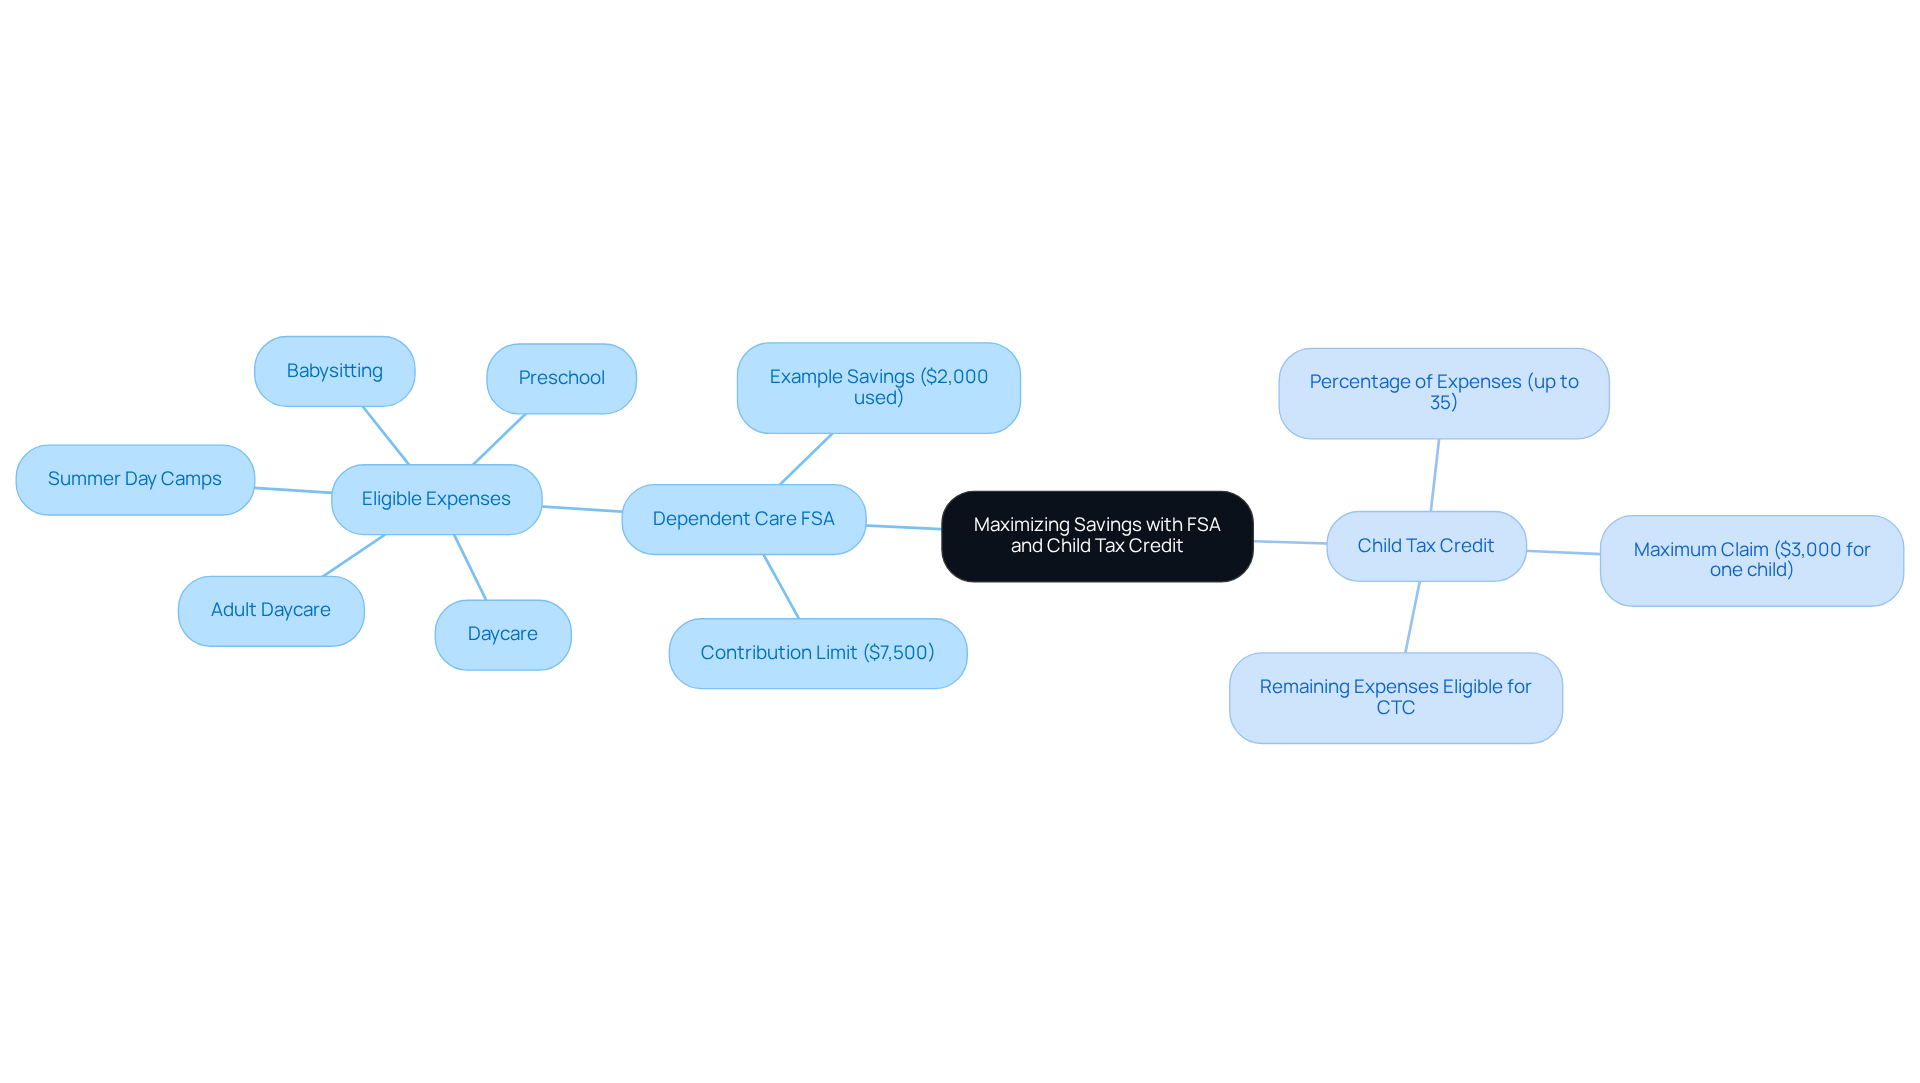
To maximize your savings, consider utilizing both the dependent care FSA and child tax credit. For young families, understanding how the dependent care FSA and child tax credit work together is crucial. For 2024, households can contribute up to $7,500 to a dependent care flexible spending account for eligible childcare costs. It’s important to know that while you can claim the Child Tax Credit for any remaining eligible expenses, you cannot double-dip by using the same expenses for both the dependent care FSA and Child Tax Credit.
Imagine if you incur $3,000 in childcare expenses and use $2,000 from your flexible spending account. You can still claim the Child Tax Credit for the remaining $1,000. This approach allows families to optimize their savings, significantly lowering total childcare costs.
Statistics show that families can save substantial amounts on taxes by utilizing the dependent care FSA and child tax credit. For instance, one couple saved $5,197.50 by utilizing a dependent care flexible spending account for $10,500 in qualifying expenses. Additionally, parents can claim up to 35% of qualifying childcare expenses through the CTC, with a maximum claim of $3,000 for one child or $6,000 for two or more children.
Financial advisors stress the importance of understanding eligibility requirements and strategically combining benefits like the dependent care FSA and child tax credit. As one expert noted, maximizing your contributions to a dependent care FSA and child tax credit can lead to significant tax savings for families. By navigating these options effectively, parents can alleviate some of the financial burdens associated with childcare.
Together, we can navigate this journey and ensure that your family’s financial future is secure.
Conclusion
Maximizing savings through the Dependent Care Flexible Spending Account (DCFSA) and the Child Tax Credit is an essential strategy for families navigating the rising costs of childcare. Imagine if you could significantly reduce your taxable income while enhancing your overall financial well-being. By understanding how these two financial tools work together, families can take proactive steps toward a more secure future. With upcoming increases in contribution limits and the potential for substantial tax savings, taking advantage of these benefits is more critical than ever.
Key insights from this guide highlight the importance of utilizing both the DCFSA and the Child Tax Credit effectively. Families can allocate pre-tax funds for eligible childcare costs while also claiming credits for any remaining expenses. This dual approach not only alleviates financial strain but also empowers families to budget more efficiently for their childcare needs. The potential savings can be substantial—families could save hundreds or even thousands of dollars each year by strategically combining these benefits.
Ultimately, understanding and implementing these savings strategies can pave the way for a more secure financial future. We encourage families to explore their options, enroll in a DCFSA through their employer, and ensure they meet the eligibility requirements for the Child Tax Credit. Together, we can navigate this journey. By taking proactive steps today, families can secure the resources necessary for their children’s care, education, and overall well-being, creating a brighter tomorrow for all involved.
Frequently Asked Questions
What is a Dependent Care Flexible Spending Account (DCFSA)?
A DCFSA allows families to set aside pre-tax funds from their paycheck specifically for qualified dependent care costs, helping to reduce taxable income and save on taxes.
What is the contribution limit for a DCFSA in 2025?
In 2025, individuals can contribute up to $5,000 per household to a DCFSA, or $2,500 for married couples filing separately.
Will the contribution limit for DCFSA change in the future?
Yes, starting January 1, 2026, the contribution limit will increase to $7,500.
What types of expenses are eligible for reimbursement through a DCFSA?
Eligible expenses include daycare, preschool, and summer camps for children under 13 years old.
How can utilizing a DCFSA and child tax credit benefit families financially?
By using a DCFSA and the child tax credit, families can lower their taxable income, potentially saving around $625 to $875 each year on childcare expenses.
How do contributions to a DCFSA work?
Contributions to a DCFSA are deducted from your paycheck before taxes are applied, which helps increase your overall savings.
How can I enroll in a DCFSA?
Enrollment in a DCFSA is required through your employer.
Are there any fees associated with a DCFSA that I should consider?
Yes, it’s important to consider minimal fund fees in your overall financial planning, as they can impact your savings strategy.
List of Sources
- Understand the Dependent Care FSA Basics
- The $7,500 Dependent Care FSA Limit: A Win for Families—If Employers Can Pass the Test | Employee Benefits Corporation | Third Party Benefits Administrator (https://ebcflex.com/2026-dependent-care-fsa-limits)
- Big News for Working Parents: Your Dependent Care FSA Just Got a Major Increase (https://beneliance.com/dependent-care-fsa-limit-update-2025)
- Explore the Benefits of a Dependent Care FSA
- Big News for Working Parents: Your Dependent Care FSA Just Got a Major Increase (https://beneliance.com/dependent-care-fsa-limit-update-2025)
- The $7,500 Dependent Care FSA Limit: A Win for Families—If Employers Can Pass the Test | Employee Benefits Corporation | Third Party Benefits Administrator (https://ebcflex.com/2026-dependent-care-fsa-limits)
- Dependent Care FSA – FSAFEDS (https://fsafeds.gov/explore/dcfsa)
- 10 Tax Saving Options in USA for Young Families to Maximize Savings – Bright Advisers (https://brightadvisers.com/10-tax-saving-options-in-usa-for-young-families-to-maximize-savings)
- Big Boost for Families: Dependent Care FSA Limit Increases to $7,500 Under New Tax Law – Accountants and Advisors | Froehling Anderson CPAs (https://fa-cpa.com/big-boost-for-families-dependent-care-fsa-limit-increases-to-7500-under-new-tax-law)
- Determine Eligibility for the Child Tax Credit
- Treasury and IRS Announce Families of Nearly 60 Million Children Receive $15 Billion in First Payments of Expanded and Newly Advanceable Child Tax Credit (https://home.treasury.gov/news/press-releases/Treasury-and-IRS-Announce-Families-of-Nearly-60-Million-Children-Receive-$15-Billion-Dollars-in-First-Payments-of-Expanded-and-Newly-Advanceable-Child-Tax-Credit)
- The Child Tax Credit: How It Works and Who Receives It (https://congress.gov/crs-product/R41873)
- Child tax credit 2025: Child tax credit updates and payments (https://jacksonhewitt.com/tax-help/tax-tips-topics/family/child-tax-credit-2025)
- What is the child tax credit? (https://taxpolicycenter.org/briefing-book/what-child-tax-credit)
- 2024-2025 Child Tax Credit: Top 7 Requirements (https://turbotax.intuit.com/tax-tips/family/7-requirements-for-the-child-tax-credit/L3wpfbpwQ)
- Combine Savings: Using Both FSA and Child Tax Credit
- Big News for Working Parents: Your Dependent Care FSA Just Got a Major Increase (https://beneliance.com/dependent-care-fsa-limit-update-2025)
- Navigating Child Tax Credits: Key Points for Maximizing Savings | Taxfyle (https://taxfyle.com/blog/child-tax-credit-maximize-savings)
- How does the tax system subsidize child care expenses? (https://taxpolicycenter.org/briefing-book/how-does-tax-system-subsidize-child-care-expenses)
- 2021 Changes to DCFSA & CDCTC | White Coat Investor (https://whitecoatinvestor.com/dcfsa-and-cdctc-tax-credits)

Kevin has advised high-income W-2 tech and biotech families since 2015, and leads the education-first Age Five Family Office from Brea, California.
Connect on LinkedIn → · About KevinThis is part of how we approach Tax Management for high-income W-2 families at Bright Advisers.
Keep reading