

Key Highlights
- A Charitable Remainder Unitrust (CRUT) allows individuals to transfer assets into a fund, providing income while supporting a chosen charity.
- Income from a CRUT can vary annually based on fund performance, potentially increasing over time.
- Contributions to a CRUT can yield significant tax benefits, including charitable deductions and avoidance of capital gains taxes on appreciated assets.
- Assets in a CRUT are removed from the donor’s estate, reducing estate tax liability and facilitating wealth transfer to future generations.
- Setting up a CRUT involves selecting assets, choosing a trustee, drafting a trust agreement, and applying for a tax identification number.
- Annual compliance includes filing IRS Form 5227, ensuring required distributions, and maintaining detailed records.
- Regular management of the CRUT’s investments and communication with trustees is essential for aligning with financial and philanthropic goals.
- Families in Southern California can benefit from CRUTs as part of their intentional wealth management strategy, ensuring both financial security and charitable impact.
Introduction
What if you could support causes that matter to you while also ensuring your family’s financial security? A Charitable Remainder Unitrust (CRUT) offers a unique opportunity to achieve both, allowing families to enjoy a steady income stream while making a lasting impact. Many families feel overwhelmed by the intricacies of financial planning, especially when it comes to charitable giving.
What are the essential steps to maximize charitable deductions and ensure compliance? This guide will help you navigate the path to establishing and managing a CRUT. With the right guidance, you can turn your charitable intentions into a legacy that benefits both your family and the community.
Understand the Basics of a Charitable Remainder Unitrust (CRUT)
Imagine being able to support a cause you love while also securing your family’s financial future. A Charitable Remainder Unitrust (CRUT) lets you do just that.
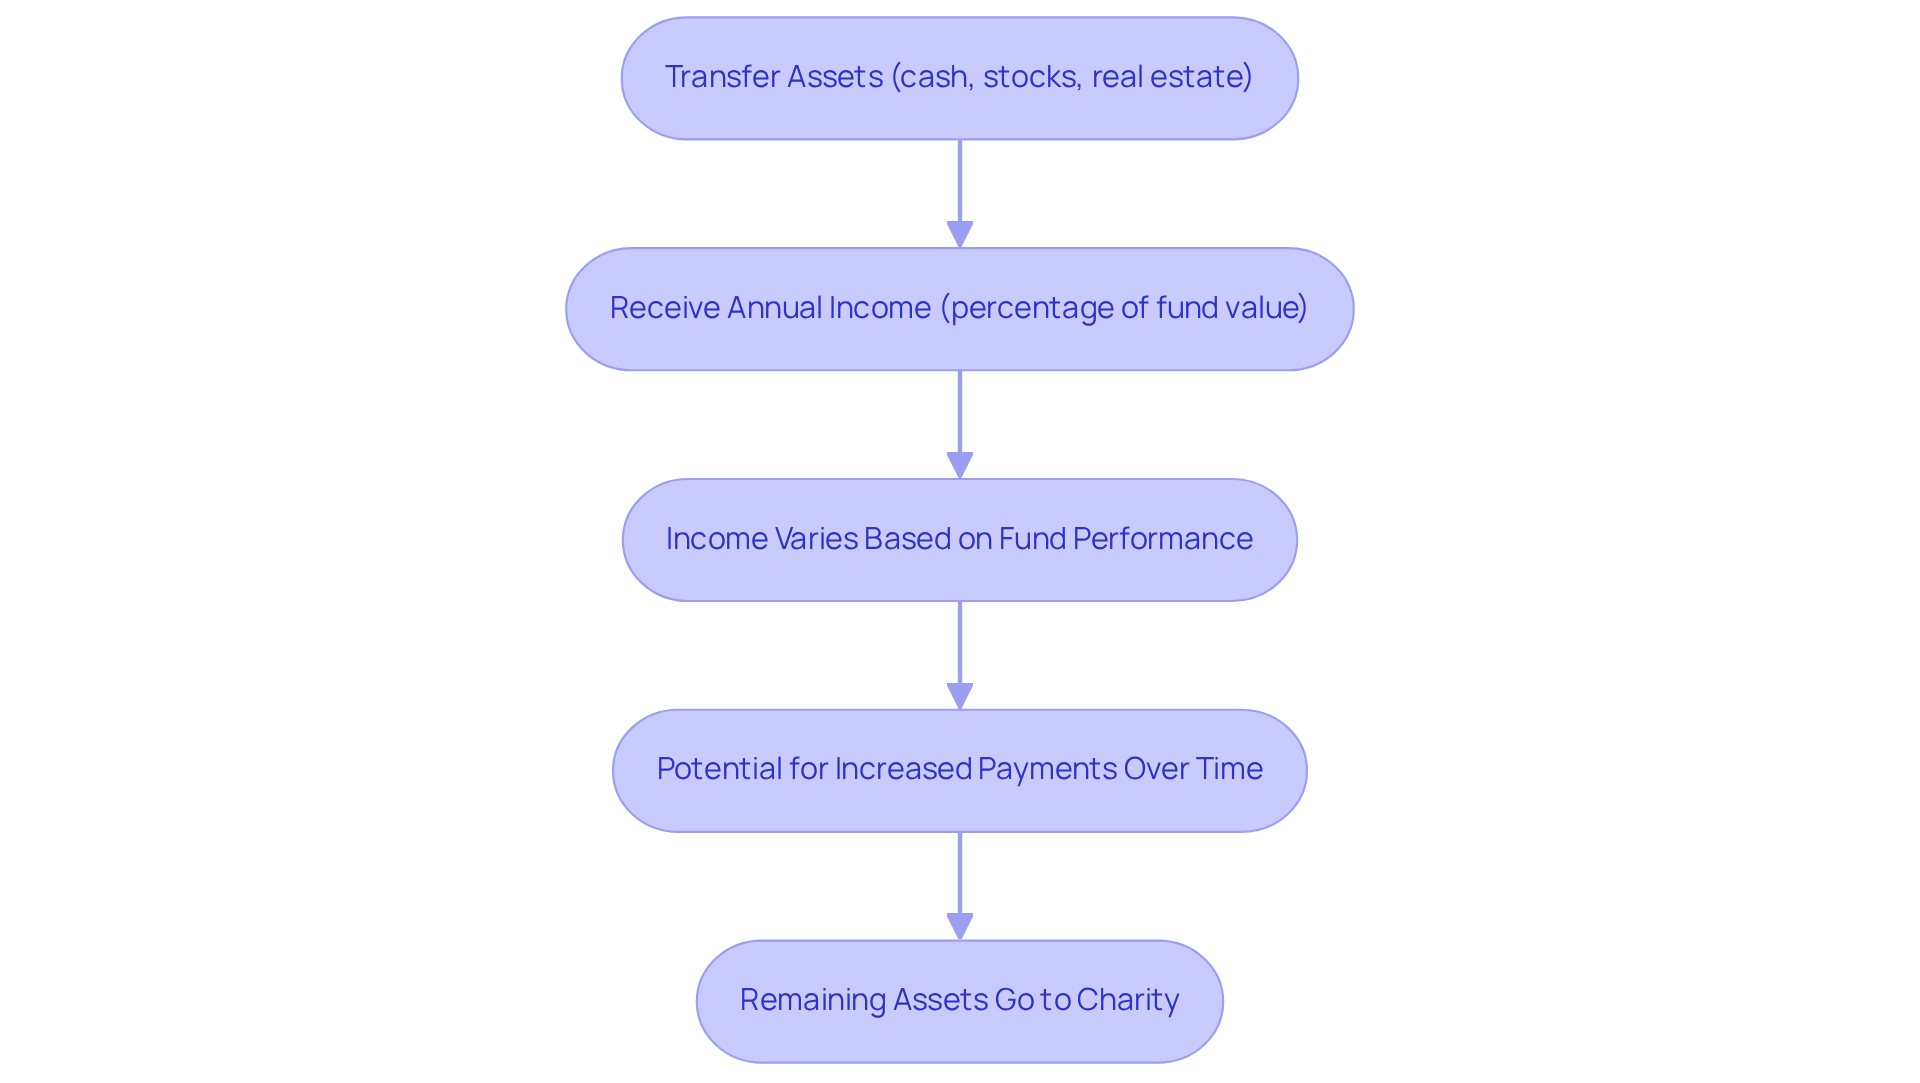
Here’s how it works: You transfer assets – like cash, stocks, or even real estate – into the fund. Then, the fund pays you or your loved ones a percentage of its value each year. This means you can enjoy a steady income while making a difference.
The income you receive can change each year, depending on how well the fund performs. This means you could see your payments grow over time, providing more support for your family. For example, if the fund earns a 7% return, your payments could increase significantly, giving you peace of mind.
When the time comes, the remaining assets in the trust will go to the charity you care about, ensuring your values live on. This way, you can support a cause that matters to you while also benefiting from the income during your lifetime.
Plus, making contributions to a CRUT charitable deduction can provide you with great tax benefits, allowing you to retain more of your hard-earned money for your family. By exploring a Charitable Remainder Unitrust, you can create a lasting impact for your family and the causes you cherish.
Identify the Tax Benefits of Establishing a CRUT
Many families worry about how to give back while ensuring their financial security, but establishing a Charitable Remainder Unitrust (CRUT) can help you achieve both.
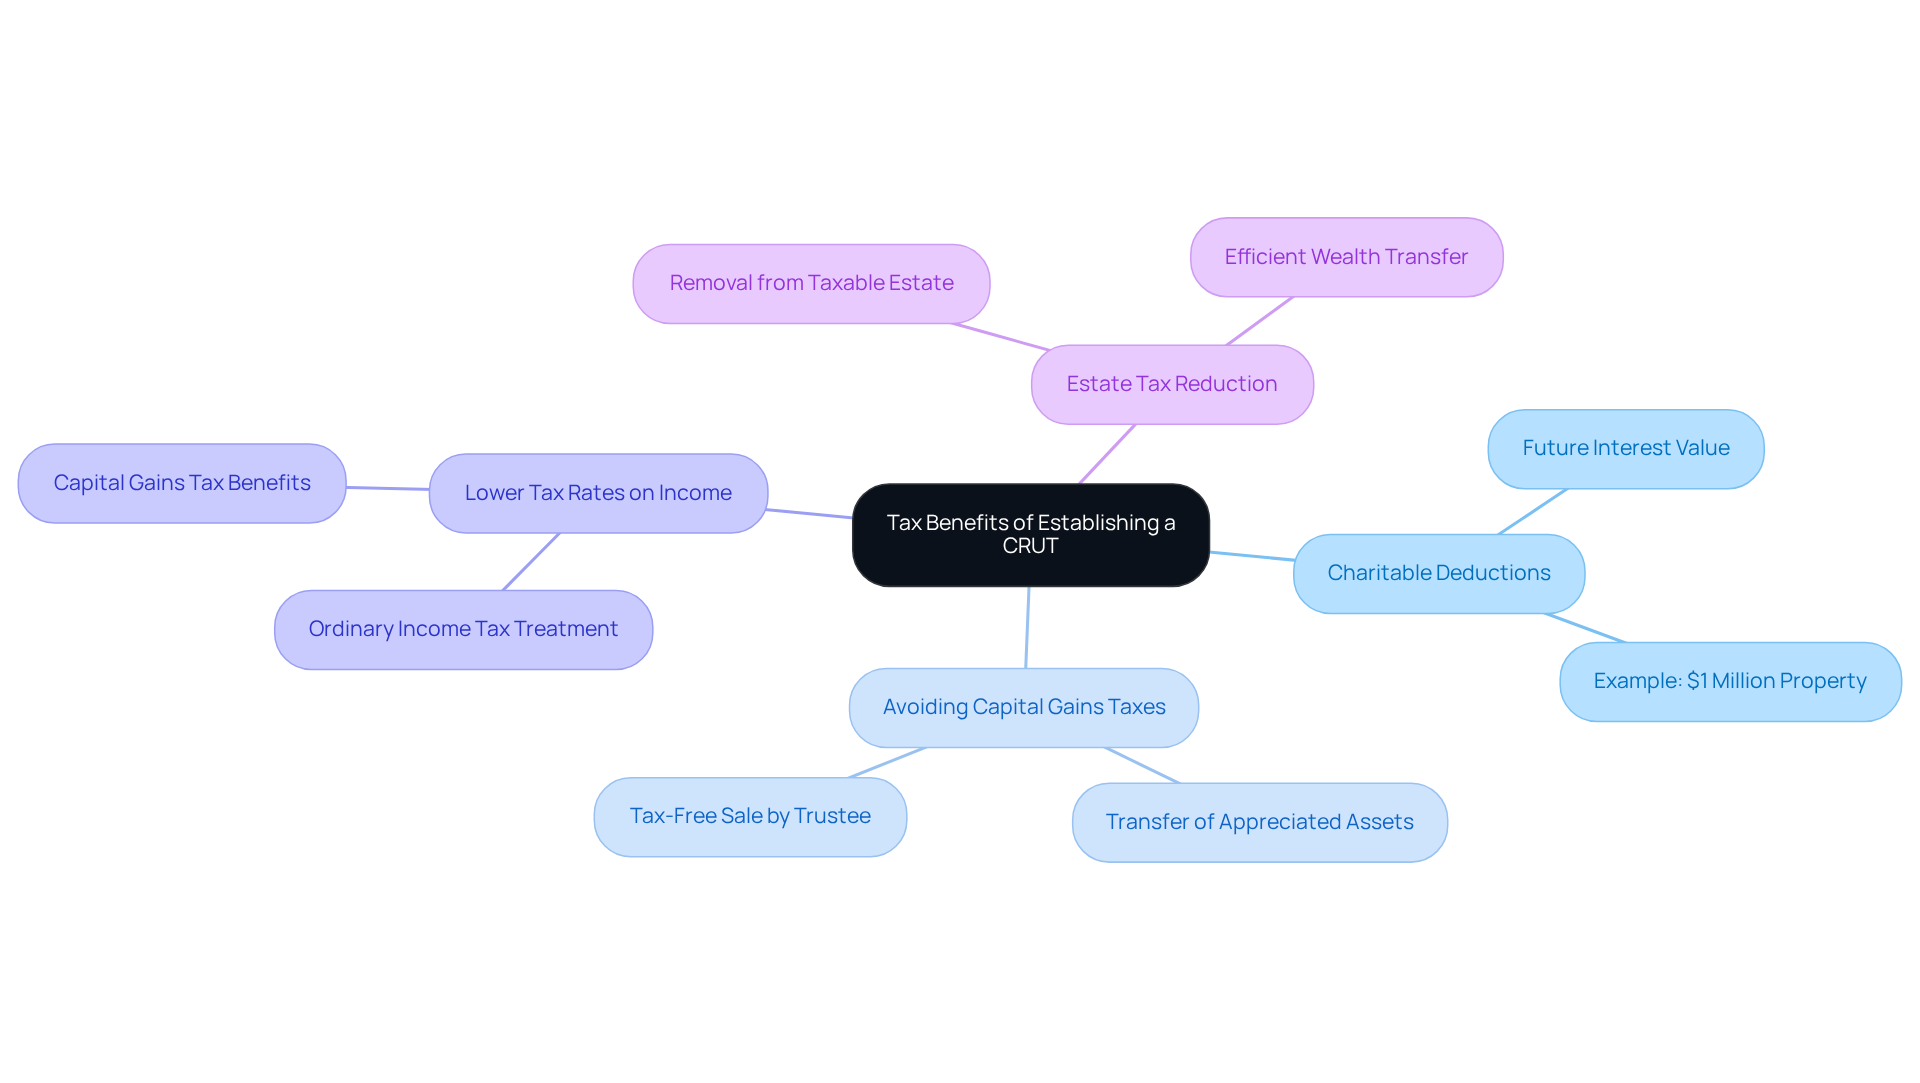
Funding a Charitable Remainder Unitrust means you can feel good knowing you’re also claiming a crut charitable deduction on your income tax return. This deduction reflects the charity’s future interest, which can be quite significant – often between 30% and 60% of the asset’s value, depending on what you donate. For instance, a 60-year-old widow transferring a $1 million property to a charitable remainder trust could receive a charitable deduction based on the present value of the remainder interest, calculated using IRS guidelines.
By funding your charitable remainder unitrust with appreciated assets, like stocks or real estate, you can avoid capital gains taxes on the appreciation. This means you can transfer the complete value of the asset into the fund without incurring immediate tax obligations, allowing for greater investment growth within the fund. This strategy is particularly beneficial for families like Allison and Brian, who want to minimize their tax burden while maximizing their investment potential.
The income produced from the charitable remainder unitrust is generally taxed at a lower rate than regular income, especially if the trust produces capital gains. Distributions from a charitable remainder unitrust are taxed as ordinary income initially, followed by capital gains, which can lead to a more favorable tax scenario for you as a beneficiary, improving your overall financial standing.
Assets placed in a Charitable Remainder Unitrust are removed from your estate, which can help reduce your estate tax liability. This is especially advantageous for families with significant assets, as it facilitates more efficient wealth transfer to future generations. By employing a charitable remainder unitrust, families can strategically manage their estate planning while ensuring that their philanthropic intentions are fulfilled.
By understanding these tax advantages, families can see how a charitable remainder unitrust and the associated crut charitable deduction can be valuable resources for their wealth and philanthropic planning, especially in Southern California. At Bright Advisers, we empower families like Jay & Emma and Emily & Mark to navigate these complexities, ensuring they optimize their financial well-being while achieving their charitable goals.
Establish Your Charitable Remainder Unitrust: Step-by-Step Setup
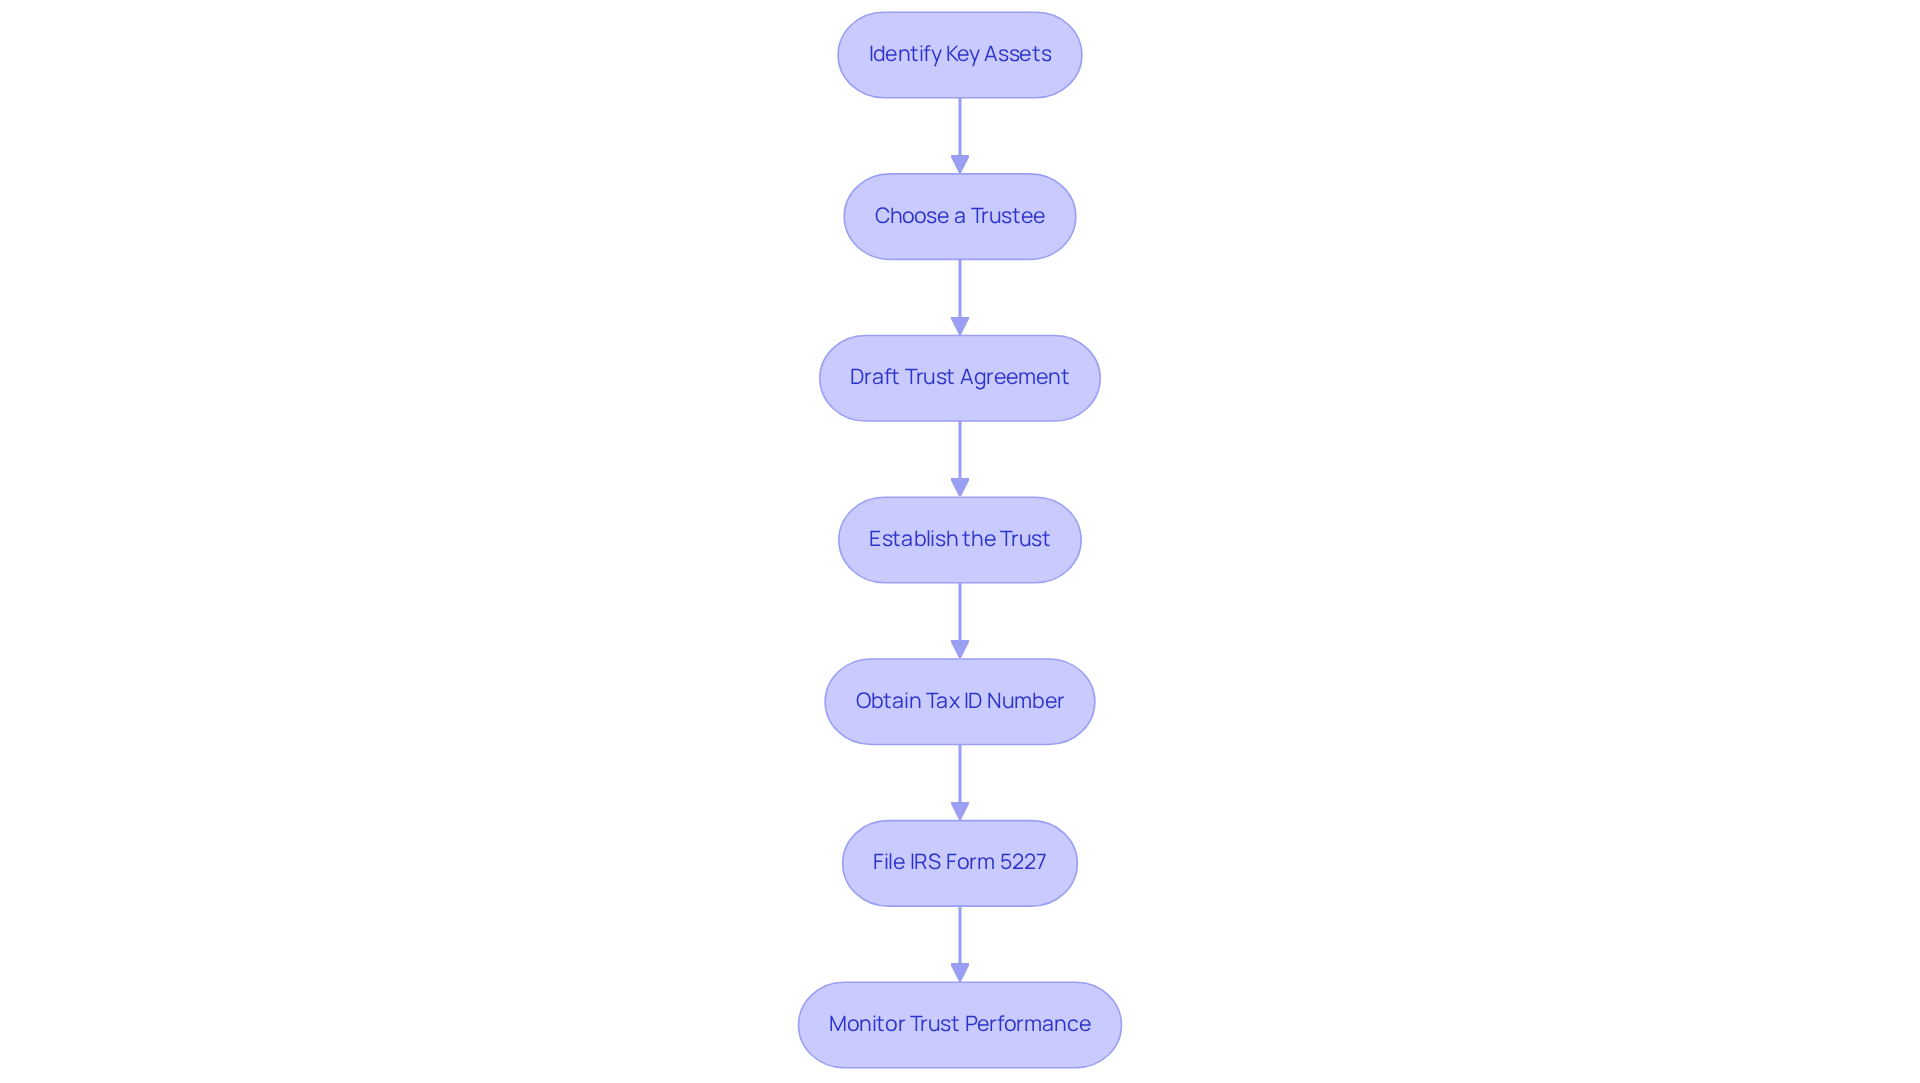
Imagine being able to support your favorite causes while also securing your family’s financial future. Setting up a CRUT charitable deduction can be a meaningful way to achieve both goals. Here are some essential steps to guide you through the process:
- Think about the assets that mean the most to you and your family – perhaps stocks or real estate that have appreciated over time. These can help you maximize your tax benefits while supporting your charitable goals.
- Consider who you trust to manage your charitable remainder unitrust – this could be a loved one, a financial institution, or a charitable organization that shares your values.
- Work closely with an attorney to craft a trust agreement that reflects your family’s wishes, detailing how you want to support your chosen charities while ensuring your loved ones are taken care of.
- Once you’ve chosen your assets, it’s time to officially establish your charitable remainder unitrust, allowing it to start generating income for your family and your favorite causes.
- You’ll need to apply for a tax identification number for your trust – this is an important step for keeping everything in order and compliant with tax regulations.
- Each year, remember to complete and file IRS Form 5227 to report your trust’s income and distributions – this helps maintain its tax-exempt status and ensures everything runs smoothly.
- Regularly check in on your trust’s performance and make any necessary adjustments to keep it aligned with your family’s financial goals and charitable aspirations.
By following these steps, you can create a charitable remainder unitrust that not only supports your philanthropic interests but also allows for a CRUT charitable deduction, enhancing your overall financial planning strategy. With the right guidance, you can create a legacy that reflects your family’s values and aspirations.
Manage Your CRUT: Compliance and Ongoing Responsibilities
Imagine the peace of mind that comes from knowing your charitable giving is both impactful and compliant. Effectively managing your CRUT is crucial for compliance and maximizing the benefits of the crut charitable deduction. Here are the key responsibilities to uphold:
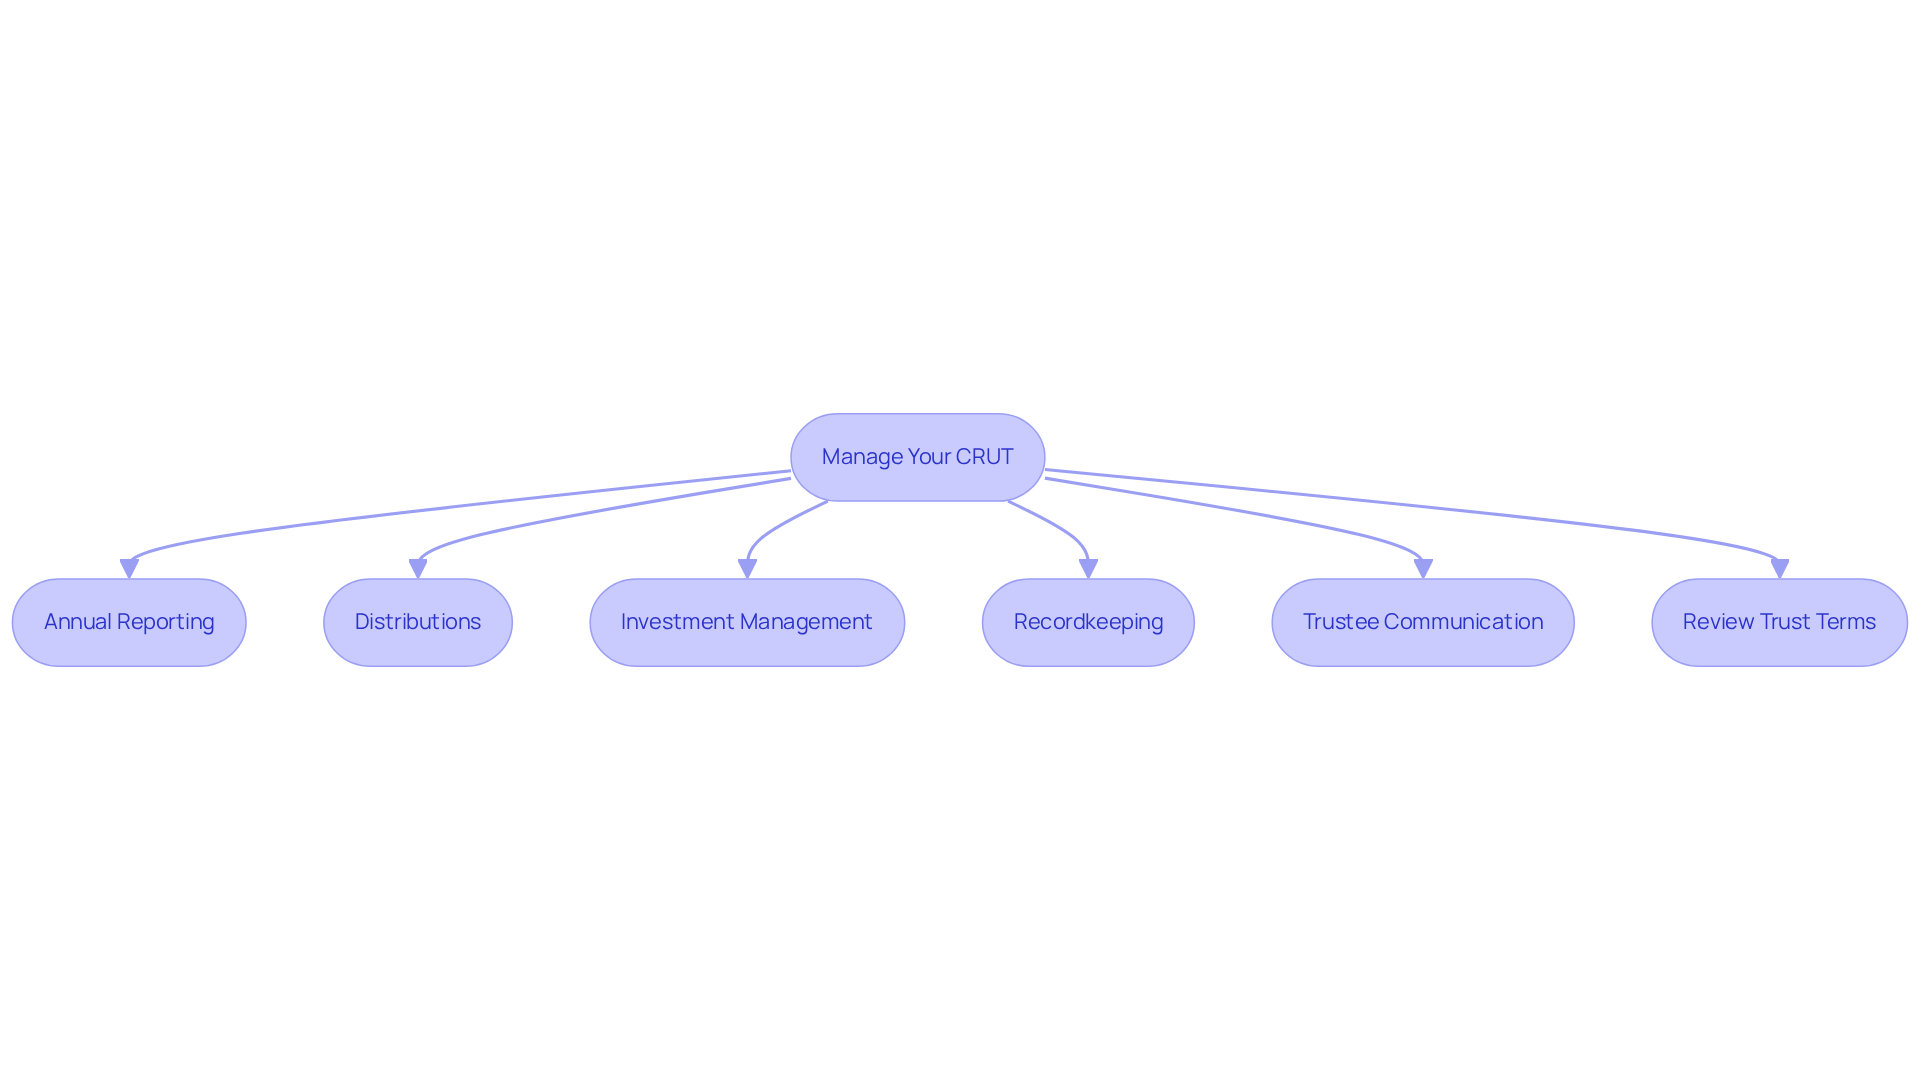
- Annual Reporting: Each year, file IRS Form 5227 to report the entity’s income, distributions, and other pertinent information. This form is essential for preserving the tax-exempt status of the organization and ensuring compliance with IRS regulations.
- Distributions: Ensure that the fund meets its required annual distributions to beneficiaries, which must range from 5% to 50% of the fund’s value as outlined in the agreement. Non-compliance can jeopardize the trust’s tax status. Imagine the stress of facing penalties; it’s vital to stay on top of these requirements. As observed in recent studies, the median age of active CRUT charitable deductions is 20 years, emphasizing the significance of continuous management to adapt to evolving economic landscapes.
- Investment Management: Take a moment to check in on your CRUT investments, ensuring they align with your family’s goals. Regularly assess performance, rebalance the portfolio, and make necessary adjustments to adapt to market conditions. Remember, investment income from a charitable remainder fund is exempt from taxation, providing a significant economic benefit through a crut charitable deduction.
- Recordkeeping: Keep detailed records of all transactions, distributions, and communications associated with the charitable remainder unitrust. This documentation is essential for tax reporting and compliance, providing peace of mind.
- Trustee Communication: If a trustee is appointed, maintain open lines of communication to ensure they are effectively fulfilling their responsibilities. Regular updates and discussions can help align the trust’s management with your monetary objectives.
- Review Trust Terms: Periodically revisit the terms of the trust to ensure the crut charitable deduction aligns with your monetary and philanthropic objectives. If you feel changes are needed, don’t hesitate to reach out to a financial advisor or attorney for guidance. As David M. Barral, a senior wealth adviser, states, “CRTs can work very well for those who are charitably inclined and also looking to defer income tax.”
By taking charge of your charitable remainder unitrust, you can make sure your giving truly makes a difference while also caring for your family’s financial health. With these ongoing responsibilities highlighted, remember, we’re here for you as you navigate the complexities of CRUT management effectively.
Conclusion
Imagine being able to support the causes you love while also securing your family’s financial future. Establishing a Charitable Remainder Unitrust (CRUT) can help you do just that. With a CRUT, you can give back to your community and enjoy tax benefits that help your family thrive. This way, you can build a legacy that reflects your values while keeping your family’s future secure.
We’ve explored how a CRUT can work for you and your family. Choosing the right assets and understanding the tax benefits are key steps in making the most of your CRUT. You can enjoy tax deductions and avoid capital gains taxes, making this a smart choice for your family.
Starting a CRUT is about more than just finances; it’s about creating a legacy that matters to you and your family. Together, we can take steps to ensure your contributions truly make a difference. We’re here to help you navigate the CRUT process, ensuring your family’s financial decisions reflect your values.
Frequently Asked Questions
What is a Charitable Remainder Unitrust (CRUT)?
A Charitable Remainder Unitrust (CRUT) is a financial arrangement that allows you to transfer assets into a fund, which then pays you or your loved ones a percentage of its value each year while ultimately benefiting a charity of your choice.
How does a CRUT work?
You transfer assets such as cash, stocks, or real estate into the CRUT. The fund pays you or your beneficiaries a percentage of its value annually, providing a steady income. The income can vary each year based on the fund’s performance.
What are the potential benefits of a CRUT?
A CRUT offers the potential for a steady income that may increase over time, tax benefits from charitable deductions, and the ability to support a cause you care about after your lifetime.
How is the income from a CRUT determined?
The income you receive from a CRUT is based on a percentage of the fund’s value, which can change each year depending on the fund’s performance.
What happens to the assets in a CRUT after the income payments end?
Once the income payments have concluded, the remaining assets in the trust are donated to the charity you designated, ensuring your values continue to have an impact.
What types of assets can be transferred into a CRUT?
You can transfer various types of assets into a CRUT, including cash, stocks, and real estate.
Are there tax benefits associated with a CRUT?
Yes, contributions to a CRUT can provide significant tax benefits, allowing you to retain more of your income for your family while supporting charitable causes.
List of Sources
- Understand the Basics of a Charitable Remainder Unitrust (CRUT)
- How Many Charitable Remainder Trusts Are There? Findings From My Tax Notes-Federal Analysis of a Decade of IRS Form 5227 Data (https://calcrut.com/post/how-many-charitable-remainder-trusts-are-there-findings-from-my-tax-notes-federal-analysis-of-a-dec)
- Planned Giving at Caltech | Caltech (https://giftplanning.caltech.edu/ways-you-can-give/charitable-remainder-unitrusts)
- Trusts and the Benefits of Giving Back (https://legacy.laist.com/charitable-remainder-trusts)
- Charitable Remainder Trusts vs. Charitable Lead Trusts: Options for Philanthropy in California – Garmo & Garmo, LLP (https://garmolaw.com/charitable-remainder-trusts-vs-charitable-lead-trusts-options-for-philanthropy-in-california)
- Identify the Tax Benefits of Establishing a CRUT
- Charitable remainder trusts | Internal Revenue Service (https://irs.gov/charities-non-profits/charitable-remainder-trusts)
- Cash Flow & Philanthropy: Charitable Remainder Trusts (https://schwab.com/learn/story/cash-flow-and-philanthropy-charitable-remainder-trusts)
- Establish Your Charitable Remainder Unitrust: Step-by-Step Setup
- Charitable remainder trusts | Internal Revenue Service (https://irs.gov/charities-non-profits/charitable-remainder-trusts)
- GiftLaw Pro, our charitable tax reference service, features detailed information on gift and estate planning strategies. It includes links to relevant Internal Revenue code sections, regulations, rulings, cases and more. (https://giftplanning.calvin.edu/giftlawpro/glawpro_subsection.jsp?CC=3&SS=10&SS2=1)
- Charitable Remainder Trusts (CRTs) | Wealthspire (https://wealthspire.com/guides-whitepapers/charitable-remainder-trusts)
- How To Set Up a Charitable Remainder Unitrust (CRUT) (https://seracapital.com/wealth-management/how-to-set-up-a-charitable-remainder-unitrust-crut)
- Pointers in Selecting Assets to Fund Charitable Trusts – Riker Danzig (https://riker.com/publications/pointers-in-selecting-assets-to-fund-charitable-trusts)
- Manage Your CRUT: Compliance and Ongoing Responsibilities
- How Many Charitable Remainder Trusts Are There? Findings From My Tax Notes-Federal Analysis of a Decade of IRS Form 5227 Data (https://calcrut.com/post/how-many-charitable-remainder-trusts-are-there-findings-from-my-tax-notes-federal-analysis-of-a-dec)
- Charitable Remainder Trusts – NCF California (https://ncfcalifornia.com/charitable-remainder-trusts)
- Planning with charitable remainder trusts (https://thetaxadviser.com/issues/2025/sep/planning-with-charitable-remainder-trusts)

Kevin has advised high-income W-2 tech and biotech families since 2015, and leads the education-first Age Five Family Office from Brea, California.
Connect on LinkedIn → · About KevinThis is part of how we approach Philanthropy for high-income W-2 families at Bright Advisers.
Keep reading