

Overview
Deciding between a Mega Backdoor Roth IRA and a brokerage account can feel overwhelming for families. It’s essential to consider your unique financial goals, income levels, and liquidity needs.
Imagine if you could maximize your savings while still having access to funds when life throws you a curveball. The Mega Backdoor Roth IRA offers significant tax advantages and higher contribution limits, making it an attractive option for long-term retirement savings. However, it’s important to recognize that brokerage accounts provide immediate access to your funds, offering flexibility that many families need.
This choice ultimately depends on your family’s financial situation and priorities. Whether you lean towards the security of a Mega Backdoor Roth or the accessibility of a brokerage account, remember that you’re not alone in this journey. Together, we can navigate these options to find what best suits your family’s needs.
We’re here for you, ready to support you in making informed decisions that align with your family values and aspirations.
Key Highlights:
- The Mega Backdoor Roth IRA allows high-income earners to contribute after-tax dollars to a 401(k) and convert to a Roth IRA, enhancing retirement savings beyond standard limits.
- In 2025, individuals under 50 can contribute up to $70,000 to a Mega Backdoor Roth, significantly increasing tax-advantaged savings potential.
- Brokerage accounts are taxable investment accounts with no contribution limits, providing liquidity and flexibility for immediate financial needs.
- Mega Backdoor Roth offers tax-free growth and withdrawals in retirement, but has complexities and potential tax implications, requiring professional guidance.
- Brokerage accounts provide diverse investment options and quick access to funds, but may incur capital gains taxes on earnings.
- Only 21% of employers allow after-tax contributions to 401(k) plans, limiting access to the Mega Backdoor Roth strategy for some families.
- Families should evaluate their income, goals, and liquidity needs when choosing between a Mega Backdoor Roth and a brokerage account.
- Consulting with financial advisors can help families navigate these options and align them with their long-term aspirations.
Introduction
Navigating the complexities of retirement savings can feel overwhelming, especially for families striving to secure their financial futures. Imagine the peace of mind that comes from making informed decisions about your savings. The Mega Backdoor Roth IRA and brokerage accounts present two distinct pathways, each offering unique advantages and challenges. While the Mega Backdoor Roth provides significant tax benefits and enhanced contribution limits, brokerage accounts offer flexibility and immediate access to funds.
It’s important to understand how families can determine which option aligns best with their financial goals, particularly when faced with the intricacies of tax implications and liquidity needs. This article delves into the critical comparisons between these two strategies, guiding you through the decision-making process. Together, we can navigate this journey to find the best fit for your unique circumstances, ensuring that your family’s future is secure.
Understanding Mega Backdoor Roth and Brokerage Accounts
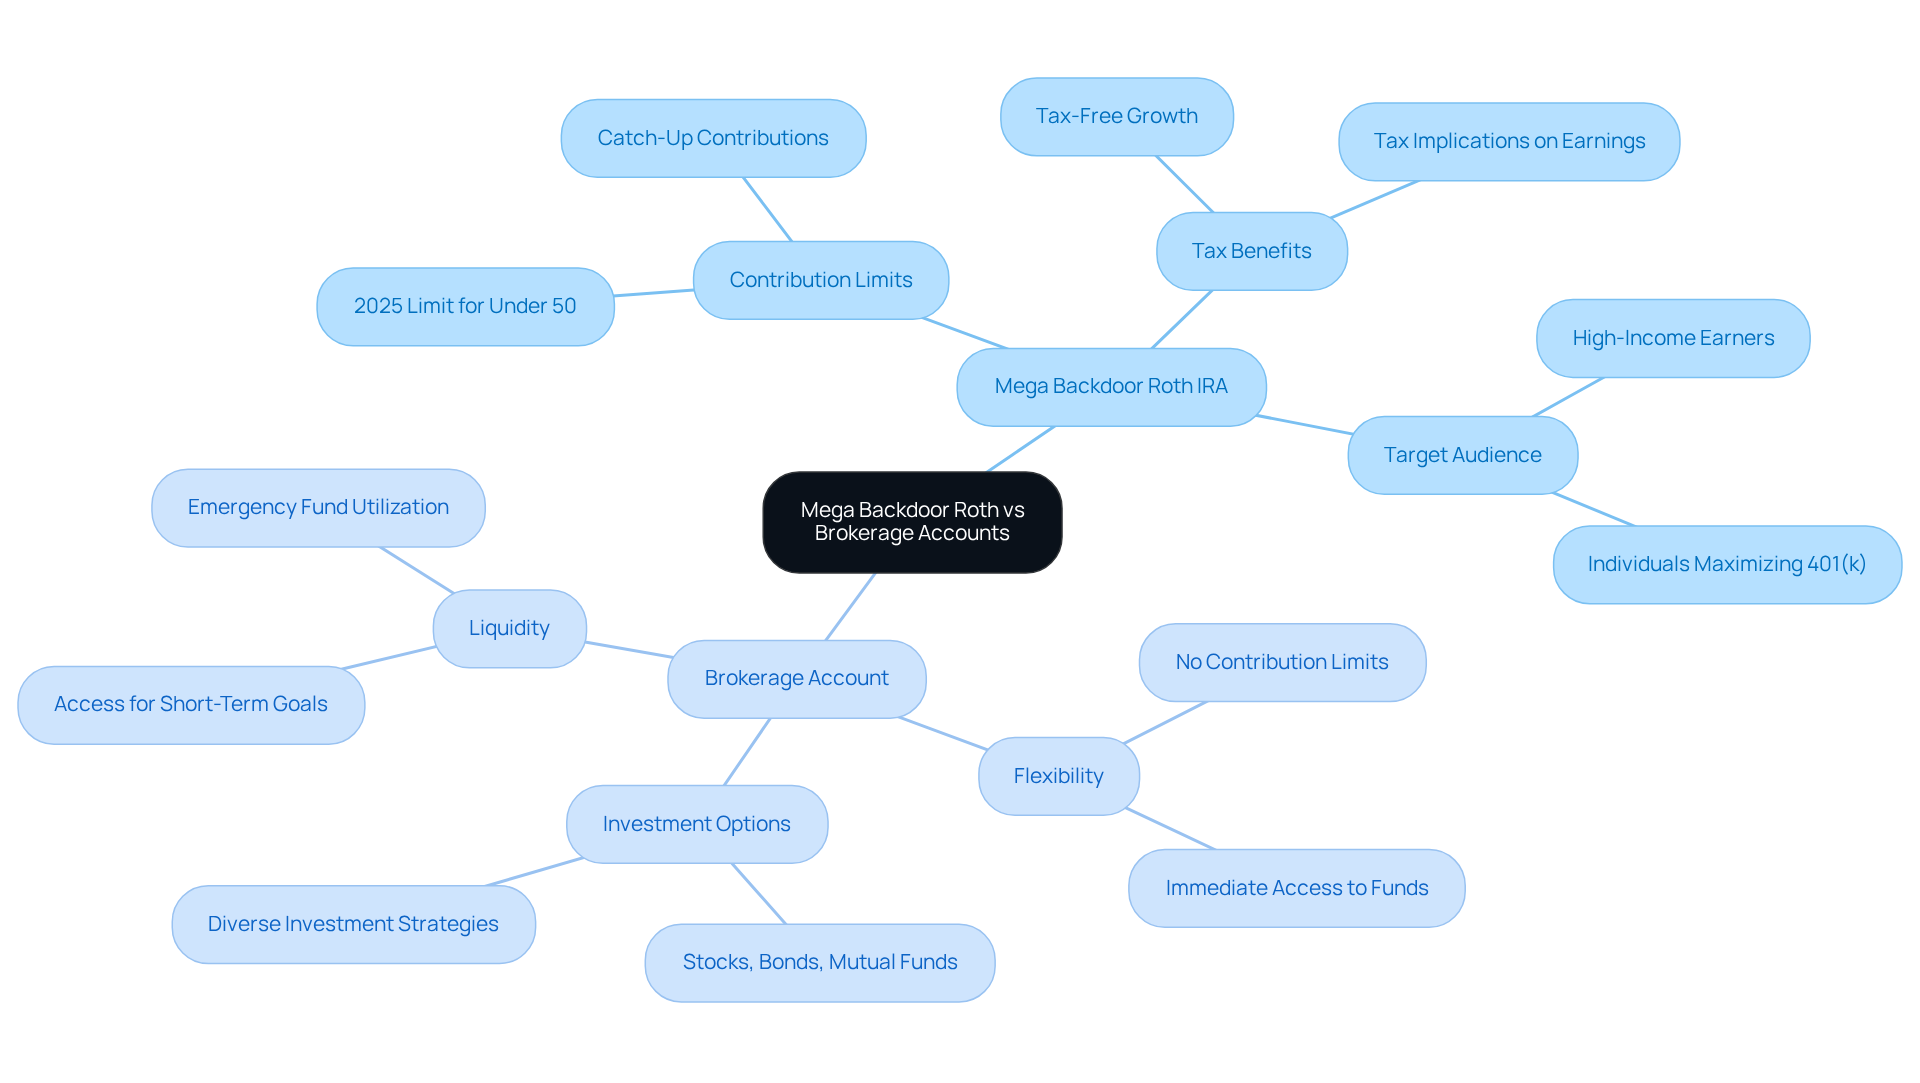
The Mega Backdoor Roth IRA is a sophisticated retirement savings strategy that allows individuals to contribute after-tax dollars to their 401(k) plans and then convert those contributions into a Roth IRA. This approach can be especially beneficial for high-income earners who want to boost their tax-advantaged retirement savings beyond standard contribution limits. For example, in 2025, individuals under 50 can contribute up to $70,000, significantly enhancing their retirement savings potential.
On the other hand, a brokerage account functions as a taxable investment account, enabling individuals to buy and sell a variety of investment products, such as stocks, bonds, and mutual funds. Unlike retirement accounts, brokerage accounts have no contribution limits, providing greater flexibility in investment choices and immediate access to funds. This can be particularly advantageous for families needing liquidity for short-term financial goals or emergencies.
Understanding the nuances of mega backdoor Roth vs brokerage options is crucial for families looking to secure their financial futures while managing current obligations. For instance, families like Emily and Mark have successfully utilized the strategy of mega backdoor Roth vs brokerage to bolster their retirement savings. In contrast, others have opted for brokerage accounts to maintain liquidity and flexibility in their investment strategies when considering the mega backdoor Roth vs brokerage. By evaluating their unique financial situations with the support of Bright Advisers, families can make informed decisions that align with their long-term goals, ultimately reducing financial stress and enhancing their overall financial security. Bright Advisers emphasizes the importance of personalized financial planning and tax optimization strategies to help families navigate these options effectively.
Comparing Benefits: Mega Backdoor Roth vs. Brokerage Accounts
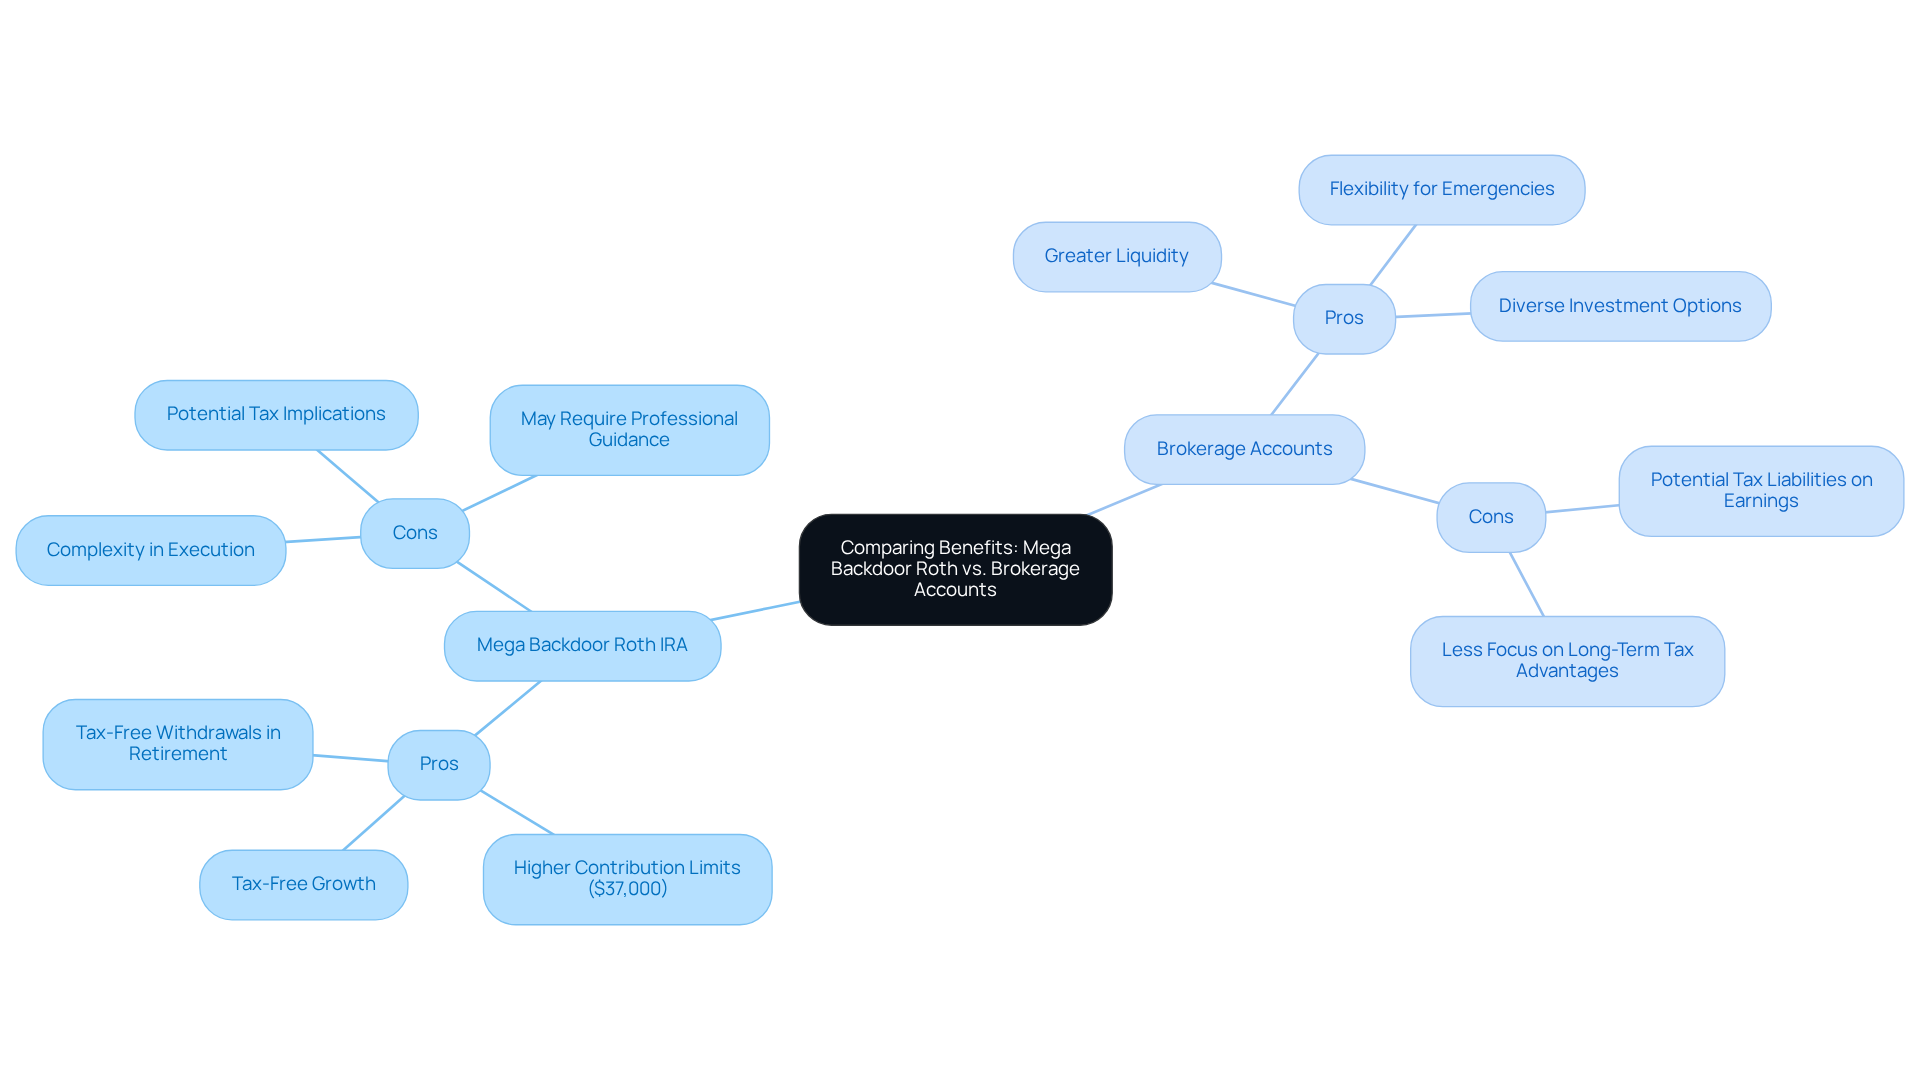
The Mega Backdoor Roth IRA offers significant tax advantages, including tax-free growth and withdrawals during retirement, making it a compelling option for families aiming to build wealth over time. With contribution limits reaching up to $37,000 beyond standard Roth IRA limits, families can substantially enhance their retirement savings. However, it’s important to consider the complexities and potential tax implications of this strategy. Consulting with a financial advisor can be beneficial, especially for young families like Jay and Emma, who are looking to alleviate financial stress while planning for their future.
On the other hand, brokerage accounts provide greater liquidity and flexibility, allowing families to access their funds without penalties or restrictions. This flexibility can be particularly valuable for young families who may need to tap into their investments for emergencies or educational expenses. It’s worth noting that brokerage accounts may incur capital gains taxes on earnings, which is a crucial consideration for families striving to optimize their financial strategies.
Additionally, brokerage accounts offer a wider array of investment options, enabling families to diversify their portfolios and tailor their investment strategies to changing economic conditions. By weighing the long-term tax benefits of a Mega Backdoor Roth vs brokerage accounts against the immediate liquidity advantages of brokerage, families can create a comprehensive financial plan that meets both their current needs and future aspirations. This balanced approach empowers them to secure their financial futures and reduce anxiety.
Pros and Cons:
-
Mega Backdoor Roth IRA:
- Pros: Tax-free growth, higher contribution limits ($37,000), tax-free withdrawals in retirement.
- Cons: Complexity in execution, potential tax implications, may require professional guidance.
-
Brokerage Accounts:
- Pros: Greater liquidity, flexibility for emergencies, diverse investment options.
- Cons: Potential tax liabilities on earnings, less focus on long-term tax advantages.
Evaluating Drawbacks: Challenges of Mega Backdoor Roth and Brokerage Accounts
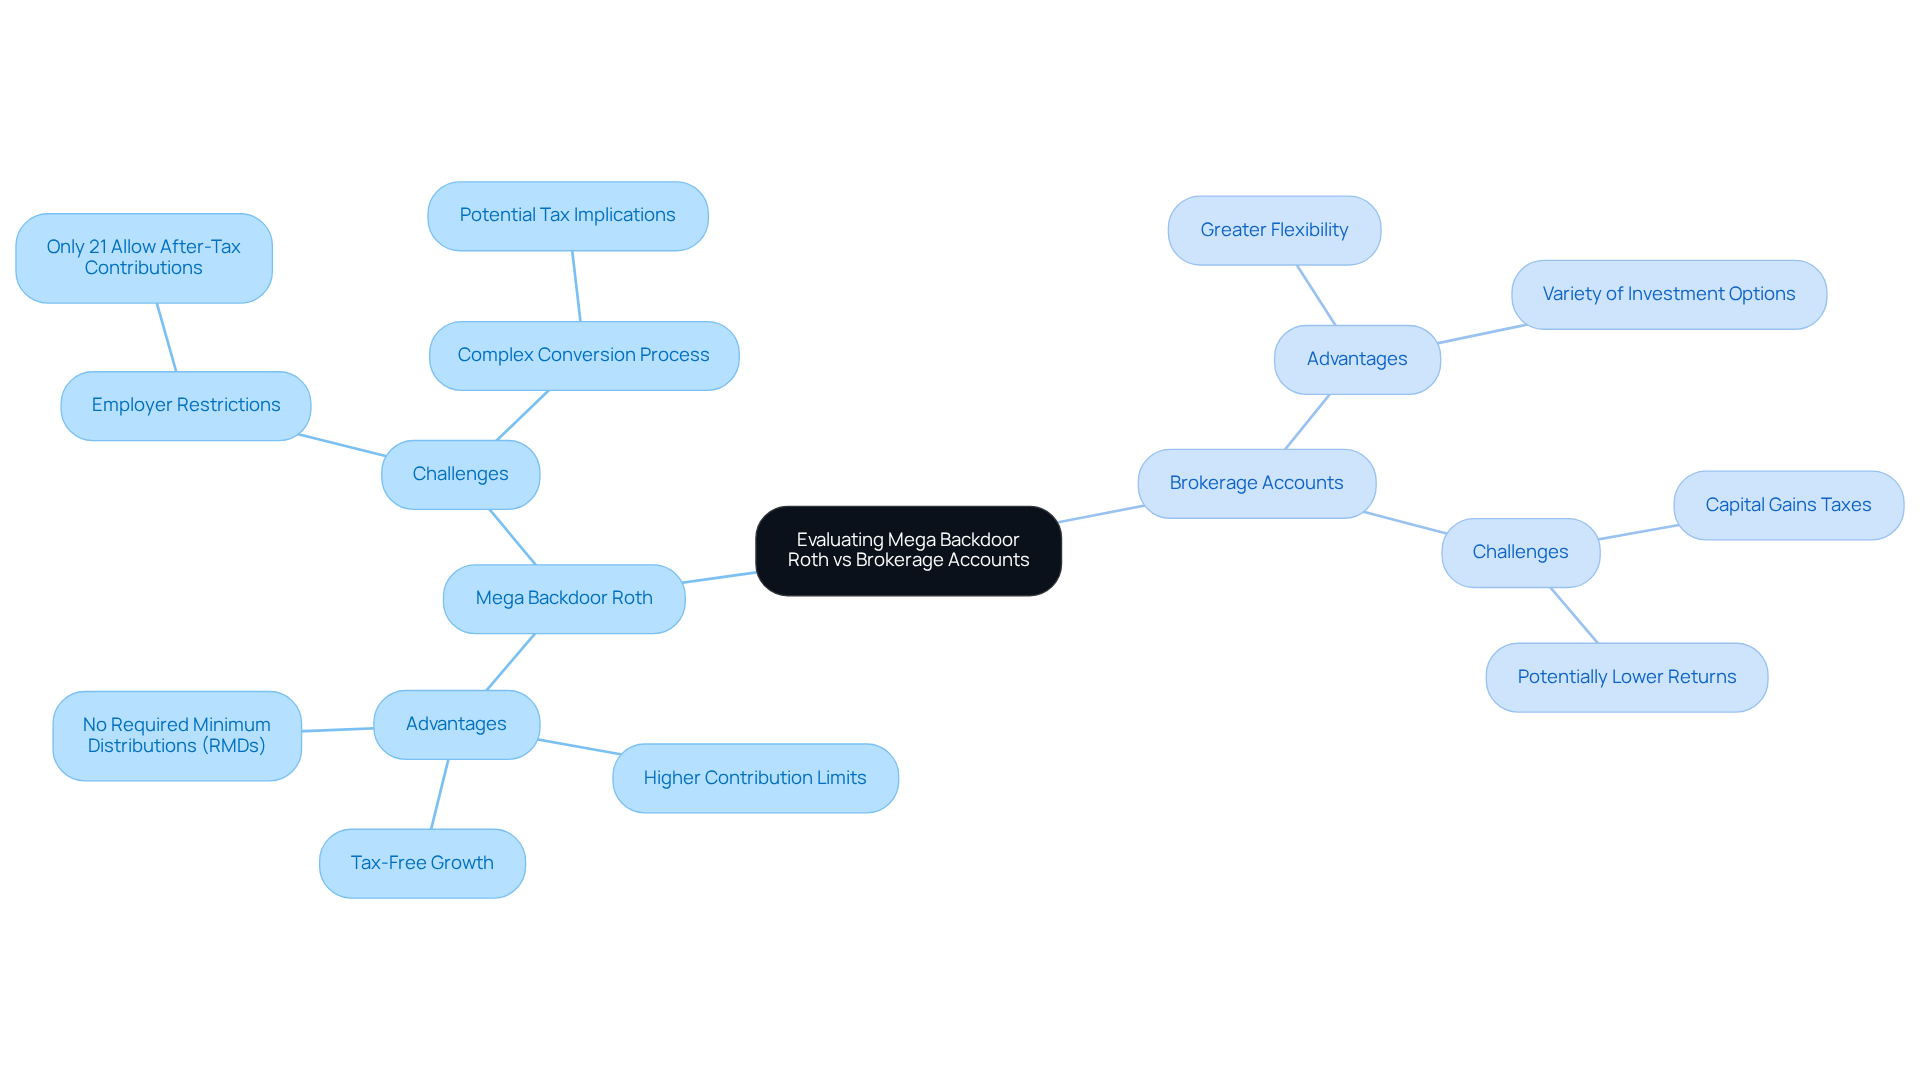
When considering the mega backdoor Roth vs brokerage, the Mega Backdoor Roth offers some significant advantages, but it also comes with its own set of challenges. Imagine navigating your family’s financial future with this powerful tool, only to find that a significant drawback is that only 21% of employers allow after-tax contributions to 401(k) plans. This limitation can restrict access for many households, making it essential for families to carefully assess their employer’s plan to determine eligibility.
It’s important to understand that the conversion process can be intricate. If not managed correctly, it could lead to unexpected tax implications. In comparing mega backdoor Roth vs brokerage accounts, the latter provides greater flexibility, yet they bring their own challenges, such as capital gains taxes on profits, which can diminish your overall investment returns.
Comprehending these elements is crucial as you assess your family’s economic plans. Remember, you’re not alone in this journey. We’re here for you, ready to help you navigate these complexities and find the best path forward for your family. Together, we can explore the options that align with your values and goals.
Determining Suitability: Which Option Fits Your Financial Goals?
Choosing between a Mega Backdoor Roth vs brokerage account can feel overwhelming, especially for families navigating their financial futures. It’s essential to consider factors like income level, goals, and liquidity needs. For families with higher incomes who are focused on long-term retirement savings, the discussion of mega backdoor roth vs brokerage often reveals that the Mega Backdoor Roth is a more advantageous option. This strategy allows for optimized contributions and tax-free growth, significantly bolstering economic security over time. For example, individuals under 50 can contribute up to $46,500 in after-tax dollars to their 401(k) plans. Those aged 50 and above can further enhance their savings with an additional catch-up contribution of $7,500.
Allison and Brian, a couple eager to maximize their financial potential, discovered through their partnership with Bright Advisers how effective tax planning can significantly impact wealth growth. Bright Advisers employed strategies like tax-loss harvesting and strategic asset allocation to improve their tax situation. By prioritizing their children’s education funding and aiming for early retirement, they exemplify how families can leverage options like the mega backdoor roth vs brokerage to improve their financial outcomes.
On the other hand, families that prioritize quick access to their funds or have fluctuating financial needs might lean towards a brokerage account. This choice offers greater flexibility and a wider array of investment options, allowing families to adapt their strategies as circumstances change. For instance, families assessing their retirement savings might consider how soon they may need to access their investments, influencing their decision. It’s also crucial to remember that leaving after-tax contributions in a 401(k) can lead to tax liabilities on earnings upon withdrawal, making timely conversions vital to avoid unnecessary tax burdens.
Pros and Cons Summary:
- Mega Backdoor Roth:
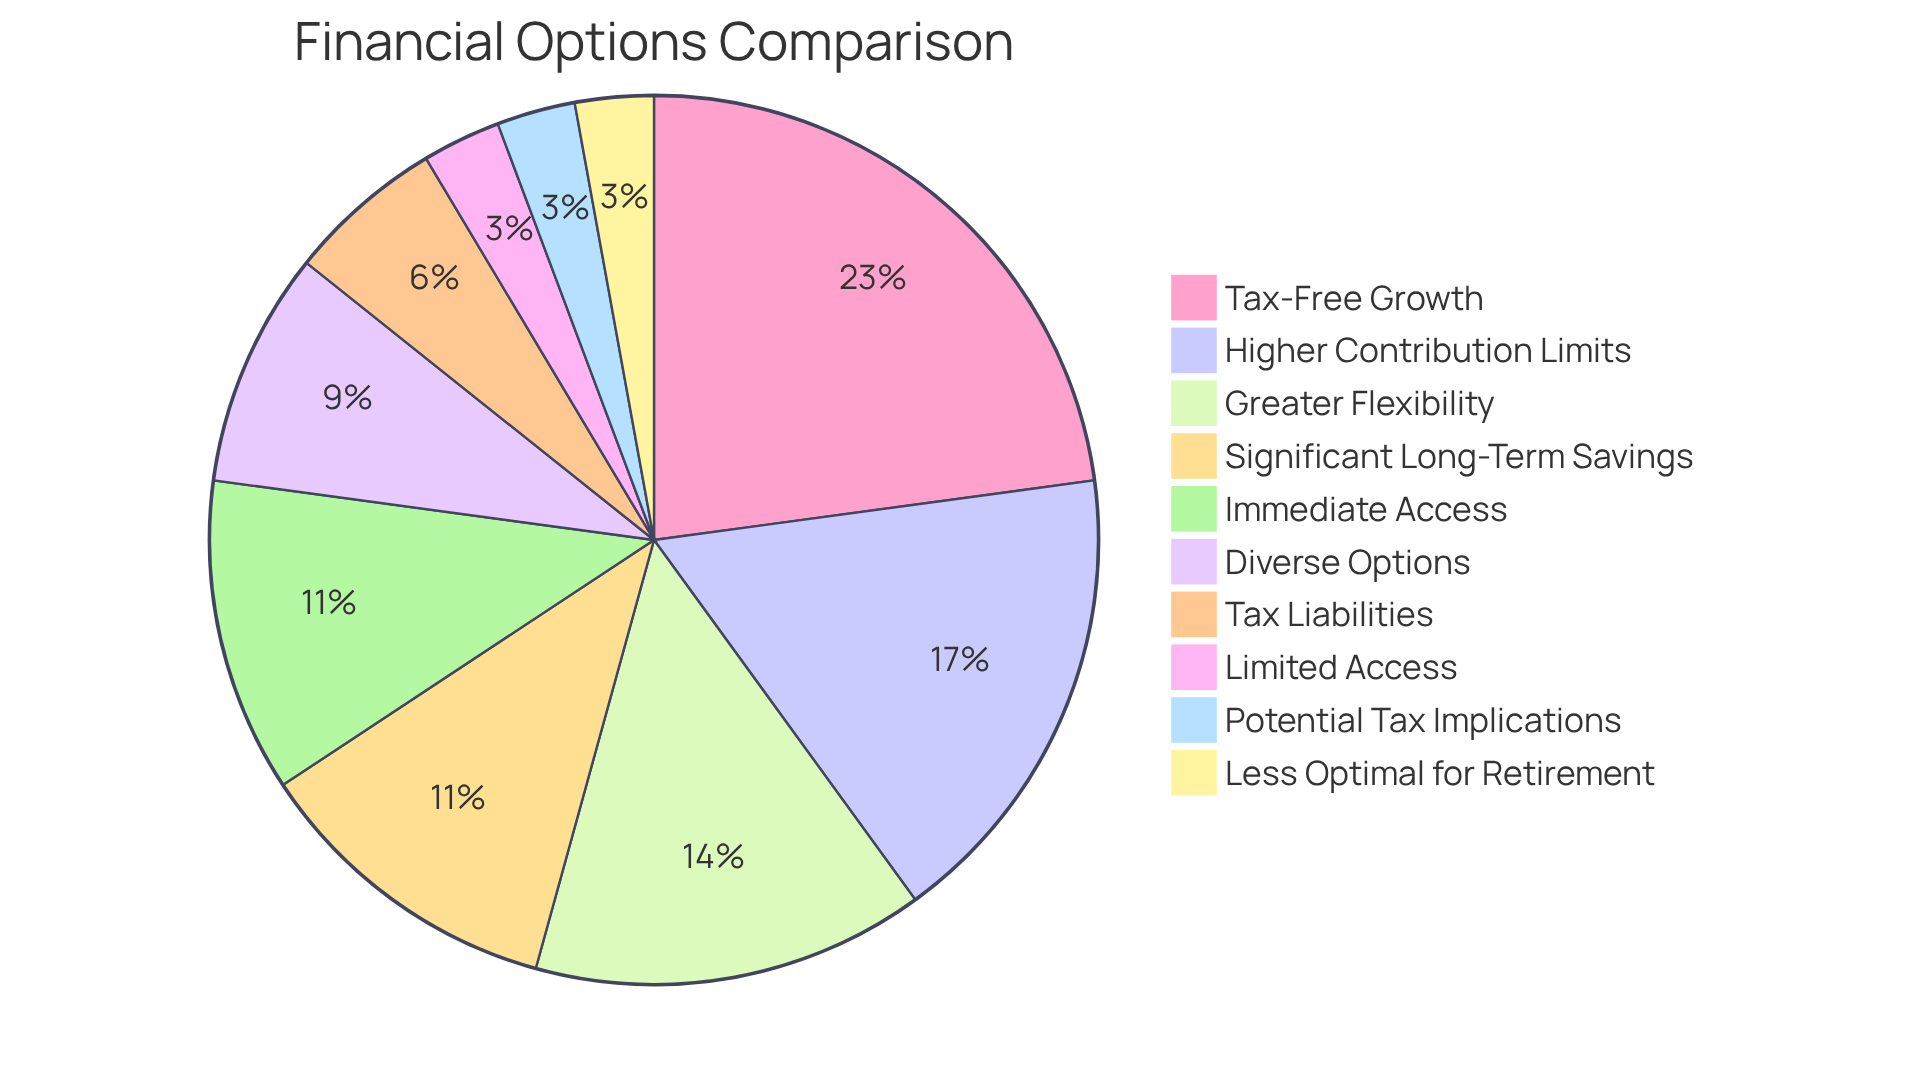
- Pros: Tax-free growth, higher contribution limits, potential for significant long-term savings.
- Cons: Limited access to funds until retirement age, potential tax implications if not managed properly.
- Brokerage Account:
- Pros: Greater flexibility, immediate access to funds, diverse investment options.
- Cons: Tax liabilities on capital gains, less optimal for long-term retirement savings.
Ultimately, deciding between a Mega Backdoor Roth vs brokerage account should stem from a thoughtful evaluation of each family’s unique financial situation and future aspirations. Wealth management consultants emphasize the importance of aligning financial strategies with personal values, ensuring families can effectively navigate their financial journeys while achieving their long-term goals. Bright Advisers notes a growing acceptance of this approach among young families over the past five years, reflecting an increasing awareness of its benefits. Emily and Mark, for instance, found financial freedom through tailored wealth management strategies, illustrating the power of informed financial planning. Together, we can navigate this journey.
Conclusion
Choosing between a Mega Backdoor Roth IRA and a brokerage account is a pivotal decision for families striving to secure their financial futures. Each option presents distinct advantages and challenges, catering to different financial needs and goals. The Mega Backdoor Roth offers significant tax benefits and higher contribution limits, making it an attractive choice for long-term retirement savings. On the other hand, brokerage accounts provide immediate access to funds and greater investment flexibility, appealing to families with pressing liquidity needs.
Imagine if you could choose a financial path that truly aligns with your family’s unique situation. Throughout this article, we’ve highlighted the importance of understanding your individual circumstances when selecting the right financial strategy. Families with higher incomes may find the Mega Backdoor Roth particularly beneficial due to its tax-free growth potential. Meanwhile, those requiring quick access to their investments might prefer the adaptability of brokerage accounts. The insights shared underscore the necessity of personalized financial planning to navigate these options effectively, ensuring that families can align their strategies with their unique aspirations.
Ultimately, the path to financial security lies in informed decision-making. Families should weigh the long-term benefits of a Mega Backdoor Roth against the immediate liquidity of brokerage accounts, considering their specific financial situations and goals. By consulting with financial experts, such as Bright Advisers, families can develop tailored strategies that not only reduce financial stress but also empower them to achieve lasting wealth and stability.
Together, we can navigate this journey toward financial well-being. Understanding these options is the first step in crafting a secure future for you and your loved ones.
Frequently Asked Questions
What is the Mega Backdoor Roth IRA?
The Mega Backdoor Roth IRA is a retirement savings strategy that allows individuals to contribute after-tax dollars to their 401(k) plans and convert those contributions into a Roth IRA, enabling higher tax-advantaged retirement savings.
Who can benefit from the Mega Backdoor Roth IRA?
High-income earners can particularly benefit from the Mega Backdoor Roth IRA as it allows them to exceed standard contribution limits and significantly enhance their retirement savings potential.
What are the contribution limits for the Mega Backdoor Roth IRA in 2025?
In 2025, individuals under 50 can contribute up to $70,000 to their 401(k) plans through the Mega Backdoor Roth strategy.
What is a brokerage account?
A brokerage account is a taxable investment account that allows individuals to buy and sell various investment products, such as stocks, bonds, and mutual funds, without contribution limits.
What are the advantages of using a brokerage account?
Brokerage accounts provide greater flexibility in investment choices and immediate access to funds, making them advantageous for families needing liquidity for short-term financial goals or emergencies.
How can families decide between a Mega Backdoor Roth IRA and a brokerage account?
Families can evaluate their unique financial situations and long-term goals with the support of financial advisors, like Bright Advisers, to make informed decisions that align with their needs, whether to bolster retirement savings or maintain liquidity.
Why is personalized financial planning important in navigating these options?
Personalized financial planning and tax optimization strategies help families effectively navigate the choices between Mega Backdoor Roth IRAs and brokerage accounts, ultimately reducing financial stress and enhancing overall financial security.
List of Sources
- Understanding Mega Backdoor Roth and Brokerage Accounts
- Mega Backdoor Roth – A Perfect Fit for Solo 401(k) Plans (https://employeefiduciary.com/blog/mega-backdoor-roth)
- 10 Essential Facts About the Max Mega Backdoor Roth for Young Families – Bright Advisers (https://brightadvisers.com/10-essential-facts-about-the-max-mega-backdoor-roth-for-young-families)
- UNDERSTANDING MEGA BACKDOOR ROTH CONTRIBUTIONS – Baltimore Washington Financial Advisors (https://bwfa.com/understanding-mega-backdoor-roth-contributions)
- Mega Backdoor Roth (2025): Limits, Steps & Big Benefits (https://districtcapitalmanagement.com/mega-backdoor-roth)
- Mega Backdoor Roths: How They Work, Limits – NerdWallet (https://nerdwallet.com/article/investing/mega-backdoor-roths-work)
- Comparing Benefits: Mega Backdoor Roth vs. Brokerage Accounts
- Mega Backdoor Roths: How They Work, Limits – NerdWallet (https://nerdwallet.com/article/investing/mega-backdoor-roths-work)
- Tax Advantages Of The Mega Backdoor Roth (https://fa-mag.com/news/tax-advantages-of-the-mega-backdoor-roth-51168.html)
- 5 Ways To Know If A Mega Backdoor Roth Makes Sense For You | Bankrate (https://bankrate.com/retirement/how-to-know-if-you-need-a-mega-backdoor-roth-ira)
- Evaluating Drawbacks: Challenges of Mega Backdoor Roth and Brokerage Accounts
- Mega Backdoor Roths: How They Work, Limits – NerdWallet (https://nerdwallet.com/article/investing/mega-backdoor-roths-work)
- Why the Mega Backdoor Roth Rarely Works – Monument Wealth Management (https://monumentwealthmanagement.com/resource/mega-back-door-roth)
- Mega Backdoor Roth IRA: The Ultimate 2025 Guide for High-Income Savers (https://thehourlyadvisor.com/mega-backdoor-roth-ira-2025)
- Determining Suitability: Which Option Fits Your Financial Goals?
- Mega Backdoor Roths: How They Work, Limits – NerdWallet (https://nerdwallet.com/article/investing/mega-backdoor-roths-work)
- Mega Backdoor Roth Explained: Eligibility, Contribution Limits, and Tax Benefits (https://withum.com/resources/mega-backdoor-roth-explained-eligibility-contribution-limits-and-tax-benefits)
- 10 Essential Facts About the Max Mega Backdoor Roth for Young Families – Bright Advisers (https://brightadvisers.com/10-essential-facts-about-the-max-mega-backdoor-roth-for-young-families)

Kevin has advised high-income W-2 tech and biotech families since 2015, and leads the education-first Age Five Family Office from Brea, California.
Connect on LinkedIn → · About KevinThis is part of how we approach Tax Management for high-income W-2 families at Bright Advisers.
Keep reading