

Key Highlights
- Liquidity events allow shareholders to convert ownership into cash or accessible assets, impacting financial situations significantly.
- Examples of liquidity events include IPOs, mergers, and acquisitions, which can lead to substantial cash influxes for families.
- Understanding liquidity events is crucial for families with stock options or equity compensation to reassess financial plans.
- Estate tax implications are significant, especially in states like New York, where exceeding the $7.35 million exemption can result in high tax bills.
- Strategic tax planning steps include developing a tax baseline, considering tax-smart strategies, optimising compensation, engaging in charitable giving, and consulting with tax professionals.
- Families should diversify investments, reevaluate financial goals, consider tax efficiency, conduct regular portfolio reviews, and seek expert advice post-liquidity event.
- Bright Advisers emphasises fiduciary duty and transparency in helping families navigate financial complexities and develop personalised strategies.
Introduction
Imagine facing a sudden windfall and feeling lost about what to do next – this is the reality for many families after a liquidity event. These pivotal moments, like IPOs or acquisitions, can significantly change a family’s financial landscape, bringing both exciting opportunities and daunting challenges.
We’re here to share some friendly strategies for year-end tax planning that can help you feel more secure about managing your newfound wealth. It’s important to understand the implications of these events and how they can affect your family’s financial future.
Let’s explore how families can not only tackle immediate tax challenges but also pave the way for a brighter financial future together.
Define Liquidity Events and Their Importance
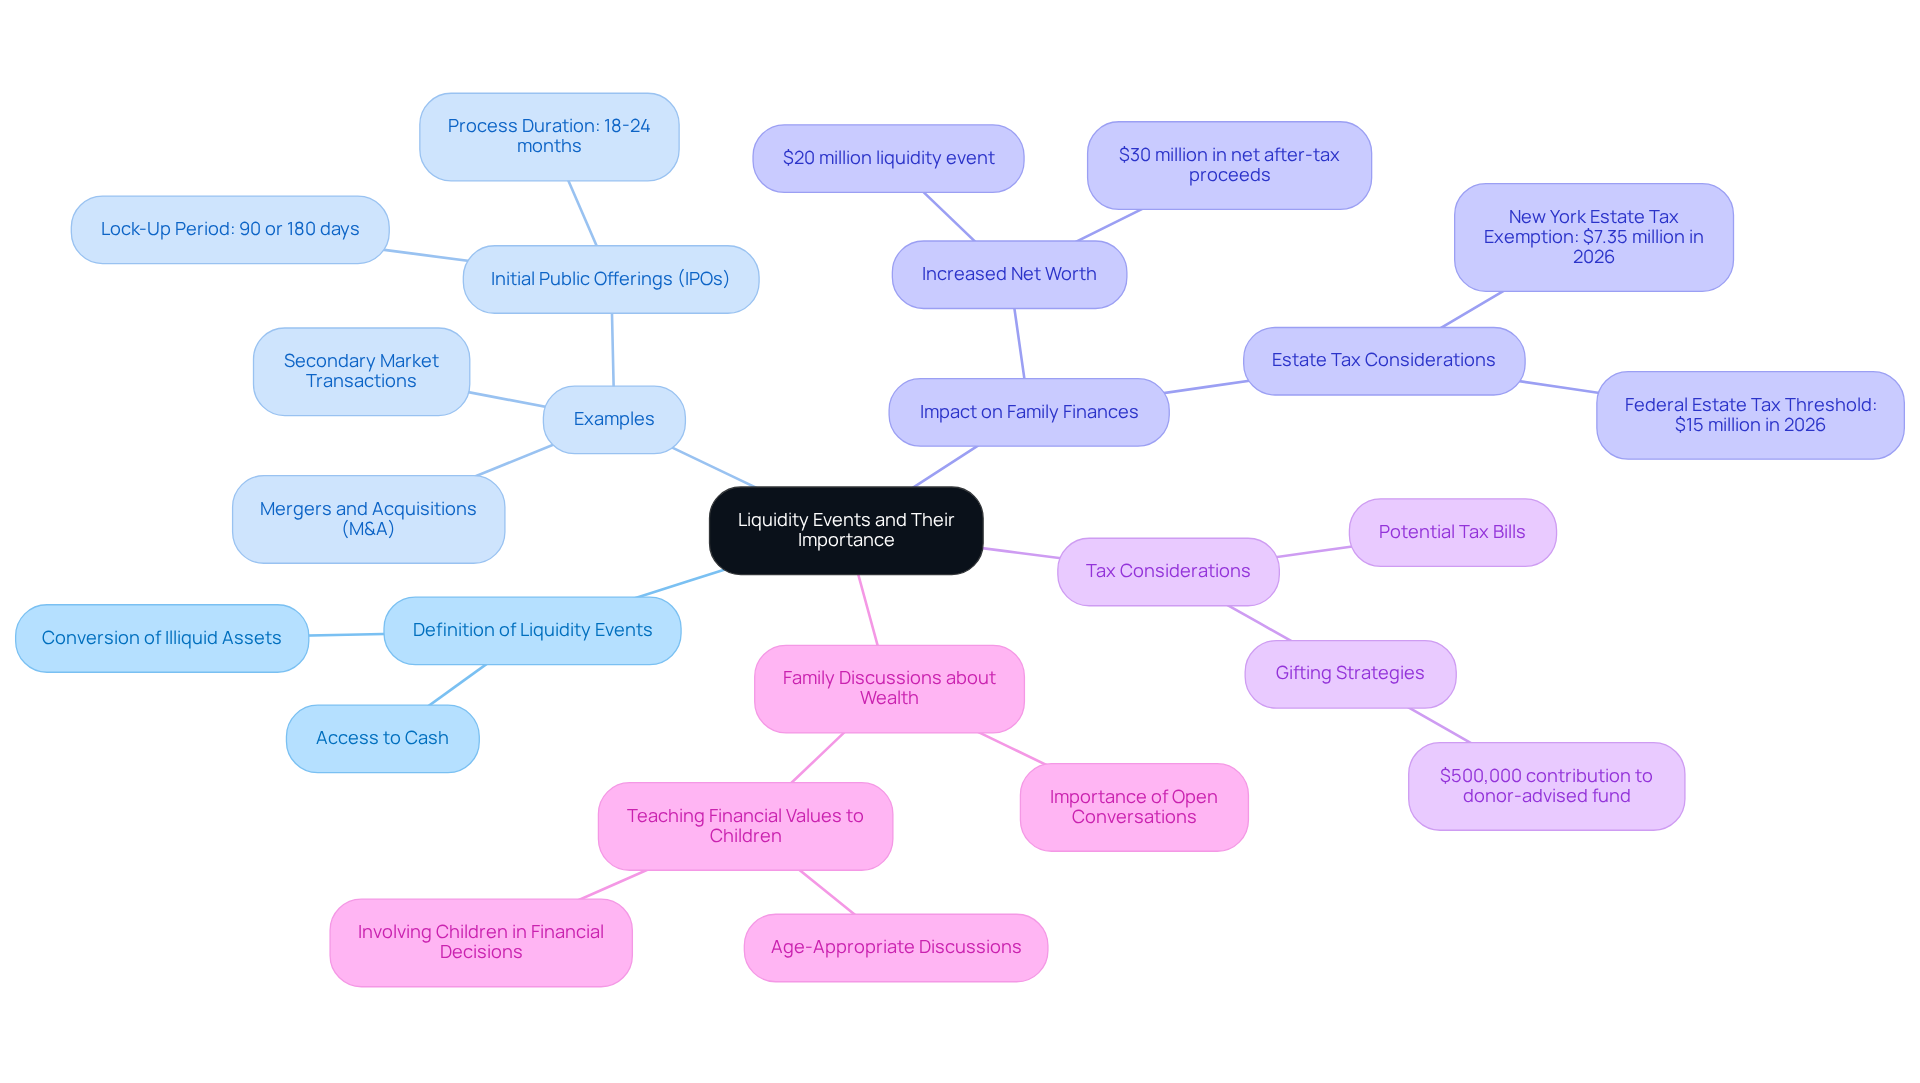
Imagine the moment when your family’s financial landscape shifts dramatically, and you’re left wondering how to navigate this new reality. A liquidity transaction is a way for shareholders to turn their ownership in a company into cash or other easily accessible assets. You might have heard of things like IPOs, mergers, or acquisitions – these are all examples of liquidity events that can impact families like yours.
If your family has stock options or equity compensation, understanding these liquidity events is crucial, as they can really change your financial situation. It’s important to reassess your plans, especially since exceeding the estate tax exemption can lead to significant tax bills, particularly in places like New York, where the exemption is $7.35 million in 2026.
At Bright Advisers, we’re here to help families like yours navigate these complexities with tailored tax strategies and investment management services that truly make a difference. When a company goes public, it can mean a big cash influx for employees, bringing both exciting opportunities and some challenges to consider. With this new wealth, it’s essential to plan carefully to manage it well for your family’s future.
Families also need to think about estate taxes, especially in states like New York, where exceeding the $7.35 million exemption in 2026 can lead to hefty tax bills. Recognizing the importance of liquidity events helps families prepare for the financial decisions that come next, ensuring they can manage their wealth wisely.
Talking openly about money values and goals during these transitions can help instill a sense of responsibility in younger generations, guiding them through the complexities of managing wealth. At Bright Advisers, we understand the unique challenges families with young children face during these transitions, and we’re here to support you. Joanna Dingle, our National Director of Family Engagement, reminds us that ‘Wealth without values is a fragile inheritance – starting early, honest conversations with kids about money and meaning is the true legacy that lasts across generations.’
Working with Bright Advisers, families can develop personalized financial strategies that not only address immediate needs but also lay the groundwork for lasting economic stability and educational readiness.
Understand Tax Implications of Liquidity Events
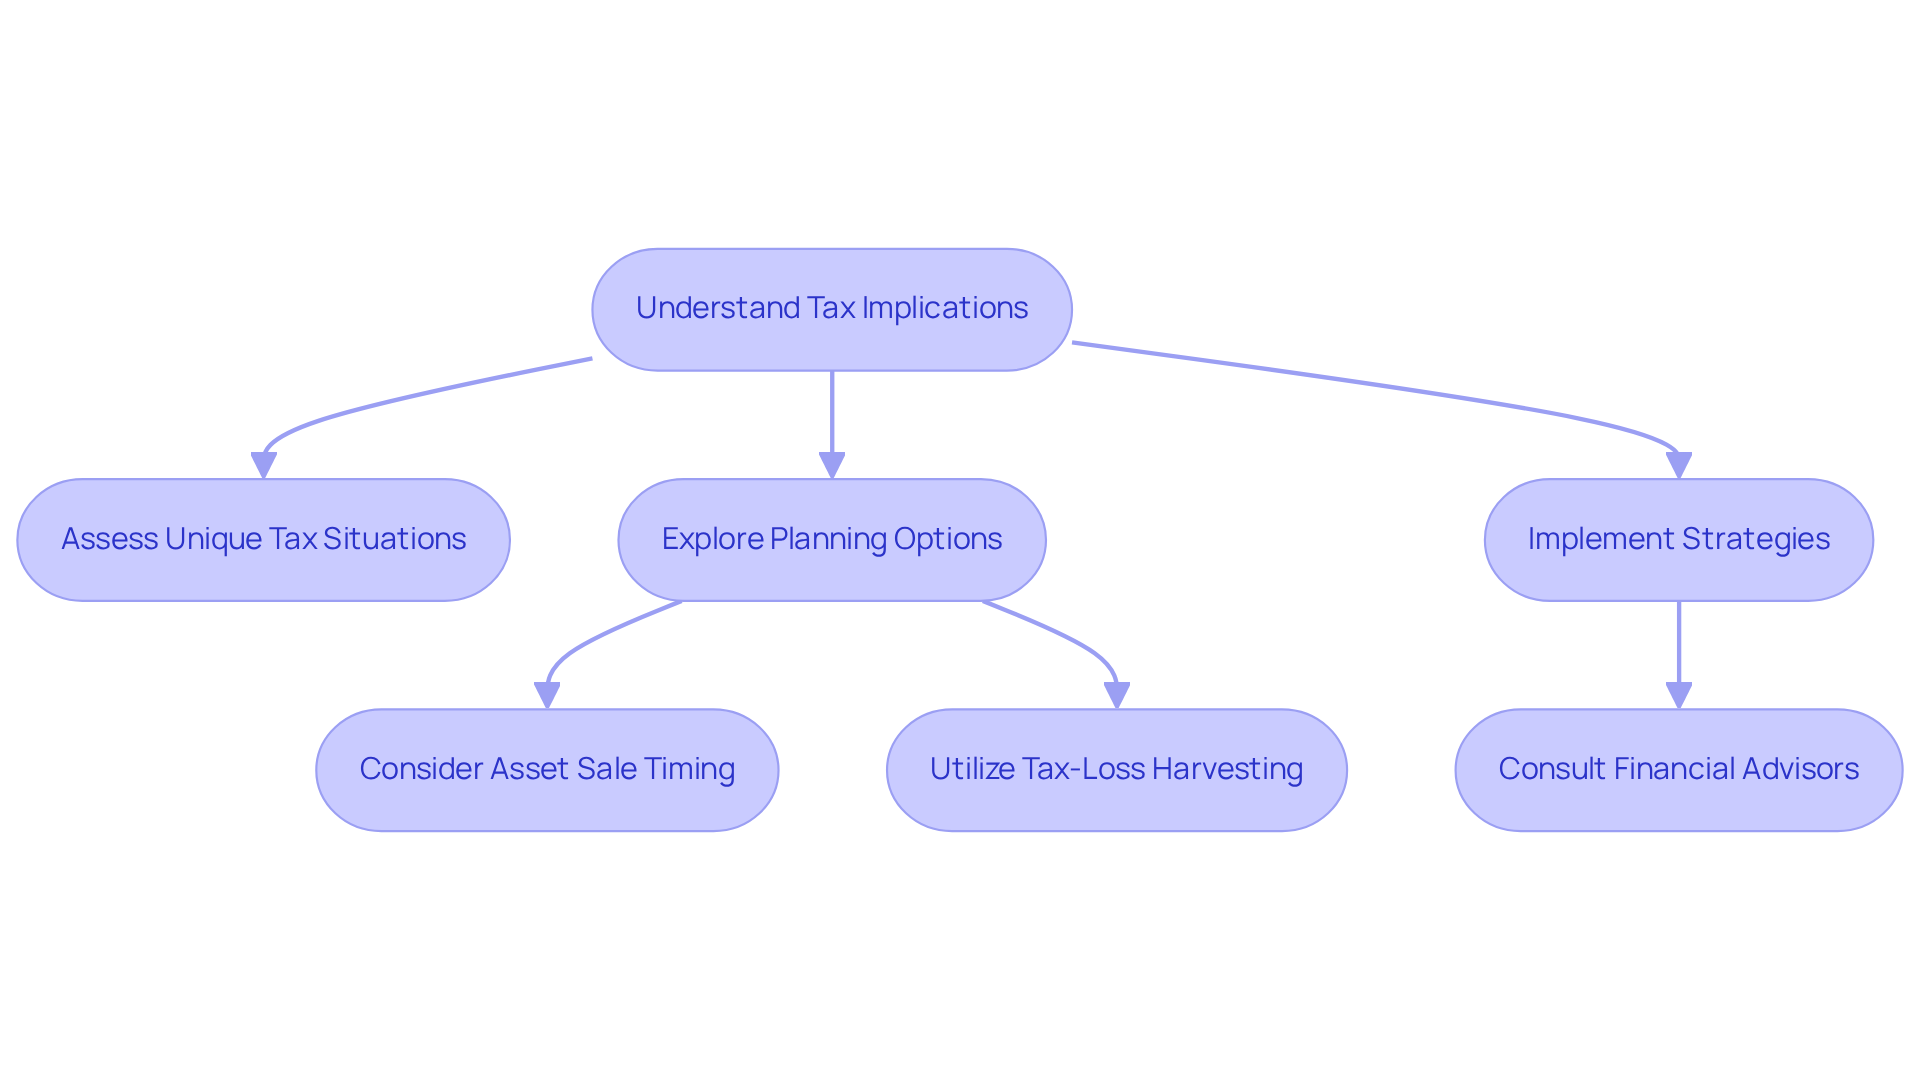
Imagine facing unexpected tax bills just when you thought you were on solid financial ground. Many families, even those with good incomes, can feel overwhelmed by unexpected tax obligations that come from not planning ahead. It’s important for parents to be aware of how their unique tax situations can affect their family’s finances, especially since state tax rates can differ widely.
By planning ahead and exploring options like spreading out asset sales, families can ease their tax burdens and keep more of what they earn for their loved ones. Together, we can navigate this journey and secure a brighter future for our children.
Implement Strategic Tax Planning Steps
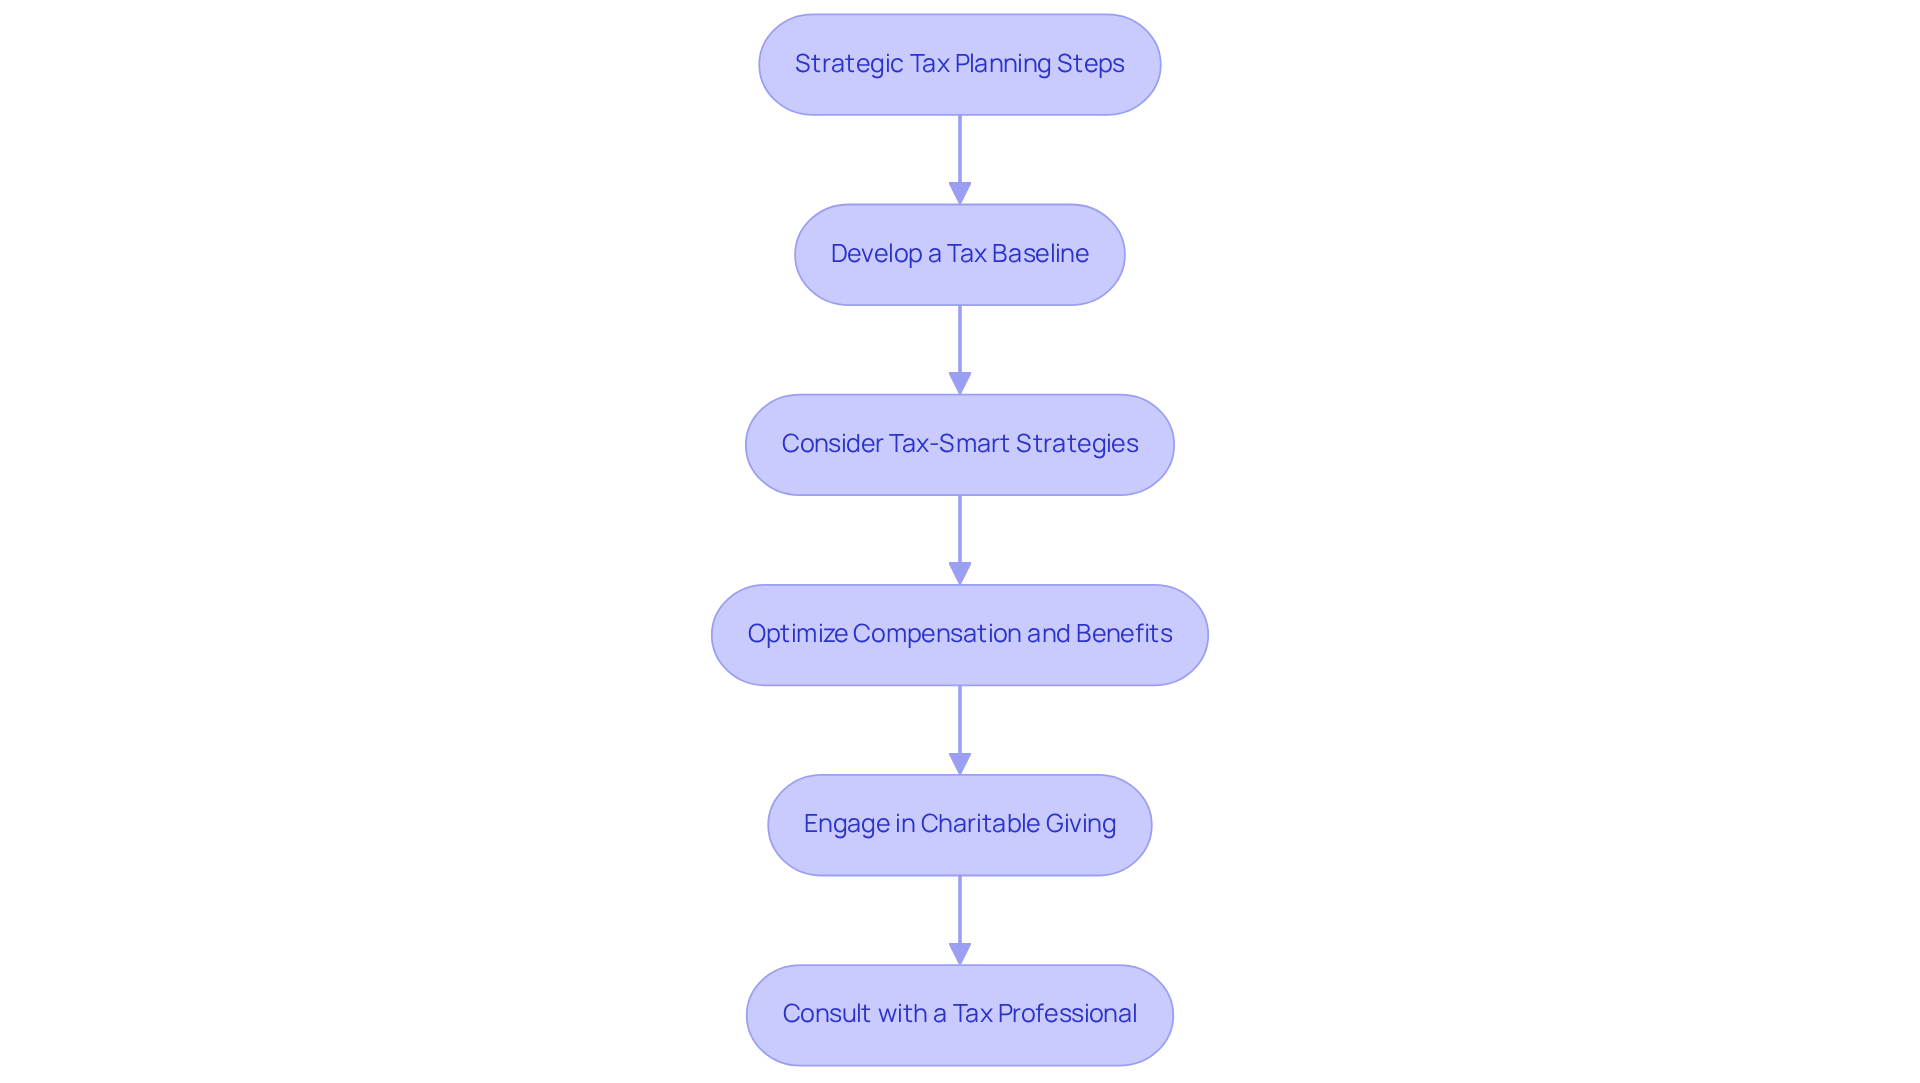
Imagine facing a liquidity event and feeling overwhelmed by the tax implications that follow. To effectively manage these implications, families should consider a few strategic steps:
-
Develop a Tax Baseline: It’s important to take a moment to evaluate your current tax situation and see how a liquidity event might impact your overall tax liability. This means looking closely at your income sources, deductions, and credits.
-
Consider Tax-Smart Strategies: Explore options like tax-loss harvesting, where you sell underperforming investments to offset gains, or making tax-wise gifts to children to reduce taxable income. Engaging in charitable giving in the same tax year as a liquidity event can help offset a large income spike, reducing tax liability. Bright Advisers has effectively assisted households like Allison and Brian in utilizing these strategies to improve their economic results.
-
Optimize Compensation and Benefits: If you have stock options, think about the timing of exercising them. Delaying exercise until a more favorable tax year can help lighten your tax burden.
-
Engage in Charitable Giving: Donating appreciated stock can provide a double benefit: you avoid capital gains tax and receive a charitable deduction. This method was crucial for families aiming to secure their financial future while contributing to causes they care about.
-
Consult with a Tax Professional: Given the complexities of tax laws, working with a tax advisor can help tailor strategies to your specific situation, ensuring compliance and optimization of your tax position. Bright Advisers emphasizes the importance of professional guidance in navigating these challenges.
Case Studies on Strategic Tax Planning for Families After Liquidity Events
-
Sequence Sales and Cash Flows Across Tax Years: This strategy emphasizes the importance of timing in managing sales, bonuses, and distributions to optimize tax outcomes. By coordinating timing across income, distributions, and sales, families can achieve lower tax outflows, steadier liquidity, and fewer end-of-year surprises, as demonstrated in the success of Allison and Brian.
-
Place Assets for Tax-Efficient Returns: Families that strategically locate assets can capture compounding benefits that traditional calculations may overlook, improving overall post-tax performance. This involves placing high-turnover or ordinary-income assets in sheltered accounts to enhance after-tax returns.
-
Engage in Charitable Giving with Donor-Advised Funds: Utilizing donor-advised funds allows families to bunch deductions in high-income years while maintaining control over grant timing. This strategy offers flexibility and efficiency in charitable giving, allowing families to enhance tax deductions and manage cash flow predictably.
By taking these steps, you can protect your family’s future and ensure that your wealth works for you, not against you. Remember, taxes can reduce returns by as much as 2% per year on average, highlighting the importance of proactive tax planning. Families interested in learning more about these strategies can join our current waitlist for personalized guidance.
Manage Investments After Liquidity Events
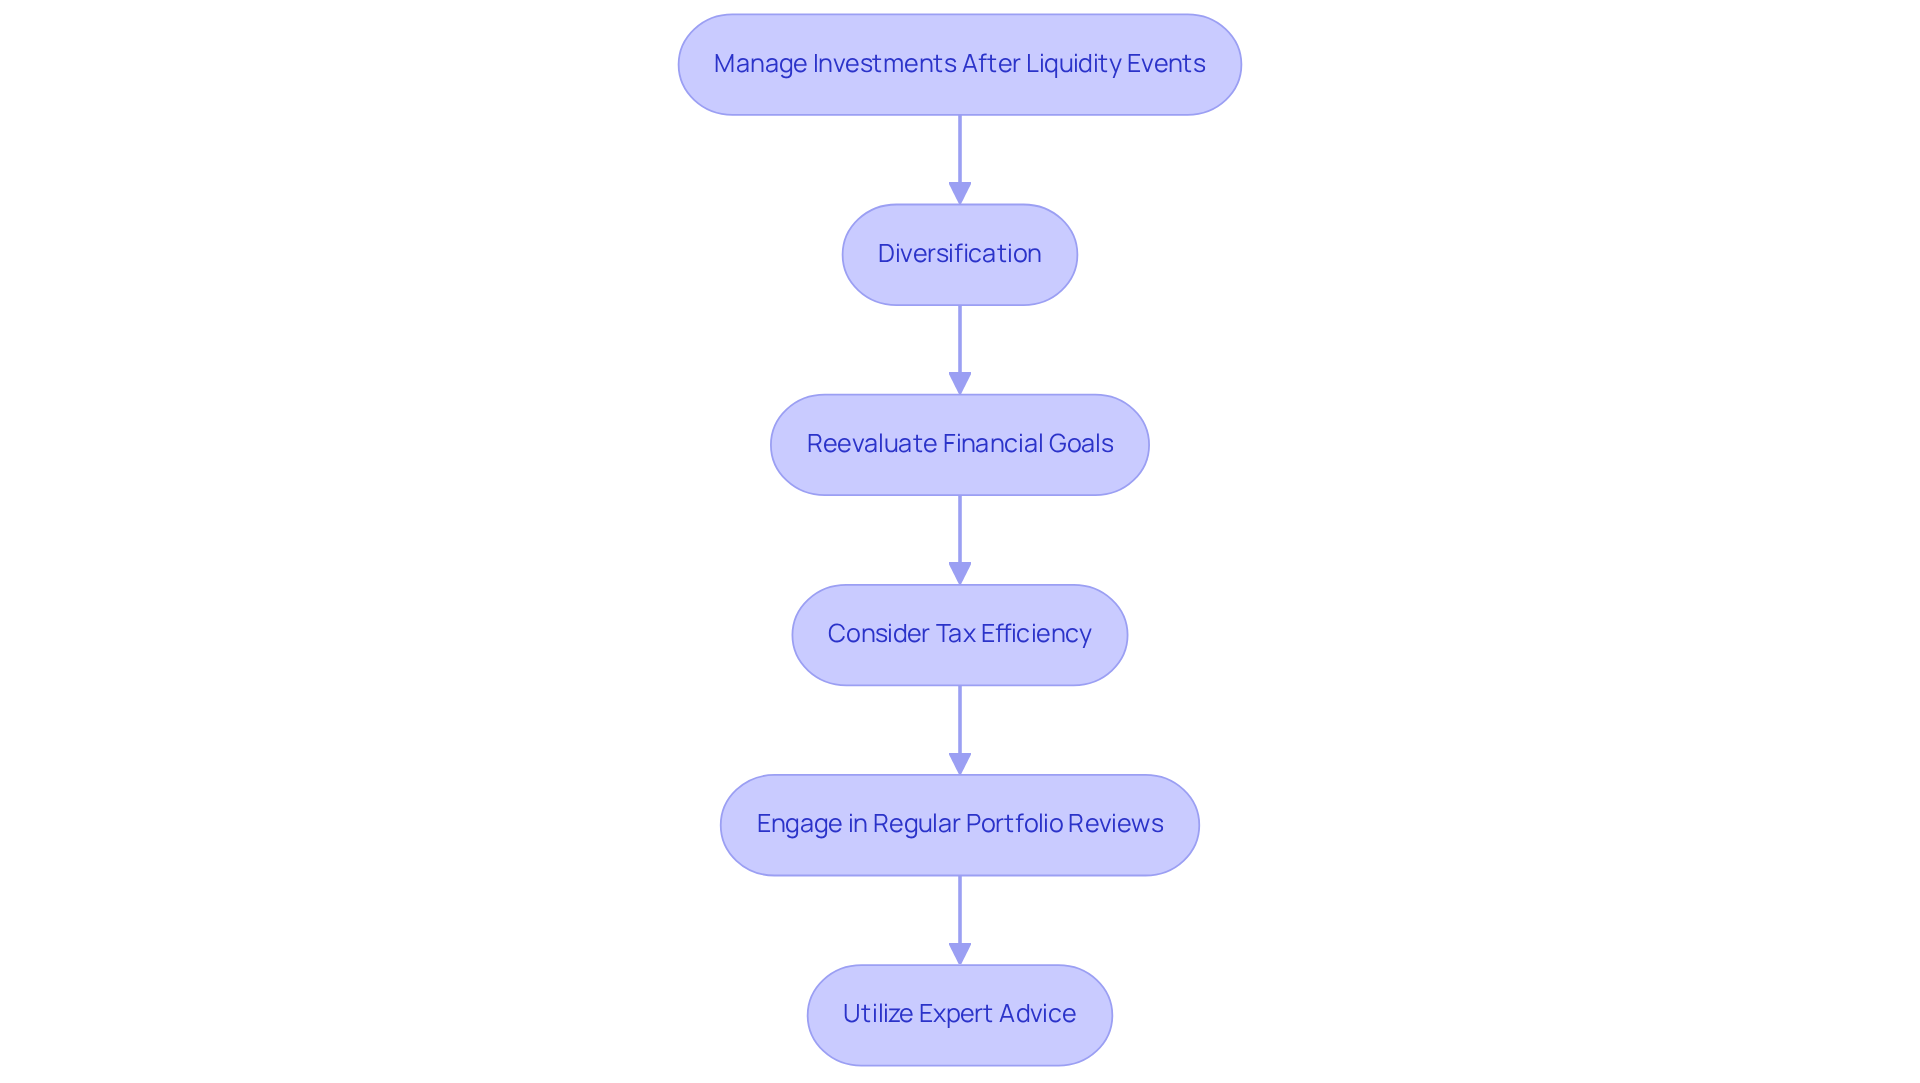
After a significant financial change, many families find themselves at a crossroads, unsure of how to proceed. Here are some essential considerations to help you navigate this journey:
-
Diversification: Putting all your money in one place can be risky. Spreading investments across different sectors and asset types helps reduce risk and can enhance overall returns. A well-diversified portfolio can protect you from major market losses while potentially yielding better long-term results.
-
Reevaluate Financial Goals: New financial opportunities often mean it’s time to revisit your family’s monetary objectives. Think about your family’s future – education, retirement, and giving back. Make sure your investment strategies reflect these evolving priorities.
-
Consider Tax Efficiency: Using smart investment options can help you save on taxes. This is especially important for families living in high-tax states, where strategic planning can lead to significant savings.
-
Engage in Regular Portfolio Reviews: Regularly checking and adjusting your investment portfolio is crucial to keep it aligned with your family’s financial situation and goals. This proactive approach allows you to adapt to changing market conditions and personal circumstances.
-
Utilize Expert Advice: Working with a fiduciary advisor, like Bright Advisers, can provide personalized strategies that align with your values and financial goals. This comprehensive approach to wealth management ensures that your family is well-equipped to navigate the complexities of your financial landscape, particularly in relation to liquidity after vesting year end tax planning.
By taking these steps, you can ensure your family’s financial future is secure and aligned with your values.
Conclusion
Imagine facing a sudden financial change and feeling unsure about your family’s future. Navigating liquidity after a vesting event is a critical process for families, especially those with young children. It’s crucial to grasp how liquidity events affect your family’s financial planning. By understanding these events and their implications, you can make informed decisions that not only address immediate financial needs but also secure your long-term financial future.
Let’s explore some key strategies that can help your family navigate these tricky financial waters:
- Understanding tax implications
- Managing investments effectively
Each aspect plays a vital role in ensuring a smooth transition. Engaging in proactive discussions about your financial values and goals can further enhance your family’s ability to manage wealth responsibly.
The importance of effective tax and investment strategies cannot be overstated. We encourage you to reach out to professionals like Bright Advisers for personalized support on this journey. By prioritizing strategic planning and open communication, your family can ensure that your wealth serves as a lasting legacy of security and opportunity for generations to come.
Frequently Asked Questions
What is a liquidity event?
A liquidity event is a transaction that allows shareholders to convert their ownership in a company into cash or other easily accessible assets. Examples include initial public offerings (IPOs), mergers, and acquisitions.
Why are liquidity events important for families?
Liquidity events can significantly impact a family’s financial situation, especially if they hold stock options or equity compensation. Understanding these events is crucial for reassessing financial plans and managing potential tax implications.
What are the tax implications of liquidity events?
Exceeding the estate tax exemption, particularly in states like New York where the exemption is $7.35 million in 2026, can lead to substantial tax bills. Families need to be aware of these implications when navigating liquidity events.
How can Bright Advisers assist families during liquidity events?
Bright Advisers provides tailored tax strategies and investment management services to help families navigate the complexities of liquidity events and manage their newfound wealth effectively.
What should families consider after a liquidity event?
Families should carefully plan how to manage the cash influx from a liquidity event, considering both immediate needs and long-term financial stability. This includes addressing estate taxes and developing personalized financial strategies.
How can families prepare younger generations for wealth management?
Open discussions about money values and goals during transitions can instill a sense of responsibility in younger generations. Bright Advisers emphasizes the importance of starting early, honest conversations about money and its meaning.
Who is Joanna Dingle and what is her perspective on wealth management?
Joanna Dingle is the National Director of Family Engagement at Bright Advisers. She believes that ‘Wealth without values is a fragile inheritance,’ highlighting the importance of instilling financial values in children for lasting legacies.
List of Sources
- Define Liquidity Events and Their Importance
- Financial Planning Following a Liquidity Event | William Blair (https://williamblair.com/Insights/Financial-Planning-Following-a-Liquidity-Event)
- Liquidity Events: Definition, Types & How to Prepare (https://carta.com/learn/equity/liquidity-events)
- Estate Planning After a Liquidity Event: What Changes and What Can’t Wait | Simon Quick Advisors (https://simonquickadvisors.com/insights/estate-planning-after-a-liquidity-event-what-changes-and-what-cant-wait)
- Why Values and Early Conversations Matter When Talking About Wealth (https://bernstein.com/our-insights/insights/2026/articles/why-values-and-early-conversations-matter-when-talking-wealth.html)
- Teaching Kids About Money After a Liquidity Event | Values, Literacy, and Family Conversations (https://rsassetmanagement.com/teaching-kids-about-money-after-a-liquidity-event-values/teaching-kids-about-money-after-liquidity-event)
- Understand Tax Implications of Liquidity Events
- California Capital Gains Tax: 2026 Rates & Rules (Up to 13.3%) | Taxstra (https://taxstra.com/california-capital-gains-tax)
- California’s Long-term Capital Gains Tax (https://edelmanfinancialengines.com/education/tax/capital-gains-tax-california)
- State Capital Gains Tax Rates for 2026: How Much Investors Pay This Year (https://kiplinger.com/taxes/state-capital-gains-tax-rates)
- State Income Tax Planning Considerations for a Liquidity Event (https://withum.com/resources/state-income-tax-planning-considerations-for-a-liquidity-event)
- Implement Strategic Tax Planning Steps
- Navigating Liquidity Events: Tax‑Efficient Strategies for Thoughtful Wealth Planning | PeakSpan Master Classes (https://peakspancapital.com/resources/master-classes/navigating-liquidity-events-tax-efficient-strategies-for-thoughtful-wealth-planning)
- 12 Tactics Wealthy Families Use to Cut Real Tax Drag – Asset Vantage (https://assetvantage.com/blogs/high-net-worth-tax-strategies)
- Tax-smart strategies | Fidelity Investments (https://fidelity.com/learning-center/wealth-management-insights/top-tax-tips)
- Tax Planning for Liquidity Events: Avoid Costly Cash Mistakes (https://kahnlitwin.com/blogs/tax-blog/whats-the-real-cost-of-holding-cash-tax-planning-for-liquidity-events)
- Manage Investments After Liquidity Events
- Why Investment Diversification Matters (https://epwealth.com/blog/why-investment-diversification-matters)
- Preparing for liquidity events in a Single-Family Office (https://linkedin.com/pulse/preparing-liquidity-events-single-family-office-doug-noble-19xne)
- Mastering Family Office Portfolios Strategies for Effective Diversification (https://questorg.com/mastering-family-office-portfolios-strategies-for-effective-diversification)
- Don’t Put All Your Eggs (investments) in one Basket! (https://citizensbank.com/learning/why-diversification-is-important.aspx)
- Diversifying investments for the long run | BlackRock (https://blackrock.com/americas-offshore/en/education/portfolio-construction/diversifying-investments)

Kevin has advised high-income W-2 tech and biotech families since 2015, and leads the education-first Age Five Family Office from Brea, California.
Connect on LinkedIn → · About KevinThis is part of how we approach Tax Management for high-income W-2 families at Bright Advisers.
Keep reading