

Overview
The main question addressed in this article is how young families can navigate the risks associated with Traditional IRAs while maximizing their benefits for retirement savings. Imagine if you could secure a brighter financial future for your family. This article outlines the advantages of tax-deferred growth and potential tax deductions, which can be incredibly beneficial for your family’s long-term goals. However, it’s important to understand the risks as well, such as:
- Tax liabilities on withdrawals
- Early withdrawal penalties
- Market volatility
To effectively mitigate these risks, we provide strategies like:
- Diversification
- Consulting with a wealth advisor
Together, we can navigate this journey and ensure that your family’s financial future remains secure. Remember, we’re here for you every step of the way, helping you make informed decisions that align with your family’s values and aspirations.
Key Highlights:
- Traditional IRAs allow pre-tax contributions that grow tax-deferred, offering families a way to save for retirement effectively.
- Contributions may be tax-deductible, potentially lowering taxable income and providing immediate financial relief.
- Investment earnings within the IRA grow tax-free until withdrawal, aiding in wealth accumulation over time.
- In 2025, individuals can contribute up to $6,500 annually, with an increased limit of $7,500 for those aged 50 and older.
- Withdrawals are taxed as ordinary income, and early withdrawals before age 59½ incur a 10% penalty.
- Families face risks such as tax liabilities on withdrawals, early withdrawal penalties, and market risks affecting investment value.
- Required Minimum Distributions (RMDs) start at age 73, necessitating careful tax planning to avoid unexpected liabilities.
- Strategies to mitigate IRA risks include diversifying investments, planning withdrawals, staying informed on tax laws, and consulting a wealth advisor.
- Understanding tax implications and potential penalties is essential for optimizing retirement savings and minimizing costs.
Introduction
In the journey towards financial security, many families find solace in Traditional Individual Retirement Accounts (IRAs) as a thoughtful tool for retirement savings. These tax-advantaged accounts come with a host of benefits, from tax deductions on contributions to tax-deferred growth, making them appealing options for those eager to nurture their wealth over time.
Yet, the world of Traditional IRAs can feel overwhelming. Families must carefully consider potential risks, such as:
- Tax liabilities on withdrawals
- Early withdrawal penalties
- Market fluctuations
By embracing both the advantages and challenges, families can craft informed strategies that not only maximize their retirement savings but also minimize possible setbacks. Imagine being equipped with the knowledge to make sound financial decisions for your family’s future.
This article explores the essential features, risks, and tax implications of Traditional IRAs, offering valuable insights to support families in making choices that align with their aspirations.
Define Traditional IRA: Key Features and Benefits
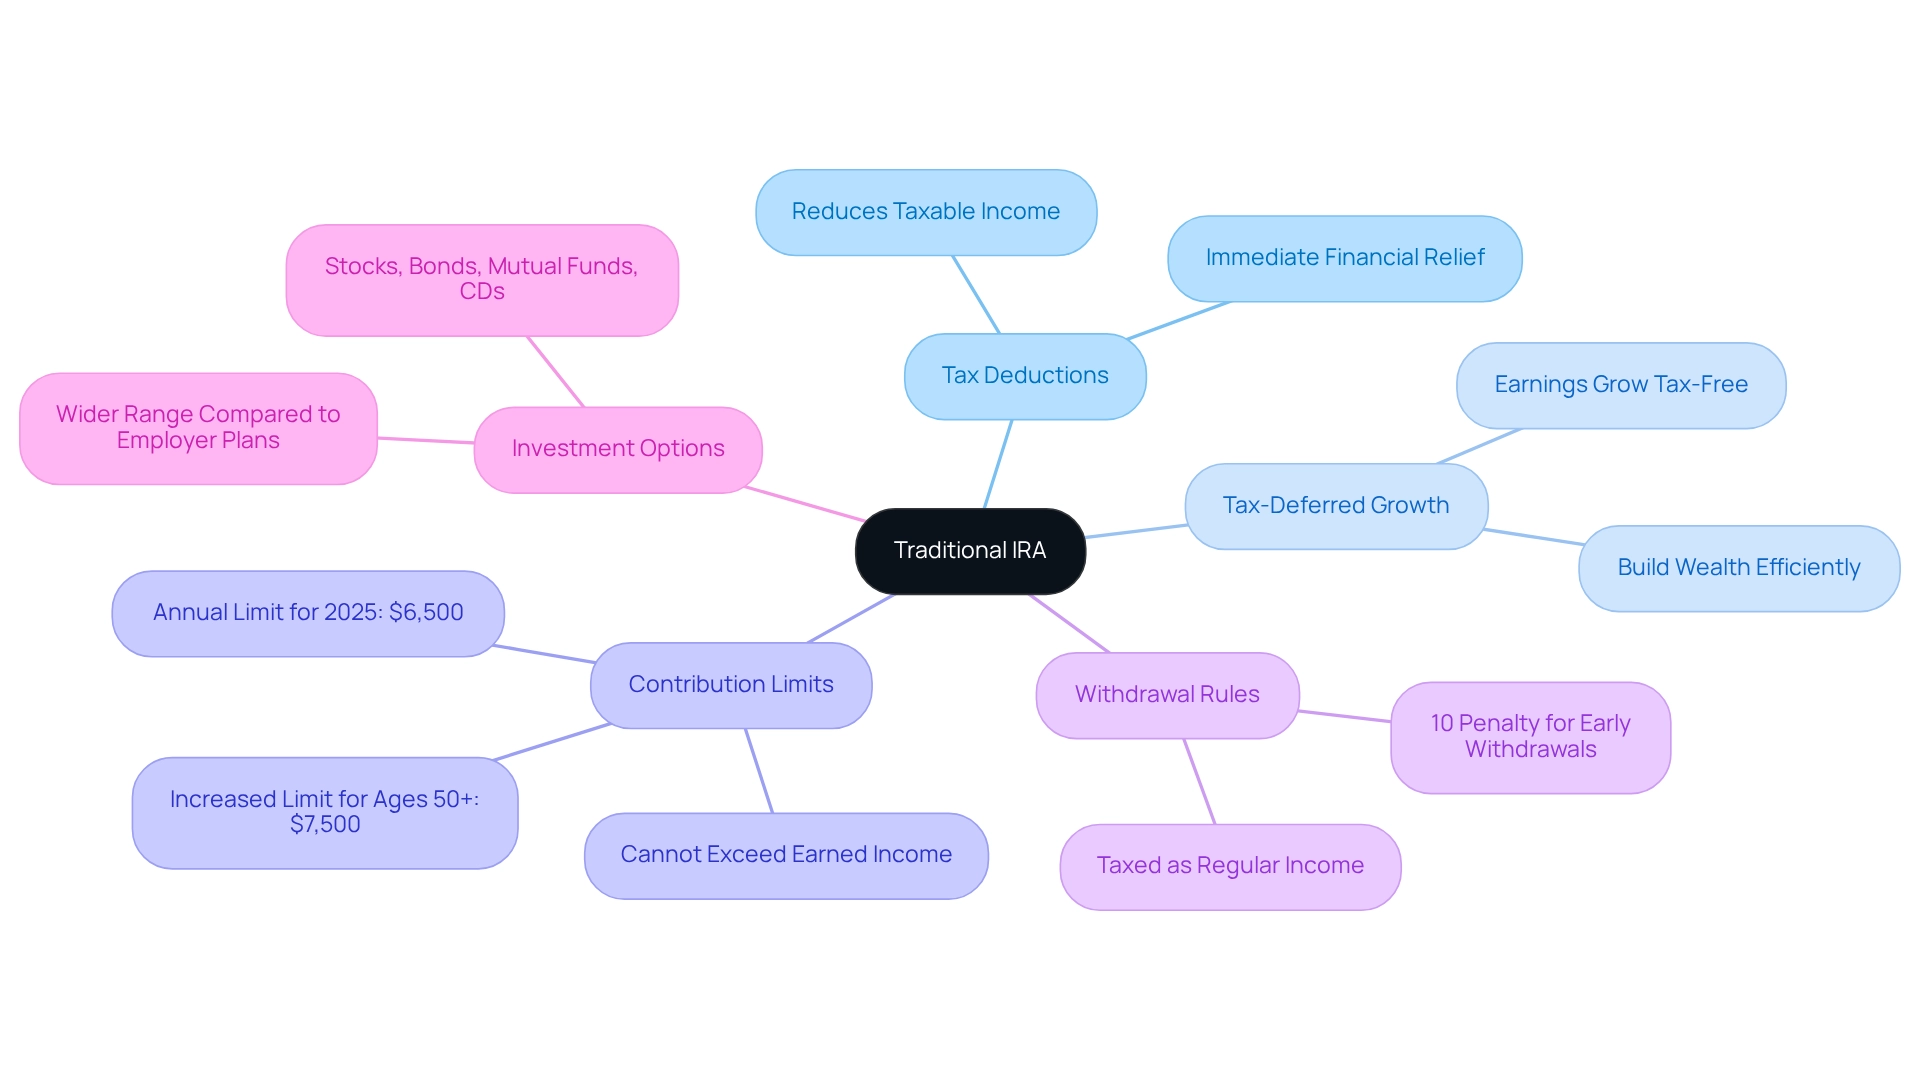
A Conventional Individual Retirement Account (IRA) serves as a nurturing approach to retirement savings, allowing you to contribute pre-tax income that grows tax-deferred until you need it. This type of account offers several essential features that can be particularly beneficial for families:
- Tax Deductions: Contributions to a Traditional IRA may be tax-deductible, potentially reducing your taxable income for the year and providing immediate financial relief. This is crucial for families like Allison and Brian, who have benefited from thoughtful tax planning to enhance their financial well-being.
- Tax-Deferred Growth: The earnings on investments within your IRA grow tax-free until withdrawal, enabling families to build wealth more efficiently over time. This aligns perfectly with the goals of families seeking to secure their financial future, much like Emily and Mark, who found financial freedom through tailored wealth management strategies.
- Contribution Limits: For 2025, individuals can contribute up to $6,500 annually, with an increased limit of $7,500 for those aged 50 and older, allowing for greater savings as retirement approaches. Just remember, total IRA contributions cannot exceed your earned income for the year.
- Withdrawal Rules: Withdrawals are taxed as regular income, and early withdrawals (before age 59½) may incur a 10% penalty, encouraging a long-term savings mindset.
These features make IRAs a compelling choice for families looking to secure their financial future while enjoying immediate tax benefits. Imagine being able to leverage tax-deferred growth to enhance your retirement savings, ultimately freeing up more resources for your children’s education or other important priorities.
At Bright Advisers, we understand the importance of flexibility. We highlight that IRAs offer a broader range of investment options compared to employer-sponsored plans. This customization allows families to tailor their portfolios to their specific risk tolerances and financial goals, further enhancing the appeal of IRAs in 2025. Plus, our commitment to keeping fund fees low ensures that more of your investment returns are preserved, making these accounts more accessible for families.
Real-life stories illustrate how families use IRAs to build wealth. For instance, a family that consistently contributes the maximum amount to their Traditional IRA can significantly boost their retirement savings over time, although they should consider the traditional IRA risks that come with their investment choices. This strategic approach not only prepares them for retirement but also sets a strong financial example for their children, instilling a sense of economic responsibility. Moreover, the experiences of clients like Allison and Brian showcase how Bright Advisers has transformed their financial futures through effective tax optimization and comprehensive planning, making these accounts even more appealing for young families. We’re here for you, ready to help you navigate this journey together.
Identify Risks of Traditional IRAs: What Families Should Know
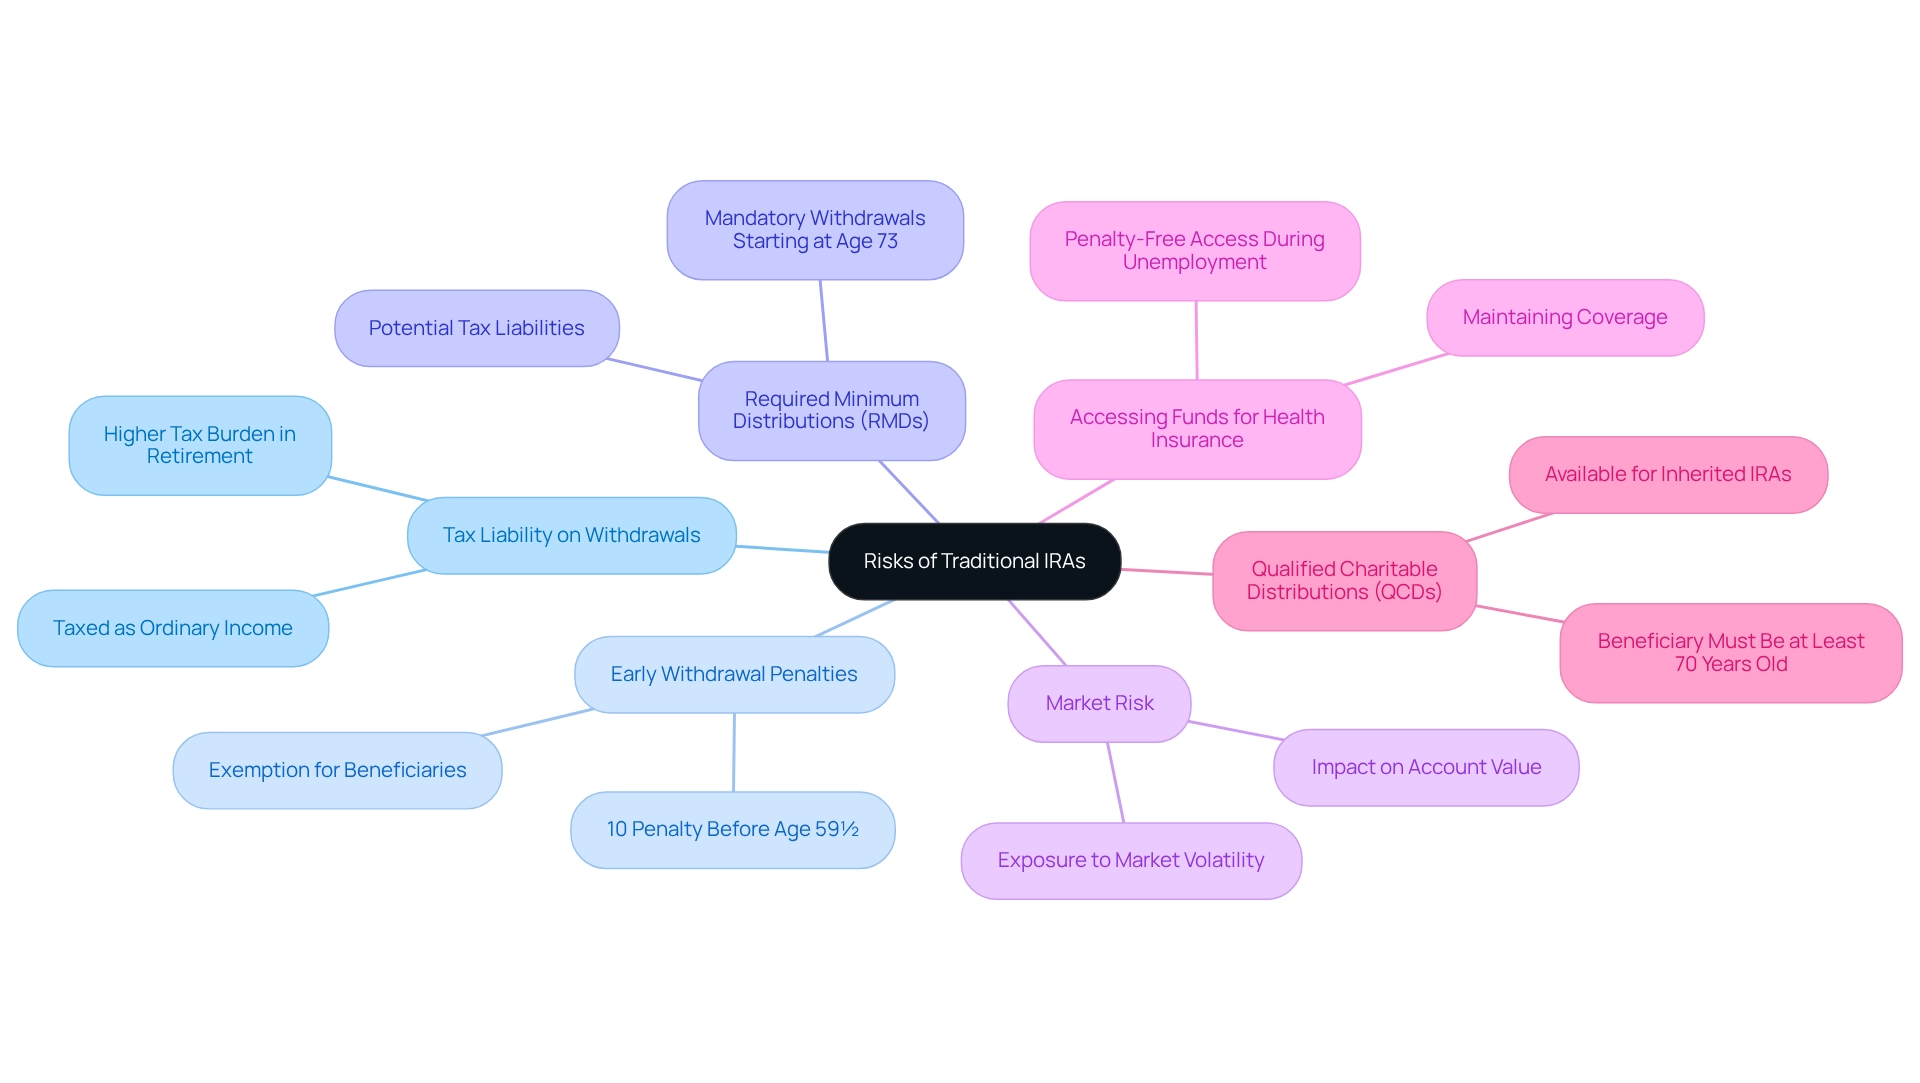
While Traditional IRAs offer valuable benefits for families, it’s essential to recognize the associated risks that can impact your financial journey:
- Tax Liability on Withdrawals: When you withdraw from a Traditional IRA, those funds are taxed as ordinary income. This could lead to a higher tax burden during retirement, which is something to consider if you expect a reduced income later on. For example, Allison and Brian, eager to maximize their financial potential, understood the importance of this aspect in their comprehensive financial strategy. Similarly, Jay and Emma were mindful of tax implications while planning for their children’s education and their own retirement.
- Early Withdrawal Penalties: If you need to access your funds before age 59½, a 10% penalty applies. However, if distributions are made to a beneficiary due to the IRA owner’s death, this penalty is waived. This consideration is crucial for families engaged in estate planning. For instance, Emily and Mark were aware of their liquidity needs as they navigated their financial planning, ensuring they were prepared for any situation.
- Required Minimum Distributions (RMDs): Starting at age 73, account holders must withdraw a minimum amount from their IRAs. This requirement can complicate tax planning and may lead to unexpected tax liabilities if families are unprepared for the additional income. Allison and Brian’s journey illustrates how effective planning can help mitigate these challenges, a lesson that resonates with Jay and Emma as well.
- Market Risk: The investments within a Traditional IRA are exposed to traditional IRA risks resulting from market volatility. Changes in the market can affect the overall value of the account, posing a risk for families relying on these funds for future expenses. Understanding traditional IRA risks is vital for households like Emily and Mark, who are building a strong financial foundation.
- Accessing Funds for Health Insurance: In certain situations, such as unemployment, families may need to access IRA funds to cover health insurance premiums without incurring penalties. Understanding these conditions can help families maintain coverage during tough times.
- Qualified Charitable Distributions (QCDs): For families considering their estate planning options, it’s worth noting that QCDs are available for inherited IRAs if the beneficiary is at least 70 years old. This can provide additional strategies for managing their IRAs effectively.
Recognizing traditional IRA risks empowers families to develop effective strategies that minimize potential downsides, ensuring a more secure financial future. As Brian Dobbis, Retirement Solutions Lead, advises, “File IRS Form 5329 Additional Taxes on Qualified Plans (Including IRAs) and Other Tax-Favored Accounts along with your tax return” to stay informed about tax implications. Together, we can navigate this journey and make informed decisions for our families.
Understand Tax Implications and Penalties: Navigating the Complexities
Navigating the tax implications and penalties of standard IRAs can feel overwhelming, but with a clear understanding of a few critical factors, you can take control of your financial future.
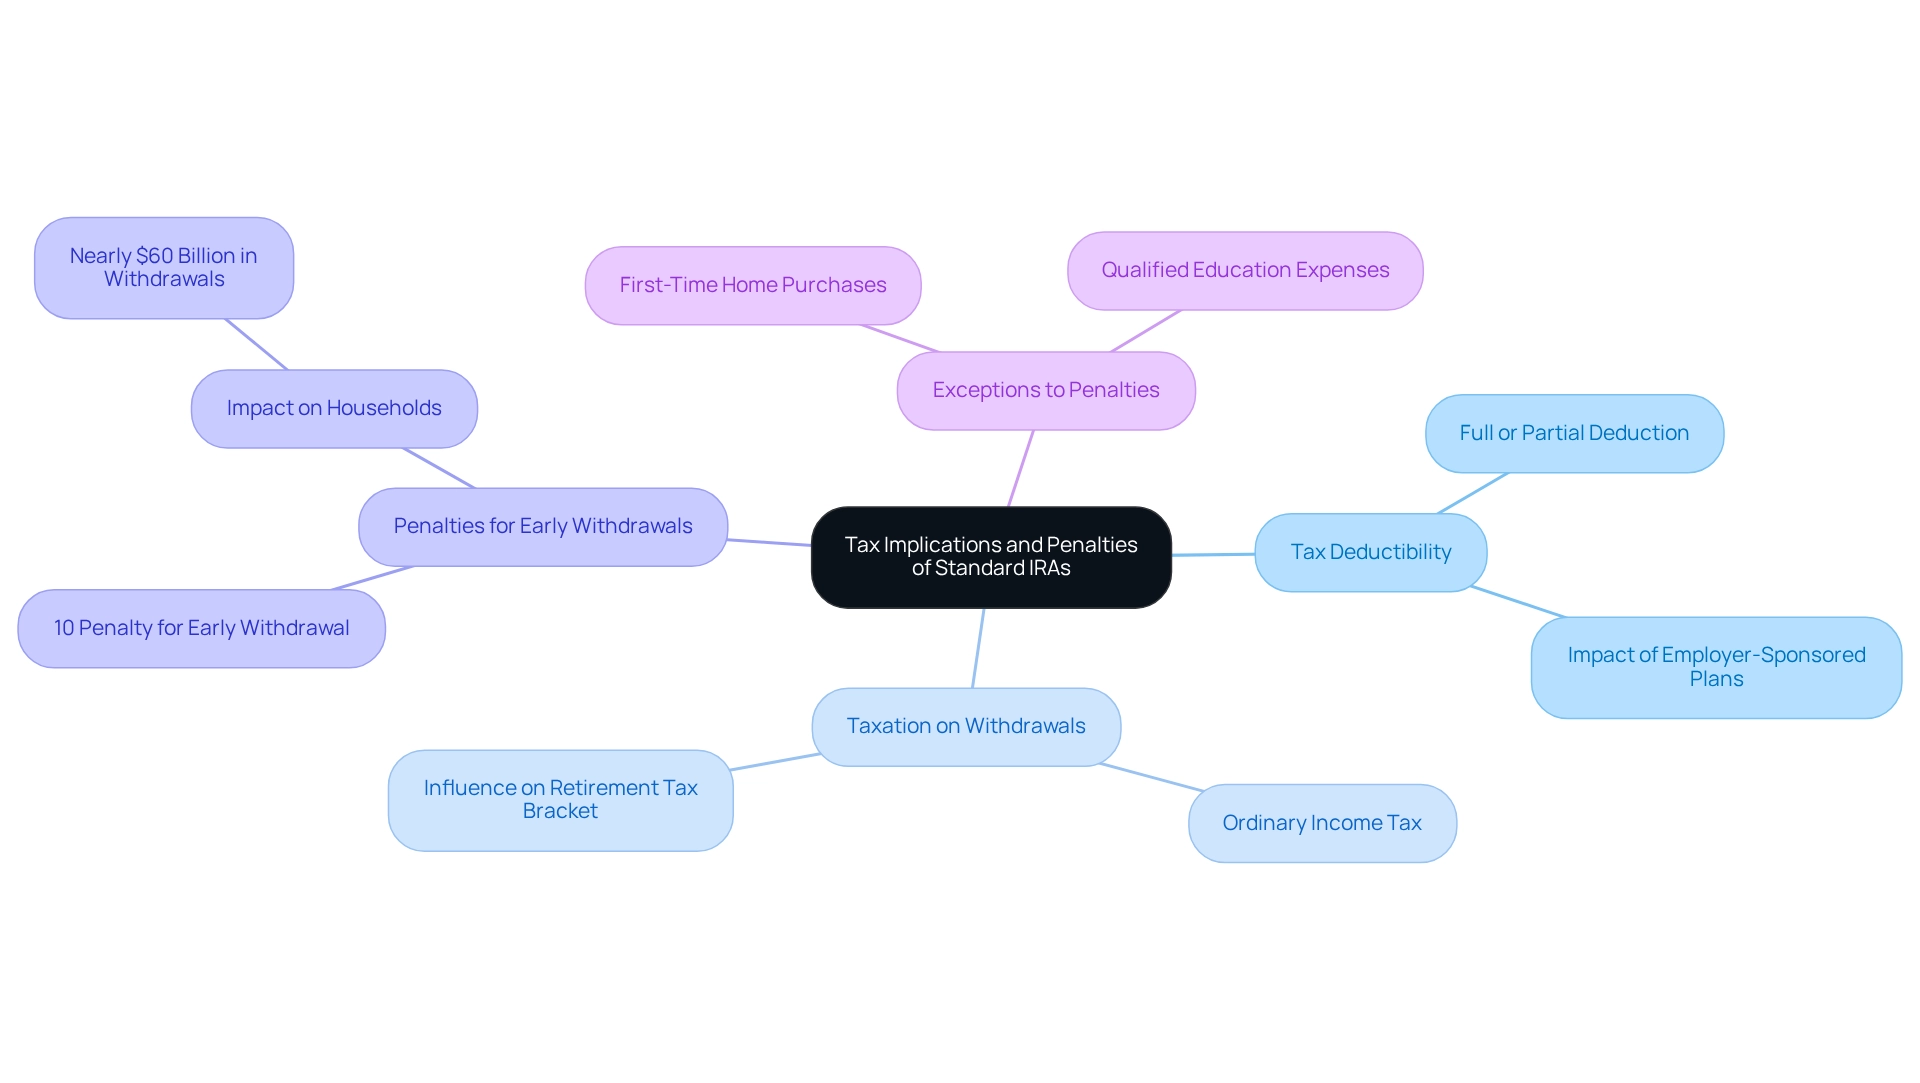
Tax Deductibility: Contributions to a standard IRA may be fully or partially deductible, depending on your income levels and whether you or your spouse participates in an employer-sponsored retirement plan. This can significantly impact your household’s overall tax strategy, especially if you are covered by such a plan, as it may limit the deductible amount. For instance, households like Jay and Emma, who sought guidance from Bright Advisers, were able to optimize their tax planning. By understanding how their contributions would affect their tax situation and the traditional IRA risks involved, they improved their economic strategy.
Taxation on Withdrawals: All withdrawals from a Traditional IRA are taxed as ordinary income, which can influence your tax bracket during retirement. It’s essential to consider how traditional IRA risks and taxes will impact your budgeting in the long run. Emily and Mark, for example, worked with Bright Advisers to develop a comprehensive plan that accounted for these factors, enabling them to make informed decisions about their future income and tax liabilities.
Penalties for Early Withdrawals: If you withdraw funds before age 59½, you will incur a 10% penalty in addition to regular income tax. This penalty can lead to almost $60 billion in withdrawals being transferred annually, placing a strain on households. Young parents must plan their withdrawals carefully to avoid the traditional IRA risks that could lead to penalties. Through their collaboration with Bright Advisers, Allison and Brian learned how to navigate these penalties effectively, ensuring they could access their funds without incurring unnecessary costs.
Exceptions to Penalties: Certain situations, such as first-time home purchases or qualified education expenses, may allow for penalty-free withdrawals. Understanding these exceptions can help you navigate the traditional IRA risks more effectively, providing you with greater flexibility in managing your finances. Bright Advisers empowers families by educating them on these nuances, ensuring you can leverage your IRAs to meet your economic goals without incurring penalties.
A study on the tax revenue implications of withdrawal policies highlights the complex relationship between withdrawal penalties and lifetime tax remittances. It indicates that while raising the age for withdrawals may decrease lifetime tax payments, it could also lead to larger inherited IRA balances. This underscores the necessity for families to navigate these regulations carefully.
By understanding these tax implications, you can strategically plan your contributions and withdrawals, ultimately minimizing your tax burdens and enhancing your overall well-being. If you are a young parent aiming to improve your financial strategy, consider reaching out to Bright Advisers for tailored support in managing your IRA choices. Together, we can navigate this journey and ensure a secure financial future for your family.
Implement Strategies to Mitigate IRA Risks: A Practical Guide
Navigating the world of Traditional IRAs can feel overwhelming, but there are several key strategies that families can embrace to effectively mitigate risks and secure their financial future.
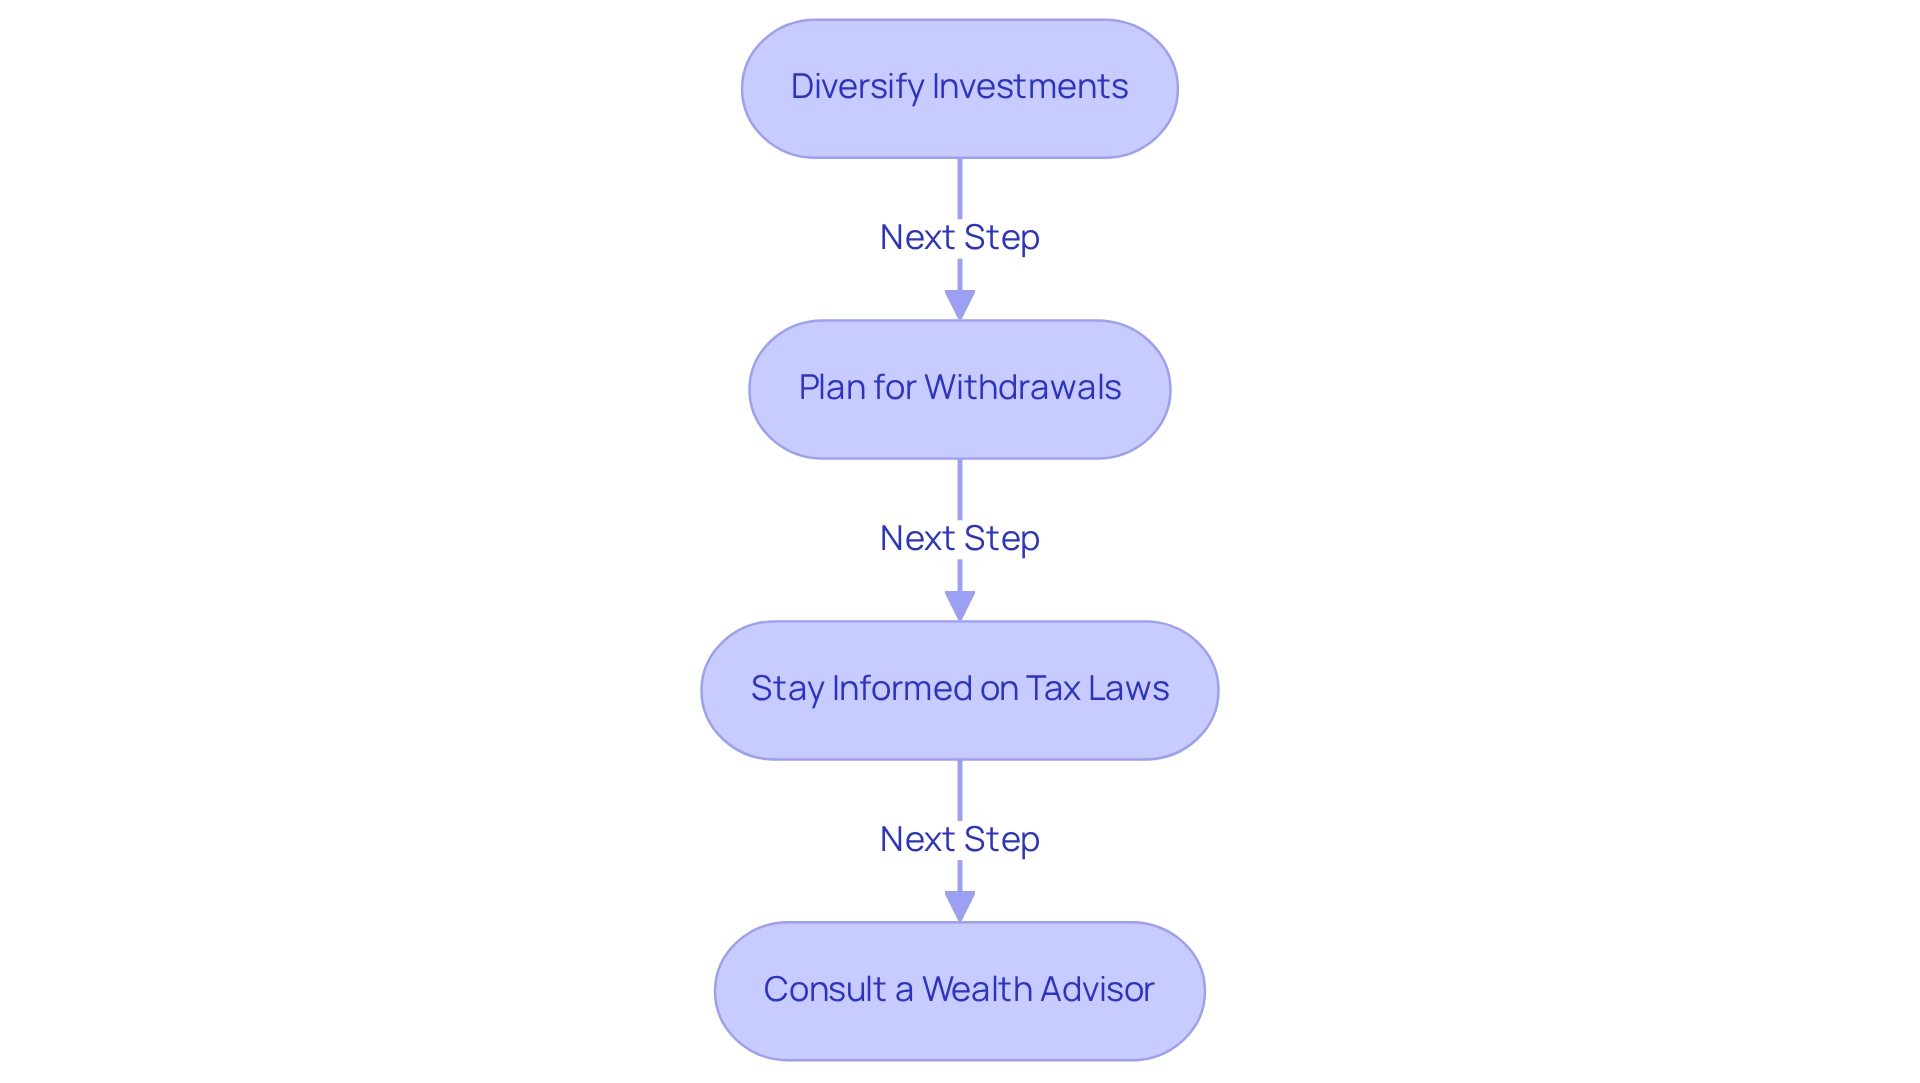
- Diversify Investments: Imagine the peace of mind that comes from knowing your assets are spread across various classes—stocks, bonds, and real estate. This thoughtful allocation not only reduces market risk but also enhances your potential returns. Just like Emily and Mark, who found guidance with Bright Advisers, understanding the unique features of Traditional and Roth IRAs can help you create a diversification strategy tailored to your family’s needs.
- Plan for Withdrawals: It’s important to establish a withdrawal strategy that aligns with your family’s financial goals. As you approach retirement age, considering tax implications and minimizing penalties becomes crucial. By prioritizing withdrawals from taxable accounts first, you can navigate this process more smoothly. Plus, if you’re 50 or older, contributing an extra $1,000 to your retirement accounts can make a significant difference, bringing your total contributions to $8,000.
- Stay Informed on Tax Laws: Regularly reviewing tax laws and IRA regulations is essential for ensuring compliance and optimizing your tax benefits. Understanding the nuances of tax implications can lead to substantial savings over time. Households like Allison and Brian have experienced the benefits of effective tax planning with Bright Advisers, enhancing their economic potential.
- Consult a Wealth Advisor: Partnering with a wealth advisor who specializes in personal wealth management can provide you with strategies that resonate with your financial objectives. Bright Advisers is dedicated to supporting families by offering comprehensive monetary planning, including ways to minimize fund charges and explore tax-loss harvesting options. Remember Albert Einstein’s words: “Compound interest is the eighth wonder of the world. He who understands it, earns it … he who doesn’t … pays it.” This highlights the importance of informed investment strategies.
By adopting these strategies, families can navigate the complexities associated with traditional IRA risks with confidence, ensuring a secure financial future while maximizing their investment potential. We’re here for you, ready to support you on this journey.
Conclusion
Traditional Individual Retirement Accounts (IRAs) offer families a valuable opportunity to secure their financial futures. These accounts combine tax deductions, tax-deferred growth, and flexible investment options, creating a pathway to a more stable tomorrow. Yet, the journey to fully harness these benefits can present challenges. It’s crucial for families to understand potential risks—such as tax liabilities on withdrawals, early withdrawal penalties, and market fluctuations—so they can make informed decisions that protect their loved ones.
Imagine if families recognized the power of strategic planning. By diversifying investments, planning for withdrawals, staying updated on tax laws, and consulting with financial advisors, they can navigate the complexities of Traditional IRAs with confidence. Many families have successfully implemented these strategies, building strong retirement savings while preparing for future expenses. Their stories serve as inspiring reminders of what is possible when we take charge of our financial futures.
Ultimately, the key to leveraging Traditional IRAs lies in finding a balance between embracing their benefits and acknowledging the inherent risks. With the right knowledge and resources, families can optimize their retirement savings, ensuring a secure financial future for themselves and their children. As they engage in thoughtful financial planning, they are not just securing their own futures but also paving the way for lasting wealth and responsibility. Together, we can navigate this journey, making sound decisions today for a brighter tomorrow.
Frequently Asked Questions
What is a Conventional Individual Retirement Account (IRA)?
A Conventional IRA is a retirement savings account that allows you to contribute pre-tax income, which grows tax-deferred until withdrawal.
What are the tax benefits of contributing to a Traditional IRA?
Contributions to a Traditional IRA may be tax-deductible, potentially lowering your taxable income for the year and providing immediate financial relief.
How does tax-deferred growth work in a Traditional IRA?
The earnings on investments within a Traditional IRA grow tax-free until withdrawal, helping families build wealth more efficiently over time.
What are the contribution limits for a Traditional IRA in 2025?
In 2025, individuals can contribute up to $6,500 annually, with an increased limit of $7,500 for those aged 50 and older. Total contributions cannot exceed your earned income for the year.
What are the withdrawal rules for a Traditional IRA?
Withdrawals from a Traditional IRA are taxed as regular income, and early withdrawals (before age 59½) may incur a 10% penalty.
How can IRAs benefit families financially?
IRAs provide immediate tax benefits and the potential for tax-deferred growth, allowing families to secure their financial future and allocate more resources for priorities like children’s education.
What investment options are available in a Traditional IRA?
IRAs offer a broader range of investment options compared to employer-sponsored plans, allowing families to customize their portfolios based on their risk tolerances and financial goals.
How can consistent contributions to a Traditional IRA impact retirement savings?
Consistently contributing the maximum amount to a Traditional IRA can significantly boost retirement savings over time, preparing families for retirement and setting a strong financial example for their children.
How does Bright Advisers assist families with IRAs?
Bright Advisers helps families navigate their financial journey through effective tax optimization and comprehensive planning, making Traditional IRAs more appealing for young families.
List of Sources
- Define Traditional IRA: Key Features and Benefits
- The benefits of traditional IRAs (https://thrivent.com/insights/retirement-planning/the-benefits-of-traditional-iras)
- What is a Traditional IRA? – NerdWallet (https://nerdwallet.com/article/investing/what-is-a-traditional-ira)
- IRA Rules: 8 Things You Need to Know (https://schwab.com/learn/story/ira-rules-8-things-you-need-to-know)
- Identify Risks of Traditional IRAs: What Families Should Know
- Income Tax Treatment of IRA Distributions (https://answerconnect.cch.com/topic/2ce76de67c6b10009f8b90b11c18c902071/income-tax-treatment-of-ira-distributions)
- IRAs: What You Need to Know about the 10% Early Distribution Penalty | Lord Abbett (https://lordabbett.com/en-us/financial-advisor/insights/retirement-planning/2025/iras-what-you-need-to-know-about-the-10-early-distribution-penalty.html)
- Understand Tax Implications and Penalties: Navigating the Complexities
- The impact of withdrawal penalties on retirement savings (https://sciencedirect.com/science/article/pii/S0047272724000197)
- 4 new ways to avoid a tax penalty for early individual retirement account withdrawals (https://cnbc.com/2022/12/28/new-ways-to-avoid-the-ira-early-withdrawal-penalty.html)
- Roth IRA vs. Traditional IRA: Rules & Tax Benefits | Vanguard (https://investor.vanguard.com/investor-resources-education/iras/roth-vs-traditional-ira)
- Implement Strategies to Mitigate IRA Risks: A Practical Guide
- Managing accounts to lower taxes | Vanguard (https://investor.vanguard.com/investor-resources-education/taxes/tax-advantaged-accounts)
- Eight Great Investing Quotes (https://texasfa.com/Eight-Great-Investing-Quotes.c10271.htm)

Kevin has advised high-income W-2 tech and biotech families since 2015, and leads the education-first Age Five Family Office from Brea, California.
Connect on LinkedIn → · About KevinThis is part of how we approach Retirement & Employee Benefits for high-income W-2 families at Bright Advisers.
Keep reading