

Overview
Families today face a crucial decision when it comes to managing their wealth. Public wealth management companies present scalable, technology-driven services with lower fees, appealing to those seeking cost-effective investment management. However, traditional advisors offer personalized financial planning that truly caters to the unique needs of each family.
Imagine if you could navigate the complexities of financial planning with tailored support that understands your family’s specific situation. It’s important to understand that while lower costs are attractive, the value of personalized guidance can be invaluable, especially when addressing complex financial matters.
As families plan for their children’s futures, the expertise of traditional advisors can make a significant difference. They excel in navigating intricate financial landscapes, ensuring that your family’s goals are not just met, but exceeded. Together, we can navigate this journey, ensuring that your family’s financial future is secure and bright.
Ultimately, the choice lies in weighing these trade-offs. Are you looking for cost-effective solutions, or do you value the peace of mind that comes with personalized support? Whatever your decision, remember that we’re here for you, ready to assist you in making the best choices for your family’s future.
Key Highlights:
- Public wealth management firms cater to high-net-worth individuals, offering scalable services like investment management and estate planning through advanced technology.
- Traditional advisors focus on personalized financial planning, addressing unique client needs, which is beneficial for families planning for children’s futures.
- Bright Advisers exemplifies personalized service, providing tailored wealth management strategies regardless of a client’s wealth level.
- The wealth management industry has seen significant growth, with the number of millionaires in North America doubling from 2010 to 2022.
- Families must choose between technology-driven public firms and relationship-focused traditional advisors based on their financial goals and preferences.
- Public wealth management companies offer lower fees (0.65% to 1.00%) but may lack the personalized service found in traditional advisory firms (1% to 1.5%).
- Families should evaluate the trade-offs between cost savings and the value of personalized assistance when selecting an advisor.
- Bright Advisers emphasizes low fund charges and tailored solutions that promote financial security and independence.
- Choosing the right advisor involves assessing family financial complexity, comfort with technology, and the need for personalized support.
- The article highlights the importance of understanding fee structures to navigate potential conflicts of interest in financial advisory services.
Introduction
In the evolving landscape of financial services, families find themselves at a crucial crossroads, choosing between public wealth management companies and traditional financial advisors. Each option offers unique advantages designed to meet diverse needs and preferences. Public wealth management firms, with their scalable solutions and cutting-edge technology, appeal to a wide range of families. In contrast, traditional advisors focus on providing personalized service and tailored financial strategies that resonate deeply with family values.
As the number of affluent families continues to rise, it becomes increasingly important to understand the subtle distinctions between these services. This understanding empowers families to make informed decisions that align with their individual financial goals. Imagine if you could navigate your financial journey with confidence, knowing you have the right support by your side.
This article delves into the key differences, benefits, and considerations that families must weigh when selecting the ideal advisor. Together, we can explore the options available, ensuring that your family’s financial future is secure and flourishing. We’re here for you every step of the way, ready to assist in this important journey.
Understanding Public Wealth Management Companies and Traditional Financial Advisors
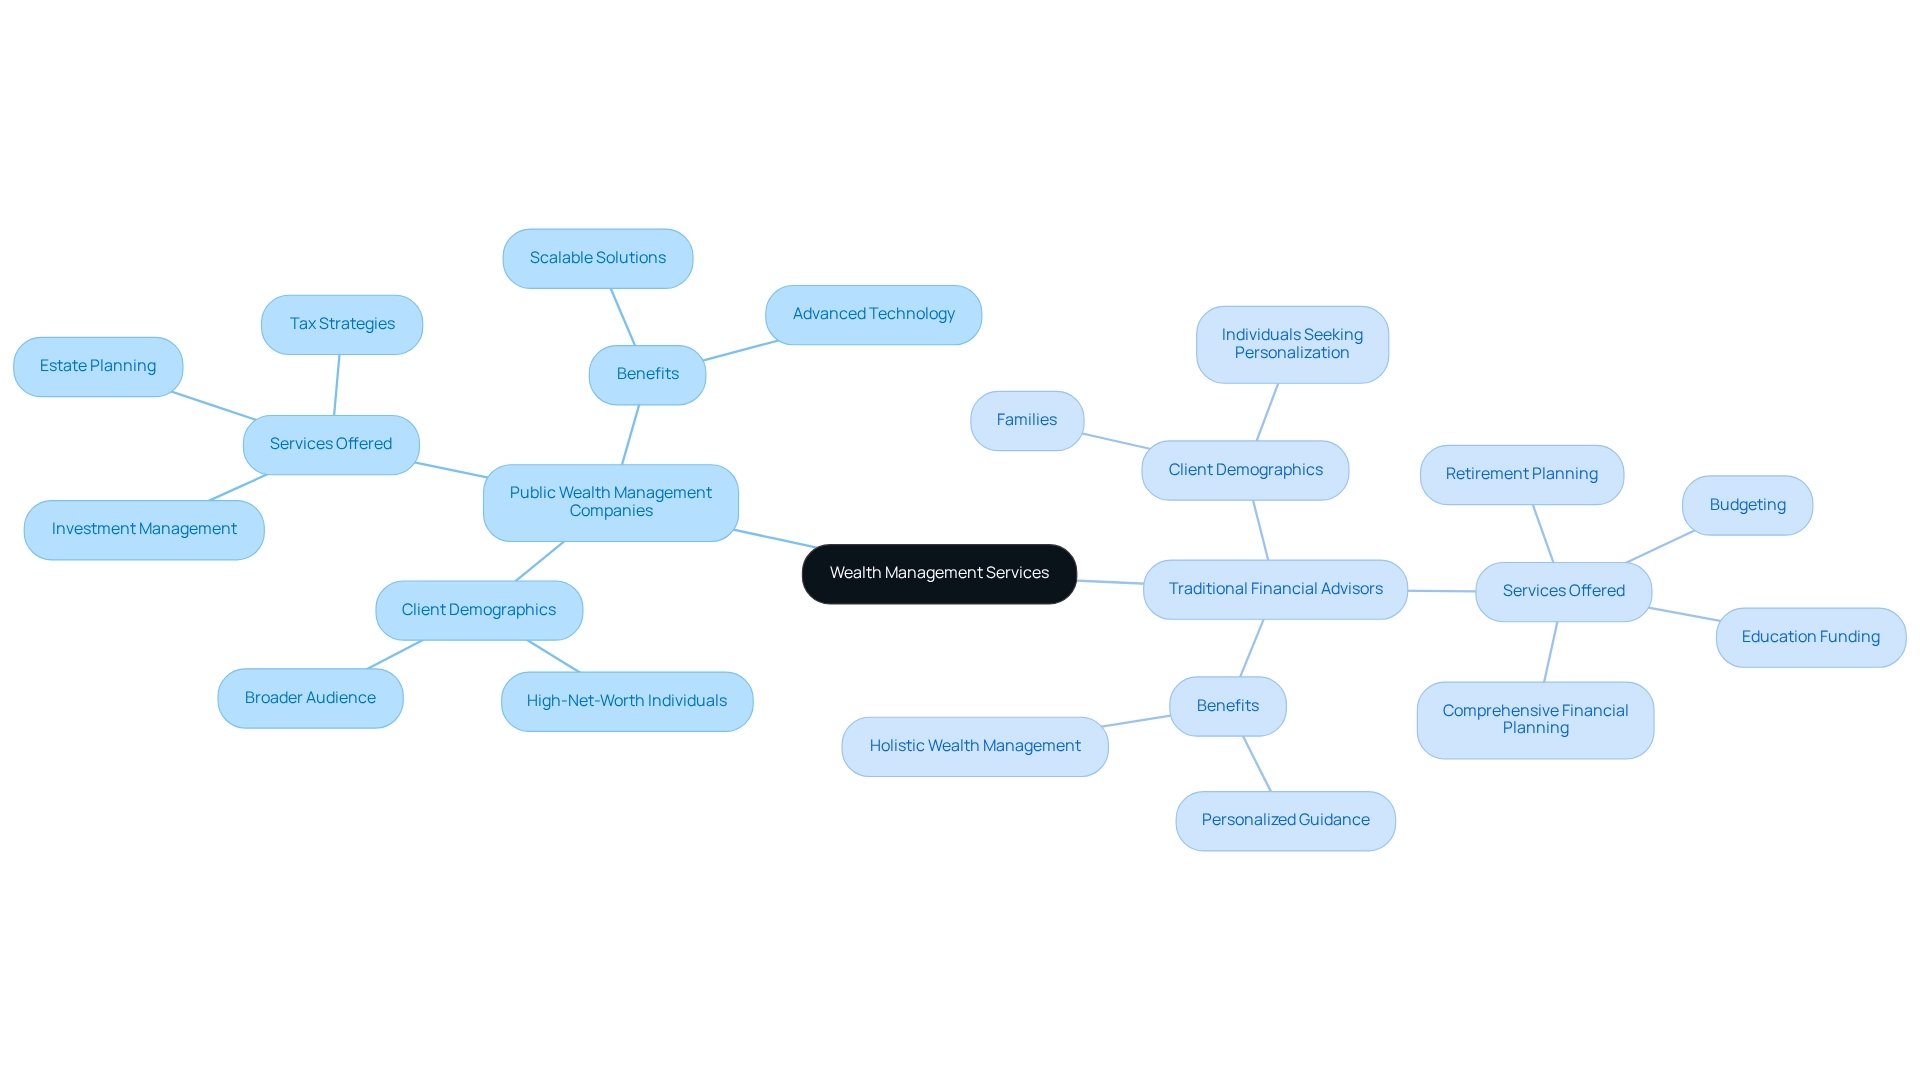
Public wealth advisory firms generally cater to a broad demographic, primarily focusing on high-net-worth individuals and families. They offer a variety of options, including investment management, estate planning, and tax strategies, often leveraging advanced technology to provide scalable solutions. This approach allows them to manage a larger client base effectively, with the average advisor handling up to 80 clients. However, this can limit the level of individualized attention clients receive.
In contrast, traditional advisors emphasize a more personalized approach, offering tailored guidance and strategies that address the unique needs of each client. Their focus often encompasses comprehensive financial planning aspects, such as budgeting, retirement planning, and education funding. This is especially beneficial for families looking to secure their children’s financial futures.
Bright Advisers exemplifies this personalized approach, offering ultra-high-net-worth level services regardless of wealth. They prioritize a holistic wealth management process that aligns values, vision, and goals with individualized financial strategies. For instance, their dedicated team of advisors works closely with clients like Emily and Mark, a young couple striving for financial independence and stability. Through a thorough assessment of their financial situation, including coordinated internal tax strategies and estate planning support, Bright Advisers helped them develop a customized plan that not only improved their financial health but also allowed them to make career choices that reflect their desired work-life balance.
The landscape of wealth management has evolved significantly, with the number of millionaires in North America more than doubling from 2010 to 2022. This surge in wealth has led to an expansion of private wealth management options, making them accessible to a broader audience, including families with lower disposable incomes. The case study titled “Empowering Financial Freedom for Young Families – Emily and Mark’s Journey with Bright Advisers” illustrates how tailored wealth guidance can transform financial futures through strategic planning and tax optimization.
As families explore these options, understanding the key differences between public wealth management companies and traditional consultants is crucial in determining which type of service aligns best with their financial goals. Families may find that public wealth management companies provide innovative investment opportunities that cater to their growing wealth, while traditional consultants offer the personalized approach necessary for long-term planning. By recognizing these distinctions, families can make informed decisions that best suit their unique financial situations. Together, we can navigate this journey toward financial security and peace of mind.
Comparing Services: What Each Type of Advisor Offers Families
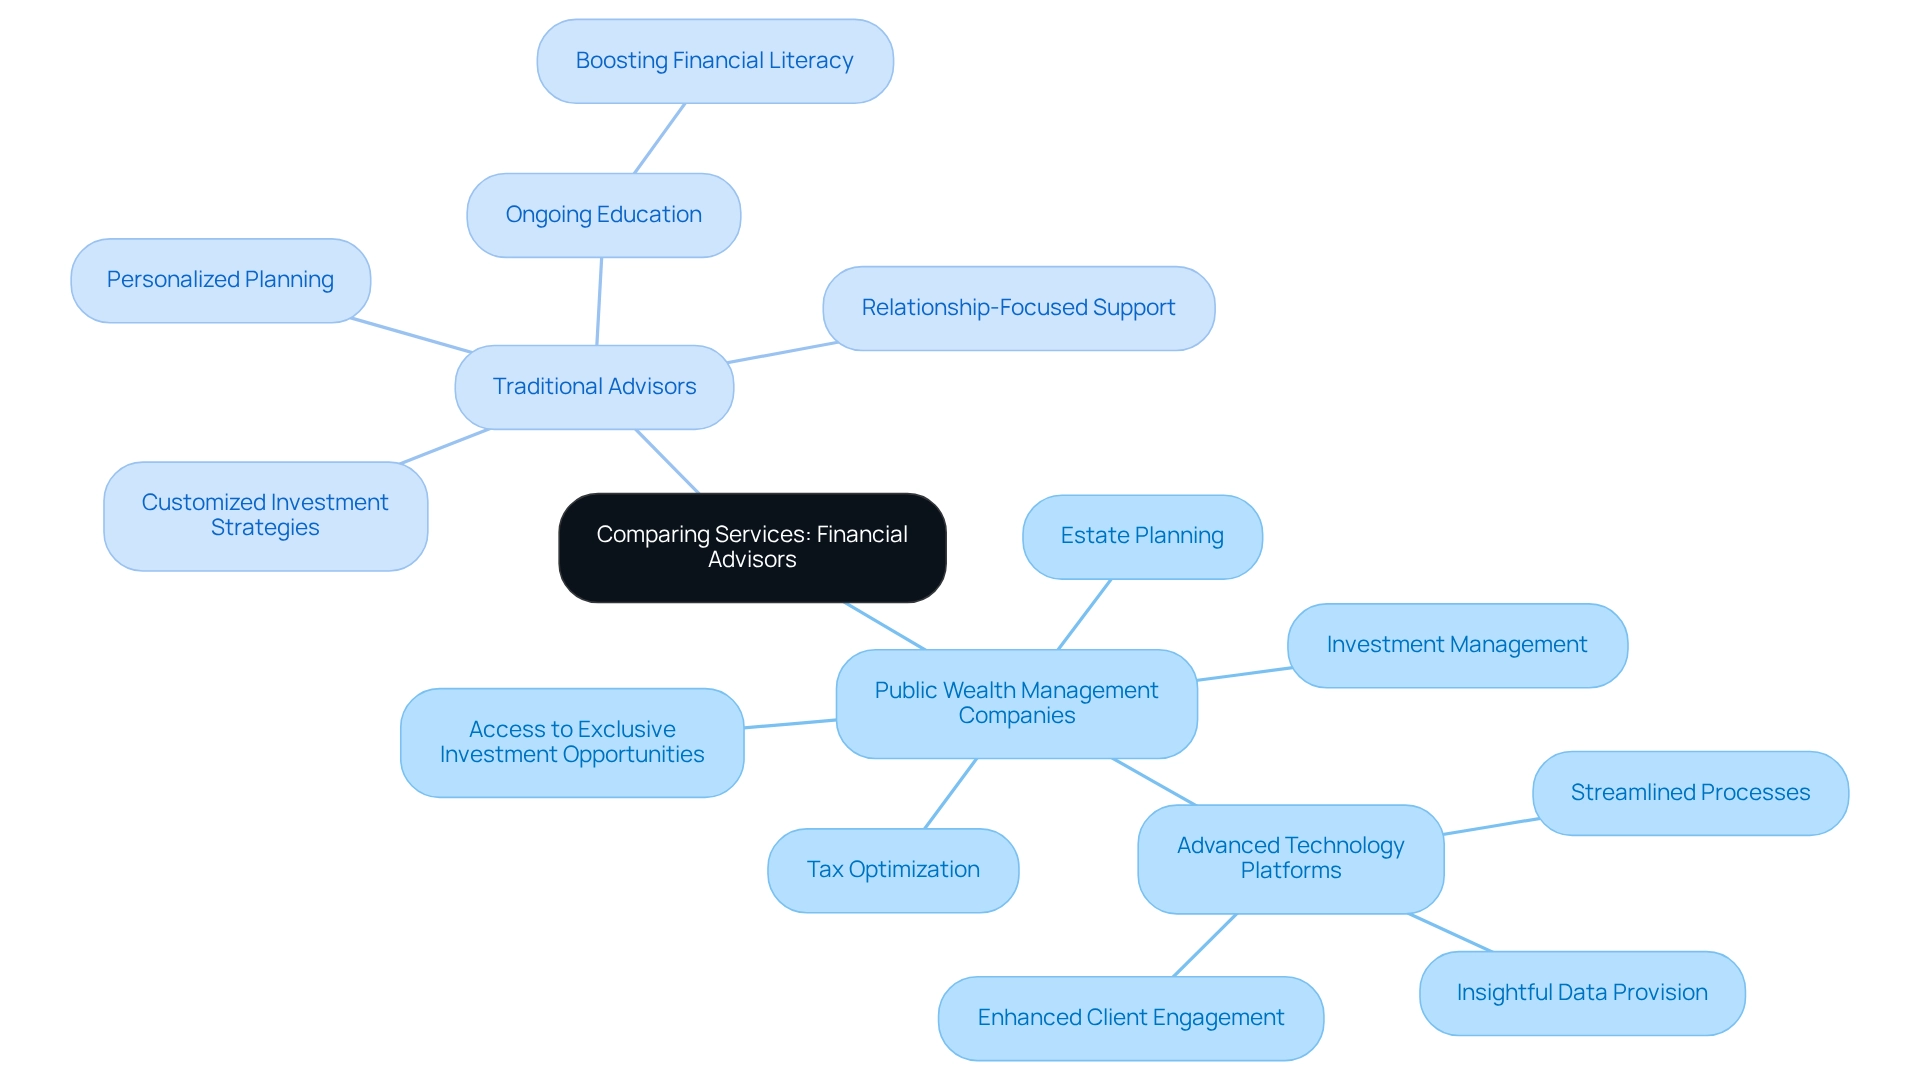
Public wealth management companies often present a wide range of options, including investment management, estate planning, tax optimization, and access to exclusive investment opportunities. These firms harness advanced technology platforms to streamline processes, enhance client engagement, and provide insightful data. In contrast, traditional advisors typically emphasize personalized offerings, such as individual planning sessions, customized investment strategies, and ongoing education to boost clients’ financial literacy.
For families, the decision between these two types of advisors often hinges on their preference for either a technology-driven approach or a more relationship-focused support system. Imagine if you could incorporate educational materials for your children into your financial planning. Bright Advisers stands out by promoting economic understanding from an early age. This family-oriented model not only addresses immediate financial needs but also prepares the next generation for future responsibilities, a feature that many traditional advisors may overlook.
Additionally, Bright Advisers employs innovative strategies like smart beta and factor investing to create hyper-personalized portfolios, ensuring families can optimize their financial outcomes. It’s important to recognize that 79% of high-net-worth individuals (HNWIs) seek assistance from relationship managers to help address investment biases. This statistic underscores the significance of tailored service in wealth management, especially for families with young children who often face unique financial challenges and choices.
Moreover, the wealth advisory sector, estimated at $458.02 billion in 2023 and projected to grow at a 36.4% CAGR from 2024 to 2030, reflects the increasing awareness among families of the importance of customized financial solutions that align with their unique goals and values. Many individuals engage advisors after significant life changes, which can be pivotal moments for families, highlighting the necessity for expert support during these transitions. In conclusion, while public wealth management companies offer sophisticated technological solutions, Bright Advisers provides tailored services that are essential for families navigating their financial journeys. Their focus on hyper-personalized investment strategies and comprehensive financial planning empowers families like Emily and Mark to achieve financial independence and make informed choices about their futures. Together, we can navigate this journey, ensuring that your family’s financial well-being is in caring hands.
Evaluating Pros and Cons: Public Wealth Management vs. Traditional Advisors
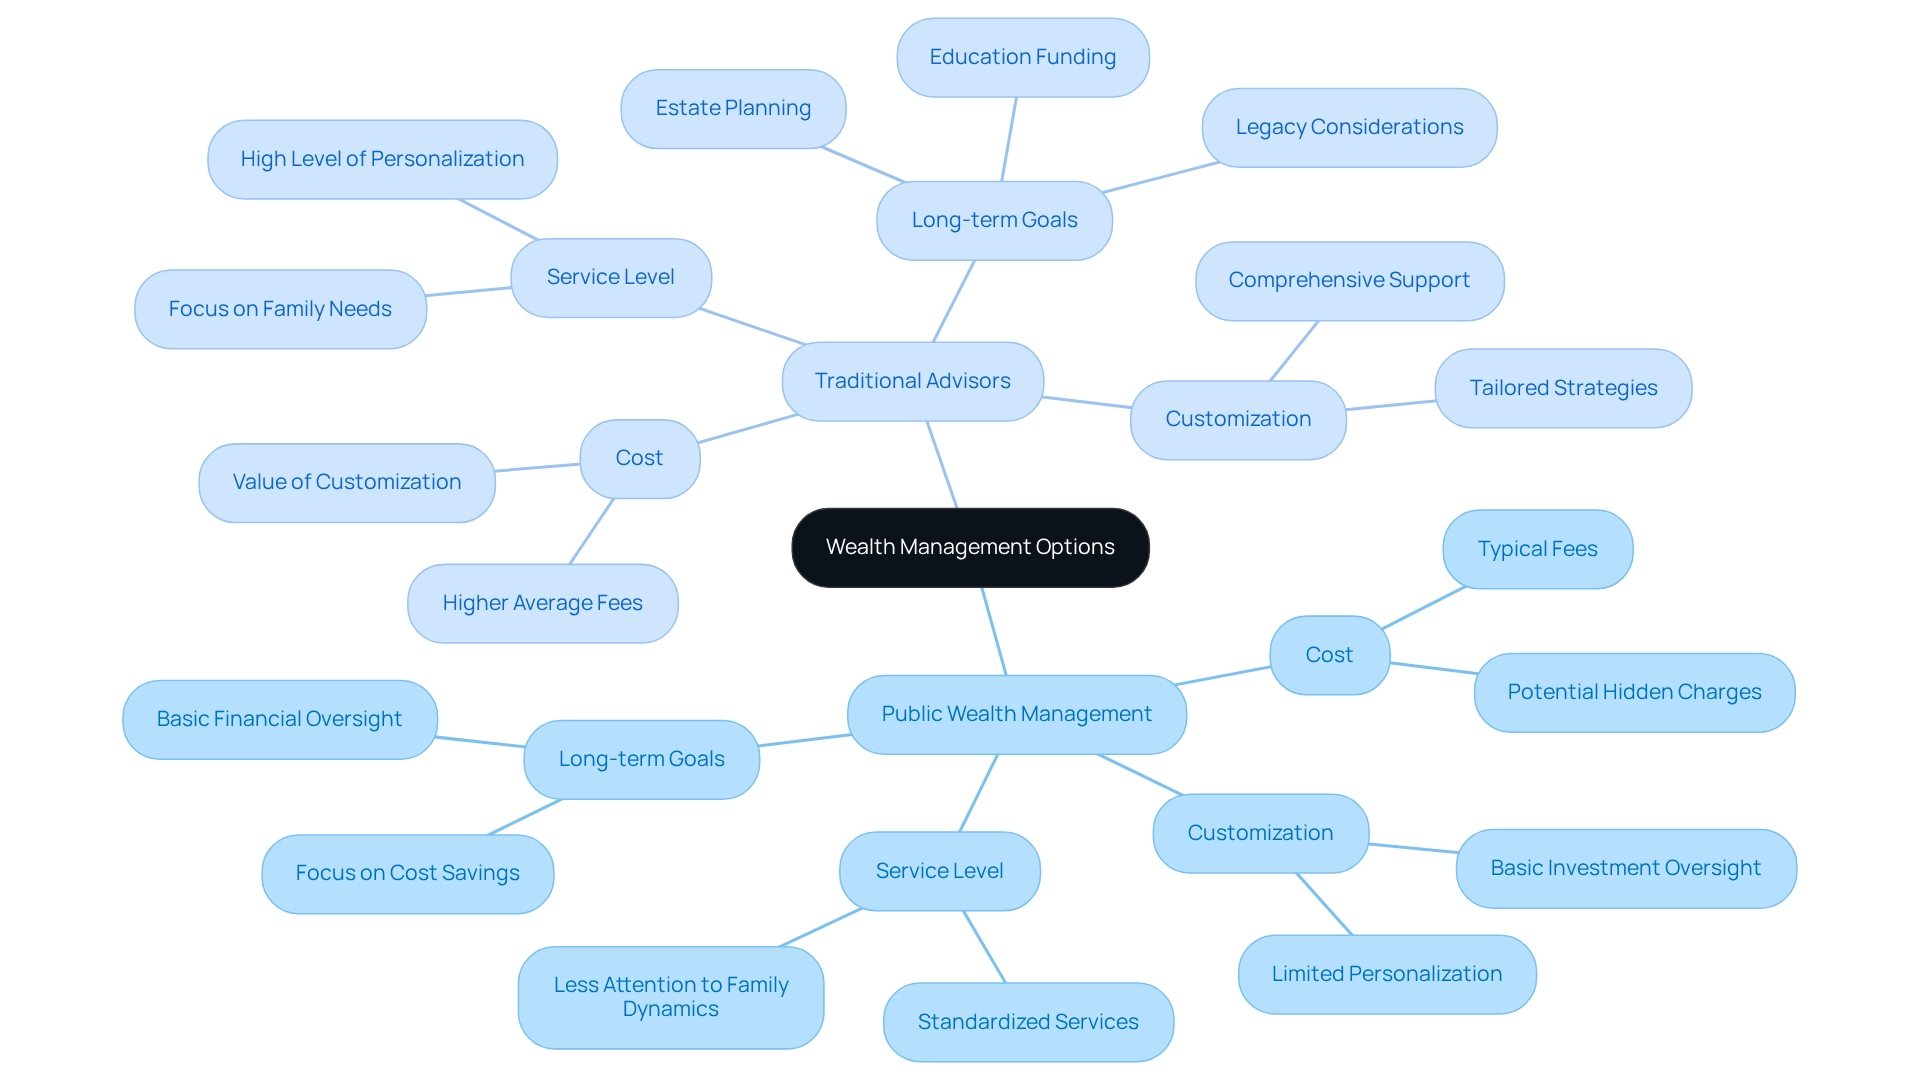
Public wealth management companies often attract families with their reduced fees, typically ranging from 0.65% to 1.00% of assets under management, thanks to their scale and technology-driven models. This cost-effectiveness can be especially appealing for families striving to minimize expenses. However, it’s important to recognize that these firms may incur additional costs for customized financial services, potentially leading to hidden charges that families should consider. In contrast, traditional advisors, while generally more expensive—averaging between 1% and 1.5% of portfolio value—offer a high level of customization. They can adapt their strategies to meet the evolving needs of a family, providing extensive support that includes education funding, estate planning, and legacy considerations.
Families must weigh the significance of cost savings against the value of personalized assistance when deciding between these two options. For instance, while public companies may offer basic investment oversight at a lower cost, they might not provide the same level of care or attention to individual family dynamics that traditional advisors can. As Andrea Coombes noted, “If you’re seeking basic investment oversight of a relatively small account, a flat fee of $2,000 a year is probably excessive,” highlighting the potential gap between service level and fees.
This distinction is crucial, especially for families evaluating their long-term financial goals and the complexities of multi-generational wealth management. Bright Advisers emphasizes its commitment to low fund charges, enhancing access to public wealth management companies for families while providing tailored solutions that promote financial security and independence through personalized planning and tax optimization. Additionally, some clients may hold legacy fee-bearing mutual funds and ETFs, which can affect overall fee structures. Ultimately, the decision hinges on whether families prioritize affordability or the tailored guidance that can significantly impact their financial future. Understanding the different payment structures of advisors—like fee-only, fee-based, and commission-only—can help families navigate potential conflicts of interest and make more informed choices.
Determining Suitability: Which Advisor Fits Your Family’s Needs?
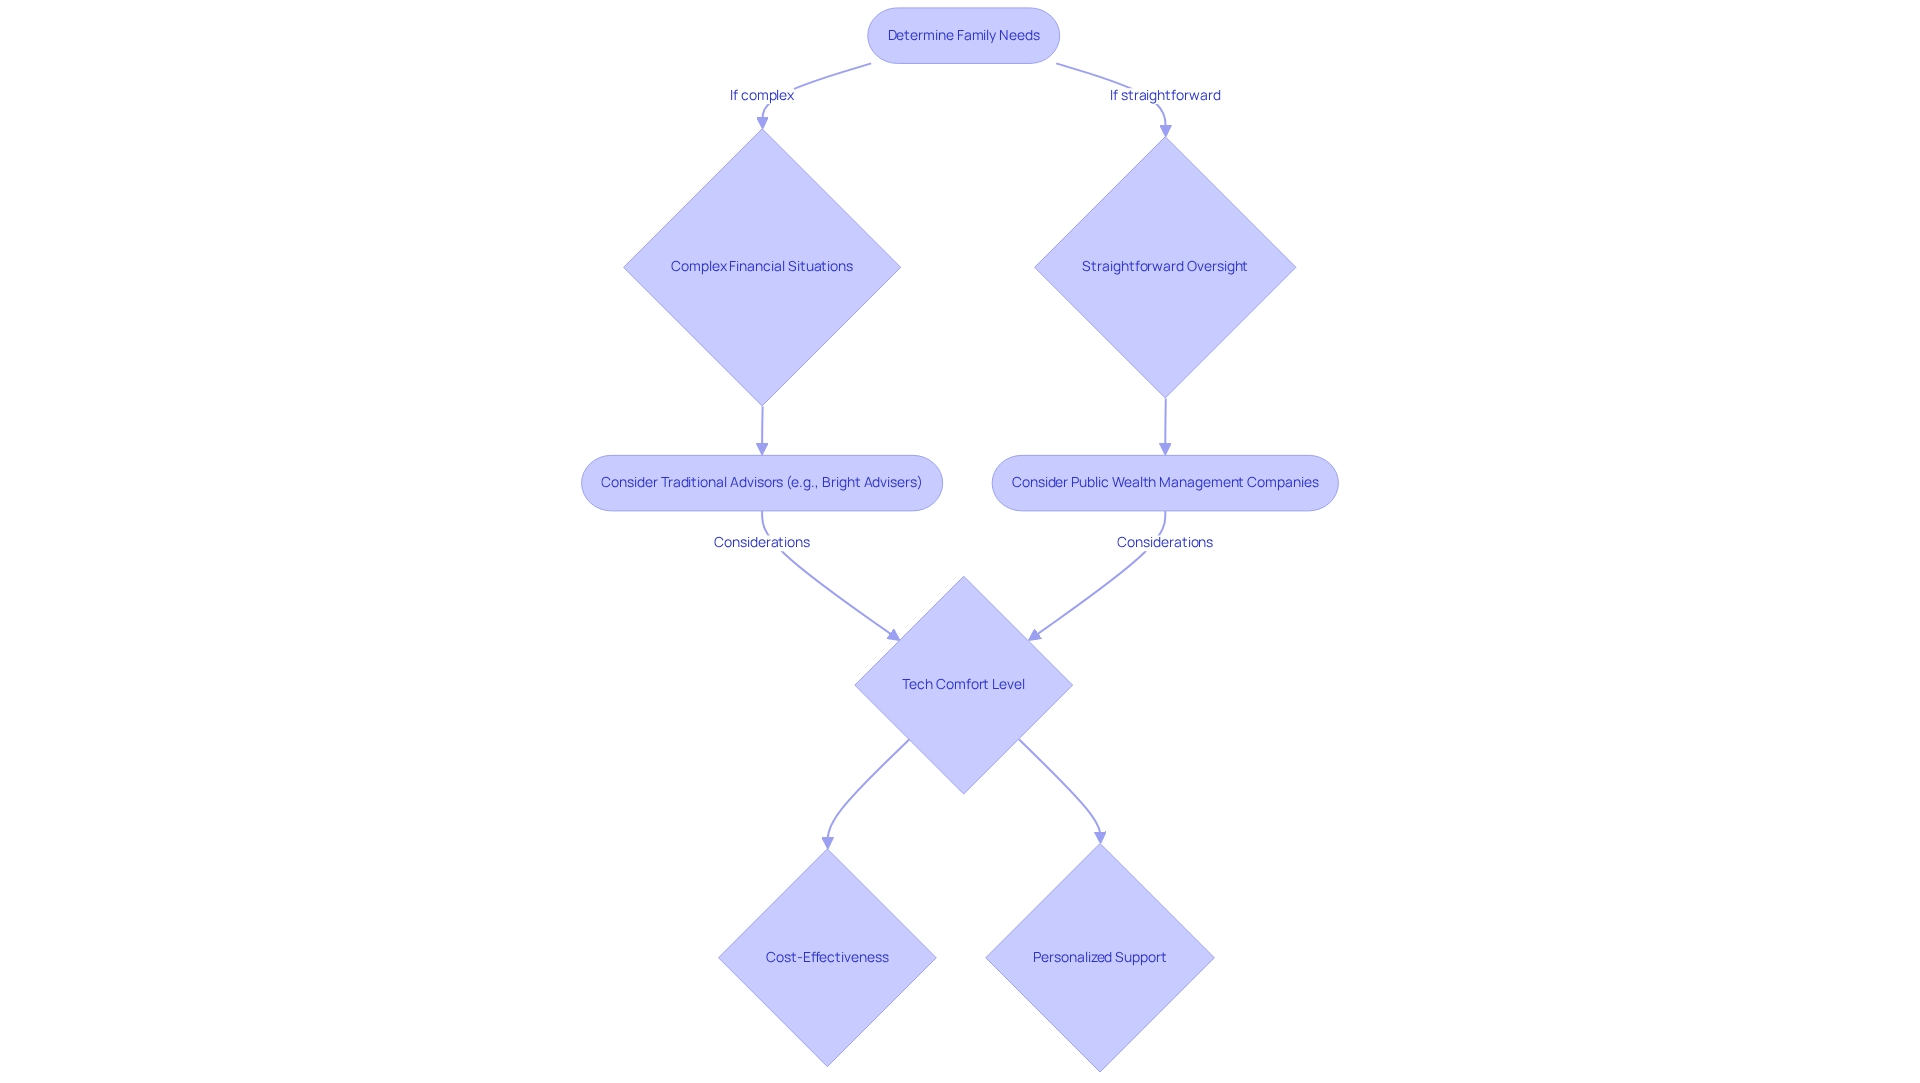
Choosing the right monetary consultant for your family is an important decision that requires careful thought. If your household has a complex financial situation—like multiple income streams or substantial assets—you might find that traditional advisors, such as Bright Advisers, can provide the comprehensive services you need to navigate these complexities. Bright Advisers offers a personalized onboarding process, guiding new clients through meetings and strategy sessions to create tailored plans and investment approaches that align with your unique family goals. This process includes essential steps like:
- Data collection
- Budgeting
- Developing a balance sheet
These steps ensure that every aspect of your family’s financial situation is thoughtfully considered. On the other hand, if your household is looking for straightforward investment oversight and planning, public wealth management companies may offer a more budget-friendly option.
Another vital consideration is your family’s comfort with technology. If you’re tech-savvy, you might appreciate the efficiency and accessibility of public wealth management companies, which often use innovative technology to simplify planning. Conversely, if you value personal interactions, you may be more inclined to choose traditional consultants who offer in-person guidance and customized advice.
Ultimately, selecting a consultant should reflect your family’s financial aspirations, values, and desired level of personalized support. As you explore your options, it’s essential to consider the growing trend of economic instability. For instance, a significant percentage of Americans—34%—report having no savings, as highlighted in the case study ‘Zero Savings Crisis.’ This underscores the importance of effective budgeting. Additionally, GoBankingRates reveals that 40% of women have saved less than $10,000 for retirement, compared to 31% of men, highlighting the need for tailored financial guidance that addresses the specific circumstances of different demographics.
By aligning your choice of advisor with your family’s unique needs and goals, you can better protect your financial future. To assist in this decision-making process, families should weigh the pros and cons of traditional advisors like Bright Advisers against public wealth management companies, considering factors such as:
- The comprehensiveness of services
- Cost-effectiveness
- The level of personalized support desired
Understanding the fee structures and wrap fee programs offered by advisors can also provide valuable insights as you make your choice.
Together, we can navigate this journey towards financial well-being, ensuring that your family’s future is secure and prosperous.
Conclusion
The landscape of wealth management offers families distinct options, each with its unique advantages and considerations. Public wealth management companies shine in providing scalable solutions and innovative financial products, appealing to a wide range of families. Their technology-driven approach allows for efficient management of a larger client base, offering essential services like investment management and tax optimization at competitive rates. However, some families may find that the potential lack of personalized service leaves them yearning for deeper, customized guidance.
Imagine if you could work with a financial advisor who truly understands your family’s values and long-term goals. Traditional financial advisors, like Bright Advisers, prioritize this personalized service. They craft tailored financial strategies that resonate with your family’s needs. Their focus on comprehensive planning—including estate planning, education funding, and financial literacy for future generations—addresses the unique challenges families face, especially during significant life transitions. This bespoke approach often proves invaluable for families with complex financial situations, emphasizing the importance of relationship-driven advice.
Ultimately, the decision between public wealth management firms and traditional advisors depends on your family’s unique needs, preferences, and financial goals. It’s important to evaluate the trade-offs between cost-effectiveness and the depth of personalized service, considering your comfort with technology and the significance of a tailored financial plan. By understanding the nuances of each option, you can confidently navigate your financial journey, ensuring that you select the advisor best suited to secure your financial future and achieve your aspirations. Together, we can navigate this journey, ensuring your family’s financial well-being is in caring hands.
Frequently Asked Questions
Who do public wealth advisory firms primarily serve?
Public wealth advisory firms primarily cater to high-net-worth individuals and families.
What services do public wealth advisory firms offer?
They offer a variety of services including investment management, estate planning, and tax strategies, often using advanced technology to provide scalable solutions.
How many clients does the average advisor at a public wealth advisory firm handle?
The average advisor at a public wealth advisory firm handles up to 80 clients.
What is the main focus of traditional advisors compared to public wealth advisory firms?
Traditional advisors emphasize a more personalized approach, providing tailored guidance and strategies that address the unique needs of each client.
What aspects of financial planning do traditional advisors cover?
Traditional advisors often cover comprehensive financial planning aspects such as budgeting, retirement planning, and education funding.
How does Bright Advisers exemplify a personalized approach in wealth management?
Bright Advisers offers ultra-high-net-worth level services regardless of wealth and prioritizes a holistic wealth management process that aligns clients’ values, vision, and goals with individualized financial strategies.
Can you provide an example of how Bright Advisers has helped clients?
Bright Advisers helped a young couple, Emily and Mark, develop a customized financial plan that improved their financial health and allowed them to make career choices reflecting their desired work-life balance.
How has the wealth management landscape changed from 2010 to 2022?
The number of millionaires in North America has more than doubled from 2010 to 2022, leading to an expansion of private wealth management options accessible to a broader audience.
What is the significance of the case study involving Emily and Mark?
The case study illustrates how tailored wealth guidance can transform financial futures through strategic planning and tax optimization.
Why is it important for families to understand the differences between public wealth management companies and traditional consultants?
Understanding these differences helps families determine which type of service aligns best with their financial goals and needs, allowing for informed decisions regarding their financial situations.
List of Sources
- Understanding Public Wealth Management Companies and Traditional Financial Advisors
- Financial Advisory – United States | Market Forecast (https://statista.com/outlook/fmo/wealth-management/financial-advisory/united-states)
- The future of financial advice and wealth management | Blog | QED Investors (https://qedinvestors.com/blog/the-future-of-financial-advice-and-wealth-management)
- Comparing Services: What Each Type of Advisor Offers Families
- Wealth Management – United States | Market Forecast (https://statista.com/outlook/fmo/wealth-management/united-states)
- The Most Important Wealth Management Statistics To Know (https://passivesecrets.com/wealth-management-statistics)
- 30+ Financial Advisor Statistics (https://bizplanr.ai/blog/financial-advisor-statistics)
- Wealth Management Statistics By Market Size and AI Impact (https://electroiq.com/stats/wealth-management-statistics)
- Evaluating Pros and Cons: Public Wealth Management vs. Traditional Advisors
- Average Advisor Fees Charged By Brokerage (https://financialsamurai.com/average-adviser-fees-charged-by-brokerage)
- How Much Does a Financial Advisor Cost in 2025? – NerdWallet (https://nerdwallet.com/article/investing/how-much-does-a-financial-advisor-cost)
- How Much Does a Financial Advisor Cost? (2025) (https://talo.com/costs/financial-advisor-cost)
- Determining Suitability: Which Advisor Fits Your Family’s Needs?
- 20 + Personal Finance Statistics for 2025 | Fortunly (https://fortunly.com/statistics/personal-finance-statistics)
- Majority of Americans Say “Seek Financial Advice Before Age 40,” According to Northwestern Mutual Planning & Progress Study (https://news.northwesternmutual.com/2025-05-06-2025-NORTHWESTERN-MUTUAL-PLANNING-PROGRESS-STUDY)
- 13 Important Personal Finance Stats You Need to Know – Savology (https://savology.com/13-financial-statistics-you-need-to-know)
- 27 eye-opening financial planning statistics (https://contentsnare.com/financial-planning-statistics)

Kevin has advised high-income W-2 tech and biotech families since 2015, and leads the education-first Age Five Family Office from Brea, California.
Connect on LinkedIn → · About KevinThis is part of how we approach Investment & Risk Management for high-income W-2 families at Bright Advisers.
Keep reading