

Overview
Required Minimum Distributions (RMDs) are the minimum amounts that the IRS mandates individuals to withdraw from tax-deferred retirement accounts, such as traditional IRAs and 401(k)s, starting at age 73. This requirement is crucial for ensuring tax revenue generation, but it can feel overwhelming. Imagine if you could navigate this process with confidence, knowing that you’re making informed decisions for your family’s future.
The article explains the calculation process for RMDs, breaking it down into manageable steps. It’s important to understand that compliance is key to avoiding penalties that could impact your financial well-being. By planning ahead, you can effectively manage withdrawals during retirement, ensuring that your family’s needs are met.
As you think about your financial journey, consider the benefits of strategic planning. By taking the time to understand RMDs and their implications, you can create a roadmap that aligns with your family’s values and goals. Together, we can navigate this journey, ensuring that you feel supported every step of the way.
In conclusion, remember that we’re here for you. With the right guidance, you can approach RMDs with a sense of empowerment, making choices that benefit not just you, but your entire family.
Key Highlights:
- RMDs are the minimum amounts required by the IRS to withdraw from tax-deferred accounts like traditional IRAs and 401(k)s after reaching age 73.
- Starting in 2025, individuals must begin taking RMDs by April 1 of the year following their 73rd birthday.
- RMDs help prevent indefinite tax deferral on retirement savings, generating tax revenue for the government.
- To calculate RMDs, divide the account balance at year-end by a life expectancy factor provided by the IRS.
- Multiple IRAs can be combined for RMD purposes, allowing for flexible withdrawal strategies.
- Failing to take the required distributions can result in a penalty of up to 25% of the amount not withdrawn.
- It’s crucial to maintain accurate records, especially for amounts accumulated before 1987, to ensure compliance with RMD rules.
- Financial planning around RMDs is essential to manage tax obligations and ensure income during retirement years.
- Professional financial advice can help navigate RMD complexities and optimize withdrawal strategies.
Introduction
As you approach retirement, understanding Required Minimum Distributions (RMDs) becomes incredibly important in your financial planning journey. These mandated withdrawals from tax-deferred retirement accounts, like traditional IRAs and 401(k) plans, are essential for ensuring that you make the most of your savings while also adhering to IRS regulations. Imagine the peace of mind that comes with knowing you’re on the right path.
Starting in 2025, the rules surrounding RMDs will become even more significant, as you will need to begin taking distributions by April 1 following your 73rd birthday. It’s important to understand how these changes can impact your financial future. This article delves into the intricacies of RMDs—covering their calculation, compliance, and the implications they hold for your overall retirement strategies.
We’ll emphasize the essential role RMDs play in managing tax liabilities and securing your financial stability in those later years. Together, we can navigate this journey, ensuring that your retirement is as fulfilling as you’ve envisioned.
Define Required Minimum Distributions (RMDs)
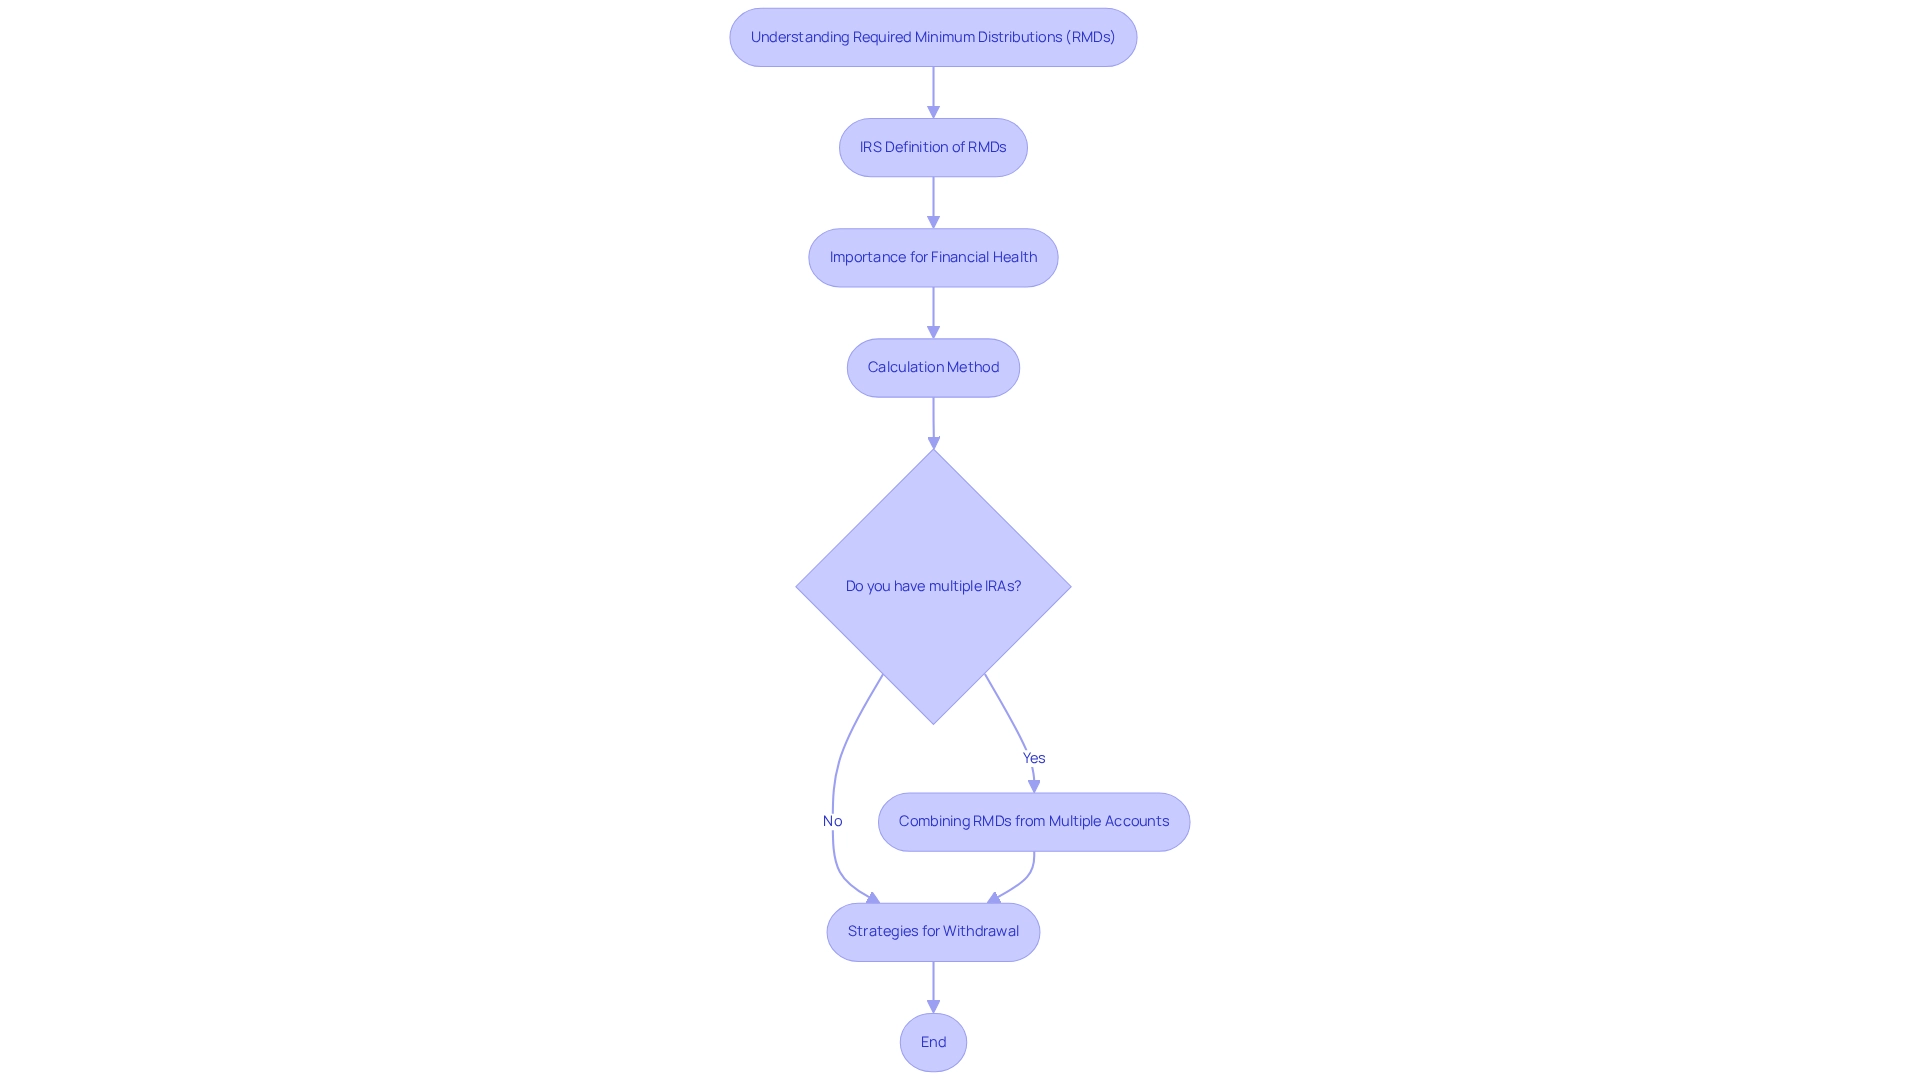
Understanding the required minimum distribution definition is crucial for your family’s financial health. The required minimum distribution definition outlines the minimum amounts that the Internal Revenue Service (IRS) requires you to withdraw from tax-deferred savings accounts, such as traditional IRAs and 401(k) plans, once you reach a certain age. Starting in 2025, you will need to begin taking RMDs by April 1 of the year after your 73rd birthday. The required minimum distribution definition is intended to prevent the indefinite deferral of taxes on your retirement savings, ultimately generating tax revenue for the government.
Calculating your RMDs might seem daunting, but it’s straightforward. You simply divide the balance at the end of the previous year by a life expectancy factor set by the IRS. This method ensures that your withdrawals align with your longevity, fostering a sustainable withdrawal strategy. If you have multiple IRAs, don’t worry! The IRS allows you to combine your RMD amounts, giving you the flexibility to withdraw the total from one account or spread it across several. This can ease the withdrawal process and help you manage tax implications more effectively.
At Bright Advisers, we recognize the importance of RMDs in your financial planning journey. Our commitment is to provide personalized wealth management solutions that empower families like yours. We offer educational resources to help you navigate your options for accessing funds without penalties, such as emergency expenses that allow for penalty-free withdrawals of up to $1,000 per calendar year. As Judith Ward, CFP Thought Leadership Director, points out, “The employer is responsible for determining the RMD amount from plans (e.g., 401(k)s) and distributing the RMD.” This highlights the necessity of understanding the required minimum distribution definition within the broader context of your financial strategy.
By focusing on low fund charges and tailored planning, Bright Advisers ensures that your family can effectively manage RMDs while working towards financial security and independence. Remember, we’re here for you—together, we can navigate this journey toward a stable financial future.
Understand the Importance of RMDs in Retirement Planning
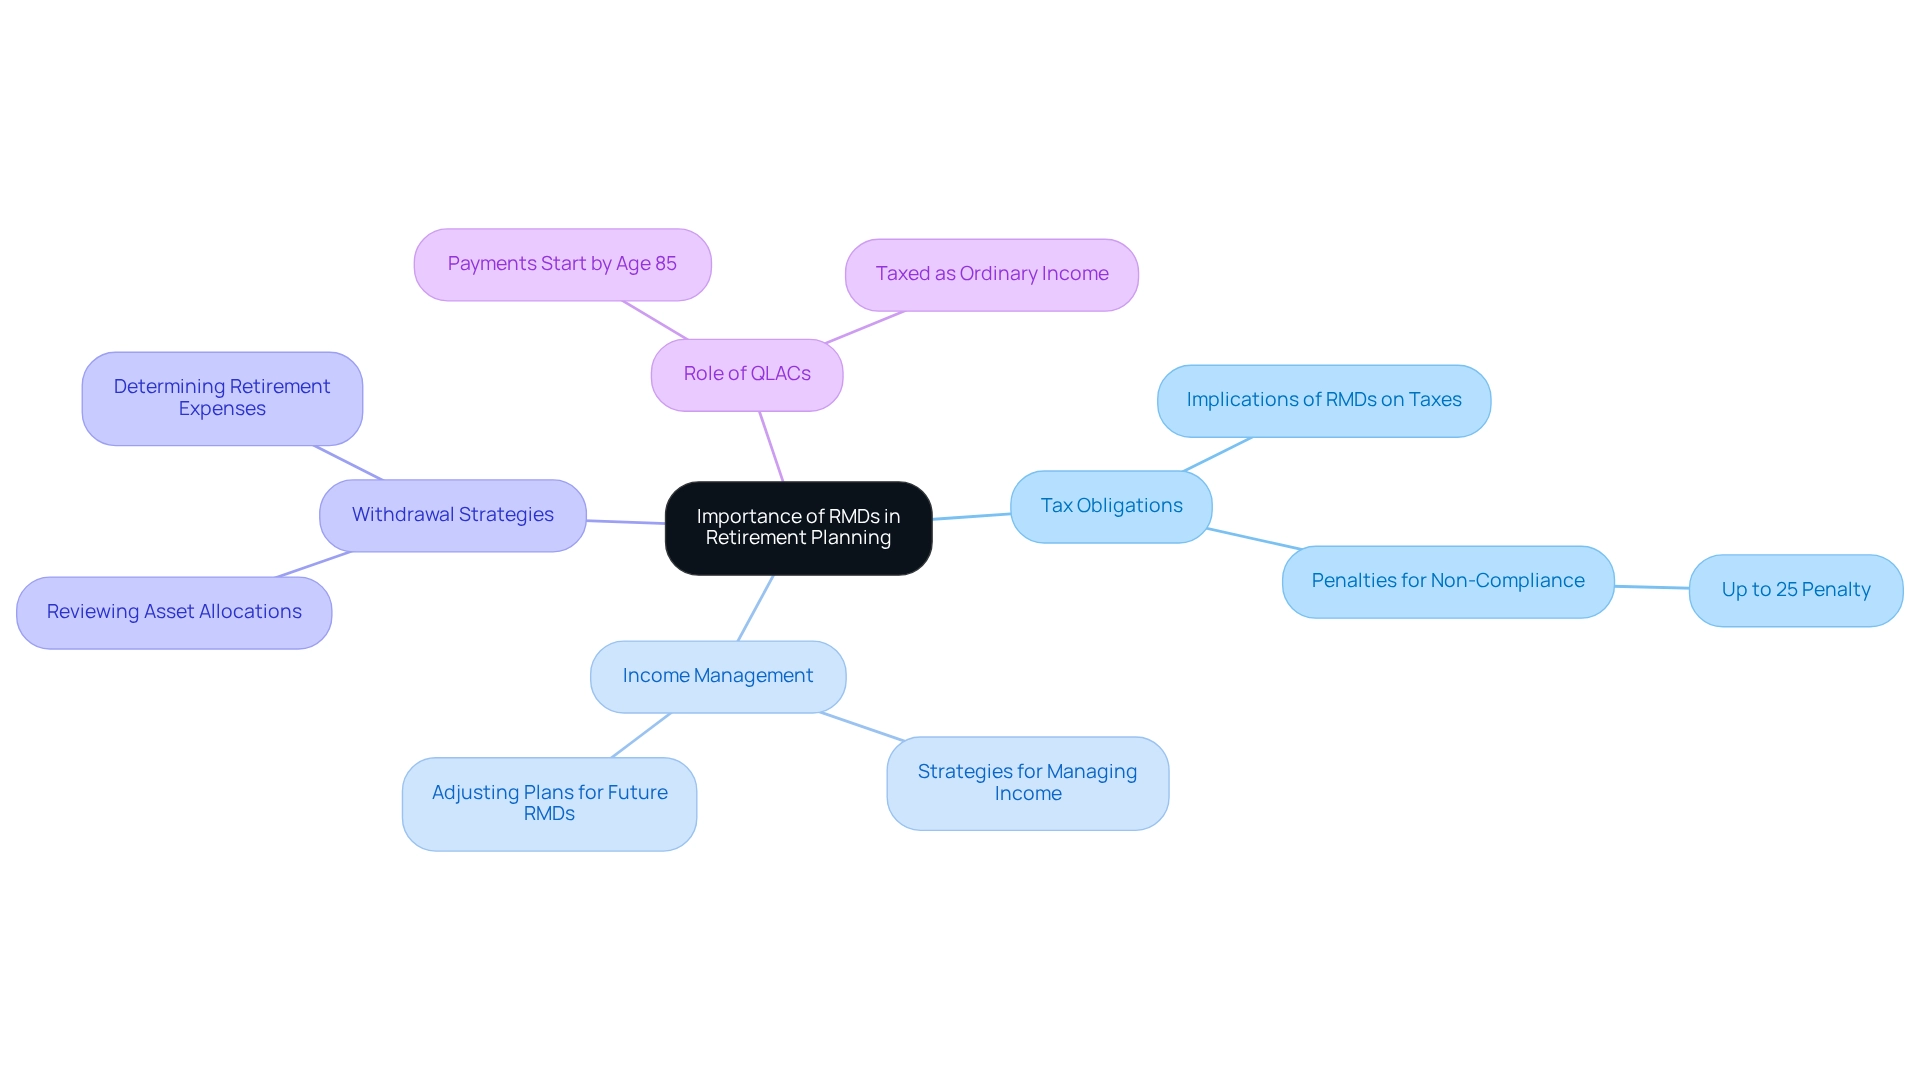
Mandatory Minimum Withdrawals play a vital role in post-employment planning, helping retirees access their hard-earned savings. This regulation not only aids in managing tax obligations but also provides essential income during later years. By requiring withdrawals, the IRS encourages individuals to avoid the indefinite accumulation of tax-advantaged accounts, fostering financial sustainability.
Imagine facing your retirement years with confidence, knowing that you have a plan in place. In 2025, understanding the required minimum distribution definition is more important than ever, especially as many retirees find their required distributions may exceed their income needs. Recent studies show that about two-thirds of traditional IRA-owning households have developed strategies for managing their income and assets in their later years. This often involves reviewing asset allocations and determining expenses during that time. Such proactive planning is crucial for ensuring financial stability in those later years.
It’s important to understand that failing to take the required distributions can result in severe penalties, potentially reaching up to 25% of the amount not withdrawn. Therefore, incorporating the required minimum distribution definition into a comprehensive financial strategy is not just advisable; it is essential for complying with tax regulations and preserving your economic well-being. Financial consultants emphasize the importance of evaluating investment options that align with your overall financial strategy, particularly concerning the implications of required minimum distribution definitions on tax obligations and income during later life. As you navigate your financial landscape in your later years, managing required minimum distribution definitions effectively can significantly impact your withdrawal rates and overall tax strategy. This ensures that your savings are utilized efficiently while minimizing tax burdens. Additionally, if you anticipate that your withdrawals at age 73 might exceed your needs, consider adjusting your plans to reduce future required minimum distributions. Remember, payments from a Qualified Longevity Annuity Contract (QLAC) must commence by age 85 and are taxed as ordinary income, which further influences your income planning for those later years.
Together, we can navigate this journey, ensuring that you are well-prepared for a financially secure future.
Explore RMD Rules and Regulations
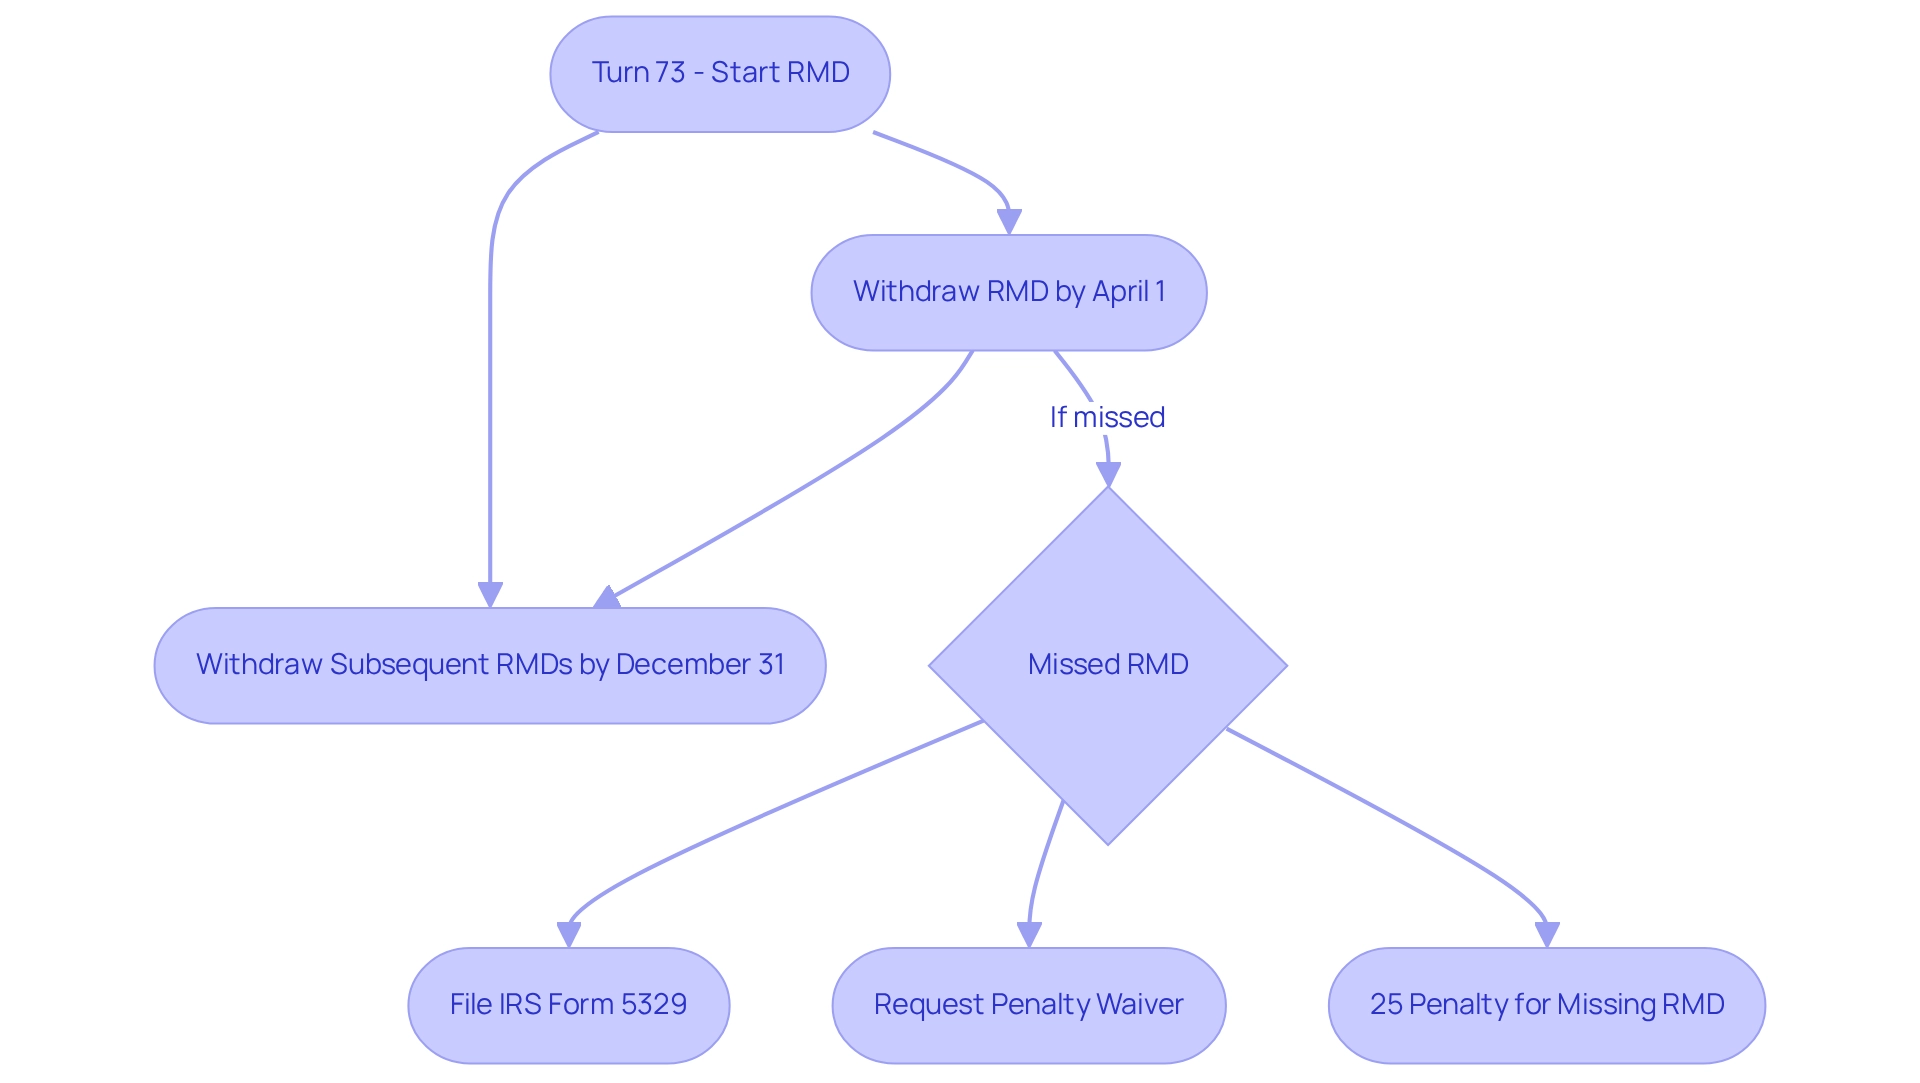
As you approach retirement, it’s crucial to understand the required minimum distribution definition and the IRS rules surrounding Required Minimum Distributions (RMDs). Starting on April 1 of the year after you turn 73, you’ll need to begin withdrawing these required amounts. If you retire after age 75, remember that any amounts accumulated before 1987 must be distributed by April 1 of the following year. After that, subsequent distributions should be completed by December 31 each year. According to the required minimum distribution definition, the RMD amount is calculated by dividing your balance as of December 31 of the previous year by a life expectancy factor from the IRS’s Uniform Lifetime Table.
Missing your RMD can lead to a significant penalty—25% of the amount you didn’t withdraw. This penalty highlights the importance of adhering to RMD regulations. RMDs apply to various savings plans, such as traditional IRAs and 401(k)s, but they do not apply to Roth IRAs during your lifetime.
Imagine if you miss your RMD. It’s vital to act quickly to minimize penalties. The IRS imposes a 25% excise tax on the amount not withdrawn as required. To address this, take the missed RMD right away, file IRS Form 5329, and request a waiver for the penalty. Consulting with a financial advisor can provide you with personalized guidance to navigate these complexities effectively. As the SmartAsset Team advises, “Seeking professional advice from an expert could help you find additional ways to handle your specific situation and avoid future mistakes.”
Looking ahead to 2025, maintaining accurate records is essential, especially for amounts before 1987. Failing to keep these records may subject your entire balance to the age 73 RMD rules. Understanding the required minimum distribution definition is essential for ensuring compliance and avoiding costly penalties. Remember, we’re here for you, and together, we can navigate this journey toward a secure financial future.
Calculate Your Required Minimum Distributions
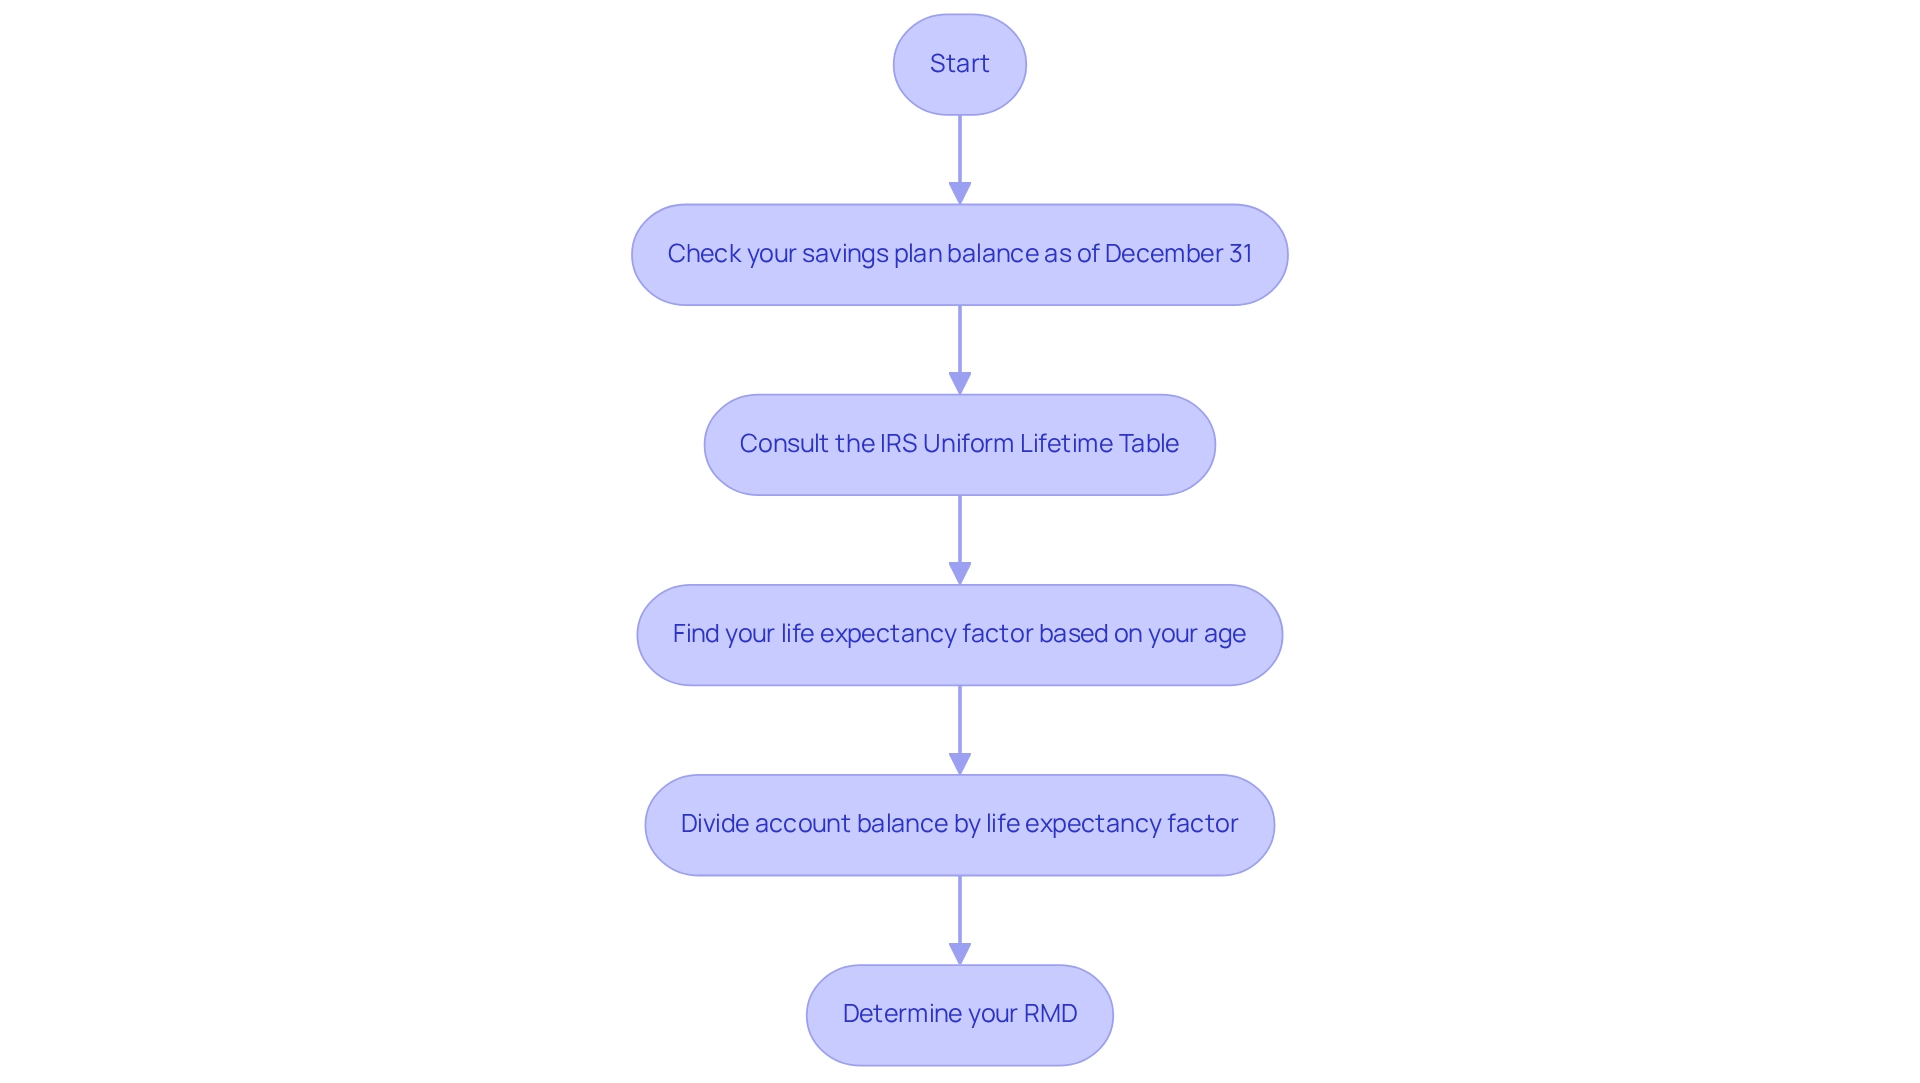
Calculating the required minimum distribution definition can feel overwhelming, but it’s a straightforward process that you can navigate with ease. Start by checking the balance of your savings plan as of December 31 of the last year. Next, take a moment to consult the IRS’s Uniform Lifetime Table. This will guide you to find the appropriate life expectancy factor based on your age. To determine your RMD, simply divide your account balance by this life expectancy factor.
Imagine if your IRA balance is $100,000 and your life expectancy factor is 25.6. In that case, your RMD would be approximately $3,906.25. It’s essential to remember that if you turn 73 on November 30, 2023, you have until April 1, 2024, to make your first withdrawal. The RMD rule is designed to ensure that individuals fulfill their deferred tax obligations on contributions made for later life. Understanding this aspect of financial planning is crucial for your family’s future.
Many financial institutions offer RMD calculators to simplify this process. These tools allow you to easily determine your required withdrawals and plan your finances accordingly. Moreover, working with a skilled financial consultant can help you manage the complexities of the required minimum distribution definition. They can assist you in minimizing taxes while protecting your principal and ensuring you have adequate income during your later years.
As Ben Fuchs, a CERTIFIED FINANCIAL PLANNER®, shares, “Disappointment is not in his vocabulary, and that has flowed down to me as his client.” This highlights the value of professional guidance in financial planning. A strategic approach is vital, especially for families with unique circumstances, such as having a significantly younger spouse, as it may affect how RMDs are calculated. Understanding these nuances can lead to a more effective retirement strategy, ensuring that you and your loved ones are well-prepared for the future. Together, we can navigate this journey and secure your family’s financial well-being.
Conclusion
Understanding Required Minimum Distributions (RMDs) is essential for effective retirement planning, especially as you approach the age of 73. At this stage, it becomes necessary to begin taking these mandated withdrawals from your tax-deferred retirement accounts. RMDs not only help you stay compliant with IRS regulations but also play a vital role in managing your tax liabilities and providing the income you need during your retirement years. The calculation of RMDs is quite straightforward, involving your account balance and a life expectancy factor. This allows for a personalized approach to withdrawals that considers your unique circumstances.
As we look ahead to 2025, when the rules surrounding RMDs will evolve, it’s crucial to stay informed about your obligations and options. The potential penalties for not withdrawing the required amounts can be significant, highlighting the importance of timely compliance. Engaging with a financial advisor can offer you valuable insights and strategies to navigate these complexities, optimize tax implications, and ensure that your retirement savings are utilized effectively.
Incorporating RMDs into a comprehensive retirement strategy isn’t just advisable; it’s essential for achieving financial stability and security. By proactively managing your RMDs and understanding their impact on your overall financial planning, you can enjoy your later years with confidence, knowing that you are making the most of your hard-earned savings while adhering to necessary regulations. Remember, we’re here for you, and together, we can navigate this journey towards a secure and fulfilling retirement.
Frequently Asked Questions
What is the required minimum distribution (RMD)?
The required minimum distribution (RMD) is the minimum amount that the IRS requires you to withdraw from tax-deferred savings accounts, such as traditional IRAs and 401(k) plans, once you reach a certain age.
When do I need to start taking RMDs?
Starting in 2025, you must begin taking RMDs by April 1 of the year after your 73rd birthday.
Why does the IRS require RMDs?
The required minimum distribution is intended to prevent the indefinite deferral of taxes on retirement savings, ultimately generating tax revenue for the government.
How do I calculate my RMD?
To calculate your RMD, divide the balance of your account at the end of the previous year by a life expectancy factor set by the IRS.
Can I withdraw my RMD from multiple accounts?
Yes, if you have multiple IRAs, the IRS allows you to combine your RMD amounts, giving you the flexibility to withdraw the total from one account or spread it across several accounts.
What resources does Bright Advisers offer regarding RMDs?
Bright Advisers provides personalized wealth management solutions and educational resources to help you navigate your options for accessing funds without penalties, including penalty-free withdrawals for emergency expenses.
Who is responsible for determining the RMD amount from employer plans like 401(k)s?
The employer is responsible for determining the RMD amount from plans such as 401(k)s and distributing the RMD.
How does Bright Advisers support families in managing RMDs?
Bright Advisers focuses on low fund charges and tailored planning to help families effectively manage RMDs while working towards financial security and independence.
List of Sources
- Define Required Minimum Distributions (RMDs)
- Required Minimum Distributions | RMD Rules & Options | Fidelity (https://fidelity.com/retirement-ira/rmd)
- Required Minimum Distribution (RMD): Definition and Calculation (https://investopedia.com/terms/r/requiredminimumdistribution.asp)
- T. Rowe Price Personal Investor – Watch: Eight important things you should know about RMDs (https://troweprice.com/personal-investing/resources/insights/things-you-should-know-about-rmds.html)
- Understand the Importance of RMDs in Retirement Planning
- T. Rowe Price Personal Investor – A Closer Look at RMDs and the SECURE 2.0 Rules (https://troweprice.com/personal-investing/resources/insights/a-closer-look-at-rmds-and-the-new-secure-20-rules.html)
- Ask IFA: Can I Delay Taking My RMDs? (https://ifa.com/articles/navigating-rmds-retirement-income-strategy)
- IRAs Play a Key Role in US Households’ Retirement Planning (https://ici.org/news-release/24-news-ira-retirement-plan)
- Explore RMD Rules and Regulations
- Retirement plan and IRA required minimum distributions FAQs | Internal Revenue Service (https://irs.gov/retirement-plans/retirement-plan-and-ira-required-minimum-distributions-faqs)
- What Is the Penalty for Not Taking Your RMD? (https://nasdaq.com/articles/what-penalty-not-taking-your-rmd)
- Calculate Your Required Minimum Distributions
- Required Minimum Distributions (RMDs) From Retirement Accounts (https://nolo.com/legal-encyclopedia/free-books/avoid-probate-book/chapter2-3.html)
- Required Minimum Distribution (RMD): Definition and Calculation (https://investopedia.com/terms/r/requiredminimumdistribution.asp)
- How To Calculate Your Required Minimum Distributions (RMDs)? (https://fuchsfinancial.com/how-to-calculate-your-required-minimum-distributions-rmds)
- Understanding Required Minimum Distributions – Johnson Wealth and Income Management (https://johnsonwim.com/understanding-required-minimum-distributions-full)

Kevin has advised high-income W-2 tech and biotech families since 2015, and leads the education-first Age Five Family Office from Brea, California.
Connect on LinkedIn → · About KevinThis is part of how we approach Retirement & Employee Benefits for high-income W-2 families at Bright Advisers.
Keep reading