

Overview
Retirement planning for high-income earners can feel daunting, especially with unique challenges like higher tax liabilities, lifestyle inflation, and the complexity of managing multiple income sources. It’s important to recognize that these obstacles require tailored strategies for success. Imagine navigating this journey with confidence, knowing you have a plan in place.
As you consider your financial future, implementing tax-efficient tactics and setting strict savings goals become essential steps. These strategies not only help in addressing your specific challenges but also pave the way for a secure financial future for you and your family. Exploring alternative savings options can further enhance your ability to meet your goals.
Together, we can navigate this journey, ensuring that your financial planning aligns with your family values and aspirations. Remember, you’re not alone in this; we’re here for you, ready to provide the support and guidance you need to thrive.
Key Highlights:
- High-income earners face unique retirement challenges, including higher tax brackets that can reduce net retirement income.
- Implementing tax-efficient strategies like tax-loss harvesting and maximising contributions to tax-advantaged accounts is crucial.
- Lifestyle inflation can limit savings; setting strict savings goals and automating contributions can help mitigate this.
- Managing multiple income sources and investments complicates retirement planning, necessitating a comprehensive financial plan.
- High-income individuals may be ineligible for certain savings accounts, requiring exploration of alternatives like Non-Qualified Deferred Compensation plans.
- Maintaining an Emergency Savings Account with 3-6 months’ worth of living expenses is advisable for financial stability.
- Strategies for effective retirement savings include maximising contributions to 401(k) and IRA accounts, and utilising backdoor Roth IRA options.
- Tax-efficient withdrawal strategies, such as strategic withdrawal sequencing and tax-loss harvesting, can help preserve wealth.
- Legacy planning is essential; establishing clear goals and utilising trusts can protect family wealth and reduce estate taxes.
- Regularly reviewing and updating estate plans ensures alignment with current desires and financial circumstances.
Introduction
Navigating retirement planning can feel overwhelming for high-income earners, who often face a maze of challenges that can impact their financial security. This article gently explores essential strategies crafted for affluent individuals, focusing on opportunities to optimize savings, manage tax liabilities, and thoughtfully incorporate legacy planning into their financial frameworks.
Imagine if you could safeguard your wealth while ensuring a prosperous retirement. As the stakes rise, it’s important to understand how you can effectively overcome the hurdles that accompany financial success. Together, we can navigate this journey, addressing your concerns and aspirations every step of the way.
Understand Unique Retirement Challenges for High-Income Earners
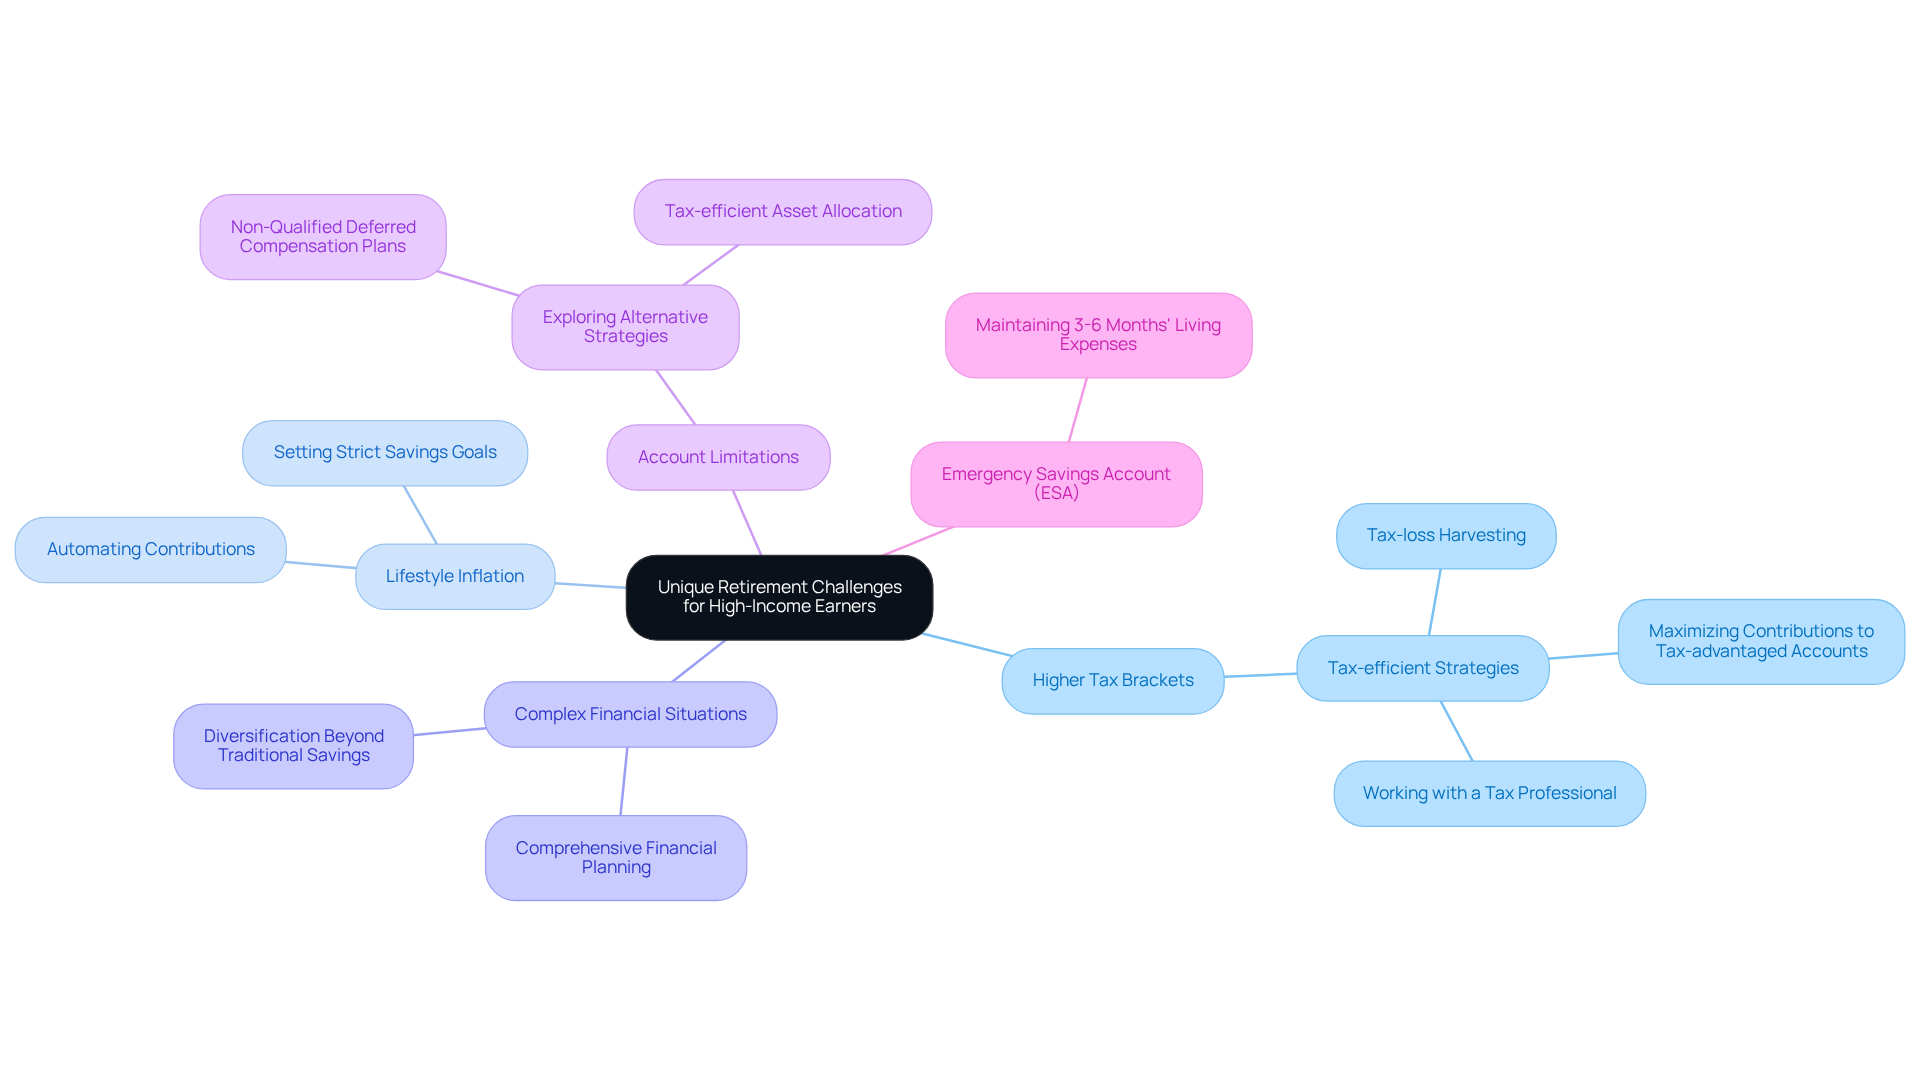
High-income earners often face unique challenges in their later years, highlighting the importance of retirement planning for high income earners to ensure their financial stability. Let’s explore some key issues together:
-
Higher Tax Brackets: As income increases, so do tax liabilities, which can significantly reduce net retirement income. Implementing tax-efficient strategies is crucial for retirement planning for high income earners, such as tax-loss harvesting and maximizing contributions to tax-advantaged accounts. Working with a tax professional can be a wonderful way to minimize taxes and enhance wealth accumulation.
-
Lifestyle Inflation: The tendency for lifestyle creep is common among high earners. As incomes rise, spending often follows suit, which can limit the resources available for savings after employment. Setting strict savings goals and automating contributions can help counteract this trend. Imagine redirecting those funds toward long-term economic security for your family.
-
High earners frequently manage multiple income sources, investments, and properties, resulting in complex financial situations that complicate retirement planning for high income earners. A comprehensive financial plan that incorporates retirement planning for high income earners and includes diversification beyond traditional savings accounts is essential for building a secure financial future.
-
Account Limitations: Many high-income individuals find themselves ineligible for certain savings accounts, such as Roth IRAs, due to income restrictions. Exploring alternative strategies, like Non-Qualified Deferred Compensation plans and tax-efficient asset allocation, can ensure you have sufficient savings for the future.
-
Emergency Savings Account (ESA): It’s advisable for high-income earners to maintain at least 3-6 months’ worth of living expenses in an Emergency Savings Account. This safety net can cover unforeseen costs and promote economic stability for your family.
Identifying and addressing these challenges is vital for crafting a strong financial plan that supports your family’s stability in the years to come, particularly in the realm of retirement planning for high income earners. Remember, we’re here for you, and together, we can navigate this journey toward financial security.
Implement Effective Retirement Savings Strategies
To effectively save for retirement, high-income earners should consider the following strategies:
-
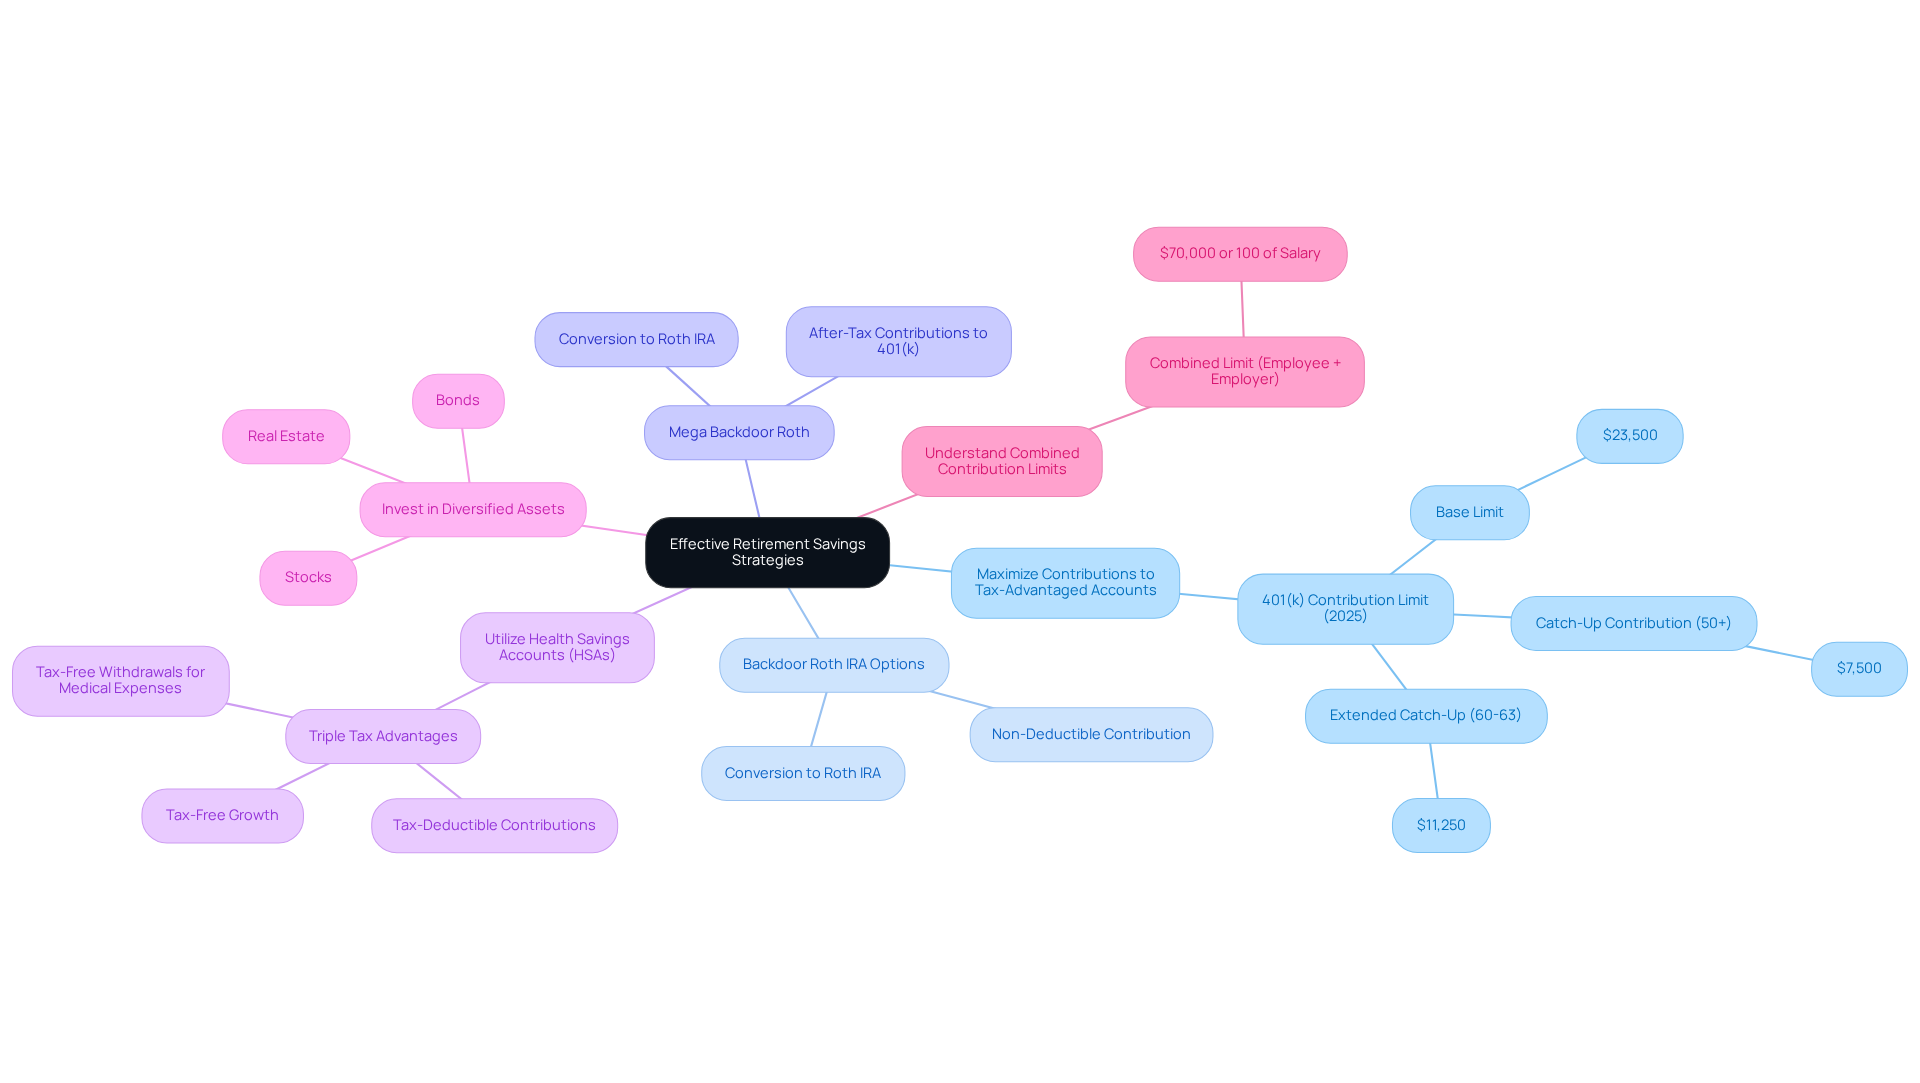
Maximize Contributions to Tax-Advantaged Accounts: Imagine fully utilizing your 401(k) and IRA accounts. In 2025, the contribution limit for 401(k) plans is set at $23,500, with an additional catch-up contribution of $7,500 for individuals aged 50 and older. For those aged 60 to 63, the extended catch-up contribution limit is $11,250. This approach not only reduces your taxable income but also allows for compound interest growth over time, helping you secure a brighter future for your family.
-
Explore backdoor Roth IRA options: It’s important to understand that retirement planning for high income earners can still involve accessing Roth IRAs through backdoor contributions. This entails making a non-deductible contribution to a traditional IRA and then converting it to a Roth IRA, allowing for tax-free growth and withdrawals during later years. This can be a valuable tool in your financial planning.
-
Consider a Mega Backdoor Roth: This advanced strategy permits individuals to contribute after-tax dollars to a 401(k) and then convert those funds to a Roth IRA. This significantly enhances your savings potential for the future, allowing for larger contributions beyond standard limits, which can be a game-changer for retirement planning for high income earners.
-
Utilize Health Savings Accounts (HSAs): HSAs provide triple tax advantages—contributions are tax-deductible, growth is tax-free, and withdrawals for qualified medical expenses are also tax-free. This makes HSAs an effective resource for saving for healthcare expenses in later life while simultaneously lowering your taxable income. Together, we can navigate these options to enhance your financial well-being.
-
Invest in Diversified Assets: Beyond conventional savings accounts, diversifying investments into real estate, stocks, and bonds can enhance growth potential and mitigate risks. A comprehensive portfolio can offer stability and growth, aligning with your long-term monetary objectives and providing peace of mind for your family.
-
Understand Combined Contribution Limits: In 2025, the combined contribution limit for employee and employer contributions to a 401(k) is $70,000 or 100% of the employee’s salary, whichever is lower. This enables increased savings potential, especially through retirement planning for high income earners like you.
By applying these approaches, high-income earners can engage in retirement planning for high income earners to create a strong investment portfolio that not only achieves their financial goals but also ensures their family’s future. Remember, we’re here for you, guiding you every step of the way.
Utilize Tax-Efficient Withdrawal and Investment Strategies
To ensure your retirement savings endure, it’s vital for high-income earners to embrace tax-efficient withdrawal and investment strategies that truly support your family’s future:
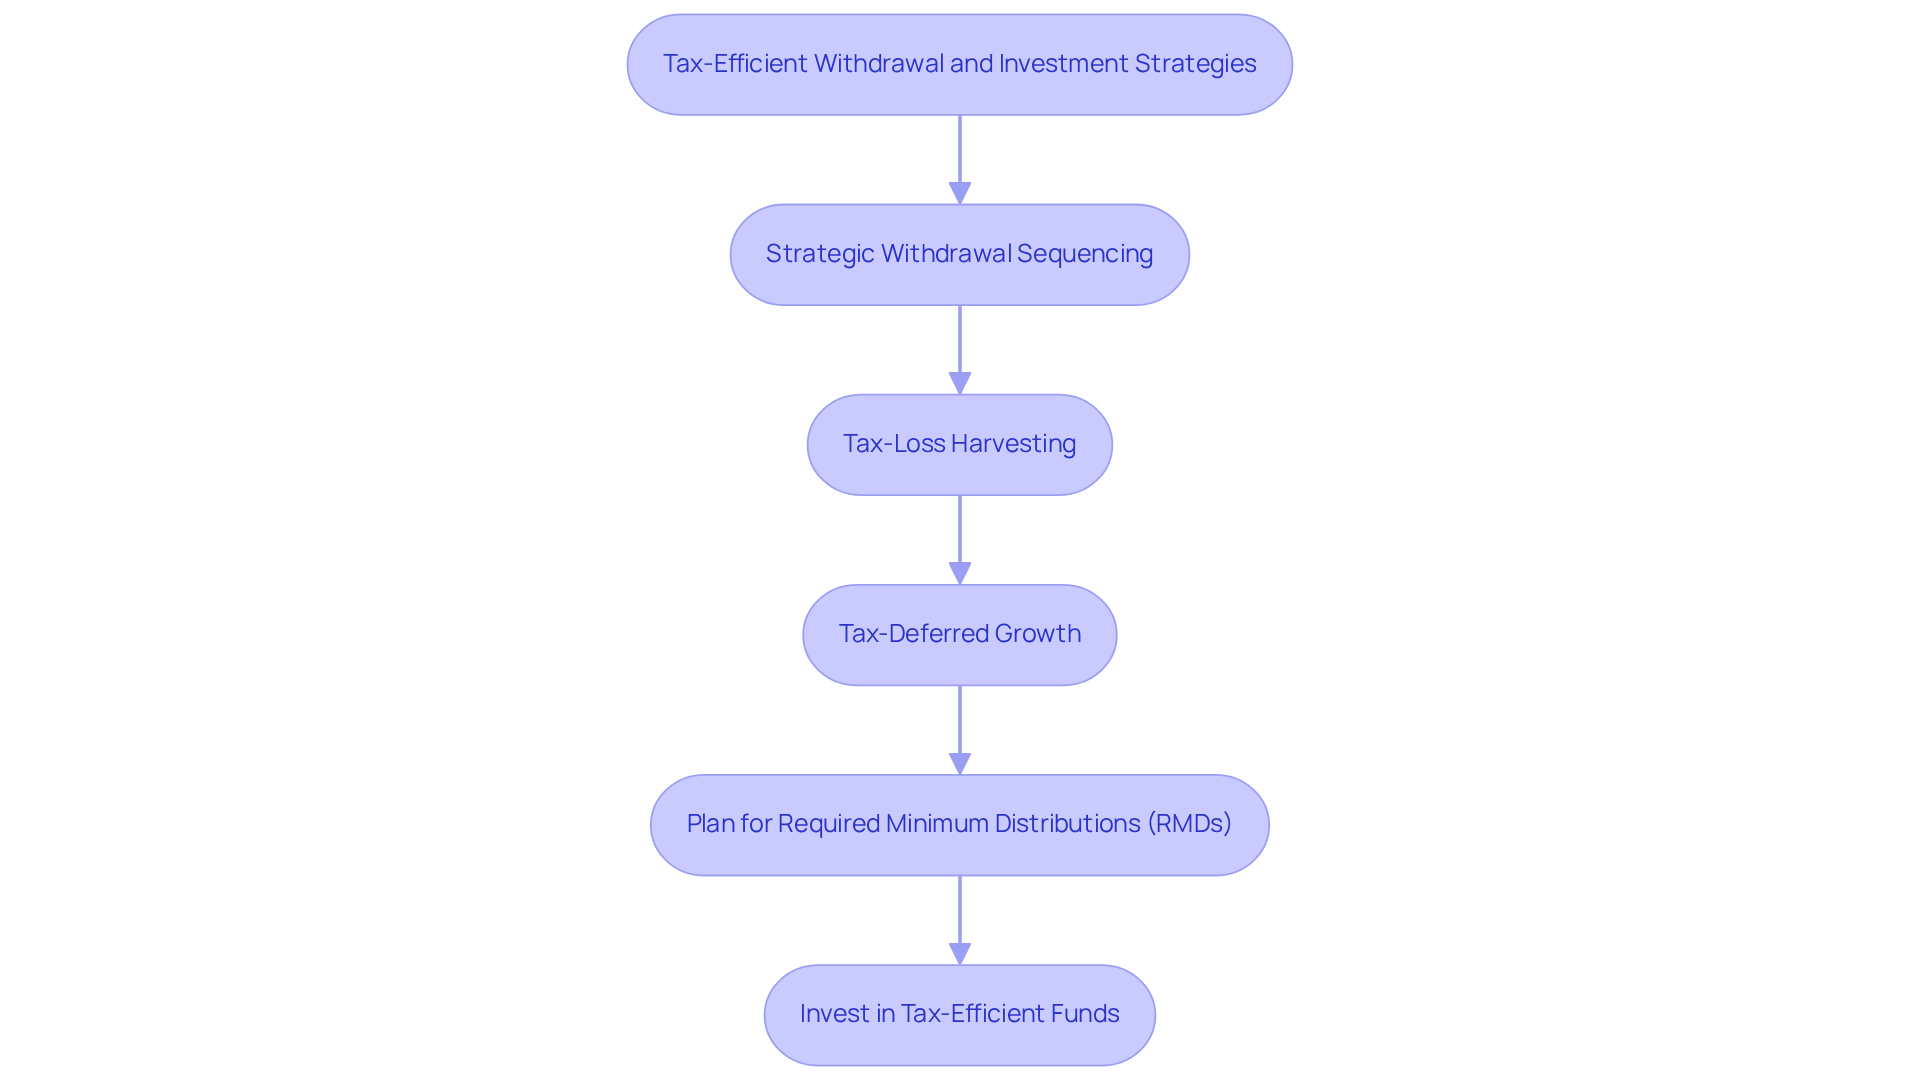
Imagine prioritizing your financial wellbeing with Strategic Withdrawal Sequencing. Start by withdrawing from taxable accounts first, then tax-deferred accounts, and finally Roth accounts. This thoughtful approach minimizes tax liabilities over time, allowing you to retain more wealth for your loved ones.
It’s also important to Consider Tax-Loss Harvesting. This strategy involves selling investments at a loss to offset capital gains, effectively reducing your taxable income. Research shows that timely tax-loss harvesting can enhance your after-tax wealth, especially during market corrections. Rather than waiting until year-end, a proactive approach can make a significant difference.
Next, Utilize Tax-Deferred Growth. Focus on investments that grow tax-deferred, like traditional IRAs and 401(k)s, to maximize growth potential before taxes come into play. This strategy allows for compounding without immediate tax implications, giving your savings the chance to flourish.
Don’t forget to Plan for Required Minimum Distributions (RMDs). Understanding RMD rules is crucial; withdrawals must begin by April 1 of the year following your 73rd birthday. For instance, if your account balance is $500,000 and your life expectancy factor is 25.6, your RMD would be $19,531.25. Planning these withdrawals can help you avoid unnecessary tax burdens as you age, ensuring a smoother transition into retirement.
Lastly, consider investing in Tax-Efficient Funds. Opt for mutual funds or ETFs designed to minimize capital gains distributions. This choice can significantly reduce tax liabilities, allowing you to accumulate wealth more efficiently.
By embracing these strategies for retirement planning for high income earners, you can confidently manage your withdrawals and investments, optimizing your resources while reducing tax effects. Remember, continual assistance from financial consultants can further enhance the effectiveness of these approaches. Together, we can navigate this journey toward a secure and prosperous retirement for you and your family.
Incorporate Legacy Planning into Retirement Strategies
Incorporating legacy planning into retirement strategies involves several key considerations that can profoundly impact your family’s future.
-
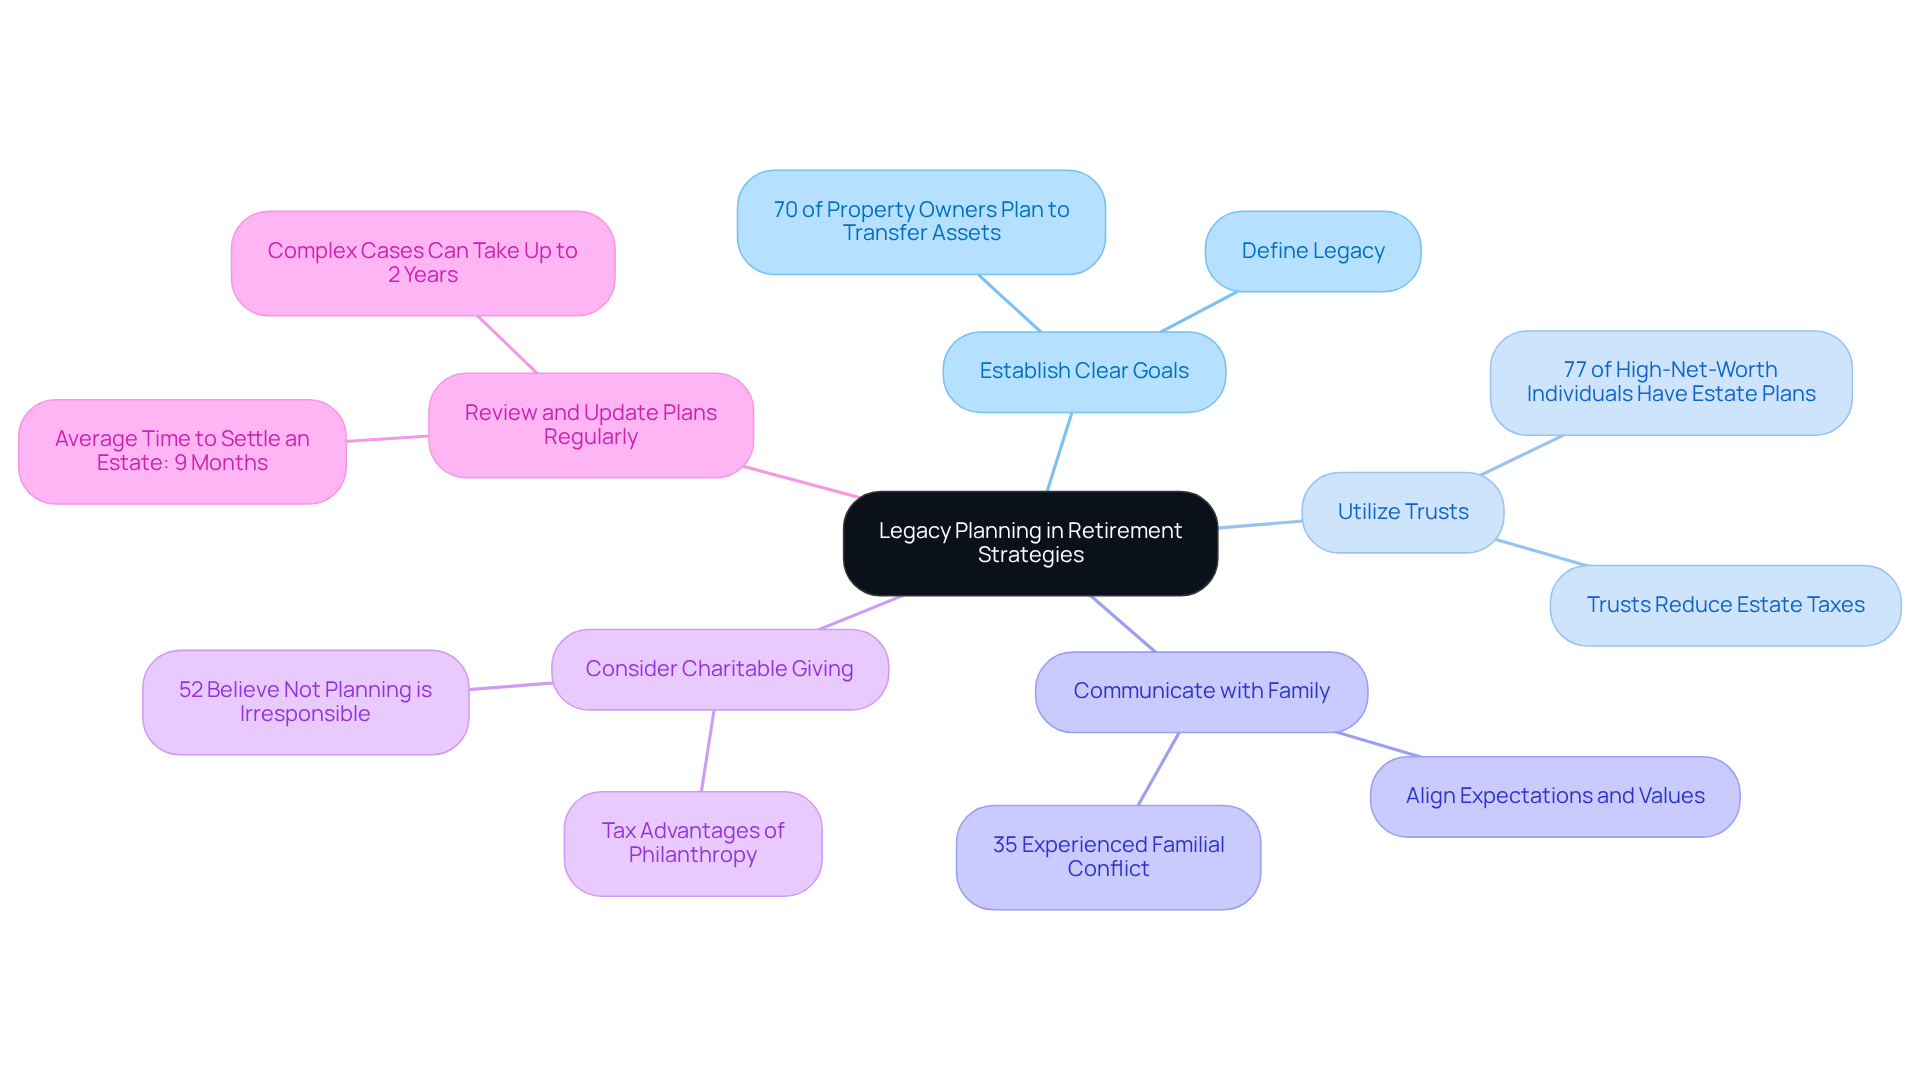
Establish Clear Goals: Imagine defining what legacy means to you and your family. This could include monetary assistance for children, charitable contributions, or the preservation of family wealth. Did you know that nearly 70% of property owners intend to transfer their properties to the next generation through inheritance? This statistic highlights the importance of clear legacy goals. As estate planning specialist Sasha Berson wisely states, “Estate planning is a proactive measure to safeguard families and ensure their economic future.”
-
Utilize Trusts and Estate Planning Tools: It’s important to understand that establishing trusts can effectively manage how assets are distributed after death, potentially reducing estate taxes and ensuring that your wishes are honored. Statistics reveal that 77% of individuals with a household net worth over $1 million have an estate plan, will, or trust, underscoring the prevalence of these tools among high-net-worth individuals. An estate planning attorney emphasizes, “Utilizing trusts is essential for high-net-worth individuals to ensure their legacy is preserved.”
-
Communicate with Family: Open discussions with family members about monetary goals and legacy intentions can help align everyone’s expectations and values. Research indicates that 35% of U.S. adults have experienced familial conflict due to a lack of estate planning, reinforcing the need for clear communication. This statistic connects back to our earlier point about establishing clear goals, creating a more cohesive narrative for your family.
-
Consider Charitable Giving: Incorporating philanthropy into your financial strategy can provide tax advantages while fulfilling personal values and leaving a lasting impact. A significant portion of the population believes that failing to create an estate plan is irresponsible, with 52% of adults over 55 expressing this sentiment. Together, we can navigate this journey of giving back while securing your family’s future.
-
Review and Update Plans Regularly: As life circumstances change, so should your legacy plans. Frequently assessing and modifying your estate plan to align with current desires and economic circumstances is essential. The average time to settle an estate in the U.S. is around nine months, but complex cases can extend this to two years, making timely updates essential for peace of mind.
By integrating legacy planning into retirement planning for high income earners, individuals can ensure that their financial legacy aligns with their values and supports their family’s future. Remember, we’re here for you every step of the way.
Conclusion
High-income earners encounter unique retirement planning challenges that require thoughtful and personalized strategies for success. It’s essential to recognize these specific hurdles—such as navigating higher tax brackets, coping with lifestyle inflation, and managing intricate financial situations—so that a solid retirement plan can be crafted. By addressing these concerns, individuals can safeguard their financial future and create stability for their families.
This article presents vital strategies that include:
- Maximizing contributions to tax-advantaged accounts
- Utilizing health savings accounts
- Implementing tax-efficient withdrawal methods
Furthermore, integrating legacy planning into retirement strategies ensures that financial goals reflect personal values and family needs. These insights empower high-income earners to construct a comprehensive and effective retirement plan.
Ultimately, successful retirement planning for affluent individuals calls for a proactive approach that encompasses financial management, tax efficiency, and legacy considerations. By embracing these steps, high-income earners can not only enhance their wealth but also leave a meaningful legacy for future generations. Taking action today can lead to a more secure and prosperous tomorrow, ensuring that financial well-being endures long after retirement.
Frequently Asked Questions
What unique challenges do high-income earners face in retirement planning?
High-income earners face challenges such as higher tax brackets, lifestyle inflation, complex financial situations with multiple income sources, account limitations, and the need for adequate emergency savings.
How do higher tax brackets affect retirement income for high-income earners?
Higher tax brackets increase tax liabilities, which can significantly reduce net retirement income. Implementing tax-efficient strategies is crucial to minimize taxes and enhance wealth accumulation.
What is lifestyle inflation and how does it impact high-income earners?
Lifestyle inflation, or lifestyle creep, refers to the tendency of individuals to increase their spending as their income rises. This can limit the resources available for savings, making it important for high-income earners to set strict savings goals and automate contributions.
Why is a comprehensive financial plan important for high-income earners?
High-income earners often manage multiple income sources, investments, and properties, resulting in complex financial situations. A comprehensive financial plan that includes retirement planning and diversification is essential for building a secure financial future.
What account limitations do high-income earners face regarding retirement savings?
Many high-income individuals may be ineligible for certain savings accounts, like Roth IRAs, due to income restrictions. Exploring alternative strategies, such as Non-Qualified Deferred Compensation plans and tax-efficient asset allocation, can help ensure sufficient savings.
How much should high-income earners maintain in an Emergency Savings Account (ESA)?
It is advisable for high-income earners to maintain at least 3-6 months’ worth of living expenses in an Emergency Savings Account to cover unforeseen costs and promote economic stability.
List of Sources
- Understand Unique Retirement Challenges for High-Income Earners
- Beyond Six Figures: Why High-Income Earners Still Need Smart Retirement Planning (https://securesave.com/blog/beyond-six-figures-why-high-income-earners-still-need-smart-retirement-planning)
- High Earners Face Retirement Challenges (https://captrust.com/resources/high-earners-face-retirement-challenges)
- How Much High-Income Earners Have Saved for Retirement (https://smartasset.com/retirement/average-retirement-savings-for-high-income-earners)
- Implement Effective Retirement Savings Strategies
- IRS Raises 401(k) Contribution Limit for 2025 (https://shrm.org/topics-tools/news/benefits-compensation/irs-raises-401k-contribution-limit-for-2025)
- 401(k) Contribution Limits in 2025 | Guideline (https://guideline.com/education/articles/how-much-can-you-contribute-to-a-401-k-in-2025)
- 401(k) limit increases to $23,500 for 2025, IRA limit remains $7,000 | Internal Revenue Service (https://irs.gov/newsroom/401k-limit-increases-to-23500-for-2025-ira-limit-remains-7000)
- 2025 Retirement Plan Limits Announced | Groom Law Group (https://groom.com/resources/2025-retirement-plan-limits-announced)
- Utilize Tax-Efficient Withdrawal and Investment Strategies
- 5 Common Retirement Tax Traps o Avoid at All Costs (https://finance.yahoo.com/news/5-common-retirement-tax-traps-155005423.html)
- Understanding RMD Age: Key Facts for Retirees – Insight Wealth Strategies (https://insight2wealth.com/blog/understanding-rmd-age-key-facts-for-retirees)
- Future-Proofing: Fundamental Strategies for Success for Every Age in Retirement (https://stearnsfinancial.com/blogs/planning-resources/future-proofing-fundamental-strategies-for-success-for-every-age-in-retirement)
- Combining Investment and Tax Strategies for Optimizing Lifetime Solvency under Uncertain Returns and Mortality (https://mdpi.com/1911-8074/14/7/285)
- Tax-Loss Harvesting: Frequency Matters (https://russellinvestments.com/us/blog/tax-loss-harvesting-frequency-matters)
- Incorporate Legacy Planning into Retirement Strategies
- Only 26% of Americans Have an Estate Plan (https://thinkadvisor.com/2024/04/23/only-26-of-americans-have-an-estate-plan)
- Estate Planning Statistics to Read Before Writing Your Will (https://legalzoom.com/articles/estate-planning-statistics)
- Top Estate Planning Law Statistics and Trends for [2025] (https://growlaw.co/blog/estate-planning-law-statistics)
- 50 Estate Planning Statistics and Facts You Need to Know (https://justvanilla.com/blog/estate-planning-statistics-and-facts-you-need-to-know)
- Estate Planning Statistics Statistics: ZipDo Education Reports 2025 (https://zipdo.co/estate-planning-statistics)

Kevin has advised high-income W-2 tech and biotech families since 2015, and leads the education-first Age Five Family Office from Brea, California.
Connect on LinkedIn → · About KevinThis is part of how we approach Retirement & Employee Benefits for high-income W-2 families at Bright Advisers.
Keep reading