

Key Highlights:
- RIAs operate under a fiduciary standard, prioritising clients’ best interests and offering personalised investment guidance.
- Broker-Dealers earn commissions on trades, focusing on short-term investments, which may conflict with clients’ long-term goals.
- Wirehouses provide a broad range of services but often charge higher fees and may lack personalised attention.
- RIAs are expected to grow by 12% by 2028, indicating their increasing relevance for young families.
- Broker-Dealers have lower minimum investment requirements but offer less tailored advice.
- Wirehouses offer comprehensive services but may limit advisors’ flexibility in meeting clients’ specific needs.
- Choosing the right advisor involves considering financial goals, service needs, cost structure, and the importance of trust and communication.
- The trend towards fee-based revenue is anticipated to grow, with 77.6% of the wealth management industry projected to operate on a fee-based model by 2026.
Introduction
Navigating the financial landscape can feel overwhelming, especially for young families eager to secure a bright future. With so many advisory options out there, understanding the differences between Registered Investment Advisors (RIAs), Broker-Dealers, and Wirehouses is essential. This article explores these three financial advisory models, shedding light on their unique features and the potential benefits they can bring to your family.
Imagine if you could find the right financial guidance that truly resonates with your family’s values and long-term goals. It’s important to understand how each model operates and what they can offer you. By delving into these options, you can make informed decisions that align with your aspirations.
As we journey through this topic together, remember that you’re not alone. We’re here for you, ready to support you in making the best choices for your family’s financial well-being. Let’s explore how these advisory models can help you build a secure future.
Understanding Financial Advisory Models: RIAs, Broker-Dealers, and Wirehouses
Understanding [financial advisory models](https://brightadvisers.com/?p=12378) is crucial for young households looking to secure their economic futures. Let’s explore the differences among the three primary types of advisors available to you: ria vs broker dealer vs wirehouse.
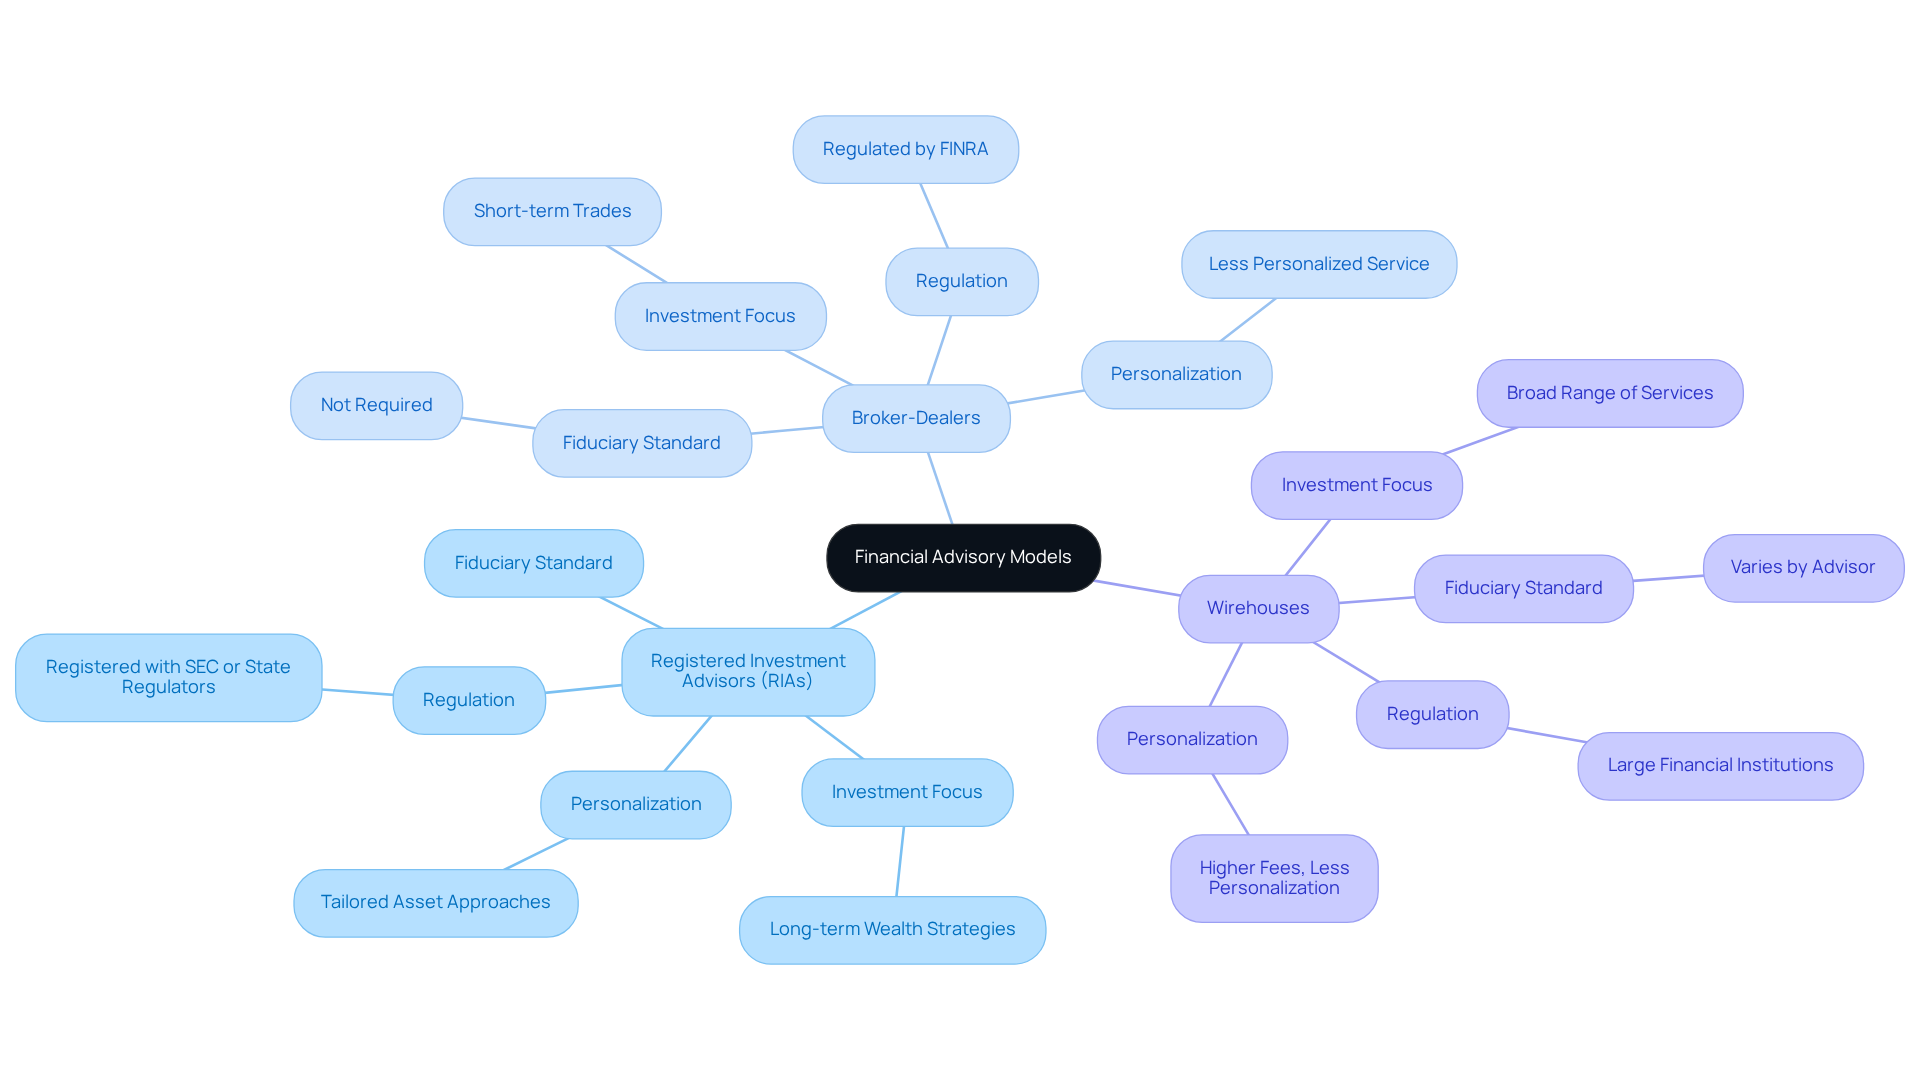
- [[Registered Investment Advisors (RIAs)](https://sec.gov/data-research/statistics-data-visualizations/investment-adviser-statistics)](https://investmentadviser.org/industry-snapshots) are dedicated firms that provide [personalized investment guidance](https://brightadvisers.com/?p=11118). They’re registered with the SEC or state regulators and operate under a fiduciary standard, meaning they must act in your best interests. RIAs focus on [long-term wealth strategies](https://brightadvisers.com/?p=10972) and tailor their asset approaches to fit your unique needs, making them a great choice for families wanting to build a secure financial future.
- Broker-Dealers are primarily in the business of buying and selling securities, earning commissions on each trade. They’re regulated by FINRA and often focus on short-term trades. While they can be helpful, their approach may not align with the that many families seek over time.
- Wirehouses are large financial institutions that offer a broad range of services, including investment management and financial planning. They come with the advantage of strong brand recognition and extensive resources. However, they often charge higher fees and may not provide the personalized service that RIAs do.
For young families, understanding the concepts of ria vs broker dealer vs wirehouse is essential. Choosing a financial mentor who aligns with your long-term goals can lead to better resource management and a stronger financial foundation. Imagine if you could navigate your financial journey with confidence, knowing you have the right support by your side.
We’re here for you, ready to help you make informed decisions that resonate with your family values. Together, we can navigate this journey toward a secure financial future.
Defining Characteristics: RIAs, Broker-Dealers, and Wirehouses
Each financial advisory model has unique attributes designed to meet the diverse needs of clients, especially young families.
RIAs:
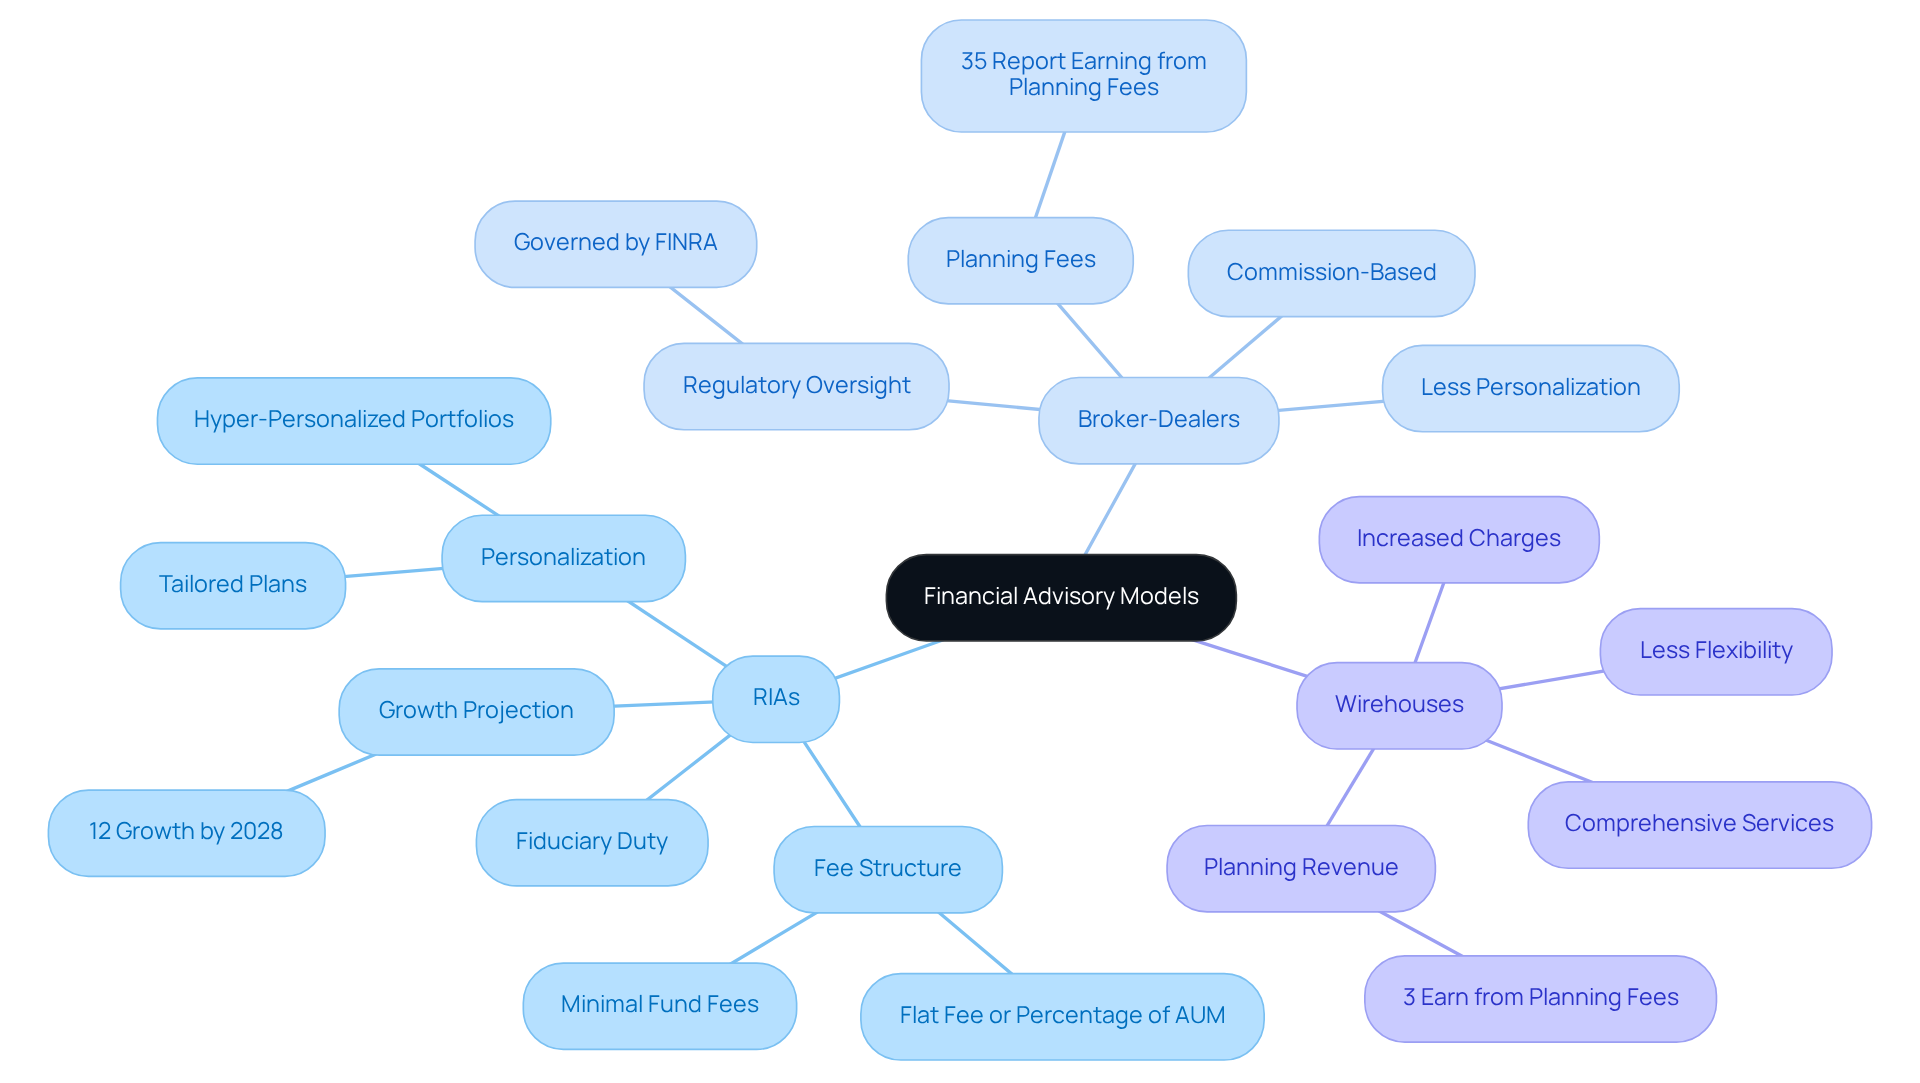
- [Fiduciary Duty](https://aboutschwab.com/ria-benchmarking-study-2025): RIAs are committed to acting in their clients’ best interests, ensuring ethical practices that you can trust.
- Fee Structure: They typically use a clear fee model, charging either a flat fee or a percentage of assets under management. This transparency helps families budget effectively. Bright Advisers exemplifies this with their focus on [minimal fund fees](https://brightadvisers.com/10-benefits-of-fee-only-investment-for-young-families), making financial services more accessible for households.
- Personalization: RIAs shine in crafting tailored plans that align with your family’s goals, whether it’s education funding or retirement planning. Bright Advisers leverages advanced technology to create [hyper-personalized portfolios](https://brightadvisers.com/private-client-investment-management-for-young-families-success), optimizing financial outcomes for families. Their innovative investment strategies, like the Tactical Portfolio and Quality Strategy, showcase their commitment to your financial well-being.
- Growth Projection: Independent RIAs are expected to grow by 12% by 2028, highlighting their increasing importance in the advisory landscape for young households.
Broker-Dealers:
- Commission-Based: Broker-Dealers primarily earn revenue through commissions on trades, which can sometimes lead to conflicts of interest when recommending products.
- Less Personalization: Their offerings often lean towards standardized products, which may not meet the tailored needs of many families.
- Regulatory Oversight: Governed by FINRA, Broker-Dealers focus on suitability rather than fiduciary responsibility, which might not always align with your best interests.
- [Planning Fees](https://planadviser.com/fee-based-models-dominate-advisers-respond-shifting-client-expectations): Only 35% of independent Broker-Dealer channel advisors report earning revenue from planning fees, indicating a limitation in personalized service.
Wirehouses:
- Comprehensive Services: Wirehouses offer a wide range of financial services, including investment banking and wealth management, catering to various financial needs.
- Increased Charges: Their extensive service options and brand reputation often lead to higher costs, which can be a concern for budget-conscious families.
- Less Flexibility: Advisors in Wirehouses may face restrictions on customizing solutions due to corporate policies, potentially limiting their ability to meet your unique needs.
- Planning Revenue: Only 3% of wirehouse advisors earn income from planning fees, which could be a crucial factor for young families evaluating their options.
Understanding these traits is vital for young families seeking a consultant that aligns with their values and , particularly in the context of ria vs broker dealer vs wirehouse. As Andrew Blake wisely noted, “Open and candid discussions about the cost of services will build trust and strengthen relationships between clients and advisors while attracting prospective clients willing to pay for advice.” Moreover, the trend towards fee-based revenue is anticipated to grow, with 77.6% of the wealth management industry projected to operate on a [fee-based model](https://wealthsolutionsreport.com/cerulli-almost-78-of-industry-on-fee-based-model-by-2026) by 2026.
Together, we can navigate this journey, ensuring that your family’s [financial future](https://brightadvisers.com/essential-tax-planning-strategies-for-young-families-financial-health) is secure.
Pros and Cons of RIAs, Broker-Dealers, and Wirehouses
When it comes to choosing the right , such as ria vs broker dealer vs wirehouse, understanding the pros and cons can be overwhelming. But don’t worry, we’re here to help you navigate this journey with confidence.
RIAs:
- Pros:
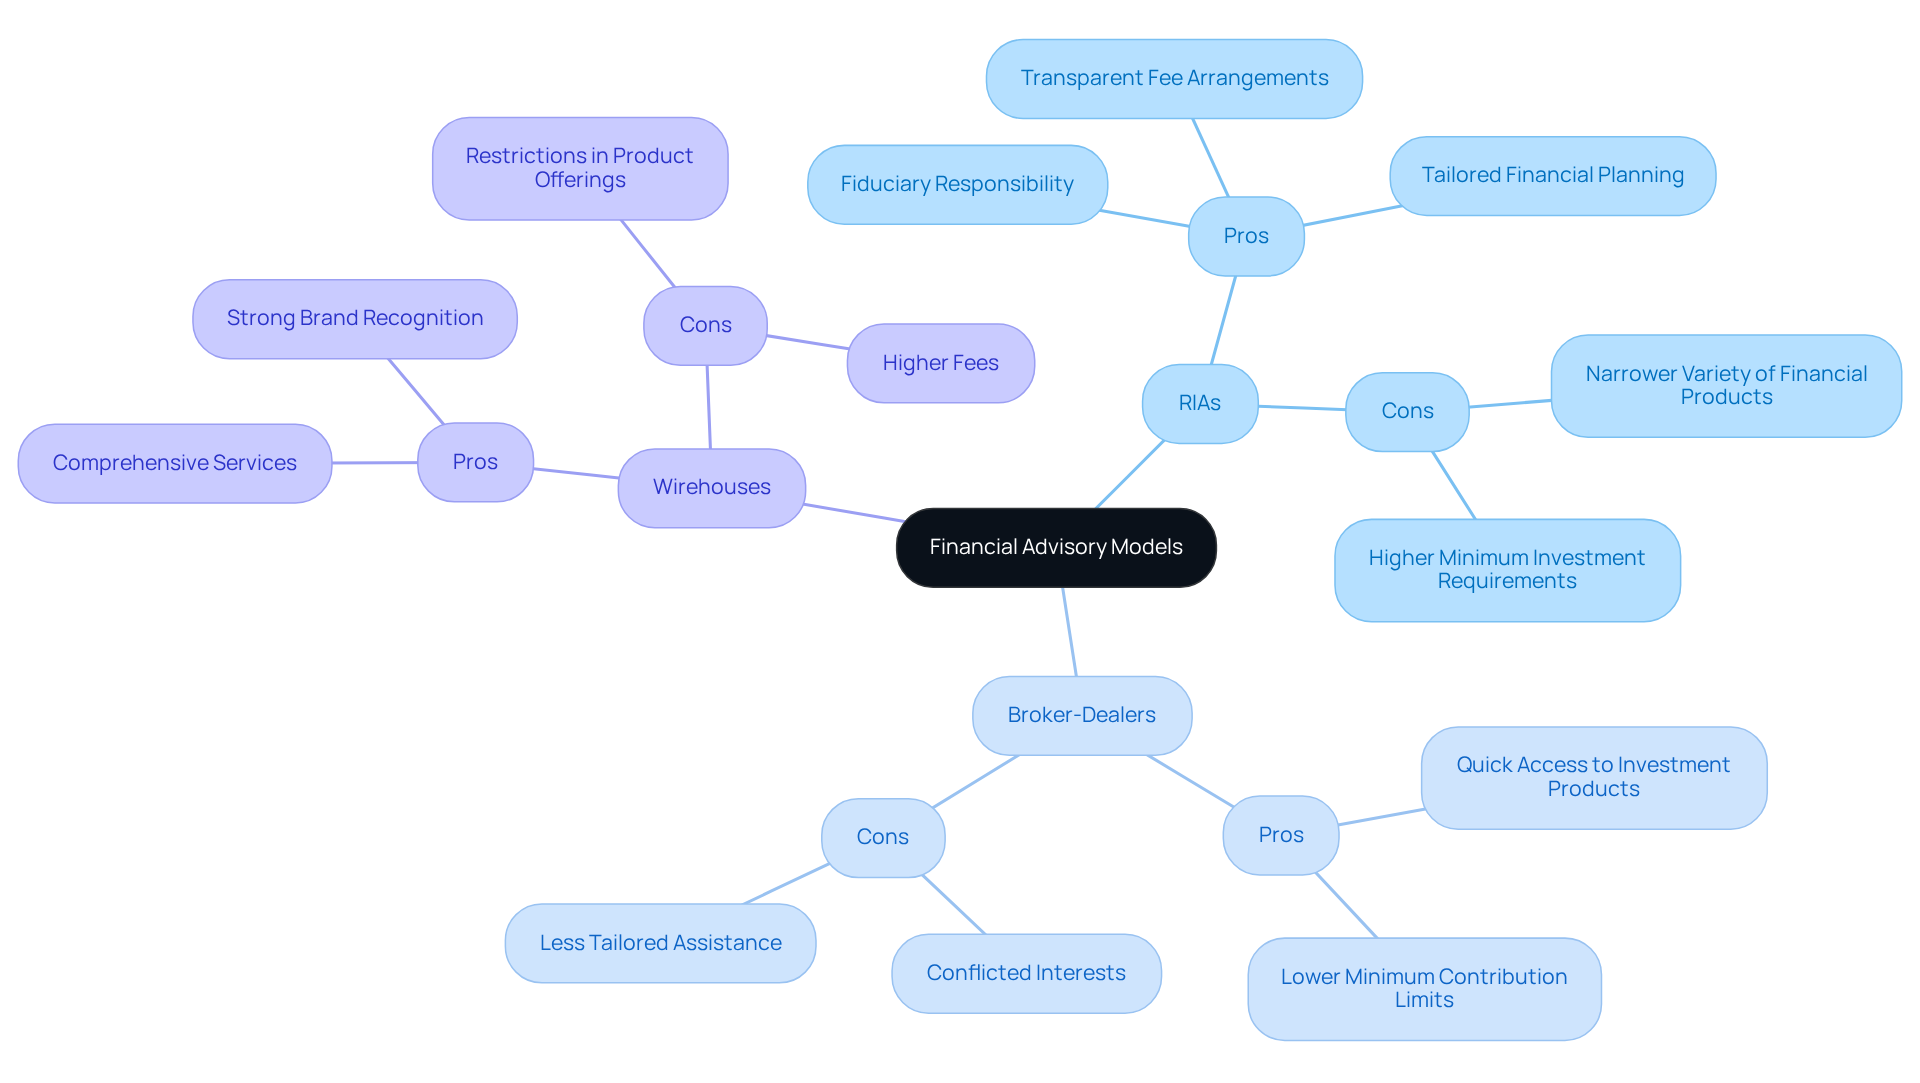
- They’re legally bound by fiduciary responsibility, which means your best interests come first.
- With clear fee arrangements, like Bright Advisers’ commitment to low fund charges, you can trust that there are no hidden expenses. This transparency helps optimize your financial returns, benefiting your household.
- RIAs offer tailored financial planning that aligns with your unique needs, creating a more personalized experience.
- Cons:
- They often have higher minimum investment requirements, which might limit access for some families.
- You may find a narrower variety of financial products compared to larger firms, which could restrict your choices.
Broker-Dealers:
- Pros:
- They provide quick access to a wide range of investment products, making it easy to jump into investment opportunities.
- Typically, they have lower minimum contribution limits, making them more accessible for families just starting their financial journey.
- Cons:
- Conflicted interests can arise from commission-based earnings, which might affect the quality of advice you receive.
- They usually offer less tailored assistance and planning, which may not fully meet your family’s specific needs.
Wirehouses:
- Pros:
- These firms offer comprehensive services, including investment banking, all under one roof, simplifying your financial management.
- Their strong brand recognition and established reputation can instill confidence in clients like you.
- Cons:
- They often come with higher fees, which can eat into your investment returns over time.
- Advisors may face restrictions in product offerings due to corporate policies, limiting their flexibility to meet your needs.
This analysis aims to empower young households like yours to navigate the complexities of financial advisory options. By understanding these models, such as ria vs broker dealer vs wirehouse, you can choose one that aligns with your unique situation and financial goals. Plus, the investment adviser sector is growing, with the number of advisers increasing to 15,870 in 2024, reflecting a strong demand for diverse services. Remember, together, we can navigate this journey and find the right support for your family.
Choosing the Right Advisor: Suitability for Young Families and Financial Goals
Choosing the right monetary consultant is crucial for young families as they navigate their financial futures. Here are some key considerations to help guide your decision:
-
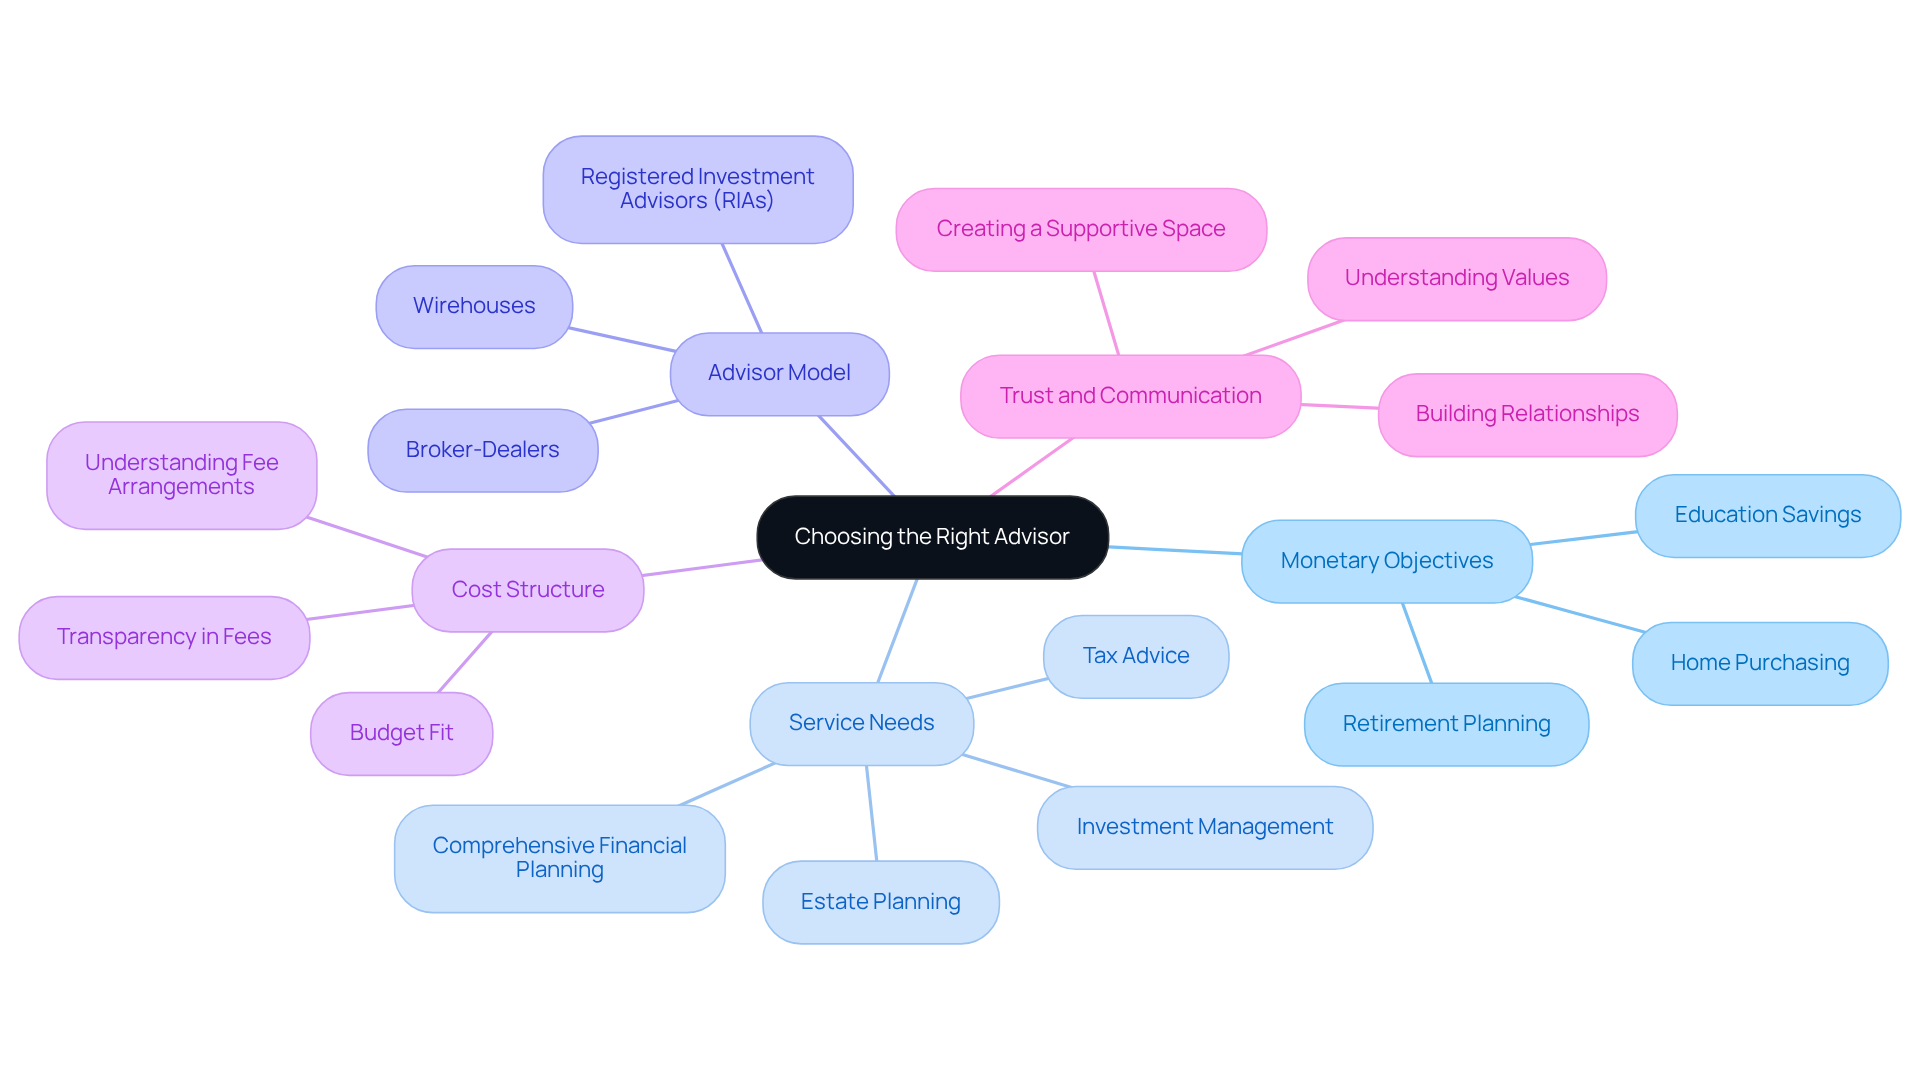
Monetary Objectives: Think about your short-term and long-term financial goals. Are you saving for your children’s education, planning for retirement, or dreaming of buying a home? In 2025, many families are focusing on education savings, showing a growing awareness of the importance of money management.
-
Service Needs: Consider what services your household truly needs. Do you require comprehensive financial planning, investment management, or specialized help like estate planning and tax advice? A holistic approach to wealth management can help you balance immediate needs with your long-term dreams.
-
Advisor Model:
- Registered Investment Advisors (RIAs) are perfect for families looking for personalized, fiduciary advice tailored to your unique situation. They often take a collaborative approach, ensuring your financial strategies align with your values and goals.
- Broker-Dealers might appeal to those wanting quick access to investment products, but in the context of ria vs broker dealer vs wirehouse, they often lack the depth of thorough planning.
- Wirehouses offer a wide range of services, but when considering options like RIA vs broker dealer vs wirehouse, families on a budget may find the higher fees and less personalized attention concerning.
-
Cost Structure: It’s vital to understand the fee arrangements of potential advisors. Make sure they fit within your family’s budget and financial strategy. Transparency in fees can greatly impact your long-term financial health.
-
Trust and Communication: Building a strong relationship with your advisor is essential. Ensure they understand your values and financial aspirations, creating a supportive space for discussing money matters.
By thoughtfully considering these factors, you can choose an advisor who not only meets your immediate financial needs but also supports your long-term financial well-being. Together, we can towards a more secure future.
Conclusion
Navigating the financial advisory landscape can be a pivotal step for young families aiming to secure their economic future. Imagine if you could make informed decisions that truly align with your unique financial goals and values. By understanding the distinctions between Registered Investment Advisors (RIAs), Broker-Dealers, and Wirehouses, you can find the right support to guide you on this journey.
- RIAs stand out for their fiduciary duty and tailored financial planning, making them a preferred choice for families seeking a more personalized approach. They prioritize your long-term growth and offer the kind of service that feels like a partnership.
- In contrast, Broker-Dealers provide quick access to investment products, but they may not offer the depth of comprehensive planning that your family deserves.
- Wirehouses, while offering a broad range of services, often come with higher fees and less flexibility.
It’s important to understand these nuances as you evaluate your options and consider what best suits your family’s financial aspirations.
Ultimately, the choice of a financial advisor should reflect your family’s specific needs, goals, and budget considerations. As you look toward the future, prioritizing transparency, trust, and a collaborative approach in your financial planning will be crucial. Together, we can navigate this journey, ensuring that you have the right support to manage the complexities of financial management.
By thoughtfully assessing these factors, young households can embark on a path toward a secure and prosperous financial future. Remember, we’re here for you, ready to help you every step of the way.
Frequently Asked Questions
What are the three primary types of financial advisors?
The three primary types of financial advisors are Registered Investment Advisors (RIAs), Broker-Dealers, and Wirehouses.
What is a Registered Investment Advisor (RIA)?
A Registered Investment Advisor (RIA) is a dedicated firm that provides personalized investment guidance, operates under a fiduciary standard, and focuses on long-term wealth strategies tailored to individual needs.
How are RIAs regulated?
RIAs are regulated by the SEC or state regulators.
What is the main focus of Broker-Dealers?
Broker-Dealers primarily focus on buying and selling securities and earn commissions on each trade, often emphasizing short-term trades.
How are Broker-Dealers regulated?
Broker-Dealers are regulated by FINRA.
What services do Wirehouses offer?
Wirehouses are large financial institutions that offer a broad range of services, including investment management and financial planning.
What are the advantages and disadvantages of Wirehouses?
Wirehouses offer strong brand recognition and extensive resources, but they often charge higher fees and may not provide the personalized service that RIAs do.
Why is it important for young families to understand these financial advisory models?
Understanding these financial advisory models helps young families choose a financial mentor that aligns with their long-term goals, leading to better resource management and a stronger financial foundation.
List of Sources
- Understanding Financial Advisory Models: RIAs, Broker-Dealers, and Wirehouses
- Industry Statistics (https://investmentadviser.org/industry-snapshots)
- 2025 RIA Benchmarking Study | Charles Schwab (https://aboutschwab.com/ria-benchmarking-study-2025)
- SEC.gov | Investment Adviser Statistics (https://sec.gov/data-research/statistics-data-visualizations/investment-adviser-statistics)
- Schwab 2025 RIA benchmarking study: Growth drivers and performance (https://advisorengine.com/action-magazine/articles/schwab-2025-ria-benchmarking-study-growth-drivers-and-performance)
- Financial advisor industry statistics: key data and trends (https://unbiased.com/pro/discover/trends-insight/financial-advisor-industry-statistics)
- Defining Characteristics: RIAs, Broker-Dealers, and Wirehouses
- 2025 RIA Benchmarking Study | Charles Schwab (https://aboutschwab.com/ria-benchmarking-study-2025)
- Asset-based fees remain dominant, fixed and hourly models gaining ground among RIAs (https://investmentnews.com/practice-management/asset-based-fees-remain-dominant-fixed-and-hourly-models-gaining-ground-among-rias/261568)
- Cerulli: Almost 78% Of Industry On Fee-Based Model By 2026 (https://wealthsolutionsreport.com/cerulli-almost-78-of-industry-on-fee-based-model-by-2026)
- Cerulli Associates | More Than 72% of Financial Advisors Are… (https://cerulli.com/press-releases/more-than-72-of-financial-advisors-are-compensated-by-fee-based-models)
- Fee-Based Models Rise as Advisers Adapt to Client Needs | PLANADVISER (https://planadviser.com/fee-based-models-dominate-advisers-respond-shifting-client-expectations)
- Pros and Cons of RIAs, Broker-Dealers, and Wirehouses
- Industry Statistics (https://investmentadviser.org/industry-snapshots)
- Choosing the Right Financial Advisor: Differences Between RIAs, Wirehouses, and Broker-Dealers (https://merceradvisors.com/insights/personal-finance/choosing-the-right-financial-advisor-differences-between-rias-wirehouses-and-broker-dealers)
- Wirehouses lead alternatives adoption, RIAs face strategic crossroads (https://investmentnews.com/alternatives/wirehouses-lead-alternatives-adoption-rias-face-strategic-crossroads/262247)
- Why Financial Advisors Are Leaving their Wirehouses to be RIAs (https://aldeninvestmentgroup.com/blog/why-financial-advisors-are-leaving-their-wirehouses-to-be-rias)
- The top fee-only RIAs ranked by AUM in 2025 (https://financial-planning.com/list/ria-leaders-2025-top-20-firms-by-aum)
- Choosing the Right Advisor: Suitability for Young Families and Financial Goals
- Only 41% of Americans Use a Financial Advisor—And Most Younger Adults Shun the Professionals (https://investopedia.com/americans-using-a-financial-advisor-11812935)
- 35 Quotes for Financial Advisors on a Tough Day | Don Connelly & Associates (https://donconnelly.com/35-quotes-for-financial-advisors)
- What to Ask a Financial Planner for Young Families – Bright Advisers (https://brightadvisers.com/what-to-ask-a-financial-planner-for-young-families)
- Confronted with Higher Living Costs, 72% of Young Adults Take Action to Improve their Financial Health, finds BofA Better Money Habits Study (https://newsroom.bankofamerica.com/content/newsroom/press-releases/2025/07/confronted-with-higher-living-costs–72–of-young-adults-take-ac.html)
- Majority of Americans Say “Seek Financial Advice Before Age 40,” According to Northwestern Mutual Planning & Progress Study (https://news.northwesternmutual.com/2025-05-06-2025-NORTHWESTERN-MUTUAL-PLANNING-PROGRESS-STUDY)

Kevin has advised high-income W-2 tech and biotech families since 2015, and leads the education-first Age Five Family Office from Brea, California.
Connect on LinkedIn → · About KevinThis is part of how we approach Investment & Risk Management for high-income W-2 families at Bright Advisers.
Keep reading