

Key Highlights:
- A 529 plan helps families save for education expenses with tax advantages, allowing tax-free growth and withdrawals for eligible costs.
- Starting January 1, 2024, families can transfer unspent 529 funds to a Roth IRA, enhancing flexibility in educational savings.
- Eligibility for rollover requires the 529 account to be open for at least 15 years and funds to be in the account for a minimum of 5 years.
- The transfer amount must comply with Roth IRA contribution limits, set at $7,000 for 2025, with a lifetime maximum of $35,000 per beneficiary.
- To avoid penalties, funds must be rolled over within 60 days of withdrawal from a 529 account.
- Common rollover challenges include understanding eligibility, paperwork delays, timing of transfers, and accurate tax reporting.
- Maintaining detailed records throughout the rollover process is crucial for compliance and future reference.
Introduction
As families increasingly seek flexible financial strategies to secure their children’s educational futures, the new opportunity to transfer unspent funds from a 529 account to a Roth IRA is generating significant interest. Imagine if you could optimize your savings while adapting to your child’s changing educational needs. This process not only offers a chance to make the most of your hard-earned money but also provides peace of mind during uncertain times.
However, navigating the intricacies of this rollover can feel daunting. It’s important to understand the eligibility requirements, tax implications, and potential pitfalls that may arise. What steps can families take to ensure a smooth transition while maximizing the benefits of their savings?
We’re here for you. Together, we can navigate this journey and explore how this financial strategy can align with your family’s goals. By taking informed steps, you can secure a brighter future for your children, ensuring that their educational aspirations are within reach.
Understand 529 Accounts and Their Purpose
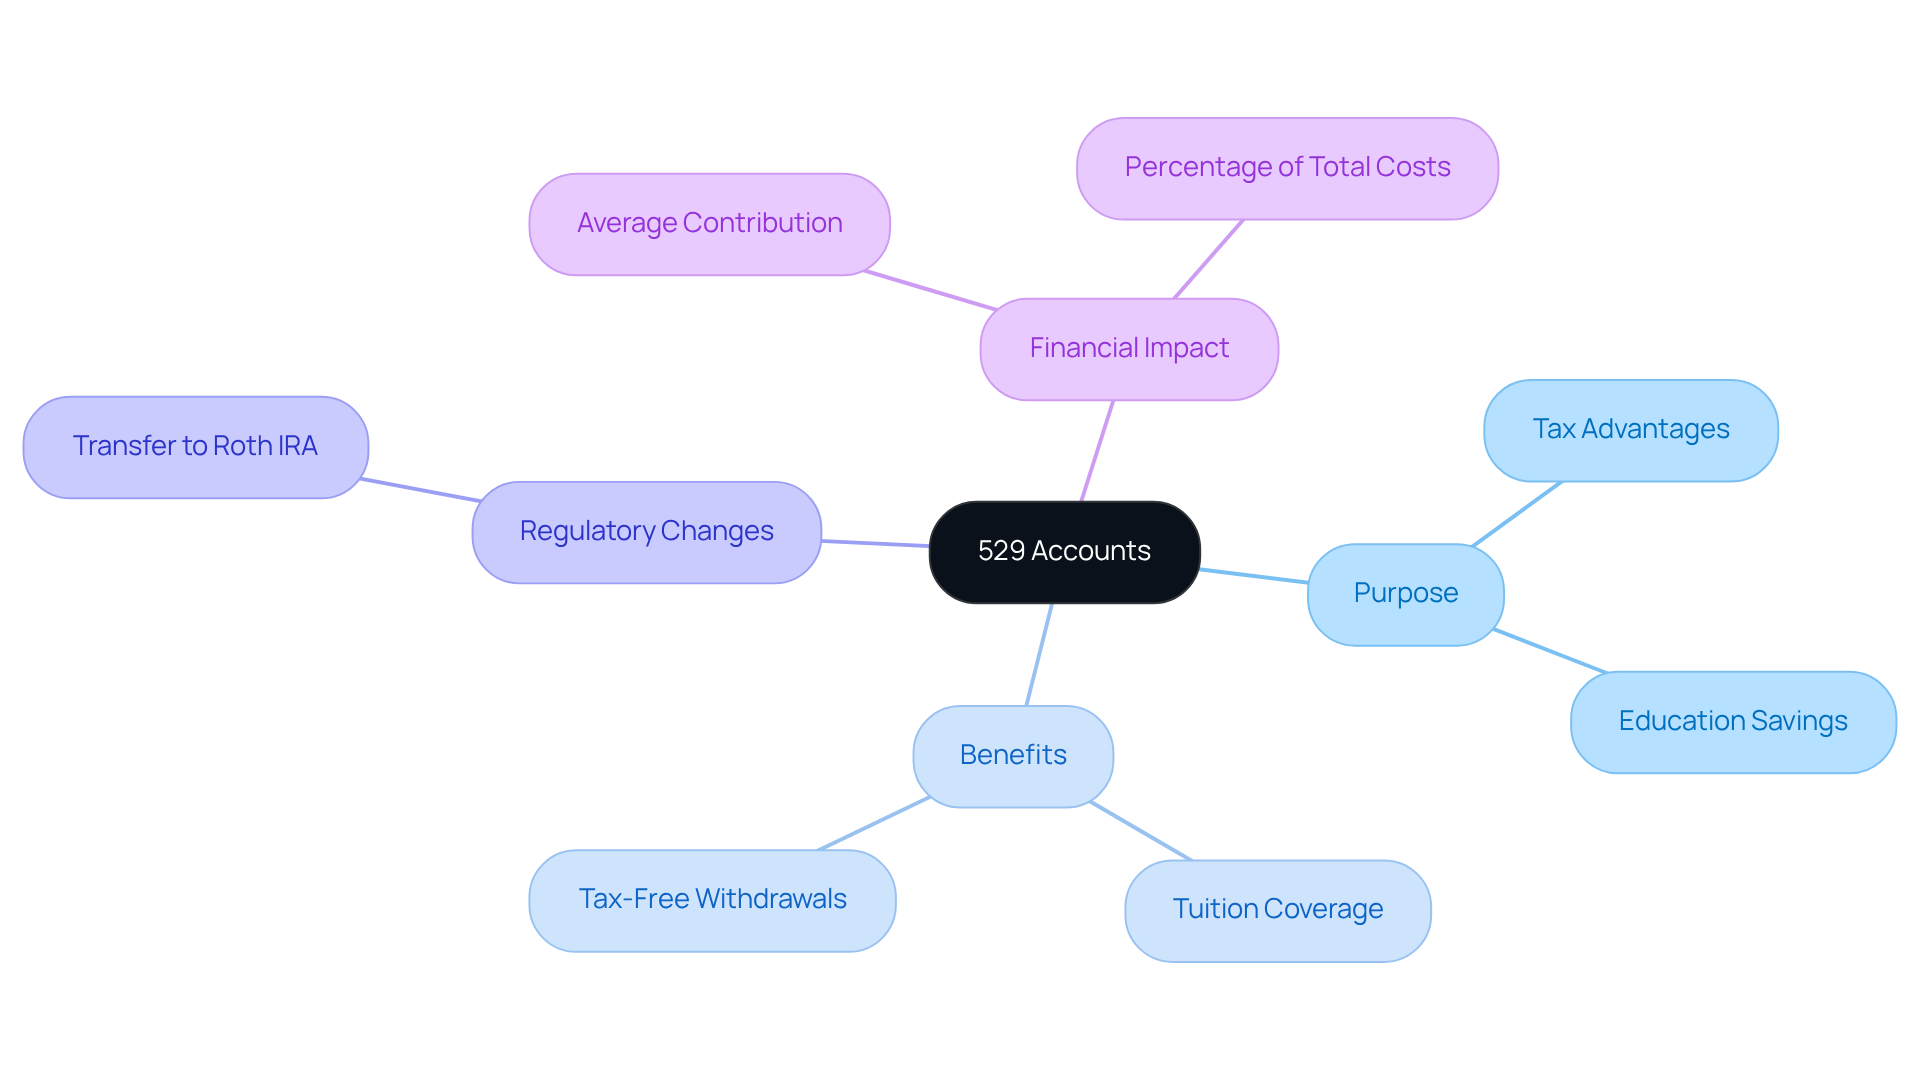
A 529 plan is a wonderful way to save for your child’s future education, offering tax advantages that make it easier for families to prepare for those important costs. These funds can help cover essential expenses like tuition, room and board, and other related costs. Understanding the purpose of a 529 plan is crucial; it empowers families to save efficiently while enjoying tax-free growth and withdrawals for eligible expenses.
Imagine starting January 1, 2024, when new regulations will allow families to [transfer unspent funds from a 529 account to Roth IRA](https://brightadvisers.com/?p=9793). This change offers increased flexibility for managing educational savings, especially for those who may have saved more than needed or whose children might not require the full amount set aside for education.
For instance, families earning $150,000 or more contributed an average of $7,726 to their college savings plans, covering about 21% of total college costs. This shows just how impactful 529 plans can be in reaching your educational financial goals. Financial advisors emphasize that these plans are essential resources for families, helping to secure their children’s educational futures while facilitating strategic planning and investment growth.
We’re here for you as you . Together, we can ensure that your family is well-prepared for the educational opportunities ahead.
Execute the Rollover Process Step-by-Step
Navigating the world of finances can feel overwhelming, especially for young parents. If you’re considering rolling over your 529 account to a Roth IRA, here’s a gentle guide to help you through the process:
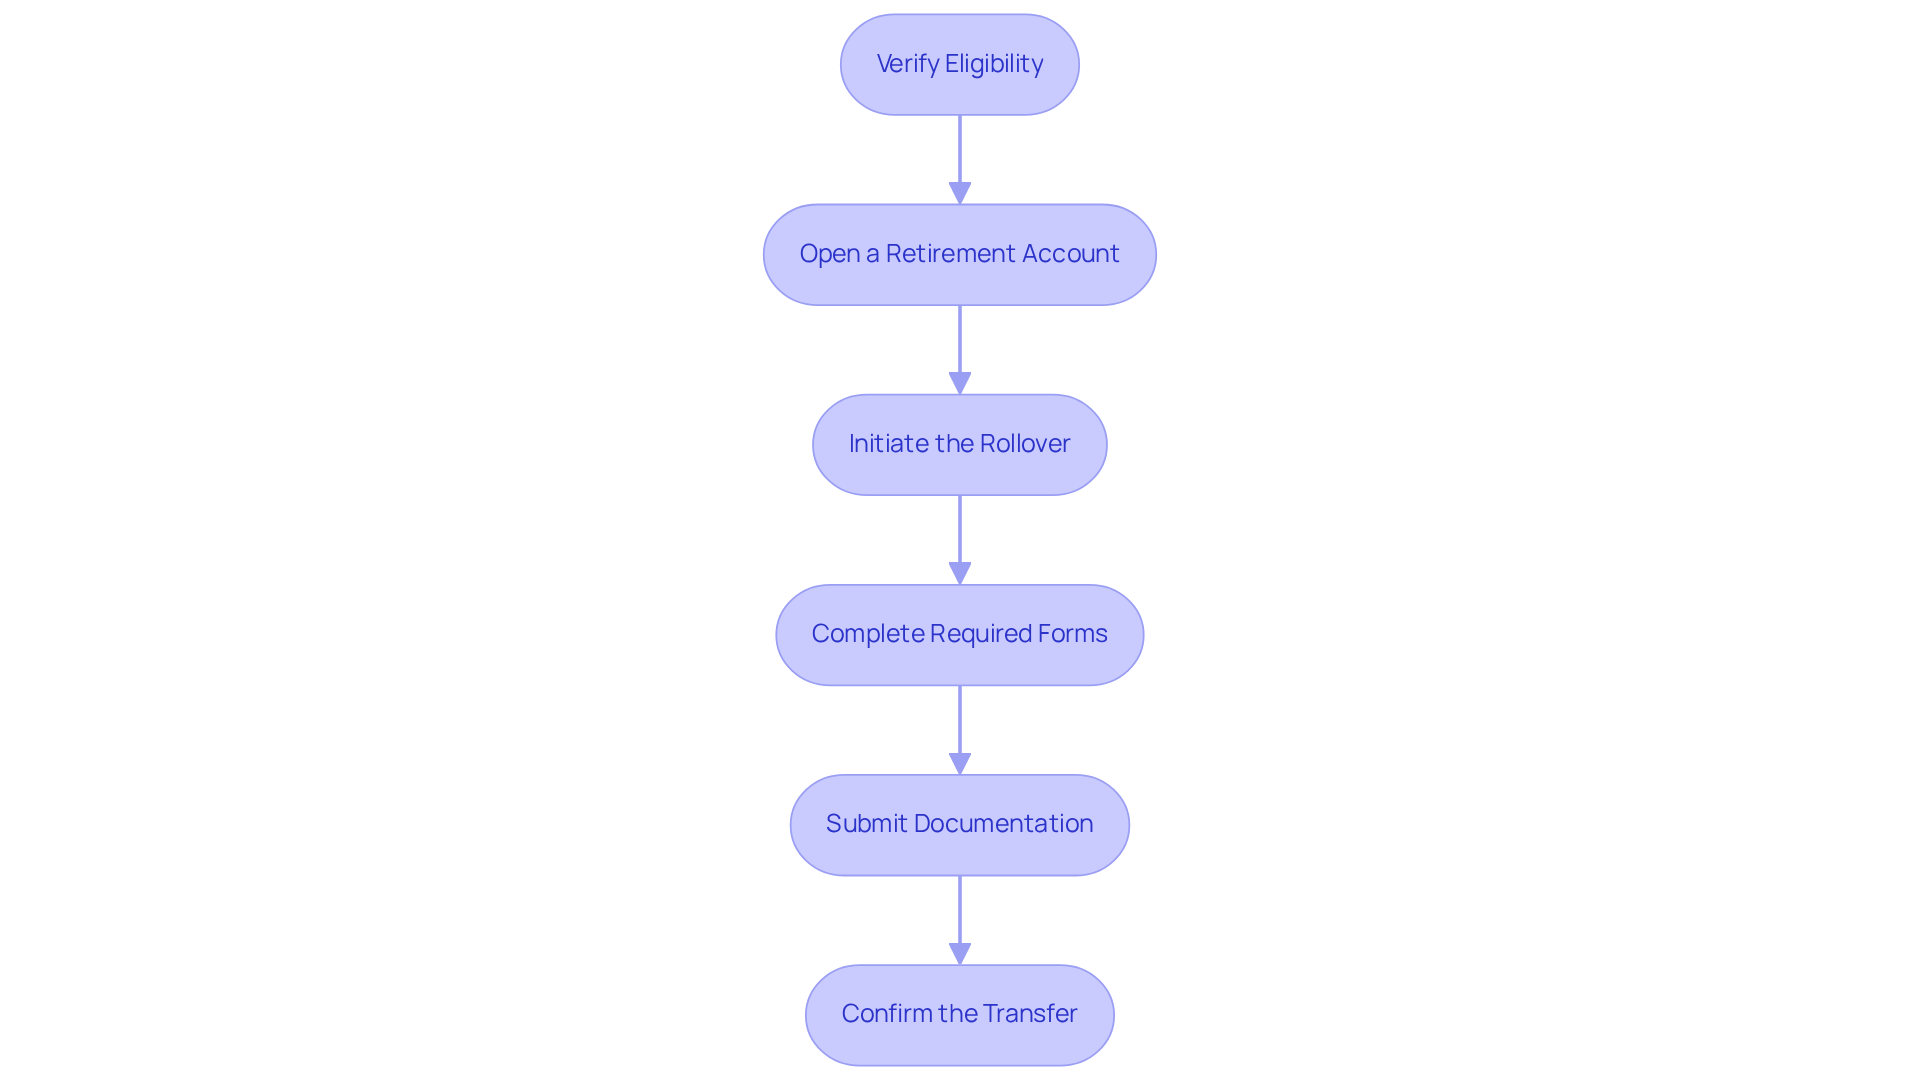
- : First, take a moment to confirm that your 529 account has been open for at least 15 years and that the funds you want to roll over have been in the account for a minimum of 5 years. This step is crucial for complying with IRS regulations and maximizing the benefits of your rollover.
- Open a Retirement Account: If you don’t have a retirement account yet, it’s time to establish one. Look for a financial organization that offers individual retirement accounts, and complete the necessary documentation to set up your profile. Remember, this is a step towards securing your family’s future.
- Initiate the Rollover: Reach out to your 529 plan provider and request a trustee-to-trustee transfer. This method allows the funds to transfer directly from your 529 account to a Roth IRA, helping you avoid any tax penalties that might come with withdrawals.
- Complete Required Forms: You’ll need to fill out some forms from both your 529 plan and your IRA provider. This might include a transfer request form and a letter of acceptance from the IRA custodian. Ensuring all documentation is in order is key to a smooth transition.
- Submit Documentation: Once you’ve completed the forms, send them to your 529 plan provider. Make sure they handle the transfer, and keep copies of all documents for your records. You might need these for tax reporting later on.
- Confirm the Transfer: After a few weeks, check in with your Roth IRA provider to confirm that the funds have been successfully transferred and are properly allocated within your Roth IRA. This step is essential to ensure everything is complete and compliant with IRS guidelines.
Engaging a financial advisor during this process can provide clarity and peace of mind. They can help ensure that every step adheres to IRS requirements, helping you avoid unexpected taxes or penalties. Many families have successfully navigated this journey by carefully verifying eligibility and keeping precise records, which is vital for a smooth transition.
Remember, you’re not alone in this. Together, we can navigate this journey toward a secure financial future for your family.
Navigate Tax Implications and Avoid Penalties
When it comes to rolling over funds from a 529 account to a Roth IRA, it is crucial to understand the for your family’s financial future.
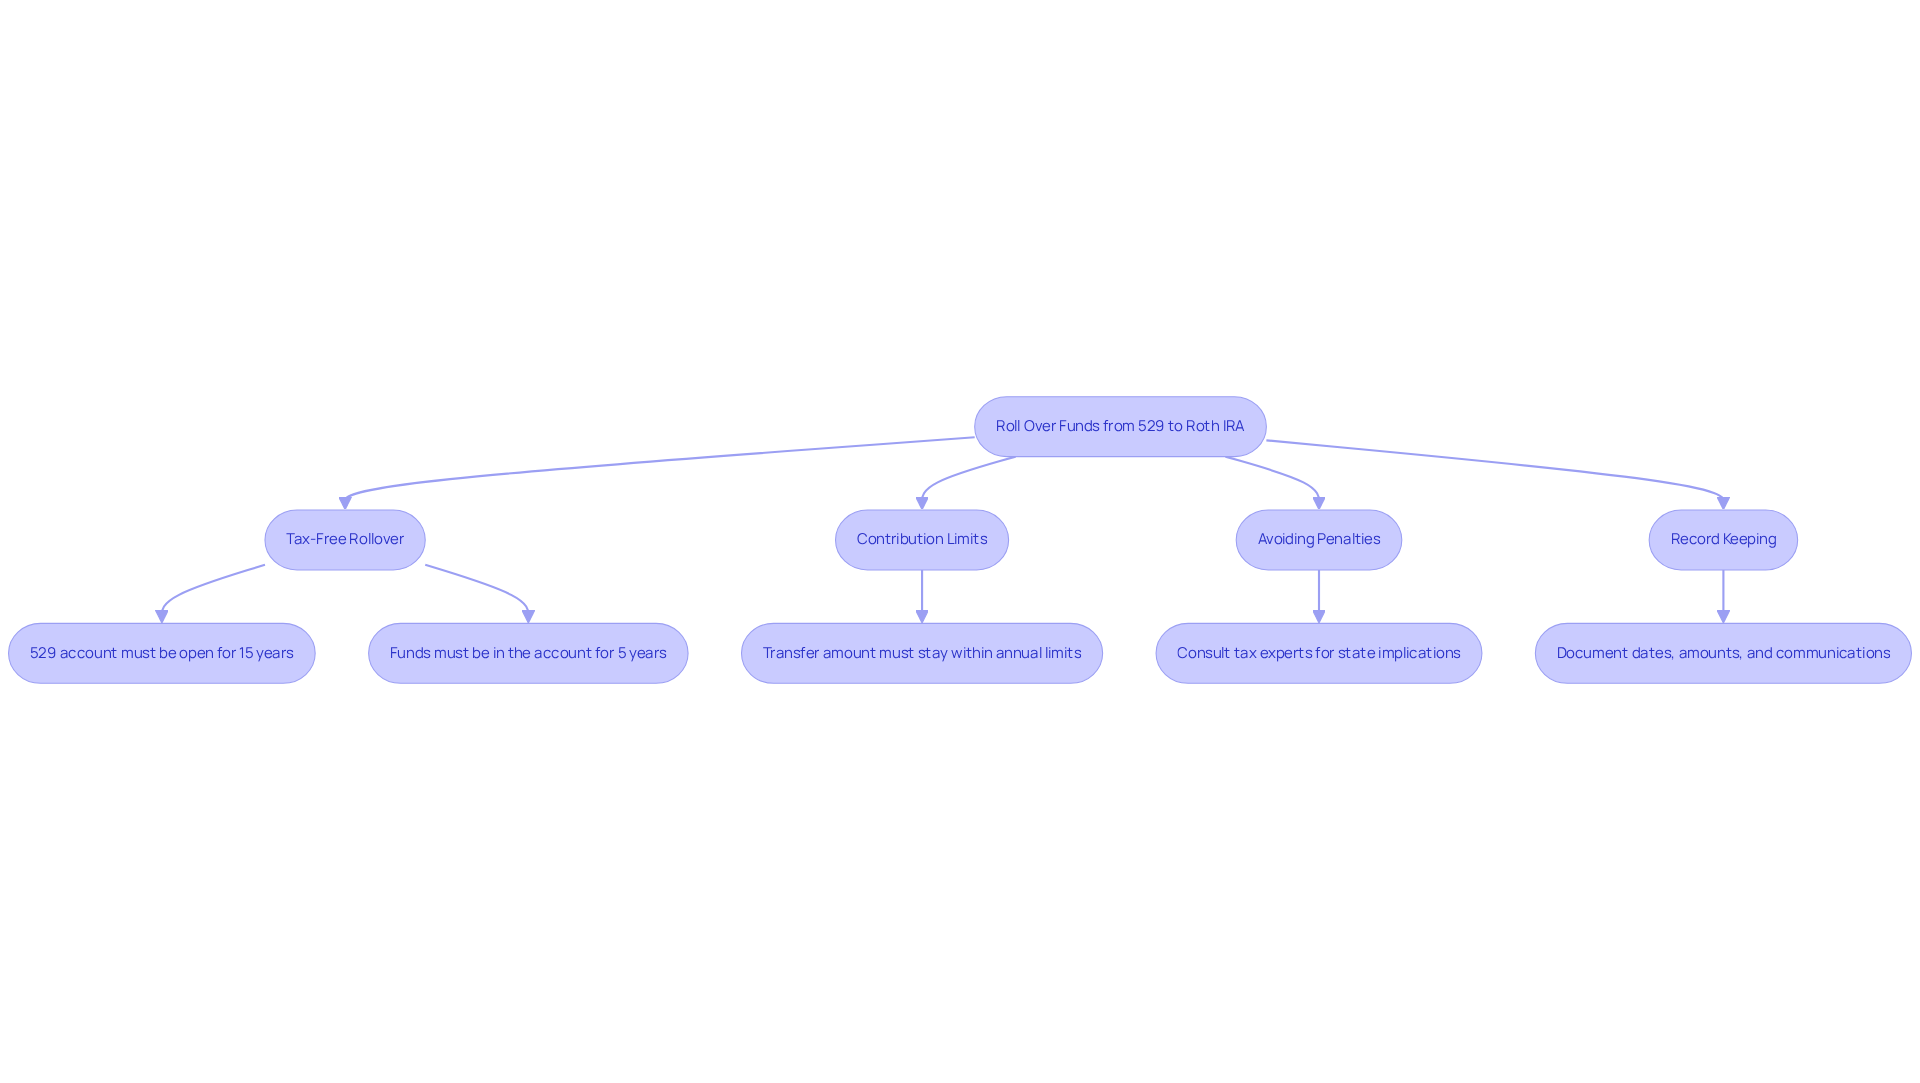
- Tax-Free Rollover: Starting in 2024, you can roll over unused funds from a 529 account to Roth IRA without incurring taxes. Just remember, the 529 account needs to be open for at least 15 years, and the funds must have been in the account for a minimum of 5 years. Imagine the peace of mind knowing your savings can grow without the burden of taxes!
- Contribution Limits: It’s important to keep in mind that the transfer amount must stay within the annual Roth IRA contribution limits. For 2025, this is set at $7,000 (or $8,000 if the beneficiary is 50 or older). Plus, there’s a lifetime maximum of $35,000 for transfers from a 529 account to Roth IRA per beneficiary. Ensuring your transfer doesn’t exceed these limits can help you avoid any complications down the road.
- Avoiding Penalties: To steer clear of penalties, [executing the transfer properly is key](https://brightadvisers.com/?p=11464). If you withdraw funds from the 529 account and don’t roll them over within 60 days, you might face income tax and a 10% penalty on earnings. It’s wise to consult with tax experts about any potential state tax implications related to the transfer. Remember, you’re not alone in this; there are professionals ready to help you navigate these waters.
- Record Keeping: [Keeping detailed records of the transfer process](https://brightadvisers.com/?p=10998) is essential. Document dates, amounts, and any communications with financial institutions. This not only ensures compliance but also serves as a helpful reference for the future, giving you confidence that every aspect of the transition is properly documented.
Together, we can navigate this journey, ensuring your family’s financial goals are met with care and understanding.
Troubleshoot Common Rollover Challenges
Navigating the world of finance can feel overwhelming, especially for young parents. [[Rolling over a 529 account](https://schwab.com/learn/story/529-to-roth-ira-rollovers-what-to-know)](https://schwab.com/learn/story/529-to-roth-ira-rollovers-what-to-know) to a Roth IRA might seem like a smart move, but it’s important to be aware of some [[common challenges](https://whitecoatinvestor.com/the-529-to-roth-ira-rollover)](https://whitecoatinvestor.com/the-529-to-roth-ira-rollover) that could arise along the way:
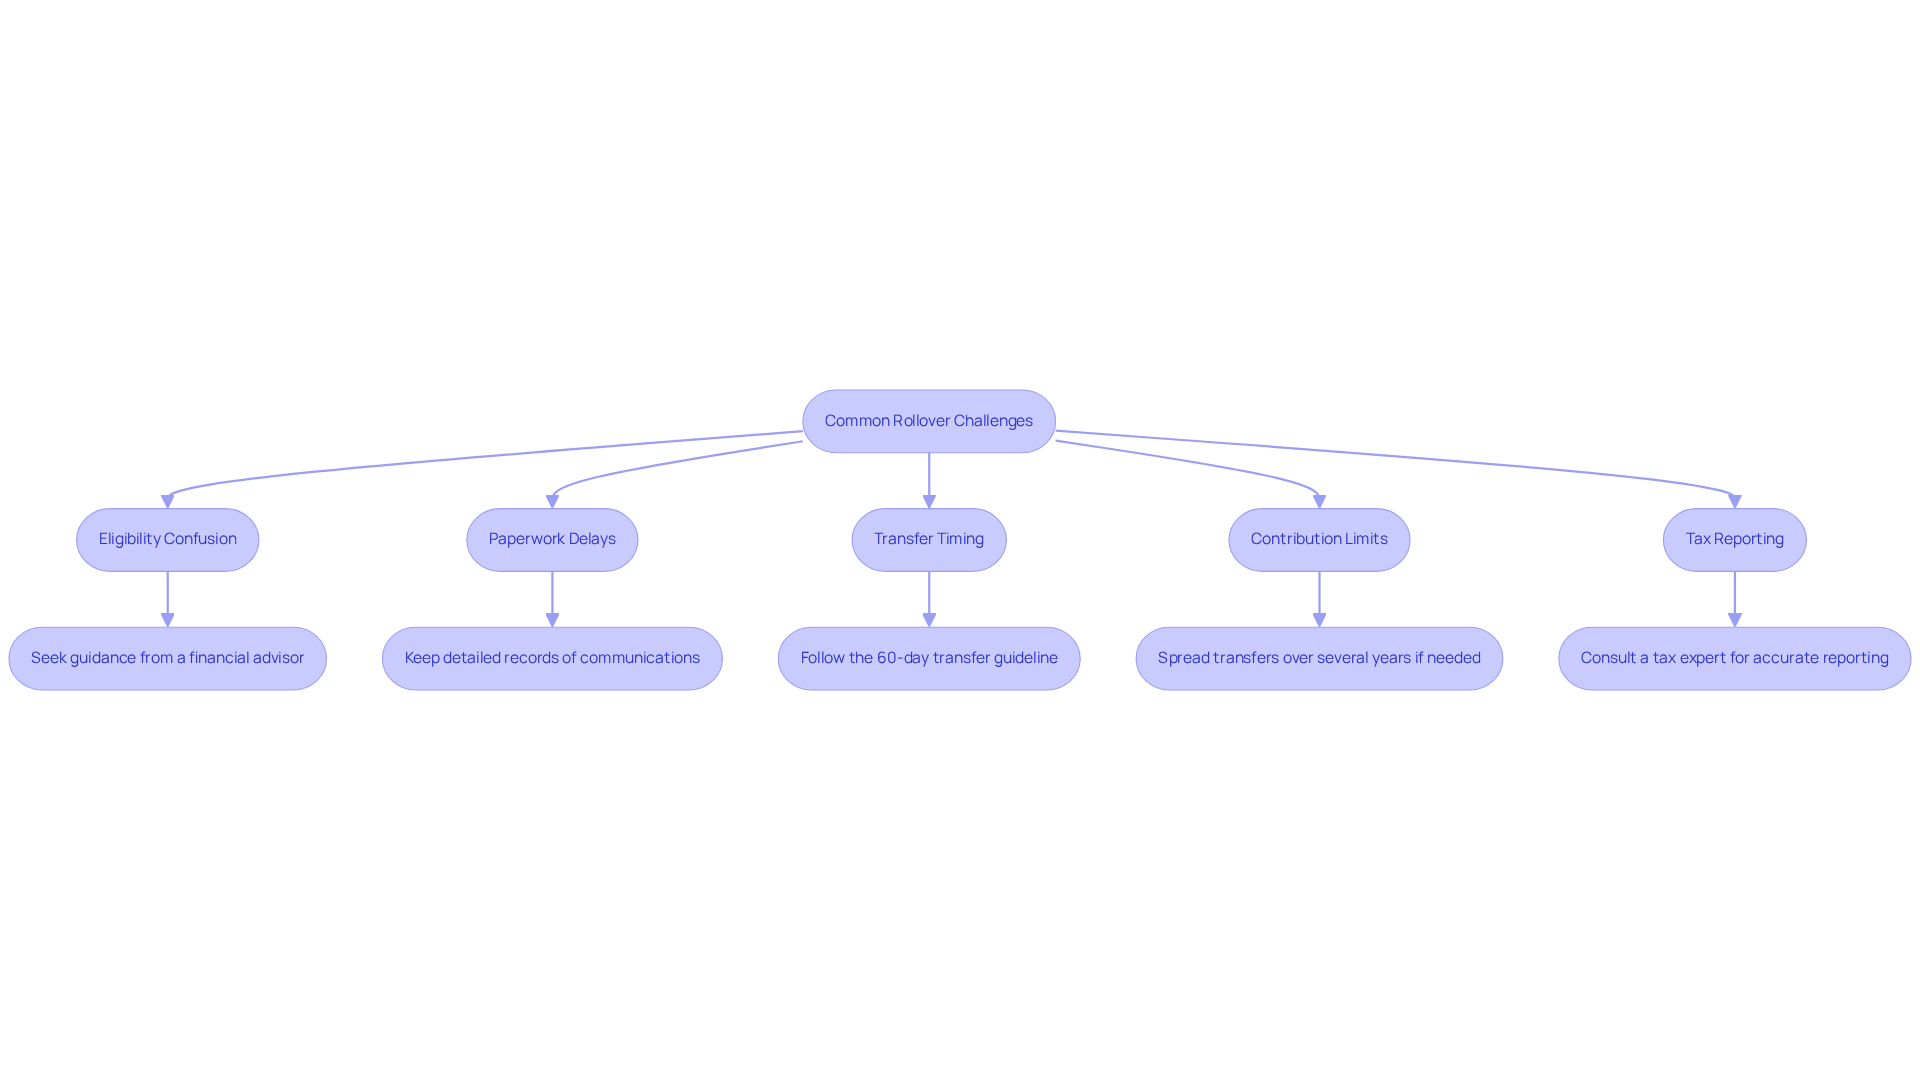
- Eligibility Confusion: It’s essential to understand the [eligibility requirements for both the 529 account and the Roth IRA](https://brightadvisers.com/?p=11125). Many families mistakenly think that all funds can be rolled over without any restrictions. Seeking guidance from a financial advisor or your account provider can help clarify these requirements. Remember, contributions made to the 529 plan within the last five years may not be eligible for a [[tax-free transfer](https://brightadvisers.com/?p=11958)](https://brightadvisers.com/?p=11125).
- Paperwork Delays: If you experience delays in processing your transfer, it can be frustrating. Don’t hesitate to follow up proactively with both your 529 plan and your individual retirement account provider. Keeping a detailed record of all communications can really help speed things up.
- Transfer Timing: Be mindful of the 60-day guideline for transfers. If you withdraw funds from your 529 account, they need to be transferred into the individual retirement account within this timeframe to avoid penalties. Missing this window can lead to unnecessary tax implications, which is something we all want to avoid.
- [[Contribution Limits](https://troweprice.com/personal-investing/resources/insights/five-things-to-know-about-529-to-roth-ira-rollovers.html)](https://troweprice.com/personal-investing/resources/insights/five-things-to-know-about-529-to-roth-ira-rollovers.html): Make sure your transfer amount doesn’t exceed the annual contribution limits for Roth IRAs, which is $7,000 for the tax year 2025. If your transfer amount is higher, consider spreading it out over several years to stay within these limits.
- Tax Reporting: After completing the transfer, it’s crucial to report it accurately on your tax return. Misreporting can lead to complications, so it’s wise to consult a tax expert on how to report the transfer correctly.
By addressing these challenges with careful planning and professional advice, families can navigate the rollover process more effectively. Remember, you’re not alone in this journey. Together, we can ensure your financial strategies align with your family’s goals.
Conclusion
Rolling over a 529 account to a Roth IRA can be a wonderful opportunity for families looking to enhance their financial flexibility and secure a brighter future. Imagine being able to transition your educational savings into a retirement vehicle, allowing those unspent funds to continue growing tax-free. This strategic move not only maximizes your savings potential but also aligns with today’s financial landscape, which encourages thoughtful planning for your family’s future.
It’s crucial to verify eligibility, understand tax implications, and navigate the common challenges that may arise during the rollover process. Engaging with a financial advisor can provide the support you need to ensure compliance and make informed decisions about your savings. Remember, keeping meticulous records throughout this journey is essential to avoid penalties and ensure a smooth transition.
Ultimately, we encourage families to take charge of their financial future. By leveraging the benefits of both 529 plans and Roth IRAs, you can prepare for educational expenses while also building a robust retirement strategy. Embracing these financial tools with confidence can lead to a more secure and prosperous future, empowering your family to achieve long-term goals together. We’re here for you, ready to support you every step of the way.
Frequently Asked Questions
What is a 529 plan?
A 529 plan is a savings account designed to help families save for their child’s future education, offering tax advantages and allowing for tax-free growth and withdrawals for eligible expenses.
What expenses can a 529 plan cover?
A 529 plan can cover essential expenses such as tuition, room and board, and other related educational costs.
What new regulations regarding 529 plans will take effect on January 1, 2024?
Starting January 1, 2024, families will be allowed to transfer unspent funds from a 529 account to a Roth IRA, providing increased flexibility in managing educational savings.
How much do families typically contribute to 529 plans?
Families earning $150,000 or more contributed an average of $7,726 to their college savings plans, which covers about 21% of total college costs.
Why are 529 plans considered essential resources for families?
529 plans are essential resources because they help families secure their children’s educational futures and facilitate strategic planning and investment growth.
List of Sources
- Understand 529 Accounts and Their Purpose
- Why 529 plans are worth it for saving for college (https://cnbc.com/select/how-529-college-plans-become-more-valuable)
- 10 things that may surprise you about 529s | Vanguard (https://investor.vanguard.com/investor-resources-education/article/things-that-may-surprise-you-about-529s)
- The Biggest Pros and Cons of 529 Plans for College (https://studentloanplanner.com/pros-cons-529-plans)
- 529 College Savings Plan Statistics | BestColleges (https://bestcolleges.com/research/529-college-savings-plan-statistics)
- College Saving Statistics [2025]: Average Savings & 529 Balance (https://educationdata.org/college-savings-statistics)
- Execute the Rollover Process Step-by-Step
- What You Need to Know about Roth IRA Rollovers (https://invest529.com/blog/what-you-need-to-know-about-roth-ira-rollovers)
- 529 to Roth IRA Rollover: Rules, Limits, and How It Works Under SECURE 2.0 (https://landsbergbennett.com/blogs/insights/529-to-roth-ira-rollover-rules-limits-and-how-it-works-under-secure-2-0)
- Understanding 529 rollovers to a Roth IRA (https://fidelity.com/learning-center/personal-finance/529-rollover-to-roth)
- Navigate Tax Implications and Avoid Penalties
- T. Rowe Price Personal Investor – Five things to know about 529-to-Roth IRA Rollovers (https://troweprice.com/personal-investing/resources/insights/five-things-to-know-about-529-to-roth-ira-rollovers.html)
- Unsupported browser | TIAA (https://tiaa.org/public/invest/services/wealth-management/perspectives/529-to-roth-ira-rules)
- A retirement savings head start: 529-to-Roth rollovers (https://thetaxadviser.com/issues/2024/jul/a-retirement-savings-head-start-529-to-roth-rollovers)
- Troubleshoot Common Rollover Challenges
- Five things to know about rolling a 529 account into a Roth IRA — Manulife John Hancock Investments (https://jhinvestments.com/viewpoints/college-saving/five-things-to-know-about-rolling-a-529-account-into-a-roth-ira)
- The 529 to Roth IRA Rollover (Including for Yourself) | White Coat Investor (https://whitecoatinvestor.com/the-529-to-roth-ira-rollover)
- Unsupported browser | TIAA (https://tiaa.org/public/invest/services/wealth-management/perspectives/529-to-roth-ira-rules)
- T. Rowe Price Personal Investor – Five things to know about 529-to-Roth IRA Rollovers (https://troweprice.com/personal-investing/resources/insights/five-things-to-know-about-529-to-roth-ira-rollovers.html)
- 529-to-Roth IRA Rollovers: What to Know (https://schwab.com/learn/story/529-to-roth-ira-rollovers-what-to-know)

Kevin has advised high-income W-2 tech and biotech families since 2015, and leads the education-first Age Five Family Office from Brea, California.
Connect on LinkedIn → · About KevinThis is part of how we approach Tax Management for high-income W-2 families at Bright Advisers.
Keep reading