

Overview
Young families, have you considered a Roth IRA? It offers the promise of tax-free growth and flexible access to your funds, which can be incredibly beneficial for your family’s financial journey. On the other hand, a 401(k) presents higher contribution limits and the potential for employer matching, which can significantly boost your savings.
It’s important to weigh these options carefully. Each has its own advantages and disadvantages, and the right choice truly depends on your family’s current financial situation and retirement goals. Imagine if you could secure a brighter future for your children while also enjoying the peace of mind that comes with smart financial planning.
Remember, we’re here for you. Together, we can navigate this journey, ensuring that your family’s needs and values are at the forefront of your financial decisions. Making informed choices today can lead to a more secure tomorrow.
Key Highlights:
- A Roth IRA allows contributions from after-tax income, enabling tax-free withdrawals in retirement, making it beneficial for young families.
- A 401(k) is an employer-sponsored plan that allows pre-tax income contributions, reducing taxable income and growing tax-deferred until withdrawal.
- For 2025, Roth IRA contribution limits are $7,000 for individuals under 50, and $8,000 for those 50 and older; 401(k) limits are $23,500, with a $7,500 catch-up for older individuals.
- Roth IRA contributions phase out for single filers with MAGI over $150,000 and joint filers over $236,000, impacting eligibility for some households.
- Roth IRAs offer broader investment options and penalty-free withdrawals of contributions, while 401(k)s may provide employer matching but have stricter withdrawal rules.
- Pros of Roth IRA: tax-free growth, flexible access; Cons: lower contribution limits, no employer matching.
- Pros of 401(k): higher contribution limits, potential employer matching; Cons: limited investment options, penalties for early withdrawals.
- Choosing between a Roth IRA and a 401(k) depends on a family’s current financial situation, future income expectations, and retirement goals.
Introduction
The financial landscape for young families is filled with choices that can significantly impact their future security. Imagine navigating this journey, where every decision matters. Among these options, the Roth IRA and 401(k) stand out as two popular retirement savings vehicles, each offering unique advantages and challenges. Families seeking to optimize their savings must gently navigate the intricate details of contribution limits, tax implications, and investment flexibility.
It’s important to understand that with so much at stake, choosing the right option can feel overwhelming. Which path truly aligns with the financial aspirations of young households? This article delves into the essential comparisons between Roth IRAs and 401(k)s, illuminating the paths to informed decision-making. Together, we can navigate this journey toward a secure financial future.
Define Roth IRA and 401(k): Key Features and Functions
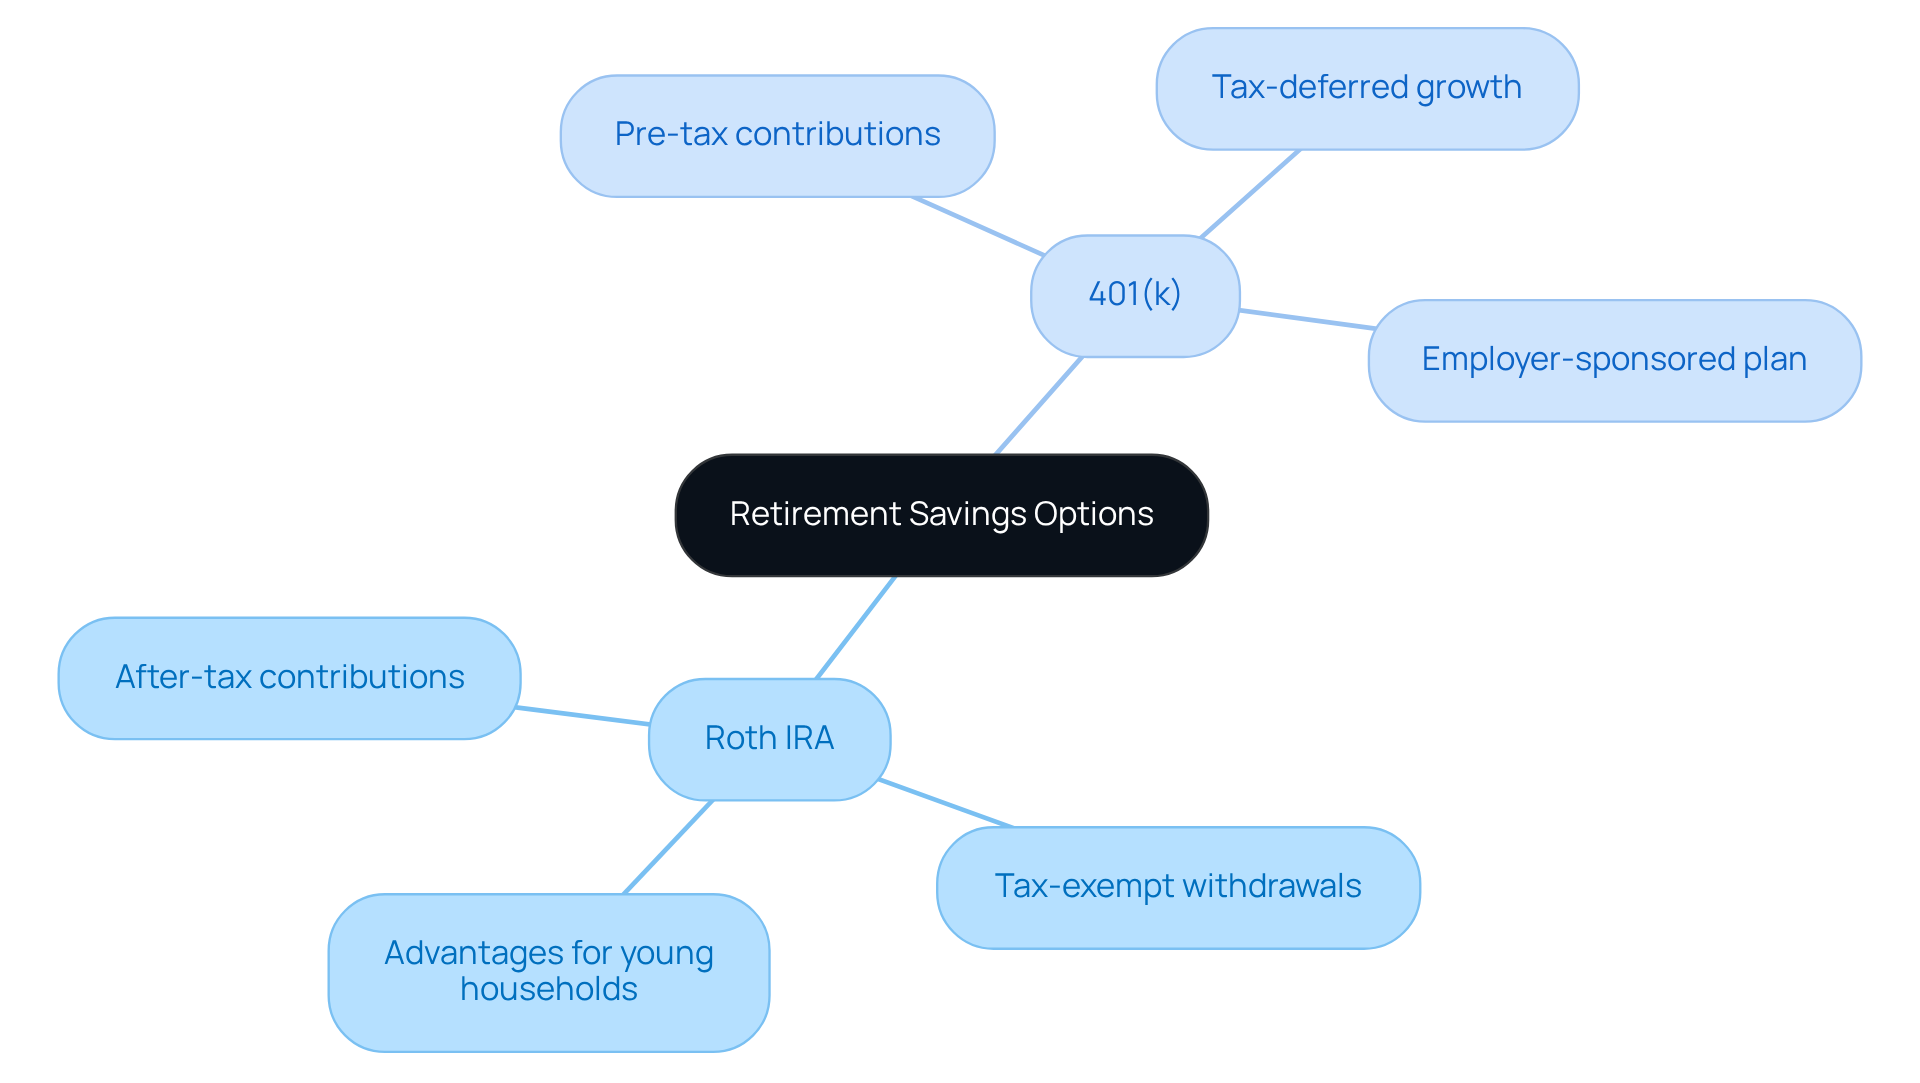
Imagine a future where your family’s financial security is assured. An individual savings account, such as a Roth IRA, allows you to contribute after-tax income, meaning the money you put in has already been taxed. The beauty of a Roth IRA lies in its tax-exempt withdrawals during your later years, providing significant tax advantages for young households like yours. This aligns perfectly with Bright Advisers’ commitment to innovative wealth management, empowering families to secure their financial future through personalized planning and investment strategies.
In contrast, consider a 401(k), an employer-sponsored savings plan that lets employees contribute a portion of their pre-tax income. This approach lowers your taxable income for the year, allowing your contributions to grow tax-deferred. Taxes are then paid upon withdrawal during retirement. Understanding these fundamental differences in tax treatment, particularly when considering Roth IRA vs 401(k) which is better, is essential for families as it directly impacts your long-term financial security and freedom.
It’s important to understand that making informed choices today can pave the way for a brighter tomorrow for you and your loved ones. Together, we can navigate this journey, ensuring that you have the support and guidance needed to make the best decisions for your family’s future.
Examine Contribution Limits and Rules for Roth IRA and 401(k)
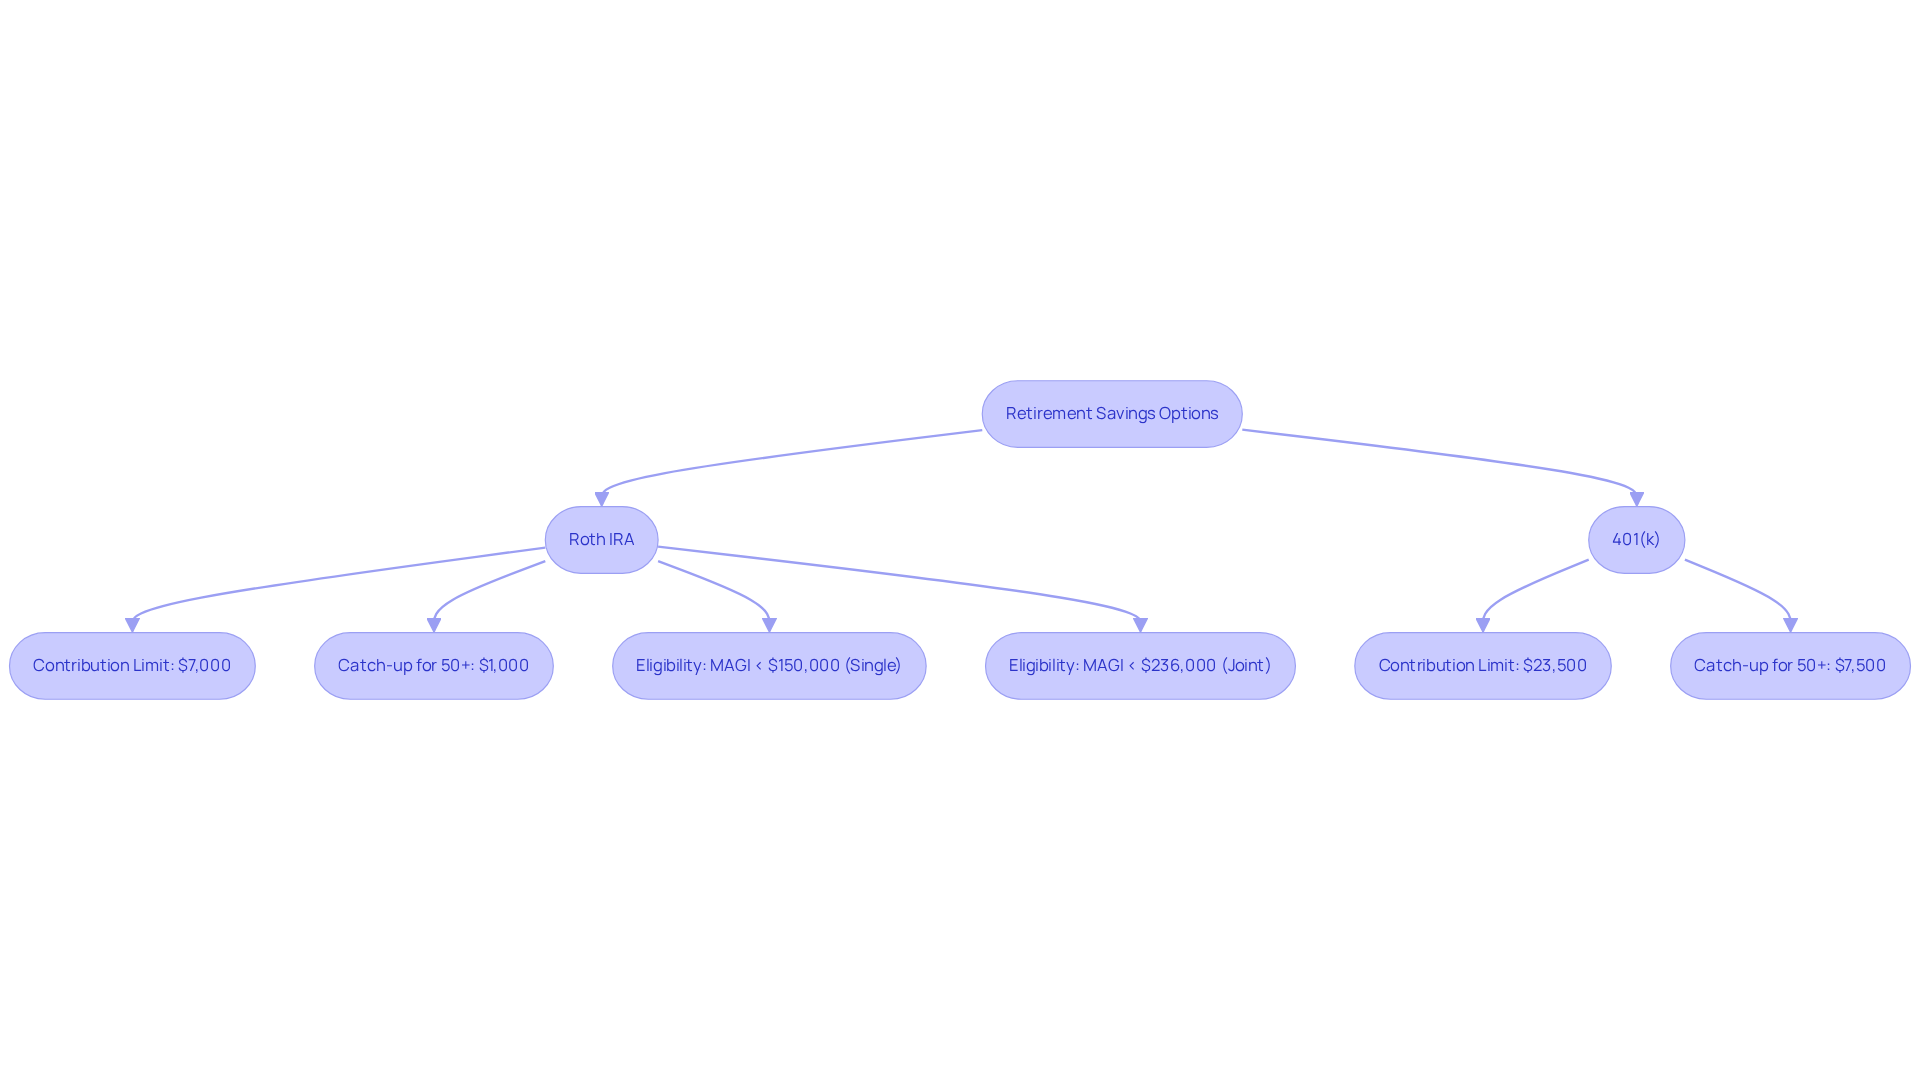
As you think about your family’s future, it’s crucial to understand the retirement savings options available to you, particularly in terms of the Roth IRA vs 401(k) which is better. In 2025, the limit for a Roth IRA is set at $7,000 for individuals under 50. For those aged 50 and older, there’s an extra catch-up amount of $1,000, bringing the total to $8,000. On the other hand, the limit for a 401(k) is significantly higher at $23,500, which includes a catch-up payment of $7,500 for individuals aged 50 and older. This notable difference in allowance limits makes the 401(k) an appealing choice for families who are evaluating the Roth IRA vs 401(k) which is better for optimizing their retirement savings.
However, it’s important to understand that eligibility for Roth IRA contributions phases out at higher income levels, which may impact some households. For 2025:
- Single filers must have a modified adjusted gross income (MAGI) of less than $150,000 to qualify for full contributions.
- Joint filers face a MAGI limit of $236,000.
Comprehending these thresholds is essential for families as they devise their financial strategies for the future.
Additionally, considering minimal fund fees is crucial, as they can greatly influence your total returns on these savings accounts. Families should explore low-fee options, such as certain ETFs, to enhance their investment outcomes and ensure that their retirement savings grow effectively. Together, we can navigate this journey and make informed decisions that align with your family’s values and goals.
Compare Investment Options and Flexibility in Roth IRA vs 401(k)
When considering retirement savings, young parents like Allison and Brian often evaluate the choices between Roth IRA vs 401k which is better to align with their family goals. When considering Roth IRA vs 401k which is better, it’s clear that Roth IRAs typically offer a broader range of investment choices compared to 401(k) plans, which are often limited to a selection of mutual funds chosen by employers. This flexibility allows families to tailor their investment strategies to their specific financial objectives and risk tolerance. Imagine being able to incorporate tax optimization strategies, such as enjoying tax-free growth and withdrawals. This approach can help maximize your family’s financial potential and secure your future.
It’s also important to note that individual retirement accounts allow for penalty-free withdrawals of contributions at any time. This feature provides families with enhanced access to their funds when needed, offering peace of mind during uncertain times. On the other hand, when evaluating Roth IRA vs 401k which is better, it’s worth noting that 401(k) plans may offer employer matching funds, which can significantly boost retirement savings. However, when considering Roth IRA vs 401k which is better, these plans come with stricter withdrawal regulations and potential penalties for early access, which can be a concern for families needing flexibility.
Pros and Cons Summary:
Roth IRA:
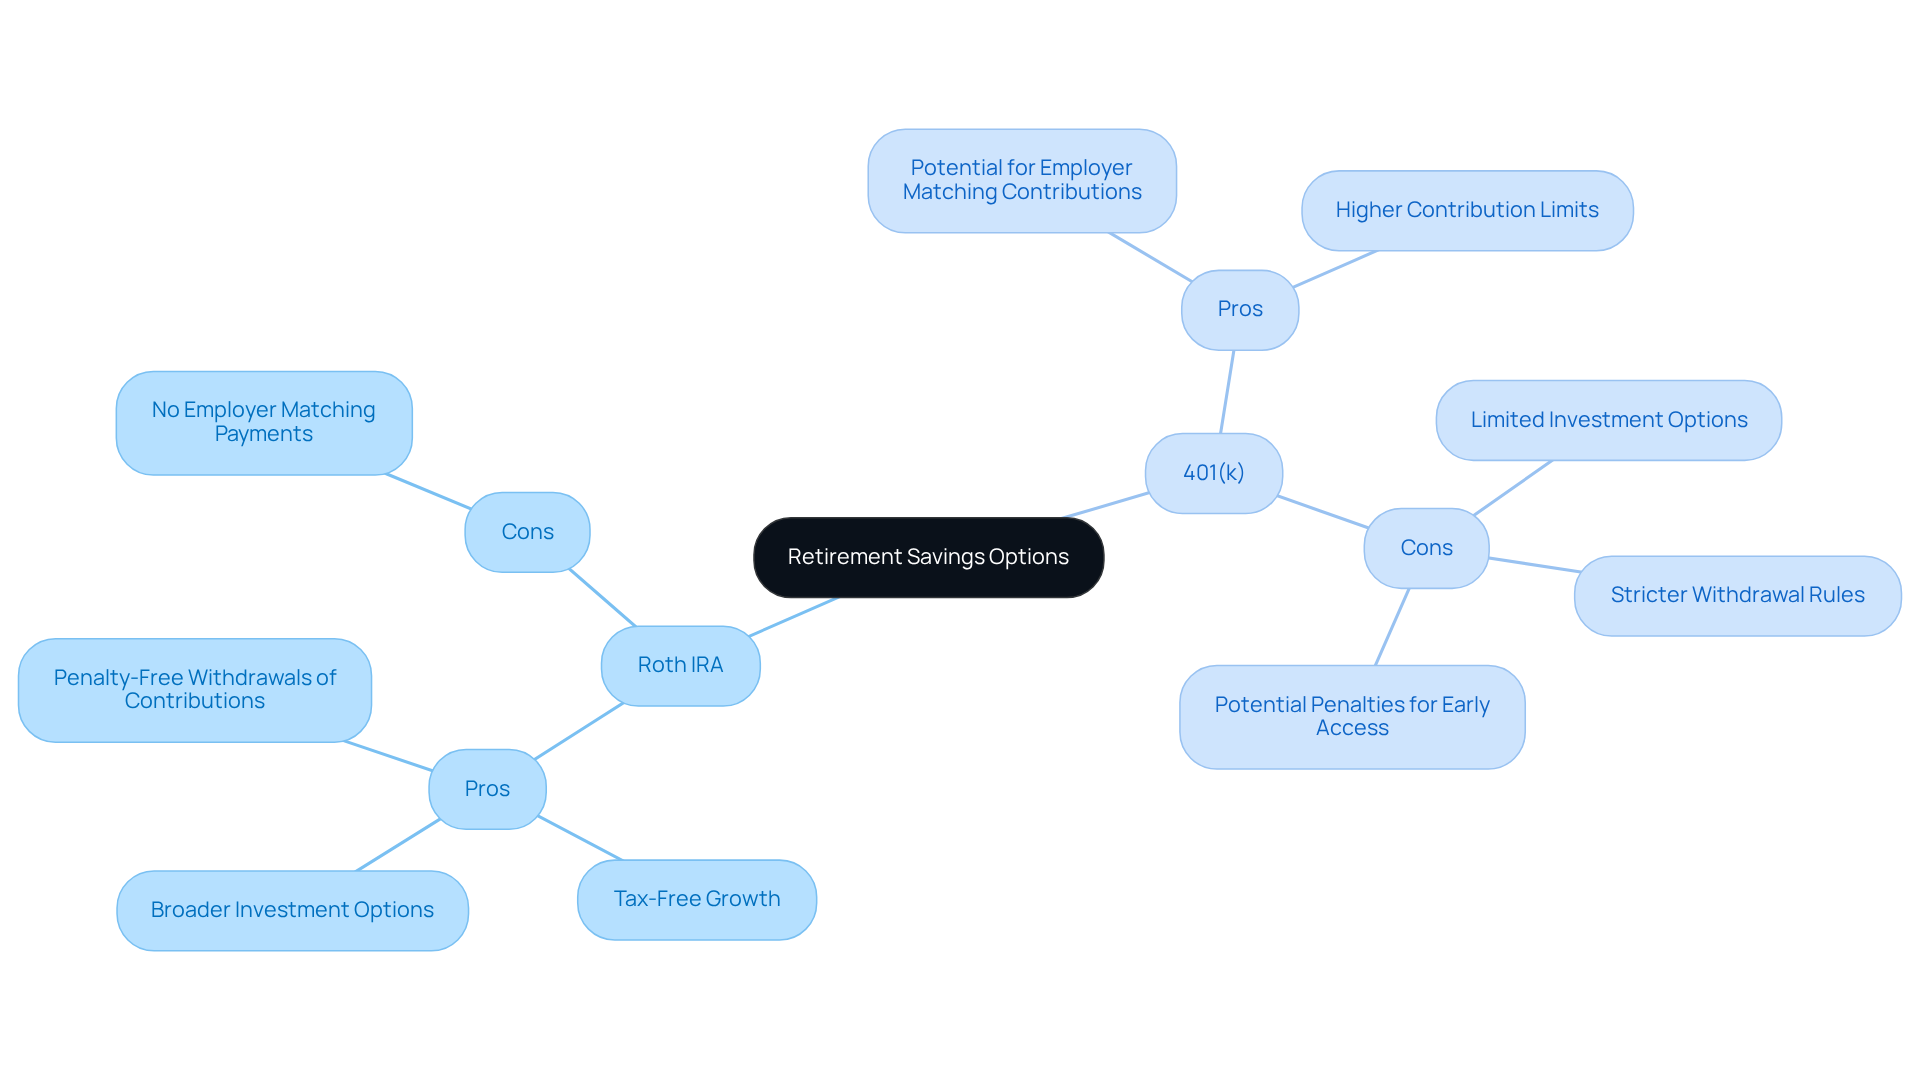
- Pros: Broader investment options, tax-free growth, penalty-free withdrawals of contributions.
- Cons: No employer matching payments.
401(k):
- Pros: Potential for employer matching contributions, higher contribution limits.
- Cons: Limited investment options, stricter withdrawal rules, potential penalties for early access.
Navigating these options can feel overwhelming, but remember, we’re here for you. Together, we can explore the best strategies for your family’s financial future, ensuring you make informed decisions that align with your values and aspirations.
Evaluate Pros and Cons: Roth IRA vs 401(k) for Young Families
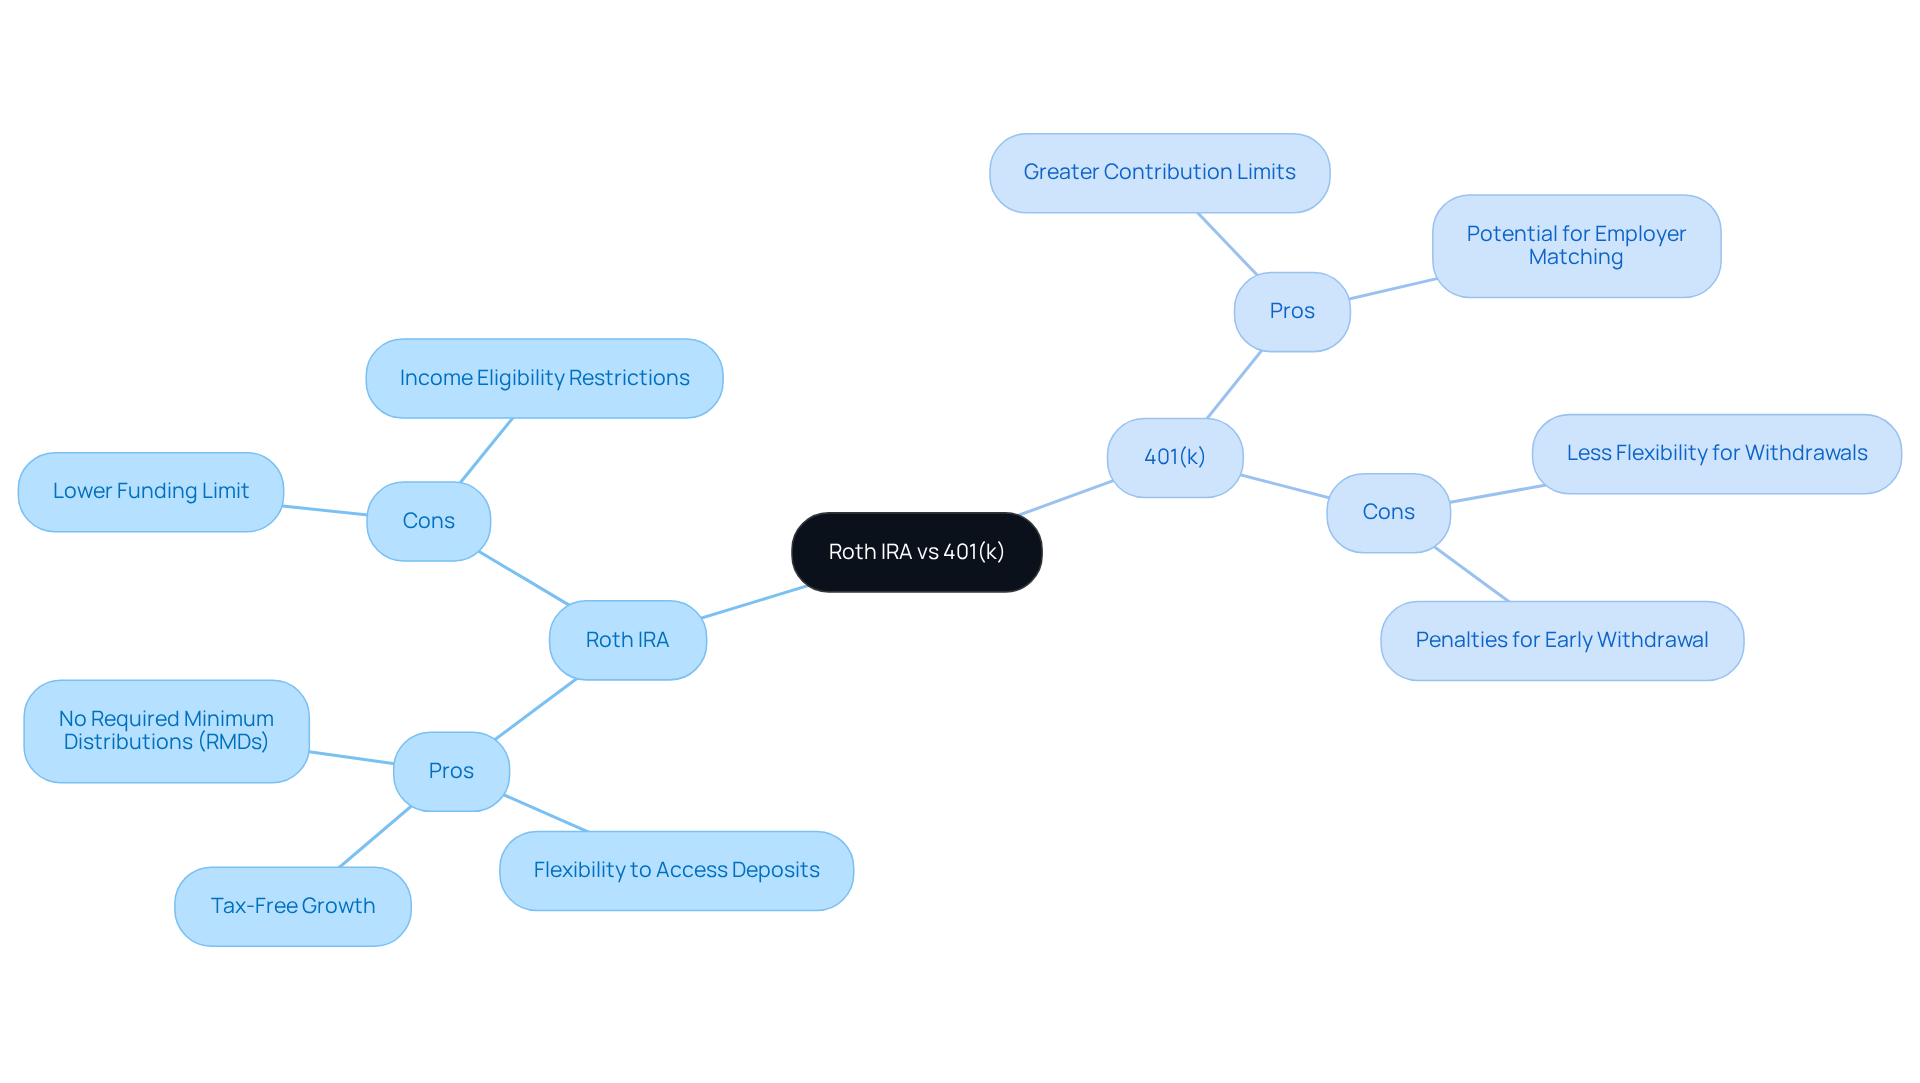
When considering a Roth IRA, it’s heartening to recognize its main benefits: tax-free growth and withdrawals, the flexibility to access your deposits, and no required minimum distributions (RMDs) during your lifetime. These features can truly support your family’s financial journey. However, it’s important to note that the lower funding limit and income eligibility restrictions can pose challenges.
On the other hand, 401(k) plans offer greater contribution limits and the potential for employer matching, which can significantly boost your savings for the future. Yet, they may present less flexibility when it comes to withdrawals and could incur penalties for early access.
For young families like Emily and Mark, who are striving for financial freedom through tailored wealth management strategies, evaluating the decision of Roth IRA vs 401(k) which is better often depends on their current financial situation, future income expectations, and retirement aspirations.
Imagine if you could choose a path that not only secures your future but also aligns with your family’s values. We’re here for you, ready to help you navigate this journey together. Your family’s financial well-being is worth the thoughtful consideration of these options.
Conclusion
Choosing between a Roth IRA and a 401(k) is a pivotal decision for young families seeking to secure their financial future. Each option presents unique advantages and challenges that can significantly impact long-term savings and investment strategies. By understanding the distinct features of these retirement accounts, families can make informed choices that resonate with their financial goals and aspirations.
This article highlights essential aspects of both retirement plans, including:
- Tax implications
- Contribution limits
- Investment flexibility
- The pros and cons associated with each option
Roth IRAs offer tax-free growth and a wider array of investment choices, while 401(k) plans provide higher contribution limits and potential employer matching. It’s crucial for families to reflect on their current income, future financial needs, and the importance of accessibility to funds when evaluating which plan best suits their situation.
Ultimately, the decision between a Roth IRA and a 401(k) transcends mere numbers; it embodies a family’s values and vision for their future. Engaging in thoughtful financial planning can empower families to build a secure and prosperous tomorrow. By carefully weighing the benefits and limitations of each option, young families can confidently navigate their retirement savings journey. Remember, together, we can take proactive steps toward achieving your financial dreams.
Frequently Asked Questions
What is a Roth IRA?
A Roth IRA is an individual savings account that allows you to contribute after-tax income, meaning the money you put in has already been taxed. It offers tax-exempt withdrawals during retirement, providing significant tax advantages.
What are the key benefits of a Roth IRA for families?
The key benefits of a Roth IRA for families include tax-exempt withdrawals in retirement and the ability to contribute after-tax income, which can be particularly advantageous for young households.
What is a 401(k)?
A 401(k) is an employer-sponsored savings plan that enables employees to contribute a portion of their pre-tax income. This approach reduces taxable income for the year, allowing contributions to grow tax-deferred until withdrawal during retirement.
How does the tax treatment differ between a Roth IRA and a 401(k)?
The main difference in tax treatment is that Roth IRA contributions are made with after-tax income and withdrawals are tax-exempt, while 401(k) contributions are made with pre-tax income and taxes are paid upon withdrawal during retirement.
Why is it important to understand the differences between a Roth IRA and a 401(k)?
Understanding the differences is essential because it impacts long-term financial security and freedom, helping families make informed choices that can enhance their financial future.
How can families navigate their retirement savings options effectively?
Families can navigate their retirement savings options effectively by seeking support and guidance to make informed decisions that align with their financial goals and needs.
List of Sources
- Examine Contribution Limits and Rules for Roth IRA and 401(k)
- 2025 401(k) and IRA Contribution Limits (https://modwm.com/2025-401k-and-ira-contribution-limits)
- Roth IRA income and contribution limits for 2025 | Vanguard (https://investor.vanguard.com/investor-resources-education/iras/roth-ira-income-limits)

Kevin has advised high-income W-2 tech and biotech families since 2015, and leads the education-first Age Five Family Office from Brea, California.
Connect on LinkedIn → · About KevinThis is part of how we approach Retirement & Employee Benefits for high-income W-2 families at Bright Advisers.
Keep reading