

Overview
Understanding the key differences between Restricted Stock Units (RSUs) and Common Stock is essential for young families like yours. These differences revolve around vesting conditions, ownership rights, tax implications, and liquidity. Imagine if you could navigate these financial waters with confidence, knowing exactly what each option means for your family’s future.
RSUs, granted by employers, vest over time, which means they don’t provide immediate voting rights. In contrast, Common Stock offers immediate ownership and liquidity. It’s important to understand these distinctions so you can make informed decisions that align with your family’s financial goals.
As you embark on this journey of financial planning, remember that you are not alone. Together, we can explore these options and find the best path for your family’s needs. We’re here for you, ready to support you every step of the way.
Key Highlights:
- Restricted Stock Units (RSUs) are gifted by employers and vest over time, converting into Common Stock.
- Common Stock provides immediate ownership and voting rights, whereas RSUs do not grant voting rights until vested.
- Vesting conditions for RSUs often require employees to remain with the company or meet performance goals.
- RSUs are taxed as regular income upon vesting, while Common Stock is taxed on capital gains when sold.
- Selling Common Stock after a year can result in lower capital gains tax rates compared to the immediate tax implications of RSUs.
- Common Stock offers higher liquidity as it can be traded anytime, unlike RSUs which have a vesting schedule that delays access to funds.
- Understanding the differences between RSUs and Common Stock is crucial for families to develop effective financial planning strategies.
Introduction
Navigating the financial landscape can feel overwhelming, particularly for young families eager to secure their future. The decision between Restricted Stock Units (RSUs) and common stock holds the potential to shape financial planning significantly, each option presenting its own set of benefits and challenges. As families reflect on these choices, it is crucial to consider how each type of equity resonates with their unique goals and immediate needs.
What are the key differences that might influence a family’s financial strategy? Understanding these nuances can empower families to make more informed decisions that align with their values and aspirations. Imagine if you could confidently navigate these options, knowing that each choice brings you closer to your family’s financial security. We’re here for you, ready to support you on this journey.
Define Restricted Stock Units and Common Stock
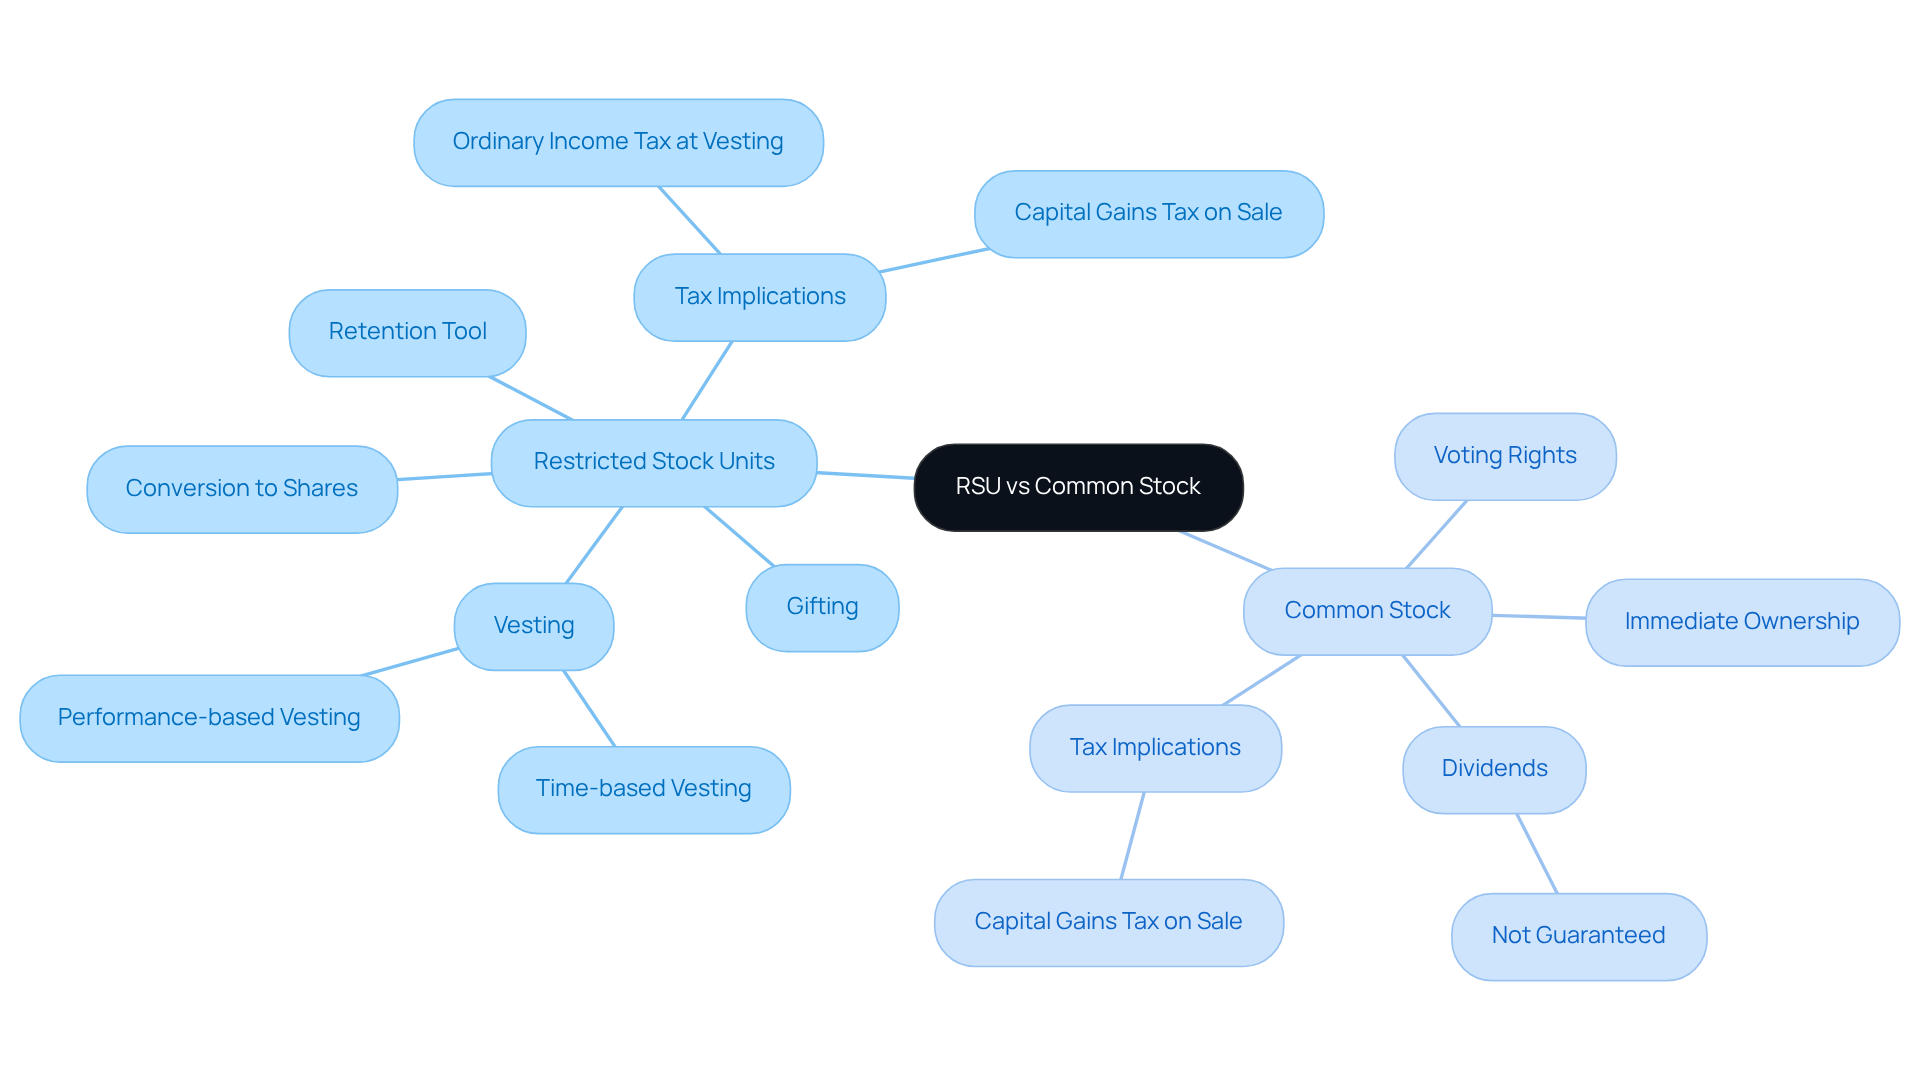
Imagine navigating your financial journey with confidence. Restricted Stock Units (RSUs) are a thoughtful way employers reward you with company stock, especially when evaluating the benefits of RSU vs common stock to support your family’s future. Unlike traditional equity options, you don’t need to buy these units; they are gifted to you and become available over time, often tied to your ongoing commitment or specific goals. Once they vest, these units turn into actual shares of common stock, allowing you to choose between selling or retaining them, thus providing a sense of security for your loved ones in the context of RSU vs common stock.
On the other hand, when discussing RSU vs common stock, it is clear that Common Stock represents a direct stake in a company, complete with voting rights that empower you to influence important decisions. While common stockholders may receive dividends, these are not guaranteed and depend on how well the company performs. Unlike the comparison of RSU vs common stock, you can buy shares directly on the open market, granting you immediate ownership without the waiting period, allowing you to take action for your family’s financial well-being.
Together, understanding these options can help you make informed decisions that align with your family values. We’re here for you as you explore these opportunities, ensuring that your financial planning supports the life you envision for your loved ones.
Compare Ownership Rights and Vesting Conditions
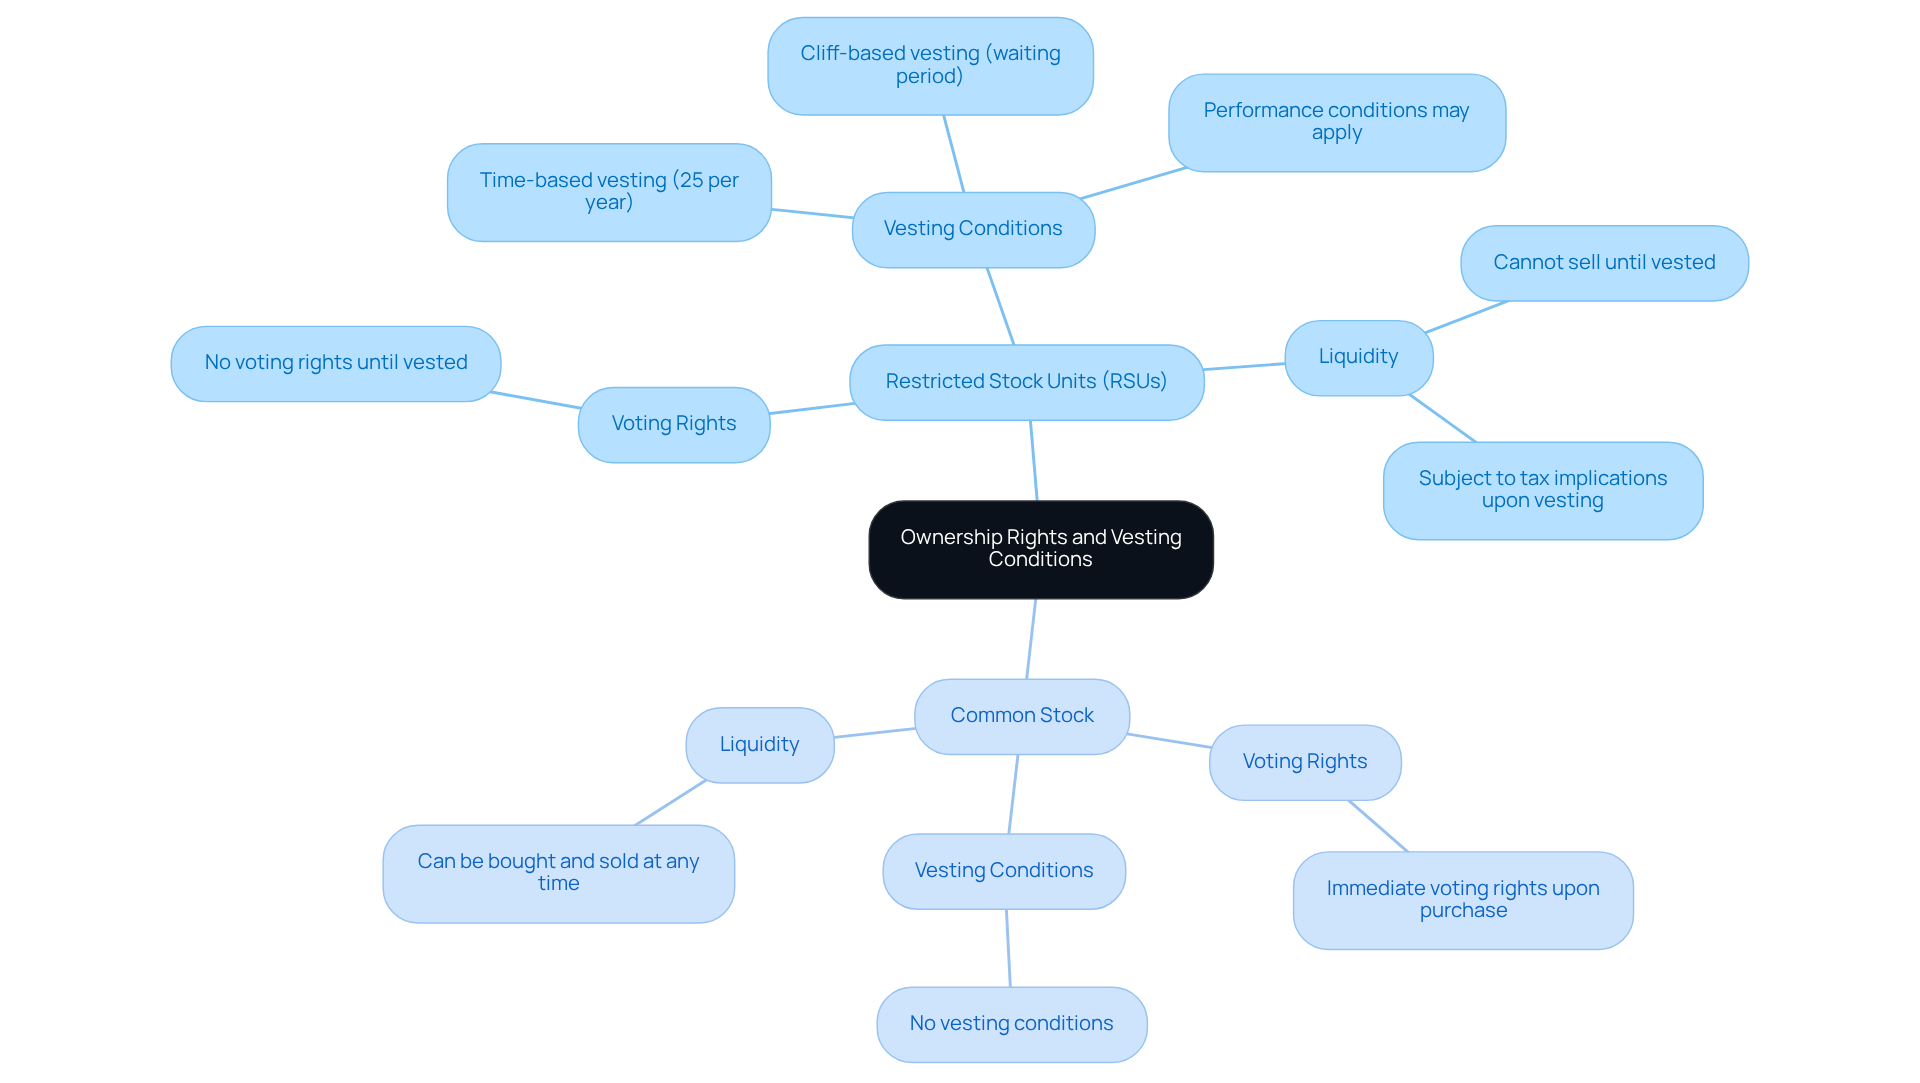
Understanding ownership rights is essential for young families as they navigate their financial planning. It’s important to realize that there are significant differences when considering RSU vs common stock. Restricted stock units, for instance, do not grant voting privileges until they are converted into regular stock. This means employees can’t participate in corporate governance until their holdings vest. On the other hand, common stockholders enjoy immediate voting rights upon purchase, allowing them to influence company decisions and engage in shareholder meetings.
Vesting conditions for restricted stock units can vary widely across different sectors. Often, employees must remain with the organization for a specific period or achieve certain performance goals before they can access their shares. This delay can make it challenging for families to grasp the value of their restricted stock units when they need it most. In contrast, ordinary shares can be bought and sold at any time, offering instant liquidity and flexibility for families who want to actively manage their investments.
Recognizing these differences is crucial for families as they create tailored financial planning and investment strategies. By understanding the nuances of RSU vs common stock, families can enhance their financial security and freedom. Remember, we’re here for you—together, we can navigate this journey toward a brighter financial future.
Evaluate Tax Implications of RSUs vs Common Stock
Understanding the tax implications of RSU vs common stock is crucial for families aiming to secure their financial future. The differences in taxation, especially when considering RSU vs common stock, can be quite significant, and it’s important to navigate them with care.
-
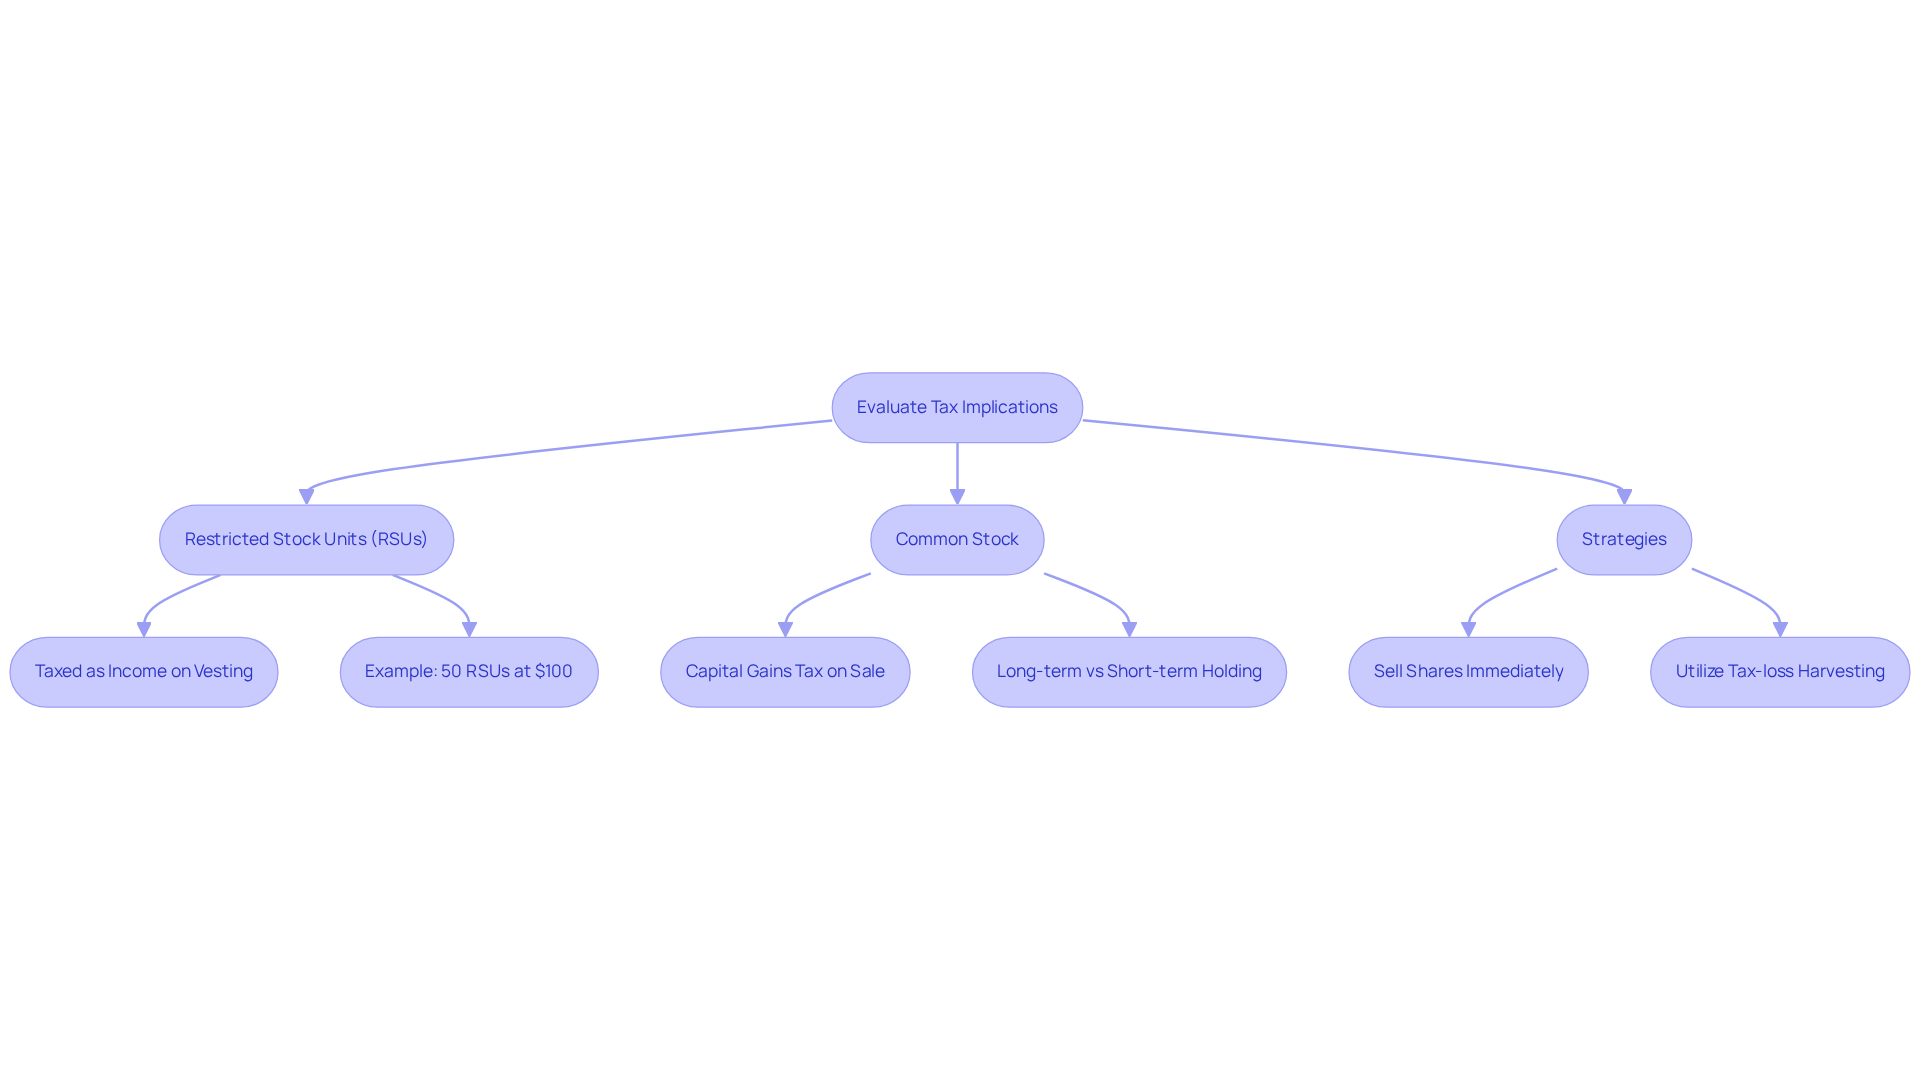
Restricted stock units, for instance, are taxed as regular income when they vest. This means that the fair market value of the units at that moment is added to the employee’s taxable income. Imagine if 50 RSUs vest at a fair market value of $100 each—this could mean an additional $5,000 in income, taxed at the ordinary income rate. This can lead to a hefty tax bill, especially if the stock price is high at the time of vesting.
-
On the other hand, ordinary shares are taxed differently. When shares are sold, capital gains tax applies to the profit earned. If these shares have been held for over a year, they qualify for long-term capital gains rates, which are typically more favorable than regular income tax rates. This distinction between RSU vs common stock can make ordinary shares a more tax-efficient investment for families aiming to build wealth over time. For example, selling shares after holding them for more than a year may result in a lower tax rate compared to the immediate tax consequences of restricted units.
To effectively manage tax obligations from restricted stock units, families might consider strategies such as:
- Selling shares immediately upon vesting to avoid additional capital gains taxes.
- Utilizing tax-loss harvesting to offset gains.
Consulting with a financial advisor can provide valuable insights and tailored strategies to navigate these complexities. Remember, we’re here for you, and together, we can navigate this journey towards a secure financial future.
Assess Liquidity and Flexibility
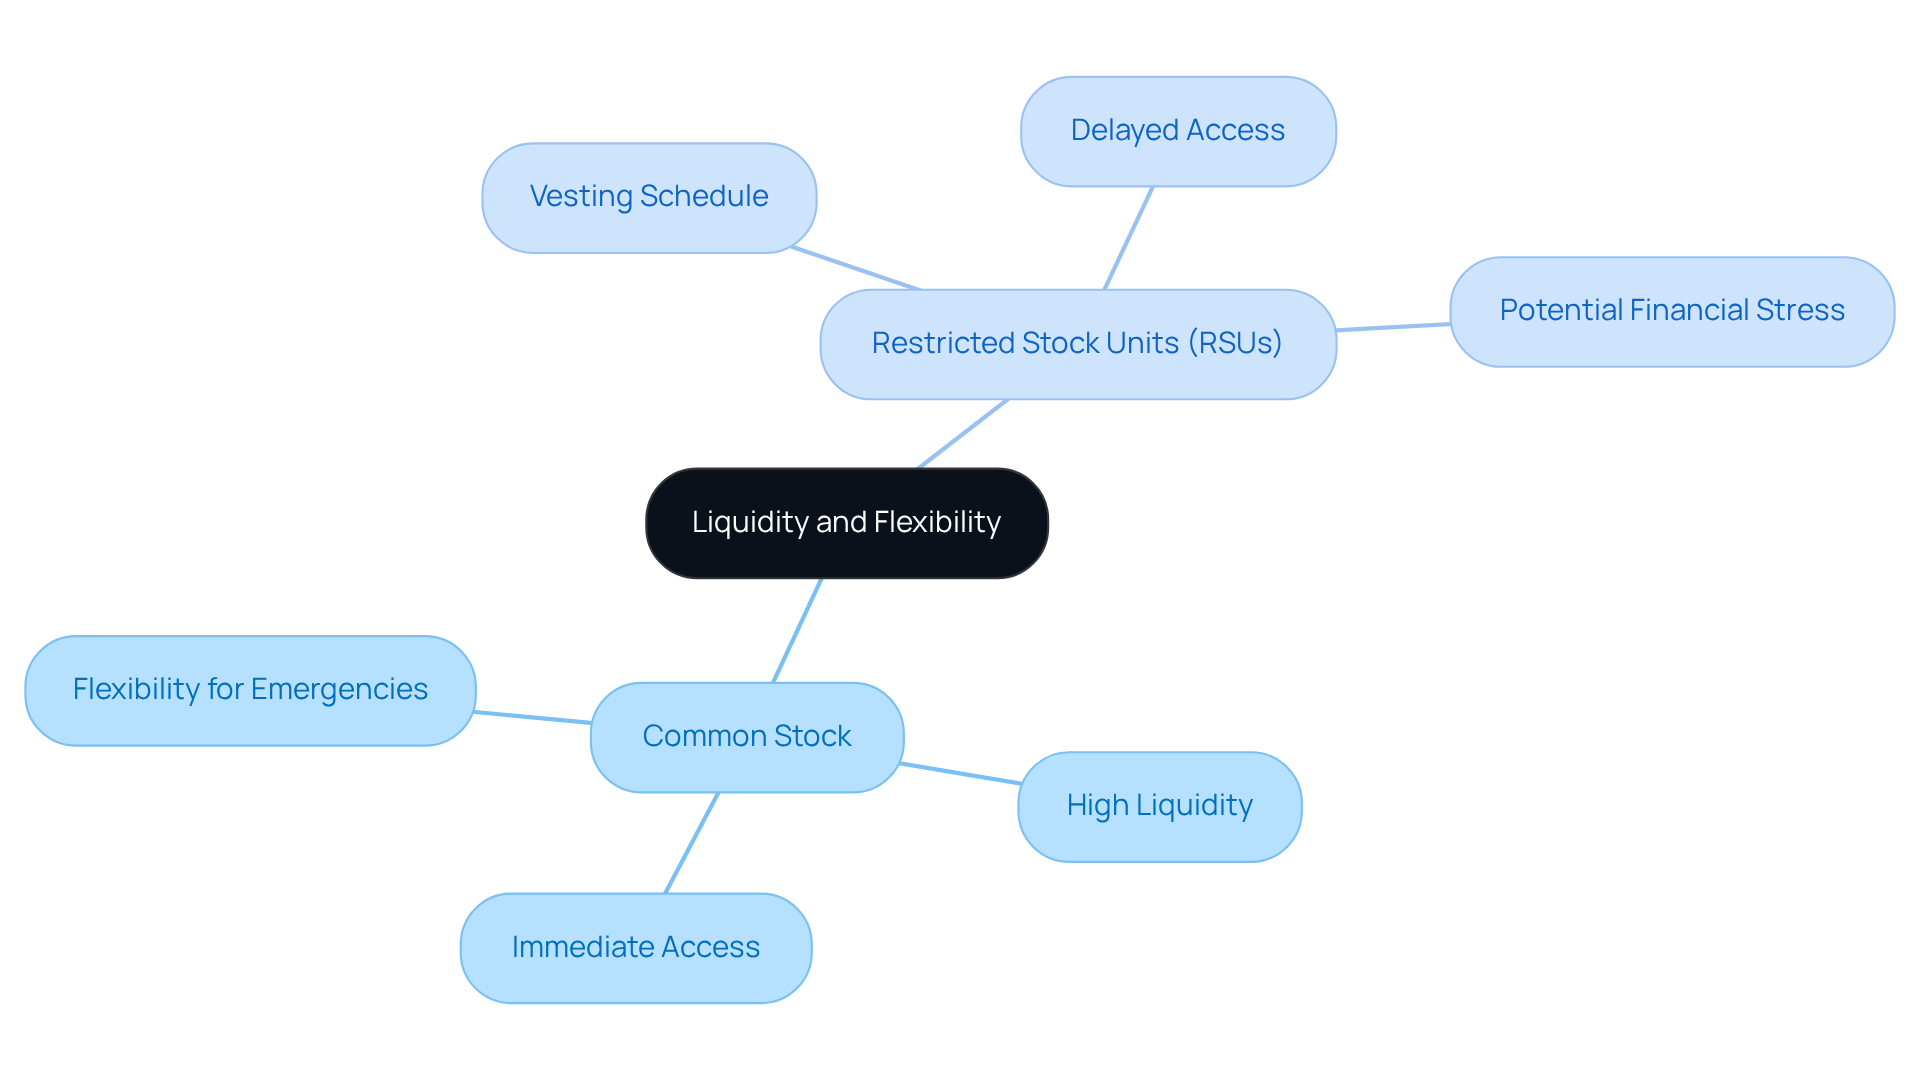
Liquidity is the ease with which an asset can be converted into cash without significantly impacting its market price. Imagine the peace of mind that comes with knowing you can access your funds quickly when you need them most. When considering RSU vs common stock, common stock generally provides higher liquidity, as it can be traded on the open market at any moment. This characteristic allows families to access funds quickly for emergencies, educational expenses, or other financial goals, providing essential flexibility in their financial planning.
In contrast, restricted stock units come with a vesting schedule, which can delay access to your funds. It’s important to understand that families may need to wait for shares to vest before they can sell them, potentially limiting their ability to respond to urgent financial needs. This lack of immediate liquidity can pose challenges for families who require quick access to cash for unexpected expenses or opportunities. For instance, consider a family facing a sudden medical bill or a time-sensitive investment opportunity. If their restricted stock units are still unvested, it can feel like their financial options are restricted, adding to their stress.
Financial advisors emphasize the importance of liquidity for young families, encouraging them to reflect on how their equity compensation aligns with their overall financial strategy. Understanding the average duration to access funds from restricted stock units after vesting is crucial; typically, families might encounter a waiting period of several months to years, depending on the vesting timeline. This can greatly influence their financial strategy, especially when contrasted with the prompt accessibility of cash from selling regular shares.
Ultimately, while RSUs can be a valuable part of a family’s wealth-building strategy, the advantages of common stock compared to RSUs in terms of liquidity make it a more flexible option for those needing quick access to funds. Together, we can navigate this journey and ensure that your family’s financial future is secure and adaptable.
Conclusion
Understanding the distinctions between Restricted Stock Units (RSUs) and common stock is essential for young families as they plan for their financial future. Imagine the peace of mind that comes from knowing how these options can shape your family’s financial landscape. RSUs offer a structured approach to equity compensation, rewarding employees with stock over time, while common stock provides immediate ownership and voting rights. Each option carries its own implications for financial security, liquidity, and tax obligations, making it crucial for families to evaluate which aligns best with their goals.
Key points to consider include:
- The nature of ownership rights
- Vesting conditions
- The tax implications associated with each type of stock
RSUs typically come with vesting requirements that delay access to funds, whereas common stock can be bought and sold at will, offering greater liquidity. It’s important to understand the tax treatment of these assets: RSUs are taxed as income upon vesting, while common stock is taxed on capital gains when sold. This distinction can lead to more favorable tax outcomes for families, allowing for better financial planning.
Ultimately, the choice between RSUs and common stock should be guided by your individual financial circumstances and goals. Reflect on your immediate liquidity needs and long-term wealth-building strategies. By gaining clarity on these options, you can make informed decisions that not only enhance your financial security but also empower you to navigate life’s uncertainties with confidence. Remember, we’re here for you, ready to support you on this journey toward a brighter financial future.
Frequently Asked Questions
What are Restricted Stock Units (RSUs)?
Restricted Stock Units (RSUs) are a form of compensation offered by employers that reward employees with company stock. They are granted to employees and become available over time, often based on the employee’s commitment or achievement of specific goals.
How do RSUs differ from common stock?
RSUs are gifted to employees and convert into actual shares of common stock once they vest, while common stock represents direct ownership in a company that can be purchased on the open market. Common stockholders have voting rights and may receive dividends, although dividends are not guaranteed.
What happens to RSUs once they vest?
Once RSUs vest, they become actual shares of common stock, allowing the employee to choose between selling the shares or retaining them for potential future value.
Do common stockholders receive dividends?
Yes, common stockholders may receive dividends, but these are not guaranteed and depend on the company’s performance.
Can common stock be purchased directly?
Yes, common stock can be bought directly on the open market, giving immediate ownership without the waiting period associated with RSUs.
How can understanding RSUs and common stock help with financial planning?
Understanding the differences between RSUs and common stock can help individuals make informed decisions about their financial options, aligning their investments with their family values and financial goals.
List of Sources
- Define Restricted Stock Units and Common Stock
- What are Restricted Stock Units (RSUs)? A Complete Guide (https://compport.com/blog/rsus?4d75b8d4_page=45)
- The Complete Guide to Restricted Stock Units (RSUs) (https://districtcapitalmanagement.com/rsu)
- Restricted Stock Unit (RSU): A Complete Guide to RSUs (https://carta.com/learn/equity/rsu)
- Restricted Stock Units and How They Work | Wealthspire (https://wealthspire.com/blog/restricted-stock-units-rsus-how-they-work-6-common-misconceptions)
- All about RSUs (https://beqom.com/blog/restricted-stock-units-all-you-need-to-know-about-rsus)
- Compare Ownership Rights and Vesting Conditions
- Restricted Stock Unit (RSU): A Complete Guide to RSUs (https://carta.com/learn/equity/rsu)
- Restricted Stock Unit (RSU): How It Works and Pros and Cons (https://investopedia.com/terms/r/restricted-stock-unit.asp)
- RSU Vesting: A Guide to Understanding Restricted Stock Units (https://brightonjones.com/blog/rsu-vesting)
- RSUs: A Guide to Understanding Restricted Stock Units | Facet (https://facet.com/equity/understanding-restricted-stock-units-rsus-taxes-vesting-schedules-pros-cons)
- Restricted Stock Units (RSUs) and Tax Planning Strategy: 3 Key Questions for Tech Professionals in 2025 (https://maprivatewealth.com/insights/restricted-stock-units-tax-planning-strategy-tech-professionals)
- Evaluate Tax Implications of RSUs vs Common Stock
- Are RSUs Taxed Twice? What You Need to Know | Consilio Wealth Advisors (https://consiliowealth.com/insights/are-rsus-taxed-twice-what-you-need-to-know)
- RSU Taxes: How Are Restricted Stock Units (RSUs) Taxed? | Facet (https://facet.com/equity/rsu-taxes-calculations-reporting-strategies)
- Understanding RSU Tax Rates: Comprehensive Guide with Calculator (https://advisorfinder.com/resources-for-clients/tax/rsu-tax-rate)
- The Taxation of Restricted Stock Units | Cerity Partners (https://ceritypartners.com/insights/the-taxation-of-restricted-stock-units)
- How Are Restricted Stock Units (RSUs) Taxed? (https://smartasset.com/investing/how-are-restricted-stock-units-taxed)
- Assess Liquidity and Flexibility
- Restricted Stock Units and How They Work | Wealthspire (https://wealthspire.com/blog/restricted-stock-units-rsus-how-they-work-6-common-misconceptions)
- RSU Taxes Explained + 4 Tax Strategies for 2023 (https://cordantwealth.com/rsus-tax-saving-and-hedging)
- The RSU Tax Withholding Conundrum (https://tciwealth.com/blog/rsu-tax-withholding)
- Biotech Industry Trends in Equity Compensation: Influence of Market Volatility on Equity Program Strategy (https://paygovernance.com/viewpoints/biotech-industry-trends-in-equity-compensation-influence-of-market-volatility-on-equity-program-strategy)
- Restricted Stock Units: 10 Fast Facts (https://foley.com/insights/publications/2020/08/restricted-stock-units-10-fast-facts)

Kevin has advised high-income W-2 tech and biotech families since 2015, and leads the education-first Age Five Family Office from Brea, California.
Connect on LinkedIn → · About KevinThis is part of how we approach Tax Management for high-income W-2 families at Bright Advisers.
Keep reading