

Key Highlights:
- A 529 plan is a tax-advantaged savings account for future educational costs, with contributions growing tax-free.
- There are two main types of 529 accounts: prepaid tuition arrangements and education savings options.
- As of December 2024, 32% of families utilise college savings programmes, highlighting their importance in education financing.
- To convert a 529 account to a Roth IRA, the account must be open for at least 15 years, and funds must be in the account for a minimum of 5 years.
- The rollover limit is capped at $35,000 per beneficiary over their lifetime, and the beneficiary must have earned income for the year.
- The rollover from a 529 to a Roth IRA can be tax-free if done according to the Secure 2.0 Act guidelines.
- Annual contribution limits for IRAs are $7,000 for those under 50 and $8,000 for those 50 and older.
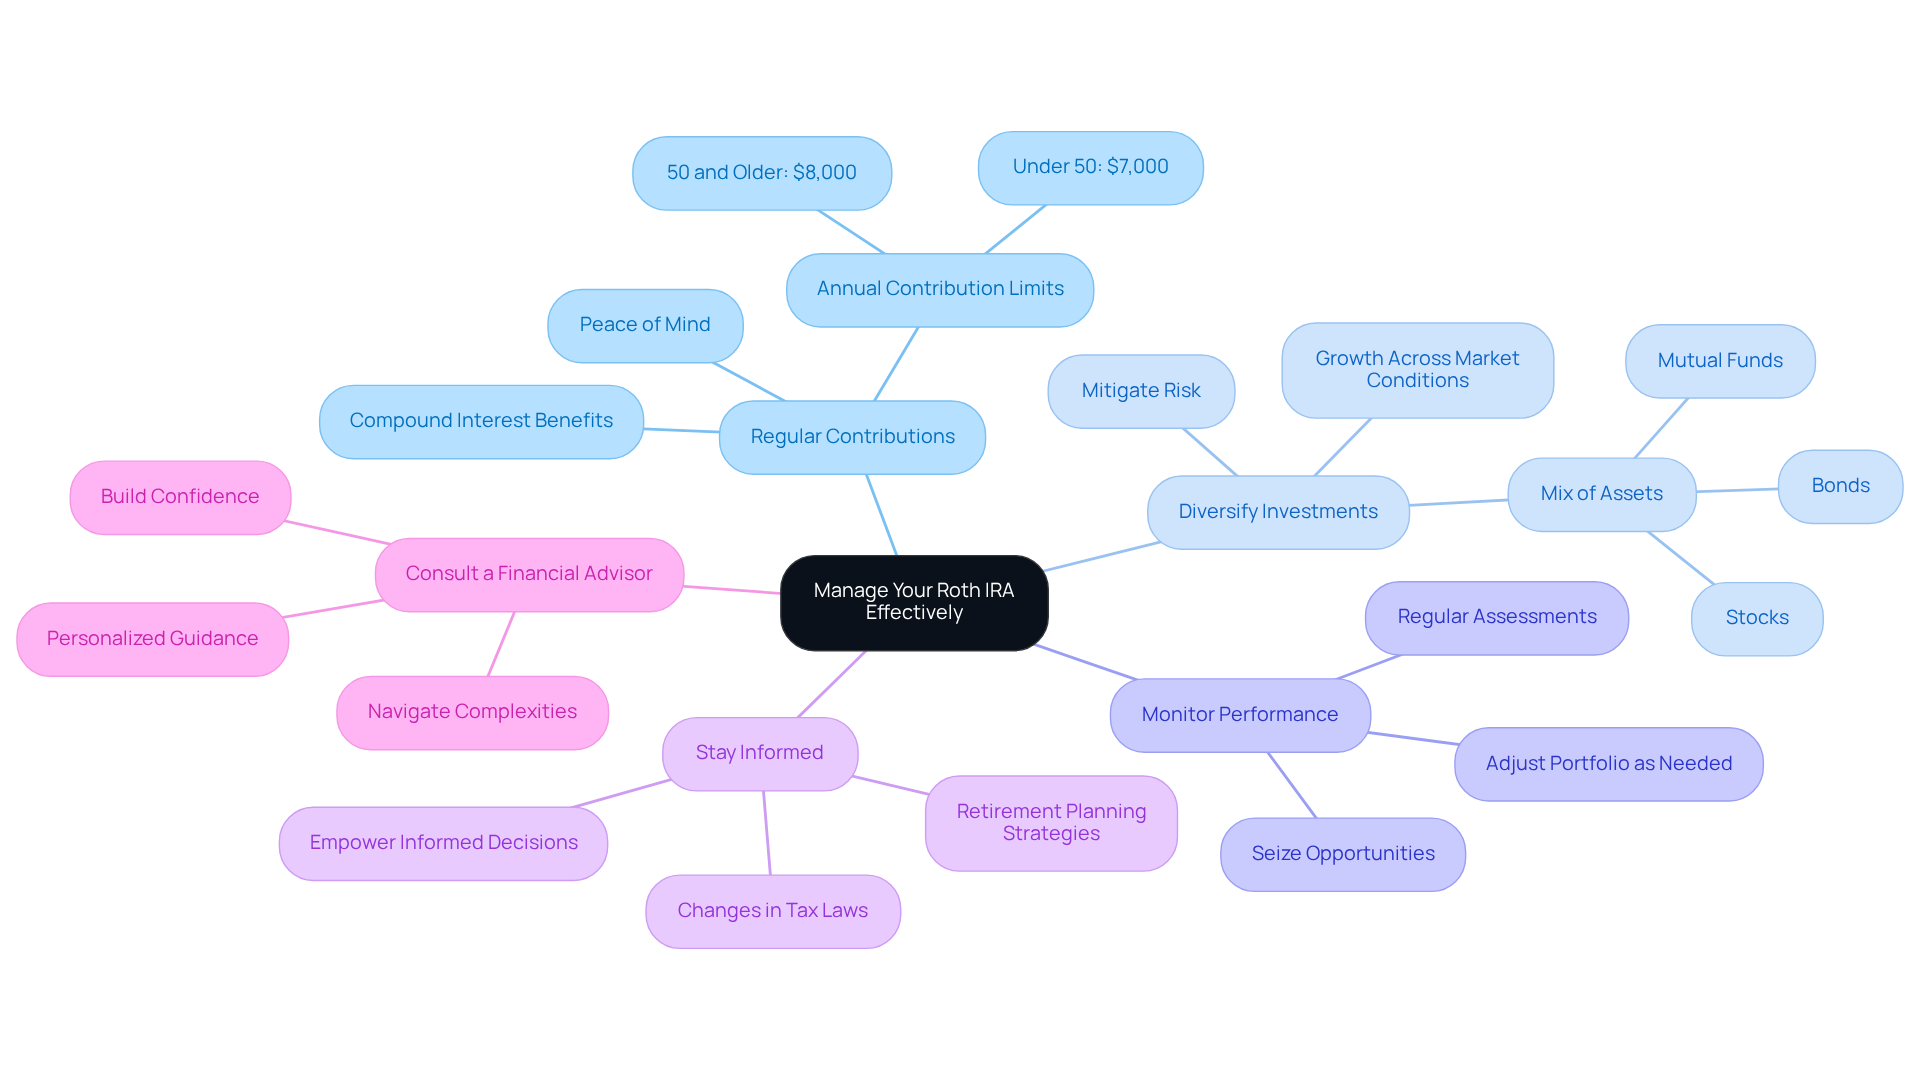
- Effective management of a Roth IRA includes regular contributions, diversifying investments, monitoring performance, staying informed on tax laws, and consulting a financial advisor.
Introduction
Navigating the world of education savings can feel overwhelming, especially with the recent changes brought about by the Secure 2.0 Act. Imagine if you could convert a 529 plan into a Roth IRA—this opens up exciting possibilities for families eager to secure their financial future.
In this guide, we’ll gently walk you through the straightforward steps involved in this conversion. We’ll highlight both the potential benefits and challenges along the way, ensuring you feel informed and empowered. How can families best leverage this opportunity to meet their children’s educational and financial needs?
Together, we can navigate this journey, making sure that your family’s priorities are at the forefront of your financial planning. We’re here for you, ready to support you in making the best decisions for your loved ones.
Understand the Basics of a 529 Plan
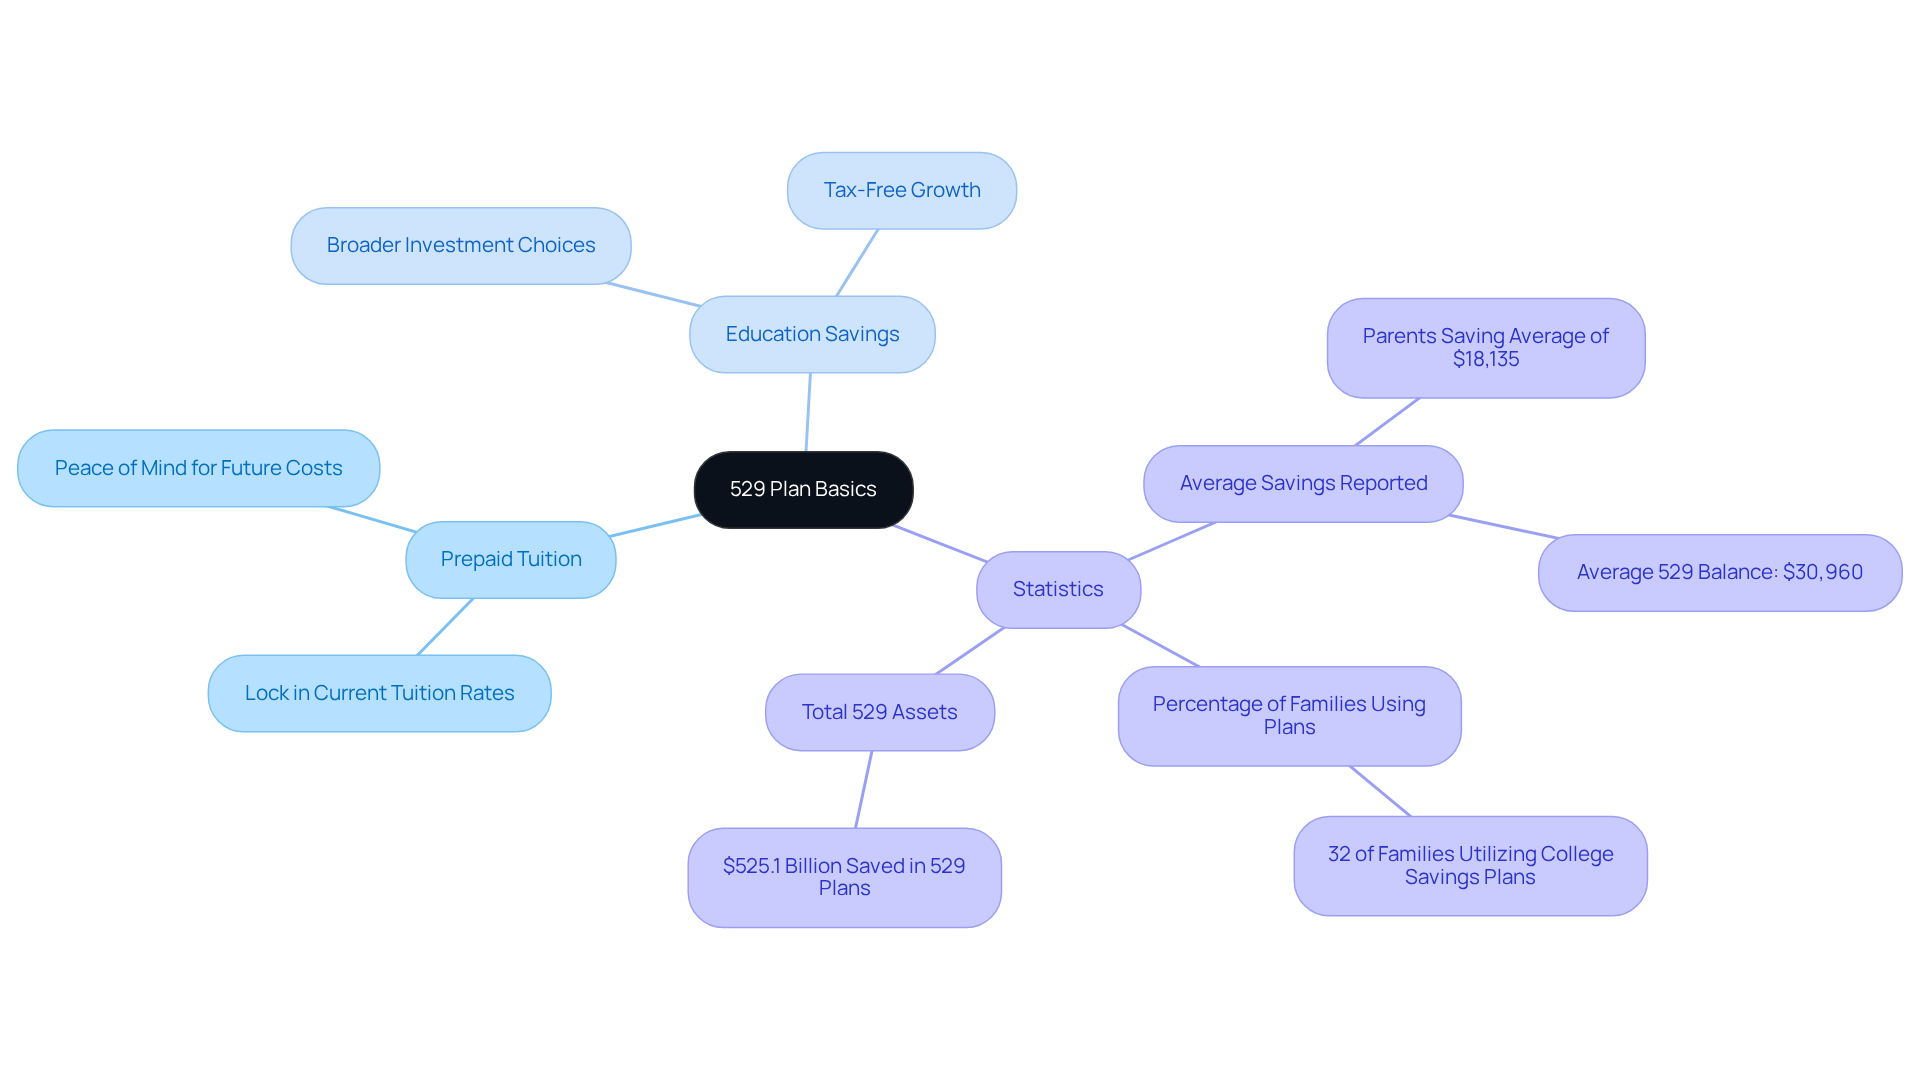
Imagine a future where your child’s education is secure and financially manageable. A 529 program can be a wonderful tool in this journey, acting as a tax-advantaged savings account designed to help you accumulate funds for future educational costs. With contributions growing without tax implications, and withdrawals for eligible education expenses being tax-free, it’s a smart choice for families looking to invest in their children’s future.
It’s important to understand the two primary categories of 529 accounts:
- Prepaid tuition arrangements allow families to lock in current tuition rates for future college enrollment, providing peace of mind.
- Education savings options offer a broader range of investment choices that can grow with market performance.
This knowledge is vital, especially for families considering how much they can roll over into a Roth IRA under the new provisions related to secure 2.0 529 to Roth.
As of December 2024, around 32% of families are utilizing college savings programs, showcasing their growing importance in education financing. Financial advisors often highlight the advantages of tax-free growth in 529 accounts, which can significantly boost your savings over time. For instance, families who began saving early for their children’s education reported an average savings of $9,930 in 2025. This illustrates how these strategies can help establish a solid financial foundation for your child’s educational needs.
Together, we can navigate this journey toward financial security for your family. We’re here for you, ready to support you in making informed decisions that align with your family’s values and goals.
Determine Eligibility for Conversion
Transforming your 529 account into an IRA can feel daunting, but we’re here to help you navigate this journey with confidence. To make this transition, there are a few important eligibility requirements to keep in mind:
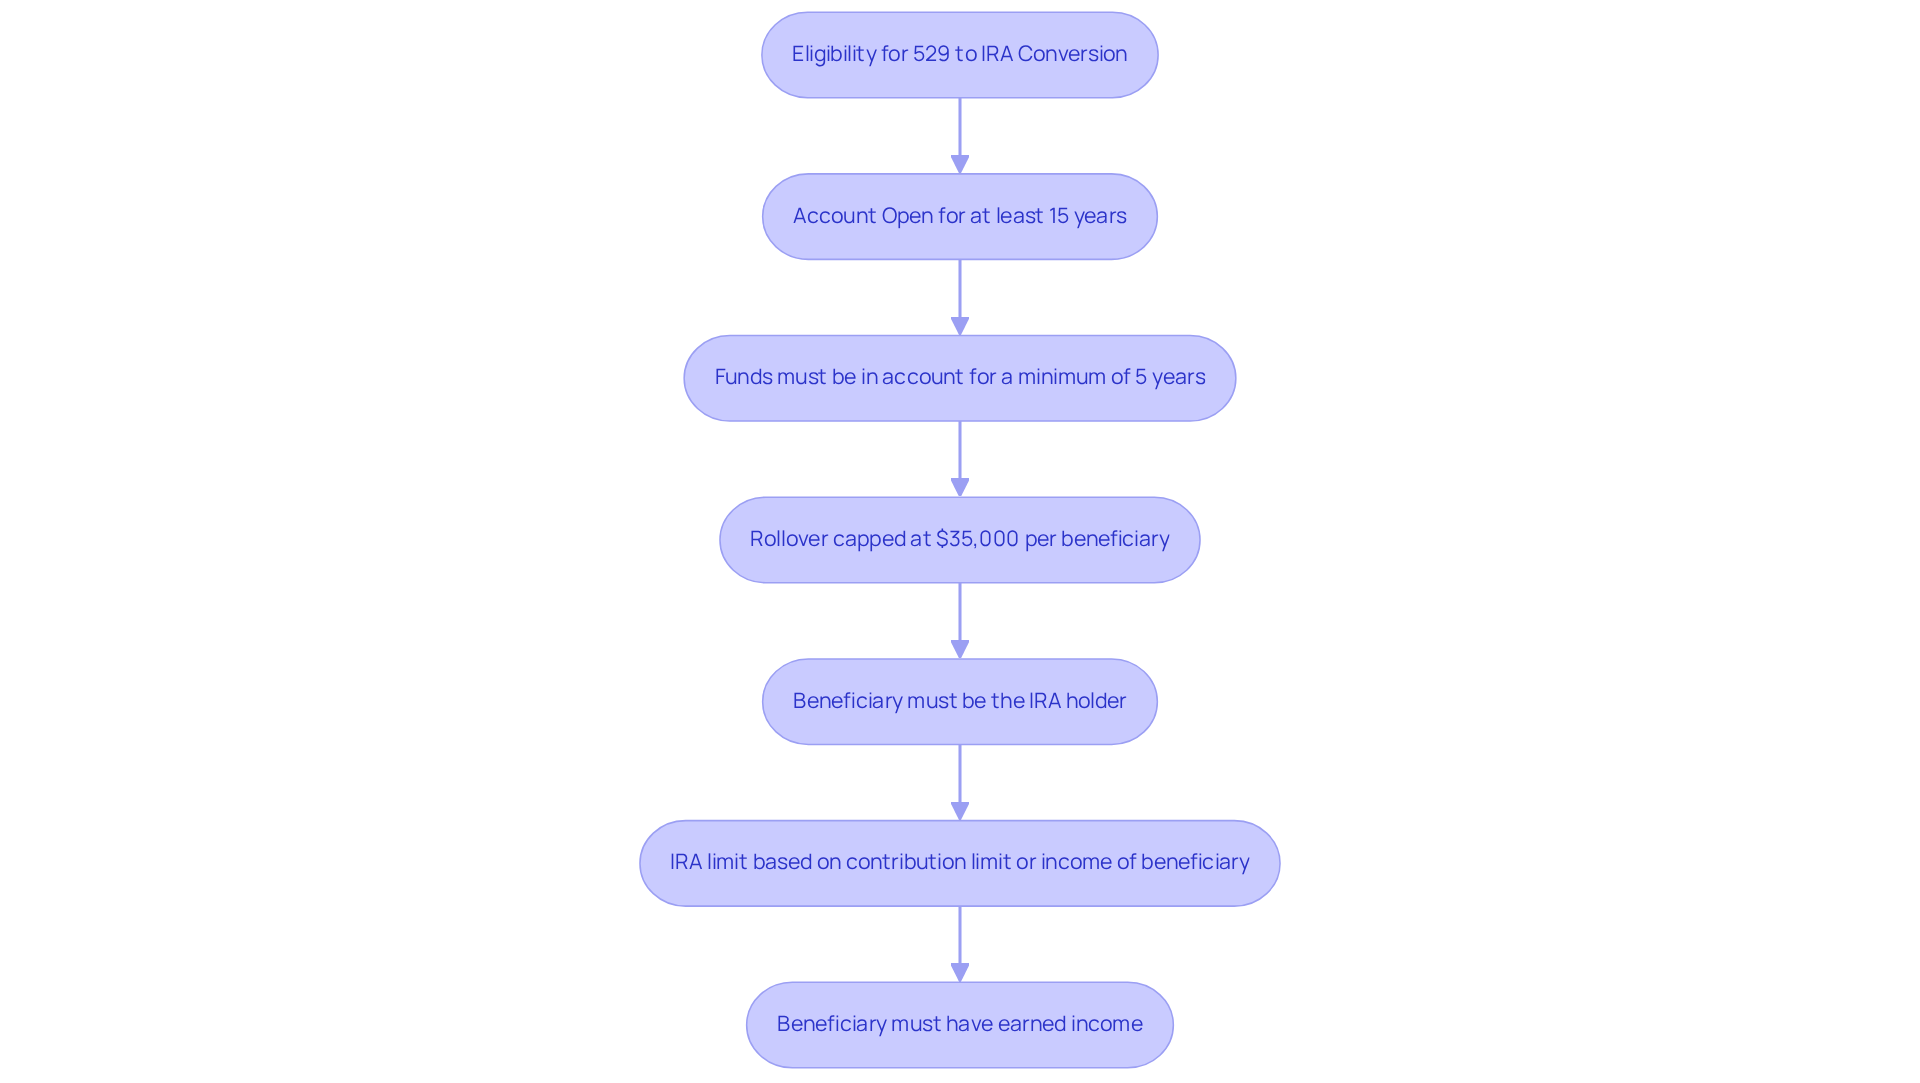
- Your 529 account needs to have been open for at least 15 years.
- Any funds you wish to roll over must have been in the account for a minimum of 5 years.
- The total amount you can roll over is capped at $35,000 per beneficiary over their lifetime.
- The recipient of the 529 account must also be the holder of the IRA to comply with the new rules set by the Secure 2.0 Act.
When it comes to contributions, the IRA limit is determined by the lesser of the annual contribution limit or the income of the 529 beneficiary for that year. This is an important detail to consider as you plan for your family’s future. However, it’s worth noting that the IRS has yet to provide guidance on the secure 2.0 529 to Roth transfer provision, which may bring some uncertainties into the mix.
Lastly, ensure that the beneficiary has earned income that meets or exceeds the rollover amount. This step is vital to comply with the new regulations. Remember, we’re here for you every step of the way, helping you make informed decisions that support your family’s financial well-being.
Initiate the Conversion Process
Navigating Your 529 Plan to Roth IRA Conversion: A Caring Guide
Are you feeling overwhelmed by the thought of converting your 529 plan to a Roth IRA? You’re not alone. Many parents share this concern, and we’re here to help you through it, step by step.
-
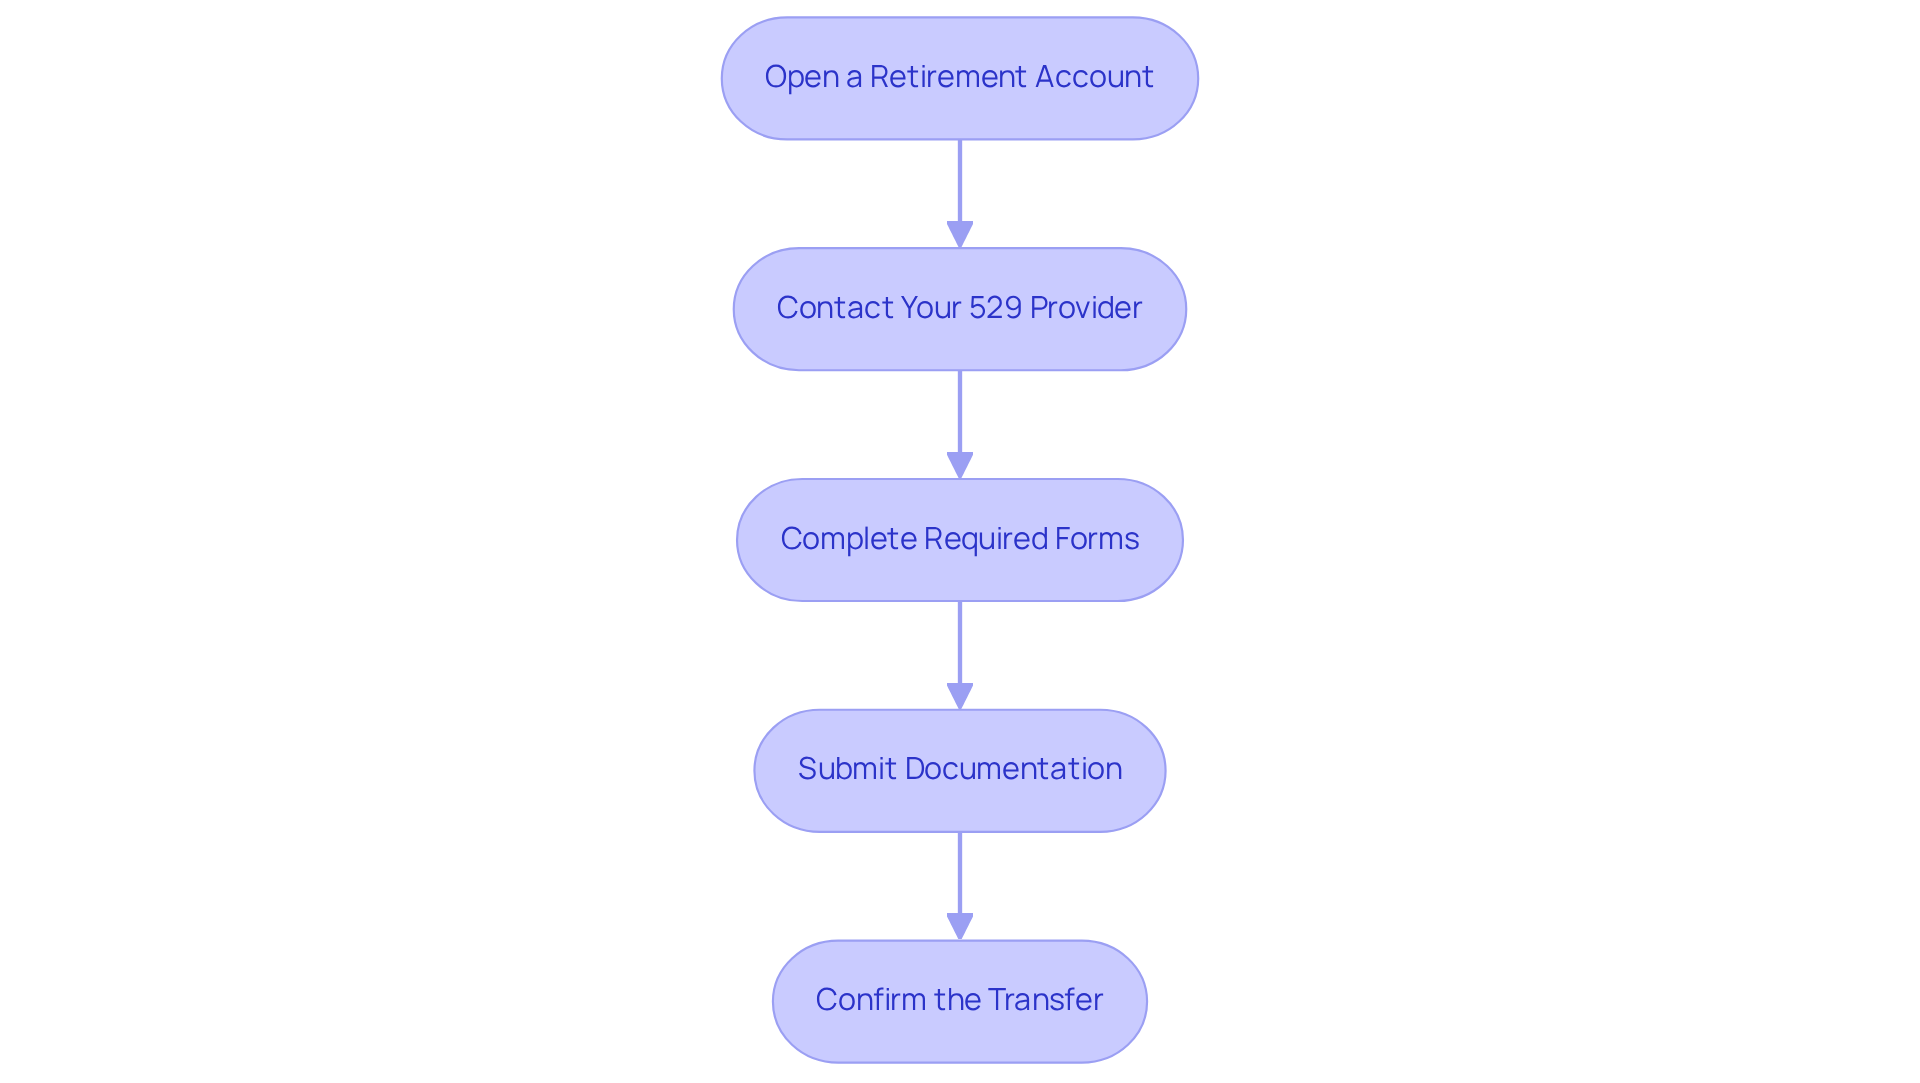
Open a Retirement Account: If you haven’t done so yet, it’s time to set up an individual retirement account with a financial institution that feels right for you. Remember, the beneficiary of your 529 account should also be the owner of the Roth IRA. This connection is key to a smooth transition.
-
Contact Your 529 Provider: Reach out to your 529 provider and ask for a trustee-to-trustee transfer. This crucial step helps you avoid any tax penalties that could come with the conversion. It’s all about making this process as seamless as possible for you.
-
Complete Required Forms: Take a moment to fill out the necessary documents your 529 provider gives you to kick off the rollover. Usually, this includes a direct rollover request form. Don’t worry; it’s straightforward!
-
Submit Documentation: Once you have everything ready, send all required documents to both your 529 account provider and the IRA custodian. This will help facilitate the transfer process smoothly.
-
Confirm the Transfer: After you’ve submitted your request, check in with both institutions to ensure the transfer has been completed successfully. It’s always good to double-check!
Keep in mind that in order to secure 2.0 529 to Roth, your 529 account needs to be open for at least 15 years. Plus, beneficiaries can transfer up to $35,000 from a 529 account to an IRA without incurring taxes or penalties. By following these steps, you can effectively manage your 529 funds and convert them into a retirement account, paving the way for a brighter financial future for your family.
Together, we can navigate this journey, ensuring that your family’s financial goals are met with care and understanding.
Evaluate Tax Implications and Benefits
When it comes to transferring assets from a 529 account to an IRA, understanding the tax implications is crucial. Imagine feeling secure knowing that the secure 2.0 529 to Roth rollover can be tax-free, as long as you follow the guidelines set by the Secure 2.0 Act. This means you won’t face taxes or penalties, which can be a relief for many families.
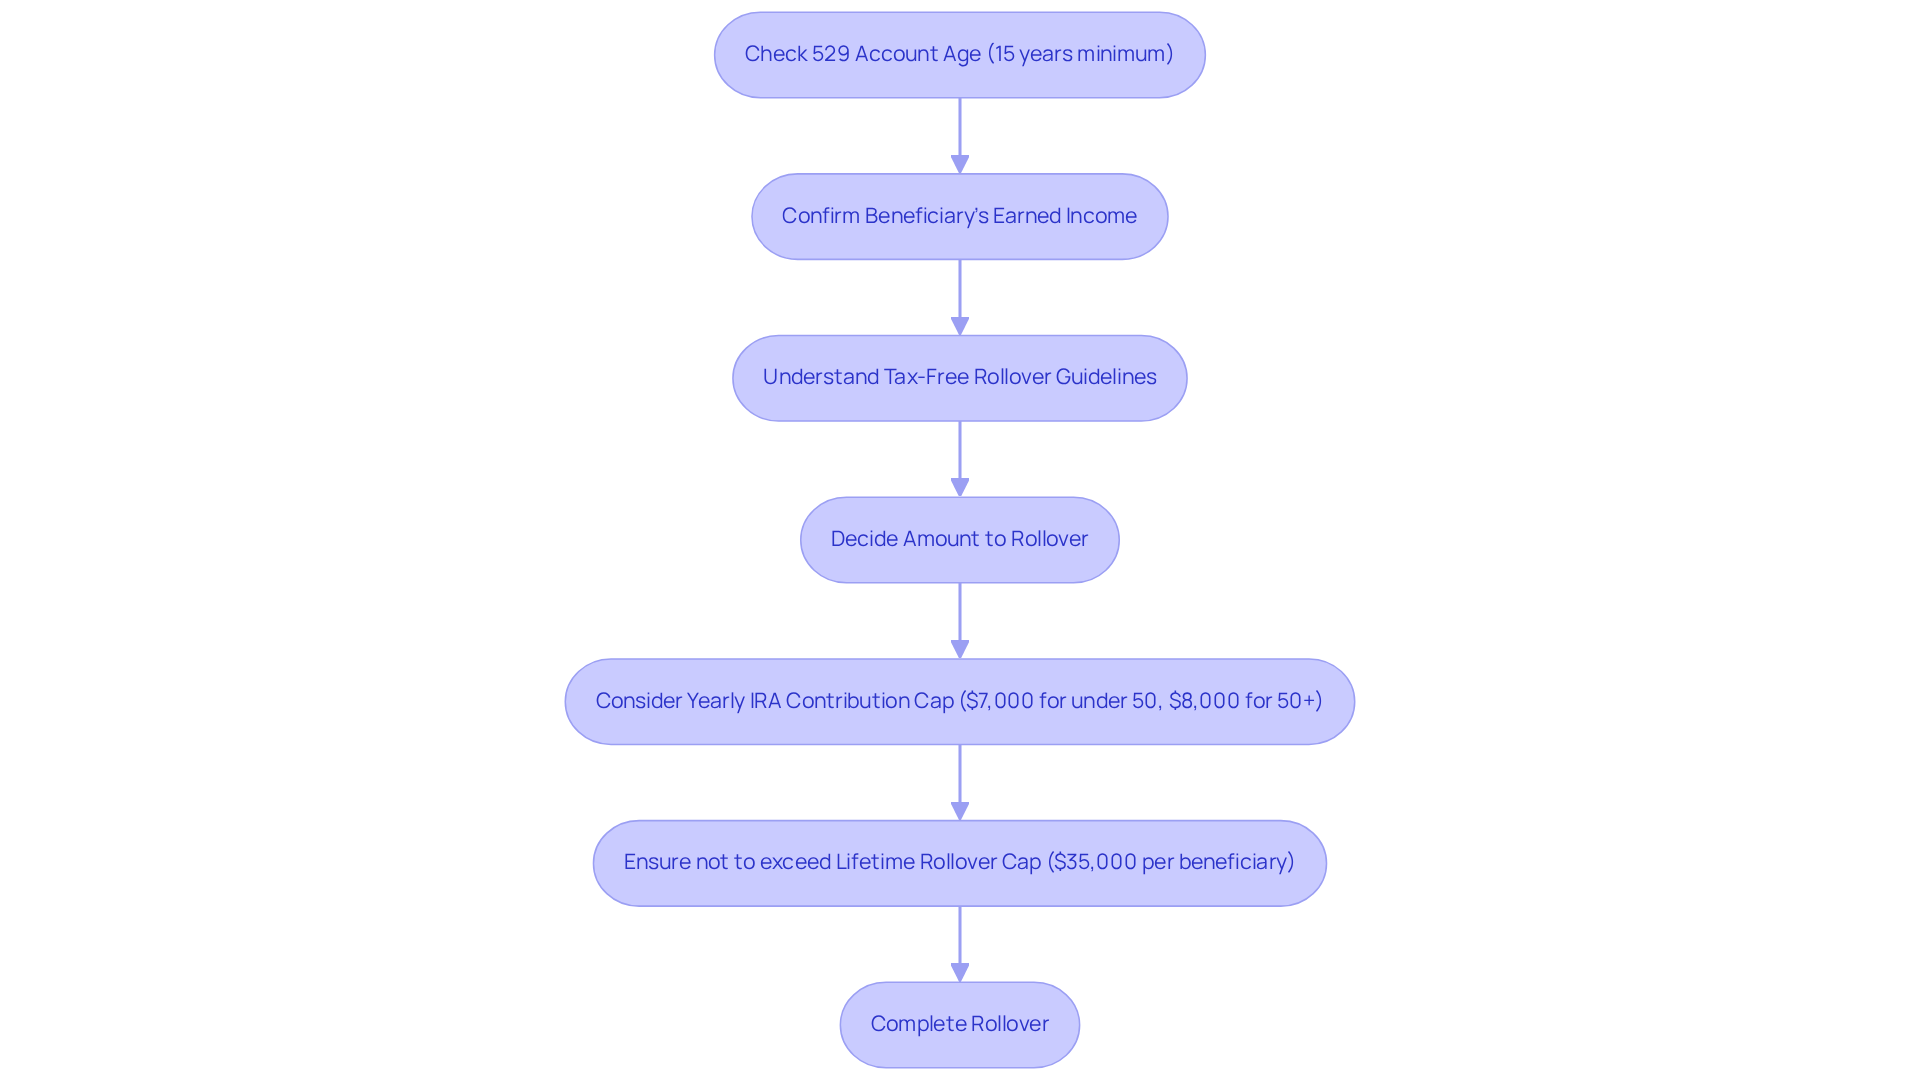
However, it’s important to keep in mind that the amount you roll over counts toward your yearly IRA contribution cap. For individuals under 50, that cap is $7,000, and for those 50 and older, it’s $8,000. Picture this: if you decide to roll over $35,000, you’ll need to spread that amount over several years to stay within the annual limit. Plus, there’s a lifetime rollover cap of $35,000 for each beneficiary, so planning is key.
Also, remember that the 529 account must be at least 15 years old for a rollover to happen, and the beneficiary needs to have earned income for the year. This can feel overwhelming, but you’re not alone in this journey. Engaging with a tax professional can provide clarity on how this rollover fits into your overall tax strategy. Together, we can navigate these complexities, ensuring you maximize benefits while minimizing potential pitfalls.
We’re here for you, ready to support you in making the best financial decisions for your family.
Manage Your Roth IRA Effectively
Maximizing your investment is a journey that requires thoughtful management after you secure 2.0 529 to Roth. Here are some essential strategies to help you along the way:
-
Regular Contributions: Imagine the peace of mind that comes from contributing annually up to the IRS limits—$7,000 for those under 50 and $8,000 for those 50 and older in 2025. By making consistent contributions, you can significantly enhance your retirement savings growth, harnessing the power of compound interest over time.
-
Diversify Investments: It’s important to create a well-rounded portfolio. Think about incorporating a mix of assets like stocks, bonds, and mutual funds. This balance not only helps mitigate risk but also positions your investments for growth across various market conditions, ensuring your family’s financial future is secure.
-
Monitor Performance: Regularly assessing your investment performance is key. Adjust your portfolio as needed to stay aligned with your financial goals and market trends. This proactive approach allows you to seize opportunities and minimize losses, keeping your family’s best interests at heart.
-
Stay Informed: Keeping up with changes in tax laws and retirement planning strategies can feel overwhelming, but it’s crucial. Understanding these shifts empowers you to make informed decisions that optimize your financial future, ensuring you’re always one step ahead.
-
Consult a Financial Advisor: If managing your IRA feels daunting, remember that you’re not alone. Seeking advice from a financial advisor can provide personalized guidance tailored to your unique situation, helping you navigate this journey with confidence.
By implementing these strategies, families can effectively manage their Roth IRAs and secure 2.0 529 to Roth, thus laying a strong foundation for future financial security. Together, we can navigate this journey, ensuring that your family’s dreams and goals are within reach.
Conclusion
Converting a 529 plan to a Roth IRA can be a powerful step for families looking to secure their financial future while maximizing educational savings. This guide walks you through the essential steps of this process, from understanding the basics of a 529 plan to effectively managing your newly converted Roth IRA. By grasping the eligibility requirements and following the conversion steps, you can transition your savings with confidence, ensuring that your investments continue to grow tax-free.
It’s crucial to know the eligibility criteria, like the age of the 529 account and the limits on rollover amounts. Understanding the tax implications and managing your investments carefully after conversion is equally important. Engaging with financial professionals and staying informed about investment strategies can enhance the benefits of this transition, paving the way for a more secure financial future.
Imagine a future where financial literacy and planning are at the forefront of your family’s priorities. Taking proactive steps to convert a 529 plan to a Roth IRA can significantly impact your family’s long-term financial health. Embracing this opportunity not only prepares you for educational expenses but also lays the groundwork for a robust retirement strategy. We encourage you to take action, consult with financial advisors, and remain vigilant in your investment management to optimize the benefits of your savings. Together, we can navigate this journey toward a brighter financial future.
Frequently Asked Questions
What is a 529 plan?
A 529 plan is a tax-advantaged savings account designed to help families accumulate funds for future educational costs, allowing contributions to grow without tax implications and enabling tax-free withdrawals for eligible education expenses.
What are the two primary categories of 529 accounts?
The two primary categories of 529 accounts are prepaid tuition arrangements, which allow families to lock in current tuition rates for future college enrollment, and education savings options, which offer a broader range of investment choices that can grow with market performance.
How prevalent are 529 plans among families?
As of December 2024, around 32% of families are utilizing college savings programs, indicating their growing importance in education financing.
What are the benefits of starting to save early in a 529 plan?
Families who began saving early for their children’s education reported an average savings of $9,930 in 2025, highlighting how early investment strategies can help establish a solid financial foundation for educational needs.
What are the eligibility requirements for converting a 529 account into an IRA?
To convert a 529 account into an IRA, the account must have been open for at least 15 years, funds must have been in the account for a minimum of 5 years, and the total amount rolled over is capped at $35,000 per beneficiary over their lifetime.
Who can hold the IRA after converting a 529 account?
The recipient of the 529 account must also be the holder of the IRA to comply with the new rules set by the Secure 2.0 Act.
How is the IRA contribution limit determined in relation to a 529 account rollover?
The IRA contribution limit is determined by the lesser of the annual contribution limit or the income of the 529 beneficiary for that year.
What is a critical requirement for the beneficiary when rolling over funds from a 529 account to an IRA?
The beneficiary must have earned income that meets or exceeds the rollover amount to comply with the new regulations.
List of Sources
- Understand the Basics of a 529 Plan
- Why 529 plans are worth it for saving for college (https://cnbc.com/select/how-529-college-plans-become-more-valuable)
- Release: 529 Plan Program Statistics, December 2024 | Investment Company Institute (https://ici.org/research/stats/529s/529s_24_q4)
- 529 Plan And College Savings Statistics (https://thecollegeinvestor.com/529-plan-and-college-savings-statistics?srsltid=AfmBOoqnQxMAMF3pQhfsqDzTNeZmGRwdlkF1pAX2joWap9izAEZv4Vxo)
- 529 College Savings Plan Statistics | BestColleges (https://bestcolleges.com/research/529-college-savings-plan-statistics)
- College Saving Statistics [2025]: Average Savings & 529 Balance (https://educationdata.org/college-savings-statistics)
- Determine Eligibility for Conversion
- Unsupported browser | TIAA (https://tiaa.org/public/invest/services/wealth-management/perspectives/529-to-roth-ira-rules)
- Understanding 529 rollovers to a Roth IRA (https://fidelity.com/learning-center/personal-finance/529-rollover-to-roth)
- T. Rowe Price Personal Investor – Five things to know about 529-to-Roth IRA Rollovers (https://troweprice.com/personal-investing/resources/insights/five-things-to-know-about-529-to-roth-ira-rollovers.html)
- Initiate the Conversion Process
- How To Convert A 529 Plan To A Roth IRA | Bankrate (https://bankrate.com/retirement/roll-over-529-roth-ira)
- Rolling Unused Funds from a 529 Account into a Roth IRA – (https://nextgenforme.com/rolling-unused-funds-from-a-529-account-into-a-roth-ira)
- Rolling a 529 account into a Roth IRA — Manulife Investments | John Hancock — Manulife John Hancock Investments (https://jhinvestments.com/viewpoints/college-saving/Rolling-a-529-account-into-a-Roth-IRA-helping-clients-navigate-the-details)
- How to Convert a 529 Plan to a Roth IRA (https://morningstar.com/financial-advisors/how-convert-529-plan-roth-ira)
- A retirement savings head start: 529-to-Roth rollovers (https://thetaxadviser.com/issues/2024/jul/a-retirement-savings-head-start-529-to-roth-rollovers)
- Evaluate Tax Implications and Benefits
- 529 to Roth IRA Rollover: Rules, Limits, and How It Works Under SECURE 2.0 (https://landsbergbennett.com/blogs/insights/529-to-roth-ira-rollover-rules-limits-and-how-it-works-under-secure-2-0)
- Five things to know about rolling a 529 account into a Roth IRA — Manulife John Hancock Investments (https://jhinvestments.com/viewpoints/college-saving/five-things-to-know-about-rolling-a-529-account-into-a-roth-ira)
- Unsupported browser | TIAA (https://tiaa.org/public/invest/services/wealth-management/perspectives/529-to-roth-ira-rules)
- Is a Roth IRA conversion right for you? | Vanguard (https://investor.vanguard.com/investor-resources-education/iras/ira-roth-conversion)
- Manage Your Roth IRA Effectively
- 7 Ways to Maximize Your IRA in 2025 (https://morningstar.com/retirement/7-ways-maximize-your-ira-2025)
- 7 Reasons To Max Out Your Roth IRA | Bankrate (https://bankrate.com/investing/reasons-to-max-out-your-roth-ira)
- Retirement Account Statistics 2025 – NerdWallet (https://nerdwallet.com/article/investing/retirement-statistics)
- Ed Slott: The Case for Roth IRA Contributions (https://morningstar.com/retirement/ed-slott-case-roth-ira-contributions)

Kevin has advised high-income W-2 tech and biotech families since 2015, and leads the education-first Age Five Family Office from Brea, California.
Connect on LinkedIn → · About KevinThis is part of how we approach Tax Management for high-income W-2 families at Bright Advisers.
Keep reading