

Key Highlights
- Restricted Stock Units (RSUs) are equity compensation granted outright to employees, vesting over time or upon meeting performance milestones.
- Once vested, RSUs convert into actual shares or cash, providing clear value to employees and minimising risks for companies.
- Understanding the vesting schedule is crucial for budgeting and can influence financial decisions, such as using RSUs as collateral for loans.
- Companies typically withhold 22% for taxes on vested RSUs, impacting financial planning and decision-making.
- Eligibility for loans against RSUs requires fully vested RSUs, stable employment history, and accurate income verification.
- Different creditors have varying policies regarding RSUs; research is essential to understand lender requirements.
- Gathering necessary documentation, including RSU grant letters and tax returns, is vital for a smooth loan application process.
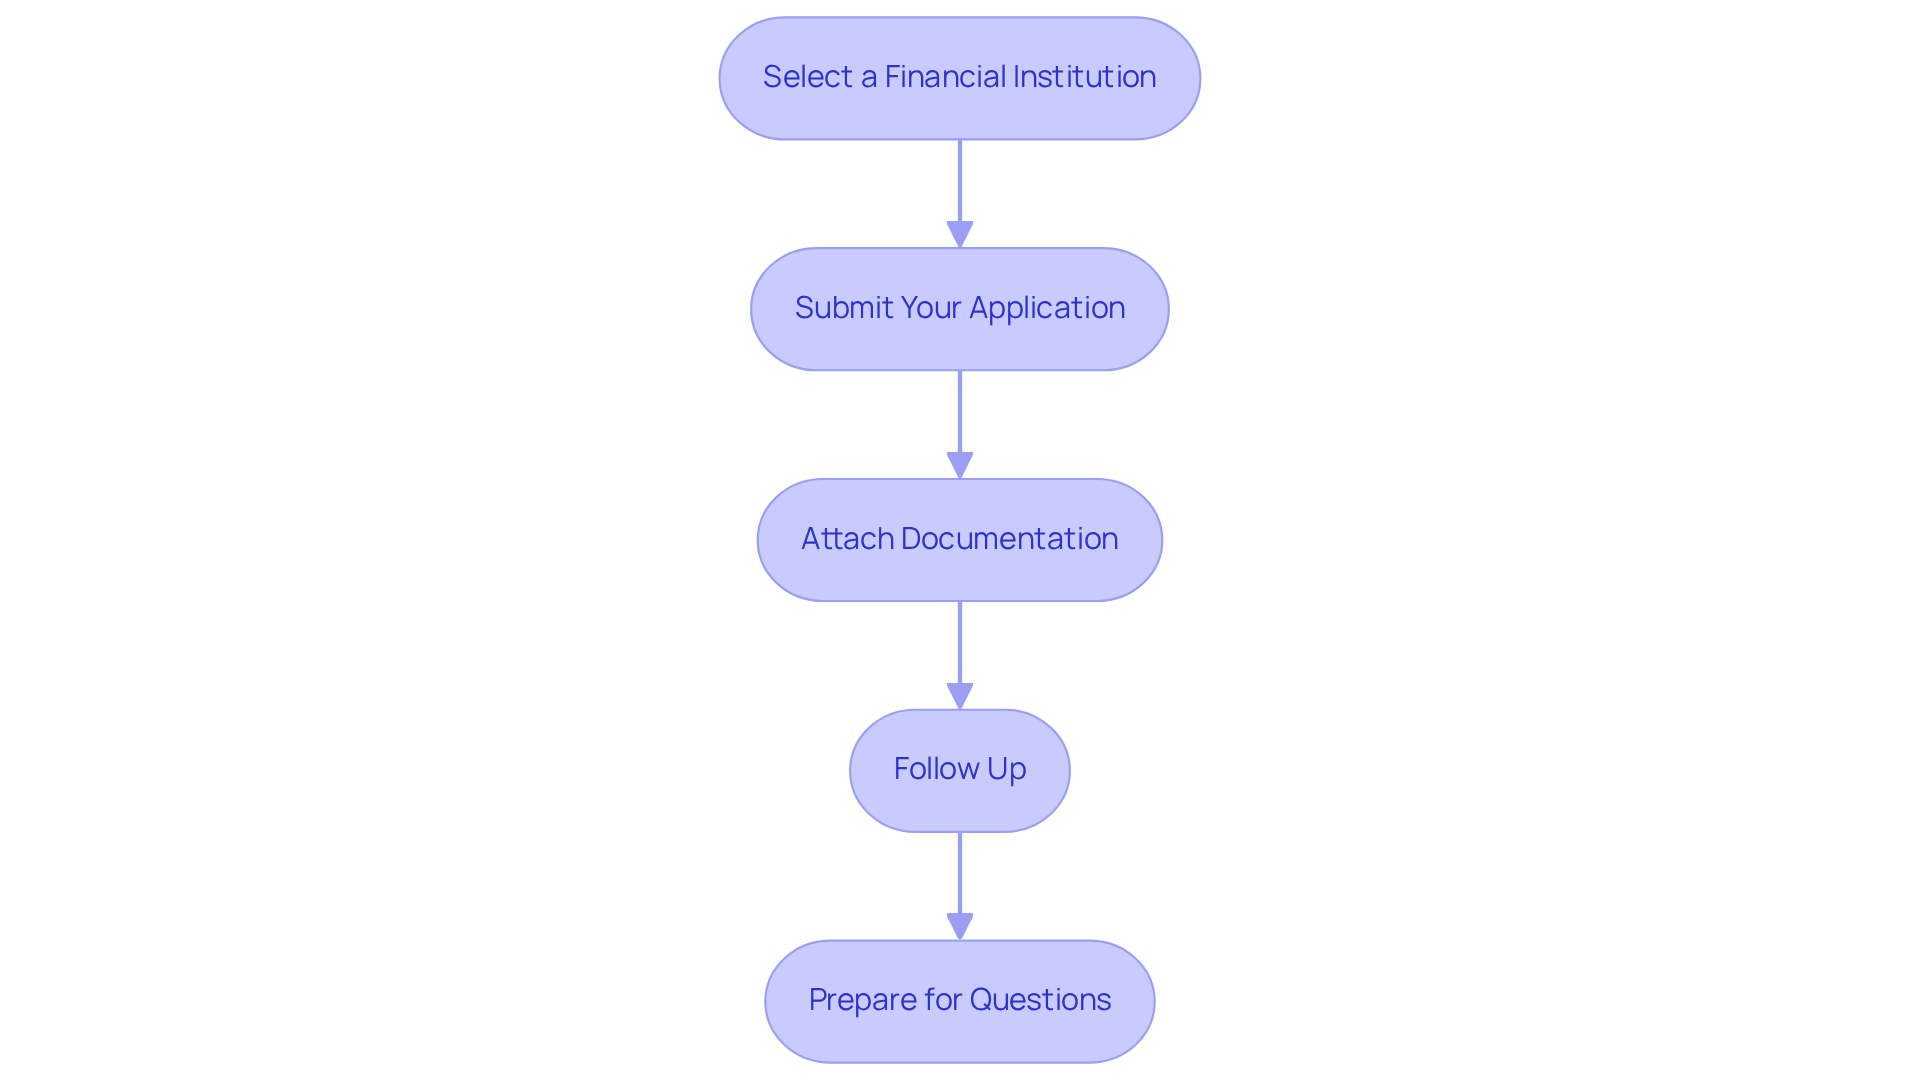
- The loan application process involves selecting a financial institution, submitting applications, and preparing for follow-up questions.
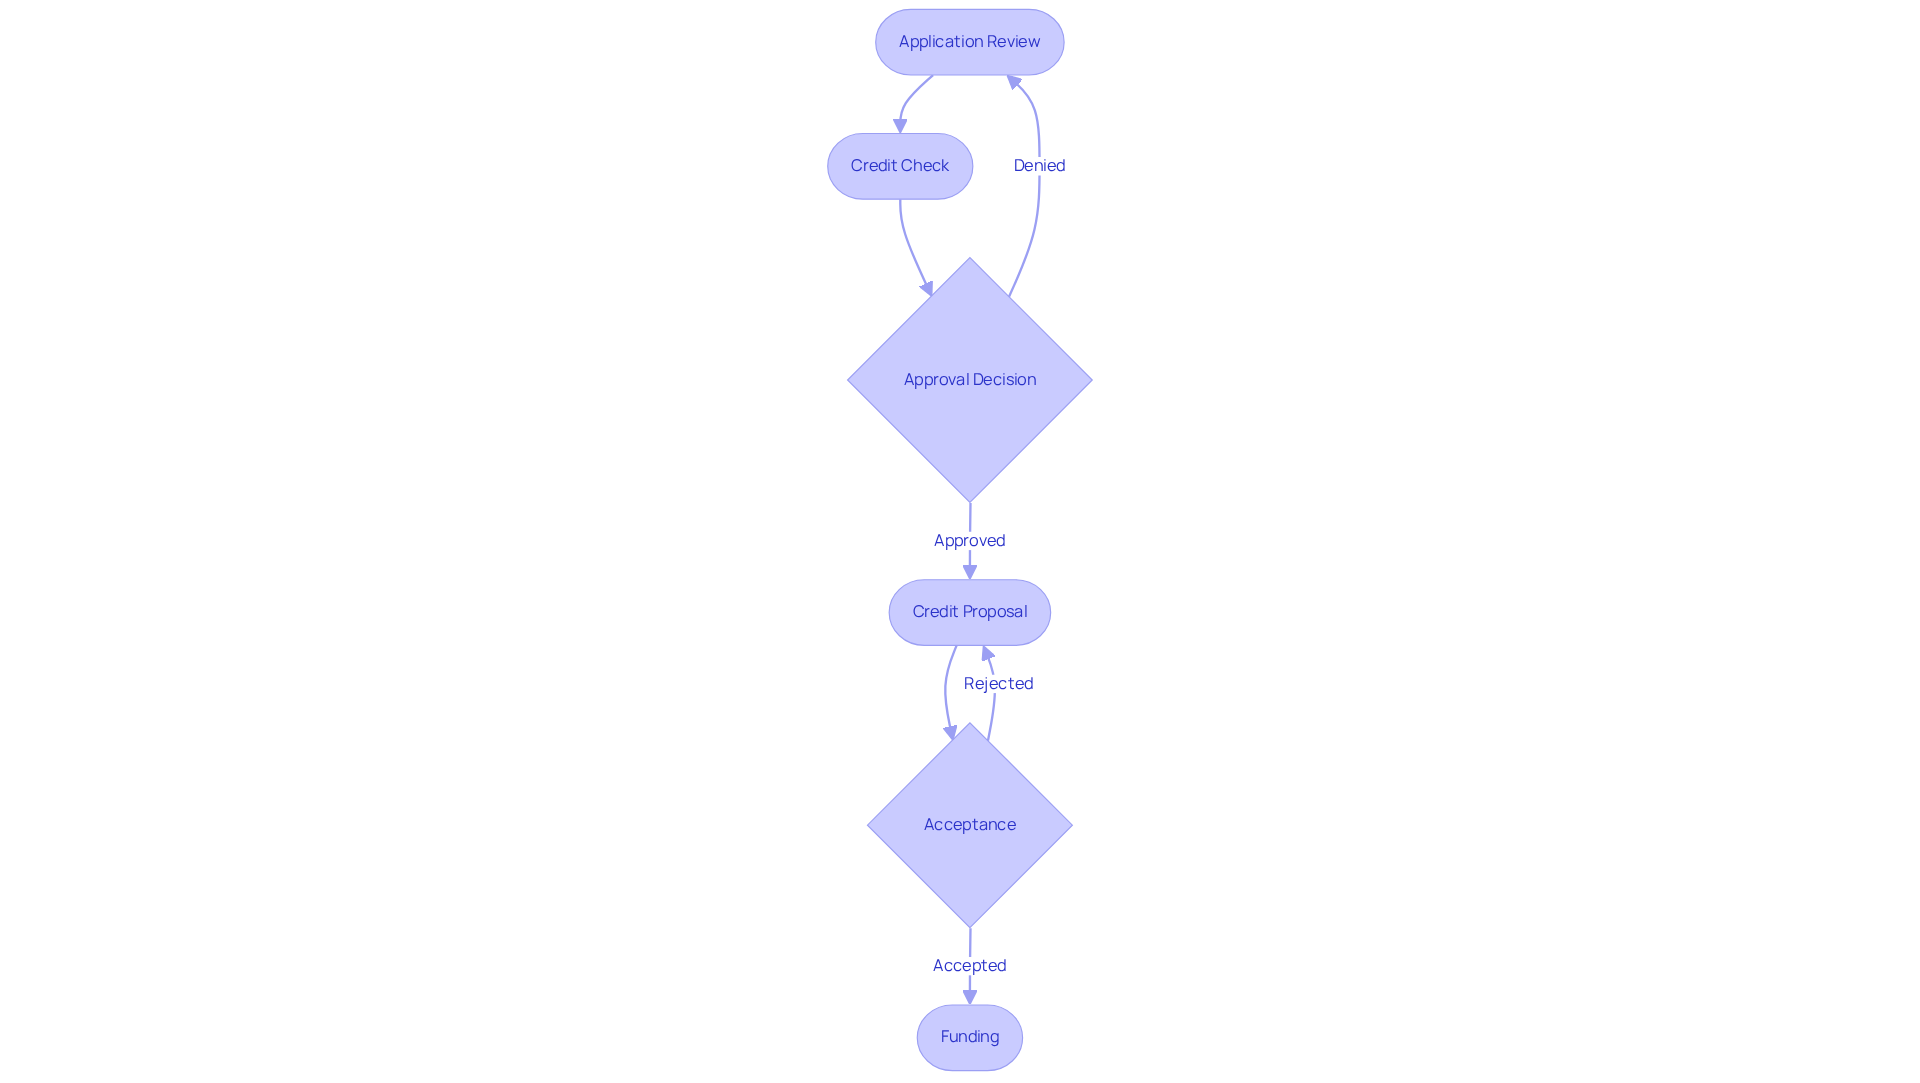
- The approval process includes application review, credit checks, and receiving a credit proposal outlining loan terms.
- Families should be proactive and organised to enhance their chances of securing favourable financing against RSUs.
Introduction
Navigating the financial landscape can feel overwhelming for young families, especially when it comes to understanding assets like Restricted Stock Units (RSUs). As more companies include RSUs in their compensation packages, knowing how to leverage these valuable assets for securing loans can truly make a difference in achieving financial stability.
Imagine if you could turn your RSUs into a stepping stone for your family’s future. Many families may find themselves asking: what are the steps to secure a loan against RSUs, and what challenges might they face along the way? This guide is here to walk you through the process, step by step, demystifying RSU-backed loans and empowering you to make informed decisions that align with your family’s financial goals.
Together, we can navigate this journey, ensuring that you feel supported every step of the way.
Understand Restricted Stock Units (RSUs)
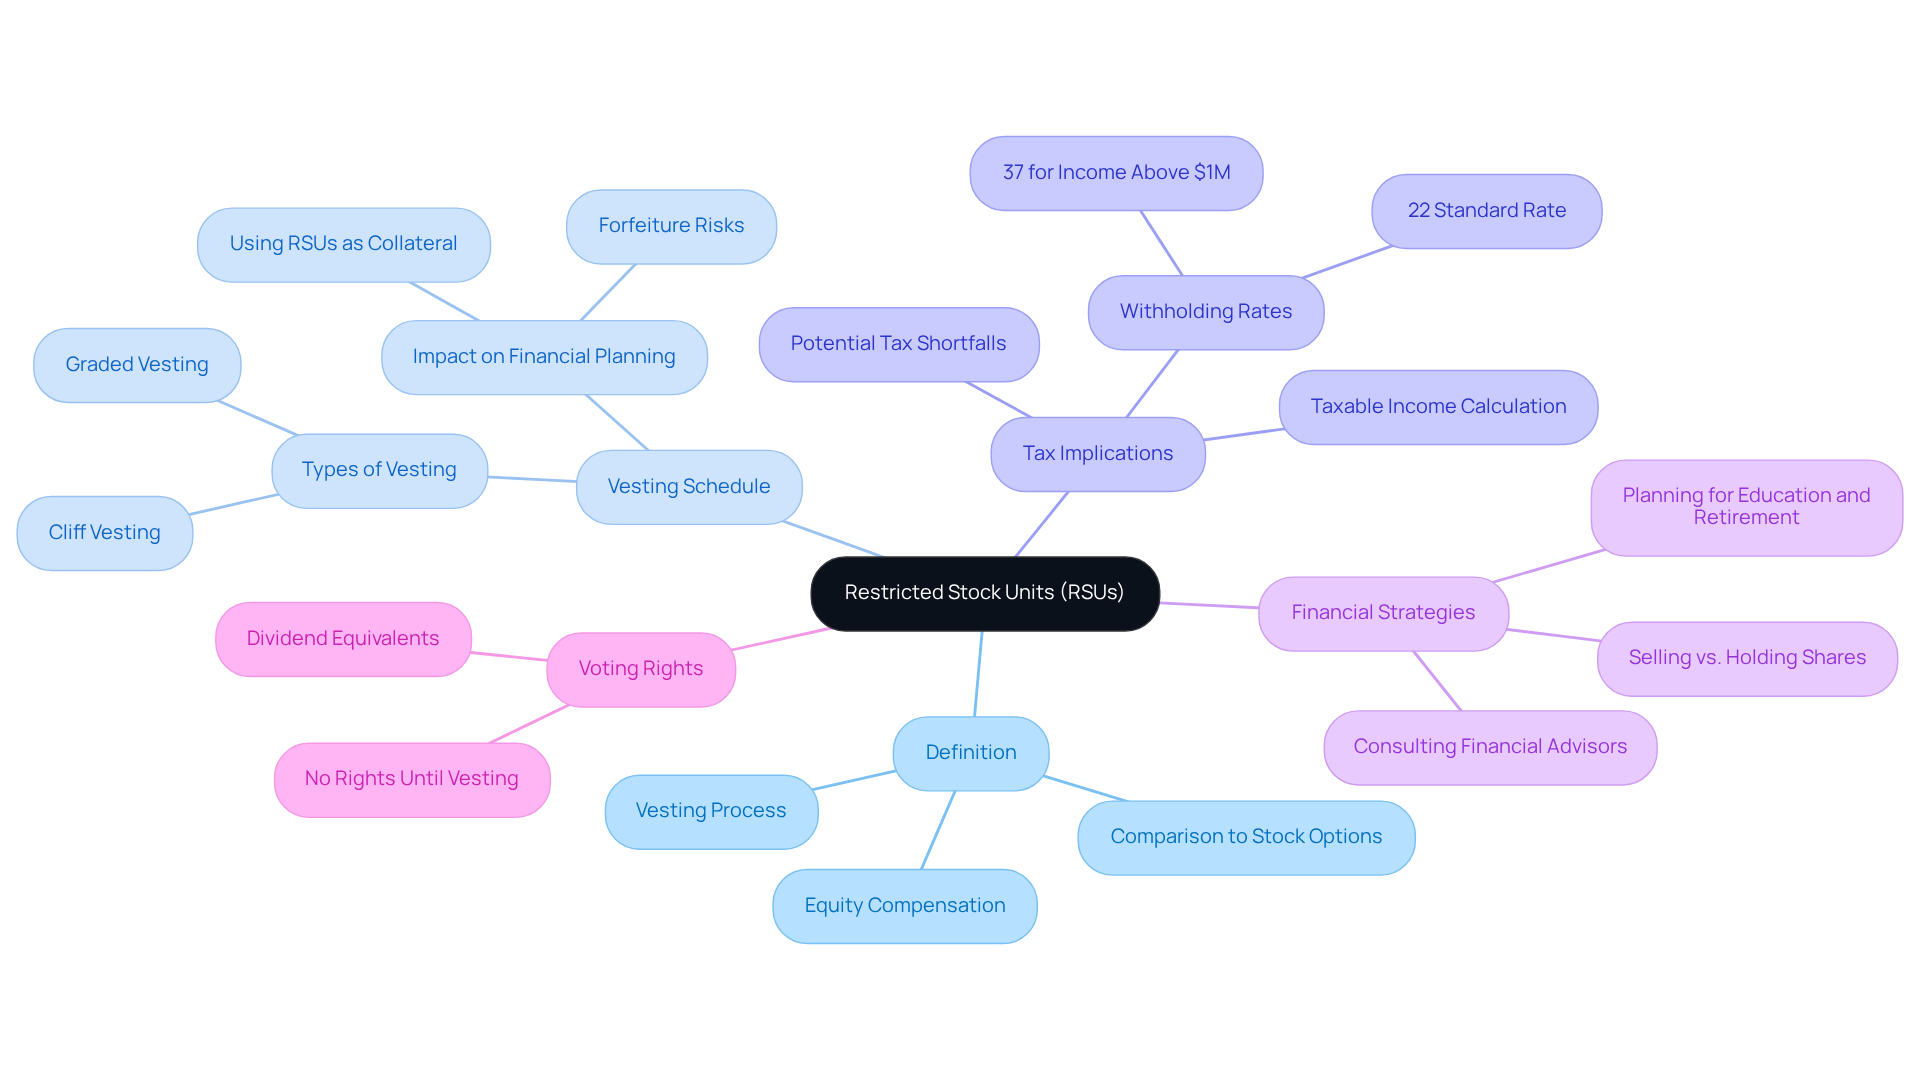
Restricted Stock Units (RSUs) are a popular form of equity compensation that employers offer to their employees. Unlike traditional stock options, which require you to purchase shares, RSUs are granted outright and vest over time or when specific performance milestones are met. Once they vest, RSUs convert into actual shares of stock or a cash equivalent, depending on the company’s policies. In 2026, more companies are choosing RSUs, as they provide clearer value to employees and help minimize risks.
Understanding the vesting schedule is crucial. It determines when your shares become accessible and can influence your budgeting. Imagine if you own RSUs that are set to vest within the next year; you might be able to use them as collateral for a loan, as long as you meet the lender’s requirements. This can be especially helpful for families like Jay and Emma, who turned to Bright Advisers for guidance. They wanted to ease their financial worries and allocate their resources wisely. By leveraging their stock options, they secured funding that helped them manage their financial obligations while preparing for their children’s education and their retirement.
It’s important to note that companies typically withhold 22% for taxes on vested RSUs, which can significantly affect your financial situation. Families like Emily and Mark, who are striving for economic independence and stability, found that understanding the implications of RSUs – including tax considerations and potential market fluctuations – empowered them to make informed decisions about utilizing these assets. Investment consultants emphasize the importance of grasping the nuances of RSUs, as this knowledge can greatly influence your financial strategies and outcomes.
Additionally, keep in mind that RSU recipients do not have voting rights or receive dividends until their shares vest. This is a key aspect to consider when planning your financial future. Remember, we’re here for you, and together, we can navigate this journey toward financial security.
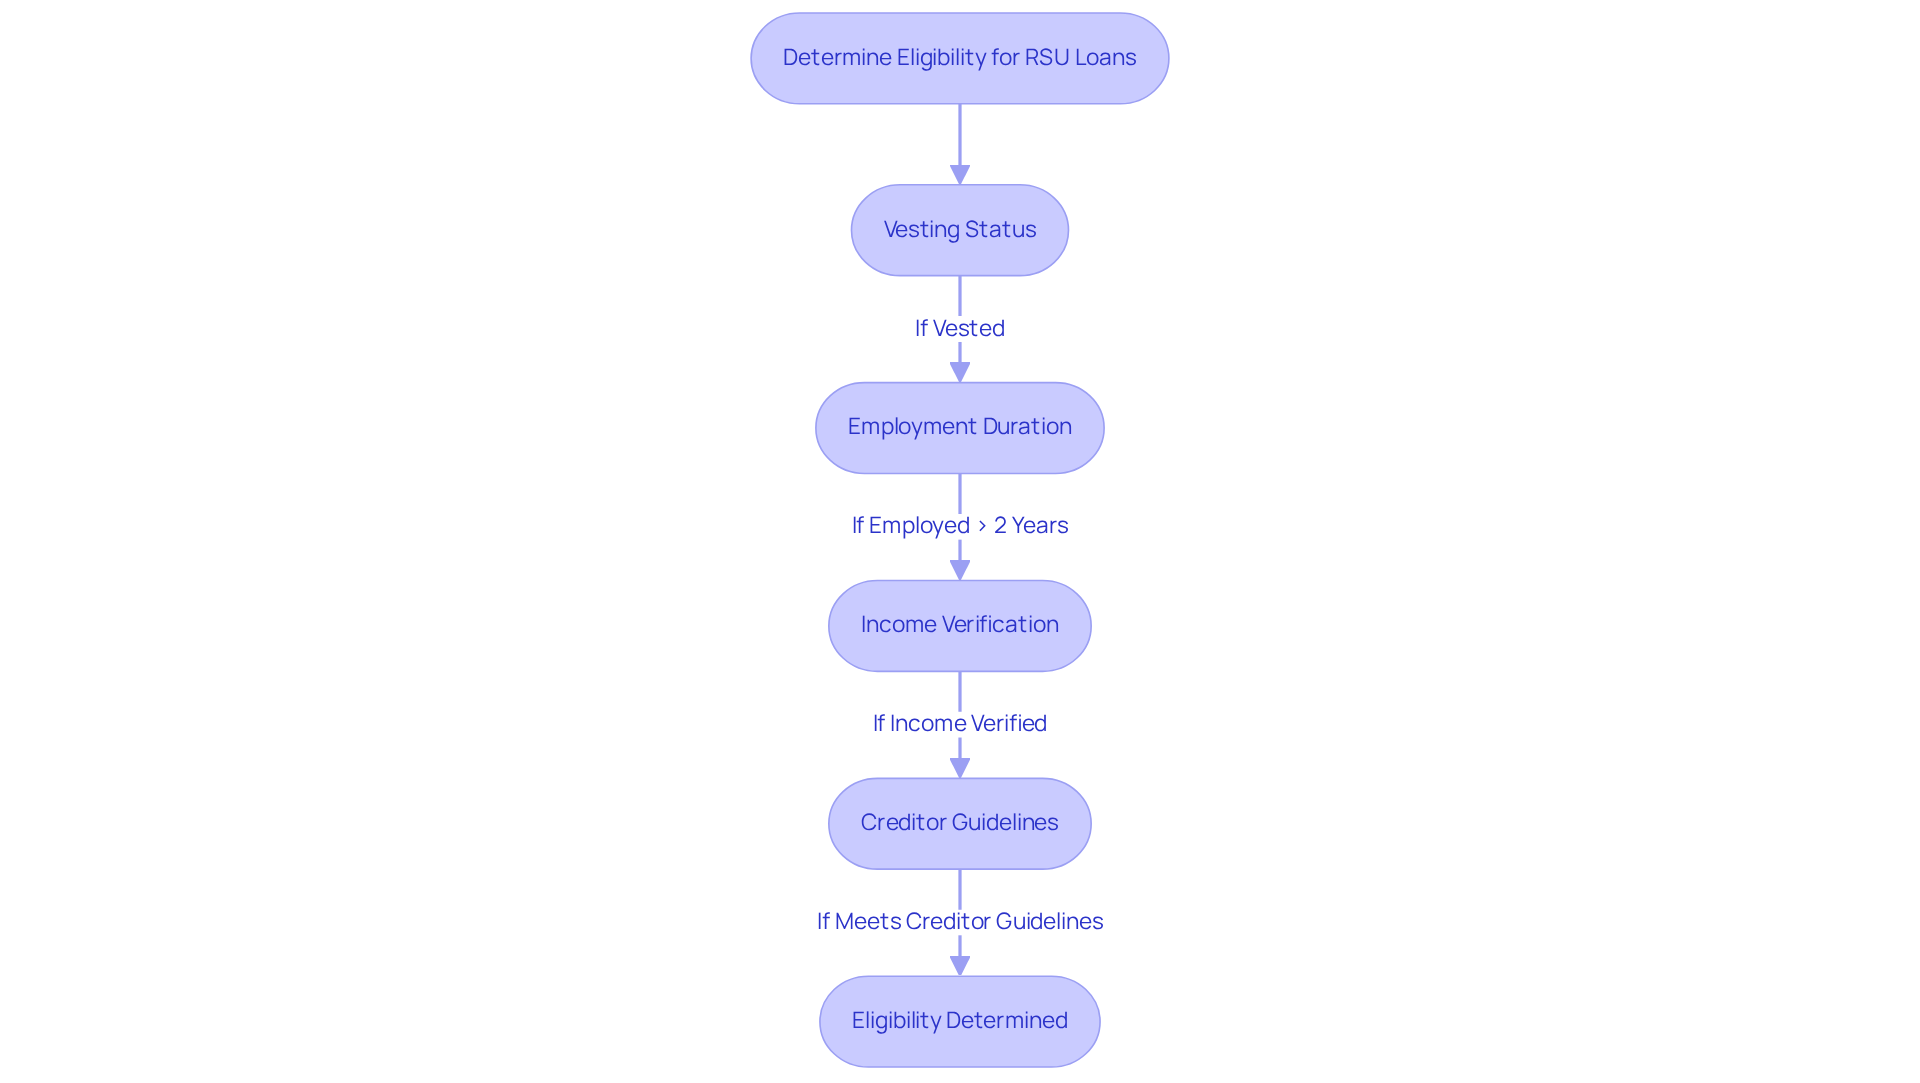
Determine Eligibility for RSU Loans
Navigating the world of loans can feel overwhelming, especially when it comes to your restricted stock units (RSUs). Let’s break down what you need to know to determine your eligibility for a loan against RSUs, which are valuable assets.
-
Vesting Status: First and foremost, it’s crucial to ensure that your RSUs are fully vested. Most financial institutions require this before they can be used as collateral. Think of it as a safety net for your family’s future.
-
Employment Duration: A stable employment history is essential. Financial institutions typically look for at least two years with your current employer to evaluate your income dependability. This stability can provide peace of mind as you plan for your family’s needs.
-
Income Verification: You’ll need to document your income, including tax returns and pay stubs. This is vital to demonstrate your financial stability. Remember, vested RSU income must be reported accurately, as it’s taxed as regular wage income when the shares vest.
-
Creditor Guidelines: Different creditors have distinct policies regarding restricted stock units. It’s important to research and consult with potential lenders to understand their specific requirements. Many organizations require a minimum two-year history of vesting and sale of RSUs for financing approval. They may also apply discounts of 10-25% to current projections based on stock price fluctuations.
Understanding these elements can greatly improve your chances of securing a loan against RSU. Together, we can navigate this journey and ensure your family’s financial future is secure.
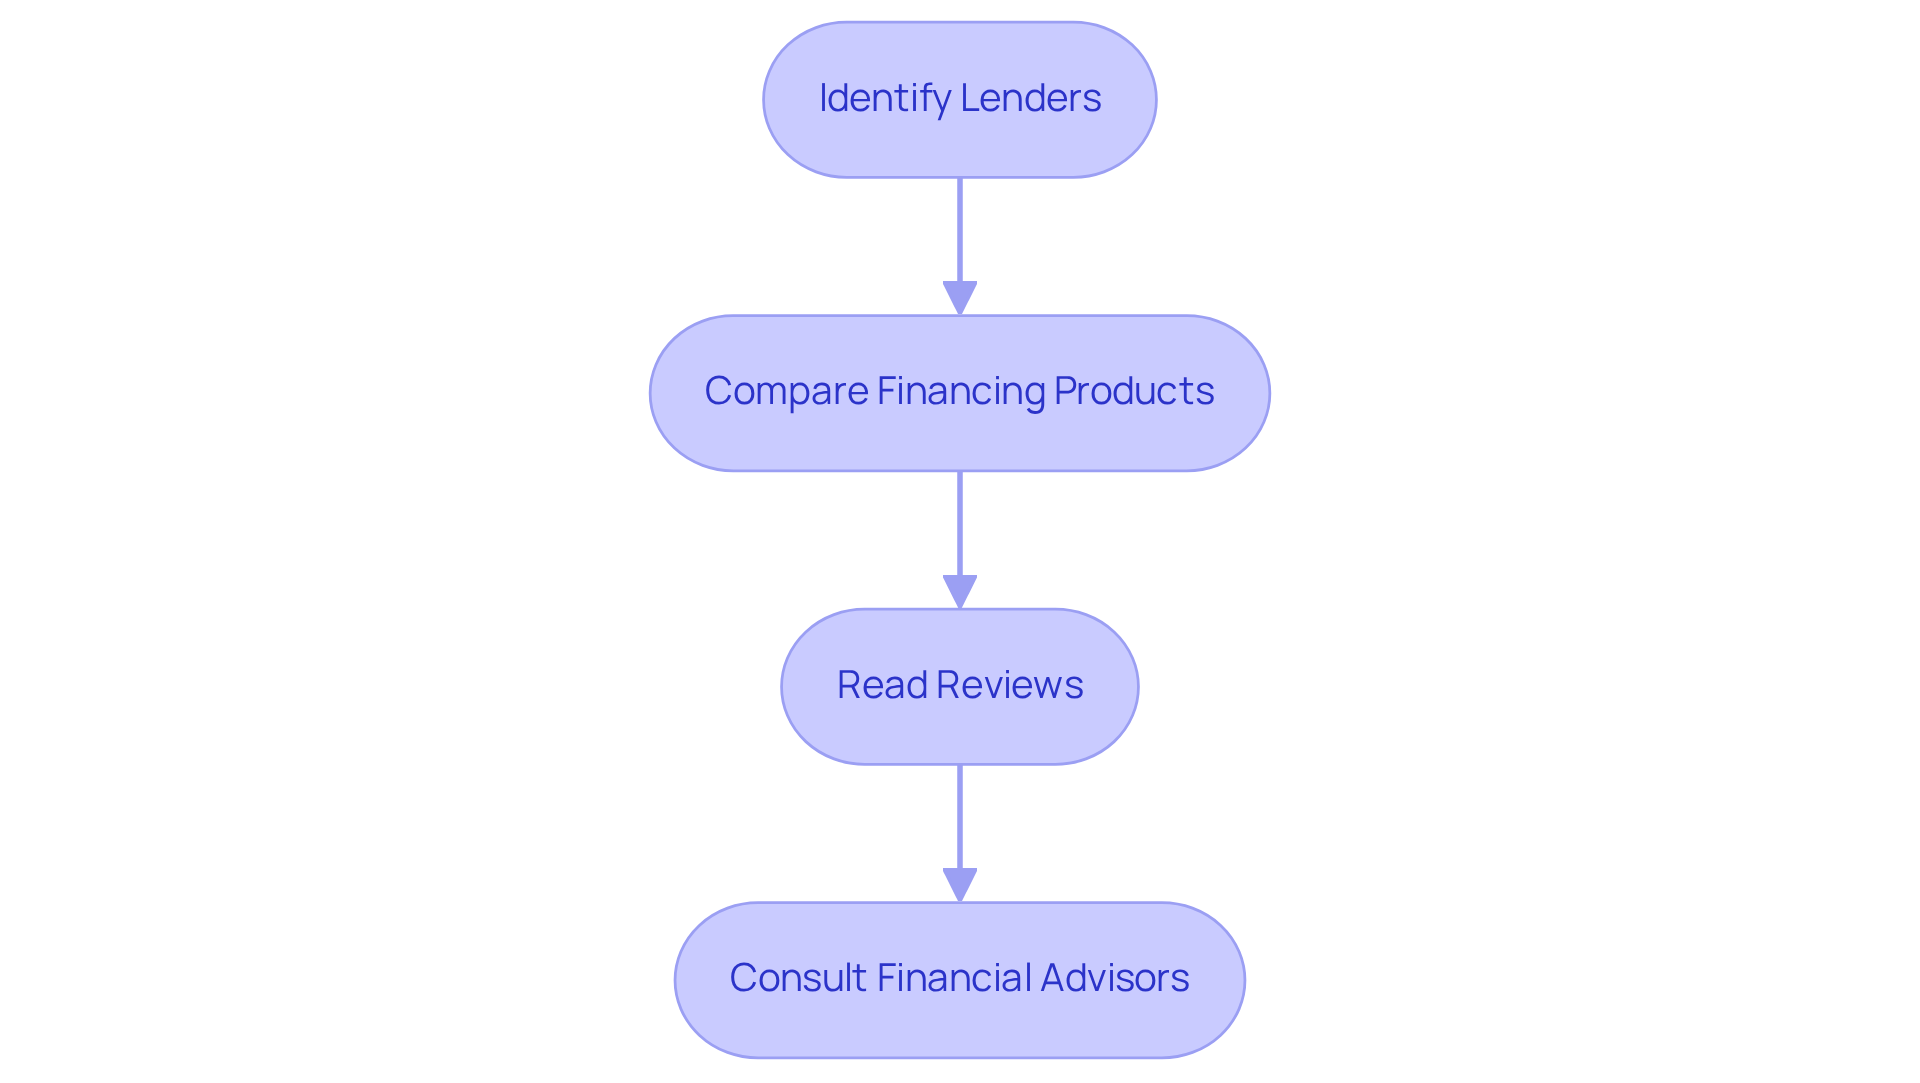
Research Lenders and Loan Options
When you’re looking for lenders to secure a loan against RSUs for financing your RSUs, it’s important to take a thoughtful approach.
- Identify Lenders: Start by seeking out banks and financial institutions that specialize in equity compensation financing. You might find that both online platforms and local banks offer different terms tailored for RSU holders.
- Compare Financing Products: Take the time to assess various financing options. Look closely at interest rates, repayment terms, and any associated fees. Some financial institutions even have specific programs designed for those with RSUs, which can include a loan against RSU that provides more favorable conditions. Remember, as Bright Advisers emphasizes, understanding the importance of minimal fund fees can enhance your wealth management accessibility and influence your choice of loan products.
- Read Reviews: Investigate customer reviews and ratings to get a sense of the lender’s reputation and the quality of their customer service. This can give you valuable insights into the experiences of other borrowers.
- Consult Financial Advisors: If you can, consider engaging with a financial advisor, like those at Bright Advisers. They can offer personalized guidance based on your unique financial circumstances. Their expertise can help you navigate the complexities of a loan against RSUs, ensuring you fully understand the implications of financing terms and conditions.
As you look ahead to 2026, it’s good to know that typical interest rates for personal financing against restricted stock units vary. For instance, credit unions might offer rates around 10.72% for three-year terms, while commercial banks average about 12.06%. Understanding these rates is crucial for making informed decisions. Financial specialists, such as Jack Caporal, highlight the importance of comparing credit products to secure the best conditions, especially for families weighing their options. For example, some lenders may accept a loan against RSUs of up to 100% of vested restricted stock units for affordability evaluations, making it essential to compare options and understand lender preferences.
However, it’s also vital to recognize the potential risks associated with a loan against RSUs, as it can lead to financial pressure if not managed carefully. By following these steps, families can better position themselves to secure favorable financing terms that align with their financial goals. Remember, we’re here for you, and together, we can navigate this journey.
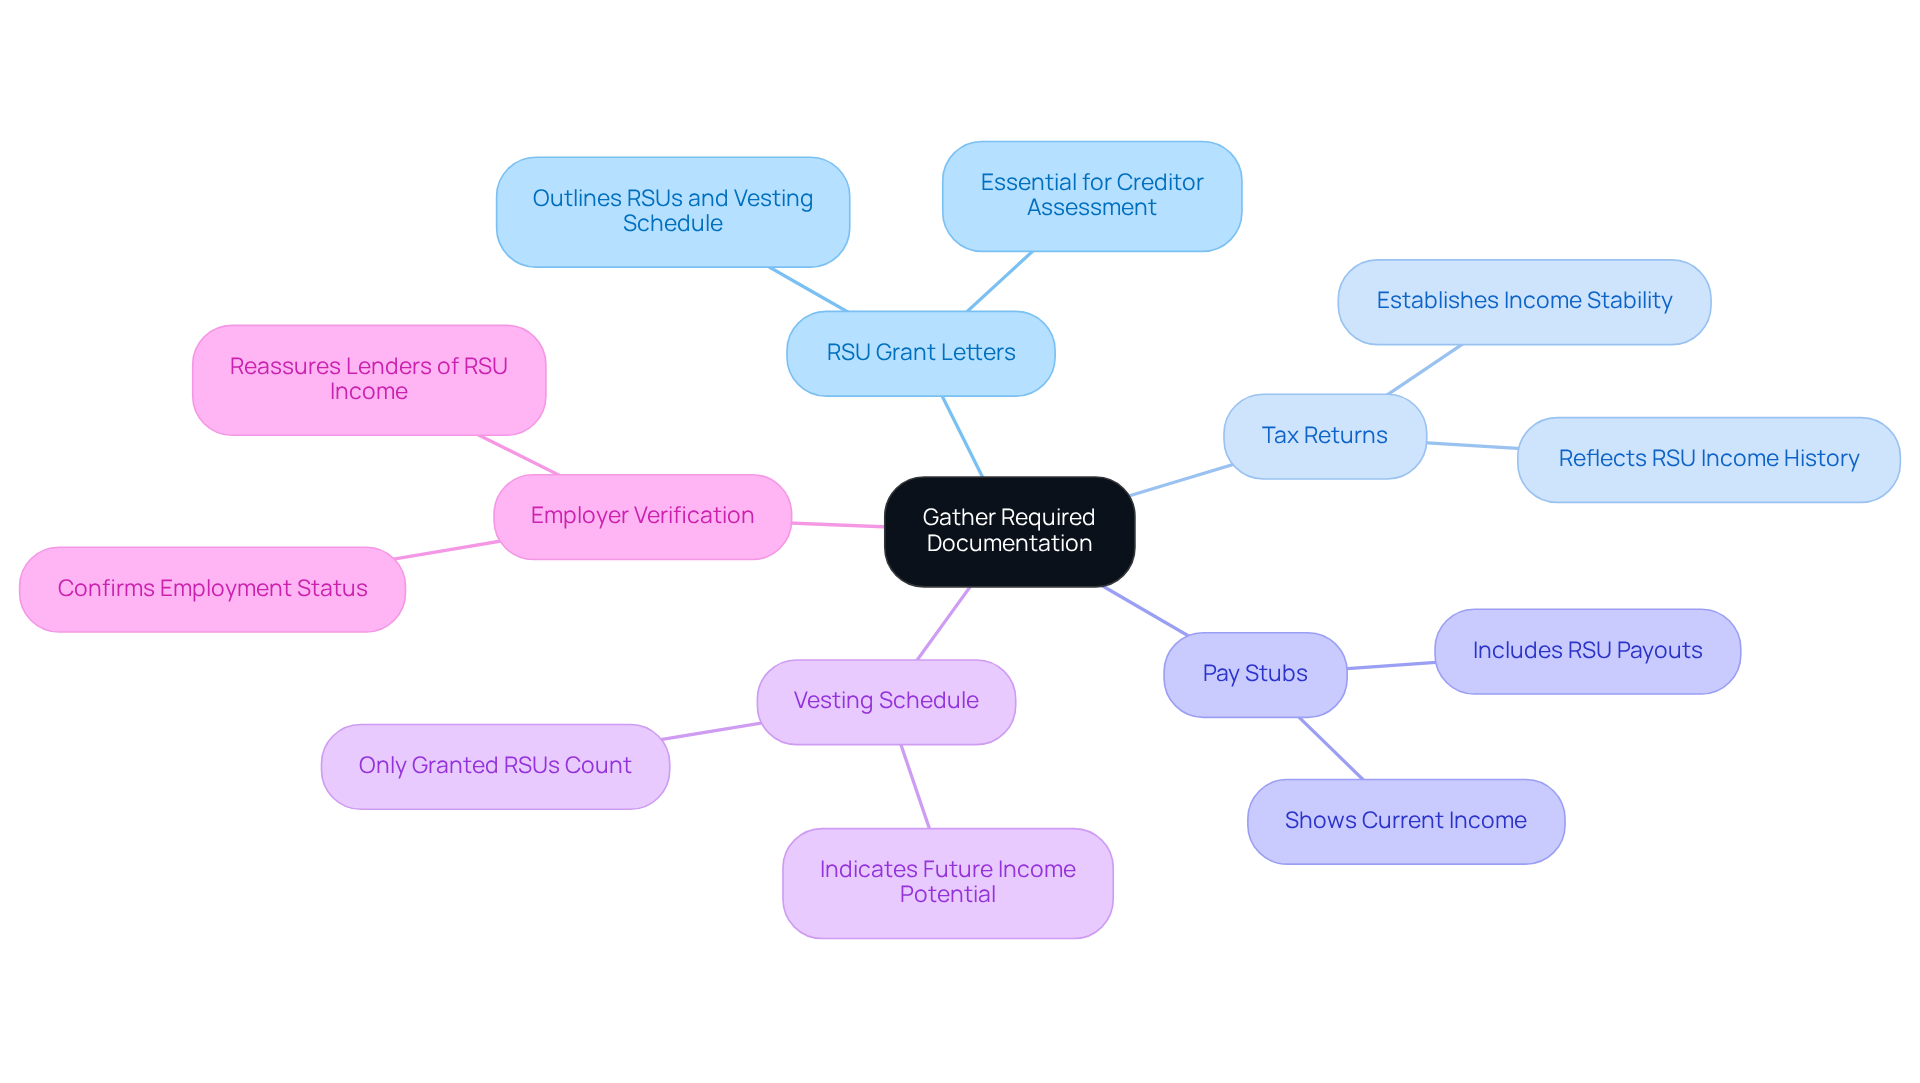
Gather Required Documentation
Navigating the world of loan against RSUs can feel overwhelming, especially for families. But don’t worry; we’re here to help you through this journey. To make the process smoother, it’s essential to gather a few key documents that will support your application.
-
RSU Grant Letters are your first step. These letters outline your RSUs, including the vesting schedule and the number of shares granted. Having a clear RSU grant letter is crucial, as it provides creditors with the information they need to assess your equity compensation. As Eric Bernstein points out, “Restricted Stock Units (RSU) account for a considerable share of compensation for numerous tech professionals and executives, but utilizing this equity income for mortgage approval necessitates understanding particular financial institution guidelines and documentation requirements.”
-
Next up are your Tax Returns. Make sure to include your tax returns for the past two years, reflecting any RSU income reported on your W-2 forms. This documentation helps establish your income history and stability. Lenders typically look for at least a two-year history of vested RSU income for mortgage qualification, so having this ready is important.
-
Don’t forget your Pay Stubs! Recent pay stubs that show your current income and any RSU payouts are vital. They give creditors a snapshot of your financial situation and ongoing earnings, which can make a big difference in your application.
-
A clear Vesting Schedule is also necessary. This document shows when your restricted stock units will vest and become accessible for use. Remember, only granted restricted stock units can be considered for mortgage purposes, so this schedule is essential for financial institutions to understand your future income potential.
-
Lastly, you may need Employer Verification. A letter from your employer confirming your employment status and the details of your restricted stock units can reassure lenders of your ongoing relationship with the company and the reliability of your RSU income.
Families looking for a loan against RSU should ensure they have all these documents ready. For instance, one family effectively gathered their RSU grant letters and tax returns, which greatly simplified their application process. By being organized and proactive, you can enhance your chances of securing the financing you need. Remember, together, we can navigate this journey and improve your approval outcomes.
Complete the Loan Application Process
Navigating the financing application process for a loan against RSU can feel overwhelming, but we’re here to assist you every step of the way. Here are some essential steps to guide you through this journey:
-
Select a Financial Institution: Take the time to find a financial entity that specializes in RSU financing. Look for one that offers favorable terms and understands the nuances of equity compensation. As Eric Bernstein, President and Co-Founder of LendFriend Mortgage, wisely points out, ‘Selecting a financial institution that comprehends RSUs can make a significant difference in your approval process.’
-
Submit Your Application: Fill out the loan application form with accurate and thorough information. This is your chance to present your financial story clearly.
-
Attach Documentation: Gather all necessary documents, like pay stubs, W-2 forms, and proof of RSU vesting. Make sure everything is clearly labeled for easy reference. Remember, RSU grants can represent 30% to 70% of your total annual compensation, so it’s vital to showcase this information effectively.
-
Follow Up: After you submit your application, don’t hesitate to reach out to the financial institution. Confirm they received your application and ask about the approval timeline. This shows your commitment and keeps you informed.
-
Prepare for Questions: Be ready to answer any additional questions the lender may have about your financial situation or your RSUs. This is a normal part of the process, and being prepared can ease your mind.
For extra support, consider using the interactive PDF and tutorial video available for RSU calculations. By following these steps, you can enhance your chances of securing financing that aligns with your family’s financial goals. Remember, loan against RSU financing programs offer flexibility, including shorter seasoning requirements for new RSUs. Together, we can navigate this journey and find the best path for your family’s future.
Understand Approval Process and Next Steps
When you submit your loan application, it’s natural to wonder what happens next. Here’s a gentle guide to help you understand the process:
-
Application Review: Your financial institution will carefully evaluate your application and the supporting documents. This step is all about determining your eligibility, so you can feel confident in the process.
-
Credit Check: A credit check will be conducted to assess your creditworthiness. This is a crucial step, and it’s important to know that it helps the lender understand your financial background.
-
Approval Decision: Based on your financial profile and the value of your Restricted Stock Units (RSUs), the lender will make a decision regarding your application. This is a significant moment, and we’re here to support you through it.
-
Credit Proposal: If you’re approved, you’ll receive a credit proposal outlining the terms, including interest rates and repayment schedules. Take your time to review this offer; it’s designed to meet your needs.
-
Acceptance: Carefully consider the proposal. If it aligns with your family’s goals, accept the financial agreement and complete any necessary signatures. Remember, this is a step towards securing your family’s future.
-
Funding: After acceptance, the lender will disburse the funds, allowing you to utilize the loan as intended. This is an exciting moment, as it opens doors for your family’s aspirations.
Together, we can navigate this journey, ensuring that your financial decisions align with your family values and priorities.
Conclusion
Navigating the process of securing a loan against Restricted Stock Units (RSUs) can be a wonderful opportunity for young families to leverage their equity compensation for financial stability. Imagine if you could turn your hard-earned RSUs into a stepping stone for your family’s future. By understanding the intricacies of RSUs – like their vesting schedules, tax implications, and loan eligibility criteria – you can make informed decisions that truly align with your long-term goals.
Throughout this guide, we’ve shared key insights to help you on this journey. From gathering necessary documentation to comparing lenders and understanding the loan application process, each step is crucial. It’s important to assess your financial situation carefully and consider engaging with financial advisors who can guide you toward the best loan options available. While the journey may seem daunting, remember that with the right knowledge and preparation, you can make empowered financial choices.
Ultimately, taking the step to secure a loan against RSUs can open doors to significant milestones – whether it’s funding your children’s education or planning for a comfortable retirement. As you explore this financing avenue, stay proactive, informed, and ready to seize the opportunities that come your way. Embracing this approach can lead to a brighter financial future, reinforcing the idea that understanding and utilizing RSUs effectively can truly be a game changer for your family’s well-being. Together, we can navigate this journey toward financial empowerment.
Frequently Asked Questions
What are Restricted Stock Units (RSUs)?
Restricted Stock Units (RSUs) are a form of equity compensation granted by employers to employees. Unlike stock options, RSUs are given outright and vest over time or upon achieving specific performance milestones. Once vested, they convert into actual shares of stock or a cash equivalent.
How do RSUs vest, and why is the vesting schedule important?
RSUs vest over a set period or when certain performance goals are met. Understanding the vesting schedule is crucial as it determines when shares become accessible, which can influence financial planning and budgeting.
What tax implications should I be aware of regarding RSUs?
Companies typically withhold 22% for taxes on vested RSUs, which can significantly impact your financial situation. It’s important to understand these tax considerations when planning your finances.
Do RSU recipients have voting rights or receive dividends before the shares vest?
No, RSU recipients do not have voting rights or receive dividends until their shares vest.
What factors determine eligibility for a loan against RSUs?
Eligibility for a loan against RSUs depends on several factors: the RSUs must be fully vested, the employee should have a stable employment history (typically at least two years), and income verification is required, including documentation like tax returns and pay stubs.
What do creditors consider when evaluating loans against RSUs?
Creditors have different policies regarding RSUs. They often require a minimum two-year history of vesting and sale of RSUs for financing approval and may apply discounts of 10-25% to current projections based on stock price fluctuations.
How can understanding RSUs benefit my financial planning?
Understanding the nuances of RSUs, including their vesting schedules, tax implications, and market fluctuations, can empower individuals to make informed decisions about utilizing these assets for better financial outcomes.
List of Sources
- Understand Restricted Stock Units (RSUs)
- Biotech Equity Trends: RSUs Rise Amid Market Shifts (https://paygovernance.com/resource/biotech-industry-trends-in-equity-compensation-influence-of-market-volatility-on-equity-program-strategy)
- How Do Restricted Stock Units (RSUs) Work? | 7 Key Points (https://twotenplanning.com/blog/how-do-restricted-stock-units-rsus-work)
- Equity Trends 2026: How Long-Term Incentives Are Changing (https://sequoia.com/2026/01/equity-trends-2026-long-term-incentives)
- A Guide To Restricted Stock Units (RSUs): Key Points You Must Know (https://mystockoptions.com/articles/restricted-stock-units-rsus-checklist-of-key-points-to-know)
- Determine Eligibility for RSU Loans
- RSU Income for Mortgages: Lender Guidelines (https://lendfriendmtg.com/learning-center/rsu-income-guidelines-mortgages)
- Restricted stock units (RSU) income: how to review & calculate (https://getblueprint.io/restricted-stock-units-rsu-income-how-to-review-calculate)
- Using RSUs to Qualify for a Mortgage: The Complete Guide for 2025 – Bridgepoint Funding (https://bpfund.com/using-rsus-to-qualify-for-a-mortgage-the-complete-guide-for-2025)
- Research Lenders and Loan Options
- Which lenders offer Restricted Stock Unit or RSU Income mortgages? : Trinity Financial, Mortgage Brokers in London. (https://trinityfinancialgroup.co.uk/mortgage-tools/mortgage-news/How-do-i-get-an-RSU-income-mortgage)
- Current HELOC Rates In March 2026 | Bankrate (https://bankrate.com/home-equity/heloc-rates)
- Restricted Stock & RSUs: 3 Planning Tips From Top Financial Advisors (https://forbes.com/sites/brucebrumberg/2021/06/17/restricted-stock–rsus-3-planning-tips-from-top-financial-advisors)
- Personal loan debt statistics (https://fool.com/money/research/personal-loan-statistics)
- Average Personal Loan Interest Rates in March 2026 | Bankrate (https://bankrate.com/loans/personal-loans/average-personal-loan-rates)
- Gather Required Documentation
- Can RSUs be used as Income for a Home Loan? (https://carlylefinancial.com/blog/rsu-mortgage-from-use-restricted-stock-units-buy-home)
- RSU Income for Mortgages: Lender Guidelines (https://lendfriendmtg.com/learning-center/rsu-income-guidelines-mortgages)
- Underwriting Loans with Restricted Stock Units as Income – Enact’s Discover360℠ (https://blog.enactmi.com/post/underwriting-loans-with-restricted-stock-units-as-income)
- Using RSUs to Qualify for a Mortgage: The Complete Guide for 2025 – Bridgepoint Funding (https://bpfund.com/using-rsus-to-qualify-for-a-mortgage-the-complete-guide-for-2025)
- Complete the Loan Application Process
- RSU review and calculation tool (https://mgic.com/mortgage-connects/rsu-review-and-calculation-tool)
- Underwriting Loans with Restricted Stock Units as Income – Enact’s Discover360℠ (https://blog.enactmi.com/post/underwriting-loans-with-restricted-stock-units-as-income)
- RSU Loan Programs Explained: Complete Guide (https://lendfriendmtg.com/learning-center/rsu-loan-programs)
- Summary of 2022 Data on Mortgage Lending | Consumer Financial Protection Bureau (https://consumerfinance.gov/data-research/hmda/summary-of-2022-data-on-mortgage-lending)
- Understand Approval Process and Next Steps
- 10 Quotes About Finance & Credit (https://creditonebank.com/articles/10-famous-quotes-about-finances-credit)
- US HY and Loan Default Rates Rise Modestly, Credit Conditions Stay Constructive (https://fitchratings.com/research/corporate-finance/us-hy-loan-default-rates-rise-modestly-credit-conditions-stay-constructive-17-02-2026)
- 2026 Report on Employer Firms: Findings from the 2025 Small Business Credit Survey (https://fedsmallbusiness.org/reports/survey/2026/2026-report-on-employer-firms)
- Credit Score Quotes (18 quotes) (https://goodreads.com/quotes/tag/credit-score)

Kevin has advised high-income W-2 tech and biotech families since 2015, and leads the education-first Age Five Family Office from Brea, California.
Connect on LinkedIn → · About KevinThis is part of how we approach Tax Management for high-income W-2 families at Bright Advisers.
Keep reading