

Overview
Understanding the differences between Sell to Cover and Same Day Sale can be crucial for your family’s financial health. These two strategies vary in liquidity, tax implications, and investment approaches. With Sell to Cover, you can retain shares for future growth, which can be comforting as you think about your family’s long-term goals. On the other hand, Same Day Sale offers immediate cash flow, which might be what you need for pressing expenses.
Imagine if you could minimize your immediate tax liabilities while still supporting your family’s future. Sell to Cover does just that, allowing you to invest in your family’s dreams without the stress of high tax burdens. Conversely, Same Day Sale, while providing quick cash, can lead to higher taxable income since it involves selling all vested shares at once. This is why it’s so important to assess your financial needs and market conditions carefully.
Together, we can navigate these decisions. Remember, your family’s priorities matter, and we’re here to support you every step of the way.
Key Highlights:
- Sell to Cover involves selling a portion of vested RSUs to cover tax obligations, allowing retention of remaining shares for future growth.
- Same Day Sale entails selling all vested stocks immediately, providing cash to cover taxes and expenses.
- Liquidity is a key consideration; Sell to Cover supports long-term investment, while Same Day Sale provides immediate cash flow.
- Tax implications differ: Sell to Cover may avoid capital gains tax on sold units, while Same Day Sale adds total proceeds to taxable income.
- High-income individuals may face higher tax rates; understanding these implications is crucial for effective financial planning.
- Choosing between the two strategies should reflect personal financial situations, market conditions, and individual risk tolerance.
- Consulting with a financial advisor can help optimise tax obligations and investment strategies.
Introduction
Navigating the complexities of stock options can be particularly challenging for families striving to secure their financial future. Among the various strategies available, the comparison between sell to cover and same day sale emerges as a pivotal decision point that can significantly influence both liquidity and tax implications.
Imagine if you could manage your tax obligations while still holding onto shares for potential growth. Sell to cover offers that opportunity. On the other hand, same day sale provides immediate cash flow, which may be essential for more urgent financial needs.
How does one choose between these two approaches, especially when the stakes involve both immediate cash and long-term investment potential? It’s important to understand that this decision can shape not just your finances, but your family’s future as well.
Together, we can navigate this journey and find the best path forward.
Understanding Sell to Cover and Same Day Sale
Navigating the world of stock options can feel overwhelming, especially for young parents focused on their family’s future. One strategy to consider is the comparison of sell to cover vs same day sale methods. This approach allows you to sell a portion of your vested Restricted Stock Units (RSUs) specifically to meet tax withholding obligations at the time of vesting. By doing so, you can keep the remaining shares for potential future growth. For instance, if you have 100 stocks vesting with a tax obligation of $1,000, you might sell 10 stocks at $100 each. This way, you cover the tax while retaining 90 stocks for future possibilities.
On the other hand, there’s the option of sell to cover vs same day sale. This involves selling all vested stocks immediately upon vesting, providing you with cash to cover taxes and other expenses. Using the same example, in a Same Day Sale, you would sell all 100 shares, receiving $10,000 in cash to pay the tax obligation.
Choosing between sell to cover vs same day sale methods can have a significant impact on your liquidity, tax implications, and overall investment strategy. The comparison of sell to cover vs same day sale shows that while sell to cover allows for continued investment in the company’s stock, a same day sale provides immediate cash flow, which can be crucial for managing short-term financial needs. Understanding these distinctions is essential for anyone managing stock options, particularly for families aiming to enhance their financial strategies with expert guidance.
Key Considerations:
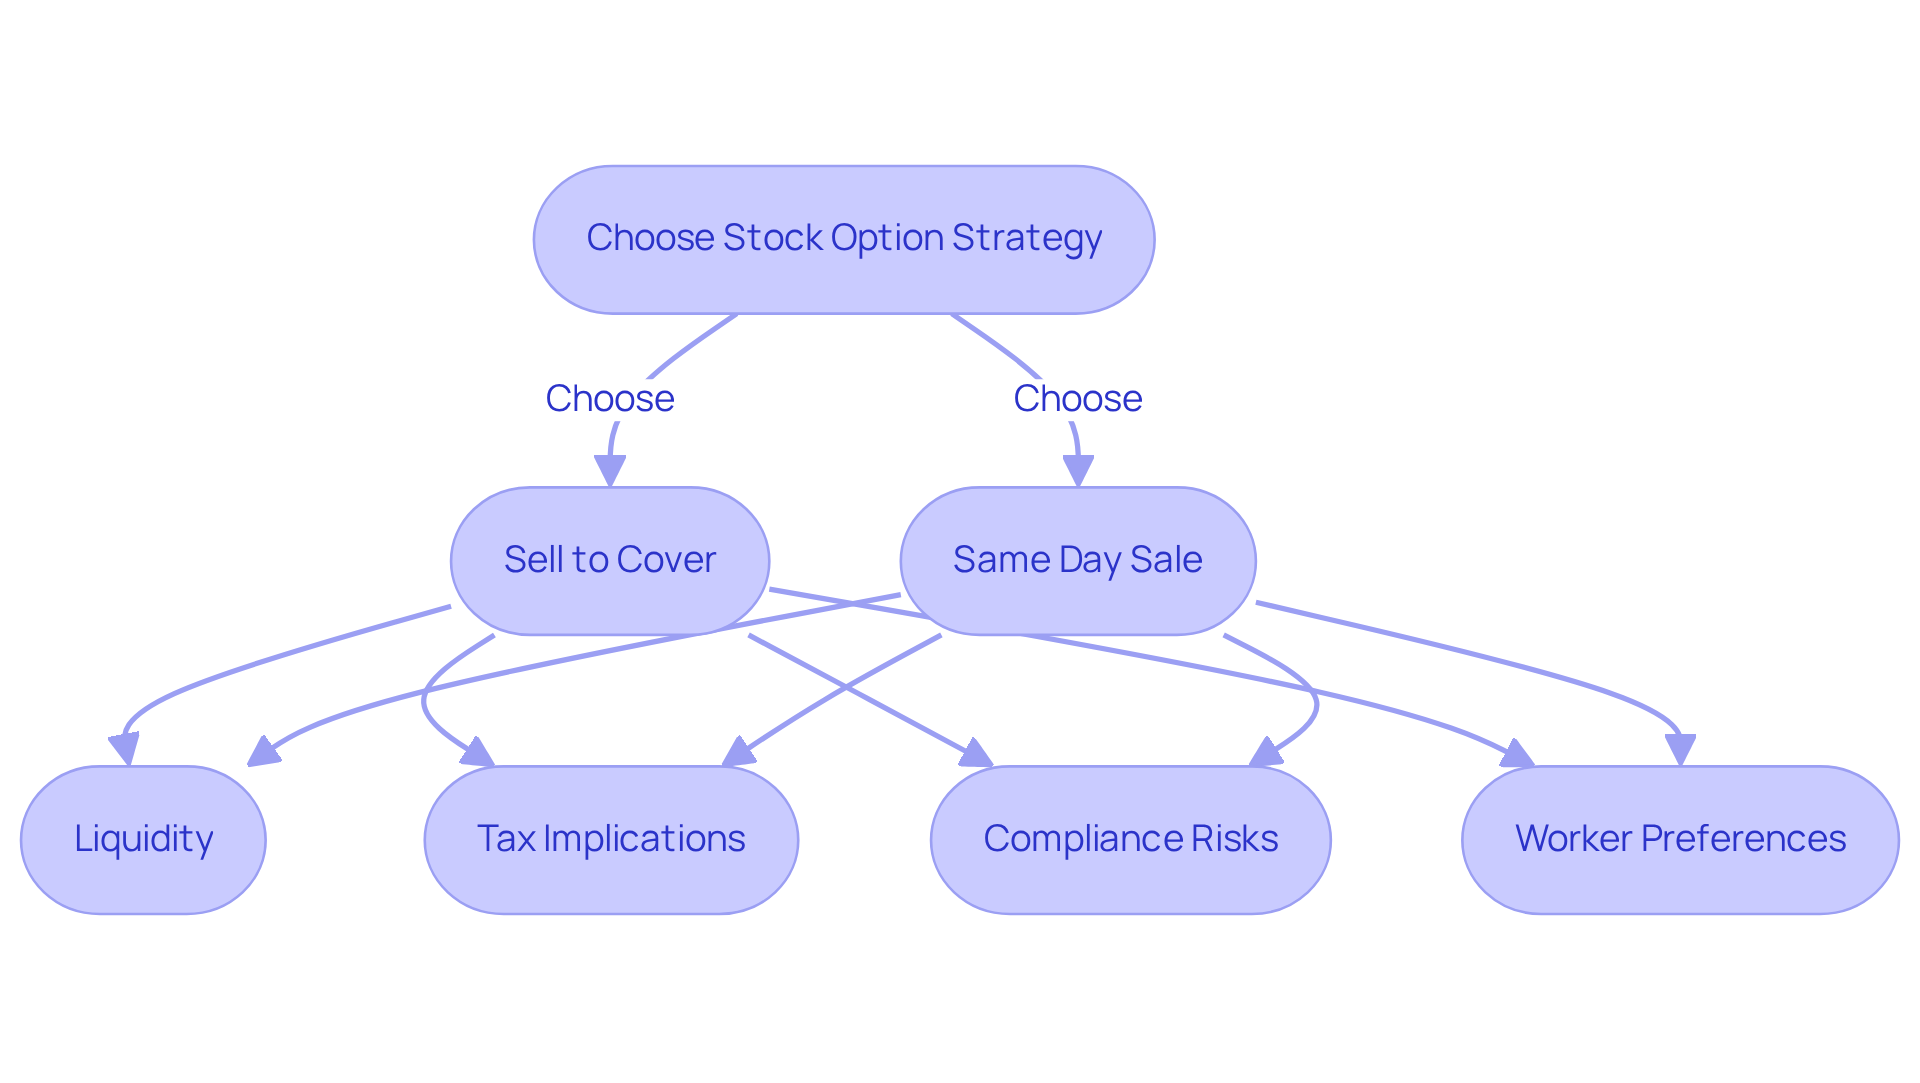
- Liquidity: Sell to Cover supports ongoing investment in the company’s stock, beneficial for long-term wealth accumulation, while a Same Day Sale offers immediate cash flow, which is crucial for short-term financial needs.
- Tax Implications: It’s vital to understand the tax consequences of each method, especially for high-income families. Companies must disclose to all shareholders before sales exceeding $10 million in a 12-month period, and failing to provide timely disclosures can jeopardize the Rule 701 exemption for all options or stock granted.
- Compliance Risks: Transactions exempt from registration under Rule 701 are still subject to anti-fraud provisions of federal securities laws, which may require substantial disclosure.
- Worker Preferences: Statistics show that many workers prefer the sell to cover vs same day sale strategies, reflecting a common practice that can influence decision-making.
Together, we can navigate this journey and make informed choices that align with your family’s financial goals.
Tax Implications of Sell to Cover vs Same Day Sale
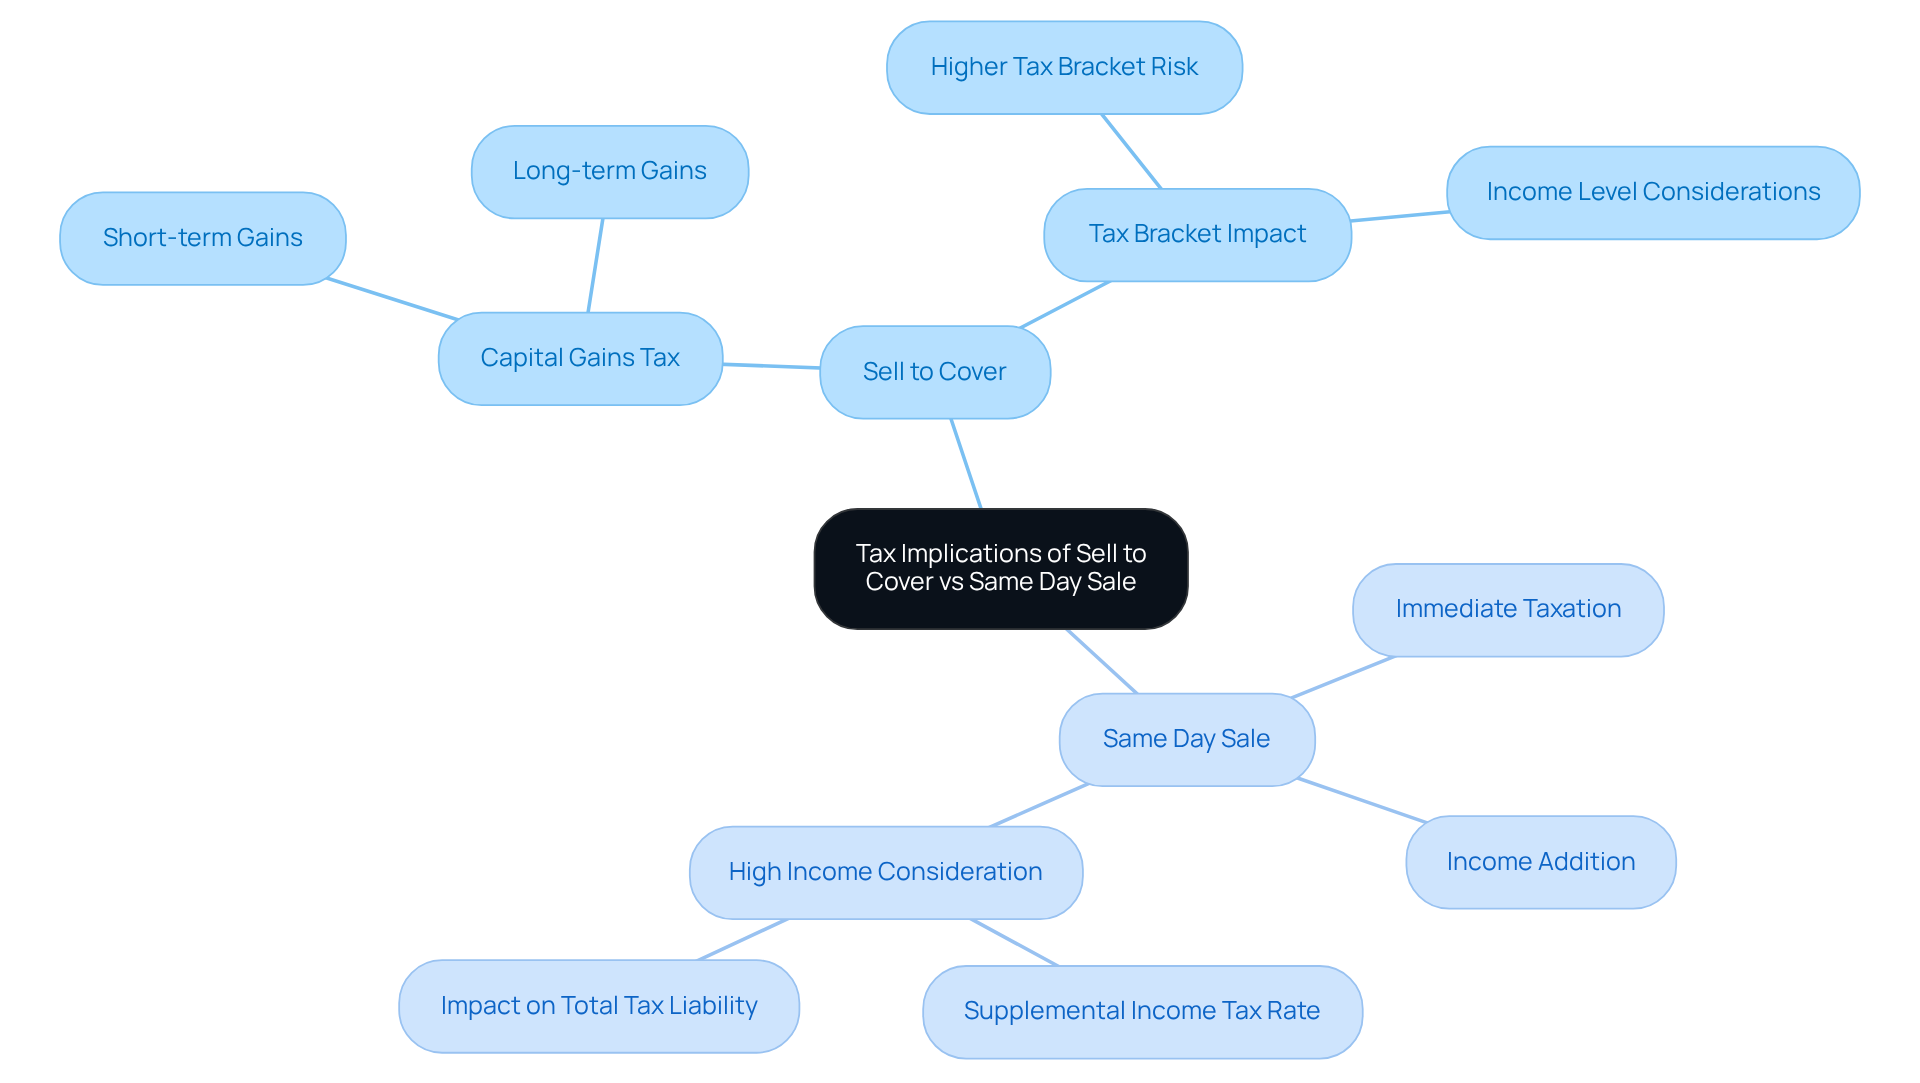
Understanding the tax implications of sell to cover vs same day sale transactions is crucial for your financial well-being. In the context of sell to cover vs same day sale, the units sold to cover taxes are typically not subject to capital gains tax at the moment of sale, as they are considered part of your income. However, any remaining stocks may incur capital gains tax when sold later, depending on how long you’ve held them. For example, if you sell stocks within a year of acquiring them, you might face short-term capital gains tax, which is taxed at regular income rates.
Imagine if you chose a sell to cover vs same day sale instead. This would mean immediate taxation on the total proceeds from selling your stocks, particularly when considering the implications of sell to cover vs same day sale, which are classified as ordinary income. Such a decision could elevate you into a higher tax bracket based on your overall annual income. For instance, if you engage in a sell to cover vs same day sale of stocks valued at $10,000, this amount is added to your taxable income for the year, potentially leading to a significant increase in your tax obligation. It’s important to note that individuals with an income exceeding $1 million may face a supplemental income withholding rate of 37%, which can further impact their tax responsibilities.
Navigating these implications is essential for effective tax planning. Take Mr. Jones, for instance, to understand the difference between sell to cover vs same day sale. After a sell to cover vs same day sale transaction, his total taxable income stands at $51,000, which demonstrates how utilizing this method can help manage tax liabilities. As a parent, you should consider strategies to manage your tax obligations, such as timing your sales or consulting with a financial advisor to optimize your after-tax income. Together, we can navigate the complexities of RSU taxation and make informed decisions that align with your family’s financial goals.
Remember, we’re here for you. By being proactive and informed, you can take control of your financial journey and ensure a brighter future for your family.
When to Use Sell to Cover or Same Day Sale: Practical Scenarios
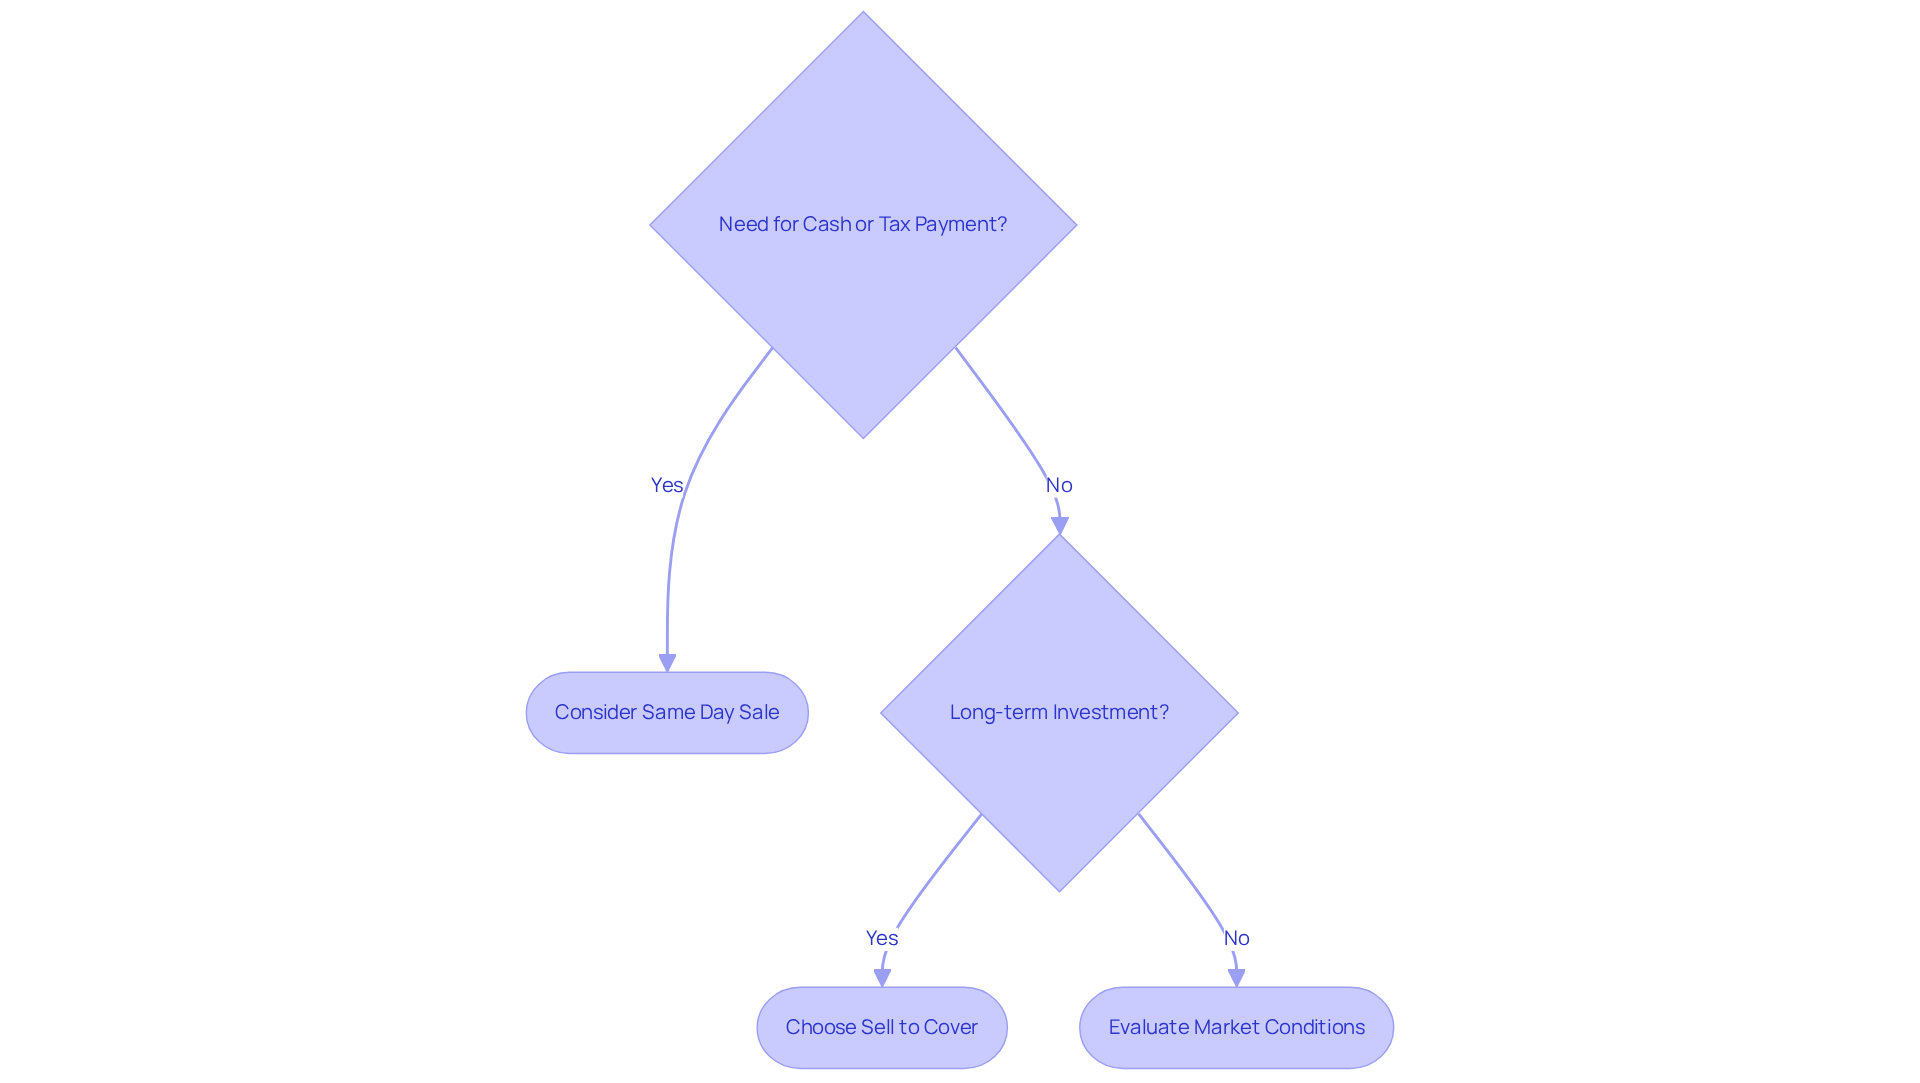
When deciding between Sell to Cover vs Same Day Sale, it’s essential to consider your personal financial situation and the current market dynamics. Imagine you’re a parent who believes your company’s stock will soar. Choosing between sell to cover vs same day sale enables you to retain more shares for future growth while responsibly managing your tax obligations. This strategy is especially beneficial for long-term investors who trust in their company’s potential. As Mark Nicolosi wisely points out, “The sell-to-cover approach is tax-efficient in numerous scenarios, particularly when liquidating all of your holdings would elevate you into a higher tax bracket.”
On the flip side, if you find yourself in need of immediate cash to cover expenses or tax liabilities, you may want to evaluate the sell to cover vs same day sale options as the better choice. This choice offers liquidity, helping you meet your financial responsibilities without delay. Furthermore, in times of market volatility or when stock prices are expected to drop, the choice between sell to cover vs same day sale can safeguard you from the risks of holding shares that may lose value. For instance, consider Mr. Jones, who faced a significant capital loss of $375 due to a drop in stock price; a Same Day Sale could have helped him avoid further losses.
Ultimately, your decision should reflect your financial goals, risk tolerance, and perspective on market conditions. It’s important to weigh the potential capital gains tax implications of each strategy. Remember, you’re not alone in this journey; we’re here for you, ready to support you in making the best financial choices for your family.
Conclusion
The choice between sell to cover and same day sale is a crucial decision for families managing stock options, especially those striving to secure their financial future. By understanding the nuances of each method, individuals can make informed choices that resonate with their financial goals. Sell to cover enables continued investment in company shares while effectively managing tax liabilities. In contrast, same day sale offers immediate cash flow, catering to urgent financial needs.
Throughout this discussion, we’ve highlighted key distinctions, including liquidity considerations, tax implications, and compliance risks. Sell to cover supports long-term wealth accumulation by retaining shares, while same day sale ensures quick access to cash. The tax consequences of each strategy can significantly impact overall financial health, particularly for high-income families. Therefore, it’s essential to evaluate personal circumstances and market conditions before making a decision.
Ultimately, the choice between sell to cover and same day sale should reflect your family’s financial objectives, risk tolerance, and market outlook. Engaging with a financial advisor can enhance your understanding and optimize your outcomes, ensuring that you navigate these complexities effectively. By taking a proactive approach, you can better manage your stock options and pave the way for a more secure financial future. Remember, together, we can navigate this journey toward financial well-being.
Frequently Asked Questions
What is the difference between sell to cover and same day sale?
Sell to cover involves selling a portion of vested Restricted Stock Units (RSUs) to meet tax withholding obligations while retaining the remaining shares for future growth. In contrast, a same day sale means selling all vested stocks immediately upon vesting to receive cash for taxes and expenses.
How does the sell to cover method work?
In the sell to cover method, if you have stocks vesting with a tax obligation, you sell a portion of those stocks to cover the tax. For example, if 100 stocks vest with a $1,000 tax obligation, you might sell 10 stocks at $100 each, covering the tax while keeping 90 shares for potential future growth.
What are the benefits of a same day sale?
A same day sale provides immediate cash flow by selling all vested shares upon vesting. Using the previous example, selling all 100 shares would yield $10,000 in cash, which can be used to cover tax obligations and other expenses.
What are the key considerations when choosing between sell to cover and same day sale?
Key considerations include liquidity, as sell to cover supports ongoing investment in the company’s stock for long-term wealth accumulation, while same day sale offers immediate cash flow for short-term needs. Additionally, tax implications and compliance risks must be understood, especially for high-income families.
Are there any compliance risks associated with these methods?
Yes, although transactions under Rule 701 are exempt from registration, they are still subject to anti-fraud provisions of federal securities laws, which may require substantial disclosure.
How do worker preferences influence the choice between sell to cover and same day sale?
Statistics indicate that many workers prefer the sell to cover method over same day sale, reflecting a common practice that can influence decision-making regarding stock options.
List of Sources
- Understanding Sell to Cover and Same Day Sale
- Stock Options, ESPPs and Other Individual Equity Compensation Plans (https://nceo.org/what-is-employee-ownership/stock-options-restricted-phantom-sars-espps)
- Tax Implications of Sell to Cover vs Same Day Sale
- A Simple Guide: How to Report Sell-to-Cover RSUs on Taxes (https://harness.co/articles/how-to-report-sell-to-cover-rsu-on-taxes)
- RSUs and RSAs: Key Differences and Tax Implications (https://purposebuiltfs.com/blog/rsus-and-rsas-key-differences-and-tax-implications)
- RSU Sell-To-Cover: Tax Tricks Explained (https://candor.co/articles/issuer-knowledge/rsu-sell-to-cover-tax-tricks-explained)
- Sell to Cover RSU: Tax Strategies & Tips — Brooklyn Fi (https://brooklynfi.com/blog/sell-to-cover-rsu)
- Tax Implications for Stock-Based Compensation – Bloomberg Tax (https://pro.bloombergtax.com/insights/federal-tax/tax-implications-for-stock-based-compensation)
- When to Use Sell to Cover or Same Day Sale: Practical Scenarios
- The Sell to Cover Tax Strategy for Restricted Stock Units (RSUs) (https://kubera.com/blog/sell-to-cover-rsu)
- RSU Sell-To-Cover: Tax Tricks Explained (https://candor.co/articles/issuer-knowledge/rsu-sell-to-cover-tax-tricks-explained)
- Same-Day Sales: Advantages, Disadvantages, and Tax Considerations – Rosenberg Chesnov (https://rcmycpa.com/same-day-sales-advantages-disadvantages-and-tax-considerations)
- How Are Restricted Stock Units Taxed? Vesting, Withholding, and Selling Explained (https://plancorp.com/blog/restricted-stock-units-taxes)
- Understanding Same-Day Sales Of Employee Stock Options: A Guide For Business Owners – IRSProb (https://irsprob.com/understanding-same-day-sales-of-employee-stock-options-a-guide-for-business-owners)

Kevin has advised high-income W-2 tech and biotech families since 2015, and leads the education-first Age Five Family Office from Brea, California.
Connect on LinkedIn → · About KevinThis is part of how we approach Tax Management for high-income W-2 families at Bright Advisers.
Keep reading