

Key Highlights
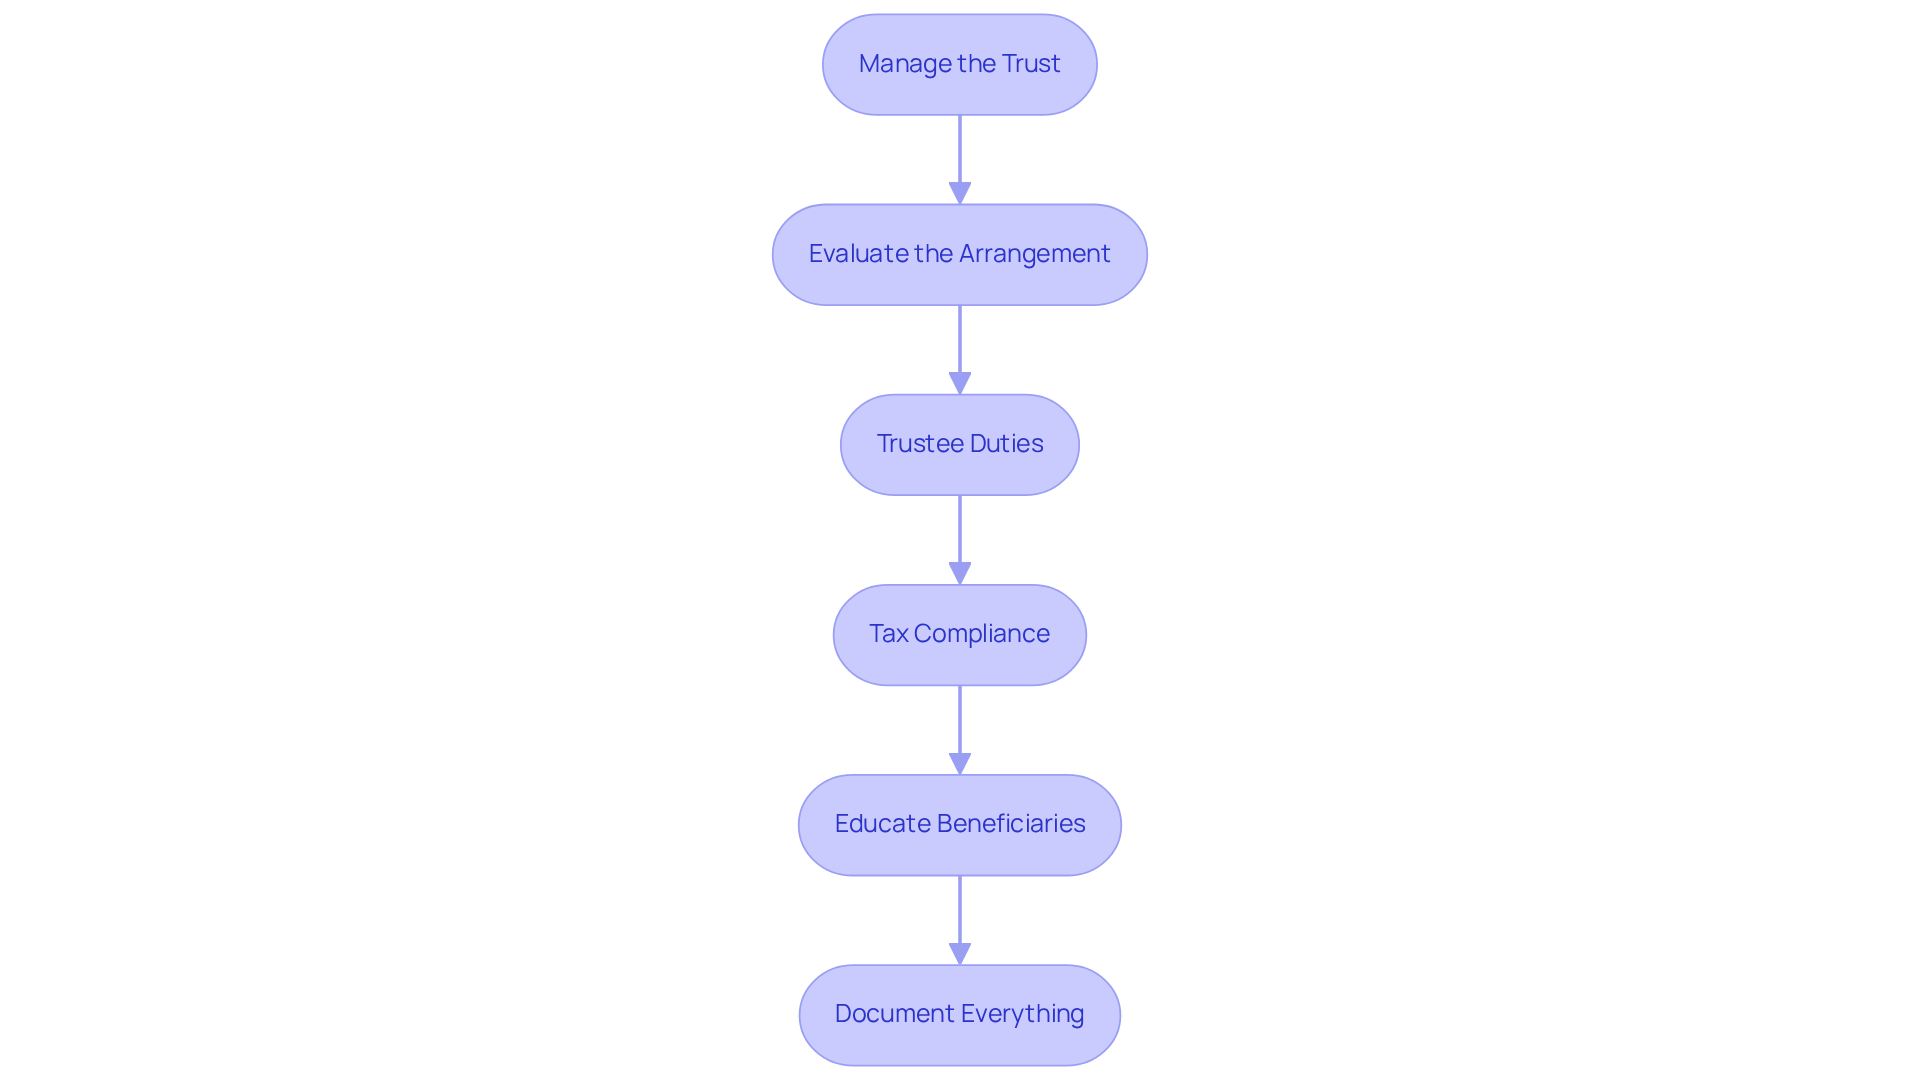
- An irrevocable generation-skipping trust allows asset transfer directly to grandchildren or beneficiaries at least two generations younger, protecting wealth from estate taxes.
- Once established, the trust cannot be altered or cancelled, ensuring the assets are safeguarded from creditors and legal claims.
- Current tax exemptions allow individuals to transfer up to $15 million without taxes, which can be combined for married couples, providing significant wealth preservation opportunities.
- Gather essential documents including personal identification, financial statements, existing wealth management documents, tax information, and clearly defined goals before creating the trust.
- Engage with estate planning attorneys and financial advisors to create a trust that reflects family values and ensures proper management of assets.
- Regular evaluations of the trust with professionals are crucial to adapt to changing family needs and tax laws.
- Trustees must be well-informed to manage assets effectively, and beneficiaries should be educated about their rights and responsibilities to ensure responsible inheritance management.
- Maintaining thorough documentation of all transactions and distributions is essential for tax compliance and transparency among beneficiaries.
Introduction
Imagine feeling confident about your family’s financial future, even amidst the complexities of wealth management. A generation skipping trust (GST) can be a wonderful way to protect your family’s assets while ensuring they pass on to future generations in a tax-efficient manner. But setting up a trust can feel daunting, leaving many families wondering about the best steps to take. How can you make sure your family is on the right path to secure your legacy and achieve your dreams?
Understand the Basics of an Irrevocable Generation-Skipping Trust
Imagine being able to secure your family’s future while easing the burden of taxes – this is where an irrevocable generation skipping trust can help. This powerful wealth planning tool allows you to transfer assets directly to your grandchildren or other beneficiaries who are at least two generations younger than you. Once created, this trust cannot be changed or canceled, ensuring that the resources placed within it are safeguarded from future claims and levies. The beauty of an irrevocable generation skipping trust lies in its ability to bypass immediate estate taxes, enabling you to directly support your grandchildren’s future. This strategic method not only protects wealth for future beneficiaries but also enables organized management and distribution of resources according to your specific desires.
Establishing an irrevocable generation skipping trust can provide peace of mind, ensuring that your family’s wealth is protected and managed according to your wishes. For instance, assets in a GST are shielded from creditors, divorce settlements, and lawsuits, providing an additional layer of protection for your family’s wealth. Furthermore, the current property and gift tax exemption allows individuals to transfer up to $15 million without incurring taxes, which can be combined for married couples to shelter up to $27.98 million. This exemption is indexed for inflation, making it a valuable tool for long-term financial planning.
In 2021, contributions to estates totaled $96.3 billion, highlighting the growing trend of families using estates for wealth management. Imagine being part of a family that successfully leverages an irrevocable generation skipping trust to preserve wealth across generations. For example, a couple who created a GST with assets valued at $26 million saw their fund grow to around $46.5 million over a decade, enabling their grandchild to receive a significant sum without tax.
Expert opinions emphasize the importance of financial literacy for beneficiaries, ensuring they are prepared to manage their inheritance responsibly. Engaging in conversations about the organization’s purpose and values can help beneficiaries understand their roles and responsibilities. As you consider your family’s legacy, remember that a GST can be a compassionate way to ensure their financial well-being for generations to come.
Gather Necessary Documentation and Information
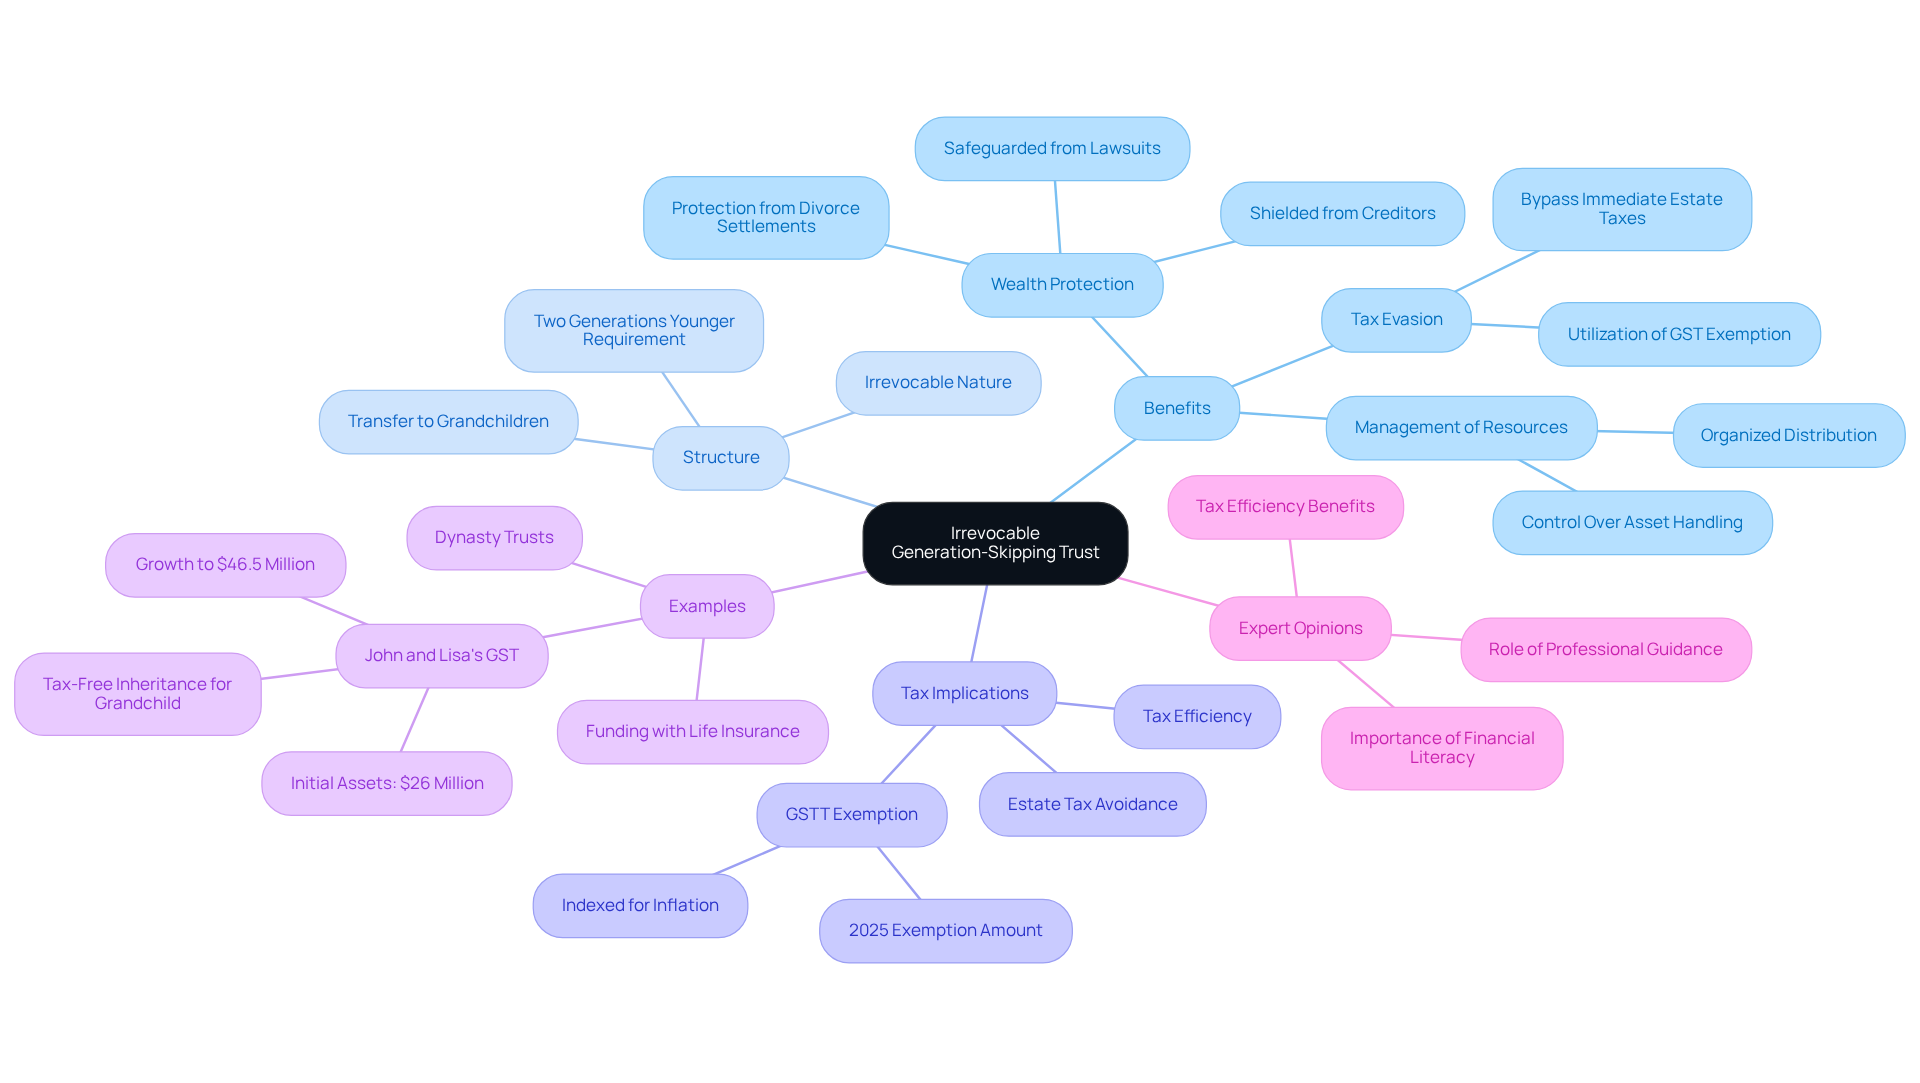
Imagine the relief of knowing your family’s future is secure, but first, you need to gather the right documents. Before creating your irrevocable generation skipping trust, it’s essential to compile everything you need.
Start by collecting Personal Identification: Gather identification documents for everyone involved, including you, the beneficiaries, and the trustee. This step is crucial for ensuring that everyone’s interests are protected.
Next, prepare your Financial Statements. Make a detailed list of your assets, including bank accounts, real property, investments, and any other valuable possessions you want to include in the arrangement. This clarity will help you see the full picture of your wealth.
Don’t forget your Wealth Management Documents. If you have existing wills or trusts, gather these to ensure everything aligns with your wealth planning. Consistency is key to a smooth process.
It’s also important to understand your Tax Information. Be aware of your current tax situation, including any potential inheritance taxes that may apply. This knowledge will be invaluable when you consult with your estate planning attorney.
Finally, take a moment to define your Goals and Objectives. Clearly outline how you want the assets to be managed and distributed. This will help your lawyer tailor the arrangement to fit your family’s unique needs.
When you gather these important documents, you’re taking a big step toward ensuring a smoother process for your family’s future. With the right preparation, you can ensure your family’s legacy is protected and cherished for generations to come.
Follow the Step-by-Step Process to Establish the Trust
Imagine the peace of mind that comes from knowing your family’s future is secure, even when you’re not there to guide them. Establishing an irrevocable generation skipping trust can feel daunting, but with the right support, you can navigate this journey with confidence.
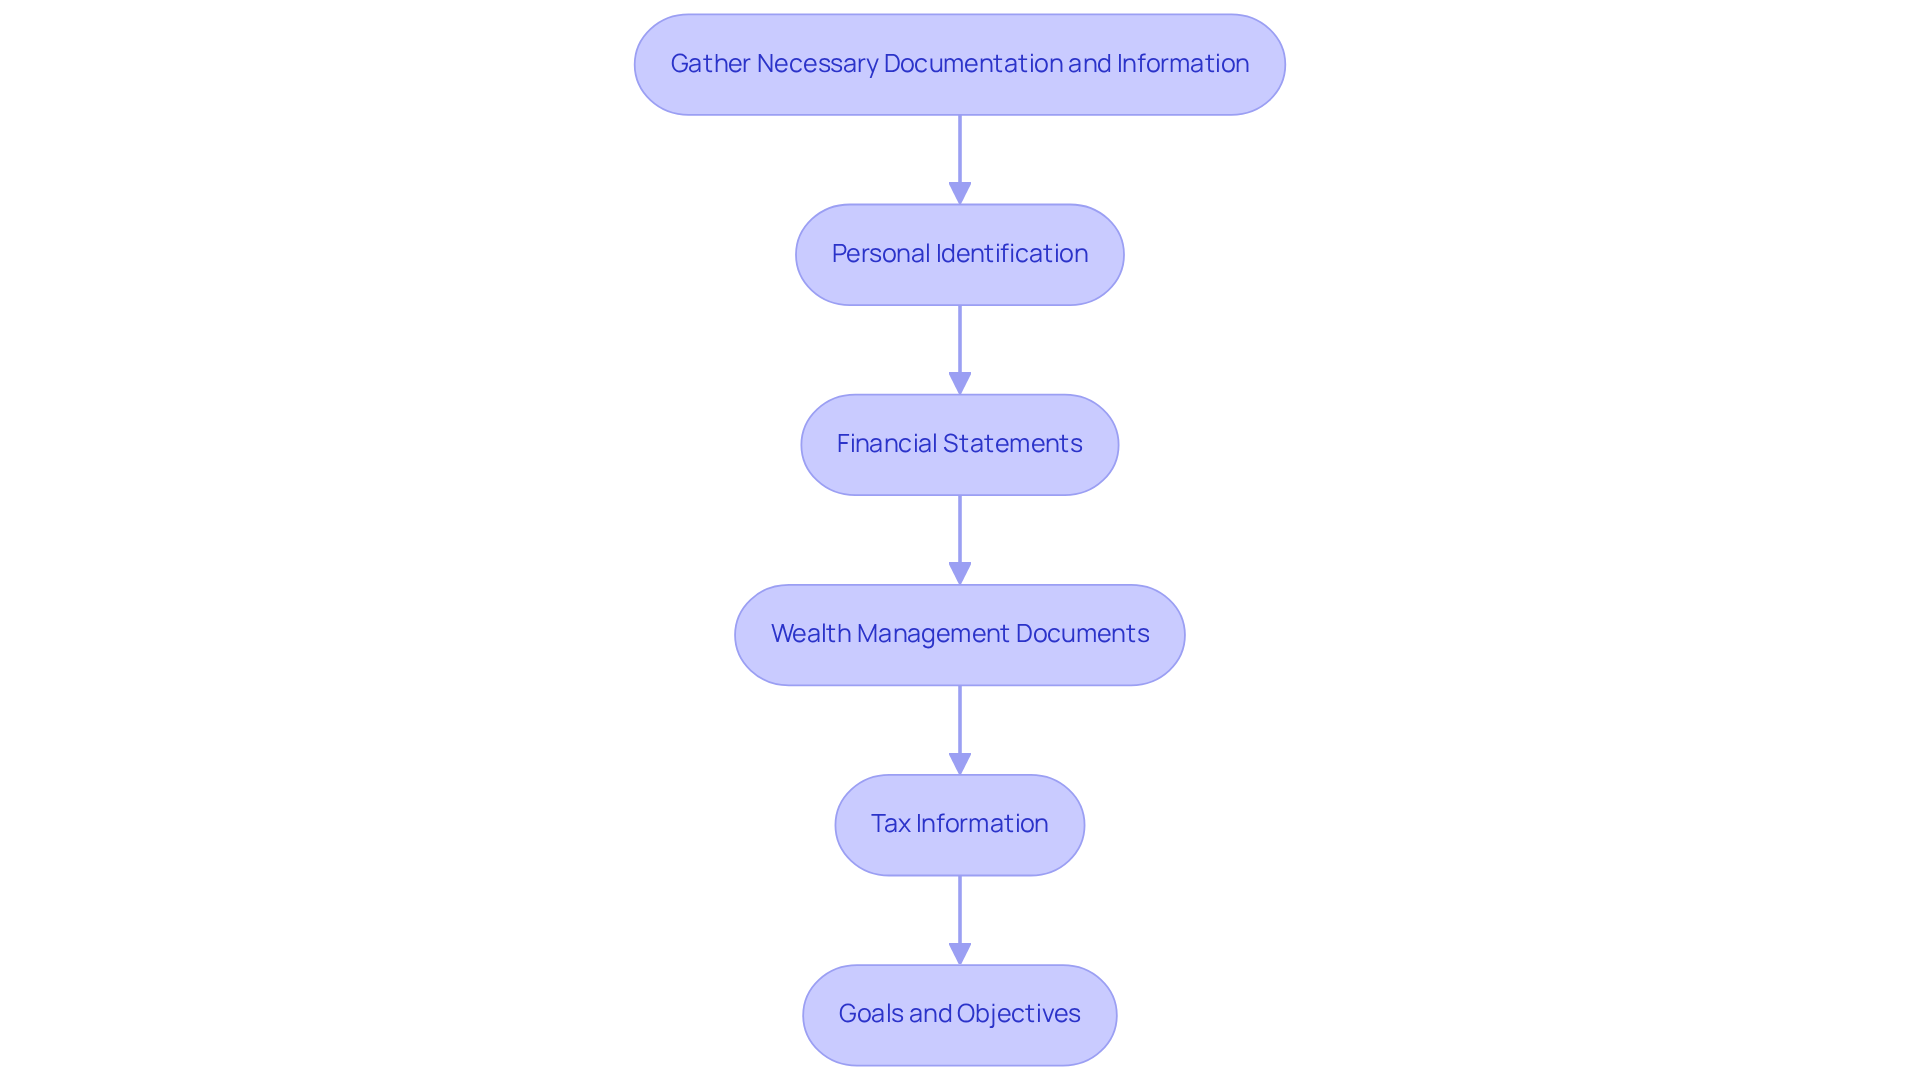
It’s important to reach out to trusted experts who can help guide you through this process with care. Engaging an estate planning attorney and a financial advisor who specialize in estate arrangements will ensure you have the expertise needed to tackle the legal and financial complexities.
Together with your attorney, you can create an irrevocable generation skipping trust that reflects your family’s values and wishes. This agreement should clearly outline the terms, including the trustee’s powers, the beneficiaries, and the governing rules, ensuring that your intentions are honored.
Consider how to best fund your trust, whether through cash, property, or investments. Make sure everything is in order for your family’s future by correctly titling the properties in the name of the trust.
Don’t forget to apply for a Tax Identification Number, which is essential for managing your trust’s finances smoothly. This number will be used for any income generated by the trust’s resources, helping you stay organized.
Finally, take a moment to review everything with your attorney, ensuring that every detail aligns with your family’s wishes and dreams. With the right support, you can confidently take these steps to protect your family’s legacy for years to come.
Manage the Trust and Understand Tax Implications
Imagine the peace of mind that comes from knowing your family’s future is secure, even amidst the complexities of financial planning. Once your irrevocable generation skipping trust is established, effective management and understanding of tax implications are crucial. Here’s how to manage your trust effectively:
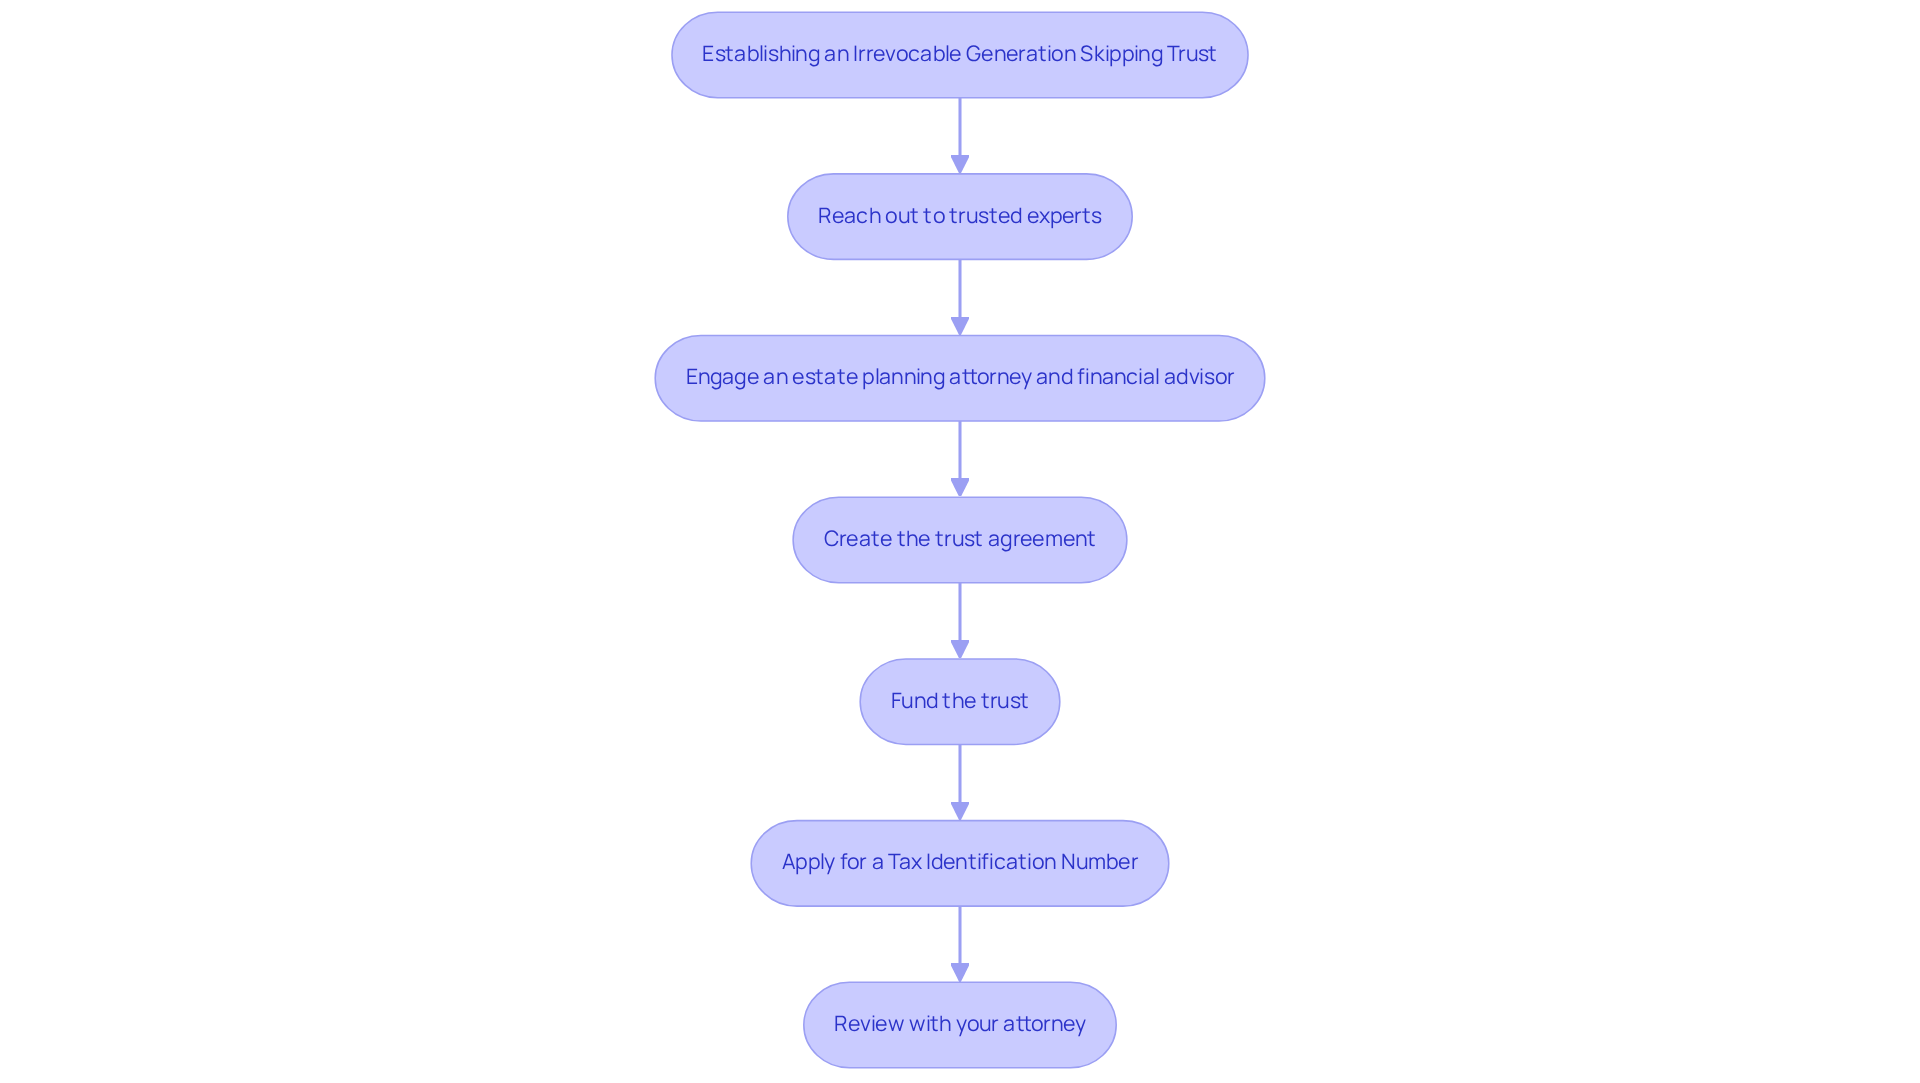
- Consistently Evaluate the Arrangement: Arrange regular assessments with your attorney and financial advisor to ensure the arrangement aligns with your family’s evolving needs and goals. This proactive approach can help adapt to changes in tax laws and family circumstances.
- Trustee Duties: It’s so important to make sure your trustee knows what they’re doing. They need to manage assets, make distributions, and keep everything organized. A well-informed trustee can really make a difference in how your fund performs.
- Tax Compliance: Be aware of the tax implications associated with the estate. The generation-skipping transfer tax (GSTT) may apply to distributions made to skip persons, with a flat rate of 40% on transfers exceeding the exemption amount. Consulting with a tax professional can help optimize tax efficiency and ensure compliance.
- Educate Beneficiaries: Provide education to beneficiaries about the fund and their rights. This fosters financial literacy and responsible management of their inheritance, which is essential for preserving wealth across generations.
- Document Everything: Maintain thorough records of all transactions, distributions, and communications related to the fund. This documentation is crucial for tax reporting and ensuring transparency among beneficiaries, which can prevent disputes and misunderstandings.
Navigating the intricacies of trust management can feel daunting, especially when balancing family needs and tax regulations. Without the right planning, the wealth you’ve built could fade away, leaving your family’s dreams hanging in the balance. By effectively managing the estate and understanding its tax implications, you can protect your wealth and pass it down just as you intend. For instance, the Martinez family successfully utilized a charitable lead trust and donor advised fund to manage their $18 million estate, generating over $3 million in charitable distributions while minimizing GST tax exposure. With the right guidance, you can ensure your family’s legacy thrives for generations to come, creating a brighter future for your loved ones.
Conclusion
Imagine securing your family’s future with a trust that honors your wishes and protects your legacy. Establishing an irrevocable generation skipping trust is a powerful strategy for families aiming to secure their wealth across generations. This trust is a way to protect what you’ve worked hard for, ensuring your wishes for your family are honored. By taking the necessary steps to set up this trust, you’re not just planning for today; you’re creating a legacy that will support your loved ones for years to come.
Throughout this guide, we’ve outlined key steps, including:
- Understanding the basics of the trust
- Gathering essential documentation
- Following a structured process for establishment
- Managing the trust effectively
Each of these components plays a vital role in ensuring that the trust operates smoothly and aligns with your family’s goals. It can feel overwhelming to navigate the complexities of estate planning, but you don’t have to do it alone. Connecting with caring professionals can make this journey smoother for you and your family.
Ultimately, the establishment of an irrevocable generation skipping trust is not just about financial planning; it’s about fostering a secure future for your loved ones. By prioritizing education and transparency, families can empower beneficiaries to manage their inheritance responsibly. Taking these steps today can ensure your family’s wealth is not just preserved, but cherished and passed down with love for generations to come. For personalized guidance on setting up your trust, reach out to Bright Advisers at hello@brightadvisers.com or call (714) 987-2967.
Frequently Asked Questions
What is an irrevocable generation-skipping trust (GST)?
An irrevocable generation-skipping trust is a wealth planning tool that allows you to transfer assets directly to your grandchildren or other beneficiaries who are at least two generations younger than you. Once established, this trust cannot be changed or canceled, protecting the assets from future claims and taxes.
How does an irrevocable GST help with taxes?
An irrevocable GST can bypass immediate estate taxes, allowing you to support your grandchildren’s future without incurring tax liabilities on the transferred assets.
What are the benefits of establishing an irrevocable GST?
The benefits include safeguarding wealth from creditors, divorce settlements, and lawsuits, as well as organized management and distribution of resources according to your wishes. It also allows for significant tax exemptions, enabling substantial transfers without incurring taxes.
What is the current property and gift tax exemption related to GSTs?
The current property and gift tax exemption allows individuals to transfer up to $15 million without incurring taxes, which can be combined for married couples to shelter up to $27.98 million. This exemption is indexed for inflation.
Can you provide an example of how an irrevocable GST can grow wealth?
For instance, a couple who created a GST with assets valued at $26 million saw their fund grow to around $46.5 million over a decade, allowing their grandchild to receive a significant sum without tax implications.
Why is financial literacy important for beneficiaries of a GST?
Financial literacy is crucial for beneficiaries to ensure they are prepared to manage their inheritance responsibly. Engaging in discussions about the organization’s purpose and values can help them understand their roles and responsibilities.
What is the mission of Bright Advisers in relation to wealth management?
Bright Advisers aims to help families make wise wealth decisions and preserve wealth across generations, emphasizing fiduciary duty and transparency in their advisory services.
List of Sources
- Understand the Basics of an Irrevocable Generation-Skipping Trust
- Trusts: Income and Estate and Gift Tax Issues (https://congress.gov/crs-product/R48879)
- 3 Smart Generation-Skipping Trust Strategies – Lawvex (https://lawvex.com/generation-skipping-trust)
- Generation Skipping Trusts | GSTs | Estate Planning | RJS LAW (https://irssolution.com/blog/generation-skipping-trusts)
- Generation-Skipping Trusts in 2026: How Retirees Can Pass Wealth to Grandchildren (https://finance.yahoo.com/economy/policy/articles/generation-skipping-trusts-2026-retirees-090400723.html)
- An Introduction to Generation Skipping Trusts – Smith and Howard (https://smith-howard.com/an-introduction-to-generation-skipping-trust)
- Gather Necessary Documentation and Information
- Estate Planning Statistics to Read Before Writing Your Will (https://legalzoom.com/articles/estate-planning-statistics)
- Alarming Estate Planning Statistics (https://financialsense.com/blog/21022/alarming-estate-planning-statistics)
- 50 Estate Planning Statistics and Facts You Need to Know (https://justvanilla.com/blog/estate-planning-statistics-and-facts-you-need-to-know)
- 5 Eye-Opening Statistics About Estate Planning – Nickerson Law: A Professional Corporation (https://jeffreycnickersonlaw.com/blog/5-eye-opening-statistics-about-estate-planning)
- Follow the Step-by-Step Process to Establish the Trust
- Estate Lawyers & Attorneys in the US Number of Businesses Statistics for 2026 | IBISWorld (https://ibisworld.com/united-states/number-of-businesses/estate-lawyers-attorneys/4807)
- How Much Does It Cost To Set Up a Trust? – Policygenius (https://policygenius.com/trusts/how-much-does-a-trust-cost)
- How Much Does It Cost to Set Up a Trust? (https://smartasset.com/estate-planning/how-much-does-it-cost-to-set-up-a-trust)
- How Much Does It Cost to Set Up a Trust: All You Need to Know (https://contractscounsel.com/b/how-much-does-it-cost-to-set-up-a-trust)
- Manage the Trust and Understand Tax Implications
- Wealth Preservation with Charitable Giving: The Generation-Skipping Transfer Tax (https://ghcf.org/articles/generation-skipping-transfer-tax)
- Generation-Skipping Transfer Tax: How It Can Affect Your Estate Plan | U.S. Bank (https://usbank.com/wealth-management/financial-perspectives/trust-and-estate-planning/generation-skipping-tax-affect-on-estate-plan.html)
- Generation skipping transfer tax (GSTT) explained | Fidelity (https://fidelity.com/viewpoints/wealth-management/insights/generation-skipping-transfer-tax)

Kevin has advised high-income W-2 tech and biotech families since 2015, and leads the education-first Age Five Family Office from Brea, California.
Connect on LinkedIn → · About KevinThis is part of how we approach Estate Planning for high-income W-2 families at Bright Advisers.
Keep reading